
Cardiovascular Drugs Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 171.25 Billion |
| Market Size (2032) | USD 201.58 Billion |
| Growth Rate (2027 - 2032) | 3.31 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Cardiovascular Drugs Market Analysis by Mordor Intelligence
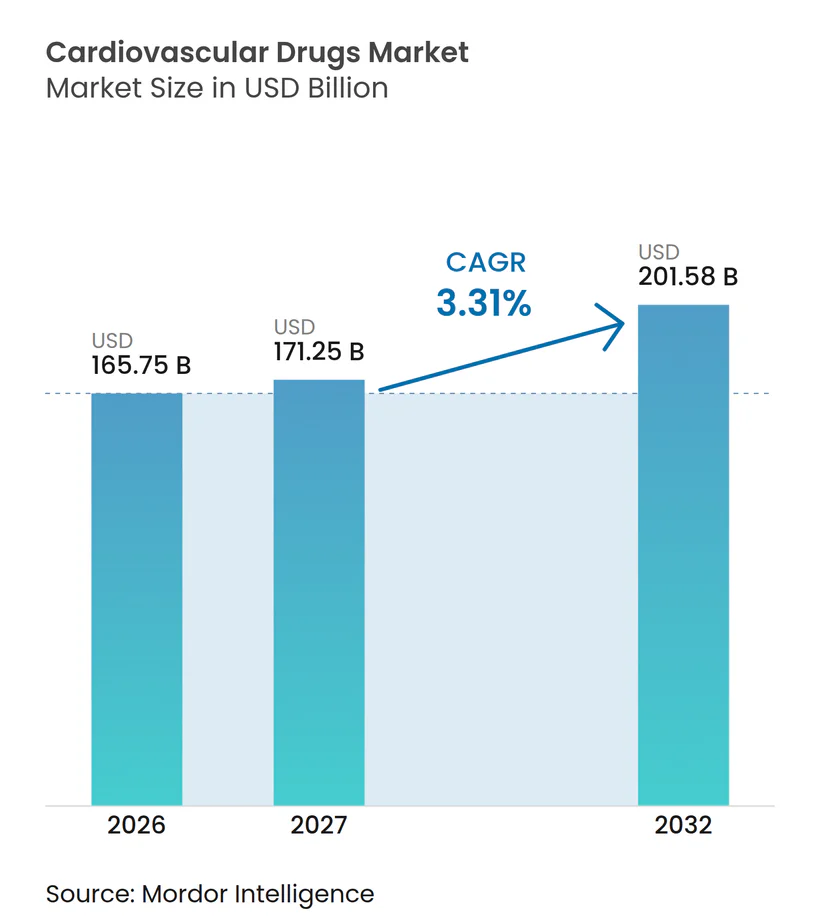
The Cardiovascular Drugs Market size is projected to be USD 165.75 billion in 2026, USD 171.25 billion in 2027, and reach USD 201.58 billion by 2032, growing at a CAGR of 3.31% from 2027 to 2032.
Ongoing patent expiries are pushing manufacturers to shift from blockbuster small molecules toward targeted biologics and digital-enabled care pathways, even as health systems move reimbursement models from volume to value. Uptake of PCSK9 inhibitors, sodium-glucose co-transporter-2 (SGLT-2) inhibitors, and novel oral anticoagulants (NOACs) is accelerating because regulators now accept real-world evidence for label expansions, which shortens market-entry timelines. Payers are simultaneously demanding outcomes-based contracts that link reimbursement to reductions in major adverse cardiovascular events, forcing companies to wrap therapies with analytics and adherence programs. Supply-chain resilience has emerged as a competitive differentiator after recent active pharmaceutical ingredient shortages underscored the risk of single-region sourcing concentrated in China and India.
Key Report Takeaways
- By drug class, antihypertensives held 29.56% of the cardiovascular drugs market share in 2026, while lipid-lowering agents are forecast to expand at a 4.85% CAGR through 2032.
- By disease indication, hypertension accounted for 31.53% of revenue in 2026, whereas dyslipidemia is the fastest-growing segment at a 4.75% CAGR through 2032.
- By route of administration, oral formulations dominated with an 82.16% share in 2026, yet transdermal delivery is set to grow at a 5.82% CAGR on the strength of next-generation nitroglycerin patches.
- By distribution channel, hospital pharmacies captured 45.52% of sales in 2026, while online pharmacies are advancing at a 6.12% CAGR as telehealth prescribing becomes mainstream.
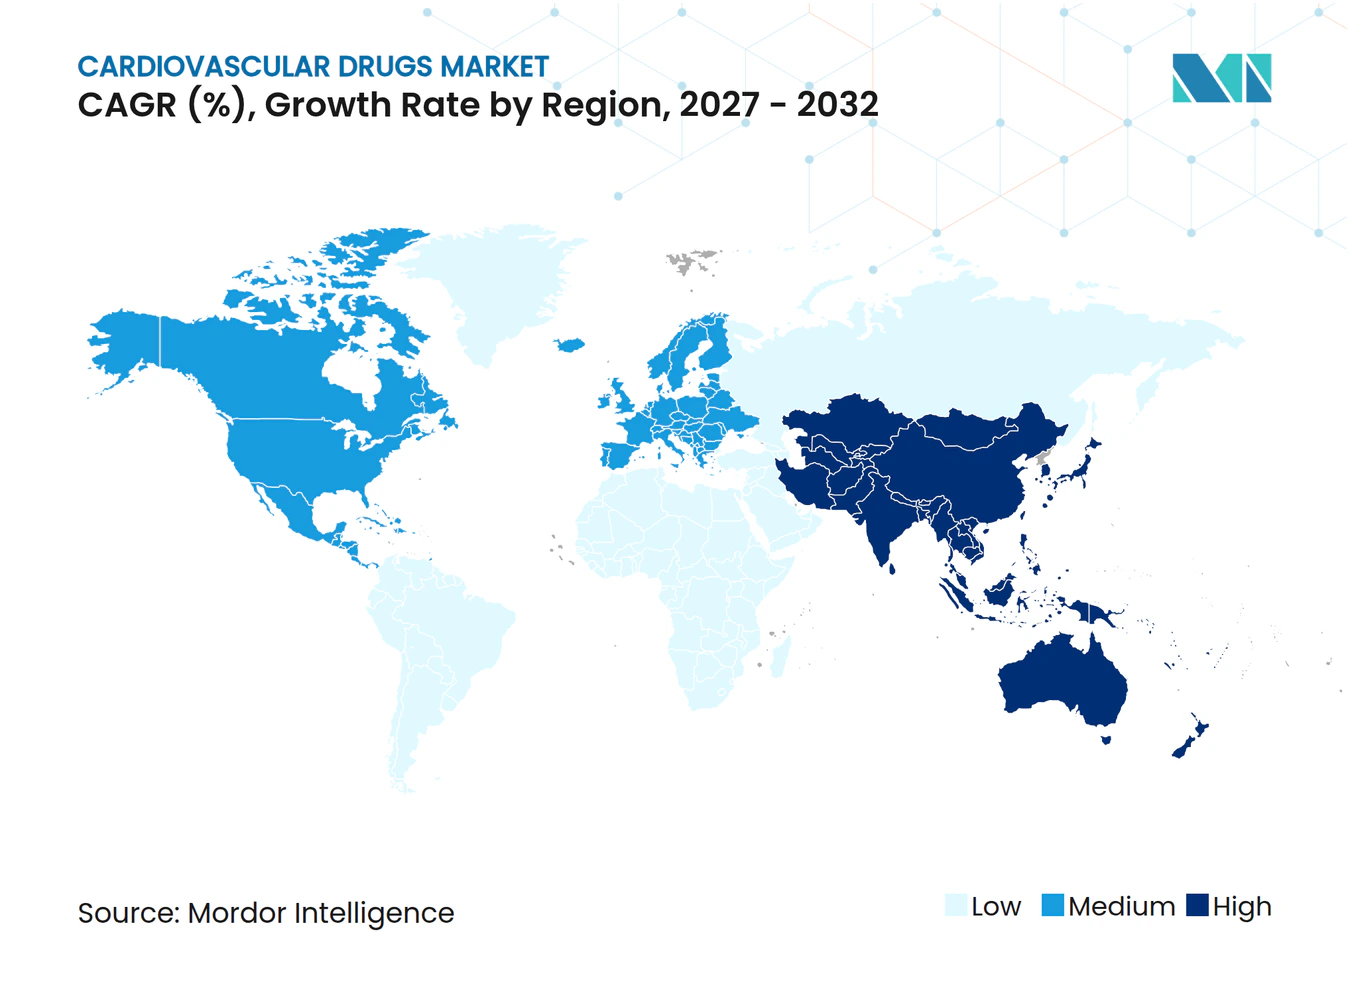
- By geography, North America retained a 38.55% share in 2026, but Asia-Pacific is the fastest-growing region at a 5.72% CAGR through 2032, following insurance expansions that cover NOACs and SGLT-2 inhibitors.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Cardiovascular Drugs Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising prevalence of CVDs in aging populations | +0.9% | Global, stronger in Asia-Pacific and Europe | Long term (≥4 years) |
| Rapid uptake of NOACs & SGLT-2 inhibitors | +1.2% | North America and EU core, expanding to tier-2 APAC cities | Medium term (2-4 years) |
| Expanding reimbursement in emerging markets | +0.7% | Asia-Pacific core, Latin America, Middle East | Medium term (2-4 years) |
| Regulatory reliance on real-world evidence for label extensions | +0.4% | North America and EU, pilots in Japan and Australia | Short term (≤2 years) |
| AI-driven in-silico repurposing accelerating pipeline | +0.3% | Global R&D hubs | Long term (≥4 years) |
| Source: Mordor Intelligence | |||
Rising Prevalence of CVDs in Aging Populations
The percentage of adults aged 65 and older is growing faster than any other demographic group, and cardiovascular diseases (CVDs) remain the leading cause of death worldwide[1]. Japan reported in 2025 that 68% of cardiovascular patients aged 75 and above take at least five concurrent medicines, which complicates adherence and heightens drug–drug interaction risk. Regulators now require geriatric-specific dosing studies, adding up to 18 months to development timelines but improving post-market safety. Health plans are shifting resources toward preventive options such as PCSK9 inhibitors, provided manufacturers link payment to event-reduction metrics. This epidemiologic swell ensures sustained demand for therapies that address polypharmacy and multimorbidity.
Rapid Uptake of NOACs & SGLT-2 Inhibitors
Between 2024 and 2025 the U.S. Food and Drug Administration approved seven label expansions for SGLT-2 inhibitors that now include heart failure with preserved ejection fraction, a population that lacked disease-modifying drugs. The European Medicines Agency noted that NOAC prescriptions in atrial fibrillation surpassed warfarin for the first time in Eastern European markets in 2025, catalyzed by lower monitoring costs. Adoption remains uneven in Latin America and Sub-Saharan Africa where generic warfarin still dominates formularies. Companies are offering tiered pricing and voluntary licenses, yet market-access talks often stretch two to three years after approval. Despite disparities, faster uptake in high-income regions is boosting global revenue growth.
Expanding Reimbursement in Emerging Markets
China’s National Healthcare Security Administration added 12 cardiovascular drugs to its reimbursement list in 2025, cutting patient out-of-pocket costs by up to 80% and triggering demand that outpaced supply forecasts[2]. India’s Ayushman Bharat scheme started covering direct oral anticoagulants in 2024, though state-level roll-out is still uneven. Brazil cut regulatory review times to nine months in 2024 for FDA-approved drugs, yet private insurers restrict branded drugs unless generics fail. These dynamics encourage manufacturers to localize production and run real-world studies that satisfy each country’s health-technology-assessment needs. Broader reimbursement is narrowing the treatment gap but compressing prices through large-volume tenders.
Regulatory Reliance on Real-World Evidence for Label Extensions
The FDA’s Sentinel Initiative analyzed electronic health records from 12 million patients in 2024-2025 to confirm cardiovascular safety signals without fresh randomized trials. Europe’s DARWIN EU platform links 150 million longitudinal patient records, letting companies request indication expansions if pre-specified outcomes are met. Japan adopted a conditional approval pathway in 2025 for rare lipid disorders, requiring companies to enroll patients in post-marketing registries for five years. Smaller biotechs gain faster market entry but also shoulder greater surveillance duties. Real-world evidence is therefore both an accelerator and a continual compliance obligation.
Restraints Impact Analysis of Cardiovascular Drugs Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Patent expiries & generic erosion of blockbuster brands | -0.8% | Global, sharper in North America and EU | Short term (≤2 years) |
| High cost of biologic & gene-based therapies | -0.5% | Global, access barriers in emerging markets | Long term (≥4 years) |
| Single-region API sourcing creating supply-chain risk | -0.3% | Global, concentrated in China and India | Medium term (2-4 years) |
| Digital-therapeutics cannibalization risk | -0.2% | North America and EU, employer-sponsored plans | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Patent Expiries & Generic Erosion of Blockbuster Brands
Apixaban lost exclusivity in 2024, and six months later branded sales volumes fell 42% in the United States, according to company filings[3]. Rivaroxaban followed in 2025 with eight generic challengers in queue, and price erosion is projected to reach 70% by 2027. Companies respond by launching authorized generics and fixed-dose combinations, yet payers now scrutinize incremental innovation claims. Outcomes-based contracts that hinge on stroke-prevention metrics are replacing traditional rebates. The near-term revenue drag weighs on the cardiovascular drugs market until pipeline biologics offset generics.
High Cost of Biologic & Gene-Based CV Therapies
Inclisiran costs roughly USD 6,500 per year in the U.S., far above generic statins at USD 300, constraining uptake to high-risk patients. CRISPR-based candidate VERVE-101 entered phase 1b in 2024 with an anticipated six-figure price, sparking debate on cost-effectiveness thresholds. Health technology bodies in the UK and Germany have rejected several high-cost biologics because long-term outcomes are unproven. Manufacturers propose installment payments and risk-sharing, but complex administration delays market entry. Affordability hurdles therefore temper the growth contribution of cutting-edge modalities despite strong clinical promise.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Cardiovascular Drugs Market Segment Analysis
By Drug Class:
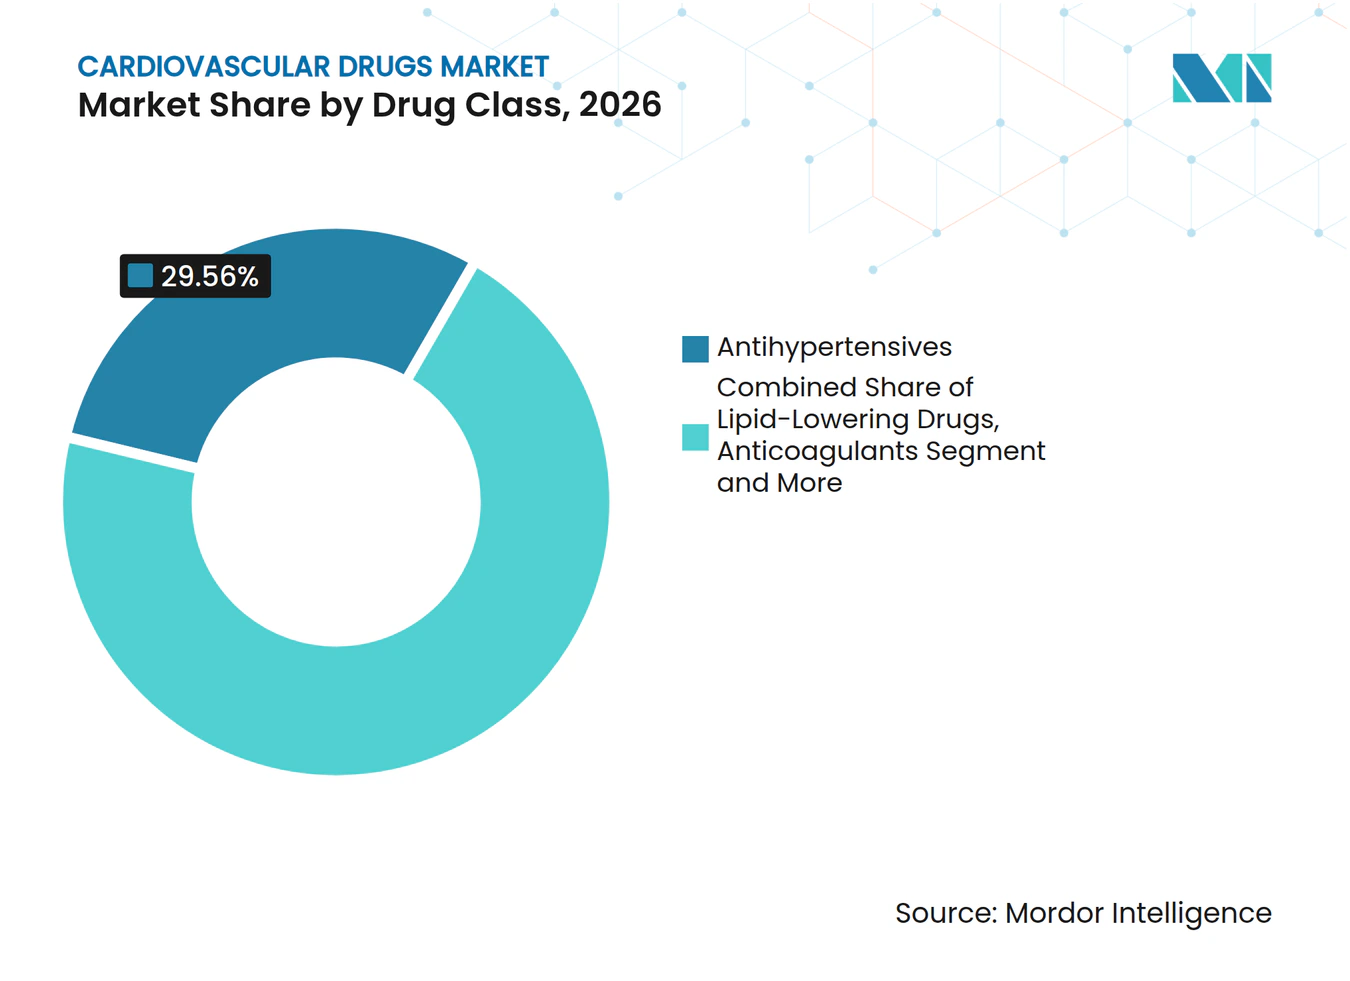
Lipid-Lowering Agents Lead InnovationIn 2026, antihypertensives captured a 29.56% share of the cardiovascular drugs market size, reflecting entrenched demand across all income levels. Lipid-lowering agents are growing fastest at 4.85% CAGR as PCSK9 inhibitors and bempedoic acid address statin intolerance. The cardiovascular drugs market share of anticoagulants is contracting because generic apixaban and rivaroxaban squeeze prices, yet edoxaban is gaining traction in Asia where once-daily dosing fits local adherence patterns. Heart-failure therapies now include SGLT-2 inhibitors and ARNIs, broadening treatment beyond diuretics and ACE inhibitors.
Pulmonary arterial hypertension remains a lucrative niche with high-priced endothelin receptor antagonists and the recent launch of sotatercept. Antiarrhythmics hold a modest proportion but benefit from integration with catheter ablation services. Manufacturers pursue triple-drug fixed-dose combinations that improve adherence while extending intellectual property life. Collectively, drug-class diversification cushions the cardiovascular drugs market against single-segment volatility.



By Disease Indication:
Dyslipidemia Gains MomentumHypertension held 31.53% of revenue in 2026, consistent with guideline-driven early treatment initiation. Dyslipidemia is expanding at 4.75% CAGR as aging populations accumulate cardiometabolic risk factors and payers approve PCSK9 inhibitors under outcomes-based contracts. Coronary artery disease remains sizeable, but adherence to long-term dual antiplatelet therapy is challenged by polypharmacy fatigue. Heart-failure indications benefit from quadruple therapeutic regimens that cut hospitalization by up to 40% relative to legacy therapy.
Arrhythmia management is migrating toward device solutions that alter the pharmaceutical mix but raise demand for peri-procedural anticoagulation. Venous thromboembolism care is lengthening as guidelines recommend indefinite treatment for unprovoked events, sustaining oral anticoagulant demand even amid price erosion. Overall, shifting comorbidity patterns diversify revenue sources across indications within the cardiovascular drugs market.
By Route of Administration:
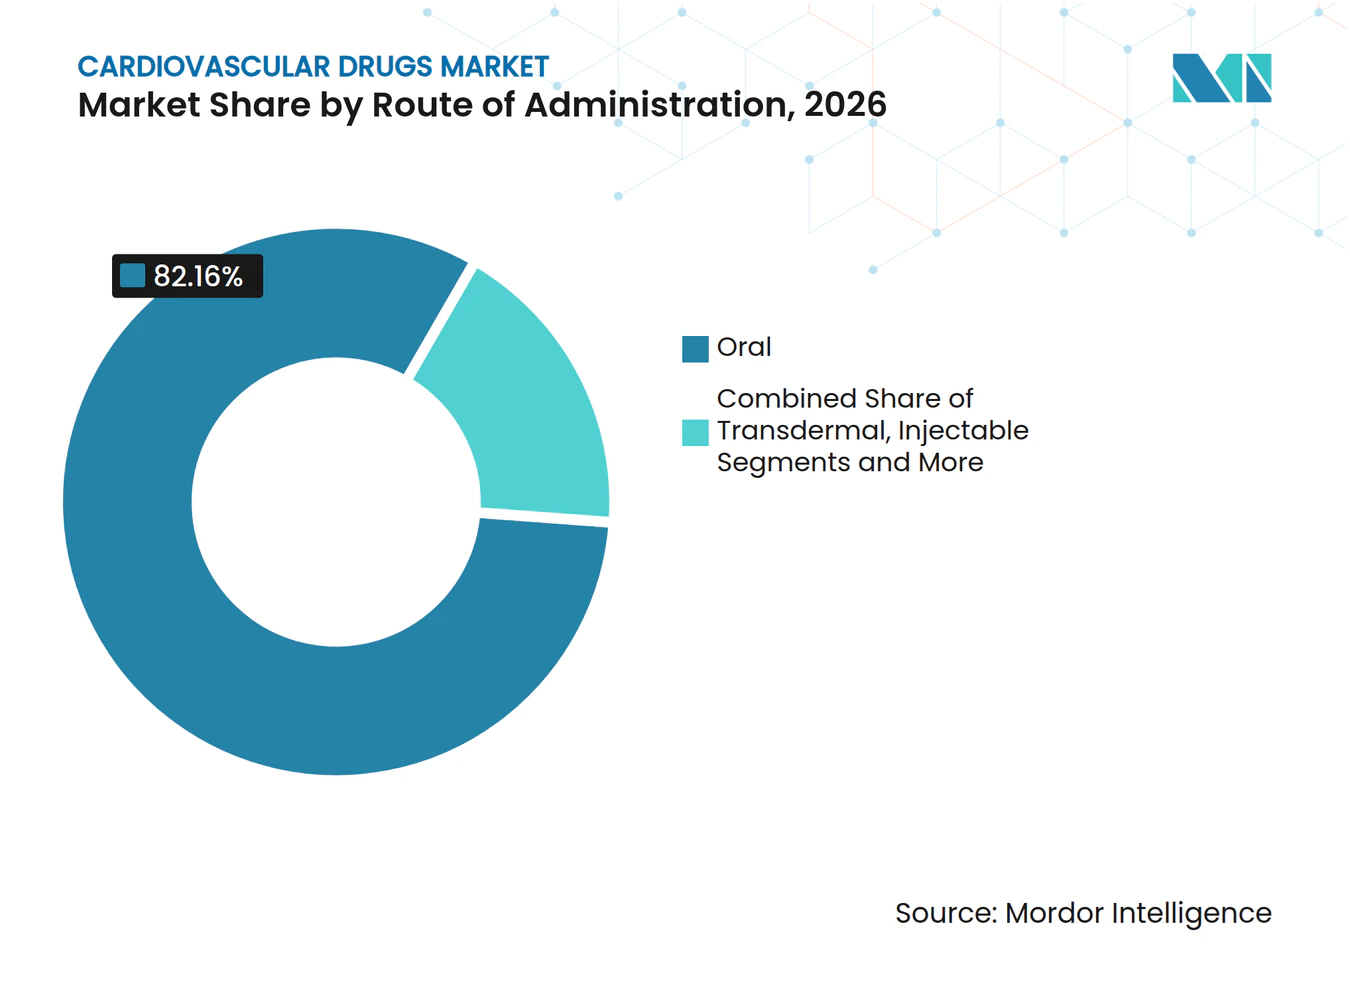
Transdermal Gains TractionOral dosage forms accounted for 82.16% of sales in 2026 owing to patient familiarity and low production cost. Transdermal systems are projected to rise at a 5.82% CAGR because microneedle patch technologies deliver steady-state plasma levels and enhance adherence for chronic angina. Injectable routes dominate biologic delivery, with PCSK9 inhibitors and reversal agents relying on subcutaneous or intravenous formats.
Regulators released guidance in 2025 clarifying bioequivalence for auto-injectors, which should stimulate generic competition for monoclonal antibodies. Long-acting injectables for beta-blockers launched in 2024 but face reimbursement barriers. Demand for home-administered formulations grows with telehealth, underpinning investment in wearable-compatible drug-device combinations that integrate dosing reminders and remote monitoring.

By Distribution Channel:
Online Pharmacies SurgeHospital pharmacies led with a 45.52% share in 2026 due to their central role in acute care and specialty biologic dispensing. Online platforms are rising at a 6.12% CAGR, accelerated by mail-order incentives that lower copays and ensure supply continuity for chronic therapies. Retail chains are upgrading digital ordering and medication-therapy-management services to protect foot traffic.
Regulators enforce serialization under the European Falsified Medicines Directive, which raises compliance costs yet boosts consumer trust. U.S. policy changes in 2024 allowed telemedicine refills for most cardiovascular prescriptions, reinforcing growth in direct-to-patient fulfillment. Over the forecast period, the cardiovascular drugs market will likely split between high-touch retail for complex regimens and automated online channels for stable maintenance therapy.
Geography Analysis
APAC Cardiovascular Drugs Market
Asia-Pacific led the cardiovascular drugs market with a 34.35% share in 2026, and its 5.25% CAGR outpaces all other regions thanks to China’s procurement reforms and India’s infrastructure expansion. Local firms now secure 71% of new NRDL listings, signaling stronger domestic competitive pressure for multinationals. Japan’s streamlined approval timelines further ease market entry for cutting-edge therapies, promoting steady uptake of GLP-1 agents and next-generation anticoagulants.
North America Cardiovascular Drugs Market
North America remains a pivotal innovation hub in the cardiovascular drug market, underpinned by reimbursement frameworks that quickly absorb breakthrough therapies. Nonetheless, the Inflation Reduction Act introduces price-negotiation uncertainty that may reshape launch-sequence strategies for high-value cardiovascular assets.
EMEA and LATAM Cardiovascular Drugs Market
Europe benefits from harmonised regulatory pathways that accelerate parallel submissions, though Brexit-related logistics adjustments persist. Latin America’s policy moves toward domestic production—exemplified by Brazil’s preference margins—create dual imperatives of localisation and cost control. The Middle East and Africa record incremental gains aligned with cardiovascular-disease awareness campaigns, yet infrastructure gaps still limit high-cost biologic penetration.
Competitive Landscape
Market Concentration
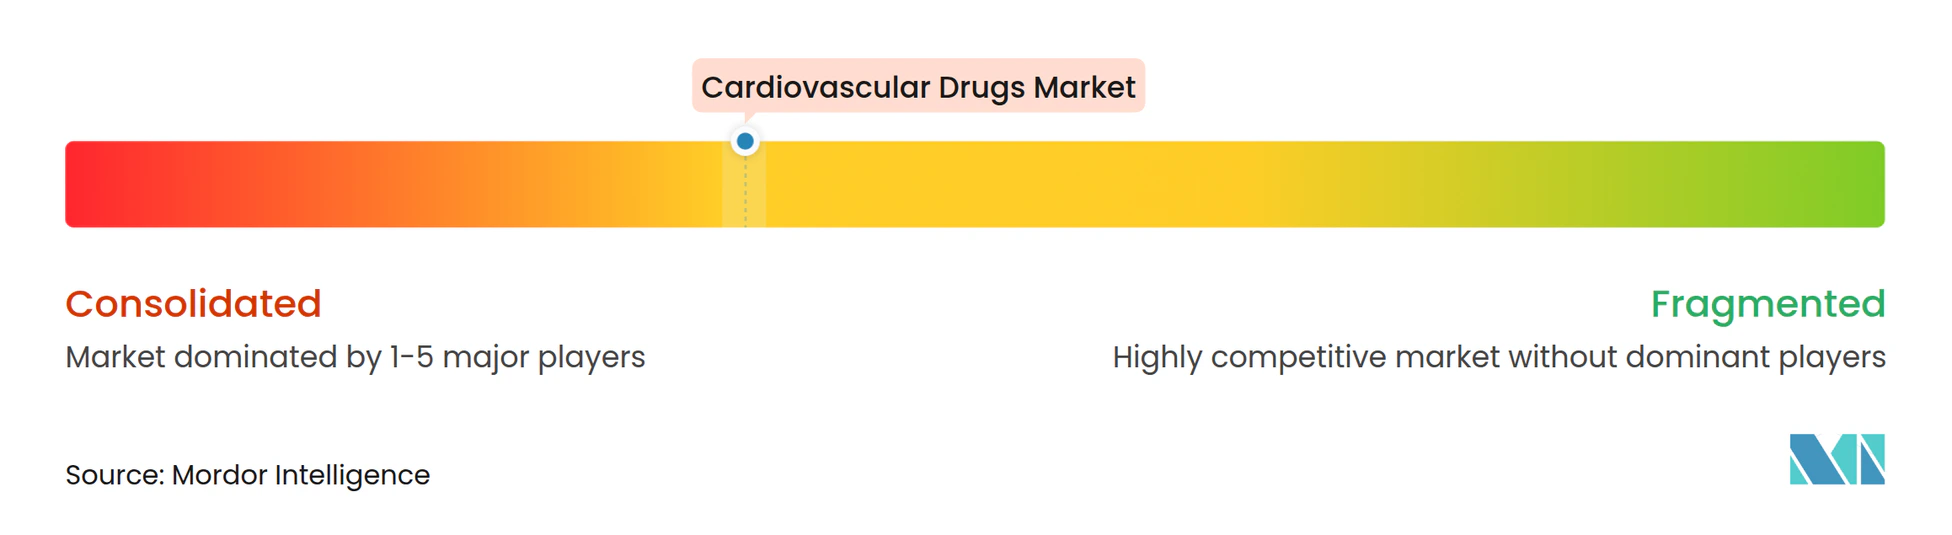
The cardiovascular drugs market exhibits moderate consolidation, with the top 10 companies holding a substantial share in 2026, yet competition remains intense because of patent cliffs, biosimilar entry, and digital-health disruption. Bristol Myers Squibb and Pfizer launched authorized generics for apixaban after 2024 exclusivity loss, shifting focus toward lower-risk atrial fibrillation populations. Novartis pursues label expansions for sacubitril-valsartan into post-myocardial infarction and hypertension indications, supported by real-world evidence that demonstrates mortality benefits. Smaller biotechs such as Cytokinetics and Lexicon Pharmaceuticals target heart-failure subtypes with novel mechanisms, exploiting white space in preserved ejection fraction and rare genetic dyslipidemias.
Digital-therapeutics firms position algorithm-driven hypertension management as adjuncts to pharmacotherapy, though reimbursement remains underdeveloped and adoption is concentrated in employer-sponsored plans. Patent filings for cardiovascular drugs rose 12% in 2024, signaling sustained research investment despite pricing headwinds. Companies differentiate through supply-chain resilience, establishing dual sourcing for active pharmaceutical ingredients to mitigate geopolitical risk. Competitive strategies increasingly blend life-cycle management, outcomes-based contracting, and digital companion apps to retain formulary access in value-based care networks.
Cardiovascular Drugs Industry Leaders
-
Pfizer Inc
-
Bristol Myers Squibb
-
Novartis AG
-
AstraZeneca plc
-
Johnson & Johnson
- *Disclaimer: Major Players sorted in no particular order
Cardiovascular Drugs Market Companies Covered in this Report
- Abbott Laboratories
- Abbvie
- Amgen
- AstraZeneca
- Bayer
- Boehringer Ingelheim
- Bristol-Myers Squibb
- Daiichi Sankyo
- Eli Lilly and Company
- GlaxoSmithKline
- Johnson & Johnson
- Merck
- Novartis
- Novo Nordisk
- Otsuka Pharma
- Pfizer
- Roche
- Sanofi
- Servier
- Takeda Pharmaceuticals
Recent Industry Developments in Cardiovascular Drugs Market
- January 2026: Cytokinetics announced U.S. availability of MYQORZO (aficamten) tablet, approved by the FDA for adults with symptomatic obstructive hypertrophic cardiomyopathy to improve functional capacity and symptoms.
- August 2025: Roche and Alnylam initiated a phase 3 cardiovascular outcomes trial evaluating zilebesiran, an RNAi therapeutic, to reduce major adverse cardiovascular events in patients with uncontrolled hypertension.
Cardiovascular Drugs Market Report Scope and Research Methodology
Market Definition and Coverage
Our study defines the cardiovascular drugs market as the global sales value of prescription and over-the-counter pharmacological agents that are clinically approved to prevent, treat, or manage disorders of the heart and blood vessels, including hypertension, dyslipidemia, coronary artery disease, arrhythmia, heart failure, venous thromboembolism, and pulmonary hypertension. Oral, injectable, and transdermal formulations distributed through hospital, retail, and online pharmacies are counted; veterinary products and herbal supplements are excluded.
Scope Exclusion: Devices, nutraceuticals, and pipeline biologics still in clinical phases are not considered.
Segments Covered in This Report
- By Drug Class
- Antihypertensives
- Anticoagulants
- Antiplatelet Agents
- Lipid-Lowering Drugs
- Heart-Failure Drugs
- Antiarrhythmics
- Pulmonary-Hypertension Drugs
- By Disease Indication
- Hypertension
- Coronary Artery Disease
- Heart Failure
- Arrhythmia
- Dyslipidemia
- Venous Thrombo-Embolism
- By Route of Administration
- Oral
- Injectable / IV
- Transdermal
- Others
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Primary Research
Mordor analysts interviewed cardiologists, hospital pharmacy managers, and procurement leads across North America, Europe, and fast-growing Asia Pacific. These dialogues clarified real-world utilization rates, average selling prices, and channel shifts, filling gaps that secondary data alone could not bridge.
Desk Research
We began with publicly available cornerstones such as the World Health Organization mortality database, the UN Population Prospects, and trade statistics from UN Comtrade, which reveal prevalence trends and import values for finished formulations. Region-specific insights were gathered from bodies like the American Heart Association, the European Society of Cardiology, Japan's PMDA, and India's CDSCO, providing treatment guidelines and approval timelines that shape therapeutic uptake. Financial signals were cross-checked through company 10-Ks and investor decks, and pricing benchmarks were traced in national reimbursement lists. Finally, paid archives, such as Dow Jones Factiva for news flow and D&B Hoovers for audited revenue splits, helped us align corporate disclosures with reported sales. This list is illustrative; many other credible sources informed the desk review.
Market-Sizing & Forecasting
A top-down prevalence-to-treated cohort framework converts disease populations into therapy demand, followed by sampled ASP × volume checks to validate totals from a bottom-up angle. Key model drivers include the diagnosed hypertension pool, statin penetration in dyslipidemia, generic erosion rates, average therapy duration, and public reimbursement expansions. Multivariate regression with GDP per capita and elderly share forecasts projects demand through 2030, and scenario analysis adjusts for patent cliffs or breakthrough entrants.
Data Validation & Update Cycle
Outputs pass variance checks against script volume audits and IMS sell-out flashes before a multi-analyst review. Reports refresh annually, with interim revisions when material events, such as major label expansions or pricing reforms, emerge, ensuring clients receive the latest view.
How Mordor Intelligence's Cardiovascular Drugs Market Size Compares to Other Published Estimates
Published numbers often differ because firms pick diverse drug baskets, convert currencies on separate dates, or stretch forecasts without re-contacting market actors. Our disciplined scope selection, yearly refresh, and front-line interviews temper these variances.
Key gap drivers include variation in included drug classes, treatment rate assumptions, and cadence of price updates, which are subsequently magnified over multi-year horizons.
Benchmark comparison
| Market Size | Anonymized source | Primary gap driver |
|---|---|---|
| USD 160.39 B (2025) | Mordor Intelligence | - |
| USD 155.96 B (2025) | Global Consultancy A | Narrower drug-class coverage and limited field validation |
| USD 153.70 B (2024) | Industry Research B | Excludes hospital tender sales and holds ASP constant |
These contrasts show that Mordor's numbers sit at the balanced center, anchored to transparent variables and a repeatable update cycle that decision-makers can trust.
Key Questions Answered in the Report
What is the projected value by 2032?
The global cardiovascular drugs market size is forecasted to reach USD 201.58 billion by 2032, growing at a 3.31% CAGR from 2027 to 2032.
Which therapeutic class is expanding fastest?
Lipid-lowering agents are advancing at 4.85% CAGR through 2032, driven by PCSK9 inhibitor adoption and bempedoic acid uptake among statin-intolerant patients.
What are the main growth drivers?
Key drivers include rising CVD prevalence in aging populations, rapid uptake of NOACs and SGLT-2 inhibitors, expanding reimbursement in emerging markets, and regulatory acceptance of real-world evidence for label extensions.
Which region is growing fastest?
Asia-Pacific is projected to expand at 5.72% CAGR through 2032, fueled by national insurance expansions in China and India that now cover novel oral anticoagulants and SGLT-2 inhibitors.
How are patent expiries affecting the sector?
Apixaban and rivaroxaban lost exclusivity in 2024 and 2025, triggering generic competition and up to 70% price erosion by 2027, which is compressing margins for branded manufacturers.
What role do digital therapeutics play?
Algorithm-driven hypertension management platforms are emerging as adjuncts to pharmacotherapy, with some payers offering copay waivers for patients who enroll, though reimbursement frameworks remain fragmented.