
Africa Olive Market Analysis by Mordor Intelligence
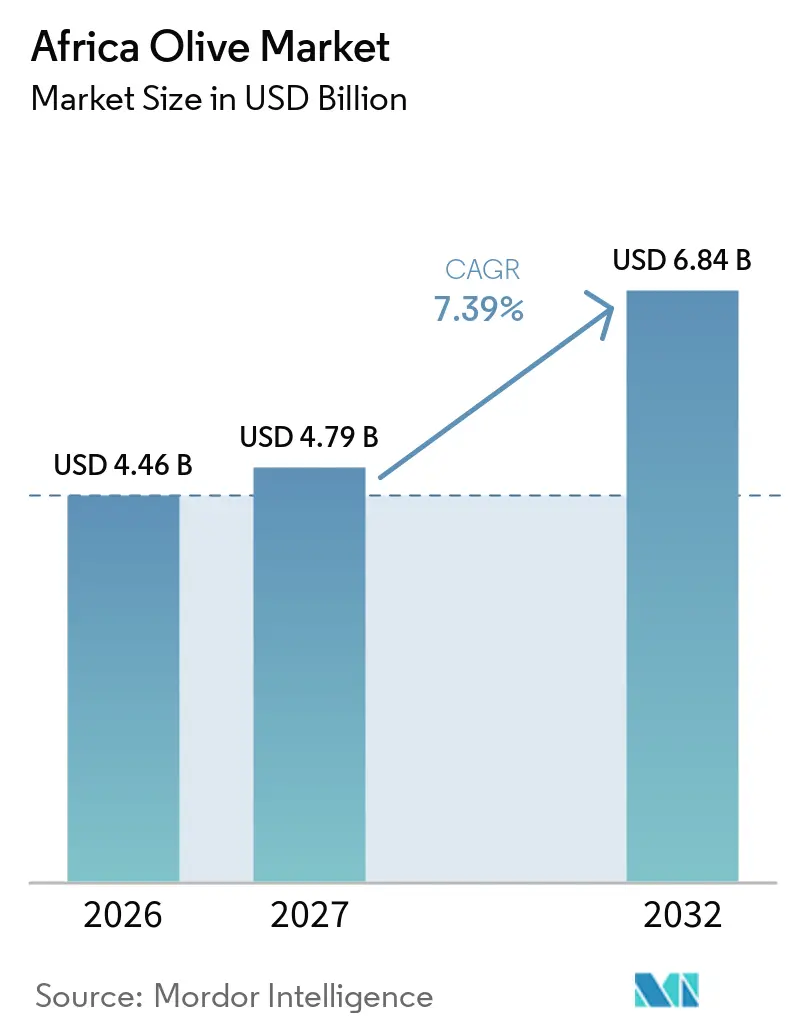
The Africa olives market size was valued at USD 4.46 billion in 2026 and is forecast to grow from USD 4.79 billion in 2027 to USD 6.84 billion by 2032, at a CAGR of 7.39% from 2027 to 2032. Growth is driven by the increasing adoption of modern farming practices and the growing global demand for organic and premium products. North African countries, particularly Morocco, Tunisia, and Egypt, play a significant role in production and exports, supported by favorable trade conditions and large-scale plantation initiatives. Tunisia's strong position in organic certification enhances its premium market positioning, while Algeria is focusing on expanding its cultivation capacity. Technological advancements, including precision irrigation, blockchain traceability, and carbon credit initiatives, are contributing to improved efficiency and value realization. However, climate variability and biological risks continue to pose challenges to long-term stability.
Key Report Takeaways
- By geography, Morocco accounted for the largest share at 28.0% of the Africa olive market size in 2026, whereas Egypt is forecast to be the fastest-growing market with 9.9% CAGR between 2027 and 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Africa Olive Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Health Shift Toward Mediterranean Diets | +1.2% | Morocco, Algeria, and Egypt | Medium term (2-4 years) |
| Subsidized Olive Seedling Programs in North Africa | +1.5% | Algeria, Morocco, and Egypt | Long term (≥ 4 years) |
| Growth in Clean-Label Organic Olive Oil Exports | +1.3% | Tunisia dominant Morocco emerging | Medium term (2-4 years) |
| AI-Driven Precision Irrigation Boosting Olive Yields | +0.9% | Morocco, Algeria, and Tunisia | Short term (≤ 2 years) |
| Blockchain Traceability Premiums in Extra Virgin Olive Oil Exports | +0.6% | Tunisia, Morocco, and Libya | Medium term (2-4 years) |
| Carbon Credit Monetization for Regenerative Olive Farming | +0.4% | Morocco and Tunisia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Health Shift Toward Mediterranean Diets
The growing adoption of Mediterranean dietary patterns is contributing to increased demand for olive-based products in both global and African markets. Olive oil, a central element of this diet, is appreciated for its health benefits, such as cardiovascular support and nutritional value. This shift in consumer preferences is influencing both domestic consumption and export demand for olives and olive-derived products. According to the International Olive Council, the Mediterranean diet is projected to remain widely acknowledged as one of the healthiest dietary patterns globally in 2025, underscoring the importance of olives in health-oriented consumption trends [1]. This is increasing olive demand by driving health awareness and boosting the consumption of table olives among health-conscious consumers worldwide.
Subsidized Olive Seedling Programs in North Africa
Government-supported olive seedling programs in North Africa are playing a crucial role in enhancing the region's long-term supply capacity and export competitiveness. Algeria’s Ministry of Agriculture has set a target to expand olive cultivation to 1 million hectares by 2030. As of 2024, olive groves span approximately 443,000 hectares, with over 65 million productive trees nationwide [2]. These efforts aim to increase farmer incomes, optimize land use, and solidify Algeria's position as a model for olive sector development in the region.
Growth in Clean-Label Organic Olive Oil Exports
The growing demand for clean-label and traceable food products is boosting the competitiveness of African olive exporters in international markets. Producers are focusing on obtaining organic certifications and emphasizing quality differentiation to access premium segments, particularly in Europe. Tunisia plays a significant role in this development, benefiting from strong export connections and established trade networks. According to Tunisienumerique, Tunisia accounted for 27.9% of global olive oil exports during the 2024–2025 season, with total exports amounting to 226,472 metric tons. This underscores Tunisia's prominent position in premium export markets and highlights the critical role of certified and traceable products in driving demand.
AI-Driven Precision Irrigation Boosting Olive Yields
The implementation of precision agriculture technologies is significantly impacting olive cultivation in water-stressed regions of Africa. Farmers are adopting sensor-based irrigation systems and digital tools to optimize water usage, enhance crop management, and boost productivity. These technologies facilitate improved decision-making by providing real-time data on soil moisture and plant health. With increasing climate variability, precision irrigation is becoming crucial for sustaining yields and minimizing resource wastage. This development is especially vital in North Africa, where effective water management is essential for ensuring long-term agricultural productivity and resilience.
Restraints Impact Analysis of Africa Olive Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Climate-Change-Induced Drought Cycles | -1.8% | Morocco dominant, Algeria and Tunisia moderate | Short term (≤ 2 years) |
| International Olive Oil Price Volatility | -1.1% | Global effect on North African exporters | Short term (≤ 2 years) |
| Limited Cold-Pressing Capacity Outside North Africa | -0.7% | Libya, Egypt, and rest of Sub-Saharan Africa | Medium term (2-4 years) |
| Threat of Xylella fastidiosa Spread Into Maghreb Groves | -0.5% | North Africa core with catastrophic tail risks | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Climate-Change-Induced Drought Cycles
Climate change-driven drought cycles are directly affecting the stability of olive production in North Africa. Recent industry data indicates that Morocco's olive oil production dropped to 90,000 metric tons in the 2024/2025 crop year, significantly below the five-year average of 141,600 metric tons. This decline is attributed to persistent drought and elevated temperatures. The reduction in yields and disruption of supply consistency underscore water scarcity as a major constraint on olive production and overall market growth in Africa.
International Olive Oil Price Volatility
Global olive oil price fluctuations continue to pose challenges for North African exporters, especially those dependent on bulk trade markets. Price volatility impacts farm-level income and hampers long-term planning, complicating cost management and investment decisions for producers. Additionally, limited downstream processing and branding capabilities constrain the ability to achieve premium pricing, leaving many exporters reliant on external pricing trends. Consequently, producers face heightened vulnerability to changes in international demand and competitive pressures, which can adversely affect profitability and weaken their position within global supply chains.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Geography Analysis
Morocco Olive Market
Morocco accounted for the largest share at 28.0% of the Africa olive market size in 2026. This is supported by robust cultivation infrastructure and favorable trade positioning. The country benefits from established export channels and tariff advantages, enhancing its competitiveness in international markets. However, olive production remains sensitive to climatic variability, particularly drought cycles, which impact output and pricing dynamics. Government programs focusing on irrigation efficiency and yield improvement are bolstering resilience. Domestic consumption remains significant, balancing local demand with export supply, while ongoing modernization efforts are projected to support long-term production stability across key olive-growing regions.
Egypt Olive Market
Egypt is forecast to be the fastest-growing market with a 9.9% CAGR from 2027 to 2032, driven by large-scale plantation programs and increasing domestic demand for olive products. The country is transitioning from import dependency to strengthening its domestic supply base and export potential. Expansion in olive tree cultivation is projected to enhance production capacity and support the growth of the processing industry. A key indicator is Egypt’s high table olive consumption, which accounted for 540,000 metric tons in the 2024–2025 season, according to the International Olive Council[3]. This reflects strong domestic demand and supports long-term market expansion, alongside increasing investments in processing and export capabilities.
Tunisia Olive Market
Tunisia continues to be a major export-oriented market, leveraging its strong processing infrastructure and established trade relationships with international buyers. The country plays a critical role in supplying bulk olive oil to global markets, although limited branding capabilities constrain value capture. Government initiatives aimed at enhancing export diversification and logistics are improving market access beyond traditional destinations. Precision irrigation and sustainable farming practices are gaining prominence as Tunisia seeks to expand cultivated areas while managing water resources efficiently. These advancements are strengthening Tunisia’s position as a competitive supplier in the global olive trade.
Competitive Landscape
The Africa olive market features a diverse range of regional producers engaged in cultivation, processing, and export activities. Companies are increasingly strengthening their presence through integrated value chains that link farming, processing, and distribution. North African producers hold a dominant position due to their established infrastructure and proximity to major export markets. However, many producers continue to rely on bulk exports, which limits value capture. A gradual shift toward branded and packaged products is underway, improving positioning in premium segments and enabling differentiation in competitive international markets.
Technology adoption is emerging as a critical factor for competitiveness, with producers investing in precision agriculture, advanced irrigation systems, and modern processing techniques. These innovations enhance productivity, reduce resource consumption, and ensure consistent product quality. Additionally, traceability and certification systems are becoming increasingly important as exporters align with international standards and meet consumer demands for transparency. Companies are also forming partnerships to expand processing capacity and improve operational efficiency. These measures are helping producers address challenges such as climate variability and evolving market requirements while strengthening their competitive edge.
Opportunities are emerging in regions where olive cultivation is expanding, but processing and export infrastructure remains underdeveloped. Producers are focusing on local value addition to minimize dependence on intermediaries and achieve higher profit margins. Investments in storage, milling, and logistics infrastructure are enhancing market access and improving supply chain efficiency. These efforts are driving the growth of branded exports and bolstering competitive positioning in global markets. For instance, in March 2026, Tunisia became the global leader in organic olive cultivation, with approximately 144,000 hectares dedicated to organic olives. This achievement has strengthened its competitive position through certification-driven production and integrated value chains.
Recent Industry Developments in Africa Olive Market
- January 2026: Libya launched the One Million Olive Tree Project in Tarhuna, introducing a linear pivot irrigation approach to olive cultivation. The initiative aims to modernize the country’s agricultural sector, improve water-use efficiency, and support sustainable olive production.
- June 2025: The International Olive Council, in collaboration with the Moroccan government, designated the Marrakesh olive collection, comprising 580 varieties, for protection under the International Treaty on Plant Genetic Resources. The initiative aims to preserve olive genetic diversity for future agricultural research and conservation.
- October 2024: Algeria launched a national olive-planting program in collaboration with the National Chamber of Agriculture (ANCA) to expand cultivation. At the time, the country had approximately 442,900 hectares of olive groves and more than 65 million olive trees, with a target of expanding the cultivated area to 1 million hectares by 2030.
Africa Olive Market Report Scope
A small, oval fruit from the olive tree (Olea europaea), native to the Mediterranean region. Olives are commonly green or black, depending on their ripeness, and are widely used in cooking and food preparation, often for their oil, which is a staple in Mediterranean diets. The Africa olive market report includes production analysis (volume), consumption analysis (value and volume), import market analysis (value and volume), export market analysis (value and volume), wholesale price trend analysis and forecast, regulatory framework, list of key players, logistics and infrastructure analysis, and seasonality analysis. The market is segmented by country (Morocco, Algeria, Tunisia, Egypt, Libya, and the rest of Africa). The market forecasts are provided in terms of value (USD) and volume (metric tons).
Segmentation Overview
By Geography
| Africa | Morocco | Production Analysis (Area Harvested, Yield, and Production Volume) |
| Consumption Analysis (Consumption Value and Volume) | ||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | ||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | ||
| Wholesale Price Trend Analysis and Forecast | ||
| Regulatory Framework | ||
| List of Key Players | ||
| Logistics and Infrastructure | ||
| Seasonality Analysis | ||
| Algeria | Production Analysis (Area Harvested, Yield, and Production Volume) | |
| Consumption Analysis (Consumption Value and Volume) | ||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | ||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | ||
| Wholesale Price Trend Analysis and Forecast | ||
| Regulatory Framework | ||
| List of Key Players | ||
| Logistics and Infrastructure | ||
| Seasonality Analysis | ||
| Tunisia | Production Analysis (Area Harvested, Yield, and Production Volume) | |
| Consumption Analysis (Consumption Value and Volume) | ||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | ||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | ||
| Wholesale Price Trend Analysis and Forecast | ||
| Regulatory Framework | ||
| List of Key Players | ||
| Logistics and Infrastructure | ||
| Seasonality Analysis | ||
| Egypt | Production Analysis (Area Harvested, Yield, and Production Volume) | |
| Consumption Analysis (Consumption Value and Volume) | ||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | ||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | ||
| Wholesale Price Trend Analysis and Forecast | ||
| Regulatory Framework | ||
| List of Key Players | ||
| Logistics and Infrastructure | ||
| Seasonality Analysis | ||
| Libya | Production Analysis (Area Harvested, Yield, and Production Volume) | |
| Consumption Analysis (Consumption Value and Volume) | ||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | ||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | ||
| Wholesale Price Trend Analysis and Forecast | ||
| Regulatory Framework | ||
| List of Key Players | ||
| Logistics and Infrastructure | ||
| Seasonality Analysis | ||
| By Geography | Africa | Morocco | Production Analysis (Area Harvested, Yield, and Production Volume) |
| Consumption Analysis (Consumption Value and Volume) | |||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | |||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | |||
| Wholesale Price Trend Analysis and Forecast | |||
| Regulatory Framework | |||
| List of Key Players | |||
| Logistics and Infrastructure | |||
| Seasonality Analysis | |||
| Algeria | Production Analysis (Area Harvested, Yield, and Production Volume) | ||
| Consumption Analysis (Consumption Value and Volume) | |||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | |||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | |||
| Wholesale Price Trend Analysis and Forecast | |||
| Regulatory Framework | |||
| List of Key Players | |||
| Logistics and Infrastructure | |||
| Seasonality Analysis | |||
| Tunisia | Production Analysis (Area Harvested, Yield, and Production Volume) | ||
| Consumption Analysis (Consumption Value and Volume) | |||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | |||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | |||
| Wholesale Price Trend Analysis and Forecast | |||
| Regulatory Framework | |||
| List of Key Players | |||
| Logistics and Infrastructure | |||
| Seasonality Analysis | |||
| Egypt | Production Analysis (Area Harvested, Yield, and Production Volume) | ||
| Consumption Analysis (Consumption Value and Volume) | |||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | |||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | |||
| Wholesale Price Trend Analysis and Forecast | |||
| Regulatory Framework | |||
| List of Key Players | |||
| Logistics and Infrastructure | |||
| Seasonality Analysis | |||
| Libya | Production Analysis (Area Harvested, Yield, and Production Volume) | ||
| Consumption Analysis (Consumption Value and Volume) | |||
| Import Market Analysis (Import Value, Volume, and Key Supplying Markets) | |||
| Export Market Analysis (Export Value, Volume, and Key Destination Markets) | |||
| Wholesale Price Trend Analysis and Forecast | |||
| Regulatory Framework | |||
| List of Key Players | |||
| Logistics and Infrastructure | |||
| Seasonality Analysis | |||
Key Questions Answered in the Report
How large is the Africa olives market projected to be by 2032?
The Africa olives market is forecast to reach USD 6.84 billion by 2032, growing at a CAGR of 7.39% from 2027 to 2032.
Which country leads Africa olive production?
Morocco accounted for the largest share of Africa olive production in 2026, at 28.0%.
Which country is forecast to experience the fastest market growth?
The Egypt olives market is forecast to grow at a CAGR of 9.9% from 2027 to 2032, the fastest among the countries covered.
Which technology offers the greatest potential to improve near-term yields?
Sensor-based precision irrigation has demonstrated yield gains of 19–38% and water savings of 25% in Moroccan plots.