
Watch Market Analysis by Mordor Intelligence
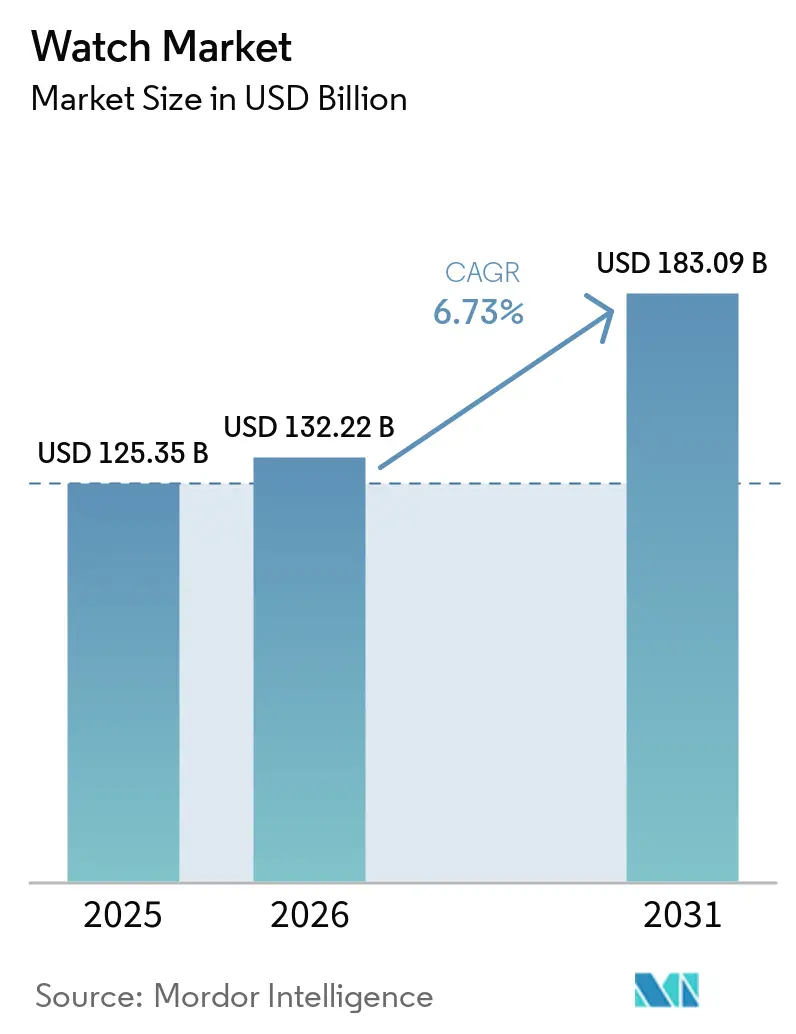
The watch market size was valued at USD 132.2 billion in 2026 and estimated to grow from USD 141.1 billion in 2027 to reach USD 192.3 billion by 2032, at a CAGR of 6.38% during the forecast period (2027-2032).
Health utility in smartwatches and mechanical workmanship give buyers reasons to choose a timepiece, so brands compete on product value. Suppliers selling in Germany and the United Kingdom face a choice about whether a collection’s appeal rests on a function or on the work embodied in its construction. Specialist stores and direct digital purchasing provide different routes for connecting those propositions with watch buyers. Counterfeit alternatives complicate the conversion of buyer interest into branded purchases, while Swiss production costs constrain the economics of mechanical watchmaking. For mechanical-watch suppliers, explaining the production work behind the price becomes consequential because the same workmanship that distinguishes the product also has to earn enough revenue to sustain its manufacture.
Key Report Takeaways
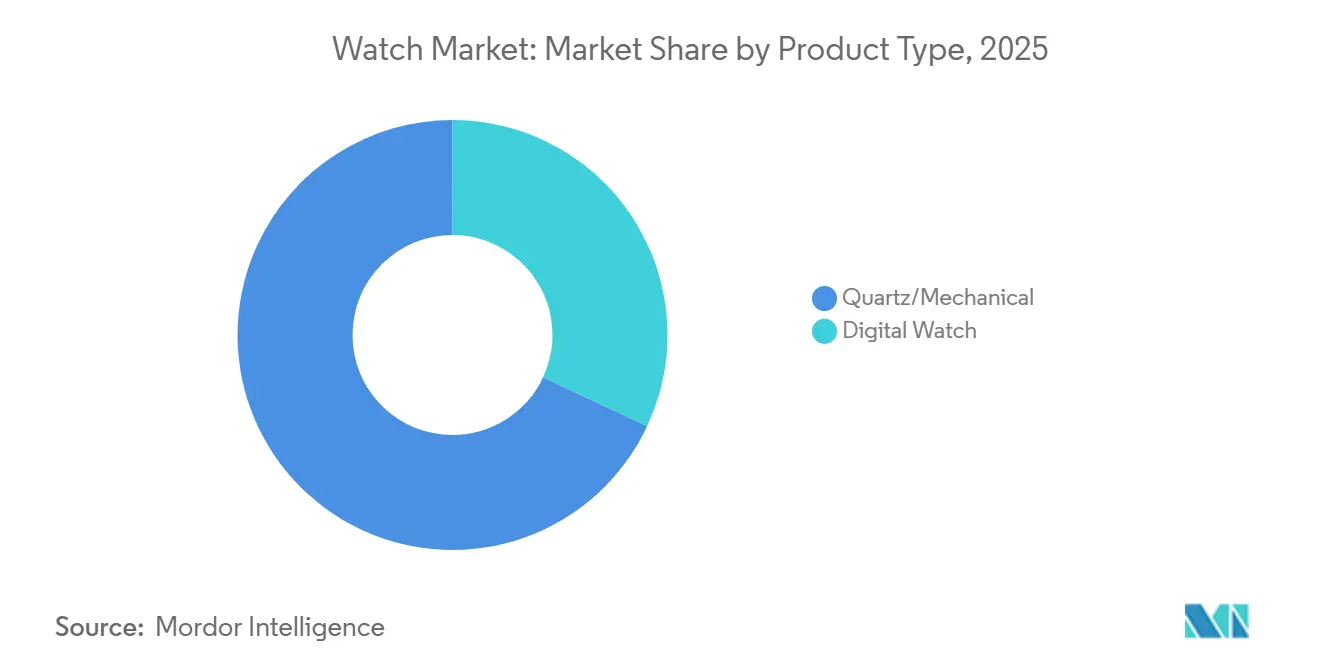
- By product type, quartz/mechanical watches held a 67.89% watch market share in 2026, while digital watches are forecast to be the fastest-growing segment at a 6.85% CAGR during 2027-2032.
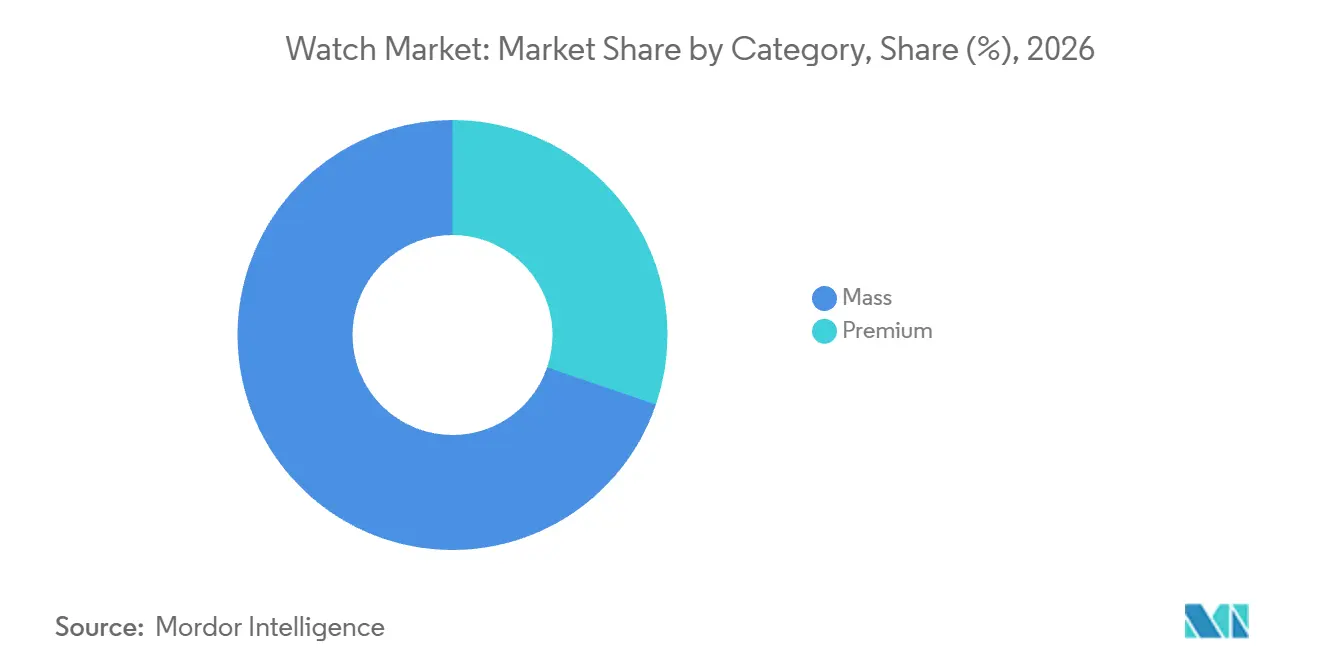
- Mass watches led the category breakdown with a 69.76% share of the watch market size in 2026, whereas premium watches are forecast to grow fastest at a 6.88% CAGR during 2027-2032.
- Men represented the largest end-user segment with a 40.44% revenue share in 2026, and unisex watches are projected to be the fastest-growing segment at a 7.05% CAGR during 2027-2032.
- Across distribution channels, specialty stores led with a 55.51% revenue share in 2026, while online retail stores are forecast to grow fastest at an 8.3% CAGR during 2027-2032.
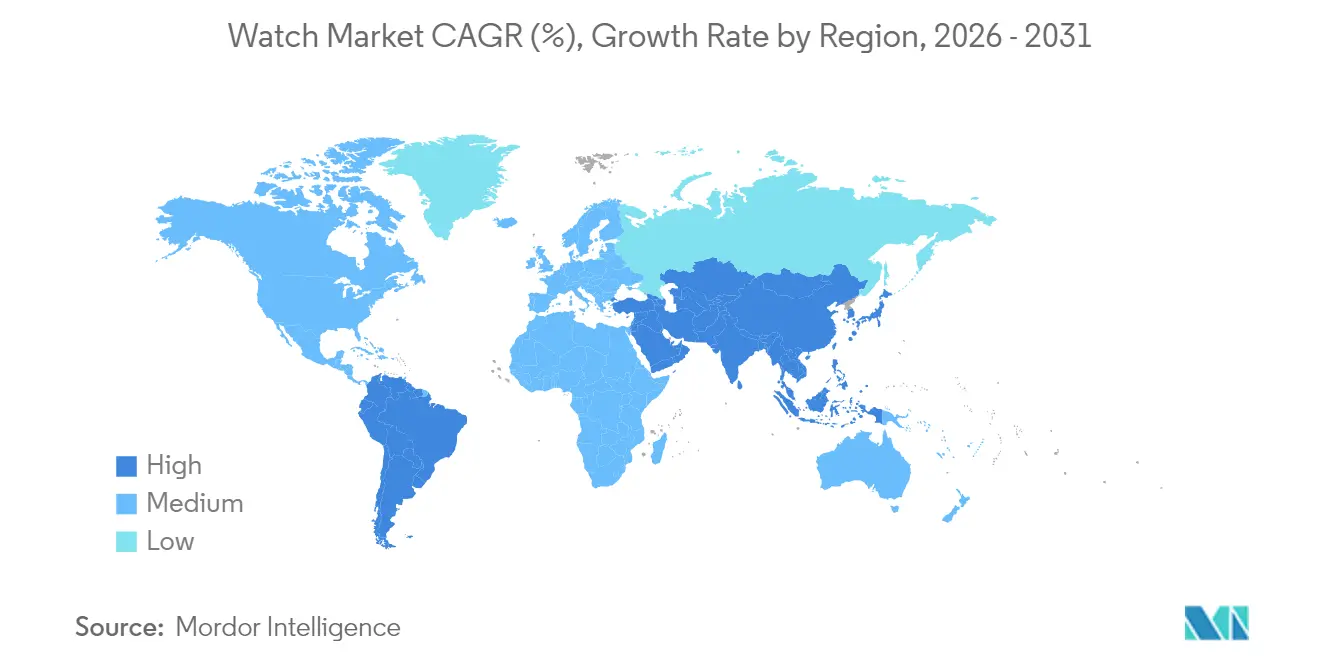
- Asia-Pacific led the geographic breakdown with a 39.49% revenue share in 2026, and South America is projected to be the fastest-growing region at a 7.2% CAGR during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Watch Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Demand for Smartwatches with Health Features | +2.3% | United Kingdom, Germany, France, Poland, and Spain | Medium term (2-4 years) |
| Technological Advancements and Innovation | +1.8% | United States and European Union | Medium term (2-4 years) |
| Increasing Demand For Luxury Watches | +1.6% | United Kingdom and United States | Short term (≤ 2 years) |
| Brand Heritage and Craftsmanship | +1.2% | Switzerland and Germany | Long term (≥ 4 years) |
| Growing Demand For Sports Watches From Fitness Conscious Consumers | +0.9% | North America, Europe, and Asia-Pacific | Medium term (2-4 years) |
| Growing Social Media Influence and Celebrity Endorsements | +0.6% | North America, including Mexico | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising Demand for Smartwatches with Health Features
In Ipsos’s April 2025 survey commissioned by Huawei, 85% of European smartwatch users in 8 surveyed countries said health-related features were important when purchasing smartwatches. The survey covered the United Kingdom, Germany, France, Poland, Spain, Romania, Bulgaria, and Turkey. Because respondents rated health features at the point of purchase, models with defined health functions compete on a criterion that most surveyed users weighed when buying.
Technological Advancements and Innovation
Software innovation can increase a watch’s usefulness while making regulatory eligibility part of its product differentiation. The FDA cleared Apple Inc.’s Apple Watch Hypertension Notification Feature for over-the-counter use on September 11, 2025.[1] Apple released notifications on Apple Watch Series 9 and later and Apple Watch Ultra 2 and later on September 15, 2025, subject to regional availability. The feature analyzes watch sensor data for possible hypertension notifications. It is intended for people aged 22 or older without a prior hypertension diagnosis, excludes pregnancy, and is not intended to replace diagnosis, monitor treatment effects, or provide blood-pressure surveillance. Cleared health notifications add a purchase reason on supported models for eligible buyers seeking that function alongside timekeeping.
Increasing Demand For Luxury Watches
Luxury-watch demand can expand manufacturers’ commercial opportunities through retailers that already convert interest into category revenue. Watches of Switzerland Group plc reported 10% year-over-year growth in luxury-watch revenue for the 53 weeks ended May 3, 2026. Its comparison period comprised 52 weeks ended April 27, 2025. The result covered the retailer’s luxury-watch category across its operations in the United Kingdom, Europe and the United States. Higher spending through this channel supports demand for branded timepieces. For watchmakers, the result shows luxury-watch demand reaching consumers through a retailer that operates across the United Kingdom, Europe and the United States.
Brand Heritage and Craftsmanship
Craftsmanship can sustain demand for mechanical timepieces by giving buyers a production-based reason to value a branded watch beyond time display. Porsche Design Timepieces, whose parent company is Porsche AG, opened its Grenchen, Switzerland, manufactory in March 2026 with 10 watchmaking stations for precision mechanical production.[2] On March 11, 2025, the Dresden Chamber of Industry and Commerce recognized A. Lange & Söhne’s training at its Glashütte, Germany, manufactory, which had 48 apprentices across 6 occupations. The facility and training program address different parts of craft-led supply, with workstations providing the production setting and apprenticeships developing the people who can sustain it. Porsche Design’s new workstations and Lange’s apprentice cohort give the craft claim a physical basis that brands can show buyers weighing a mechanical watch against a digital one.
Restraints Impact Analysis of Watch Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Availability of Counterfeit Products | -0.7% | Europe, including the United Kingdom | Short term (≤ 2 years) |
| Surge in Demand For Smart Wearables | -0.6% | United States and Europe | Medium term (2-4 years) |
| High Production Cost Associated With Luxury Watches | -0.4% | Europe, including Switzerland | Long term (≥ 4 years) |
| Fluctuating Raw Material Prices | -0.3% | Asia-Pacific, including China | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Availability of Counterfeit Products
Counterfeit availability creates demand leakage when buyers would otherwise consider purchasing a genuine branded watch. In the UK Intellectual Property Office’s 2025 survey, 30% of knowing counterfeit-watch buyers said they would buy from the brand if counterfeits were unavailable.[3] The watch category included smartwatches, and the survey base comprised 85 people who had knowingly purchased counterfeit watches. Another 27% said they would choose a cheaper alternative, revealing a different commercial problem within the same buyer population. For legitimate brands, the responses distinguish potential recovered demand from purchases that would migrate toward lower-priced substitutes. Counterfeit removal alone therefore leaves a price-sensitive group that genuine brands cannot assume will convert at their existing price points.
Surge in Demand For Smart Wearables
Smart wearables create a substitution risk for quartz and mechanical watchmakers when a buyer wants digital functions from the device worn on the wrist. The constraint is the choice of wrist-worn product, since a purchase directed toward a smartwatch can displace a separate traditional-watch purchase. For a traditional-watch supplier, that choice makes functional relevance part of the commercial challenge even when the product competes on design or craftsmanship. Distinctive mechanical or design positioning can give a buyer a reason to retain a separate watch. The remaining exposure is deferred traditional-watch demand whenever the buyer treats the smart wearable as sufficient for the same wrist-worn role.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Watch Market Segment Analysis
By Product Type:
Mechanical Scale Meets Digital AdoptionQuartz/mechanical watches accounted for a 67.89% share of the watch market size in 2026, making them the largest product-type segment. The Federation of the Swiss Watch Industry reported 5.21 million mechanical wristwatches exported from Switzerland in 2025. Mechanical wristwatches shipped abroad in that volume show that Swiss producers’ output reaches overseas distribution and does not depend on domestic demand alone.
Digital watches are forecast to be the fastest-growing product segment, with a 6.85% CAGR during 2027-2032. In February 2026, 37% of U.S. adults reported owning a smartwatch. Ownership was 44% among both adults ages 18 to 29 and those ages 30 to 49, compared with 35% among adults ages 50 to 64. Lower ownership among adults ages 50 to 64 leaves proportionally more headroom to add owners than in either surveyed cohort under 50.

By Category:
Core Entry-Level Lines Support ScaleMass watches represented a 69.76% watch market share in 2026, making them the largest category segment. Casio reported higher Timepiece Business sales in the year ended March 31, 2026, and strong CASIO WATCH sales worldwide. Sales of its G-SHOCK 5000, 5600, and 2100 series remained firm under a strategy focused on standard, entry-level models. This connects mass-category demand with defined core lines, giving the producer a specific commercial focus within the entry-level part of its range. Higher timepiece sales alongside firm core-series sales show that Casio’s expansion was compatible with maintaining a standard, entry-level proposition.
Premium watches are forecast to be the fastest-growing category segment, with a 6.88% CAGR during 2027-2032. In the year ended March 31, 2026, Richemont’s Specialist Watchmakers recorded 1% sales growth at constant exchange rates. Sales fell 4% at actual exchange rates over the same period. Strong growth in the Americas compensated for declines in Richemont’s Asia-Pacific and Japan business areas. Regional mix therefore set the direction of the division’s constant-rate result, with the Americas offsetting Asia-Pacific and Japan.
By End User:
Private Buyers Reinforce Demand Beyond Dealer ActivityMen were the largest end-user segment, accounting for 40.44% of market revenue in 2026. Roseberys reported that men represented 69% of its private watch buyers across its December 2024 to August 2026 auctions. Men also accounted for 71% of all watch buyers at the auction house, including its trade-dealer clientele. The male majority persisted in the private-buyer population, showing that Roseberys’ male skew extended beyond its trade-dealer clientele.
Unisex watches are forecast to be the fastest-growing end-user segment, with a 7.05% CAGR during 2027-2032. Timex and Dimepiece’s gender-neutral Intrepid 1995 reissue sold out shortly after its spring 2025 release. Dimepiece proposed the rerelease to Timex, which produced the collaboration.
By Distribution Channel:
Specialist Choice Connects With Digital TransactionsSpecialty stores were the largest distribution-channel segment, with a 55.51% share of market revenue in 2026. In Deloitte’s 2025 survey of consumers in Switzerland and top Swiss watch export markets, 38% preferred multi-brand stores for watch purchases, compared with 23% favoring mono-brand boutiques. The multi-brand format creates a route to selling across different watchmakers within a specialist retail environment. Mono-brand boutiques concentrate the watch proposition on a single brand, creating a different retail identity within the broader specialist channel. The preference balance gives multi-brand operators a reason to preserve cross-brand choice as a specific advantage when developing their store experience.
Online retail stores are forecast to be the fastest-growing distribution segment, with an 8.3% CAGR during 2027-2032. Among watch brands and retailers surveyed by Deloitte in 2025, two thirds reported that online channels represented around 10% of their sales. Watches of Switzerland Group launched an updated Hodinkee app enabling direct online purchases toward the end of FY26, which ended May 3, 2026. Online therefore starts from a modest base in surveyed brands’ and retailers’ sales, so a purchase route in an enthusiast app offers a way to develop that channel. The opportunity includes making existing engagement transactional, giving the retailer a way to present a purchase path to an established watch audience.
Geography Analysis
Asia-Pacific Watch Market
Asia-Pacific held a 39.49% watch market share in 2026, making it the largest regional market. Within the region, Japan’s estimated finished-watch market totaled 17.7 million units in 2025, down 9% from 2024, according to the Japan Clock & Watch Association. For watchmakers entering Japan, that 2025 volume represents a substantial addressable flow of finished-watch purchases, even though the national unit market contracted that year. Asia-Pacific’s 2026 revenue leadership sits alongside Japan’s earlier unit contraction, distinguishing regional revenue scale from growth in a particular national unit market.
South America Watch Market
South America is forecast to be the fastest-growing region, with a 7.2% CAGR during 2027-2032. In Brazil, Grupo Technos sold 679,000 watches in the second quarter of 2026, up 11.4% from the second quarter of 2025. Its average selling price fell 4.8% over the same comparison as its product mix shifted. Increasing unit sales alongside a lower average price makes assortment choices consequential for the revenue generated by each additional watch sold. For suppliers targeting Brazil, expanding physical sales therefore creates a different commercial opportunity from moving customers into more expensive collections, with the mix between those approaches determining revenue per watch.
In North America, Swiss watch exports to the United States fell 14.8% in the first half of 2026 against a high comparison base following the surge after additional tariffs were announced in April 2025. In Europe, first-half 2026 Swiss watch exports rose 5.8% to the United Kingdom and fell 10.5% to Germany, while French routing reflected re-exports elsewhere on the continent. Within the Middle East and Africa, Swiss watch exports to the Middle East fell 2% in that period, while the United Arab Emirates gained 1.6%. In South Africa, Shemer opened a combined fine-watch and jewelry flagship boutique at Nelson Mandela Square in Sandton in 2025. These differences favor country-specific distribution choices because destination shipments, re-export routing, and specialist retail openings create different routes to serving watch buyers.
Regulatory Framework and Outlook
This comparison examines selected jurisdictions from the perspective of watch manufacturers facing product standards, battery obligations, and connected-device market access. The United States’ Consumer Product Safety Commission is assessing UL 4200A-2026 following a September 2026 consultation, while the operative rule incorporates UL 4200A-2023. China’s recommended standard for analog quartz watches, GB/T 6044-2025, took effect on May 1, 2026, replacing the 2016 edition. The commercial distinction is between a voluntary product benchmark and mandatory procedures that apply when a watch falls within a battery or telecom rule’s scope.
Regulatory Table of Watch Market
| Decision factor | United States | Germany | China | Brazil | Saudi Arabia |
|---|---|---|---|---|---|
| Primary authority | Consumer Product Safety Commission | Länder market-surveillance authorities; Stiftung ear for battery-producer registration | Standardization committee TC 160, supervised by the China National Light Industry Council | Agência Nacional de Telecomunicações, Anatel | Communications, Space and Technology Commission, CST |
| Key instruments or direction | 16 CFR Part 1263 and UL 4200A-2023 for covered button- or coin-battery products | EU Batteries Regulation Article 11 from February 18, 2027; BattDG producer registration; adopted wearable derogation takes effect 20 days after Official Journal publication | Recommended GB/T 6044-2025 for analog quartz watches | Resolution 715/2019 homologation; Resolution 780/2025 platform and listing-seller responsibility | Telecom and Information Technology Bylaw Article 89 for covered telecom watches |
| Commercial effect | Safety compliance for covered products; compliant toys and zinc-air batteries excluded | Battery-design work for covered products; registration for qualifying battery producers; wearable derogation requires necessity for user and device safety | Voluntary product-standard benchmark | Homologation for commercial sales of covered telecom watches; listing sellers and involved platforms, including advertising-only platforms, are jointly responsible for code disclosure and verification | Approval and applicant-funded testing by a CST-approved body before covered market activity |
| Current policy attractiveness | Medium | Medium | High | Medium | Medium |
| Future direction of policy attractiveness | No change | Hardening | No change | No change | No change |
| Source: Mordor Intelligence | |||||
The United States’ operative safety rule supports Medium attractiveness and continuity, while China’s implemented voluntary benchmark supports High attractiveness for the selected analog-quartz standard. The EU Batteries Regulation’s removal and replacement duty, which applies from February 18, 2027 to products incorporating portable batteries placed on the German market and is subject to exceptions, supports Hardening, while the European Commission’s July 2026 adopted wearable derogation awaits entry into force. The exemption would allow batteries replaceable only by independent professionals in wearables too small for safe user replacement or requiring sealed construction if user access may compromise safety, durability, or water resistance. Brazil’s commercial homologation route and Saudi Arabia’s approval and applicant-funded testing create upfront compliance work, supporting Medium ratings and continuity in these operative access procedures.
Value Chain Stages
Value capture differs across movement supply, finished-watch manufacturing, and watch retail, reflecting the capability each stage contributes. ETA produces quartz and mechanical movements, while Sellita supplies mechanical movements and Citizen Watch Co., Ltd.’s MIYOTA business makes movements in Japan for watch brands worldwide. This separation lets movement expertise support multiple finished-watch businesses while leaving product development, brand execution, and customer relationships as distinct commercial responsibilities.
Value Chain Analysis Table of Watch Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Movement manufacture and supply | Movement manufacturers such as ETA, Sellita, and Citizen Watch Co., Ltd.’s MIYOTA business | Movement sales | Dependence on specialized movement-making capability | Develop alternative qualified movement-supply routes |
| Finished-watch manufacture | Watch manufacturers such as Seiko Watch Corporation | Finished-watch sales | Coordinating watch development with manufacturing execution | Release collections against verified manufacturing readiness |
| Watch retail | Watch retailers such as Watches of Switzerland and Bucherer, part of Rolex since 2024 | Retail watch sales | Sustaining ownership support alongside showroom selling | Connect sales channels with defined servicing routes |
| Source: Mordor Intelligence | ||||
Watches of Switzerland offers movement servicing, strap replacement, and bracelet adjustment for branded watches. These services extend the retailer’s role into the use and upkeep of a watch after its sale. Linking watch sales with that ownership support gives retailers a way to sustain the customer relationship beyond the initial purchase and makes service execution part of their commercial differentiation.
Competitive Landscape
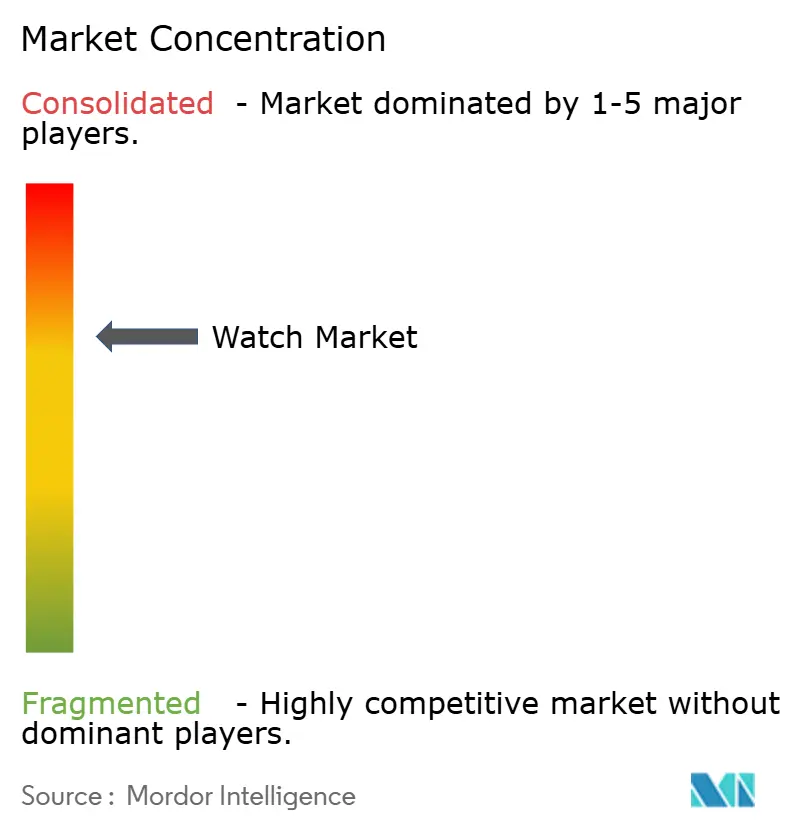
Brand portfolios organize much of the leading competitive field, with The Swatch Group operating brands including Longines, Tissot, and Hamilton. Fossil Group Inc. designs and distributes watches through owned and partner brands, combining brand development with an extensive distribution network. LVMH (Louis Vuitton Moët Hennessy) operates TAG Heuer within its Watches & Jewelry business, connecting its watch presence with a broader luxury portfolio. Compagnie Financière Richemont S.A operates specialist watchmakers including Jaeger-LeCoultre and Vacheron Constantin in a distinct business area. Rolex SA raised U.S. retail prices by an average of 7% on January 1, 2026.
Swatch Group reported that Omega’s global retail sales rose 20% at constant exchange rates in the first half of 2026. Part of that performance was supported by global marketing around Omega’s role as Official Timekeeper of the Olympic Winter Games Milano Cortina 2026. Year-over-year constant-currency sales fell 0.9% for Fossil Group’s traditional watches in its fiscal second quarter ended July 4, 2026, versus 8% growth for Richemont’s Specialist Watchmakers division in the quarter ended June 30, 2026. Alongside Omega’s first-half retail-sales result, these opposing quarterly movements distinguish individual brand and division performance from a uniform competitive upswing.
In June 2025, Samsung Electronics Co., Ltd. expanded its Galaxy Watch Sleep Apnea feature to European Economic Area markets after CE marking and approvals in Australia and Singapore. Its over-the-counter, software-only application detects signs of moderate to severe obstructive sleep apnea over 2 nights using a compatible Galaxy Watch and phone. People under 22 or diagnosed with sleep apnea are excluded, and users are directed to consult qualified health professionals before clinical action because the feature does not replace diagnosis or treatment. These distinct regulatory milestones show why medical-feature positioning depends on jurisdiction-specific clearance as well as watch functionality. Traditional watch groups pursuing comparable functions would need medical-software capabilities alongside their brand portfolios, so competing for health-oriented buyers would require a different development commitment.
Watch Industry Leaders
-
The Swatch Group
-
Fossil Group Inc.
-
LVMH (Louis Vuitton Moët Hennessy)
-
Compagnie Financière Richemont S.A
-
Rolex SA
- *Disclaimer: Major Players sorted in no particular order
Watch Market Companies Covered in this Report
- Rolex SA
- The Swatch Group
- Apple Inc.
- Casio Computer Co., Ltd.
- Fossil Group Inc.
- Citizen Watch Co., Ltd.
- Seiko Group Corporation
- Timex Group B.V.
- Garmin Ltd.
- Samsung Electronics Co., Ltd.
- Titan Company Limited
- Movado Group, Inc.
- Daniel Wellington AB
- LVMH (Louis Vuitton Moët Hennessy)
- Compagnie Financière Richemont S.A
- Xiaomi Corporation
- Patek Philippe SA
- Audemars Piguet Holding SA
- Richard Mille SA
- Breitling
Key Opportunities for Market Participants
The opportunities compare expanded access to luxury watches with product and retail responses to older adults’ smartwatch usability barriers. In September 2026, Watches of Switzerland Group plc said Rolex Glasgow, Betteridge Greenwich, Watches of Switzerland Marlton, and Mayors Marlton showrooms were expected to open before Christmas 2026. In February 2026, 24% of adults ages 65 and older in the United States reported smartwatch ownership. A 2025 IEEE Access study identified small screens and complex smartwatch interfaces as usability barriers for older adults.
Market Opportunities Table of Watch Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Local luxury-watch customer acquisition | Showroom openings expected before Christmas 2026 | Watch buyers near the planned UK and US locations | Build local watch appointments around the additional retail access | Completing openings and converting visits into purchases | Watches of Switzerland Group plc and participating watch brands |
| Easier-to-use smartwatches | A 2026 older-adult ownership base alongside documented interface barriers | Adults ages 65 and older in the United States | Simplify core watch tasks and improve interaction targets | Small screens and complex interfaces | Smartwatch developers such as Apple Inc. and Samsung Electronics Co., Ltd. |
| Assisted smartwatch evaluation | 2026 adoption data and documented interface barriers | Older adults considering a smartwatch | Demonstrate essential watch tasks before purchase and provide an initial setup path | Usability complexity after the initial demonstration | Watch retailers that can pair product selling with guided setup |
| Source: Mordor Intelligence | |||||
The central opening is to make a smartwatch easier for older buyers to evaluate and use through a coherent product and sales experience. A demonstration can reveal whether essential watch tasks are manageable before the buyer commits, while simpler controls address the same difficulty during ownership. Product accessibility and assisted selling therefore reinforce each other, with commercial value depending on whether the watch resolves the interaction problem in everyday use.
Recent Industry Developments in Watch Market
- Jul 2026: The Damiani Group completed its acquisition of specialist watchmaker Baume & Mercier from Richemont after the transaction’s conditions were fulfilled.
- Jun 2026: Casio Computer Co., Ltd. announced the GWR-B3000, a shock-resistant watch in the GRAVITYMASTER line of G-SHOCK with a newly developed movement designed for aircraft-cockpit conditions.
- Mar 2026: Porsche Design opened its new timepieces manufactory in Grenchen, Switzerland, increasing production capacity for its timepieces business.
Watch Market Report Scope and Research Methodology
Market Definition and Coverage
Watch market measures annual global end-user spending on portable timepieces sold as watches, classified by watch type, category, wearer, distribution channel, and geography. Value is counted once at the consumer retail transaction.
Scope exclusions: Fitness bands and other wearable devices not sold as timekeeping watches, stationary clocks, separately sold watch parts and accessories, watch repair and maintenance services, and raw materials sold separately for watchmaking are excluded.
Segments Covered in This Report
- By Product Type
- Quartz/Mechanical
- Digital Watch
- Smart Watches
- Other Digital Types
- By Category
- Mass
- Premium
- By End User
- Men
- Women
- Unisex
- By Distribution Channel
- Supermarkets/Hypermarkets
- Specialty Stores
- Online Retail Stores
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Secondary research would draw on public sources such as the Federation of the Swiss Watch Industry's annual export and import review, which provides trade flows and market signals, the UK Intellectual Property Office's counterfeit-goods research, which informs demand leakage, Pew Research Center's smartwatch ownership survey, which provides an adoption indicator, and Casio's annual results, which offer company-level product and timepiece sales context.
Company filings and investor materials can clarify watch-segment performance, pricing, production, and channel exposure, while reputable press can help date material retail, product, and policy developments. Analysts compare these materials with trade and survey indicators before they inform the market model. These named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include watchmakers, movement suppliers, retailers, distributors, and market specialists, with respondents covering mass and premium watches, digital and traditional products, and major global regions. Analysts would use these discussions to test secondary evidence on retail pricing, channel mix, product demand, and geographic patterns, then investigate gaps through additional source checks or targeted follow-up. Market totals and segment views would be triangulated across respondent perspectives, public company disclosures, trade indicators, and consumer research.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 32% |
| Smaller Players: 25% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
The model would estimate global retail value for complete watches sold to end users, beginning with a top-down view of household spending and watch-category revenue, then checking selected totals against supplier and retailer disclosures and sampled average selling price multiplied by units. Key indicators include disposable income and consumer spending for purchase capacity, watch import and export values for trade movement, company watch revenue for producer and category trends, channel mix for online and specialist retail, and smartwatch ownership for digital-watch adoption. Segment shares would be built from disclosed product and price mixes, retailer channel information, consumer use patterns, and trade evidence, with the same watch sale assigned once across product, category, wearer, channel, and geography views. Forecast value would use scenario analysis to combine expected demand, price and product mix, channel shifts, and regional economic conditions, while public disclosures and market specialists would check whether the variable-level paths are plausible. Where a selective supplier roll-up or sampled price-times-units check is incomplete, analysts would retain the supported components, compare them with independent retail, trade, and company signals, and narrow the estimate only when those checks converge.
Data Validation & Update Cycle
Analysts would triangulate market totals and segment patterns across company disclosures, trade statistics, consumer indicators, and respondent evidence, then investigate outliers and material variances against the underlying source and period before sign-off. A second analyst review would check definitions, units, geographic coverage, duplicate counting, and model assumptions, with re-contact triggered when a respondent's evidence conflicts with public data or a material input remains unclear. The dataset would be refreshed annually, updated between cycles when material events change demand or supply, and given a fresh pre-delivery review.
Mordor Intelligence's Watch Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Watch market measures annual global end-user spending on portable timepieces sold as watches, classified by watch type, category, wearer, distribution channel, and geography.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key indicators include disposable income and consumer spending for purchase capacity, watch import and export values for trade movement, company watch revenue for producer and category trends, channel mix for online and specialist retail, and smartwatch ownership for digital-watch adoption.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 141.1 B (2027) | |
| Global Research Publisher A | USD 69.1 B (2025) | At its 2025 base, this estimate is 51.0% below this report's 2027 value of USD 141.1 B, 2 years later. The 2025 measurement year precedes the report's 2027 comparison year. |
| Global Research Publisher B | USD 48 B (2025) | At its 2025 base, this estimate is 66.0% below this report's 2027 value of USD 141.1 B, 2 years later. Its published luxury-watch category covers a narrower price and product tier than the full watch market. |
Mordor Intelligence's analysts would triangulate market totals and segment patterns across company disclosures, trade statistics, consumer indicators, and respondent evidence, then investigate outliers and material variances against the underlying source and period before sign-off.
Key Questions Answered in the Report
What is the watch market size and growth outlook?
The size is estimated at USD 141.1 billion in 2027 and forecast to reach USD 192.3 billion by 2032, at a 6.38% CAGR during 2027-2032.
Which forces support watch demand?
In Ipsos’s April 2025 survey commissioned by Huawei, 85% of European smartwatch users in 8 surveyed countries said health features were important when purchasing smartwatches. Luxury-watch spending and craftsmanship provide additional commercial supports.
Which watch product type leads revenue?
Quartz/mechanical watches were the largest product-type segment, with a 67.89% revenue share in 2026.
Which companies shape watch competition?
The Swatch Group, Fossil Group Inc., LVMH (Louis Vuitton Moët Hennessy), Compagnie Financière Richemont S.A, and Rolex SA are major competitors.
How do counterfeits affect branded-watch demand?
In the UK Intellectual Property Office’s 2025 survey of 85 knowing counterfeit-watch buyers, 30% said they would buy from the brand if counterfeits were unavailable. The watch category included smartwatches.
Which region leads watch sales and which is forecast to grow fastest?
Asia-Pacific held 39.49% of market revenue in 2026, while South America is forecast to grow fastest at a 7.2% CAGR during 2027-2032.