
Vietnam Furniture Market Analysis by Mordor Intelligence
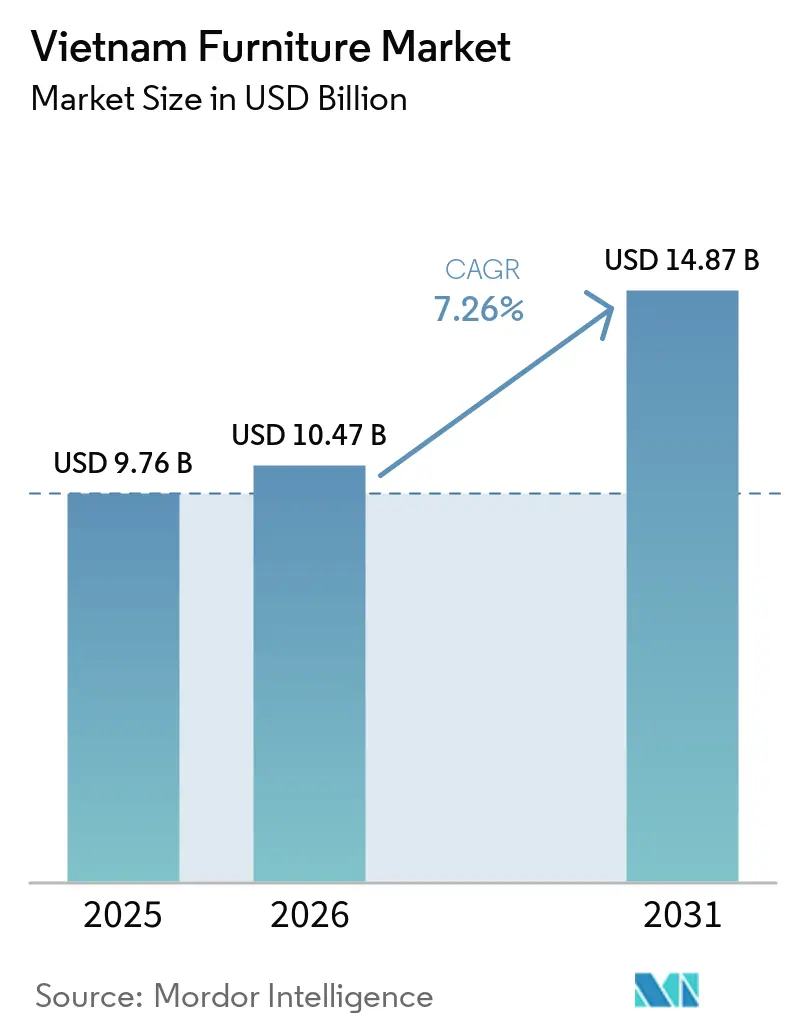
The Vietnam furniture market size was valued at USD 10.47 billion in 2026 and estimated to grow from USD 11.23 billion in 2027 to reach USD 15.62 billion by 2032, at a CAGR of 6.82% during the forecast period (2027-2032).
Vietnam's furniture growth draws on added manufacturing capacity and urban households served through showrooms and assisted digital ordering. Overseas wooden-furniture buyers provide a separate outlet under EU trade access, with freight and documentation adding costs. Middle East conflict disrupted Vietnamese export shipping from March 2026 through Cape of Good Hope rerouting, pressuring deliveries and margins. In the EU, concerns about information system loads and administrative burdens prompted postponement and simplification of the EU Deforestation Regulation from December 2025. The additional preparation time favors suppliers that pair compliance capability with dependable furniture production and customer access.
Key Report Takeaways
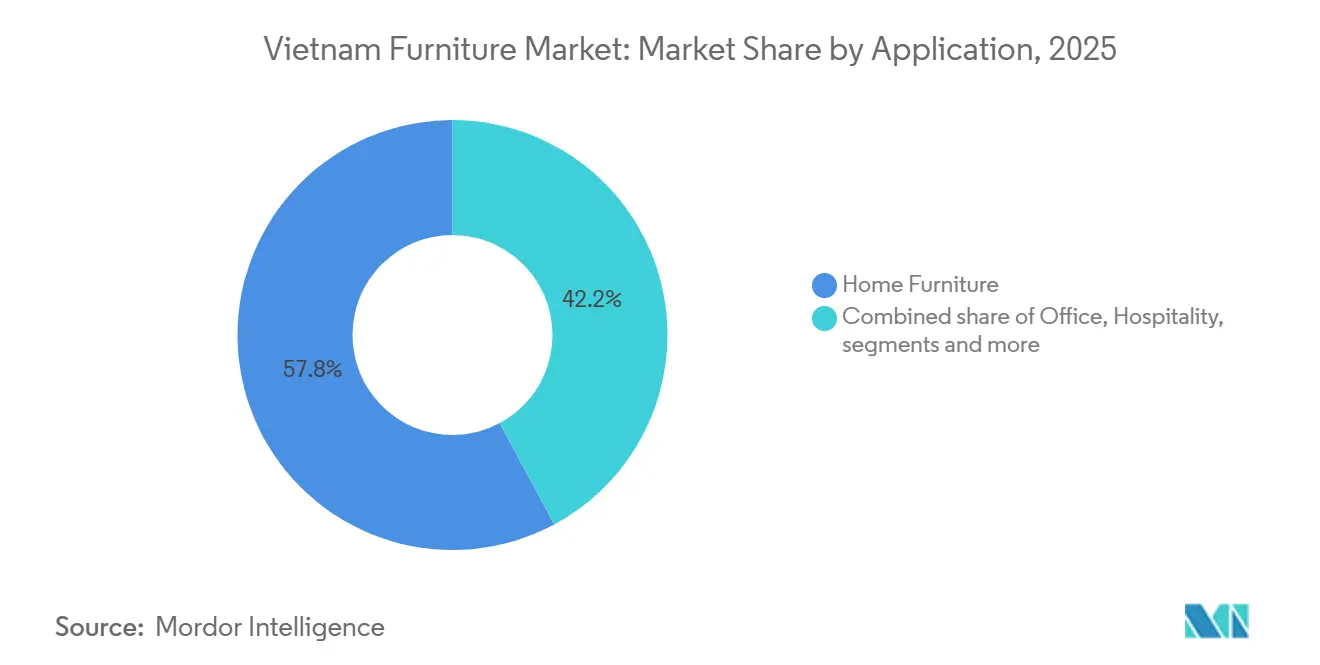
- By application, home furniture led with a 57.73% Vietnam furniture market share in 2026, while hospitality furniture is forecast to grow fastest at a CAGR of 8.4% during 2027-2032.
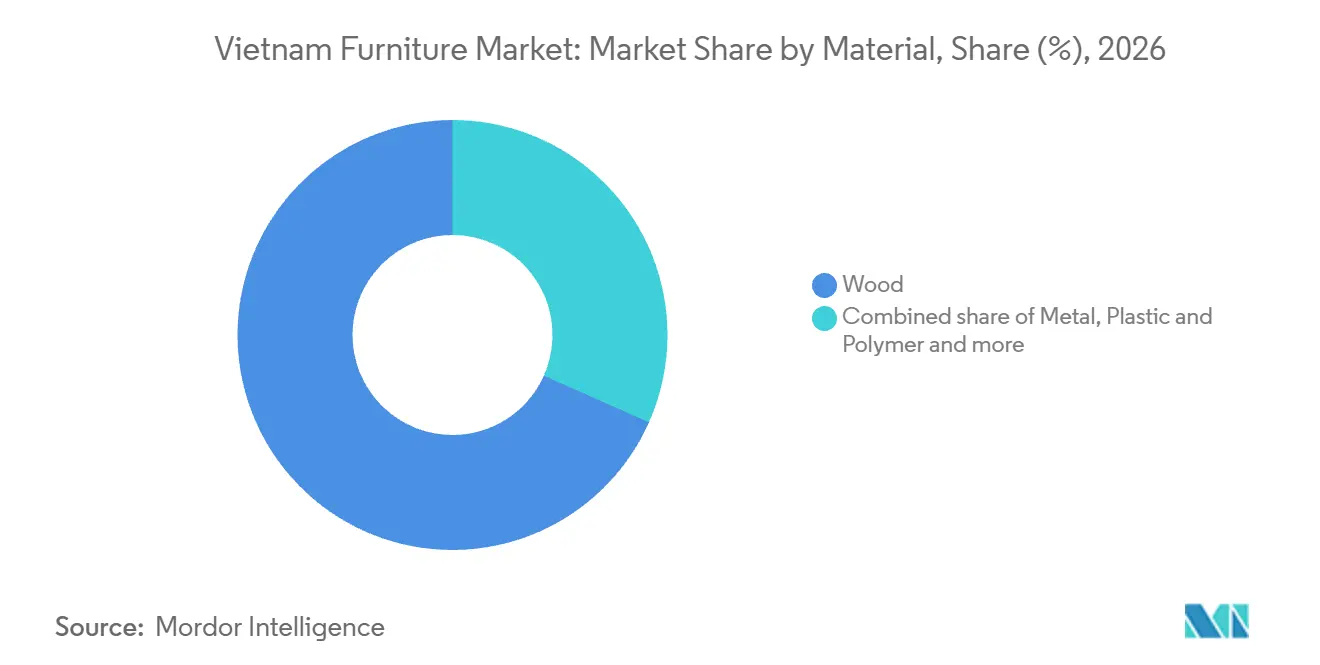
- Wood led the material categories with a 68.34% share of the Vietnam furniture market size in 2026, whereas plastic & polymer is projected to be the fastest-growing segment at a CAGR of 9% during 2027-2032.
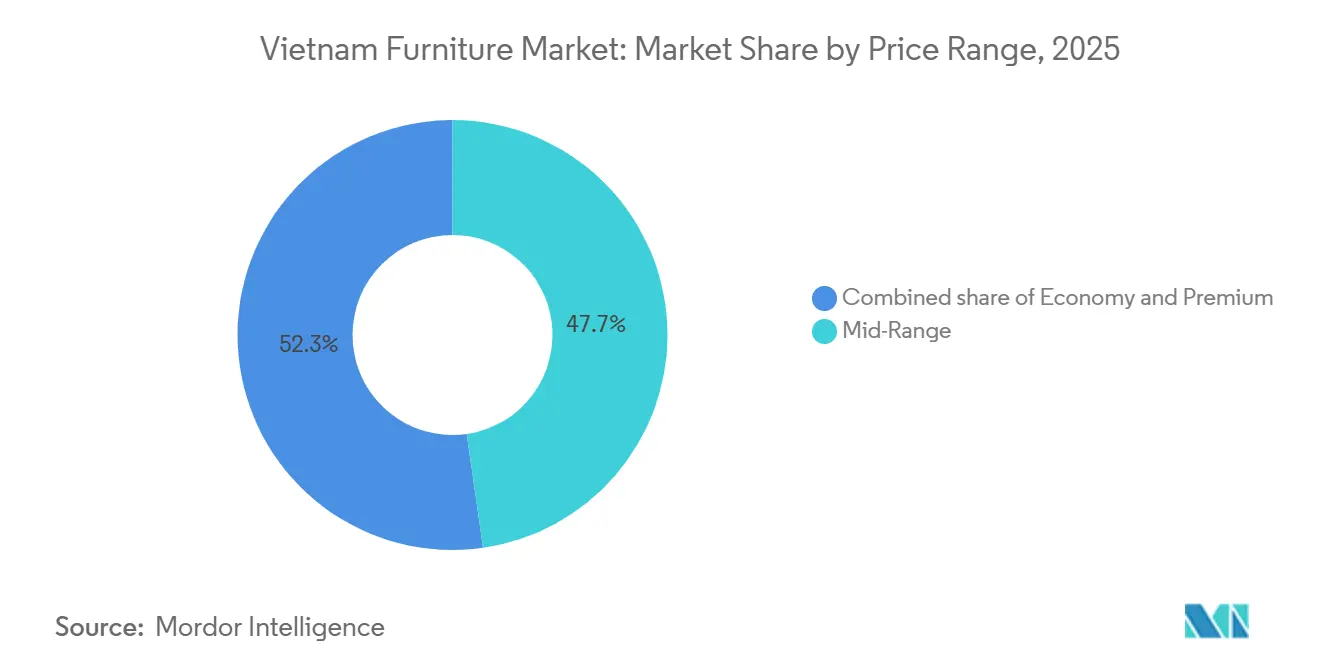
- Across price ranges, mid-range accounted for 47.67% of market revenue in 2026, and premium is forecast to be the fastest-growing segment at a CAGR of 8.5% during 2027-2032.
- B2C/Retail led distribution with 70.02% of market revenue in 2026 and is forecast to be the fastest-growing segment at a CAGR of 7.1% during 2027-2032.
- Southern Vietnam led the geographic breakdown with 52.59% of market revenue in 2026 and is forecast to be the fastest-growing geography at a CAGR of 8.6% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Vietnam Furniture Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| China+1 Strategy Driving Large-Scale Production Capacity Additions | +2.3% | Ho Chi Minh City and Binh Duong | Medium term (2-4 years) |
| Growing Urban Consumer Base Driving Home Furnishing and Interior Upgrades | +2.2% | Ho Chi Minh City and other urban centers | Long term (≥ 4 years) |
| Multilateral Trade Frameworks Unlocking Premium Market Entry Opportunities | +1.8% | Nationwide | Medium term (2-4 years) |
| Digital Commerce Infrastructure Enabling Direct-to-Consumer Distribution Models | +1.5% | Ho Chi Minh City and Hanoi | Short term (≤ 2 years) |
| Commercial Real Estate Pipeline Creating Sustained Institutional Buyer Demand | +1% | Ho Chi Minh City | Medium term (2-4 years) |
| Industry 4.0 Adoption and Automation Driving Production Efficiency and Quality Upgrades | +0.7% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
China+1 Strategy Driving Large-Scale Production Capacity Additions
Production diversification creates demand for Vietnam-based furniture manufacturing when international groups add operating facilities in the country. Jason Furniture (Hangzhou) Co., Ltd. put 2 new furniture production bases in Binh Duong and Ho Chi Minh City into operation in 2025 as it accelerated global capacity deployment. The group's Vietnamese subsidiaries operate these bases within the parent's wider manufacturing organization. KUKA Home announced in July 2025 a planned 43,700-square-meter furniture manufacturing plant in Binh Phuoc as part of shifting more of its capacity to Vietnam. These operating bases and the planned plant show commitments to Vietnamese furniture capacity during 2025, widening the factory base that export buyers can draw on as investments enter production.
Growing Urban Consumer Base Driving Home Furnishing and Interior Upgrades
Vietnam's urban population provides a sizable audience for home-furnishing retailers, creating a commercial role for accessible city stores. Vietnam's urban population was 39.4 million, or 38.6% of the national average population, in 2025.[1] Nitori Holdings opened its fourth Vietnam store, the NITORI Dong Khoi global flagship, in Ho Chi Minh City on April 11, 2025. A dedicated flagship can bring product selection and brand presentation closer to potential household customers, supporting conversion of demographic scale into retail demand. The flagship gives urban households in Ho Chi Minh City a branded point of sale for home furnishings and gives Nitori a direct route to those buyers.
Multilateral Trade Frameworks Unlocking Premium Market Entry Opportunities
Trade frameworks give exporters a defined route for qualifying furniture to reach overseas buyers. Under the EVFTA, the EU tariff schedule lists a 0% duty for qualifying Vietnamese-origin wooden office, bedroom, dining and living room, shop and other wooden furniture. EU import value for wooden furniture from Vietnam rose 11.3% from January to November 2025 compared with the same period in 2024. Vietnam's share of EU wooden-furniture imports rose from 2.5% in January 2025 to 2.8% in January 2026. These trade readings point to an established EU customer base, giving suppliers a route to develop relationships within the access framework. Origin-qualified wooden-furniture suppliers can use that tariff position when competing for EU import orders.
Digital Commerce Infrastructure Enabling Direct-to-Consumer Distribution Models
Online furniture orders provide an additional route to demand even for products handled as bulky goods. Shopee reported that average daily furniture orders in Vietnam nearly doubled in the first half of 2026 compared with the first half of 2025. BAYA displays furniture choices on its website and takes orders by hotline, email, or at its stores. These examples show that expanding digital activity can coexist with assisted selling, giving retailers several ways to receive and convert product interest. BAYA's website-to-staff route keeps direct advice in furniture sales even as Shopee's order growth demonstrates stronger online activity.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Raw Material and Logistics Expenses Squeezing Profitability | -1.2% | Nationwide | Short term (≤ 2 years) |
| Stricter US Customs Scrutiny and Anti-Circumvention Measures Elevating Export Costs | -0.8% | Nationwide | Medium term (2-4 years) |
| Elevated Real Estate Costs and Disjointed Distribution Networks Limiting Retail Expansion | -0.3% | Ho Chi Minh City | Medium term (2-4 years) |
| Evolving Environmental Standards and Trade Regulations Creating Certification Barriers | -0.4% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Raw Material and Logistics Expenses Squeezing Profitability
Middle East conflict disrupted Vietnamese export shipping from March 2026, with vessels rerouting around the Cape of Good Hope. Lam Viet JSC director Nguyen Liem said Cape of Good Hope rerouting raised the company's ocean freight costs for wood exports to the US or Europe by 30-40%, affecting delivery times and profits. For Lam Viet, the constraint extended beyond the freight invoice to delivery commitments. A longer route can erode the margin available to absorb other production expenses. Bao Hung Co., Ltd. production director Phung Quoc Cuong said recycled, environmentally friendly eco packaging reduced packaging costs by about 20% in 2026. That saving addresses packaging expenditure while leaving the exporter exposed to the cost of the shipping route.
Stricter US Customs Scrutiny and Anti-Circumvention Measures Elevating Export Costs
Customs documentation creates an additional cost of serving US furniture buyers even when a factory can meet the product specification. In 2026, US importer TOV Furniture's co-founder and CEO Bruce Krinsky reported well over 100 team hours spent compiling and responding to US Customs documentation requests covering 17 import entries from Vietnam.[2] The reported workload makes staff time part of TOV's cost of sourcing these Vietnam-origin entries. A lower furniture price does not eliminate the work needed to compile a customs response. Cost comparisons for US importers facing similar requests must account for response work as well as the furniture invoice.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Application: Household Scale Meets Hospitality Demand
Home furniture accounted for a 57.73% share of the Vietnam furniture market size in 2026. NITORI FURNITURE VIETNAM EPE's Hanoi factory covers 160,000 square meters and produces storage furniture, bed frames, sofas and mattresses. Those lines span storage, sleeping and seating within one Hanoi operation. A supplier able to combine these categories can address linked room requirements rather than a single furniture item. Bed frames, mattresses and storage can form a bedroom package, increasing the scope available within the largest application.
Hospitality furniture is forecast to be the fastest-growing segment, with a CAGR of 8.4% during 2027-2032. According to Savills, Ho Chi Minh City hotel occupancy exceeded 70% in the second quarter of 2026, driven by international visitors, businesses and meetings, incentives, conferences and exhibitions travel. Different guest purposes can support different furnishing briefs, giving suppliers a reason to develop hospitality offers around how a property operates. Accommodation activity provides a buyer context from which furniture contracts can develop, with the property setting the project brief. Furniture specialists can develop separate guest-room and shared-area packages around that visitor mix, extending a hotel brief beyond beds and storage.

By Material: Wood's Export Base and Polymer Distribution
Wood represented a 68.34% Vietnam furniture market share in 2026. Wooden furniture accounted for nearly 60% of Vietnam's wood and wooden-products export value in 2025. That export weight connects the material's manufacturing base to overseas finished-furniture demand. For manufacturers, the material's importance therefore extends to maintaining an exportable furniture offer across the product families they serve. For suppliers serving overseas buyers, wooden furniture's export role brings freight exposure and, on US-bound orders, potential customs-response costs.
Plastic & polymer is forecast to be the fastest-growing segment, with a CAGR of 9% during 2027-2032. In October 2026, producer and distributor Qui Phúc reported more than 15,000 company-wide sales points nationwide and product categories including plastic chairs, tables and cabinets. That broader network gives the company's plastic-furniture business a potential route to domestic buyers within its wider assortment. In May 2025, the company described furniture production on automated and semi-automated equipment that includes plastic injection. A producer that molds plastic furniture on its own lines and sells through the same company-wide network can shift volume toward plastic products without building a separate retail channel.
By Price Range: Mid-Range Breadth and Premium Production Investment
Mid-range was the largest segment, accounting for a 47.67% share of market revenue in 2026. For urban apartment households in Vietnam, this tier can spread furnishing expenditure across beds, seating and storage while allowing selected material and finish upgrades. Those upgrades add production cost, making their extent across an apartment relevant to the manufacturer's pricing. If wood or freight costs rise, premium specifications across every piece would leave less room to maintain a middle selling price. Standardizing less visible components can preserve room for selected upgrades within a complete apartment package.
Premium is forecast to be the fastest-growing segment, with a CAGR of 8.5% during 2027-2032. Gainwell, a custom hotel-furniture manufacturer, said in August 2026 that its second Vietnam facility, in Quy Nhơn, came online alongside its established Binh Duong plant. Separately, Gainwell Vietnam broke ground on a planned high-end indoor and outdoor furniture factory at Nhơn Hội Industrial Park in Gia Lai on December 25, 2025. Gainwell says its China and Vietnam bases give hotel clients a choice of production origin, a consideration that has grown in importance as tariff and logistics conditions shift. For premium hotel projects, Vietnamese capacity beyond Binh Duong lets Gainwell offer that choice from more than one Vietnamese site.
By Distribution Channel: Retail Scale and Institutional Qualification
B2C/Retail was the largest segment, accounting for 70.02% of market revenue in 2026, and is forecast to be the fastest-growing segment with a CAGR of 7.1% during 2027-2032. Nitori Holdings reported 4 Nitori Group stores in Vietnam at September 2026 month-end. The retail group's business includes furniture and interior goods, providing a basis for a broader household offer within one consumer-facing organization. Nitori Group manufactures furniture as well as selling it, so its Vietnam stores extend a producer directly into household sales.
B2C/Retail also includes BAYA's staffed confirmation of stock and price before customers place orders. In B2B /Project business, furniture specifications can become part of a formal qualification process before supplier selection. In 2026, An Binh Ward's project management unit in Can Tho completed supplier selection for public-school teaching equipment, after bidders sought clarification on student desk-and-chair material-testing requirements. The furniture-related clarification shows how a project route can involve technical questions that bidders must address in preparing their offer. Relative to consumer retail, the project channel makes interpretation of an institutional brief and technical qualification central to the furniture supplier's proposition, shaping the capabilities needed to compete for this type of buyer.
Geography Analysis
Southern Vietnam Furniture Market
Southern Vietnam accounted for a 52.59% share of the Vietnam furniture market size in 2026 and is forecast to grow fastest at a CAGR of 8.6% during 2027-2032. In Dong Nai, output of beds, cabinets, tables and chairs increased 24.36% year over year in August 2026. Over January to May 2025, Dong Nai produced 5.43 million beds, cabinets, tables and chairs, up 8.78% from the same period in 2024. For suppliers, this production range creates scope to assemble room-level assortments from a southern manufacturing locality.
Northern Vietnam's hospitality projects illustrate a furniture brief centered on the operational workplaces within a hotel. In the second quarter of 2025, NESTA completed and handed over an interior contract for back-of-house operational office areas at the BRG Group-developed Four Seasons Hotel Hanoi. The package included loose and built-in furniture for that area, plus furniture for technical zones. Such work connects furniture supply to a property's support functions, giving contract manufacturers a role defined by the intended working areas. The completed Hanoi package shows that hotel support areas offer a furniture brief distinct from guest-room fit-outs.
Central Vietnam's institutional furniture needs include the basic task of equipping local schools for student use. In September 2025, Khanh Cuong Commune in Quang Ngai reported that some schools lacked enough student desks and chairs and were temporarily using old ones. Temporary use of old desks and chairs places the need inside existing classrooms rather than in new school construction. For suppliers, this type of requirement can support a desk-and-chair offer focused on adequate student seating and the learning environment's intended use.
Regulatory Framework and Outlook
The selected-jurisdiction comparison examines national rules and Ho Chi Minh City implementation from the perspective of a furniture manufacturer planning plant operations. Decree 05/2025 delegates environmental assessment and permit authority to provincial People's Committees for eligible projects otherwise within ministry jurisdiction, subject to specified exceptions. On August 7, 2026, Ho Chi Minh City issued Công ty TNHH Chế biến Gỗ Hợp Thắng an emissions permit for its 50,000-unit-per-year wooden furniture plant in Tân Hiệp.[3] The plant's wastewater was routed to factory lessor Công ty TNHH MTV Ki Bu's treatment system, which has a capacity of 60 cubic meters per day.
Regulatory Table
| Decision factor | Vietnam | Ho Chi Minh City |
|---|---|---|
| Primary authority | Provincial People's Committees for eligible delegated projects | Department of Agriculture and Environment, through its Environmental Protection Subdepartment |
| Key instruments or direction | Timber Legality Assurance System under Decree 102/2020, amended by Decree 120/2024; environmental assessment and permitting under Decree 05/2025 | Environmental permit 6554/GPMT-SNNMT-CCBVMT, issued August 7, 2026, for Hợp Thắng's wooden furniture plant |
| Commercial effect | Delegated environmental assessment and permitting exclude cross-province projects, marine areas without assigned provincial responsibility and designated inter-provincial wastewater discharges | Air-treatment trials required for the permitted plant; wastewater handled through the lessor's system |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Easing | Easing |
| Source: Mordor Intelligence | ||
Vietnam's Medium rating reflects limited environmental decentralization and timber-legality rules amended in 2024, while Ho Chi Minh City's reflects Hợp Thắng's required air-treatment trials ending 6 months after their start. The Government's draft amendment to the Law on Environmental Protection, proposed in May 2026, would simplify environmental procedures and delegate more authority locally while strengthening environmental-quality controls. On September 22, 2026, it remained a draft scheduled for National Assembly consideration in October 2026. That proposed procedural direction supports Easing in both jurisdictions, while permit eligibility and pollution control shape the manufacturer's compliance task.
Value Chain Stages
The comparison follows custom furniture development, factory production and retail access to distinguish how suppliers capture value. On June 19, 2026, Nhà Xinh, a brand under AKA Furniture, opened a furniture showroom at The Antonia Phú Mỹ Hưng. The opening adds a showroom at the customer-facing end of the chain, where a furniture brand presents its range directly to buyers.
Value Chain Analysis Table
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Custom furniture development | Project furniture developers such as Gainwell | Development embedded in furniture contract revenue | Translating project requirements into repeatable furniture specifications | Agree product scope and samples before production |
| Furniture manufacturing | Furniture producers such as NITORI FURNITURE VIETNAM EPE and teak furniture manufacturers such as Lam Viet JSC | Finished-furniture manufacturing revenue | Coordinating different product families within production | Sequence work around the capabilities needed by each product family |
| Retail distribution | Furniture retailers such as BAYA and Nhà Xinh | Retail furniture sales | Providing physical access while converting interest into orders | Connect showroom access with direct order intake |
| Source: Mordor Intelligence | ||||
Gainwell's development-and-supply role for All Suites Hotel Hoi An / Da Nang spans suite bedrooms, living zones, work and storage areas, and shared spaces. For a provider undertaking both roles, furniture-contract revenue can compensate specification work as well as production. The supplier's earning opportunity extends beyond making individual pieces to resolving how furniture works across the hotel's different room uses.
Competitive Landscape
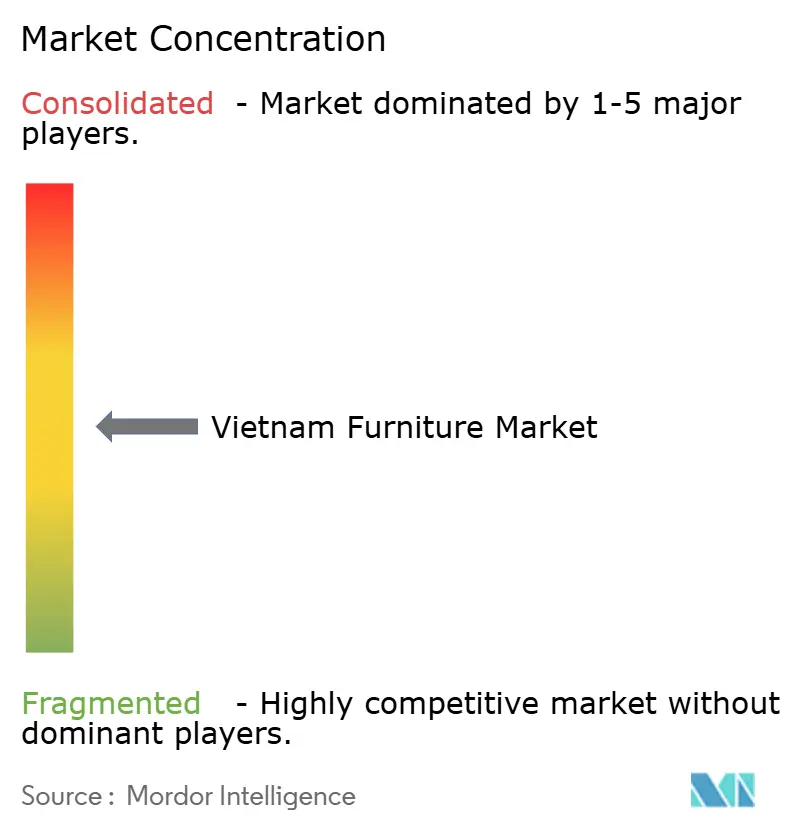
Competition spans manufacturers and project specialists, giving the industry a fragmented structure with several distinct routes to buyers. Duc Thanh Wood Processing JSC reported 2025 consolidated revenue at 99.1% of its 2024 result, and AA Corporation provides bespoke hospitality furniture and fit-out services worldwide. Kaiser 1 Furniture Industry (Vietnam) Co., Ltd manufactures bedroom, living room, dining room and office furniture, plus customized sofas. Tran Duc Furnishings is the hotel-furniture cluster of TranDuc Corporation, while Cam Ha Furniture JSC manufactures indoor and outdoor furniture for homes, restaurants and resorts. This mix leaves supplier selection tied to the furniture application and the scope of production or project responsibility.
Dedicated furniture capacity can be strategically important even when it sits inside a much broader manufacturing investment. On June 23, 2025, TranDuc Corporation broke ground on its Nam Tan Uyen factory in Binh Duong, including a planned 65,000-square-meter hotel-furniture manufacturing zone. The announced project's wider scope included timber components, modular homes and accessories, making the dedicated hotel-furniture zone one part of the investment. The planned hotel-furniture zone places Tran Duc Furnishings in the same project-buyer segment as AA Corporation, which also supplies hospitality projects.
Competitors differ in how much of a furniture package they take on and in the credentials they hold. In 2025, ARES Vietnam awarded Kaiser 1 Furniture Industry (Vietnam) Co., Ltd ISO 9001:2015 quality-management and ISO 14064-1:2018 greenhouse-gas quantification and reporting certifications. Those credentials give buyers defined quality-management and emissions-reporting standards to assess. The EU Deforestation Regulation's legality and traceability conditions for covered wooden furniture are separate from what these quality and emissions certificates cover. AA Corporation's combined furniture-and-fit-out offer supports a broader hospitality contract, while Cam Ha Furniture JSC's manufacturing role suits a narrower furniture-supply package for resort and restaurant buyers.
Vietnam Furniture Industry Leaders
-
Duc Thanh Wood Processing JSC
-
AA Corporation
-
Kaiser 1 Furniture Industry (Vietnam) Co., Ltd
-
Tran Duc Furnishings
-
Cam Ha Furniture JSC
- *Disclaimer: Major Players sorted in no particular order
Key Opportunities for Market Participants
The comparison assesses opportunities around EU-ready wooden furniture, school desk-and-chair fit, and furnishing new high-end apartments. Under the EU's deforestation rules, large and medium operators, and micro or small operators already covered by the EU Timber Regulation, face application from December 30, 2026. Other micro and small operators face June 30, 2027. Vietnamese suppliers of specified new wooden furniture can help the relevant EU-market operator meet deforestation-free, legal-production and declaration conditions.
Market Opportunities Table
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| EU-ready wooden furniture supply | Preparation window before phased EU application | EU-market operators buying covered new wooden furniture | Supply furniture with information supporting the buyer's due diligence | Documenting lawful, deforestation-free wood supply | Wooden-furniture makers able to support EU operators' due diligence |
| Height-matched school desks and chairs | August 2026 guidance while anthropometric research and standards reviews were pending | General education schools | Match furniture size codes to student heights and classroom conditions, separating repair from purchase needs | Translating each school's review into a furniture brief | School-furniture producers such as Xuan Hoa Furniture |
| Movable-furniture packages for apartment buyers | 1,116 new high-end apartments in Ho Chi Minh City in Q2 2026 | Buyers furnishing high-end apartments in Ho Chi Minh City | Offer coordinated room-level furniture packages with clear pricing | Housing commitments can constrain the furnishing offer | Home-furniture suppliers serving apartment buyers |
| Source: Mordor Intelligence | |||||
School-furniture fit provides the clearest specification-led entry point because a height review can translate into distinct repair and purchase requirements. A supplier that turns those findings into a usable desk-and-chair offer addresses a concrete institutional decision. The repair option limits how much of each review becomes new-furniture demand, making height-matched ranges a targeted sales opening whose volume depends on school-level purchase decisions.
Recent Industry Developments
- Aug 2026: Vietnam's Ministry of Education and Training guided education departments to have general education schools assess student heights and classroom conditions and select, buy, repair and arrange desks and chairs. Anthropometric research and standards reviews were pending when the guidance was issued.
- Aug 2026: Gainwell said its Quy Nhơn facility came online alongside its established Binh Duong plant, expanding its Vietnam production base for custom hotel furniture.
- Jun 2026: Nhà Xinh, a brand under AKA Furniture, opened its furniture showroom at The Antonia Phú Mỹ Hưng on June 19, expanding its physical retail presence.
Research Methodology Framework and Report Scope
Market Definition and Coverage
The Vietnam furniture market measures the annual value of movable furniture sales in Vietnam, including imported furniture sold there, and furniture manufactured in Vietnam for export. Value is counted once when finished furniture is sold for residential, commercial, institutional, or hospitality use.
Scope exclusions: Interior design services sold separately from furniture, construction and fit-out packages, built-in kitchens, wardrobes and fixed joinery, and separately sold furniture materials and inputs are excluded.
Segmentation Overview
- By Application
- Home Furniture
- Chairs
- Tables (side tables, coffee tables, dressing tables, etc.)
- Beds
- Wardrobes
- Sofas
- Dining Tables/Dining Sets
- Kitchen Cabinets
- Other Home Furniture (bathroom furniture, outdoor furniture, etc.)
- Office Furniture
- Chairs
- Tables
- Storage Cabinets
- Desks
- Sofas and Other Soft Seating
- Other Office Furniture
- Hospitality Furniture
- Educational Furniture
- Healthcare Furniture
- Other Applications (public places, retail malls, government offices, etc.)
- Home Furniture
- By Material
- Wood
- Metal
- Plastic & Polymer
- Other Materials
- By Price Range
- Economy
- Mid-Range
- Premium
- By Distribution Channel
- B2C/Retail
- Home Centers
- Specialty Furniture Stores
- Online
- Other Distribution Channels
- B2B /Project
- B2C/Retail
- By Geography
- Southern Vietnam
- Northern Vietnam
- Central Vietnam
Data Sources, Market Sizing, and Validation
Desk Research
Secondary research draws on illustrative public sources such as the National Statistics Office of Vietnam for population, household, construction and price indicators, the Ministry of Industry and Trade for trade policy and export developments, Eurostat trade data cited in ministry reporting for destination-market demand, and International Tropical Timber Organization reporting for wood-product trade and supply conditions. These sources help analysts size demand and export activity, distinguish finished furniture from upstream wood products, and track regulatory or logistics changes relevant to furniture sales.
Company annual reports and filings, investor presentations, association material such as Vietnam Timber and Forest Product Association publications, and reputable business reporting can clarify producer portfolios, channel activity, capacity and investment. These are illustrative sources, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Fieldwork interviews with furniture manufacturers, importers, retailers, project suppliers and institutional buyers, covering commercial, product, sales, sourcing and finance roles, test secondary estimates of domestic sales, export revenue, channel mix, price realization and application demand. Analysts use interview evidence to clarify conflicting definitions or missing inputs, triangulate those explanations against trade, company and channel evidence, and document unresolved gaps for review.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 32% | CXOs: 20% | |
| Mid tier: 48% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
The model estimates Vietnam sales and Vietnam-manufactured furniture exports from a top-down market total, then checks selected applications, material groups, price tiers, channels and regions against supplier, retailer and project evidence. Demand indicators include household formation and housing completions for home furniture, office and hospitality investment for institutional orders, furniture import and export values for traded supply, retail and e-commerce activity for B2C sales, and material and freight costs for price realization. Together these indicators explain demand, channel reach, export activity and value per unit. Analysts develop segment shares from reported sales mixes, trade classifications, company product exposure and buyer evidence, with the same furniture revenue counted once at the finished-product sale. Forecasts use scenario analysis around household demand, commercial investment, export orders, trade access, raw-material costs and channel development, with market totals and segment trends reviewed separately. Selective bottom-up checks use sampled supplier revenue and channel or project checks to test the top-down totals. Interview evidence tests variable assumptions and forecast ranges, while analysts triangulate residual differences with adjacent years, public trade data and comparable company evidence and document them for review.
Data Validation & Update Cycle
Analysts triangulate official trade and economic series, company disclosures, association information and buyer or supplier evidence, checking whether each signal measures finished furniture sales, production or trade. They investigate unusual year-on-year movements, segment shares that do not reconcile, and material differences between independent estimates before sign-off, documenting the cause or seeking clarification from the source or respondent. The team refreshes the model annually, updates it between cycles after material trade, policy or demand events, and completes a fresh source and calculation review before delivery.
Mordor Intelligence's Vietnam Furniture Market Sizing Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Vietnam furniture market measures the annual value of movable furniture sales in Vietnam, including imported furniture sold there, and furniture manufactured in Vietnam for export.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Demand indicators include household formation and housing completions for home furniture, office and hospitality investment for institutional orders, furniture import and export values for traded supply, retail and e-commerce activity for B2C sales, and material and freight costs for price realization.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 11.23 B (2027) | |
| Global Consultancy A | USD 9.76 B (2025) | At its 2025 base, this estimate is 13.1% below this report's 2027 value of USD 11.23 B, 2 years later. The earlier base year can account for a lower value as market activity grows through the intervening period. |
| Industry Journal B | USD 2.5 B (2025) | At its 2025 base, this estimate is 77.7% below this report's 2027 value of USD 11.23 B, 2 years later. Domestic consumption at producer prices excludes export sales and downstream seller value counted in this report. |
Mordor Intelligence's analysts triangulate official trade and economic series, company disclosures, association information and buyer or supplier evidence, checking whether each signal measures finished furniture sales, production or trade.
Key Questions Answered in the Report
What is the Vietnam furniture market size and growth outlook?
It is estimated at USD 11.23 billion in 2027 and forecast to reach USD 15.62 billion by 2032, with a CAGR of 6.82% during 2027-2032.
Which forces support furniture demand in Vietnam?
Urban scale and digital ordering support demand. Vietnam had 39.4 million urban residents in 2025, and Shopee reported that average daily furniture orders nearly doubled in the first half of 2026 compared with the first half of 2025.
Which furniture application has the largest share in Vietnam?
Home furniture led applications with a 57.73% share of market revenue in 2026.
Who are the leading furniture suppliers in Vietnam?
Key companies include Duc Thanh Wood Processing JSC, AA Corporation, Kaiser 1 Furniture Industry (Vietnam) Co., Ltd, Tran Duc Furnishings and Cam Ha Furniture JSC.
What documentation burden can US Customs scrutiny place on importers of Vietnamese furniture?
In 2026, US importer TOV Furniture reported well over 100 team hours compiling and responding to US Customs documentation requests covering 17 import entries from Vietnam.
Which Vietnamese region leads furniture activity and growth?
Southern Vietnam held 52.59% of market revenue in 2026 and is forecast to be the fastest-growing geography at a CAGR of 8.6% during 2027-2032.