
UK Construction Market Analysis by Mordor Intelligence
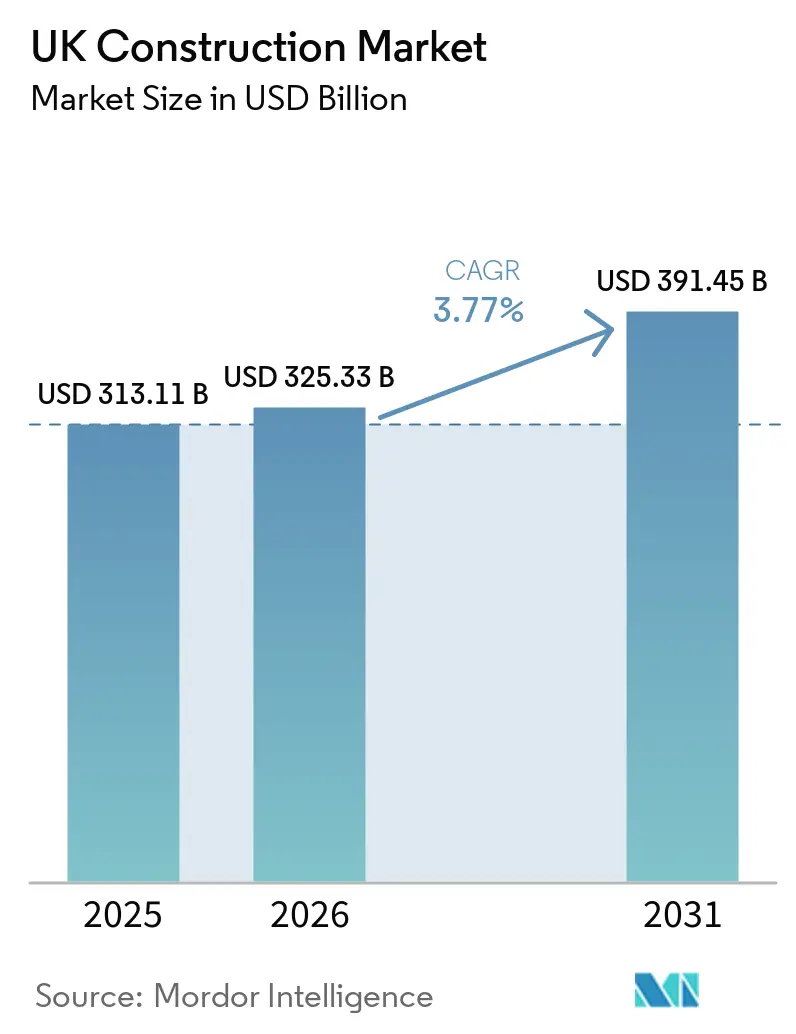
The UK construction market size was valued at USD 325.3 billion in 2026 and estimated to grow from USD 337.6 billion in 2027 to reach USD 402.5 billion by 2032, at a CAGR of 3.58% during the forecast period (2027-2032).
Public construction programs and funded upgrades to existing homes create complementary routes to demand in England. Yet the work contractors can turn into delivery depends on skilled-trades availability and their ability to manage supply-cost uncertainty. Modular procurement and repeatable building designs offer ways to organize public facilities and multi-site projects around defined construction packages. Competitive responses also connect project delivery with maintenance capabilities and supply-chain competency assurance. Contractors that secure scarce trade capacity and contain material-cost exposure are better placed to convert England’s funded public programs and social-housing retrofits into completed work.
Key Report Takeaways
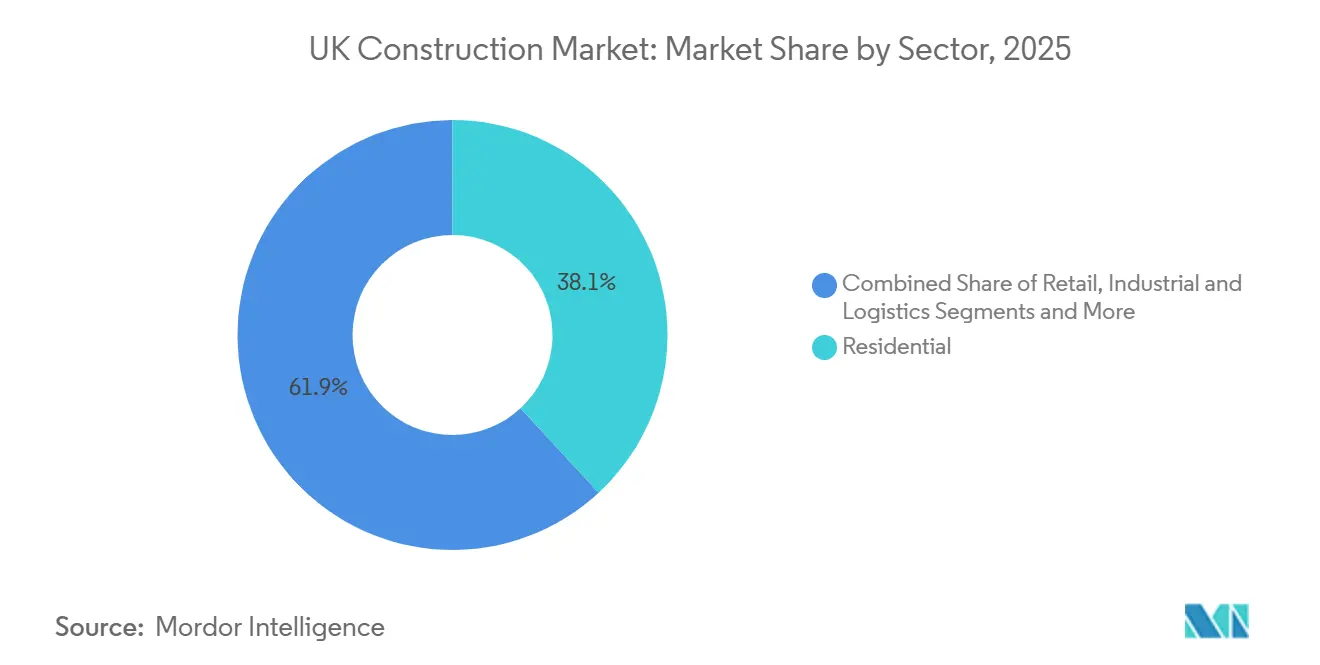
- By sector, residential held a 37.63% UK construction market share in 2026, while infrastructure is forecast to grow fastest at a 7.3% CAGR during 2027-2032.
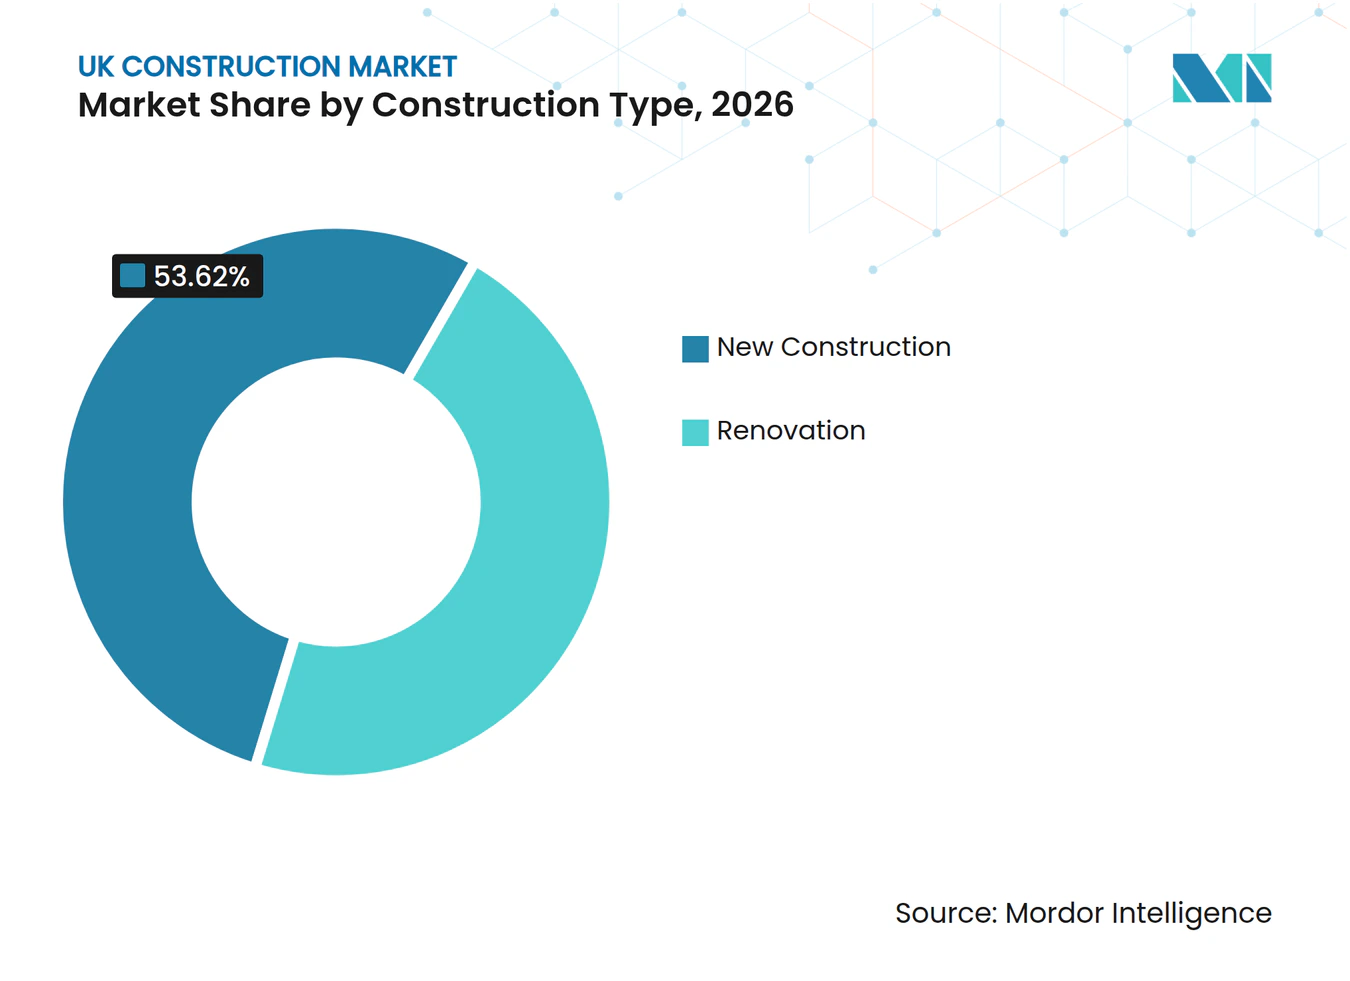
- Within construction type, new construction accounted for a 53.62% share of the UK construction market size in 2026, and renovation is forecast to grow fastest at a 6.9% CAGR during 2027-2032.
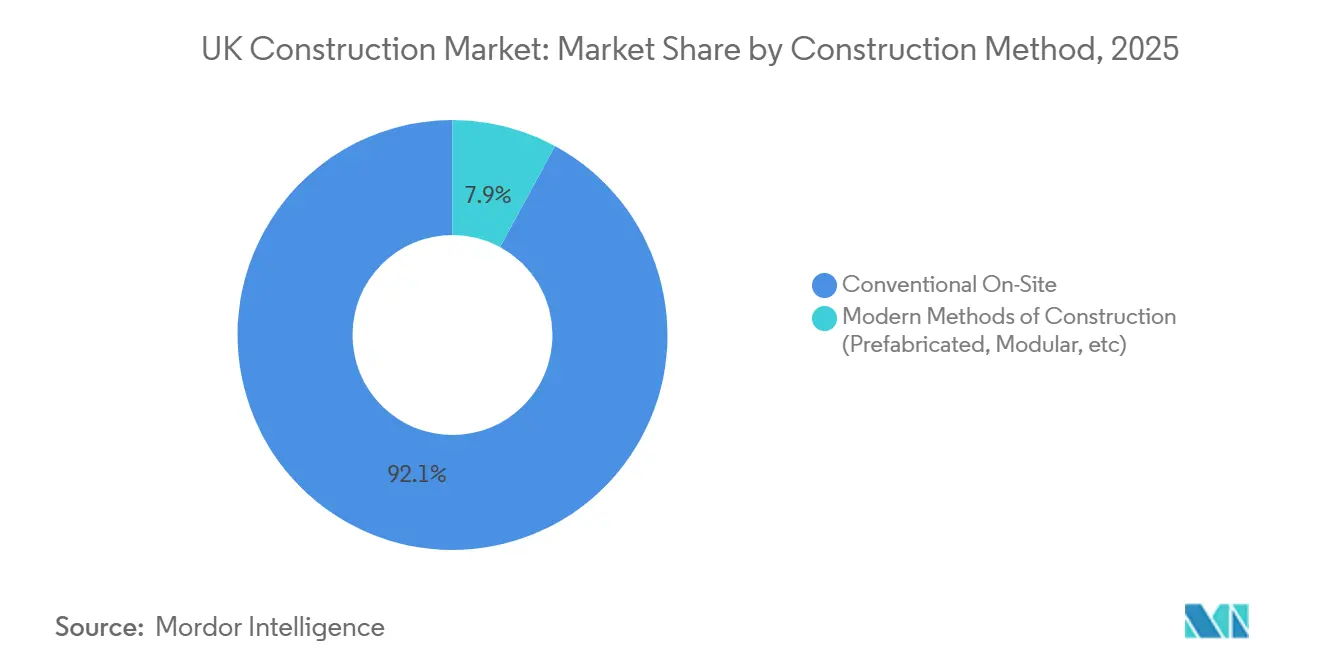
- Construction method was led by conventional on-site work with a 91.6% share in 2026, while modern methods of construction are forecast to grow fastest at a 10.1% CAGR during 2027-2032.
- By investment source, private investment led with a 74.09% share in 2026, and public investment is forecast to grow fastest at a 7.7% CAGR during 2027-2032.
- Across the UK nations, England held the largest share at 79.37% in 2026, while Northern Ireland is forecast to grow fastest at a 5.8% CAGR during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of UK Construction Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Government mega-projects (HS2, RIS3) boosting civil-engineering backlog | +1.8% | England strategic road corridors | Long term (≥ 4 years) |
| Chronic housing shortfall pushing residential starts | +1.3% | English local planning authority areas | Medium term (2-4 years) |
| Net-Zero 2050 targets stimulating green retrofit demand | +1.1% | English social housing communities | Medium term (2-4 years) |
| Off-site & modular building uptake post-Building Safety Act | +0.8% | Nationwide | Medium term (2-4 years) |
| Infrastructure secondary-market M&A by global PE & pension funds | +0.25% | Nationwide | Short term (≤ 2 years) |
| Digital-twin adoption improving project delivery efficiency | +0.35% | Woodham Academy project area | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Government mega-projects (HS2, RIS3) boosting civil-engineering backlog
Civil-engineering demand depends on the work still to be delivered and the timing of subsequent public programs. By February 2026, HS2 had completed over 108 million cubic meters of earthworks across its civil construction, around 70% of the planned quantity.[1] That left roughly 30% of planned earthworks to complete at that date. The Department for Transport’s RIS3 sets an investment plan for operating, maintaining, renewing, and enhancing England’s strategic road network from April 2026 to March 2031. Civil contractors active on both programs can balance the remaining railway earthworks against road renewal packages during the April 2026 to March 2031 RIS3 period.
Chronic housing shortfall pushing residential starts
Unmet housing need creates construction demand when it can be converted into deliverable residential schemes. Seasonally adjusted new-build dwelling starts in England were estimated at 35,910 in the second quarter of 2026, up 20% year over year but 47% below the second-quarter 2023 peak. The building-control series covered an estimated 80% of England’s housebuilding, and the recent increase partly reflected Building Safety Regulator reporting. England’s planning framework deems unmet housing need to exist for policy S5(1)(j) when an authority’s delivery falls below 75% of its requirement over the previous 3 years. That deemed unmet need applies in addition to the separate action-plan and 20% land-supply buffer requirements. For housebuilders, an authority’s delivery shortfall can therefore matter commercially as a location-specific basis for developing housing proposals.
Net-Zero 2050 targets stimulating green retrofit demand
For social landlords, funded retrofit programs translate energy-performance requirements into packages of building work. The Department for Energy Security and Net Zero offered grants for 138 Warm Homes: Social Housing Fund Wave 3 retrofit projects in England, with all agreements countersigned by November 7, 2025. Delivery was scheduled from 2025 through September 2028 for existing social homes below energy performance certificate band C, with applicants providing at least matching funding. Through July 2026, 94 of the 138 grant recipients reported around 25,770 energy-efficiency measures in around 12,900 households, with the figures provisional. Committed projects and reported installations together support a construction opportunity extending beyond the initial award of funds. The matching-funds requirement makes landlord co-investment part of the route from a grant offer to a completed retrofit.
Off-site & modular building uptake post-Building Safety Act
Public buyers need a workable procurement route before modular construction can become an executable building requirement. NHS Shared Business Services’ Modular Buildings 3 framework provides NHS and wider public-sector organizations nationwide a route to purchase, hire, or lease modular buildings from June 12, 2025, through June 11, 2029. Its eligible users include education, residential, and local-authority organizations. The choice of purchase, hire, or lease can align the commercial commitment with the buyer’s intended duration of use. For suppliers, that creates scope to address temporary accommodation and longer-lived building needs through different offers. The demand opportunity therefore depends on converting an accessible procurement route into a building solution suited to the buyer’s use period.
Restraints Impact Analysis of UK Construction Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Skilled-labor shortage & aging workforce | -0.9% | Nationwide | Long term (≥ 4 years) |
| Material-price volatility & supply-chain disruption | -0.6% | Nationwide | Short term (≤ 2 years) |
| Lengthy planning & permitting timelines | -0.35% | English local planning authority areas | Medium term (2-4 years) |
| Cyber-security risks in BIM-centric projects | -0.15% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Skilled-labor shortage & aging workforce
Skilled-labor shortages constrain how much work smaller contractors can turn into completed projects. In July to December 2025, 72% of 493 small and medium-sized UK construction businesses surveyed by the Federation of Master Builders and Chartered Institute of Building reported a skilled-trades shortage.[2] Shortages caused job delays for 49%, job cancellations for 22%, and paused expansion plans for 30% of respondents. The expansion response was newly introduced in that survey wave. The October 2026 Construction Jobs Plan separately identified recruitment that was failing to replace workers nearing retirement quickly enough or at the required skill level. Without sufficient skilled capacity, additional orders risk adding delivery commitments that a smaller contractor cannot fulfill on time.
Material-price volatility & supply-chain disruption
Material-price volatility constrains construction demand by making the price of a deliverable project harder to establish. In August 2026, the Royal Institution of Chartered Surveyors reported that volatile material and energy costs, alongside supply-chain disruption, had impaired UK construction professionals’ ability to maintain project cost certainty. The UK construction-material price index for all work rose 6.4% in the year to August 2026. Fabricated structural steel prices rose 21.2% in the UK over those 12 months. RICS also reported that forecasting difficulties led contractors and developers to build larger contingencies into project budgets. For steel-frame contractors committing before material purchase, a higher steel bill can therefore erode the margin allowed in the construction price.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
UK Construction Market Segment Analysis
By Sector:
Residential Scale Meets Utility InvestmentResidential accounted for a 37.63% share of the UK construction market size in 2026, making it the largest segment. England’s provisional dwelling-stock estimate was 25.8 million on March 31, 2025, an increase of 208,600 dwellings from a year earlier. That installed base gives residential contractors a demand context extending beyond the homes added during an individual year, with work on existing dwellings included within construction activity. Builders and suppliers can consequently address different contract packages across housing additions and interventions in the existing residential stock.
Infrastructure is the fastest-growing segment in the United Kingdom construction market, with a forecast CAGR of 7.3% during 2027-2032. The Office for National Statistics’ infrastructure statistics in development recorded 3.2% current-price growth in Great Britain’s new-work infrastructure construction in 2025 compared with 2024. Within that series, water, sewerage, and electricity spending rose 17.8%, 74.8%, and 15.3%, respectively, over the same period. Commercial construction faced a different order signal, as private commercial new work contributed to the 11.8% quarter-over-quarter fall in Great Britain’s total construction new orders in the second quarter of 2026. That contrast makes utility-work capability a distinct commercial option for contractors seeking demand beyond commercial building awards.



By Construction Type:
New Assets Lead While Existing Buildings Offer Adaptation WorkNew construction represented a 53.62% UK construction market share in 2026 and was the largest segment. Seasonally adjusted chained-volume construction output in Great Britain in 2025 was GBP 128.5 billion (USD 169.4 billion) for all new work. In February 2026, the Department for Education planned to rebuild over 750 schools and sixth-form colleges across England through 2034-35. The program prioritizes the worst-condition buildings where places are needed now and in the future. For education contractors, that planned sequence makes replacement-building delivery capacity relevant across successive school projects, extending the opportunity beyond a single site.
Renovation is the fastest-growing segment in the United Kingdom construction market, with a forecast CAGR of 6.9% during 2027-2032. Repair and maintenance construction output in Great Britain increased 0.4% month over month in August 2026. ODS completed the refurbishment of The Leys Children and Family Centre for Oxfordshire County Council in Oxford in January 2025. Jointly funded by the Education and Skills Funding Agency, the work extended and reconfigured the existing building for the Family Solutions Service and the Oxfordshire Hospital School. That combination makes the connection between added space and the retained building central to the contractor’s scope for this public-service refurbishment.

By Construction Method:
Tailored Structures and Repeatable Modular ProgramsConventional on-site construction was the largest segment in the United Kingdom construction market, with a 91.6% share in 2026. In October 2025, IMPACT Scotland awarded Balfour Beatty the Dunard Centre concert-hall construction contract in Edinburgh, including an in-situ concrete double basement. The basement was intended to house performer changing and storage areas and back-of-house facilities. For a cultural-building client, that requirement connects specialized below-ground construction with the operating purpose of the venue. The on-site opportunity lies in tailored structural packages whose value depends on fitting the particular spaces and functions required by the complete building.
Modern methods of construction, including prefabricated and modular methods, form the fastest-growing segment, with a forecast CAGR of 10.1% during 2027-2032. In 2025, Premier Modular was awarded a contract for 42 modules for security facilities at Manchester, London Stansted, and East Midlands airports. The project used a bespoke building blueprint intended to be repeated at each site. For an airport operator with several locations, repeatability can reduce the need to redefine the same functional building package for every site. The resulting opportunity rewards a supplier able to connect factory-made modules with a coordinated construction program across the operator’s estate.
By Investment Source:
Private Funding Scale Meets Public Program CommitmentsPrivate investment was the largest segment in the United Kingdom construction market, accounting for 74.09% of construction spending in 2026. Private-sector infrastructure new work exceeded public-sector new work in Great Britain for the second consecutive year in 2025, on a current-price, non-seasonally adjusted basis. Funding classification distinguishes who finances the work while leaving its physical infrastructure category unchanged. An infrastructure opportunity can therefore arise through a private funding route even where its physical construction requirements resemble those of a publicly funded asset, widening the range of potential clients.
Public investment is the fastest-growing segment in the United Kingdom construction market, with a forecast CAGR of 7.7% during 2027-2032. NHS trusts and construction partners signed 11 long-term partnerships to deliver new hospitals across England in July 2026.[3] Those agreements connect public healthcare clients with construction organizations over a delivery horizon that extends beyond the signing itself, creating a basis for coordinating future building work. Coordination across related hospital schemes can consequently become part of a supplier’s public-program proposition, alongside the capabilities needed to deliver an individual construction package.
Geography Analysis
England UK Construction Market
England accounted for a 79.37% share of the UK construction market size in 2026. The Ministry of Housing, Communities and Local Government reported that new construction, conversion, and renovation represented 67% of English local authorities’ provisional capital expenditure in 2025-26. That mix makes local-authority construction relevant to builders whose capabilities span creating new assets, converting existing premises, and improving buildings for a range of public needs. The commercial opportunity is consequently distributed across different interventions in public assets, allowing a council-facing contractor to address a wider set of building requirements than new development alone would suggest.
Northern Ireland UK Construction Market
Northern Ireland is the fastest-growing geography in the United Kingdom construction market, with a forecast CAGR of 5.8% during 2027-2032. The Northern Ireland Statistics and Research Agency’s provisional figures showed construction-output volume within Northern Ireland up 3.5% year over year in the second quarter of 2026, excluding local firms’ work elsewhere. Within that local activity, provisional infrastructure output, including new work and repair and maintenance, rose 6.3% in volume from the same quarter of 2025. Maintaining and extending physical networks therefore offers contractors work on both new assets and infrastructure already in service, connecting project delivery with needs arising across an asset’s life.
Scotland’s January 2026 infrastructure pipeline planned investment for April 2026 to March 2030 to support 36,000 affordable homes. Its commercial relevance is the opportunity to align affordable-housing delivery capacity with a multi-year investment horizon. Wales’s March 2026 loan agreements with 5 registered social landlords were intended to fund 159 affordable homes across Cardiff, Swansea, Newport, Torfaen, Bridgend, and Rhondda Cynon Taf. In Wales, the homes were planned across social rented, intermediate rented, and shared ownership tenures. Where Scotland’s program points to sustained delivery planning, the Welsh agreements create a more specific route to construction opportunities through identifiable social-landlord clients.
Regulatory Framework and Outlook
This comparison covers selected jurisdictions from the perspective of a construction contractor choosing compliant products and preparing building work. The national column addresses regulated construction products under guidance that distinguishes Great Britain and Northern Ireland. England and Wales are compared on building-control requirements and announced transitions affecting construction work. These layers affect product selection and the way a contractor prepares a construction package.
Regulatory Table of UK Construction Market
| Decision factor | United Kingdom | England | Wales |
|---|---|---|---|
| Primary authority | Office for Product Safety and Standards for regulated construction products | Building Safety Regulator for specified higher-risk work; local authorities and registered approvers where other work needs approval | Local authorities and registered building control approvers; only local authorities for new higher-risk work |
| Key instruments or direction | Construction Products Regulations 2013, amended in 2022; proposed Great Britain replacement for products covered by designated standards and technical assessments, intended to commence with the general safety requirement subject to parliamentary time | Building Regulations 2010 and adopted Future Homes and Buildings Standards amendments | Higher-risk building procedures and building-control reforms effective July 1, 2026; Part L amendments scheduled March 4, 2027 |
| Commercial effect | Product supervision within the regulated product population | Approval before applicable higher-risk work, subject to exemptions; most new standards provisions start March 24, 2027, with specified higher-risk provisions starting September 24, 2027, subject to transitions | Gateways, golden-thread requirements and dutyholder roles for applicable work; qualifying earlier work protected under transition conditions, with protection ceasing on rejection or lapse |
| Current policy attractiveness | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | Hardening | No change |
| Source: Mordor Intelligence | |||
The UK’s Medium rating and No change direction reflect continued product supervision under operative regulations, while the proposed Great Britain replacement for covered products is subject to parliamentary time. England’s Medium rating and Hardening direction reflect higher-risk approvals and adopted 2027 standards for low-carbon heating and high energy efficiency in new homes and non-domestic buildings. Wales’s Medium rating and Hardening direction reflect its July 1, 2026 control reform and the March 4, 2027 Part L changes requiring on-site renewable electricity for newly erected dwellings or buildings containing them, except regulation 7(4) relevant buildings and where reasonable output cannot be achieved given the design and surroundings. New dwellings must also meet a minimum energy-use-intensity rating, with the person carrying out the work notifying the local authority of design specifications no later than the day before work starts and reporting as-built performance and specification changes no later than 5 days after completion.
Value Chain Stages
This comparison follows construction-product distribution, project delivery, and building maintenance to distinguish the work and earnings at each stage. Distributors earn from material sales, contractors from construction contracts, and maintenance providers from service work. On large cable projects, a main contractor or subcontractor generally procures cables from distributors for delivery to installers, so distributor delivery timing sets when installation can proceed.
Value Chain Analysis Table of UK Construction Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Construction-product distribution | Building-material distributors such as Travis Perkins plc | Material sales revenue | Availability of some low-carbon products in 4 southern UK cities | Identify suitable product alternatives before committing the construction package |
| Construction delivery | Main contractors such as Kier Group | Construction contract revenue | Cable procurement handoff on large projects | Coordinate cable ordering with installation milestones |
| Building maintenance and refurbishment | Lifecycle service providers such as Kier Places, part of Kier Group | Maintenance and refurbishment service revenue | Coordinating maintenance with refurbishment | Phase building improvements around the maintenance schedule |
| Source: Mordor Intelligence | ||||
Construction delivery and later building services can generate revenue within one group, as Kier’s FY2026 activities illustrate. That allows the supplier relationship to extend beyond the completion of an initial building project. The economic distinction is between earning from one construction package and earning from successive interventions in the same asset.
Competitive Landscape
Market Concentration
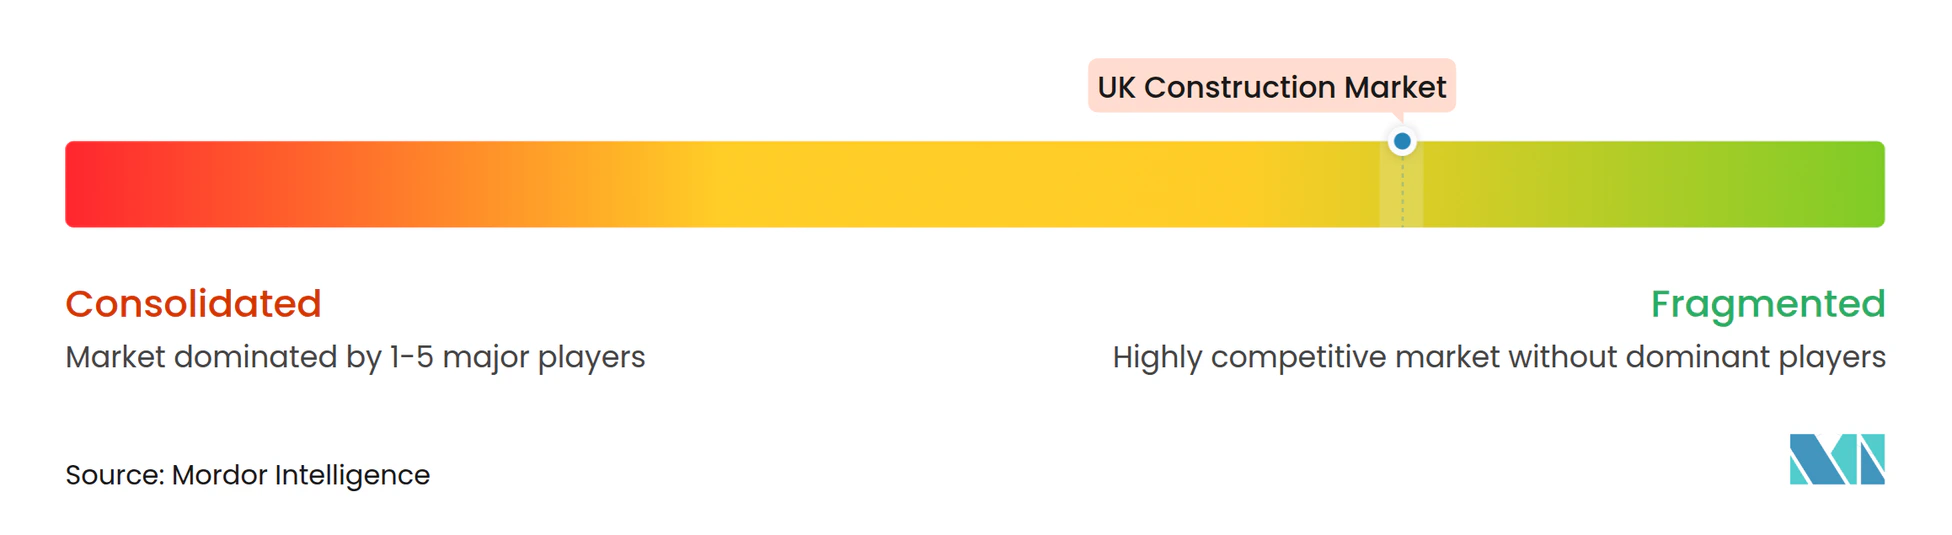
Competition is dispersed across national contractors and specialist construction businesses, with Balfour Beatty, Kier Group, Morgan Sindall Group, and Laing O’Rourke among the active participants. Eight ISG companies entered administration on September 20, 2024, and ISG’s UK construction and related services operations ceased trading immediately. Balfour Beatty’s UK Construction division reported a 3.5% profit-from-operations margin in 2025, exceeding its 3% target after a fifth consecutive annual improvement. In FY2026, Kier Group’s Kier Places business provided facilities management and housing maintenance alongside the group’s construction work. With ISG’s UK operations gone, clients choosing among active contractors can weigh Balfour Beatty’s improving construction returns alongside Kier Group’s ability to support assets beyond the building phase.
In October 2025, Kier Group was appointed to Norfolk County Council’s highways and infrastructure works contract, announced with an April 2026 start and a term of up to 14 years. Such a prospective term makes the ability to sustain service over many years central to the contractor’s commercial proposition. Morgan Sindall Group’s Fit Out division reported 37% revenue growth and 41% operating-profit growth in 2025, with the company citing exceptional volumes, operational leverage, and a transitional competitive environment. The exceptional-volume contribution makes replenishing the Fit Out workload central to sustaining that divisional earnings improvement.
Laing O’Rourke began widening 2 entrances at Calderdale Royal Hospital in Halifax on October 12, 2026, to create ambulance access for the new emergency department and improve construction-site access. In June 2026, the company said its UK supplier onboarding requires Safety Schemes in Procurement compliance through the Deem to Satisfy framework, plus alignment with the Common Assessment Standard and Building Safety Act requirements. Suppliers and specialist firms seeking to work with Laing O’Rourke therefore need to meet those requirements before onboarding. Competency credentials become a condition of access to its supply chain alongside price. At Calderdale, preparing entrances for ambulances and large construction vehicles makes site-access work part of delivering on the existing hospital campus.
UK Construction Industry Leaders
-
Balfour Beatty
-
Kier Group
-
Morgan Sindall Group
-
Laing O'Rourke
-
ISG
- *Disclaimer: Major Players sorted in no particular order
UK Construction Market Companies Covered in this Report
- Balfour Beatty
- Kier Group
- Morgan Sindall Group
- Laing O'Rourke
- ISG
- Skanska UK
- BAM Construct & Ventures UK
- Bouygues UK
- Willmott Dixon
- Wates Group
- Galliford Try
- Sir Robert McAlpine
- Mace Group
- Multiplex
- Costain Group
- VINCI Construction UK (incl. Taylor Woodrow)
- Ferrovial Construction UK
- Lendlease Europe (UK)
- John Sisk & Son (UK)
- Barratt Redrow
- Persimmon
- Taylor Wimpey
- Vistry Group
- Berkeley Group
Key Opportunities for Market Participants
The comparison covers council-led housing, community-led rural schemes, and preparation for later hospital construction in England. Homes England accepts eligible Continuous Market Engagement bids for one or more development schemes during its 2026-2036 housing program, subject to available funding. The commercial question is how construction suppliers can translate a funding route or an early project stage into a deliverable package of physical work.
Market Opportunities Table of UK Construction Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Council-led affordable-housing portfolios | Earlier multi-site grant bids announced for the 2026-2036 program | Councils developing affordable housing | Sequence construction packages across the proposed sites | Multi-site readiness and sequencing | Housing contractors supporting council delivery |
| Community-led rural affordable housing | Flexible grant rates support small, often rural schemes, subject to bid assessment | Community land trusts and housing cooperatives | Package smaller construction projects around the community developer’s site | Relatively high development costs | Contractors able to serve smaller rural housing schemes |
| Site readiness for later hospital schemes | July 2026 schedule placed Wave 2 main-build starts in 2030-2035 | NHS trusts developing hospital schemes | Develop site-preparation and infrastructure packages for later schemes | Potential capacity constraints identified in the 2025-26 report | Enabling-works and infrastructure contractors |
| Source: Mordor Intelligence | |||||
The central opening is to turn funding access into schemes that smaller or public housing buyers can deliver. Flexible grant rates can improve community-led scheme viability, while relatively high development costs shape the feasible construction package. Construction suppliers can therefore compete by matching the scale of their work packages to the delivery capabilities of the housing organization.
Recent Industry Developments in UK Construction Market
- Oct 2026: Laing O’Rourke began widening 2 entrances at Calderdale Royal Hospital in Halifax to create ambulance access for the new emergency department and improve construction-site access.
- Jul 2026: NHS trusts and construction partners signed 11 long-term partnerships to deliver new hospital schemes across England.
- Apr 2026: Great British Energy – Nuclear and Rolls-Royce SMR signed a contract to design and build small modular reactors for the Wylfa project in Wales.
UK Construction Market Report Scope and Research Methodology
Market Definition and Coverage
The UK construction market measures annual spending on construction activity delivered in the United Kingdom, including new build and renovation of buildings and civil engineering works. It covers construction work and related installation, maintenance, and repair.
Scope exclusions: Real estate transactions and land values, pure architecture and design-only fees, and the offsite manufacturing value of standalone building products sold without an associated construction contract are excluded.
Segments Covered in This Report
- By Sector
- Residential
- Apartments/Condominiums
- Villas/Landed Houses
- Commercial
- Office
- Retail
- Industrial and Logistics
- Others
- Infrastructure
- Transportation Infrastructure (Roadways, Railways, Airways, others)
- Energy & Utilities
- Others
- Residential
- By Construction Type
- New Construction
- Renovation
- By Construction Method
- Conventional On-Site
- Modern Methods of Construction (Prefabricated, Modular, etc)
- By Investment Source
- Public
- Private
- By Geography
- England
- Scotland
- Wales
- Northern Ireland
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the Office for National Statistics construction output, new orders, and price series provide measures of delivered work, sector mix, price movement, and forward order signals. The ONS construction statistics methodology defines chargeable output, the UK Infrastructure Pipeline from the National Infrastructure and Service Transformation Authority shows planned public and private infrastructure construction and maintenance, and HM Government infrastructure program information helps track public program timing.
Analysts can use company filings, annual reports, investor materials, and reputable UK construction press to cross-check contractor activity, project timing, and changes in costs or capacity against those public series. These sources are illustrative rather than exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
A structured interview guide would seek views from UK residential, commercial, infrastructure, renovation, and construction-method specialists, including contractor leaders, project and estimating managers, and public and private client-side construction leads. Interviews and a targeted survey would test the source-based interpretation of contract activity, delivery timing, pricing, and segment mix, identify gaps in regional or project coverage, and help reconcile independent evidence without substituting opinion for measured activity.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 37% | CXOs: 20% | |
| Mid tier: 38% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The model starts with UK annual construction spending by buildings and civil engineering, anchored in current-price output and adjusted for construction price movement so that changes in work volume can be distinguished from price change. It separates new work from repair and maintenance, then estimates residential, commercial, and infrastructure activity using indicators such as housing starts and completions, new orders by sector, infrastructure pipeline status and anticipated spend, and output price indices for labor, plant, and materials. Project and construction-type shares are built from the distribution of measured work and cross-checked against the public and private funding mix and the four UK nations. A missing sector observation is estimated from the nearest available official series and flagged for review against related indicators. A top-down forecast applies a multivariate regression to activity, order, pipeline, and price drivers, with scenario analysis for project timing or cost changes where the pipeline does not establish delivery dates. Selective bottom-up checks compare sampled contract values with reported project progress and supplier roll-ups. Interviews with UK contractors and clients test whether variable-level forecasts reflect actual award and delivery conditions. Where sources disagree, the estimate follows observed output and orders, and any remaining gap stays within the affected model input until independent evidence supports a change.
Data Validation & Update Cycle
Analysts triangulate official output and orders with price indices, infrastructure pipeline status, company disclosures, and sampled project evidence, then investigate outliers, year-on-year changes, and sector or geographic totals that do not reconcile. A second analyst reviews source definitions, calculations, and variance explanations before sign-off, and the team recontacts relevant respondents when new evidence conflicts with earlier interpretation or a project timing, price, or scope assumption changes materially. The dataset is refreshed annually, reviewed between cycles after material policy, funding, or project events, and checked again in a fresh pre-delivery pass.
Mordor Intelligence's United Kingdom Construction Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The UK construction market measures annual spending on construction activity delivered in the United Kingdom, including new build and renovation of buildings and civil engineering works.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. A missing sector observation is estimated from the nearest available official series and flagged for review against related indicators.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 337.6 B (2027) | |
| Global Consultancy A | USD 307.84 B (2025) | At its 2025 base, this estimate is 8.8% below this report's 2027 value of USD 337.6 B, 2 years later. Its published value predates the comparison year, and its forecast shows continued market growth after that base year. |
| Industry Databook B | GBP 161.39 B (2025) | Its base-year value precedes the comparison period, and its published series projects continued expansion afterward. |
Mordor Intelligence's dataset is refreshed annually, reviewed between cycles after material policy, funding, or project events, and checked again in a fresh pre-delivery pass.
Key Questions Answered in the Report
What is the UK construction market size and growth outlook?
It was valued at USD 325.3 billion in 2026 and is forecast to grow from USD 337.6 billion in 2027 to USD 402.5 billion by 2032, at a 3.58% CAGR during 2027-2032.
What is supporting demand for UK construction work?
England’s strategic road investment plan runs from April 2026 to March 2031, while funded upgrades to English social homes support building work.
Which sector leads UK construction spending?
Residential led with a 37.63% share in 2026, while infrastructure is forecast to grow fastest at a 7.3% CAGR during 2027-2032.
Which companies compete in UK construction?
Balfour Beatty, Kier Group, Morgan Sindall Group, and Laing O’Rourke are active participants.
What could constrain UK construction delivery?
Among 493 surveyed small and medium-sized UK construction businesses, 49% reported job delays caused by skilled-trades shortages in July to December 2025. Capacity constraints can limit the conversion of orders into completed work.
Which UK nation leads construction spending and which grows fastest?
England led with a 79.37% share in 2026, while Northern Ireland is forecast to grow fastest at a 5.8% CAGR during 2027-2032.