
Translation Services Market Size and Share
Translation Services Market Analysis by Mordor Intelligence
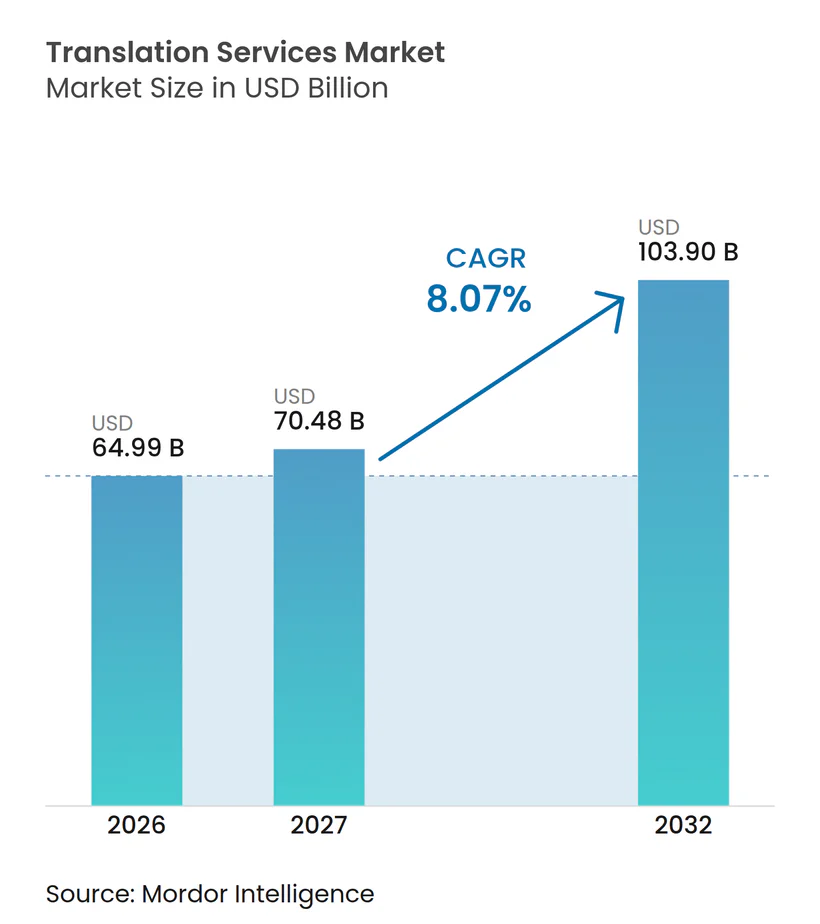
The translation services market size was valued at USD 64.99 billion in 2026 and estimated to grow from USD 70.48 billion in 2027 to reach USD 103.9 billion by 2032, at a CAGR of 8.07% during the forecast period (2027-2032).
Digital retail and international streaming enlarge the potential audience for multilingual content, while public-service access requirements create institutional workloads. For software vendors serving customers in Japan and Brazil, localized product language connects international delivery with understandable functionality. Integrated drafting, review and delivery give suppliers a way to serve that demand. Privacy obligations and specialist scarcity constrain how quickly regulated assignments can be delivered. Paid review offers a distinct source of service revenue as language coverage broadens and routine translation faces pricing pressure.
Key Report Takeaways
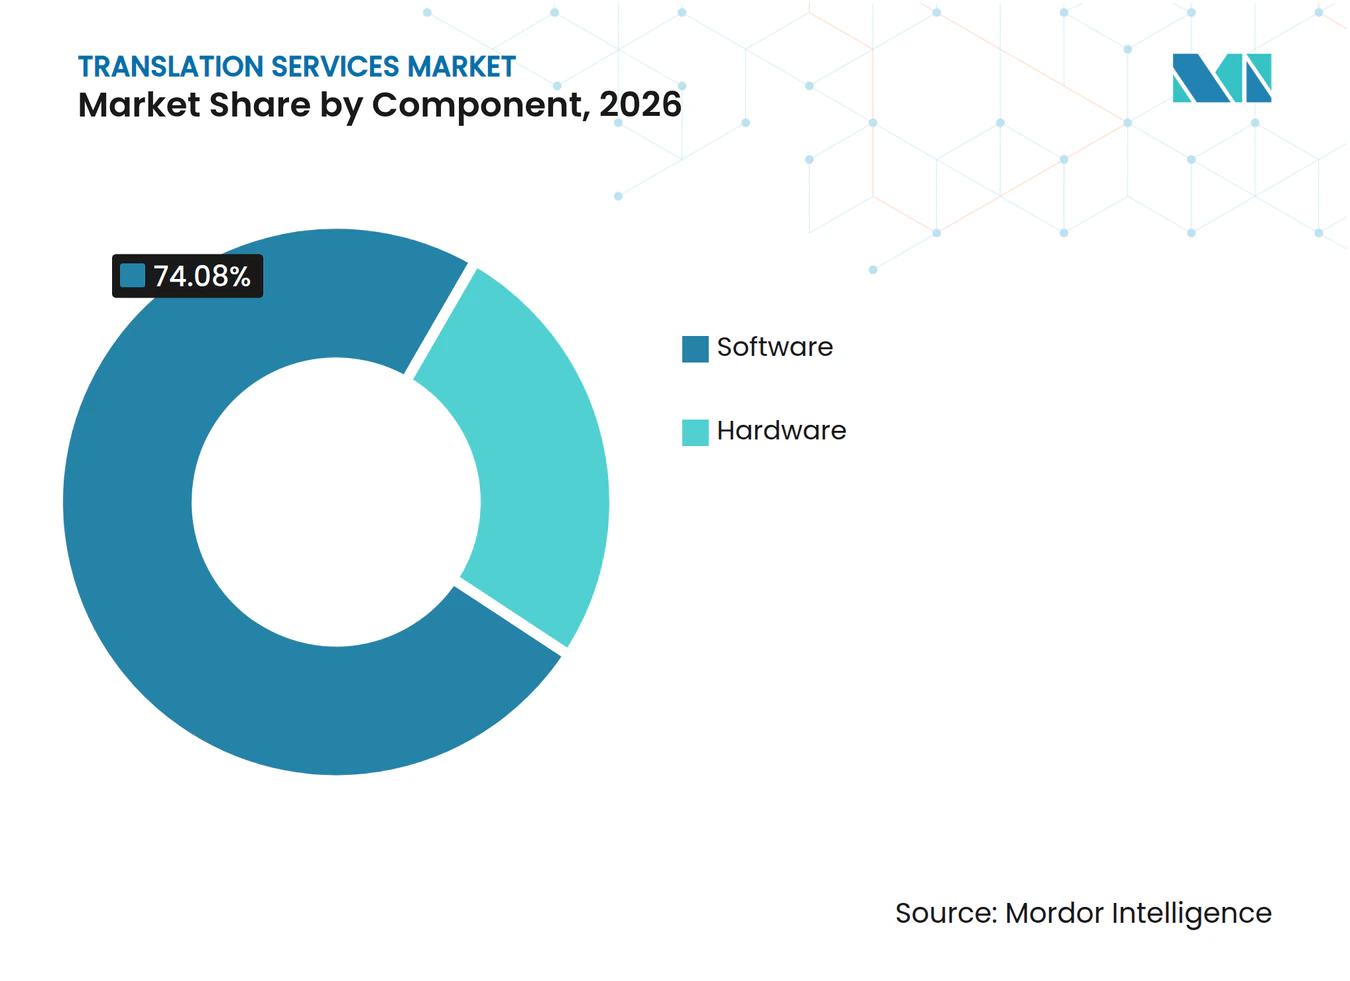
- By component, software held a 74.08% translation services market share in 2026 and is forecast to grow fastest at a CAGR of 9.85% during 2027-2032.
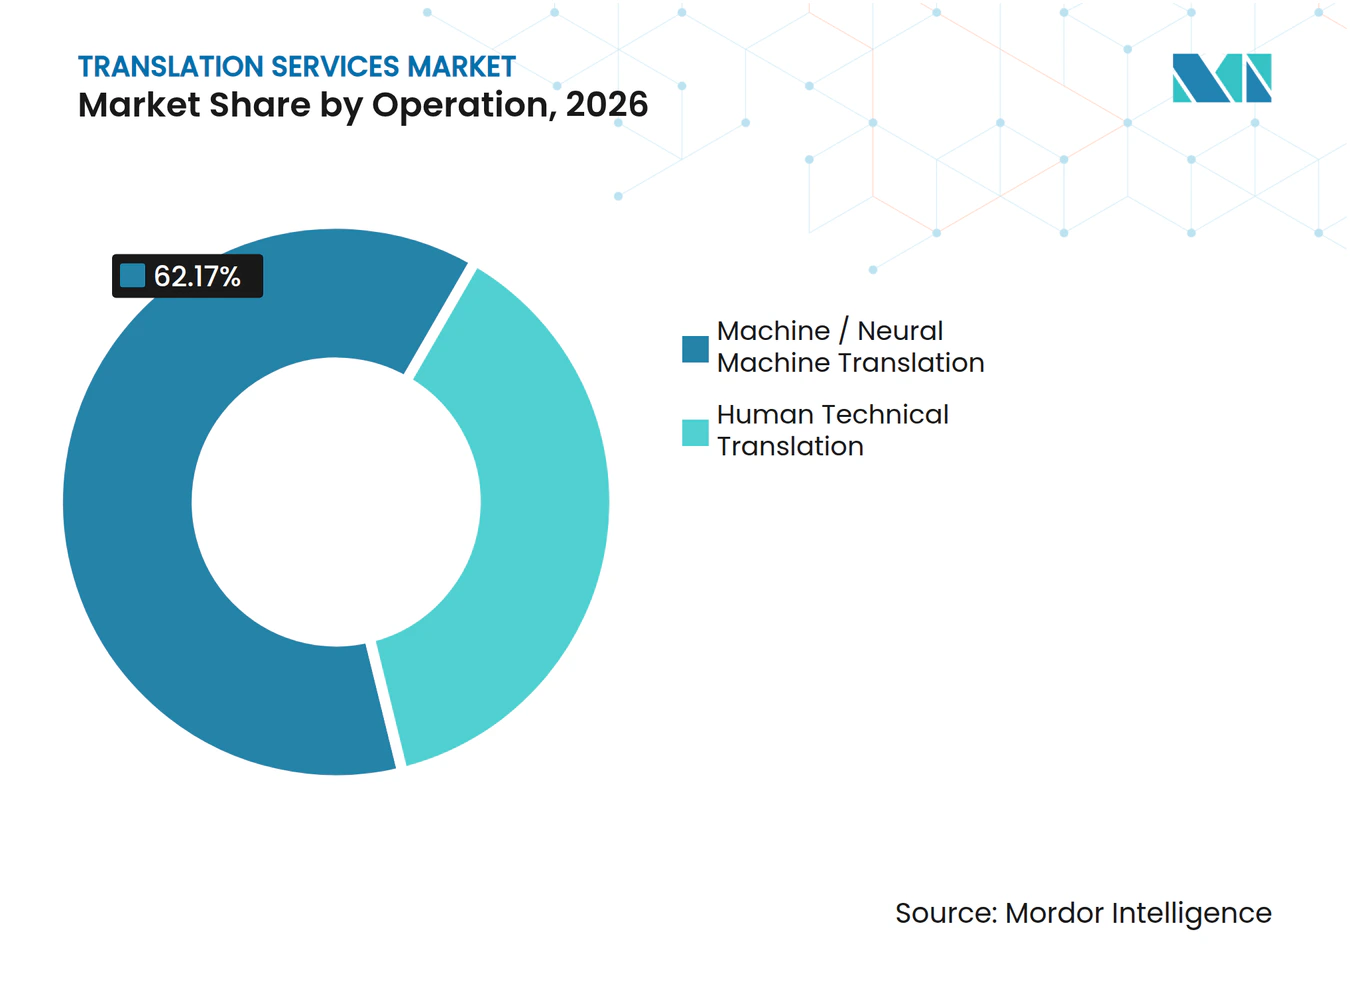
- For translation operations, machine / neural machine translation accounted for a 62.17% share of the translation services market size in 2026 and is forecast to grow fastest at a CAGR of 9.7% during 2027-2032.
- Among services, written translation led with a 52.91% share in 2026, while the transcreation and multimedia localization segment is forecast to grow fastest at a CAGR of 12.3% during 2027-2032.
- IT and telecom led end-user demand with a 32.34% share in 2026, while the media, gaming and entertainment segment is forecast to grow fastest at a CAGR of 11.9% during 2027-2032.
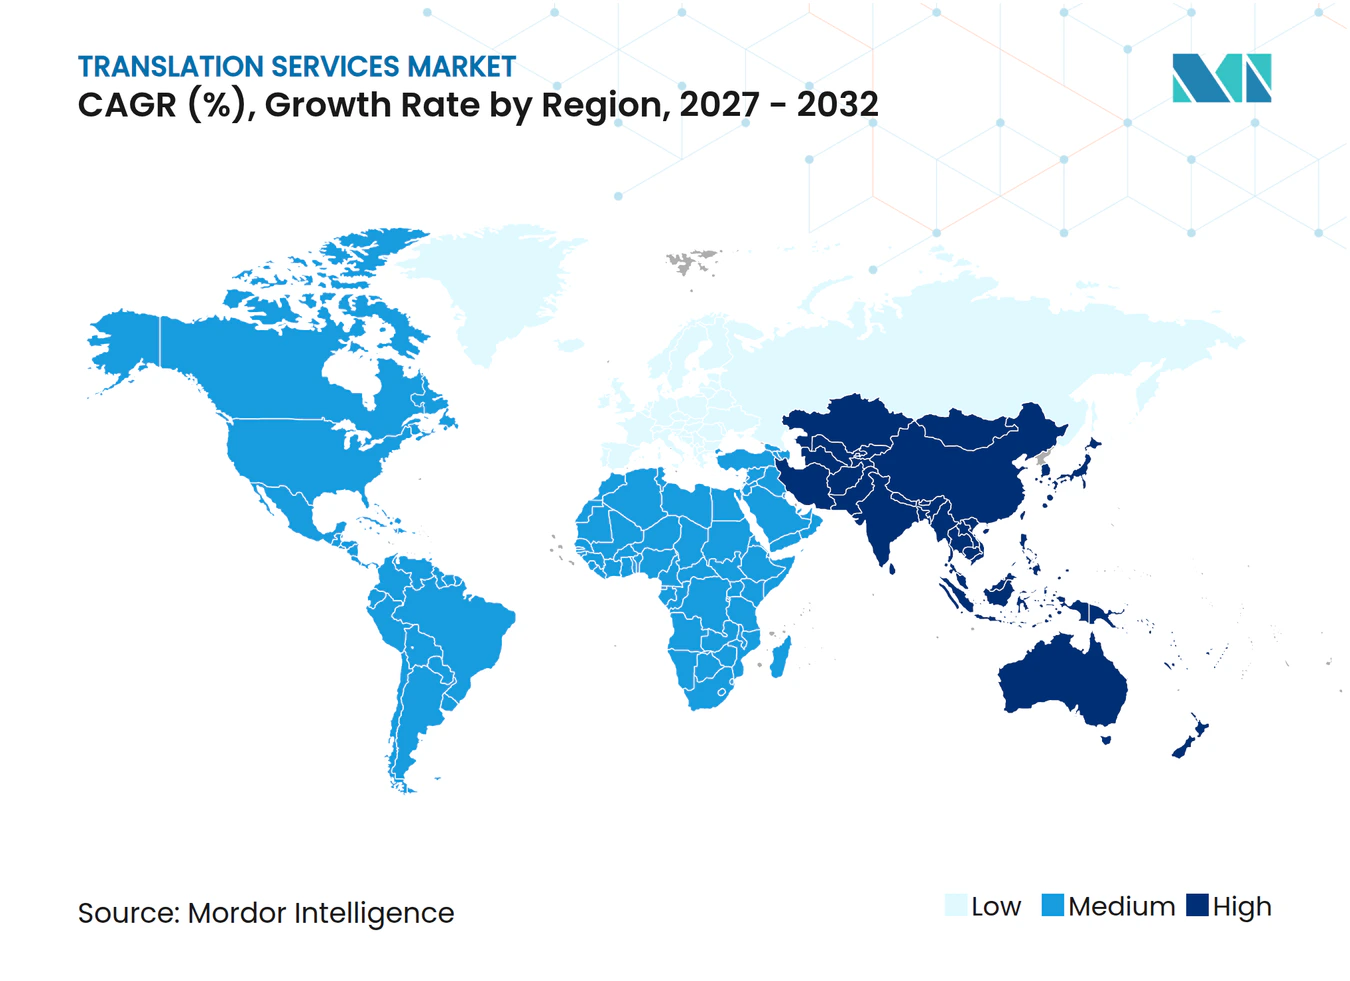
- Geographically, Europe led with a 43.37% share in 2026, whereas Asia-Pacific is forecast to grow fastest at a CAGR of 14.6% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Translation Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growth of Global E-Commerce | +3% | The United States | Medium term (2-4 years) |
| Explosion of Multimedia/Streaming Content | +2.8% | North America, Europe and Asia-Pacific | Short term (≤ 2 years) |
| Regulatory Push for Language Access in Public Services | +2.2% | United States and Australia | Short term (≤ 2 years) |
| Accelerating Cross-Border SaaS Deployments | +1.8% | Australia, Ireland, Canada and United States | Medium term (2-4 years) |
| Shift to Continuous Localization Pipelines | +0.9% | Japan and Brazil | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Growth of Global E-Commerce
Retailers selling across languages need translated purchase journeys that connect product discovery with an understandable offer. U.S. retail e-commerce sales were estimated at USD 1.23 trillion in 2025, up 5.4% (±1.2%) from 2024 on an unadjusted basis without adjustment for price changes.[1] That larger commercial base creates an opening for localization providers when retailers extend their offer to additional language groups. Product descriptions alone cannot resolve a purchase if the accompanying delivery conditions or return instructions remain incomprehensible to the intended buyer. The completeness of the localized transaction, from product description to delivery terms and return instructions, becomes a basis for choosing a translation supplier. The resulting opportunity depends on sellers choosing multilingual expansion rather than on digital sales growth alone.
Explosion of Multimedia/Streaming Content
International circulation gives a localized audiovisual title a commercial life beyond its country of origin. Netflix audiences watched more than 97 billion hours across genres and languages in the first half of 2026, its highest viewing total for any half-year period.[2] In 2025, 70% of Netflix viewing came from members watching titles from countries other than their own. For a distributor choosing additional language versions, this audience pattern supports treating localization as an investment in wider circulation rather than a single domestic release cost. For each additional version, linguistic adaptation must produce material suited to the chosen delivery format, extending the assignment beyond text conversion alone.
Regulatory Push for Language Access in Public Services
Public-service language access creates a delivery obligation that agencies cannot satisfy through discretionary marketing localization. New Jersey requires executive-branch entities serving the public to translate vital documents and information into the 7 most common languages among residents with limited English proficiency. The staged timetable expected translation into the top 5 languages by December 12, 2025, and the other 2 in the year thereafter. Immediate translation during public health or governor-declared emergencies and interpreting in constituents' primary languages when services or benefits are provided are separate requirements. Australia's TIS National received 1.55 million interpreting requests in fiscal 2024-25, when demand for immediate, non-pre-booked telephone interpreting increased 10.4%. Continuing interpreter availability, alongside a finished document set, is therefore part of what an agency must secure to meet its language access duties.
Accelerating Cross-Border SaaS Deployments
In September 2025, BMC reported that its Control-M workflow-automation SaaS solution had become available in the AWS Sydney Region, providing compliance with regional data-sovereignty requirements in Australia. Atlassian ships products in more than 20 languages and cites customers in Tokyo and São Paulo as localization contexts. BMC's regional hosting addresses data residency, while Atlassian's language coverage addresses how international customers use its products. For a software producer extending language coverage, each additional version requires translation and professional review of its product strings. Cross-border delivery can thus multiply language assignments around the same product release, creating work beyond the expansion of hosting infrastructure.
Restraints Impact Analysis of Translation Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data-privacy and Security Concerns | -1.1% | The United States | Short term (≤ 2 years) |
| Shortage of Qualified Domain-specialist Linguists | -0.8% | The United States | Long term (≥ 4 years) |
| Good-enough Free MT Eroding Price Realizations | -0.4% | Countries across Europe | Medium term (2-4 years) |
| Rising Gen-AI Hallucination Risk in Regulated Verticals | -0.3% | The United States | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Data-privacy and Security Concerns
Data-sensitive language work faces both vendor-onboarding barriers and assignment-specific restrictions. Smartling said on December 4, 2025, that ISO 27001 and HITRUST certifications were often prerequisites for onboarding translation and localization vendors in healthcare, life sciences and insurance. In the United States, when a language-service contractor acts as a HIPAA business associate for a covered provider, its contract must limit uses and disclosures and require appropriate safeguards. Applicable Security Rule requirements also extend to electronic protected health information. In the same announcement, Smartling said it had achieved ISO 27001 certification covering controls applied to its AI translation workflows. The separate contracting step can delay a covered assignment even when the translator has the certifications needed for onboarding.
Shortage of Qualified Domain-specialist Linguists
Scarce specialist capacity can prevent an interpreting requirement from becoming a timely delivered service. Michigan's 2025 sign-language interpreter assessment identified few interpreters with legal endorsements, alongside high training costs and limited training access. The same assessment identified major delays for DeafBlind and rural patients needing in-person healthcare interpreters. For Michigan legal-service buyers, general sign-language coverage cannot substitute for interpreters holding the relevant endorsement. Michigan healthcare buyers seeking in-person sign-language interpreters for DeafBlind and rural patients face a separate delivery constraint. Delays in obtaining in-person interpreters and the cost of training for legal endorsements therefore constrain expansion of these sign-language services in Michigan.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Translation Services Market Segment Analysis
By Component:
Software Connects Product Approval and Recurring Tool UseSoftware accounted for a 74.08% share of the translation services market size in 2026 and is forecast to be the fastest-growing segment, at a CAGR of 9.85% during 2027-2032. Atlassian routes product translations through Smartling's translation management system, where professional translators review and approve strings before they ship. The software's role is therefore to organize approval within product delivery, making coordination between drafting and sign-off part of its commercial usefulness. Because the translator signs off inside the translation management system before anything ships, the software holds the point where drafting becomes an approved product string.
RWS reported 170,000 monthly subscribers to its Trados translation software in FY2025. In FY2025, RWS launched Smart Insights, an AI-powered project-manager copilot, and Connected AI, which integrates large language models directly with translation engines, in Trados Enterprise. Those additions address the coordination and model connections surrounding automated translation, extending the product beyond the generation of translated text.



By Operation:
Processing Scale and Domain Judgment Serve Different NeedsMachine / neural machine translation represented a 62.17% translation services market share in 2026 and is forecast to be the fastest-growing segment, at a CAGR of 9.7% during 2027-2032. The European Commission's eTranslation service, available free to eligible users, processed more than 890 million pages in 2025. When eligible users can obtain processing without a service fee, commercial suppliers need a reason for payment beyond access to an automatic translation function. This makes fitting a buyer's particular task and deployment requirements a stronger basis for pricing than raw processing throughput alone.
Human technical translation can retain value within a technology-supported workflow when the assignment requires subject-matter judgment. In FY2025, RWS's Regulated Industries division provided specialized technical translations for life sciences, financial services and the legal sector, emphasizing quality and security. For buyers in those verticals, the usefulness of a translation depends on expressing the intended domain meaning, which gives specialized language expertise a defined purpose alongside technology. Specialization can make an assignment harder to substitute solely on word volume, because another provider must supply the relevant professional judgment as well as a translated text.

By Service:
Document Coverage and Audiovisual Production Shape ValueWritten translation was the largest service segment, with a 52.91% share in 2026. The European Commission's Directorate-General for Translation produced 2.5 million pages in the EU's official languages in 2025. An institutional document requiring several language versions gives suppliers multiple linked assignments from one source text. Revision cycles on a source text therefore generate update work across its language versions, a stream of assignments separate from the first translation.
Transcreation and multimedia localization is forecast to be the fastest-growing service segment, at a CAGR of 12.3% during 2027-2032. On June 26, 2025, RWS acquired Papercup's AI dubbing intellectual property to expand its support for multilingual video, voice and content localization.[3] The acquired asset concerns a production capability that can support multiple audiovisual versions, creating a reusable technical resource for language adaptation. For buyers, this offers a route to connect linguistic work with voice production while retaining attention to the intended audience and format. Commercial value depends on turning that capability into an appropriate finished language version, making production execution an important complement to ownership of the technology.
By End-User:
Product Functionality and Entertainment Require Distinct DeliveryThe IT and telecom segment was the largest end-user segment, with a 32.34% share in 2026. Atlassian reported that words sent for product translation grew 272% year over year in H2 FY2025 as AI-assisted development accelerated. Faster source-content creation therefore enlarges the language workload associated with delivering software products. Translation capacity must keep pace with changing product text if additional language versions are to accompany those releases. For suppliers serving software producers, the commercial task is to handle that changing workload within product delivery, making responsiveness to release-driven demand more relevant than the size of a single document assignment.
The media, gaming and entertainment segment is forecast to be the fastest-growing end-user segment, at a CAGR of 11.9% during 2027-2032. In the fiscal year ended March 2026, overseas units accounted for 89.9% of CAPCOM's Digital Contents title unit sales, with overseas units up 22.2% year over year. KRAFTON's February 12, 2025, update for James Bendon's Dinkum expanded the game to 14 official languages. Overseas unit exposure and actual language expansion illustrate why additional versions can serve an established international audience. For localization providers, each added language gives an existing title another audience to reach, creating an opening in catalog updates alongside work on new releases.
Geography Analysis
Europe Translation Services Market
Europe accounted for a 43.37% translation services market share in 2026, making it the largest geography. In 2025, the European Commission's Directorate-General for Translation outsourced 36% of its output when needed to meet demand beyond in-house capacity. In Rest of Europe, Switzerland's Federal Administration must produce German, French and Italian publications and documents, with some official texts also published in Romansh and English, making multilingual output a public duty. For a specialist supplier, the Commission's use of external capacity creates a route into institutional work through defined assignments, without requiring the supplier to replace an entire internal translation function.
Asia-Pacific Translation Services Market
Asia-Pacific is forecast to be the fastest-growing geography, at a CAGR of 14.6% during 2027-2032. New Zealand's Ministry of Business, Innovation and Employment awarded a syndicated contract on March 3, 2025, enabling government agencies to buy telephone and video interpreting services. The contract covers remote interpreting and sight translation, with a 3-year term from April 1, 2025, to April 1, 2028, and 2 renewal rights. Singapore's established whole-of-government translation framework gives agencies access to vendors evaluated for quality and price competitiveness. Shared purchasing channels can connect qualified suppliers with multiple public buyers, making procurement access a commercial consideration alongside the ability to deliver interpreting or written translation.
In North America, California's May 2026 award to 31 community groups supported broader emergency preparedness and in-language resources, creating a community-based delivery route. In South America, Brazil's Hospital Universitário da Grande Dourados shows healthcare interpreting at work, with Guarani interpreters mediating more than 2,000 encounters from March to October 2025, about 70% involving Guarani Kaiowá patients. In Rest of South America, Paraguay's DNCP published a tender on October 8, 2026, for written English-Spanish translation and oral interpretation, with offers due October 30, 2026. For the Middle East and Africa, South Africa's 2024/25 government monitoring found frequent ad hoc procurement of translation and interpreting rather than structured, long-term planning. Each channel rewards a different delivery strength, from continuity for clinical encounters to flexible capacity for irregular public orders.
Regulatory Framework and Outlook
This comparison considers selected jurisdictions from the perspective of enterprise translation suppliers serving public buyers, processing customer data or supplying qualifying AI systems. Privacy duties attach to the provider's processing role, while AI obligations depend on the system and service category. For covered generative systems placed on the market before August 2, 2026, the EU AI Act requires providers to take necessary measures to comply with Article 50(2) by December 2, 2026.
Regulatory Table of Translation Services Market
| Decision factor | United States | Germany | China | Brazil |
|---|---|---|---|---|
| Primary authority | U.S. Department of Justice (DOJ), Civil Rights Division | Federal and state data-protection authorities; Bundesnetzagentur with specified sector authorities | Cyberspace Administration of China and competent telecommunications, public-security and broadcasting authorities | Agência Nacional de Proteção de Dados |
| Key instruments or direction | Executive Order 14224 revoking Executive Order 13166; Title VI for DOJ funding recipients | GDPR Article 28; conditional AI Act transparency duties | AI-generated-content labeling measures, effective September 1, 2025 | Personal-data law (LGPD), operator requirements |
| Commercial effect | Federal agency discretion over services; continuing civil-rights duties for DOJ funding recipients | Safeguards and a binding contract or legal act for processing on customer controllers' behalf; covered interactive-AI notices unless obvious | Role-specific labeling for covered AI-content service providers | Operators follow controller instructions when processing personal data |
| Current policy attractiveness | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | Hardening | No change | No change |
| Source: Mordor Intelligence | ||||
In the United States, continuing Title VI duties for DOJ funding recipients support continuity, while agency discretion and guidance review temper the appeal of public-sector demand. Germany's processor requirements provide a defined qualification route, but the EU AI Act's December 2026 transition adds implementation work for covered AI providers in Germany, underpinning a hardening direction. China's July 2026 proposal for covered intelligent information service providers remained unadopted at CAC's August 21, 2026, action plan, leaving existing role-specific labeling duties as the basis for continuity among enterprise suppliers already covered. Brazil's operator-instruction duty supports continuity, while ANPD's October 20, 2026, agenda showed security and AI work in progress without creating an adopted new obligation.
Value Chain Stages
The value chain compares how suppliers earn from workflow access, language production and quality acceptance. RWS reported that client moves toward machine translation and pricing pressure reduced traditional translation volumes in its Language Services division in FY2025. That experience makes the allocation of paid work between automated drafting and accountable review commercially important for providers designing hybrid offers.
Value Chain Analysis Table of Translation Services Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Content intake and workflow routing | Workflow-platform providers such as RWS Group, Phrase and TransPerfect | Platform subscriptions and technology fees | Content streams and routing rules must be aligned | Validate routing before adding content streams |
| Language production | Localization providers such as RWS Group; interpreting providers such as LanguageLine Solutions | Translation, adaptation and interpreting fees | Routine written-work substitution, reported by RWS | Price specialist delivery separately from automated output |
| Linguistic testing and quality acceptance | Review and testing providers such as RWS Group | Testing and quality-review service fees | Potential mismatch between drafting and review capacity | Allocate specialist review by content consequence |
| Source: Mordor Intelligence | ||||
In FY2025, RWS reported continued growth in specialized linguistic testing with its largest technology clients and increased demand for quality review and accessibility services to validate and govern AI-powered workflows. The contrast with its traditional-volume experience points toward value in assessing whether translated content is suitable for use, alongside producing the first version. A defined acceptance task gives providers a basis for charging for review, while platform subscriptions provide a separate way to earn from the workflow.
Competitive Landscape
Market Concentration
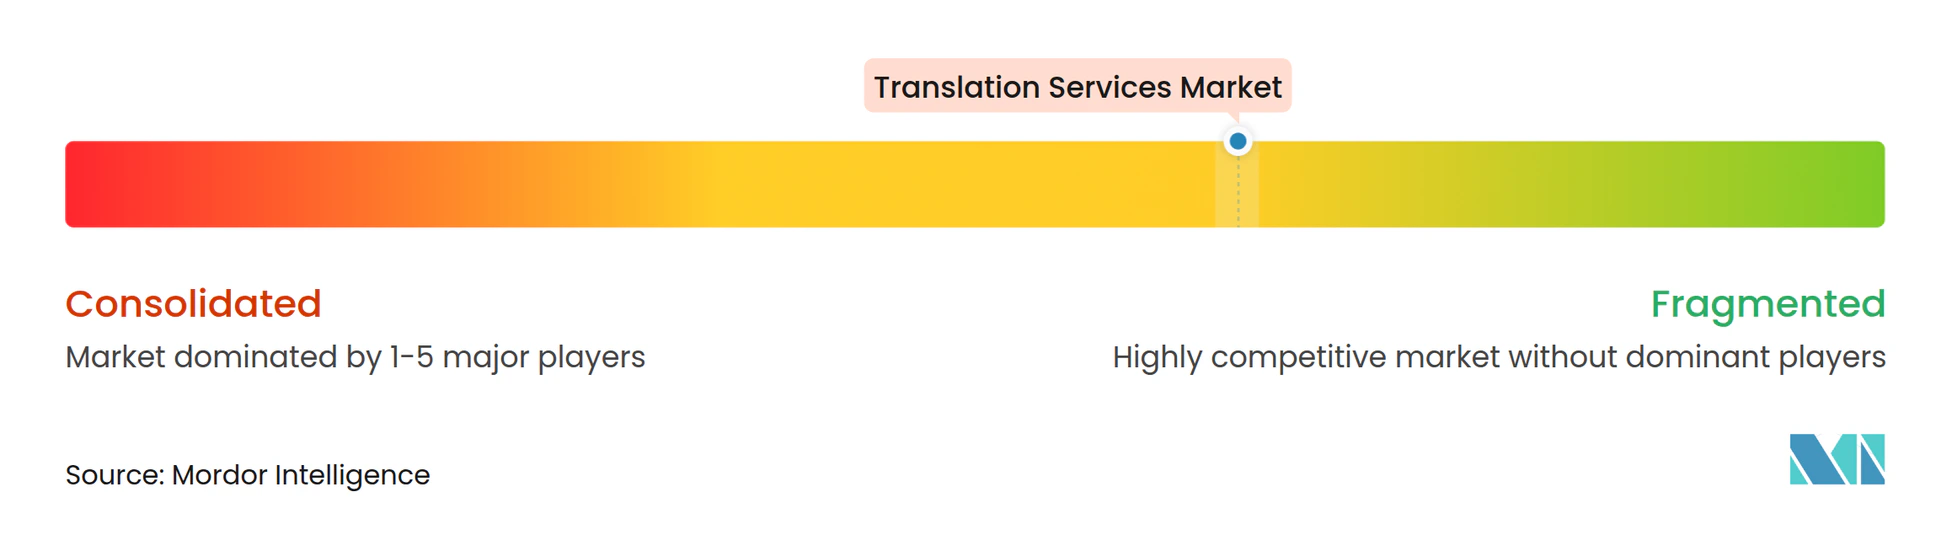
TransPerfect combines language services with its GlobalLink technology portfolio in a supplier landscape spanning platforms and staffed language delivery. Lionbridge provides language services, video-game services and over-the-phone interpretation, and on February 2, 2026, announced an ownership transition to funds managed by KKR. LanguageLine Solutions supplies phone, video and onsite interpreting, while Acolad Group combines localization and interpreting with AI-enabled technology and human services. In FY2025, RWS Group reported a linguistic network of more than 43,000 experts across 197 countries. These overlapping delivery models leave challengers an opening in particular interpreting or localization tasks, while broad groups can combine access to linguists with language technology rather than competing on geographic reach alone.
On August 22, 2025, TransPerfect acquired Unbabel, adding its TowerLLM translation model and COMET machine-translation evaluation tool to the GlobalLink technology portfolio. Owning translation generation and evaluation technology gives a supplier a basis for integrating quality checks with its wider delivery platform. For enterprise buyers, the commercial question becomes whether an integrated offer reduces handoffs between drafting, assessing and correcting multilingual content while preserving a useful basis for accepting the result. This strategy can strengthen account relationships when workflows depend on the combination, but specialist tools retain an opening where buyers need a particular function or want evaluation independent of the translation engine.
Acolad's August 2026 agreement to become part of RWS points toward closer integration of language services and content technology. Completion was expected by March 31, 2027, pending French information and consultation and regulatory approvals, with the companies operating separately until completion. LanguageLine demonstrated another competitive route through its August 2026 selection for Lot 2, telephone and video interpreting, of a 4-year Scottish Government framework for public-sector interpreting, translation and transcription services. Lot 2 will enable participating public bodies across Scotland to access LanguageLine's remote interpreting, connecting supplier capacity with a public-sector procurement channel. For buyers, regulatory clearance of combinations and framework qualification create different routes to broader offerings, making integration readiness and contract access important alongside ownership of translation technology.
Translation Services Industry Leaders
-
TransPerfect
-
Lionbridge
-
LanguageLine Solutions
-
Acolad Group
-
RWS Group
- *Disclaimer: Major Players sorted in no particular order
Translation Services Market Companies Covered in this Report
- TransPerfect
- Lionbridge
- LanguageLine Solutions
- RWS Group
- Acolad Group
- Welocalize
- Smartling
- SDL Trados (now RWS)
- Centific
- Phrase (Memsource)
- Propio Language Services
- Unbabel
- Gengo (Lionbridge)
- Appen
- BLEND (One-Hour Translation)
- TextMaster
- LanguageWire
- Pangeanic
- Straker Translations
- Bureau Works
Key Opportunities for Market Participants
The opportunities compare public buyers seeking continuous interpreting, document translation and a managed language service. Boston's October 12, 2026, solicitation calls for year-round 24/7 telephone and video interpreting. The Dutch Immigration and Naturalisation Service (IND) procurement separates primary-process translation from supporting-process and directorate work, while London's policing buyer has announced a preliminary managed-service procurement. A supplier faces different capacity commitments across these notices, from continuous interpreter availability to document work separated by administrative purpose.
Market Opportunities Table of Translation Services Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Round-the-clock municipal remote interpreting | Boston proposals due November 6, 2026 | Boston Office of Language and Communications Access | Demonstrate staffing for 24/7 phone and video coverage | Sustaining availability across all service hours | Remote-interpreting providers such as Lionbridge |
| Separate IND document-translation lots | Open procurement with bids due November 9, 2026 | Netherlands Ministry of Justice and Security for IND | Select a lot and align capacity with its document scope | Lot-one evaluation volumes provide no revenue guarantee | Enterprise translation-technology suppliers such as RWS Group |
| Managed policing translation | Engagement deadline October 20, 2026; estimated tender notice November 2, 2026 | Mayor's Office for Policing and Crime, via Metropolitan Police Service | Prepare an integrated delivery plan for the planned competition | Coordinating specialist delivery within a managed service | Enterprise translation-technology suppliers such as RWS Group |
| Source: Mordor Intelligence | |||||
The central opening is the IND's separate document-translation lots, with bids due November 9, 2026. In an October 15, 2026, clarification, the Dutch Ministry of Justice and Security said lot one's fictitious 8-million-word annual volume served price evaluation and carried no revenue guarantee. Capacity commitments sized to actual orders, rather than the evaluation scenario, keep a bidder from carrying fixed cost against billable work that the tender does not guarantee.
Recent Industry Developments in Translation Services Market
- Sep 2026: Vitruvian Partners acquired Smartling from Battery Ventures, changing ownership of the AI translation platform.
- Aug 2026: LanguageLine Solutions was selected for Lot 2 of a 4-year Scottish Government framework, which will enable participating public bodies to access its telephone and video interpreting.
- Aug 2026: Acolad entered a binding agreement to join RWS, with completion expected by March 31, 2027, pending French information and consultation and regulatory approvals. The businesses were to operate separately until completion.
Translation Services Market Report Scope and Research Methodology
Market Definition and Coverage
The translation services market measures annual spending worldwide on human and machine translation, interpretation, transcreation, multimedia localization, and the software and hardware used to deliver them. It covers purchases by organizations and individuals across industries.
Scope exclusions: General-purpose hardware and software, language education and tutoring, original content creation and production, and general-purpose cloud computing and AI infrastructure are excluded.
Segments Covered in This Report
- By Component
- Hardware
- Software
- By Operation
- Human Technical Translation
- Machine / Neural Machine Translation
- By Service
- Written Translation
- Interpretation (On-site, OPI, VRI)
- Transcreation and Multimedia Localization
- By End-User
- IT and Telecom
- BFSI
- Automotive and Manufacturing
- Healthcare and Life-Sciences
- Legal and Public Sector
- Media, Gaming and Entertainment
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public evidence such as the European Language Industry Survey, the U.S. Census Bureau's American Community Survey, the Census Bureau's retail e-commerce series, and Netflix's viewing report can show language-service business conditions, language populations, and changing multilingual content demand. These sources help analysts test demand indicators and identify relevant language-service activities, while public agency requirements and procurement records can clarify institutional service needs.
Company annual reports and investor materials can clarify the revenue mix, technology use, customer verticals, and operating changes of service and software suppliers, while reputable business press and trade publications can cross-check acquisitions, product launches, and contract activity. These named sources are illustrative, not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would seek input from translation and interpretation providers, translation-software vendors, and organizational buyers in major end-user industries, including IT and telecom, healthcare, legal services, and media. Respondents would review secondary findings on service mix, technology adoption, pricing, buyer demand, and delivery capacity, while analysts would reconcile conflicting views against public company, agency, and industry evidence. Where evidence remains sparse, estimates would be bounded with the closest observable demand and supplier indicators and the resulting gaps would be carried into the review for clarification.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 30% | EMEA: 35% |
| Smaller Players: 25% | Managers: 50% | Americas: 25% |
Market-Sizing & Forecasting
The model estimates global annual customer spending from a top-down view of translation, interpretation, localization, and translation-specific product activity, then checks selected totals with supplier revenue roll-ups and sampled service price times delivered volume. Analysts would track multilingual e-commerce activity, streaming and gaming content distributed across languages, public language-access requests and contracts, cross-border software releases, and the balance between machine-assisted and human-led work. These indicators inform service, buyer, regional, and operational demand assumptions. Segment shares would be built from supplier and buyer activity by service, component, operation, end-user, and geography, with bundled purchases counted once and allocated across components where evidence permits. A multivariate regression would relate the historical market series to these demand indicators, with scenario analysis for changes in automation, pricing, and regulated workload. Primary respondents would check the direction and plausibility of variable-level assumptions, and sparse markets would use bounded estimates informed by adjacent geographies and observable supplier activity. Value forecasts would reflect both delivered workload and price or service mix, including possible price compression in routine machine translation and higher-value specialist adaptation. Selective bottom-up checks would be reconciled to the global estimate, and material gaps would prompt review of coverage, duplicated channel revenue, or missing activity before the model is finalized.
Data Validation & Update Cycle
Analysts would triangulate the modeled total and segment splits against independent company, industry, public procurement, and demand indicators, then check year-on-year movements, shares, units, and supplier roll-ups for anomalies or unexplained variance. A second analyst would review source fit, assumptions, calculations, and reconciliations, with material outliers resolved before sign-off. Respondents would be re-contacted when a key operating assumption conflicts with observable activity or a material source change affects an estimate. The data would be refreshed annually, updated between cycles when material technology, regulatory, or market events change demand, and subjected to a fresh pre-delivery review.
Mordor Intelligence's Translation Services Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The translation services market measures annual spending worldwide on human and machine translation, interpretation, transcreation, multimedia localization, and the software and hardware used to deliver them.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. A multivariate regression would relate the historical market series to these demand indicators, with scenario analysis for changes in automation, pricing, and regulated workload.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 70.48 B (2027) | |
| Global Consultancy A | USD 27.78 B (2025) | At its 2025 base, this estimate is 60.6% below this report's 2027 value of USD 70.48 B, 2 years later. Its published 2025-2030 growth outlook is slower, supporting a lower reported trajectory. |
| Global Consultancy B | USD 42.62 B (2025) | At its 2025 base, this estimate is 39.5% below this report's 2027 value of USD 70.48 B, 2 years later. Its published 2026-2034 growth outlook is slower, supporting a lower reported trajectory. |
Mordor Intelligence's analysts would triangulate the modeled total and segment splits against independent company, industry, public procurement, and demand indicators, then check year-on-year movements, shares, units, and supplier roll-ups for anomalies or unexplained variance.
Key Questions Answered in the Report
What is the translation services market size and growth outlook?
The size was USD 64.99 billion in 2026 and is estimated at USD 70.48 billion in 2027. It is forecast to reach USD 103.9 billion by 2032, at a CAGR of 8.07% during 2027-2032.
What drives demand for translation and interpreting services?
A larger digital-content base and public-service access requirements support demand. Australia's TIS National received 1.55 million interpreting requests in fiscal 2024-25.
Which translation service category has the largest share?
Written translation led services with a 52.91% share in 2026. Transcreation and multimedia localization is forecast to be the fastest-growing service segment, at a CAGR of 12.3% during 2027-2032.
Which companies are major providers in the translation industry?
Major providers include TransPerfect, Lionbridge, LanguageLine Solutions, Acolad Group and RWS Group.
What limits translation and interpreting work in regulated sectors?
Data-use obligations and specialist capacity constrain delivery. In the United States, HIPAA business-associate contracts must restrict uses and disclosures and require safeguards when contractors handle protected health information for covered providers.
Which regions lead translation services demand and forecast growth?
Europe held the largest share at 43.37% in 2026. Asia-Pacific is forecast to grow fastest at a CAGR of 14.6% during 2027-2032.