
Philippines Retail Market Analysis by Mordor Intelligence
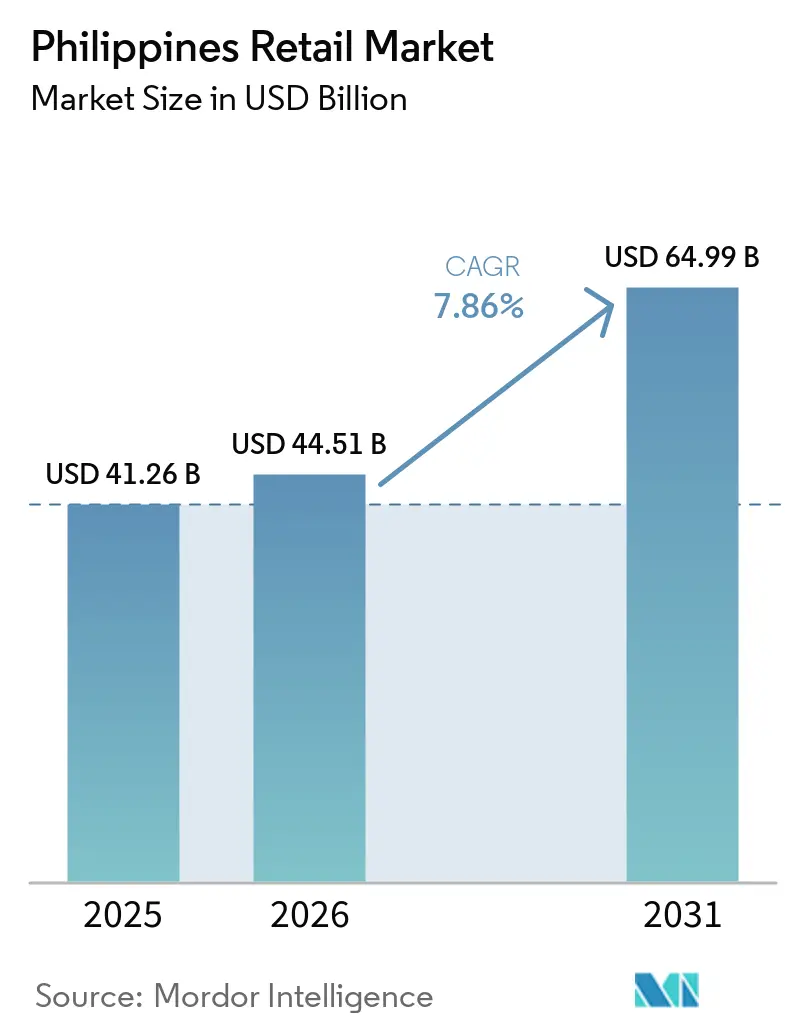
The Philippines retail market size is projected to expand from USD 44.51 billion in 2026 and USD 48.01 billion in 2027 to USD 68.67 billion by 2032, registering a CAGR of 7.42% between 2027 and 2032.
In the Philippines, higher average family incomes and wider digital-payment use support retail demand through grocery stores and online channels. Broader checkout options can increase spending at convenience stores, while category-specific online offers complement differentiated physical formats. Higher power and logistics costs can absorb part of that additional spending, making the cost of serving each outlet or order central to store earnings. Convenience operators can pursue larger baskets at existing counters, while grocery delivery expands profitably only where each extra order covers its fulfillment cost.
Key Report Takeaways
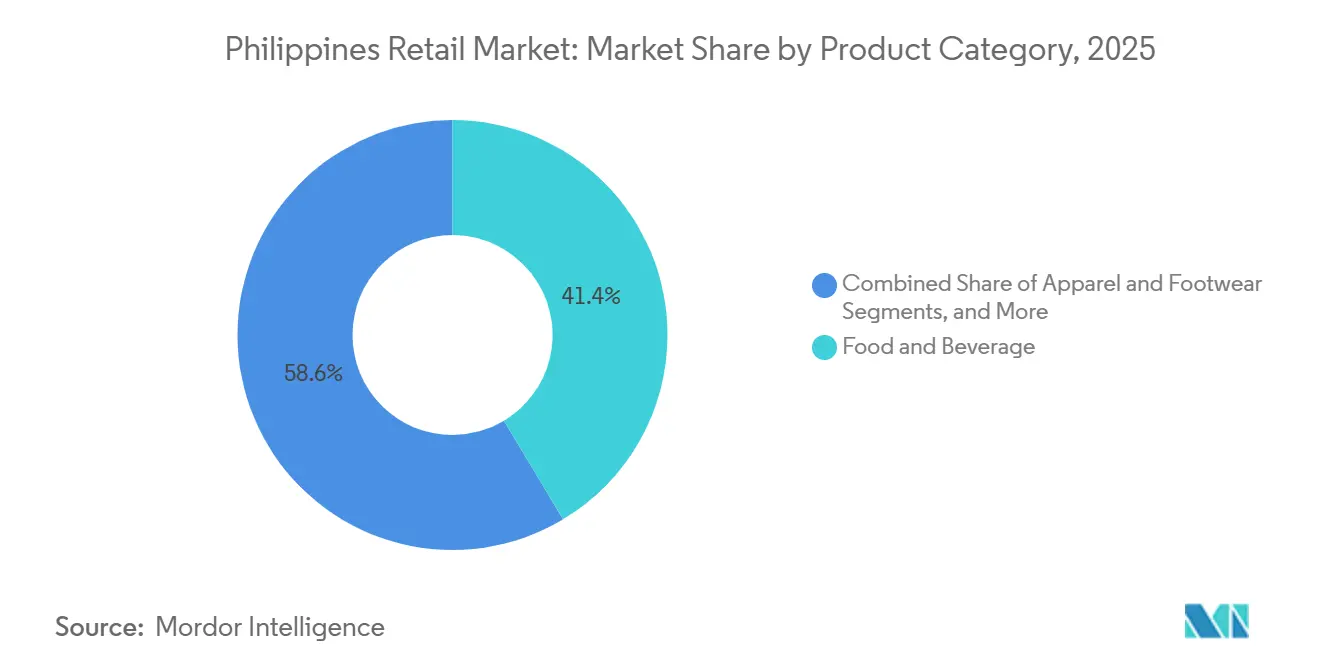
- Across product categories, food and beverage led with a 41.18% Philippines retail market share in 2026, while health, beauty and personal care is forecast to grow fastest at an 11.45% CAGR between 2027 and 2032.
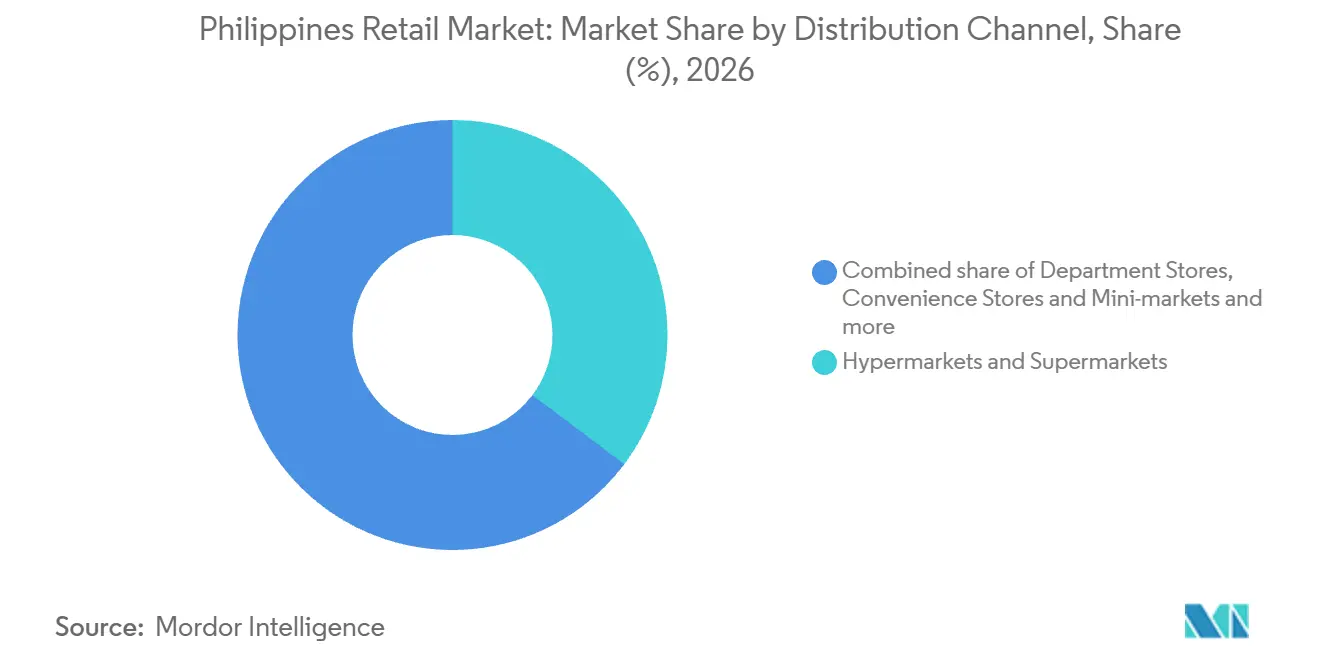
- In distribution channels, hypermarkets and supermarkets held a 35.26% share of the Philippines retail market size in 2026, with online retail projected to grow fastest at a 7.95% CAGR between 2027 and 2032.
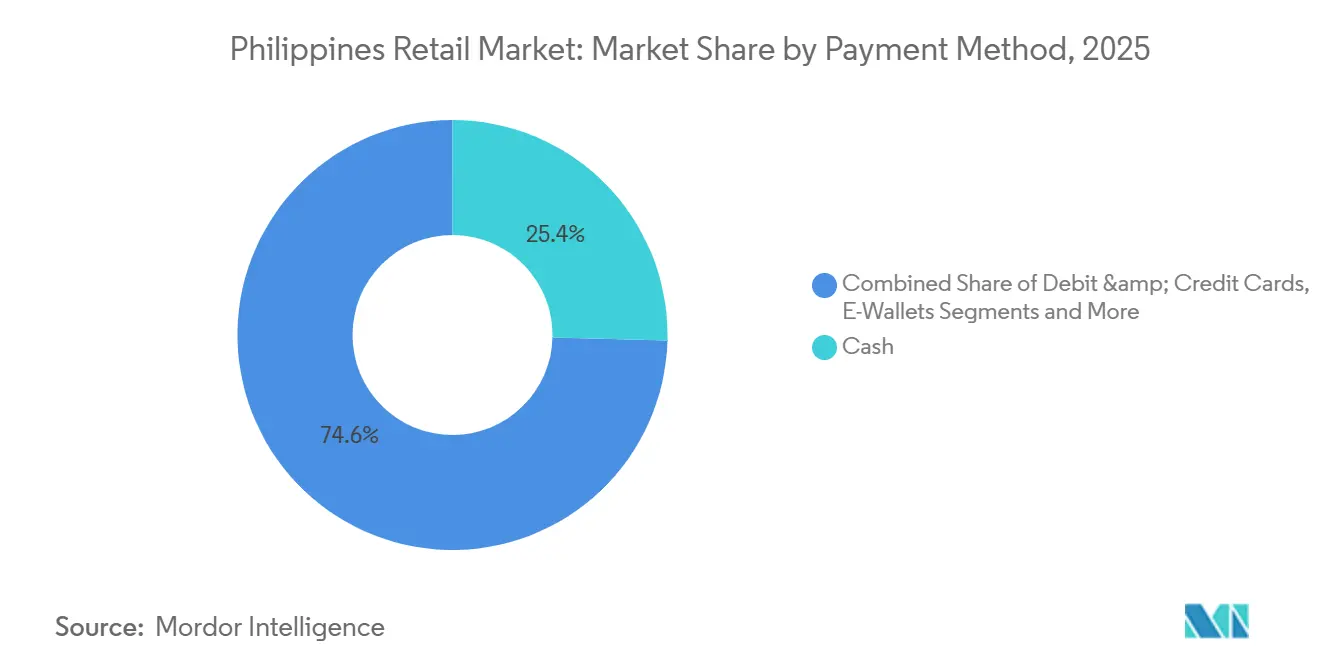
- By payment method, cash led with a 25.14% share of the retail industry in the Philippines in 2026, whereas e-wallets are forecast to grow fastest at a 13.15% CAGR between 2027 and 2032.
- Geographically, Luzon accounted for the largest Philippine retail industry share at 59.36% in 2026, and Mindanao is projected to grow fastest at a 7.55% CAGR between 2027 and 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Philippines Retail Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising disposable incomes & expanding middle class | +2.5% | Nationwide | Medium term (2-4 years) |
| Accelerating e-commerce adoption & digital payments | +2.9% | Nationwide | Short term (≤ 2 years) |
| Growth of convenience-oriented F&B retailing | +1.9% | Nationwide | Short term (≤ 2 years) |
| Government logistics infrastructure improvements | +0.9% | Samar and Leyte | Medium term (2-4 years) |
| Overseas remittances fueling discretionary consumption | +0.8% | Nationwide | Short term (≤ 2 years) |
| Emergence of micro-fulfillment “dark stores” | +0.5% | Metro Manila, Baguio, Cebu and Davao | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising disposable incomes & expanding middle class
Rising family income and faster-growing household expenditure point to demand expansion accompanied by pressure on spending choices. The Philippine Statistics Authority reported that average annual family income in the Philippines rose 16.5% from 2023 to 2025. Average annual family expenditure increased 24.7% over the same period. A larger spending base can support merchandise demand, but faster expenditure growth raises the risk of relying only on premium purchases. Where outlays are outgrowing income, stocking an entry price tier next to premium lines can help retailers compete for additional spending.
Accelerating e-commerce adoption & digital payments
Checkout access can broaden a convenience store’s customer base as digital payments become more widely used. Digital payments accounted for 64.7% of Philippine retail-payment volume in 2025, up from 57.4% in 2024, according to the Bangko Sentral ng Pilipinas.[1] Philippine Seven equipped more than 1,000 7-Eleven stores with card-payment terminals during October-December 2025. The company said the initiative generated more than 6% of sales in those locations and attracted new customers with larger average baskets. Those reported sales and larger baskets make card acceptance a commercial lever within existing stores, beyond its role as a checkout convenience.
Growth of convenience-oriented F&B retailing
Convenience-oriented food retailing can deepen the use of an established store network as well as support additional locations. At its August 18, 2026 investor-day presentation, Philippine Seven Corporation said food service, including ready-to-eat rice meals, sandwiches and snack foods, contributed 20% of its total revenues. The operator had 4,491 7-Eleven stores in the Philippines at year-end 2025. For food suppliers, that combination offers a route to consumers through a large operating network, while giving the retailer another reason for shoppers to use the convenience format. Shoppers can access a broader prepared-food range through Philippine Seven’s operating outlets before new sites open, separating food assortment expansion from the pace of network growth.
Government logistics infrastructure improvements
Restoring an interrupted freight link can improve retail supply without requiring operators to build additional stores. San Juanico Bridge reopened to 15-ton trucks on December 12, 2025, allowing cargo trucks to cross between Samar and Leyte. The reopening was partial, with bridge repairs unfinished at that time. Cargo access across that link can support replenishment for stores on either side by reopening a route for trucks that previously could not cross. Permitted truck weight determines which replenishment loads retailers on Samar and Leyte can route through the restored crossing.
Restraints Impact Analysis of Philippines Retail Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Chronic traffic congestion & last-mile inefficiencies | -0.7% | Nationwide | Short term (≤ 2 years) |
| Rising utility and operating costs for modern formats | -0.9% | Nationwide | Medium term (2-4 years) |
| Dominance of informal sari-sari stores | -0.3% | Nationwide | Long term (≥ 4 years) |
| VAT equalization on foreign e-commerce platforms | -0.2% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Chronic traffic congestion & last-mile inefficiencies
Grocery delivery in Philippine cities loses fleet time to traffic before an order reaches the customer. If a vehicle spends more operating time in traffic, the same fleet has less time available for store replenishment or doorstep deliveries. Longer trips reduce the number of deliveries a vehicle can complete within its operating hours, so wider coverage can stretch fleet capacity. For low-value orders, a higher delivery effort can absorb more of the value earned on the merchandise. A trip that earns little on a low-value order leaves an operator choosing between a narrower delivery radius and thinner margins.
Rising utility and operating costs for modern formats
Modern retail expansion must generate enough store earnings to absorb recurring operating costs. At its August 2026 investor day, Philippine Seven Corporation said increased utility and logistics costs were pressuring its profit margins. That pressure raises the earnings hurdle for additional locations even when merchandise sales offer expansion potential. Each added store carries utility and logistics costs that its own sales must cover before it adds to chain earnings. The company said it was switching stores to renewable suppliers through the Retail Aggregation Program, seeking savings, although digital-meter availability hindered full transition. Until that procurement change delivers savings, the operator bears the higher cost against the same store-level earnings requirement.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Philippines Retail Market Segment Analysis
By Product Category:
Food Spending Anchors Demand While Beauty Broadens AccessFood and beverage accounted for a 41.18% share of the Philippines retail market size in 2026, making it the largest segment. In 2025, food and non-alcoholic beverages accounted for 33.3% of Filipino families’ total expenditure, the largest expenditure group.[2] That concentration of family expenditure gives food retailers a substantial demand base, while making their commercial reach depend on which household food purchases their assortments can serve. Retailers that serve routine food baskets reliably tap this established budget, making repeat food shopping commercially significant alongside discretionary purchases.
Health, beauty and personal care is the fastest-growing segment in the Philippines retail market, with a projected CAGR of 11.45% between 2027 and 2032. In September 2025, SM Beauty offered more than 1,000 beauty brands across its 77 Philippine branches. That breadth lets shoppers seek global premium brands within the same retail network as a wider beauty assortment. Consumer electronics and appliances bring different requirements, with Robinsons Retail naming durability, energy efficiency and a strong service network among customers’ top requirements when choosing consumer electronics and home appliances. Beauty’s opportunity centers on broadening access to a varied assortment, while appliance retailers must connect product selection with a service proposition that addresses those stated requirements.



By Distribution Channel:
Supermarket Scale Meets Digital and Neighborhood Shopping NeedsHypermarkets and supermarkets represented a 35.26% Philippines retail market share in 2026, making them the largest segment. USDA FAS estimated Philippine supermarket sales at USD 12.2 billion for 2025. Food made up the majority of sales in that supermarket estimate. This food-weighted base gives grocery suppliers a substantial route through organized retail.
Online retail is the fastest-growing segment in the Philippines retail market, with a projected CAGR of 7.95% between 2027 and 2032. E-commerce accounted for 32.2% of Philippine digital-economy gross value added in 2025. Digital commercial activity creates an established setting for retail ordering, but an online channel must convert access into delivered merchandise to earn its role in household spending. Traditional sari-sari stores offer consumers living on or below minimum wage small food purchases and credit suited to seasonal or daily income. Small purchases on credit can preserve a role for neighborhood stores because a wider online assortment alone does not address the timing of daily or seasonal income.

By Payment Method:
Cash Access Coexists With Wallet AdoptionCash was the largest segment, accounting for a 25.14% share of retail sales in 2026. Worldpay’s Global Payments Report 2026 reported that cash accounted for 42% of Philippine point-of-sale transaction value in 2025. This puts physical-store access at the center of cash’s role, even when a retailer also invests in digital options. A retailer that builds physical checkout solely around app access would narrow the payment route despite the substantial cash use indicated by in-person transactions.
E-wallets are the fastest-growing segment in the Philippines retail market, with a projected CAGR of 13.15% between 2027 and 2032. GCash ranked first among Philippine finance apps by monthly active users in December 2025, based on Sensor Tower. G-Xchange Inc., a Mynt company, operates the GCash wallet. Accepting GCash at checkout lets a retailer reach that audience through an app shoppers already use, lowering the effort of starting wallet purchases.
Geography Analysis
Luzon Retail Market
Luzon accounted for a 59.36% share of the Philippines retail market size in 2026, making it the largest geography. SM Investments reported that Alfamart Philippines opened 280 new minimart grocery stores within Luzon in 2025. At year-end 2025, Alfamart’s Philippine network comprised 2,309 stores, mostly outside Metro Manila, with its minimarts primarily in residential neighborhoods. The Luzon openings show how neighborhood grocery access adds to the region’s retail supply base.
Mindanao Retail Market
Mindanao is the fastest-growing geography, with a projected CAGR of 7.55% between 2027 and 2032. Packworks’ 2025 app-network figures for the Bangsamoro Autonomous Region in Muslim Mindanao (BARMM) showed app-active sari-sari stores up 116%, gross merchandise value up 119% and transactions up 97%. By August 2025, Puregold Price Club Inc. had opened a supermarket branch in Sindangan, Zamboanga del Norte. Packworks’ app-network activity in BARMM and the single supermarket opening in Sindangan show distinct routes to retail access within Mindanao, with small-store participation and organized grocery capacity serving different local settings.
Visayas expansion can improve access to several retail formats while Metro Retail’s consolidated results show rising but contained operating costs. By June 2026, Metro Retail Stores Group had launched Metro Naval in Naval, Biliran, combining market, department-store and home-lifestyle offerings for communities across Biliran Province. The group’s company-wide operating expenses rose 4.8% in the first half of 2026 versus the same period in 2025 due to higher contracted-services, repair, utility and personnel costs. New sites and mandated minimum-wage increases contributed to personnel and contracted-services costs, while consolidated operating income rose 22.8% over the same period. Revenue gains and cost control can give this expanding retailer room to serve provincial communities while absorbing a larger expense base.
Regulatory Framework and Outlook
The selected jurisdictions comparison examines national online-retail duties and Iloilo Province’s regulation of retail packaging from the perspective of a formal retailer operating physical and online channels. For qualifying business-to-business and business-to-consumer internet transactions, the Internet Transactions Act places primary liability for consumer claims on e-retailers and online merchants. Iloilo’s provincial ordinance regulates single-use plastics and Styrofoam for goods and commodities and promotes native baskets, eco-bags and other biodegradable and recyclable materials. This separates accountability for the transaction from the materials used to handle goods, creating distinct compliance decisions for the same operator.
Regulatory Table of Philippines Retail Market
| Decision factor | Philippines | Iloilo Province |
|---|---|---|
| Primary authority | DTI E-Commerce Bureau; Bureau of Internal Revenue (BIR) | Environmental Program Management Services Division |
| Key instruments or direction | Republic Act No. 11967; BIR registration-seal display requirement | Provincial Ordinance No. 2019-193 regulating single-use plastics and Styrofoam for goods and commodities |
| Commercial effect | Seller pricing, delivery-condition and primary liability duties; registration-proof display for covered online businesses | Regulated packaging-material use; native baskets, eco-bags and other biodegradable and recyclable alternatives promoted |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | No change |
| Source: Mordor Intelligence | ||
The national Medium rating balances clear seller obligations against registration-display work, with relief from penalties solely for non-display running through October 31, 2026. The specified end of that relief supports a hardening direction for covered online operations. Iloilo Province’s Medium rating reflects regulated material choice with promoted alternatives, backed by provincial compliance monitoring at Janiuay Public Market on April 23, 2025. The August 13, 2026 review concerned a proposed circular economy ordinance, leaving the existing packaging framework operative and supporting a No change direction.
Value Chain Stages
The value-chain comparison follows produce sourcing, merchandise consolidation, store delivery and retail operations to show how participants earn revenue. On September 17, 2025, Nueva Vizcaya Agricultural Terminal Inc. delivered 1,900 kilograms of Satsuma citrus to 6 Robinsons Supermarket branches in Metro Manila.[3] The delivery connected a produce terminal with several supermarket branches, making multi-branch distribution part of the supplier’s route to produce sales.
Value Chain Analysis Table of Philippines Retail Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Produce sourcing | Produce suppliers and terminals such as Nueva Vizcaya Agricultural Terminal Inc. | Produce sales | Matching shipment volume with branch orders | Aggregate orders across served branches |
| Merchandise consolidation | Distribution-center operators such as Robinsons Retail Holdings Inc. | Retail merchandise sales supported by internal distribution | Dispatch timing varies by segment and destination | Align release schedules with destination dispatch windows |
| Store delivery | Third-party logistics providers such as FAST Logistics Group | Space-based transport charges | Smaller consignments may not fill a truck | Consolidate shipments from several shippers |
| Retail operations | Convenience-store franchisors such as Philippine Seven Corporation | Franchisor share of store profits | Back-office workload competes with store selling | Use franchisor bookkeeping and maintenance support |
| Source: Mordor Intelligence | ||||
In 2025, Robinsons Retail’s nonperishable cross-docking dispatch windows ranged from 1 to 5 days in Metro Manila and 3 to 10 days in the Visayas and Mindanao, depending on business segment. The longer dispatch windows for the Visayas and Mindanao require more scheduling allowance between supplier receipt and release to stores. For suppliers shipping nonperishable goods to Robinsons stores in the Visayas and Mindanao, dispatch can take up to 10 days after receipt, before onward delivery.
Competitive Landscape
Market Concentration
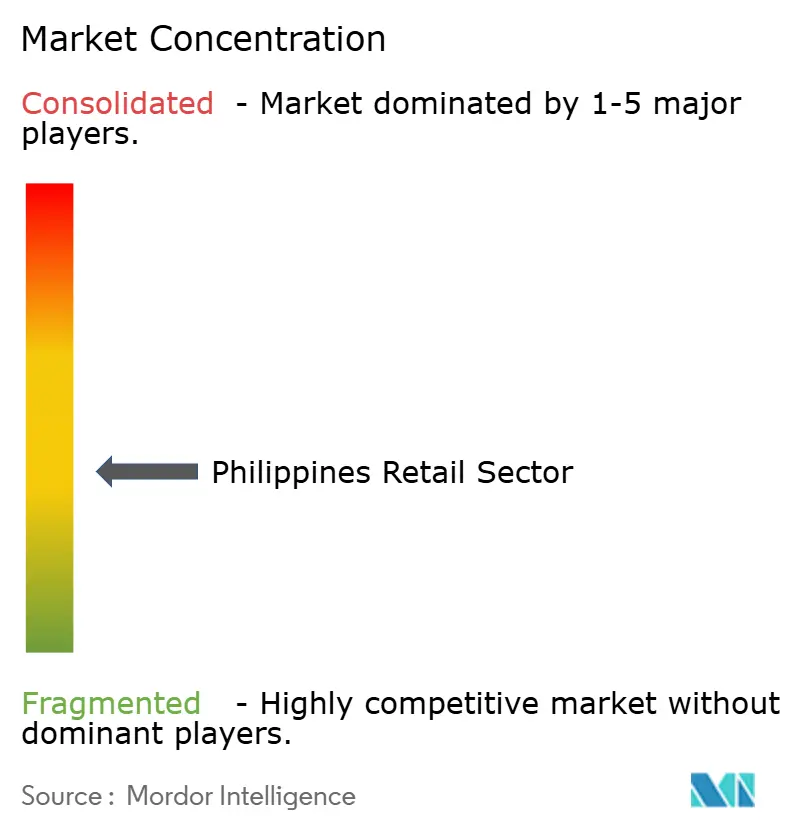
Competition combines large multi-format groups with specialized retailers, creating a moderately fragmented structure with several routes to household spending. SM Investments Corp. (SM Retail Inc.) participates through retail subsidiaries, including beauty retailer SM Beauty. Robinsons Retail Holdings Inc. operated 2,763 stores across food, drugstore, department-store, do-it-yourself and specialty retail at year-end 2025, excluding 2,154 TGP franchised stores. Grocery retailer Puregold Price Club Inc. opened 28 Puregold stores and 3 S&R Membership Shopping warehouses during 2025. These networks create a substantial execution hurdle for challengers seeking comparable breadth, while leaving room for competitors focused on a particular format or shopping occasion.
Metro Retail Stores Group Inc. had opened its first Negros Oriental site in Bais City by November 2025, combining a supermarket and department store. Its separate Metro Corner format in Mandaue City offered essentials, artisan goods and international specialties. SSI Group Philippines operated 628 specialty stores across approximately 110 Philippine malls and represented 102 brands in its own portfolio at year-end 2025. For suppliers, a combined grocery and department-store site creates a different point of access from a mall specialty portfolio, so distribution choices turn on the shopping mission each format can serve.
In 2025, Robinsons Retail launched an e-commerce site for appliances and electronics through Robinsons Appliances. In September 2025, the Department of Trade and Industry (DTI) said DAO No. 25-12 required online merchants, e-retailers, e-marketplaces and digital platforms to register for the E-Commerce Philippine Trustmark by September 30, 2025. DTI’s FAQ describes application as voluntary. SSI opened 43 stores and closed 21 in the fourth quarter of 2025. SSI’s simultaneous openings and closures show physical expansion reshaping its specialty network, while Robinsons’ appliance site extends an established group’s category offer online.
Philippines Retail Industry Leaders
-
SM Investments Corp. (SM Retail Inc.)
-
Robinsons Retail Holdings Inc.
-
Puregold Price Club Inc.
-
Metro Retail Stores Group Inc.
-
SSI Group Philippines
- *Disclaimer: Major Players sorted in no particular order
Philippines Retail Market Companies Covered in this Report
- SM Investments Corp. (SM Retail Inc.)
- Puregold Price Club Inc.
- Robinsons Retail Holdings Inc.
- Metro Retail Stores Group Inc.
- SSI Group Philippines
- Rustan Supercenters Inc.
- Alfamart Philippines
- Philippine Seven Corp. (7-Eleven)
- Golden ABC Inc.
- Mercury Drug Corp.
- Rose Pharmacy Inc.
- Ever Bilena Cosmetics Inc.
- AllDay Marts Inc.
- Landers Superstore / S&R
- Gaisano Capital Group
- Prince Retail Group
- WalterMart (WM Retail)
- LCC Supermarket
- Davao Central Warehouse Club Inc.
- Uncle John's
Key Opportunities for Market Participants
The opportunity comparison assesses how round-the-clock online grocery service can support distinct plays in shopping availability, supplier access and city-focused operations. In March 2026, foodpanda Philippines shifted pandamart to 24/7 operations, with service live in major urban centers including Metro Manila, Baguio, Cebu and Davao. Its distribution centers are dedicated exclusively to online orders, making service hours and hub-based merchandise supply practical dimensions on which suppliers and operators can develop a commercial offer.
Market Opportunities Table of Philippines Retail Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| After-hours online grocery assortments | Deployed round-the-clock service window | Urban online grocery shoppers | Prioritize core grocery needs during additional service hours | Additional hours must earn their staffing and delivery costs | Online grocery operators such as foodpanda Philippines |
| Supplier access to order-only hubs | Distribution centers dedicated to online orders | Grocery suppliers and hub buying teams | Aggregate replenishment for a defined hub assortment | Supply frequency must match hub sell-through | Grocery suppliers and online grocery operators |
| City-focused online grocery coverage | Live-service examples in Baguio, Cebu and Davao | Online grocery operators serving these urban areas | Develop merchandising and dispatch plans for each served city | Each city must support its own cost to serve | foodpanda Philippines and prospective urban fulfillment providers |
| Source: Mordor Intelligence | |||||
The central opening is to make a demonstrated service window commercially productive within the urban hubs it can serve. A focused grocery offer can target additional shopping occasions while keeping the merchandise and operating commitment proportionate to the orders it attracts. Operators can test each hub’s extra-hour demand against its staffing and delivery cost before committing to the next city.
Recent Industry Developments in Philippines Retail Market
- Sep 2026: Metro Retail Stores Group Inc. opened Metro Living in the Home Section of its existing Metro Department Store at Market! Market! on September 18.
- Jun 2026: Metro Retail Stores Group launched Metro Naval in Naval, Biliran, combining market, department-store and home-lifestyle offerings at one retail destination.
- Feb 2026: In partnership with Robinsons Retail Holdings Inc., Konvy opened its first Philippine store at Robinsons Galleria in Quezon City on February 6, offering beauty brands and its private-label products.
Philippines Retail Market Report Scope and Research Methodology
Market Definition and Coverage
The Philippines retail market measures annual household spending on consumer goods sold by retailers in the Philippines at final ticket value, converted from pesos to USD using annual average exchange rates. It classifies sales by product category, retail channel, payment method, and region.
Scope exclusions: Wholesale trade, duty-free shops serving tourists, and offshore e-commerce orders fulfilled outside the country are excluded.
Segments Covered in This Report
- By Product Category
- Food and Beverage
- Apparel and Footwear
- Consumer Electronics and Appliances
- Home and Furniture
- Health, Beauty and Personal Care
- Others
- By Distribution Channel
- Hypermarkets and Supermarkets
- Department Stores
- Convenience Stores and Mini-markets
- Specialty Stores
- Traditional (Warung / Kiosks)
- Online
- By Payment Method
- Cash
- Debit & Credit Cards
- E-Wallets
- Bank Transfers / Pay-Later
- By Geography
- Luzon
- Visayas
- Mindanao
Data Sources, Market Sizing, and Validation
Desk Research
Secondary research draws on sources such as the Philippine Statistics Authority's household expenditure and domestic trade series to frame consumption and merchandise movement, the Bangko Sentral ng Pilipinas' retail payment reporting to assess payment use, the USDA Foreign Agricultural Service's Retail Foods Annual for supermarket and food-channel context, and World Bank household consumption indicators for the wider spending backdrop. These sources inform category demand, channel coverage, geographic variation, price movement, currency conversion inputs, and the distinction between household purchases and upstream trade.
Company annual reports, investor presentations, regulatory filings, retailer announcements, and reputable business press provide cross-checks on store networks, sales trends, online operations, and format expansion. The named sources are illustrative and are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Structured interviews and surveys would cover Philippine retailers across food, apparel, electronics, home, health and beauty, and general merchandise, including modern chains, traditional trade operators, online merchants, and payment or distribution specialists. Respondents would include executives, functional leaders, and managers who can explain sales definitions, channel overlaps, category mix, and regional operating conditions. Their input would test secondary-source interpretations and clarify missing splits or inconsistent definitions, with unresolved gaps triangulated against independent company disclosures, government data, and observed market indicators.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
A top-down estimate would anchor household retail spending in the Philippines and isolate sales of consumer goods at the retailer's final ticket value, excluding wholesale resale, duty-free sales to tourists, and offshore e-commerce orders fulfilled outside the country. Analysts would reconcile household consumption by purpose, retail trade indicators, company sales disclosures, and reported format activity, then convert peso values using annual average exchange rates. A selective bottom-up check would multiply sampled retailer or channel sales by store counts or transaction volumes and average selling prices where those inputs are disclosed, using supermarket, convenience, specialty, traditional, and online evidence to test totals rather than build a wholly bottom-up model. Product, channel, payment, and regional shares would be derived from compatible published splits, company disclosures, trade indicators, and respondent checks, with residual categories used only to reconcile identified coverage gaps. Forecasts would use scenario analysis informed by household income and expenditure, population and household formation, retail price movements, digital payment adoption, store expansion, and logistics access, while analysts would separately check value growth for price and mix effects and test variable-level assumptions with relevant Philippine market specialists. Where source definitions or years do not align, analysts would retain the closest documented series, adjust only for supported coverage and timing differences, and use ranges or scenarios rather than fill unsupported detail.
Data Validation & Update Cycle
Analysts would triangulate the estimate against household spending, retail trade activity, payment trends, company disclosures, and selective channel roll-ups, then investigate outliers, unexplained year-to-year changes, and material differences from comparable estimates before sign-off. A second review would check the market boundary, source dates, exchange-rate treatment, unit consistency, segment shares, and calculations, with re-contact triggered when respondent evidence conflicts with published disclosures or a material definition remains unclear. The model would be refreshed annually, reviewed between cycles after material economic, regulatory, or industry events, and subjected to a fresh pre-delivery review.
Mordor Intelligence's Philippines Retail Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Philippines retail market measures annual household spending on consumer goods sold by retailers in the Philippines at final ticket value, converted from pesos to USD using annual average exchange rates.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Product, channel, payment, and regional shares would be derived from compatible published splits, company disclosures, trade indicators, and respondent checks, with residual categories used only to reconcile identified coverage gaps.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 48.01 B (2027) | |
| Global Consultancy A | USD 74.8 B (2025) | At its 2025 base, this estimate is 55.8% above this report's 2027 value of USD 48.01 B, 2 years later. Its broad retail coverage does not state the same final-ticket household goods boundary or exclusions. |
| Global Consultancy B | USD 107.7 B (2025) | At its 2025 base, this estimate is 124.3% above this report's 2027 value of USD 48.01 B, 2 years later. Its 2020 forecast assumed sharp post-pandemic retail-sales growth in 2021 and 2022. |
Mordor Intelligence's analysts would triangulate the estimate against household spending, retail trade activity, payment trends, company disclosures, and selective channel roll-ups, then investigate outliers, unexplained year-to-year changes, and material differences from comparable estimates before sign-off.
Key Questions Answered in the Report
What is the Philippines retail market size and growth outlook?
The industry is projected to expand from USD 48.01 billion in 2027 to USD 68.67 billion by 2032, registering a CAGR of 7.42% between 2027 and 2032.
What is driving retail demand in the Philippines?
Higher family incomes, digital payment access and convenience-oriented food retailing support demand. Digital payments accounted for 64.7% of Philippine retail-payment volume in 2025.
Which product category leads Philippine retail sales?
Food and beverage led with a 41.18% share in 2026. Health, beauty and personal care is forecast to grow fastest at an 11.45% CAGR between 2027 and 2032.
Which companies are major retailers in the Philippines?
Major players include SM Investments Corp. (SM Retail Inc.), Robinsons Retail Holdings Inc., Puregold Price Club Inc., Metro Retail Stores Group Inc. and SSI Group Philippines.
What operating challenge could limit retail expansion?
Philippine Seven reported utility and logistics cost pressure on margins at its August 2026 investor day. These costs raise the earnings hurdle for adding stores.
Which Philippine region has the strongest growth outlook?
Mindanao is forecast to grow fastest at a 7.55% CAGR between 2027 and 2032. Luzon led with a 59.36% share in 2026.