
Indonesia Real Estate Market Analysis by Mordor Intelligence
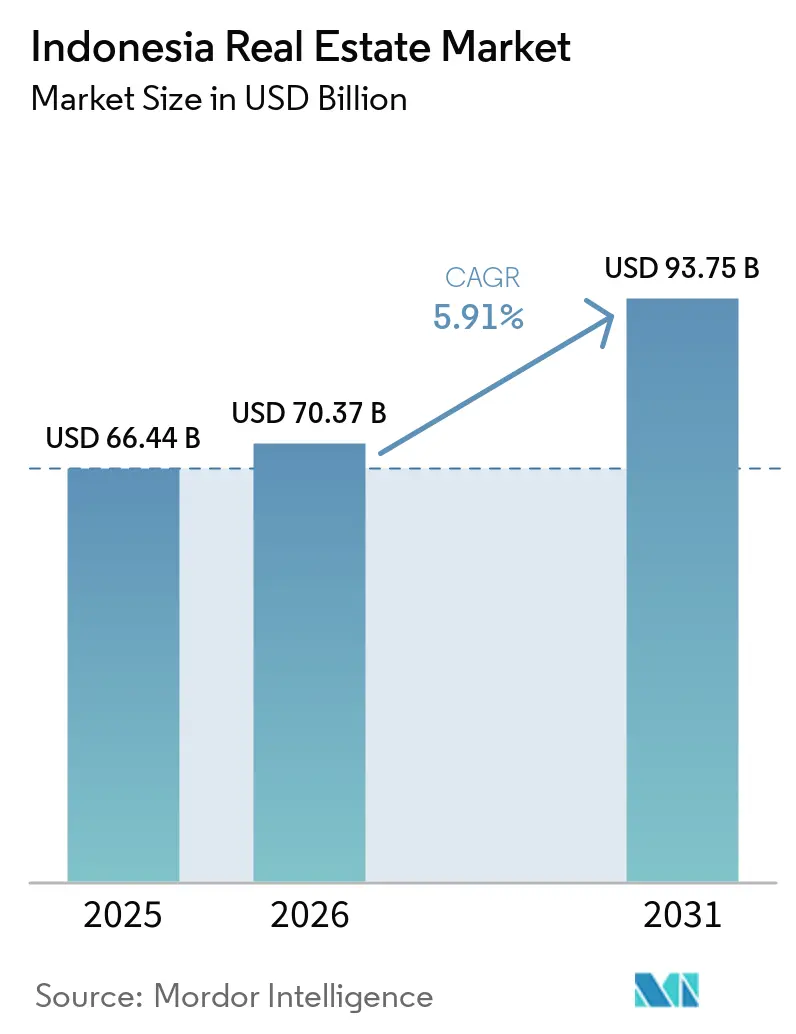
The Indonesia real estate market size is expected to increase from USD 70.37 billion in 2026 to USD 74.53 billion in 2027 and reach USD 97.04 billion by 2032, growing at a CAGR of 5.42% over 2027-2032.
Housing-finance access and demand for usable warehouse and hospitality space support property activity in Indonesia. Land-use uncertainty and construction-cost pressure can interrupt the conversion of that demand into completed, occupied assets. Subsidized financing for landed homes addresses buyers' access to ownership, while industrial and hospitality demand creates a separate opening for space ready for occupation. Finished landed homes for financed buyers and operating-ready commercial space are consequently less exposed to the land-use decisions and building-cost changes that can delay new construction.
Key Report Takeaways
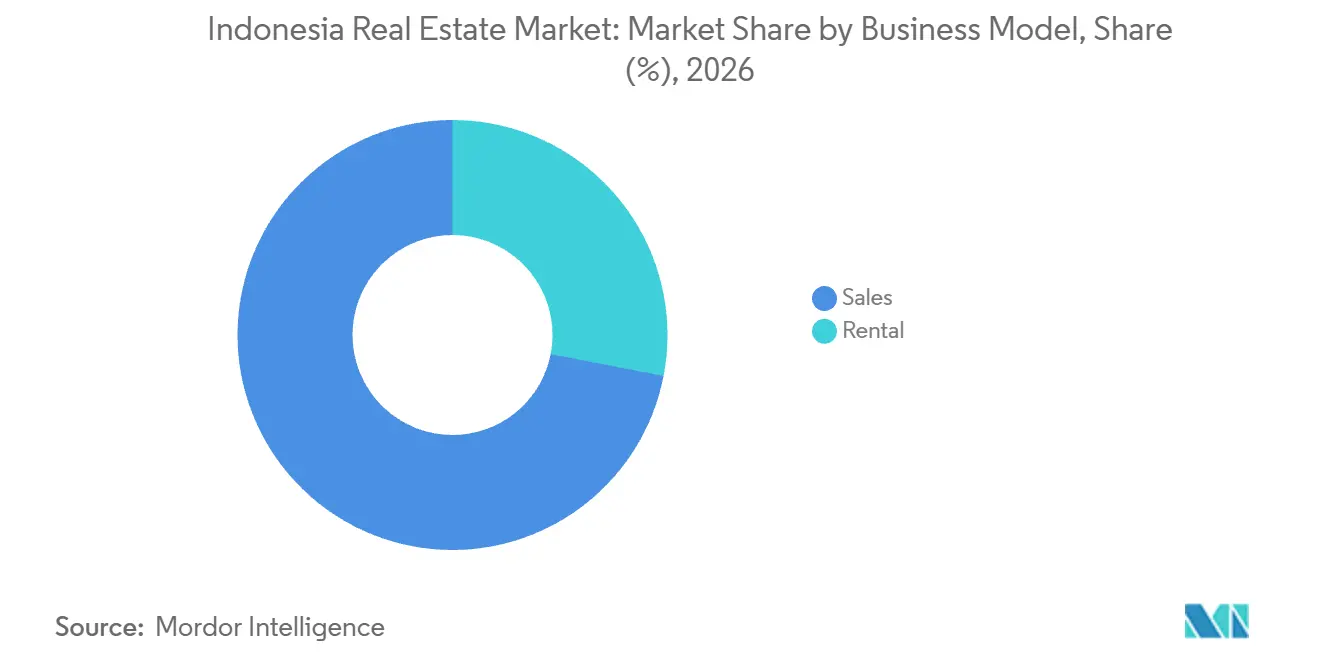
- By business model, sales held a 71.95% Indonesia real estate market share in 2026, while rental is forecast to grow fastest at a CAGR of 6.45% over 2027-2032.
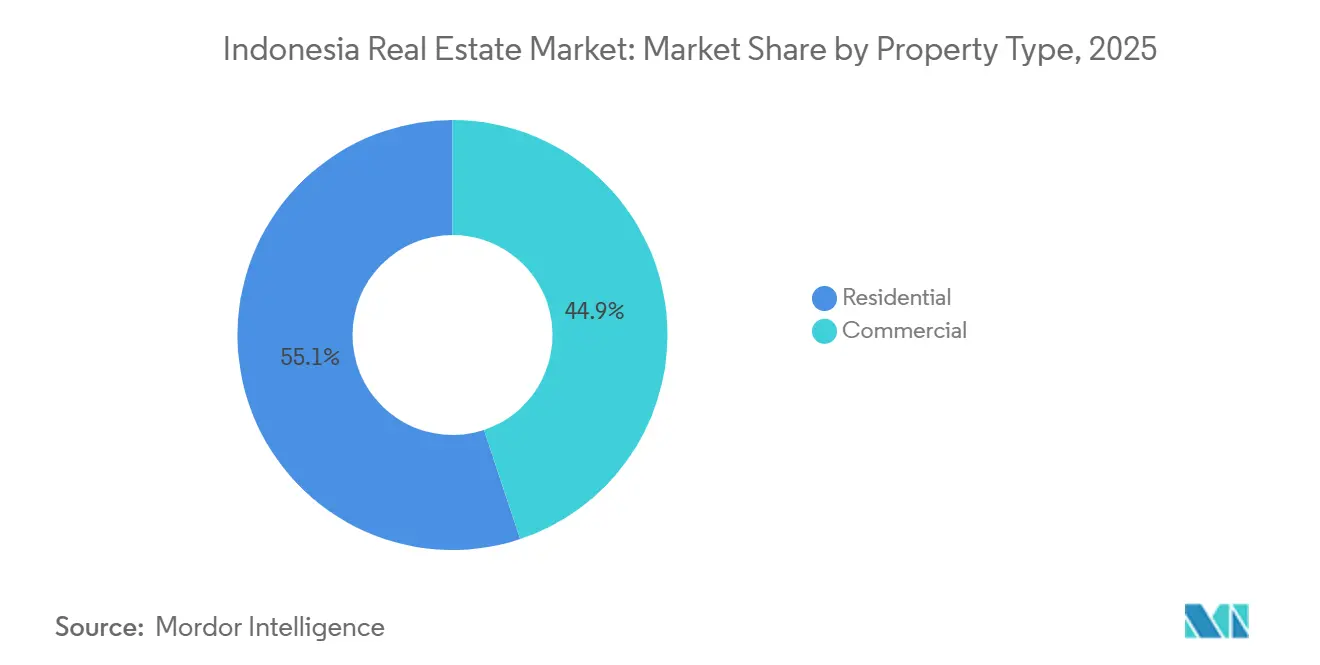
- Residential led property types with a 54.79% share of the Indonesia real estate market size in 2026, and commercial is projected to grow fastest at a CAGR of 6.15% over 2027-2032.
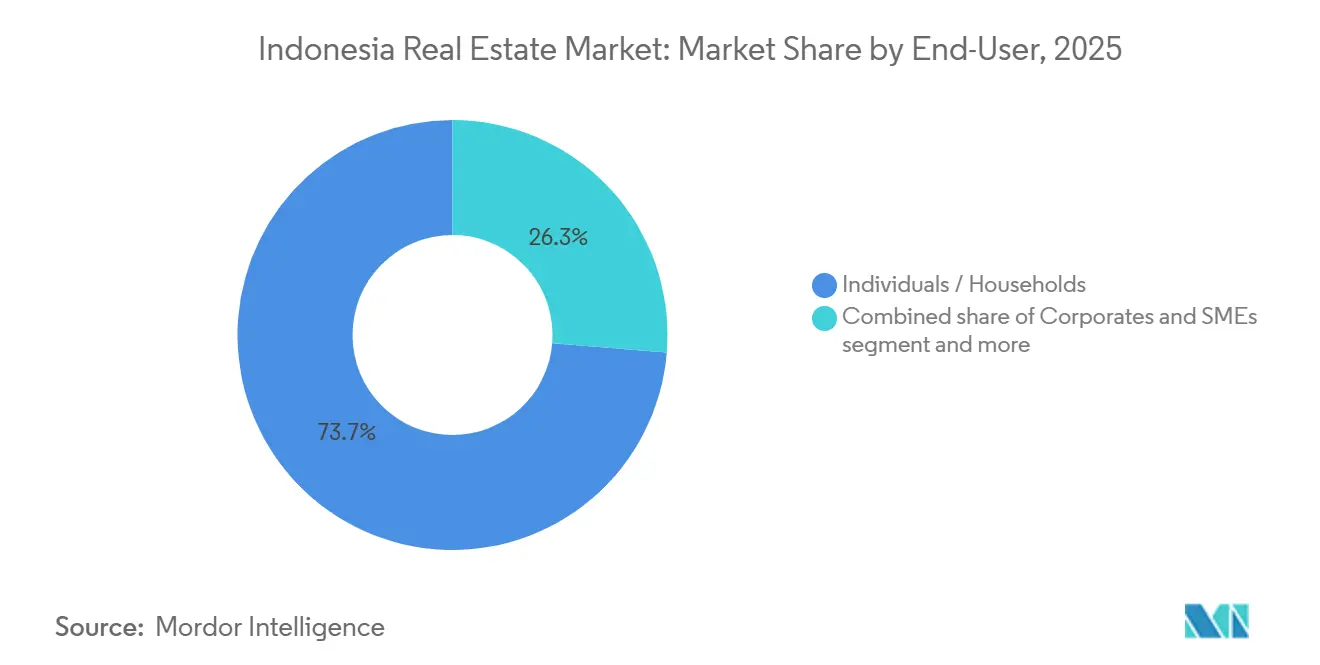
- Among end-users, individuals and households held the largest share at 73.51% in 2026, while corporates and SMEs are expected to grow fastest at a CAGR of 6.35% over 2027-2032.
- Across Indonesian geographies, DKI Jakarta held the largest share at 39.19% in 2026, with East Java (Jawa Timur) forecast to grow fastest at a CAGR of 6.55% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Indonesia Real Estate Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Strong demographics, urbanization, and rising middle class boosting housing, retail, and services demand. | +2.2% | Nationwide | Long term (≥ 4 years) |
| Infrastructure push and the new capital (IKN Nusantara) unlocking development corridors and mixed-use pipelines. | +1.8% | IKN Nusantara development areas | Long term (≥ 4 years) |
| “China+1” FDI and manufacturing growth driving industrial parks, warehousing, and worker housing. | +1.6% | Jakarta and industrial estates nationwide | Medium term (2-4 years) |
| Tourism rebound and MICE activity supporting hotel, resort, and lifestyle mixed-use projects. | +1.3% | Nationwide | Short term (≤ 2 years) |
| REITs/collective investment schemes and proptech adoption improving capital access and transparency. | +0.7% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Strong demographics, urbanization, and rising middle class boosting housing, retail, and services demand.
Subsidized housing finance through BP Tapera, the public housing savings agency, and the housing finance liquidity facility (FLPP) gives household need a route toward residential transactions with a landed-home emphasis. BP Tapera reported 177,161 subsidized FLPP mortgage disbursements for homes in Indonesia as of October 9, 2026.[1] These home mortgage loans, known as KPR, covered 177,140 landed houses and 21 apartments. The World Bank’s 2025 housing assessment also identified substantial need for new housing among Indonesian households. Against that need, the disbursement mix places landed homes at the center of this financing channel. Landed-home developers gain a demonstrated financed-buyer channel from this disbursement mix, without treating every household needing housing as a purchase-ready customer.
Infrastructure push and the new capital (IKN Nusantara) unlocking development corridors and mixed-use pipelines.
Supporting facilities in IKN Nusantara offer a route from new-capital development to a wider range of commercial property uses. In 2026, PT Panca Karya Sentosa, PT Maxi Nusantara Raya and PT Borneo Berkah Abadi signed development agreements for facilities in IKN. The agreements covered shopping centers, food areas and sports facilities in development areas 1A and 1C. The IKN Nusantara capital authority (Otorita IKN) reported 411,778 visitors during the 2026 Eid and Easter holiday periods of March 18 to 29 and April 3 to 5. Those visits provide a concrete customer occasion for prospective retail and food premises in the new capital. Holiday use of public spaces therefore gives the separate 1A and 1C facilities a potential audience, but does not establish their own trading demand.
“China+1” FDI and manufacturing growth driving industrial parks, warehousing, and worker housing.
Industrial occupiers give completed warehouses a demand base linked to business operations rather than household purchasing cycles. Indonesia’s industrial estates had 11,970 tenant companies in January 2026, according to the Industry Minister. Separately, JLL reported strong occupancy in Jakarta’s modern logistics warehouses in Q2 2026, alongside inquiries from diverse industries and new brands entering Indonesia. The tenant base demonstrates the scale of industrial use, while the warehouse evidence identifies a channel through which operators can seek additional premises. For warehouse landlords, converting those inquiries into formal leases depends on presenting space that can accommodate the intended activity. Industrial-estate occupiers nationwide and prospective warehouse entrants in Jakarta represent different leasing opportunities, serving an installed business base and new inquiries, respectively.
Tourism rebound and MICE activity supporting hotel, resort, and lifestyle mixed-use projects.
Tourism supports hospitality properties through room use and event activity, giving owners more than one operating proposition. Statistics Indonesia recorded 10.58 million international tourist visits to Indonesia in January to August 2026, up 5.38% from January to August 2025. The country also hosted 110 international association meetings in 2025, according to ICCA’s Country and City Rankings. PT Eastparc Hotel Tbk reported average occupancy of 93.39% at its Eastparc Hotel Yogyakarta property in Sleman in 2025. Room use creates a commercial base for a hotel operator, while association meetings provide a separate rationale for accommodation paired with event facilities. Eastparc’s occupancy provides a property-specific operating record that a prospective owner or lessee can assess when considering a hospitality asset.
Restraints Impact Analysis of Indonesia Real Estate Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Land/title complexity, zoning/permitting delays, and regional policy variability slowing execution. | -1% | Nusa Tenggara Barat | Long term (≥ 4 years) |
| High funding costs and construction inflation tightening feasibility for new starts. | -0.8% | Nationwide | Short term (≤ 2 years) |
| Segment-specific oversupply/uneven recovery (e.g., offices in Jakarta) weighing on rents and absorption. | -0.4% | DKI Jakarta office districts | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Land/title complexity, zoning/permitting delays, and regional policy variability slowing execution.
Unsettled spatial plans can prevent housing developers from turning a proposed residential use into a deliverable property. On July 6, 2026, Hery Athmaja, chair of Real Estate Indonesia’s Nusa Tenggara Barat chapter (REI NTB), said most local developers were postponing new housing projects. They were awaiting certainty on regional spatial plans and the conversion of paddy fields into residential land. Those reported decisions illustrate how the legal suitability of a site can constrain development before the question of buyer demand becomes decisive. For developers, committing construction resources before resolving the intended use can expose a project to an interruption that stronger sales interest cannot remove. The execution cost is uncertainty over when a marketable housing concept can become deliverable supply, even before construction performance is tested.
High funding costs and construction inflation tightening feasibility for new starts.
Construction inflation can weaken project feasibility when selling prices provide little room to recover higher building costs. Indonesia’s property-construction wholesale price index rose 8.1% year over year in April 2026, versus 0.8% in April 2025. Residential property prices rose 0.6% in Q1 2026, and a Bank Mandiri analyst assessed that incomplete cost pass-through could erode property-company margins. The analyst also said rising borrowing costs can strain developer cash flow and hamper expansion, while higher mortgage rates can prompt purchase postponements. Together, these pressures can reduce the margin available to absorb a slower sales schedule during construction. Debt-dependent new projects consequently face both a narrower cost cushion and the risk of financing inventory for longer before completed homes sell.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Indonesia Real Estate Market Segment Analysis
By Business Model:
Mortgage Access Supports Sales While Leasing Broadens DemandSales accounted for a 71.95% share of the Indonesia real estate market size in 2026. Bank Indonesia’s 18-city survey found that KPR mortgage financing accounted for 70.05% of consumer purchase schemes for primary-market residential properties in Q2 2026.[2] For this largest segment, the financing concentration gives home sellers a substantial channel for converting purchase interest into completed transactions. A finished home that meets a buyer’s requirements still needs a financing route before a mortgage-dependent purchase can close. Mortgage approval consequently becomes a transaction-completion dependency for sellers serving these primary-market residential buyers.
Rental is the fastest-growing segment, with a forecast CAGR of 6.45% over 2027-2032. Bank Indonesia’s commercial-property rental-demand index grew 1.32% year over year in Q2 2026 after contracting 0.17% in Q1 2026. Hotel demand rose in most surveyed cities, while convention-hall demand increased in Jakarta. These distinct uses give rental operators a demand base that can respond to travel and organized gatherings, with the commercial opportunity tied to usable space and the ability to attract occupiers. Rental operators can earn income from completed hospitality and event properties by serving the recovering hotel and convention-hall demand.

By Property Type:
Residential Scale Meets Selective Commercial ExpansionResidential represented a 54.79% Indonesia real estate market share in 2026. Bank Indonesia surveyed primary-market homes across 18 cities. The survey recorded sales growth of 9.39% quarter over quarter in Q2 2026, following a 7.69% contraction in Q1 2026. Sales nevertheless contracted 2.36% year over year in Q2 2026. Renewed quarterly activity therefore gives sellers a recovery from the weak first quarter, but its lower prior-year comparison limits the case for treating that rebound as sustained expansion.
Commercial is the fastest-growing segment, with a projected CAGR of 6.15% over 2027-2032. Golden Goose and COS entered Indonesia through Jakarta prime retail locations in Q2 2026. ACE Hardware and KKV also reopened stores in Q2 2026 following earlier exits. New entrants and returning retailers represent distinct pools of potential tenants, giving shopping-center landlords more than one route to attracting operators into completed space. Leasing that distinguishes an entrant’s first location from a returning operator’s next premises can broaden the tenant pool served by a shopping center and reduce dependence on a single type of retail expansion.
By End-user:
Household Ownership Needs Anchor Demand While Corporate Relocations Add ActivityIndividuals and households were the largest segment, accounting for 73.51% of the market in 2026. Statistics Indonesia (BPS) counted about 9.29 million Indonesian households without their own home in March 2026. Effective September 4, 2026, BP Tapera Regulation 1/2026 replaced Regulation 9/2021 and limited KPR Sejahtera FLPP eligibility to low-income unmarried individuals or married couples with Indonesian citizenship. They must be registered in one regency or city, own no home, meet the income cap, and have received no government subsidy or financing aid through mortgages or self-help housing loans unless law provides otherwise. Eligible households define the FLPP sales opportunity, so developers serving this channel must distinguish ownership need from qualification for subsidized financing.
Corporates and SMEs form the fastest-growing segment, with an expected CAGR of 6.35% over 2027-2032. Cushman & Wakefield recorded a 3,000-square-meter relocation by a banking tenant to District 8 in Jakarta’s Sudirman submarket during Q2 2026. In the same quarter, an unnamed China-origin company leased 1,000 square meters at District 8 through a relocation, within leasing statistics that exclude renewals. These relocations show corporate occupiers, including a China-origin company, signing office leases in Jakarta's Sudirman submarket, adding transactions beyond renewals to the segment's formal leasing activity.
Geography Analysis
DKI Jakarta Real Estate Market
DKI Jakarta accounted for a 39.19% share of the Indonesia real estate market size in 2026. Jakarta CBD offices recorded 45,500 square meters of net take-up in the first half of 2026, with a significant portion contributed by Grade A offices. That leasing activity demonstrates an active office-demand base within the central business district, giving owners of completed buildings a practical channel for attracting occupiers. The Grade A contribution supports a differentiated office proposition, with landlord returns depending on matching the building to an occupier’s use rather than relying on the province’s scale to make every property equally attractive.
East Java (Jawa Timur) Real Estate Market
East Java (Jawa Timur) is the fastest-growing geography, with a projected CAGR of 6.55% over 2027-2032. PT PP Properti Tbk recorded marketing volume of 236 units in its East Java marketing area in 2025, compared with 204 units in 2024 and 394 in 2023. Pakuwon City on Surabaya's east coast covers 600 hectares, with more than 5,000 houses built since development began in 1994. Surabaya reported obstacles to housing-infrastructure handovers in 2025 involving land titles not in developers’ names, unpaid property tax, and facilities not built according to site plans. PP Properti's partial marketing recovery illustrates renewed selling activity alongside an established township base, while Surabaya's experience shows the separate compliance work required to hand over housing infrastructure.
In West Java (Jawa Barat), BP Tapera reported 31,229 units distributed under the subsidized KPR Sejahtera FLPP mortgage program from January 1 through August 19, 2026. That channel gives housing developers a way to connect completed homes with buyers using a defined public financing program. Within the Rest of Indonesia, Bali’s star-rated hotels averaged 60.62% room occupancy across 2025, according to the provincial tourism office. Tourism accommodation creates a different property proposition, linking the usefulness of a completed hotel to the operator’s ability to attract room demand. The regional choices consequently differ between housing sold through a household financing channel and hospitality assets whose operating appeal can support a sale or formal lease to an accommodation operator.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions, assessing Indonesia’s national framework alongside DKI Jakarta and East Java from the perspective of developers supplying completed residential and commercial properties. Policy attractiveness depends on whether the planning framework gives a usable route to development while preserving the required conformity of each proposed use. National spatial-planning rules establish the framework, while provincial instruments specify local planning conditions that shape the property a developer can bring to completion.
Regulatory Table of Indonesia Real Estate Market
| Decision factor | Indonesia | DKI Jakarta | East Java (Jawa Timur) |
|---|---|---|---|
| Primary authority | Ministry of Agrarian Affairs and Spatial Planning/National Land Agency | DKI Jakarta Provincial Government | East Java provincial and relevant local governments |
| Key instruments or direction | Government Regulation 21/2021 and Ministerial Regulation 6/2026 on spatial planning and plan procedures | Governor Regulation 31/2022 on the detailed spatial plan and zoning | Provincial Regulation 10/2023, the 2023-2043 spatial plan |
| Commercial effect | Proposed uses must conform to spatial plans | Sub-zone uses and building-intensity controls shape development options | Space-use activities require conformity under applicable law, with the route depending on the activity |
| Current policy attractiveness | Medium | Medium | Medium |
| Future direction of policy attractiveness | Easing | Easing | Easing |
| Source: Mordor Intelligence | |||
Indonesia’s medium rating reflects spatial-conformity duties, which require proposed uses to fit the planning framework even when a plan is available. DKI Jakarta’s medium rating reflects sub-zone and building-intensity controls, with easing concerning procedures for future revisions to its existing detailed plan. East Java’s medium rating reflects its long-term plan and activity-dependent conformity routes, with easing concerning provincial revisions and local detailed-plan preparation under the amended procedures. Adopted on May 12, 2026, Ministerial Regulation 6/2026 took effect upon promulgation in 2026 and amended national procedures to accelerate provincial and local spatial-plan availability.[3]
Value Chain Stages
The value chain compares building construction, transaction intermediation, and operation of completed properties, with different earnings mechanisms at each stage. Construction creates the usable asset, brokerage connects it to buyers or tenants, and property operation supports income from continued occupancy. This sequence separates the commercial value of delivering a building from the fees associated with arranging a transaction and the recurring earnings available to an owner or operator.
Value Chain Analysis Table of Indonesia Real Estate Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Building construction | Building contractors such as PT Wijaya Karya (Persero) Tbk | Payments for construction services | Unsafe or noncompliant work can interrupt delivery | Site-level stop-work authority and correction of hazardous conditions |
| Sales and leasing intermediation | Real estate agencies and brokers such as PT Era Graharealty Tbk | Agency and brokerage fees or contract income | Matching available properties with a buyer or tenant able to transact | Qualify counterparties and align transaction requirements before closing |
| Leasing and property operation | Property owners and operators such as PT Pakuwon Jati Tbk and PT Intiland Development Tbk | Space rent, service charges, and property-management income | Unoccupied space limits the asset base producing rental income | Coordinate leasing and operation around the uses that can sustain occupancy |
| Source: Mordor Intelligence | ||||
In 2025, PT Wijaya Karya (Persero) Tbk (WIKA) authorized employees and work partners to stop work when they encountered dangerous actions or conditions or work that did not comply with applicable rules. This company-specific safety authority can interrupt hazardous work during construction, before the building reaches buyers or occupiers. Downstream, PT Pakuwon Jati Tbk earned space rental and service charges in 2025, while PT Intiland Development Tbk earned office-leasing and property-management income. Construction controls address one interruption point, leaving brokers and operators exposed to whether completed space attracts a transaction and stays let.
Competitive Landscape
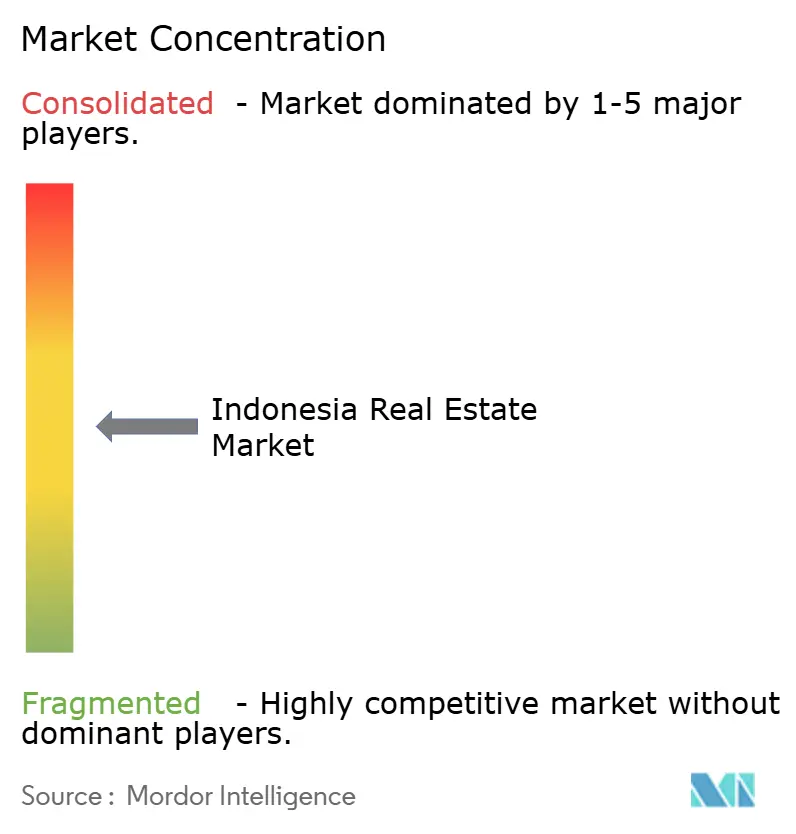
The competitive field spans industrial estates, landed homes, townships and serviced apartments supplied by several established developers. Major participants include PT Intiland Development Tbk, Tokyu Land Indonesia, Agung Podomoro Land, Ciputra Group, and Sinar Mas Land. Intiland achieved 80.4% of its marketing-sales target in 2025, with marketing sales slightly below 2024. Tokyu Land Indonesia and Japan Overseas Infrastructure Investment Corporation for Transport & Urban Development opened the 240-unit Swissôtel Living Jakarta Mega Kuningan serviced apartment on April 1, 2025, with Accor managing the property. Tokyu's operating example shows how development capability and a hospitality manager can combine in a specific asset format, giving buyers and occupiers alternatives beyond a conventional housing offer.
PT Bumi Serpong Damai Tbk, developer of Sinar Mas Land’s flagship BSD City, reported first-half 2026 marketing sales 1% above the same period of 2025. In March 2025, Sinar Mas Land and Hankyu Hanshin Properties Corp. announced PT Sinar Hankyu Hanshin Mas, a joint venture to develop a residential project in BSD City. Agung Podomoro Land reported 232% year-over-year growth in its combined sales and operating revenue in Q1 2026. Sinar Mas Land’s announced BSD City venture positions it to pursue new residential supply with a partner, whereas the reported results concern existing businesses.
PT Ciputra Development Tbk generally presells property before project completion and uses the proceeds to fund development. Its 2025 marketing sales reached 94.6% of target, indicating buyer commitments close to its planned sales goal. Buyers commit before the finished property is available, exposing them to the interval between purchase and delivery. PT Pakuwon Jati Tbk, by comparison, reported that its 2025 marketing sales came mainly from apartments at Pakuwon Mall Surabaya and Pakuwon Residences Bekasi, supported by landed houses at Grand Pakuwon and Pakuwon City townships. Near-target presales support Ciputra's stated financing model, giving its sales performance significance for project funding as well as demand.
Indonesia Real Estate Industry Leaders
-
PT Intiland Development Tbk
-
Tokyu Land Indonesia
-
Agung Podomoro Land
-
Ciputra Group
-
Sinar Mas Land
- *Disclaimer: Major Players sorted in no particular order
Indonesia Real Estate Market Companies Covered in this Report
- PT Intiland Development Tbk
- Tokyu Land Indonesia
- Agung Podomoro Land
- Ciputra Group
- Sinar Mas Land
- PP Properti
- Lippo Group
- Trans Property
- Agung Sedayu Group
- PT Pakuwon Jati Tbk
- Summarecon Agung
- LOGOS Property Indonesia
- ESR Indonesia
- DP World Indonesia
- PT Bumi Serpong Damai Tbk
- PT Alam Sutera Realty Tbk
- PT Modernland Realty Tbk
- PT Astra Land Indonesia
- PT Wika Realty
- Perum Perumnas
Key Opportunities for Market Participants
The opportunities compare additional subsidized-home capacity, completed inventory for the announced 2027 housing-tax incentive, and utility-ready homes that can progress through financing. These plays address different commercial tasks, from adding properties for prospective buyers to bringing an existing development to a condition suitable for occupancy. Physical readiness and access to a defined household financing channel jointly determine whether these proposals can become completed sales.
Market Opportunities Table of Indonesia Real Estate Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Additional completed homes for FLPP buyers | BP Tapera reported potential demand of 39,155 units and potential supply of 27,443 units as of October 9, 2026 | Households seeking subsidized home financing | Phase additional finished homes around identifiable program buyers | Converting potential buyer interest into financed purchases | Developers serving FLPP households |
| Completed inventory for announced 2027 VAT support | Government announced continuation on September 30, 2026, for qualifying home purchases within announced price tiers | Eligible residential buyers | Prepare finished inventory and align offers with the operative 2027 terms | Committing delivery capacity before effective buyer demand is established | Residential sellers with qualifying completed inventory |
| Utility-ready subsidized homes | Banks identified physical progress, particularly electricity and water provision, as an FLPP financing constraint in October 2026 | FLPP buyers awaiting homes ready for occupancy | Complete utility connections and coordinate home readiness with participating banks | Electricity and water readiness constraining completion and financing | Developers able to deliver utility-ready homes |
| Source: Mordor Intelligence | |||||
The central opening is subsidized housing that can progress from financing interest to actual occupancy. In October 2026, participating banks identified physical construction progress, particularly electricity and water provision, as a constraint on completing homes and their financing. Utility readiness therefore limits the commercial value of adding subsidized units before their connections are ready, even when prospective buyers have been identified.
Recent Industry Developments in Indonesia Real Estate Market
- Sep 2026: Indonesia’s government announced that VAT support for qualifying home purchases would continue in 2027, creating a prospective incentive for eligible residential transactions.
- Aug 2026: PT Intiland Development Tbk launched Aurora Residence, a limited release of 23 homes at Graha Natura in West Surabaya, with handover targeted for Q4 2027.
Indonesia Real Estate Market Report Scope and Research Methodology
Market Definition and Coverage
Indonesia real estate market measures the annual gross value in Indonesia of completed residential and commercial properties sold and formally leased. Sales are valued at completed-property transaction prices, while rentals are valued as rent under formal leases.
Scope exclusions: Land-only transactions without standing structures, informal rental arrangements that are not captured through formal leasing, sales of properties that are not completed, and construction and property-management services sold separately are excluded.
Segments Covered in This Report
- By Business Model
- Sales
- Rental
- By Property Type
- Residential
- Apartments & Condominiums
- Villas & Landed Houses
- Commercial
- Office
- Retail
- Logistics
- Others (industrial, hospitality, etc.)
- Residential
- By End-user
- Individuals / Households
- Corporates & SMEs
- Others
- By Geography
- DKI Jakarta
- West Java (Jawa Barat)
- East Java (Jawa Timur)
- Rest of Indonesia
Data Sources, Market Sizing, and Validation
Desk Research
Desk research draws on sources such as Bank Indonesia's residential property price survey for primary-market prices, sales and financing, while the World Bank's Indonesia housing assessment provides household housing needs and policy context, the Ministry of Investment and Downstream Industry/BKPM's investment releases provide regional investment and housing, industrial-estate and office-building activity, and Bank Indonesia's commercial property series provides rental-demand signals. These indicators describe demand, financing, prices and activity that can be tested against the completed-property sales and formal-lease boundary.
Company filings and investor presentations can clarify completed sales, rental income, project timing and geographic exposure, while reputable Indonesian business press can help check dated openings, transactions and policy changes against public records. Such sources are used to explain changes in property type, business model, end-user and provincial evidence. The named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Primary research draws on interviews and structured surveys with Indonesian residential and commercial developers, property owners and landlords, brokers, lenders and planning specialists to clarify transaction conventions, lease coverage, timing and regional differences. Interviews and structured surveys test secondary-source interpretations, identify evidence gaps on completed sales and formal rents, and check whether observed activity belongs inside the stated market boundary. Where measures are unavailable, independent transaction, pricing, financing and company disclosure signals are compared, and unresolved inputs are documented for follow-up.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | |
| Mid tier: 40% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The Indonesia estimate uses a top-down annual value model of completed residential and commercial property sales plus formal rent, converted to USD at average annual exchange rates, with sampled property-level checks to test scale. The model separates sales from rent and builds property-type, end-user and provincial shares from available transaction, price, occupancy and rental evidence, company disclosures and financing indicators. Key inputs include completed-home sales and primary-market price movement, formal residential and commercial rental demand, transaction or occupancy volumes, housing-loan activity, and project completions or leasing activity, which indicate how transaction volume, realized prices and rental utilization affect value. A multivariate regression can relate these demand, price and financing indicators to market value, with scenario analysis used when infrastructure, policy or funding conditions create materially different paths. Selective bottom-up checks can multiply sampled completed-property transactions by observed prices and combine sampled formal leased space with rents, then compare those roll-ups with the top-down totals, and gaps in sampled coverage are bounded using documented market indicators and company disclosures rather than treated as full-market counts. Primary experts review the role and direction of these variables, forecast assumptions and material gaps at segment and regional level, and differing views are checked against the independent evidence.
Data Validation & Update Cycle
Analysts triangulate transaction values and rents against independent price, sales, occupancy, financing, completion and company-reporting signals, then investigate outliers and material variances between sources or periods before sign-off. A second review checks boundary treatment, units, currency conversion, segment and regional totals, and forecast consistency, and analysts re-contact respondents when definitions conflict, evidence is missing or an unexpected change cannot be reconciled. The dataset is refreshed annually, updated between cycles when a material policy, financing or market event changes the evidence, and given a fresh pre-delivery review.
Mordor Intelligence's Indonesia Real Estate Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Indonesia real estate market measures the annual gross value in Indonesia of completed residential and commercial properties sold and formally leased.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key inputs include completed-home sales and primary-market price movement, formal residential and commercial rental demand, transaction or occupancy volumes, housing-loan activity, and project completions or leasing activity, which indicate how transaction volume, realized prices and rental utilization affect value.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 74.53 B (2027) | |
| Global Consultancy A | USD 149.2 B (2024) | At its 2024 base, this estimate is 100.2% above this report's 2027 value of USD 74.53 B, 3 years later. The broader stated categories of land and real estate investment can add value outside completed-property sales and formal lease rent. |
| Industry Publisher B | USD 66 B (2025) | At its 2025 base, this estimate is 11.4% below this report's 2027 value of USD 74.53 B, 2 years later. The 2025 estimate precedes the 2027 comparison year, while its stated coverage also includes brokerage, asset management and recurring property income. |
Mordor Intelligence's analysts triangulate transaction values and rents against independent price, sales, occupancy, financing, completion and company-reporting signals, then investigate outliers and material variances between sources or periods before sign-off.
Key Questions Answered in the Report
What is the Indonesia real estate market size and growth outlook?
The market is expected to reach USD 74.53 billion in 2027 and USD 97.04 billion by 2032, growing at a CAGR of 5.42% over 2027-2032.
What supports demand for property in Indonesia?
Housing finance and industrial occupancy support demand. BP Tapera, the public housing savings agency, reported 177,161 subsidized mortgage disbursements under the housing finance liquidity facility by October 9, 2026, while industrial estates had 11,970 tenant companies in January 2026.
Which property type leads Indonesian real estate?
Residential held the largest share at 54.79% in 2026, while commercial is forecast to grow fastest at a CAGR of 6.15% over 2027-2032.
Which companies compete in Indonesia’s real estate sector?
Major participants include PT Intiland Development Tbk, Tokyu Land Indonesia, Agung Podomoro Land, Ciputra Group, and Sinar Mas Land.
What could constrain Indonesian property development?
Construction-cost pressure and land-use uncertainty can constrain development. In July 2026, Real Estate Indonesia’s Nusa Tenggara Barat chapter chair Hery Athmaja said most local developers were postponing housing projects while awaiting spatial-plan and paddy-field conversion certainty.
Which Indonesian geographies lead property activity and forecast growth?
DKI Jakarta held the largest share at 39.19% in 2026, while East Java (Jawa Timur) is forecast to grow fastest at a CAGR of 6.55% over 2027-2032.