
- Africa
- Africa
- Africa
- Africa
- Africa
- Algeria
- Argentina
- Asia
- Asia
- Australia
- Austria
- Azerbaijan
- Belarus
- Botswana
- Brazil
- Canada
- Chile
- China
- Colombia
- Denmark
- Egypt
- Ethiopia
- Europe
- Europe
- Europe
- Europe
- Europe
- Finland
- France
- Germany
- Greece
- Hungary
- India
- Indonesia
- Iran
- Israel
- Italy
- Japan
- Kazakhstan
- Malaysia
- Mexico
- Middle East and Africa
- Netherlands
- New Zealand
- Nigeria
- North America
- Norway
- Peru
- Poland
- Portugal
- Romania
- Russia
- Saudi Arabia
- Singapore
- Slovakia
- South Africa
- South America
- South Asia
- South East Asia
- South Korea
- Spain
- Sweden
- Switzerland
- Tunisia
- Turkey
- United Arab Emirates
- United Kingdom
- United States
- Uzbekistan
- Venezuela
- Zimbabwe
Philippines Renewable Energy Market Analysis by Mordor Intelligence
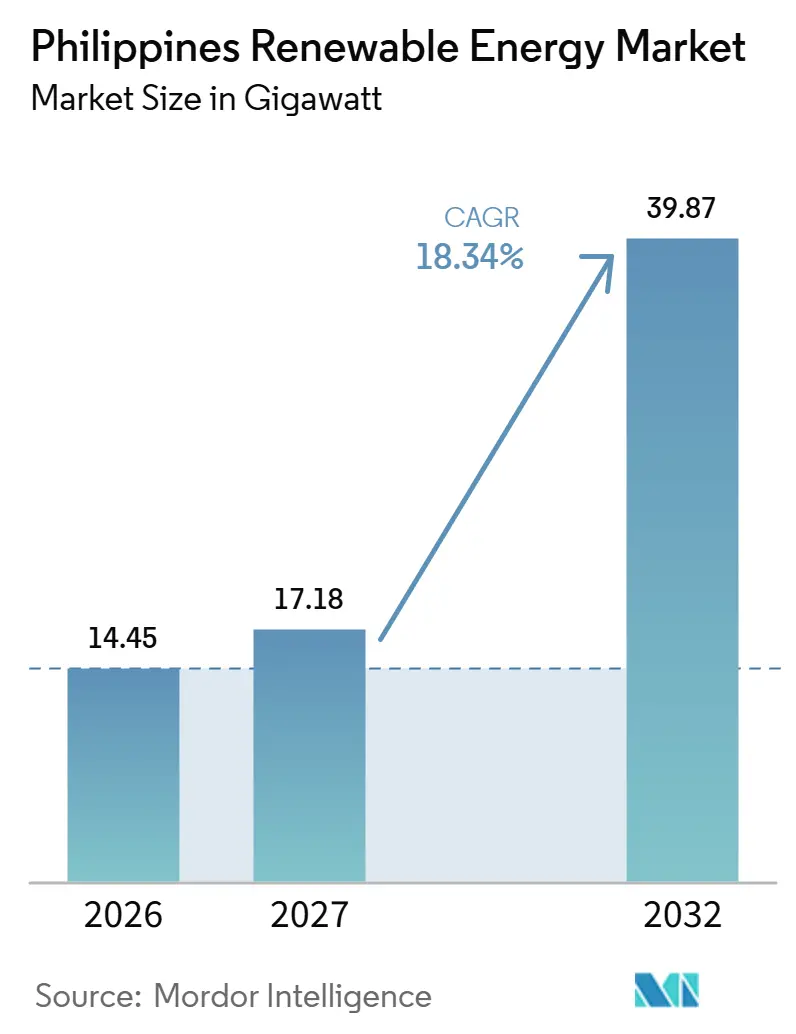
The Philippines renewable energy market size is projected to expand from 14.45 gigawatt in 2026 and 17.18 gigawatt in 2027 to 39.87 gigawatt by 2032, registering a CAGR of 18.34% between 2027 and 2032.
Rising electricity needs and tariff pressure in the Philippines strengthen the commercial case for renewable supply, including solar generation for businesses. Global equipment-cost relief supports wind expansion more directly than solar expansion, where financing costs and output can offset savings. Suppliers can reach corporate demand through property operators and retail supply contracts, linking renewable projects to defined customer requirements. Transmission access and project approval conditions determine how readily those offers become operating capacity. Suppliers that establish grid access before pricing corporate contracts can offer firmer delivery terms, positioning them to capture tariff-driven demand without promising electricity ahead of network access.
Key Report Takeaways
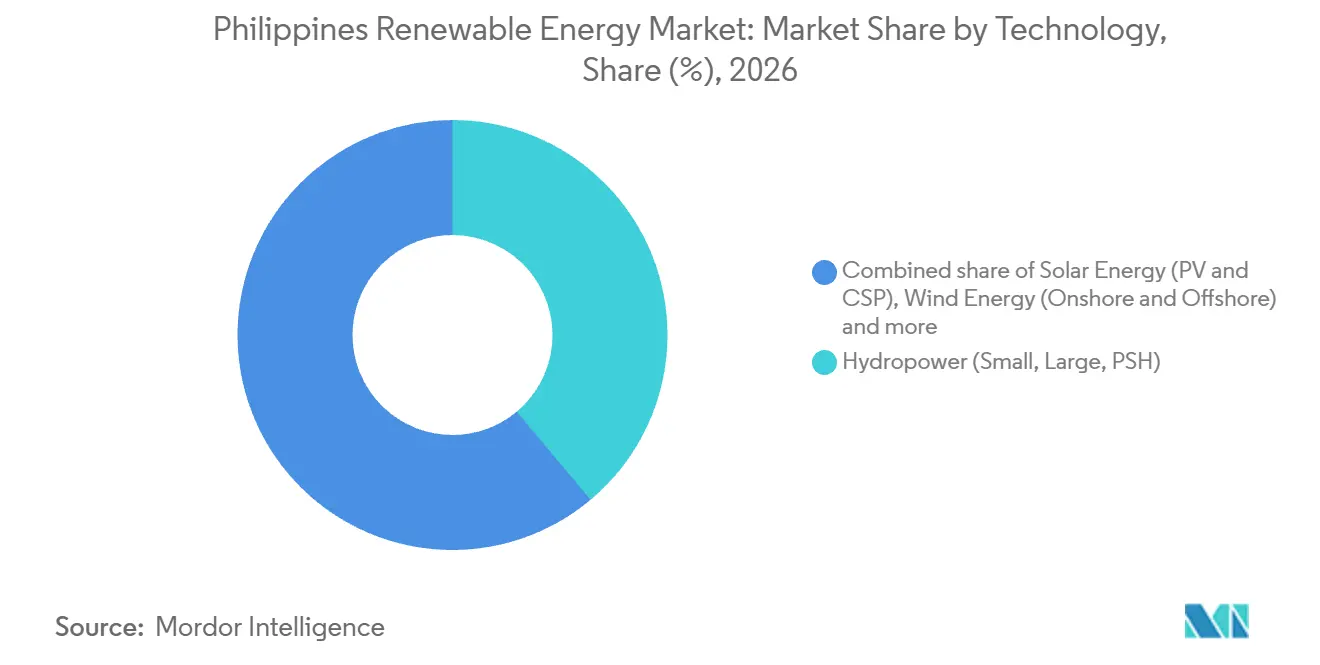
- By technology, hydropower held a 38.9% Philippines renewable energy market share in 2026, while ocean energy is forecast to be the fastest-growing segment at a CAGR of 106% between 2027 and 2032.
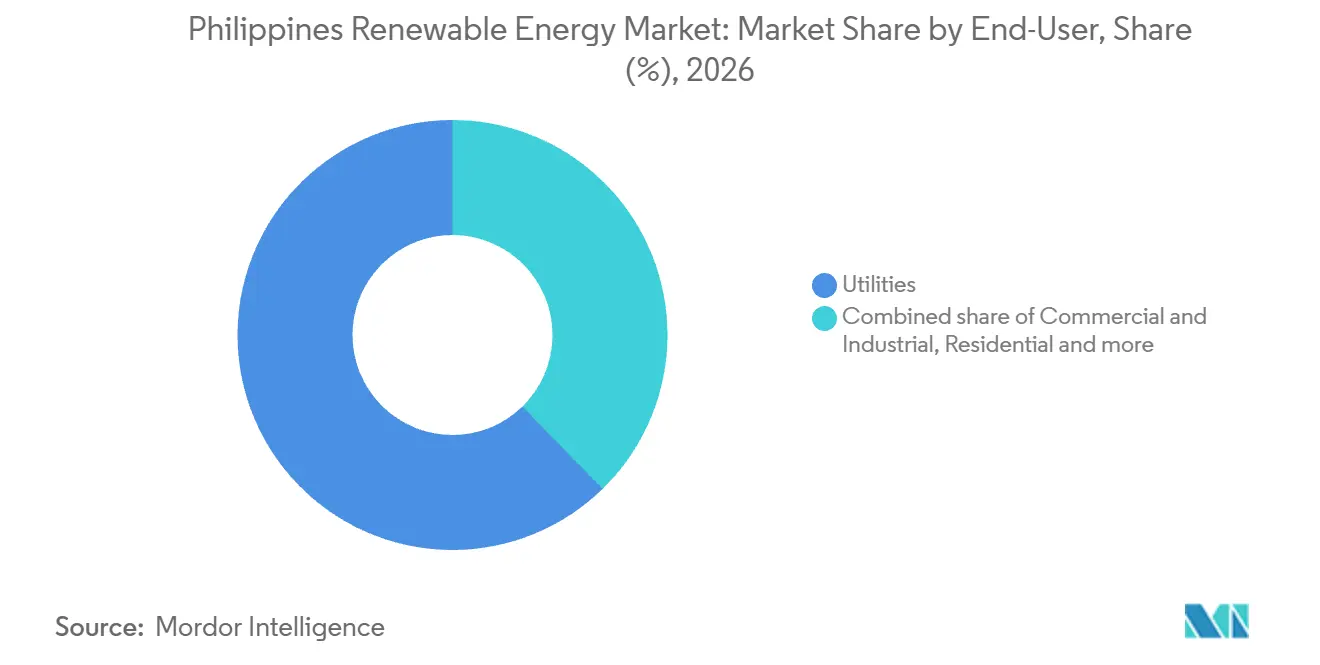
- Across end users, utilities held a 62.3% share of the Philippines renewable energy market size in 2026, while commercial and industrial users form the fastest-growing segment at a forecast CAGR of 22.3% between 2027 and 2032.
- Geographically, Luzon is the largest regional market, supported by its established renewable capacity across on-grid and off-grid systems.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Philippines Renewable Energy Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Renewable Portfolio Standards & Feed-in Tariffs | +5.6% | Nationwide | Short term (≤ 2 years) |
| Declining Solar-PV & Wind Turbine Capex | +5% | Nationwide | Medium term (2-4 years) |
| Rising Electricity Demand & High Retail Tariffs | +6.2% | Nationwide | Short term (≤ 2 years) |
| Corporate PPAs from BPO/IT Hubs | +3.5% | Araneta City, Quezon City | Medium term (2-4 years) |
| Grid Upgrades via JICA-funded Projects | +1.6% | Nationwide | Long term (≥ 4 years) |
| Disaster-resilient Island & Micro-grid Programs | +0.9% | Pag-asa Island community | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Renewable Portfolio Standards & Feed-in Tariffs
Tariff-funded payments give eligible renewable generators a revenue route that can support investment in additional grid-supplying capacity. The Energy Regulatory Commission authorized the National Transmission Corporation, the fund administrator, to collect the 2026 Feed-in-Tariff Allowance from January 2026 billing. Under the 2026 decision, eligible generators are paid for actual generation volume supplied to the grid. The Department of Energy (DOE) project list neither guarantees final tariff eligibility nor restricts payments to the listed projects. A project delayed in grid connection earns no tariff support before supplying electricity, so transmission access determines when an eligible investment can begin capturing this revenue.
Declining Solar-PV & Wind Turbine Capex
Lower equipment costs can improve renewable project economics without producing an equivalent reduction in the price of delivered electricity. The International Renewable Energy Agency (IRENA) reported that cheaper equipment and lower installed costs helped reduce global onshore wind generation costs in 2025. Solar PV’s global levelized cost of electricity was unchanged, as a higher cost of capital and slightly lower capacity factors offset the equipment and installation benefits. The 2025 global weighted-average levelized cost was USD 33 per MWh for onshore wind and USD 44 per MWh for solar PV. This global cost contrast strengthens the investment case for additional Philippine onshore wind capacity more directly than for solar expansion, where equipment savings did not lower the generation-cost benchmark.
Rising Electricity Demand & High Retail Tariffs
Electricity demand and tariff pressure strengthen different parts of the case for additional renewable supply. The Department of Energy (DOE) recorded Philippine electricity sales of 105,741 GWh in 2025, compared with 103,908 GWh in 2024. Meralco’s average retail rate rose 15% in the first half of 2026 from the corresponding 2025 period, largely on higher pass-through generation and transmission charges and related taxes.[1] Higher sales increase the volume that generation must serve, while higher retail charges strengthen the economic incentive to consider alternatives. For commercial consumers, renewable supply is consequently a potential response to price pressure alongside meeting additional consumption. A renewable supplier’s cost advantage must therefore survive transmission charges and other bill components before it can improve the buyer’s electricity economics.
Corporate PPAs from BPO/IT Hubs
Business process outsourcing (BPO) tenants can influence renewable procurement through the property operator that contracts electricity for their buildings. In July 2026, Araneta City said its BPO tenants had asked it to source renewable energy. That month, First Gen signed renewable supply deals covering 4 additional Araneta City properties, including Cyberpark Tower 3, with combined supply estimated at 3.4 MW.[2] The properties also included the mixed-use Aurora Tower and a Fiesta Carnival site undergoing redevelopment. Araneta City was the contracting buyer, while the BPO tenants expressed demand through their requests. Procurement through the property operator can therefore connect a renewable supplier with a wider mix of electricity uses than the BPO tenant requests alone would suggest.
Restraints Impact Analysis of Philippines Renewable Energy Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Grid Congestion & Limited Transmission Capacity | -2.6% | Nationwide | Short term (≤ 2 years) |
| Regulatory Uncertainty around CREZ Auctions | -1.2% | Nationwide | Medium term (2-4 years) |
| Typhoon-driven Insurance Cost Escalation | -0.4% | Nationwide | Medium term (2-4 years) |
| Land-use Conflicts with Agrarian Reform Lands | -0.3% | Barangay Tingub, Daanbantayan | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Grid Congestion & Limited Transmission Capacity
Securing transmission access can delay the commercial value of investment in renewable generating equipment. The OECD’s 2026 survey described difficult transmission access for renewable developers and over 160 projects awaiting National Grid Corporation of the Philippines (NGCP) System Impact Studies, with backlog clearance potentially taking an additional year. NGCP conducts these studies as part of the process for obtaining transmission-network access. A developer therefore faces a separate approval sequence even when a generation design and customer opportunity are already defined. New applicants carry the added exposure, since the OECD noted that the backlog could cause them further delays.
Regulatory Uncertainty around CREZ Auctions
A delay in finalizing auction documents can defer the commercial route for a fixed-bottom offshore-wind developer before plant construction begins. In July 2026, DOE placed offshore-wind activities for Green Energy Auction Program round 5 (GEA-5) on hold for a review of port readiness, permitting, environmental and port-related costs, and possible supply-chain disruptions. Resumption required approved supplemental documents and updated instructions, with an indicative December 1, 2026 auction target subject to change. That timing exposure puts development capital at risk of being committed ahead of the approved procurement conditions needed for a firm bid.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Philippines Renewable Energy Market Segment Analysis
By Technology:
Hydropower Scale Meets Ocean Energy PotentialHydropower accounted for a 38.9% share of the Philippines renewable energy market size in 2026. First Gen’s hydro-platform revenue rose 8.4% between the first quarters of 2025 and 2026. The increase largely reflected higher generation at its FG Hydro plants, which increased spot-market sales and capacity available for ancillary services in the Reserve Market. Lower generation at Casecnan, another plant in First Gen’s hydro platform, partly offset that revenue gain. Operators in the largest segment can earn from electricity sales while offering available capacity for reserve services, giving usable operating flexibility a role in installed-asset value.
Ocean energy, covering tidal and wave technologies, is forecast to be the fastest-growing segment, with a CAGR of 106% between 2027 and 2032. The forecast implies commercialization from an undeveloped tidal industry, since no commercial tidal power facility operated in Southeast Asia in June 2026. A 2025 Ateneo study identified the San Bernardino, San Juanico, and Cebu straits in the Visayas as potential tidal-stream generation sites. For tidal developers, realizing that growth requires commercial projects, with the potential Visayas sites offering a starting point for assessing where entry could occur. Bioenergy, by contrast, had an operating cogeneration example in the 8 MW expansion associated with Central Azucarera de San Antonio as of April 17, 2026.



By End-User:
Utility Scale Meets Direct Corporate DemandUtilities represented a 62.3% Philippines renewable energy market share in 2026. MTerra Solar Phase 1, an integrated solar and storage project, began commercial operations on August 26, 2026, under a power supply agreement with Meralco covering 600 MWac of mid-merit capacity.[3] The facility’s connection approval covered 950 MWac of solar and 825 MW of battery storage. Delivering the agreed mid-merit profile is therefore central to the largest segment’s utility relationship, because the contracted supply service differs from the project’s solar and storage equipment capacity.
Commercial and industrial users form the fastest-growing segment, forecast to register a CAGR of 22.3% between 2027 and 2032. ACEN Renewable Energy Solutions (ACEN RES) served 753 commercial and industrial customers in FY2025. Its overall Philippine retail electricity supply portfolio reached 587 MW in the first half of 2026. This nearly 22% expansion from end-2025 within six months supports the segment’s retail-supply opportunity, where contracting more electricity can serve business demand without requiring buyers to operate generation.

Geography Analysis
Luzon Renewable Energy Market
Luzon is the largest geography for renewable energy, with its commercial importance linked to both installed assets and the scale of electricity supply. DOE recorded 10,533 MW of installed renewable capacity on Luzon across on-grid and off-grid systems in 2025. Across generating technologies, the Luzon grid produced 89,614 GWh of gross electricity in 2025. For developers, this combines an established renewable fleet with a substantial electricity system in which a new project must find its commercial role.
Utility supply arrangements can give a hydro asset a commercial footprint extending beyond the province in which its equipment is located. SNAP-Benguet owns and operates the Ambuklao-Binga hydro complex in Benguet, comprising the 112.5 MW Ambuklao and 140 MW Binga plants. In Ilocos Sur, Luzon Hydro Corporation’s Bakun AC plant supplies the National Power Corporation under a power purchase agreement, with output dispatched to the Luzon grid through the Bauang-Bakun transmission line. Utility offtake can therefore shape the value of a hydro site alongside local generating capacity, because the buyer relationship connects that asset with the wider Luzon electricity system.
Ilocos Norte and Leyte present different commercial tasks involving investment in existing wind assets and the operation of geothermal generation. ACEN completed a 2-phase maintenance and repair program at its 52 MW NorthWind project in Bangui Bay, Ilocos Norte, during 2025 and 2026. First Gen’s 2025 operating portfolio included Leyte geothermal plants under its subsidiary Energy Development Corporation (EDC). The wind work illustrates investment in an existing facility, while the Leyte portfolio establishes an operating generation presence managed through a subsidiary. Maintaining plant performance can create commercial work independently of adding nameplate capacity, making asset condition a separate source of demand from new construction.
Regulatory Framework and Outlook
The comparison examines selected jurisdictions from the perspective of a registered renewable-energy developer assessing national support and provincial operating costs. Republic Act No. 9513 establishes a fiscal and nonfiscal incentive policy, with DOE as its lead implementing agency. Benguet’s revenue code levies 1.5% of assessed value on civil works, equipment, machinery, and other improvements actually and exclusively used for registered developers’ renewable-energy facilities. These instruments affect different parts of the investment case, with national project support and local asset-tax exposure each shaping commercial returns.
Regulatory Table of Philippines Renewable Energy Market
| Decision factor | Philippines | Benguet |
|---|---|---|
| Primary authority | Department of Energy | Provincial tax authorities |
| Key instruments or direction | Republic Act No. 9513; announced annual renewable auctions from 2026 | 2023 Revised Revenue Code, Section 8 |
| Commercial effect | Incentive framework and planned procurement access | Levy on qualifying renewable-facility improvements |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Easing | No change |
| Source: Mordor Intelligence | ||
The national Medium rating reflects incentive support tempered by project eligibility. Planned annual auctions from 2026 and deliveries from 2027 through 2035 support Easing through additional procurement opportunities, although July 2026’s GEA-5 offshore-wind hold made resumption conditional on approved supplemental documents. Benguet’s Medium rating balances defined tax treatment with a recurring charge on qualifying facility improvements. Its operative renewable-specific provision supports a No change direction, making local asset-tax exposure a continuing component of the developer’s cost structure.
Value Chain Stages
The value chain compares construction, generation sales, and retail supply, where suppliers earn through different contractual relationships. Terra Solar Philippines executed an engineering, procurement, and construction (EPC) contract with onshore contractor GEDI Construction Development Corporation for MTerra Solar’s South Block in Central Luzon on October 23, 2025. ACEN’s Philippine business used contracted sales channels for a significant portion of its capacity and sold remaining supply through the wholesale electricity spot market in FY2025. Value capture therefore shifts from delivering a physical project to selling its output and defining the terms of customer supply.
Value Chain Analysis Table of Philippines Renewable Energy Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Engineering, procurement, and construction | Onshore EPC contractors such as GEDI Construction Development Corporation; offshore EPC contractors such as China Energy International Group Co., Ltd. | EPC contract earnings | Coordination of design interfaces and construction milestones | Set interface responsibilities and acceptance milestones before mobilization |
| Generation and wholesale supply | Generation businesses such as ACEN Corporation | Contracted and wholesale electricity sales | Exposure of uncontracted output to spot-market pricing | Balance contracted commitments with residual spot-market sales |
| Retail electricity supply | Retail suppliers such as ACEN Renewable Energy Solutions | Electricity-agreement pricing for contracted or actual customer requirements | Pricing and delivery exposure under customer commitments | Align customer pricing and volumes with upstream supply terms |
| Source: Mordor Intelligence | ||||
Commercial entry and contract pricing create different exposures after project construction. In April 2026, DOE coordinated with grid, regulatory, and market bodies on transmission, interconnection, inspection, registration, and metering requirements for projects awaiting commercial operation. In FY2025, ACEN RES’s agreements with contestable customers under retail competition and the Green Energy Option Program used fixed rates or benchmark-indexed variable pricing. Retail earnings protection consequently depends on matching the customer’s price basis with the supplier’s underlying electricity exposure.
Competitive Landscape
Market Concentration
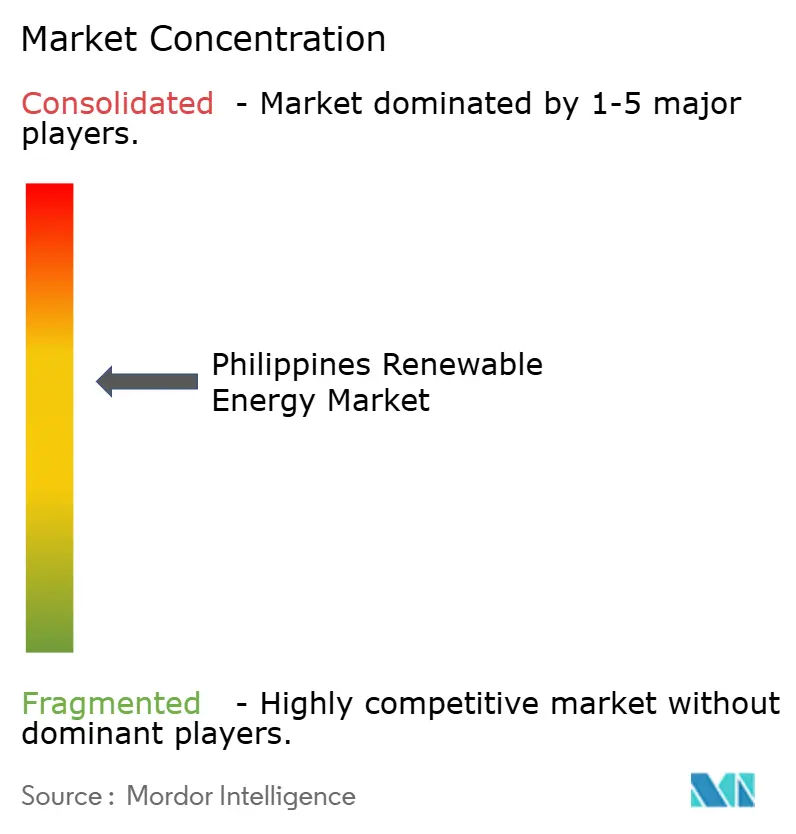
Competition is moderately concentrated around established generating groups, including Aboitiz Power Corporation and ACEN Corporation, alongside developers financing additional projects. Aboitiz Power’s Philippine operating renewable portfolio had 1,775 MW of attributable net sellable capacity as of February 28, 2026. First Gen Corporation’s operating portfolio comprised 31 renewable projects and installations across the Philippines, totaling 1,764.2 MW of installed capacity at year-end 2025. Solar Philippines Power Project Holdings Inc. held an interest in SP New Energy Corporation (SPNEC) on January 14, 2026. Vena Energy began building approximately 380 MWp across 2 Ilocos Norte solar projects in May 2026, positioning its prospective supply alongside Aboitiz Power’s and First Gen’s operating portfolios.
Corporate transactions and operating performance provide different routes to stronger competitive positions, with distinct consequences for the electricity available to buyers. ACEN’s Philippine renewable portfolio generated 1,091 GWh in the first half of 2026, up 17% from the corresponding 2025 period, largely because its Pagudpud and Capa 2 wind assets were more available. In October 2025, Meralco’s renewable affiliate MGreen acquired 10.8 billion SPNEC common shares from Solar Philippines Power Project Holdings. Better asset availability can therefore increase electricity from an existing portfolio, whereas a share transaction changes control of a corporate interest with no intrinsic addition to generating equipment.
Regulatory positioning becomes consequential when competition shifts from operating portfolios toward participation in proposed generation projects. In May 2025, ACEN signed agreements to acquire a 25% minority stake in Copenhagen Infrastructure Partners’ proposed Camarines Sur offshore-wind project, subject to applicable regulatory approvals. ACEN’s June 30, 2026 quarterly filing lists a 25% holding in the project company. Minority ownership gives ACEN a position in offshore-wind development. The operating wind assets contributed electricity in the first half of 2026, while the offshore stake remained a development position.
Philippines Renewable Energy Industry Leaders
-
Aboitiz Power Corporation
-
ACEN Corporation
-
First Gen Corporation
-
Solar Philippines Power Project Holdings Inc.
-
Vena Energy
- *Disclaimer: Major Players sorted in no particular order
Philippines Renewable Energy Market Companies Covered in this Report
- Aboitiz Power Corporation
- ACEN Corporation
- Solar Philippines Power Project Holdings Inc.
- Vena Energy
- First Gen Corporation
- Energy Development Corporation (EDC)
- SN Aboitiz Power Group
- Alternergy Holdings Corp.
- Trina Solar Co. Ltd.
- Vestas Wind Systems A/S
- Solenergy Systems Inc.
- Solaric Corp.
- National Power Corporation (NPC)
- Philippine Geothermal Production Company Inc.
- Meralco PowerGen Corp.
- Siemens Gamesa Renewable Energy
- Nexif Ratch Energy
- Kepco Philippines Holdings
- Enfinity Global Inc.
- Sharp Energy Solutions
Key Opportunities for Market Participants
The opportunities compare smaller own-use solar installations with renewable generation offers for remote electricity service. In August 2026, DOE simplified specified approvals for micro-solar systems up to 1 kilowatt and qualifying zero-export installations, while retaining applicable technical and safety requirements. Its September 2026 preliminary microgrid list covered 369 areas across 23 provinces and about 101,468 unenergized households, subject to validation, updating, and final determination for possible future bidding. These developments open different routes to customers, with installation compliance determining the smaller-system offer and service-area definition determining the remote-service proposition.
Market Opportunities Table of Philippines Renewable Energy Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Own-use micro-solar installations | Simplified micro-solar notification route | Households considering systems up to 1 kilowatt | Offer technically compliant installation and utility-notification support | Safe installation and compliance costs | Micro-solar suppliers and installers |
| Zero-export solar for care facilities | Specified approval waivers for qualifying installations | Clinics and hospitals | Combine zero-export safeguards with site-clearance verification | Cost of zero-export controls and structural compliance | Solar installers serving care facilities |
| Renewable generation for remote electricity service | Preliminary areas identified for possible future microgrid bidding | Unserved and underserved communities | Assess renewable configurations before committing development capital | Service-area uncertainty before final DOE determination | Prospective microgrid service providers |
| Source: Mordor Intelligence | |||||
The clearest near-term opening is a compliant own-use solar offer that converts narrower approval requirements into a practical installation service. Micro-solar systems still face applicable technical and safety duties, while the building-permit waiver for qualifying zero-export systems depends on existing structural clearance. Suppliers therefore need to distinguish these customer routes before quoting a standardized package, because the policy advantage comes from fitting the installation to the qualifying category.
Recent Industry Developments in Philippines Renewable Energy Market
- Sep 2026: DOE identified an initial 369 unserved and underserved areas across 23 provinces, covering about 101,468 unenergized households, for potential inclusion in future microgrid competitive bidding, subject to validation, updating, and final determination.
- Aug 2026: MTerra Solar Phase 1 began commercial operations on August 26 under its Meralco power supply agreement covering 600 MWac of mid-merit capacity.
- Aug 2026: DOE simplified specified approvals for qualifying own-use solar installations, including micro-solar systems up to 1 kilowatt, while retaining applicable technical and safety requirements.
Philippines Renewable Energy Market Report Scope and Research Methodology
Market Definition and Coverage
The Philippines renewable energy market measures installed capacity of renewable electricity assets operating in the Philippines, in gigawatts. Capacity is classified by generation technology and the end-user category served.
Scope exclusions: Renewable power revenue and wholesale electricity value, renewable energy certificate trading values, proposed or under-construction generation projects, separately sold generation equipment and construction services, and transmission and distribution assets are excluded.
Segments Covered in This Report
- By Technology
- Solar Energy (PV and CSP)
- Wind Energy (Onshore and Offshore)
- Hydropower (Small, Large, PSH)
- Bioenergy
- Geothermal
- Ocean Energy (Tidal and Wave)
- By End-User
- Utilities
- Commercial and Industrial
- Residential
Data Sources, Market Sizing, and Validation
Desk Research
The Department of Energy's 2025 Power Statistics and renewable energy project records provide installed and dependable capacity series, technology detail, and project status for the Philippines. The DOE's Green Energy Auction releases show the planned timing and technology focus of procurement, while the National Grid Corporation of the Philippines' transmission development plan informs checks on available connection capacity and grid constraints. The Board of Investments' renewable energy industry brief supplies sector context and cited public investment indicators. Examples such as these sources frame the Philippine capacity fact base and support cross-checks of annual changes.
Company annual reports, investor presentations, regulatory filings, and reputable Philippine energy coverage can clarify ownership, commissioning dates, contract activity, and project changes when public agency records need context. These named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would be directed to Philippine renewable project developers and operators, utilities, corporate procurement leads, and relevant engineering or regulatory specialists to test commissioning status, capacity classification, grid access, and expected additions. Analysts would reconcile respondent evidence with DOE records and public filings, investigate gaps through project-status and technology documentation, and triangulate unresolved items against independent capacity and transmission signals.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The model starts with a top-down total for operating renewable generation capacity in the Philippines, then estimates annual capacity additions and retirements by technology before deriving technology and end-user shares from the operating asset base and project commissioning evidence. Key inputs include DOE installed-capacity and technology records, auction awards and expected delivery dates, grid-connection availability and transmission constraints, electricity demand and sales trends, and project commissioning or retirement status. Each input informs the timing or likely scale of capacity entering service. Scenario analysis carries these indicators through the forecast period under different commissioning and grid-access schedules, while primary interviews check the plausibility of variable-level timing and capacity assumptions. Selective bottom-up checks compare the total with sampled project and supplier capacity roll-ups and channel evidence, using confirmed operating nameplate capacity rather than equipment sales or project costs. Gaps are investigated against project status and unit definitions, then reconciled to the top-down series without counting uncommissioned projects.
Data Validation & Update Cycle
Analysts triangulate the model against DOE capacity tables and project records, NGCP transmission signals, auction schedules, and company disclosures, then investigate unusual changes, inconsistent units, and material variances by technology and end-user. A second review checks source dates, commissioning status, classifications, arithmetic, and the fit between forecast additions and grid access, with anomalies resolved before sign-off and relevant respondents re-contacted when a project status, capacity figure, or delivery date remains unclear. The dataset is refreshed annually, updated between cycles after material policy, project, or grid events, and checked again in a fresh pre-delivery review.
Mordor Intelligence's Philippines Renewable Energy Market Sizing Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Philippines renewable energy market measures installed capacity of renewable electricity assets operating in the Philippines, in gigawatts.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key inputs include DOE installed-capacity and technology records, auction awards and expected delivery dates, grid-connection availability and transmission constraints, electricity demand and sales trends, and project commissioning or retirement status.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | 17.18 gigawatt (2027) | |
| Global Consultancy A | 7.1 gigawatt (2025) | At its 2025 base, this estimate is 58.7% below this report's 2027 value of 17.18 gigawatt, 2 years later. This is an earlier cumulative capacity stock than the report's estimate year. |
| Regional Consultancy B | 12.03 gigawatt (2025) | At its 2025 base, this estimate is 30.0% below this report's 2027 value of 17.18 gigawatt, 2 years later. This is an earlier installed-capacity stock than the report's estimate year. |
Mordor Intelligence's analysts triangulate the model against DOE capacity tables and project records, NGCP transmission signals, auction schedules, and company disclosures, then investigate unusual changes, inconsistent units, and material variances by technology and end-user.
Key Questions Answered in the Report
What is the Philippines renewable energy market size and growth outlook?
It is projected to reach 39.87 gigawatt by 2032 from 17.18 gigawatt in 2027, with a CAGR of 18.34% between 2027 and 2032.
What is driving Philippine renewable power demand?
Rising electricity demand and high retail rates support the commercial case for additional renewable supply. Meralco’s average retail rate rose 15% in the first half of 2026 from the corresponding 2025 period.
Which renewable technology held the largest share in the Philippines?
Hydropower was the largest technology segment, with a 38.9% share in 2026.
Which companies are prominent in the Philippine renewable power sector?
Aboitiz Power Corporation, ACEN Corporation, First Gen Corporation, Solar Philippines Power Project Holdings Inc., and Vena Energy are the major participants. Solar Philippines Power Project Holdings Inc. held an interest in SP New Energy Corporation on January 14, 2026.
What is a key constraint on Philippine renewable project delivery?
Grid access is a key constraint. In its 2026 survey, the OECD reported over 160 Philippine projects awaiting National Grid Corporation of the Philippines (NGCP) System Impact Studies, with backlog clearance potentially taking an additional year.
Which region is the largest renewable energy hub in the Philippines?
Luzon is the largest geography and had 10,533 MW of installed renewable capacity across on-grid and off-grid systems in 2025.