
- Albania
- Argentina
- Asia
- Australia
- Austria
- Bahrain
- Belgium
- Brazil
- Bulgaria
- Canada
- Chile
- China
- Croatia
- Cyprus
- Czech Republic
- Denmark
- Egypt
- Estonia
- Europe
- Finland
- France
- Germany
- Greece
- Hong Kong
- Hungary
- Iceland
- India
- Indonesia
- Ireland
- Italy
- Japan
- Kuwait
- Latvia
- Lithuania
- Luxembourg
- Macedonia
- Malaysia
- Malta
- Mexico
- Middle East and Africa
- Moldova
- Netherlands
- New Zealand
- Nigeria
- North America
- Norway
- Oman
- Panama
- Poland
- Portugal
- Qatar
- Romania
- Saudi Arabia
- Serbia
- Singapore
- Slovenia
- South Africa
- South Korea
- Spain
- Sweden
- Switzerland
- Taiwan
- Turkey
- United Arab Emirates
- United Kingdom
- United States
- Vietnam
Philippines E-commerce Market Analysis by Mordor Intelligence
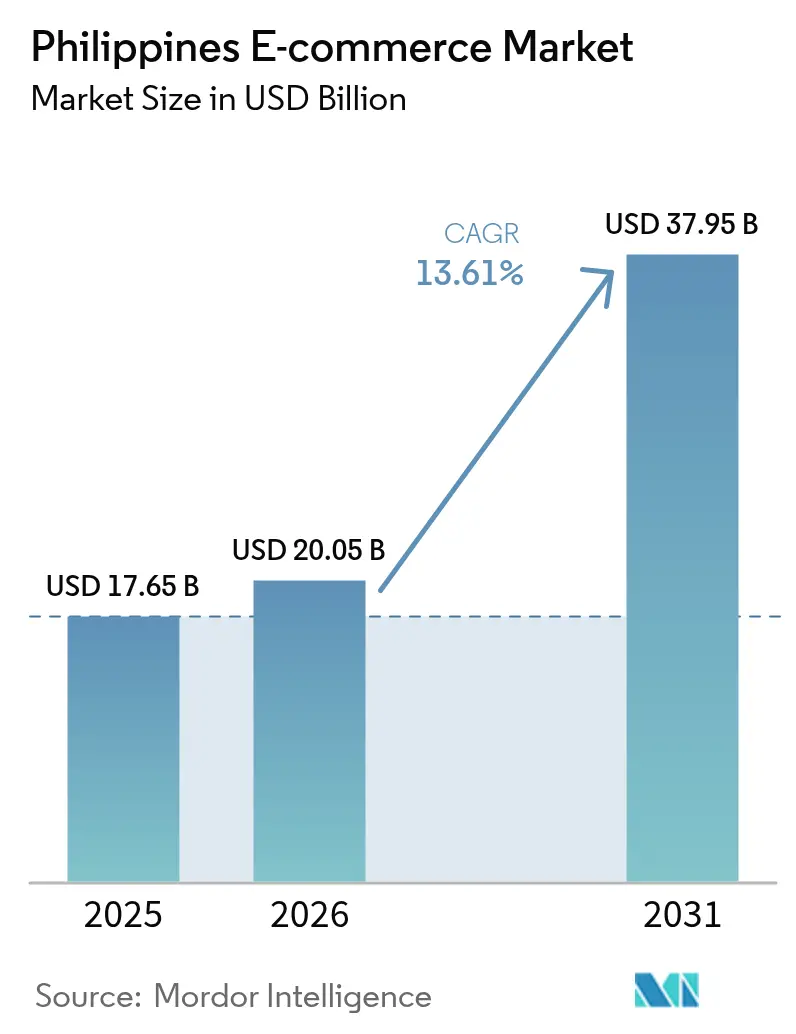
The Philippines e-commerce market size is projected to expand from USD 20.05 billion in 2026 and USD 22.78 billion in 2027 to USD 44.09 billion by 2032, registering a CAGR of 14.12% between 2027 and 2032.
Expansion in the Philippines depends on connecting digital payment access, usable selling channels and provincial fulfillment into a complete transaction. Mobile-first ordering benefits from wallets and installment options that let buyers pay within online checkout. Providers respond with forward warehouses in provincial cities and payment links inside logistics apps. Provincial parcel charges add delivery costs, while separate VAT and percentage-tax filing paths add administrative work for online sellers. Forward stock placement matters especially for small-parcel sellers beyond Metro Manila, because easier checkout leaves the cost of long-distance dispatch unresolved.
Key Report Takeaways
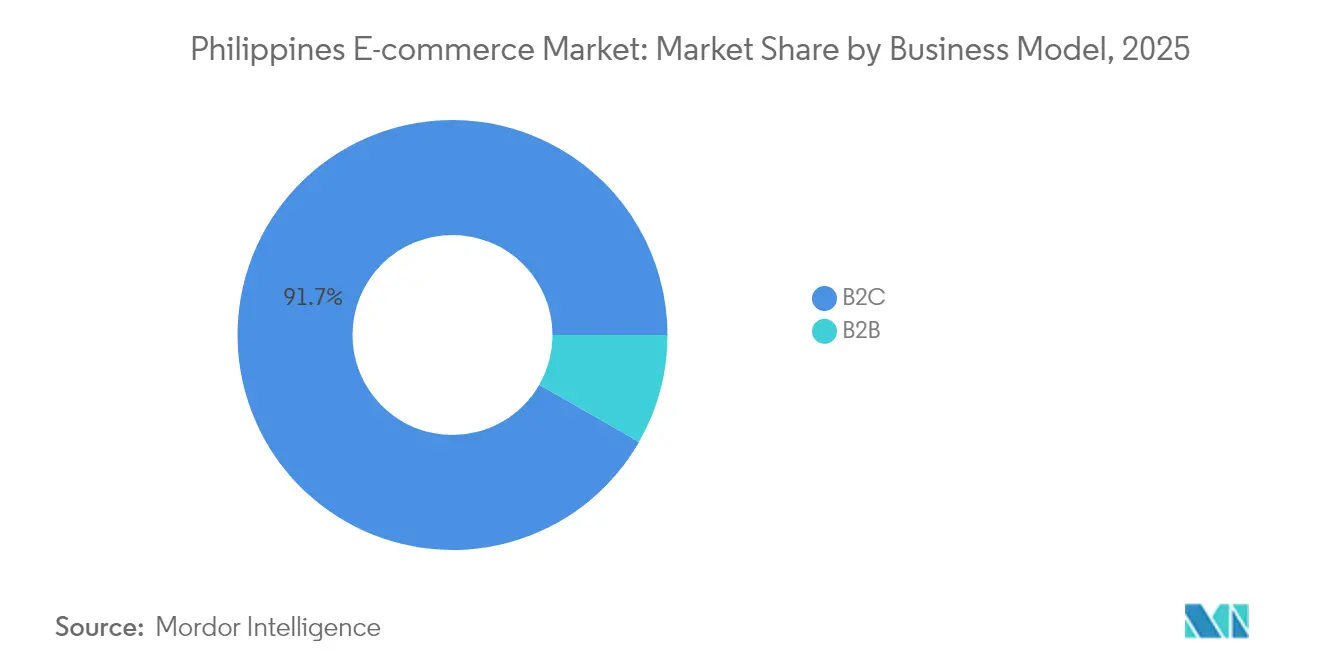
- By business model, B2C held a 91.64% Philippines e-commerce market share in 2026, and B2B is the fastest-growing segment at a 15.2% CAGR between 2027 and 2032.
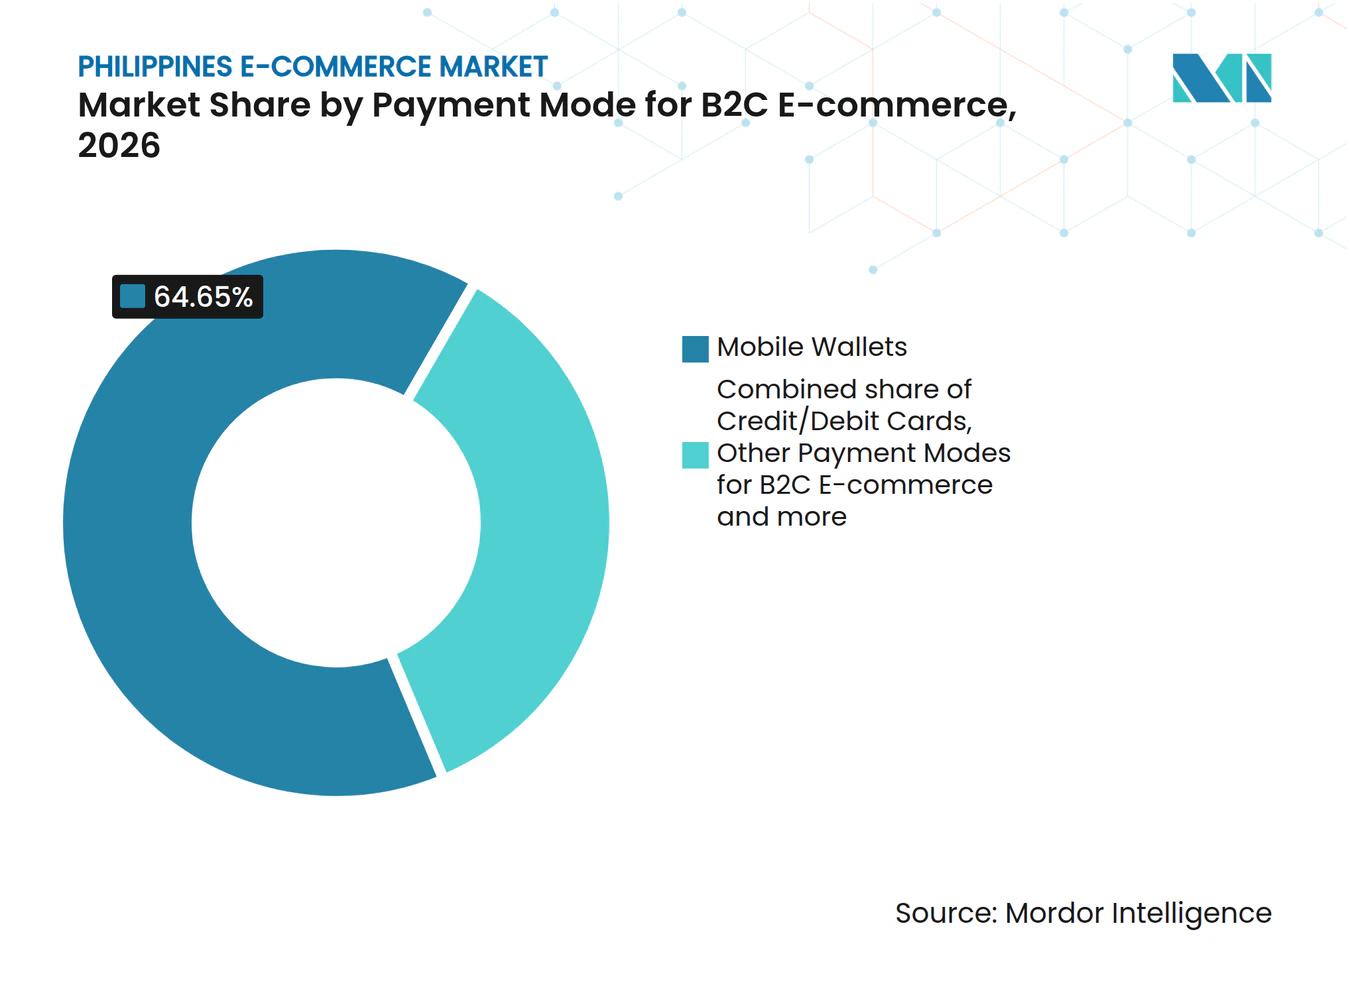
- Among payment modes for B2C e-commerce, mobile wallets led with a 64.65% share of market value in 2026, while other payment modes for B2C e-commerce are projected to grow fastest at a 15.85% CAGR between 2027 and 2032.
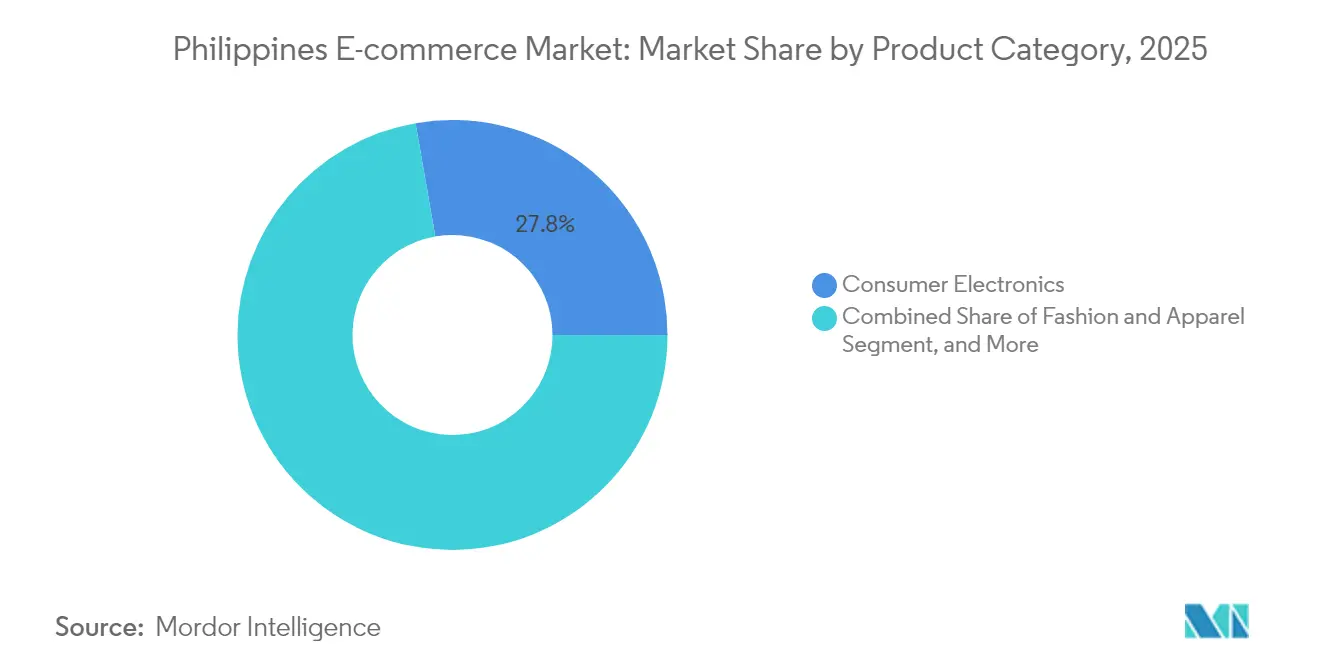
- By product category, consumer electronics accounted for a 27.58% share of the Philippines e-commerce market size in 2026, and food and beverages are forecast to grow fastest at a 14.85% CAGR between 2027 and 2032.
- Across shopping devices, smartphones were the largest segment with 78.9% of market value in 2026 and are projected to grow fastest at a 14.4% CAGR between 2027 and 2032.
- Geographically, Metro Manila (NCR) led spending in 2025, while Central Visayas is the fastest-growing regional market.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Philippines E-commerce Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Soaring mobile-wallet penetration (GCash, Maya) | +5.1% | Nationwide | Short term (≤ 2 years) |
| Logistics mini-hubs in provincial cities | +4.8% | Cagayan de Oro | Medium term (2-4 years) |
| Rapid cross-border social-commerce adoption | +3.9% | Nationwide | Short term (≤ 2 years) |
| Digital-payment mandates for government fees | +1.6% | Nationwide | Medium term (2-4 years) |
| MSME onboarding incentives | +1.2% | Nationwide | Short term (≤ 2 years) |
| AI-powered live-commerce engagement | +0.7% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Soaring mobile-wallet penetration (GCash, Maya)
An established e-money account base provides a pool of potential digital payers for online merchants. E-money account ownership among Filipino adults was 36% in 2025, steady from 2021, according to the Bangko Sentral ng Pilipinas (BSP) Consumer Finance and Inclusion Survey. The GSM Association (GSMA) described in December 2025 an online payment route in which users select GCash at a merchant checkout gateway and validate the payment by SMS. That connection lets an existing wallet account become a means of paying for an online order, giving merchants a way to serve holders who choose it. Wallet-led demand can develop through wider acceptance and more purchases per account even when the adult ownership share holds steady.
Logistics mini-hubs in provincial cities
Provincial fulfillment locations can change which orders are commercially practical for logistics operators to serve. In 2025, J&T Express launched a Cagayan de Oro forward warehouse for physical warehousing and forward fulfillment. The launch added a provincial location to the operator's logistics network. Positioning goods at such a node can shorten the portion of an order's route that must be handled after the order is placed. A forward-fulfillment model can shift part of the distribution task ahead of the final customer order, potentially making a wider service area feasible. Merchants serving buyers far from their main stock point stand to benefit most, because pre-positioning can remove a long dispatch leg from each subsequent order.
Rapid cross-border social-commerce adoption
Cross-border social commerce can expand the sellers reaching Philippine buyers within an in-app shopping environment. Under TikTok Shop's global-selling terms effective January 12, 2025, sellers usually resident or registered in mainland China or Hong Kong use cross-border seller accounts to sell to customers in available markets, including the Philippines. Sales are permitted only in jurisdictions made available to the particular account, subject to compliance with the terms and local product law. The sale contract remains between seller and customer, with TikTok Shop providing the marketplace. Additional eligible sellers can broaden product choice for Philippine shoppers, linking overseas supply to demand inside the app.
Digital-payment mandates for government fees
Public-service payments give digital payment providers an acceptance opportunity beyond discretionary online shopping. Under the Philippines' Executive Order 170 (EO 170) implementing rules adopted in 2022, covered agencies must offer digital collection of taxes, fees, tolls and other charges. The rules require cash and traditional payment methods to remain available alongside digital channels. They also specified a readiness-based, tiered transition capped at 3 years, tying implementation to agencies' operational capabilities. For e-commerce providers, broader acceptance can make the same payment channel useful across public and commercial transactions, strengthening the reason to maintain an accessible digital account. Because cash stays available under the rules, digital collection depends on agencies and payment providers making the digital option convenient enough for voluntary use.
Restraints Impact Analysis of Philippines E-commerce Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High last-mile costs outside NCR | -1.6% | Provincial Luzon, Visayas and Mindanao | Long term (≥ 4 years) |
| Fragmented VAT compliance among merchants | -0.8% | Nationwide | Medium term (2-4 years) |
| Data-privacy skills gap in SMEs | -0.5% | Nationwide | Medium term (2-4 years) |
| Port congestion and customs delays | -0.3% | Manila, Batangas and Subic Bay | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
High last-mile costs outside NCR
Provincial delivery charges can absorb a disproportionate part of the economics of a small online order. In its June 27, 2026 rate card, GoGo Xpress priced a 24 by 36 centimeter pouch weighing up to 3 kilograms at PHP 200 (USD 3.27) from Greater Metro Manila to Mindanao. The comparable within-Greater Metro Manila price was PHP 71.43 (USD 1.17), with both tariffs subject to VAT. Greater Metro Manila includes Metro Manila and specified surrounding cities, making this a comparison of the courier's defined delivery zones. For merchants serving these destinations, the higher charge raises the minimum order value needed to spread delivery expense economically. Absorbing that difference reduces the seller's proceeds, while passing it through raises the buyer's delivered price.
Fragmented VAT compliance among merchants
Different tax-filing paths create a classification task when a merchant expands its online selling activity. Bureau of Internal Revenue (BIR) guidance assigns VAT filing to online sellers above the gross-sales threshold and to sellers that choose VAT registration. For a business whose activity is covered by VAT, percentage-tax filing applies when sales do not exceed the threshold and it is not VAT-registered. This makes registration choice as well as sales level relevant to the correct filing path. Sellers near the threshold must account for a potential change in filing obligations, since exceeding it or opting into VAT registration changes which return they must file.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Philippines E-commerce Market Segment Analysis
By Business Model:
Consumer Scale and Business Network ExpansionB2C accounted for a 91.64% share of the Philippines e-commerce market size in 2026. Philippine video-commerce transaction volume rose 35% year over year in 2025. Within video-led B2C selling, that increase adds transactions for platforms and sellers to process. Over the same year, the number of Philippine video-commerce sellers and stores rose 90%, so transaction growth accompanied a much larger seller base.
B2B is forecast to be the fastest-growing segment, with a CAGR of 15.2% between 2027 and 2032. In March 2025, Shoppable Business reported more than 1,000 buyer companies and 2,500+ suppliers in its Philippine supply-chain network. The company operates a managed B2B marketplace, bringing business buyers and suppliers into a shared commercial environment. Supplier breadth can make that network relevant to more business requirements, while a broader company-buyer base increases the potential pool of counterparties. For company buyers, a managed network offers a way to compare suppliers within one marketplace rather than build each sourcing relationship separately.



By Payment Mode for B2C E-commerce:
Wallet Access and Installment DistributionMobile wallets were the largest segment, accounting for 64.65% of market value in 2026. Mynt's GCash reports more than 6 million partner merchants and social sellers on its app. In July 2025, Mynt, GCash's parent company, and logistics provider Flash Express introduced the Webpay payment option in the Philippines. At launch, Webpay enabled users to pay through the Flash Express app using GCash.[1] GCash thereby gains a payment point inside a delivery app, extending its usefulness beyond an individual merchant's checkout.
Other payment modes for B2C e-commerce are forecast to be the fastest-growing segment, with a 15.85% CAGR between 2027 and 2032. In September 2026, Billease and Swiftpay made buy-now-pay-later available at Swiftpay online checkouts in the Philippines.[2] Merchants already accepting payments through Swiftpay could enable Billease from their existing setup. Access through an established checkout can lower the implementation task associated with adding an installment option. Billease reaches Swiftpay merchants that choose to enable it, so wider installment availability depends on individual merchant activation rather than checkout integration alone.

By Product Category:
Electronics Reach and Grocery OrderingConsumer electronics represented a 27.58% Philippines e-commerce market share in 2026. In a survey reported by the Hong Kong Trade Development Council (HKTDC) in 2025, 90% of surveyed Philippine online shoppers had bought consumer electronics in the preceding 12 months. HKTDC's category definition spanned home appliances, computer-related products, smartphones, tablets, wearables and accessories. High purchase incidence within the surveyed audience leaves more scope for repeat, replacement and additional-device purchases than for recruiting first-time electronics buyers.
Food and beverages are forecast to be the fastest-growing segment, with a 14.85% CAGR between 2027 and 2032. In 2025, food and beverage accounted for only 3% of Philippine video-commerce gross merchandise value, leaving a small base for category expansion within that channel. By June 2026, WalterMart Grocery Delivery's recipe feature let shoppers in its delivery areas add a recipe's ingredients to their online cart in one click. A one-click recipe basket gives the grocer an opportunity to sell several ingredients from a single meal idea, potentially increasing items per order.
By Device Type for B2C E-commerce:
Smartphone Reach and Device FinancingSmartphones were the largest segment, with 78.9% of market value in 2026, and are projected to be the fastest-growing segment at a 14.4% CAGR between 2027 and 2032. In 2025, 86% of Filipino adults owned smartphones, up from 81% in 2021. That ownership base places device access within reach of a substantial adult audience, giving smartphone-oriented selling a broad potential customer pool. The gain of 5 percentage points between 2021 and 2025 widened the phone-owning adult base, consistent with the segment's forecast growth position.
A separate commercial mechanism is the financing of the devices themselves. Home Credit Philippines financed about 2.5 million smartphones between January 2024 and August 2025. Home Credit reported an average of 5,000 financed devices per day as of August 2025, providing a recurring route to handset access through consumer finance. For mobile merchants, device lenders support access to the hardware shoppers need before a retail promotion can reach them on a phone.
Geography Analysis
NCR E-commerce Market
NCR led regional e-commerce spending in 2025, with marketplace-linked logistics infrastructure supporting its role as the largest geography. In August 2026, SM Warehouses turned over a 40,000-square-meter Pasig facility to Shopee partners SPX Express and Scommerce Philippines. Dense logistics infrastructure and same-day fulfillment underpin that regional position. The Pasig addition gives Shopee's logistics partners more space close to metropolitan buyers, reinforcing the local fulfillment infrastructure behind NCR's spending leadership.
Central Visayas E-commerce Market
Central Visayas is the fastest-growing regional market, with seller preparation providing a route to broader digital participation. At least 70 micro, small and medium enterprises from Cebu gathered on March 2, 2026, for an online-marketing and digital-selling workshop. Shopee conducted the workshop with the Cebu Provincial Government and the Department of Trade and Industry (DTI). For participating businesses, the practical commercial task is to turn product-promotion capabilities into an offer that can be ordered and fulfilled. Training existing Cebu businesses can expand the pool of prepared marketplace suppliers without requiring those firms to be newly established.
Mindanao's seller onboarding and Clark's airport-linked construction plan address different parts of the regional commercial landscape. By June 2025, Lazada Philippines said it had onboarded more than 500 Mindanao sellers over the preceding few months. On May 19, 2026, Robinsons Land Corporation and Asian Infrastructure and Holdings Corporation broke ground on a planned FedEx logistics facility at Clark International Airport in the Clark Freeport Zone. The planned 15-hectare development is expected to deliver close to 78,000 square meters of gross floor area, with completion targeted for the first quarter of 2028. Lazada's onboarding count shows platform reach into Mindanao by mid-2025, while the Clark facility, with completion targeted for the first quarter of 2028, is a logistics project on a longer timetable.
Regulatory Framework and Outlook
The comparison covers the Philippines' national framework and Quezon City's local business-permit regime from the perspective of small, medium and large online goods merchants. The Internet Transactions Act covers Department of Trade and Industry (DTI)-regulated B2B and B2C transactions where a party is in the Philippines or a seller or platform serves the Philippine market with minimum contacts. Online media content and consumer-to-consumer transactions are excluded, while DTI administers the e-commerce jurisdiction. For a merchant with a business operation in Quezon City, the local permit requirement adds a separate administrative layer to that national framework.
Regulatory Table of Philippines E-commerce Market
| Decision factor | Philippines national framework | Quezon City local regime |
|---|---|---|
| Primary authority | Department of Trade and Industry for e-commerce; Bureau of Internal Revenue for tax administration | Quezon City Business Permits and Licensing Department |
| Key instruments or direction | Internet Transactions Act; RMC No. 98-2026 | Quezon City Revenue Code, Article 21, Section 67; City Ordinance No. SP-3013, S-2021 |
| Commercial effect | Electronic invoices by December 31, 2026 for small, medium and large e-commerce taxpayers; micro taxpayers exempt | Businesses operating in the city require a permit valid for 1 year from issuance |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Easing |
| Source: Mordor Intelligence | ||
National attractiveness is Medium given DTI's defined jurisdiction, while Hardening reflects required electronic invoicing by December 31, 2026 for small, medium and large e-commerce taxpayers, with micro taxpayers exempt. Electronic sales reporting depends on separate BIR implementing policies, keeping that obligation distinct from invoice issuance. On October 16, 2026, Quezon City and the Bureau of Fire Protection were coordinating linkage of their online permit and inspection systems, with full implementation targeted by the end of 2026's fourth quarter. Quezon City rates Medium because its permit duty recurs annually from issuance, while the planned system linkage supports Easing by coordinating permit and inspection administration.
Value Chain Stages
Value capture moves from marketplace access through payment acceptance to parcel delivery, with each stage monetizing a different part of a completed order. From May 11, 2026, Shopee Philippines added a category-dependent seller growth support fee calculated as a percentage of gross settlement price on successful transactions. It starts after 90 days from a seller's first listing unless Shopee determines and notifies the seller of another period. This timing creates a cost transition between initial entry and routine selling, while linking the platform's additional earnings to completed transactions.
Value Chain Analysis Table of Philippines E-commerce Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Marketplace selling and order placement | Marketplace operators such as Shopee Philippines | Seller fees on successful transactions | Seller fee exposure after the initial listing period | Include the fee commencement date in product-level contribution calculations |
| Payment acceptance and processing | Payment-service providers such as PayMongo Philippines, Inc. | GCash payment-processing fees | Processing deductions reduce the merchant's net receipt | Include acceptance charges in the minimum viable transaction contribution |
| Parcel pickup and delivery | Integrated express delivery groups such as J&T Global Express Limited | Parcel-delivery service charges | Charges depend on parcel size, weight, route and other factors | Determine parcel configuration and destination before committing a delivery price |
| Source: Mordor Intelligence | ||||
PayMongo quotes a 2.23% GCash payment-processing fee, exclusive of VAT. In its 2025 annual report, J&T described integrated delivery to certain enterprise and individual customers in the Philippines, using parcel size, weight, route and other factors to determine charges. Percentage-based digital fees and parcel-based delivery charges therefore respond to different characteristics of an order. Sellers must model the payment fee against order value and the parcel charge against size, weight and route as separate costs.
Competitive Landscape
Market Concentration
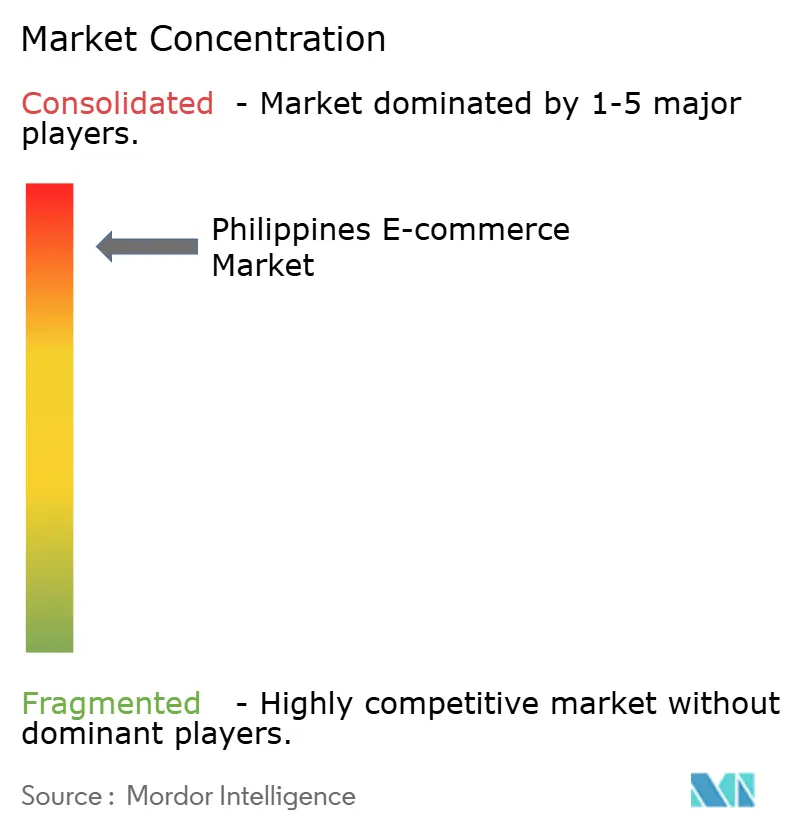
Competition combines multinational marketplace groups with fashion specialization and export facilitation. Major participants include Shopee Philippines (Sea Ltd.), Lazada Philippines (Alibaba Group), TikTok Shop Philippines (ByteDance Ltd.), Zalora Philippines (Global Fashion Group) and Amazon Global Selling Philippines (Amazon.com Inc.). In 2025, Shopee's global gross merchandise value rose 27% year over year, and its adjusted earnings before interest, taxes, depreciation and amortization exceeded USD 880 million. Such platform economics can make replicating a general-purpose selling service more demanding for entrants that must build operating capabilities and achieve sustainable earnings.
On September 24, 2025, Lazada Philippines and the Department of Science and Technology (DOST) signed a memorandum of understanding to onboard DOST-assisted MSMEs to LazMall and the Lazada Marketplace. TikTok Shop's Philippines Seller Academy introduced an AI livestream companion on June 24, 2026, offering tailored suggestions and scripts to selected sellers and affiliate creators. TikTok advises users to review recommendations for accuracy and compliance because the AI may make mistakes. Zalora Philippines operates a fashion marketplace with local independent sellers and nationwide delivery, while Amazon Global Selling provides Philippines-based sellers resources for selling through Amazon.com in the United States. Lazada's agreement targets assisted MSMEs, TikTok Shop equips selected livestream sellers with AI guidance, Zalora offers fashion sellers nationwide delivery and Amazon provides export resources, making seller support a distinct dimension of competition.
TikTok Shop Philippines' head of public policy reported 200% sales growth among its local sellers in 2025. Zalora's parent, Global Fashion Group, recorded a 15.2% year-over-year fall in Southeast Asia net merchandise value at constant currency in 2025, easing to a 9.7% decline in the fourth quarter. For challengers, these different performance signals make the target seller's category and selling channel central to a competitive offer. The Internet Transactions Act also requires e-marketplaces to provide effective, responsive reporting for consumers and merchants who deem a user or platform information unlawful. Entrants that operate an e-marketplace must support that reporting mechanism alongside seller acquisition, because the Act places the duty on every e-marketplace. DTI launched the E-Commerce Philippine Trustmark in July 2025 to help consumers identify legitimate online merchants and transact with greater confidence.[3] Its buyer-facing purpose makes verified seller identity commercially relevant to the presentation of an online offer. Certification support, seller training and sourcing discussions can each help merchants prepare a specific route to customers.
Philippines E-commerce Industry Leaders
-
Shopee Philippines (Sea Ltd.)
-
Lazada Philippines (Alibaba Group)
-
TikTok Shop Philippines (ByteDance Ltd.)
-
Zalora Philippines (Global Fashion Group)
-
Amazon Global Selling Philippines (Amazon.com Inc.)
- *Disclaimer: Major Players sorted in no particular order
Philippines E-commerce Market Companies Covered in this Report
- Shopee Philippines (Sea Ltd.)
- Lazada Philippines (Alibaba Group)
- TikTok Shop Philippines (ByteDance Ltd.)
- Zalora Philippines (Global Fashion Group)
- Amazon Global Selling Philippines (Amazon.com Inc.)
- Alibaba.com Philippines (Alibaba Group)
- Globe Fintech Innovations Inc. (GCash)
- Maya Philippines Inc.
- SM Retail Inc.
- Robinsons Retail Holdings Inc.
- UnionBank of the Philippines
- GrabExpress Philippines
- Ninja Van Philippines
- J&T Express Philippines
- Entrego Fulfillment Solutions Inc.
- LBC Express Holdings Inc.
- PayMongo Philippines
- Dragonpay Corporation
- Xendit Philippines
- Meta Platforms Inc. (Facebook Marketplace PH)
- Kumu, Inc.
Key Opportunities for Market Participants
Near-term selling opportunities differ according to whether merchants need consumer confidence, practical storefront activation, or access to institutional sourcing discussions. DTI launched the E-Commerce Philippine Trustmark in July 2025 to help consumers identify legitimate online merchants and transact with greater confidence.[3] Its buyer-facing purpose makes verified seller identity commercially relevant to the presentation of an online offer. Certification support, seller training and sourcing discussions can each help merchants prepare a specific route to customers.
Market Opportunities Table of Philippines E-commerce Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Trustmark-supported micro-merchant storefronts | Initial Trustmark registration fee waived for DTI-registered micro enterprises through December 31, 2026 | Eligible online micro-merchants | Pair a usable storefront with a Trustmark application and clear seller identity | Web-administration and documentary-stamp charges still apply | Eligible micro-merchants and their consumer buyers |
| Livelihood-product social storefronts | DSWD Field Office I and TikTok Shop trained livelihood sellers from several Luzon regions on September 3, 2026 | Participating Sustainable Livelihood Program product sellers | Turn training into sale-ready product offers and a workable order-handling process | Completing the operational steps between product promotion and an actual order | Participating sellers and TikTok Shop |
| Digital discovery for institutional sourcing | Trade-fair sourcing discussions continue through DTI's Buyers Day 2026 initiative | Institutions seeking Philippine products and MSME suppliers | Present supplier offers through the Bagong Pilipinas Marketplace's B2B engagement and negotiation route | Moving early-stage matching and negotiation into an agreed transaction | Philippine MSME suppliers and institutional buyers using the sourcing route |
| Source: Mordor Intelligence | |||||
The clearest immediate opening combines an eligible micro-merchant's sale-ready storefront with the time-limited Trustmark incentive. Web-administration and documentary-stamp charges leave a residual application cost. Social promotion must still be turned into orders and institutional matching into agreed transactions, so both routes depend on steps beyond a fee waiver. For an application-ready micro-merchant, seeking the Trustmark before the waiver ends is the most time-sensitive decision.
Recent Industry Developments in Philippines E-commerce Market
- Oct 2026: Hapag-Lloyd suspended new bookings to Manila, Batangas and Subic Bay from all origins and trade lanes, with the suspension scheduled through December 31, 2026.
- Sep 2026: The Bureau of Internal Revenue required small, medium and large taxpayers engaged in e-commerce or internet transactions to issue electronic invoices by December 31, 2026, with micro taxpayers exempt.
- Sep 2026: Billease and Swiftpay made buy-now-pay-later available at Swiftpay online checkouts in the Philippines. Merchants already accepting payments through Swiftpay could enable Billease from their existing setup.
Philippines E-commerce Market Report Scope and Research Methodology
Market Definition and Coverage
The Philippines e-commerce market measures the annual value of goods and services sold through online channels to buyers located in the Philippines, covering business-to-business and business-to-consumer commerce. The value is annual transaction spending in USD, classified by business model and product category and, for B2C purchases, by payment mode and ordering device.
Scope exclusions: Offline-only retail sales, pure C2C reselling between individuals, non-commerce digital services such as online media and ride-hailing, and transactions with buyers outside the Philippines are excluded.
Segments Covered in This Report
- By Business Model
- B2B
- B2C
- By Payment Mode for B2C E-commerce
- Credit/Debit Cards
- Mobile Wallets
- Other Payment Modes for B2C E-commerce
- By Product Category
- Beauty and Personal Care
- Consumer Electronics
- Fashion and Apparel
- Food and Beverages
- Furniture and Home
- Toys, DIY and Media
- Other Product Categories for B2C E-commerce
- By Device Type for B2C E-commerce
- Smartphone
- Desktop/Laptop
- Other Device Types for B2C E-commerce
Data Sources, Market Sizing, and Validation
Desk Research
The research uses Philippine market and policy context from sources such as the U.S. International Trade Administration's Philippines eCommerce guide, the World Bank's review of internet connectivity and digital transformation, the e-Conomy SEA country report, and BusinessWorld's reporting on online commerce and the digital economy. These materials help assess access, mobile use, digital payments, online retail channels, video commerce and the practical constraints that affect buyer reach and transaction activity.
Public company filings, investor materials and reputable business reporting can supplement this evidence by checking platform activity, merchant services, payment products, fulfillment capacity and material market developments. The named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Structured interviews would be sought with Philippine marketplace and merchant leaders, payment providers, fulfillment operators and online sellers, with survey input from buyers used to clarify purchase frequency, channel use, product mix and transaction value. Respondents would help check secondary evidence and assumptions by business model, category, payment mode and device, while unresolved differences would be traced to the underlying definition, year or coverage and compared with independent market signals.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 18% | |
| Mid tier: 40% | Functional/Unit leaders: 32% | |
| Smaller Players: 25% | Managers: 50% |
Market-Sizing & Forecasting
The model starts with a top-down estimate of annual online transaction spending by Philippine buyers, then checks selected totals against sampled average order value multiplied by order volume and a limited roll-up of seller or channel evidence. Key inputs include the number of online buyers and internet users, purchase frequency and average order values, merchant and fulfillment reach outside major urban centers, and payment use, and these indicators help explain the spending base and its expected change. Evidence from business-model totals and B2C product, payment and device patterns is used to derive segment shares that reconcile to the market total. Scenario analysis tests how changes in buyer adoption, spending, digital payment use and delivery coverage may alter the forecast. Interviews with Philippine market participants can test the variable-level assumptions and explain gaps between top-down totals and selective channel checks, while unavailable observations are handled with transparent proxy ranges and sensitivity checks rather than unsupported precision.
Data Validation & Update Cycle
Analysts triangulate annual transaction spending against independent indicators of online purchasing, digital payments, seller activity, platform development and delivery reach, then investigate outliers and material variance between source estimates. A second review checks the calculation trail, boundary, units, segment shares and year alignment, with source re-contact considered when definitions, coverage or reported values conflict. Analysts resolve anomalies before sign-off, refresh the model annually, reopen relevant inputs after material market or policy events, and conduct a fresh validation pass before delivery.
Mordor Intelligence's Philippines Ecommerce Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Philippines e-commerce market measures the annual value of goods and services sold through online channels to buyers located in the Philippines, covering business-to-business and business-to-consumer commerce.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key inputs include the number of online buyers and internet users, purchase frequency and average order values, merchant and fulfillment reach outside major urban centers, and payment use, and these indicators help explain the spending base and its expected change.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 22.78 B (2027) | |
| Global Data Provider A | USD 24.77 B (2025) | At its 2025 base, this estimate is 8.7% above this report's 2027 value of USD 22.78 B, 2 years later. Its page reports online retail revenue growth of 15-20% and a similar near-term forecast range, indicating a faster projected path. |
| Global Market Research Publisher B | USD 24 B (2025) | At its 2025 base, this estimate is 5.4% above this report's 2027 value of USD 22.78 B, 2 years later. Its forecast rises from the consumer retail GMV base, pointing to a higher projected path despite excluding B2B digital transactions and several services. |
Mordor Intelligence's analysts triangulate annual transaction spending against independent indicators of online purchasing, digital payments, seller activity, platform development and delivery reach, then investigate outliers and material variance between source estimates.
Key Questions Answered in the Report
What is the Philippines e-commerce market size and growth outlook?
The size is projected to rise from USD 22.78 billion in 2027 to USD 44.09 billion by 2032, at a 14.12% CAGR between 2027 and 2032.
Which forces support e-commerce demand in the Philippines?
Wallet acceptance, provincial fulfillment and cross-border social commerce support demand. Mynt and Flash Express introduced Webpay for GCash payments inside the Flash Express app in July 2025.
Which business model leads Philippine e-commerce?
B2C held 91.64% of total market value in 2026, making it the largest business-model segment.
Which companies are major participants in Philippine e-commerce?
Major participants include Shopee Philippines (Sea Ltd.), Lazada Philippines (Alibaba Group), TikTok Shop Philippines (ByteDance Ltd.), Zalora Philippines (Global Fashion Group) and Amazon Global Selling Philippines (Amazon.com Inc.).
What constrains expansion for Philippine online sellers?
GoGo Xpress's June 2026 pouch rate from Greater Metro Manila to Mindanao exceeded its comparable within-Greater Metro Manila rate. VAT and percentage-tax filing paths also differ by applicable sales and registration conditions.
Which regions lead Philippine e-commerce spending and growth?
NCR led spending in 2025, while Central Visayas is the fastest-growing regional market.