
Master Data Management Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 21.63 Billion |
| Market Size (2031) | USD 50.85 Billion |
| Growth Rate (2026 - 2031) | 18.66 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Master Data Management Market Analysis by Mordor Intelligence
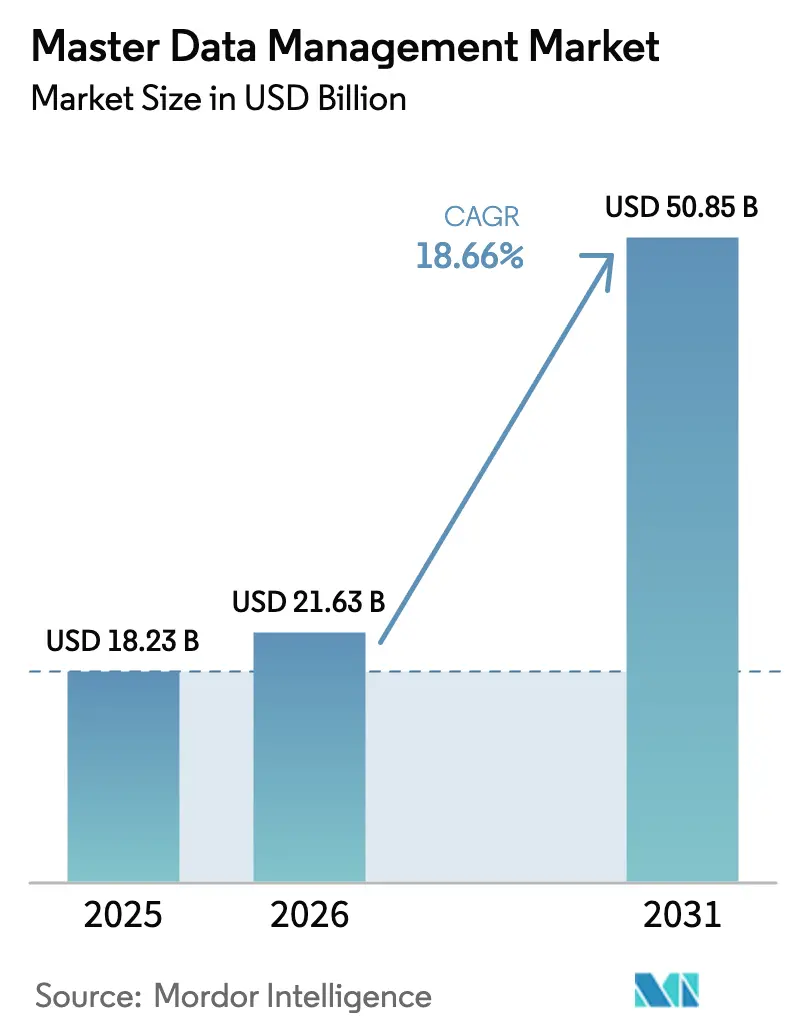
Master Data Management market size in 2026 is estimated at USD 21.63 billion, growing from 2025 value of USD 18.23 billion with 2031 projections showing USD 50.85 billion, growing at 18.66% CAGR over 2026-2031.
Enterprise priorities around generative-AI readiness, mandatory real-time ESG reporting, and cyber-resilience are accelerating demand for unified, high-quality data layers that feed analytics, automation, and risk engines. Software still dominates revenues, yet services are expanding faster as organizations seek design, change-management, and governance expertise to unlock value from increasingly complex deployments. Cloud implementations already deliver 61% of new installations, reflecting mid-market ERP migrations and the appeal of elastic, pay-per-use models that speed time-to-value. [1]Stibo Systems, “Cloud MDM Adoption Trends 2025,” stibosystems.com North America retains leadership with 39% share, while Asia Pacific is advancing at 19.52% CAGR on the back of data-localization laws and rapid digitalization.
Key Report Takeaways
- By component, software captured 67.42% of the Master Data Management market share in 2025, while services are expanding at a 19.26% CAGR through 2031.
- By deployment model, cloud deployments accounted for 60.35% of the Master Data Management market size in 2025 and are advancing at a 20.88% CAGR.
- By enterprise size, large enterprises held 63.25% share in 2025, whereas SMEs are projected to grow at a 19.74% CAGR to 2031.
- By application, customer-360 solutions led with 41.35% revenue share in 2025; finance & reference data management is expected to accelerate at a 22.06% CAGR.
- By industry vertical, BFSI commanded 20.58% of 2025 revenue, while healthcare is forecast to expand at a 18.73% CAGR.
- By integration pattern, batch ETL retained 53.10% share in 2025, whereas real-time event-driven architectures are rising at an 18.72% CAGR.
- By cloud deployment type, multi-tenant SaaS represented 41.30% of cloud implementations in 2025; hybrid architectures are growing at a 21.32% CAGR.
- By geography, North America led with 38.55% market share in 2025, and Asia Pacific is advancing at a 19.14% CAGR
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Master Data Management Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surging Gen-AI readiness drives need for high-quality training data | +4.2% | Global, led by North America & EU | Medium term (2-4 years) |
| Regulatory shift to real-time ESG disclosures | +3.1% | EU primary, expanding to North America & APAC | Short term (≤ 2 years) |
| Data-fabric & data-mesh architectures mainstreaming | +2.8% | Global, large-enterprise focus | Medium term (2-4 years) |
| Rapid cloud ERP migrations in mid-market firms | +3.5% | North America & EU core, growing in APAC | Short term (≤ 2 years) |
| Expansion of industry-specific 360-MDM SaaS (e.g., Retail, Life Sciences) | +2.9% | Global, sector-specific adoption patterns | Medium term (2-4 years) |
| Cyber-resilience mandates for critical infrastructure (NIS2, DORA) | +2.7% | EU primary (NIS2/DORA), spreading globally | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Surging Gen-AI Readiness Drives Need for High-Quality Training Data
Generative-AI projects expose the direct link between model accuracy and master data consistency. Informatica’s AI-enhanced cloud processed 86 trillion transactions, helping customers cut data-program time-to-value by 40%[2]Informatica, “Informatica Cloud Logs 86 Trillion Transactions,” informatica.com . Healthcare and financial services adopters are blending ChatGPT-style enrichment with MDM to raise data-matching accuracy to 80%, turning data quality from a compliance checkbox into a competitive edge. Continuous validation, enrichment, and lineage tracking are therefore moving from optional add-ons to core platform requirements inside the Master Data Management market.
Regulatory Shift to Real-Time ESG Disclosures
The EU’s Digital Operational Resilience Act obliges financial entities to maintain exhaustive ICT risk controls, including auditable master data governance that supports real-time ESG reporting. Traditional quarterly cycles cannot supply investors with carbon-footprint or supply-chain-ethics metrics at the required granularity, pushing enterprises toward platforms that reconcile sustainability data with the rigor of financial ledgers. Multi-jurisdictional operations must additionally accommodate differing data-sovereignty rules, complicating centralization strategies and fuelling hybrid-MDM demand.
Data-Fabric & Data-Mesh Architectures Mainstreaming
Capital One and the U.S. Centers for Medicare & Medicaid Services each deployed federated data-mesh patterns that hand domain teams ownership of master data while preserving enterprise standards. The approach reduces bottlenecks, shortens development cycles, and fits large manufacturers seeking to govern sprawling product hierarchies. MDM vendors are responding with decentralized stewardship workflows, fine-grained access controls, and shared semantics registries that align with mesh principles.
Rapid Cloud ERP Migrations in Mid-Market Firms
Two-thirds of 2024 ERP projects selected cloud delivery, creating urgent need for MDM to reconcile data during migrations and future hybrid states. Early-stage SAP S/4HANA programs that embed MDM cut cutover timelines and system complexity, proving that data quality determines ERP ROI. Subscription pricing and template-based deployments make enterprise-grade governance attainable for mid-market manufacturers and distributors seeking agility without ballooning IT overhead.
Restraints Impact Analysis of Master Data Management Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shortage of MDM-skilled data stewards | -2.1% | Global, acute in emerging markets | Medium term (2-4 years) |
| Hidden technical debt in legacy source systems | -1.8% | North America & EU legacy enterprises | Long term (≥ 4 years) |
| Access-control conflicts under emerging data sovereignty laws | -1.5% | APAC primary, expanding globally | Short term (≤ 2 years) |
| Rising hyperscaler egress fees inflating total cost of ownership | -1.3% | Global cloud deployments | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Shortage of MDM-Skilled Data Stewards
Seventy-five percent of manufacturers reported difficulty filling data-steward roles in 2024, reflecting demand for professionals who blend domain expertise with AI and governance fluency. While automation eases repetitive cleansing, human oversight remains vital for policy definition and exception handling. Managed-service and embedded-governance offerings are therefore rising as stop-gaps, especially in emerging markets where skill pipelines lag digital-transformation ambitions.
Hidden Technical Debt in Legacy Source Systems
Decades of custom logic, undocumented transformations, and inconsistent schemas double timelines and budgets once MDM discovery phases surface surprise dependencies inside financial-services and manufacturing estates. Organizations now insist on platforms offering deep data-lineage visualization and adaptive integration that can respect idiosyncratic legacy rules while establishing forward-looking standards.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Master Data Management Market Segment Analysis
By Component:
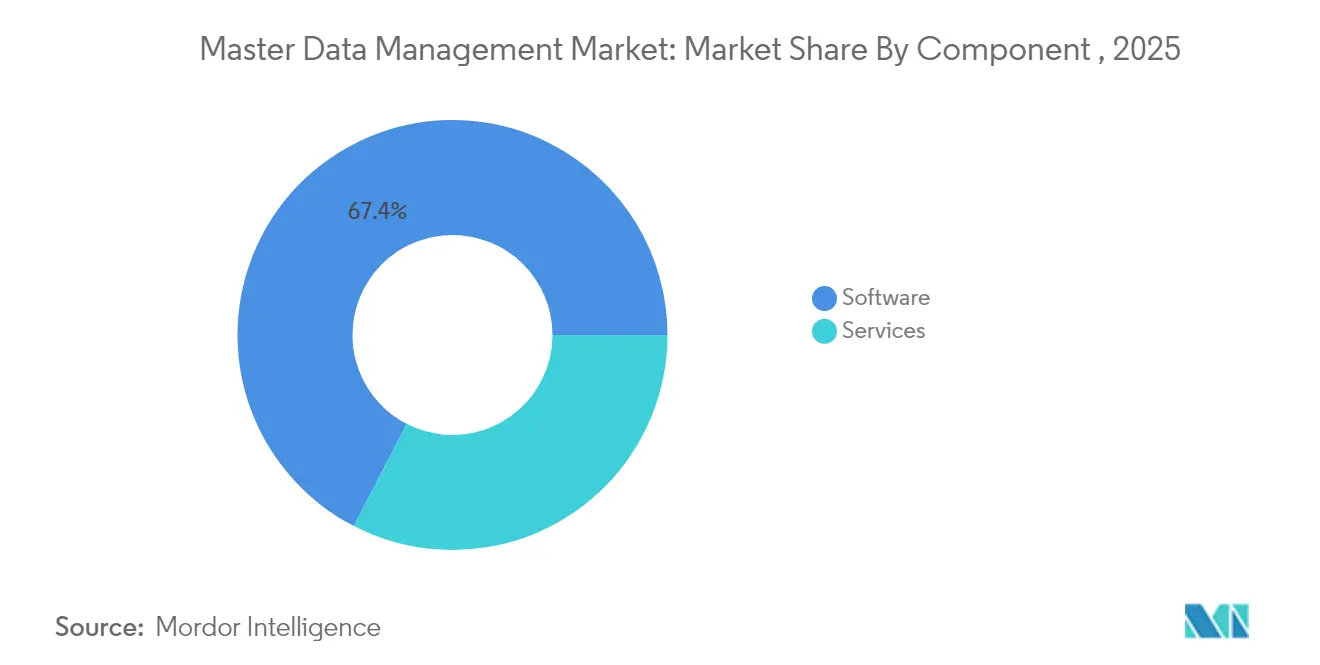
Services Growth Outpaces Software DominanceSoftware delivered 67.42% of 2025 revenue, but services are accelerating at 19.26% CAGR, signalling that the Master Data Management market is no longer technology-first. Enterprises in healthcare and banking invest in advisory, data-architecture design, and change management to navigate complex compliance landscapes. Professional services now encompass governance framework development and cross-domain policy harmonization, extending far beyond initial system integration.
Managed-service adoption among mid-market organizations shows that outsourcing stewardship and platform operations can balance limited internal capacity with quality expectations. As vertical regulations tighten, service partners with domain credentials become pivotal to monetizing software capabilities, reinforcing a shift where value lies in sustained governance outcomes.


By Deployment Model:
Cloud Acceleration Reshapes Market DynamicsCloud deployments commanded a 60.35% share in 2025 and are scaling at a 20.88% CAGR, redefining vendor selection criteria inside the Master Data Management market. Elastic scaling, automated patching, and usage-based pricing lower entry barriers, while pre-built connectors shorten time-to-insight for analytics teams.
Even highly regulated sectors now blend on-premise controls with cloud agility through containerized or SaaS edge nodes. The Master Data Management industry benefits as platforms integrate natively with cloud AI services, enabling real-time enrichment without heavyweight data-movement pipelines. Hybrid patterns thus satisfy sovereignty, latency, and economics in one architecture.
By Enterprise Size:
SME Adoption Accelerates Through Cloud AccessibilityLarge enterprises still hold a 63.25% share, yet SMEs are growing at a 19.74% CAGR as subscription models democratize the Master Data Management market. Smaller firms typically target single-domain wins—customer data unification or product catalog clarity—before expanding scope.
Cloud-native vendors supply template libraries and guided workflows that cut configuration effort, letting SMEs realize 15% revenue uplift and 20% lower risk exposure from better analytics. These proof points reinforce the business-case narrative that robust master data is no longer a luxury reserved for global conglomerates.
By Application Domain:
Finance & Reference Data Drives Regulatory ComplianceCustomer-360 use cases held 41.35% share in 2025, proving that unified customer experiences remain the prime catalyst for Master Data Management market investments. Yet, finance & reference data is projected to climb at 22.06% CAGR as real-time reporting mandates sweep across accounting standards and ESG frameworks.
Unifying supplier, product, and risk attributes under one governance umbrella equips CFOs to meet immediate audit requests and close books faster, converting compliance spending into decision-support value. Convergence toward multi-domain platforms is therefore accelerating, with asset and location data next in line as IoT digitizes physical operations.
By Industry Vertical:
Healthcare Transformation Accelerates GrowthBFSI contributed 20.58% of 2025 revenue, but healthcare is moving fastest at 18.73% CAGR, pushing the Master Data Management market toward patient-centric innovation. Verato’s identity-resolution cloud allows providers to match electronic records across institutions, lowering duplicate charts and enhancing clinical insights, Healthcare IT News. Regulatory incentives tied to care-quality metrics make robust provider and patient master data a non-negotiable foundation.
Retail, manufacturing, and telecom also expand footprints, each seeking domain-specific gains—digital-shelf accuracy, supply-chain resiliency, and converged customer-device profiles—underscoring that sector specialization is becoming a key vendor differentiator.
By Integration Pattern:
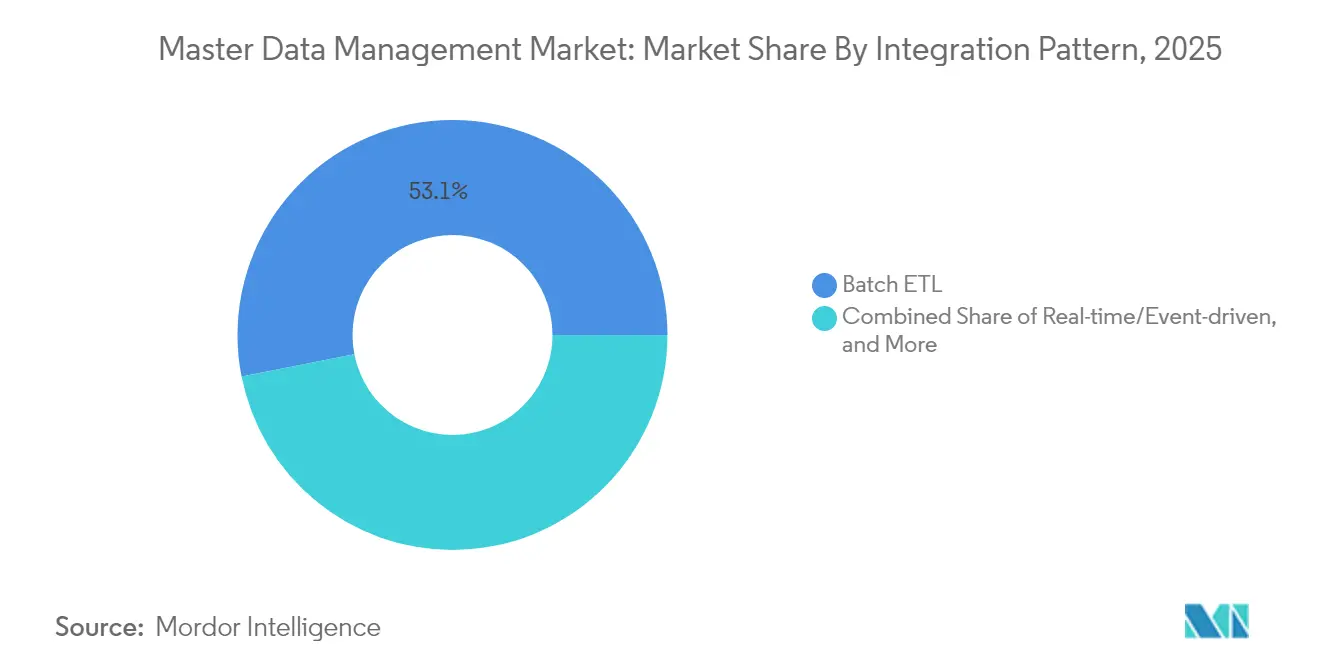
Real-Time Architectures Challenge Batch DominanceBatch ETL still represents 53.10% of integrations, yet event-driven designs are leaping forward at 18.72% CAGR as instant personalization and fraud-detection use cases proliferate. Streaming pipelines push updates into downstream applications within milliseconds, elevating data-quality SLAs and demanding fine-grained error-handling built into MDM cores.
API-first microservices broaden developer adoption, letting digital-product teams tap governed master data without complex middleware. The Master Data Management market therefore pivots toward low-latency orchestration where data contracts, versioning, and observability take center stage.
By Cloud Deployment Type:
Hybrid Models Balance Control with ScalabilityMulti-tenant SaaS delivers 41.30% of cloud installations thanks to rapid pay-as-you-go rollouts. Still, hybrid architectures are climbing at 21.32% CAGR, enabling headquarters to keep sensitive master records on-premise while leveraging cloud analytics for less regulated datasets. European enterprises, facing GDPR and upcoming AI Act requirements, exemplify the demand for architectures that partition workloads by jurisdiction while presenting a unified data-governance façade.
Vendors now package policy-based routing that decides where master attributes reside and how they synchronize, ensuring compliance without losing cloud elasticity—an approach quickly becoming a baseline requirement for multinational deployments.
Geography Analysis
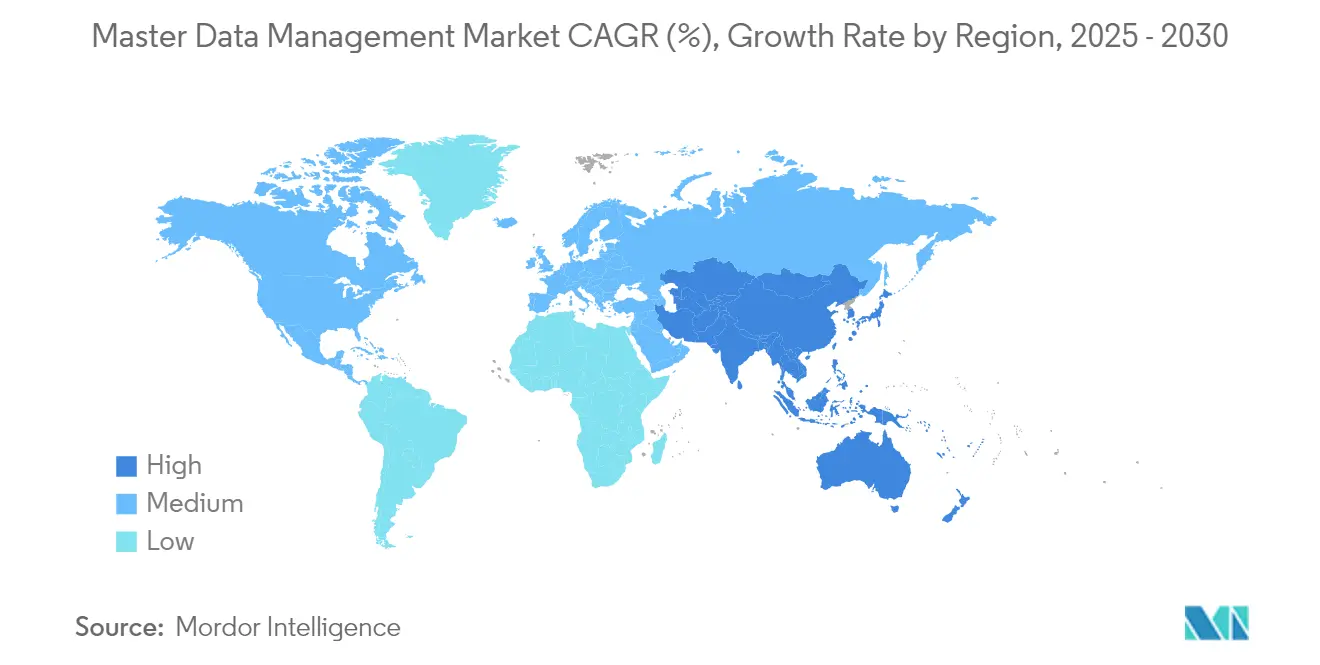
North America Master Data Management Market
North America led with a 38.55% share of the Master Data Management market in 2025, supported by stringent sectoral regulations and early AI adoption. U.S. firms such as WeightWatchers streamlined 30 million client records using Oracle Customer Hub, illustrating how mature governance programs translate into lower customer-experience frictions. Canadian and Mexican enterprises are close behind, exploiting cross-border commerce and USMCA incentives to modernize data architectures.
APAC Master Data Management Market
Asia Pacific is forecast to grow at 19.14% CAGR through 2031 as data-localization mandates reshape enterprise strategies. China’s rapid data-center build-out, coupled with constraints on cross-border transfers, drives demand for domestically hosted MDM solutions that interoperate with global supply-chain data . India’s 2025 Digital Personal Data Protection Act draft rules intensify the focus on consent management and data-lineage transparency, prompting local firms to adopt governance-rich platforms ahead of enforcement thresholds. ASEAN’s 20% data-center revenue growth signals rising capacity to support region-wide MDM rollouts
Europe Master Data Management Market
Europe maintains steady expansion under GDPR, DORA, and the incoming EU AI Act, positioning the region as a global benchmark for comprehensive data governance. Institutions such as Deutsche Börse centralized master data with SAP Master Data Governance to cut manual maintenance and accelerate product launches. Heightened enforcement actions in nations like the Netherlands propel investment in lineage-rich solutions that can evidence compliance when regulators demand audits. Hybrid architectures dominate European roadmaps, balancing sovereignty with the need to tap global cloud ecosystems.

Regulatory Landscape
Regulation is tightening around demonstrable data governance, lineage, and operational resilience, which elevates master data management from an IT best practice to a compliance control. In the EU, the Digital Operational Resilience Act (DORA) has applied since January 17, 2025, requiring financial entities to evidence ICT risk controls and auditable data flows. The EU AI Act also adds explicit data governance obligations for high-risk AI systems, including training-data quality and bias controls, with major high-risk obligations anchored to August 2, 2026. This combination increases demand for MDM capabilities that can produce defensible provenance, policy controls, and audit-ready documentation across domains used in risk, reporting, and AI pipelines.
Outside the EU, government data-management mandates are also formalizing requirements that map to MDM practices. The UK published a Data Asset Management Policy in May 2026, setting minimum expectations for data quality, discoverability, and interoperability across government bodies. In the United States, OMB Memorandum M-25-05 (January 2025) reinforces open standards and comprehensive data inventories under the Evidence Act implementation guidance. In Asia-Pacific and adjacent markets, Pakistan approved a National Data Governance Policy in June 2026 covering privacy-by-design and auditability, and Papua New Guinea issued Government Data Standards effective January 1, 2026. Under the Papua New Guinea standards, public bodies are required to meet data lifecycle requirements by December 1, 2026, reinforcing adoption of governance-led MDM architectures aligned to sovereignty and public-sector controls.
Value Chain Analysis
The value chain for master data management starts with upstream data creation and capture across ERP, CRM, HCM, PLM, EHR, and industry systems, then moves into ingestion and integration (connectors, ETL/ELT, APIs, event streams) and data quality services (profiling, matching, deduplication, enrichment). Core platform activities include identity resolution, survivorship and golden-record management, hierarchy management, metadata and lineage, and policy-driven access controls, followed by publishing and activation into analytics, AI, customer engagement, and operational applications. With cloud deployments accounting for 60.35% of installations (2025), cloud marketplaces and hyperscaler ecosystems increasingly sit in the distribution layer, influencing integration patterns and cost-to-serve dynamics.
Downstream value realization depends heavily on services partners and internal governance roles (data owners, stewards, and compliance teams) to define policies, resolve exceptions, and measure data-quality SLAs. This matches the market split where services hold 32.58% of revenue in 2025 and are expanding faster than software. Common bottlenecks include legacy-source technical debt and the shortage of skilled data stewards, which pushes more buyers toward managed services and automation features such as AI-assisted matching and enrichment. In supply-chain and trade-facing use cases, MDM hubs are also being linked with external reference feeds (for example, tariff and sustainability-related attributes) so enterprises can operationalize product, supplier, and compliance master data in near real time, raising the value of orchestration layers that connect MDM outputs to procurement, logistics, and risk workflows.
Competitive Landscape
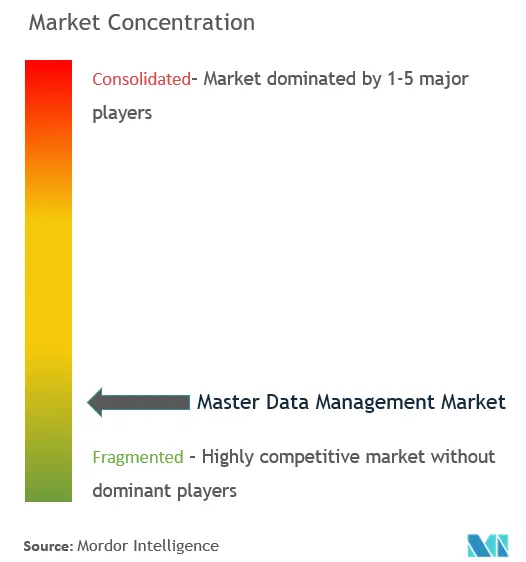
The Master Data Management market is moderately fragmented: top legacy vendors IBM, SAP, and Oracle compete with cloud-native challengers Reltio, Stibo Systems, and Semarchy, while hyperscalers embed native governance services that threaten standalone platforms. Salesforce’s USD 8 billion purchase of Informatica melds CRM data with enterprise-grade governance, signalling consolidation that blends front-office context with back-office rigor.
Innovation patterns show a pivot toward AI-embedded governance; Informatica processed trillions of transactions using CLAIRE AI to automate profiling and matching, whereas Palantir patented attribute-analysis engines that enrich master records during ingest. Vertical templates are now mainstream: Stibo Systems’ STEP for retail and Semarchy’s Snowflake integration exemplify turnkey offerings that shorten deployment cycles for focused use cases.
Vendor strategy increasingly centers on partnerships. Stibo Systems joined Microsoft’s software ecosystem to fuse Azure OpenAI with product-data optimization, and Reltio linked with Workato to combine workflow automation and data activation. Private-equity backing, such as Pamlico Capital’s investment in Profisee, funds accelerated R&D aimed at SME-friendly cloud propositions. Collectively, these moves illustrate a market in which speed-to-value and domain fit often outweigh breadth of generic functionality.
Master Data Management Industry Leaders
IBM
Oracle
Informatica Inc.
SAP SE
Ataccama
- *Disclaimer: Major Players sorted in no particular order
Master Data Management Market Companies Covered in this Report
- IBM
- SAP SE
- Oracle Corporation
- Informatica Inc.
- SAS Institute Inc.
- TIBCO Software Inc.
- Talend (Qlik)
- Ataccama
- Stibo Systems
- Profisee
- Reltio
- Semarchy
- Syndigo
- Teradata Corporation
- Riversand (Syndigo)
- Magnitude Software
- Informatica MDM Cloud
- CluedIn
- Pimcore

Market Opportunities and Future Outlook
A whitespace is forming around MDM as the governed context layer for agentic AI, where AI systems require trusted entity data, lineage, and controls, not only batch-published golden records. Market activity in 2026 has focused on standard interfaces and delivery patterns that let AI agents consume and invoke MDM capabilities directly, including support for the Model Context Protocol (MCP) and headless consumption models. Stibo Systems launched an MCP Server (June 2026), Informatica added MCP-focused capabilities in its Spring 2026 IDMC release (May 2026), and Profisee made generally available a 2026 R1 release positioned around AI agents and MCP server support (March 2026). These announcements create an opportunity for vendors and integrators to productize governed data access for AI workflows without expanding manual stewardship overhead.
Another opportunity is platform consolidation and tighter integration with enterprise application estates, especially where cloud ERP migrations and regulatory documentation requirements converge. SAPs announced agreement to acquire Reltio (March 2026), highlighting how large platform vendors are pulling MDM closer to data clouds and application platforms to accelerate AI-ready data foundations and reduce integration friction. At the same time, sovereign and regulated deployments continue to need hybrid control planes, supporting offerings that combine role-based and attribute-based access controls, auditability, and migration tooling across cloud and on-premise footprints. IBM MDM 2.4 positioning around enhanced governance and access control (June 2026) also fits this demand pattern.
Recent Industry Developments in Master Data Management Market
- June 2026: Informatica expanded the reach of its agentic MDM direction, positioning Agentic Multidomain MDM to support enterprise AI data governance across SAP and non-SAP environments. The update reinforces MDM as an operational layer for governed data context in heterogeneous application landscapes, not only as a back-office hub.
- May 2026: Informatica announced Agentic Multidomain MDM and introduced headless data management capabilities, including Model Context Protocol (MCP) support to let AI agents invoke MDM functions across major cloud and data platforms (AWS, Microsoft, Google Cloud, Databricks, and Snowflake). This shifts competitive differentiation toward standards-based, API-first activation of golden records and stewardship workflows for AI use cases.
- February 2026: IBM rebranded IBM Match 360 as IBM Master Data Management (MDM) with the 5.3 release, emphasizing a cloud-native, machine-learning-powered architecture. The repositioning aligns the product portfolio more directly with enterprise MDM buying motions and modern governance requirements.


Master Data Management Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the master data management market is defined as revenue earned from software and related services used to create, govern, match, and maintain a trusted master record for core business data (such as customer, product, supplier, and location) across enterprise systems.
Scope exclusions: We exclude general-purpose data warehousing and BI tools, pure ETL tools without an MDM hub, and internal IT labor that is not billed as an MDM product or service.
Segments Covered in This Report
- By Component
- Software
- Services
- By Deployment Model
- On-premise
- Cloud
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
- By Application Domain
- Customer
- Product
- Supplier
- Finance and Reference Data
- Asset and Location
- By Industry Vertical
- BFSI
- Healthcare and Life Sciences
- Retail and e-Commerce
- Manufacturing
- IT and Telecom
- Government and Public Sector
- Energy and Utilities
- Others (Education, Media, etc.)
- By Integration Pattern
- Batch ETL
- Real-time/Event-driven
- API-led Micro-services
- By Cloud Deployment Type
- Multi-tenant SaaS
- Single-tenant SaaS
- Self-managed Cloud (IaaS)
- Hybrid (Cloud + On-prem)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- GCC (Saudi Arabia, UAE, Qatar, etc.)
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the outer boundaries of the market and to align terminology so we do not mix MDM with adjacent data management categories. We referenced public materials such as US SEC filings, company annual reports, and investor presentations to understand reported revenue splits, partner motions, and product positioning.
To anchor adoption and policy signals, we also reviewed reputable public sources such as NIST publications on data governance and identity practices, ISO standards pages related to data quality concepts, guidance and statistics from the US Bureau of Labor Statistics on IT spending and employment, OECD digital economy publications, and selected peer reviewed journal articles on master data quality and stewardship outcomes. Where needed, paid databases were used for company financials and intelligence, news and financials, and patent databases to cross-check product direction and major release timing. This list is illustrative only, and other public and paid sources were used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on validating what portion of enterprise data management budgets is realistically captured by MDM programs, and how that share changes by industry and deployment choice. We spoke with solution implementers, channel partners, enterprise data leaders, and data governance owners across major regions, so assumptions on pricing, renewal behavior, and cloud migration timing could be checked and adjusted to better match buying behavior.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 32% | CXOs: 15% | APAC: 44% |
| Mid tier: 50% | Functional/Unit leaders: 26% | EMEA: 35% |
| Smaller Players: 18% | Managers: 59% | Americas: 21% |
Market-Sizing & Forecasting
Sizing was built using a top-down and bottom-up logic. First, global enterprise software and data-management spending is narrowed into the addressable MDM pool by applying adoption and budget-share filters that were verified in interviews. To keep the results realistic, we then cross-check the total using selective bottom-up approximations, such as sampled vendor revenue disclosures, channel checks on typical deal sizes, and an ASP-by-customer cohort approach.
Inputs that materially influence the model include cloud versus on-premises mix (which changes subscription recognition), average contract duration and renewal rates, implementation-to-license ratios for common deployment patterns, the share of regulated industries that run formal data governance programs, and the pace of consolidation that triggers MDM re-platforming. Forecasting uses scenario analysis supported by short time series smoothing, since buying cycles can be uneven and depend on broader IT budget intent. If bottom-up signals are incomplete for smaller providers, the gap is handled through calibrated penetration rates constrained by observed procurement behavior and partner activity, and then reviewed again with primary feedback.
Data Validation & Update Cycle
Totals are validated through triangulation across multiple independent checks, including vendor reported growth commentary, hiring trends for data roles, cloud migration indicators, and contract language shifts that affect recurring revenue timing. Outliers are flagged early, then investigated by rechecking the original assumptions, the currency conversion window, and whether revenues were counted as software, services, or bundled subscriptions.
Before sign-off, the model is reviewed in steps by another analyst to confirm that the logic, math, and scope rules are consistent across regions and years. The report is refreshed annually, and we also do interim updates when material events occur, such as major pricing changes, licensing model shifts, or sharp macro demand changes. Right before delivery, a final pass is completed so clients receive the most current view supported by the latest available inputs.
Mordor Intelligence's Master Data Management Market Size Compared With Other Published Estimates
Published market sizes for master data management can vary widely because the counted revenue line is not always the same, and because currency timing and subscription recognition can shift the reported value in a given year. Differences also show up when one estimate treats MDM as a narrow hub product, while another rolls in broader data governance, data quality, or integration tools.
When refresh cadence is slower, older contract price points and prior year exchange rates can stay embedded in the model even after vendors move toward new cloud packaging and bundled subscriptions, which changes effective ASPs. By rechecking pricing logic around subscription terms, services attachment, and currency conversion windows during updates, Mordor Intelligence ties the number to what enterprises typically pay for MDM programs in the stated year, and then validates it using interview-backed adoption filters.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 18.23 B (2025) | |
| Trade Journal B | USD 18.01 B (2024) | Uses an earlier base year and may include a broader set of data management capabilities around MDM, with limited transparency on currency conversion timing and recurring revenue treatment. |
| Regional Consultancy A | USD 22.59 B (2025) | Appears to apply a more aggressive ASP progression and may count adjacent governance and data quality tooling within the same revenue pool, which lifts the 2025 total versus a stricter MDM-only boundary. |
The spread across published values is mainly explained by what is included with MDM, and by how subscription pricing and currency are timed to a specific year. Our approach stays traceable to clear scope rules and repeatable checks, so users can reconcile the total back to adoption, pricing, and deployment mix assumptions.


Key Questions Answered in the Report
What is the current size of the Master Data Management market?
The Master Data Management market stands at USD 21.63 billion in 2026 and is projected to reach USD 50.85 billion by 2031.
Which deployment model is growing fastest
Cloud implementations lead growth, expanding at 20.88% CAGR as enterprises shift workloads to scalable, pay-per-use architectures.
Why is healthcare the fastest-growing vertical?
Healthcare records unify patient identities and provider data to power AI-driven clinical decisions, driving a 18.73% CAGR through 2031.
How are generative-AI projects influencing MDM investments?
AI initiatives demand pristine training data, increasing MDM platform adoption to automate cleansing, enrichment, and lineage tracking.
What restraints could slow market expansion?
global shortage of data-steward talent and unresolved technical debt within legacy systems can stretch project timelines and budgets.
Page last updated on:





