
Indonesia Life and Non-Life Insurance Market Analysis by Mordor Intelligence
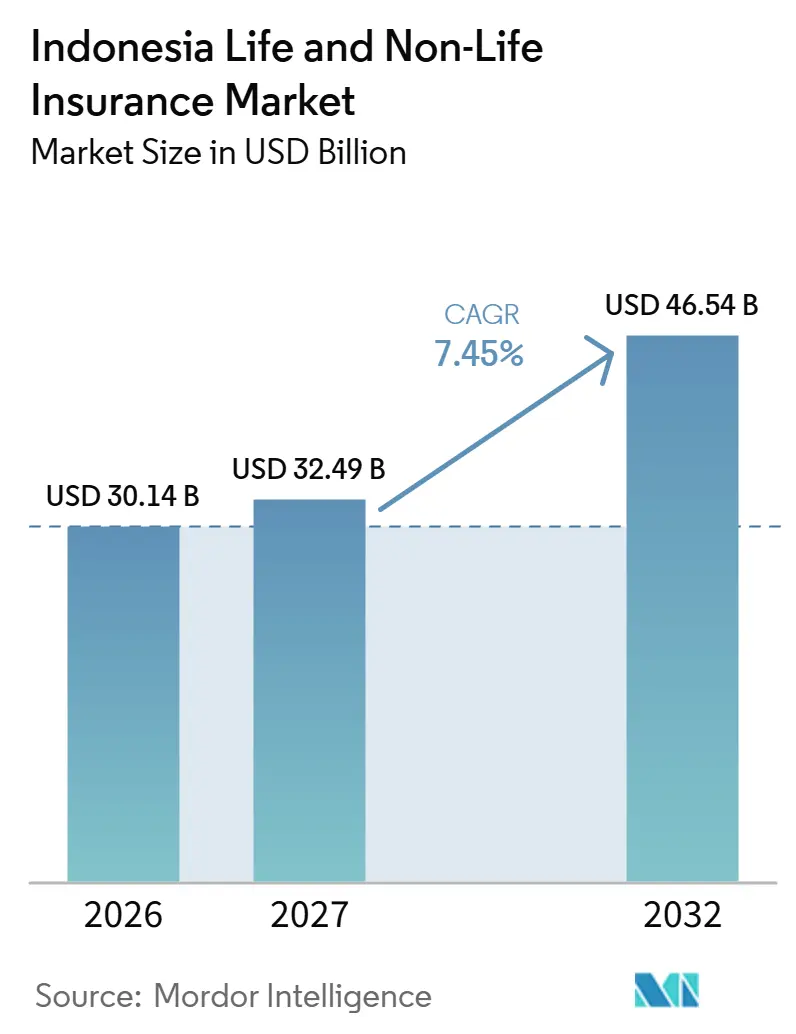
The Indonesia life and non-life insurance market size is expected to increase from USD 30.14 billion in 2026 to USD 32.49 billion in 2027 and reach USD 46.54 billion by 2032, growing at a CAGR of 7.45% over 2027-2032.
Indonesia's insurers can broaden protection through digital bank access and supplemental health cover, while climate-related weather exposure can increase the relevance of property risk transfer. Capturing these needs requires insurers to connect a clear benefit proposition with distribution and claims support. Capital and health-line approval obligations make the ability to carry and service new business a condition of expansion. Competition consequently turns on how well customer reach, provider access and funded underwriting capacity work together. Health-line approval makes medical and digital capability part of the threshold for scaling supplemental cover.
Key Report Takeaways
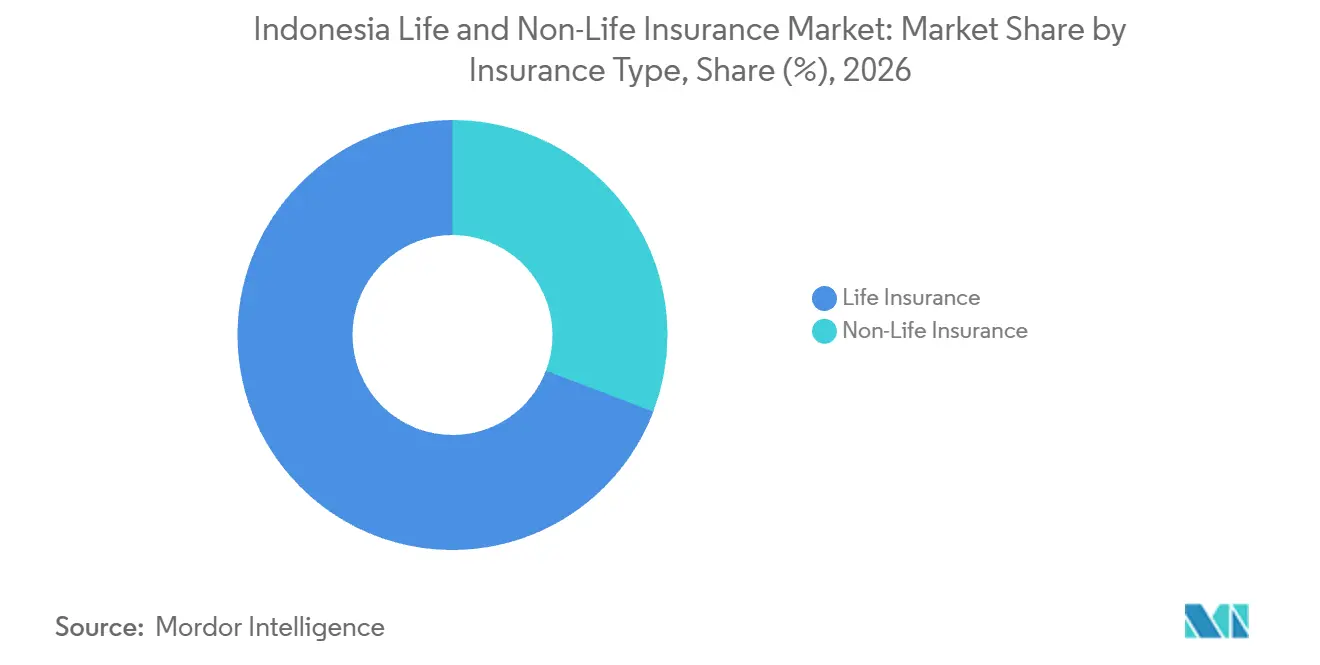
- By insurance type, life insurance held a 69.2% Indonesia life and non-life insurance market share in 2026, while non-life insurance is forecast to grow fastest at a CAGR of 10.4% over 2027-2032.
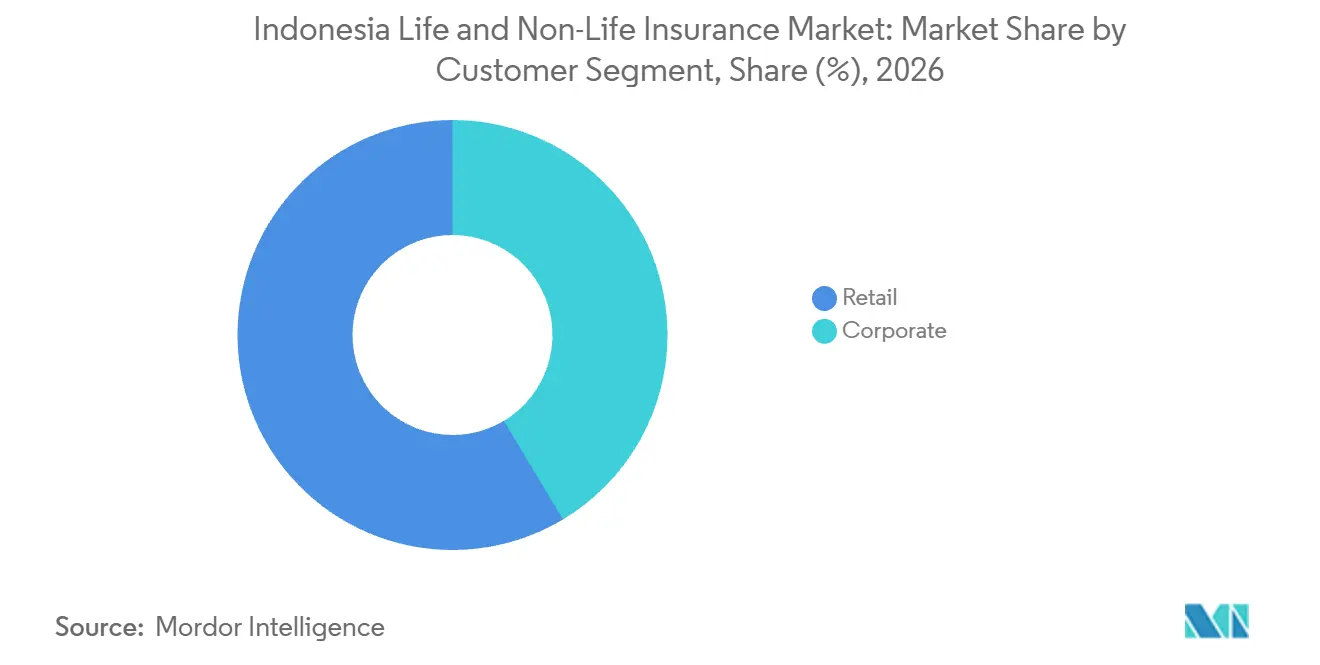
- Among customer segments, retail accounted for a 58.6% share of the Indonesia life and non-life insurance market size in 2026 and is expected to grow fastest at a CAGR of 8.5% over 2027-2032.
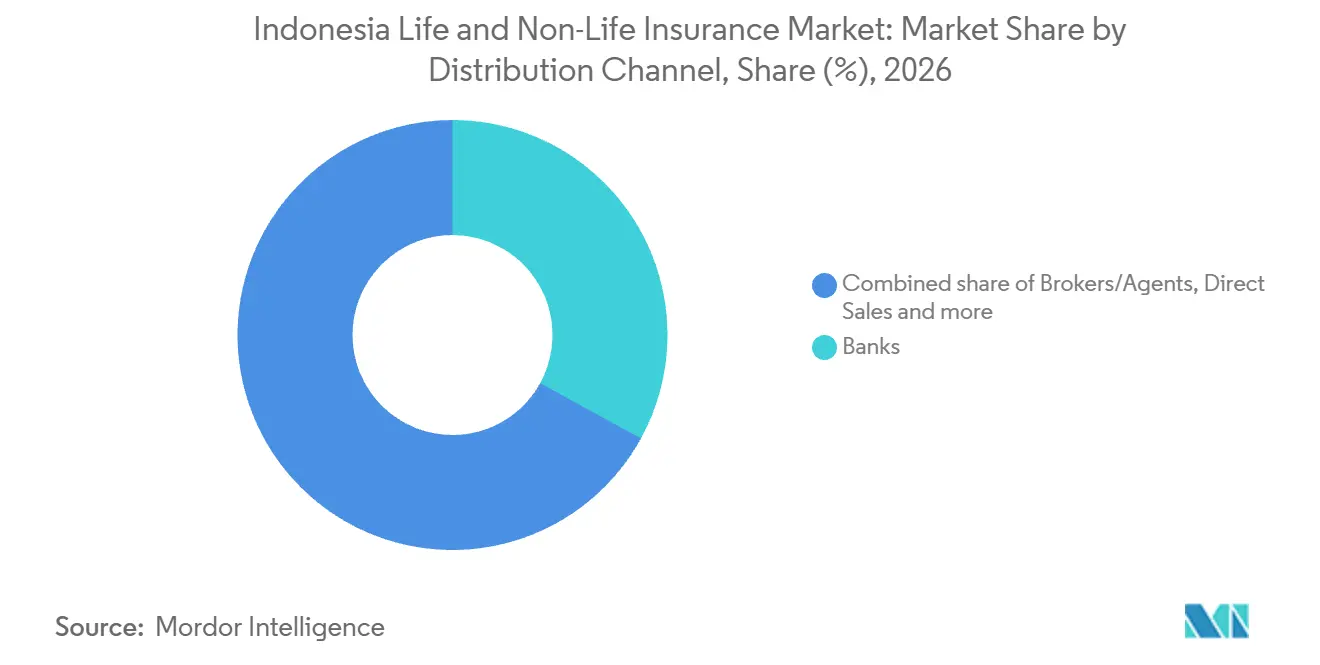
- The distribution channel mix was led by banks with a 33% share in 2026, while other channels are projected to grow fastest at a CAGR of 14.8% over 2027-2032.
- Across geographies, Java held the leading position in 2026, with premium activity concentrated on the island.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Indonesia Life and Non-Life Insurance Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Digital Bancassurance Adoption Supported by POJK 8/2024 | +3.1% | Nationwide | Medium term (2-4 years) |
| Mandatory BPJS Reforms Spurring Supplemental Health Policies | +2.4% | Nationwide | Short term (≤ 2 years) |
| Climate-Induced Catastrophe Risk Elevating Property Cover Demand | +2% | West Sumatra and Aceh | Long term (≥ 4 years) |
| Syariah Finance Boom Catalyzing Takaful Product Uptake Outside Java | +1.5% | Banda Aceh City | Medium term (2-4 years) |
| PAYDI (Investment-Linked) Regulation Unlocking Unit-Linked Growth | +0.9% | Nationwide | Short term (≤ 2 years) |
| E-commerce & Ride-Hailing Micro-insurance Expanding Risk Pools | +0.7% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Digital Bancassurance Adoption Supported by POJK 8/2024
Combining bank-led advice with digital access can create several routes into a life insurance purchase. On February 11, 2025, PT Sun Life Financial Indonesia and Bank Muamalat Indonesia announced a bancassurance extension through 2036. Their agreed distribution model included digital platform-based offerings alongside branch recommendations, telemarketing and insurance bundled with financing solutions. This combination can connect an online offer with an assisted explanation when the customer needs help understanding the cover. Digital offerings are one of several channels in the extended partnership, so the online route complements relationship-managed sales.
Mandatory BPJS Reforms Spurring Supplemental Health Policies
Supplemental health cover offers a route for participants in Indonesia's National Health Insurance (JKN) scheme, run by BPJS Kesehatan, seeking care above their public entitlement. Effective May 8, 2024, Presidential Regulation 59/2024 permits additional insurance to finance higher care, including executive outpatient services.[1] Participants may instead pay the difference between BPJS-covered and upgraded care costs, subject to the regulation's exceptions. For private health insurers, this creates room to design benefits around the upgrade expense rather than duplicate the underlying entitlement. A policy's commercial relevance consequently depends on how clearly its benefits match that additional treatment cost.
Climate-Induced Catastrophe Risk Elevating Property Cover Demand
Property owners can respond to catastrophe exposure through insurance when the assets and funding for protection are identified. Indonesia's meteorological, climatological and geophysical agency (BMKG) linked climate change to increasing extreme-rainfall intensity in Indonesia and reported that Cyclone Senyar brought about 3 times normal November rainfall to Koto Tangah, West Sumatra, and twice normal rainfall to Singkil Utara, Aceh, in late 2025.[2] In 2026, Indonesia's state-asset insurance program used disaster pooling funding to protect 20,838 objects belonging to the Ministry of Religious Affairs, Ministry of Health and State Secretariat. The government program demonstrates how property-cover demand can be organized around an institutional buyer and its identified assets. Because the pooling fund finances the premiums, this demand rests on a funded government buyer rather than on private owners deciding to pay for catastrophe cover.
Syariah Finance Boom Catalyzing Takaful Product Uptake Outside Java
Sharia-based general insurance can reach a broader geographic buyer base when insurers add distribution outside Java. PT Sompo Insurance Indonesia opened a marketing office in Banda Aceh on November 12, 2025, to expand its Sharia-based general insurance services. An insurer-operated marketing office can support discussion of product terms with prospective customers. PT Sompo Insurance Indonesia described the office as strengthening its presence across Sumatra, extending its Sharia-based general insurance services to a province outside Java.
Restraints Impact Analysis of Indonesia Life and Non-Life Insurance Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Low Insurance Literacy in Eastern Provinces | -1.3% | Eastern provinces of Indonesia | Long term (≥ 4 years) |
| POJK 23/2023 Equity Hikes Pressuring Small Domestic Carriers | -1.1% | Nationwide | Medium term (2-4 years) |
| Motor Claims Fraud & Data-Quality Gaps Eroding Margins | -0.4% | Nationwide | Short term (≤ 2 years) |
| IDR Volatility Complicating ALM & Capital Buffers | -0.3% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Low Insurance Literacy in Eastern Provinces
An eastern-province household considering unit-linked life insurance must understand both protection and the investment component before deciding whether the policy meets its needs. If that choice is discussed with an agent or bank representative, limited literacy can lengthen the explanation required before a sale. A health-cover discussion raises a different question, because benefits, exclusions and claim responsibilities determine which treatment expenses a policy can address. The insurer's constraint is the work involved in explaining a specific contract to a prospective policyholder. Clearer explanations can reduce confusion, but a unit-linked sale still requires time to establish that the buyer understands both parts of the product.
POJK 23/2023 Equity Hikes Pressuring Small Domestic Carriers
Equity compliance can constrain product breadth as well as the capital available for an insurer's expansion. As of August 2026, Indonesia's financial services authority (OJK) reported that 117 of 147 insurance and reinsurance companies had met the first-stage minimum-equity requirement due by December 31, 2026, leaving 30 still to comply. OJK Regulation (POJK) 23/2023 sets a second-stage deadline of December 31, 2028, and limits the KPPE 1 equity-tier group to simple insurance business and products. OJK determines the further company-grouping details. For a carrier targeting more complex cover, its financing decision therefore affects the range of business it can pursue alongside its underwriting capacity. The equity needed for the intended product range can consequently delay a carrier's planned expansion.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Indonesia Life and Non-Life Insurance Market Segment Analysis
By Insurance Type:
Coverage Scale Supports Life Insurance LeadershipLife insurance accounted for a 69.2% share of the Indonesia life and non-life insurance market size in 2026. The Indonesian Life Insurance Association (AAJI) reported that the number of people insured under life insurance rose 24.8% year over year to 153.6 million in January-June 2026. At its August 31, 2026 briefing, AAJI explained that partial withdrawals allow access to part of a policy's value while keeping the policy in force, where product terms permit. For insurers, that feature makes contract servicing part of the commercial response to a policyholder seeking liquidity.
Non-life insurance is the fastest-growing segment, with a projected CAGR of 10.4% over 2027-2032. The General Insurance Association of Indonesia (AAUI) recorded motor-vehicle premiums up 4.9% year over year in January-June 2026, in data with 2 companies' submissions outstanding. Total recorded general-insurance premiums in the same dataset declined 0.5% year over year in January-June 2026. Because motor premiums rose while the total fell, the other general-insurance lines declined in aggregate in the dataset. Motor provided a source of premium growth, but non-life's forecast expansion requires growing lines to outweigh the contractions recorded elsewhere in this dataset.

By Customer Segment:
Individual Protection Anchors Retail DemandRetail represented a 58.6% Indonesia life and non-life insurance market share in 2026, making it the largest segment, and is forecast to be the fastest-growing segment at a CAGR of 8.5% over 2027-2032. OJK reported that individual-segment life insurance premiums grew 6.58% year over year through October 2025. This individual protection business gives retail insurers an identifiable premium-generating route within household demand. Wider customer reach must therefore convert into paid protection to extend that premium growth.
Retail's next commercial question is how to develop premium value around an expanding base of insured individuals. AAJI reported 22.38 million people insured in the individual life-insurance segment in January-June 2026, up 6.5% year over year. Additional protection can address a distinct need within an existing coverage relationship as well as reach a first-time insurance buyer. Corporate clients receive a different proposition at AIG Indonesia, which focuses on general insurance, risk-management solutions and local expertise. Individual benefit design and organizational risk management consequently provide separate routes for insurers to develop business with these customer groups.
By Distribution Channel:
Banks Lead as Embedded Distribution ExpandsBanks were the largest segment by distribution channel, with a 33% share in 2026. AAJI identified bancassurance as the largest life-insurance distribution channel on an unweighted premium basis in January-June 2026. On January 15, 2025, PT Sun Life Financial Indonesia and PT Bank CIMB Niaga Tbk extended their bancassurance partnership through 2039. Because the extension runs through 2039, past the end of the forecast period, this bank partnership has an agreed term covering every forecast year.
Other channels are the fastest-growing segment, with a projected CAGR of 14.8% over 2027-2032. On September 23, 2025, Igloo announced a Telkomsel partnership offering cybersecurity, gadget, travel and phone screen protection during MyTelkomsel credit top-ups or data-package purchases.[3] Telkomsel distributes protection through its app and outlets, while Igloo manages distribution and claims as insurance broker and insurance partners provide the products. Outlet staff add protection after the customer confirms the choice. Expansion through this model therefore depends on converting a familiar telecom transaction into an explicit protection decision, with claims service coordinated by the broker.
Geography Analysis
Java Life and Non-Life Insurance Market
Java held the leading position in 2026, with insurance premium activity concentrated on the island. PT Asuransi Bina Dana Arta Tbk reported Jabodetabek, a metropolitan cluster on Java, as its largest geographic gross-premium segment in January-June 2025. This book exceeded each of its Sumatra and Batam, Kalimantan, Sulawesi and Bali segments. Its distinct Jawa segment formed a smaller premium base on the same island. The insurer's Java premiums therefore sat mainly in the Jabodetabek cluster, with the separately listed Jawa segment adding a smaller base.
Sumatra offers a service-led route for developing life insurance relationships around a regional operating point. In 2026, PT Sequis Life inaugurated Sequis Center Medan, whose Regional Service Center provides in-person premium payments, policy updates, claims submission and product consultations. Combining these transactions in one center can make ongoing cover easier to administer for customers who choose to deal with an insurer in person. Kontan reported the center as a step to widen market penetration in North Sumatra, and it combines customer service with sales-agent activity, so servicing and acquisition share one site.
Agency-led expansion provides another commercial route in Sulawesi, where a marketing office can give an insurer a local point for originating life business. PT Sequis Life inaugurated the Legend Fighter Agency marketing office in Makassar on May 8, 2025. The opening extended its agency distribution presence in Sulawesi. For an insurer using this model, a regional office creates a place to organize the sales activity needed to reach prospective policyholders and explain protection choices. Local agency origination gives this Sulawesi expansion a different operating focus from the policy-service model in Medan.
Regulatory Framework and Outlook
These selected jurisdictions compare Indonesia's national insurance obligations with Aceh's additional framework from the perspective of a Sharia-compliant insurer seeking to operate a health-insurance line. POJK 8/2024 requires OJK approval for new insurance products and those meeting specified criteria. POJK 36/2025 requires medical, digital and medical-advisory capabilities and OJK approval before an insurer operates a health-insurance line. Aceh's Qanun Number 11 of 2018 requires financial institutions, including nonbank institutions, to operate under Sharia principles.
Regulatory Table of Indonesia Life and Non-Life Insurance Market
| Decision factor | Indonesia | Aceh |
|---|---|---|
| Primary authority | OJK | OJK for insurance supervision; Government of Aceh for the provincial framework |
| Key instruments or direction | POJK 8/2024; POJK 36/2025 | National OJK rules; Qanun Number 11 of 2018 |
| Commercial effect | Product approval and health-line capability obligations | National approval duties plus Sharia-principle operations |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Hardening |
| Source: Mordor Intelligence | ||
POJK 36/2025 was issued December 17, 2025, and takes effect 3 months after promulgation. Providers already operating a health-insurance line before it took effect must obtain OJK approval within one year of promulgation. For a Sharia-compliant health-line insurer, Indonesia's Medium rating reflects defined approval and capability duties, while Aceh's Medium rating reflects those duties plus its Sharia-principle operating condition. Hardening in both jurisdictions rests on the national approval phase-in, with Aceh's additional condition arising from its established provincial framework.
Value Chain Stages
The comparison traces value capture from bank distribution through insurance underwriting and reinsurance using selected 2025 company examples. SMBC Indonesia reported a consolidated commission-income category combining bancassurance, insurance and investment products under agreements with insurers in 2025. Distribution can therefore generate income through the access relationship, while risk acceptance is a separate commercial activity. Bank distributors therefore depend on connecting each sale to a risk commitment the insurer can support.
Value Chain Analysis Table of Indonesia Life and Non-Life Insurance Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Bank distribution and origination | Bank distributors such as SMBC Indonesia, Bank Tabungan Negara and Bank Syariah Indonesia | Commission income under insurer agreements | Risk of inconsistent product explanations across partner handoffs | Agree product explanations and escalation responsibilities with insurers |
| Insurance underwriting | General insurers such as Tugu Insurance | Insurance revenue in consolidated general-insurance segment reporting | Mismatch between accepted risks and available capacity | Align accepted exposures with available risk capacity |
| Reinsurance risk transfer | Reinsurers such as PT Tugu Reasuransi Indonesia | Gross premium income from indirectly written business | Mismatch between underlying cover and reinsurance terms | Align transferred risks and contract terms with the underlying cover |
| Source: Mordor Intelligence | ||||
PT Tugu Reasuransi Indonesia's unaudited, nonconsolidated 2025 statement recorded gross premium income from indirectly written business. Insurance revenue and reinsurance premiums arise at the risk-carrying stages, giving those participants a different economic exposure from distribution commissions. Resilience depends on keeping product explanations, underwriting limits and transferred risks consistent as the business passes between these roles. Bank-led distribution can thus broaden origination while leaving the funding of insurance and reinsurance risk with the risk-carrying businesses.
Competitive Landscape
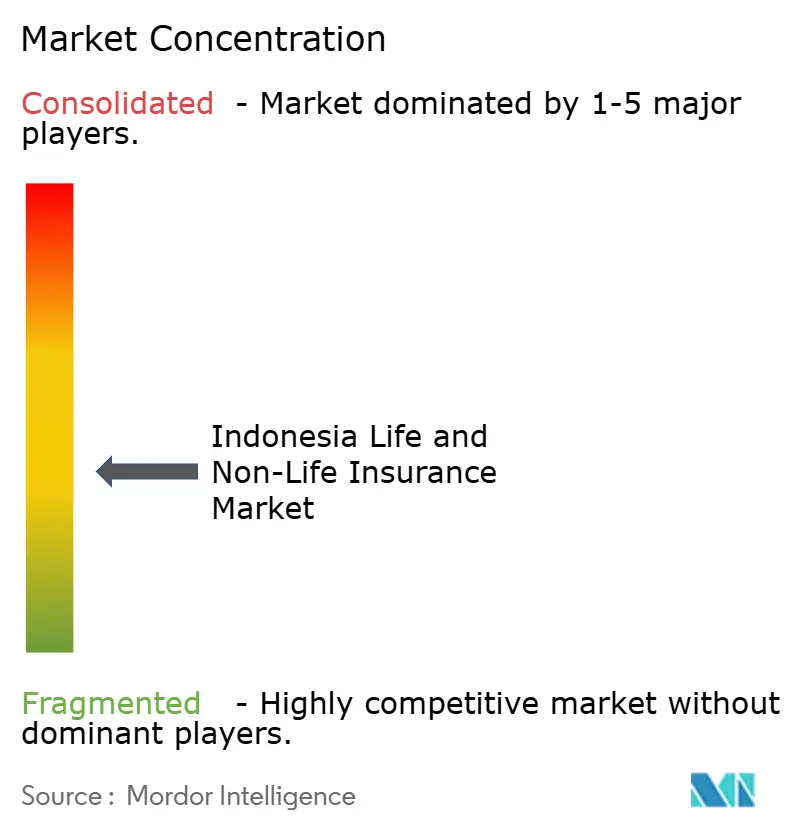
Competition is moderately fragmented, and PT Prudential Life Assurance (Prudential Indonesia) supported more than 62,000 licensed agency business partners and financial service consultants in 2025. PT AIA Financial launched the AIA+ digital platform for policy information and claims in August 2026, while PT Manulife Indonesia issues investment-linked life insurance. PT Allianz Life Indonesia said in August 2026 it was strengthening agency, bancassurance and corporate-solution channels to broaden protection access. PT AXA Financial Indonesia launched AXA Long Term Life Protector, a traditional life product with customer-selectable premium and coverage terms, on January 16, 2025. A challenger therefore competes against established origination capacity, making the resources to build and maintain its own route to customers commercially consequential.
Service capacity gives an insurer a concrete way to differentiate after a policy has been sold, alongside policy terms and distribution access. By 2025, PT Prudential Life Assurance's PRUPriority Hospitals network covered more than 1,700 hospitals across more than 500 Indonesian cities and regencies. A broad provider network can make the health-benefit proposition practical across locations, creating a commercial reason to invest in access as well as product design. Reproducing that health-service proposition across many locations requires challengers to build provider relationships as well as sell policies.
Regulatory positioning adds a financial condition to competition over distribution and service. PT Manulife Indonesia (PT Asuransi Jiwa Manulife Indonesia), the conventional life insurer, reported a 650% risk-based capital ratio at year-end 2025, above the 120% regulatory threshold. This capital headroom can support its ability to carry insured obligations while developing distribution and service capabilities. A challenger seeking customers beyond its established reach must similarly fund both the risks accepted and the capacity to support the resulting policy relationships. A challenger accepting more insured risk must also provide the capital required to meet the 120% threshold, while Manulife reported a substantial cushion at 650%.
Indonesia Life and Non-Life Insurance Industry Leaders
-
PT Prudential Life Assurance
-
PT AIA Financial
-
PT Manulife Indonesia
-
PT Allianz Life Indonesia
-
PT AXA Financial Indonesia
- *Disclaimer: Major Players sorted in no particular order
Indonesia Life and Non-Life Insurance Market Companies Covered in this Report
- PT Prudential Life Assurance
- PT AIA Financial
- PT Manulife Indonesia
- PT Allianz Life Indonesia
- PT AXA Financial Indonesia
- PT Sun Life Financial Indonesia
- PT Great Eastern Life Indonesia
- PT BNI Life Insurance
- PT Sequis Life
- PT Asuransi Jiwasraya (Persero)
- PT Asuransi Astra Buana
- PT Asuransi Sinar Mas
- PT Zurich General Takaful Indonesia
- PT Tokio Marine Indonesia
- PT Zurich Asuransi Indonesia Tbk
- PT Sompo Insurance Indonesia
- PT Chubb General Insurance Indonesia
- Perusahaan Perseroan (Persero) PT Asuransi Jasa Indonesia
- PT KB Insurance Indonesia
- PT AXA Insurance Indonesia
- PT Asuransi Central Asia
- PT Asuransi Tugu Pratama Indonesia Tbk
- Perusahaan Perseroan (Persero) PT Asuransi Kredit Indonesia (Askrindo)
Read Analysis of Indonesia Life and Non-Life Insurance Companies
Key Opportunities for Market Participants
The comparison focuses on health-insurance opportunities created by benefit-coordination rules and planned product revisions. POJK 36/2025 requires insurers to prioritize benefit and claim-payment coordination with BPJS Kesehatan or other guarantors, include enabling product features and apply prudent risk management. Prudential Indonesia plans changes to specified health and supplementary health products effective December 1, 2026. Cash-allowance products outside the regulation's scope are excluded from those adjustments.
Market Opportunities Table of Indonesia Life and Non-Life Insurance Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Coordinated supplemental health cover | Required benefit-coordination features | Buyers also covered by BPJS Kesehatan or another guarantor | Design complementary benefits and coordinated claims under prudent risk controls | Aligning payment responsibilities across guarantors | Health insurers such as Prudential Indonesia |
| Earlier conditional inpatient protection | Planned disease-exclusion revision | Buyers of affected cover for specified diseases | Position earlier eligibility with clear staged-payment terms | Partial claim payment before full benefits apply | Prudential Indonesia |
| Daily cash-benefit positioning | Exception for out-of-scope cash-allowance products | Buyers seeking daily cash benefits | Explain the allowance's distinct benefit purpose and limits | Matching the cash benefit to the intended protection need | Prudential Indonesia |
| Source: Mordor Intelligence | |||||
For affected inpatient or surgical cover from Prudential Indonesia, certain disease exclusion periods are planned to shorten from 12 to 6 months from December 1, 2026, with terms varying by product. Under the planned schedule, eligible claims will receive 25% payment in months 7-11 and 100% in month 12. Applicable waiting periods remain 30 days generally, 90 days for cancer and 12 months for HIV/AIDS cash benefits, if any. Earlier eligibility consequently creates a product opportunity around partial protection, with benefit explanations needing to distinguish that initial coverage from full claim payment.
Recent Industry Developments in Indonesia Life and Non-Life Insurance Market
- Oct 2026: Prudential Indonesia announced adjustments to specified health and supplementary health products, effective December 1, 2026, to comply with POJK 36/2025.
- Aug 2026: PT AIA Financial launched AIA+, a digital platform providing access to policy information, insurance claims and related services in Indonesia.
- May 2026: PT Great Eastern Life Indonesia added an SGD-denominated option to GREAT Investlink Protection, its existing investment-linked insurance product.
Indonesia Life and Non-Life Insurance Market Report Scope and Research Methodology
Market Definition and Coverage
The Indonesia Life and Non-Life Insurance Market measures annual gross written premiums for life and non-life insurance policies issued by licensed insurers in Indonesia, valued in USD using yearly average rupiah exchange rates. It covers premiums written for retail and corporate policyholders through brokers or agents, banks, direct sales, and other channels.
Scope exclusions: Policies written offshore, captive reinsurance, and micro-takaful schemes under IDR 50 million are excluded.
Segments Covered in This Report
- By Insurance Type
- Life Insurance
- Non-Life Insurance
- Motor Insurance
- Health Insurance
- Property Insurance
- Liability Insurance
- Other Insurance
- By Customer Segment
- Retail
- Corporate
- By Distribution Channel
- Brokers/Agents
- Banks
- Direct Sales
- Other Channels
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as OJK's Investor Relations Unit, which publishes insurance-sector premium and capital updates, AAUI, which reports general-insurance line performance, AM Best, whose Asia-Pacific report summarizes Indonesia's life and non-life premium series, and BMKG, which documents Indonesian rainfall and climate patterns, help track market totals, product mix, coverage, and risk conditions. Their published series also help set periods and test whether reported movements align across life and non-life business.
Company annual reports, audited financial statements, investor materials, and reputable business reporting can add carrier-level premium, product, distribution, and capital detail for cross-checking. These sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews and structured surveys with executives and functional specialists at life and general insurers, brokers, bank distributors, and insurance associations in Indonesia can test how published premium, channel, and product indicators reflect market activity. Responses can clarify gaps in secondary series, explain differences in reporting definitions, and cross-check forecast drivers at the variable level before findings are triangulated against regulator, association, and company evidence.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 50% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
The market total is built top down from annual gross written premiums on eligible policies issued by licensed insurers in Indonesia, converted from rupiah at yearly average exchange rates. Life and non-life premiums are estimated separately, then checked against insurer-level premium roll-ups. Retail and corporate demand and broker or agent, bank, direct, and other routes define the customer and channel axes. Segment shares combine regulator and association premium distributions with analyst assessment of each insurance type, customer group, and channel, and are reconciled to the market total. Forecast inputs include recent premiums by insurance type, insured-person and policy growth, claims and premium trends by major non-life lines, household and business activity, distribution access combined with regulatory product changes, and catastrophe exposure. These 6 indicators capture demand, pricing, access, product, and risk conditions. A multivariate regression can relate these series to premium growth, with scenario analysis for material regulatory, claims, or weather changes. Where a series is missing, the analyst checks related OJK and association indicators and carries a documented range into the forecast. Selective bottom-up checks multiply sampled policy or insured counts by representative premium levels and compare the result with the top-down total, while insurer and channel specialists can test whether each forecast driver and its direction fit Indonesia's market. Any gap is traced to differences in period, product definition, insurer coverage, or exchange-rate treatment before the estimate is reconciled.
Data Validation & Update Cycle
Analysts triangulate OJK totals with AAJI and AAUI series, insurer filings, and independent activity signals such as insured-person trends and reported claims. They reconcile reporting periods, premium definitions, exchange rates, and possible double counting, then investigate anomalous movements or material variance against the prior estimate before sign-off through analyst review and a separate editorial review. A targeted source or respondent is re-contacted when a definition, series break, or unusual movement remains unexplained. The dataset is refreshed annually, updated between cycles when a material regulatory or market event changes an input, and reviewed again against current source releases immediately before delivery.
Mordor Intelligence's Indonesia Life Non Life Insurance Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Indonesia Life and Non-Life Insurance Market measures annual gross written premiums for life and non-life insurance policies issued by licensed insurers in Indonesia, valued in USD using yearly average rupiah exchange rates.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Forecast inputs include recent premiums by insurance type, insured-person and policy growth, claims and premium trends by major non-life lines, household and business activity, distribution access combined with regulatory product changes, and catastrophe exposure.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 32.49 B (2027) | |
| Global Research Institute A | USD 18.7 B (2024) | At its 2024 base, this estimate is 42.4% below this report's 2027 value of USD 32.49 B, 3 years later. Its 2024 direct-premium base predates the report's 2027 measurement by three years. |
| Regional Consultancy B | USD 29.53 B (2025) | At its 2025 base, this estimate is 9.1% below this report's 2027 value of USD 32.49 B, 2 years later. Its premium-value base is for 2025, two years before the report's 2027 measurement. |
Mordor Intelligence's analysts triangulate OJK totals with AAJI and AAUI series, insurer filings, and independent activity signals such as insured-person trends and reported claims.
Key Questions Answered in the Report
What is the Indonesia life and non-life insurance market size and growth outlook?
The size is expected to reach USD 32.49 billion in 2027 and USD 46.54 billion in 2032, with a CAGR of 7.45% over 2027-2032.
What is supporting demand for insurance in Indonesia?
Digital bancassurance and supplemental health cover can broaden access. PT Sun Life Financial Indonesia and Bank Muamalat Indonesia announced an extension through 2036 in 2025, including digital offerings among several channels.
Which insurance type leads by value in Indonesia?
Life insurance held a 69.2% share in 2026, while non-life insurance is expected to grow fastest at a CAGR of 10.4% over 2027-2032.
Which companies are major life insurers in Indonesia?
Major players include PT Prudential Life Assurance, PT AIA Financial, PT Manulife Indonesia, PT Allianz Life Indonesia and PT AXA Financial Indonesia.
What could constrain insurance-sector expansion in Indonesia?
POJK 23/2023 sets a second-stage equity deadline of December 31, 2028, and restricts the KPPE 1 equity-tier group to simple insurance business and products, making capital availability relevant to business scope.
Where is Indonesia's insurance activity concentrated?
Java held the leading geographic position in 2026, while PT Sequis Life's 2026 service center in Medan and 2025 agency marketing office in Makassar extended insurer presence outside Java.