
Land-based Military Electro-Optical and Infrared Systems Market Size and Share
Market Overview
| Study Period | 2020 - 2032 |
|---|---|
| Market Size (2027) | USD 1.81 Billion |
| Market Size (2032) | USD 2.21 Billion |
| Growth Rate (2027 - 2032) | 4.07 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Land-based Military Electro-Optical and Infrared Systems Market Analysis by Mordor Intelligence
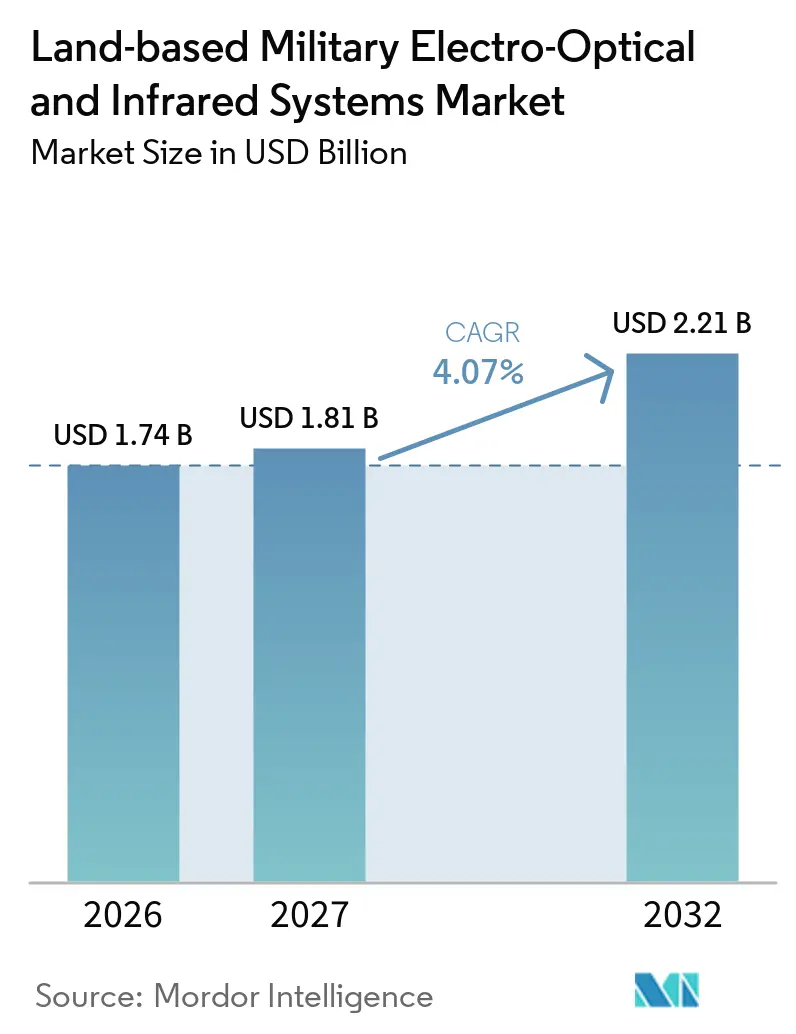
The land-based military electro-optical and infrared systems market size was valued at USD 1.74 billion in 2026 and is forecast to grow from USD 1.81 billion in 2027 to USD 2.21 billion by 2032, at a CAGR of 4.07% during 2027-2032. Security pressures are extending the service lives of armored vehicles and supporting upgrades to observation, targeting, and surveillance equipment. Defense forces are favoring modular designs that can be installed on fielded platforms without a full vehicle redesign. This approach creates an opportunity for retrofit suppliers while raising the value of systems that combine sensors, processing, and network interfaces. The market is shaped by the move toward multispectral payloads, automated target functions, and vehicle coverage. Supply constraints for advanced detectors and restrictions on transfers of sensitive equipment remain limits on procurement outside established allied supply chains.
Key Report Takeaways
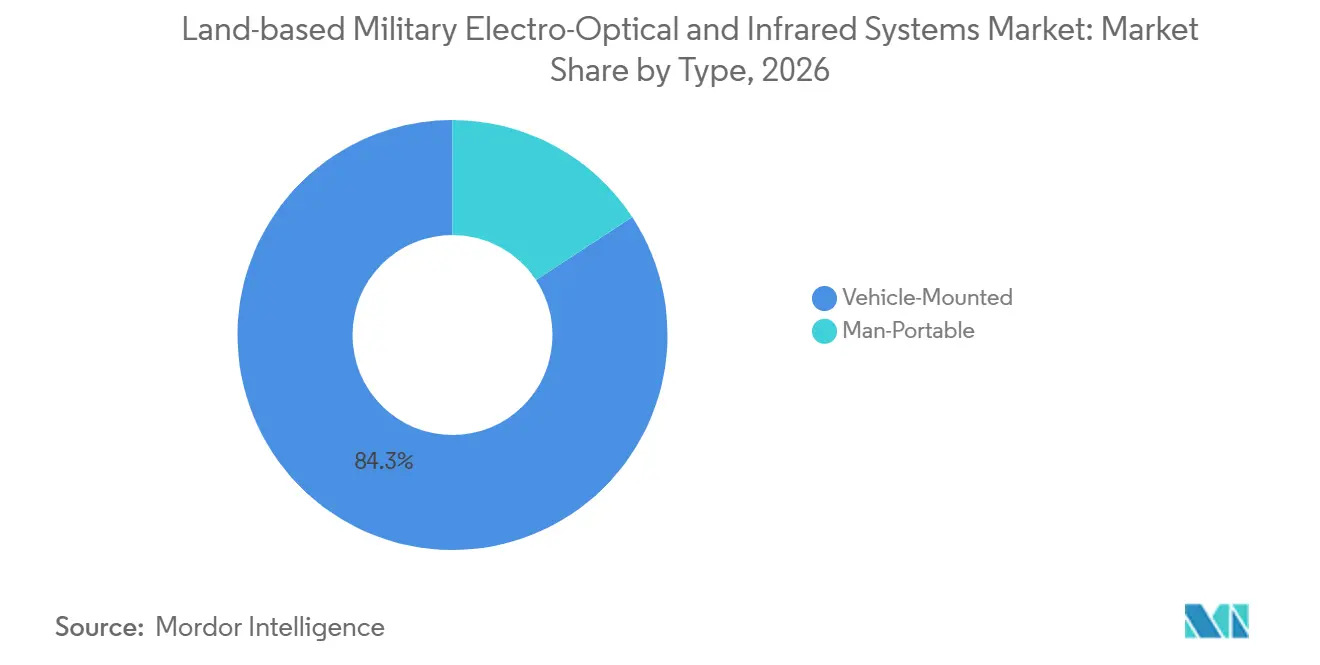
- By type, vehicle-mounted platforms held 84.25% of the land-based military electro-optical and infrared systems market share in 2026, while man-portable systems are forecast to grow at a 5.35% CAGR through 2032.
- By system, imaging systems held 48.21% share in 2026, while electronic support measure systems are forecast to grow at a 5.80% CAGR through 2032.
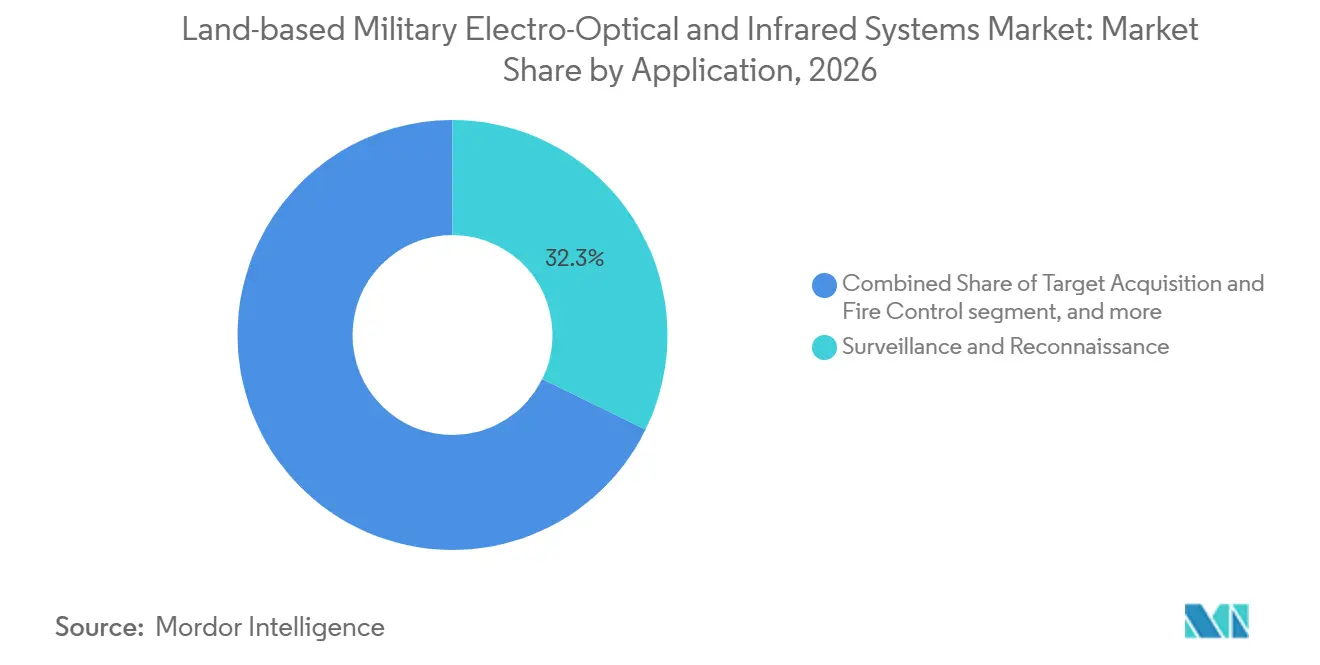
- By application, surveillance and reconnaissance held 32.25% share in 2026, while target acquisition and fire control are forecast to grow at a 5.55% CAGR through 2032.
- By cooling technology, cooled systems held 56.50% share in 2026, while uncooled systems are forecast to grow at a 5.41% CAGR through 2032.
- By fit, retrofit held 57.75% share in 2026, while linefit is forecast to grow at a 5.91% CAGR through 2032.
- By geography, North America held 39.90% share in 2026, while the Asia-Pacific is forecast to grow at a 5.52% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Land-based Military Electro-Optical and Infrared Systems Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Armored fleet modernization accelerating optronics demand | +1.00% | Global, concentrated near-term in North America and Europe | Short term (≤ 2 years) |
| Border surveillance and persistent reconnaissance demand | +0.80% | Asia-Pacific, Middle East and Africa, and Eastern Europe | Medium term (2-4 years) |
| Vehicle protection and 360-degree situational awareness integration | +0.60% | North America, Europe, and Israel | Short term (≤ 2 years) |
| Multispectral sensing and AI-assisted target recognition | +0.50% | Global, with early deployment in North America and Europe | Medium term (2-4 years) |
| Asia-Pacific indigenous defense procurement | +0.40% | India, South Korea, Japan, and Australia | Medium term (2-4 years) |
| Open-architecture upgrades for legacy combat fleets | +0.30% | North America and Europe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Armored Fleet Modernization and Open-Architecture Upgrades
Modernization of armored combat vehicles is supporting demand for advanced EO/IR systems, particularly thermal sights, stabilized observation equipment, and digital sensor integration. In H1 2026, HENSOLDT reported EUR 971 million (USD 1.08 billion) in order intake for its Optronics segment, compared with EUR 164 million (USD 186.86 million) in H1 2025. The company attributed much of this growth to contracts supplying digital optronics for Germany's Puma IFVs and Schakal wheeled IFVs. Its Ground-Based Systems product line also contributed to strong segment revenue growth. These developments highlight the importance of advanced observation and targeting technologies in military vehicle modernization. A Modular Open Systems Approach (MOSA) can facilitate future sensor replacement and subsystem upgrades, although platform-specific integration remains necessary. Continued vehicle procurement and modernization programs are therefore supporting opportunities across linefit and retrofit EO/IR applications.
Border Surveillance and Persistent Reconnaissance Demand
Military requirements for continuous battlefield surveillance, border monitoring, and force protection are supporting demand for multisensor EO/IR systems capable of operating in low-light and nighttime conditions. In February 2026, the US Army issued a sources-sought notice for gimballed high-definition EO/IR sensor replacements for its Base Expeditionary Targeting Surveillance Systems–Combined (BETSS-C) and Ground-Based Operational Surveillance System. The requirements included thermal imaging, color and low-light cameras, short-wave infrared (SWIR) capabilities, and 360-degree observation. These specifications reflect continuing interest in integrated sensor architectures that combine multiple imaging technologies for target detection and surveillance. Requirements for extended observation ranges and improved image processing create opportunities for advanced EO/IR equipment.
Vehicle Protection and 360-Degree Situational Awareness
Modern battlefield threats are increasing the need for integrated observation, threat detection, and situational awareness capabilities in armored vehicles. In November 2025, HENSOLDT secured a contract valued at under EUR 1 billion (USD 1.16 billion) from General Dynamics European Land Systems (GDELS) to supply advanced sensors and its CERETRON mission system for Germany's LUCHS 2 reconnaissance vehicles. The initial production batch covers equipment for 274 vehicles.[1] The system integrates daylight and thermal imaging, 360-degree observation through SETAS, laser warning, and acoustic sensors to improve threat detection and crew awareness. CERETRON also processes multisensor information to support target recognition, tracking, and tactical decision-making. This development highlights growing opportunities for integrated EO/IR technologies as military forces prioritize comprehensive vehicle surveillance and protection capabilities.
Multispectral Sensing, Automated Recognition, and Indigenous Procurement
Advances in multispectral imaging and digital sensor processing are supporting demand for military EO/IR systems capable of combining information from different spectral bands. ASELSAN's 2025 annual report, published in 2026, disclosed that its upgraded DRAGONEYE 2 system incorporates a SWIR sensor and that approximately 300 DRAGONEYE-family systems were delivered in 2025. The company also reported deliveries of more than 500 ATS thermal cameras during 2025, with additional deliveries planned for 2026. These developments illustrate continued investment in imaging capabilities for ground-based military applications. Indigenous development and manufacturing initiatives further support domestic supply chains and the availability of technology. In October 2026, ASELSAN announced USD 157.90 million in export contracts spanning EO equipment and other defense technologies. These activities support opportunities for manufacturers supplying advanced sensor systems, image-processing technologies, and military observation equipment.
Restraints Impact Analysis of Land-based Military Electro-Optical and Infrared Systems Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Advanced IR detector supply remains a critical bottleneck | -0.60% | Global, most acute in Asia-Pacific and Middle East and Africa outside established supply chains | Medium term (2-4 years) |
| Export controls and sovereign sourcing limiting global scalability | -0.50% | Asia-Pacific, Middle East and Africa, and Eastern Europe | Medium term (2-4 years) |
| Vehicle SWaP-C constraints challenging sensor integration | -0.30% | Global | Medium term (2-4 years) |
| High cost and qualification complexity constraining advanced EO/IR adoption | -0.20% | Middle East and Africa, South America, and smaller NATO allies | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Detector Supply and Export-Control Constraints
Manufacturing advanced military EO/IR equipment requires specialized IR detectors, optical components, readout electronics, and qualified production capabilities. Supply-chain dependence on technically capable manufacturers can affect procurement flexibility and increase sourcing complexity. In May 2026, RRP Defence reportedly secured an order worth approximately INR 29.8 crore (USD 3.11 million) from Bharat Electronics Limited to supply high-precision germanium lenses for IR and thermal imaging applications, illustrating the importance of specialized optical components in defense equipment supply chains. Export regulations create additional barriers for international suppliers. The US Export Administration Regulations, including provisions updated in July 2026, impose licensing requirements on specified thermal imaging cameras and other controlled technologies based on classification and destination. These restrictions can complicate technology transfers, component sourcing, and international equipment sales. However, the available evidence does not establish a universal shortage of military IR detectors during 2026.
Platform Integration, Cost, and Qualification Complexity
Integrating advanced EO/IR equipment into military vehicles requires consideration of size, weight, power, and cost (SWaP-C), particularly where existing platforms have limited electrical capacity or installation space. Thermal imaging systems, stabilized observation assemblies, and image-processing components may require additional power distribution, mechanical interfaces, and cooling arrangements. HENSOLDT's NDP30 night-driver periscope illustrates efforts to address integration requirements by providing compact, modular imaging equipment that incorporates uncooled thermal and low-light cameras. Its compatibility with common vehicle periscope arrangements highlights the importance of retrofit-oriented designs. Nevertheless, replacing legacy equipment can require platform-specific testing, electromagnetic compatibility assessments, and operational qualification. These requirements increase integration expenditure and can extend deployment schedules. Higher acquisition and lifecycle costs may also influence procurement decisions, particularly where operators must modernize large vehicle fleets within constrained budgets.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Land-based Military Electro-Optical and Infrared Systems Market Segment Analysis
By Type:
Vehicle-Mounted Platforms Lead While Man-Portable Systems ExpandVehicle-mounted platforms accounted for 84.25% of the land-based military electro-optical and infrared systems market share in 2026, reflecting their widespread use on tanks, IFVs, UGVs, and mobile air defense platforms. Combat vehicles form the largest demand base, as they require sights, targeting equipment, driver vision systems, and broader surveillance coverage. Recovery and support vehicles also require observation equipment when operating near the front line. Counter-unmanned aircraft roles are increasing demand for sensors capable of detecting and tracking low, slow threats around mobile formations. In September 2025, Rheinmetall introduced its SEOSS 400 stabilized fire-control sensor at DSEI, featuring three-axis stabilization, AI-supported target identification, and an identification range of up to 6 km under specified conditions. The system was developed for next-generation combat vehicles and designed for integration into manned and unmanned platforms. Such developments reflect continued investment in vehicle-mounted sensing technologies as militaries modernize ground combat platforms.[2]
Man-portable systems are forecast to grow at a 5.35% CAGR through 2032, faster than other types of subsegments. Infantry modernization creates demand for weapon sights, handheld thermal imagers, and dismounted soldier vision systems. Man-portable EO/IR equipment supports infantry surveillance, nighttime observation, target detection, and weapon aiming. Demand is driven by the need to enhance individual soldiers' capabilities without relying on vehicle-mounted observation systems. In October 2025, MKU Limited announced a contract worth approximately INR 660 crore (USD 74.69 million) to supply 29,762 Netro NW 3000 night-vision weapon sights to the Indian Army.[3] The procurement involves image-intensifier-based equipment for infantry weapons, illustrating the scale of investment in soldier-carried EO technologies. Man-portable thermal imagers, weapon sights, and portable laser-ranging equipment address different operational requirements. Infantry modernization programs and vehicle-based sensing initiatives together support opportunities across both deployment categories.


By System:
Imaging Systems Maintain Scale as Electronic Support Measure Functions GrowImaging systems accounted for 48.21% of the land-based military electro-optical and infrared systems market size in 2026. Imaging systems support fundamental observation and situational awareness requirements across military ground operations. These systems include visible-spectrum cameras, thermal imagers, night-vision devices, and integrated imaging assemblies used in combat vehicles and portable equipment. Their operational applications span driver vision, reconnaissance, battlefield observation, and surveillance. Advances in detector technology, image processing, and sensor integration have supported the development of increasingly capable imaging solutions. Targeting systems incorporate imaging equipment alongside functions such as laser ranging, stabilization, target tracking, and fire-control interfaces. Rheinmetall's SEOSS 400, introduced in September 2025, illustrates this integration through its stabilized sensor architecture, AI-supported target identification, and automated fire-control capabilities. These developments support demand for imaging and targeting equipment designed to meet increasingly complex military operational requirements.
Electronic support measure systems are forecast to grow at a 5.80% CAGR through 2032. EO warning and detection systems represent an adjacent opportunity within integrated land-platform sensing architectures. Such equipment can include laser warning receivers and EO/IR threat-detection sensors, depending on the system configuration. These technologies provide complementary information to vehicle crews and can be integrated with observation, targeting, and protection systems. However, conventional electronic support measures primarily detect and analyze radio-frequency emissions and should not be included in EO/IR equipment revenue without a clearly defined allocation methodology. This distinction is important when assessing market demand, as broader vehicle mission-system contracts can contain imaging, EW, and other sensor technologies.
By Application:
Surveillance and Reconnaissance Lead While Fire Control Gains PaceSurveillance and reconnaissance held 32.25% share in 2026, making it the largest application in the land-based military electro-optical and infrared systems market. Surveillance and reconnaissance applications generate demand for EO/IR equipment across military observation, reconnaissance, border monitoring, and force protection missions. Vehicle-mounted and man-portable systems enable military personnel to observe terrain, detect potential threats, and collect visual information under varying lighting conditions. Thermal imaging provides nighttime observation capabilities, while visible-spectrum and low-light sensors offer complementary imaging functions. These technologies support reconnaissance vehicles, dismounted soldiers, and mobile observation platforms. Continuous battlefield monitoring requires stabilized imaging, appropriate detection ranges, and integration with tactical communications systems. The operational importance of detecting and identifying potential threats before engagement supports sustained demand for surveillance and reconnaissance equipment within land-based military EO/IR applications.
Target acquisition and fire control are forecast to expand at a 5.55% CAGR through 2032. These missions require higher image quality, rapid processing, and stable sensor mounts that can support precise handoff to weapons. Target acquisition and fire control applications require precise sensor stabilization, target identification, range measurement, and integration with weapon control systems. Rheinmetall's SEOSS 400 illustrates developments in this category, incorporating three-axis stabilization, multimodal tracking, and AI-supported identification capabilities. The company stated that the sensor was developed for next-generation combat vehicles and advanced air defense applications. Its architecture also supports modular sensor expansion and digital connectivity. These capabilities reflect efforts to improve the integration of observation and targeting functions within ground combat platforms. Driver vision, navigation, and battlefield situational awareness represent additional application areas for EO/IR technologies as military forces expand the use of sensor-based observation and decision-support systems.


By Cooling Technology:
Cooled Systems Retain Performance Leadership as Uncooled Systems ImproveCooled systems held 56.50% share in 2026, giving them the leading position in the land-based military electro-optical and infrared systems market. Cooled IR systems are used in demanding military applications that require high thermal sensitivity, extended detection ranges, and detailed target observation. Their detector assemblies operate at controlled low temperatures to reduce thermal noise and support imaging performance. These characteristics make cooled technologies relevant to long-range surveillance, advanced targeting, and reconnaissance systems where performance requirements justify additional power consumption, mechanical complexity, and acquisition costs. However, performance in the presence of smoke, dust, humidity, or other obscurants depends on wavelength, atmospheric conditions, target characteristics, and sensor design. Cooled systems should therefore not be described as universally superior in degraded visibility conditions. Their continued relevance reflects the operational importance of high-performance thermal imaging in selected military applications.
Uncooled systems are forecast to grow at a 5.41% CAGR through 2032 as resolution improves and unit costs decline. Uncooled IR systems offer advantages in size, power consumption, and integration complexity because they do not require cryogenic cooling of detectors. These characteristics support applications including driver vision, portable thermal imaging, short- and medium-range surveillance, and vehicle observation systems. Advances in detector resolution, image processing, and compact optical assemblies are expanding the capabilities available to military equipment manufacturers. Uncooled systems can also simplify maintenance requirements relative to comparable cryogenically cooled configurations. Nevertheless, their suitability depends on the imaging performance required for a particular mission. Cooled and uncooled technologies, therefore, address overlapping but distinct operational requirements, supporting continued procurement across different military platforms and applications.
By Fit:
Retrofit Leads Existing Fleets While Line Fit Gains in New ProgramsRetrofit accounted for 57.75% share in 2026, making it the leading fit category in the land-based military electro-optical and infrared systems market. Retrofit installations enable military forces to improve observation, targeting, and nighttime operating capabilities across existing ground combat vehicles. Upgrading thermal sights, driver vision equipment, and electronic interfaces can extend the operational relevance of legacy platforms without requiring complete vehicle replacement. Retrofit programs may also allow defense organizations to introduce new sensing capabilities through phased modernization schedules. However, existing vehicle configurations can impose limitations related to installation space, electrical power, cooling, and system compatibility. Integration and qualification requirements can therefore influence retrofit costs and implementation timelines. These considerations create opportunities for EO/IR suppliers offering modular imaging equipment and platform-compatible upgrade solutions that support military fleet modernization.
Linefit is forecast to grow at a 5.91% CAGR through 2032 as newer platforms integrate sensor architecture from the start. Linefit integration enables EO/IR equipment to be incorporated into ground vehicle designs during initial development and production. This approach allows manufacturers to account for sensor placement, electrical interfaces, processing requirements, and maintenance accessibility at the design stage. In October 2025, L3Harris described its collaboration with American Rheinmetall on a next-generation combat vehicle concept incorporating the WESCAM MX-GCS B multispectral sighting system. The company highlighted its MOSA and consideration of SWaP-C during vehicle development. This collaboration illustrates how EO/IR technologies can be incorporated into platform architectures from an early stage. Linefit programs consequently provide opportunities for integrated sensing solutions, although concept-stage partnerships do not necessarily represent confirmed production orders.
Geography Analysis
North America Land-based Military Electro-Optical and Infrared Systems Market
North America held 39.90% of the land-based military electro-optical and infrared systems market share in 2026. The region is supported by US Army modernization programs that cover main battle tanks, infantry vehicles, Stryker variants, and specialized reconnaissance vehicles. In April 2025, Teledyne FLIR Defense received a USD 74.20 million, four-year US Army contract for the M1135 Stryker NBCRV Sensor Suite Upgrade Program. Open-architecture requirements encourage modular equipment that can be upgraded over time. Canada adds allied procurement demand, while Mexico has more limited defense-spending capacity. The regional opportunity remains broad because vehicles across many mission types require sensing and decision-support equipment.
Europe Land-based Military Electro-Optical and Infrared Systems Market
Europe is expanding as NATO members reinforce land-force capability and update equipment in response to the war in Ukraine. Germany is a significant procurement center for weapon sights, night-vision devices, fire-control sensors, and vehicle surveillance systems. Rheinmetall signed a framework contract with BAAINBw in February 2025 for the IdZ-ES soldier system, with a maximum volume of EUR 3.10 billion (USD 3.23 billion) through 2030. The market also gains from this larger regional push toward capable, networked land forces. The UK, France, Italy, Poland, the Scandinavian countries, and Eastern European allies provide additional depth to the program. Russian export capacity remains limited by component-supply disruption linked to sanctions and constrained access to key components.
APAC, South America and MEA Land-based Military Electro-Optical and Infrared Systems Market
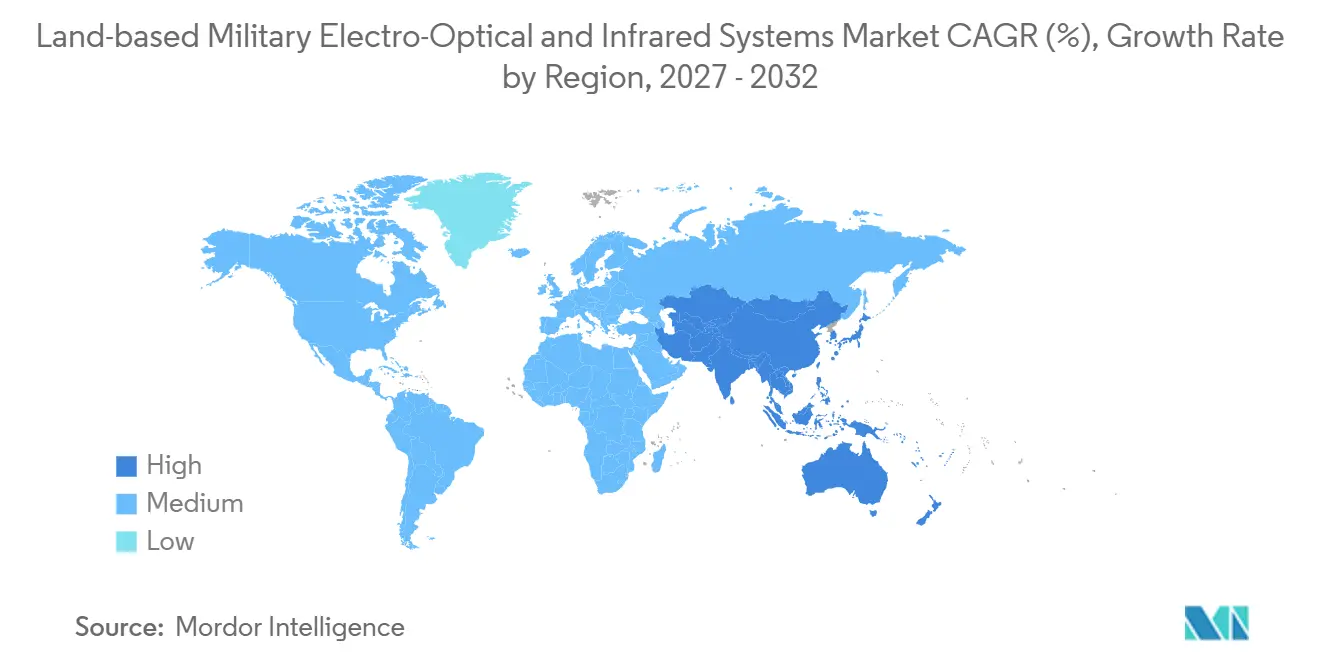
Asia-Pacific is forecast to grow at a 5.52% CAGR through 2032, the fastest regional pace in the land-based military electro-optical and infrared systems market. Defense budget growth, territorial disputes, and national manufacturing goals are supporting modernization across the region. India, South Korea, Japan, and Australia are important procurement markets, with China also advancing armored modernization. Regional customers are seeking sensors for vehicles, border missions, and dismounted soldiers. The market is also supported by local supplier development as governments look to strengthen national control over sensitive technology. South America contributes selectively through upgrades in Brazil and Chile, while Gulf states and Israel continue to integrate advanced equipment on land platforms. Demand in the Middle East and Africa is driven by both platform modernization and border security requirements.
Competitive Landscape
Market Concentration
Top Companies in Land-based Military Electro-optical and Infrared Systems Market
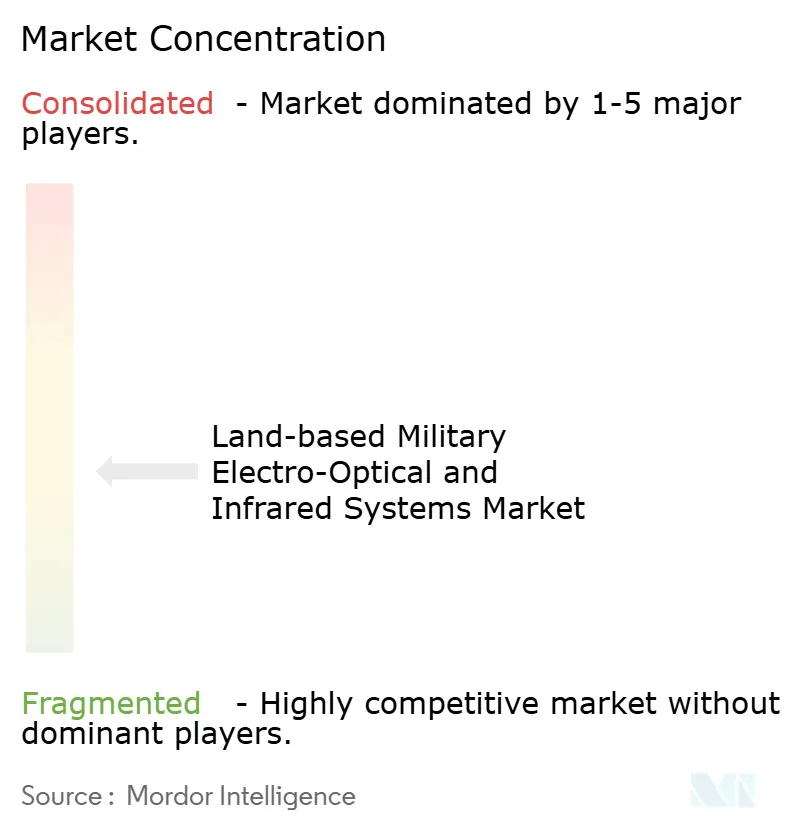
The land-based military electro-optical and infrared systems market is moderately concentrated, with major Western suppliers holding established platform qualifications and long-running support relationships. BAE Systems, Elbit Systems, Teledyne Technologies Incorporated, Thales, HENSOLDT, L3Harris Technologies, Inc., RTX Corporation, Leonardo, Safran, and Rheinmetall are prominent participants in vehicle and soldier-system programs. Their positions are supported by integrated capabilities across optics, sensors, processing, platform interfaces, and logistics. Competition increasingly depends on modularity, software capability, supply security, and the ability to support vehicles over long service periods. HENSOLDT’s LUCHS 2 package illustrates a strategy of providing sensors, mission systems, and associated support within a single vehicle program. This structure can make it difficult for smaller suppliers to compete for roles in complete systems within major programs.
Rheinmetall’s 2025 launch of the SEOSS 400 for MGCS and MARTE-compatible architectures shows how suppliers position equipment early for future multinational vehicle programs. L3Harris is also pursuing this approach through its open-architecture WESCAM MX-GCS B system for American Rheinmetall’s vehicle concept. These moves show the strategic importance of designing systems that can work across multiple stations and future upgrades. Firms that control key detectors, optical components, and software elements can reduce supply risk and protect their technical differentiation. The market also creates room for specialists who provide lower-cost thermal systems or software layers for automated recognition. However, access to regulated detector technology remains an important barrier for many new entrants.
ASELSAN, Bharat Electronics, and Hanwha Systems are building stronger positions through national procurement programs and regional export activity. Their progress may broaden the supplier base as countries seek to reduce dependence on established Western sources. The land-based military electro-optical and infrared systems market remains favorable to incumbents in the near term because military qualification cycles are long and platform integration is complex. Yet domestic sourcing policies in India, South Korea, and Turkey can improve the scale and credentials of local firms over time. The competitive environment is not dominated by a single supplier, but large integrated contractors retain advantages in major programs. National suppliers and specialized firms nevertheless preserve meaningful competition across distinct product niches and regional procurement channels worldwide today.
Land-based Military Electro-Optical and Infrared Systems Industry Leaders
-
BAE Systems plc
-
Elbit Systems Ltd.
-
Teledyne Technologies Incorporated
-
L3Harris Technologies, Inc.
-
RTX Corporation
- *Disclaimer: Major Players sorted in no particular order
Land-based Military Electro-Optical and Infrared Systems Market Companies Covered in this Report
- BAE Systems plc
- Elbit Systems Ltd.
- Teledyne Technologies Incorporated
- L3Harris Technologies, Inc.
- RTX Corporation
- Leonardo S.p.A.
- Rheinmetall AG
- Thales Group
- HENSOLDT AG
- Israel Aerospace Industries Ltd.
- Saab AB
- Northrop Grumman Corporation
- Lockheed Martin Corporation
- Safran SA
- Rafael Advanced Defense Systems Ltd.
- ASELSAN A.Ş.
- Kongsberg Gruppen ASA
- Bharat Electronics Limited
- Hanwha Systems Co., Ltd.
- CONTROP Precision Technologies Ltd.
Recent Industry Developments in Land-based Military Electro-Optical and Infrared Systems Market
- June 2026: Teledyne FLIR Defense launched three upgraded EO/IR vision systems for military vehicles: ThermoVision® Situational Awareness HD (SA90-HD), ThermoVision® Driver Vision HD (DV55-HD), and MilSight® LIRC III. These systems combine thermal and EO imaging to support target acquisition, driver vision, threat detection, obstacle avoidance, and up to 360-degree situational awareness on armored and tactical vehicles. Teledyne reported that more than 3,500 of its vehicle vision systems have been deployed across nearly 20 countries.
- April 2026: Teledyne FLIR Defense received a contract valued at more than USD 35 million from WB Electronics S.A., part of Poland's WB Group, to equip reconnaissance vehicles with TacFLIR® 280-HDEP multispectral surveillance systems. The systems provide daylight and thermal imagery, video processing, Aided Target Recognition, situational awareness, target identification, and tracking capabilities for ground reconnaissance missions.
- January 2026: Teledyne FLIR Defense received a US Army contract worth up to USD 32 million to deliver and integrate EO/IR systems for Stryker Infantry Carrier Vehicle Recon Kits under a Foreign Military Sales (FMS) program supporting Bulgaria. The package includes TacFLIR® 280-HDEP EO/IR systems, providing long-range thermal imaging and ISR-T capabilities for Bulgaria's Stryker armored vehicles. The contract has a three-year performance period.
Global Land-based Military Electro-Optical and Infrared Systems Market Report Scope
Electro-optical and infrared (EO/IR) systems comprise visible-spectrum and infrared sensing technologies designed to support military surveillance, reconnaissance, target detection, identification, and situational awareness during day and night operations. Land-based military EO/IR systems are integrated into combat vehicles, UGVs, mobile air-defense platforms, support vehicles, and man-portable equipment used by dismounted military personnel.
The land-based military electro-optical and infrared systems market is segmented by type, system, application, cooling technology, fit, and geography. By type, the market is segmented into vehicle-mounted and man-portable systems. By system, the market is segmented into imaging systems, targeting systems, and electronic support measure systems. By application, the market is segmented into surveillance and reconnaissance, Identify Friend or Foe (IFF), target acquisition and fire control, driver vision and navigation, battlefield situational awareness, and border, base, and perimeter surveillance. By cooling technology, the market is segmented into cooled and uncooled systems. By fit, the market is segmented into linefit and retrofit systems. The report also covers the market sizes and forecasts for the land-based military electro-optical and infrared systems market in major countries across different regions. For each segment, the market size is provided in terms of value (USD).
Segmentation Overview
| Vehicle-Mounted | Combat Vehicles |
| Unmanned Ground Vehicles (UGVs) | |
| Mobile Air-Defense and Counter-UAS Platforms | |
| Armored Recovery and Support Vehicles | |
| Man-Portable | Weapon Sights and Thermal Weapon Sights |
| Handheld Thermal Imagers | |
| Laser Rangefinders and Designators | |
| Dismounted Soldier Vision Systems |
| Imaging Systems |
| Targeting Systems |
| Electronic Support Measure Systems |
| Surveillance and Reconnaissance |
| Identify Friend or Foe (IFF) |
| Target Acquisition and Fire Control |
| Driver Vision and Navigation |
| Battlefield Situational Awareness |
| Border, Base, and Perimeter Surveillance |
| Cooled Systems |
| Uncooled Systems |
| Linefit |
| Retrofit |
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | United Kingdom | |
| France | ||
| Germany | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Rest of South America | ||
| Middle East and Africa | Middle East | United Arab Emirates |
| Saudi Arabia | ||
| Israel | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Rest of Africa | ||
| By Type | Vehicle-Mounted | Combat Vehicles | |
| Unmanned Ground Vehicles (UGVs) | |||
| Mobile Air-Defense and Counter-UAS Platforms | |||
| Armored Recovery and Support Vehicles | |||
| Man-Portable | Weapon Sights and Thermal Weapon Sights | ||
| Handheld Thermal Imagers | |||
| Laser Rangefinders and Designators | |||
| Dismounted Soldier Vision Systems | |||
| By System | Imaging Systems | ||
| Targeting Systems | |||
| Electronic Support Measure Systems | |||
| By Application | Surveillance and Reconnaissance | ||
| Identify Friend or Foe (IFF) | |||
| Target Acquisition and Fire Control | |||
| Driver Vision and Navigation | |||
| Battlefield Situational Awareness | |||
| Border, Base, and Perimeter Surveillance | |||
| By Cooling Technology | Cooled Systems | ||
| Uncooled Systems | |||
| By Fit | Linefit | ||
| Retrofit | |||
| By Geography | North America | United States | |
| Canada | |||
| Mexico | |||
| Europe | United Kingdom | ||
| France | |||
| Germany | |||
| Italy | |||
| Spain | |||
| Russia | |||
| Rest of Europe | |||
| Asia-Pacific | China | ||
| Japan | |||
| India | |||
| South Korea | |||
| Australia | |||
| Rest of Asia-Pacific | |||
| South America | Brazil | ||
| Rest of South America | |||
| Middle East and Africa | Middle East | United Arab Emirates | |
| Saudi Arabia | |||
| Israel | |||
| Rest of Middle East | |||
| Africa | South Africa | ||
| Rest of Africa | |||
Key Questions Answered in the Report
What is the forecast for land-based military EO/IR systems?
The sector is projected to rise from USD 1.74 billion in 2026 to USD 2.21 billion by 2032, at a 4.07% CAGR.
Which platform type leads demand for land-based military EO/IR systems?
Vehicle-mounted platforms lead, with an 84.25% share in 2026, because tanks, IFVs, and other land platforms require multiple sensing functions.
Which system category is growing fastest?
Electronic support measure systems are forecast to grow at a 5.80% CAGR through 2032 as warning and cueing functions are integrated with imaging payloads.
Why are cooled thermal systems still important for land forces?
Cooled systems held 56.50% share in 2026 because demanding reconnaissance and fire-control missions require long-range thermal sensitivity.
Which region is expanding most quickly?
Asia-Pacific is forecast to grow at a 5.52% CAGR through 2032, supported by modernization, territorial pressures, and domestic manufacturing programs.
What is driving retrofit demand for military electro-optical equipment?
Retrofit held 57.75% share in 2026 because forces can improve long-serving armored vehicles without replacing entire fleets.