
Instant Noodles Market Analysis by Mordor Intelligence
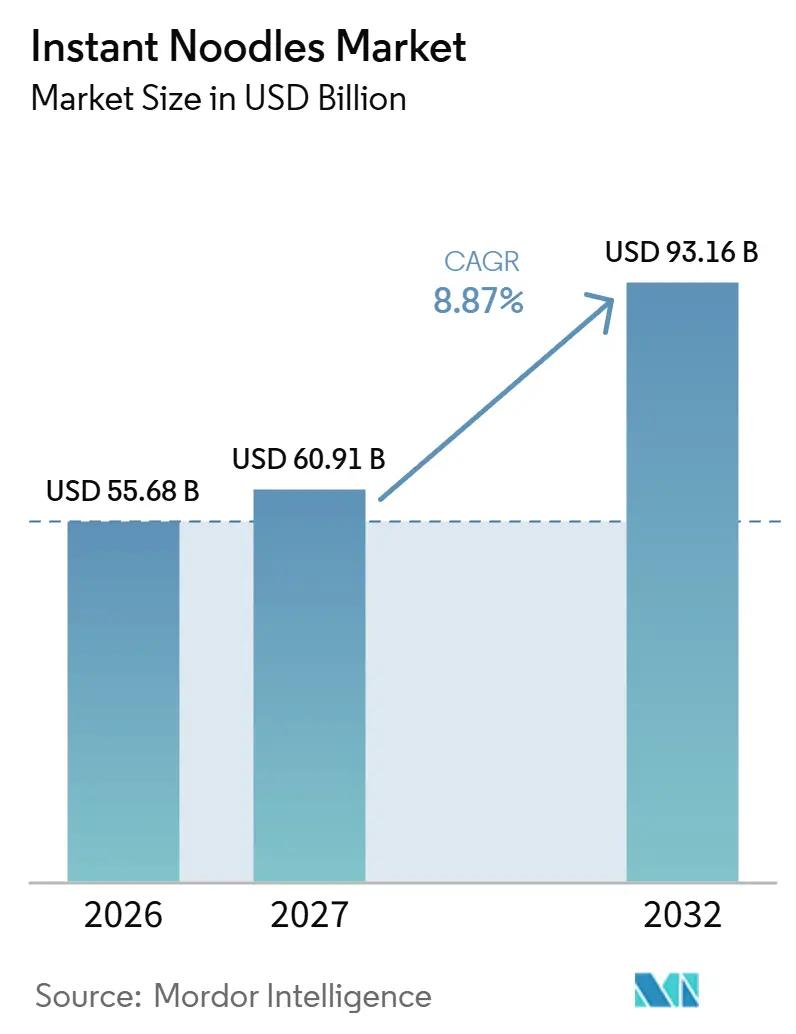
The instant noodles market size is expected to increase from USD 55.68 billion in 2026 to USD 60.91 billion in 2027 and reach USD 93.16 billion by 2032, growing at a CAGR of 8.87% over 2027-2032. The market volume is expected to increase from 123.7 billion servings in 2026 to 127.2 billion servings in 2027 and reach 146 billion servings by 2032, growing at a CAGR of 2.8% over 2027-2032.
Quick preparation and fortified recipes broaden the appeal of everyday noodle meals. In Japan, soup-less formats add differentiation through texture and flavor. Taiwan’s disaster-preparedness concerns prompted household food-stock guidance from November 2025. Growth favors producers pairing soup-less and fortified recipes with lower-sodium formulations, since dietary sodium limits constrain the frequency of repeat meals.
Key Report Takeaways
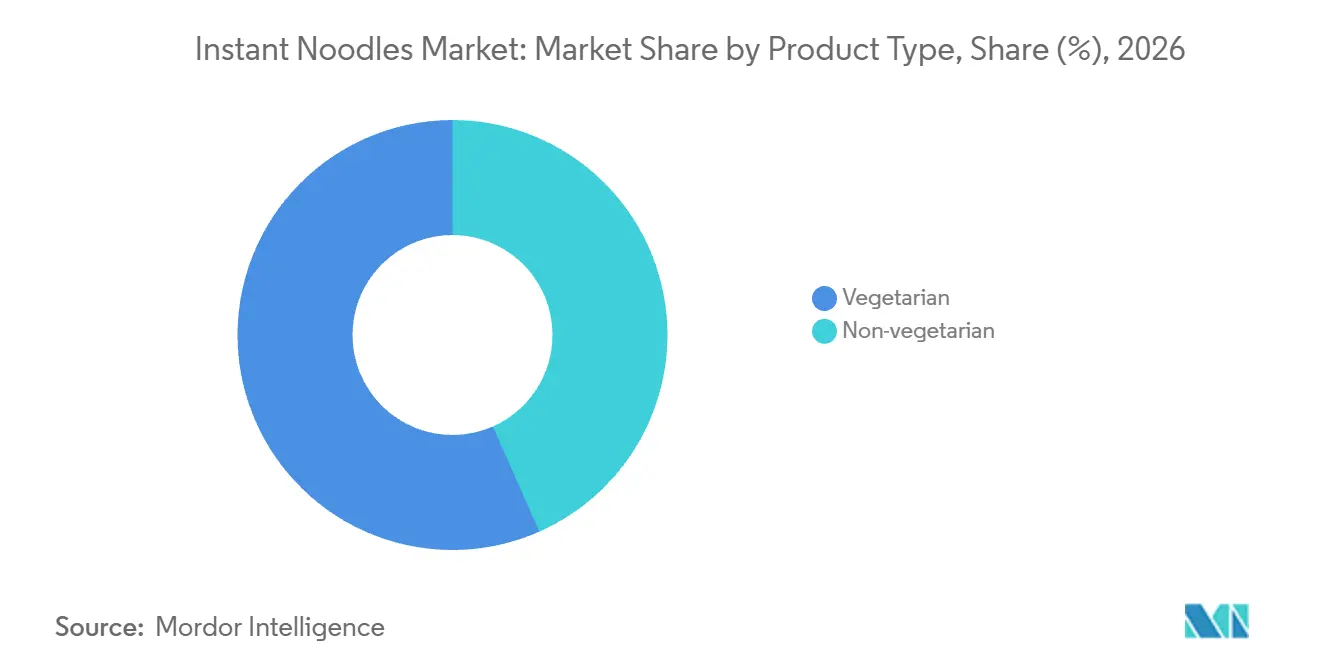
- Within product type, vegetarian products led with a 56.62% instant noodles market share in 2026 and are the fastest-growing segment, with a projected CAGR of 9.4% over 2027-2032.
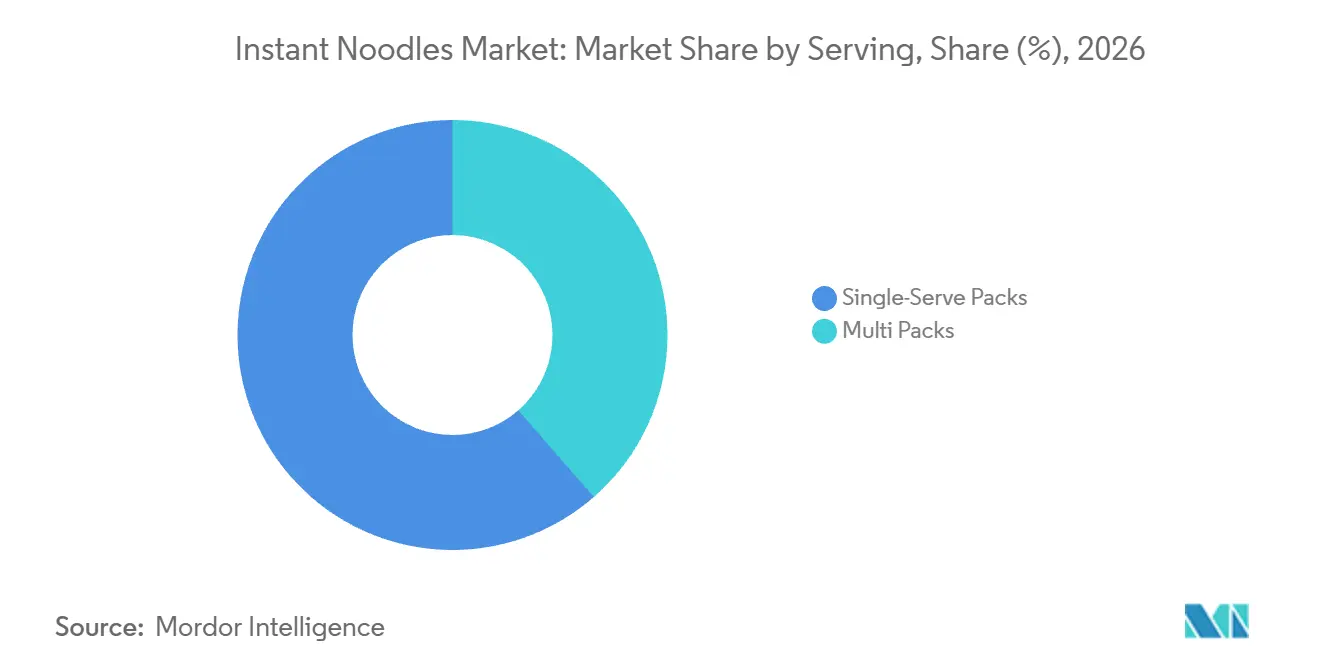
- By serving, single-serve packs led with a 61.42% share of the instant noodles market size in 2026, while multipacks are forecast to grow fastest at a CAGR of 10.05% over 2027-2032.
- For packaging, packets led with 63.25% of market value in 2026, while cup and bowl products are the fastest-growing segment, with a projected CAGR of 10.3% over 2027-2032.
- Among distribution channels, supermarkets and hypermarkets led with 42.63% of market value in 2026, as online retail stores are forecast to grow fastest at a CAGR of 10.5% over 2027-2032.
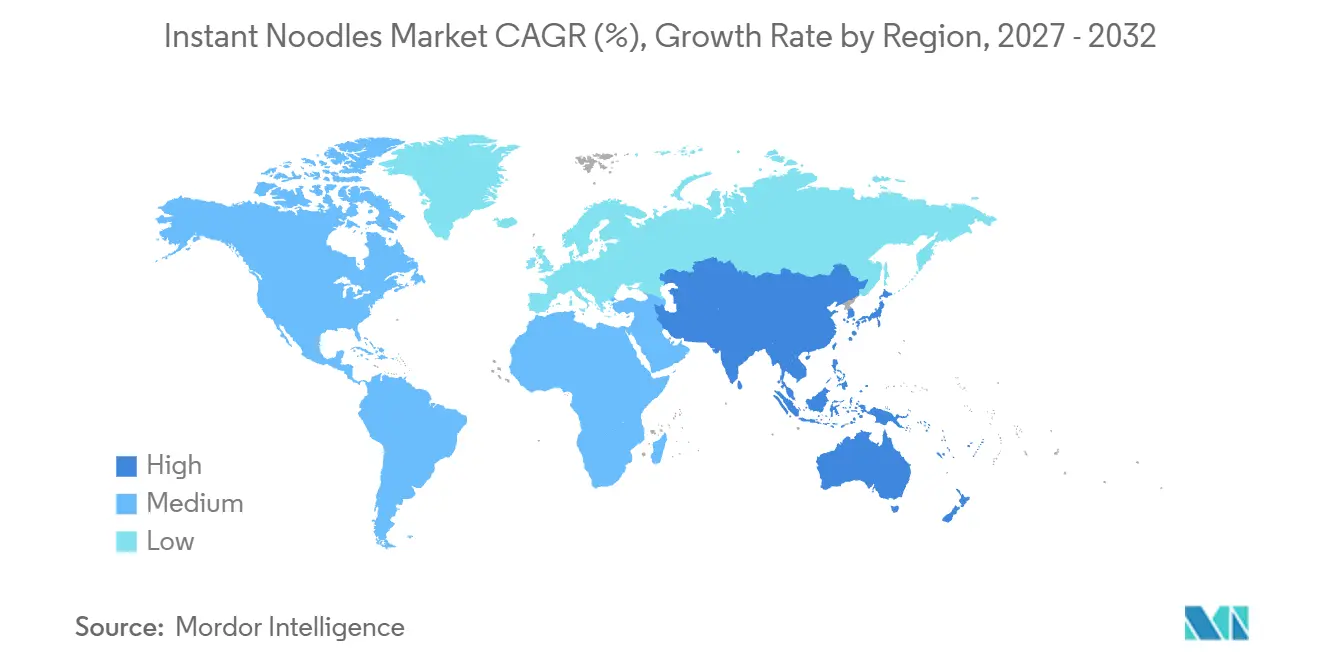
- Geographically, Asia-Pacific led with 75.77% of market value in 2026 and is the fastest-growing region, with a projected CAGR of 10.25% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Instant Noodles Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Busy lifestyles increase demand for quick, ready-to-eat meals | +4.1% | Asia-Pacific, North America, and Europe | Short term (≤ 2 years) |
| Fortified noodles with vitamins and minerals target nutrition needs | +2.4% | Indonesia and Japan | Long term (≥ 4 years) |
| Innovative textures like stir-fried or soup-less noodles attract foodies | +2.8% | Japan and Europe | Medium term (2-4 years) |
| Long shelf life supports stocking and emergency use | +1.2% | Japan and Taiwan | Short term (≤ 2 years) |
| Online retail and delivery platforms expand product availability | +1% | India and the Philippines | Medium term (2-4 years) |
| Wide flavor variety attracts diverse taste preferences | +0.8% | United States and Indonesia | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Busy lifestyles increase demand for quick, ready-to-eat meals
For a time-pressed buyer, a meal prepared by adding hot water reduces the preparation effort needed to fit food into the day. The World Instant Noodles Association (WINA) estimated global instant-noodle demand at 123.4 billion servings in its revised 2025 total. That serving base makes additional eating occasions commercially consequential. An extra occasion adds demand without requiring a larger portion in each pack. At that scale, a hypothetical 1% increase in eating occasions would equal about 1.2 billion additional servings.
Fortified noodles with vitamins and minerals target nutrition needs
Fortification lets producers address nutrition needs within a familiar convenience meal, allowing nutritional positioning to support the core range. PT Indofood Sukses Makmur Tbk reported that all Indomie instant-noodle products contained added iron, vitamin A, and B-complex vitamins B1, B6, B12, niacin, folic acid, and pantothenic acid in 2025.[1] The named additions give that appeal a specific basis in recipe composition rather than preparation speed. Manufacturers can make those specific additions visible when seeking households that weigh convenience alongside nutritional content. Incremental demand depends on the nutrients making noodles acceptable for a meal a household would otherwise exclude.
Innovative textures like stir-fried or soup-less noodles attract foodies
Soup-less formats can compete on the eating experience, expanding the appeal of instant noodles beyond a familiar broth. In its 2025 integrated report, Nissin Foods Holdings Co., Ltd. said soup-less noodles offer a stronger sense of texture and flavor. INTAGE SRI+ nationwide retail data showed that Japan’s bag-type yakisoba sales rose 12% in 2025. In Europe, Nissin reported Soba net sales value at 2.9 times that of Cup Noodles in the year ended March 2026, comparing regular cups and excluding multipacks and other items. The Japanese sales increase and European product result make soup-less texture a commercially demonstrated alternative to broth-led variety.
Long shelf life supports stocking and emergency use
Emergency reserves give shelf-stable noodles a use that separates the purchase from the meal eventually consumed. Japan’s Ministry of Agriculture, Forestry and Fisheries gives cup noodles an approximate 6-month best-before guideline and recommends starting with a 3-day food stock, with one week as the target. The finite storage window makes a usable reserve more commercially meaningful than simply maximizing the number of packs held. Suppliers can support this occasion by matching pack quantities to a household’s planned food assortment and keeping preparation requirements clear. A household following the one-week target would need to check pack dates against the approximate 6-month guideline when deciding whether to retain or replace its reserve.
Restraints Impact Analysis of Instant Noodles Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising health concerns over high sodium content | -1.9% | Malaysia and Canada | Medium term (2-4 years) |
| Gluten and concerns about MSG limit consumption for sensitive groups | -0.8% | India and China | Long term (≥ 4 years) |
| Environmental concerns about single-use plastic packaging | -0.5% | South Australia and Germany | Medium term (2-4 years) |
| Counterfeit and unbranded products undermine trusted brands | -0.2% | China, Southeast Asia, and the United States | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising health concerns over high sodium content
Health-related salt limits can constrain how often a buyer considers an instant-noodle meal, making sodium content a barrier to frequent use. Malaysia’s Ministry of Health, in its 2020 dietary guidance, advises limiting high-salt foods, including instant noodles, and choosing lower-sodium foods within the same food group. This makes sodium composition a dietary objection that a wider range of flavors alone cannot settle. Canada requires covered prepackaged foods that meet the applicable sodium threshold to carry a prescribed front-of-package symbol, subject to exemptions and calculation rules. For a noodle recipe that meets the applicable threshold and is not exempt, the symbol puts its sodium warning on the principal display panel at the point of sale.
Gluten and concerns about MSG limit consumption for sensitive groups
For an ingredient-averse buyer, a noodle product can fail the purchase test before flavor or preparation speed matters. In a 2022 interview study involving Thai and Danish consumers, one participant said MSG kept them from eating instant noodles and expressed willingness to buy a non-MSG version. The purchase condition in that response was formulation, making a different flavor insufficient to regain that particular eating occasion. India’s packaged-food rules separately require gluten-containing cereals, including wheat, to be named in allergen declarations, subject to listed exceptions. For the MSG-averse participant, clearer labeling would identify the formulation objection without resolving it, leaving that eating occasion unavailable to the existing recipe.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Instant Noodles Market Segment Analysis
By Product Type:
Vegetarian Formulations Lead the Core RangeVegetarian noodles represented a 56.62% instant noodles market share in 2026 as the largest segment and are forecast to be the fastest-growing segment, with a CAGR of 9.4% over 2027-2032. In March 2025, Wow! Momo said it had entered India’s FMCG cup-noodle segment with Wow! Noodles, a line including vegetarian flavors. The restaurant brand’s entry provides a concrete example of suppliers extending the vegetarian offer into packaged meals. Its new line brings vegetarian recipes into a cup format rather than treating the dietary category as a packaging declaration alone.
Existing Food Safety and Standards Authority of India (FSSAI) regulations require vegetarian food packages containing plant-origin ingredients, additives and processing aids to display a green filled circle inside a green-outlined square. Non-vegetarian noodle packages in India with animal-origin ingredients, additives or processing aids require a brown filled triangle inside a brown-outlined square meeting regulation 5(4)(c)’s minimum dimensions, and the manufacturer, packer or seller may add a declaration when egg is the only non-vegetarian ingredient. The green symbol makes the vegetarian status of a qualifying packaged meal visible, giving manufacturers a defined way to distinguish it in India. Plant-origin additives and processing aids are part of the vegetarian recipe boundary, so the dietary promise reaches beyond the noodle’s main ingredient.



By Serving:
Individual Meals Anchor Sales as Multipacks ExpandSingle-serve packs accounted for a 61.42% share of the instant noodles market size in 2026. In Japan, Nissin Food Products’ Cup Noodle ranked first in cup-type instant-noodle sales by value from April 2025 to March 2026. Cup Noodle, sold as 78-gram individual meals, also set record sales in Japan for the ninth consecutive fiscal year in FY2025, which ran from April 2025 through March 2026. This example connects an individual meal format with sustained branded sales, rather than preparation convenience alone.
Multipacks are the fastest-growing segment, with a projected CAGR of 10.05% over 2027-2032. Premier Foods plc reported higher Nissin noodle sales in its UK Grocery business for the 52 weeks ended March 28, 2026, supported by launches of Demae Ramen chicken multipacks and Soba Protein pots. Ottogi Corporation said 13 million produced units of its Jin Ramen 5-pack multipack, offered with a sticker-insert promotion, sold out within 50 days in the first half of 2025. Both cases place multipack competition in bundle design, with recipe-specific packs in the UK and a promotion-backed 5-pack from Ottogi.

By Packaging:
Packets Lead While Cups Broaden DistributionPacket noodles held the largest packaging share, accounting for 63.25% of market value in 2026. Tingyi (Cayman Islands) Holding Corp. reported CNY 11.06 billion (USD 1.55 billion) in 2025 high-priced packet instant-noodle revenue, down 0.3% from 2024. The sizable high-priced product category makes packet leadership compatible with differentiated pricing, because container format and price tier describe separate commercial choices. Tingyi’s result places a substantial premium tier inside the packet format, so choosing a packet need not mean competing only on low price.
Cup/bowl noodles are the fastest-growing segment, with a projected CAGR of 10.3% over 2027-2032. Nissin Food Products reported steady sales contributions in Japan from the Assari Oishii Cup Noodle series and Cup Noodle Big in the year ended March 2026, following the latter’s September 2025 renewal. In its FY2026 CFO message, Nissin Foods Holdings said demand for cup-type instant noodles was expanding rapidly in Brazil and that it was expanding production capacity there. WINA described cup-type noodle distribution as expanding in suburban Vietnam. Brazil’s demand expansion and Vietnam’s wider suburban distribution offer distinct routes to cup-format growth, while Japan’s result concerns sustaining an established range.
By Distribution Channel:
Supermarkets Lead While Online Sales AdvanceSupermarkets and hypermarkets were the largest segment, with 42.63% of market value in 2026. Across all product categories, Japan’s supermarkets recorded retail sales of JPY 16.8 trillion (USD 112.3 billion) in 2025. That all-category retail total was up 4.7% from 2024. The result illustrates the supermarket format’s retail scale within Japan.
Online retail stores are the fastest-growing segment, with a projected CAGR of 10.5% over 2027-2032. Compas data reported by FORTUNE Indonesia showed that online transaction value for instant noodles and pasta rose 91% year over year in Indonesia in H1 2026. For a producer, this adds a distribution decision to product development, because the commercial opportunity concerns how packaged meals are sold as well as what the meal contains. Indonesia’s reported digital expansion makes online distribution a country-specific priority for reaching buyers of the combined noodle-and-pasta category.
Geography Analysis
Asia-Pacific Instant Noodles Market
Asia-Pacific held a 75.77% instant noodles market share in 2026 and is the largest and fastest-growing region, with a projected CAGR of 10.25% over 2027-2032. WINA estimated instant-noodle demand in China/Hong Kong at 43.27 billion servings in 2025, establishing a substantial consumption base within the region. India’s estimated demand rose from 8.82 billion servings in 2024 to 9.6 billion in 2025, adding a separate source of incremental consumption. For manufacturers, serving growth in India presents an expansion opportunity distinct from supplying China/Hong Kong’s much larger established consumption base.
In North America, WINA says chicken is the most popular U.S. instant-noodle flavor, with short noodles generally eaten using a spoon and fork and microwaveable products also popular. That combination makes preparation and eating behavior commercially relevant design choices, encouraging a close fit between noodle length, serving vessel and heating method. Europe presented a different volume backdrop, as WINA reported that it was the only region where instant-noodle demand in servings did not grow in 2025. In that setting, a European producer’s volume gain requires capturing a larger share of existing servings rather than relying on category expansion.
South America’s use profile is illustrated by Brazil, where WINA describes a preference for savory soup-less instant noodles, especially chicken, alongside popular creamy soup varieties. That combination supports separate product positions for soup-less noodles and creamy soup meals, with texture and flavor shaping the local eating occasion. In the Middle East and Africa, Nigeria provides a different demand example, with children and students eating noodles for breakfast, snacks and school lunches. Those occasions create a potential role for products suited to school-day meals and between-meal use, making the intended eater central to product design. Nigerian children’s and students’ preference for a large amount of noodles per meal makes a small snack-sized pack a weaker fit for a full meal.
Regional Editions
Regulatory Framework and Outlook
The comparison evaluates selected jurisdictions from the perspective of an established packaged-noodle manufacturer serving national distribution. Argentina assigns food-control execution to the Servicio Nacional de Sanidad y Calidad Agroalimentaria (SENASA), while the Ministry of Health’s Secretaría de Gestión Sanitaria retains stewardship. Canadian nutrient symbols depend on thresholds, exemptions, prohibitions and calculation rules, while Argentine warning seals depend on final food composition exceeding applicable limits. From August 12, 2026, food-contact packaging in Germany is subject to limits on per- and polyfluorinated alkyl substances (PFAS) where no other EU act already prohibits placement.
Regulatory Table of Instant Noodles Market
| Decision factor | Canada | Germany | China | Argentina | Saudi Arabia |
|---|---|---|---|---|---|
| Primary authority | Canadian Food Inspection Agency; Health Canada | Federal-state surveillance authorities; Federal Office of Consumer Protection and Food Safety coordination | State Administration for Market Regulation | SENASA | Saudi Food and Drug Authority |
| Key instruments or direction | Safe Food for Canadians Regulations; Food and Drug Regulations | Regulation (EU) 2025/40 | Instant-noodle production licensing; GB 7718-2011 and GB 7718-2025 | Código Alimentario Argentino (CAA); Law 27.642; Decreto 697/2026 | SFDA.FD GSO 1871:2022; SFDA.FD GSO 9:2022 |
| Commercial effect | Manufacturing, packaging or labeling license for interprovincial trade or export; conditional nutrient symbols | Food-contact PFAS limits; staged recyclability qualification | Production-license controls; direct-ingredient allergen alerts from March 16, 2027, subject to exemptions | SENASA food controls; threshold-triggered warning seals | Assessment against adopted noodle and prepackaged-label standards |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | Hardening | Hardening | No change | No change |
| Source: Mordor Intelligence | |||||
Canada’s front-of-package symbol duty has applied since January 1, 2026, with products imported, manufactured in Canada or packaged at retail before that date allowed to remain on sale, and the Canadian Food Inspection Agency’s forward regulatory plan announces no noodle-specific labeling change, supporting a No change judgment. China’s switch from recommended to mandatory alerts for listed allergens used directly as ingredients from March 16, 2027, subject to exemptions, supports a hardening judgment. Argentina’s completed authority transfer leaves the CAA and conditional warning-label duties operative, while Saudi Arabia’s adopted noodle and labeling standards provide an established compliance framework. Germany hardens through recyclability grades A, B or C from the later of January 1, 2030 and 24 months after the relevant delegated acts take effect, subject to Article 6(10).
Value Chain Stages
The value chain compares flour production, packaging-component supply and finished-noodle manufacturing, separating each supplier’s earnings from the capability needed downstream. Interflour Group’s Sarawak Flour Mill supplies the instant-noodle segment in Sarawak, Malaysia, while Korpack Corporation makes customized cups, bowls and lids for instant noodles. In this structure, flour and packaging suppliers earn input sales, while the finished-food manufacturer earns the packaged-meal sale.
Value Chain Analysis Table of Instant Noodles Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Noodle-flour production | Flour millers such as Interflour Group’s Sarawak Flour Mill | Flour sales to noodle producers | Qualification of flour specifications | Qualify additional flour sources to the same specification |
| Packaging-component production | Cup, bowl, and lid suppliers such as Korpack Corporation | Customized packaging sales | Specification fit when changing formats | Qualify complete cup-and-lid combinations |
| Noodle manufacturing and finished-product sales | Manufacturing groups such as the Nissin Foods Holdings Co., Ltd. group, through operating companies | Finished packaged-noodle sales | Coordinating noodle output with packaging availability | Match production schedules to qualified packaging formats |
| Source: Mordor Intelligence | ||||
Nissin Foods Holdings’ group provides the manufacturing example, with operating companies conducting production within a wider footprint that includes instant-noodle businesses. Korpack’s customized cups, bowls and lids make packaging design a distinct supply decision within a cup-noodle offer. A change in cup format would involve that component stage as well as noodle manufacturing, so a finished-product expansion can create upstream business without requiring the component supplier to own a consumer brand.
Competitive Landscape
Market Concentration
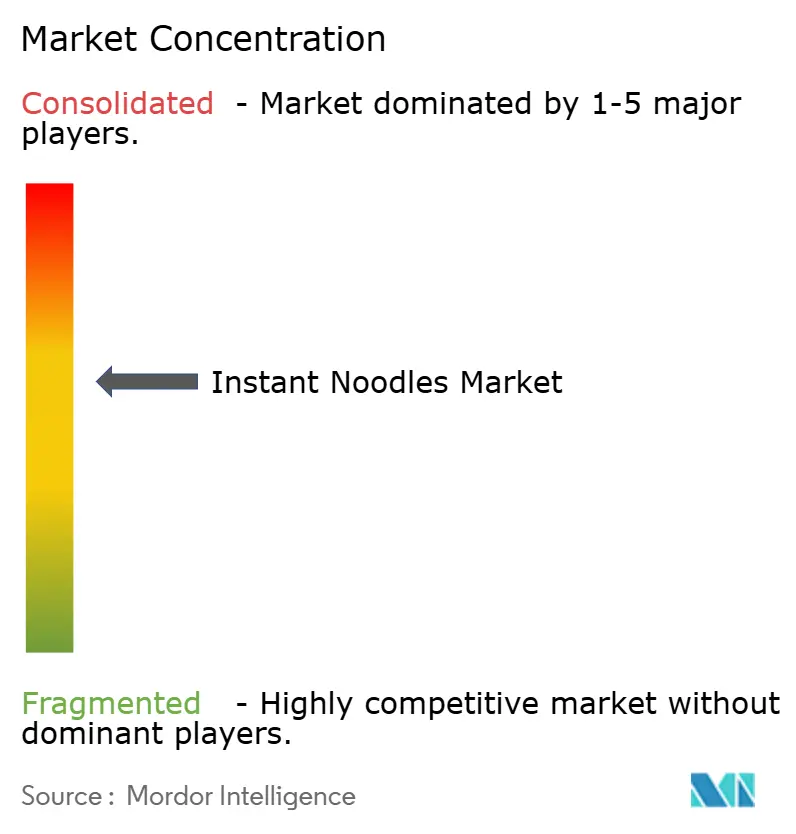
The market is moderately concentrated around established branded manufacturers, with rivalry extending from product design to industrial capacity. Major players include Nissin Foods Holdings Co., Ltd., Unilever PLC and Nestlé S.A. Nongshim Co., Ltd. and PT Indofood CBP Sukses Makmur Tbk are also among the major participants. Nissin Food Products Co., Ltd. announced in August 2026 a planned Cup Noodle dedicated factory in Tsukubamirai, Japan, with construction scheduled to start in May 2027 and operations in fiscal 2029. The announced plant makes future production capability part of branded competition alongside product design, although its contribution depends on execution of that schedule.
Nestlé launched Maggi Saucy Noodles in Europe in 2025 with Japanese Teriyaki and Pad Thai recipes for small meals that could be prepared in minutes. Nestlé reported that noodles were the largest growth driver for its food category in 2025.[2] Nestlé attributed that contribution to the Saucy Noodles initiative. The reported result makes a focused quick-meal recipe range a demonstrated route to growth within Nestlé’s food category, placing product development alongside capacity expansion as a competitive approach.
In 2025, a Taiwanese food safety listing put an Indomie batch under review in 2 jurisdictions. On September 18, 2025, Indonesia’s National Agency of Drug and Food Control (BPOM) reported that ethylene oxide (EtO) and 2-chloroethanol (2-CE) were not detected in a retained sample of the PT Indofood CBP Sukses Makmur Tbk product Indomie Soto Banjar Limau Kuit, from the same batch that Taiwan’s Food and Drug Administration had listed as containing EtO at 0.1 mg/kg.[3] At quantification limits of 0.003 mg/kg for EtO and 0.005 mg/kg for 2-CE, the result met Indonesia’s limit below 0.01 mg/kg. For the tested sample, that finding supplies residue-compliance evidence that can support product assurance alongside production and recipe development. The export-market listing prompted retained-sample testing at home, showing that a major producer’s export assurance can involve regulators in both jurisdictions.
Instant Noodles Industry Leaders
-
Nissin Foods Holdings Co., Ltd.
-
Unilever PLC
-
Nestlé S.A.
-
Nongshim Co., Ltd.
-
PT Indofood CBP Sukses Makmur Tbk
- *Disclaimer: Major Players sorted in no particular order
Instant Noodles Market Companies Covered in this Report
- Nissin Foods Holdings Co., Ltd.
- Unilever PLC
- Nestlé S.A.
- Nongshim Co., Ltd.
- PT Indofood CBP Sukses Makmur Tbk
- Tingyi (Cayman Islands) Holding Corp.
- Samyang Foods Co., Ltd.
- Toyo Suisan Kaisha, Ltd.
- Ajinomoto Co., Inc.
- Ottogi Corporation
- Acecook Co., Ltd.
- Uni-President Enterprises Corp.
- Wings Food
- Masan Consumer Holdings
- Vifon
- Capital Foods Pvt Ltd.
- Thai President Foods PCL
- Paldo Co., Ltd.
- Baixiang Food Group
- Mr Lee’s Pure Foods Co.
Key Opportunities for Market Participants
The opportunities compare packaged-noodle supply to new business buyers with production expansion intended to support a broader product range. In June 2026, Indian retailers and restaurants were adding self-service ramyun bars, creating a food-service channel for packaged instant noodles. The format’s longer-term commercial success depends on product quality and affordability, making those conditions central to a supplier’s offer. In August 2026, Nissin Foods Brazil said its Ponta Grossa plant in Paraná was scheduled to start operating in early 2027 to expand instant-noodle capacity.
Market Opportunities Table of Instant Noodles Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Retailer-operated ramyun stations | Emerging Indian self-service channel | Retailers operating ramyun bars | Build a focused packaged-noodle assortment for self-service preparation | Affordable meal pricing | Noodle producers such as Nongshim Co., Ltd. |
| Restaurant ramyun assortments | Restaurant adoption of the self-service format | Restaurant operators | Supply packaged ranges for operator-designed ramyun menus | Consistent product quality | Noodle producers such as Nongshim Co., Ltd. |
| Brazilian production and range expansion | Ponta Grossa plant scheduled for early 2027 | Brazilian packaged-noodle channels | Phase range expansion with production readiness | Construction and production ramp-up | Nissin Foods Brazil |
| Source: Mordor Intelligence | |||||
The Indian channel offers producers access to a new business buyer while retaining their role as packaged-food suppliers. They can concentrate on the noodle assortment and its economics, with the retailer or restaurant operating the venue. The Ponta Grossa plant creates a different opening in Brazil, but its capacity benefit depends on commissioning and ramp-up.
Recent Industry Developments in Instant Noodles Market
- Aug 2026: Nissin Foods Brazil said its Ponta Grossa plant in Paraná was scheduled to start operating in early 2027 to expand instant-noodle capacity.
- Aug 2026: Nissin Food Products Co., Ltd. announced a planned Cup Noodle factory in Tsukubamirai, Japan, with construction scheduled to start in May 2027 and operations in fiscal 2029.
Instant Noodles Market Report Scope and Research Methodology
Market Definition and Coverage
Instant noodles market measures annual manufacturer sales value of factory-produced, shelf-stable noodle products supplied with seasoning for consumer reconstitution in hot water. Global sales of packet, cup, and bowl products are valued at the manufacturer selling price.
Scope exclusions: Cold or fresh ramen, wet-noodle kits, handmade noodles, and restaurant-prepared servings are excluded.
Segments Covered in This Report
- By Product Type
- Vegetarian
- Non-vegetarian
- By Serving
- Single-Serve Packs
- Multi Packs
- By Packaging
- Cup/Bowls
- Packet
- By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience/Grocery Stores
- Online Retail Stores
- Others Distribution Channel
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Secondary analysis would draw on sources such as the World Instant Noodles Association demand rankings for country and regional servings, the Food and Agriculture Organization Food Outlook for grain and oil input conditions, USDA Foreign Agricultural Service country reports for local food-processing and consumption context, the Food Safety and Standards Authority of India product standards, and public manufacturer filings such as Nissin Foods' integrated report. These sources help distinguish physical demand from value, check product definitions and regulation, and relate changes in flour, oils, pack formats, and channel access to packaged noodle sales.
Public filings, investor materials, trade reporting, national statistics, and customs or retail data can supplement these references by checking producer sales, market access, and regional timing. These named sources are illustrative rather than exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Structured interviews would include executives and functional leaders at instant noodle manufacturers, ingredient and packaging suppliers, distributors, retailers, and food-service buyers across APAC, EMEA, and the Americas. Interview prompts would test product boundaries, manufacturer selling prices, pack and channel mix, serving volumes, and regional assumptions against documentary evidence. Conflicting or missing inputs would be recorded by variable, checked with a second source or a targeted follow-up, and triangulated before they inform an estimate.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 32% | CXOs: 15% | APAC: 55% |
| Mid tier: 43% | Functional/Unit leaders: 35% | EMEA: 25% |
| Smaller Players: 25% | Managers: 50% | Americas: 20% |
Market-Sizing & Forecasting
A top-down model would estimate global manufacturer sales value and servings separately, then allocate each series across product type, serving format, packaging, distribution channel, and geography using observed company sales, market shares, demand rankings, retail or trade indicators, and reported product mix. Value inputs would include packaged noodle sales, average manufacturer selling prices, and changes in recipe, pack, and channel mix. Volume inputs would include reported servings and country demand, with price and mix effects explaining why value and servings can move differently. Income and urban household growth, food input costs, retail availability, online access, and product launches would inform the outlook, with time-series smoothing or scenario analysis used where series are short or shocks disrupt the trend. Selective bottom-up checks would multiply sampled annual packaged volumes by manufacturer-level selling prices and compare supplier, distributor, and channel roll-ups with the global model. Unmatched coverage would be isolated and the remaining gap estimated from the broader series rather than filled with unsupported supplier detail. Expert interviews would test the direction and plausibility of variable-level forecasts and identify missing channels or country evidence before assumptions are retained.
Data Validation & Update Cycle
Analysts would triangulate manufacturer filings, demand and trade signals, channel evidence, and country data, then investigate unusual year-on-year movements, inconsistent units, and material differences between top-down and sampled bottom-up checks. A second analyst review would trace key inputs to sources and confirm reconciliations before sign-off, with follow-up interviews triggered when definitions, prices, volumes, or channel coverage conflict. The model would refresh annually, update sooner after material market events, and receive a fresh source and calculation review before delivery.
Mordor Intelligence's Instant Noodles Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Global sales of packet, cup, and bowl products are valued at the manufacturer selling price.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. A top-down model would estimate global manufacturer sales value and servings separately, then allocate each series across product type, serving format, packaging, distribution channel, and geography using observed company sales, market shares, demand rankings, retail or trade indicators, and reported product mix.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | Value: USD 60.91 B (2027) / Volume: 127.2 billion servings (2027) | |
| Global Consultancy A | USD 57.3 B (2025) | The source's upward sequence after its measured base supports a lower earlier-period value. |
| Global Consultancy B | USD 57.02 B (2025) | The source's upward sequence after its measured base supports a lower earlier-period value. |
Mordor Intelligence's analysts would triangulate manufacturer filings, demand and trade signals, channel evidence, and country data, then investigate unusual year-on-year movements, inconsistent units, and material differences between top-down and sampled bottom-up checks.
Key Questions Answered in the Report
What is the instant noodles market size and growth outlook?
Value is forecast at USD 60.91 billion in 2027 and USD 93.16 billion by 2032, growing at a CAGR of 8.87% over 2027-2032.
What supports demand for instant noodles?
Quick preparation, fortified recipes and soup-less formats support demand. All Indomie instant-noodle products contained added iron, vitamin A and B-complex vitamins in 2025.
Which product type leads instant-noodle sales?
Vegetarian noodles held 56.62% of market value in 2026 and are forecast to grow fastest at a CAGR of 9.4% over 2027-2032.
Which companies are major competitors in instant noodles?
Nissin Foods Holdings Co., Ltd., Unilever PLC, Nestlé S.A., Nongshim Co., Ltd. and PT Indofood CBP Sukses Makmur Tbk are major players.
What health concern could limit repeat instant-noodle consumption?
Malaysia’s 2020 dietary guidance advises limiting high-salt foods, including instant noodles, and choosing lower-sodium alternatives within the same food group.
Which region leads sales of packaged instant noodles?
Asia-Pacific held 75.77% of market value in 2026 and is the fastest-growing region, with a projected CAGR of 10.25% over 2027-2032.