
Indonesia Telecom Towers Market Size and Share
Indonesia Telecom Towers Market Analysis by Mordor Intelligence
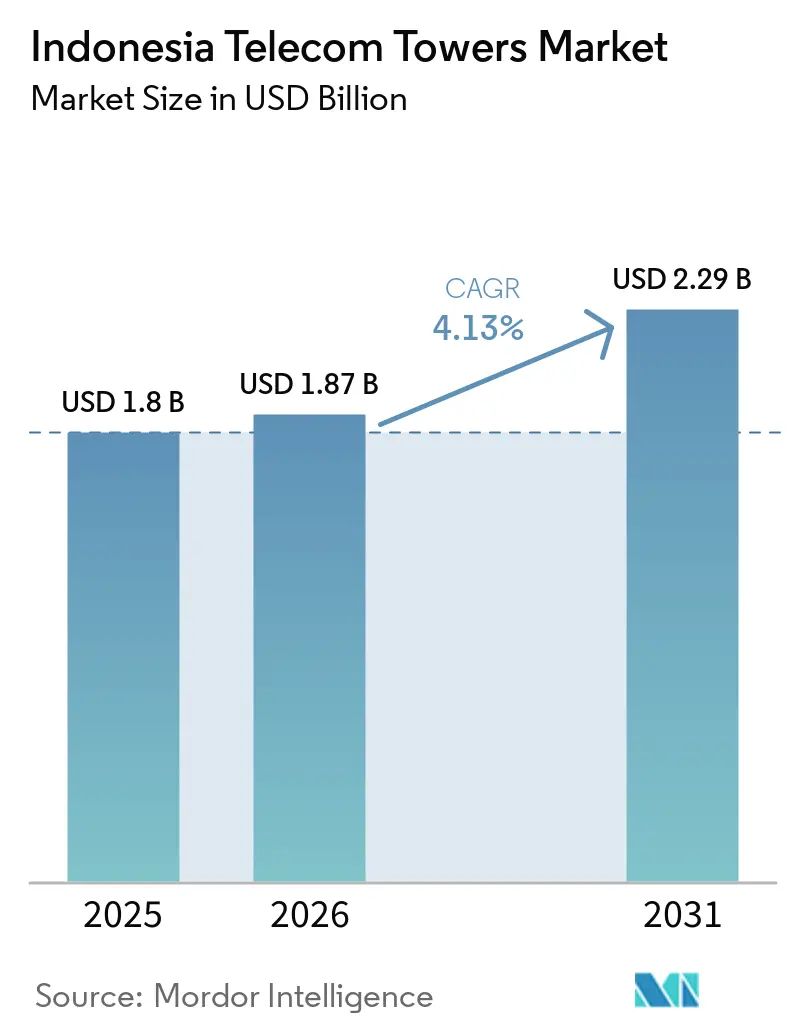
The Indonesia telecom towers market size is expected to increase from USD 1.87 billion in 2026 to USD 1.95 billion in 2027 and reach USD 2.41 billion by 2032, growing at a CAGR of 4.36% over 2027-2032. The market volume is expected to increase from 114 thousand units in 2026 to 116.4 thousand units in 2027 and reach 129.7 thousand units by 2032, growing at a CAGR of 2.18% over 2027-2032.
Komdigi, Indonesia’s Ministry of Communication and Digital Affairs, attached coverage obligations to its July 2026 spectrum awards in Indonesia. This supports rooftop and rural hosting, while lease repricing pressures returns on occupied sites. Sumatra’s floods and landslides disrupted electricity and telecommunications from November 2025, underscoring backup-power needs. Competition combines site additions with the defense of existing tenancies. Financing capacity can constrain how quickly those requirements become operating towers.
Key Report Takeaways
- In ownership terms, independent TowerCos held a 53.53% Indonesia telecom towers market share in 2026 and are also forecast to be the fastest-growing segment, at a CAGR of 7.58% over 2027-2032.
- By installation, ground-based sites held a 64.4% share of the Indonesia telecom towers market size in 2026, while rooftop installations are forecast to grow fastest, at a CAGR of 5.85% over 2027-2032.
- Across fuel types, grid/diesel hybrid sites led with 79.4% of tower-market revenue in 2026, while renewable-powered sites are forecast to grow fastest, at a CAGR of 20.2% over 2027-2032.
- Among tower types, monopoles led with 46.19% of tower-market revenue in 2026, and stealth / concealed towers are forecast to be the fastest-growing segment, at a CAGR of 10.4% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Indonesia Telecom Towers Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Nationwide 5G spectrum release and rollout momentum | +2% | Nationwide | Long term (≥ 4 years) |
| Rural 4G connectivity mandates and BAKTI subsidies | +1.6% | Underserved, frontier, and outermost areas | Short term (≤ 2 years) |
| Sale-leaseback deals by MNOs | +1% | Nationwide | Medium term (2-4 years) |
| 3G switch-off unlocking spare tower capacity | +0.8% | Nationwide | Short term (≤ 2 years) |
| TowerCo move into fiber-to-tower and edge micro-DC services | +0.6% | Nationwide | Medium term (2-4 years) |
| ESG-linked financing for green sites | +0.4% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Nationwide 5G spectrum release and rollout momentum
Coverage commitments give Indonesia’s spectrum awards a clearer route into demand for usable telecommunications sites. On July 21, 2026, Komdigi named XLSMART, Telkomsel, and Indosat winners of the 700 MHz and 2.6 GHz spectrum selection after all stages concluded.[1] The winning operators must provide 5G service covering at least 51% of the national population by year five. This obligation supports site-access demand by requiring operators to translate spectrum rights into a service footprint. Existing towers can participate through additional hosting or upgrades, while coverage gaps create a separate case for new locations. For tower owners, the commercial gain depends on securing serviceable operator tenancies as rollout commitments become network investment.
Rural 4G connectivity mandates and BAKTI subsidies
Rural coverage obligations create a defined infrastructure requirement in remote areas. By June 5, 2026, BAKTI, the Telecommunications and Information Accessibility Agency, had built 5,514 4G base transceiver stations (BTS), all reported on air in remote areas. Separately, 1,233 BTS in its underserved, frontier, and outermost-area network were funded through Universal Service Obligation duties of providers including Telkomsel, Indosat Ooredoo Hutchison, and XLSMART at that date. Those obligations connect rural infrastructure funding to operators that need serviceable network locations. For lessors and site-service contractors, supplying a usable host or maintaining its supporting infrastructure would turn that requirement into a commercial service beyond the initial build.
Sale-leaseback deals by MNOs
Operator transactions become a source of recurring site-service demand when an asset sale is accompanied by a leaseback commitment. XLSMART’s June 2025 interim statements retained tower-leaseback accounting for the group’s earlier transactions with Protelindo and PT Solusi Tunas Pratama Tbk (STP). The Protelindo sale occurred in 2016 and the STP sale in 2014, with transaction gains amortized over the leaseback periods. This arrangement separates the operator’s use of a site from ownership of the underlying infrastructure. The leased assets were recorded at the present value of minimum lease payments with related lease liabilities. Those liabilities show that the operator’s lease commitment can outlast the transaction year, giving the lessor a contractual relationship after the sale.
3G switch-off unlocking spare tower capacity
Retiring 3G equipment can support additional hosting demand when the change frees usable capacity for another paying tenancy. The relevant capacity is the hosting space, structural allowance, and supporting power that an owner can make available at the same location. An operator able to reuse that location can pursue an upgrade without treating new land access as part of every deployment. The available allowance has to match the replacement equipment’s requirements, making site-specific engineering the condition for offering that space as another service position. Only a contracted upgrade or colocation converts the released hosting allowance into incremental revenue for the site owner.
Restraints Impact Analysis of Indonesia Telecom Towers Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Lease-rate renegotiation pressure from MNOs | -0.9% | Nationwide | Short term (≤ 2 years) |
| High leverage amid rising interest-cost environment | -0.6% | Nationwide | Medium term (2-4 years) |
| Municipal crackdowns on unlicensed BTS structures | -0.3% | Menden Village in Klaten Regency | Short term (≤ 2 years) |
| LEO-satellite backhaul substituting remote towers | -0.2% | Priority villages in Bungo Regency | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Lease-rate renegotiation pressure from MNOs
Lease renegotiations can reduce tower earnings even when the tenant continues using the same infrastructure. In the first quarter of 2026, PT Sarana Menara Nusantara Tbk’s effective monthly lease rate per XL Axiata (EXCL) tenancy was 7.5% below its FY2025 level following downward repricing. EXCL’s sites formed part of the merged XLSMART operator business. For a lessor, this separates physical utilization from revenue productivity, weakening the return available from an occupied site. The post-merger agreement provided for retaining EXCL’s sites without churn but at lower monthly rates, leaving less income per retained tenancy.
High leverage amid rising interest-cost environment
Leverage can constrain a tower owner’s expansion before any deterioration in site occupancy becomes visible. At June 30, 2026, PT Tower Bersama Infrastructure Tbk reported company-wide net debt of 4.8 times its second-quarter EBITDA on an annualized basis. This debt load makes the financing of additional sites sensitive to the cash available after servicing existing obligations. A project with attractive prospective tenancy income can consequently face a tighter funding test than its operating economics alone suggest. Additional borrowing also increases exposure to the cost of refinancing before a new site has established recurring receipts. New builds compete with debt service for the cash generated by existing leases.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Indonesia Telecom Towers Market Segment Analysis
By Ownership:
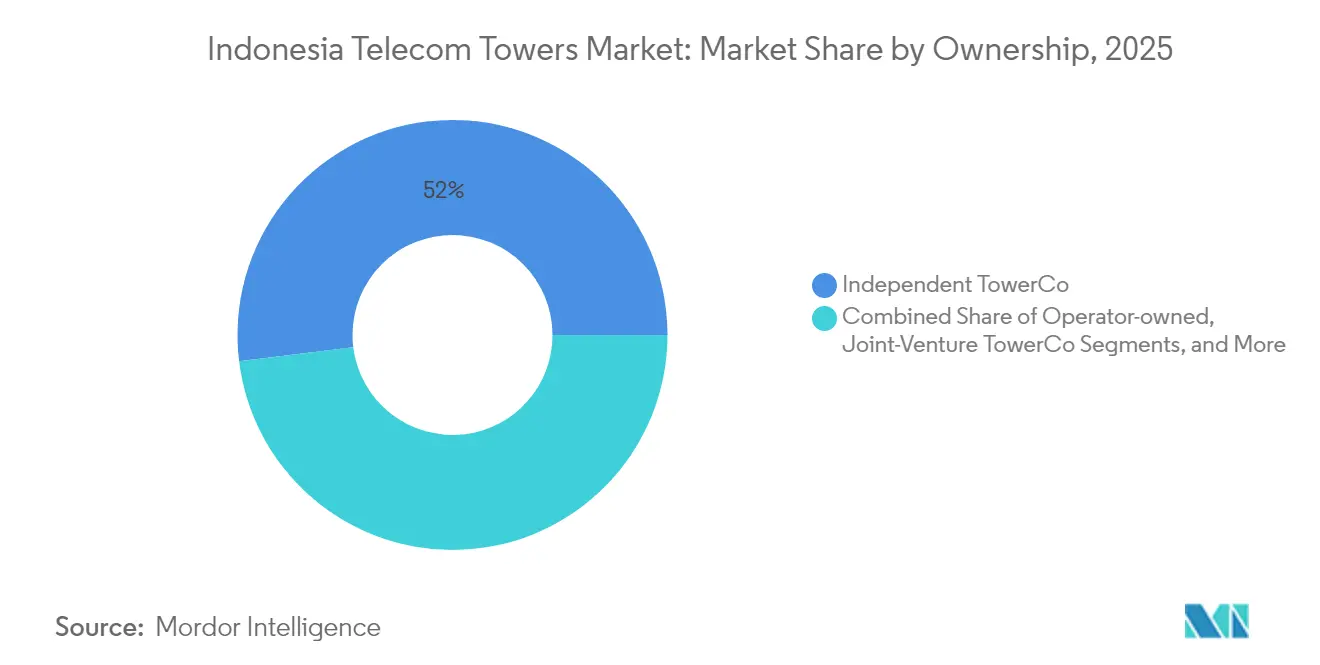
Shared Infrastructure Leads the Ownership MixIndependent TowerCos were the largest segment with 53.53% of tower-market revenue in 2026 and are forecast to grow fastest, at a CAGR of 7.58% over 2027-2032. At December 31, 2025, PT Sarana Menara Nusantara Tbk reported approximately 36,000 towers and 60,500 tenants for its group in Indonesia. Its stated tenancy ratio for that date was 1.67x. The ratio makes retention and additional occupancy relevant to the performance of a shared estate, tying income to the use of available hosting positions. Adding a tenant to an existing tower creates another rental relationship without the capital commitment of another structure.
MNO-captive holdings are forecast to contract over 2027-2032. Telkom reported approximately 4,472 towers owned by Telkomsel at December 31, 2025. Those operator-held towers illustrate the ownership choice between retaining physical infrastructure and obtaining commercial hosting, with the forecast assigning a smaller role to captive ownership.



By Installation:
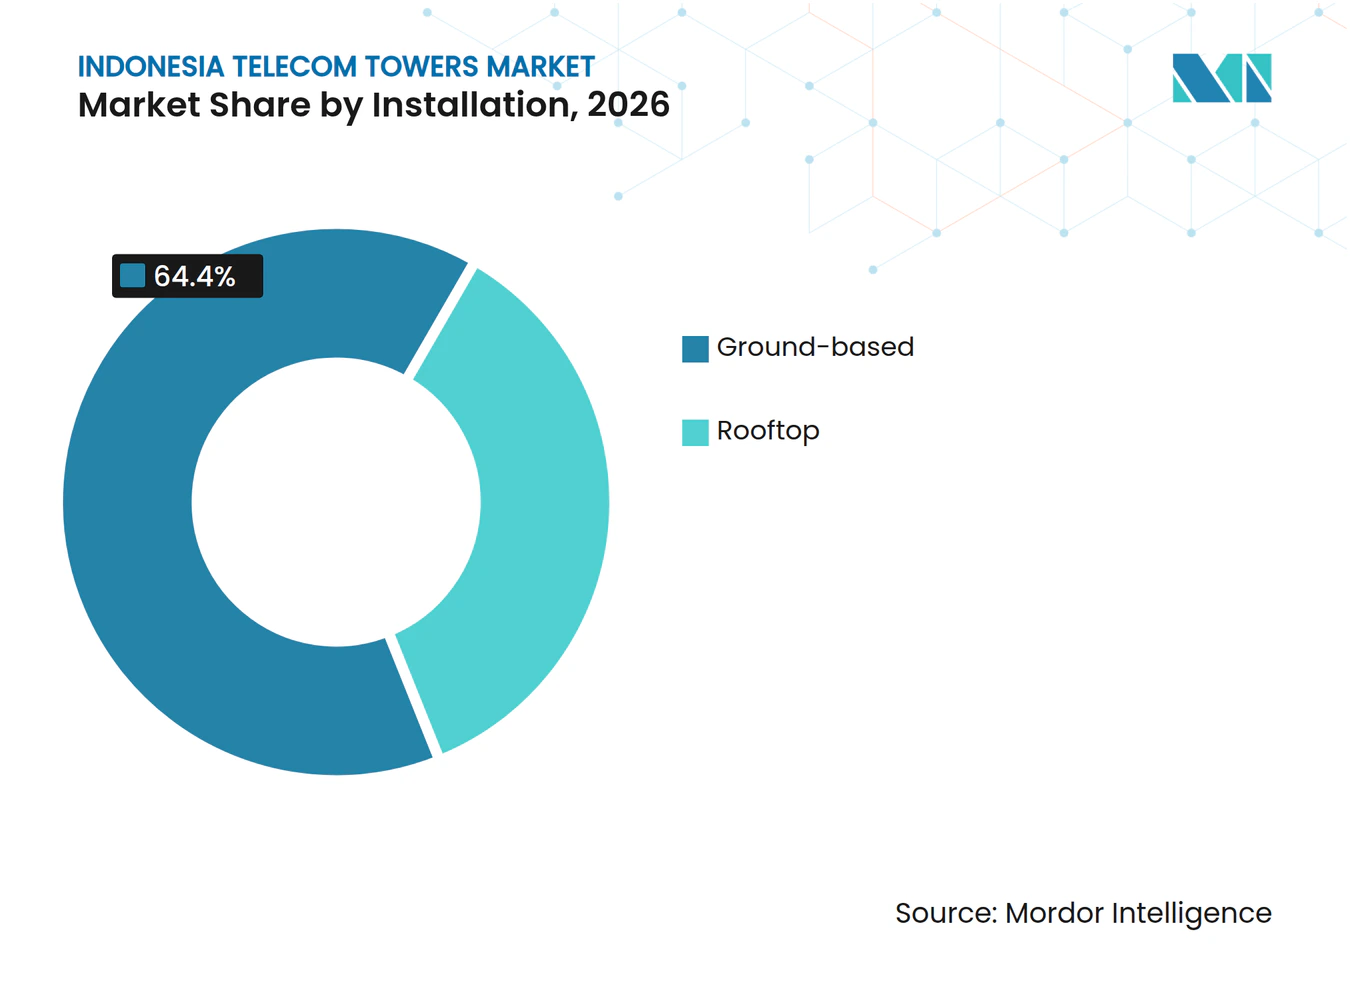
Land Sites Lead as Rooftop Leasing ExpandsGround-based installations accounted for a 64.4% share of the Indonesia telecom towers market size in 2026. In June and July 2025, PT Solusi Tunas Pratama planned a 60-meter Indosat BTS tower on a resident-owned site in Dusun II, Desa Kampung Baru, Rejang Lebong, subject to remaining procedures. The process involved land-ownership documentation, nearby residents’ consent, and permitting. A dedicated plot gives the tower provider a physical location for the structure, but securing that location does not by itself make it ready for construction. Resolving landowner consent and permits is what would convert this planned plot into a host available to the operator.
Rooftop installations are forecast to be the fastest-growing segment, with a CAGR of 5.85% over 2027-2032. In January 2026, Lampung Province extended Mitratel’s right to lease rooftop space at the Provincial Secretariat building. Renewal preserves a legal route to using that building for telecommunications infrastructure, giving the property right an ongoing role in site availability. For a tower lessor, a renewed right can support an onward hosting offer to mobile operators without requiring purchase of the underlying building. The extension gives Mitratel a route to continued rooftop use without relocating to another property.

By Fuel Type:
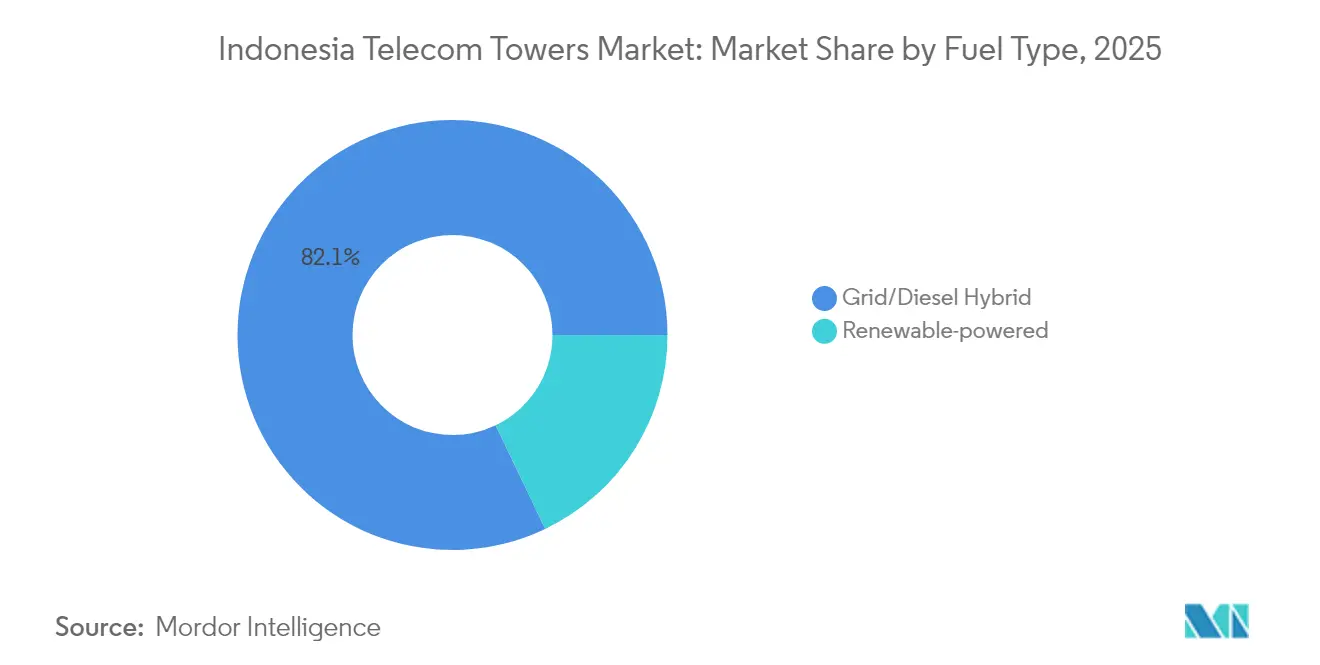
Backup Power Anchors Scale as Renewables AccelerateGrid/diesel hybrid sites were the largest segment, accounting for 79.4% of tower-market revenue in 2026. Sumatra’s floods and landslides, which began in November 2025, disrupted electricity and telecommunications. In December 2025, TelkomGroup deployed 470 generators through Telkomsel to support network recovery in Sumatra. That recovery effort illustrates the operational role of backup generation when electricity supply becomes unreliable. Because renewable-powered sites start from a small base, hybrid sites are the dominant configuration that operators must keep running through outages.
Renewable-powered sites are forecast to be the fastest-growing segment, at a CAGR of 20.2% over 2027-2032. Telkomsel added 86 solar power plants at BTS sites during 2025 and reported 360 BTS units with solar panels. Together with one microhydro-powered BTS, those solar installations generated 13,926 GJ in 2025. Its renewable-powered BTS served major cities and underdeveloped, frontier, and outermost regions in 2025. Operating these solar and microhydro systems creates an ongoing maintenance requirement alongside the initial equipment supply.
By Tower Type:
Monopole Scale and Concealed Siting OptionsMonopole towers represented a 46.19% Indonesia telecom towers market share in 2026. In 2025, contractor PT Binatel Prima reported work on new monopole tower projects for client MULTILAB in Papua, Sumatra, Bali, and Kalimantan. For the largest segment, these assignments show the format participating in geographically separate project pipelines. A contractor serving those locations can organize around the same structural category while handling each project’s site-specific execution requirements. For contractors, these assignments connect monopole expertise to repeat business with one client across separate projects.
Stealth / concealed towers are forecast to be the fastest-growing segment, at a CAGR of 10.4% over 2027-2032. Pekalongan City’s 2025 rules permit camouflage towers as lighting poles, mosque towers, or trees. Only lighting- or tree-shaped camouflage towers receive the stated exemption from the roadside-supervision-area siting restriction. For an operator seeking a host within that restricted area, a qualifying design creates a potential route to site access. In Pekalongan, selecting lighting- or tree-shaped concealment opens a roadside siting option that other camouflage forms do not receive.
Geography Analysis
The regional commercial picture combines established owner portfolios with publicly supported coverage sites, creating separate routes to infrastructure-service work across Java and the outer islands. In the first half of 2026, Mitratel operated 40,563 towers nationwide, with a majority located outside Java. In Sumatra, Komdigi’s 2025 public connectivity program for underserved, frontier, and outermost areas included 131 4G BTS and 135 on-air Universal Service Obligation BTS. For infrastructure suppliers, these footprints make service reach across separate operating areas commercially relevant, with tower owners and public coverage programs providing distinct potential routes to recurring site work.
East Kalimantan illustrates a capacity-led expansion opportunity in Kalimantan. In the first half of 2026, Indosat expanded network capacity in East Kalimantan’s Balikpapan, Samarinda, and Tenggarong as digital-service use increased. Across Kalimantan, its second-quarter 2026 data traffic grew 27.6% year over year, while its customer count increased 2.2%. Komdigi’s 2025 program for underserved, frontier, and outermost areas recorded 531 4G BTS and 74 on-air Universal Service Obligation BTS in Sulawesi. Serving these examples calls for distinct commercial offers, accommodating additional radio capacity for an expanding operator network and sustaining the usability of publicly supported coverage locations.
Bali-Nusa Tenggara combines seasonal network readiness with incremental village coverage, giving infrastructure demand different timing within the region. For Christmas 2025 and New Year 2026, Telkomsel prepared its Bali-Nusa Tenggara network with 241 5G BTS across 8 cities or regencies and 8 mobile BTS on standby. A standby approach can address temporary load without making permanent tower construction the only response to seasonal requirements. From early April 2025, Telkomsel activated BTS-based service in Sanleo and Uabau in Malaka Regency and Barang in Manggarai Regency, East Nusa Tenggara. The commercial distinction is between flexible capacity for an existing regional network and sustained site support for newly connected villages, which creates different deployment and servicing requirements.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of a tower owner leasing usable infrastructure to mobile operators. Indonesia’s national framework requires owners of usable passive infrastructure to offer fair, reasonable, nondiscriminatory access while maintaining service continuity.[2] Jakarta adds shared-load design and cell-plan siting requirements, placing construction readiness alongside access terms in the owner’s commercial decision.
Regulatory Table of Indonesia Telecom Towers Market
| Decision factor | Indonesia | DKI Jakarta |
|---|---|---|
| Primary authority | Ministry of Communication and Digital Affairs | Jakarta communications department for tower-zone recommendations |
| Key instruments or direction | Government Regulation No. 46 of 2021; September 2026 mobile-broadband draft, proposed | Regulation No. 14 of 2014, in force; Secretary Decree No. 57 of 2026 establishing a draft-discussion team |
| Commercial effect | Usable passive infrastructure must offer fair, nondiscriminatory access with service continuity; use prices must be fair and cost-based | New towers must structurally support at least 2 operators, subject to shared-tower load capacity; a cell-plan recommendation valid for up to 30 days precedes the building-permit application |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
The national Medium and No change judgments reflect the continuing access framework and fair, cost-based pricing obligations. Komdigi’s September 2026 draft proposed minimum-spacing exemptions between microwave-link radio stations in yellow and red zones, a consultation-stage easement that does not amend tower-site permits or change those owner obligations. Jakarta’s Medium rating balances shared hosting against design and zoning requirements, while its 2026 program called the 2014 rule outdated and targeted replacement for the third quarter of 2026. A June 5, 2026 decree formed a discussion team, but no adopted replacement has been published, leaving the 2014 duties operative and supporting No change.
Value Chain Stages
The value chain compares project-service earnings with recurring tower-access and maintenance revenue. In 2025, PT Gihon Telekomunikasi Indonesia Tbk provided tower-leasing services to mobile operators through long-term agreements lasting up to 10 years.[3] Lessors such as Gihon earn over the lease period, while acquisition and construction contractors capture fees from delivering each project.
Value Chain Analysis Table of Indonesia Telecom Towers Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Site acquisition | Site-acquisition contractors such as PT Kanayama Sukses Abadi | Site-acquisition service fees | Unresolved site rights and access | Clear site rights before committing construction resources |
| Tower construction and power installation | Tower builders such as PT Datatel Indonesia; power installers such as PT Kanayama Sukses Abadi and PT Terex | Construction and power-installation fees | Mitratel’s reported 2025 Bali-Nusra material-logistics cost and timing burden | Coordinate shipments and regional staging before mobilizing site crews |
| Site hosting and leasing | Tower lessors such as PT Gihon Telekomunikasi Indonesia Tbk | Tower-access lease revenue | Tenant commitment before site returns accrue | Align site development with contracted hosting demand |
| Operations and maintenance | Maintenance contractors such as PT Kanayama Sukses Abadi and PT Terex | Maintenance and power-system service fees | Coordinating repairs across tower and power equipment | Coordinate power-system and tower maintenance visits |
| Source: Mordor Intelligence | ||||
In December 2025, Mitratel’s deployment manager described material logistics as a construction constraint in Bali-Nusa Tenggara, especially East Nusa Tenggara. Materials had to be brought from Jakarta, making logistics costlier and construction longer than in other areas. Coordinating material staging with site readiness can address the risk of mobilizing crews before the necessary components arrive. Service work can then outlast the construction assignment, connecting local field capabilities with the owner’s longer lease economics.
Competitive Landscape
Market Concentration
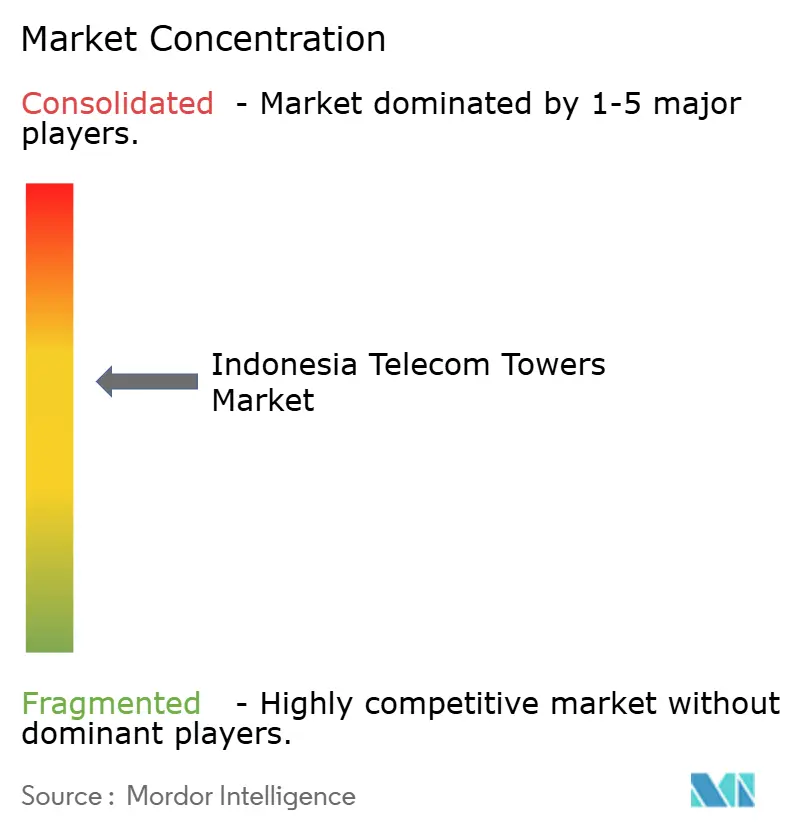
Large portfolios anchor competition, with Telkom reporting approximately 40,230 towers owned by PT Dayamitra Telekomunikasi Tbk (Mitratel) at December 31, 2025. PT Profesional Telekomunikasi Indonesia (Protelindo) is the principal tower-operating subsidiary of PT Sarana Menara Nusantara Tbk, which reported approximately 36,000 towers for the group at December 31, 2025, while PT Tower Bersama Infrastructure Tbk (TBIG) had 24,212 towers at year-end 2025. PT Centratama Menara Indonesia (EdgePoint) and PT Bali Towerindo Sentra Tbk also participate, the latter operating and leasing towers and facilities directly or through subsidiaries in 2025. On May 26, 2026, PT Centratama Telekomunikasi Indonesia Tbk, a subsidiary of EdgePoint Infrastructure, reported portfolio growth from approximately 4,600 to more than 11,000 sites nationwide during its outgoing leaders’ tenure. For operators needing several locations, those extensive estates make matching network requirements within one lessor’s portfolio a practical alternative to separate site negotiations.
In 2025, TBIG added 1,280 gross tenancies, comprising 797 telecommunications sites and 483 colocations, showing both new-site and shared-site activity. Some expiring tenancies were not renewed after the XL Axiata-Smartfren merger that created XLSMART, lowering net tenancy additions for that year. On July 1, 2026, Mitratel merged wholly owned PT Persada Sokka Tama, a tower lessor, and PT Ultra Mandiri Telekomunikasi, an infrastructure-service provider, into itself, taking over their assets, liabilities, rights, obligations, and business activities. Operators using those transferred services can address tower leasing and infrastructure-service obligations through Mitratel as one successor counterparty.
Competitive direction favors providers that can turn estate size into technically usable access for an operator at a required location. In Jakarta, Governor Regulation 14 of 2014 requires providers and managers to disclose technical suitability and available capacity transparently. It also requires priority by the order of requests submitted to the relevant agency, reporting of tower use and backbone-network details, and observance of competition law. Jakarta’s 2026 program called the 2014 rule outdated and targeted a replacement for the third quarter of 2026, but no adopted replacement has been published. Under the operative duties, transparent capacity and request order make usable space at the required location a basis for competition among providers of any size.
Indonesia Telecom Towers Industry Leaders
-
PT Dayamitra Telekomunikasi Tbk (Mitratel)
-
PT Profesional Telekomunikasi Indonesia (Protelindo)
-
PT Tower Bersama Infrastructure Tbk (TBIG)
-
PT Centratama Menara Indonesia (EdgePoint)
-
PT Bali Towerindo Sentra Tbk
- *Disclaimer: Major Players sorted in no particular order
Indonesia Telecom Towers Market Companies Covered in this Report
- PT Dayamitra Telekomunikasi Tbk (Mitratel)
- PT Profesional Telekomunikasi Indonesia (Protelindo)
- PT Tower Bersama Infrastructure Tbk (TBIG)
- PT Centratama Menara Indonesia (EdgePoint)
- PT Bali Towerindo Sentra Tbk
- EDOTCO Indonesia (EDOTCO Group Sdn Bhd)
- Gihon Telekomunikasi Indonesia
- PT Inti Bangun Sejahtera, Tbk (IBST)
- PT Solusi Tunas Pratama Tbk (STP)
- PT Telekomunikasi Selular (Telkomsel)
- PT Indosat Ooredoo Hutchison Tbk
- PT XLSMART Telecom Sejahtera Tbk (XLSMART)
- PT XLSMART Telecom Sejahtera Tbk
Key Opportunities for Market Participants
The opportunities compare ways tower providers can convert underserved-location commitments into site-access and infrastructure-service revenue. Under the July 2026 spectrum selection, Komdigi required the winning operators to provide 4G service in 538 villages and urban wards with no or weak signal, from Sumatra to Papua. That obligation supports different commercial responses depending on whether a location needs a new host, signal infill, or improvements to a usable site.
Market Opportunities Table of Indonesia Telecom Towers Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Shared sites for uncovered settlements | Unserved settlements fall within the coverage obligation | Spectrum-winning MNOs | Secure an anchor tenancy for a ground-based site where no suitable host exists | Operator commitment before construction | Independent TowerCos |
| Site access for weak-signal infill | Weak-signal villages and urban wards also qualify | MNOs improving service in obligated locations | Offer rooftop hosting or colocation where it meets the required coverage need | A usable location within the operator’s radio design | Rooftop lessors and existing tower owners |
| Tower-site readiness services | Coverage commitments require serviceable network locations | Tower owners serving the winning MNOs | Package necessary structural, power, and commissioning work around a defined site | Site-specific retrofit scope and acceptance | Tower construction and maintenance contractors |
| Source: Mordor Intelligence | |||||
The central opening is to connect a defined coverage gap with a location that an operator will actually use. Weak-signal communities already receive some coverage, creating a potential case for improving an existing host if its location and capacity fit the required service. Where that fit exists, leasing and upgrading the host can address the gap without first developing another site.
Recent Industry Developments in Indonesia Telecom Towers Market
- Jul 2026: Komdigi finalized Indonesia’s 700 MHz and 2.6 GHz spectrum selection on July 21, naming XLSMART, Telkomsel, and Indosat as winners. The operators must provide 4G service in 538 selected villages and urban wards with no or weak signal and 5G coverage reaching at least 51% of the national population by year five.
- Jul 2026: Mitratel merged its wholly owned subsidiaries PT Persada Sokka Tama, a tower lessor, and PT Ultra Mandiri Telekomunikasi, a telecommunications-infrastructure service provider, into itself effective July 1. Their assets, liabilities, rights, obligations, and business activities transferred to Mitratel as the surviving entity.
Indonesia Telecom Towers Market Report Scope and Research Methodology
Market Definition and Coverage
The Indonesia telecom towers market measures annual spending in Indonesia on telecom tower sites and tower-related infrastructure services that support radio communications. It covers sites equipped to host telecommunications antennas across the ownership, installation, power-source, and structural forms used in the market.
Scope exclusions: Fiber infrastructure and fiber services, small-cell systems and services, active radio access network equipment sold separately, and mobile connectivity services sold to subscribers are excluded.
Segments Covered in This Report
- By Ownership
- Operator-owned
- Independent TowerCo
- Joint-Venture TowerCo
- MNO Captive
- By Installation
- Rooftop
- Ground-based
- By Fuel Type
- Renewable-powered
- Grid/Diesel Hybrid
- By Tower Type
- Monopole
- Lattice
- Guyed
- Stealth / Concealed
Data Sources, Market Sizing, and Validation
Desk Research
Komdigi spectrum-award notices describe operator coverage obligations and village commitments, while World Bank Indonesia indicators provide economic context for demand scenarios. PEFINDO's Telco Tower Industry Outlook and Protelindo's investor presentation provide tower-company evidence on tenancy, portfolios, consolidation, and fiber activity, such as inputs for distinguishing site access from adjacent infrastructure services.
Company annual reports, regulatory filings, investor materials, exchange disclosures, and reputable Indonesian business reporting provide cross-checks on tower portfolios, lease revenue, capital spending, debt, site additions, and asset transfers. These named sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Primary research would seek perspectives from Indonesian tower owners, infrastructure service providers, mobile network operators, and relevant site, engineering, and finance specialists. Interviews would test secondary findings on site counts, tenancy, lease terms, deployment constraints, and service revenue, while clarifying differences in definitions and timing. Where records remain incomplete, analysts would compare independent company, regulatory, and market indicators and document the remaining gap before selecting the estimate or forecast assumption.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 25% | CXOs: 15% | |
| Mid tier: 55% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 50% |
Market-Sizing & Forecasting
The analyst estimates Indonesia's annual market value from a top-down view of operator demand and tower-service revenue, then checks the result selectively against tower-company revenue roll-ups and sampled site-fee times occupied tenancy. Site counts, tenants per site, lease rates, and service revenue per site indicate how network additions and colocation affect the value pool. Spectrum rollout commitments, rural coverage programs, and operator capital spending inform the pace of demand. Installation, ownership, power configuration, and tower structure shares are built from disclosed portfolios, site additions, leasing activity, and available company mix data, with unmatched records assigned only after checking their site and service definitions. A multivariate regression can relate the historical revenue series to these demand and operating indicators, with scenario analysis used where rollout timing or integration changes make the historical relationship unstable. Value and installed-site volume are forecast separately, with the gap between them reflecting changes in occupancy and revenue mix rather than assuming equal growth. Primary experts can test the direction and feasibility of variable-level forecasts. For selective bottom-up checks, analysts reconcile company disclosures and sampled site-fee-times-tenancy estimates to the national total, then bound missing observations using comparable disclosed operators and documented historical ranges.
Data Validation & Update Cycle
Analysts triangulate company disclosures, regulatory and public statistics, investor materials, and primary input, comparing independent signals for site additions, tenancy, revenue, and coverage obligations. They investigate anomalies and material variances against prior periods and related indicators, trace them to source definitions or timing, and resolve them through a second source or targeted re-contact before sign-off. The model is refreshed annually, revisited between cycles when spectrum awards, mergers, major asset transfers, or regulatory changes materially alter demand, and checked again in a fresh pre-delivery review.
Mordor Intelligence's Indonesia Telecom Towers Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Indonesia telecom towers market measures annual spending in Indonesia on telecom tower sites and tower-related infrastructure services that support radio communications.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. A multivariate regression can relate the historical revenue series to these demand and operating indicators, with scenario analysis used where rollout timing or integration changes make the historical relationship unstable.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | Value: USD 1.95 B (2027) / Volume: 116.4 thousand units (2027) | |
| Market Research Publisher A | USD 167 M (2025) | Its two-year-earlier measurement year can contribute to the lower value. |
| Market Research Publisher B | USD 3.8 B (2025) | Its inclusion of small cells and in-building solutions broadens the counted infrastructure categories. |
Mordor Intelligence's analysts triangulate company disclosures, regulatory and public statistics, investor materials, and primary input, comparing independent signals for site additions, tenancy, revenue, and coverage obligations.
Key Questions Answered in the Report
What is the Indonesia telecom towers market size and growth outlook?
Value is forecast at USD 1.95 billion in 2027 and USD 2.41 billion by 2032, growing at a CAGR of 4.36% over 2027-2032.
What supports demand for telecom tower services in Indonesia?
Komdigi’s 2026 spectrum awards carry coverage obligations. BAKTI had built 5,514 4G BTS, all reported on air in remote areas by June 5, 2026.
Which ownership model leads Indonesian tower services?
Independent TowerCos held 53.53% of tower-market revenue in 2026 and were the largest ownership segment.
Which companies compete for Indonesian tower-hosting business?
Major participants include PT Dayamitra Telekomunikasi Tbk (Mitratel), PT Profesional Telekomunikasi Indonesia (Protelindo), PT Tower Bersama Infrastructure Tbk (TBIG), PT Centratama Menara Indonesia (EdgePoint), and PT Bali Towerindo Sentra Tbk.
What is a key earnings challenge for Indonesian tower lessors?
Lease repricing pressures returns. PT Sarana Menara Nusantara Tbk’s effective monthly lease rate per XL Axiata (EXCL) tenancy was 7.5% below its FY2025 level in the first quarter of 2026.
How does tower-service demand differ across Indonesian regions?
East Kalimantan saw Indosat capacity expansion in the first half of 2026, while East Nusa Tenggara had Telkomsel village-service activations from early April 2025.