
India Energy Drinks Market Analysis by Mordor Intelligence
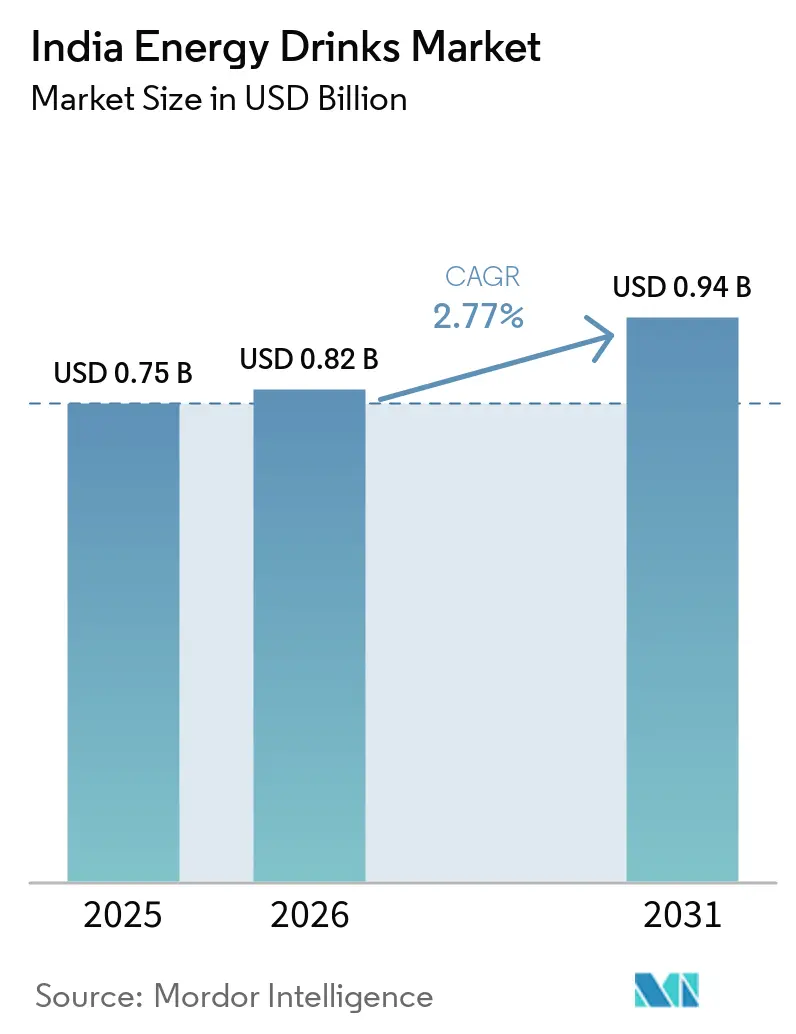
The India energy drinks market size is expected to increase from USD 0.82 billion in 2026 to USD 0.84 billion in 2027 and reach USD 0.98 billion by 2032, growing at a CAGR of 3.15% over 2027-2032.
In India, recurring work and adult gaming occasions create room for convenient ready-to-drink servings and differentiated price propositions. Chilled access can widen those occasions, while botanical formulations give suppliers another way to distinguish the drink itself. The Food Safety and Standards Authority of India (FSSAI) began labeling enforcement in India in July 2026 to remove the energy-drink descriptor, and package wording becomes a commercial constraint. Suppliers are adding price-tiered portfolios, and expansion depends on whether serving convenience and formulation choice can carry a caffeine proposition through the labeling dispute over the energy-drink descriptor.
Key Report Takeaways
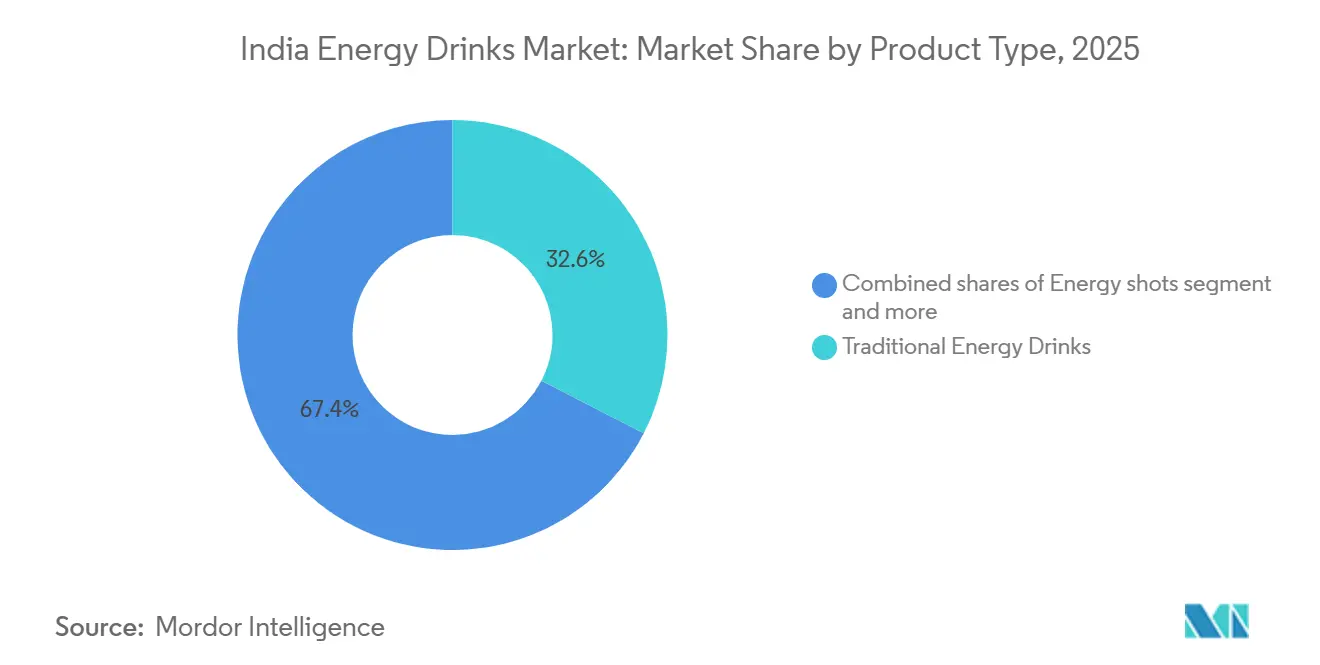
- By product type, traditional energy drinks held a 32.3% India energy drinks market share in 2026, while natural/organic energy drinks are forecast to grow fastest at a CAGR of 4.4% over 2027-2032.
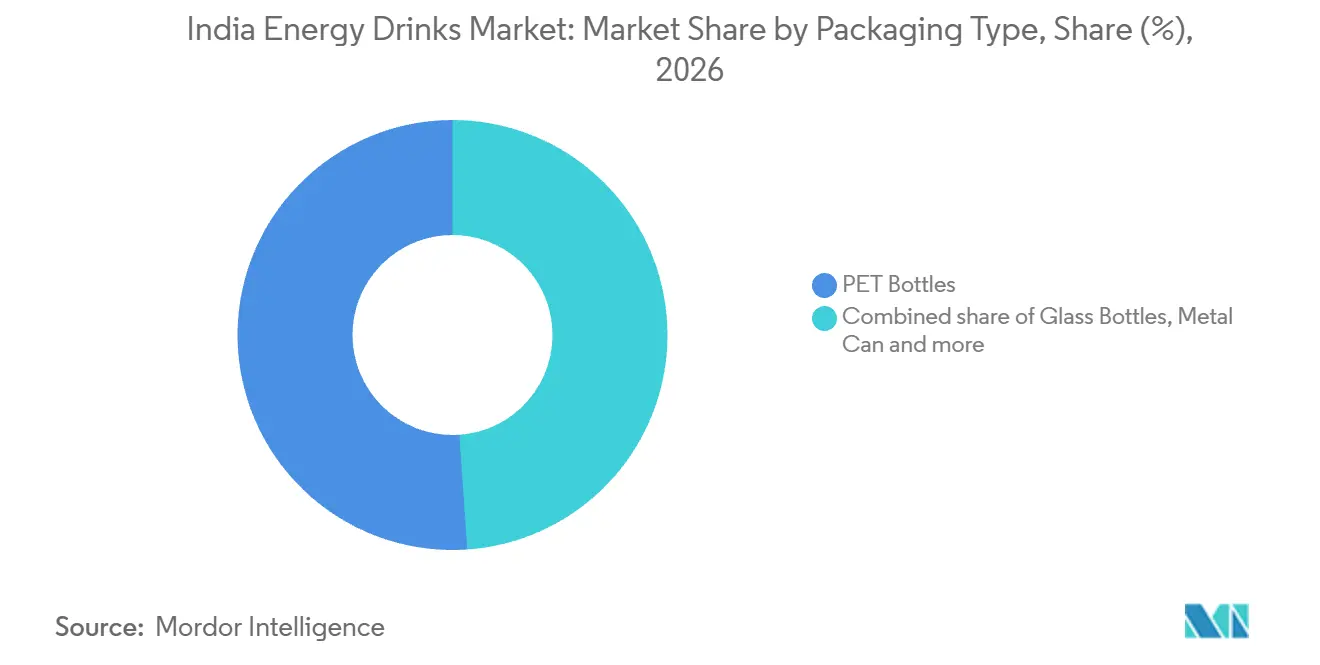
- In packaging, PET bottles held a 51.1% share of the India energy drinks market size in 2026, and glass bottles are forecast to be the fastest-growing segment at a CAGR of 4.05% over 2027-2032.
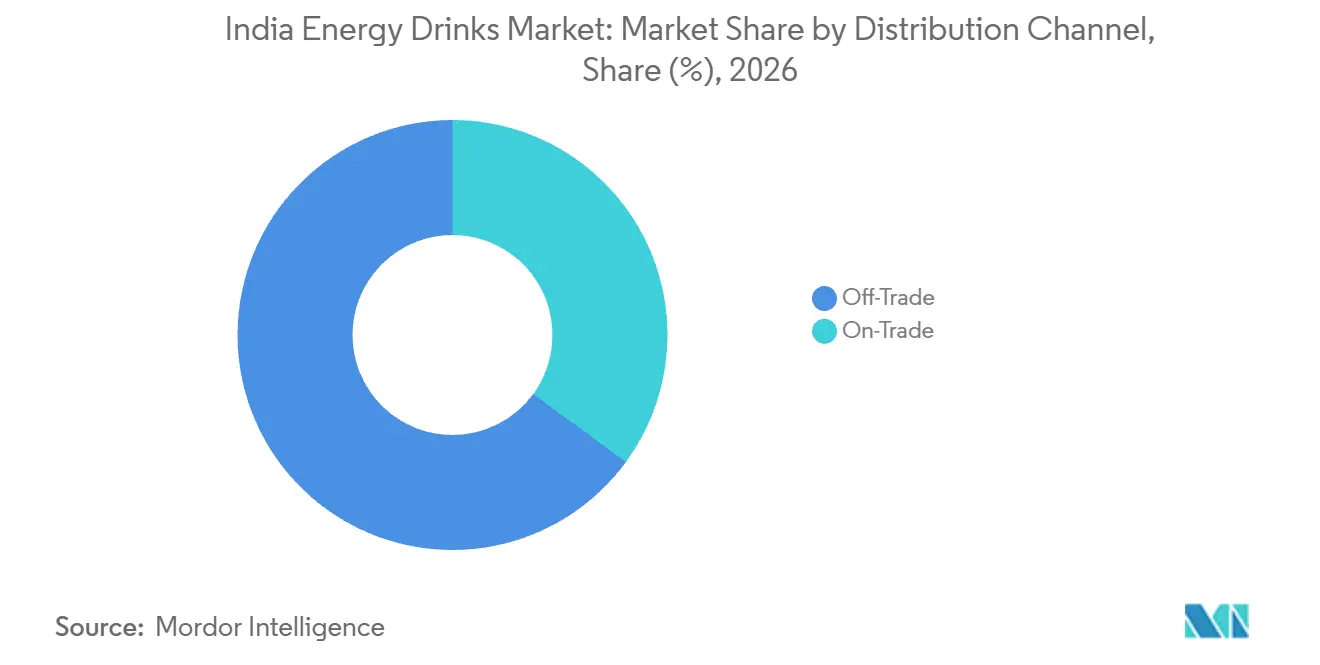
- Across distribution channels, off-trade accounted for 64.94% of market revenue in 2026, whereas on-trade is forecast to grow fastest at a CAGR of 4.45% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of India Energy Drinks Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising on-the-go workforce and demand for convenient energy options | +1.4% | Nationwide | Medium term (2-4 years) |
| Expanding fitness and sports participation culture | +1.2% | Nationwide | Medium term (2-4 years) |
| Surge in e-sports and gaming boosting caffeine beverages | +0.9% | Nationwide | Short term (≤ 2 years) |
| Cold-chain reach in Tier-2/3 cities enabling chilled RTD formats | +0.8% | Nationwide | Medium term (2-4 years) |
| Shift to natural, sugar-free, and functional variants | +0.5% | Nationwide | Medium term (2-4 years) |
| Rapid urbanization and rising disposable incomes among working professionals | +0.4% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising on-the-go workforce and demand for convenient energy options
A larger mobile workforce creates more occasions for energy drinks that require little preparation or interruption to work. India's gig workforce, including delivery, ridesharing, and freelancing, grew 55% to 12 million workers from FY2021 to FY2025.[1] In FY2025-26, Tata Consumer Products Ltd re-entered India's caffeine energy segment with Zip Zap, a still-based, noncarbonated energy drink in a cup format. Serving convenience gives suppliers a practical way to reach workers who travel between tasks, without relying on a performance claim alone. The still, noncarbonated format opens another way to compete for mobile work occasions, allowing a caffeine beverage to differ in both carbonation and container.
Expanding fitness and sports participation culture
Organized adult fitness participation gives energy-drink suppliers an audience whose consumption occasions can extend beyond commuting and desk work. India's 89th Fit India Sundays on Cycle edition brought together more than 5 million young people across over 25,000 locations on September 6, 2026, promoting a drug-free youth message and illustrating organized recreation's scale. At the January 18, 2026 Tata Mumbai Marathon, 70,065 participants took part, 60% of them aged 25 to 44. The marathon's adult age profile supplies a distinct audience for energy-drink servings around recreation, extending potential demand beyond work-related convenience.
Surge in e-sports and gaming boosting caffeine beverages
Frequent adult gaming creates a potential recurring occasion for energy beverages beyond the physical activity settings associated with the category. The Trade Desk Intelligence and PA Consulting surveyed 2,000 Indian adults aged 18 or older from January to March 2025. Among those respondents, 74% played games weekly and 51% played daily. In January 2025, Monster Energy became the official energy drink partner of iQOO SOUL, S8UL's Battlegrounds Mobile India division. The sponsorship linked an energy-drink brand to organized play, while the survey's weekly and daily rates suggest opportunities across ordinary gaming sessions.
Cold-chain reach in Tier-2/3 cities enabling chilled RTD formats
Chilled availability can expand an energy drink's selling occasion only when the supplier can connect distribution with refrigeration near the consumer. In its 2025 annual report, Varun Beverages Ltd said electrification improvements and investment in chilling infrastructure, including visi-coolers, were improving chilled-beverage access in underserved Indian markets. Its account linked those developments to more consistent beverage consumption over time. In underserved markets, this makes outlet chilling a complement to shipping finished products, because distribution reach alone does not establish chilled availability. As a PepsiCo bottler and distributor, Varun Beverages reports chilling investment downstream of production, which ties chilled availability to the cooler base at outlets as well as to supply.
Restraints Impact Analysis of India Energy Drinks Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Health concerns over high caffeine, sugar, and artificial additives | -0.8% | Nationwide | Long term (≥ 4 years) |
| Stringent regulations on labeling and caffeine limits, alongside self-regulatory safeguards for advertising to children | -0.7% | Nationwide | Short term (≤ 2 years) |
| Raw-material price spikes for botanicals and vitamins | -0.3% | Nationwide | Short term (≤ 2 years) |
| Rise of alternative functional beverages like kombucha or nootropics | -0.2% | Southern regions of India | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Health concerns over high caffeine, sugar, and artificial additives
Caffeine-related health concerns limit how broadly suppliers can position an energy drink as an everyday refreshment. Medical guidance reported in India in July 2026 advised children and adolescents to avoid caffeinated energy drinks because of greater susceptibility to stimulant-related adverse effects. The advice creates a boundary around youth-oriented recruitment and makes a general refreshment message harder to reconcile with the product's stimulant character. In June 2026, HELL Energy launched its zero-sugar HELL ZERO range in India, providing a product option that addresses sugar content. Removing sugar leaves the caffeine-related barrier for younger consumers in place, limiting the audience that such reformulation can responsibly unlock.
Stringent regulations on labeling and caffeine limits, alongside self-regulatory safeguards for advertising to children
India's energy-drink labeling enforcement began on July 2, 2026, when FSSAI directed removal of the energy-drink descriptor. By July 30, distributors were refusing existing stocks, contributing to reported retail shortages across dozens of brands. Separately, the caffeinated-beverage standard sets total caffeine from all sources at 145 to 300 mg/L, constraining formulation choices. The self-regulatory Code of the Advertising Standards Council of India (ASCI) also bars child-addressed advertisements that could cause harm or exploit children's vulnerability, limiting how brands can address that audience. Court orders since then have given company-specific, interim relief, and the Delhi High Court has not decided the merits of FSSAI's labeling position. For suppliers and distributors, the commercial burden is coordinating compliant packaging and stock acceptance when a labeling transition interrupts the route to retail.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
India Energy Drinks Market Segment Analysis
By Product Type:
Traditional Drinks Anchor Demand as Botanical Propositions DiversifyTraditional energy drinks accounted for a 32.3% share of the India energy drinks market size in 2026. Varun Beverages Ltd introduced Sting Classic in PET bottles in April 2026 and also launched the product in cans. In its May 2026 earnings call, the bottler reported favorable early performance for the PepsiCo product. A traditional offering can therefore compete through product renewal within the same product type, without requiring a different botanical or ingredient proposition to define the offer. In the same call, Varun's chairman reported demand above expectations while discussing the Sting Classic launch.
Natural/organic energy drinks are the fastest-growing segment, with a projected CAGR of 4.4% over 2027-2032. In March 2025, SAGE founder Archana Nagar reported cultivating hibiscus sabdariffa on about 25 acres in Harda and operating a small production unit for a flower-based energy drink. In that example, the product identity connects a distinctive botanical ingredient with its cultivation and production. For a supplier pursuing this model, scaling the proposition means connecting the agricultural and beverage operations while preserving the intended formulation. With about 25 acres and a small production unit in March 2025, this example had a modest supply base, so replicating its flower-based model requires other producers to secure comparable botanical supply.



By Packaging Type:
PET Supports Scale While Glass Requires a Distinct Serving RolePET bottles represented a 51.1% India energy drinks market share in 2026. Separately, HELL Energy reported that PET bottles generated 85% of its India energy-drink revenue in Q1 FY26. The brand-level revenue mix illustrates a supplier whose India energy-drink revenue in the reported quarter depended heavily on this format, so bottle execution is a core part of its product offer. Renewing the PET offer addresses this supplier's principal revenue base, while an additional package serves a narrower commercial role.
Glass bottles are the fastest-growing segment, with a projected CAGR of 4.05% over 2027-2032. In India's alcoholic-beverage industry, United Spirits Limited reported buying, cleaning, and reusing empty glass bottles through its return system in FY2025-26. United Spirits linked that return loop to raw-material conservation and stronger local vendor networks. In this alcoholic-beverage model, glass procurement extends beyond new-container supply to the recovery and preparation of bottles for reuse.

By Distribution Channel:
Retail Reach and Hospitality Serve Different Consumption OccasionsOff-trade was the largest segment, accounting for 64.94% of market revenue in 2026. Across its broader beverage business, Varun Beverages reported reaching 4 million FMCG outlets in India in February 2025. An integrated supplier can use such a footprint to offer energy drinks through established retail routes alongside its broader beverage portfolio. Retail reach creates an entry route for energy drinks, but the brand must secure the shopper's choice without a hospitality setting to frame immediate consumption.
On-trade is the fastest-growing segment, with a projected CAGR of 4.45% over 2027-2032. Red Bull India's sales organization serves on-premise hospitality venues, where its cans are consumed immediately. That arrangement connects the drink to a service occasion, where the venue helps present the choice at the point of consumption. For a supplier, developing this channel means building relationships around the way the product is served, as well as ensuring that it reaches the premises.
Geography Analysis
Zepto's 2025 year-end data recorded 784,637 liters of energy drinks consumed in Mumbai through its platform, providing a city-specific quick-commerce example.[2] In April 2025, New Products' Non Stop energy drinks, imported from Dubai, were reported available in Delhi NCR, Mumbai, and Pune. These examples point to different commercial routes within urban India, with a delivery platform recording consumption and an imported brand establishing access across several cities. A platform's recorded volume and an importer's multi-city availability call for different routes to the consumer and different local partners.
In May 2026, 28 BLACK's importer Yinbev announced a Blinkit launch for Mumbai and Hyderabad. The announcement said consumers in those cities could order the imported German energy drink chilled for rapid delivery. Rapid chilled delivery lets an imported brand reach immediate consumption, which shelf placement alone does not provide. It also makes the delivery proposition part of the product's local appeal, rather than treating import status as a sufficient reason to buy. Expansion through this route depends on sustaining the connection between local fulfillment and a chilled serving, so execution within each city matters more than the nominal breadth of a national launch.
Bengaluru provides a different distribution example, with ARB Group distributing Red Bull in Bengaluru and Karnataka. ARB Group's broader business handles a portfolio of Indian and international consumer-goods brands, placing the energy drink within a mixed-category intermediary. A mixed-category intermediary can give the energy-drink brand access to established local account relationships, reducing the need to build each connection directly. The corresponding commercial challenge is securing attention for an energy-drink proposition within a portfolio serving several consumer categories.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of suppliers selling compliant finished energy drinks in India. FSSAI's April 2024 clarification permitted the energy-drink term only for licensed products in specified carbonated or noncarbonated water-based flavored-drink categories standardized as caffeinated beverages. Maharashtra's Food and Drug Administration implements the national food-safety framework within the state, so local enforcement forms part of the same route to market.
Regulatory Table of India Energy Drinks Market
| Decision factor | India national regime | Maharashtra |
|---|---|---|
| Primary authority | Food Safety and Standards Authority of India | Food and Drug Administration, Maharashtra |
| Key instruments or direction | Product-category and licensing clarification for the energy-drink term | National Food Safety and Standards Act, Rules, and FSSAI regulations implemented in the state |
| Commercial effect | Label positioning must fit the specified licensed caffeinated-beverage categories | Suppliers face state implementation of the national framework |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
India's Medium rating reflects the defined classification route and labeling condition in FSSAI's operative 2024 clarification. The Delhi High Court's October 2026 stays for PepsiCo India, Monster Energy India, and Reliance Consumer Products, pending further hearing, permitted PepsiCo and Monster existing stock sales but no further manufacture using the descriptor. July's 90-day relabeling directive, the November 5, 2026 hearing, and possible FSSAI reconsideration of Red Bull concern enforcement of the unchanged clarification, supporting No change for suppliers' classification duties despite contested production labels. Maharashtra receives the same rating and direction because it implements the national framework, leaving suppliers responsible for category compliance and state administration.
Value Chain Stages
The value chain compares where ingredient suppliers, manufacturers, and distribution organizations earn revenue from bringing energy drinks to Indian consumers. Oasis Beverages Private Limited manufactures flavor-emulsion concentrates near Noida for energy drinks alongside carbonated soft drinks and juice-based drinks. Varun Beverages Ltd commissioned 4 greenfield production facilities in India in 2025, illustrating how an integrated beverage producer can expand its operating base across locations.
Value Chain Analysis Table of India Energy Drinks Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Concentrate supply | Beverage-concentrate manufacturers such as Oasis Beverages Private Limited | Concentrate sales | Reproducing the intended flavor across production batches | Qualify formulations and retain batch specifications |
| Beverage manufacturing | Energy-drink contract manufacturers such as Biove Life Science | Bulk production and private-label manufacturing revenue | Matching brand specifications at the contracted production scale | Validate production runs before scaling orders |
| Distribution and channel sales | Integrated bottler-distributors such as Varun Beverages Ltd and beverage brands with general-trade networks such as Vold Energy Asia Pvt. Ltd. | Finished-beverage sales, including energy drinks within broader portfolios | Coordinating finished-product availability with downstream delivery | Align production and distribution schedules around outlet replenishment |
| Source: Mordor Intelligence | ||||
Contract manufacturing offers a route for a brand to obtain production without replicating a producer's entire operating base. Red Bull's India operations team coordinates localization, production, imports, storage, transportation, and delivery, showing the range of functions that must connect around a finished drink. Access to manufacturing therefore leaves a separate coordination task, and a new brand must assemble that integrated capability through its own organization or partners.
Competitive Landscape
Market Concentration
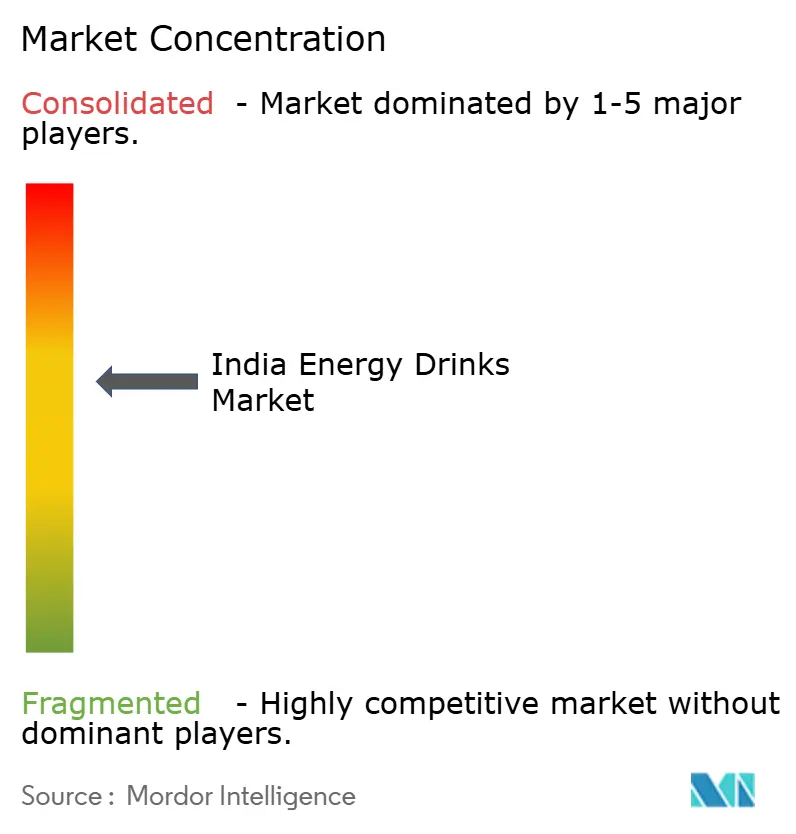
Competition centers on established multinational brand portfolios, while differentiated price tiers create room for distinct consumer propositions. Major suppliers include Red Bull GmbH, PepsiCo Inc. (Sting), Monster Beverage Corp., The Coca-Cola Co. (Thums Up Charged), and Anheuser-Busch InBev SA/NV (Budweiser Beats). A June 2026 report quoted a Monster executive describing Predator in India as about half the price of Monster, a lower-priced tier within its portfolio. Predator's lower tier sits within Monster's own portfolio, narrowing the space for outside challengers whose main selling point is a lower price.
PepsiCo's portfolio adds a second price position next to Sting. In June 2026, it announced the Indian launch of Adrenaline Rush as a mass-premium energy-drink brand priced above Sting. The Coca-Cola Co. offers Charged by Thums Up in cans and PET bottles in India, giving its product more than one package route to the consumer. For buyers, these approaches create choice across brand position and serving format.
Regulatory positioning can influence competitive continuity as directly as a new brand or price tier. On September 29, 2026, the Delhi High Court set aside FSSAI's direction ordering Red Bull India to stop using the energy-drink description.[3] The court left FSSAI free to decide again after giving Red Bull a hearing. Procedural relief and an enduring label position carry different commercial implications, so regulatory capability becomes part of sustaining a consumer-facing proposition.
India Energy Drinks Industry Leaders
-
Anheuser-Busch InBev SA/NV (Budweiser Beats)
-
Monster Beverage Corp.
-
PepsiCo Inc. (Sting)
-
Red Bull GmbH
-
The Coca-Cola Co. (Thums Up Charged)
- *Disclaimer: Major Players sorted in no particular order
India Energy Drinks Market Companies Covered in this Report
- Red Bull GmbH
- PepsiCo Inc. (Sting)
- Monster Beverage Corp.
- The Coca-Cola Co. (Thums Up Charged)
- Anheuser-Busch InBev SA/NV (Budweiser Beats)
- Goldwin Healthcare Pvt Ltd (Cloud 9)
- Hector Beverages Pvt Ltd (Tzinga)
- Ghodawat Consumer Ltd (Rider)
- Radiohead Brands Pvt Ltd (Hustle)
- Hell Energy Magyarország Kft.
- Tata Consumer Products Ltd (Himalayan Energy)
- Varun Beverages Ltd
- Bisleri International Pvt Ltd (Urzza)
- Power Horse Energy Drinks GmbH
- Taisho Pharmaceutical Co. Ltd (Lipovitan)
- Osotspa Co. Ltd (M-150)
- Ocean Drinks Pvt Ltd
- BPI Sports LLC
- Prime Hydration LLC
- Congo Brands (Predator)
Recent Industry Developments in India Energy Drinks Market
- Oct 2026: On October 12, the Delhi High Court declined PepsiCo's request to continue manufacturing beverages with the energy-drink label.
- Oct 2026: The Delhi High Court stayed FSSAI orders against PepsiCo India, Monster Energy India, and Reliance Consumer Products pending hearing, permitting PepsiCo and Monster existing stock sales but no further manufacture using the term.
- Sep 2026: On September 29, the Delhi High Court set aside FSSAI's direction ordering Red Bull India to stop using the energy-drink description, leaving FSSAI free to decide again after due process.
Scope and Methodology
Segmentation Overview
By Product Type
| Energy Shots |
| Natural/Organic Energy Drinks |
| Sugar-Free/Low-Calorie Energy Drinks |
| Traditional Energy Drinks |
| Other Energy Drinks |
By Packaging Type
| PET Bottles |
| Glass Bottles |
| Metal Can |
| Others |
By Distribution Channel
| On-Trade | |
| Off-Trade | Supermarket/Hypermarket |
| Convenience Stores | |
| Specialty Stores | |
| Online Retail | |
| Other Distribution Channels |
| By Product Type | Energy Shots | |
| Natural/Organic Energy Drinks | ||
| Sugar-Free/Low-Calorie Energy Drinks | ||
| Traditional Energy Drinks | ||
| Other Energy Drinks | ||
| By Packaging Type | PET Bottles | |
| Glass Bottles | ||
| Metal Can | ||
| Others | ||
| By Distribution Channel | On-Trade | |
| Off-Trade | Supermarket/Hypermarket | |
| Convenience Stores | ||
| Specialty Stores | ||
| Online Retail | ||
| Other Distribution Channels | ||
Market Definition
- Carbonated Soft Drinks (CSDs) - Carbonated soft drinks (CSDs) refer to non-alcoholic beverages that are carbonated and typically flavored, containing dissolved carbon dioxide to create effervescence. These beverages commonly include cola, lemon-lime, orange, and various fruit-flavored sodas. Marketed in cans, bottles, or fountain dispense.
- Juices - We have considered packaged juices which encompass non-alcoholic beverages derived from fruits, vegetables, or a combination thereof, processed and sealed in various packaging formats such as bottles, cartons, or pouches. Excluding fresh juices, this market segment involves commercially prepared and preserved juices, often with added preservatives and flavors.
- Ready-to-Drink (RTD) Tea and RTD Coffee - Ready-to-Drink (RTD) tea and RTD coffee are pre-packaged, non-alcoholic beverages that are brewed and prepared for consumption without further dilution. RTD tea typically includes various tea varieties, infused with flavors and sweeteners, and comes in bottles, cans, or cartons. Similarly, RTD coffee involves pre-brewed coffee formulations, often mixed with milk, sugar, or flavorings, and is conveniently packaged for on-the-go consumption.
- Energy Drinks - Energy drinks are non-alcoholic beverages formulated to provide a quick boost of energy and alertness. Whereas, sports drinks are beverages designed to hydrate and replenish electrolytes, particularly after physical exertion, exercise, or intense activity
| Keyword | Definition |
|---|---|
| Carbonated Soft Drinks | Carbonated soft drinks (CSDs) are a combination of carbonated water and flavouring, sweetened by sugar or a non-sugar sweeteners. |
| Standard Cola | Standard Cola is defined as the original flavor of cola soda. |
| Diet Cola | A cola-based soft drink containing no or low amounts of sugar |
| Fruit Flavored Carbonates | A carbonated beverage prepared from fruit juice/fruit flavor with carbonated water and containing sugar, dextrose, invert sugar or liquid glucose either singly or in combination. It may contain peel oil and fruit essences. |
| Juice | Juice is a drink made from the extraction or pressing of the natural liquid contained in fruit and vegetables. |
| 100% Juice | Fruit/vegetable juice made from fruit in the form of its juice with no water added to make up the volume. It is not permitted to add sugars, sweeteners, preservatives, flavourings or colourings to fruit juice. |
| Juice Drinks (up to 24% Juice) | Fruit/vegetable juice drinks with up to 24% fruits/vegetable extract. |
| Nectars (25-99% Juice) | Juices that can have between 25 and 99% of fruit, with the minimum legal limits defined depending on the type of fruit |
| Juice concentrates | Juice Concentrates are those form of juices when most of this liquid is removed resulting in a thick, syrupy product known as juice concentrate. |
| RTD Coffee | Packaged coffee beverages that are sold in a prepared form and are ready for consumption at the time of purchase. |
| Iced Coffee | An iced coffee is a cold version of coffee, usually a combination of hot espresso and milk with ice added to it. |
| Cold Brew Coffee | Cold brew also called cold water extraction or cold pressing is made by steeping ground coffee in room-temperature water for several hours. |
| RTD Tea | Ready-to-drink (RTD) tea is a packaged tea product ready for immediate consumption without brewing or preparation |
| Iced Tea | Ice tea or iced tea is a drink made from tea without milk but with sugar and sometimes fruit flavourings, drunk cold. |
| Green Tea | Green tea is a tea beverage which promotes mental alertness, relieving digestive symptoms and promoting weight loss. |
| Herbal Tea | Herbal tea beverages are made from the infusion or decoction of herbs, spices, or other plant material in hot water. |
| Energy Drink | A type of drink containing stimulant compounds, usually caffeine, which is marketed as providing mental and physical stimulation. They may or may not be carbonated and may also contain sugar, other sweeteners, or herbal extracts, among numerous possible ingredients. |
| Sugar-free or Low-calories Energy Drinks | Sugar-free or Low-calories Energy Drinks are sugar-free, artificially sweetened energy drinks with few or no calories. |
| Traditional Energy Drink | Traditional Energy Drinks are functional soft drinks containing ingredients designed to boost the consumer's energy. |
| Natural/Oraganic Energy Drinks | Natural/Organic energy drinks are energy drinks free of artificial sweeteners and synthetic colorings. Instead, they contain naturally derived ingredients such as green tea, yerba mate, and botanical extracts. |
| Energy Shots | A small but highly concentrated energy drink that contains large amounts of caffeine and/or other stimulants. The quantity is comparatively smaller compared to energy drinks. |
| Sports Drink | Sports drinks are beverages designed specifically for the rapid supply of fluid, carbohydrates, and electrolytes before, during or after exercise. |
| Isotonic | Isotonic drinks contain similar concentrations of salt and sugar as in the human body, and are designed to quickly replace fluids lost during exercise but with an increase of carbohydrate. |
| Hypertonic | Hypertonic drinks have a higher concentration of salt and sugar than the human body. They are best drunk after exercise as it is important to replace glycogen levels quickly after exercise. |
| Hypotonic | Hypotonic drinks are designed to quickly replace fluids lost during exercise. They have very low carbohydrate content and a lower concentration of salt and sugar than the human body. |
| Electrolyte-Enhanced Water | Electrolyte water is water infused with electrically-charged minerals, such as sodium, potassium, calcium, and magnesium. |
| Protein-based Sport Drinks | Protein-based sports drinks are those sports drinks which has added protein in it that will improve performance and reduce muscle protein breakdown. |
| On-Trade | The on-trade refers to places that sell beverages for immediate consumption on the premises like bars, restaurants, and pubs |
| Off-Trade | Off-trade usually means places like liquor stores, supermarkets and other places where you don't consume the beverage right away. |
| Convenience Store | A retail business that provides the public with a convenient location to quickly purchase a wide variety of consumable products and services, generally food and gasoline. |
| Specialty store | A specialty store is a shop/store that carries a deep assortment of brands, styles, or models within a relatively narrow category of goods |
| Online Retail | Online retail is a type of eCommerce whereby a business sells goods or services directly to consumers from a website. |
| Aseptic Packaging | Aseptic packaging refers to the filling of a cold, commercially sterile product under sterile conditions into a presterilized container and closure under sterile conditions to form a seal that effectively excludes microorganisms. These includes tetra packs, cartons, pouches etc. |
| PET Bottle | PET bottle means a bottle made of polyethylene terephthalate. |
| Metal Cans | Metal containers made of aluminum or tin- plated or zinc-plated steel, which are commonly used for packaging food, beverages or other products. |
| Disposable Cups | Disposable Cup means a cup or other container designed for single use to serve beverages, such as water, cold drinks, hot drinks and alcoholic beverages. |
| Gen Z | A way of referring to the group of people who were born in the late 1990s and early 2000s. |
| Millenial | Anyone born between 1981 and 1996 (ages 23 to 38 in 2019) is considered a Millennial |
| Taurine | Taurine is an amino acid that supports immune health and nervous system function. |
| Bars & Pubs | It is a drinking establishment licensed to serve alcoholic drinks for consumption on the premises. |
| Café | It is a foodservice establishment serving refreshments (mainly coffee) and light meals. |
| On the go | It means doing / dealing with while busily engaged with something and not diverting plans in order to accommodate. |
| Internet Penetration | The Internet Penetration Rate corresponds to the percentage of the total population of a given country or region that uses the Internet. |
| Vending Machine | A machine that dispenses small articles such as food, drinks, or cigarettes when a coin or token is inserted |
| Discount store | A discount store or discounter offers a retail format in which products are sold at prices that are in principle lower than an actual or supposed "full retail price". Discounters rely on bulk purchasing and efficient distribution to keep down costs. |
| Clean Label | Clean label on the beverage market are drinks that are made from few ingredients of natural origin and are not or only slightly processed. |
| Caffeine | An alkaloid compound which is a stimulant of the central nervous system. It is mainly used recreationally, as a mild cognitive enhancer to increase alertness and attentional performance. |
| Extreme sport | Action sports, adventure sports or extreme sports are activities perceived as involving a high degree of risk. |
| High-intensity interval training | It incorporates several rounds that alternate between several minutes of high intensity movements to significantly increase the heart rate to at least 80% of one's maximum heart rate, followed by short periods of lower intensity movements. |
| Shelf life | The length of time for which an item remains usable, fit for consumption, or saleable. |
| Cream Soda | Cream soda is a sweet soft drink. Generally flavored with vanilla and based on the taste of an ice cream float |
| Root Beer | Root beer is a sweet North American soft drink traditionally made using the root bark of the sassafras tree Sassafras albidum or the vine of Smilax ornata as the primary flavor. Root beer is typically, but not exclusively, non-alcoholic, caffeine-free, sweet, and carbonated. |
| Vanilla Soda | A carbonated soft drink flavoured with vanilla. |
| Dairy-Free | A product that does not contain any milk or milk products from cows, sheep or goats. |
| Caffeine-Free Energy Drinks | Caffeine-free energy drinks rely on other ingredients to boost the energy. Popular choices include amino acids, B vitamins, and electrolytes. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: IDENTIFY KEY VARIABLES: In order to build a robust forecasting methodology, the variables and factors identified in Step 1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set, and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period for each country.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated reports, custom consulting assignments, databases & subscription platforms


