
MEO Satellite Market Size and Share
Market Overview
| Study Period | 2020 - 2032 |
|---|---|
| Market Size (2027) | USD 13.41 Billion |
| Market Size (2032) | USD 41.03 Billion |
| Growth Rate (2027 - 2032) | 25.06 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
MEO Satellite Market Analysis by Mordor Intelligence
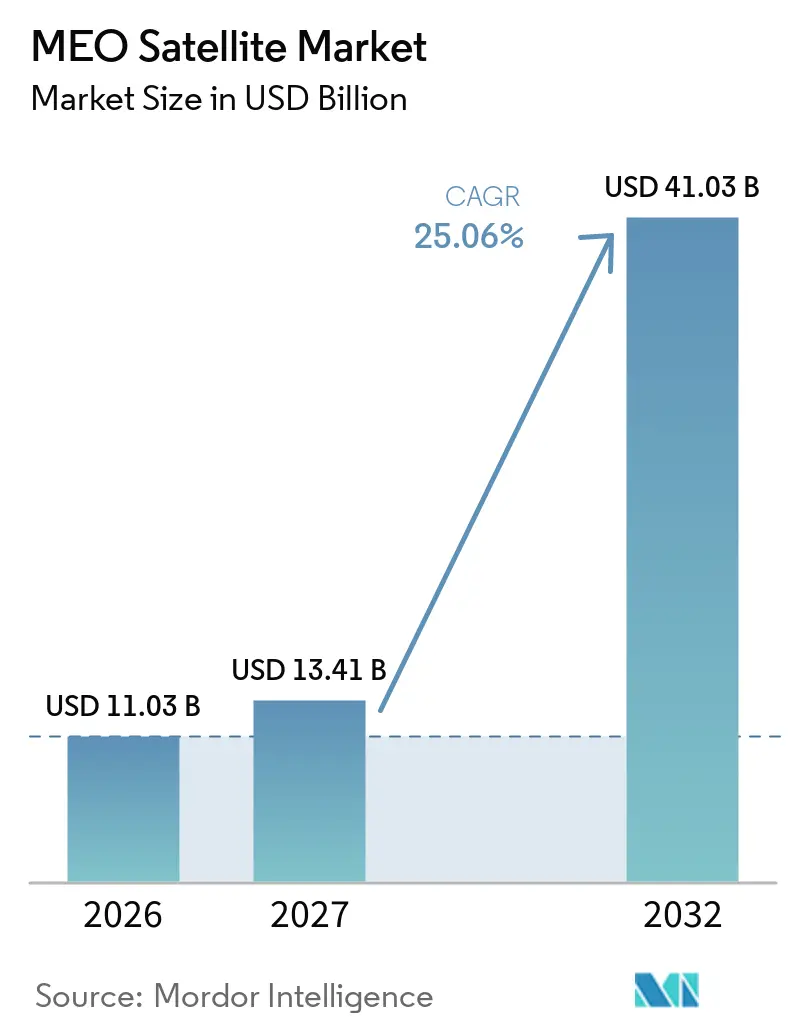
The MEO satellite market size was valued at USD 11.03 billion in 2026 and is forecast to grow from USD 13.41 billion in 2027 to reach USD 41.03 billion by 2032, growing at a 25.06% CAGR from 2027 to 2032. The MEO satellite market is supported by navigation upgrades, resilient defense networks, and broadband capacity for aviation, maritime, and remote enterprise customers. Governments are treating MEO capacity as part of sovereign communications and navigation infrastructure, which makes demand less dependent on commercial bandwidth cycles. Operators are also combining LEO, MEO, and GEO capacity to offer managed service coverage rather than a single-orbit product. The main commercial opportunity lies in applications that value consistent throughput, service guarantees, and wide-area coverage. Competitive pressure from LEO systems remains material because their latency profile is attractive for consumer and real-time applications.
Key Report Takeaways
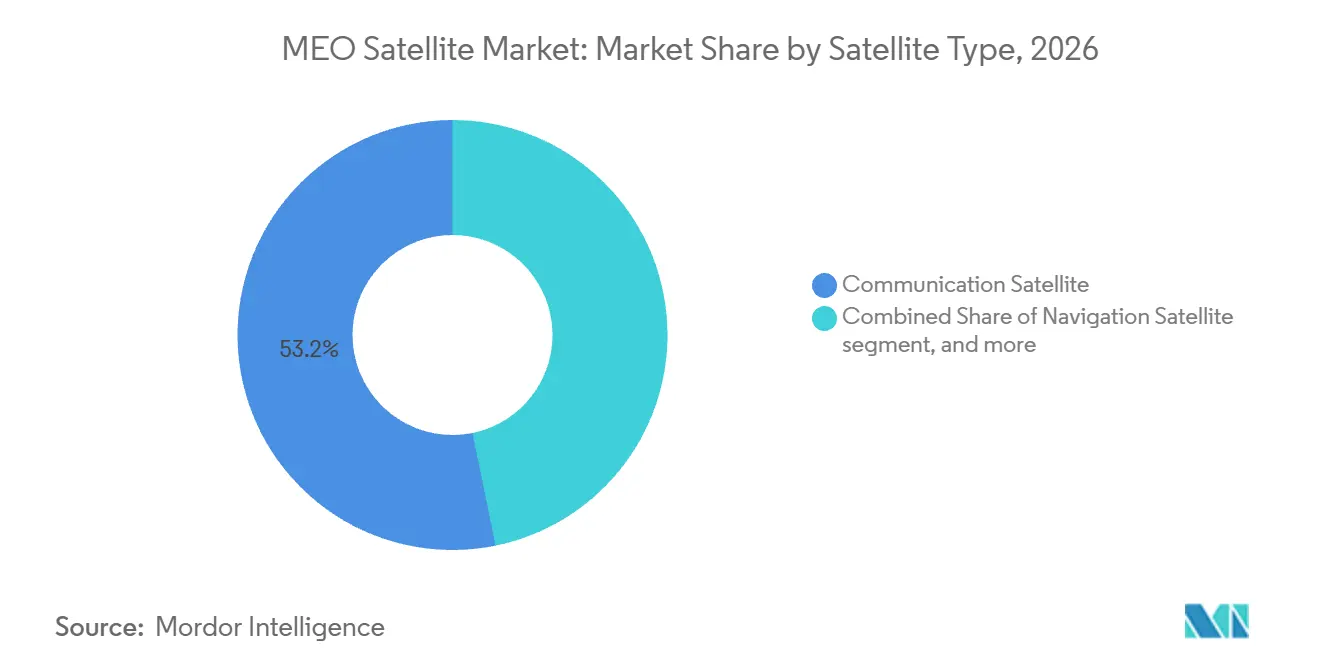
- By satellite type, communication satellites held a 53.21% revenue share in 2026, while earth observation satellites are forecast to grow at a 26.71% CAGR through 2032.
- By satellite mass, large satellites held a 51.75% revenue share in 2026, while medium satellites are forecast to grow at a 27.83% CAGR through 2032.
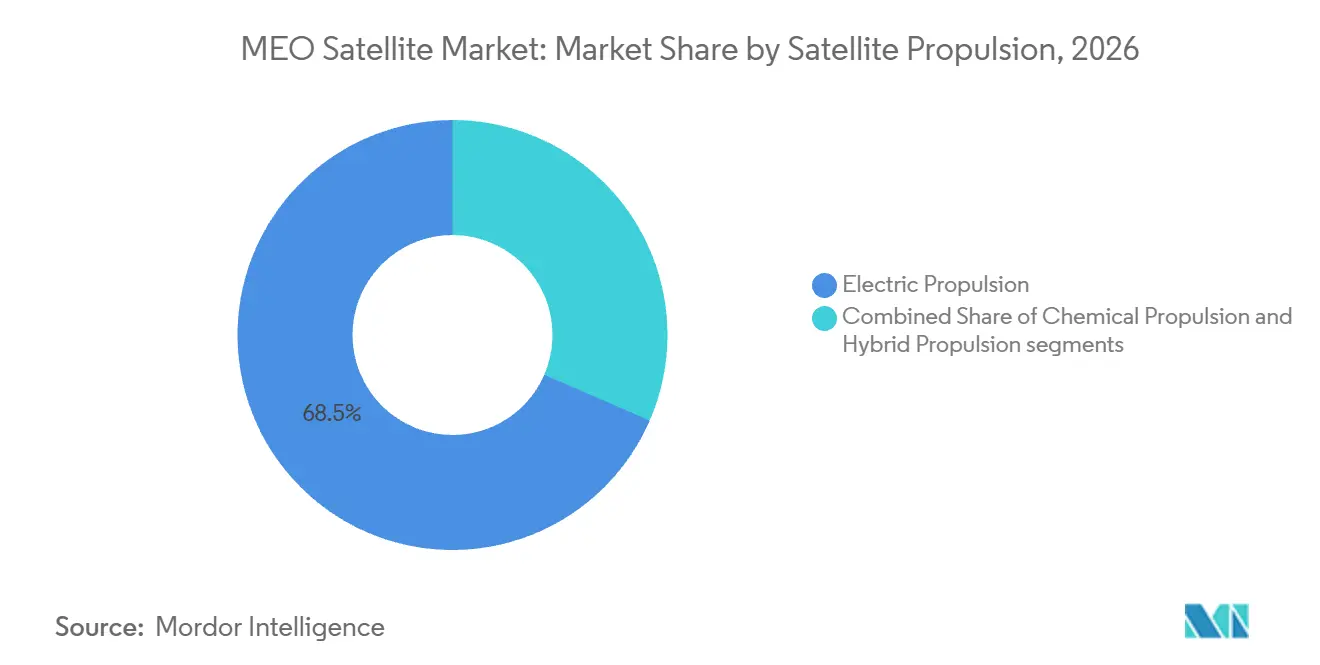
- By propulsion, electric propulsion held a 68.49% revenue share in 2026 and is forecast to grow at a 28.73% CAGR through 2032.
- By end user, commercial users held 63.63% revenue share in 2026 and are forecast to grow at a 29.52% CAGR through 2032.
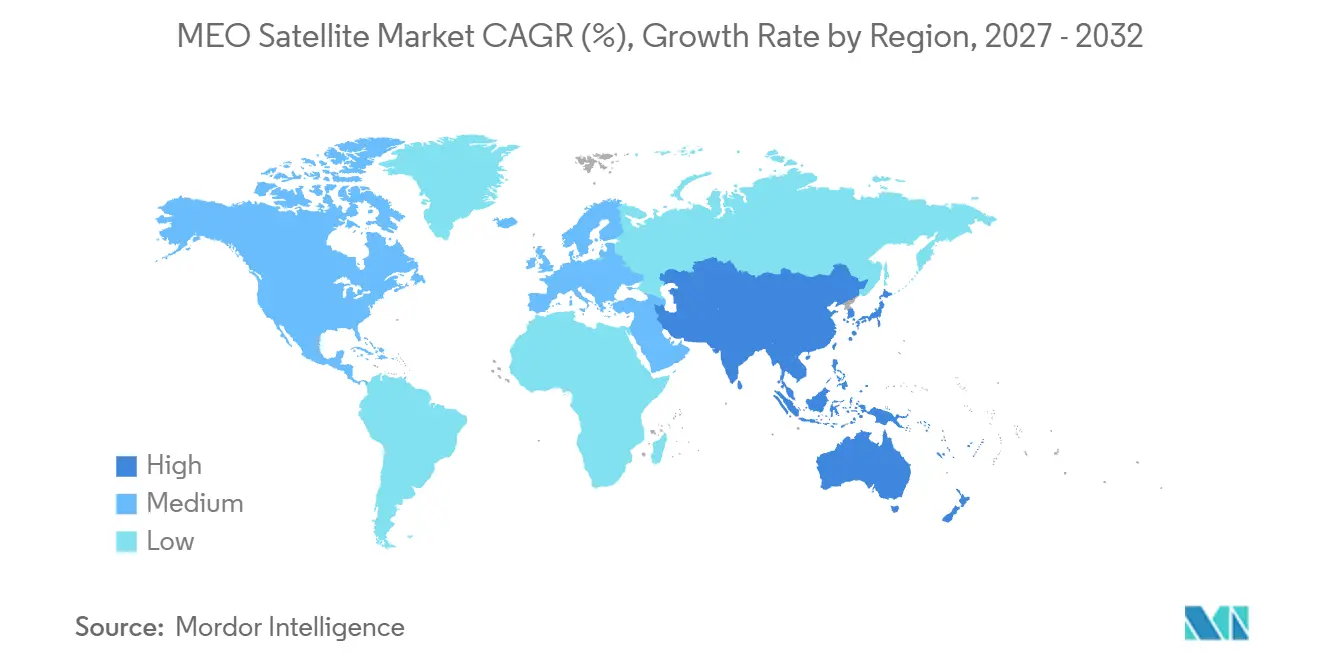
- By geography, North America held a 51.77% revenue share in 2026, while Asia-Pacific is forecast to grow at a 30.63% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of MEO Satellite Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Demand for high-throughput, predictable-latency connectivity | 5.10% | Global, strongest in maritime corridors and remote enterprise locations | Medium term (2-4 years) |
| Expansion of global navigation satellite systems | 4.20% | Global, concentrated in Europe, China, and the United States | Long term (≥ 4 years) |
| Growth in secure defense positioning, navigation, and timing (PNT) | 3.70% | North America, NATO Europe, and the Indo-Pacific | Short term (≤ 2 years) |
| Adoption of software-defined payloads and reconfigurable beams | 3.00% | Global, with early use in Europe and North America | Medium term (2-4 years) |
| Sovereign MEO capacity for government and multinational programs | 2.60% | Europe, India, Japan, and Australia | Long term (≥ 4 years) |
| MEO integration with multi-orbit network architectures | 2.30% | Global, with early commercial use in aviation and maritime | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Expansion of Global Navigation Satellite Systems
The MEO satellite market benefits from concurrent modernization programs for GPS, Galileo, GLONASS, and BeiDou. These systems place their core constellations in medium Earth orbit, which makes replacement and enhancement cycles more closely tied to satellite demand. The European Space Agency confirmed that Galileo satellites 33 and 34 entered service in 2026 after launch on Ariane 6.[1] China completed an in-orbit software upgrade across all 24 BeiDou-3 MEO satellites in 2026, supporting global service improvements without additional launches. The MEO satellite market, therefore, has a replacement pipeline that extends beyond new constellation launches. Second-generation systems are expected to use electric propulsion, inter-satellite links, and software-defined navigation payloads, which also raises requirements for satellite buses and ground control systems.
Demand for High-Throughput, Predictable-Latency Connectivity
Enterprise and mobility customers are seeking high-capacity connectivity across routes and locations that terrestrial networks do not serve. This supports the MEO satellite market because its coverage and latency profile can meet the needs of managed services for aircraft, ships, remote sites, and government users. SES reported the launch of the final 3 O3b mPOWER satellites in September 2026, completing its 13-satellite second-generation MEO broadband constellation.[2] SES expects the completed constellation to deliver a threefold increase in network capacity compared with the initial 8-satellite configuration. The MEO satellite market has an advantage in that customers buy committed service levels rather than consumer broadband access. Operators with MEO, GEO, and LEO capacity can also provide a managed network with orbital switching and multiple frequency options.
Growth in Secure Defense Positioning, Navigation, and Timing (PNT)
Defense procurement is increasing demand for MEO systems that support resilient PNT, tracking, and missile warning. The MEO satellite market benefits from this shift, as a layered architecture can use MEO alongside LEO systems rather than relying on a single orbital tier. In June 2025, the US Space Force awarded BAE Systems a USD 1.20 billion contract for 10 Epoch 2 MEO satellites to provide resilient missile warning and tracking. The planned baseline includes 30 MEO satellites, complementing a larger LEO tracking layer. MEO can provide broad coverage with fewer satellites than a LEO-only system, which can reduce replenishment needs and simplify logistics. The MEO satellite market is consequently tied to defense priorities that extend beyond conventional communications demand.
Adoption of Software-Defined Payloads and Reconfigurable Beams
The adoption of software-defined payloads and reconfigurable beams is driving growth in the MEO satellite market by enabling dynamic bandwidth allocation, flexible coverage, and real-time capacity optimization. These capabilities allow satellite operators to respond to changing traffic patterns, support diverse user requirements, improve spectrum efficiency, and deliver scalable connectivity across commercial, government, and mobility applications. Software-defined payloads can help satellite operators direct capacity toward changing aviation, maritime, enterprise, and government requirements. Galileo’s second-generation program incorporates digital payload technology and electric propulsion, reflecting the shift toward more adaptable MEO spacecraft. Reconfigurable beams can also help operators make better use of available spectrum and respond to demand across different service areas. The benefit depends on compatible ground systems, secure network controls, and operators’ ability to manage changing customer requirements.
Restraints Impact Analysis of MEO Satellite Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | |
|---|---|---|---|
| Competitive pressure from LEO mega-constellations | -2.50% | Global, strongest in consumer broadband and maritime | Short term (≤ 2 years) |
| High capital intensity and long deployment cycles | -2.10% | Global, most acute for new operators | Long term (≥ 4 years) |
| Limited availability of MEO-specific ground equipment and terminals | -1.30% | Global, strongest in enterprise and government applications | Medium term (2-4 years) |
| MEO spectrum coordination and sovereign gateway complexity | -1.10% | Multi-region, concentrated in Asia-Pacific and emerging locations | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Competitive Pressure from LEO Mega-Constellations
LEO constellations are a major constraint for the MEO satellite market, especially in consumer and cost-sensitive applications. Their latency can be under 50 ms, which is attractive for interactive video, financial services, and vehicle communications. The issue is not that MEO cannot serve these applications. Instead, buyers often select the lowest-latency option when coverage differences are not decisive. MEO operators are responding through throughput commitments, managed service-level agreements, and multi-orbit packages. The MEO satellite market will need continued investment in ground systems and service management to support this positioning.
High Capital Intensity and Long Deployment Cycles
A MEO satellite program can take 5 to 8 years from contract award to full commercial service. Operators must fund spacecraft, launches, ground systems, spectrum coordination, and customer operations before recognizing much revenue. SES’s commitment to the IRIS² MEO segment, up to EUR 1.35 billion (USD 1.49 billion), underscores the financial requirements for established operators.[3] New entrants may face lower manufacturing costs, but they often lack spectrum rights, ground infrastructure, and long-term customer contracts. The MEO satellite market is likely to favor companies that can finance long deployment cycles and combine public and commercial demand. This can limit entry by smaller operators even when demand conditions are favorable and prospective customers have identified a service need. Scale remains important.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
MEO Satellite Market Segment Analysis
By Satellite Type:
Communication Satellites Lead The Revenue BaseCommunication satellites held 53.21% of the MEO satellite market share in 2026. Their lead reflects broadband constellations serving aviation, maritime, enterprise, and remote government locations. These customers often need throughput consistency and managed support across routes beyond terrestrial coverage. MEO systems can provide a practical balance between service reach and latency for these use cases. The MEO satellite industry also maintains a dependable navigation satellite base, as the major GNSS constellations deploy their core assets in this orbit. Galileo and BeiDou replacement programs support demand for navigation payloads, electric propulsion, and inter-satellite connectivity. The MEO satellite market is also affected by international spectrum coordination rules, which shape the timing of gateway placement and commercial service entry. These rules require operators to align network design, licensing, and service rollout plans before capacity can be sold at scale.
Earth observation satellites are forecast to grow at a 26.71% CAGR through 2032. Defense ministries in Europe, Asia, and North America are using these systems for intelligence, surveillance, and reconnaissance requirements. Navigation, surveillance and intelligence, and other satellite types account for the remaining share of the revenue mix. Hosted payloads are becoming relevant because operators can use spare bus capacity for government payloads alongside commercial communications missions. This model can reduce acquisition costs for public agencies while preserving control over sensitive equipment. A single platform can therefore support communication, navigation, and government missions when payload and security requirements allow. The MEO satellite market can benefit from this wider use of shared spacecraft architecture. It also gives governments a route to add mission capability without having to develop a dedicated satellite bus for every requirement.



By Satellite Mass:
Large Platforms Hold The Largest PositionLarge satellites held 51.75% of revenue in 2026. These satellites typically support high-power transponders, large antennas, and long mission lives for navigation and communications programs. Government-grade navigation satellites and adapted GEO-derived buses contribute to their position. Their longer operating life can support revenue planning for applications that require stable capacity over many years. Large spacecraft are also well-suited to payloads with demanding power and thermal requirements. The MEO satellite market size for large platforms is therefore supported by major government programs and high-capacity communications systems. However, operators are changing their procurement approach to achieve shorter build cycles and more frequent technology updates. This creates a mixed procurement environment in which a few large platforms operate alongside repeatable medium-class spacecraft.
Medium satellites are forecast to grow at a 27.83% CAGR through 2032. This class is aligned with constellation designs that prioritize launch-batch economics, modular payloads, and repeatable production. SES selected K2 Space to supply 28 MEO platforms for its meoSphere program.[4] Small satellites remain an early-stage category because MEO radiation conditions place higher demands on components and operational life. SES’s Gravitas demonstrator is part of a pathfinder sequence for the meoSphere program. The MEO satellite market can use these missions to validate satellite bus and payload performance before broader deployment. Radiation performance, power handling, and reliable operations are especially important before any system moves from a demonstrator to a production constellation.
By Propulsion:
Electric Propulsion Leads System DemandElectric propulsion held 68.49% of the MEO satellite propulsion market share in 2026. Its position reflects the value of high-efficiency station-keeping during long missions. Hall-effect and ion thrusters can preserve more payload mass than chemical systems when operators prioritize long-term efficiency. Electric propulsion is also compatible with navigation satellites and high-throughput communications designs that require sustained power. The MEO satellite market has an incentive to use this technology because spacecraft commonly operate for more than 12 years. Galileo's second-generation satellites are expected to combine electric propulsion with digital payloads and inter-satellite links. This approach supports a move toward more flexible MEO satellite designs. It may also make payload changes easier during a satellite's operating life, which is valuable for navigation and communications missions.
Electric propulsion is forecast to grow at a 28.73% CAGR through 2032. NASA's Advanced Electric Propulsion System testing has demonstrated the qualification progress of a 12 kW Hall thruster for government and commercial applications. Chemical propulsion remains useful when satellites need rapid orbit raising or high-thrust maneuvers. Hybrid systems can combine early-mission maneuverability with electric station-keeping for the rest of the mission. This can be relevant to military systems that require rapid deployment and extended operation. The MEO satellite market will continue to use multiple propulsion approaches because mission priorities vary by payload, orbit, and customer. Suppliers that can integrate electrical and chemical subsystems can address a broader range of defense and commercial requirements.

By End User:
Commercial Users Hold The Leading PositionCommercial users held 63.63% of MEO satellite revenues in 2026. Their demand comes from broadband, in-flight connectivity, maritime services, cloud connectivity, and data relay. MEO systems can offer managed coverage for routes that cross oceans and remote land areas. Commercial users also value service-level agreements that specify capacity and availability. The MEO satellite market is being supported by multi-orbit offerings that combine MEO capacity with GEO and LEO options. This allows operators to respond to varying latency, coverage, and capacity requirements within a single contract. Commercial demand also provides a revenue base for hosted government payloads and other multi-mission uses. This structure can improve use of spacecraft capacity when government customers need a smaller payload than a dedicated satellite would require.
Commercial users are forecast to grow at a 29.52% CAGR through 2032, the highest rate among end-user groups. Government and civil agencies procure GNSS augmentation, Earth observation, resilient communications, and disaster-response capacity. Government SATCOM (GOVSATCOM) became operational in January 2026 with 8 satellites from 5 EU member states. Military demand accounts for a smaller share of 2026 revenue, but it has a high value per satellite because systems require specialized payloads and security controls. Defense users increasingly consider placing sensitive payloads on commercial spacecraft while retaining payload sovereignty. The MEO satellite market can benefit from this model, which reduces acquisition timelines and spreads satellite bus costs across several users. The approach depends on clear security arrangements, payload interfaces, and mission control responsibilities between the operator and public customer.
Geography Analysis
North America held 51.77% of the MEO satellite market share in 2026. The region's position is supported by US investment in navigation, missile warning, intelligence, surveillance, and reconnaissance satellites. The US Space Force is a major source of demand through GPS modernization and resilient missile-warning programs. Commercial activity also contributes through O3b mPOWER and future meoSphere deployment. Canada's spectrum position and Mexico's early adoption of enterprise connectivity add regional depth. The MEO satellite market in North America remains most dependent on US government and commercial procurement across navigation, defense, and connectivity applications. This concentration makes federal awards, navigation program schedules, and operator investment decisions important for regional manufacturing activity.
Asia-Pacific is forecast to grow at a 30.63% CAGR through 2032. China's BeiDou evolution, Japan's QZSS expansion, and India's domestic satellite manufacturing plans form the main demand base. China had 24 operational BeiDou-3 MEO satellites and completed a 2026 system software upgrade. NEC was contracted by JAXA in October 2025 to develop positioning mission payloads for Japan's expanded 11-satellite QZSS system.
Europe is the second-largest geographic segment. Galileo's planned second-generation satellites and the IRIS² program are central to government-led demand. The European Commission has described IRIS² as a secure multi-orbit connectivity initiative that includes 18 MEO satellites. Galileo had 27 operational satellites out of a planned 30 in May 2026. European activity also includes developing sovereign ground systems and national satellite defense initiatives. The MEO satellite market in Europe is therefore linked to both navigation modernization and strategic communications priorities. European activity also shows how demand for satellite capacity can be connected to industrial policy, launch access, and control over critical infrastructure.
South America remains smaller but has enterprise and government connectivity opportunities, especially in Brazil. The Middle East and Africa are emerging locations for broadband and earth observation services, supported by resource, logistics, and government requirements. The MEO satellite market in these regions depends on operators' ability to provide affordable terminals, reliable ground infrastructure, and locally compliant gateway arrangements. These conditions are important because customer demand alone does not ensure that a MEO service can be deployed across several national jurisdictions.
Competitive Landscape
Market Concentration
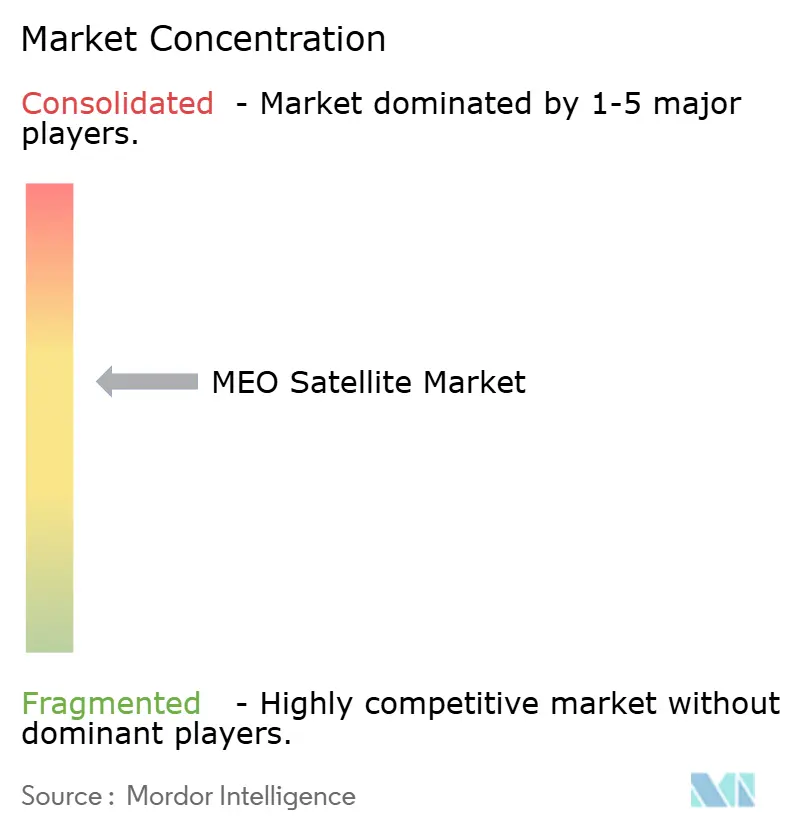
The MEO satellite market is moderately consolidated among commercial operators and more fragmented among manufacturers. The combination is important because customers can choose a service design based on their needs for route, throughput, latency, resilience, and continuity, rather than committing to a single orbit. It also allows a large operator to coordinate network planning, gateway operations, billing, and customer support across its fleet. Manufacturers compete more widely across national programs and specialized payload requirements. Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation, L3Harris Technologies, Inc., The Boeing Company, Airbus SE, OHB SE, China Aerospace Science and Technology Corporation, and Thales Alenia Space are relevant across defense, navigation, and communications programs.
SES has pursued several strategic moves that illustrate the direction of competition. It strengthened its commercial position by completing the Intelsat acquisition in July 2025 for USD 3.10 billion. The company also finished the O3b mPOWER constellation and selected K2 Space for 28 next-generation meoSphere platforms. Airbus SE signed an initial contract with Eutelsat in September 2026 to develop the first IRIS² LEO satellite layer. The European program is relevant to MEO because SES is responsible for the MEO segment of the multi-orbit architecture. The MEO satellite market increasingly rewards companies that can combine spacecraft, payload, ground systems, and service operations. This capability matters when a contract includes satellite capacity, secure terminals, gateway access, network management, and performance commitments for several customer locations. Intellectual property related to reconfigurable payloads and beam management can also affect competitive positioning. These capabilities can determine how quickly an operator changes coverage or capacity allocation after customer requirements shift.
Hosted payloads and space-based data relay create opportunities for specialist suppliers and newer spacecraft companies. K2 Space is a notable example because it is supplying platforms for the 28-satellite MEO Sphere program. Smaller companies can participate through subsystem demonstrations even when they are not prime contractors for MEO spacecraft. Their role may include payload components, software, or technologies that are validated before use in larger constellations. This can shift some value toward payload and ground-segment specialists as production increases. The MEO satellite market remains difficult for new operators because capital needs, spectrum rights, and operational experience are substantial. However, the mix of commercial and sovereign demand creates several routes to participation across the value chain. Companies that specialize in secure payloads, gateway equipment, satellite software, or integrated network operations can participate even when they do not manufacture the full spacecraft.
MEO Satellite Industry Leaders
-
Airbus SE
-
SES S.A.
-
Lockheed Martin Corporation
-
The Boeing Company
-
Thales Alenia Space
- *Disclaimer: Major Players sorted in no particular order
MEO Satellite Market Companies Covered in this Report
- SES S.A.
- Lockheed Martin Corporation
- The Boeing Company
- Thales Alenia Space
- Airbus SE
- Northrop Grumman Corporation
- OHB SE
- RTX Corporation
- L3Harris Technologies, Inc.
- China Aerospace Science and Technology Corporation
- China Satellite Communications Co., Ltd.
- Mitsubishi Electric Corporation
- ArianeGroup SAS
- GomSpace A/S
- AAC Clyde Space AB
- Maxar Technologies Inc.
- Eutelsat Communications S.A.
- Honeywell Aerospace Inc.
- Indian Space Research Organisation
- Space Exploration Technologies Corp.
Recent Industry Developments in MEO Satellite Market
- September 2026: SES successfully launched its final 3 O3b mPOWER satellites, numbers 11, 12, and 13, completing the 13-satellite second-generation MEO broadband constellation. The full constellation is expected to be operational by mid-2027 and to provide a threefold increase in capacity over the initial 8-satellite configuration.
- August 2026: The European Commission and the SpaceRISE consortium signed the IRIS² implementation agreement. The program includes 348 satellites, comprising 330 LEO and 18 MEO satellites.
- August 2026: SES completed the Rendez-vous 1 milestone under the IRIS² program, confirming readiness to proceed with implementation.
- July 2026: ESA confirmed that Galileo satellite 34 entered service, bringing the active Galileo constellation to 27 operational satellites.
Global MEO Satellite Market Report Scope
The MEO satellite market includes the design, engineering, production, assembly, integration, and testing of satellites and their major subsystems for deployment in MEO orbit. It covers the manufacture of satellite platforms/buses, payloads, propulsion systems, power systems, thermal and structural components, avionics, communication systems, and other spacecraft subsystems.
The MEO satellite market is segmented by satellite type, satellite mass, propulsion, end user, and geography. By satellite type, the market is segmented into communication satellites, earth observation satellites, navigation satellites, surveillance and intelligence satellites, and others. By satellite mass, the market is segmented into small, medium, and large. By propulsion, the market is segmented into electric propulsion, chemical propulsion, and hybrid propulsion. By end user, the market is segmented into commercial, government and civil, and military. The report also covers the market sizes and forecasts for the MEO satellite market in major countries across different regions. For each segment, the market size is provided in terms of value (USD).
Segmentation Overview
| Communication Satellites |
| Earth Observation Satellites |
| Navigation Satellites |
| Surveillance and Intelligence Satellites |
| Others |
| Small |
| Medium |
| Large |
| Electric Propulsion |
| Chemical Propulsion |
| Hybrid Propulsion |
| Commercial |
| Government and Civil |
| Military |
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | United Kingdom | |
| France | ||
| Germany | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Rest of South America | ||
| Middle East and Africa | Middle East | Saudi Arabia |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Rest of Africa | ||
| By Satellite Type | Communication Satellites | ||
| Earth Observation Satellites | |||
| Navigation Satellites | |||
| Surveillance and Intelligence Satellites | |||
| Others | |||
| By Satellite Mass | Small | ||
| Medium | |||
| Large | |||
| By Propulsion | Electric Propulsion | ||
| Chemical Propulsion | |||
| Hybrid Propulsion | |||
| By End User | Commercial | ||
| Government and Civil | |||
| Military | |||
| By Geography | North America | United States | |
| Canada | |||
| Mexico | |||
| Europe | United Kingdom | ||
| France | |||
| Germany | |||
| Russia | |||
| Rest of Europe | |||
| Asia-Pacific | China | ||
| India | |||
| Japan | |||
| South Korea | |||
| Australia | |||
| Rest of Asia-Pacific | |||
| South America | Brazil | ||
| Rest of South America | |||
| Middle East and Africa | Middle East | Saudi Arabia | |
| United Arab Emirates | |||
| Rest of Middle East | |||
| Africa | South Africa | ||
| Rest of Africa | |||
Market Definition
- Application - Various applications or purposes of the satellites are classified into communication, earth observation, space observation, navigation, and others. The purposes listed are those self-reported by the satellite’s operator.
- End User - The primary users or end users of the satellite is described as civil (academic, amateur), commercial, government (meteorological, scientific, etc.), military. Satellites can be multi-use, for both commercial and military applications.
- Launch Vehicle MTOW - The launch vehicle MTOW (maximum take-off weight) means the maximum weight of the launch vehicle during take-off, including the weight of payload, equipment and fuel.
- Orbit Class - The satellite orbits are divided into three broad classes namely GEO, LEO, and MEO. Satellites in elliptical orbits have apogees and perigees that differ significantly from each other and categorized satellite orbits with eccentricity 0.14 and higher as elliptical.
- Propulsion tech - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Mass - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Subsystem - All the components and subsystems which includes propellants, buses, solar panels, other hardware of satellites are included under this segment.
| Keyword | Definition |
|---|---|
| Attitude Control | The orientation of the satellite relative to the Earth and the sun. |
| INTELSAT | The International Telecommunications Satellite Organization operates a network of satellites for international transmission. |
| Geostationary Earth Orbit (GEO) | Geostationary satellites in Earth orbit 35,786 km (22,282 mi) above the equator in the same direction and at the same speed as the earth rotates on its axis, making them appear fixed in the sky. |
| Low Earth Orbit (LEO) | Low Earth Orbit satellites orbit from 160-2000km above the earth, take approximately 1.5 hours for a full orbit and only cover a portion of the earth’s surface. |
| Medium Earth Orbit (MEO) | MEO satellites are located above LEO and below GEO satellites and typically travel in an elliptical orbit over the North and South Pole or in an equatorial orbit. |
| Very Small Aperture Terminal (VSAT) | Very Small Aperture Terminal is an antenna that is typically less than 3 meters in diameter |
| CubeSat | CubeSat is a class of miniature satellites based on a form factor consisting of 10 cm cubes. CubeSats weigh no more than 2 kg per unit and typically use commercially available components for their construction and electronics. |
| Small Satellite Launch Vehicles (SSLVs) | Small Satellite Launch Vehicle (SSLV) is a three-stage Launch Vehicle configured with three Solid Propulsion Stages and a liquid propulsion-based Velocity Trimming Module (VTM) as a terminal stage |
| Space Mining | Asteroid mining is the hypothesis of extracting material from asteroids and other asteroids, including near-Earth objects. |
| Nano Satellites | Nanosatellites are loosely defined as any satellite weighing less than 10 kilograms. |
| Automatic Identification System (AIS) | Automatic identification system (AIS) is an automatic tracking system used to identify and locate ships by exchanging electronic data with other nearby ships, AIS base stations, and satellites. Satellite AIS (S-AIS) is the term used to describe when a satellite is used to detect AIS signatures. |
| Reusable launch vehicles (RLVs) | Reusable launch vehicle (RLV) means a launch vehicle that is designed to return to Earth substantially intact and therefore may be launched more than one time or that contains vehicle stages that may be recovered by a launch operator for future use in the operation of a substantially similar launch vehicle. |
| Apogee | The point in an elliptical satellite orbit which is farthest from the surface of the earth. Geosynchronous satellites which maintain circular orbits around the earth are first launched into highly elliptical orbits with apogees of 22,237 miles. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. For sales conversion to volume, the average selling price (ASP) is kept constant throughout the forecast period for each country, and inflation is not a part of the pricing.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


