
Military Satellite Market Size and Share
Market Overview
| Study Period | 2020 - 2032 |
|---|---|
| Market Size (2027) | USD 9.06 Billion |
| Market Size (2032) | USD 16.74 Billion |
| Growth Rate (2027 - 2032) | 13.06 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Military Satellite Market Analysis by Mordor Intelligence
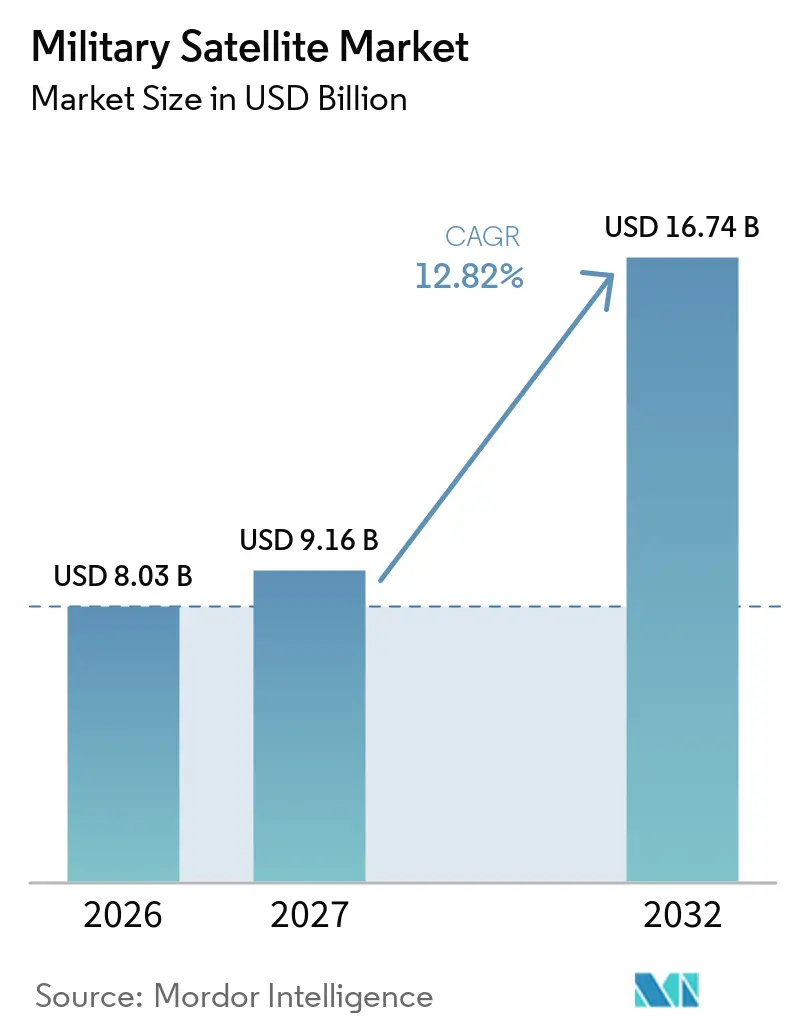
The military satellite market size was valued at USD 8.03 billion in 2026 and is forecast to grow from USD 9.06 billion in 2027 to reach USD 16.74 billion by 2032, growing at a 13.06% CAGR from 2027 to 2032. The military satellite market is moving away from a small number of high-value geostationary platforms toward constellations operating across multiple orbits, thereby supporting resilience and enabling faster links between sensors and military users. Rising geopolitical tensions are shortening procurement schedules and are strengthening sovereign programs for satellite procurement, ground systems, and launch infrastructure. The military satellite market is also shaped by a shift in which satellite connectivity supports operational decision-making rather than only logistics. At the same time, electronic interference, orbital debris, high capital requirements, and classified procurement rules constrain adoption. These conditions favor providers that can deliver secure, resilient systems while giving governments a clear path to sustain and replace constellations.
Key Report Takeaways
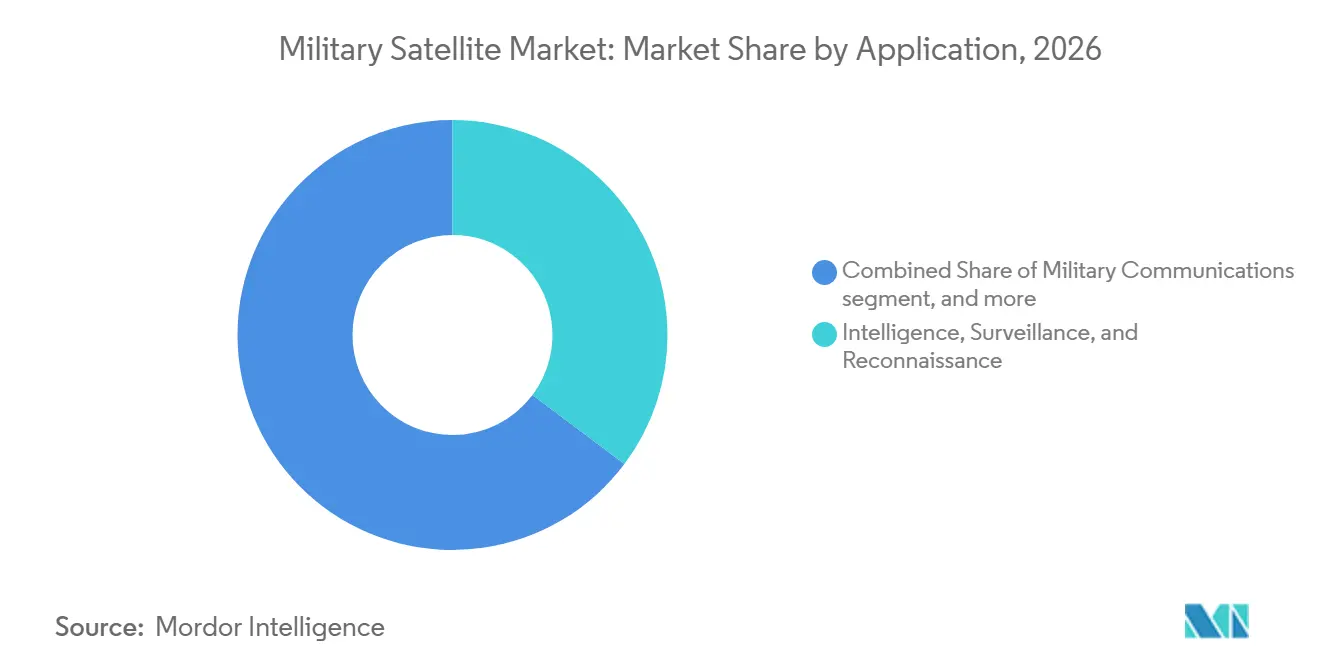
- By application, intelligence, surveillance, and reconnaissance (ISR) held 35.25% of the military satellite market share in 2026, while military communications is projected to grow at a 14.71% CAGR through 2032.
- By satellite mass, large satellites accounted for 58.75% of the military satellite market share in 2026, while small satellites are forecast to expand at a 15.83% CAGR through 2032.
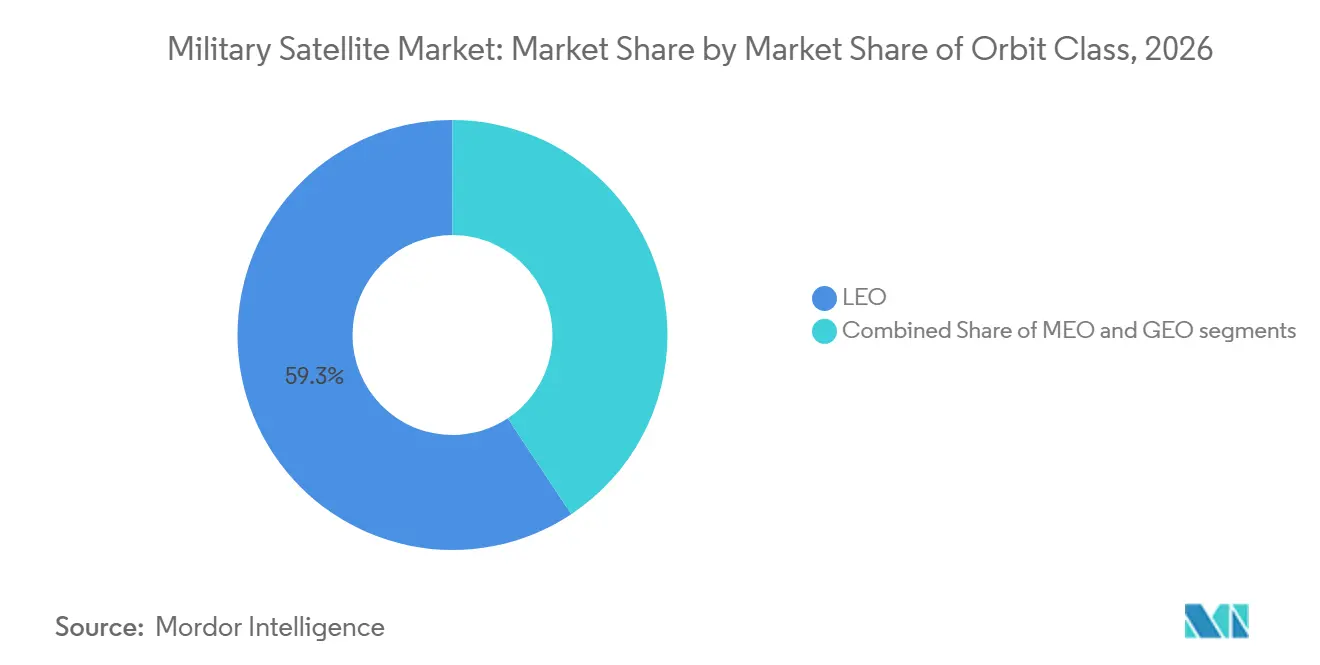
- By orbit class, LEO accounted for 59.32% of the military satellite market in 2026, while MEO is projected to grow at a 14.91% CAGR through 2032.
- By payload type, communication payloads held 32.69% revenue share in 2026, while SIGINT and ELINT payloads are forecast to grow at a 14.52% CAGR through 2032.
- By geography, North America held 51.77% revenue share in 2026, while Asia-Pacific is projected to grow at a 16.63% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Military Satellite Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising defense expenditure and space modernization | 3.20% | Global, concentrated in North America, Europe, and Asia-Pacific | Medium term (2-4 years) |
| Demand for real-time ISR and persistent situational awareness | 2.80% | Global, critical in North America, Asia-Pacific, and the Middle East | Short term (≤ 2 years) |
| Resilient multi-orbit and proliferated constellation deployment | 2.10% | North America, Europe, and Asia-Pacific | Medium term (2-4 years) |
| Commercial-military SATCOM and remote-sensing integration | 1.80% | North America and Europe, with spillover to the Middle East and Africa | Medium term (2-4 years) |
| COTS software-defined payloads and AI-enabled mission processing | 1.50% | North America, with early gains in Europe and Asia-Pacific | Long term (≥ 4 years) |
| Coalition interoperability and sovereign space capability programs | 1.20% | NATO members and Asia-Pacific Five Eyes partners | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Defense Expenditure and Space Modernization
National defense budgets are allocating a larger share of new spending to military space systems. Germany announced plans in September 2025 to invest EUR 35 billion (approximately USD 41 billion) over 5 years in space security, including redundant constellations, a military satellite operations center, and cybersecurity measures. France’s 2024 to 2030 military programming law allocated EUR 6.40 billion (USD 7.50 billion) for military space, and a further EUR 4.20 billion (USD 4.92 billion) was subsequently announced.[1] Japan’s defense-space spending reached JPY 540 billion (USD 3.41 billion) in FY2025, representing a near-sevenfold increase from FY2022. These commitments support the military satellite market by funding satellites, secure ground stations, launch access, and hardened cyber defenses together rather than as separate programs. They also enable commercial-origin manufacturers to enter national-security space programs, as Rocket Lab received a USD 816 million prime contract in December 2025 for a missile-defense constellation. The performance standards set by major programs such as the Proliferated Warfighter Space Architecture raise supplier requirements and can concentrate work among firms with qualified capabilities.
Demand for Real-Time ISR and Persistent Situational Awareness
Military users increasingly require satellite intelligence at tactical timescales rather than through long strategic reporting cycles. ICEYE launched its ISR Cell in September 2025, a containerized system designed to provide near-real-time synthetic aperture radar intelligence to combat units within minutes.[2] The National Reconnaissance Office stated in December 2025 that it operates more than 200 proliferated LEO satellites and that the constellation can reduce intelligence delivery from hours to minutes.[3]The military satellite market benefits from distributed constellations, which can support direct tasking by combatant commands and maintain more persistent coverage. NATO’s Alliance Persistent Surveillance from Space program brings together 19 allies and an equivalent investment of more than USD 1 billion through its virtual Aquila constellation. This approach makes imagery, signals, and other collection services a shared operational resource for coalition users. It also creates demand for ground processing, secure data links, and systems that can convert satellite data into timely operational information.
Resilient Multi-Orbit and Proliferated Constellation Deployment
Defense planners are deploying layered networks across several orbits rather than relying only on a few large satellites. The US Space Development Agency began launching 154 operational Tranche 1 satellites in September 2025 and, in December 2025, awarded USD 3.50 billion for 72 Tranche 3 LEO missile-warning satellites for FY2029 launches. MEO is developing as a distinct layer for missile warning because it can track hypersonic glide vehicles that geostationary sensors cannot observe with sufficient resolution. The Space Force awarded BAE Systems USD 1.20 billion for 10 MEO satellites under the EPOCH 2 program. This combination of LEO, MEO, and GEO gives military users several paths for sensing and communications. It also reduces dependence on any single platform, although it raises the burden of coordination, ground control, and replacement planning. The military satellite market, therefore, favors architectures that can combine disparate orbital layers without compromising security or availability.
Commercial-Military SATCOM and Remote-Sensing Integration
Commercial satellite operators have become capacity providers for military communications and remote sensing programs. France signed a 10-year NEXUS framework agreement with Eutelsat in June 2025 for EUR 1 billion (USD 1.17 billion), giving French forces priority access to OneWeb's LEO capacity alongside sovereign Syracuse geostationary assets. SES's O3b mPOWER service supported the French Navy carrier strike group during the Clémenceau 25 mission in 2025, showing that commercial MEO capacity can meet naval needs for latency and reliability. The military satellite market gains additional near-term capacity when governments combine commercial services with sovereign systems. Such agreements can shorten acquisition timelines because commercial constellations are already operational or in the process of deployment. They also require clear priority-access rules, security provisions, and continuity plans in the event a commercial provider's constellation changes. The continued integration of commercial and military networks makes service delivery, not only satellite manufacturing, an important competitive capability.
Restraints Impact Analysis of Military Satellite Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance |
|---|---|---|
| Cyberattack, jamming, spoofing and electronic-warfare exposure | -1.80% | Global, most acute on the NATO eastern flank, in the Middle East, and in the Indo-Pacific |
| High upfront capital, long development cycles and launch dependence | -1.40% | Global, proportionally more severe for mid-tier nations |
| Orbital congestion and debris-mitigation burden | -0.90% | Global, concentrated in LEO below 600 km |
| Commercial service dependency and constellation replacement-rate risk | -0.70% | North America and Europe, with the highest commercial integration |
| Source: Mordor Intelligence | ||
Cyberattack, Jamming, Spoofing, and Electronic-Warfare Exposure
Electronic threats have become a recurring operating condition for satellite users. More than 10,000 satellite interference events were documented during the 12 months through February 2025, including daily GPS jamming and spoofing across northeastern European airspace, Baltic shipping lanes, Ukraine, and the Middle East. The CSIS Space Threat Assessment 2025 identified threats including uplink jamming, spoofing, co-orbital anti-satellite capabilities, and cyber intrusions targeting ground networks. A 2025 study found that protocol-aware jammers can exploit cyclical vulnerabilities in SATCOM protocols and outperform conventional jamming in the face of current countermeasures.[4] These risks can delay procurement, increase system costs, and reduce confidence in unprotected services. They also sustain demand for hardened, frequency-agile, software-defined systems that can operate in the presence of interference. The military satellite market must therefore balance rapid constellation deployment with stronger protection for links, payloads, and ground infrastructure.
High Upfront Capital, Long Development Cycles, and Launch Dependence
Large military satellite programs require substantial upfront investment and often have delivery schedules that span many years. Boeing received a USD 2.80 billion contract in July 2025 for 2 Evolved Strategic SATCOM satellites, with delivery extending to 2031 and options that could bring the program to USD 12 billion. The satellites will support US nuclear command, control, and communications, which places long-term national capabilities in a limited number of orbital assets. Countries without sovereign launch capacity can face further schedule and geopolitical risk when they depend on third-party launch services. Proliferation of small-satellite constellations can lower the cost of an individual spacecraft, but it requires high-rate manufacturing and frequent replacement. Mid-tier defense industries may struggle to fund this industrial base without continued government support. These constraints limit procurement agility even when military demand for new space capabilities is strong.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Military Satellite Market Segment Analysis
By Application:
ISR Holds the Largest Revenue Position While Military Communications Grows FasterISR accounted for 35.25% of revenue in 2026, making it the largest application by revenue. Embedded collection infrastructure across the Five Eyes, China’s People’s Liberation Army Strategic Support Force, and growing European sovereign programs support this position. Users increasingly seek persistent services instead of delayed batches of intelligence products. ICEYE received a EUR 240 million (USD 281.14 million) multiyear German government imagery contract and delivered sovereign synthetic aperture radar capability to the Royal Netherlands Air Force in 2025. The largest application remains dependent on secure ground processing and data dissemination, not only on satellites.
Military communications is expected to record a 14.71% CAGR from 2027 to 2032, the highest rate among applications in the military satellite market. The Proliferated Warfighter Space Architecture transport layer and comparable European systems create demand for secure relay capacity that supports tactical operations. Navigation and positioning remain mature yet active, as operators harden receivers against GPS spoofing and pursue alternative positioning, navigation, and timing signals. Missile detection, early warning, and space domain awareness remain smaller by revenue, although hypersonic threats and the need for real-time orbital awareness have raised their priority. Growth is broadening from traditional intelligence collection toward connected command, protected communications, and warning missions.



By Satellite Mass:
Large Satellites Retain Program Value While Small Satellites Change Constellation DesignLarge satellites accounted for 58.75% of the military satellite market size in 2026. Nuclear communications, protected strategic relays, and high-resolution reconnaissance systems need power, aperture, and operational life that smaller platforms cannot always provide. Boeing’s Evolved Strategic SATCOM program and Thales Alenia Space’s SpainSat NG-1 illustrate long-lifecycle programs that support demand for large satellites. These satellites anchor national communications systems, and their high cost and low production volumes reinforce the role of established prime contractors. Large satellites will remain essential where strategic missions require proven, high-capacity platforms.
Small satellites are projected to grow at a 15.83% CAGR from 2027 to 2032 as governments build proliferated constellations. The category has changed because smaller platforms can deliver capabilities that previously required much larger spacecraft. ICEYE’s Gen4 synthetic aperture radar satellite delivered imagery with resolution up to 16 cm and 500 images per satellite per day in 2025. This performance supports the military satellite market by making constellations of smaller spacecraft practical for military users. Medium satellites retain regional ISR and theater communications roles but face pressure from systems above and below them in scale.
By Orbit Class:
LEO Leads While MEO Builds a Dedicated Defense RoleLEO accounted for 59.32% of revenue in 2026. Its leading position reflects the National Reconnaissance Office’s proliferated constellation, the Space Development Agency’s architecture, and commercial-military remote-sensing and communications systems. LEO supports frequent revisit rates and reduced latency, which suit tactical data relay and persistent surveillance. The Space Development Agency’s plan includes 154 Tranche 1 satellites and further Tranche 3 missile-warning awards. The military satellite market remains exposed to congestion, debris, and recurring replenishment needs, all of which require mitigation and replacement plans at the outset of a program.
MEO is forecast to expand at a 14.91% CAGR from 2027 to 2032, the strongest growth rate across orbit classes. It supports commercial broadband for NATO naval and allied government users, as well as new missile-warning missions from medium altitude. SES O3b mPOWER served the French carrier strike group during the Clémenceau 25 mission in 2025. The EPOCH 2 program awarded BAE Systems USD 1.20 billion to develop 10 dedicated MEO satellites to track hypersonic targets. The GEO satellites continue to support nuclear communications and national operator services, underscoring why future architectures will combine the 3 orbit classes.

By Payload Type:
Communications Leads While SIGINT and ELINT Respond to Electronic ThreatsCommunication payloads accounted for 32.69% of revenue in 2026, driving demand across protected geostationary relays, LEO mesh networks, and tactical UHF services. Their leading role reflects the requirement for secure links between forces, platforms, and command systems. L3Harris delivered the KSV-650 in 2025 as the first National Security Agency-certified cryptographic platform fully reprogrammable in orbit. The platform meets agile cryptography requirements and raises the technical standard for protected communications payloads. Navigation and imaging payloads remain stable, while the military satellite industry needs payloads that protect critical data and adapt after launch.
SIGINT and ELINT payloads are expected to grow at a 14.52% CAGR from 2027 to 2032. Growth reflects the need to collect electronic order-of-battle information against adversaries expanding jamming and spoofing capabilities. The National Reconnaissance Office is expanding classified SIGINT capacity, while Germany and the Netherlands are pursuing sovereign collection at constellation scale. Missile-warning payloads remain smaller, although their role is expanding as the Space Development Agency Tracking Layer and EPOCH program mature. The payload mix is shifting toward systems that can detect, secure, process, and distribute information in contested electromagnetic conditions.
Geography Analysis
North America Military Satellite Market
North America accounted for 51.77% of the military satellite market in 2026. The military satellite market in the region draws on Space Force programs, National Reconnaissance Office expansion, and a large defense industrial base. The first operational launch of the Tranche 1 Proliferated Warfighter Space Architecture in September 2025 began a campaign intended to deploy 154 operational vehicles. The Evolved Strategic SATCOM program supports the nuclear communications backbone through a contract with an initial value of USD 2.80 billion and options for up to USD 12 billion. The acceptance of Meadowlands jammers in June 2025 also showed that the regional strategy addresses EW alongside satellite deployment.
Europe Military Satellite Market
Europe is the second-largest geographic segment and is experiencing a major rise in sovereign military space investment. The military satellite market in Europe is supported by Germany's EUR 35 billion (approximately USD 41 billion) commitment, France's EUR 10.60 billion (USD 12.42 billion) allocation through 2030, and the Rheinmetall-ICEYE joint venture's EUR 1.70 billion (USD 1.99 billion) contract for 40 synthetic aperture radar satellites signed in December 2025. NATO's NSS6G program has an investment of more than EUR 1 billion (USD 1.17 billion) for 2020 to 2034, and Spain and Luxembourg joined NATO in 2025. The Alliance Persistent Surveillance from Space program coordinates ISR across 19 allies through NATO's virtual Aquila constellation. NATO also launched the HALO initiative in Ankara in 2026 to connect national military satellites into a shared constellation.
APAC, MEA and South America Military Satellite Market
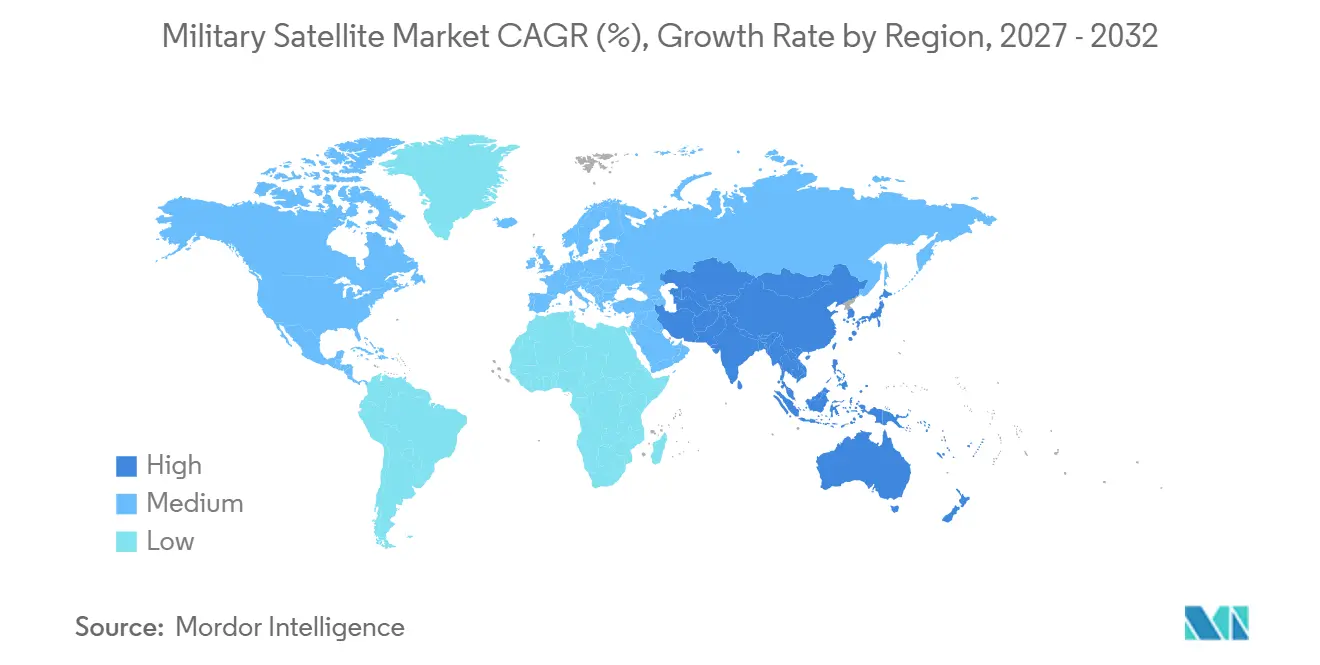
Asia-Pacific is the fastest-growing region, with the military satellite market forecast to expand at a 16.63% CAGR from 2027 to 2032. Japan's defense-space budget reached JPY 540 billion (USD 3.41 billion) in FY2025, and its JPY 280 billion (USD 1.78 billion) optical and synthetic aperture radar program seeks continuous awareness over a 3,000 km territorial radius. China's Guowang constellation, Indian indigenous programs, and stronger procurement activity in South Korea, Australia, and Southeast Asia are reshaping regional demand. The Middle East remains active in geostationary communications and Earth observation, while Africa and South America depend mainly on commercial capacity.
Competitive Landscape
Market Concentration
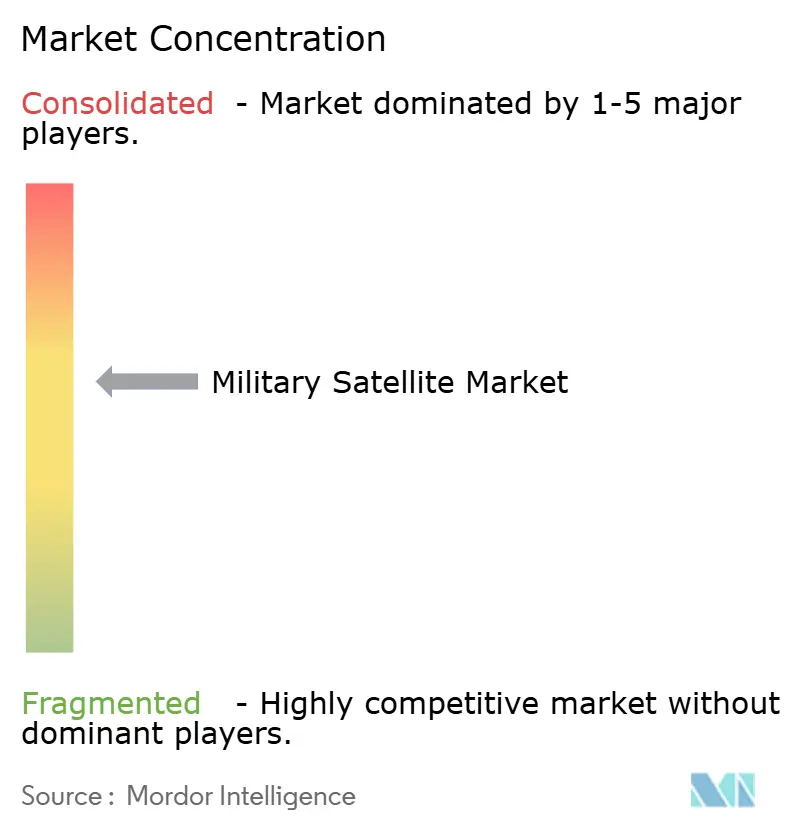
The military satellite market has 2 distinct competitive tiers. Large-satellite prime contracting has high entry barriers because programs require clearances, proven platforms, and government relationships. The Boeing Company, Lockheed Martin Corporation, Northrop Grumman Corporation, Airbus SE, and Thales Alenia Space hold leading roles in GEO and large LEO programs. Boeing’s July 2025 Evolved Strategic SATCOM award followed a 5-year competition with Northrop Grumman and used the 702MP platform already in Space Force service. L3Harris Technologies, Inc. and Viasat, Inc. are also pursuing software-defined payloads as firms seek protection and adaptability.
Competition is more intense in small satellites and service delivery, where entry barriers are lower. Rocket Lab’s elevation to Space Development Agency prime contractor status shows that launch providers can move into national-security satellite production. ICEYE operates as a commercial synthetic aperture radar provider, a defense prime through Rheinmetall, and a payload supplier. Its September 2025 Gen4 launch delivered imagery with resolution up to 16 cm, 500 images per satellite per day, and simultaneous imaging and downlink up to 700 Mbps. These capabilities increase pressure on established contractors to integrate commercial technology without weakening their position with government users.
AI-enabled onboard processing is another competitive area within the military satellite market. Helsing and Kongsberg Defence and Aerospace are self-funding an ISR/T constellation with algorithms demonstrated on the Loft Orbital YAM-6 platform and a deployment target of 2029. This approach works outside conventional procurement timelines. The resulting environment is concentrated in strategic large-satellite programs but more fragmented among small-satellite providers, payload specialists, and data-service firms.
Military Satellite Industry Leaders
-
Lockheed Martin Corporation
-
Northrop Grumman Corporation
-
The Boeing Company
-
Airbus SE
-
Thales Alenia Space
- *Disclaimer: Major Players sorted in no particular order
Military Satellite Market Companies Covered in this Report
- Airbus SE
- The Boeing Company
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- Space Exploration Technologies Corp.
- China Aerospace Science and Technology Corporation
- Thales Alenia Space
- Maxar Technologies Inc.
- Mitsubishi Electric Corporation
- Blue Canyon Technologies LLC (RTX Corporation)
- ICEYE Oy
- OHB SE
- GomSpace A/S
- L3Harris Technologies, Inc.
- Planet Labs PBC
- Spire Global, Inc.
- AAC Clyde Space AB
- Indian Space Research Organisation
- BAE Systems plc
- Viasat, Inc.
Recent Industry Developments in Military Satellite Market
- October 2026: Rheinmetall and Argotec successfully launched their first satellite aboard SpaceX’s Falcon 9, marking Rheinmetall’s entry into space-based defense capabilities. The satellite is designed to strengthen military airspace surveillance, early warning, and AI-enabled situational awareness, supporting Rheinmetall’s broader strategy to develop an integrated defense satellite constellation.
- September 2026: The UK Royal Air Force established No. III Space Effects Squadron, its first dedicated unit, focused on protecting military satellites from hostile activities. The squadron will employ EW and countermeasures to disrupt, degrade, and deny threats, strengthening UK space-control capabilities and protecting communications, navigation, and missile-warning infrastructure.
- July 2026: The US Space Development Agency awarded approximately USD 1.75 billion for 36 satellites under Tranche 3 of its Proliferated Warfighter Space Architecture. The satellites will provide missile warning, tracking, and defense capabilities across multiple orbital planes, supporting global coverage and the space-based architecture planned under the Golden Dome missile-defense initiative.
- December 2025: The US Space Development Agency awarded USD 3.50 billion to L3Harris Technologies, Lockheed Martin, Northrop Grumman, and Rocket Lab for 72 PWSA Tracking Layer Tranche 3 satellites, each carrying infrared missile-warning and missile-defense sensors, with launches scheduled for FY2029.
Global Military Satellite Market Report Scope
A military satellite is an artificial satellite designed, launched, and operated to support defense, national security, and strategic intelligence objectives. These satellites perform critical functions in modern defense operations, including communications, ISR, navigation and timing, early warning, and electronic intelligence (ELINT).
The military satellite market is segmented by application, satellite mass, orbit class, payload type, and geography. By application, the market is segmented into intelligence, surveillance, and reconnaissance (ISR), military communications, navigation and positioning, missile detection and early warning, and space domain awareness. By satellite mass, the market is segmented into small, medium, and large. By orbit class, the market is segmented into low Earth orbit (LEO), medium Earth orbit (MEO), and geostationary orbit (GEO). By payload type, the market is segmented into communication payloads, navigation payloads, imaging payloads, radar payloads, SIGINT and ELINT payloads, and missile-warning payloads. The report also covers the market sizes and forecasts for the military satellite market in major countries across different regions. For each segment, the market size is provided in terms of value (USD).
Segmentation Overview
| Intelligence, Surveillance and Reconnaissance |
| Military Communications |
| Navigation and Positioning |
| Missile Detection and Early Warning |
| Space Domain Awareness |
| Small |
| Medium |
| Large |
| Low Earth Orbit (LEO) |
| Medium Earth Orbit (MEO) |
| Geostationary Orbit (GEO) |
| Communication Payloads |
| Navigation Payloads |
| Imaging Payloads |
| Radar Payloads |
| SIGINT and ELINT Payloads |
| Missile-Warning Payloads |
| North America | United States | |
| Canada | ||
| Mexico | ||
| Europe | United Kingdom | |
| France | ||
| Germany | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Rest of South America | ||
| Middle East and Africa | Middle East | Saudi Arabia |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Rest of Africa | ||
| By Application | Intelligence, Surveillance and Reconnaissance | ||
| Military Communications | |||
| Navigation and Positioning | |||
| Missile Detection and Early Warning | |||
| Space Domain Awareness | |||
| By Satellite Mass | Small | ||
| Medium | |||
| Large | |||
| By Orbit Class | Low Earth Orbit (LEO) | ||
| Medium Earth Orbit (MEO) | |||
| Geostationary Orbit (GEO) | |||
| By Payload Type | Communication Payloads | ||
| Navigation Payloads | |||
| Imaging Payloads | |||
| Radar Payloads | |||
| SIGINT and ELINT Payloads | |||
| Missile-Warning Payloads | |||
| By Geography | North America | United States | |
| Canada | |||
| Mexico | |||
| Europe | United Kingdom | ||
| France | |||
| Germany | |||
| Russia | |||
| Rest of Europe | |||
| Asia-Pacific | China | ||
| Japan | |||
| India | |||
| Australia | |||
| Rest of Asia-Pacific | |||
| South America | Brazil | ||
| Rest of South America | |||
| Middle East and Africa | Middle East | Saudi Arabia | |
| United Arab Emirates | |||
| Rest of Middle East | |||
| Africa | South Africa | ||
| Rest of Africa | |||
Market Definition
- Application - Various applications or purposes of the satellites are classified into communication, earth observation, space observation, navigation, and others. The purposes listed are those self-reported by the satellite’s operator.
- End User - The primary users or end users of the satellite is described as civil (academic, amateur), commercial, government (meteorological, scientific, etc.), military. Satellites can be multi-use, for both commercial and military applications.
- Launch Vehicle MTOW - The launch vehicle MTOW (maximum take-off weight) means the maximum weight of the launch vehicle during take-off, including the weight of payload, equipment and fuel.
- Orbit Class - The satellite orbits are divided into three broad classes namely GEO, LEO, and MEO. Satellites in elliptical orbits have apogees and perigees that differ significantly from each other and categorized satellite orbits with eccentricity 0.14 and higher as elliptical.
- Propulsion tech - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Mass - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Subsystem - All the components and subsystems which includes propellants, buses, solar panels, other hardware of satellites are included under this segment.
| Keyword | Definition |
|---|---|
| Attitude Control | The orientation of the satellite relative to the Earth and the sun. |
| INTELSAT | The International Telecommunications Satellite Organization operates a network of satellites for international transmission. |
| Geostationary Earth Orbit (GEO) | Geostationary satellites in Earth orbit 35,786 km (22,282 mi) above the equator in the same direction and at the same speed as the earth rotates on its axis, making them appear fixed in the sky. |
| Low Earth Orbit (LEO) | Low Earth Orbit satellites orbit from 160-2000km above the earth, take approximately 1.5 hours for a full orbit and only cover a portion of the earth’s surface. |
| Medium Earth Orbit (MEO) | MEO satellites are located above LEO and below GEO satellites and typically travel in an elliptical orbit over the North and South Pole or in an equatorial orbit. |
| Very Small Aperture Terminal (VSAT) | Very Small Aperture Terminal is an antenna that is typically less than 3 meters in diameter |
| CubeSat | CubeSat is a class of miniature satellites based on a form factor consisting of 10 cm cubes. CubeSats weigh no more than 2 kg per unit and typically use commercially available components for their construction and electronics. |
| Small Satellite Launch Vehicles (SSLVs) | Small Satellite Launch Vehicle (SSLV) is a three-stage Launch Vehicle configured with three Solid Propulsion Stages and a liquid propulsion-based Velocity Trimming Module (VTM) as a terminal stage |
| Space Mining | Asteroid mining is the hypothesis of extracting material from asteroids and other asteroids, including near-Earth objects. |
| Nano Satellites | Nanosatellites are loosely defined as any satellite weighing less than 10 kilograms. |
| Automatic Identification System (AIS) | Automatic identification system (AIS) is an automatic tracking system used to identify and locate ships by exchanging electronic data with other nearby ships, AIS base stations, and satellites. Satellite AIS (S-AIS) is the term used to describe when a satellite is used to detect AIS signatures. |
| Reusable launch vehicles (RLVs) | Reusable launch vehicle (RLV) means a launch vehicle that is designed to return to Earth substantially intact and therefore may be launched more than one time or that contains vehicle stages that may be recovered by a launch operator for future use in the operation of a substantially similar launch vehicle. |
| Apogee | The point in an elliptical satellite orbit which is farthest from the surface of the earth. Geosynchronous satellites which maintain circular orbits around the earth are first launched into highly elliptical orbits with apogees of 22,237 miles. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. For sales conversion to volume, the average selling price (ASP) is kept constant throughout the forecast period for each country, and inflation is not a part of the pricing.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


