
Freeze Dried Food Market Analysis by Mordor Intelligence
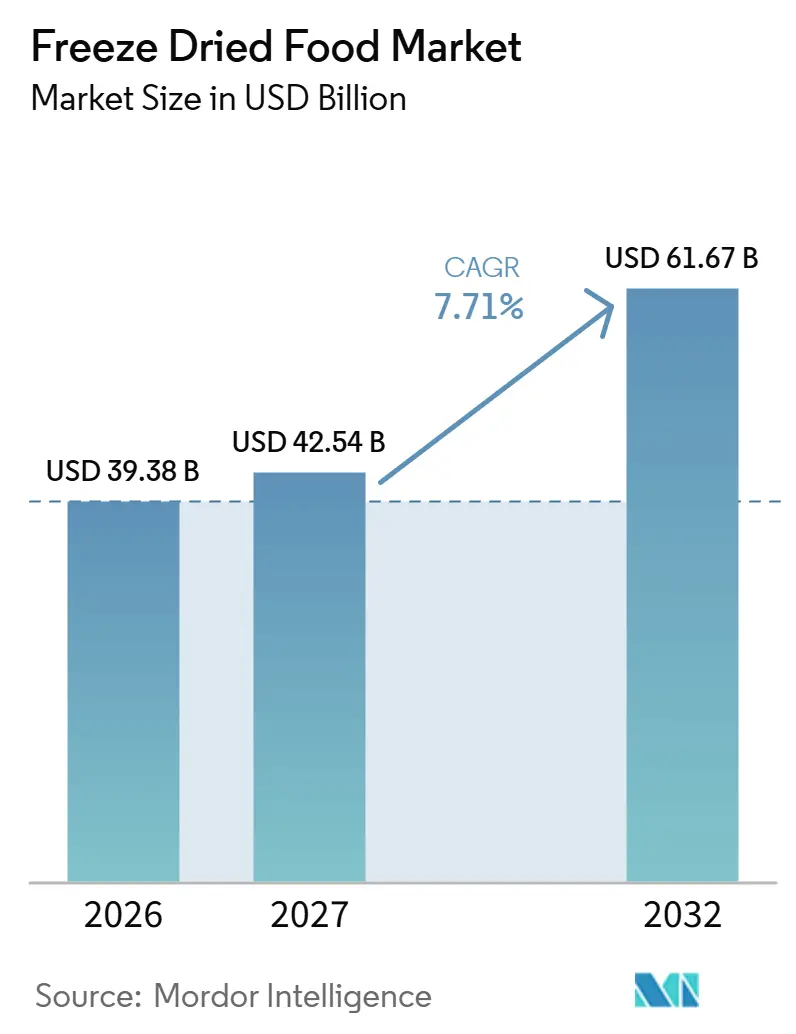
The freeze dried food market size is expected to increase from USD 39.38 billion in 2026 to USD 42.54 billion in 2027 and reach USD 61.67 billion by 2032, growing at a CAGR of 7.71% over 2027-2032.
Consumer discovery of snack formats and wider ingredient uses support demand across different eating occasions, including fruit within blended toddler snacks. In the United States, growing camping participation adds outdoor meal occasions, while social-media discovery encourages trial of freeze-dried candy. Brands and contract processors can respond through consumer products and manufacturing services, while batch constraints and energy costs limit expansion economics. The strongest commercial openings lie in high-value, heat-sensitive ingredients whose retained flavor and color can justify the processing premium.
Key Report Takeaways
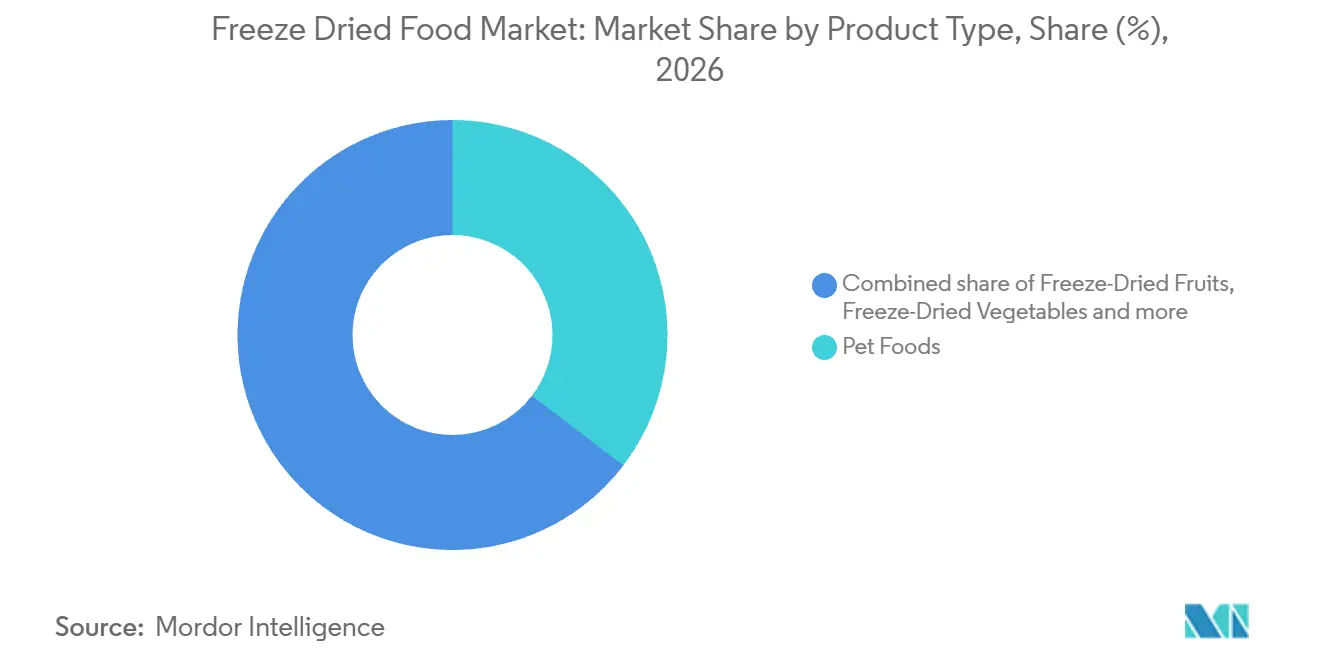
- By product type, pet foods led with a 35.38% freeze dried food market share in 2026, while freeze-dried vegetables are forecast to grow fastest at a CAGR of 9.1% over 2027-2032.
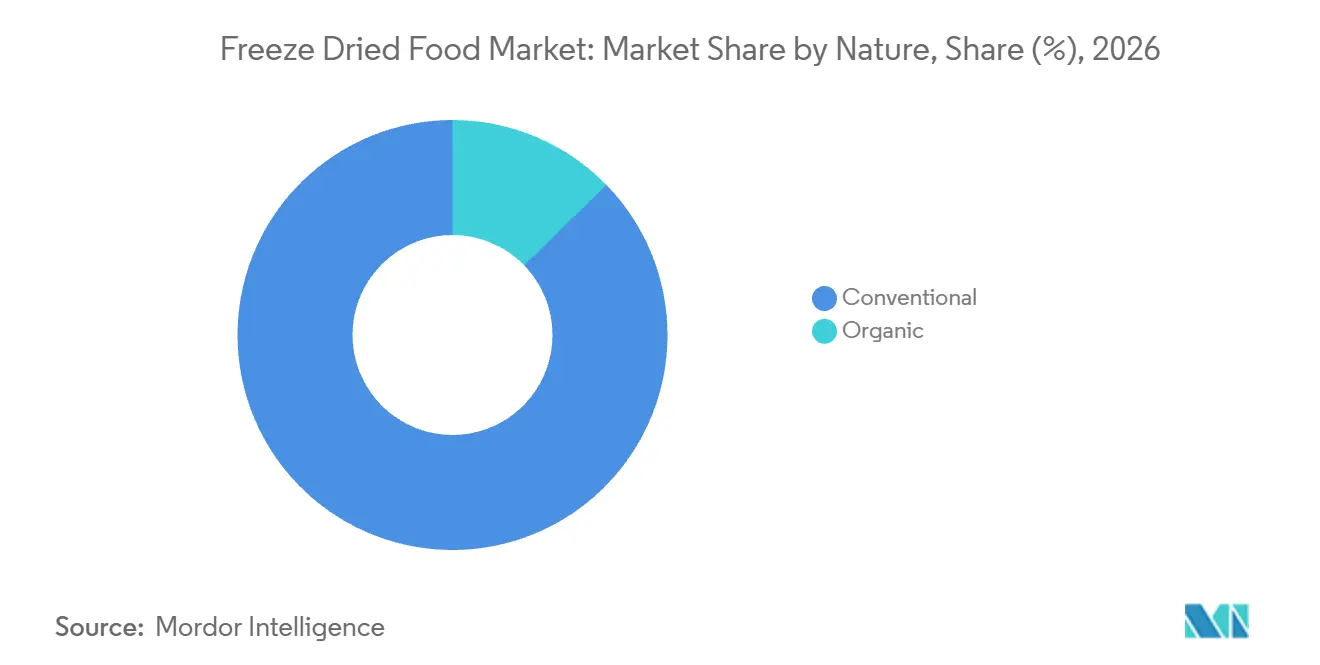
- Within the nature segmentation, conventional products held an 87.3% share of the freeze dried food market size in 2026, and organic products are forecast to record the fastest CAGR of 9% over 2027-2032.
- Supermarkets/hypermarkets led distribution with 54.84% of the market in 2026, with online stores projected to grow fastest at a CAGR of 10% over 2027-2032.
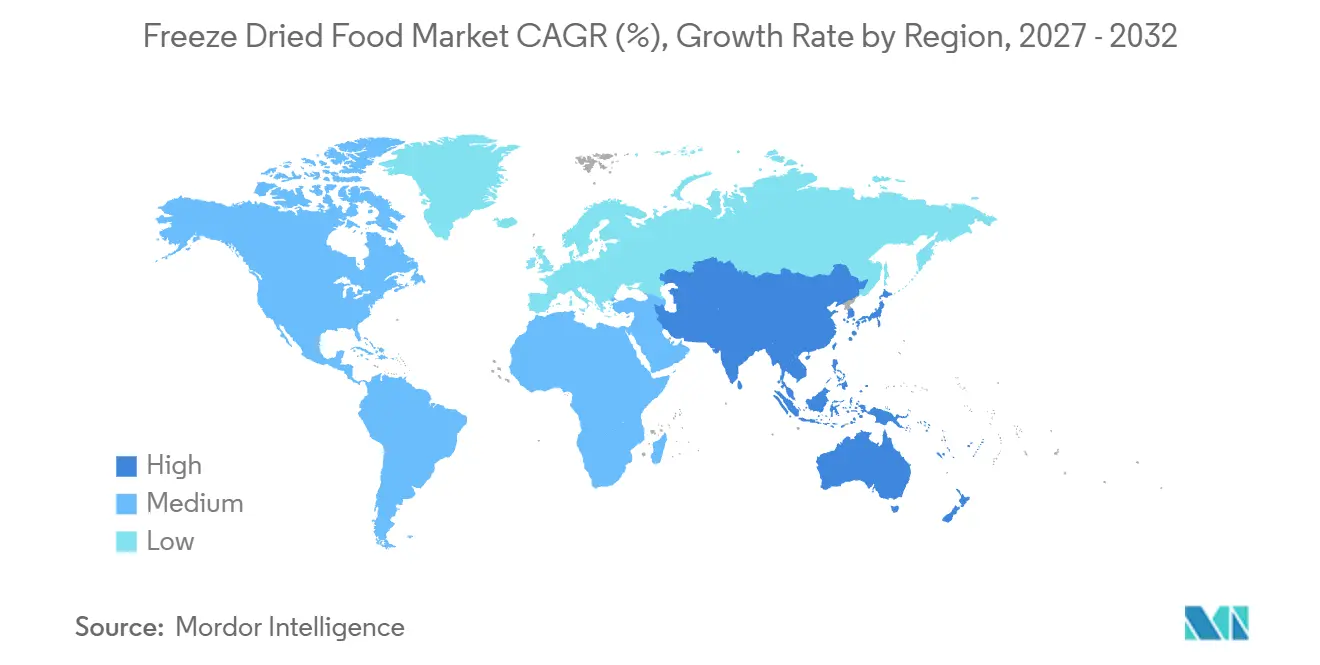
- Geographically, North America held the largest share at 34.69% in 2026, while Asia-Pacific is forecast to grow fastest at a CAGR of 9.05% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Freeze Dried Food Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Social Media Influence Boosting Market Growth | +2% | The United States | Short term (≤ 2 years) |
| Growth of Adventure, Outdoor, and Emergency Food Markets | +2.5% | The United States | Medium term (2-4 years) |
| Global Disruption Driving Interest in Shelf-Stable Foods | +2.3% | North America and Europe | Medium term (2-4 years) |
| Rise in Infant and Toddler Freeze-Dried Snacks | +1.6% | Canada and Singapore | Medium term (2-4 years) |
| Culinary and Foodservice Innovation | +0.8% | United States, Canada and Mexico | Medium term (2-4 years) |
| Snackification of Whole Ingredients | +1.1% | The United States | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Social Media Influence Boosting Market Growth
Social discovery gives freeze-dried candy a route to consumer trial that starts before shoppers encounter a retail shelf. By summer 2026, videos under #freezedriedcandy had accumulated more than 4.7 billion TikTok views, which Hershey’s senior brand manager for sweets credited with helping drive awareness, trial and demand. Taffy Town’s chief marketing officer said social media played a major role in the category’s growth, which began with hobbyists experimenting with home freeze-drying appliances. A pack recognizable from the online demonstration can carry consumer curiosity through to a first purchase.
Growth of Adventure, Outdoor, and Emergency Food Markets
Growing camping participation expands the pool of potential customers for freeze-dried meals designed for use away from home. The Outdoor Industry Association reported 42.3 million US vehicle-accessible camping participants in 2025, up more than 5% in one year. That makes campsite eating a specific consumer occasion around which meal brands can develop assortments. The commercial opening is an assortment sized around those occasions, allowing a meal brand to pursue new campers without depending on a change in their everyday diet.
Global Disruption Driving Interest in Shelf-Stable Foods
For households and institutional stockpilers in North America and Europe, freeze-dried meals offer a way to separate food storage from immediate consumption. Long ambient shelf life makes the format suited to holding complete meals for interruptions to ordinary replenishment. A household can build a pantry around the meals it expects to use, while an institution must consider portions across a larger stored assortment. By June 2026, Sweden’s Board of Agriculture had its first wheat contingency reserves in place in 4 northern counties, with suppliers storing and rotating the grain. Replacement purchases would then follow stock rotation and use, creating a replenishment cycle distinct from everyday grocery demand. Initial stocking and later replacement call for distinct meal offers because their purchase cycles differ.
Rise in Infant and Toddler Freeze-Dried Snacks
Toddler snacks give freeze-dried fruit a commercial route into blended products alongside sales of standalone fruit pieces. In July 2026, Little Bellies announced 5 new organic snacks for Walmart Canada nationwide, including 2 Nibbles variants for toddlers aged 12 months and older. The Nibbles combine puffed corn stars with freeze-dried fruit, placing the preserved ingredient within a snack offering different textures and shapes. This broadens the potential use of freeze-dried ingredients beyond finished snacks composed entirely of dried pieces. The ingredient sale depends on fitting the toddler-snack formulator’s blend with puffed corn rather than recreating a standalone fruit pouch.
Restraints Impact Analysis of Freeze Dried Food Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Production Costs and Capital Investment | -1.1% | United States, Europe and Asia-Pacific | Medium term (2-4 years) |
| Energy Consumption and Sustainability Concerns | -0.8% | North America, Europe and Asia-Pacific | Long term (≥ 4 years) |
| Consumer Perception as “Artificial” or “Space Food” | -0.3% | North America and Europe | Medium term (2-4 years) |
| Competition from Alternatives | -0.4% | Nationwide in Thailand | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Production Costs and Capital Investment
Batch processing raises freeze-drying operating costs, which a 2026 food-processing review puts at 50% to 70% of total production expenses. The review identifies throughput bottlenecks as a barrier to high-volume production, linking the cost burden to output constraints. On December 30, 2025, freeze-dried candy producer Sow Good Inc. sold 6 proprietary freeze-drying machines and other manufacturing assets to related-party buyer Trea Grove. The assets had an aggregate net book value of approximately USD 10.79 million, compared with total consideration of USD 1.5 million. The sale price was a fraction of the assets’ recorded value, demonstrating the capital downside in that related-party transaction. Batch-limited throughput leaves producers seeking higher volumes with an operating-cost burden.
Energy Consumption and Sustainability Concerns
Energy requirements limit how widely industrial food processors can justify freeze-drying beyond applications that reward superior product quality. A 2026 food-industry review identified prolonged refrigeration and sustained vacuum pumping as sources of substantial energy demand.[1] It found the process economically justifiable primarily for high-value, thermally sensitive ingredients whose quality commands a premium. This makes the commercial hurdle the price customers will pay for preserved quality relative to the expense of achieving it. Extending the process into lower-priced foods depends on recovering its energy cost, narrowing the applications that can sustain the required production expense.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Freeze Dried Food Market Segment Analysis
By Product Type:
Pet-Food Scale and Vegetable Retail ExpansionPet foods accounted for a 35.38% share of the freeze dried food market size in 2026. Shepherd Boy Farms’ second-facility expansion in Greensburg, Indiana, was reported underway in October 2026. In November 2025, the producer forecast combined annual output above 20 million pounds of freeze-dried pet food from its existing and planned facilities. Its manufacturing model includes co-manufacturing and private-label partnerships, connecting the production project to business from other pet brands. Orders from other pet brands will matter alongside Shepherd Boy Farms’ own sales when filling the planned capacity.
Freeze-dried vegetables are the fastest-growing segment, with a forecast CAGR of 9.1% over 2027-2032. JUX secured a Tesco listing in the United Kingdom for its freeze-dried vegetables, herbs and spices in 2025. That brings the vegetable range into a grocery setting through which the brand can seek additional cooking-ingredient business. In 2026, JUX Food’s freeze-dried vegetables were also available through Ocado, CLF and independent retailers in the United Kingdom. Freeze-dried beverages showed a separate packaging pattern, with Strauss Group reporting that leading competitors in Russia began reducing freeze-dried instant-coffee pack sizes in the fourth quarter of 2025.



By Nature:
Conventional Scale and Organic Consumer DemandConventional products represented an 87.3% freeze dried food market share in 2026. Established supply chains and mainstream price points support an offer aimed at mass retailers and food-ingredient buyers. Pet foods and prepared meals give those retailers finished-product applications, while fruit and vegetable ingredients give processors an input for their own recipes. For these buyers, the preservation format must justify its cost through the food application rather than through organic positioning. Conventional suppliers can spread their offer across pet foods, meals and ingredients instead of relying on a single premium application.
Organic products are the fastest-growing segment, with a forecast CAGR of 9% over 2027-2032. US organic food consumer sales totaled USD 70.1 billion in 2025. That consumer base gives organic food brands a substantial audience from which to seek demand for freeze-dried formats. Suppliers entering this niche need a preserved ingredient or meal that fits the intended food application, so the growth proposition combines that application with organic positioning. For an organic brand, freeze-drying offers another format for reaching an established organic-food audience.

By Distribution Channel:
Grocery Reach and Digital Sales GrowthSupermarkets/hypermarkets accounted for 54.84% of the market in 2026, making them the largest distribution segment. In December 2025, Stella & Chewy’s announced a freeze-dried raw dog-food rollout to more than 1,400 Publix supermarkets across 8 southeastern US states, beginning that month. The announced range included Meal Mixers, Dinner Dust and Breakfast Sprinkles for shoppers making their regular grocery trips. The announced Publix placement would let shoppers add the range to a household grocery trip without a dedicated pet-store visit.
Online stores are the fastest-growing segment, with a forecast CAGR of 10% over 2027-2032. FMI and NielsenIQ reported that US online food sales rose nearly 19% in 2025.[2] This gives freeze-dried suppliers a growing general food-shopping channel through which to seek additional demand. Other distribution channels include specialty pet retail. In September 2025, Carnivore Meat Company’s Vital Essentials launched freeze-dried raw dog and cat food and treats in more than 725 US Pet Supplies Plus stores and on the retailer’s website.
Geography Analysis
North America Freeze Dried Food Market
North America accounted for a 34.69% share of the freeze dried food market size in 2026. In August 2025, Formula Raw Inc. opened a freeze-dried pet-food facility in Montreal, Canada, and stated that monthly production increased from 7.5 metric tons to more than 30 metric tons. The company said the added capacity would let it support new retail and distribution partners in the United States. That gives the Montreal plant a commercial role serving customers on both sides of the border.
Asia-Pacific Freeze Dried Food Market
Asia-Pacific is the fastest-growing region, with a forecast CAGR of 9.05% over 2027-2032. In the first half of 2026, Food Empire’s South Asia revenue rose 4.4% to USD 38.6 million on stronger demand for freeze-dried and spray-dried soluble coffee. Both of its Indian manufacturing facilities operated at full utilization during that period. At that full-utilization level, further soluble-coffee orders would require added drying capacity.
In Europe, a May 2025 Latvian agency report said Roga-Agro’s Good Mood Meals were sold through specialist tourism and active-leisure stores in Latvia and through stores and online platforms in France, the Netherlands and Finland. This connects a Latvian prepared-meal producer with leisure buyers and cross-border retail distribution. In South America, Colombia’s National Federation of Coffee Growers opened Buencafé’s Chinchiná logistics center in September 2025 to support storage and distribution of freeze-dried coffee to more than 60 countries. Within Middle East and Africa, Kenya’s Wambugu Apples launched freeze-dried fruit in Nairobi in April 2025 and reported processing apples, mangoes, strawberries, dragon fruit and bananas. These examples address different commercial tasks, from reaching leisure retailers to handling coffee exports and adding fruit-processing capacity.
Regional Editions
Regulatory Framework and Outlook
The comparison assesses selected jurisdictions from the perspective of manufacturers selling packaged human freeze-dried foods. Covered US facilities must implement food-safety plans, while Saudi market-entry conditions include food-business registration and licensing. These duties affect both the operating controls behind a food product and the steps required to bring it to customers, with labeling and packaging transitions adding country-specific adaptation work.
Regulatory Table of Freeze Dried Food Market
| Decision factor | United States | Germany | China | Brazil | Saudi Arabia |
|---|---|---|---|---|---|
| Primary authority | Food and Drug Administration | Federal-state food-control authorities and local inspection offices | State Administration for Market Regulation | Anvisa | Saudi Food and Drug Authority |
| Key instruments or direction | 21 CFR Part 117; front-of-package final rule scheduled for December 2026 | EU Regulation 1169/2011; EU Regulation 2025/40 recyclability grades from January 1, 2030 or 24 months after relevant delegated acts take effect, whichever is later | GB 7718-2011 during transition; GB 7718-2025 and food-label measures effective March 16, 2027 | RDC 429/2020 and IN 75/2020; ingredient and digital-label consultations planned for fourth-quarter 2027 | Food Hygiene Requirements and GSO 9 labeling; GSO 2233:2025 nutrition standard effective January 1, 2028 |
| Commercial effect | Covered facilities need hazard-based written plans; exemptions and modified requirements apply | Covered labels need ingredient, allergen and durability information; covered packaging placement will depend on grades A, B or C | Prepackaged-food label transition; online sellers must publish specified label information from March 16, 2027 | Covered packaged foods need nutrition tables and applicable front-of-package information | Site registration and licensing, Arabic consumer labels and approval conditions for foreign animal-origin premises |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Low |
| Future direction of policy attractiveness | Hardening | Hardening | Hardening | Hardening | No change |
| Source: Mordor Intelligence | |||||
The medium US and German ratings reflect defined operating and label duties, while scheduled nutrition-label rulemaking and future packaging-placement conditions support a hardening outlook. China’s medium rating combines an established label framework with a March 16, 2027 transition whose online-information requirements underpin the hardening direction. Brazil’s medium rating and hardening direction reflect current nutrition labeling plus proposed ingredient and digital-label work scheduled for consultation in the fourth quarter of 2027. Saudi Arabia’s low rating reflects establishment-level entry and import conditions, while adopted GSO 2233:2025 nutrition-labeling requirements take effect January 1, 2028.
Value Chain Stages
The value chain compares agricultural preparation, commercial freeze-drying and the sale of finished foods across integrated and specialist business models. Van Drunen Farms combines growing with ingredient manufacturing, while THRIVE FREEZE DRY and European Freeze Dry offer food-industry processing services. These models place value capture at different points, allowing a supplier to earn from its own ingredients or from transforming products for another business.
Value Chain Analysis Table of Freeze Dried Food Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Cultivation and ingredient preparation | Integrated growers and ingredient manufacturers such as Van Drunen Farms | Agricultural value embedded in commercial ingredient sales | Matching crop mix to requested ingredient specifications | Set processor specifications before planting |
| Freeze-drying and contract processing | Ingredient and contract-drying manufacturers such as THRIVE FREEZE DRY and European Freeze Dry | Ingredient sales, contract-processing fees and private-label product sales | Allocating drying capability among tailored customer products | Qualify alternative processors for required food applications |
| Finished-food packaging and sales | Branded meal sellers such as Mountain House, and direct and wholesale food sellers such as Harmony House Foods | Packaged-food sales and bulk wholesale revenue | Serving distinct consumer-pack and bulk-order requirements | Separate bulk-order handling from consumer-pack fulfillment |
| Source: Mordor Intelligence | ||||
Because THRIVE FREEZE DRY supplies ingredients and offers private-label manufacturing, a food brand can reach finished products without owning drying capacity. That separates ownership of the consumer brand from ownership of production capacity. Ingredient sales and private-label manufacturing let the processor earn from both intermediate inputs and finished foods.
Competitive Landscape
Market Concentration
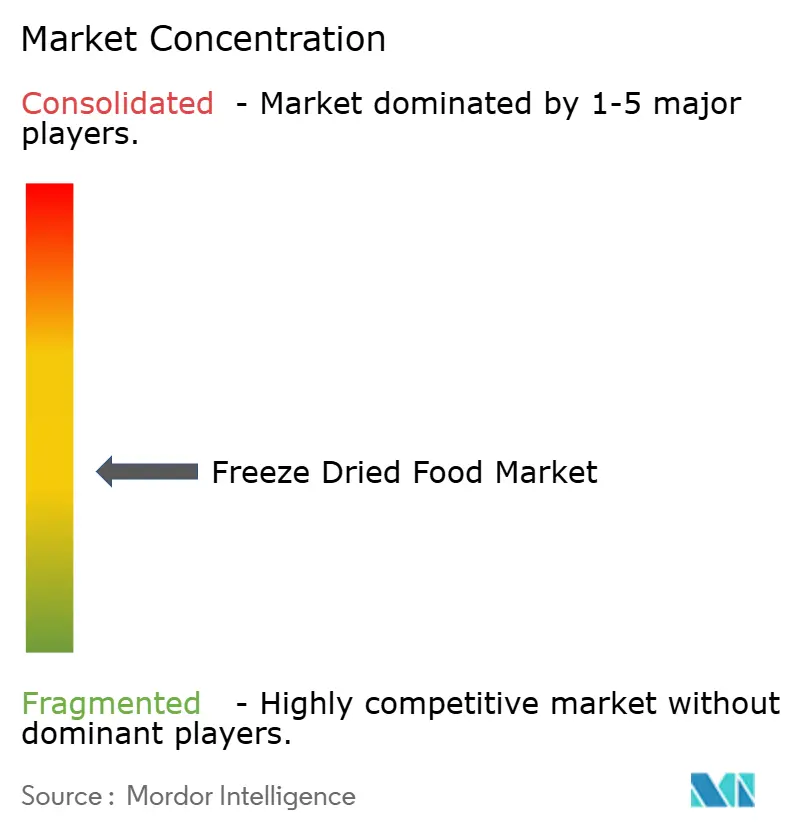
Major participants include Nestlé S.A., Ajinomoto Co. Inc., Asahi Group Foods Ltd., OFD Foods LLC (Mountain House), and European Freeze Dry. Nestlé used freeze-drying technology in Nescafé Iced Blend, launched in Japan in 2025, while Ajinomoto Group’s wholly owned Ajinomoto AGF manufactures and sells food and beverages in Japan. In 2025, Asahi Group Foods repackaged 3 Amano Foods freeze-dried meals as a rice-topping series without changing their contents, giving the existing recipes a more specific eating-occasion proposition. Branded meals and soluble coffee coexist with European Freeze Dry’s ingredient, meal and pet-treat production, creating several distinct supply models.
Mountain House’s shelf-life positioning illustrates how a supplier can compete on the promised quality of long-storage meals. In March 2025, the OFD Foods division raised its stated shelf life for freeze-dried entrees in cans and pouches to 30 years, based on its testing and taste standard.[3] The company linked the change to consumer expectations that stored emergency food should retain an acceptable taste. Its announcement said revised Best By dates would appear on packaging by the end of 2025. For emergency-food buyers, the claim ties storage life to how the meal tastes at the end of that period.
European Freeze Dry also offers commission drying services, providing a processing route alongside the branded-meal businesses. A challenger can therefore choose to supply a food application without building a consumer meal brand around it. Competing directly with Mountain House would require an eating-quality proposition that buyers can weigh against its tested storage claim. Asahi’s meal presentation similarly makes the intended use part of differentiation rather than relying on the preservation method alone. In March 2025, OFD Foods’ president contrasted Mountain House’s “tastes as good as new” standard with the “will sustain life” standard he attributed to many competitors, making the taste basis essential to interpreting shelf-life claims.
Freeze Dried Food Industry Leaders
-
Nestlé S.A.
-
Ajinomoto Co. Inc.
-
Asahi Group Foods Ltd.
-
OFD Foods LLC (Mountain House)
-
European Freeze Dry
- *Disclaimer: Major Players sorted in no particular order
Freeze Dried Food Market Companies Covered in this Report
- Nestlé S.A.
- Ajinomoto Co. Inc.
- Asahi Group Foods Ltd.
- OFD Foods LLC (Mountain House)
- European Freeze Dry
- Harmony House Foods Inc.
- Lyofood Sp. z o.o.
- Crispy Green Inc.
- Katadyn Products Inc.
- Chaucer Foods Ltd
- Mercer Foods LLC
- Thrive Life LLC
- Sow Good Inc.
- Freeze Dried USA
- Nutristore (ReadyWise)
- Tasman Foods NZ
- Forager Food Co.
- Brothers All Natural
- Van Drunen Farms
- Paradise Fruits Freeze Dried
Key Opportunities for Market Participants
The opportunities compare extending freeze-dried desserts into new eating occasions with reducing the preparation burden of introductory baby foods. In 2025, JonnyPops introduced 3 flavors of melt-free, shelf-stable freeze-dried popsicles at select US retailers, describing the format as the first of its kind. In Japan, Kikkoman Group subsidiary fufumu began full-scale sales of paqupa in 2025, using freeze-dried ingredient cubes including eggs, peanuts and nuts to address parental preparation concerns. Dessert producers can pursue ambient snack shelves, whereas baby-food suppliers can address preparation effort through ingredient cubes suited to introductory feeding.
Market Opportunities Table of Freeze Dried Food Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Ambient dessert-snack extensions | Commercial freeze-dried dessert formats offer shelf stability and melt-free handling | Grocery snack-category buyers | Position dessert flavors within ambient snack assortments | Earning additional retailer placement | Freeze-dried snack brands such as JonnyPops |
| Portable desserts for travel and outdoor occasions | Melt-free formats permit dessert consumption without frozen storage | Travel retailers and outdoor snack buyers | Develop packs suited to portable dessert occasions | Establishing repeat demand in an additional channel | Freeze-dried dessert producers |
| Ingredient cubes for introductory baby foods | Commercial egg and nut ingredient formats address preparation effort | Caregivers introducing new foods | Offer clearly identified ingredient cubes with preparation information | Building caregiver confidence around allergy-sensitive ingredients | Baby-food suppliers such as fufumu, part of Kikkoman Group |
| Source: Mordor Intelligence | |||||
Ambient dessert placement is the clearest opening because the preservation format changes where a dessert-style snack can be sold and consumed. The JonnyPops recipes combine fruit and cream, giving the new format a familiar dessert foundation. Further expansion depends on shelf placement beyond the initial select locations and on repeat demand, neither of which the preservation format guarantees.
Recent Industry Developments in Freeze Dried Food Market
- Jul 2026: Little Bellies announced 5 new organic snacks for Walmart Canada nationwide, including 2 Nibbles variants for toddlers aged 12 months and older combining puffed corn stars with freeze-dried fruit.
- May 2026: Golden Pet Brands completed its acquisition of Petsource’s pet-food production facility in Seward, Nebraska, on May 8, adding a site whose activities included freeze-drying and packaging high-protein pet-food ingredients.
Freeze Dried Food Market Report Scope and Research Methodology
Market Definition and Coverage
The freeze-dried food market covers packaged and bulk foods preserved by freeze-drying for human and pet consumption worldwide. Its value measures annual supplier sales of these foods in USD, classified by product type, nature, distribution channel, and geography.
Scope exclusions: Freeze-dried pharmaceuticals, freeze-dried lab reagents, industrial freeze-drying equipment and services, and food inputs sold separately from freeze-dried food are excluded.
Segments Covered in This Report
- By Product Type
- Freeze-Dried Fruits
- Strawberry
- Raspberry
- Pineapple
- Apple
- Mango
- Other Fruits
- Freeze-Dried Vegetables
- Pea
- Corn
- Carrot
- Potato
- Mushroom
- Other Vegetables
- Freeze-Dried Meat and Seafood
- Freeze-Dried Dairy Products
- Freeze-Dried Beverages (Instant Coffee, Tea)
- Prepared Meals
- Pet Foods
- Freeze-Dried Fruits
- By Nature
- Conventional
- Organic
- By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Stores
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
The USDA Economic Research Service's Organic Agriculture data describe organic food sales and certified acreage, while its Food Expenditure Series tracks spending by outlet and purchaser. The US Census Bureau's quarterly retail e-commerce series tracks channel direction, and analysts use these series to test demand, product-nature, and channel trends for food categories that include freeze-dried products. UN Comtrade product and partner records cross-check cross-border movement where customs categories are relevant.
Company filings, 10-Ks, investor materials, regulatory documents, and reputable food-industry reporting provide product, capacity, geography, and channel clues that analysts compare with public category and trade indicators. These named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include senior executives, product and operations leaders, sales and channel managers, and buyers familiar with freeze-dried foods across producers, processors, distributors, retailers, foodservice, and pet-food businesses. Their input would test secondary findings on product mix, supplier selling prices, capacity, channel demand, and regional differences, while analysts would resolve gaps by comparing respondent ranges with public records and independent supply and demand signals.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 15% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 40% | EMEA: 32% |
| Smaller Players: 25% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
The analyst estimates global annual supplier sales in USD with a top-down model, then develops product-type, organic or conventional, distribution-channel, and regional shares from revenue disclosures, shipment patterns, retail and foodservice demand, and regional supply evidence. A multivariate regression can relate annual market value to five indicators: freeze-drying capacity and output, crop availability and prices, food sales by outlet including e-commerce and foodservice, organic food demand, and industrial energy costs. Scenario analysis tests alternative capacity and energy-cost paths.
Where supplier disclosures provide product-level sales or shipment volume and selling prices, analysts use supplier roll-ups or sampled average selling price times shipment volume as selective bottom-up checks against the top-down total, counting each supplier sale once. Analysts compare trade flows and broader food-category series with supplier and channel evidence to contextualize demand and cross-border movement. Experts can check whether the selected variables and forecast directions fit procurement, capacity, pricing, and channel conditions, with conflicting evidence prompting a variable-level revision or a wider range.
Data Validation & Update Cycle
Analysts triangulate the estimate against independent supplier, trade, retail, food-category, and channel signals, checking units, currency, year, and transaction basis before comparisons. They flag unusual annual changes, unexplained share movements, and gaps between demand, capacity, and reported sales, trace each variance to its source, and complete successive analyst and senior reviews before sign-off. A respondent is re-contacted when an answer materially conflicts with later records or a changed facility, product mix, or channel. Analysts refresh the model annually, between cycles after material events, and in a fresh pre-delivery review.
Mordor Intelligence's Freeze Dried Food Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The freeze-dried food market covers packaged and bulk foods preserved by freeze-drying for human and pet consumption worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. A multivariate regression can relate annual market value to five indicators: freeze-drying capacity and output, crop availability and prices, food sales by outlet including e-commerce and foodservice, organic food demand, and industrial energy costs.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 42.54 B (2027) | |
| Global Consultancy A | USD 51.8 B (2027) | At its 2027 base, this estimate is 21.8% above this report's 2027 value of USD 42.54 B. Its forecast advances from a 2021 base through the stated 8.8% growth path to a 2027 endpoint, placing a stronger multi-year growth assumption behind its same-year value. |
| Global Consultancy B | USD 52.71 B (2027) | At its 2027 base, this estimate is 23.9% above this report's 2027 value of USD 42.54 B. Its published 2026 valuation is above the accepted report's prior-year base, so the same-year 2027 endpoint starts from a higher value. |
Mordor Intelligence's analysts triangulate the estimate against independent supplier, trade, retail, food-category, and channel signals, checking units, currency, year, and transaction basis before comparisons.
Key Questions Answered in the Report
What is the freeze dried food market size and growth outlook?
The size is expected to increase from USD 42.54 billion in 2027 to USD 61.67 billion in 2032, growing at a CAGR of 7.71% over 2027-2032.
What is driving demand for freeze-dried foods?
Social discovery, outdoor meal occasions and toddler-snack applications support demand. Little Bellies’ July 2026 announcement for Walmart Canada illustrates freeze-dried fruit use in blended toddler snacks.
Which freeze-dried product category leads sales?
Pet foods held a 35.38% share in 2026, while freeze-dried vegetables are forecast to grow fastest at a CAGR of 9.1% over 2027-2032.
Which companies are major freeze-dried food suppliers?
Major participants include Nestlé S.A., Ajinomoto Co. Inc., Asahi Group Foods Ltd., OFD Foods LLC (Mountain House), and European Freeze Dry.
What is the main challenge for freeze-dried food producers?
A 2026 food-processing review puts operating costs, which batch processing raises, at 50% to 70% of total production expenses and identifies throughput bottlenecks that limit high-volume production.
Which regions lead the freeze-dried food industry?
North America held 34.69% of the market in 2026, while Asia-Pacific is forecast to grow fastest at a CAGR of 9.05% over 2027-2032.