
Saudi Arabia Construction Market Analysis by Mordor Intelligence
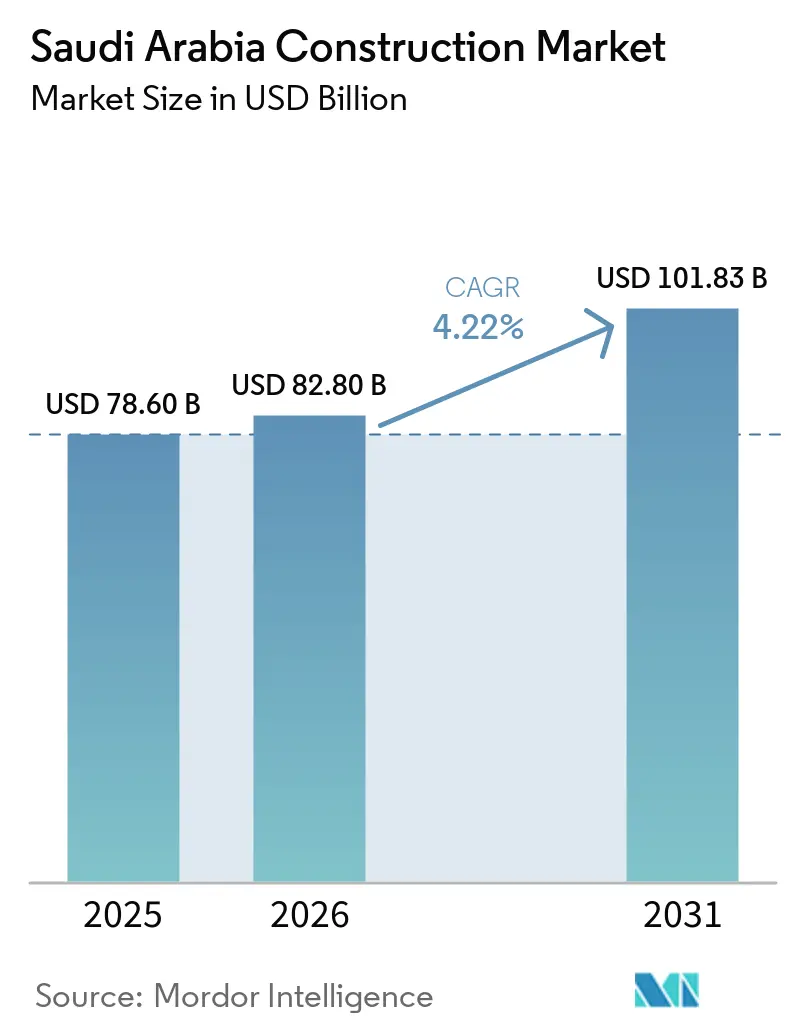
The Saudi Arabia construction market size was valued at USD 82.8 billion in 2026 and estimated to grow from USD 86.29 billion in 2027 to reach USD 104.7 billion by 2032, at a CAGR of 3.94% during the forecast period (2027-2032).
Saudi Arabia’s destination development, housing programs and utility investment sustain work across buildings and their supporting infrastructure. Specialist-trade shortages and cost pressure can slow conversion of that pipeline into finished assets, tempering expansion despite the breadth of development demand. Prefabricated modular delivery can bundle accommodation with operating services, while private finance can fund neighborhood buildings alongside a land contribution. Modular delivery and privately financed schemes are positioned to outpace overall expansion, broadening growth beyond the destination-project pipeline.
Key Report Takeaways
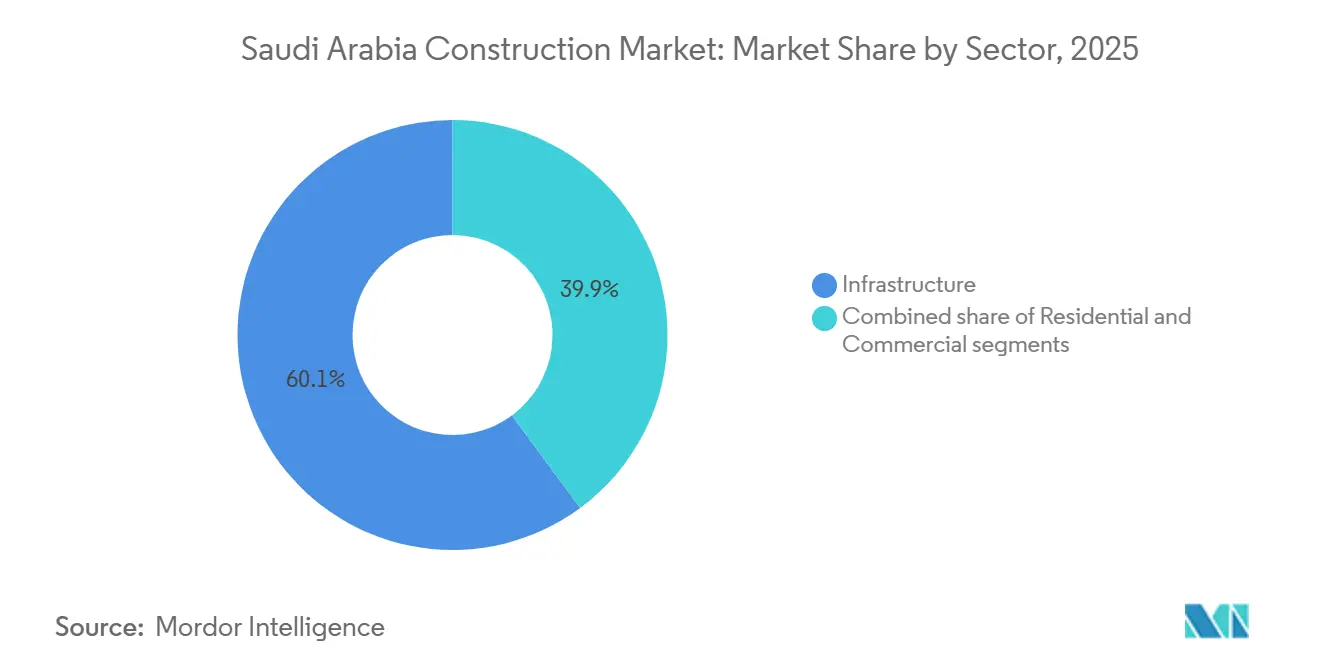
- Across sectors, infrastructure held a 59.96% Saudi Arabia construction market share in 2026, while residential construction is forecast to grow fastest at a CAGR of 4.82% during 2027-2032.
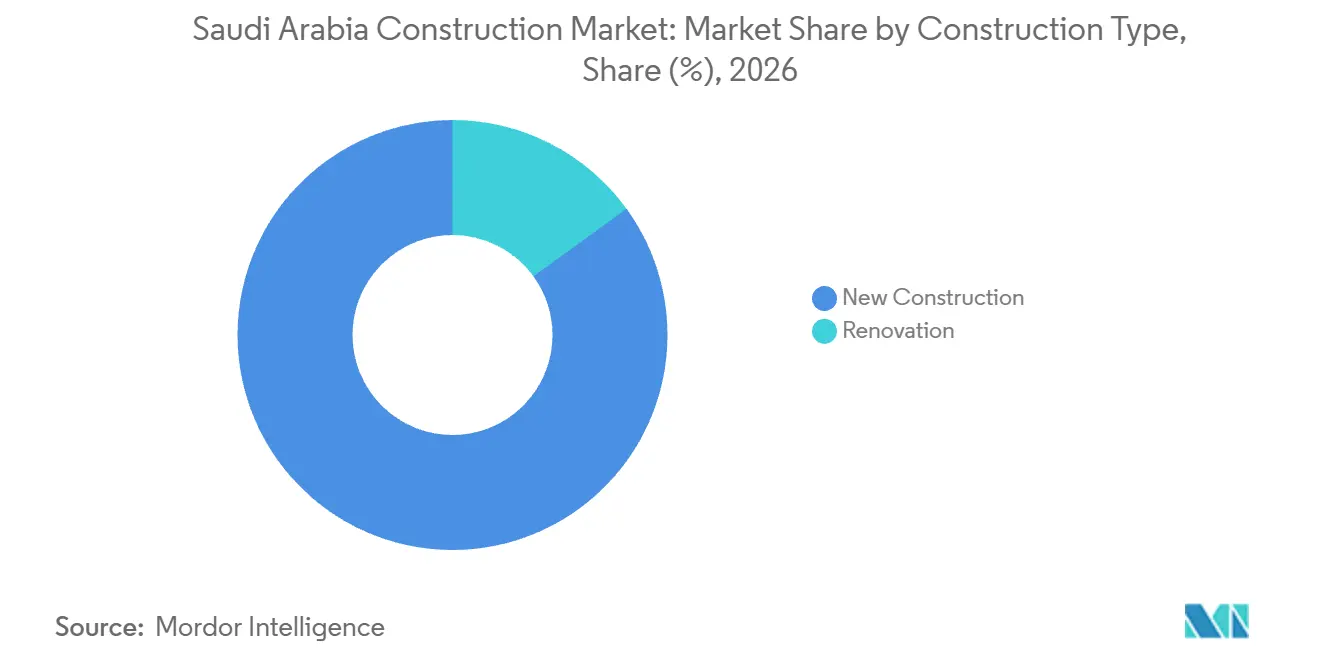
- By construction type, new construction accounted for an 84.99% share of the Saudi Arabia construction market size in 2026, and renovation is forecast to grow fastest at a CAGR of 4.55% during 2027-2032.
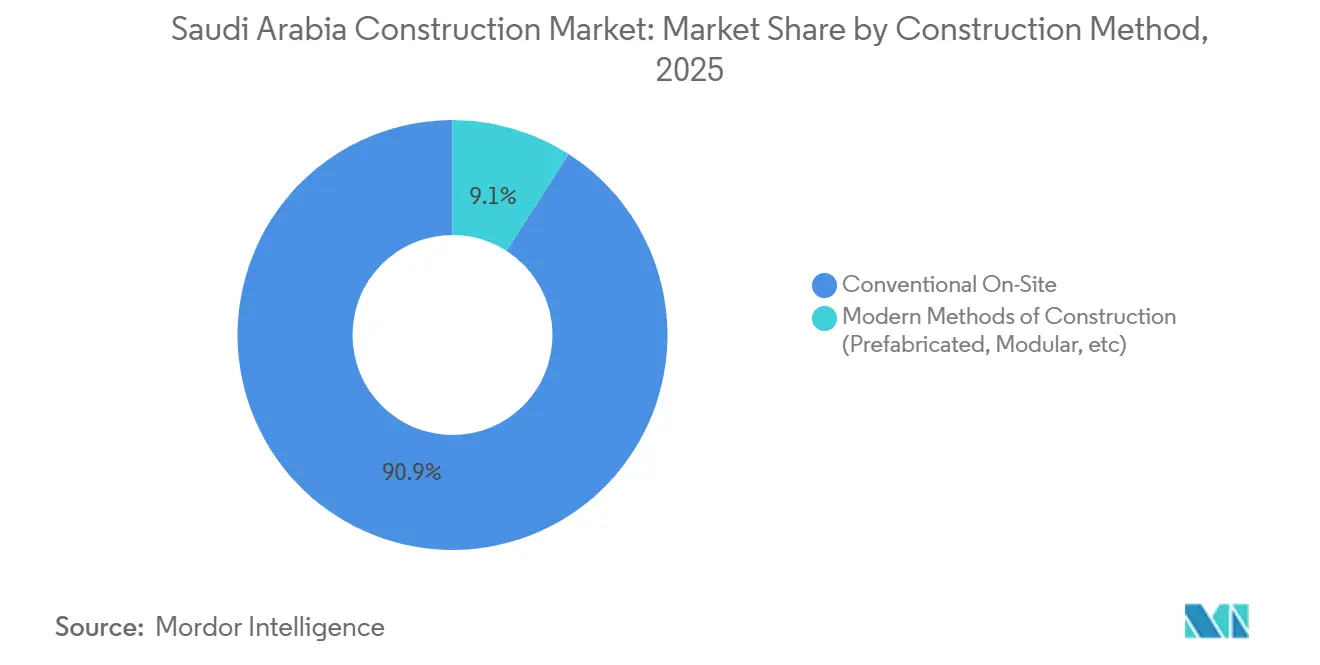
- In construction methods, conventional on-site construction led with a 90.8% share in 2026, while modern methods of construction are forecast to grow fastest at a CAGR of 5.28% during 2027-2032.
- By investment source, public funding led with a 63.32% of Saudi Arabia construction market share in 2026, while private investment is forecast to grow fastest at a CAGR of 4.05% during 2027-2032.
- Among city markets, Riyadh held the leading 28.43% share in 2026 and is forecast to grow fastest at a CAGR of 3.7% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Saudi Arabia Construction Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Vision 2030 giga- and mega-projects (NEOM, Red Sea, Diriyah) anchoring multi-year pipelines across asset classes. | +2.2% | Diriyah development area | Medium term (2-4 years) |
| Transport & logistics expansion—rail, metro, ports, airports—positioning KSA as a regional trade hub. | +1.4% | Jeddah Islamic Port | Medium term (2-4 years) |
| Housing programs (Sakani) and community infrastructure supporting fast-growing urban populations. | +1.3% | Riyadh, Jeddah, Dammam, Madinah and Khamis Mushait | Short term (≤ 2 years) |
| Energy transition capex—renewables, grid expansion, hydrogen, and carbon management—driving civil/utility works. | +1% | Nationwide | Medium term (2-4 years) |
| Water security investments—desalination, transmission, wastewater reuse—enabling industrial and urban growth. | +0.6% | Eastern Province and Alqassim | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Vision 2030 giga- and mega-projects (NEOM, Red Sea, Diriyah) anchoring multi-year pipelines across asset classes.
Large development programs support construction demand by concentrating several projects within a common destination rather than relying on isolated buildings. Saudi Vision 2030’s 2025 annual report recorded more than USD 6.6 billion in projects and awarded contracts for Diriyah.[1] It also recorded 8 major projects under development there in 2025, giving the pipeline breadth as well as financial scale. For contractors, a program of that kind can support successive work packages, although revenue depends on each package reaching execution. The commercial significance is therefore the potential continuity of delivery work across a destination, with mobilization and project coordination becoming part of the contractor’s offer.
Transport & logistics expansion—rail, metro, ports, airports—positioning KSA as a regional trade hub.
Port expansion links construction demand to additional handling capacity and the physical redevelopment required to accommodate it. In March 2025, DP World and the Saudi Ports Authority inaugurated the expanded South Container Terminal at Jeddah Islamic Port. The 3-year, SAR 3 billion (USD 800 million) project increased the terminal’s annual capacity from 1.8 million to 4 million twenty-foot equivalent units. In July 2026, the terminal handled more than 221,200 twenty-foot equivalent units, its highest monthly throughput since DP World began operating it in 1999. These distinct measures show both a delivered expansion and substantial subsequent use, linking construction exposure to an operating logistics asset. Port-facing contractors can therefore address upgrades within existing terminals as a distinct construction channel alongside entirely new ports.
Housing programs (Sakani) and community infrastructure supporting fast-growing urban populations.
Housing programs support construction beyond individual dwellings when residential delivery includes the facilities needed for functioning communities. In June 2026, the Ministry of Municipalities and Housing reported 119 Sakani developer-partner projects under construction, comprising about 155,000 housing units with diverse facilities and services.[2] Most were distributed across 7 residential suburbs in Riyadh, Jeddah, Dammam, Madinah and Khamis Mushait. The housing mix included villas, apartments and townhouses. That variety gives contractors scope to connect community facilities with several dwelling formats within the same program. The suburb can therefore be the relevant unit of demand for facility contractors, even when dwelling designs differ.
Energy transition capex—renewables, grid expansion, hydrogen, and carbon management—driving civil/utility works.
Electricity investment creates construction demand through both generating assets and the network that connects users to power. Saudi Energy Company reported about 12.3 GW of grid-connected renewable capacity in 2025, up 86.4%.[3] Separately, the company added 4,840 circuit-kilometers to its transmission network in 2025. These activities support demand for utility construction across generation connections and network extensions, with different delivery interfaces for each. For civil contractors, the commercial opportunity therefore extends beyond individual renewable sites to work coordinated with the wider electricity system. Firms able to align civil completion with electrical installation can address that interface rather than compete solely for isolated earthworks packages.
Restraints Impact Analysis of Saudi Arabia Construction Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Delivery capacity constraints and skilled labor shortages amid simultaneous mega-program execution. | -1.2% | Nationwide | Short term (≤ 2 years) |
| Cost inflation and higher financing costs pressuring feasibility and contractor margins. | -1% | Nationwide | Short term (≤ 2 years) |
| Regulatory, land, and environmental permitting complexity extending timelines, especially in coastal/heritage zones. | -0.4% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Delivery capacity constraints and skilled labor shortages amid simultaneous mega-program execution.
A shortage of specialist trades can delay usable completion even when structural work has sufficient labor. Turner & Townsend reported skilled-worker shortages, cost increases and project delays in Saudi construction in 2025. Solar installers, mechanical, electrical and plumbing workers, finishing trades and supervisors faced gaps, while structural trades and general labor appeared more balanced. This uneven availability makes the sequence of work commercially important because additional structural capacity cannot substitute for missing installation or finishing skills. Contractors exposed to those later activities face a narrower delivery constraint than a general headcount measure would suggest. For developers, the resulting risk lies in the interval between a substantially built asset and one ready for handover.
Cost inflation and higher financing costs pressuring feasibility and contractor margins.
Project feasibility can weaken before an award is canceled when cost and delivery assumptions require substantial revision. In October 2026, Knight Frank reported that rising construction and logistics costs and longer procurement and construction timelines were pressuring Saudi project economics. Its assessment was that some projects might need changes to scope, phasing or procurement to remain commercially viable. For a contractor pricing defined work, those potential changes create uncertainty over the package size and delivery sequence a buyer can ultimately authorize. This can postpone the point at which a developer converts a housing or infrastructure program into a dependable workload for crews and equipment.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Saudi Arabia Construction Market Segment Analysis
By Sector:
Infrastructure Scale Meets Residential ExpansionInfrastructure accounted for a 59.96% share of the Saudi Arabia construction market size in 2026, making it the largest segment. For FY2026, the Ministry of Finance allocated SAR 35 billion (USD 9.33 billion) to its Infrastructure and Transportation Sector. That sector covers road, port and airport construction alongside transport regulation, communications and other functions. Road, port and airport construction therefore sit within the FY2026 allocation, supporting a budget-backed civil-works pipeline in the largest segment.
Residential construction is forecast to be the fastest-growing segment in the Saudi Arabia construction market, at a CAGR of 4.82% during 2027-2032. Saudi family homeownership reached 66.24% in 2025, exceeding its 65% annual target. Expanded mortgage access, targeted financing and continued housing-supply growth under the Housing Program supported the longer-term homeownership increase, linking residential demand with the program’s delivery of homes. Commercial construction’s hospitality channel included a December 2025 agreement between Taiba Investments’ 84%-owned Smart Hotel Zone Company and Al-Saad Contracting for a 159-key Marriott hotel in Riyadh’s stc Square. Hotel meeting rooms and restaurants add shared commercial facilities to the construction brief.

By Construction Type:
New Builds Lead While Retrofit Programs Broaden DemandNew construction was the largest segment by construction type in the Saudi Arabia construction industry, with an 84.99% share in 2026. National Housing Company (NHC) announced in November 2025 that it had launched more than 134,000 new housing units across its Saudi urban destinations that year. NHC placed those launches within a plan to reach 300,000 housing units by the end of 2025. The destination program therefore gives construction firms a concentrated source of prospective housing work tied to the developer’s supply plan.
Renovation is forecast to be the fastest-growing segment in the Saudi Arabia construction market, at a CAGR of 4.55% during 2027-2032. By August 2026, the National Energy Services Company (Tarshid), working with the Ministry of Education, had retrofitted more than 17,000 government schools. The work included replacing more than 8.3 million lighting units and installing more than 183,000 motion sensors. This is an equipment-led renovation opportunity, where building-services specialists can reproduce a defined intervention across a large public estate.
By Construction Method:
Site Execution Leads as Modular Contracts DevelopConventional on-site construction represented a 90.8% Saudi Arabia construction market share in 2026, making it the largest segment by method. In February 2026, China State Construction Engineering Corporation reported that Zone 2 of the Royal Diriyah Opera House had entered concrete pouring for its first ground-level slab. The slab’s specified pour area was 1,906 square meters, with a concrete volume of 719 cubic meters. Concrete placement of this size ties the slab to the pour sequence of the surrounding structural work.
Modern methods of construction (prefabricated, modular, etc) are forecast to be the fastest-growing segment in the Saudi Arabia construction market, at a CAGR of 5.28% during 2027-2032. Red Sea International signed a December 2025 contract with Baker Hughes Saudi Arabia to design, build, supply and operate prefabricated modular camps in the Eastern Province. The agreement included catering and camp management, with a stated term through November 30, 2031, and financial impact expected from the fourth quarter of 2026. The units were specified to meet repeated relocation requirements for oil and gas exploration operations. The supplier’s commercial responsibility consequently extends from building movable accommodation to managing the camp and feeding its occupants.
By Investment Source:
Public Programs Anchor Activity as Private Partnerships ExpandPublic investment was the largest segment by funding source in the Saudi Arabia construction industry, with a 63.32% share in 2026. The Ministry of Finance reported more than 107,000 housing units and developed lands provided under Municipalities and Housing in FY2025 with real estate developers. It also reported more than 2.5 million square meters of parks and urban interventions constructed and developed in the first half of FY2025. Housing delivery, land development and public-realm works therefore reach contractors through distinct activities within the Municipalities and Housing scope.
Private investment is forecast to be the fastest-growing segment in the Saudi Arabia construction market, at a CAGR of 4.05% during 2027-2032. In November 2025, King Salman Park Foundation announced a USD 1 billion fund with Ajdan Real Estate and SEDCO Capital for homes, hotels and offices in a Riyadh neighborhood. The foundation would provide land, while the private-sector partners would fund construction. That structure separates a land contribution from the capital needed to build homes and commercial premises, allowing parties to fund different parts of development. Private construction finance can therefore enter at neighborhood scale without funding the foundation’s land contribution.
Geography Analysis
Riyadh Construction Market
Riyadh was the largest city market, with a 28.43% share of the Saudi Arabia construction market size in 2026, and is forecast to grow fastest, at a CAGR of 3.7% during 2027-2032. In January 2026, Larsen & Toubro’s Heavy Civil Infrastructure business won work on the Riyadh Metro Red Line extension through a Webuild-led consortium commissioned by the Royal Commission for Riyadh City. The contract covered design and turnkey construction of 8.4 kilometers of elevated and underground metro line with 5 stations. Because elevated sections, underground sections and 5 stations sit in one design and turnkey package, the consortium carries the interfaces between them.
Jeddah’s municipal works are intended to organize commercial activity through dedicated service districts, connecting construction demand with the city’s operating economy. In June 2026, the Ministry of Municipalities and Housing marked the start of implementation for Jeddah’s first phase, covering construction, car, warehouse, market and truck-shelter districts across about 20 million square meters. DMA (Dammam Metropolitan Area) has an industrial freight construction channel through the rail connection serving Dammam Second Industrial City. In June 2026, Saudi Railway Company awarded its construction to a joint venture of Hassan Allam Construction Saudi and OHL Arabia, subsidiaries of Hassan Allam Holding and OHLA Group, respectively.
The Rest of Saudi Arabia also has a developer-led building channel, illustrated by a residential and commercial commission in Madinah. In November 2025, MGB Alameriah Contracting Company accepted Beetah Real Estate Company’s award for a development comprising 440 apartments and commercial space. The contractor is MGB Berhad’s Saudi joint venture. MGB Berhad is a subsidiary of LBS Bina Group Berhad. The award shows how a Malaysia-based construction group participates in developer-led work in Madinah through a Saudi joint venture.
Regulatory Framework and Outlook
This comparison of selected jurisdictions examines the national framework and Riyadh’s local administration from the perspective of a compliant construction contractor. The 2024 Saudi Building Code edition has applied to all building occupancy types since June 30, 2025. National rules make code conformity and approval of plans a precondition for construction-related permits. Riyadh administers applications through accredited engineering offices and its permits department.
Regulatory Table of Saudi Arabia Construction Market
| Decision factor | Saudi Arabia | Riyadh |
|---|---|---|
| Primary authority | Ministry of Municipalities and Housing and municipal authorities | Riyadh Municipality, Permits Department |
| Key instruments or direction | Saudi Building Code 2024; municipal construction-licensing regulations | Building-permit process; 2025 urban-plan infrastructure requirements |
| Commercial effect | Code-conforming plans require approval before permits issue | Under urban-plan requirements, developers and engineering offices must complete specified infrastructure and public spaces before construction |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
The national Medium rating balances a defined approval route with the obligation to demonstrate code conformity before permitted work. Riyadh’s Medium rating reflects accredited-office submission and the infrastructure and public-space obligations attached to urban plans. The applied 2024 code edition supports continuity of the national compliance baseline. In Riyadh, the June 2026 automated urban-plan platform connects government entities and aligns raw-land development with infrastructure and service networks, consistent with continuing preconstruction coordination.
Value Chain Stages
This comparison follows project design, specialist engineering and main construction to show where suppliers capture contract income and manage delivery interfaces. In November 2025, New Murabba Development Company appointed an AECOM-Jacobs joint venture to design The Mukaab and surrounding infrastructure and public realm in Riyadh. That combined scope makes coordination between the building and its supporting infrastructure part of the professional service offered before physical delivery.
Value Chain Analysis Table of Saudi Arabia Construction Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Project design | Design consultants such as AECOM and Jacobs | Design-service fees | Building and infrastructure design interfaces | Resolve shared interfaces before issuing construction packages |
| Specialist engineering | Mechanical, electrical and plumbing engineering consultants such as Buro Happold and Saudi Diyar | Specialist engineering fees | Coordination of building-system requirements | Reconcile discipline requirements before construction packages advance |
| Main construction | Construction contractors such as El Seif Engineering Contracting Company, Midmac Contracting Company and China State Construction Engineering Corporation | Construction-contract payments | Divided responsibilities within joint delivery teams | Set explicit work boundaries and common completion milestones |
| Source: Mordor Intelligence | ||||
Diriyah Company awarded the Royal Opera House construction contract to a joint venture in April 2025, and El Seif’s announcement of the award named specialist engineering participants. El Seif’s stated main-contractor scope covers theaters, cultural and hospitality spaces, parking, vertical transportation and safety systems. That scope requires the construction team to translate several technical disciplines into one physical asset, making design interfaces a delivery responsibility. A provider that accepts accountability for that coordination alongside construction can earn on more of the chain than one limited to a single package.
Competitive Landscape
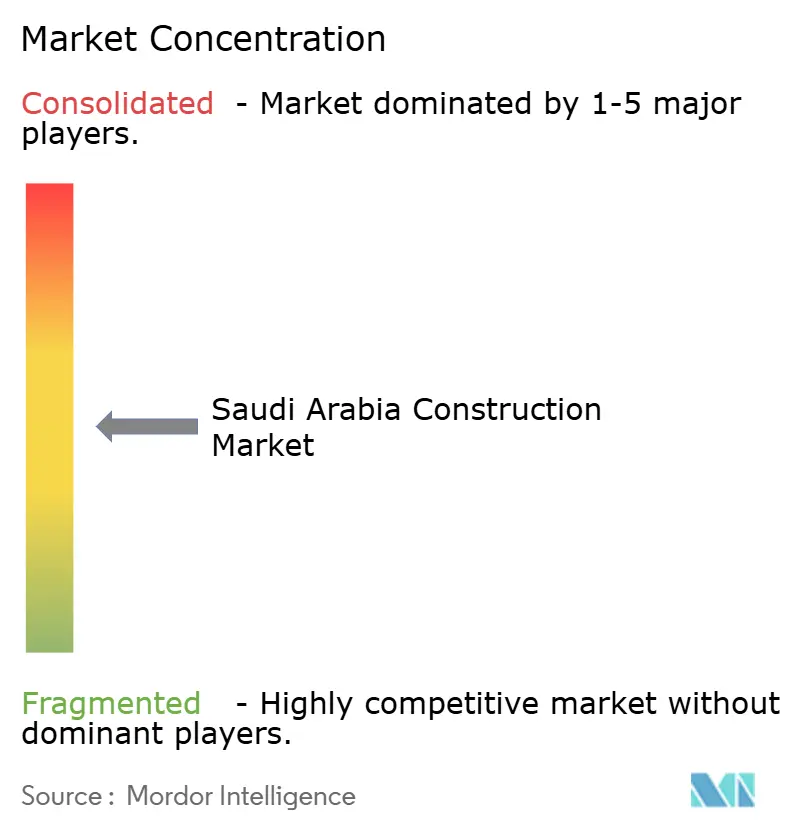
Competition is spread across several established Saudi groups. Leading participants include Saudi Binladin Group, Nesma & Partners Contracting, Al Rashid Trading & Contracting, Almabani General Contractors and Al Ayuni Investment & Contracting. In April 2025, Saudi Awwal Bank signed a credit facility with Saudi Binladin Group, a subsidiary of Binladin International Holding Group, to finance King Fahd Sports City in Riyadh. The agreement aimed to strengthen Saudi Binladin Group’s financial capacity for major-project execution, linking the lender’s support to that contractor’s stadium commission.
In July 2026, Nesma & Partners Contracting received an infrastructure award from Emaar, The Economic City, the master developer of King Abdullah Economic City. The work covered the Industrial Valley and Special Economic Zone, with WSP responsible for project management and construction supervision. The strategic infrastructure was commissioned to support the zone’s continued expansion and readiness for industrial and logistics investment. Supporting a zone positioned for industrial and logistics investment ties Nesma’s order to the developer’s expansion schedule for the Industrial Valley.
Almabani General Contractors’ November 2025 King Khalid Road main-works award from Diriyah Company illustrates how road access to Diriyah is procured as a dedicated infrastructure scope. The main works involve 3 interchanges connecting King Khalid Road with the northern and western ring roads. The award positions Almabani around physical access to the destination, linking its road works to the developer’s wider construction program. Saudi Arabia requires activity owners to obtain an environmental construction permit from the National Center for Environmental Compliance before construction or activity modification begins.
Saudi Arabia Construction Industry Leaders
-
Saudi Binladin Group
-
Nesma & Partners Contracting
-
Al Rashid Trading & Contracting
-
Almabani General Contractors
-
Al Ayuni Investment & Contracting
- *Disclaimer: Major Players sorted in no particular order
Saudi Arabia Construction Market Companies Covered in this Report
- Saudi Binladin Group
- Nesma & Partners Contracting
- Al Rashid Trading & Contracting
- Almabani General Contractors
- Al Ayuni Investment & Contracting
- El Seif Engineering Contracting
- Abdullah A.M. Al-Khodari Sons
- Al Kifah Contracting
- ZODCON
- Al Latifia Trading & Contracting
- Larsen & Toubro Saudi
- Samsung C&T KSA
- Bechtel Saudi Arabia
- Fluor Arabia
- China State Construction ME
- China Railway Construction Corp.
- Consolidated Contractors Co.
- Diriyah Company
- ROSHN Group
- National Housing Company
- Red Sea Global
- Qiddiya Investment Co.
Key Opportunities for Market Participants
This comparison examines housing structures, enabling civil works and building services as different routes into Saudi residential development. NHC said in March 2026 that it aimed to deliver 600,000 housing units by 2030, after reaching a reported 300,000-unit milestone at the end of 2025. It also reported working with 90 local real estate developers, creating a buyer-side network through which contractors can address different parts of residential delivery.
Market Opportunities Table of Saudi Arabia Construction Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Repeatable housing-structure packages | Planned residential expansion creates scope for repeatable dwelling delivery | NHC and residential developer partners | Offer defined building packages that can be repeated across residential phases | Matching execution capacity to package size | NHC and residential general contractors |
| Residential enabling works | The housing pipeline creates interfaces between new dwellings and supporting civil works | Destination developers and residential project owners | Align civil and utility packages with the sequence of dwelling delivery | Coordinating utility and building work boundaries | Developer partners and civil contractors |
| Building-services and interior completion | Partner-led residential delivery creates several points for specialist participation | Local real estate developers | Package building services and interior completion around defined handover milestones | Aligning specialist completion with the main building sequence | Building-services and interior contractors |
| Source: Mordor Intelligence | |||||
The central opening is to translate a large housing pipeline into clearly bounded packages that developers can commission and coordinate. Main builders, civil contractors and building-services firms can pursue different responsibilities around the same residential program. The breadth of NHC’s local developer network means specialist growth can come from repeating a defined scope across development counterparties.
Recent Industry Developments in Saudi Arabia Construction Market
- Sep 2026: The Ministry of Municipalities and Housing, the National Center for Privatization & PPP and Ashraq Development Company launched the request-for-qualification phase for Dammam’s King Fahd Suburb Boulevard. A proposed 43-year public-private partnership would develop a mixed-use 4-kilometer zone within a 7.3-kilometer corridor. Its proposed delivery model covers design, construction, financing, operation, maintenance and transfer.
- Jul 2026: Emaar, The Economic City awarded Nesma & Partners Contracting strategic infrastructure work for King Abdullah Economic City’s Industrial Valley and Special Economic Zone, with WSP responsible for project management and construction supervision.
- Jun 2026: The Ministry of Municipalities and Housing awarded China Architectural Construction Corporation and China State Construction Engineering Corporation contracts for 2,010 Al-Ruba housing units in Riyadh and 2,426 Al-Rasha Al-Faisaliah units in Dammam, respectively.
Saudi Arabia Construction Market Report Scope and Research Methodology
Market Definition and Coverage
The Saudi Arabia construction market measures annual USD spending on construction work performed on buildings and civil engineering assets in Saudi Arabia. It covers work for new construction and renovation, valued as construction work is delivered to project owners and public agencies.
Scope exclusions: Separate construction materials sales, separate construction machinery and equipment sales, completed building and other real estate sales, and standalone architecture, engineering, and design consulting fees are excluded.
Segments Covered in This Report
- By Sector
- Residential
- Apartments / Condominiums
- Villas / Landed Houses
- Commercial
- Office
- Retail
- Industrial & Logistics
- Others
- Infrastructure
- Transportation Infrastructure (Roadways, Railways, Airways, others)
- Energy & Utilities
- Others
- Residential
- By Construction Type
- New Construction
- Renovation
- By Construction Method
- Conventional On-Site
- Modern Methods of Construction (Prefabricated, Modular, etc)
- By Investment Source
- Public
- Private
- By Geography
- Riyadh
- Jeddah
- DMA (Dammam Metropolitan Area)
- Rest of Saudi Arabia
Data Sources, Market Sizing, and Validation
Desk Research
Saudi Vision 2030 annual reporting, Ministry of Municipalities and Housing program updates, Saudi Electricity Company investor materials, and DataSaudi construction statistics provide examples of public evidence used to track funded housing delivery, infrastructure programs, utility investment, construction activity, and labor or business conditions. The General Authority for Statistics construction cost index can inform checks on material, labor, equipment, and energy cost movements that affect the value of work delivered.
Company filings, investor presentations, public budgets, tender notices, and reputable Saudi business press can clarify contractor activity, project timing, and whether announced investment has moved into performed work. The named sources are illustrative and not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
A planned interview and survey program would include Saudi public and private project owners, contractors, developers, and construction specialists, with senior executives and functional leaders able to explain project awards, delivery timing, and spending by asset and funding source. Analyst questions would check secondary estimates and segment assumptions, clarify gaps in published project values or work completion, and triangulate reported activity against project evidence and cost or output indicators.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The model estimates Saudi Arabia's annual construction work value from a top-down assessment of construction activity, then checks selected totals with contractor and project roll-ups and sampled contract value against completed work. Residential, commercial and infrastructure work, new construction and renovation, conventional and modern methods, public and private funding, and the four stated Saudi geographies are built from project and sector evidence, then reconciled to the national total to derive segment shares. The forecast can use multivariate regression or scenario analysis, with construction cost trends, housing delivery, public infrastructure and utility investment, and the timing of funded project awards as explanatory indicators. Scenarios reflect changes in project phasing and contractor capacity. Analyst interviews would test whether these indicators and the resulting segment paths fit Saudi delivery conditions, while gaps in project-level values would be estimated from comparable awarded or completed work and checked against independent sector indicators.
Data Validation & Update Cycle
Analysts triangulate budget, project, company, cost and construction activity signals, then investigate material differences in timing, coverage or valuation before sign-off. A second review checks source dates, units, segment totals and forecast inputs, with re-contact or renewed source checks triggered by conflicting award or completion evidence, major reprioritization, or an unexpected cost or output movement. The dataset is refreshed annually, reviewed between cycles when material Saudi projects or policy changes occur, and receives a fresh pre-delivery review.
Mordor Intelligence's the Kingdom of Saudi Arabia Construction Sector Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Saudi Arabia construction market measures annual USD spending on construction work performed on buildings and civil engineering assets in Saudi Arabia.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. The forecast can use multivariate regression or scenario analysis, with construction cost trends, housing delivery, public infrastructure and utility investment, and the timing of funded project awards as explanatory indicators.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 86.29 B (2027) | |
| Regional Consultancy A | USD 101.4 B (2025) | At its 2025 base, this estimate is 17.5% above this report's 2027 value of USD 86.29 B, 2 years later. The estimate uses a broader construction establishment base and a forecast that accelerates from its reported historical activity trend. |
| Government Market Intelligence B | USD 70.33 B (2024) | At its 2024 base, this estimate is 18.5% below this report's 2027 value of USD 86.29 B, 3 years later. Its earlier measurement year and stated expectation of continued infrastructure-led growth place the estimate below a later-year market value. |
Mordor Intelligence's analysts triangulate budget, project, company, cost and construction activity signals, then investigate material differences in timing, coverage or valuation before sign-off.
Key Questions Answered in the Report
What is the Saudi Arabia construction market size and growth outlook?
The size was USD 82.8 billion in 2026 and is estimated to reach USD 104.7 billion by 2032, with a 3.94% CAGR during 2027-2032.
What supports construction demand in Saudi Arabia?
Destination development, housing programs and utility investment support demand. In June 2026, Sakani’s 119 developer-partner projects under construction comprised about 155,000 housing units.
Which sector leads construction activity?
Infrastructure held the largest share at 59.96% in 2026. Residential construction is forecast to grow fastest at a 4.82% CAGR during 2027-2032.
Which companies are major construction participants?
Major participants include Saudi Binladin Group, Nesma & Partners Contracting, Al Rashid Trading & Contracting, Almabani General Contractors and Al Ayuni Investment & Contracting.
What could constrain the construction outlook?
Specialist labor availability and project cost pressure can constrain delivery. Turner & Townsend identified specialist trade gaps in 2025, and Knight Frank reported cost and timeline pressure in October 2026.
Which city leads construction and forecast growth?
Riyadh held a 28.43% share in 2026 and is forecast to grow fastest among the named city markets, at a 3.7% CAGR during 2027-2032.