
Commercial Aircraft Engines Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 98.86 Billion |
| Market Size (2031) | USD 117.13 Billion |
| Growth Rate (2026 - 2031) | 3.45 % |
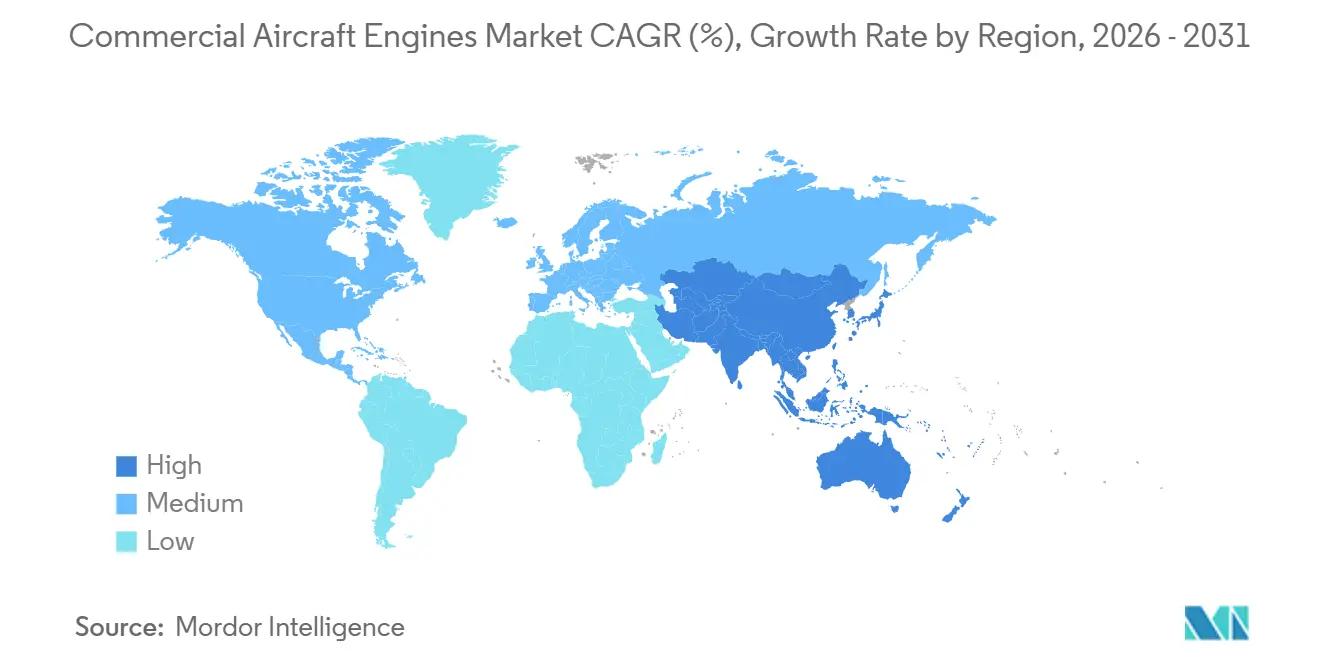
| Fastest Growing Market | North America |
| Largest Market | Asia Pacific |
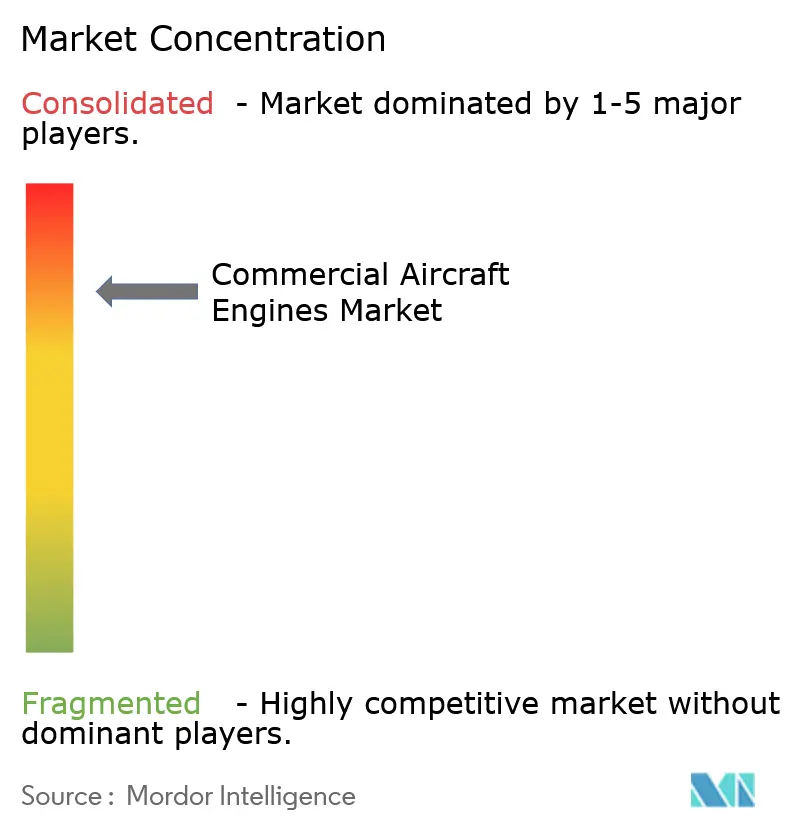
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Commercial Aircraft Engines Market Analysis by Mordor Intelligence
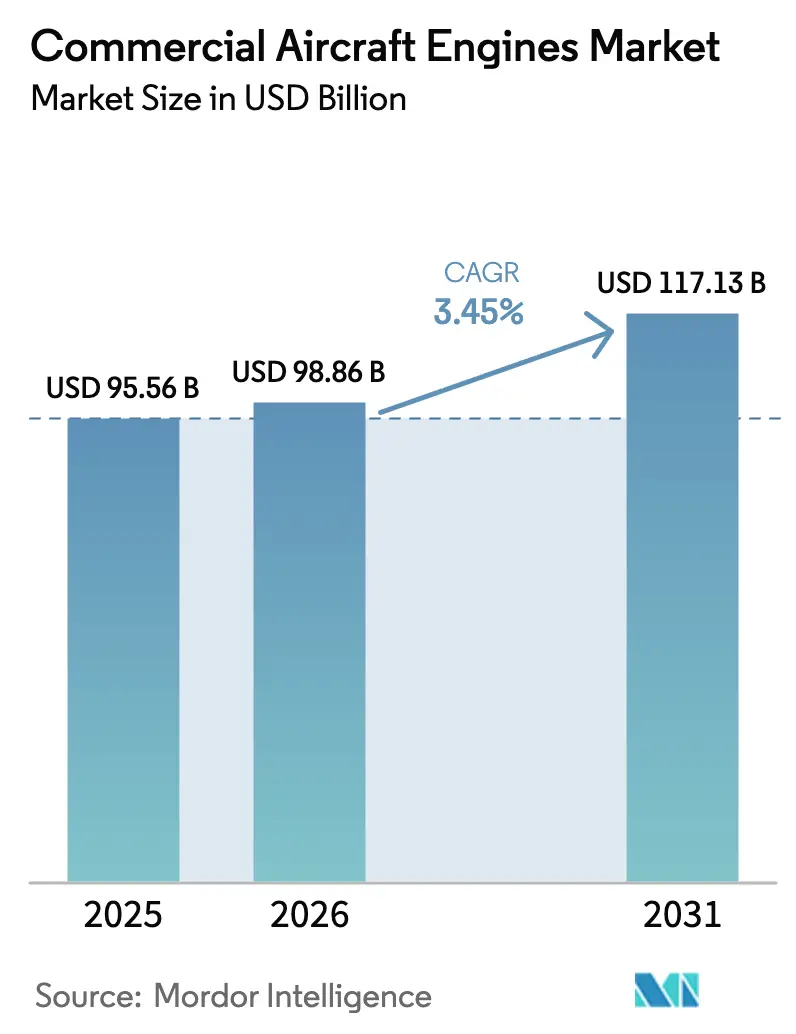
The commercial aircraft engines market size is expected to grow from USD 95.56 billion in 2025 to USD 98.86 billion in 2026 and is forecasted to reach USD 117.13 billion by 2031 at a 3.45% CAGR over 2026-2031. This expansion is tied to the growth of low-cost-carrier fleets in the Asia-Pacific region, elevated shop-visit volumes for PW1100G and LEAP engines, and a steady shift toward power-by-the-hour contracts, which enhance aftermarket revenue visibility. Turbofan platforms continue to dominate new-build deliveries, yet turboprop programs supplying thin regional routes are regaining momentum as operators in Southeast Asia and Africa replace aging ATR fleets with PW127XT-M powerplants. Technology migration remains gradual; conventional architectures still anchor much of the installed base, but hybrid-electric demonstrators from NASA and Collins Aerospace have accelerated certification road maps for sub-regional aircraft. On the supply side, persistent bottlenecks in titanium and nickel forgings are prompting GE Aerospace, Safran, and Pratt & Whitney to deepen additive manufacturing adoption and vertically integrate strategic material sources to secure engine output.
Key Report Takeaways
- By engine type, turbofan powerplants led with 57.76% commercial aircraft engines market share in 2025, while turboprops are forecast to post a 4.24% CAGR through 2031.
- By aircraft type, narrowbody installations accounted for 61.27% of the 2025 commercial aircraft engines market size, whereas regional-jet engines are expected to expand at a 5.3% CAGR through 2031.
- By technology, conventional turbofan/turboprop designs captured 38.45% of the 2025 share, and hybrid-electric propulsion is poised for the fastest growth at 5.21% through 2031.
- By thrust class, the 25,001–50,000 lbf band commanded 41.34% share in 2025, and engines above 50,000 lbf are projected to grow at a 4.87% CAGR.
- By component, turbine sections accounted for a 45.87% share in 2025, while compressor modules are forecast to achieve a 4.21% CAGR over the outlook period.
- By end-user, OEM factory-fit engines represented 61.35% of demand in 2025, and the replacement/aftermarket channel is expected to accelerate at a 4.92% CAGR through 2031.
- By geography, the Asia-Pacific region captured 36.87% of the 2025 revenue, while North America is expected to register the fastest regional expansion at a 4.55% CAGR.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Commercial Aircraft Engines Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| APAC fleet expansion led by LCCs | +1.80% | Asia-Pacific core, spill-over to Middle East | Medium term (2-4 years) |
| Accelerated narrow-body replacement | +2.10% | Global, concentration in North America and Europe | Short term (≤ 2 years) |
| Ageing fleet pushing engine-MRO demand | +1.50% | Global, mature markets in North America and Europe | Long term (≥ 4 years) |
| Unscheduled PW1100G and LEAP shop-visit surge | +1.30% | Global, acute in Asia-Pacific and North America | Short term (≤ 2 years) |
| OEM digital-twin subscription revenues | +0.90% | Global, early adoption in North America and Europe | Medium term (2-4 years) |
| Long-term SAF-backed offtake agreements | +1.20% | North America and Europe, regulatory push | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||


Asia-Pacific Fleet Expansion Led by LCCs
Low-cost carriers in India, Vietnam, and Indonesia continue to order single-aisle aircraft at volumes that exceed historic delivery averages. IndiGo’s 500-unit A320neo family order and VietJet’s 100-unit A321neo commitment underscore a structural rise in passenger traffic in the region, prompting engine makers to pre-position MRO capacity in Bangalore, Ho Chi Minh City, and Jakarta. Daily utilization exceeding 12 hours accelerates hot-section wear, which pulls forward shop-visit schedules and stabilizes aftermarket demand. Engine suppliers are therefore earmarking narrowbody spare-engine pools for Asia-Pacific operators to mitigate dispatch reliability risks. The commercial aircraft engines market benefits from the fact that every frame requires two propulsion units, along with corresponding multi-year service agreements.[1]Airbus, “AirAsia orders 100 A321neo aircraft,” airbus.com
Accelerated Narrow-Body Replacement with Fuel-Efficient Engines
United Airlines, Southwest, and European carriers are retiring CFM56-7B and V2500-A5 engines well ahead of their economic life to capture 15-20% fuel-burn savings from LEAP-1B and PW1100G successors. Surging jet-fuel costs have sharpened payback periods, making rapid fleet turnover economically rational. Early retirements, however, inject a wave of used serviceable material into secondary parts channels, depressing OEM spare-part pricing and nudging engine makers to emphasize digital-service revenue. Accelerated replacements also compress certification timetables for thrust-rating changes, pressuring engineering teams but reinforcing the value proposition of next-generation engines. Consequently, commercial aircraft engines market players are bundling long-term power-by-the-hour contracts to lock in predictable margins.
Ageing Fleet Pushing Engine-MRO Demand
Global average fleet age reached 12.3 years in 2025. Airlines that deferred new-aircraft deliveries during the pandemic must now shoulder elevated maintenance liabilities, driving a 35% year-over-year rise in CFM56 shop visits at Lufthansa Technik. OEM and independent MRO expansions in Singapore, San Antonio, and Hamburg are targeting this backlog. At the same time, proprietary repair techniques such as high-pressure turbine-blade coatings allow certain shops to charge price premiums. The sustained maintenance intensity underpins a resilient aftermarket revenue floor even if new-build deliveries slow. As a result, the commercial aircraft engines market is deriving an increasing share of EBIT from overhaul activities rather than hardware sales.[2]Lufthansa Technik, “Q2 2025 shop-visit surge,” lufthansa-technik.com
Unscheduled PW1100G and LEAP Shop-Visit Surge
Powder-metal contamination in PW1100G turbine disks and premature combustor-liner wear on LEAP engines have prompted unexpected removals, resulting in the grounding of scores of A320neo and 737 MAX jets. OEM capacity constraints created overflow demand, which was captured by independents such as StandardAero, which opened a dedicated GTF repair line to absorb the excess work. Airlines negotiating risk-transfer clauses now place greater emphasis on guaranteed turnaround times and on-wing durability metrics, shrinking engine-sale margins by 150–200 basis points. In parallel, spare-engine leasing rates increased, prompting carriers to diversify their engine selections to hedge against availability risks. These knock-on effects reinforce the commercial aircraft engines market’s pivot to service-centric value capture.[3]StandardAero, “GTF repair line opens in San Antonio,” standardaero.com
Restraints Impact Analysis of Commercial Aircraft Engines Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Persistent forge and casting supply bottlenecks | -1.40% | Global, acute in North America and Europe | Medium term (2-4 years) |
| Escalating certification and R&D costs | -0.90% | Global, regulatory burden in North America and Europe | Long term (≥ 4 years) |
| Powder-metal contamination grounding (GTF) | -1.10% | Global, concentrated in Asia-Pacific and North America | Short term (≤ 2 years) |
| Coming CFM56 USM glut eroding aftermarket margins | -0.80% | Global, mature markets in North America and Europe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Persistent Forge and Casting Supply Bottlenecks
High-pressure turbine disks and nickel-alloy forgings remain the rate-limiting factor across LEAP and GTF production lines. GE Aerospace, Safran, and Pratt & Whitney have responded by acquiring equity stakes in forging houses and expanding their additive-manufacturing footprints, thereby bypassing capacity shortfalls for non-critical parts. Despite these measures, a 15-20% supply gap in 2025 delayed multiple engine shipments, compelling airframers to revise their delivery schedules. Medium-term relief hinges on new press capacity and the qualification of powder-metal billets, but vertical integration will likely increase capital intensity for prime contractors. This bottleneck keeps commercial aircraft engines market lead times extended into 2027.[4]Safran, “Safran acquires stake in Aubert & Duval,” safran-group.com
Escalating Certification and R&D Costs
FAA and EASA scrutiny of FADEC software and high-bypass architectures has lengthened certification cycles to 36 months, pushing CFM’s RISE program past USD 1.2 billion in cumulative R&D outlays. Only scale players with multi-billion-dollar cash flows can absorb such burdens, reinforcing market oligopoly. Smaller aspirants have shifted toward business-jet niches with lower regulatory thresholds. Elevated development costs raise entry barriers, but they also encourage platform exclusivity agreements that secure decades of spares revenue. Consequently, the commercial aircraft engines industry is concentrated around a handful of conglomerates that can amortize these investments across a broad installed base.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Commercial Aircraft Engines Market Segment Analysis
By Engine Type:
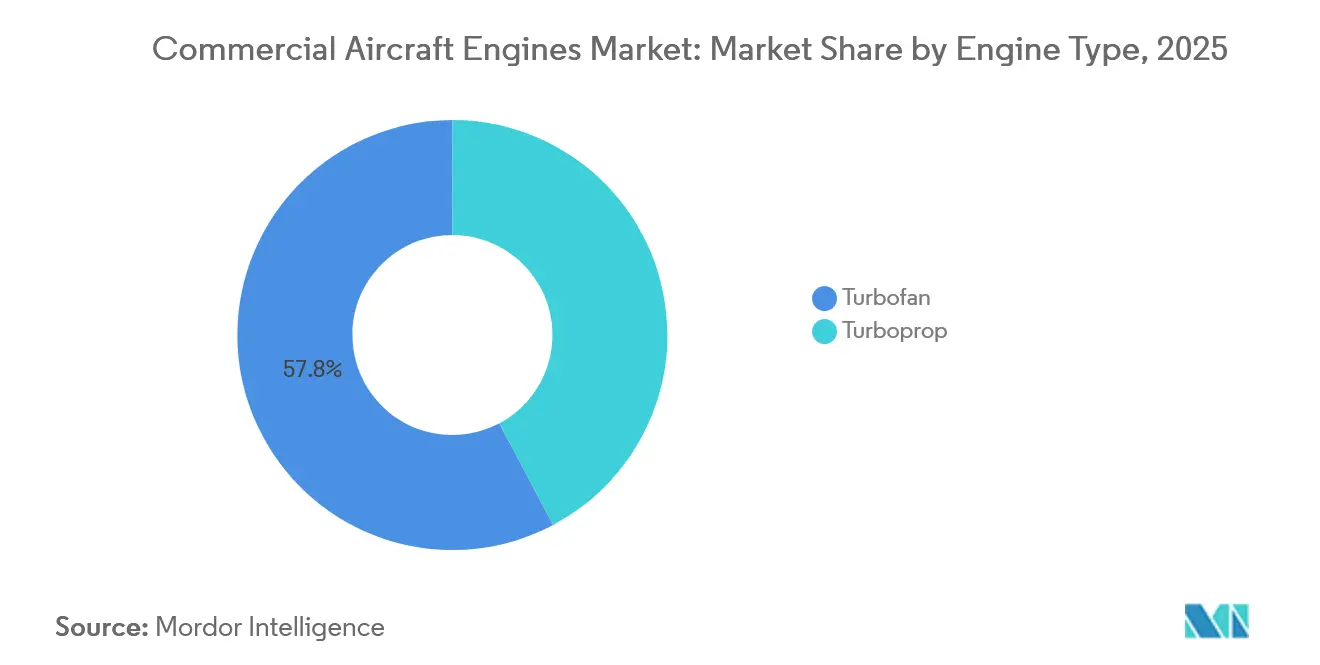
Turbofan Dominance Meets Turboprop ResurgenceTurbofan platforms supplied 57.76% of 2025 revenue in the commercial aircraft engines market. Narrowbody variants, such as the LEAP-1A/B and PW1100G families, remain production workhorses, whereas widebody programs, like the Trent XWB and GE9X, underpin long-haul growth. Turboprops, however, are on a 4.24% CAGR trajectory as regional carriers refresh ATR 42/72 fleets with PW127XT-M powerplants that deliver 3% lower fuel burn and 50% cabin noise reduction.
Growth polarity is evident: developing economies favor turboprops for short-range connectivity, while network airlines in Europe retire Dash 8 fleets for high-capacity regional jets. OEMs respond by bundling fuel-efficiency upgrades with maintenance-cost caps to entice operators who balance capital expenditures (capex) and operating expenditures (opex) trade-offs. Engine manufacturers are increasingly promoting the readiness of sustainable aviation fuel, even in the turboprop segment, to future-proof asset values. As such, the commercial aircraft engines market continues to diversify propulsion portfolios to cover both jet-dense and prop-centric route structures.


By Aircraft Type:
Narrowbody Supremacy, Regional Jet AccelerationNarrowbody engines represented 61.27% of the 2025 commercial aircraft engines market share on the back of A320neo and 737 MAX deliveries. Regional-jet engines, though smaller in unit value, are set for a 5.3% CAGR as Embraer’s E2 family gains traction among carriers serving thin routes where widebodies or high-capacity single-aisles are uneconomical.
Fleet planners in Southeast Asia and Latin America prefer sub-150-seat jets to balance load factors and frequency, boosting PW1700G and PW1900G demand. Conversely, fleet densification in North America sees major airlines up-gauging to A321neo, requiring marginal thrust enhancements. Such dual dynamics sustain a healthy pipeline for both large and small thrust classes within the commercial aircraft engines market, ensuring balanced aftermarket workloads.
By Technology:
Conventional Architectures Persist, Hybrid-Electric EmergesConventional turbofan/turboprop designs secured 38.45% of 2025 revenue, reflecting the vast in-service CFM56, V2500, and PW100 fleets. Hybrid-electric demonstrators, however, hold the highest growth outlook at 5.21% as NASA’s X-57 and Collins Aerospace’s 1-MW motor validate distributed propulsion concepts.
Regulatory uncertainty persists: EASA standards for electric systems exceeding 500 kW remain under development, potentially delaying the entry into service of large aircraft. Still, OEMs hedge with incremental technology, gear systems, CMC internals, and open-fan designs, to secure double-digit efficiency gains absent full electrification. This measured path maintains a robust conventional backlog while positioning the commercial aircraft engines market for a smoother transition once certification guardrails mature.
By Thrust Class:
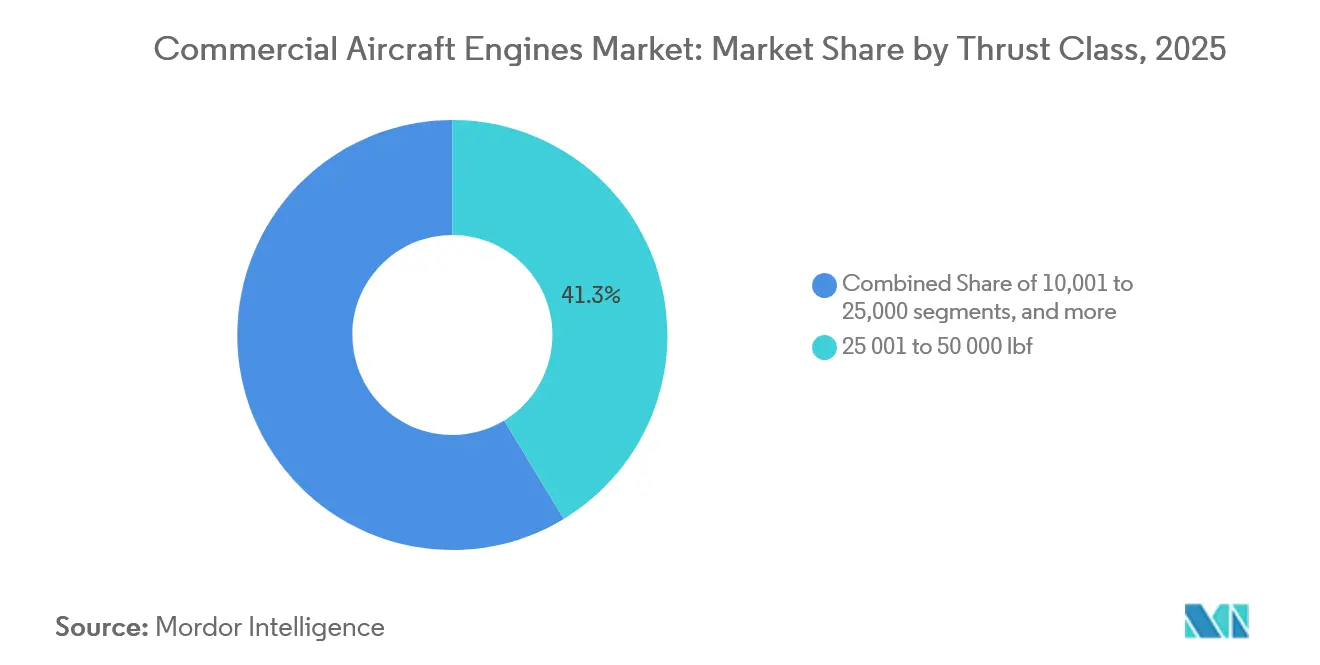
Mid-Range Dominance, Ultra-High-Thrust GrowthEngines rated 25,001–50,000 lbf delivered 41.34% of 2025 revenue and anchor the commercial aircraft engines market size for single-aisle programs. The greater than 50,000 lbf bracket is forecast to grow at a 4.87% CAGR, driven by orders for the GE9X and Trent XWB-97 engines supporting the 777X and A350-1000 fleets.
Ultra-high-thrust programs form a strategic moat, as metallurgical hurdles lock out newcomers. Meanwhile, the 10,001–25,000 lbf category retains relevance for regional jets and large turboprops, ensuring balanced industrial loading across facilities. OEMs therefore maintain dual competencies, servicing both high-volume, mid-thrust engines and capital-intensive, widebody giants within the commercial aircraft engines market.
By Engine Component:
Turbine Sections Lead, Compressor Modules AccelerateTurbine hardware comprised 45.87% of 2025 revenue, underscoring the cost concentration in single-crystal blades operating above 1,600 °C. Compressor assemblies are projected to grow at a 4.21% CAGR as additive manufacturing trims weight by 15% on LEAP modules and slashes lead times by 40%.
CMC adoption in nozzles and shrouds raises thermal ceilings, allowing for hotter core temperatures and improved fuel burn without the need for exotic alloys. Gearboxes unique to PW1000G engines remain a niche but commercially crucial subset, delivering 12% higher bypass ratios. Collectively, these advances enhance durability and efficiency, sustaining aftermarket revenue as each upgrade cascades through the installed commercial aircraft engines base.
By End-User:
OEM Factory-Fit Leads, Aftermarket SurgesFactory-fit shipments accounted for 61.35% of 2025 demand thanks to record Airbus and Boeing narrowbody output. The replacement/aftermarket channel, however, is advancing at a 4.92% CAGR as power-by-the-hour arrangements shift maintenance risk from operators to OEMs. Rolls-Royce’s TotalCare covered 70% of its Trent fleet in 2025, delivering greater than 20% EBIT margins.
Independents, such as Lufthansa Technik and ST Engineering, leverage used, serviceable material to undercut OEM shops by 20-30% on mature engines. This competition intensifies pricing pressure yet broadens service accessibility, reinforcing the commercial aircraft engines market’s transition toward lifecycle-service economics over hardware margins.
Geography Analysis
APAC Commercial Aircraft Engines Market
Asia-Pacific generated 36.87% of 2025 revenue for the commercial aircraft engines market, anchored by IndiGo’s and VietJet’s blockbuster A320neo orders that drove engine demand exceeding USD 30 billion. Fleet expansion responds to rising middle-class travel and liberalized air-service agreements, compelling OEMs to invest in localized MRO hubs to secure future maintenance, repair, and overhaul (MRO) streams.
North America and Europe Commercial Aircraft Engines Market
North America is projected to record a 4.55% CAGR through 2031, as United Airlines, American Airlines, and Delta Air Lines collectively firm more than 500 single-aisle orders in 2025. The trend is replacement-driven: carriers retire CFM56-powered 737-800s to capitalize on LEAP-1B fuel efficiency, simultaneously releasing used, serviceable material that reshapes parts pricing. Europe, with a 24% share in 2025, benefits from Toulouse- and Hamburg-centric Airbus output, while Wizz Air’s diversification to LEAP engines exemplifies risk-mitigation strategies amid PW1100G supply issues.
The Americas, APAC and MEA Commercial Aircraft Engines Market
The Middle East contributes a significant share of revenue, but widebody weighting lifts ASPs: Emirates’ 205-unit 777X deal alone underwrites USD 15 billion in GE9X business. South America and Africa remain small yet strategic, favoring turboprops and regional jets for short-haul connectivity; Azul’s ATR 72-600 purchase illustrates this niche. China, representing 18% of the Asia-Pacific market, pursues self-sufficiency via AECC’s CJ-1000A, signaling a potential bifurcation of global supply chains post-2028. Mature US fleets generate outsized aftermarket volumes, reinforcing North America’s status as the commercial aircraft engines market’s service revenue anchor.

Regulatory Landscape
Commercial aircraft engines are certified and operated under harmonized airworthiness frameworks led by the FAA and EASA, with engine-specific requirements codified in EASA CS-E and corresponding FAA engine and transport-category guidance. EASA CS-E Amendment 8 is a key anchor, entering into force in April 2025 and updating certification test expectations, including alternate endurance test pathways and stronger substantiation around the initial maintenance programme (IMP). This increases the upfront evidence needed before entry into service.
Environmental compliance is anchored in ICAO Annex 16, including Volume II aircraft engine emissions standards. nvPM mass and number limits applicable to new type and in-production engines above 26.7 kN have been active certification benchmarks since 2023. In March 2026, ICAO adopted Amendments 15, 12, and 3 to Annex 16 Volumes I, II, and III, respectively, with an applicability date of 1 January 2027, signaling tighter expectations around emissions and noise. Policy execution also intersects with market access and operational economics, as the EU continued policy work in 2026 around aviation emissions instruments (EU ETS and alignment with CORSIA), while FAA technical guidance in June 2025 emphasized early coordination on engine system and component tests and aircraft interfaces for Part 25 programs.
Value Chain Analysis
The value chain is dominated by a small set of engine OEMs (GE Aerospace, CFM International, Pratt & Whitney, and Rolls-Royce) that control core design, final assembly, and much of the aftermarket services stack. Upstream, Tier 1 and Tier 2 suppliers provide major rotating and hot-section modules (fan, compressor, combustor, turbines) and critical subsystems, supported by specialty materials providers for nickel superalloys, titanium, and advanced castings and forgings. Downstream, engine delivery is coupled to airframer production schedules, while service revenue is captured through OEM networks and licensed or independent MROs operating under long-term agreements, including power-by-the-hour. Leasing and spare-engine pools act as additional availability buffers.
Current constraints remain concentrated in cast metallic parts and forged components that gate both new production and shop-visit turnaround. That has pushed OEMs toward dual sourcing, deeper supplier oversight, and geographic expansion of manufacturing ecosystems. A visible shift is the build-out of India-based industrial participation for LEAP components: Safran Aircraft Engines signed an MoU in April 2026 with Uni Tritech Private Limited to manufacture aluminum investment cast parts for LEAP-1A and LEAP-1B engines at a facility in Dharwad, Karnataka, following earlier 2025 contracting activity in India for LEAP component production. OEMs have also actively managed allocation between factory-fit demand and spare needs, for example CFM re-allocating some engines to support Airbus assembly lines in late 2024, illustrating how supply tightness propagates through both OEM and aftermarket layers.
Competitive Landscape
The commercial aircraft engines market operates in a highly concentrated market. CFM International and Pratt & Whitney control a significant share of narrowbody propulsion, while Rolls-Royce dominates A350 widebody applications, and GE Aerospace anchors 777X powerplants. Competition is shifting from marginal fuel-burn deltas to digital-service monetization: GE’s Flight Deck and Pratt & Whitney’s eFAST platforms command subscription fees of USD 50k–100k per aircraft and deliver margins of 35-40%, surpassing hardware returns.
Supply-chain resilience strategies differentiate players. Safran’s stake in Aubert & Duval secures forging capacity, and GE’s additive-manufacturing ramp accelerates LEAP output. Meanwhile, hybrid-electric entrants, such as Collins Aerospace, target the 19- to 50-seat segment, posing a long-term challenge to incumbent turboprop suppliers. China’s AECC invests USD 5 billion to field the CJ-1000A, potentially fracturing market geography into Western and Chinese spheres by 2030.
Independent MROs are emerging as formidable competitors. Lufthansa Technik leverages proprietary repair IP to win shop visits, and StandardAero capitalizes on overflow from OEM bottlenecks. These firms utilize cost-advantaged USM sourcing to price aggressively, compelling OEMs to sweeten power-by-the-hour terms or risk erosion of their market share. Consequently, strategic partnerships, vertical integration, and digital ecosystems define the next phase of rivalry within the commercial aircraft engines market.
Commercial Aircraft Engines Industry Leaders
Safran SA
Pratt & Whitney (RTX Corporation)
CFM International
Rolls-Royce PLC
GE Aerospace
- *Disclaimer: Major Players sorted in no particular order
Commercial Aircraft Engines Market Companies Covered in this Report
- CFM International
- GE Aerospace
- Safran SA
- Rolls-Royce PLC
- Pratt & Whitney (RTX Corporation)
- United Engine Corporation (Rostec)
- Honeywell International Inc.
- MTU Aero Engines AG
- IHI Corporation
- Mitsubishi Heavy Industries Aero Engines, Ltd.
- Lycoming Engines (Textron, Inc.)
- Williams Companies, Inc.
- Lufthansa Technik AG
- GKN Aerospace Services Limited
- Singapore Technologies Engineering Ltd.
- StandardAero Aviation Holdings, Inc.

Market Opportunities and Future Outlook
Near-term opportunity centers on durability and time-on-wing improvements for the large narrowbody installed base, where unscheduled removals and harsh-environment operations elevate shop-visit demand and spare-engine requirements. Certification and production cutovers of retrofit-focused upgrades create immediate pathways for OEMs and MRO networks to monetize parts, kits, and bundled services beyond new engine deliveries. A concrete 2026 proof point is the FAA and EASA certification of the LEAP-1B high-pressure turbine durability kit announced in July 2026, with production planning tied to an early-2027 cutover.
Capacity and ecosystem expansion address bottlenecks and localize support near high-utilization fleets, particularly in Asia-Pacific and the Americas. In March 2026, GE Aerospace announced a USD 1 billion investment across US manufacturing sites and suppliers for 2026, including funding linked to LEAP durability kits and facility infrastructure. Safran expanded LEAP MRO footprint, including a new engine maintenance shop in Queretaro, Mexico (inaugurated in June 2026) and a joint venture with SIA Engineering Company to establish a CFM LEAP MRO shop in Singapore (agreement in June 2026), which opens additional channels for OEM-approved repairs, materials management, and contracted services in two high-traffic regions. Demonstrator programs moved into full-scale testing in 2026, including Safran PHILEAS hybrid-electric demonstrator at Istres in July 2026 with DGAC support, and CFM RISE open-fan program advancing to a design review milestone with a test cell planned at Villarose by year-end 2026.
Recent Industry Developments in Commercial Aircraft Engines Market
- July 2026: Safran Aircraft Engines launched a six-month, 300-hour ground testing campaign for its PHILEAS hybrid-electric demonstrator at the Istres site, with support from the French Civil Aviation Authority (DGAC). The program advances full-scale validation of hybrid-electric integration elements relevant to sub-regional propulsion road maps. It also indicates where suppliers can align around electric machines, power electronics, and system integration competencies alongside conventional core technologies.
- June 2026: Safran inaugurated a USD 140 million engine maintenance shop in Queretaro, Mexico, dedicated to CFM LEAP engines, expanding its MRO hub in the Americas. The added capacity strengthens turnaround-time resiliency for a fast-growing LEAP installed base and supports service-contract execution by reducing dependence on constrained legacy shops. It also reinforces the aftermarket shift toward geographically distributed, OEM-aligned repair networks.
- November 2024: CFM International re-allocated some engine production to prioritize Airbus assembly lines over aftermarket spares to mitigate delivery gaps under supply chain constraints. This action highlighted how constrained parts and module availability can force trade-offs between factory-fit output and spare-engine provisioning. The rebalancing had knock-on effects for airline dispatch reliability planning and for MRO scheduling tied to spare availability.


Commercial Aircraft Engines Market Report Scope and Research Methodology
Market Definition and Coverage
For this methodology, the market covers revenues linked to engines used on commercial aircraft, including OEM engine deliveries and the aftermarket tied to operating fleets (such as replacement engines and engine-related services).
Scope exclusions: Defense-only aircraft engines, space propulsion, and non-aircraft industrial turbines are not counted in this market sizing.
Segments Covered in This Report
- By Aircraft Type
- Narrowbody Aircraft
- Widebody Aircraft
- Regional Aircraft
- By Engine Type
- Turbofan
- Turboprop
- By Engine Component
- Compressor
- Turbine
- Nozzle
- Gearbox
- Other Components (Fan, Combustor,FADEC and Control Electronics, etc.)
- By Thrust Class
- Less than 10,000
- 10,001 to 25,000
- 25,001 to 50,000
- Greater than 50,000
- By End-User
- OEM Factory-Fit
- Replacement/Aftermarket
- By Technology
- Conventional Turbofan/Turboprop
- Geared Turbofan (GTF)
- Contra-Rotating Open Rotor
- Hybrid-Electric Propulsion
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts with public aviation activity signals and published fleet and traffic statistics, because these define the demand pool that engines ultimately serve. We relied on sources such as ICAO air transport statistics, IATA traffic indicators, FAA and EASA airworthiness and safety publications, and aircraft and engine certification records from regulators.
To shape the market model, we reviewed company annual reports, investor presentations, and earnings transcripts for engine program exposure, aftermarket mix, and service contract trends. Where helpful, we also used paid subscriptions for company financials and intelligence, aerospace and aviation databases at aircraft and engine level, patent databases, and global contracts and tenders, so our assumptions could be cross-checked against program activity. These sources are illustrative, and we also referred to other public and subscription sources for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary interviews and surveys were used to pressure-test what desk sources cannot fully explain, especially how shop-visit timing, spare engine strategies, and contract structures translate into revenues. We spoke with a mix of engine OEM ecosystem participants, airline and lessor-side experts, and MRO-focused specialists across major regions, then followed up where assumptions showed wide variance (for example, service intensity by fleet age).
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 13% | APAC: 47% |
| Mid tier: 54% | Functional/Unit leaders: 34% | EMEA: 35% |
| Smaller Players: 16% | Managers: 53% | Americas: 18% |
Market-Sizing & Forecasting
Sizing starts with a top-down build where global commercial fleet growth and utilization trends are reconstructed into engine demand and aftermarket intensity, and then translated into value using price and service-rate assumptions. We then corroborate totals using selective bottom-up checks, such as sampled engine-program volumes times observed price bands, plus channel checks on service event pricing. Gaps are adjusted only when multiple signals point in the same direction.
Key inputs used in the model include aircraft deliveries by category, installed engine base by program, utilization (flight hours and cycles proxies), shop-visit cadence and visit mix, and the split between time-and-material versus long-term service agreements. When forecasts were built, scenario analysis was used to reflect different delivery recovery paths and service ramp timing. The final path was aligned to expert consensus gathered during interviews so short-term volatility did not overrun longer-cycle fundamentals.
Data Validation & Update Cycle
Outputs are validated through triangulation across independent indicators, such as fleet growth versus delivery schedules, and aftermarket revenues versus expected service event counts implied by utilization. When an outlier appears, we isolate the driver (for example, currency timing, a one-time contract catch-up, or a program-specific production change) and then review again before sign-off.
Reports are refreshed annually, and interim updates are made when material events occur, such as major delivery plan shifts, certification disruptions, or step-changes in service contract coverage. Before delivery, the analyst runs a fresh pass on key inputs so clients receive the latest updated view.
Mordor Intelligence's Commercial Aircraft Engines Market Size Compared Against Other Published Estimates
Published market sizes for commercial aircraft engines can look far apart because each publisher draws the line differently on what counts as engine revenue, and they also use different timing for deliveries and service recognition. Differences in base year, currency conversion timing, and how engine services are treated (event-based versus contract-based) tend to be the biggest drivers.
Some sources focus mainly on new engine production, or they report only gas turbine hardware sales, which naturally compresses the total. Other sources expand scope by adding broader propulsion or adjacent aircraft engine categories, and then apply list-price style assumptions, which can inflate value. In this report, the wider estimates commonly come from counting broader aircraft engine families and bundled MRO lines. Mordor Intelligence limits the total to commercial aircraft engines with OEM deliveries and the engine-specific aftermarket tied to in-service fleets.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 98.86 B (2026) | |
| Trade Journal A | USD 66.07 B (2025) | Typically centers on commercial gas turbine engine hardware shipments and uses a narrower definition of aftermarket, which can undercount service contracts and replacement engines. |
| Industry Publisher B | USD 41.10 B (2025) | Often reflects a tighter engine-only revenue view and may lean on limited program coverage and simplified pricing progression, which reduces totals when fleets shift to long-term service agreements. |
The table shows that most of the spread can be explained by scope choices around what is included as aftermarket value and how engine programs are mapped to commercial fleets. By keeping assumptions tied to observable fleet activity and service intensity signals, the estimate remains traceable to repeatable inputs and can be updated consistently when deliveries or shop-visit cycles change.


Key Questions Answered in the Report
What is the projected value of the commercial aircraft engine market in 2031?
It is forecast to reach USD 117.13 billion, rising from USD 98.86 billion in 2026 on a 3.45% CAGR.
Which engine type holds the largest share today?
Turbofan powerplants account for 57.76% of 2025 revenue, reflecting their dominance on single-aisle and twin-aisle aircraft.
Which geographic region is expected to grow the fastest through 2031?
North America leads with a 4.55% CAGR, driven by fleet replacement orders from major US carriers.
Why are hybrid-electric engines attracting interest?
Demonstrators show double-digit fuel-burn cuts for sub-regional aircraft, positioning the technology for future carbon-reduction mandates.
How are OEMs responding to supply-chain bottlenecks?
They are vertically integrating forging capacity and expanding additive-manufacturing lines to secure turbine-disk and compressor-part output.
Page last updated on:





