
Ceiling Fan Market Size and Share
Ceiling Fan Market Analysis by Mordor Intelligence
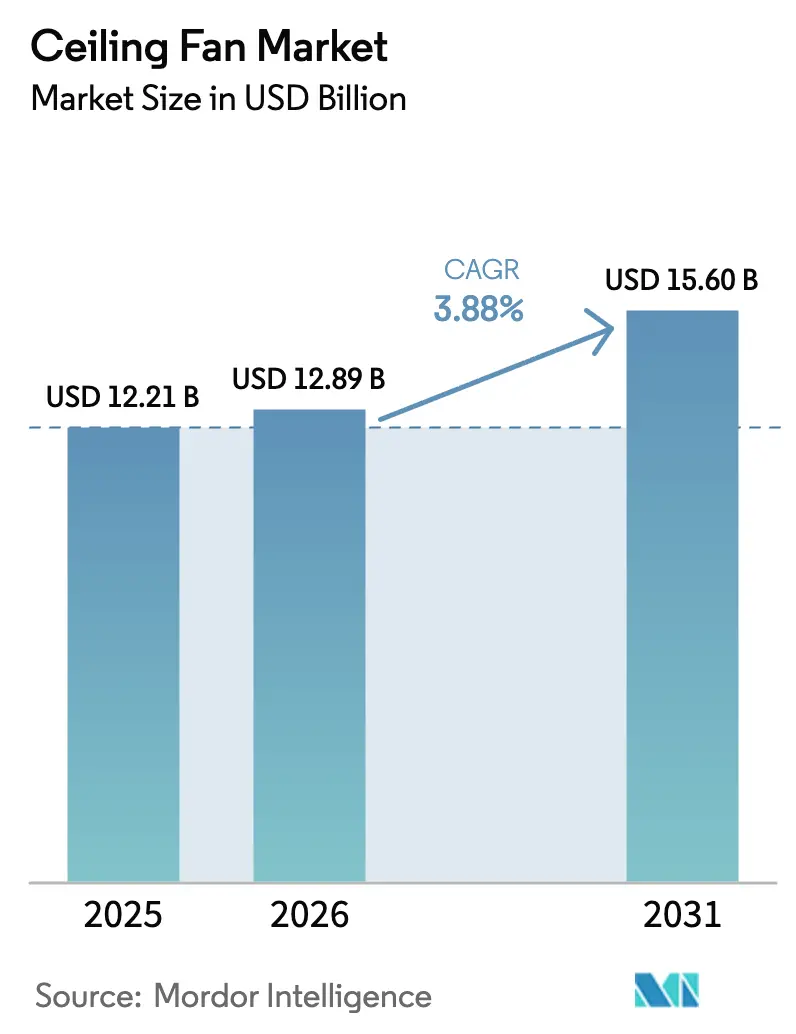
The ceiling fan market size is estimated at USD 12.89 billion in 2026 and is projected to be USD 13.39 billion in 2027, reaching USD 16.01 billion by 2032, growing at a CAGR of 3.64% from 2027 to 2032.
India’s efficiency requirements create a reason to redesign complete fans, while smart-home adoption adds connected control to the product offer. Manufacturing scale can support lower unit costs, but affordable room air-conditioners intensify competition for household cooling expenditure. Suppliers can pair efficiency redesigns with higher production volumes that spread fixed factory costs across more units. Lower BLDC price premiums can make rating-led upgrades easier to sell, while seasonal sales swings leave manufacturers exposed to unsold output and slower cash recovery.
Key Report Takeaways
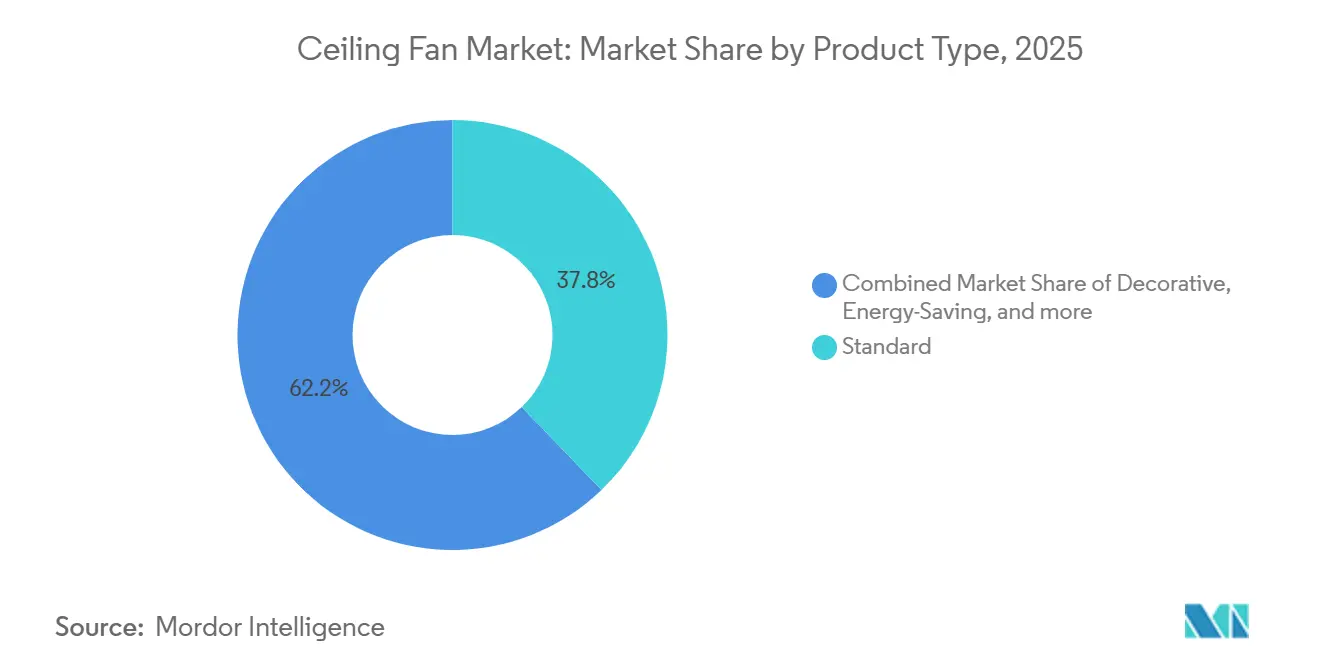
- By product type, standard fans held a 37.32% share of the ceiling fan market size in 2026, while energy-saving fans are forecast to grow fastest at a CAGR of 5.25% from 2027 to 2032.
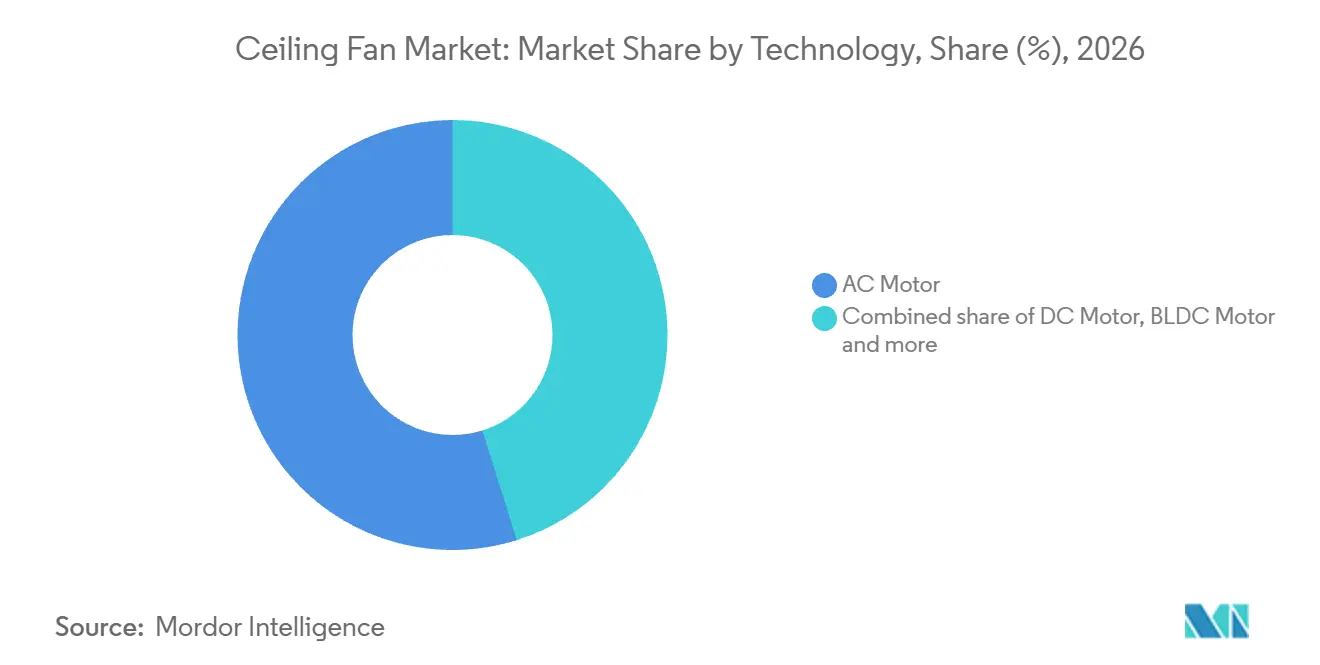
- Across motor technologies, AC motor fans represented a 54.83% ceiling fan market share in 2026, whereas BLDC motor fans are projected to grow fastest at a CAGR of 6% from 2027 to 2032.
- Residential applications led end-user demand with a 75.44% share of market revenue in 2026, and commercial applications are forecast to grow fastest at a CAGR of 5.1% from 2027 to 2032.
- Through distribution channels, B2C/retail channels led with a 91.93% share of market revenue in 2026, while B2B/project channels buying directly from manufacturers are projected to grow fastest at a CAGR of 4.6% from 2027 to 2032.
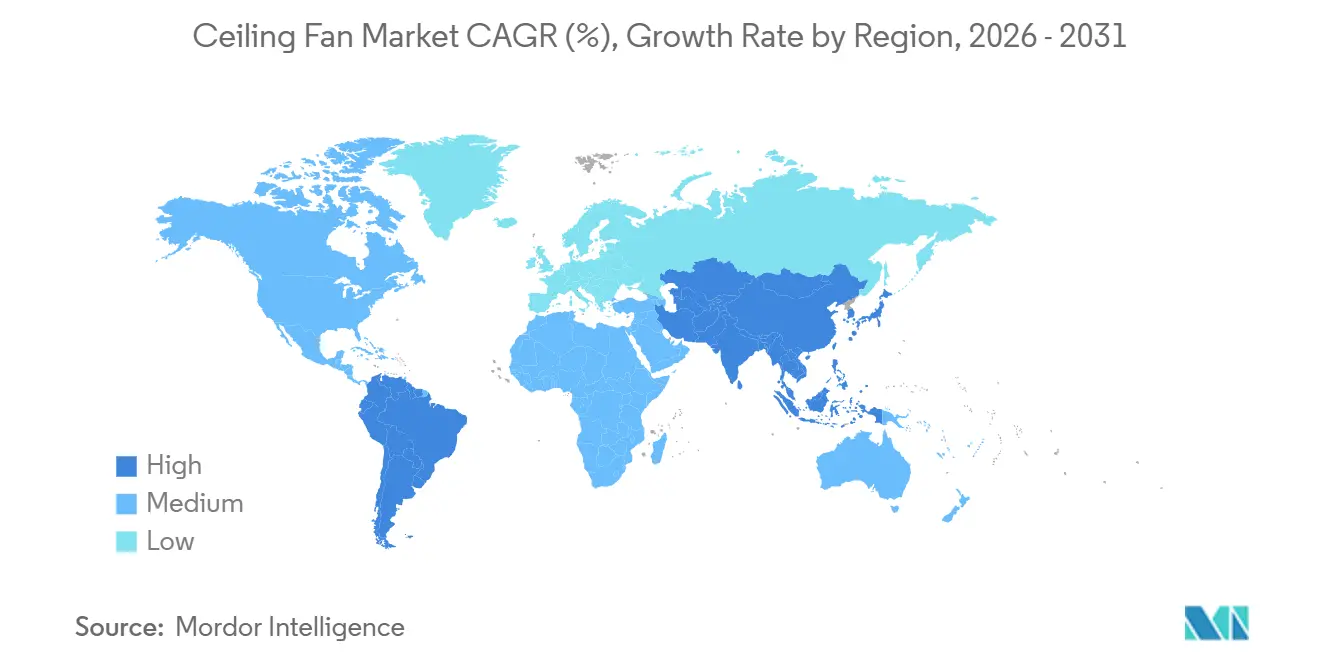
- Geographically, Asia-Pacific led with a 49.13% share of market revenue in 2026 and is projected to grow fastest at a CAGR of 4.95% from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Ceiling Fan Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Tightening energy-efficiency mandates, accelerating the transition to BLDC ceiling fans | +1.4% | India’s domestic market | Short term (≤ 2 years) |
| Rising penetration of smart homes is driving demand for IoT-enabled ceiling fans | +1% | India’s domestic market | Medium term (2-4 years) |
| Scaling of cost-competitive BLDC manufacturing hubs across Asia, lowering product price barriers | +1.1% | India’s domestic market | Short term (≤ 2 years) |
| Increasing adoption of green-building standards, promoting passive and energy-efficient cooling solutions | +0.8% | North America, Europe and Asia-Pacific | Medium term (2-4 years) |
| Growing use of HVLS ceiling fans in temperature-controlled logistics and cold-chain facilities | +0.4% | North America and Asia-Pacific | Long term (≥ 4 years) |
| Public housing programs and rural electrification initiatives are expanding first-time fan ownership | +0.5% | India’s PVTG areas | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Tightening energy-efficiency mandates, accelerating the transition to BLDC ceiling fans
Preserving an entry-level star rating can require a better-performing ceiling fan when efficiency bands rise. For sweeps greater than 750 mm and up to 1,050 mm, India's 1-star band was 3.1 to <3.6 cubic meters per minute per watt under the schedule extended through 2025. The Ministry of Power set the band at 3.6 to <4.1 cubic meters per minute per watt from January 1, 2026, through December 31, 2028. A 2025 Indian consumer guide put regular ceiling fans at 70 to 80 W and BLDC fans at 28 to 38 W for the same 230 to 250 CMM airflow. Lower input power for comparable airflow makes BLDC a route to the higher service-value floor. Motor upgrades can therefore protect an entry-level rated offering while expanding demand for BLDC components.
Rising penetration of smart homes is driving demand for IoT-enabled ceiling fans
Smart-home adoption creates a route for ceiling fans to participate in a household’s existing control environment. As more Indian consumers adopted smart-home technologies, Signify’s EcoLink brand expanded into BLDC ceiling fans in 2025. The brand introduced 4 models, including 2 available in WiZ-powered smart variants. These variants let users integrate air circulation into their connected-home ecosystems, extending connected control to another household function. For fan manufacturers, this provides a way to differentiate selected models without requiring connectivity across the entire range. Offering smart variants alongside other models can broaden a new fan range’s appeal to households at different stages of connected-home adoption.
Scaling of cost-competitive BLDC manufacturing hubs across Asia, lowering product price barriers
Higher output from an operating Asian factory creates room to spread manufacturing overhead across more units. Atomberg's Chakan consumer-appliance facility in Pune produced 4.45 million units in FY2026, up from 3.51 million in FY2025, across a business including fans and smart locks. The facility reported annual installed capacity of 6.60 million units and 67.42% utilization in FY2026. Separately, Atomberg's 2026 prospectus, citing Redseer Research, reported that the Indian price premium for next-generation BLDC fans over induction fans narrowed to 20% to 30% from Financial Year 2021 to Financial Year 2026. A narrower premium reduces the upfront hurdle for choosing BLDC, while higher factory utilization can support lower fixed costs. Suppliers can compete for price-sensitive upgrades when production economics support a more accessible complete-fan offer.
Increasing adoption of green-building standards, promoting passive and energy-efficient cooling solutions
Green-building credits can bring air movement into the thermal-comfort decisions made by warehouse project teams. In WorldGBC’s 2024-2025 member survey, more than two-thirds of Green Building Councils reported increasing uptake of sustainable building principles.[1] Projects pursuing LEED v4.1 BD+C's Thermal Comfort credit must include a qualifying design alternative in regularly occupied warehouse bulk-storage, sorting and distribution areas. Circulating fans and passive systems are options, and LEED v4.1 BD+C registration for warehouses and distribution centers is open through June 30, 2027. Growing adoption can thus widen the specification route for ceiling-fan suppliers where project teams select an air-movement strategy. The commercial opening is a defined warehouse comfort application whose demand depends on the chosen design approach.
Restraints Impact Analysis of Ceiling Fan Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Low-cost room air-conditioners are reducing reliance on ceiling fans in warm regions | -0.6% | Bangladesh’s urban areas | Long term (≥ 4 years) |
| Seasonal sales volatility leading to inventory and pricing pressure | -0.5% | India’s domestic market | Short term (≤ 2 years) |
| Rare-earth magnet supply tightness is increasing BLDC production costs | -0.3% | India’s domestic market | Short term (≤ 2 years) |
| Counterfeit electronic components are driving recalls and compliance risk | -0.2% | United States and China | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Low-cost room air-conditioners are reducing reliance on ceiling fans in warm regions
Falling air-conditioner prices can redirect household cooling expenditure toward an alternative to ceiling fans. In June 2026, The Business Standard reported that lower-priced room air-conditioners were becoming affordable to middle-income households in Bangladesh.[2] It linked expanding air-conditioner adoption to rising temperatures and falling prices, while describing ceiling fans losing dominance as the primary summer-cooling tool. A low fan price can become less decisive when an air-conditioner moves within the same household’s financial reach. With ceiling fans expected to remain in use as their primary cooling role fades, suppliers may lose incremental household cooling spending gradually rather than face an abrupt drop in unit sales.
Seasonal sales volatility leading to inventory and pricing pressure
Weather-sensitive selling periods and rating transitions can complicate the timing of fan production and sales. V-Guard Industries' CEO said its ceiling-fan sales in India had not grown much in Q1 FY26 after an unusually cool summer. In its Q1 FY27 call, management said ceiling-fan sales had occurred in November and December ahead of a January star-rating change and that the channel had a lot of inventory. Existing dealer stock can compete with newly produced units when a manufacturer prepares for the next selling period. Holding unsold fans would tie up funds, while discounting them would reduce revenue per unit. Production aligned only with expected summer demand therefore leaves cash recovery exposed to both weather swings and stock accumulated before rating changes.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Ceiling Fan Market Segment Analysis
By Product Type:
Core Air Circulation Anchors Demand While Efficiency Drives UpgradesStandard fans accounted for a 37.32% share of the ceiling fan market size in 2026. Low entry prices keep basic three-blade AC designs accessible to buyers seeking the least expensive route to ceiling-mounted air circulation. Their position depends on minimizing the initial outlay, while efficiency-led upgrades compete for buyers willing to spend more at purchase. Suppliers serving this largest segment therefore need to preserve the basic format's price advantage as higher-efficiency alternatives compete for replacement demand.
Energy-saving fans are the fastest-growing segment, with a projected 5.25% CAGR from 2027 to 2032. Polycab India Ltd. reported that energy-efficient ceiling-fan models were the main sales driver in its Fans business in FY 2025-26. A March 2026 NRDC India and GreenTree Global report put India's best-in-class BLDC ceiling fans at about 28 W and a service value of 7.5, a 25% efficiency gain over top induction fans at 6. Service value measures airflow per watt, so suppliers can ground upgrade offers in a quantified operating-efficiency advantage.



By Technology:
AC Leadership Coexists With BLDC ExpansionAC motor fans represented a 54.83% ceiling fan market share in 2026. NRDC India and GreenTree estimated Indian induction-fan manufacturing costs at INR 700 to 750 (USD 7 to 8) per fan in 2025, drawing on manufacturer and industry-expert consultations. The report linked induction-fan affordability to a mature domestic supply chain and an extensive service network. That production base supports this largest segment's low-cost positioning, giving price-sensitive buyers an accessible alternative when an efficiency upgrade would require a larger initial outlay.
BLDC motor fans are the fastest-growing segment, with a projected 6% CAGR from 2027 to 2032. Igarashi Motors India, a BLDC ceiling-fan motor supplier, reported an industry estimate of approximately 10 million BLDC units in India’s ceiling-fan motor market in FY 2025-26. For motor suppliers, access to that volume depends on winning fan manufacturers' component specifications. A repeatable motor design can consequently turn a successful specification into recurring production orders.

By End-User:
Household Ownership Anchors Demand While Institutions Specify ProjectsResidential applications formed the largest segment, accounting for 75.44% of market revenue in 2026. A survey of 500 low-income households across 3 housing types in Pune, India, conducted from April 23 to May 6, 2025, found that almost all respondents owned ceiling fans. This kind of household ownership base makes replacement a potential sales route, since a new fan can be purchased to improve an existing room’s cooling arrangement. For these low-income owners, the replacement proposition must justify a new outlay despite an existing fan, favoring affordable upgrades over offers designed around first-time ownership.
Commercial applications are the fastest-growing segment, with a projected 5.1% CAGR from 2027 to 2032. Green-building requirements and new hospitality and organized-retail spaces create a route for fans to enter whole-building cooling specifications. These buyers can consider air movement across repeated rooms or occupied zones, making the complete installation more relevant than a stand-alone appliance choice. A supplier winning that specification can pursue a multiunit installation from one design decision, giving commercial expansion a different sales mechanism from individual household replacement.
By Distribution Channel:
Retail Reach Supports Scale As Direct Projects ExpandB2C/retail channels were the largest segment, representing 91.93% of global market revenue in 2026. Atomberg reported 46,932 retail touchpoints across approximately 1,600 cities and towns in India in its general-trade network as of March 31, 2026. This footprint gives the brand repeated opportunities for local household selection across a single national general-trade system. A challenger seeking comparable reach would need to build and support many dealer relationships, making distribution investment part of the cost of competing for dispersed household purchases.
B2B/project channels, buying directly from manufacturers, are the fastest-growing segment, with a projected 4.6% CAGR from 2027 to 2032. On November 13, 2025, Security Paper Mill in Narmadapuram, India, awarded Crompton Greaves Consumer Electricals Ltd. the ceiling-fan portion of its tender.[3] The buyer issued the order for the ceiling-fan schedule only because the lowest bid for the tender's LED lighting schedule was abnormally low. This split shows that project buyers can award by line item and a manufacturer can win the fan line independently within a broader electrical tender.
Geography Analysis
Asia-Pacific Ceiling Fan Market
Asia-Pacific was the largest geography, accounting for 49.13% of the ceiling fan market size in 2026, and is the fastest-growing geography, with a projected 4.95% CAGR from 2027 to 2032. India's PM-JANMAN solar scheme targeted 100,000 unelectrified households in Particularly Vulnerable Tribal Group (PVTG) areas during 2023-24 to 2025-26 where grid supply was not techno-economically feasible, with a free fan included in planned home-lighting systems. India's Ministry of New and Renewable Energy (MNRE) reported 11,838 households in tribal and PVTG areas electrified through off-grid systems under the New Solar Power Scheme by June 30, 2026. Bangladesh's Public Works Department signed a March 1, 2026, contract with M/s Dulal Traders for ceiling-fan installation and electrical work in corridors and balconies at Dhaka's Shaheed Suhrawardy Medical College & Hospital. PM-JANMAN's planned free-fan systems support household access, while Dhaka's single contract covers institutional spaces.
In North America, the United States requires ceiling fans manufactured and distributed in its commerce to meet federal energy-conservation standards. In South America, a summer 2025 Porto Alegre retailer survey placed ceiling fans behind pedestal and portable fans at 15.3% of responses naming the most-sold fan type. Colombia's CLIMASOL S.A.S. distributes Hunter Fan Company ceiling fans nationwide to residential, office, commercial and industrial projects. Supplier routes consequently differ between winning retailer attention within a mixed summer fan assortment in Porto Alegre and serving several buyer settings through a specialist national distributor in Colombia.
The UK Office for Product Safety and Standards rejected a China-origin ceiling fan with an installable light at the border on August 31, 2025, for electric-shock risk under the Electrical Equipment (Safety) Regulations 2016. In the Middle East and Africa, Ghana's Energy Commission enforces blade-size-dependent minimum service values for ceiling fans under its comfort-fan regulations. Nigeria's DARES solar home system program had deployed more than 830,000 solar home systems across its 6 geopolitical zones by April 2026. Statistics South Africa reported that household electricity access in South Africa rose from 76.7% in 2002 to 90.6% in 2025. Ghana's blade-size service values and Nigeria's solar home deployments therefore describe different entry conditions for suppliers, a product-efficiency threshold in one and an electricity-access route in the other.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of a manufacturer placing household ceiling fans on the market. Product classification determines which rules apply, particularly Germany’s framework for personal-cooling comfort fans with input power up to 125 W. Those qualifying fans face standby/off-mode limits and product-information duties under EU Regulation 206/2012. The European Commission's comfort-fan energy-label option is under discussion, without an adopted or scheduled requirement.
Regulatory Table of Ceiling Fan Market
| Decision factor | United States | China | Brazil | Germany | Saudi Arabia |
|---|---|---|---|---|---|
| Primary authority | U.S. Department of Energy | State Administration for Market Regulation | INMETRO | Länder market-surveillance authorities | Saudi Standards, Metrology and Quality Organization |
| Key instruments or direction | 10 CFR 430.23(w), ceiling-fan test procedure | GB 12021.9-2021 for electric fans, including ceiling fans | Portaria Inmetro No. 465/2021 for residential ceiling fans | Regulation (EU) No. 206/2012 for qualifying comfort fans up to 125 W | Gulf low-voltage equipment regulation and household-fan hazardous-substances regulation |
| Commercial effect | Test covered ceiling fans using the prescribed DOE methods | Meet minimum fan-efficiency values | Declare residential ceiling-fan safety and efficiency conformity | Meet standby/off-mode limits and product-information duties | Meet premarket safety and electromagnetic-compatibility requirements plus household-fan hazardous-substance duties |
| Current policy attractiveness | Medium | Medium | Medium | High | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change | No change |
| Source: Mordor Intelligence | |||||
The United States rates Medium for prescribed testing and No change because 10 CFR 430.32(s)(1) remains the current standard following the U.S. Department of Energy's March 24, 2025 announcement that it had withdrawn a ceiling-fan conservation standard. Germany rates High because qualifying fans up to 125 W face defined standby/off-mode and product-information duties, with No change supported by the continuing framework and unadopted label option. Brazil's Medium rating and No change direction rest on the residential-fan supplier declaration under Portaria Inmetro No. 465/2021, reaffirmed by INMETRO's 2026 guidance, with the import-processing scope of changes Siscomex scheduled from March 30, 2026 supporting continuity in technical duties. China's GB 12021.9-2021 efficiency requirements and Saudi Arabia's low-voltage safety, electromagnetic-compatibility and household-fan hazardous-substance duties support their Medium ratings and No change directions because these operative frameworks have no scheduled fan-specific replacement.
Value Chain Stages
The value chain separates motor supply, complete-fan manufacturing and retail sale to compare supplier roles and earnings mechanisms. At the component stage, Igarashi Motors India supplies BLDC ceiling-fan motors for energy-efficient consumer appliances. Component suppliers can capture value through a specialized motor, while complete-fan manufacturers combine that input with an assembled and tested product.
Value Chain Analysis Table of Ceiling Fan Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Motor supply | Motor suppliers such as Igarashi Motors India Ltd. | Motor sales | Matching the motor to complete-fan performance | Qualify alternative motor designs against the finished fan |
| Complete-fan manufacturing | Ceiling-fan manufacturers such as Polycab India Ltd. | Complete-fan sales | Maintaining motor-winding and assembly consistency | Link process checks with finished-product testing |
| Retail sale | Home-improvement retailers such as Lowe’s Companies, Inc. | Retail fan revenue | Coordinating sourced supply with the retail assortment | Maintain alternative qualified supply routes |
| Source: Mordor Intelligence | ||||
Polycab’s integrated motor winding, end-cover machining and computerized testing illustrate the manufacturing-side effort involved in delivering a complete fan. At retail, Lowe’s identified ceiling fans among its China-sourced product categories in the first quarter of 2025. Greater integration between motor qualification and finished-fan testing can concentrate technical value with manufacturers, while retailers retain responsibility for sourcing the product that reaches the buyer.
Competitive Landscape
Market Concentration
The competitive structure is moderately fragmented, with established consumer brands and suppliers serving commercial and industrial sites. Hunter Fan Company sells residential ceiling fans and serves business customers through its Hunter Industrial division, while Crompton Greaves Consumer Electricals Ltd., Orient Electric Ltd. and Havells India Ltd. also operate fan businesses. Emerson Electric Co. sold its ceiling-fan product lines to Luminance Brands in May 2019. Crompton reported approximately 44% year-over-year growth in its BLDC fan portfolio in Q1 FY27, when the portfolio reached its highest quarterly sales. A technology-focused entrant therefore confronts established fan manufacturers expanding within the same motor category, increasing the need for differentiation at the finished-product level.
In April 2026, Hunter Industrial described its expanded Center for Engineering Excellence in Smyrna, Tennessee, as strengthening its ability to engineer fans for demanding environments. Engineering capability matters in industrial and commercial work because a supplier must translate an application's airflow requirements into a fan design that can be specified and supplied. Hunter Industrial offers HVLS and commercial ceiling fans for factories, warehouses, gyms and retail spaces. The expansion therefore strengthens the division serving those business buyers, broadening the parent's competitive position beyond residential fan selection.
Orient Electric Ltd. reported 26% year-over-year growth in its BLDC fan portfolio in Q2 FY27, driven by new premium launches. Premium product renewal therefore gives incumbents a way to compete with specialist BLDC entrants beyond the motor specification alone. Havells India said in October 2025 that it was continuing to invest in fans as the market shifted toward BLDC, which accounted for almost 40% of its fan portfolio. Challengers with verified efficiency designs can compete for rated upgrades under India's revised star-rating bands. Residential premium positioning and business-site engineering require different capabilities, making the target buyer more consequential to an entrant's strategy than the motor label alone.
Ceiling Fan Industry Leaders
-
Hunter Fan Company
-
Crompton Greaves Consumer Electricals Ltd.
-
Orient Electric Ltd.
-
Havells India Ltd.
-
Emerson Electric Co.
- *Disclaimer: Major Players sorted in no particular order
Ceiling Fan Market Companies Covered in this Report
- Hunter Fan Company
- Crompton Greaves Consumer Electricals Ltd.
- Orient Electric Ltd.
- Havells India Ltd.
- Emerson Electric Co.
- Panasonic Corporation
- Midea Group
- Minka Group
- Haier Group
- Usha International
- Superfan (Versa Drives)
- Atomberg Technologies
- Fanimation Inc.
- Westinghouse Lighting
- Vent-Axia (Volution Group)
- Casablanca Fan Company
- Delta Electronics
- LG Electronics
- Bajaj Electricals Ltd.
- Khind Holdings Berhad
Key Opportunities for Market Participants
The opportunities compare financed household installations in New South Wales with rating-led fan renewal in India. NSW’s Home Energy Saver zero-interest loans cover ceiling fans or other eligible technology for homeowners and landlords. Applicants must be Australian citizens or permanent residents and meet a taxable-household-income limit. The NSW Government funds the loans, which selected finance providers deliver.
Market Opportunities Table of Ceiling Fan Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Financed owner-occupied ceiling-fan installations | Zero-interest financing covers ceiling fans | Eligible NSW homeowners | Provide an itemized fan-and-installation quote for the loan application | Household eligibility and repayment capacity | Ceiling-fan retailers and installation contractors |
| Landlord-funded ceiling-fan upgrades | Landlords can use the same financing route | Eligible NSW landlords | Organize property-specific installation offers around the applicant’s approved scope | Coordinating installation access and loan repayment | Rental-property installation providers and fan suppliers |
| Rating-preserving complete-fan redesign | Indian ceiling-fan rating tables apply during 2026-2028 | Residential replacement-fan suppliers serving India | Refresh complete fans against the applicable service-value band | Achieving rated performance at the intended selling price | Manufacturers with verified efficiency designs |
| Source: Mordor Intelligence | |||||
India's revised rating tables give suppliers a reason to redesign complete fans to preserve a model's rated position. NSW provides a financing-led installation opportunity because eligible applicants select a finance provider and gather quotes before applying for a Home Energy Saver loan. A contractor quoting the complete fan-and-installation job can compete for both the equipment sale and installation earnings, making control of the installed scope commercially valuable.
Recent Industry Developments in Ceiling Fan Market
- Oct 2026: Orient Electric Ltd. reported 26% year-over-year growth in its BLDC fan portfolio in Q2 FY27, driven by new premium launches.
- Aug 2026: Crompton Greaves Consumer Electricals Ltd. reported approximately 44% year-over-year growth in its BLDC fan portfolio in Q1 FY27, which reached its highest quarterly sales.
- Apr 2026: Hunter Industrial, a division of Hunter Fan Company, reported an expanded Center for Engineering Excellence in Smyrna, Tennessee, to support fan engineering for demanding environments.
Ceiling Fan Market Report Scope and Research Methodology
Market Definition and Coverage
The ceiling fan market measures annual factory-gate sales value of newly manufactured, ceiling-mounted electric fans worldwide. It covers fans differentiated by design, airflow scale, energy performance, lighting, connectivity, power source, and motor technology, for residential, commercial, and industrial use and sold through retail or direct manufacturer-to-project channels.
Scope exclusions: Portable, wall-mounted, and pedestal fans, exhaust fans, HVLS ceiling fans with a diameter above 24 ft, and separately sold replacement parts, installation, repair, and maintenance are excluded.
Segments Covered in This Report
-
By Product Type
- Standard
- Decorative
- Energy-Saving
- High-Speed
- With Integrated Light
- HVLS
- Smart / IoT
- Solar-Powered
-
By Technology
- AC Motor
- DC Motor
- BLDC Motor
-
By End-User
- Residential
- Commercial
- Industrial
-
By Distribution Channel
-
B2C/Retail Channels
- Multi-Brand Stores
- Exclusive Brand Outlets
- Online
- Other Distribution Channels
- B2B/Project Channels (direct from the manufacturers)
-
B2C/Retail Channels
-
By Geography
-
North America
- United States
- Canada
- Mexico
-
South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
-
Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
-
Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
-
Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
-
North America
Data Sources, Market Sizing, and Validation
Desk Research
The U.S. Department of Energy's ceiling-fan standards and test-procedure pages help establish the regulated product and efficiency requirements, while India's Bureau of Energy Efficiency notification and CLASP's ceiling-fan market transformation study inform technology adoption and labeling changes. The U.S. Census Bureau's residential construction series provides a housing activity indicator, and company annual reports such as Polycab India's describe product mix, channel development, and manufacturing signals relevant to complete-fan sales.
Filings, investor materials, company announcements, and reputable press coverage can supplement these sources by clarifying manufacturer revenue, product launches, retail reach, and changes in customer demand. Source findings are checked against public market and regulatory evidence. These named sources are illustrative and not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include ceiling-fan manufacturers, motor and component suppliers, distributors and retailers, and buyers responsible for residential, commercial, or industrial projects across APAC, EMEA, and the Americas. Respondents would be asked to check secondary findings on sales routes, product mix, average realized prices, replacement demand, and regional conditions, with disagreements tested against independent public evidence. Unresolved gaps would be documented, bounded with the strongest available market indicators, and triangulated across supplier, channel, and end-user perspectives.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 18% | APAC: 42% |
| Mid tier: 50% | Functional/Unit leaders: 32% | EMEA: 30% |
| Smaller Players: 20% | Managers: 50% | Americas: 28% |
Market-Sizing & Forecasting
The model estimates global annual factory-gate value from a top-down view of complete ceiling-fan demand and checks selected totals with supplier roll-ups, channel checks, and sampled average selling price times shipment volume. Key inputs include housing completions and retrofit activity for installation demand, fan production and shipment trends for unit supply, household and building energy-efficiency rules for motor and product mix, channel mix for sell-through, and material and finished-fan prices for value per unit. Product, motor, end-user, channel, and regional shares are built from available shipment, revenue, and channel evidence and checked so each axis reconciles to the market total. When reported data do not isolate a segment, analogous product evidence and bounded expert checks guide the allocation. Historical drivers and observed sales patterns support a multivariate regression forecast, with scenario analysis used where policy, cooling substitution, or construction conditions may materially alter demand. Primary respondents check the direction and plausibility of key variables, and missing inputs are bounded using the closest comparable public series before reconciliation.
Data Validation & Update Cycle
Analysts triangulate the estimate against independent production, shipment, housing, regulatory, and company signals, then investigate unusual movements and material variance between sources before sign-off. Review proceeds from source and unit checks to segment and regional reconciliation and senior analyst review. Respondents are re-contacted when a material definition, price, volume, or timing discrepancy remains. The model is refreshed annually, updated between cycles when a material policy, supply, or demand event changes an input, and receives a fresh pre-delivery review.
Mordor Intelligence's Ceiling Fan Market Sizing Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The ceiling fan market measures annual factory-gate sales value of newly manufactured, ceiling-mounted electric fans worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key inputs include housing completions and retrofit activity for installation demand, fan production and shipment trends for unit supply, household and building energy-efficiency rules for motor and product mix, channel mix for sell-through, and material and finished-fan prices for value per unit.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 13.39 B (2027) | |
| Global Consultancy A | USD 11.8 B (2025) | At its 2025 base, this estimate is 11.9% below this report's 2027 value of USD 13.39 B, 2 years later. Its two-year-earlier base year precedes the comparison year, which can account for a lower reported value in a growing market. |
| Global Consultancy B | USD 11.33 B (2025) | At its 2025 base, this estimate is 15.4% below this report's 2027 value of USD 13.39 B, 2 years later. Its two-year-earlier base year precedes the comparison year, which can account for a lower reported value in a growing market. |
Mordor Intelligence's analysts triangulate the estimate against independent production, shipment, housing, regulatory, and company signals, then investigate unusual movements and material variance between sources before sign-off.
Key Questions Answered in the Report
What is the ceiling fan market size and growth outlook?
The size is estimated at USD 12.89 billion in 2026 and projected at USD 13.39 billion in 2027. It is forecast to reach USD 16.01 billion by 2032, with a 3.64% CAGR from 2027 to 2032.
What is driving demand for energy-efficient and connected ceiling fans?
India’s tighter 2026-2028 rating bands encourage efficiency redesign, while smart-home adoption has supported connected-fan entry, such as Signify’s 2025 EcoLink expansion.
Which ceiling-fan product type leads revenue?
Standard fans led with a 37.32% share of market revenue in 2026, while energy-saving fans are forecast to grow fastest at a 5.25% CAGR from 2027 to 2032.
Which companies compete in ceiling fans?
Established suppliers include Hunter Fan Company, Crompton Greaves Consumer Electricals Ltd., Orient Electric Ltd. and Havells India Ltd.
What limits the ceiling-fan sector’s outlook?
Affordable air-conditioners compete for household cooling spending in Bangladesh. V-Guard also reported ceiling-fan channel inventory after sales ahead of a January rating change in its Q1 FY27 call.
Which region leads ceiling-fan sales and growth?
Asia-Pacific led with 49.13% of market revenue in 2026 and is forecast to grow fastest at a 4.95% CAGR from 2027 to 2032.