
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 1.79 Billion |
| Market Size (2026) | USD 1.88 Billion |
| Market Size (2031) | USD 2.43 Billion |
| Growth Rate (2026 - 2031) | 5.27 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Canada Crop Protection Chemicals Market Analysis by Mordor Intelligence
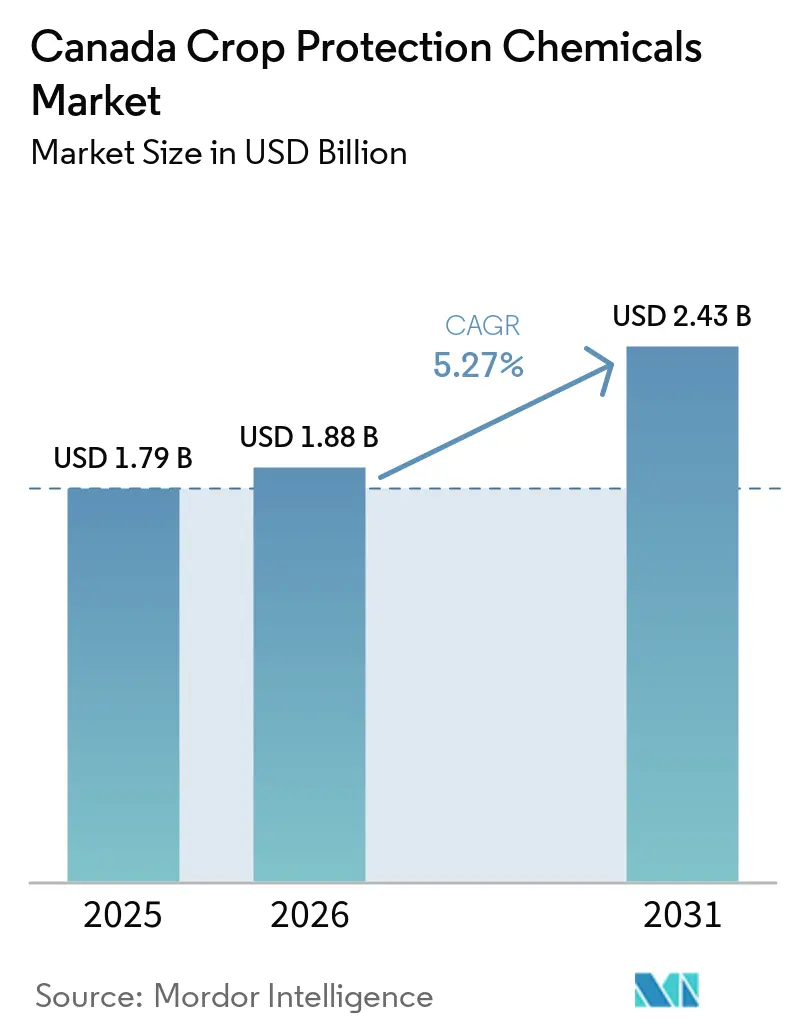
The Canada crop protection chemicals market size was valued at USD 1.79 billion in 2025 and is forecast to grow from USD 1.88 billion in 2026 to USD 2.43 billion by 2031, at a CAGR of 5.27% from 2026 to 2031. Weed resistance continues to support demand for differentiated herbicide programs across the Prairie provinces. Expanding domestic canola processing capacity strengthens crop profitability and supports grower investment in crop protection inputs. Precision application technologies are influencing product selection as growers seek improved application efficiency and reliable pest control. Suppliers are responding with integrated trait, chemistry, and digital agronomy offerings. However, regulatory review delays, tightening maximum residue limits in export markets, and dependence on imported active ingredients remain material constraints on the Canada crop protection chemicals market.
Key Report Takeaways
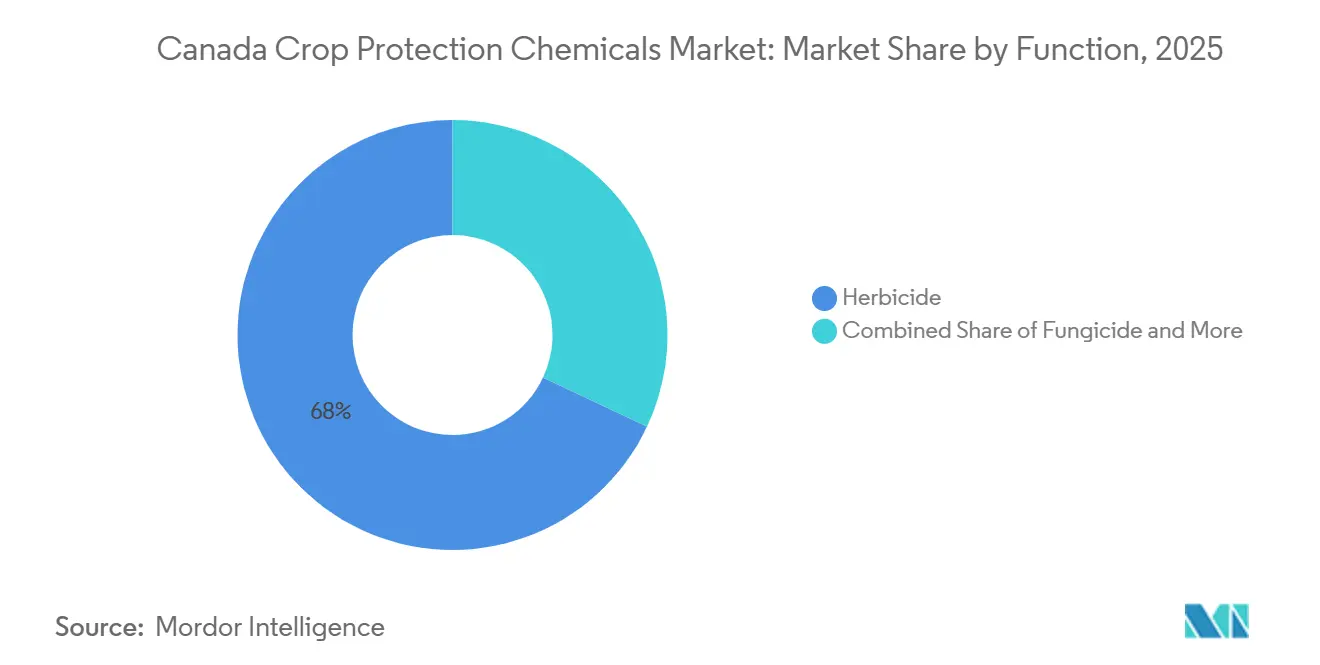
- By function, herbicides accounted for 68.2% of the Canada crop protection chemicals market share in 2025 and are forecast to grow at a CAGR of 6.50% from 2026 to 2031.
- By application mode, soil treatment accounted for 39.1% of the Canada crop protection chemicals market size in 2025 and is forecast to grow at a CAGR of 6.10% from 2026 to 2031.
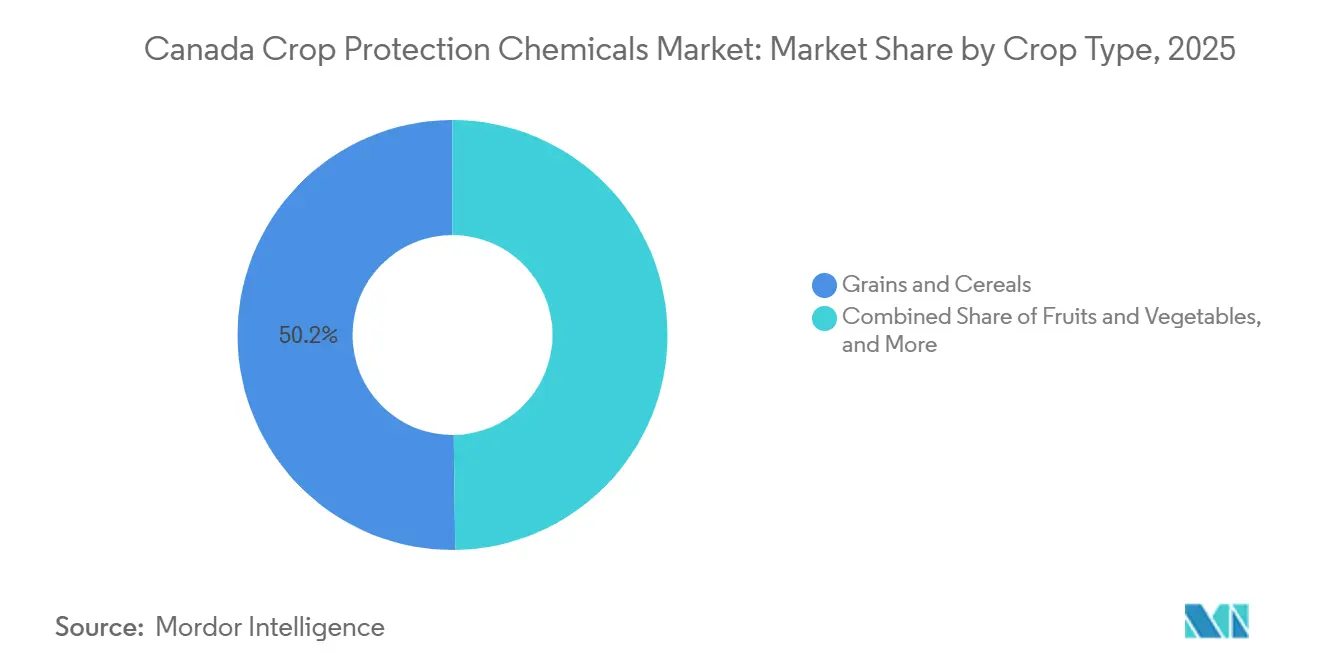
- By crop type, grains and cereals accounted for 50.2% of the market share in 2025 and are forecast to grow at a CAGR of 6.01% from 2026 to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Canada Crop Protection Chemicals Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Climate-Driven Surge in Pest Populations | +1.2% | Western Canada, with effects extending to Eastern Canada and British Columbia | Medium term (2-4 years) |
| Herbicide-Resistant Weed Management Imperatives | +1.0% | Alberta, Saskatchewan, and Manitoba | Short term (≤ 2 years) |
| Precision-Agriculture Adoption Raising Chemical Use Efficiency | +0.7% | Western Canada, with growing use in Eastern Canada | Medium term (2-4 years) |
| Government Support and Agricultural Risk Management | +0.4% | National, with strong relevance in Saskatchewan, Alberta, and Manitoba | Short term (≤ 2 years) |
| AI-Enabled Predictive Pest Forecasting | +0.5% | Western Canada and Ontario, with national expansion through digital platforms | Medium term (2-4 years) |
| Carbon Credit Programs Rewarding Yield Preservation | +0.2% | National, with strong relevance in Saskatchewan, Alberta, and Manitoba | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Climate-Driven Surge in Pest Populations
Warmer winters and longer growing seasons are extending pest life cycles and altering pest pressure across the Canadian Prairies. Agriculture and Agri-Food Canada reports that changing weather patterns affect agricultural production and can increase pest and disease risks across Canada's agricultural regions[1]. Research published in Cell Reports Sustainability in 2026 found that migratory leafhopper populations can increase after thermal thresholds are reached in Canadian agroecosystems, while also identifying risks of northward establishment for pest species historically limited by temperature[2]. These shifts can increase the frequency and geographic range of pest outbreaks, requiring growers to strengthen crop monitoring and adopt timely pest-management measures. As pest pressure expands into new production areas, demand for effective insecticides and other crop protection products is likely to increase, particularly where chemical intervention remains necessary to protect yields. Consequently, climate-driven changes in pest populations are anticipated to support the growth of the Canada crop protection chemicals market over the forecast period.
Herbicide-Resistant Weed Management Imperatives
Herbicide resistance is increasing the complexity of weed management for Prairie growers and is supporting demand for diversified crop protection programs. A 2024 study published in the Canadian Journal of Plant Science confirmed the presence of Group 14-resistant kochia in Western Canada, highlighting reduced sensitivity to protoporphyrinogen oxidase inhibitor herbicides and increasing challenges in managing the weed[3]. In response, growers are increasingly incorporating multiple modes of action, herbicide mixtures, and rotational weed-management strategies to improve control and delay the development of further resistance. This supports demand for herbicides with different modes of action and formulations that can be integrated into resistance-management programs. As resistance becomes more widespread across major crop-producing regions, the need for effective and diversified weed-control solutions is anticipated to support the growth of the market.
Precision-Agriculture Adoption Raising Chemical Use Efficiency
The adoption of precision agriculture technologies is improving the accuracy and efficiency of chemical applications for crop protection across Canada. Variable-rate systems, targeted spraying, and drone-based application technologies enable growers to adjust product placement and application rates according to crop and field conditions. Corteva Agriscience conducted spray drone trials for fungicide application in canola and wheat through EMILI Innovation Farms in Saskatchewan and Manitoba, generating field-level evidence on spray coverage and dose performance under Canadian conditions. These technologies can reduce unnecessary chemical application while supporting more precise use of crop protection products, increasing the importance of formulations that deliver consistent efficacy at optimized application rates. As Canadian growers increasingly adopt precision application technologies, demand is anticipated to shift toward higher-performance crop protection products and application solutions, supporting the evolution of the Canada crop protection chemicals market.
Government Support and Agricultural Risk Management
Government-funded agricultural risk-management programs help Canadian farmers manage income volatility and maintain production activities during periods of adverse weather, fluctuating commodity prices, and rising input costs. The Sustainable Canadian Agricultural Partnership provides CAD 3.5 billion (USD 2.5 billion) in federal, provincial, and territorial funding between 2023 and 2028, supporting agricultural programs and risk-management initiatives across Canada. Programs such as AgriStability provide financial assistance to eligible producers experiencing significant declines in farming income, helping them manage financial pressures that could otherwise constrain operating expenditures. By improving financial resilience and supporting continuity in crop production, these initiatives can help farmers maintain spending on essential agricultural inputs, including herbicides, fungicides, insecticides, and other crop protection products. Continued government support for farm risk management and agricultural resilience can therefore help sustain demand for crop protection chemicals in Canada.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Divergent Maximum Residue Limit Requirements Across Export Markets | -0.8% | National, especially Ontario crop exports and the Prairie canola belt | Short term (≤ 2 years) |
| Rising Active Ingredient Restrictions Due to Regulatory Re-evaluations | -0.5% | National, affecting canola and pulse regions | Medium term (2-4 years) |
| Supply-Chain Volatility for Key Intermediates | -0.4% | Western Canada and formulators using imported technical materials | Short term (≤ 2 years) |
| Accelerating Grower Shift to Regenerative Farming | -0.3% | National, with greater relevance in Ontario, Quebec, and British Columbia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Divergent Maximum Residue Limit Requirements Across Export Markets
Differences in maximum residue limit (MRL) requirements across international markets can constrain the use of crop protection chemicals on Canadian crops destined for export. Products registered for use in Canada may not have equivalent residue tolerances in key importing countries, requiring growers and suppliers to assess the suitability of crop protection treatments for specific export markets. In January 2025, the joint Market Access Committee for corn and soybeans, co-chaired by Soy Canada and Grain Farmers of Ontario, assessed the residue profiles and export-market requirements of three new corn crop protection products. This review highlights the importance of evaluating pesticide use against international residue standards to minimize potential trade disruptions. Differences in residue tolerances can complicate product selection for export-bound crops and require suppliers to consider the standards of destination markets when recommending crop protection programs. These compliance requirements can increase the complexity of product selection and create challenges for introducing new crop protection chemistries into export-oriented production systems in Canada.
Rising Active Ingredient Restrictions Due to Regulatory Re-evaluations
Health Canada’s Pest Management Regulatory Agency (PMRA) follows a structured work plan for pesticide re-evaluations and special reviews. The agency’s 2025-2030 plan includes work on clothianidin, thiamethoxam, spinetoram, spinosad, and glufosinate ammonium. Ongoing regulatory reviews and potential changes to permitted uses can make long-term product planning more difficult for suppliers and growers. They can also increase interest in products with a different regulatory profile, requiring suppliers to reassess product portfolios and application recommendations. Rotation programs need to adapt when established active ingredients face restrictions or changes in permitted uses. These requirements can increase regulatory uncertainty and compliance costs while limiting the pace of adoption and expansion of certain crop protection products in the Canada crop protection chemicals market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Function: Herbicides Maintain the Largest Share and Deliver Strong Growth
Herbicides accounted for 68.2% of the Canada crop protection chemicals market share in 2025 and are forecast to grow at a CAGR of 6.50% from 2026 to 2031. This dominance reflects the importance of no-till farming in Alberta, Saskatchewan, and Manitoba. Pre-plant burndown and in-crop weed control remain central to crop establishment. Canadian research has documented the spread of Group 14-resistant kochia in Western Canada, encouraging growers to use multiple modes of action within a single program.
Fungicides provide the disease-control layer within broader crop protection programs. Precision application can make fungicide decisions more field-specific rather than uniform across every acre. Insecticides address insect pressure in canola, cereals, pulses, and specialty crops. Molluscicides and nematicides serve narrower applications but remain relevant where specific field risks occur. Product portfolios that combine resistance management with crop-specific performance remain important across the Canada crop protection chemicals market.



By Application Mode: Soil Treatment Dominates, with Steady Market Expansion
Soil treatment accounted for 39.1% of the Canada crop protection chemicals market size in 2025 and is forecast to grow at a CAGR of 6.10% from 2026 to 2031. Root-zone availability and persistence support its use against soil-borne threats. Soil treatment also plays a role in resistance management where growers seek early-season control. Prairie resistance research has shown that Group 14-resistant kochia requires careful management across different application approaches.
Seed treatment remains a major mode of application because it protects crops during establishment. Syngenta introduced Curanza seed treatment for Canadian canola growers in 2026 to control flea beetle and cutworm. Foliar products retain a major role but face greater exposure to targeted spraying systems. Chemigation can gain relevance where irrigation infrastructure allows crop inputs to be applied with water. Fumigation remains a smaller application mode, focused on specific soil and pest management needs.
By Crop Type: Grains and Cereals Account for the Largest Share, with Continued Growth
Grains and cereals accounted for 50.2% of the market share in 2025 and are forecast to grow at a CAGR of 6.01% from 2026 to 2031. Wheat and barley provide a large production base for the grains and cereals segment, while canola contributes to demand within the pulses and oilseeds segment. The United States Department of Agriculture (USDA) forecasts Canadian oilseed crush capacity at 14.8 MMT in 2026, compared with 13.56 MMT in 2025. Greater domestic processing capacity supports canola economics and can sustain investment in agronomic programs. Research also shows that resistant kochia has implications for glufosinate-resistant canola systems.
Pulses and oilseeds require crop-specific weed, disease, and insect programs. Soybean production in Ontario, Manitoba, and Quebec adds a distinct demand profile to the national crop base. Fruits and vegetables have greater residue-management needs due to fresh-market and export requirements. Commercial crops, turf, and ornamental applications account for a smaller share of demand but require specialized product selection. This diversity gives suppliers several routes to serve the Canada crop protection chemicals market.

Geography Analysis
Western Canada is the largest regional segment of the Canada crop protection chemicals market, with Alberta, Saskatchewan, and Manitoba forming the core production region. Widespread cultivation of major field crops and weed resistance across Prairie farming systems support demand for herbicides and other crop protection products. The region's agricultural processing infrastructure also contributes to the broader crop production ecosystem. Louis Dreyfus Company expanded its Yorkton facility capacity to more than 2 MMT annually, while Cargill opened its Regina facility in spring 2025, strengthening regional crop-processing capacity. These developments reinforce the importance of Prairie crop production, although their direct impact on crop protection chemical demand depends on farmers' acreage, crop mix, and input-use decisions.
Eastern Canada has a different crop mix, led by corn and soybean rotations in Ontario. Quebec operates under a more restrictive provincial regulatory framework for synthetic pesticide use compared to federal requirements. Demand in this region is shaped by fungicide and insecticide needs, as well as herbicide programs. Proposed limits on post-emergence dicamba use affect soybean and corn growers in this region. The Atlantic Provinces remain a smaller market, with potato production driving focused fungicide and nematicide demand.
British Columbia serves high-value horticulture, including tree fruits, grapes, berries, and greenhouse vegetables. The region has demand for specialty fungicides, insecticides, and miticides associated with its high-value horticultural production. Health Canada completed a re-evaluation decision for potassium bicarbonate in August 2026, continuing its registration with label amendments for worker protection. These regulatory requirements influence product availability and application practices in the Canada crop protection chemicals market.
Competitive Landscape
Market Concentration
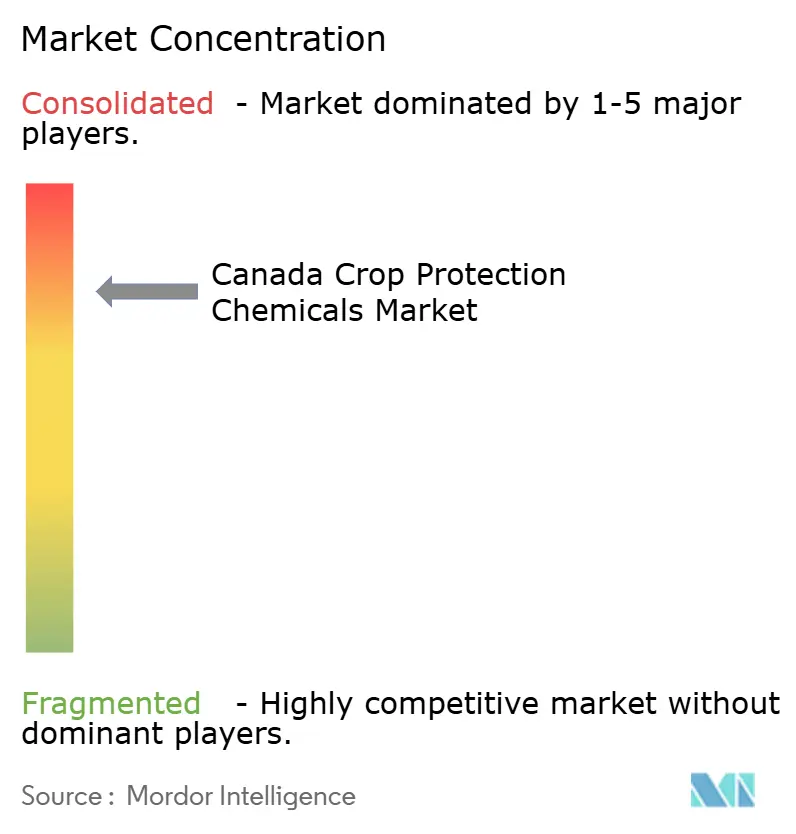
The Canada crop protection chemicals market was moderately concentrated in 2025, with Bayer AG, Syngenta Group, BASF SE, Corteva Agriscience, and FMC Corporation among the major suppliers. These companies compete through branded chemistry, seed treatment, crop traits, and agronomic support. BASF SE strengthens its canola position through its glufosinate-tolerant crop platform, while Corteva Agriscience supports its offering through the Enlist weed control system and Canadian field innovation initiatives. Smaller participants, including Nufarm Limited, UPL Limited, Gowan Company, L.L.C., and American Vanguard Corporation, target generic and specialty product categories.
Product innovation and strategic partnerships are increasingly important to resistance management and application efficiency. FMC Corporation and Corteva Agriscience signed a supply and license agreement for rimisoxafen herbicide technology in June 2026. Corteva Agriscience is also testing drone-based fungicide application in Saskatchewan and Manitoba. These developments highlight suppliers' efforts to expand technology access and improve application practices.
Competitive positioning also depends on product availability, pricing, distribution networks, and the ability to address crop-specific pest management requirements. Differences in crop mix, pest pressure, and resistance-management needs across Canada's agricultural regions influence product selection and supplier performance. Consequently, companies seek to strengthen their market positions through differentiated portfolios, reliable distribution, and solutions tailored to regional crop protection needs.
Canada Crop Protection Chemicals Industry Leaders
-
Bayer AG
-
Syngenta Group
-
BASF SE
-
Corteva Agriscience
-
FMC Corporation
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: Syngenta Canada added Kadexa SC fungicide, containing fluazinam, to its crop protection portfolio. The Group 29 fungicide is registered for use against white mold in soybeans, dry beans, and potatoes, late blight in potatoes, and fungal diseases in horticultural crops. Kadexa SC replaces Allegro 500F in Eastern Canada, while Allegro remains available in Western Canada for the 2027 growing season.
- June 2026: FMC Corporation and Corteva Agriscience entered a co-exclusive supply and license agreement to expand access to FMC’s rimisoxafen herbicide technology across corn and soybean markets in North and South America. Both companies will develop proprietary premix formulations for resistant weed management, with Corteva making an initial USD 200 million pre-purchase payment for future product supply.
- April 2026: Vive Crop Protection Inc. launched Bifender SM, a soil-applied insecticide containing bifenthrin for in-season corn insect control. The product uses Vive’s Soil Mobile platform to move the active ingredient deeper into the soil profile and is applied through chemigation systems, including drip, pivot, and overhead irrigation. Bifender SM is registered for use on corn and other row and specialty crops.
Canada Crop Protection Chemicals Market Report Scope
Crop protection chemicals are substances used in agriculture to control pests, diseases, weeds, and other harmful organisms that affect crop yield and quality. They include herbicides, insecticides, fungicides, nematicides, and molluscicides applied to crops, seeds, and soil. The scope excludes biological crop protection products, microbial pesticides, botanical biopesticides, organic crop protection products, fertilizers, plant growth regulators, and other agricultural inputs that do not primarily function as conventional chemical pesticides.
The Canada crop protection chemicals market report is segmented by function (fungicide, herbicide, insecticide, molluscicide, and nematicide), by application mode (chemigation, foliar, fumigation, seed treatment, and soil treatment), and by crop type (commercial crops, fruits and vegetables, grains and cereals, pulses and oilseeds, and turf and ornamental). The market size and forecasts are provided in terms of value (USD) and volume (metric tons) for all the above segments.
By Function
| Fungicide |
| Herbicide |
| Insecticide |
| Molluscicide |
| Nematicide |
By Application Mode
| Chemigation |
| Foliar |
| Fumigation |
| Seed Treatment |
| Soil Treatment |
By Crop Type
| Commercial Crops |
| Fruits and Vegetables |
| Grains and Cereals |
| Pulses and Oilseeds |
| Turf and Ornamental |
| By Function | Fungicide |
| Herbicide | |
| Insecticide | |
| Molluscicide | |
| Nematicide | |
| By Application Mode | Chemigation |
| Foliar | |
| Fumigation | |
| Seed Treatment | |
| Soil Treatment | |
| By Crop Type | Commercial Crops |
| Fruits and Vegetables | |
| Grains and Cereals | |
| Pulses and Oilseeds | |
| Turf and Ornamental |
Market Definition
- Function - Crop Protection Chemicals are apllied to control or prevent pests, including insects, fungi, weeds, nematodes, and mollusks, from damaging the crop and to protect the crop yield.
- Application Mode - Foliar, Seed Treatment, Soil Treatment, Chemigation, and Fumigation are the different type of application modes through which crop protection chemicals are applied to the crops.
- Crop Type - This represents the consumption of crop protection chemicals by Cereals, Pulses, Oilseeds, Fruits, Vegetables, Turf, and Ornamental crops.
| Keyword | Definition |
|---|---|
| IWM | Integrated weed management (IWM) is an approach to incorporate multiple weed control techniques throughout the growing season to give producers the best opportunity to control problematic weeds. |
| Host | Hosts are the plants that form relationships with beneficial microorganisms and help them colonize. |
| Pathogen | A disease-causing organism. |
| Herbigation | Herbigation is an effective method of applying herbicides through irrigation systems. |
| Maximum residue levels (MRL) | Maximum Residue Limit (MRL) is the maximum allowed limit of pesticide residue in food or feed obtained from plants and animals. |
| IoT | The Internet of Things (IoT) is a network of interconnected devices that connect and exchange data with other IoT devices and the cloud. |
| Herbicide-tolerant varieties (HTVs) | Herbicide-tolerant varieties are plant species that have been genetically engineered to be resistant to herbicides used on crops. |
| Chemigation | Chemigation is a method of applying pesticides to crops through an irrigation system. |
| Crop Protection | Crop protection is a method of protecting crop yields from different pests, including insects, weeds, plant diseases, and others that cause damage to agricultural crops. |
| Seed Treatment | Seed treatment helps to disinfect seeds or seedlings from seed-borne or soil-borne pests. Crop protection chemicals, such as fungicides, insecticides, or nematicides, are commonly used for seed treatment. |
| Fumigation | Fumigation is the application of crop protection chemicals in gaseous form to control pests. |
| Bait | A bait is a food or other material used to lure a pest and kill it through various methods, including poisoning. |
| Contact Fungicide | Contact pesticides prevent crop contamination and combat fungal pathogens. They act on pests (fungi) only when they come in contact with the pests. |
| Systemic Fungicide | A systemic fungicide is a compound taken up by a plant and then translocated within the plant, thus protecting the plant from attack by pathogens. |
| Mass Drug Administration (MDA) | Mass drug administration is the strategy to control or eliminate many neglected tropical diseases. |
| Mollusks | Mollusks are pests that feed on crops, causing crop damage and yield loss. Mollusks include octopi, squid, snails, and slugs. |
| Pre-emergence Herbicide | Preemergence herbicides are a form of chemical weed control that prevents germinated weed seedlings from becoming established. |
| Post-emergence Herbicide | Postemergence herbicides are applied to the agricultural field to control weeds after emergence (germination) of seeds or seedlings. |
| Active Ingredients | Active ingredients are the chemicals in pesticide products that kill, control, or repel pests. |
| United States Department of Agriculture (USDA) | The Department of Agriculture provides leadership on food, agriculture, natural resources, and related issues. |
| Weed Science Society of America (WSSA) | The WSSA, a non-profit professional society, promotes research, education, and extension outreach activities related to weeds. |
| Suspension concentrate | Suspension concentrate (SC) is one of the formulations of crop protection chemicals with solid active ingredients dispersed in water. |
| Wettable powder | A wettable powder (WP) is a powder formulation that forms a suspension when mixed with water prior to spraying. |
| Emulsifiable concentrate | Emulsifiable concentrate (EC) is a concentrated liquid formulation of pesticide that needs to be diluted with water to create a spray solution. |
| Plant-parasitic nematodes | Parasitic Nematodes feed on the roots of crops, causing damage to the roots. These damages allow for easy plant infestation by soil-borne pathogens, which results in crop or yield loss. |
| Australian Weeds Strategy (AWS) | The Australian Weeds Strategy, owned by the Environment and Invasives Committee, provides national guidance on weed management. |
| Weed Science Society of Japan (WSSJ) | WSSJ aims to contribute to the prevention of weed damage and the utilization of weed value by providing the chance for research presentation and information exchange. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


