
Bottled Water Processing Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 223.43 Billion |
| Market Size (2031) | USD 331.24 Billion |
| Growth Rate (2026 - 2031) | 8.19 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
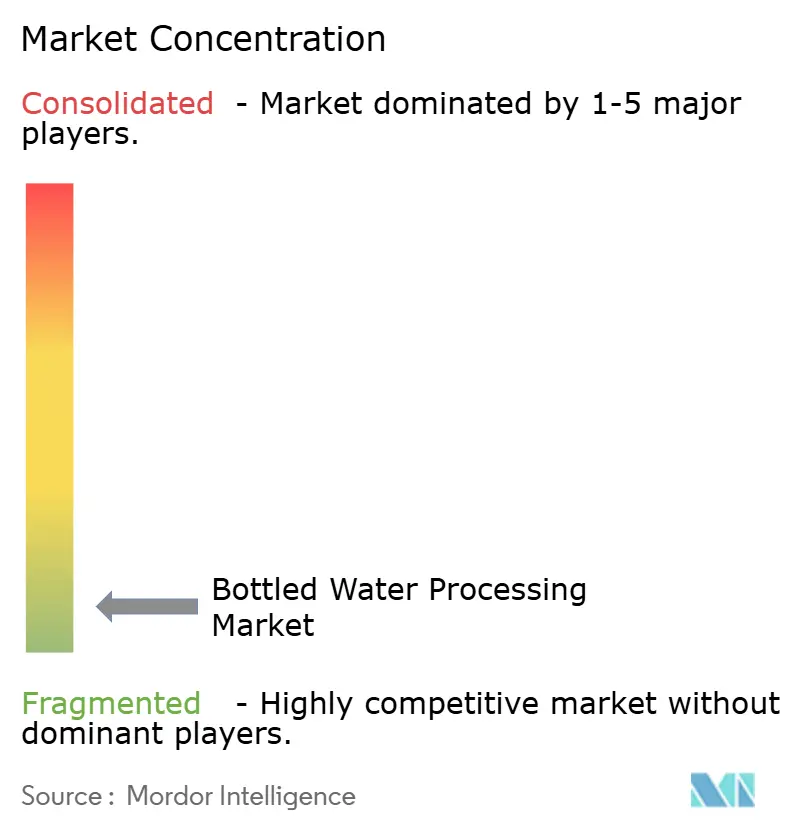
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Bottled Water Processing Market Analysis by Mordor Intelligence
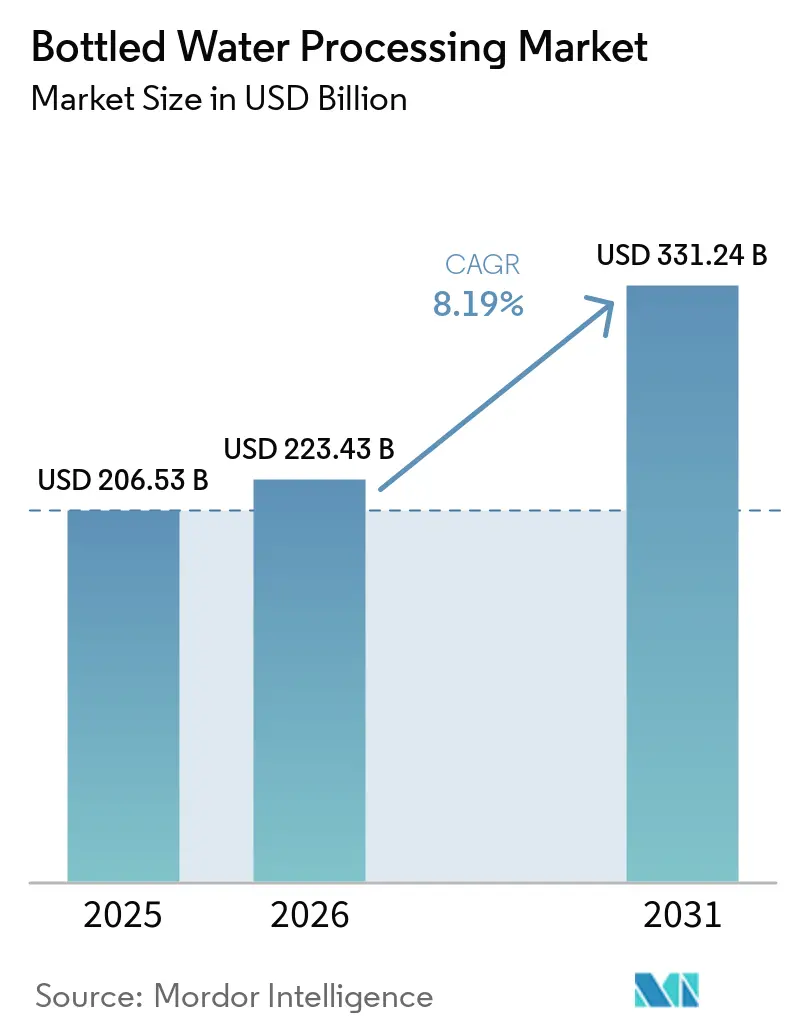
The bottled water processing market size was valued at USD 206.53 billion in 2025 and estimated to grow from USD 223.43 billion in 2026 to reach USD 331.24 billion by 2031, at a CAGR of 8.19% during the forecast period (2026-2031). Rapid urbanization, rising health awareness, and stricter potable-water regulations in both developed and developing regions underpin this expansion. Growing demand for AI-enabled real-time quality monitoring, wider use of mobile and modular bottling lines, and steady investments in energy-efficient membrane technologies further stimulate capital spending on new equipment. Companies continue to streamline operations through industry-4.0 integration, while sustainability mandates accelerate the shift toward recycled PET and emerging bioplastics. Asia–Pacific’s expanding middle class creates the largest volume upside, whereas North America and Europe drive premiumisation and compliance-driven upgrades.
Key Report Takeaways
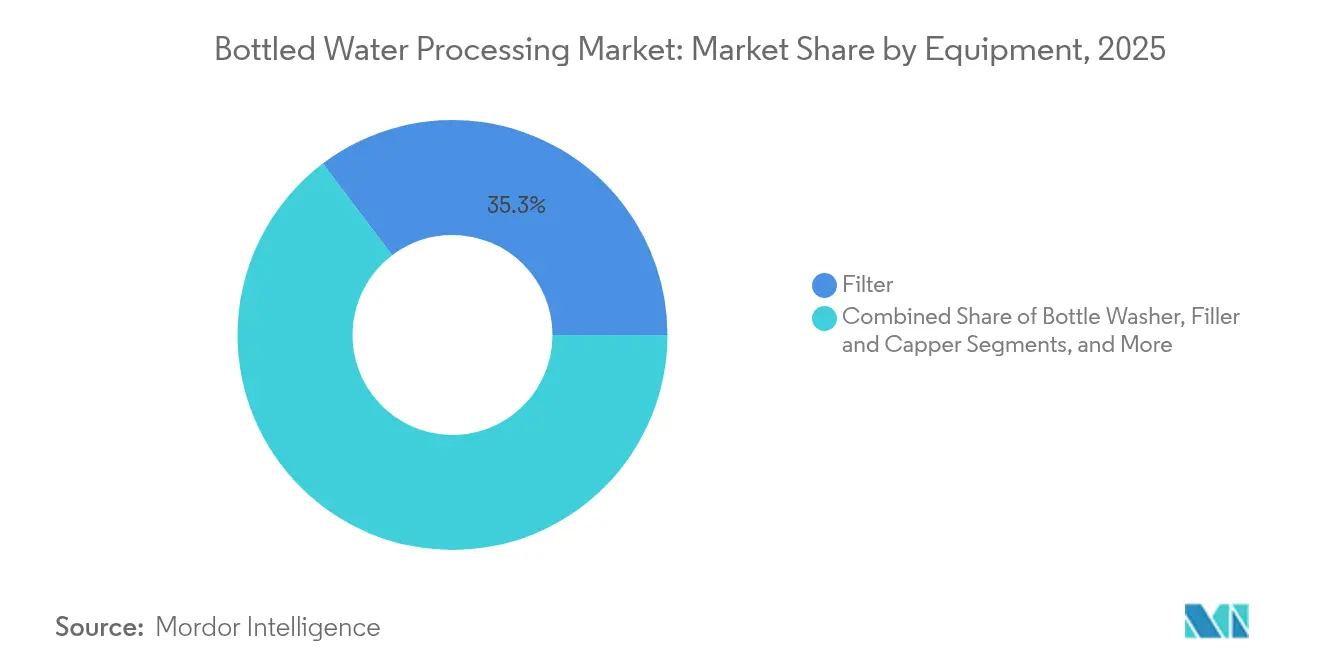
- By equipment, filters led with 35.31% revenue in 2025; shrink wrappers post the quickest 12.63% CAGR through 2031.
- By technology, reverse osmosis held 27.95% of the bottled water processing market share in 2025; microfiltration is projected to grow at 11.86% CAGR to 2031.
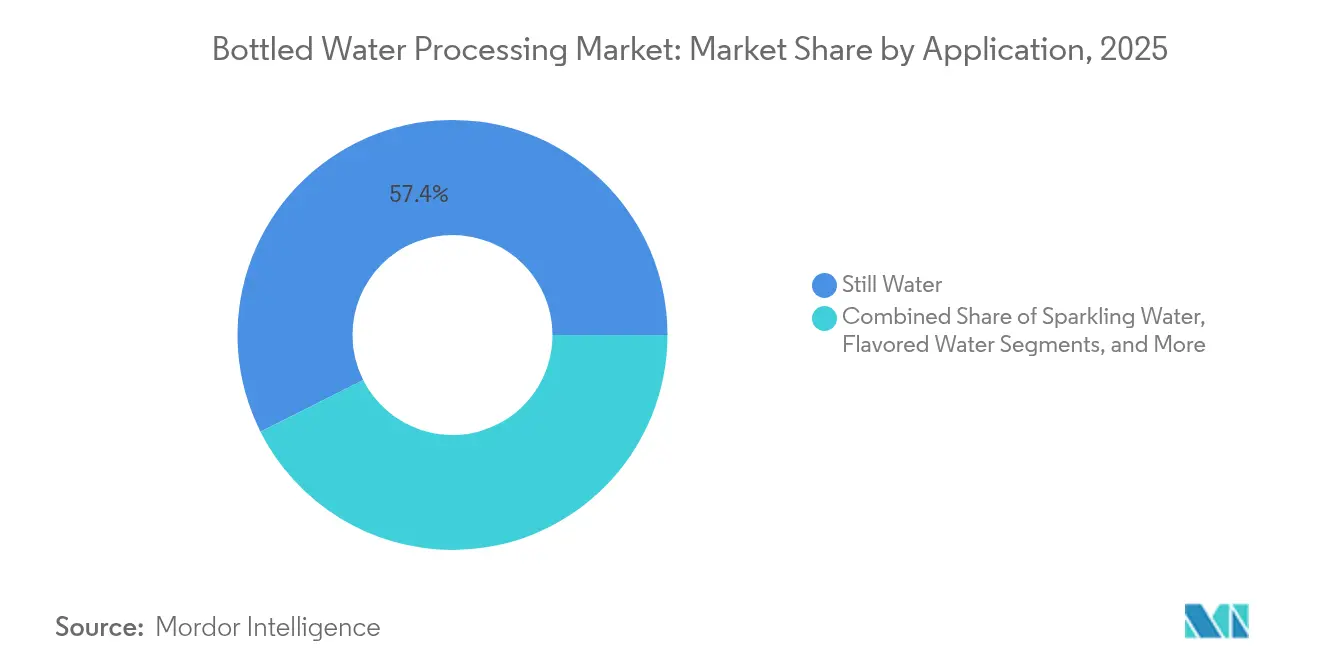
- By application, still water accounted for 57.42% share of the bottled water processing market size in 2025, whereas functional water advances at an 11.59% CAGR to 2031.
- By packaging material, PET dominated with 71.68% share in 2025; bioplastics adoption rises at 11.92% CAGR to 2031.
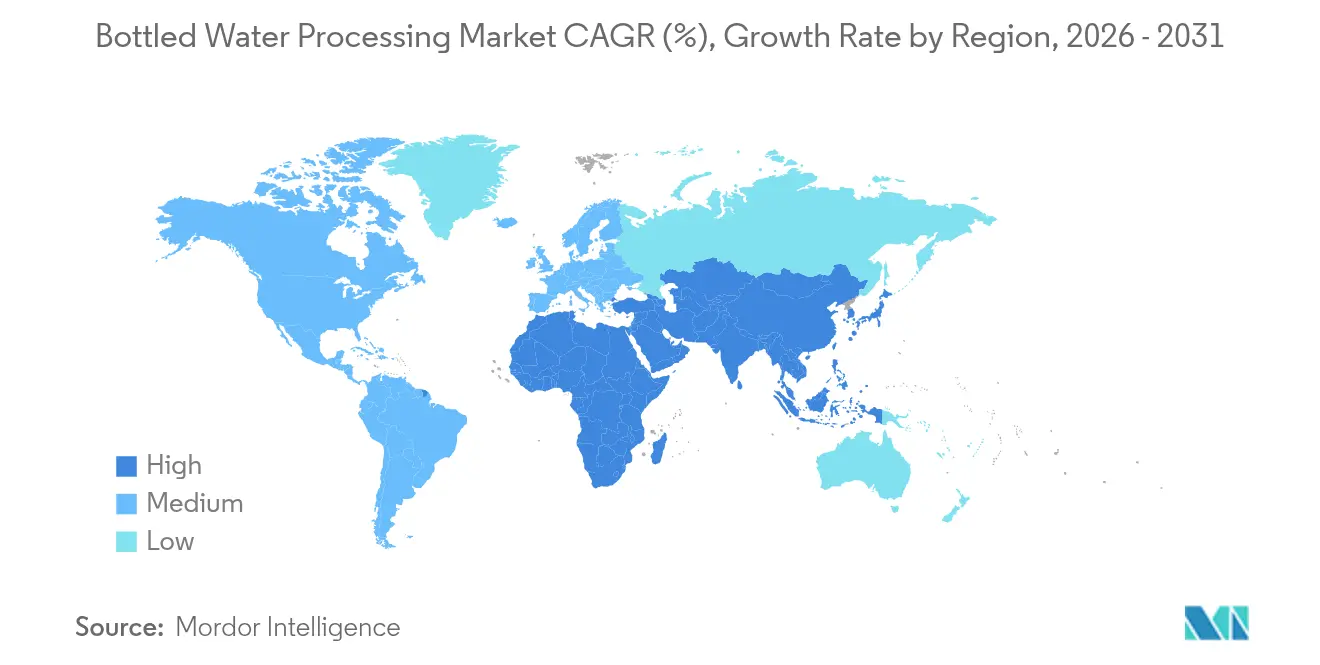
- By region, North America commanded 33.62% market share in 2025; Asia–Pacific expands fastest at 11.07% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Bottled Water Processing Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising consumer health-consciousness | +2.1% | Global; strongest in North America & Europe | Medium term (2-4 years) |
| Urban middle-class expansion in emerging economies | +1.8% | Asia–Pacific core, spill-over to MEA | Long term (≥ 4 years) |
| Regulatory push for potable-water safety | +1.5% | Global; led by EU and North America | Short term (≤ 2 years) |
| Processing and packaging technology innovation | +1.3% | Global; concentrated in developed markets | Medium term (2-4 years) |
| AI-enabled real-time quality monitoring | +0.9% | Early adoption in North America & EU; APAC following | Long term (≥ 4 years) |
| Mobile & modular bottling lines for disaster relief | +0.6% | Priority in disaster-prone regions worldwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Consumer Health-Consciousness
Heightened focus on personal well-being pushes processors to adopt advanced purification and automated microbiological testing that complies with FDA 2024 rules on coliform and E. coli limits.[1]U.S. Food and Drug Administration, “Microbiological Testing and Corrective Measures for Bottled Water,” federalregister.gov Functional water fills a premium niche, requiring multi-stage membrane systems such as Pall’s SUPRAdisc II modules that raise throughput by 40%. AI-driven optical sensors now detect chemical oxygen demand variations with over 90% accuracy, ensuring consistent flavour and safety. Brands market mineral-rich, alkaline, or electrolyte-infused lines to health-centric consumers, adding equipment for precise nutrient dosing. These shifts reinforce demand for high-efficiency filtration, inspection, and clean-in-place systems across the bottled water processing market.
Urban Middle-Class Expansion in Emerging Economies
Asia–Pacific’s sizeable urban migration fuels spending on packaged beverages as modern retail gains reach. Indian joint ventures among Indorama, Dhunseri, and Varun Beverages are building 100 kiloton rPET capacity to support mandatory 30% recycled content targets for 2025-2026. Chinese PET producers such as Wankai scaled back output in late 2024 due to higher crude costs, creating room for energy-efficient equipment suppliers. Latin America sees Brazil and Chile use public-private partnerships to modernise water infrastructure, bringing new bids for mobile treatment plants. Middle-income households in these regions gravitate toward premium still and functional lines, lifting volume and complexity requirements for bottled water processing equipment used by regional bottlers.
Regulatory Push for Potable-Water Safety
Policy makers tighten standards on contaminants, recycled content, and bottled water packaging chemistry. The EU Packaging and Packaging Waste Regulation enforces 30% rPET in beverage bottles by 2030 and bans PFAS from February 2025. The WHO 2025 call to action urges inclusive, climate-resilient water governance, influencing plant design worldwide. NSF/ANSI 53-2022 adds new reduction claims for point-of-use units, prompting wider deployment of specialised cartridges. Compliance now hinges on automated monitoring, digital documentation, and high-performance membranes, pushing the bottled water processing market toward upgraded installations.
Processing and Packaging Technology Innovation
Membrane breakthroughs include graphene-oxide layers with beta-cyclodextrin that capture short-chain PFAS more effectively than polyamide membranes. Electrochemical ozone generators achieve 99.8% bactericidal rates against E. coli without chemical residuals. Connected HMI and AI vision cut water and energy use by 30% in Krones lines. Packaging advances range from PHA bottles that compost within 90 days to lightweight glass and aluminium formats with full circularity programs. Continuous innovation sustains equipment sales as producers retrofit plants for higher speed, lower waste, and diverse containers across the bottled water processing market.
Restraints Impact Analysis of Bottled Water Processing Market*
| Restraint | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Plastic-waste sustainability pressures | -1.4% | Global; strongest in EU & other developed markets | Short term (≤ 2 years) |
| High capital expenditure for equipment | -1.1% | Global; greater impact in emerging markets | Medium term (2-4 years) |
| PET-resin price volatility | -0.8% | Worldwide with regional variations | Short term (≤ 2 years) |
| Municipal refill-station roll-outs | -0.5% | Urban centres in developed markets | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Plastic-Waste Sustainability Pressures
Europe’s BPA ban forces cooler suppliers to convert to PET alternatives by 2029, raising re-tooling costs for moulders. rPET remains USD 750-800 a tonne dearer than virgin PET, dampening adoption despite policy targets. China owns 66% of global PET capacity, undercutting European prices and heightening calls for trade remedies. Wood-based plastics now offer an alternative yet require new extrusion and blowing systems. The transition to circular packaging raises total plant investment and shifts demand toward equipment capable of handling higher recycled content across the bottled water processing market.
High Capital Expenditure for Equipment
Complex filling blocks, aseptic systems, and AI inspection modules command large outlays. Krones posted EUR 537.1 million EBITDA in 2024 partly on the Netstal acquisition for PET preform moulding. Danone spent USD 65 million on a Florida line that reduces bottle loss by 30% with novel moulding. Veolia’s emergency reverse-osmosis fleets illustrate high mobile-system costs and operator training needs. Smaller bottlers in emerging economies often delay upgrades, tempering the growth rate of the bottled water processing market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Bottled Water Processing Market Segment Analysis
By Equipment:
Automation Drives Efficiency GainsFilter assemblies retained 35.31% share in 2025 as multi-stage setups target microplastics and PFAS removal. Shrink wrappers register a 12.63% CAGR through 2031 because automated systems wrap 60-200 bottles per minute while lowering labour overhead. Integrated blow-moulder-filler blocks such as Krones ErgoBloc cut energy draw by optimising heating profiles.
Inspection technology evolves through augmented-reality service that speeds remote diagnostics and drops unplanned downtime to 0.1% in pilot sites. Conveyor systems embed AI vision to anticipate faults, which reduces idle time and boosts line utilisation. As plants target higher throughput, interest in modular conveyors and quick-changeover sleeve labelers widens the addressable base for equipment suppliers across the bottled water processing market.


By Technology:
Membrane Innovation AcceleratesReverse osmosis led with 27.95% share in 2025 thanks to ultrathin polyamide films that channel water up to eight times faster at lower pressure. Microfiltration’s 11.86% CAGR is propelled by hollow-fibre units achieving 98% recovery with minimal chemicals.
Ultrafiltration systems find favour in pre-treatment, easing fouling on downstream RO stages while keeping operating costs in check. Ion exchange sees renewed interest where selective resins strip hardness or heavy metals before bottling. UV LED arrays now provide 99.99% kill rates without mercury, supporting low-carbon operations. Electrochemical ozonation eliminates the need for separate oxygen concentrators, simplifying plant layouts. Such advances sustain the bottled water processing market as producers seek lower energy footprints and better contaminant control.
By Application:
Functional Water Processing ExpandsStill water remained the cornerstone with 57.42% of 2025 demand, produced on high-speed lines topping 80,000 bph. Functional water’s 11.59% CAGR stems from consumer appetite for vitamin, mineral, or electrolyte fortification, which needs precise micro-ingredient dosing under aseptic conditions.
Sparkling formats gain share as carbonation systems stabilise CO₂ dissolution while curbing gas loss. Flavoured waters rely on sterile dosing skids that avoid sugar crystallisation and aroma fade. Mineral water brands protect source integrity while applying UV and ozonation for microbiological safety. The resulting complexity enlarges the installation base for accurate mixing, sterile filling, and closed-loop monitoring across the bottled water processing market.
By Packaging Material:
Sustainability Drives InnovationPET secured 71.68% share in 2025, yet policy targets propel recycled content integration and alternative polymers. rPET food-grade quality demands advanced sorting, flake-washing, and solid-state polymerisation to remove impurities. Bioplastics post a 11.92% CAGR, led by PHA bottles approved for industrial composting within 90 days.
Lightweight glass, now 30% lighter, re-positions bottled water for premium audiences without major carbon penalties. Aluminium bottles benefit from high recycling value and on-the-go convenience. Processing lines shift toward flexible changeovers that handle multiple containers while maintaining sterility, a change that broadens the bottled water processing market size for turnkey integrators.
Geography Analysis
North America Bottled Water Processing Market
North America captured 33.62% market share in 2025, anchored by rigorous FDA microbiological protocols and early adoption of AI inspection. Regional bottlers benefit from established distribution and premium priced functional lines. Coca-Cola’s water stewardship programme and smartwater alkaline extensions illustrate category premiumisation, while PepsiCo pilots 100% recyclable paper bottles through Pulpex partnerships.Investment in AI-enabled maintenance keeps downtime low, reinforcing replacement demand within the bottled water processing market.
APAC Bottled Water Processing Market
Asia–Pacific registers the fastest 11.07% CAGR. Urbanisation and rising disposable incomes support volume growth, and government mandates for recycled content spur equipment upgrades. India’s 100 kiloton rPET projects broaden feedstock for local bottlers. Chinese producers improve operational efficiency after capacity cutbacks caused by high feedstock costs, creating opportunities for advanced low-energy membrane suppliers. Modular and containerised bottling lines meet growing demand in disaster-prone areas, widening the bottled water processing market.
EMEA and LATAM Bottled Water Processing Market
Europe maintains significant share under tightened environmental rules. The Packaging and Packaging Waste Regulation grants first mover advantage to plants capable of 30% rPET and PFAS-free designs. Middle East and Africa witness desalination investments like Metito’s 50,000 m³/day Kazakhstan plant that incorporates bottled output for remote regions. Latin America relies on private capital to upgrade plants in Brazil and Chile, bringing new bids for high-throughput filtration and filling lines.
Mordor Intelligence provides coverage of the bottled water processing market across other key regional markets, including Europe and North America, each with their regulatory frameworks and demand patterns.

Regulatory Landscape
Bottled water processors work within overlapping food-safety and drinking-water frameworks that increasingly require documented verification and more frequent testing. Internationally, Codex Alimentarius standards for packaged waters (including natural mineral waters and other bottled/packaged waters) set baseline definitions used in trade and national rulemaking, while the WHO Guidelines for Drinking-water Quality (4th edition, 2026) continue to shape contaminant risk-management and monitoring approaches adopted by regulators.
Regulatory enforcement is also tightening through public rules and industry codes that feed into equipment upgrades. In the United States, IBWA-aligned compliance practices, including annual third-party plant inspections under the IBWA Bottled Water Code of Practice, support demand for automated microbiological monitoring and traceable documentation. In India, the Food Safety and Standards Authority of India (FSSAI) shifted from mandatory BIS certification toward a continuous, risk-based testing and compliance regime effective January 1, 2026, moving the compliance burden toward ongoing quality systems, lab capacity, and in-line control technologies rather than one-time certification.
Competitive Landscape
The bottled water processing market exhibits fragmentation. Top suppliers combine equipment breadth, digital services, and after-sales networks to protect share. Krones booked EUR 5.29 billion revenue in 2024 and bought Netstal Maschinen for PET preform moulding, completing a closed-loop PET portfolio. Tetra Pak’s Factory Sustainable Solutions integrate nanofiltration, reverse osmosis, and heat recovery, helping plants cut energy and water costs by double-digit percentages.
Danone’s Partner for Growth programme signs 19 strategic suppliers, including SPX FLOW and Graphic Packaging, to lower resource use across its bottling network.[3]Danone, “Partner for Growth Program,” danone.com Sidel’s 80,000 bph Ghana hub shows emerging region investments that pair high speed filling with automated cleaning, giving local producers global-grade throughput.
Disruptors focus on precision membranes, electrochemical ozone, and AI diagnostics. Graphene-based filters outperform classical polymers on PFAS removal, while containerised systems by Kärcher Futuretech deliver 26,000 L/day in crisis zones. Such differentiation pressures incumbents to accelerate R&D, shaping the future trajectory of the bottled water processing market.
Bottled Water Processing Industry Leaders
Bisleri International Pvt. Ltd.
Danone S.A.
Gerolsteiner Brunnen GmbH & Co. KG
Nestle S.A.
Nongfu Spring (Yangshengtang Co. Ltd.)
- *Disclaimer: Major Players sorted in no particular order
Bottled Water Processing Market Companies Covered in this Report
- Nestlé S.A.
- Danone S.A.
- PepsiCo Inc.
- The Coca-Cola Company
- Primo Water Corporation
- Tata Consumer Products Ltd.
- Bisleri International Pvt. Ltd.
- Nongfu Spring Co. Ltd.
- Gerolsteiner Brunnen GmbH & Co. KG
- Otsuka Pharmaceutical Co. Ltd.
- Fiji Water Company LLC
- Voss of Norway AS
- CG Roxane LLC
- Sidel Group
- Krones AG
- Tetra Laval (Sidel)
- GEA Group AG
- Pall Corporation
- Veolia Water Technologies
- Norland International Inc.

Market Opportunities and Future Outlook
The most visible opportunity is where quality assurance, water stewardship, and packaging circularity converge, since producers are backing modernization and tying supplier deliverables to measurable resource outcomes. Danone has disclosed more than EUR 20 million over two years to modernize the evian bottling site and outlined additional funding for preservation of French mineral water sites, supporting demand for higher-efficiency filtration, hygienic design upgrades, and digital performance monitoring on premium lines. Separately, Nestle Waters & Premium Beverages reported 100% Alliance for Water Stewardship (AWS) certification across 39 global bottling sites as of March 2026, which increases emphasis on audit-ready data capture, process controls, and water-use optimization in plant retrofit and new-line specifications.
On packaging, regulatory recycled-content requirements and retailer-led circularity programs create room for rPET-capable bottle handling and contamination-control systems, along with flexible lines able to run multiple container formats. Primo Brands has also framed packaging goals around higher recycled or renewable material shares and a larger reusable-bottle mix, pointing to equipment demand beyond traditional single-use PET, including bottle washing, inspection, and changeover-friendly filling blocks. In Europe, deposit return scheme-linked recycled feedstock programs, including DRS-sourced recycled PET initiatives, add practical pull-through for food-grade rPET processing and typically favor preform and blowing systems that can handle variable recycled-content quality.
Recent Industry Developments in Bottled Water Processing Market
- June 2026: Bisleri International and the Bhamla Foundation inaugurated a Wings of Change art installation made from 2,000 used PET bottles to mark World Environment Day and announced a one-year strategic collaboration for sustainability initiatives. The announcement highlights Bisleri's sustainability credentials and advances PET recycling into mainstream conversations. The collaboration could affect consumer perception and premium PET packaging demand.
- April 2026: Danone announced an investment of more than 20 million euros over two years to modernize its Evian bottling facility and 8 million euros to preserve its water sites, including Evian, Volvic, Badoit, and La Salvetat. The investment supports supply security and modernization for premium brands. It also reinforces a broader sustainability footprint across the Evian portfolio.
- March 2026: Bisleri International launched the report A Vision of Water Governance for Viksit Bharat at 2047 in collaboration with the Observer Research Foundation at the Raisina Dialogue 2026. The publication positions Bisleri as a thought leader in water governance and policy discussion. It may shape regulatory discourse and influence brand trust.


Bottled Water Processing Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the bottled water processing market is defined as the end-to-end activities and systems used to convert raw water into packaged bottled water that meets quality standards. This includes treatment, bottling, and packaging operations across commercial production facilities.
Scope exclusions: We exclude retail bottled water sales value and focus on processing and packaging activities inside the production chain.
Segments Covered in This Report
- By Equipment
- Filter
- Bottle Washer
- Filler and Capper
- Blow Molder
- Shrink Wrapper
- Conveyor
- Inspection System
- Labeler
- Other Equipment
- By Technology
- Reverse Osmosis (RO)
- Microfiltration (MF)
- Ultrafiltration (UF)
- Chlorination
- Ion Exchange
- UV Disinfection
- Ozonation
- Other Technology
- By Application
- Still Water
- Sparkling Water
- Flavored Water
- Functional Water
- Mineral Water
- By Packaging Material
- Plastic (PET)
- Glass
- Aluminum Cans
- Bioplastics
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts by mapping the bottled water processing value chain and tying it to public signals that are hard to dispute, such as packaged water consumption patterns and regulatory compliance requirements. We use sources such as the US FDA bottled water rules, US EPA drinking water standards, WHO drinking water guidance, FAO AQUASTAT water data, and UN Comtrade trade statistics for packaging materials and related equipment flows.
To convert these signals into usable sizing inputs, we also review company filings, investor presentations, reputable press coverage, and association publications that discuss capacity additions. We track packaging shifts (for example, PET and rPET) and treatment upgrades mentioned in these materials. For certain checks like company financials, patent activity around filtration and disinfection, and shipment or trade line items, we also use approved paid databases for structured screening and consistency. The desk sources listed are illustrative only, and many other public and paid sources were reviewed to collect, validate, and clarify data points.
Primary Interviews and Surveys
Primary work is used to pressure-test the desk assumptions with people who see operating decisions in practice. This includes plant and operations managers, quality and compliance leads, procurement teams, and equipment or service participants across key consuming and producing regions. Interviews and surveys help confirm typical line configurations, adoption of treatment steps (such as RO, UV, and ozonation), maintenance and replacement cycles, and how packaging material choices affect spend and throughput. These inputs then support more realistic market totals.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 27% | CXOs: 12% | APAC: 50% |
| Mid tier: 55% | Functional/Unit leaders: 36% | EMEA: 32% |
| Smaller Players: 18% | Managers: 52% | Americas: 18% |
Market-Sizing & Forecasting
Sizing is built using a top-down approach where production and consumption signals for bottled water are reconstructed into a processing demand pool. We then convert that pool into value using realistic processing and packaging cost and investment parameters. To corroborate outputs, we run selective bottom-up approximations, including sampled facility throughput checks, typical line count per plant, and sampled spend per line for filtration, filling, capping, labeling, inspection, and secondary packaging.
Key inputs used in the model include bottled water volume growth by region, capacity additions and utilization signals, the split of still versus sparkling and flavored output, penetration of treatment steps like RO and UV, and packaging material mix shifts (PET, glass, cans, and emerging options). When a variable is not consistently available by country, we bridge gaps using regional proxies and interview-based ranges, and then apply conservative bounds so small-data markets do not get overstated.
For forecasting, we use scenario analysis supported by short-run time series smoothing for stable variables such as replacement cycles. We then overlay demand drivers repeatedly highlighted in interviews, including regulatory tightening, quality monitoring requirements, and sustainability-linked packaging transitions. The output is kept traceable so each region total can be explained through a small set of inputs and a few straightforward adjustments.
Data Validation & Update Cycle
Validation is done in layers so the totals do not depend on one data stream. Model outputs are checked against independent signals such as reported capacity expansions, trade and shipment movements for relevant equipment and materials, and public compliance and quality narratives that point to technology upgrades. When a number looks off, the assumption is revisited, outliers are investigated, and follow-up calls are triggered with respondents who have direct operating context.
Before sign-off, the model and write-up go through multi-step analyst reviews, with variance checks across regions and cross-links to supporting datasets. Reports are refreshed annually, and interim updates are made when material events change demand or pricing assumptions. Right before delivery, a final pass is completed so clients receive the latest updated view based on the most recent information available.
Mordor Intelligence's Bottled Water Processing Market Sizing Compared With Other Published Estimates
Published market numbers for bottled water processing can vary, largely because the boundary between beverage market value, processing activity, and equipment-only spend is not drawn the same way across publishers. Differences also come from the base year used, currency conversion timing, and whether upgrades and replacements are treated consistently or modeled as one-time spikes.
Shipment and commissioning signals for core line assets, alongside treatment-step adoption checks (such as RO and UV) and packaging material mix validation, are the evidence used to keep Mordor Intelligence anchored to processing and packaging activity rather than retail bottled water sales value.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 223.43 B (2026) | |
| Industry Publisher A | USD 191.53 B (2023) | Uses an earlier base year and can understate later-cycle line upgrades and packaging transition investments, which shifts the starting value lower even if long-term drivers are similar. |
| Industry Publisher B | USD 311.10 B (2023) | Blends bottled water market value and equipment spend into one definition, which inflates the total by counting downstream beverage sales and brand-led pricing effects that are outside processing activity. |
Looking across the three figures, the spread is mainly explained by what is counted and the year the counting starts. When the scope stays limited to treatment, bottling, and packaging activity, and inputs are anchored to observable capacity, technology adoption, and line economics, the resulting number becomes easier to track, review, and update in a repeatable way.


Key Questions Answered in the Report
What is the current size of the bottled water processing market?
The market was valued at USD 223.43 billion in 2026.
How fast is the bottled water processing market expected to grow?
It is forecast to rise at an 8.19% CAGR, reaching USD 331.24 billion by 2031.
Which region will grow the fastest through 2031?
Asia–Pacific is projected to expand at an 11.07% CAGR, driven by urbanisation and middle-class income growth.
What equipment category holds the largest share?
Filter systems led with 35.31% revenue share in 2025.
Why are bioplastics gaining traction in water packaging?
Regulatory mandates and consumer pressure for sustainable packaging are driving bioplastic adoption, which now posts a 11.92% CAGR.
How does AI benefit bottled water processing plants?
AI vision and predictive maintenance cut downtime, optimise resource use, and ensure higher product consistency, improving plant profitability.
Page last updated on:


 Your data is secure and never sold or shared.



