
Aviation Analytics Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Size (2031) | USD 7.47 Billion |
| Growth Rate (2026 - 2031) | 12.21 % |
| Fastest Growing Market | Middle East |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Aviation Analytics Market Analysis by Mordor Intelligence
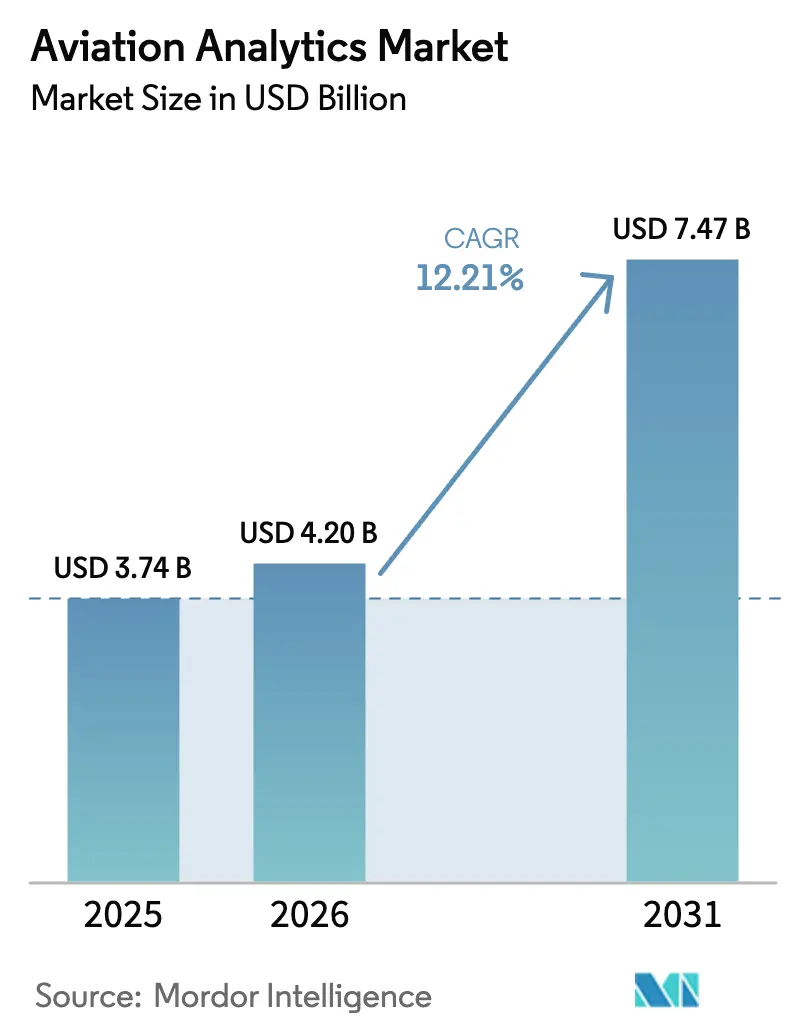
Aviation analytics market size in 2026 is estimated at USD 4.2 billion, growing from 2025 value of USD 3.74 billion with 2031 projections showing USD 7.47 billion, growing at 12.21% CAGR over 2026-2031. Expansion reflects operators’ need to curb fuel costs, comply with safety mandates, and exploit data streaming from new-generation aircraft. Predictive maintenance is being adopted to prevent Aircraft on Ground events that can cost up to USD 100,000 per hour. Fuel-management platforms remain the largest application as airlines use machine-learning models to trim 1–4.3% of total fuel spend. Cloud deployment dominates because scalable infrastructure supports real-time decision-making and AI-driven personalization initiatives. Regional growth is led by the Middle East, where airport capacity programs and fleet renewals require sophisticated data solutions.
Key Report Takeaways
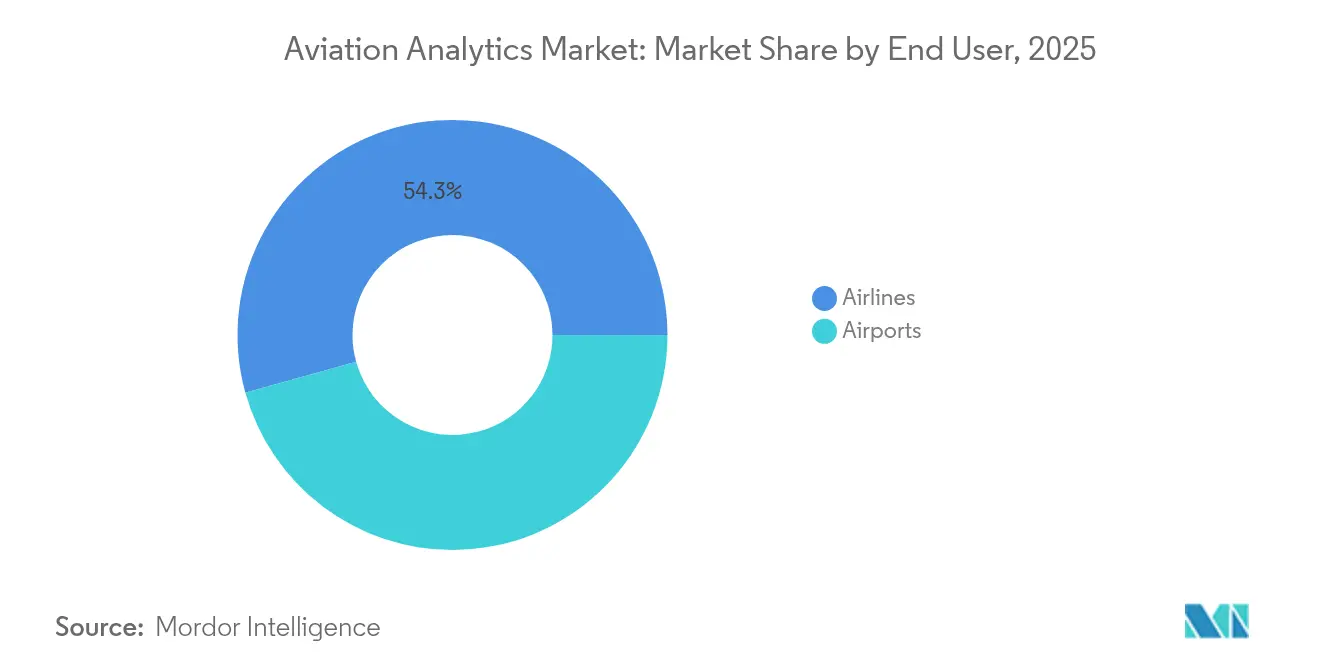
- By end user, airlines led with 54.32% revenue share in 2025, while airports are growing the fastest at a 15.05% CAGR through 2031.
- By application, fuel management captured 29.55% of the aviation analytics market share in 2025; the segment is projected to expand at a 14.08% CAGR to 2031.
- By analytics type, predictive analytics held 45.02% of the aviation analytics market size in 2025; prescriptive analytics is advancing at the highest 13.18% CAGR to 2031.
- By deployment, cloud solutions accounted for 67.12% of 2025 revenue and posted the strongest 15.21% CAGR.
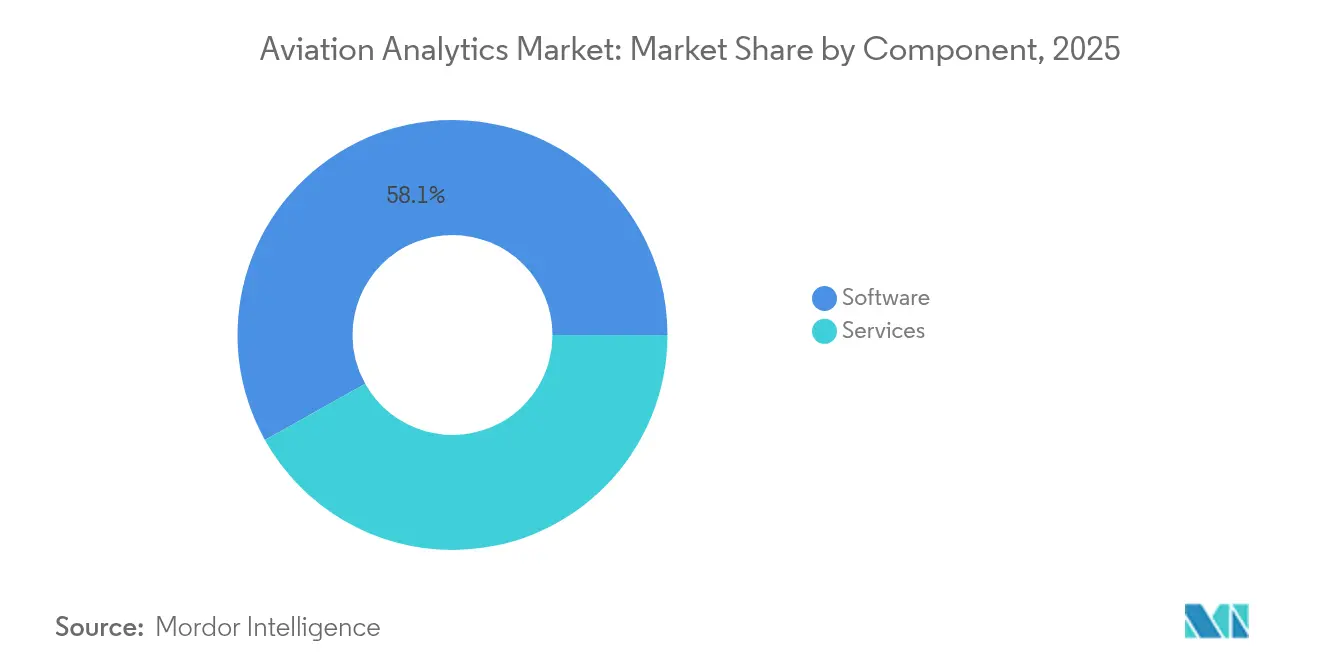
- By component, software represented 58.12% of 2025 sales, whereas services recorded a 12.05% CAGR through 2031.
- By business function, finance commanded 32.10% of the aviation analytics market size in 2025, while supply chain analytics posts a 10.62% CAGR.
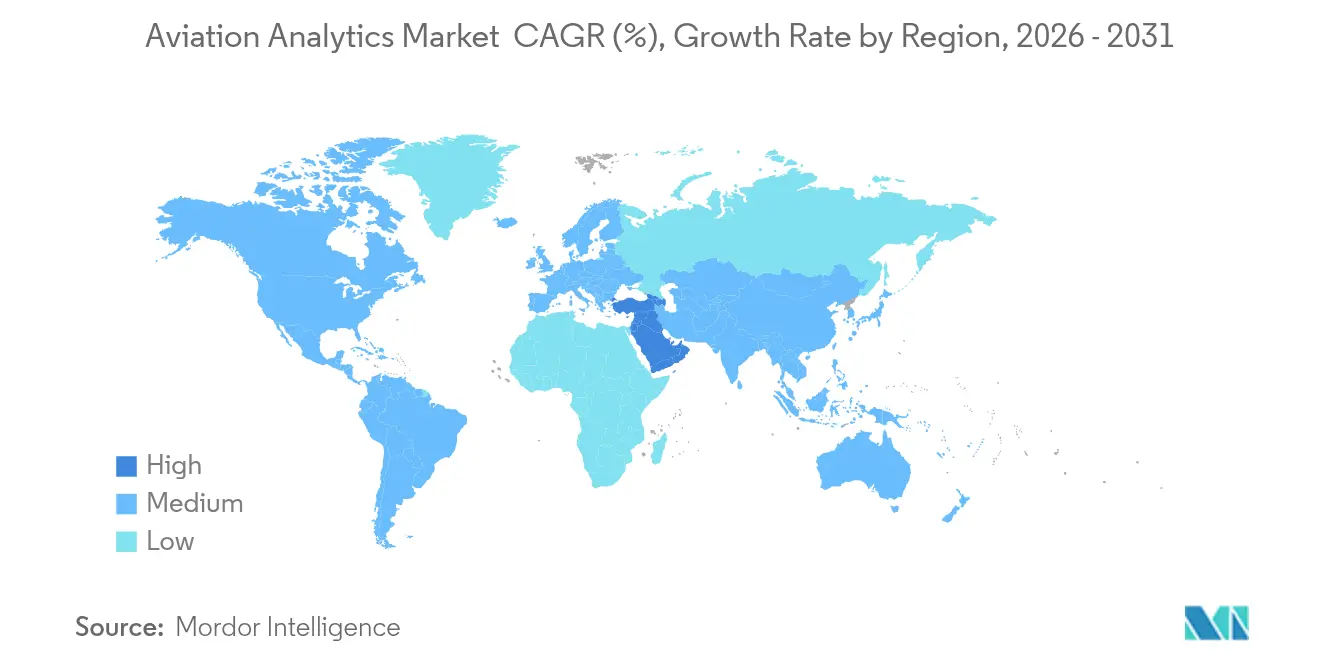
- By geography, North America held a 35.21% share in 2025, whereas the Middle East grew the fastest at an 11.31% CAGR.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Aviation Analytics Market *
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Adoption of predictive maintenance to cut AOG losses | +2.8% | Global, early uptake in North America and Europe | Medium term (2-4 years) |
| Fuel-burn optimization amid SAF cost pressures | +3.1% | Global, strongest in Europe due to regulation | Short term (≤ 2 years) |
| Big-data monetization from new-gen aircraft sensors | +2.2% | North America and Asia-Pacific | Long term (≥ 4 years) |
| Safety-management mandates driving FDM analytics | +1.9% | Europe and North America | Medium term (2-4 years) |
| Real-time SAF performance datasets enabling dynamic routing | +1.7% | Europe and North America, spreading to Asia-Pacific | Short term (≤ 2 years) |
| Edge-AI telemetry from eVTOL fleets creating micro-service analytics demand | +0.8% | North America and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Adoption of Predictive Maintenance to Cut AOG Losses
Airlines connect aircraft to cloud-based diagnostics that analyze real-time sensor feeds and flag impending faults. Airbus estimates predictive programs could save operators USD 4 billion annually by 2043 as 11,600 aircraft stream data into its Skywise ecosystem.[1]Airbus, “Skywise: Digital Alliance for Aviation,” airbus.com United Airlines has demonstrated schedule-reliability gains after scaling fleet health analytics, while Collins Aerospace reports a 30% reduction in maintenance-driven delays through its Ascentia platform.[2]Source: Collins Aerospace, “Ascentia Predictive Maintenance Case Studies,” collinsaerospace.com Veryon Diagnostics notes a 50% drop in troubleshooting time and a 10% cut in delays after embedding AI models that learn from historical part failures. As predictive insights mature, airlines shift from interval-based to condition-based maintenance, freeing labor capacity and spare-parts inventory.
Fuel-Burn Optimization Amid SAF Cost Pressures
Sustainable Aviation Fuel prices sit well above conventional jet fuel, intensifying the need for granular efficiency analytics. Virgin Atlantic’s 100% SAF transatlantic flight saved 95 tonnes of CO₂, validating data-driven flight-planning techniques. Alaska Airlines employs AI to refine track selection and descent profiles, lowering emissions while maintaining on-time performance. Boeing’s Fuel Analytics module analyses more than 650 parameters per flight, delivering 1–3% consumption savings that can top USD 1 million annually for wide-body fleets. Access to real-time SAF performance datasets enables airlines to reroute dynamically based on fuel availability and pricing differentials across hubs.
Big-Data Monetization from New-Gen Aircraft Sensors
Modern airframes generate terabytes of data per flight through advanced avionics and IoT nodes. Academic studies confirm that integrated sensor networks underpin predictive analytics and operational optimization in civil aviation. Platforms such as GE Aerospace FlightPulse convert raw flight parameters into actionable insights for crews, improving approach stability and climb performance.[3]GE Aerospace, “Safety Insight and FlightPulse Product Sheets,” geaerospace.com Airlines increasingly commercialise anonymised operational data by providing benchmarking services to peer carriers and OEMs, creating fresh revenue streams without disrupting core transport operations.
Safety-Management Mandates Driving FDM Analytics
Forty years of evolution of flight data monitoring (FDM) contributed to the fall in global hull-loss accident rates. Teledyne Controls links modern FDM systems with weather and scheduling feeds to contextualise exceedances and spot systemic hazards. GE Aerospace Safety Insight automates data cleaning and risk scoring, helping operators benchmark performance against aggregated peer datasets. European regulators now require continuous safety-performance measurement, accelerating global adoption of comprehensive FDM analytics platforms.
Restraints Impact Analysis of Aviation Analytics Market *
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Legacy IT silos hamper data interoperability | -1.8% | Global, most acute in incumbent carriers | Medium term (2-4 years) |
| Shortage of aviation-savvy data scientists | -1.4% | Severe in Asia-Pacific and Middle East | Long term (≥ 4 years) |
| Cyber-risk of streaming flight data to cloud | -1.1% | Heightened in security-sensitive regions | Short term (≤ 2 years) |
| Passenger-privacy rules limiting behavioural analytics | -0.9% | Europe under GDPR, spreading worldwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Legacy IT Silos Hamper Data Interoperability
Many established airlines run bespoke reservation, maintenance, and finance systems built over decades, resulting in fragmented data landscapes. Integrating these environments demands major investment in middleware and ETL pipelines. Lufthansa broke through this constraint by linking over 10 ERP instances to a unified procurement analytics layer, unlocking spend visibility across the group.[4]Source: “Digital Procurement at Lufthansa,” Lufthansa Group, lufthansagroup.com Nevertheless, change-management hurdles and competing budget priorities slow migration toward real-time enterprise architectures that fully exploit analytics potential.
Shortage of Aviation-Savvy Data Scientists
Advanced analytics projects require professionals versed in both aeronautical engineering and machine learning. Retirements among experienced technicians coincide with intense demand for AI talent, producing a skills gap that delays project timelines. Airlines counter by partnering with universities and offering rotation programs that pair graduates with flight operations mentors. AI-enabled workforce-planning software assists recruiters, yet the depth of domain knowledge still grows slowly compared with technology ambition, constraining the rapid scaling of complex analytics use cases.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Aviation Analytics Market Segment Analysis
By End User:
Airlines Lead, Airports SurgeThe aviation analytics market size attributed to airlines reached USD 2.03 billion in 2025, equal to 54.32% of global revenue. Full-service carriers invest in integrated revenue-management engines, which boosted operating income at Delta Air Lines by 10% after full cloud migration. Low-cost operators apply dynamic ancillary-pricing algorithms; airBaltic raised passenger spending by 6% through AI-guided offers. Cargo airlines deploy route-optimization tools to mitigate volatility in fuel and charter rates.
Although smaller in absolute terms, airports register a 15.05% CAGR to 2031. Large hubs automate baggage tracing with IDEMIA and SITA’s ALIX solution, lifting match accuracy and reducing mishandled bags. Medium hubs such as Orlando International handle 2,800 bags per hour through computer-vision sorting belts. Regional airports embrace cloud dashboards to visualise queue times and asset utilization, narrowing the technology gap with metropolitan gateways and reinforcing an analytics adoption cycle.


By Application:
Fuel Management Dominates, Safety Analytics AccelerateFuel management contributed 29.55% of the aviation analytics market share in 2025 and is expected to maintain the lead with a 14.08% CAGR, the highest among application groups. Boeing’s Fuel Analytics interrogates 200 standard analyses per leg to detect drag-producing events and recommend optimised speeds. Airlines link these insights with procurement datasets to align hedging strategies, amplifying financial returns. Inventory-management modules reduce surplus spares by up to 30%, freeing working capital for newer digital tools.
Flight-safety analytics benefit from regulatory scrutiny. Teledyne Controls reveals a strong correlation between expanded FDM coverage and declining approach-and-landing incidents. Risk-management analytics embed AI to forecast knock-on delays caused by storms, enabling proactive crewing and gate assignment. Disruption-management platforms from Amadeus shorten recovery windows when events still occur, protecting network integrity and passenger goodwill.
By Analytics Type:
Predictive Dominance, Prescriptive MomentumPredictive solutions held 45.02% of the aviation analytics market size in 2025, buoyed by decades of digital flight-data accumulation and proven return on investment in maintenance. Airbus Skywise synthesises historical and in-flight telemetry, identifying component-failure patterns long before scheduled inspections. Diagnostic analytics remain vital for root-cause investigations, yet newer prescriptive models recommend immediate actions.
Prescriptive adoption is set to grow 13.18% annually as algorithms mature. GE Aerospace’s Network Operations platform evaluates aircraft, crew, and gate variables to offer disruption-recovery scenarios that slash irregular-operation costs by 15%. Airlines integrate prescriptive outputs directly into crew-scheduling and load-planning systems, opening a pathway toward semi-autonomous network control.
By Deployment:
Cloud First, Hybrid ExpandsCloud deployments captured 67.12% of 2025 spending as carriers converted legacy workloads to hyperscale environments capable of processing millions of telemetry points every hour. Delta’s end-to-end shift enabled real-time re-accommodation during weather events, improving customer-satisfaction metrics. Elastic compute power allows airlines to test new optimization models without adding on-premises servers, accelerating innovation cycles.
Security-sensitive functions, such as aircraft-configuration data, continue to reside on premises. Rising cyber-threats—including a major 2024 attack that caused substantial flight cancellations at a US carrier—prompt boards to maintain air-gapped repositories for critical systems. Consequently, hybrid architectures gain traction, pairing local data guardianship with cloud-based advanced analytics. New FAA rules mandate that electronic system security be demonstrated for network-connected avionics, shaping investment decisions.
By Component:
Software Core, Services ScaleSoftware generated 58.12% of 2025 revenue, spanning visual dashboards, AI inferencing engines, and mobile decision-support apps. GE Aerospace, Boeing, and Collins Aerospace provide end-to-end suites that harmonise fuel, maintenance, and safety modules under uniform data models. Open APIs promote ecosystem development as third-party startups add specialist algorithms for weather risk or slot-swap optimization.
Services outpace software growth at 12.05% CAGR. Managed-service agreements help carriers lacking in-house data science talent to extract value from complex platforms. Collins Aerospace offers Ascentia Analytics Services that manage ingestion, validation, and rule-writing tasks on behalf of operators. Training and change-management engagements ensure frontline acceptance, improving project returns and cementing supplier relationships.
By Business Function:
Finance Tops Budgets, Supply Chain Gains UrgencyFinance claimed 32.10% of the 2025 revenue mix as airlines prioritised fare personalization and cost oversight. LATAM Airlines adopted Sabre Air Price IQ to move from filed fares to dynamic offers, improving unit revenue resilience through market swings. Cirium and Aerlytix launched a joint risk-analysis suite for lessors, reflecting heightened scrutiny of asset valuations amid interest-rate volatility.
Supply-chain analytics is rising fastest at a 10.62% CAGR, responding to chronic parts shortages that prolong AOG events. Aviation Week projects global MRO outlays to hit USD 119 billion by 2026, intensifying the need for predictive spare-parts planning. Ramco’s maintenance-platform clients automate 90% of routine purchase orders, reducing mechanic foot-time and freeing scarce labor for complex tasks. Inventory-visibility dashboards integrate supplier delivery forecasts, enabling planners to reroute parts shipments and avoid cascading schedule disruptions.
Geography Analysis
North America Aviation Analytics Market
North America contributed 35.21% of the 2025 global revenue, supported by early passenger-data connectivity and the presence of major aerospace OEMs. United Airlines extended predictive maintenance to its entire narrow-body fleet, improving on-time departures, while Alaska Airlines harnessed AI for route upslope adjustments that save fuel on Seattle departures. FAA guidance on AI and cybersecurity gives carriers regulatory clarity, but rising attack frequency prompts renewed investment in perimeter defenses.
APAC Aviation Analytics Market
Asia-Pacific presents a multifaceted outlook. China and India ramp up analytics around growing domestic networks, whereas Japan and South Korea integrate datasets from aging and next-gen aircraft to secure fleet-wide efficiencies. Thailand’s airport-expansion plan relies on passenger-flow dashboards to keep queue times below regulatory thresholds, underscoring rising demand for real-time situational awareness.
Middle East Aviation Analytics Market
The Middle East records the fastest 11.31% CAGR as fleets double under Vision 2030 initiatives. Seat capacity in the region rose from 70 million in 2000 to 257 million in 2024, with Emirates and Qatar Airways adopting integrated network-planning suites to balance hub-bank waves. Saudi Arabia’s launch of Riyadh Air adds further complexity, making prescriptive crew-pairing tools essential to keep utilization high. Airport operators in Dubai and Doha deploy computer-vision platforms that track passenger density and adjust resource rosters in real time.
LATAM and Africa Aviation Analytics Market
Latin America and Africa show accelerating adoption from low bases. LATAM implements intelligent pricing, while Ethiopian Airlines introduces cloud-based maintenance logs to support regional MRO growth. Currency volatility and uneven connectivity infrastructure temper deployment speed, yet partnerships with global platform providers lower entry barriers and encourage phased rollouts across secondary hubs.

Regulatory Landscape
Aviation analytics regulation is increasingly shaped by safety oversight convergence with cybersecurity expectations for network-connected avionics, alongside requirements to standardize aeronautical data for digital operations. FAA and EASA have maintained structured cooperation through recurring forums such as the International Aviation Safety Conference, hosted in Washington, D.C. in 2024 and Cologne in 2025, aligning approaches around digital modernization, safety intelligence, and cybersecurity topics that feed into how airlines design cloud and hybrid analytics deployments.
Standards and data governance are also tightening the inputs used by analytics platforms. EUROCAE Council approved Working Group WG-136 on 24 June 2026 to create a data-centric Digital Regulations and Certification Framework, with a kick-off scheduled for 21 September 2026 in France. The effort supports a shift away from document-centric certification processes toward data-ready compliance workflows. In parallel, ICAO is driving phased adoption of encoded aeronautical data sets (including terrain, obstacles, aerodrome mapping, AIP, and instrument flight procedures) using formats such as AIXM 5.1/5.1.1, with implementation timelines extending through 2031. This expands the need for data-quality, validation, and traceability capabilities across aviation analytics stacks.
Value Chain Analysis
The aviation analytics value chain begins with multi-source data capture from aircraft and operations, including flight data, fuel and performance parameters, and safety and FDM feeds, and then moves to enterprise systems that manage maintenance, parts, and finance. Airlines, airports, and OEM ecosystems consolidate and normalize these datasets through ingestion, ETL, and integration layers, and they increasingly rely on cloud and hybrid platforms to operationalize models for fuel management, predictive maintenance, safety risk scoring, and network operations.
Solution delivery typically runs across three connected tiers: (i) platform and application providers, including GE Aerospace flight operations and fuel analytics suites, (ii) enterprise software and data backbone vendors, such as SAP for ERP and cloud transformation, and (iii) systems integrators and advisory partners, including IBM, which connect legacy airline IT with modern data fabrics and governance. Upstream digitization in the aerospace supply chain adds another interoperability layer, with Fraunhofer ISSTs Aerospace-X work under Manufacturing-X focused on federated, data-space based exchange models (including concepts such as Gaia-X and Catena-X) to improve cross-tier visibility and resilience. These inputs then feed downstream analytics for inventory risk, MRO planning, and supplier performance management.
Competitive Landscape
Competitive Landscape
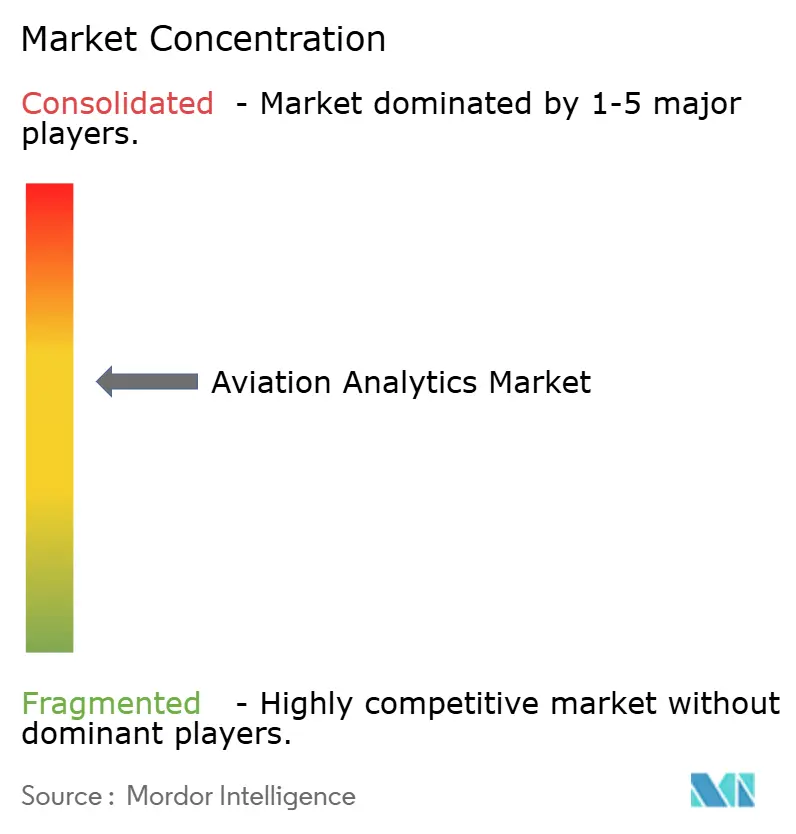
The aviation analytics market features moderate concentration: aerospace incumbents supply vertically integrated platforms, technology majors contribute cloud and AI pipelines, and startups target narrow pain points. Boeing’s agreement to divest Jeppesen, ForeFlight, and AerData to Thoma Bravo for USD 10.55 billion signals portfolio realignment toward core manufacturing and safety analytics niches. Safran’s EUR 220 million (USD 255.1 million) purchase of AI specialist Preligens underscores the premium on autonomous-system competencies.
Competition intensifies in predictive maintenance and fuel optimization, where return on investment is easy to quantify. GE Aerospace leverages engine digital twins, while SITA and Amadeus capitalise on their extensive airline-IT footprints to feed models high-quality operational data. Emerging whitespace includes eVTOL fleet analytics, airport curb-to-gate synchronization, and cross-operation control towers that break legacy silos. Providers that bundle multiple use cases under a unified data fabric gain an edge as airlines look to reduce vendor complexity and support costs.
Supplier power remains balanced because switching requires complex integration and user retraining. However, long-term service contracts and proprietary algorithms can lock clients into specific ecosystems. Successful challengers differentiate through open architectures and outcome-based pricing models that share efficiency gains with customers, aligning incentives and expanding addressable budgets.
Aviation Analytics Industry Leaders
International Business Machines Corporation (IBM)
Honeywell International Inc.
SAP SE
GE Digital (General Electric Company)
Oracle Corporation
- *Disclaimer: Major Players sorted in no particular order
Aviation Analytics Market Companies Covered in this Report
- Airbus SE
- The Boeing Company
- GE Digital (General Electric Company)
- Honeywell International Inc.
- Collins Aerospace (RTX Corporation)
- International Business Machines Corporation (IBM)
- Oracle Corporation
- SAP SE
- SITA
- Amadeus IT Group, S.A.
- Palantir Technologies Inc.
- OAG Aviation Worldwide Limited
- Sabre GLBL Inc.
- IFS World Operations AB
- Swiss-AS
- Ramco Systems Ltd.
- OpenAirlines
- Skymetrix
- Osprey Flight Solutions (Sora Risk Solutions Limited)
- L3Harris Technologies, Inc.
- Luxoft Holding, Inc.
- Cloud Software Group, Inc. (TIBCO)
- PROS, Inc.

Market Opportunities and Future Outlook
One clear opportunity is the modernization of airline and airport decision systems through consolidated, cloud-based enterprise data foundations that connect operations, maintenance, and commercial functions. Current market activity shows airlines shifting from siloed tooling to platform-centric programs. This includes RISE with SAP adoption for enterprise transformation (for example, Garuda Indonesia), as well as large-scale integration programs where SAP and IBM support airline ERP modernization. That broadens the addressable analytics scope across finance, supply chain, and MRO workflows, rather than limiting value to single-use-case deployments.
A second whitespace is analytics tied to data standardization and digital compliance. Standards bodies and regulators are pushing structured, machine-readable inputs, and this creates demand for validation, lineage, and continuous monitoring tools between source data producers and operational analytics users. EUROCAE WG-136 (approved 24 June 2026) is formalizing a digital regulations and certification framework, while ICAO-driven aeronautical data encoding programs using AIXM 5.1/5.1.1 with timelines running through 2031 extend the compliance and data-quality workload through 2031. On the application side, ongoing deployments of fuel and flight-operations analytics (for example, GE Aerospace platforms used by Air France KLM Group, SAS, and SAUDIA) point to an expansion path beyond fuel-only modules into integrated safety, disruption, and maintenance analytics, provided the underlying unified data layer and governance model are in place.
Recent Industry Developments in Aviation Analytics Market
- July 2026: IndiGo (IndiGo Airlines) Selected Honeywell Aerospace flagship avionics and power systems for 810 new Airbus A320neo family aircraft. The move defines the fleet upgrade and expands avionics supply dynamics, strengthening Honeywell's data-enabled safety and fuel-management ecosystem across a large operator; expands data sources for analytics platforms.
- July 2026: Honeywell Aerospace Announced a memorandum of understanding with Enigma Aerospace to integrate mission systems, navigation, and EW capabilities onto Enigma Phoenix UAS. The collaboration expands defense and aviation analytics capabilities for UAS and interoperability across platforms.
- June 2026: Odysight AI (Honeywell APU division collaboration) received a purchase order from Honeywell Aerospace APU division to launch proof-of-concept of Odysight AI’s predictive maintenance vision-based system on Honeywell APUs. The PoC demonstrates a direct predictive maintenance application within aviation analytics and could scale across Honeywell’s turbomachinery fleet if successful.


Aviation Analytics Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market covers software and services that turn aviation data into decision support for airlines, airports, air navigation stakeholders, and MRO users, across operational, commercial, and safety use cases.
Scope exclusions: Pure connectivity hardware, general IT outsourcing without an analytics layer, and unrelated enterprise BI tools are excluded unless they are sold and used for aviation specific analytics outcomes.
Segments Covered in This Report
- By End User
- Airlines
- Full-Service Carriers
- Low-Cost Carriers
- Cargo and Charter Operators
- Airports
- Large Hub Airports
- Medium Hub Airports
- Small and Regional Airports
- Airlines
- By Application
- Risk Management
- Inventory Management
- Fuel Management
- Revenue Management
- Customer Analytics
- Flight Safety Analytics
- Crew Management
- Disruption Management
- By Analytics Type
- Descriptive Analytics
- Diagnostic Analytics
- Predictive Analytics
- Prescriptive Analytics
- By Deployment
- On-Premises
- Cloud
- By Component
- Software
- Services
- Managed Services
- Professional Services
- By Business Function
- Sales and Marketing
- Finance
- MRO Operations
- Supply Chain
- Flight Operations
- Network Planning and Scheduling
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts with building a fact base on air traffic, fleet activity, and operating intensity, because those drivers shape how much analytics gets used and paid for. We refer to public sources such as ICAO air transport statistics, IATA releases, FAA and EASA safety publications, and World Bank or OECD macro indicators to understand demand direction and any structural breaks.
It is then supported with company filings, annual reports, investor decks, and product documentation to map typical pricing models (subscription, usage based, and services) and adoption barriers. In parallel, patent databases are reviewed to see where analytics capabilities are evolving, and a paid subscription for company financials and news is used to cross check revenue disclosures and deal activity when available. This list is not exhaustive, and many other public and paid sources were also used to collect data, validate assumptions, and clarify open questions.
Primary Interviews and Surveys
Primary work focuses on reality checks that desk sources cannot fully answer, such as how analytics budgets are approved, what functions buy first, and what drives renewals after pilots. We interview and survey airline and airport operations teams, maintenance planners, digital leaders, and solution partners across major regions so assumptions on penetration and pricing can be tuned to actual buying behavior.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 39% | CXOs: 14% | APAC: 49% |
| Mid tier: 43% | Functional/Unit leaders: 32% | EMEA: 33% |
| Smaller Players: 18% | Managers: 54% | Americas: 18% |
Market-Sizing & Forecasting
Sizing is built using a top-down demand pool that starts from aviation activity and digital spend signals, and then translates that into analytics attach rates by user group. Once that ceiling is formed, we corroborate it with selective bottom-up checks, such as sampling typical annual contract values, validating implementation and support shares, and sense checking the count of active deployments discussed in interviews.
Key inputs used in the model include commercial flight activity and capacity trends, fleet size and utilization patterns, MRO event intensity (such as checks and unscheduled removals), and the mix shift toward connected aircraft data streams that enable near real time analytics. Adoption is further shaped by cloud migration pace, data governance constraints, and regulatory reporting needs that pull analytics into safety and compliance workflows. Where direct bottom-up detail is missing, gaps are handled through conservative ranges that are narrowed using interview feedback and observed pricing bands.
Forecasts are developed using scenario analysis, where base, conservative, and high adoption cases are linked to traffic recovery paths, fuel and cost pressure, and ongoing digital modernization programs. Final forward curves are reviewed with experts so the expected ramp in penetration and average contract values stays in line with what buyers say they can implement and sustain.
Data Validation & Update Cycle
Outputs are triangulated against independent signals such as aviation IT spending commentary, reported digital transformation programs, and changes in operational KPIs that analytics is meant to improve. Variance checks are run across regions and user types, and any outliers trigger a relook at assumptions. If the gap cannot be explained, selected respondents are re-contacted to confirm the underlying driver.
Before sign-off, the model and logic go through multi step analyst reviews, including unit consistency checks, currency conversion timing checks, and stress tests on key levers like penetration and pricing. Reports are refreshed annually, and interim updates are made when material events occur, after which a final pre-delivery pass is done so the latest data is reflected.
Mordor Intelligence's Aviation Analytics Market Sizing Compared With Other Published Estimates
Published market values often differ because each publisher chooses its own boundary for what counts as analytics, the year used as the reference point, and the way pricing and adoption are projected into the forecast window. We lay out the differences so readers can align the number they use with the business decision they are making.
Traffic and fleet activity signals, along with interview checks on analytics budget allocation and renewal behavior, are the evidence used to keep Mordor Intelligence's 2026 market size anchored to what aviation operators can realistically deploy and pay for in that year. The biggest gaps usually come from whether adjacent categories like broader aviation software suites are included, whether implementation services are counted in full, and whether older base years are carried forward without resetting for cloud subscription pricing and currency timing.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 4.2 B (2026) | |
| Industry Publication A | USD 3.44 B (2024) | Uses an earlier base year, and the published summary does not clarify if services and integration revenues are fully counted, which can understate the modeled addressable spend. |
| Press Release B | USD 2.90 B (2025) | The estimate appears to apply a narrower scope tied to specific analytics functions, and it does not describe how adoption rates and subscription price progression were refreshed for the forecast period. |
The spread in the table is mainly explained by base year choice and what is bundled into the scope, especially services and broader software that can be labeled as analytics. By tying the model to observable activity indicators and then rechecking pricing and penetration with practitioners, the final value remains traceable to clear inputs and repeatable steps.


Key Questions Answered in the Report
What is the current size of the aviation analytics market?
The aviation analytics market stands at USD 4.2 billion in 2026 and is set to reach USD 7.47 billion by 2031, reflecting a 12.21% CAGR.
Which application area generates the most revenue?
Fuel-management analytics leads, holding 29.55% of 2025 revenue and expanding at a 14.08% CAGR as airlines chase fuel and SAF efficiency gains.
Why are airlines migrating analytics to the cloud?
Cloud platforms offer elastic compute power and real-time data-processing capabilities that support AI-driven decision systems while reducing on-premises infrastructure costs.
Which region is growing the fastest?
The Middle East posts the highest CAGR at 11.31% due to large-scale fleet expansion plans, airport capacity investments, and national aviation-sector strategies.
What restraints could slow market growth?
Legacy IT silos hinder data integration, and a shortage of aviation-savvy data scientists limits the speed at which complex analytics projects scale globally.
How concentrated is the supplier landscape?
With the top five vendors controlling about half of global revenue, the market shows moderate concentration, leaving opportunities for specialized startups.
Page last updated on:


 Your data is secure and never sold or shared.



