
Australia Skin Care Products Market Analysis by Mordor Intelligence
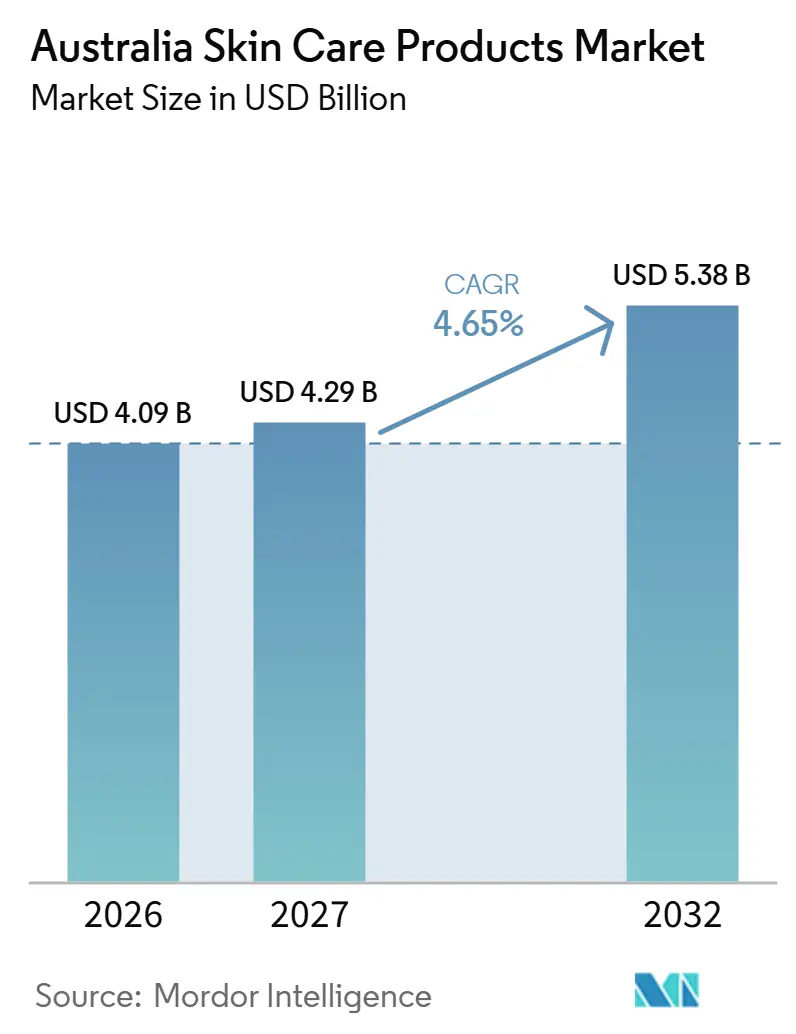
The Australia skin care products market size is expected to grow from USD 4.09 billion in 2026 to USD 4.29 billion in 2027 and is forecast to reach USD 5.38 billion by 2032 at 4.65% CAGR over 2027-2032.
Natural and organic preference, social-media influence, formulation improvements and anti-aging needs support demand for skincare creams in Australia. Counterfeit availability and ingredient-safety concerns constrain that opportunity by making authenticity and product trust part of the purchase decision. The Iran war and crude-oil supply disruption beginning in February 2026 put ingredient-cost pressure on Australian cosmetics supply, including skincare. Multinational brand owners and specialist suppliers can respond across physical and online retail routes by pairing credible product benefits with pricing and range decisions that reflect higher petroleum-derived ingredient costs.
Key Report Takeaways
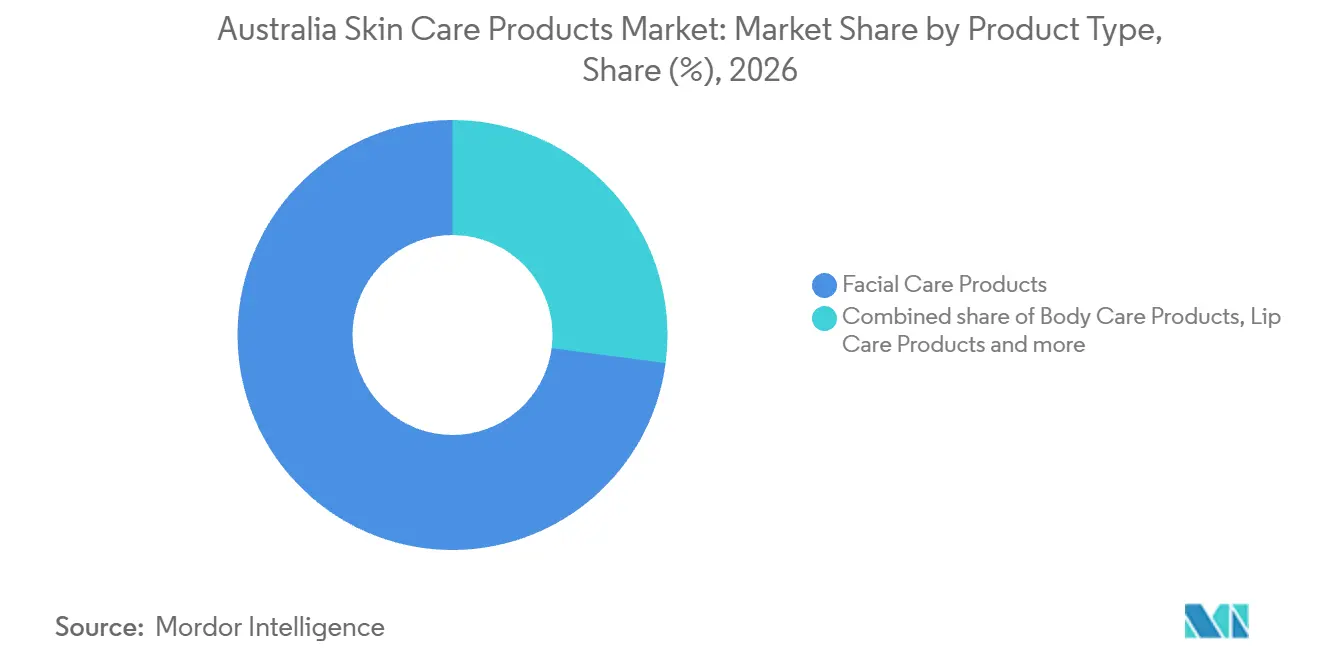
- By product type, facial care products led with a 72.91% Australia skin care products market share in 2026, while body care products are forecast to grow fastest at a 5.1% CAGR over 2027-2032.
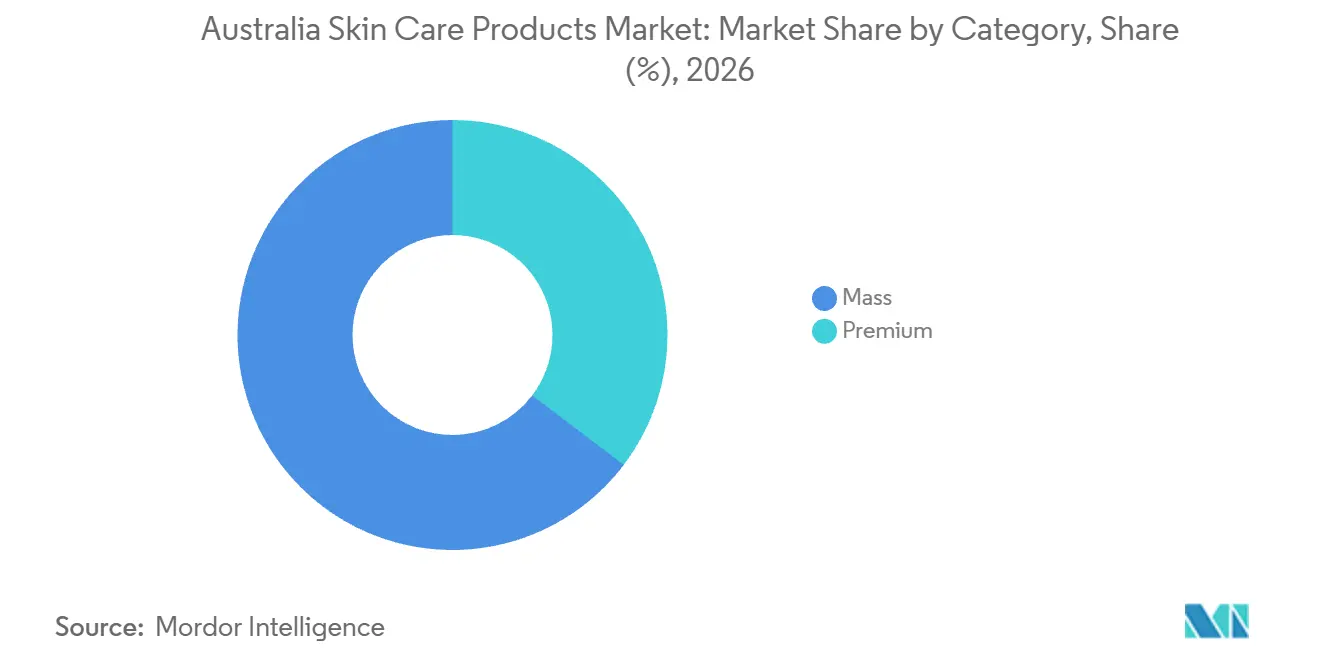
- Within the category breakdown, mass skincare held a 64.68% share of the Australia skin care products market size in 2026, while premium skincare is forecast to grow fastest at a 6.3% CAGR over 2027-2032.
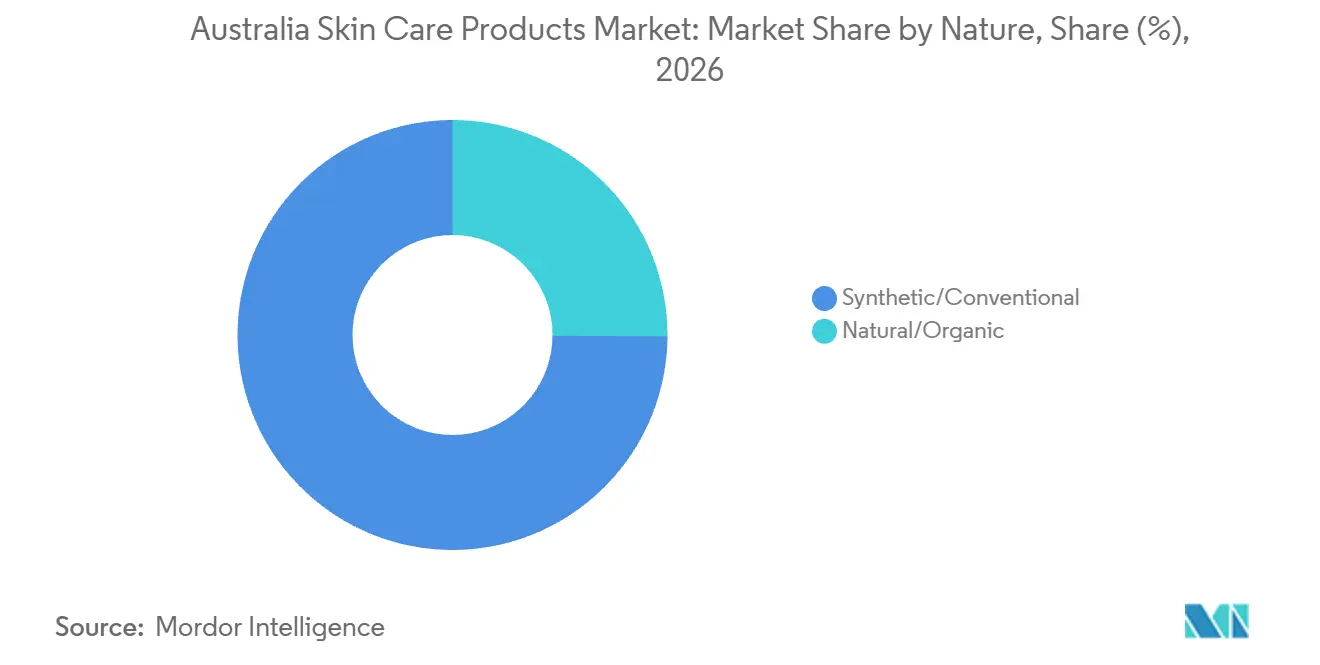
- The nature breakdown was led by synthetic/conventional products with 74.89% of market value in 2026, whereas natural/organic products are forecast to grow fastest at a 6.45% CAGR over 2027-2032.
- Among end users, adults accounted for 87.09% of market value in 2026, and kids are forecast to grow fastest at a 4.75% CAGR over 2027-2032.
- Across distribution channels, health and beauty stores held 38.27% of market value in 2026, while online retail channels are forecast to grow fastest at a 5.8% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Australia Skin Care Products Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Consumer preference for organic and natural products | +1.4% | Nationwide | Medium term (2-4 years) |
| Impact of social media and celebrity endorsements | +1.3% | Nationwide | Short term (≤ 2 years) |
| Advancements in technology driving product formulation improvements | +1.2% | Nationwide | Long term (≥ 4 years) |
| Growing consumer demand for anti-aging products | +1% | Nationwide | Medium term (2-4 years) |
| Rising preference for multifunctional facial care products | +0.7% | Nationwide | Medium term (2-4 years) |
| Increasing awareness about skin health concerns | +0.6% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Consumer preference for organic and natural products
For an Australian buyer seeking naturally derived ingredients, a cleanser or moisturizer also needs to meet the intended skin-care need. A formulation matching that ingredient preference can remove an objection that a functional claim alone would leave unanswered. This gives natural positioning a route into product consideration while keeping cleansing or moisturizing as the reason for use. The supplier’s proposition therefore needs both a recognizable application and an ingredient profile relevant to the intended buyer. Ingredient-led positioning can widen demand when buyers see which skin need the product serves, making a clear cleansing or moisturizing claim more useful than a longer ingredient list.
Impact of social media and celebrity endorsements
An endorsement is most useful to an Australian skincare supplier when it connects attention to a specific product use. For a facial serum, a message explaining where the product fits within a routine gives an interested shopper a reason to consider it. Visibility alone leaves that link between a recognizable name and the intended application unresolved. Suppliers can design social-media communication around the use being recommended, distinguishing product explanation from celebrity recognition. The resulting demand opportunity is to turn initial consideration into a trial of a clearly positioned serum, without assuming that attention itself establishes repeat purchasing.
Advancements in technology driving product formulation improvements
For an Australian moisturizer buyer, formulation innovation can increase product value by changing the benefit obtained from the same daily application. The relevant comparison is the benefit obtained from an existing product addressing the same skin concern. A supplier’s formulation work therefore needs a demonstrable performance or usability improvement to give that buyer a reason to switch. If an improved formula fits into the same application step, adopting it need not add another product to the routine. Growth through reformulation would then come from replacing an established purchase with a higher-value offer within a familiar regimen.
Growing consumer demand for anti-aging products
Anti-aging demand can be addressed through a range that connects aging-related concerns with everyday skin maintenance. AHC returned to Australia in May 2025 with skincare products targeting skin aging, hydration, firmness and brightening, available in Priceline stores and online. That combination creates an offer relevant to several reasons a buyer might consider adding a product to a routine. For a pharmacy retailer, the range can compete for shoppers evaluating an aging-related concern alongside a regular skincare need. Suppliers can broaden the relevance of an anti-aging proposition by explaining that specific role, giving the buyer a reason to consider it without adopting an entirely separate regimen.
Restraints Impact Analysis of Australia Skin Care Products Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Increase in the availability of counterfeit products | -0.6% | Nationwide | Short term (≤ 2 years) |
| Concerns regarding the health impacts of chemical ingredients | -0.5% | Nationwide | Short term (≤ 2 years) |
| Growing preference for at-home skin treatment solutions | -0.2% | Nationwide | Medium term (2-4 years) |
| Volatile raw material costs | -0.25% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Increase in the availability of counterfeit products
Counterfeit products make an apparently identical skincare offer harder to evaluate because the buyer may be unable to verify its contents. Revision Skincare Australia’s distributor warns that counterfeit Revision products have appeared on unauthorized retailer websites and are considered unsafe. It also says genuine and counterfeit products can be almost impossible to distinguish. For a shopper considering that brand, appearance alone therefore cannot resolve whether the purchase delivers the intended product. The resulting uncertainty can interrupt a sale even when the advertised product name matches what the shopper wants. The remaining cost is potential lost conversion on any listing whose authenticity the shopper cannot confirm.
Concerns regarding the health impacts of chemical ingredients
Ingredient-health concerns can create a distribution barrier before a specific cause of a reported reaction has been established. Kmart withdrew its hyaluronic acid cleansing balm from store shelves in March 2025 while investigating the product’s ingredients after reports of adverse reactions.[1] For the retailer and brand, the immediate effect was the interruption of that product’s store availability. During the reported investigation, a shopper seeking the balm could not obtain it from Kmart’s shelves. The residual exposure differs from weak demand, because access to the retail channel can be interrupted even when a shopper wants to buy the product.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Australia Skin Care Products Market Segment Analysis
By Product Type:
Facial Routines Anchor Demand While Body Care ExpandsFacial care products accounted for a 72.91% share of the Australia skin care products market size in 2026. In July 2025, AESTURA announced an exclusive Sephora Australia launch for its ATOBARRIER365 skincare collection, including facial-care products, scheduled to begin nationwide on August 26, 2025. A brand can build a coherent offer around a daily facial-care collection without requiring every buyer to adopt every product in the range. Competition is therefore for a place in the buyer’s recurring facial-care routine rather than for the broadest possible assortment. A focused cleanser-and-moisturizer proposition can give a supplier a clearer role within this large segment than several products with overlapping purposes.
Body care products are forecast to be the fastest-growing segment, with a 5.1% CAGR over 2027-2032. Australian brand Bronte launched body wash and body lotion in 2 scents in February 2025, and the launched products sold out within 72 hours. The initial sell-out provides a specific example of buyers taking up a new body-care offer. Supply expansion can be tied to subsequent reorder demand, so that an initial sell-out does not become the sole basis for committing to a wider body-care range or a larger production run.

By Category:
Mass Reach Coexists With Selective Premium DistributionMass skincare represented a 64.68% Australia skin care products market share in 2026. In September 2025, Skin Control was available nationally through Woolworths, Coles, Chemist Warehouse, Priceline and BIG W, among other retailers. That distribution example shows how one mass skincare proposition can reach buyers across grocery, pharmacy and discount retail formats. For a mass supplier, such breadth can make the same product offer accessible through several retail settings instead of depending on a specialist destination. Mass suppliers consequently need a product identity that travels across grocery, pharmacy and discount formats, since a specialist-only message would leave part of that distribution reach underused.
Premium skincare is forecast to be the fastest-growing segment, with a 6.3% CAGR over 2027-2032. In March 2026, Myer announced plans to add La Mer, Swiss Perfection and Guerlain skincare, with Swiss Perfection making its Australian debut exclusively at Myer. A selective retail relationship can give a premium brand a defined launch setting and give the retailer a proposition that distinguishes its assortment. For a premium skincare supplier, an appropriate department-store partner can therefore support a distinct product identity before the brand commits to seeking a broader distribution footprint across Australia.
By Nature:
Conventional Formulations Retain Scale As Sukin Joins a Larger PortfolioSynthetic/conventional products were the largest segment, accounting for 74.89% of market value in 2026. Amorepacific reported in August 2026 that its AESTURA brand had expanded its sales channels in Australia, Canada, China and major European markets. AESTURA’s international ATOBARRIER365 Cream ingredient list includes dimethicone, which COSMILE Europe classifies as synthetic. Distribution gives a finished skincare product access to buyers, while an ingredient classification alone does not distinguish its use within a routine. A supplier in this large segment therefore needs a defined finished-product proposition alongside channel access, rather than treating synthetic origin as sufficient differentiation.
Natural/organic products are forecast to be the fastest-growing segment, with a 6.45% CAGR over 2027-2032. Lion Corporation acquired all shares of PNB Consolidated Pty Ltd on January 20, 2026, bringing the Australian manufacturer and seller behind Sukin natural beauty care into the group. Sukin’s core offerings include skincare alongside broader beauty-care products such as hair care and body care. Ownership of Sukin gives Lion a natural skincare platform within a broader beauty-care business, providing a route for portfolio expansion without creating a new brand.
By End User:
Adult Maintenance Provides Scale While Protective Use Supports KidsAdults were the largest segment, accounting for 87.09% of market value in 2026. The Eczema Association of Australasia’s 2025 guide recommends moisturizers twice daily for people with eczema, including when it is controlled, and gives adults a recommended amount of 500 g per week. The advice makes controlled eczema part of the recommended moisturizer regimen, giving suppliers a maintenance application beyond products positioned only for an active episode. That maintenance role can support an adult offer centered on continuity of care, with replenishment linked to the recommended regimen rather than to a new cosmetic concern.
Kids are forecast to be the fastest-growing segment, with a 4.75% CAGR over 2027-2032. For outdoor periods longer than 15 minutes between 10 a.m. and 2 p.m. during the 2024-2025 summer, 59% of Australian teens aged 12 to 17 reported using sunscreen often or always. For suppliers serving teens, that reported frequency identifies sunscreen as a routine-use proposition within the broader Kids segment. Communication for this audience can link the product to the outdoor circumstances in which teens reported using it, giving a teen sunscreen range a defined protective purpose.
By Distribution Channel:
Specialist Reach Complements Digital ReplenishmentHealth and beauty stores were the largest segment, with 38.27% of market value in 2026. Wesfarmers Health’s 2026 report identified 57 non-pharmacy Priceline stores and 10 atomica stores alongside its franchise pharmacy network. Its Sister Club health and beauty loyalty program had 10.4 million members before its August 2026 relaunch as Pulse Rewards. Together, a physical network and a shared loyalty relationship give a retailer several ways to keep a skincare range visible to an existing customer base. A supplier listed across both the pharmacy network and the loyalty program can reach customers on repeat visits across locations, rather than depending on their return to a single store.
Online retail channels are forecast to be the fastest-growing segment, with a 5.8% CAGR over 2027-2032. Australia Post reported that Australian online beauty spending increased 15.7% in 2025 compared with 2024. For skincare suppliers, digital distribution can add customer reach without requiring an additional physical location for each catchment. This makes the channel useful for a defined repeat-purchase range whose product identity is already established. Online order data can then show where repeat demand concentrates, which gives a supplier evidence for choosing the next store location.
Geography Analysis
Metropolitan skincare distribution is developing through destination stores that combine skincare with a broader beauty offer. MECCA opened its Bourke Street flagship to the public in Melbourne on August 8, 2025. Tokyo Lifestyle opened a Sydney flagship in late 2025, operated by Tokyo Lifestyle Pty Ltd and offering skincare alongside other beauty products. These openings provide suppliers with additional physical routes to shoppers through locally operated retail venues. In destinations such as MECCA’s Bourke Street flagship, a skincare supplier’s opportunity depends on the range’s role beside other beauty categories, making the retailer’s assortment fit central to a listing decision.
Western Australia’s physical distribution options expanded when Adore Beauty opened stores at Carousel and Booragoon for beauty and skincare buyers during 2025. Adore Beauty Group reported that its first Queensland stores opened during the first half of fiscal 2026 in major shopping centers. Those additions make physical access part of the distribution decision for skincare suppliers working with the group, alongside its online business. A supplier can position a range for in-store discovery and subsequent online orders, allowing the physical offer to complement digital distribution rather than treating the channels as separate routes to the same shopper.
Darwin, Hobart and regional towns require a more localized view of skincare access. W Cosmetics opened at Casuarina Square in Darwin on November 11, 2025, carrying Korean, Japanese and other international skincare and makeup brands.[2] MECCA reopened its Hobart cosmetics store after renovations in September 2026, with Emma Lewisham among the brands featured in express services. Australia Post reported that capital-city areas accounted for 76% of Australian online beauty spending in 2025. A Darwin or Hobart store partnership addresses a city catchment, while serving regional towns online is a separate channel decision targeting a smaller aggregate online beauty-spending base.
Regulatory Framework and Outlook
Selected jurisdictions are compared from the perspective of skincare suppliers introducing cosmetic ingredients and developing sun-protection products. The national Industrial Chemicals Act requires introducers to register before introducing industrial chemicals, with each introduction authorized under a statutory category. New South Wales adds a state mechanism through its Poisons List, which adopts the 10 schedules of the national Poisons Standard. For suppliers, these frameworks separate the chemical-introduction decision from the additional review needed when a proposed formulation involves a scheduled ingredient.
Regulatory Table of Australia Skin Care Products Market
| Decision factor | Australia | New South Wales |
|---|---|---|
| Primary authority | Executive Director, Australian Industrial Chemicals Introduction Scheme; Therapeutic Goods Administration | NSW Health |
| Key instruments or direction | Industrial Chemicals Act 2019; proposed sunscreen regulatory options consulted on in 2026 | Poisons and Therapeutic Goods Act 1966 and Poisons List; replacement framework scheduled for November 5, 2026 |
| Commercial effect | Registration and statutory authorization route for chemical introduction; sunscreen proposals subject to future decisions | Schedule adoption adds ingredient-classification review to formulation decisions |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
National attractiveness is Medium because several statutory introduction categories offer routes to market while retaining registration and authorization duties. The TGA’s sunscreen consultation closed on May 23, 2026, with options remaining subject to future decisions. NSW also receives Medium because its defined scheduling structure supports ingredient review, and the replacement scheduled for November 5, 2026, adopts all Poisons Standard schedules and selected appendices. Retained introduction routes and continued state schedule adoption support No change for these mechanisms, alongside the conditional national sunscreen proposals.
Value Chain Stages
The comparison follows product development, manufacturing and retail distribution, showing where suppliers earn and where a brand must coordinate different capabilities. Ensign Laboratories provides contract development and manufacturing for personal care products from Mulgrave, Victoria. Its broader personal-care operation illustrates a route through which a client brand can obtain formulation and production support without owning every upstream function. Separating development income, product supply and retail sales makes clear why additional manufacturing capability alone does not secure the final customer transaction.
Value Chain Analysis Table of Australia Skin Care Products Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Formulation development | Contract developers such as Ensign Laboratories | Development fees | Translating a brand specification into a producible formulation | Validate the formulation before committing to production scale |
| Manufacturing and filling | Skincare manufacturers such as Ego Pharmaceuticals | Finished-product supply sales | Matching capacity commitments to repeat orders | Stage production expansion against confirmed demand |
| Retail distribution | Pharmacy retailers such as Priceline Pharmacy, managed by Wesfarmers Health with pharmacist franchise operators | Retail product sales | Coordinating a brand offer across independently operated outlets | Support franchise operators with consistent product information |
| Source: Mordor Intelligence | ||||
Ego Pharmaceuticals opened manufacturing facilities in Braeside and Dandenong South in 2025, with developments enabling it to double annual production capacity from over 33 million units in 2024.[3] Capacity expansion of this kind needs repeat orders to sustain utilization, linking manufacturing commitments to distribution agreements. Priceline Pharmacy’s franchise structure places outlet operation with pharmacist partners, so retail execution requires coordination beyond a central brand agreement. For a skincare brand using a contract laboratory, a pharmacy distribution agreement can provide a concrete trigger for scaling production beyond the initial formulation.
Competitive Landscape
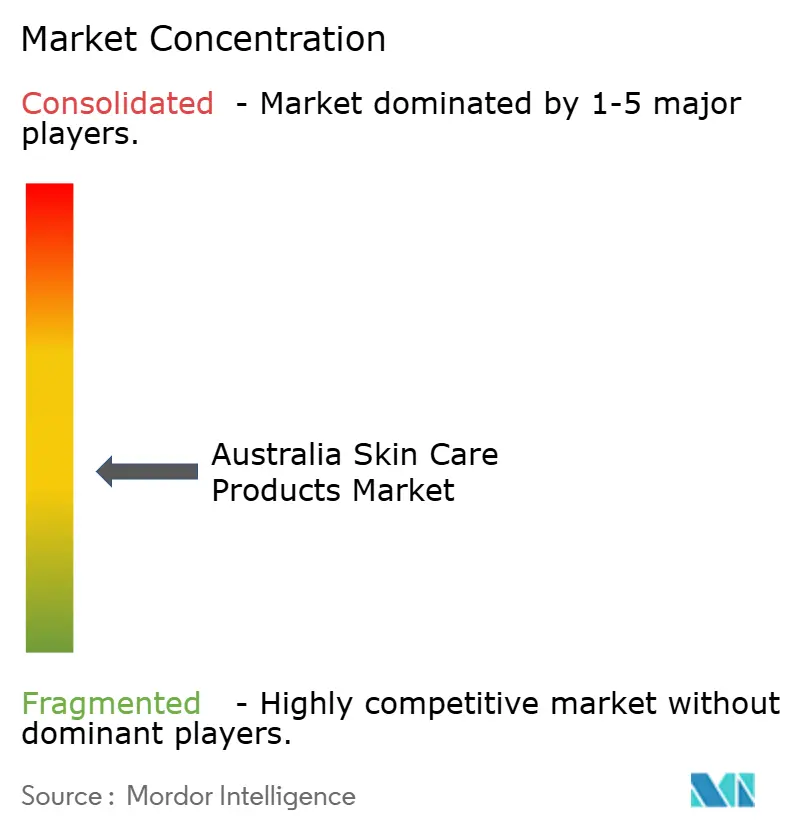
The industry is moderately fragmented, with several multinational brand owners competing alongside specialist skincare suppliers across different product propositions and retail routes in Australia. The leading participants include Unilever PLC, Beiersdorf AG, L’Oréal SA, Estée Lauder Companies Inc. and Procter & Gamble Company. Unilever, whose skincare brands include Vaseline, Dove and Pond’s, reported mid-single-digit growth in its global Core Skin Care business in 2025, with positive contributions from both volume and price. With both volume and price contributing to that global growth, a challenger competing on shelf price alone would address only one source of the portfolio’s momentum.
Portfolio strategies can support skincare growth through several brands, giving a large parent more than one proposition to sustain within retail relationships. Estée Lauder Companies Inc. reported 4% organic growth in global Skin Care net sales in the fiscal year ended June 30, 2026, primarily driven by La Mer, The Ordinary and Estée Lauder. That contribution from several named brands gives the parent multiple offers through which to compete, rather than tying the category entirely to one label. Displacing one label would leave a challenger competing with the parent’s other growth-contributing skincare brands, so a single listing win need not weaken the wider portfolio.
Beiersdorf’s global skin care business grew organically by 3.7% in 2025, when the company reported performing ahead of a slowing market. Its performance gives challengers a benchmark based on sales growth through weaker category conditions. With registration a shared obligation for chemical introducers, challengers must distinguish their offer on grounds beyond that compliance step. For retail buyers, category slowdown alone is a weak reason to replace an established skincare supplier demonstrating organic growth against that backdrop.
Australia Skin Care Products Industry Leaders
-
Unilever PLC
-
Beiersdorf AG
-
L’Oréal SA
-
Estée Lauder Companies Inc.
-
Procter & Gamble Company
- *Disclaimer: Major Players sorted in no particular order
Australia Skin Care Products Market Companies Covered in this Report
- L’Oréal SA
- KORA Organics
- Procter & Gamble Company
- Unilever PLC
- Estée Lauder Companies Inc.
- Kenvue Inc.
- Beiersdorf AG
- Shiseido Company Limited
- L’Occitane Group
- Clarins Group
- The Clorox Company
- Kao Corporation
- Pola Orbis Holdings Inc (Jurlique)
- NuCare Australia Pty Ltd
- Botani Skincare
- Sasy n Savy
- PNB Consolidated Pty Ltd (Sukin)
- AUS Cosmetics
- MooGoo AU
- Galderma S.A.
Key Opportunities for Market Participants
Skincare opportunities are compared by buyer need, distribution model and the barrier to repeat purchasing. The useful commercial distinction is between securing an initial mass-retail placement and making subsequent orders convenient. Product scope and delivery commitments need to be chosen together, since rapid replenishment only helps when the retail offer contains a product the buyer wants to purchase again.
Market Opportunities Table of Australia Skin Care Products Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Rapid replenishment of routine skincare | Next-day or same-day delivery served 29% of Australian beauty purchases in 2025 | Existing online skincare purchasers | Offer a focused replenishment range within feasible delivery areas | Economics of rapid delivery on small orders | Skincare retailers with local fulfillment capacity |
| Accessible acne-care assortments | BIG W added more Skin Control acne and skin solutions in October 2025 | Mass-retail skincare buyers | Develop a differentiated acne-care entry range for comparable retail channels | Securing assortment space against established offers | Acne-care suppliers such as Skin Control |
| Online follow-on orders after store trial | Retail assortment expansion and established rapid-delivery use | Skincare buyers replenishing a product first tried in store | Make the same clearly identified product available for remote repeat orders | Coordinating the offer across retail partners | Skincare brands combining physical and online distribution |
| Source: Mordor Intelligence | |||||
The central opening is an accessible acne-care offer that connects initial retail discovery with convenient replenishment. An entry range can serve the first task, while a focused online offer can serve customers who already know which product they want. For an acne-care supplier, linking those tasks offers a more specific growth play than expanding either the assortment or the delivery promise without a clear path to another purchase.
Recent Industry Developments in Australia Skin Care Products Market
- Sep 2026: MECCA reopened its Hobart cosmetics store after renovations, with skincare brand Emma Lewisham among the brands featured in express services.
- Mar 2026: Ego Pharmaceuticals relaunched Elucent, with its Age Defying and Bright + Balanced skincare ranges available exclusively through Chemist Warehouse Australia-wide from mid-March.
- Jan 2026: Lion Corporation acquired all shares of PNB Consolidated Pty Ltd, the Australian beauty-care business behind Sukin, on January 20.
Australia Skin Care Products Market Report Scope and Research Methodology
Market Definition and Coverage
The Australia skin care products market measures annual retail sales value of products sold in Australia for facial, body, and lip skin care. Sales are classified by price tier, product nature, end user, and distribution channel.
Scope exclusions: Color cosmetics, fragrances, hair care, and professional in-clinic skin treatment services are excluded.
Segments Covered in This Report
- By Product Type
- Facial Care Products
- Cleansers
- Moisturizers and creams
- Serums and Essence
- Toners
- Face Masks
- Other Facial Care Products
- Body Care Products
- Body Lotion
- Foot and Hand Cream
- Other Body Care Products
- Lip Care Products
- Facial Care Products
- By Category
- Mass
- Premium
- By Nature
- Natural/Organic
- Synthetic/Conventional
- By End User
- Kids
- Adults
- By Distribution Channel
- Supermarkets/Hypermarkets
- Health and Beauty Stores
- Online Retail Channels
- Other Channels
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the Australian Bureau of Statistics' Monthly Household Spending Indicator, its Retail Trade series through June 2025, its population estimates, and Australia Post's eCommerce Report 2026 provide household spending, historical retail turnover, population, and online beauty context. ABS industry and price statistics help distinguish nominal sales movements from changes in the number of products sold.
Company annual reports, investor presentations, retailer disclosures, product information, and reputable Australian business and consumer press can clarify brand activity, channel reach, and price positioning. Customs and regulatory material can help interpret product classification and ingredient rules where relevant, and these named sources are illustrative rather than exhaustive, as further sources inform collection, validation and clarification.
Primary Interviews and Surveys
A structured interview and survey program would seek input from Australian skincare brand owners and manufacturers, retailers, distributors, and category specialists, with executives and functional leaders explaining sales, assortment, pricing, and channel conditions. Analysts would use responses to check secondary-source interpretations and segment assumptions, document unresolved gaps, and triangulate conflicting evidence against company disclosures and retail indicators.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | |
| Mid tier: 43% | Functional/Unit leaders: 35% | |
| Smaller Players: 22% | Managers: 45% |
Market-Sizing & Forecasting
The model estimates Australia's annual retail sales value from a top down demand base, then checks selected totals against sampled channel and supplier evidence, including sampled average selling price multiplied by unit volume where both inputs are available. Population and household spending indicate the size and direction of the buyer pool. Historical retail turnover through June 2025 and online beauty spending provide channel context. Product price movements and tier mix inform realized sales value. Product, nature, end user, and channel evidence helps distribute the total into the report's segment shares.
A multivariate regression can relate historical market value to population, spending, price, and channel indicators, with scenario analysis used when a major change in retail access, regulation, or consumer spending makes historical relationships less representative. Segment shares are built from disclosed category sales, reported assortment and channel evidence, and relevant consumer and product indicators, then checked for consistency with the market total. Analysts compare forecast drivers and selected bottom up checks with Australian experts' explanations, investigate material gaps, and record where a proxy or conservative assumption is needed when direct market data are unavailable.
Data Validation & Update Cycle
Analysts triangulate company disclosures, official spending and population series, channel indicators, and selected sampled supplier or retailer checks, then investigate outliers and material variances against historical movement and related categories. A second review checks source dates, units, segment totals, and assumptions, with recontact triggered by unresolved contradictions or a material change in prices, product availability, regulation, or retail access. The dataset is refreshed annually, reviewed between cycles when a material event changes market conditions, and given a fresh source and calculation review before delivery.
Mordor Intelligence's Australia Skincare Product Market Estimate Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Australia skin care products market measures annual retail sales value of products sold in Australia for facial, body, and lip skin care.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. A multivariate regression can relate historical market value to population, spending, price, and channel indicators, with scenario analysis used when a major change in retail access, regulation, or consumer spending makes historical relationships less representative.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 4.29 B (2027) | |
| Global Consultancy A | USD 2.56 B (2025) | At its 2025 base, this estimate is 40.3% below this report's 2027 value of USD 4.29 B, 2 years later. The earlier base year places this estimate before the 2027 measurement year, and its stated growth forecast points upward over the intervening period. Its product coverage also includes hand and foot care. |
| Regional Consultancy B | USD 4.05 B (2025) | At its 2025 base, this estimate is 5.6% below this report's 2027 value of USD 4.29 B, 2 years later. The earlier base year precedes the 2027 measurement year, and its stated forecast growth points upward over the intervening period. The publisher also lists sun care, hand and foot care, and clinic and travel retail in its wider coverage. |
Mordor Intelligence's analysts triangulate company disclosures, official spending and population series, channel indicators, and selected sampled supplier or retailer checks, then investigate outliers and material variances against historical movement and related categories.
Key Questions Answered in the Report
What is the Australia Skin Care Products market size and growth outlook?
It is expected to reach USD 4.29 billion in 2027 and USD 5.38 billion by 2032, at a 4.65% CAGR over 2027-2032.
What supports demand for skincare products in Australia?
Anti-aging positioning, formulation improvements and natural-product preferences support demand. AHC’s May 2025 return through Priceline illustrates commercial activity in anti-aging skincare.
Which skincare product type leads sales?
Facial care products held 72.91% of market value in 2026, while body care products are forecast to grow fastest at a 5.1% CAGR over 2027-2032.
Which companies lead the skincare industry in Australia?
The leading participants are Unilever PLC, Beiersdorf AG, L’Oréal SA, Estée Lauder Companies Inc. and Procter & Gamble Company.
What is a key constraint on skincare product availability?
Ingredient-health concerns can interrupt retail access. Kmart withdrew its hyaluronic acid cleansing balm in March 2025 while investigating ingredients after adverse-reaction reports.
How is skincare retail access changing across Australia?
Retailers opened new beauty stores in 2025, including Tokyo Lifestyle in Sydney and W Cosmetics in Darwin, and MECCA reopened its renovated Hobart store in September 2026.