
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 2.75 Billion |
| Market Size (2026) | USD 3.53 Billion |
| Market Size (2031) | USD 12.09 Billion |
| Growth Rate (2026 - 2031) | 27.93 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Asia-Pacific Fuel Cell Vehicles Market Analysis by Mordor Intelligence
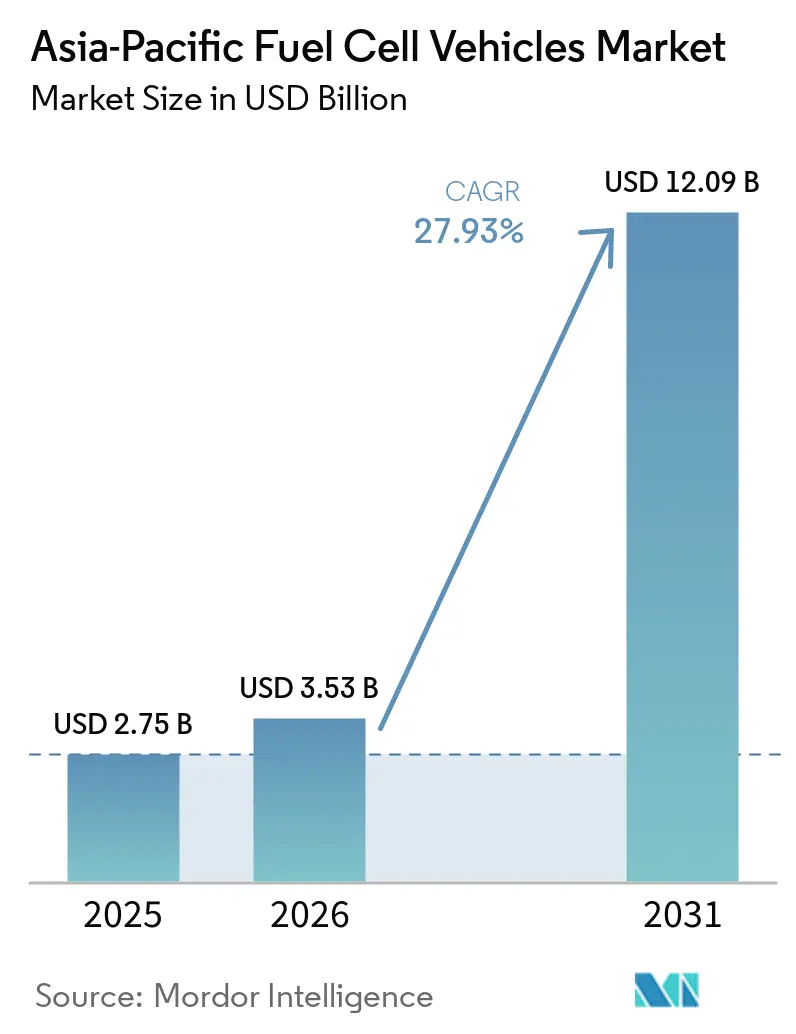
The Asia-Pacific Fuel Cell Vehicles Market size was valued at USD 2.75 billion in 2025 and reached USD 3.53 billion in 2026, and is expected to reach USD 12.09 billion by 2031, growing at a CAGR of 27.93% over 2026-2031. Government mandates, falling stack costs, and purpose-built refueling corridors are steering heavy-duty fleets toward hydrogen, especially on routes where battery weight or charging downtime would erode payload utilization. South Korea led regional revenue in 2025, yet China’s vertically integrated supply chains and municipal fleet targets position it as the fastest-growing market through 2031. Proton-exchange-membrane fuel cells are lowering platinum loading fast enough to pull total vehicle cost close to diesel parity for high-mileage operators. Infrastructure density is improving as oil, gas, and utility companies co-locate electrolyzers with service stations, a move that cuts hydrogen transport charges and raises station utilization above breakeven thresholds. Competitive dynamics favor players that marry stack production with vehicle assembly and fuel supply, compressing margins for firms that still rely on discrete, imported components.
Key Report Takeaways
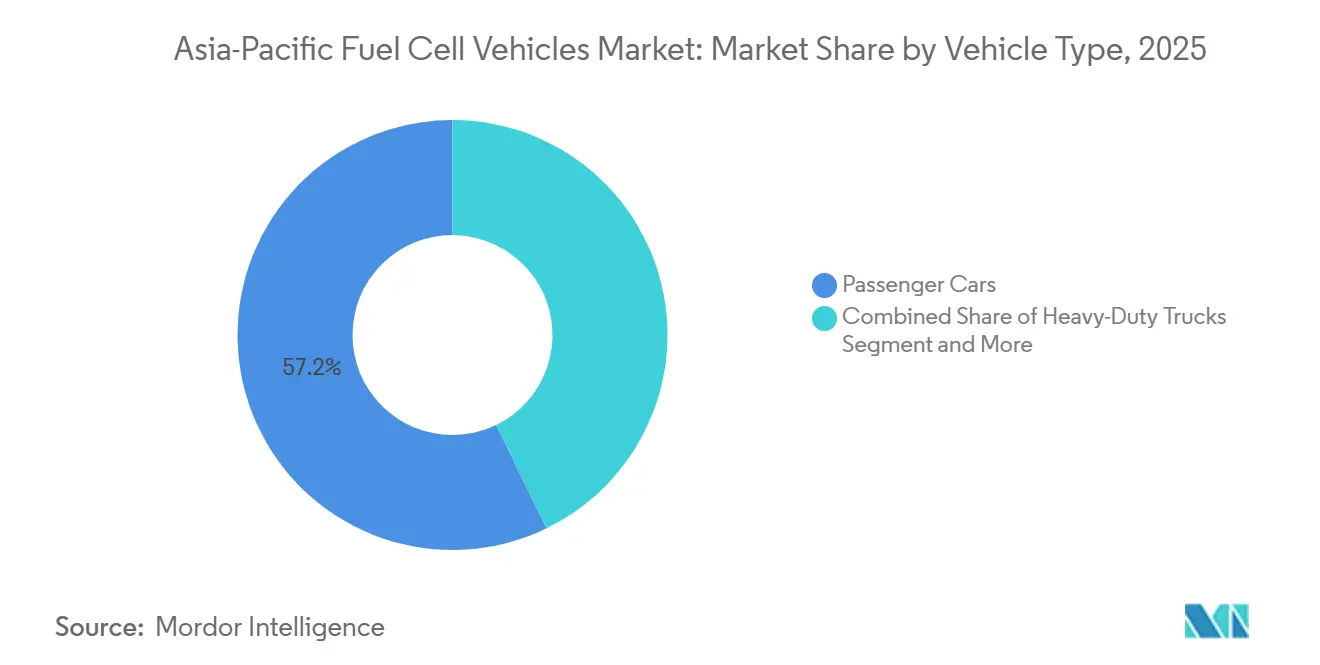
- By vehicle type, Passenger cars led with a 57.16% share of the Asia Pacific fuel cell vehicles market in 2025, while heavy-duty trucks are projected to post the highest CAGR of 28.94% to 2031.
- By fuel cell type, Proton-exchange-membrane stacks captured 83.37% of shipments in 2025 and are advancing at a 28.98% CAGR, far outpacing solid-oxide and alkaline chemistries.
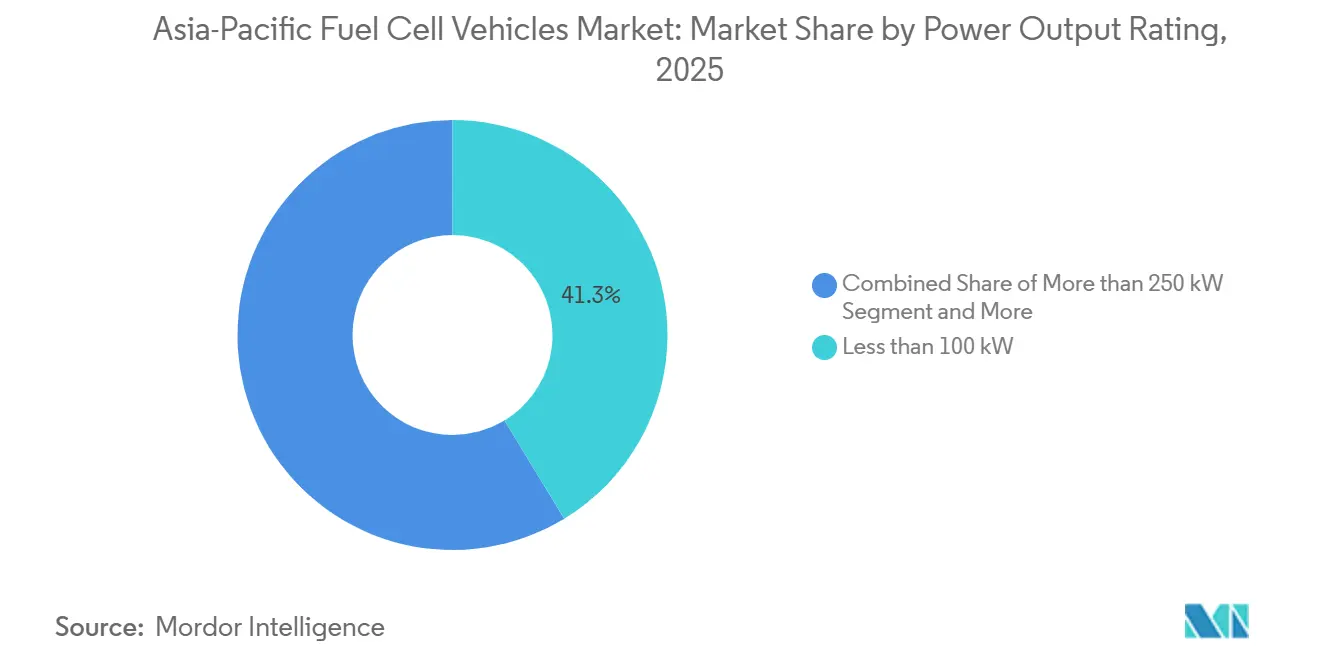
- By power output rating, Systems below 100 kW accounted for 41.27% of the Asia Pacific fuel cell vehicles market size in 2025, whereas powertrains above 250 kW are expanding at the segment-high 29.04% CAGR.
- By driving range, driving ranges of 400-700 km represented the largest 56.27% share in 2025; vehicles able to exceed 700 km are growing at 29.01% CAGR to 2031.
- By country, South Korea held 37.71% of regional revenue in 2025, but China is forecast to be the fastest-growing geography at 28.96% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Asia-Pacific Fuel Cell Vehicles Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Commercial and Heavy-Duty Decarbonization | +7.1% | Global, with concentration in China, Japan, South Korea | Long term (≥ 4 years) |
| Strong Government Policy & Subsidies | +6.2% | China, Japan, South Korea, India | Medium term (2-4 years) |
| Strategic Infrastructure Investment | +5.3% | China, South Korea, Japan, Australia | Long term (≥ 4 years) |
| Rapid Refueling Advantages | +4.8% | Asia-Pacific core, spillover to Australia, India | Medium term (2-4 years) |
| Indigenous Manufacturing and R&D | +3.9% | China, Japan, South Korea | Long term (≥ 4 years) |
| Energy Security Initiatives | +2.4% | Japan, South Korea, India, Australia | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Commercial & Heavy-Duty Decarbonization
Freight companies are increasingly turning to hydrogen, as battery packs reduce payload capacity and charging downtimes disrupt multi-shift operations. In recent years, Hyundai delivered a significant number of Xcient Fuel Cell trucks to domestic fleets, achieving a notable utilization rate due to quick refueling. This outperformed the utilization recorded by their battery-electric counterparts. Around the same period, Toyota and Hino initiated a pilot with several fuel-cell rigs for the Tokyo–Osaka port drayage, a route set to ban diesel in the near future. Responding to Chinese municipal decrees, cities with large populations must transition a portion of their transit buses to zero-emission powertrains within the next few years. This mandate leans towards fuel cells for routes covering longer distances. Internal fleet models suggest that operators with high annual mileage will see fuel-cell trucks reach cost parity with diesel in the coming years. With an increasing number of heavy-duty chassis surpassing this mileage, demand for these units is expected to surge rapidly over the forecast period.
Strong Government Policy & Subsidies
National and provincial treasuries are shifting from one-time purchase rebates to co-funding initiatives. These initiatives bundle together vehicles, hydrogen supply, and depot infrastructure. China is continuing its per-vehicle incentive for several years. However, the disbursement is now tied to sourcing hydrogen from renewable or industrial by-products. This move encourages fleets to opt for low-carbon supply contracts. South Korea's Hydrogen Economy Roadmap 2.0 allocates significant funding to establish heavy-duty corridors. These corridors stretch between major cities and aim to reduce payback periods for long-haul trucks to a competitive timeframe. Japan's updated Green Growth Strategy mandates that within a few years, metropolitan freight operators must ensure a notable portion of new commercial registrations are zero-emission. This effectively creates a reserved demand pool for fuel-cell trucks. India is investing heavily in viability-gap funding.
Strategic Infrastructure Investment
Operators are increasingly directing vehicles to high-throughput sites, leading to a significant rise in station utilization over the years and shortening breakeven horizons. China Petroleum & Chemical Corporation has allocated a substantial budget to construct numerous freeway stations, each designed to handle a high volume of vehicles daily, positioning itself to accommodate the anticipated surge in truck volumes. Over the next few years, South Korea’s Hyundai Oilbank and SK E&S joint venture plans to introduce several co-located electrolyzer stations, a strategy that not only cuts haulage costs but also allows them to price hydrogen competitively. Indian Oil Corporation has initiated projects at multiple sites in collaboration with Tata and Ashok Leyland bus fleets, targeting commissioning in the near future. As costs for electrolyzers and compression decrease, utilization benchmarks are trending downward, indicating that even medium-duty depots might achieve profitability sooner than expected [1].
Rapid Refueling Advantages
Fleet managers can now align diesel shift schedules without the need for large-scale charging depots, due to the ability to keep fill times short. Recently, Sinopec inaugurated several stations, offering city buses a swift and efficient refueling process and trucks a slightly longer but still rapid fill. Ampol of Australia is set to retrofit a number of outlets in the near future, enabling mining haulers in New South Wales and Victoria to maintain their extended duty cycles. Japan's introduction of mobile dispensers in rural prefectures has significantly reduced capital expenditures, demonstrating that station coverage can expand without the necessity of new builds. Logistics analysis reveals that trucks refueling during a single driver break see a notable utilization boost over battery-electric counterparts, a difference that effectively balances out the higher capital expenditure on vehicles. As station density increases, this refueling advantage could emerge as a pivotal factor for time-sensitive freight.
Restraints Impact Analysis of Asia-Pacific Fuel Cell Vehicles Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Upfront Costs | -4.7% | Global, acute in India, Indonesia, Thailand | Short term (≤ 2 years) |
| Nascent Refueling Infrastructure | -3.9% | India, Indonesia, Malaysia, Thailand, Australia | Medium term (2-4 years) |
| Hydrogen Supply Chain Challenges | -2.8% | Asia-Pacific excluding China, Japan, South Korea | Medium term (2-4 years) |
| Technical & Durability Issues | -1.6% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Upfront Costs
In 2025, fuel-cell trucks were significantly more expensive than their diesel counterparts, with a substantial price premium. This pricing dynamic restricted their adoption primarily to fleets benefiting from subsidies or those operating on long-distance duty cycles. For instance, a Hyundai fuel-cell truck required high annual utilization over several years to achieve payback, a threshold typically met by operations such as hub-and-spoke logistics or port drayage. Meanwhile, Toyota's Mirai was priced significantly higher than hybrid sedans in Japan, limiting its sales predominantly to corporate entities. In India, prototype buses were considerably more expensive than their CNG counterparts, leading municipalities to depend on central grants for purchases. To eliminate the premium in commercial classes, manufacturers aimed to significantly reduce stack costs within a few years.
Nascent Refueling Infrastructure
Station density outside of South Korea, Japan, and coastal China still falls short of supporting intercity coverage. By the mid-decade, India had established only a limited number of public dispensers, all concentrated in a few metro regions, which in turn constrained fleet operations. Indonesia, with plans for a small number of stations in the coming years, lags significantly behind the economically-driven benchmark required for efficient operations. Around the same period, Australia had a handful of urban stations, yet mining routes continued their reliance on diesel until funding for corridor expansions materialized. With high average capital expenditure per site, private investors remain hesitant, unless there's a throughput guarantee from anchor fleets.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Asia-Pacific Fuel Cell Vehicles Market Segment Analysis
By Vehicle Type:
Commercial Fleets Drive Hydrogen AdoptionHeavy-duty trucks are on track for a 28.94% CAGR through 2031, steadily narrowing the gap with the passenger-car segment that commanded 57.16% of 2025 revenue within the Asia Pacific fuel cell vehicles market. Last year, China's municipal fleets logged significant daily duty cycles for thousands of buses. As Japan and South Korea gear up for urban diesel restrictions in the near future, light commercial vans and pick-ups accounted for a notable portion of sales, catering to last-mile operators.
Stricter port and freeway regulations, which penalize particulate emissions, are driving momentum in the heavy-duty sector. Additionally, once vehicles reach high annual mileage, owners benefit from total-cost-of-ownership gains. In recent years, fuel cell vehicles have captured a growing market share in Asia Pacific for off-highway machinery, including port forklifts and airport tugs. This share is increasing as equipment owners realize battery packs hinder multi-shift operations. While passenger-car demand is limited by infrastructure, OEM order books remain devoid of surplus stock, indicating a balanced, albeit modest, retail niche.



By Fuel Cell Type:
PEMFC Dominance Reinforced by Cost DeclinesPEMFC technology held an 83.37% share in 2025, and supplier forecasts point to a 28.98% CAGR as automotive-grade membranes dominate propulsion use cases. Solid-oxide units captured a notable market share, primarily serving as auxiliary power sources in trucks and marine platforms, where they reap efficiency benefits at high operating temperatures.
In the Asia Pacific, the market for alkaline and phosphoric-acid fuel cell vehicles remains limited. This is due to challenges with weight, start-up time, and electrolyte handling, which don't meet fleet expectations. Meanwhile, at Hyundai Mobis, reductions in platinum loading have significantly lowered the costs of PEM stacks. On the other hand, SOFC suppliers are still addressing startup latency issues, pushing the commercial launch for their range-extender roles to a later timeline.
By Power Output Rating:
High-Power Systems Gain as Trucks ScaleSystems under 100 kW supplied 41.27% of the Asia Pacific fuel cell vehicles market in 2025, serving compact cars, vans, and city buses. In the mid-band 100-250 kW class, a decent share went to medium-duty trucks and intercity coaches that require deeper torque reserves.
Demand is shifting upward: units above 250 kW are climbing at 29.04% CAGR, buoyed by port drayage, long-haul, and mining trucks where payload penalties from batteries are most acute. Higher volume spreads fixed stack-manufacturing overhead across more kilowatts, allowing per-kW prices to fall 22% relative to sub-100 kW platforms, accelerating adoption in heavy applications.

By Driving Range:
Long-Range Platforms Capture Fleet DemandThe 400-700 km bracket represented 56.27% of 2025 sales, balancing tank mass with city-to-city coverage. Yet vehicles exceeding 700 km are growing at 29.01% CAGR because shippers prefer single-shift runs without mid-route stops.
As station density improved, the operational penalty of carrying extra hydrogen shrank, leading to a decline in the Asia Pacific market share for shorter-range fuel cell cars and vans. While liquid hydrogen prototypes have demonstrated significantly extended ranges during testing, their commercialization is contingent upon cryogenic refueling lanes, which currently lie outside existing funding cycles.
Geography Analysis
Asia-Pacific Fuel Cell Vehicles Market in Japan
Japan continues to dominate the Asia-Pacific fuel cell vehicle market, commanding approximately 98% of the total market share in 2024. The country's leadership position is underpinned by its comprehensive hydrogen society strategy, which emphasizes hydrogen as a pivotal energy source for achieving carbon neutrality by 2050. Japan's success in the hydrogen fuel cell vehicle sector is driven by substantial government investments in hydrogen technology and infrastructure development. The country has implemented specific policies supporting FCV development and deployment, including significant subsidies for vehicle purchases and funding for hydrogen refueling station construction. Japanese automakers have established themselves as global leaders in hydrogen automotive technology, continuously innovating and improving vehicle performance while reducing costs. The nation's robust research and development ecosystem, coupled with strong collaboration between industry players and government agencies, has created a favorable environment for FCV advancement. Furthermore, Japan's strategic focus on developing a comprehensive hydrogen supply chain has helped address one of the key challenges facing FCV adoption - the availability of hydrogen fuel infrastructure.
Asia-Pacific Fuel Cell Vehicles Market in India
India's hydrogen fuel cell vehicle market is experiencing remarkable growth, with a projected CAGR of approximately 107% from 2024 to 2029. The country's aggressive push towards clean mobility solutions has created a conducive environment for FCV adoption. India's approach to hydrogen mobility development is characterized by a unique blend of government initiatives and private sector participation. The country has been actively developing its hydrogen ecosystem, with several pilot projects and demonstrations showcasing the potential of fuel cell vehicle technology in various transportation applications. Major automotive manufacturers are increasingly investing in FCV research and development facilities within India, recognizing the country's potential as a key market for hydrogen mobility solutions. The government's emphasis on reducing oil imports and achieving energy independence has led to supportive policies for alternative fuel technologies, including hydrogen fuel cells. Additionally, India's strong automotive manufacturing base and engineering expertise provide a solid foundation for localizing FCV production and reducing costs. The country's focus on developing green hydrogen production capabilities further strengthens its position in the FCV market.
Asia-Pacific Fuel Cell Vehicles Market in China
China's hydrogen fuel cell vehicle market demonstrates remarkable dynamism, supported by the country's comprehensive strategy for hydrogen mobility development. The nation's approach combines strong policy support with substantial industrial investment, creating a robust ecosystem for FCV growth. Chinese authorities have implemented various initiatives to promote hydrogen fuel cell technology, including subsidies for research and development, demonstration projects, and infrastructure development. The country's vast manufacturing capabilities and supply chain advantages have enabled rapid scaling of FCV production while reducing costs. Local governments across China have been actively supporting the deployment of fuel cell vehicles, particularly in public transportation and logistics applications. The nation's commitment to developing a world-class hydrogen energy industry has attracted significant investment from both domestic and international players. Furthermore, China's strategic focus on establishing hydrogen industrial clusters has created centers of excellence for FCV technology development and commercialization. The country's emphasis on developing indigenous intellectual property in fuel cell technology has led to numerous technological breakthroughs and innovations.
Asia-Pacific Fuel Cell Vehicles Market in Other Countries
The hydrogen fuel cell vehicle market in other Asia-Pacific countries, including South Korea, Australia, Indonesia, Malaysia, and Thailand, exhibits varying degrees of development and potential. These nations are actively formulating and implementing hydrogen strategies, recognizing the crucial role of hydrogen powertrain technology in their energy transition plans. Each country brings unique strengths to the regional FCV ecosystem - South Korea's advanced automotive manufacturing capabilities, Australia's abundant renewable energy resources for green hydrogen vehicle production, and Southeast Asian nations' growing focus on sustainable transportation solutions. These markets are characterized by increasing collaboration between government agencies, research institutions, and private sector players to advance FCV technology and infrastructure development. The diversity of approaches to FCV adoption across these countries contributes to the overall robustness of the Asia-Pacific fuel cell vehicle market. Their collective efforts in developing hydrogen infrastructure, implementing supportive policies, and fostering innovation create a dynamic environment for the growth of the regional FCV industry.
Competitive Landscape
Market Concentration
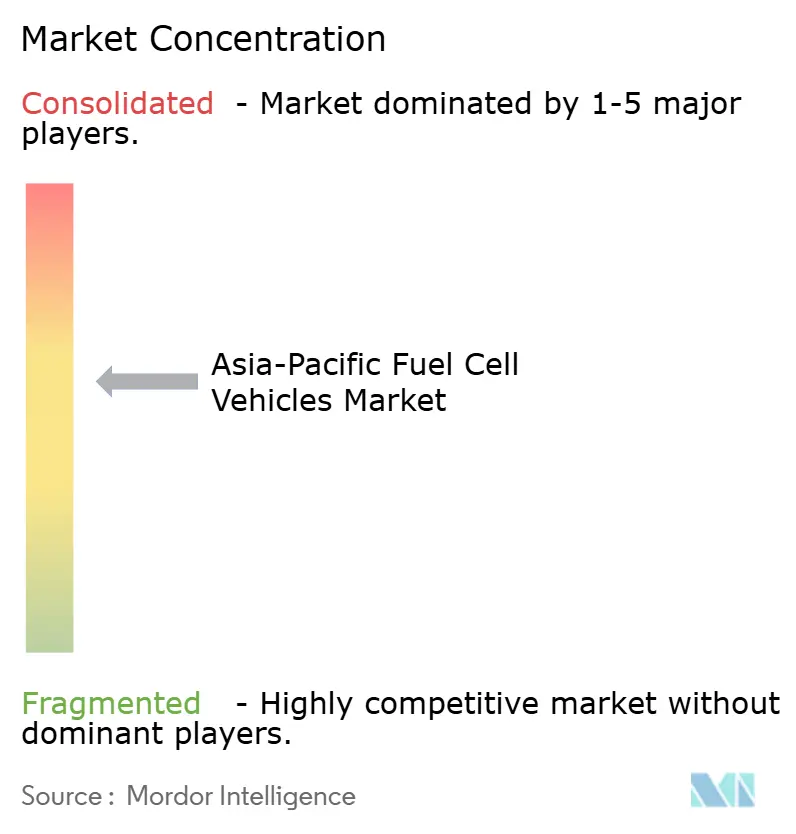
The Asia-Pacific fuel cell vehicles market shows moderate concentration, with Toyota, Hyundai, and SAIC Motor accounting for a significant share of unit shipments. Chinese state-owned enterprises are tightening supply chain margins by integrating membrane production, vehicle assembly, and fueling stations. This integration creates pricing challenges for Japanese and Korean competitors while allowing Chinese players to protect their returns.
Technology gaps are narrowing. Most OEMs are transitioning to advanced storage systems, lower platinum loadings, and modular stack architectures. Ballard has secured multiple patents focused on membrane durability and catalyst recovery, which could significantly extend stack lifetimes. Following the termination of its joint venture with Volvo, Daimler has protected its intellectual property and is actively testing prototypes in Australia and Japan.
Opportunities remain in medium-duty rigid trucks and off-highway equipment, where battery-electric vehicles continue to face mass and duty-cycle constraints. Hyzon has recently delivered a substantial number of trucks to customers in China, while Weichai has achieved a milestone by overcoming cost barriers through localized components. As infrastructure density increases, entry barriers will decline; however, cost leadership and a vertically integrated hydrogen supply will remain critical competitive factors.
Asia-Pacific Fuel Cell Vehicles Industry Leaders
-
Honda Motor Co. Ltd.
-
Hyundai Motor Company
-
Nissan Motor Co. Ltd.
-
Toyota Motor Corporation
-
Daimler Truck
- *Disclaimer: Major Players sorted in no particular order
Asia-Pacific Fuel Cell Vehicles Market Companies Covered in this Report
- Ballard Power Systems
- Daimler Truck
- Dongfeng Motor Corporation
- Honda Motor Co. Ltd.
- Hyundai Motor Company
- Sinopec
- Nissan Motor Co. Ltd.
- Toyota Motor Corporation
- Foton Motor Group
- SAIC Motor Corporation
- FAW Group
- Hyzon Motors
- Weichai Power
- Tata Motors
- Ashok Leyland
- XCMG Automotive
- SANY Group
- UD Trucks
Recent Industry Developments in Asia-Pacific Fuel Cell Vehicles Market
- July 2026: NIPPON HEV, in collaboration with Nippon Energy, introduced its next-generation urban mobility platform. The upcoming lineup combines electric and H₂ hydrogen propulsion systems for lightweight urban commuter vehicles and heavy-duty vehicles, aiming to reduce regional grid strain.
- January 2026: Toyota began retail deliveries of the 2026 Mirai, a hydrogen fuel cell electric vehicle that features an EPA-estimated driving range of 402 miles. The vehicle also includes the Toyota Safety Sense 3.0 suite, which provides advanced driver-assistance technologies designed to enhance safety and driving convenience.
- November 2025: Hyundai Motor unveiled the next-generation NEXO, targeting 826 km range on WLTP and a 190 kW combined power output ahead of its global debut in early 2026.
Asia-Pacific Fuel Cell Vehicles Market Report Scope
The scope of the report includes Vehicle Type (Passenger Cars and More), Fuel Cell Type (PEMFC and More), Power Output (Less Than 100 KW and More), Driving Range (Less Than 400 Km and More), and Geography. The Market Forecasts in Value (USD) and Volume (Units).
Segmentation Overview
By Vehicle Type
| Passenger Cars |
| Buses |
| Light Commercial Vehicles (vans & pick-ups) |
| Medium- & Heavy-Duty Trucks |
| Off-Highway & Special-Purpose Vehicles |
By Fuel Cell Type
| Proton-Exchange-Membrane (PEMFC) |
| Solid-Oxide (SOFC) |
| Alkaline (AFC) |
| Phosphoric-Acid (PAFC) |
By Power Output Rating
| Less than 100 kW |
| 100 to 250 kW |
| More than 250 kW |
By Driving Range
| Less than 400 km |
| 400 to 700 km |
| More than 700 km |
By Country
| Australia |
| China |
| India |
| Indonesia |
| Japan |
| Malaysia |
| South Korea |
| Thailand |
| Rest of Asia-Pacific |
| By Vehicle Type | Passenger Cars |
| Buses | |
| Light Commercial Vehicles (vans & pick-ups) | |
| Medium- & Heavy-Duty Trucks | |
| Off-Highway & Special-Purpose Vehicles | |
| By Fuel Cell Type | Proton-Exchange-Membrane (PEMFC) |
| Solid-Oxide (SOFC) | |
| Alkaline (AFC) | |
| Phosphoric-Acid (PAFC) | |
| By Power Output Rating | Less than 100 kW |
| 100 to 250 kW | |
| More than 250 kW | |
| By Driving Range | Less than 400 km |
| 400 to 700 km | |
| More than 700 km | |
| By Country | Australia |
| China | |
| India | |
| Indonesia | |
| Japan | |
| Malaysia | |
| South Korea | |
| Thailand | |
| Rest of Asia-Pacific |
Market Definition
- Vehicle Type - The category includes passenger cars and commercial vehicles.
- Vehicle Body Type - Under Passenger Cars, the category includes Hatchbacks, Sedans, Sports Utility Vehicles, and Multi-purpose Vehicles; for Commercial Vehicles, it covers Light Commercial Pick-up Trucks, Light Commercial Vans, Medium-duty Commercial Trucks, Heavy-duty Commercial Trucks, and Medium and Heavy Duty Buses.
- Fuel Category - The category exclusively covers Fuel Cell Electric Vehicles (FCEV).
| Keyword | Definition |
|---|---|
| Electric Vehicle (EV) | A vehicle which uses one or more electric motors for propulsion. Includes cars, buses, and trucks. This term includes all-electric vehicles or battery electric vehicles and plug-in hybrid electric vehicles. |
| BEV | A BEV relies completely on a battery and a motor for propulsion. The battery in the vehicle must be charged by plugging it into an outlet or public charging station. BEVs do not have an ICE and hence are pollution-free. They have a low cost of operation and reduced engine noise as compared to conventional fuel engines. However, they have a shorter range and higher prices than their equivalent gasoline models. |
| PEV | A plug-in electric vehicle is an electric vehicle that can be externally charged and generally includes all-electric vehicles as well as plug-in hybrids. |
| Plug-in Hybrid EV | A vehicle that can be powered either by an ICE or an electric motor. In contrast to normal hybrid EVs, they can be charged externally. |
| Internal combustion engine | An engine in which the burning of fuels occurs in a confined space called a combustion chamber. Usually run with gasoline/petrol or diesel. |
| Hybrid EV | A vehicle powered by an ICE in combination with one or more electric motors that use energy stored in batteries. These are continually recharged with power from the ICE and regenerative braking. |
| Commercial Vehicles | Commercial vehicles are motorized road vehicles designed for transporting people or goods. The category includes light commercial vehicles (LCVs) and medium and heavy-duty vehicles (M&HCV). |
| Passenger Vehicles | Passenger cars are electric motor– or engine-driven vehicles with at least four wheels. These vehicles are used for the transport of passengers and comprise no more than eight seats in addition to the driver’s seat. |
| Light Commercial Vehicles | Commercial vehicles that weigh less than 6,000 lb (Class 1) and in the range of 6,001–10,000 lb (Class 2) are covered under this category. |
| M&HDT | Commercial vehicles that weigh in the range of 10,001–14,000 lb (Class 3), 14,001–16,000 lb (Class 4), 16,001–19,500 lb (Class 5), 19,501–26,000 lb (Class 6), 26,001–33,000 lb (Class 7) and above 33,001 lb (Class 8) are covered under this category. |
| Bus | A mode of transportation that typically refers to a large vehicle designed to carry passengers over long distances. This includes transit bus, school bus, shuttle bus, and trolleybuses. |
| Diesel | It includes vehicles that use diesel as their primary fuel. A diesel engine vehicle have a compression-ignited injection system rather than the spark-ignited system used by most gasoline vehicles. In such vehicles, fuel is injected into the combustion chamber and ignited by the high temperature achieved when gas is greatly compressed. |
| Gasoline | It includes vehicles that use gas/petrol as their primary fuel. A gasoline car typically uses a spark-ignited internal combustion engine. In such vehicles, fuel is injected into either the intake manifold or the combustion chamber, where it is combined with air, and the air/fuel mixture is ignited by the spark from a spark plug. |
| LPG | It includes vehicles that use LPG as their primary fuel. Both dedicated and bi-fuel LPG vehicles are considered under the scope of the study. |
| CNG | It includes vehicles that use CNG as their primary fuel. These are vehicles that operate like gasoline-powered vehicles with spark-ignited internal combustion engines. |
| HEV | All the electric vehicles that use batteries and an internal combustion engine (ICE) as their primary source for propulsion are considered under this category. HEVs generally use a diesel-electric powertrain and are also known as hybrid diesel-electric vehicles. An HEV converts the vehicle momentum (kinetic energy) into electricity that recharges the battery when the vehicle slows down or stops. The battery of HEV cannot be charged using plug-in devices. |
| PHEV | PHEVs are powered by a battery as well as an ICE. The battery can be charged through either regenerative breaking using the ICE or by plugging into some external charging source. PHEVs have a better range than BEVs but are comparatively less eco-friendly. |
| Hatchback | These are compact-sized cars with a hatch-type door provided at the rear end. |
| Sedan | These are usually two- or four-door passenger cars, with a separate area provided at the rear end for luggage. |
| SUV | Popularly known as SUVs, these cars come with four-wheel drive, and usually have high ground clearance. These cars can also be used as off-road vehicles. |
| MPV | These are multi-purpose vehicles (also called minivans) designed to carry a larger number of passengers. They carry between five and seven people and have room for luggage too. They are usually taller than the average family saloon car, to provide greater headroom and ease of access, and they are usually front-wheel drive. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all its reports.
- Step-1: Identify Key Variables: To build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built based on these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. Market revenue is calculated by multiplying the sales volume with their respective average selling price (ASP). While estimating ASP factors like average inflation, market demand shift, manufacturing cost, technological advancement, and varying consumer preference, among others have been taken into account.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


