
Asia-Pacific Beauty and Personal Care Products Market Analysis by Mordor Intelligence
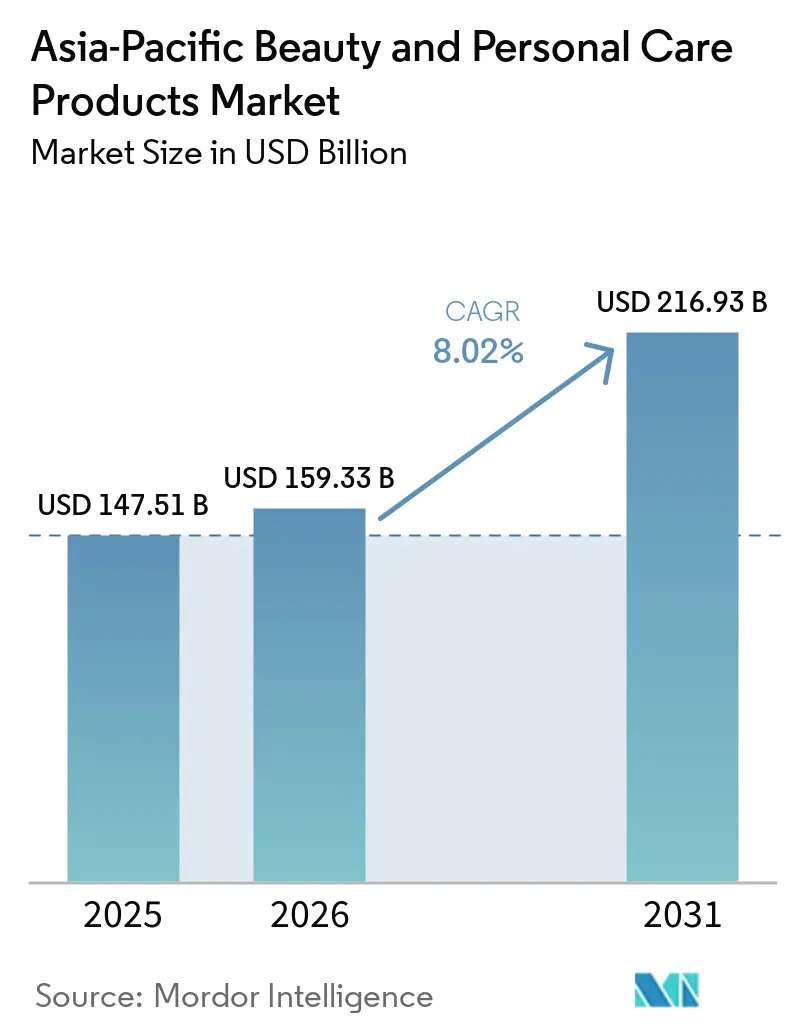
The Asia-Pacific beauty and personal care products market size is expected to grow from USD 159.3 billion in 2026 to USD 169.5 billion in 2027 and is forecast to reach USD 228.7 billion by 2032 at 6.18% CAGR over 2027-2032.
Care-focused skincare purchasing and social-media engagement support growth by linking product demand with online orders and store purchases. Premium growth in China and improved travel-retail economics favor distinctive portfolios supported by disciplined distribution. The Iran-U.S.-Israel war that began in February 2026 also exposed Indonesian cosmetics producers to fuel and plastic-packaging cost pressure. Fuel and plastic-packaging pressure in Indonesia and pre-import cosmetics registration in India temper that expansion, favoring selective ranges supported by premium demand in China and consumer-focused online channels.
Key Report Takeaways
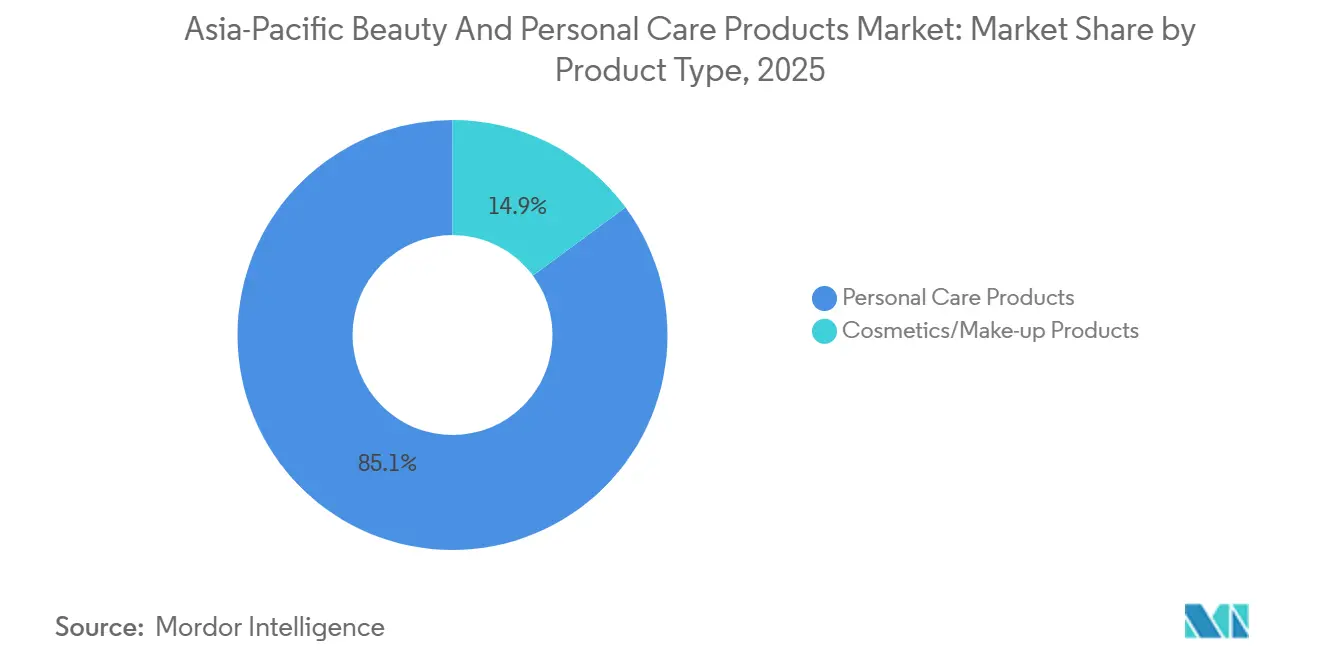
- By product type, personal care products led with an 84.96% Asia-Pacific beauty and personal care products market share in 2026, while cosmetics/makeup products are forecast to grow fastest at 7.3% CAGR over 2027-2032.
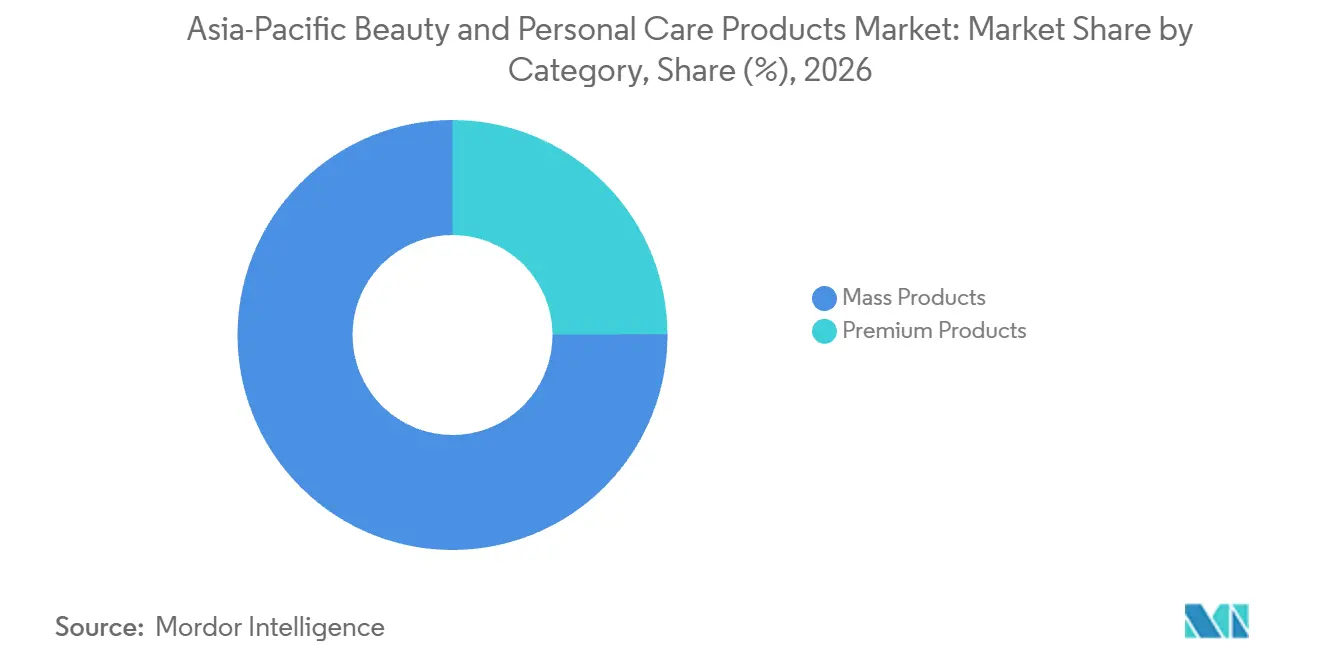
- Within the category breakdown, mass products held a 75.06% share of the Asia-Pacific beauty and personal care products market size in 2026, and premium products are forecast to grow fastest at 7.6% CAGR over 2027-2032.
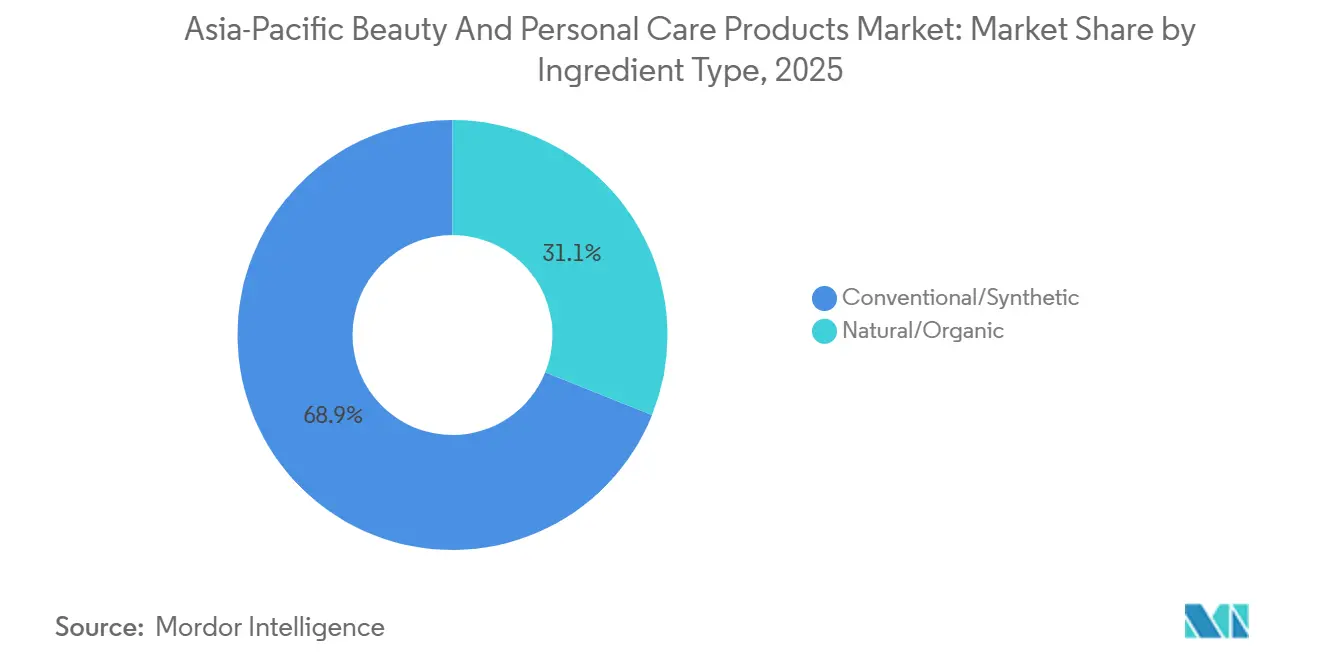
- Ingredient type results place conventional/synthetic products first with 68.43% of the market in 2026, with natural and organic products forecast to grow fastest at 7.9% CAGR over 2027-2032.
- Across distribution channels, health and beauty stores led with 36.21% of the market in 2026, while online retail stores are forecast to grow fastest at 8.35% CAGR over 2027-2032.
- Geographically, China held 40.2% of the market in 2026, and Indonesia is forecast to grow fastest at 8.15% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Asia-Pacific Beauty and Personal Care Products Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising demand for premium and natural beauty products | +2% | China | Medium term (2-4 years) |
| Increasing beauty and self-care awareness among consumers | +1.7% | Japan | Long term (≥ 4 years) |
| Growing influence of social media and beauty influencers | +1.4% | China | Short term (≤ 2 years) |
| Increasing male grooming and inclusive beauty trends | +1.1% | Japan and South Korea | Medium term (2-4 years) |
| Technological innovations in beauty and skincare formulations | +0.9% | Japan | Medium term (2-4 years) |
| Growing demand for anti-aging and personalized beauty solutions | +0.7% | Japan | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising demand for premium and natural beauty products
Premium beauty growth gives suppliers a reason to distinguish channel expansion from country selection. L'Oréal Luxe reported growth close to 5% in Asia outside Travel Retail in the second half of 2025. In the first half of 2026, North Asia was the division's largest growth contributor, boosted by double-digit growth in China. The earlier result concerns non-travel business across Asia, while the later reading locates a country contribution within North Asia. This pairing favors premium launch support concentrated on Asian non-travel channels and on China, rather than a plan dependent entirely on travel-retail demand.
Increasing beauty and self-care awareness among consumers
Self-care awareness supports skincare demand when consumers use products to address continuing skin-health needs rather than appearance alone. In a multiple-response survey of MyVoice online panelists in Japan conducted August 1-7, 2026, 47.2% of skincare and cosmetics users cited keeping skin healthy or addressing skin concerns. Shiseido reported that Elixir's 2025 sales value in Japan grew by double digits versus 2024, measured by customer purchasing behavior.[1] Elixir is positioned as an aging-care skincare brand. For suppliers serving Japan, organizing a skincare range by the concern it addresses connects product development to an expressed use motive.
Growing influence of social media and beauty influencers
Social beauty engagement can connect online discovery with store purchases across different sales channels. In the year ended March 31, 2026, Sa Sa reported that social-media engagement converted traffic into orders alongside higher sales and transaction counts in its Hong Kong and Macao business. The retailer also said some Chinese Mainland social-platform traffic drove offline sales in Hong Kong and Macao. For Sa Sa, assessing social-channel performance solely through online orders would miss the Hong Kong and Macao store sales connected to that traffic.
Increasing male grooming and inclusive beauty trends
Male beauty demand supports a more precise audience strategy than treating all men as one makeup customer group. Japan's 2025 second-half Beauty Census surveyed people ages 15-69 in cities with at least 200,000 residents and found that 13.8% of men had bought at least one makeup item in the preceding year. Among men in their 20s, the rate was 34.8%, up 8.9 percentage points year over year. Separately, Amorepacific reported more than 300,000 cumulative units sold through Daiso in South Korea for Prep by B.READY men's care since its 2025 launch, by April 23, 2026. These examples favor targeted recruitment of younger makeup buyers alongside a distinct men's care retail offer, with product and audience choices addressing different sources of demand.
Restraints Impact Analysis of Asia-Pacific Beauty and Personal Care Products Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent regulatory requirements and compliance challenges | -0.7% | India | Medium term (2-4 years) |
| Supply chain disruptions and raw material price volatility | -0.6% | Indonesia | Short term (≤ 2 years) |
| Counterfeit and unbranded product market growth | -0.3% | Vietnam and South Korea | Medium term (2-4 years) |
| Environmental concerns over packaging waste and chemicals | -0.2% | India | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Stringent regulatory requirements and compliance challenges
Assortment breadth creates a regulatory workload before an imported cosmetics range can reach Indian buyers. India's Central Drugs Standard Control Organization requires pre-import registration covering cosmetics, pack sizes, variants, and manufacturing premises. For a brand considering several variants, the relevant entry decision therefore extends beyond whether a single formula is commercially attractive. Because registration also covers manufacturing premises, an importer's range is tied to specific production sites before the first shipment.
Supply chain disruptions and raw material price volatility
Packaging and fuel costs can constrain cosmetics supply together, leaving producers with fewer ways to absorb a disruption. In May 2026, Martha Tilaar CEO Kilala Tilaar attributed higher Indonesian cosmetics packaging and fuel-related operating costs to the Iran-U.S.-Israel war that began in February 2026. Absorbing both increases would put pressure on earnings available to support product expansion. Passing them through instead would raise the delivered cost of packaged cosmetics for buyers. Perkosmi said in May 2026 that it was working with the government to encourage domestic production of selected imported palm-oil-based ingredients. That ingredient-sourcing initiative leaves the separate packaging and fuel burden as a constraint on expansion.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Asia-Pacific Beauty and Personal Care Products Market Segment Analysis
By Product Type:
Personal Care Scale and Divergent Makeup PerformancePersonal care products were the largest segment, holding 84.96% of the market in 2026. Hindustan Unilever Limited (HUL) reported INR 95.67 billion (USD 1.08 billion) in audited standalone Personal Care segment revenue from sales and other operating revenue in FY2025-26. An entrant in India therefore encounters a personal-care incumbent with annual segment revenue above USD 1 billion, which makes competing for an existing consumer franchise the relevant scale challenge.
Cosmetics/makeup products are the fastest-growing segment, with a forecast 7.3% CAGR over 2027-2032. Mao Geping Cosmetics reported company-level color-cosmetics sales volume of 12.5 million units in the first half of 2026, compared with 9.06 million in the first half of 2025. Separately, Yatsen's Color Cosmetics Brands net revenues fell 35.8% year over year in the second quarter of 2026. These company outcomes show different commercial directions, with an expanding unit-sales business alongside a contracting brand-revenue portfolio. Segment growth therefore leaves distinct tasks for suppliers, scaling delivery where product volumes rise and addressing weaker brand revenues where an individual commercial business has contracted.

By Category:
Mass Reach and Premium Brand DevelopmentMass products accounted for a 75.06% share of the Asia-Pacific beauty and personal care products market size in 2026, making them the largest segment. In January 2026, Unilever described Sunsilk as a mass hair-care line. In June 2026, HUL hair-care vice president Sairam Subramanian reported that Sunsilk reached half of Indian households. The combination of mass positioning and extensive household reach shows how a brand can participate in this category through a broad consumer-facing business. An existing mass hair-care line can therefore provide a platform for product development aimed at a wide household audience, giving brand reach a role beyond the sales of an individual item.
Premium products are the fastest-growing segment, with a forecast 7.6% CAGR over 2027-2032. For the quarter ended June 30, 2026, Yatsen reported strong skincare-portfolio growth led by clinical and premium brands including Galénic, its mainland China DR.WU business, and Eve Lom. That performance supports product development around differentiated skincare propositions within Yatsen's growing portfolio. The company also described optimization of its brand portfolio and distribution channels. For this portfolio, brand selection and channel optimization are linked decisions about which premium skincare offers buyers can reach.
By Ingredient Type:
Conventional Leadership and Botanical Product IdentityConventional/synthetic products were the largest segment, accounting for 68.43% of the market in 2026. For bath and shower, hair care, oral care, and deodorant buyers, cleansing, conditioning, hygiene, and odor control create distinct formulation requirements. Conventional/synthetic products can be designed around those functions without making a particular botanical the organizing feature of every range. That gives this ingredient approach breadth across daily-care applications rather than dependence on one natural-ingredient proposition. Suppliers serving these categories therefore compete on performance in the intended use, with different development priorities for a toothpaste and a hair conditioner.
Natural and organic products are the fastest-growing segment, with a forecast 7.9% CAGR over 2027-2032. Shanghai Forest Cabin Cosmetics Group reported that its camellia-based facial essence oil had sold over 55 million bottles cumulatively in China by December 31, 2025. The product-specific volume places a botanical identity within a finished facial-care business. For ingredient suppliers, that distinction favors development partnerships aimed at a branded essence oil, where the botanical identity can reach the skincare buyer.
By Distribution Channel:
Specialty Store Reach and Online Transaction ChoicesHealth and beauty stores represented a 36.21% Asia-Pacific beauty and personal care products market share in 2026, making them the largest segment. At March 31, 2026, Nykaa operated 313 specialty beauty stores across 99 Indian cities after adding 76 stores in FY2026. The retailer also reported double-digit same-store sales growth for the year. Expansion and same-store growth make different contributions to the store model, one extending physical reach and the other growing sales from existing locations. For beauty suppliers, the specialist store proposition therefore combines access to new locations with an established retail base that can generate additional business within its existing network.
Online retail stores are the fastest-growing segment, with a forecast 8.35% CAGR over 2027-2032. Sa Sa International reported that unaudited companywide online business-to-consumer (B2C) sales increased 22.5% year over year from July through September 2026. The retailer also said it reduced lower-margin bulk business-to-business (B2B) orders to prioritize stock allocation for its offline retail and B2C e-commerce businesses. That choice connects online revenue with the retailer's allocation of stock and commercial attention between bulk and consumer orders. The retailer described the offline retail and B2C businesses receiving priority as higher margin and rapidly growing, tying its online expansion to profitability rather than volume alone.
Geography Analysis
China Beauty and Personal Care Products Market
China accounted for 40.2% of the Asia-Pacific beauty and personal care products market size in 2026. Cosmetics retail sales by enterprises above designated size totaled CNY 465.3 billion (USD 65.1 billion) in 2025. During the 2025 Double Eleven festival, consumers used AI to calculate discounts and optimize purchases, while Tmall, JD.com, and Douyin issued AI shopping assistants. This combines an established cosmetics spending base with a festival shopping setting in which consumers can examine promotional economics before selecting an offer. Commercial execution therefore joins retail reach with clear transaction value, making how a cosmetics promotion is understood relevant alongside the product itself.
Indonesia Beauty and Personal Care Products Market
Indonesia is the fastest-growing geography, with a forecast 8.15% CAGR over 2027-2032. In 2025, Guardian's Indonesian health and beauty retail unit recorded double-digit sales and profit growth, driven by higher sales volume, product-mix optimization, and more visitors to premium shopping centers and tourist destinations. Separately, Indonesia's beauty and personal care exports reached USD 2.05 billion in 2025, up 16.19% from 2024. For suppliers serving Indonesian buyers, Guardian's June 2026 network of more than 370 health and beauty stores across more than 90 cities offered a domestic distribution base distinct from the export business.
Local expansion spans digital-first portfolios and supermarket access, with L'Oréal agreeing in June 2026 to acquire a majority of India's personal-care company Innovist, subject to approvals and customary conditions. Japan's 2025 cosmetics shipments emphasized skincare by value, while Australia's substantial online beauty channel in 2025 coexisted with Coles's September 2026 skincare announcement for more than 850 stores and online. In 2025, Amorepacific Corporation's South Korean domestic revenue grew, while Thailand's Rojukiss brand revenue and Rojukiss International's companywide general-trade revenue also increased. Singapore's cosmetics, toiletries and medical goods retail category expanded in chained-volume terms in 2025, while Malaysia permitted halal-logo use only after JAKIM certification, which manufacturers or distributors seek voluntarily for cosmetics notification. For suppliers, broader channels and prospective local brand ownership address buyer access, whereas optional certification adds a positioning decision within the chosen sales route.
Regulatory Framework and Outlook
This comparison assesses selected jurisdictions from the perspective of innovative cosmetics manufacturers entering local markets. Entry requires attention to local accountability in China and ingredient-use conditions in Indonesia. The commercial distinction is whether policy changes the route to launch or requires adaptation within an established formulation framework.
Regulatory Table of Asia-Pacific Beauty and Personal Care Products Market
| Decision factor | China | Indonesia |
|---|---|---|
| Primary authority | National Medical Products Administration (NMPA) | BPOM |
| Key instruments or direction | Cosmetics registration and filing provisions, effective May 1, 2021 | BPOM Regulation No. 25 of 2025, effective October 3, 2025 |
| Commercial effect | Overseas registrants and filers must designate a domestic responsible person | Check permitted ingredient uses, restrictions, and required label warnings |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Easing | No change |
| Source: Mordor Intelligence | ||
China's Medium rating reflects its registration, filing, and domestic responsible-person duties, while Easing concerns the immediate-review pathway for new efficacy claims announced in the November 2025 Opinions. The same agenda proposed stronger online-distribution oversight, so the anticipated relief concerns registration procedures rather than all compliance duties. Indonesia's Medium rating incorporates BPOM Regulation No. 25 of 2025, effective October 3, 2025, its announced ingredient transition through October 2026, and PP 42/2024's cosmetics halal-certification transition, which ended October 17, 2026. Its No change direction assesses the framework after those October transitions, treating ingredient requirements and halal certification, or a non-halal statement for products made from prohibited materials, as the entry baseline.
Value Chain Stages
This comparison follows value creation from personal-care ingredients through cosmetics contract production to beauty retail. Kolmar Korea distinguishes purchaser-specified manufacturing from a model in which it designs, develops, and produces cosmetics marketed under the purchaser's name. That choice determines whether the brand supplies the design or buys development alongside production, so the contract needs to assign those responsibilities explicitly.
Value Chain Analysis Table of Asia-Pacific Beauty and Personal Care Products Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Ingredient production and supply | Ingredient manufacturers such as BASF, supplying personal-care ingredients from Thailand | Ingredient sales | Regional availability of specified inputs | Broaden regional ingredient-production options |
| Product development and contract manufacturing | Cosmetics contract manufacturers such as Kolmar Korea | Contract development and production revenue | Aligning buyer designs and manufacturing responsibilities | Define design, development, and production duties before contracting |
| Retail distribution | Beauty retailers such as Sa Sa International Holdings, serving Hong Kong and Macao, mainland China, and Southeast Asia | Retail product sales | Coordinating store and online routes | Assign channel-specific assortment and sales responsibilities |
| Source: Mordor Intelligence | ||||
Regional ingredient investment can change where resilience is built into the chain, as illustrated by BASF's November 2025 announcement of a new Alkyl Polyglucosides plant at Bangpakong, Thailand. For contract manufacturers, the choice of production model creates different earnings opportunities because product development can form part of the supplied service. Brands seeking resilience therefore face linked decisions about regional ingredient access and how much development work to retain inside their own businesses.
Competitive Landscape
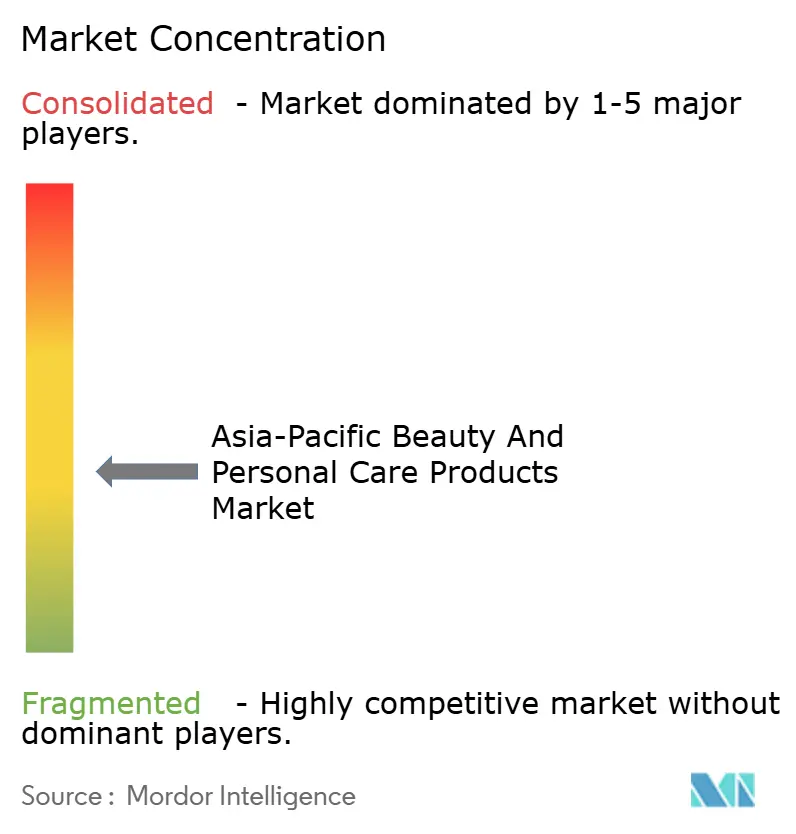
Multinational participants include L'Oréal SA, Shiseido Co., Ltd., Unilever PLC, The Estée Lauder Companies Inc., and Kao Corporation. Shiseido said Southeast Asia, particularly Thailand, and South Korea drove its Asia-Pacific growth in 2025 despite contraction in markets including Taiwan. L'Oréal completed its acquisition of Korean skincare brand Dr.G on March 25, 2025, bringing the brand into its Consumer Products Division. Kao announced Kanebo Cosmetics' SENSAI TOTAL FORM EXPERT WRINKLE AND LIFT CREAM, classified as a quasi-drug in Japan and launched there on September 3, 2025. A challenger to Dr.G therefore faces a multinational brand owner, while matching SENSAI's quasi-drug positioning calls for attention to Japan's product classification.
Kao reported 6.7% like-for-like sales growth in its global Cosmetics Business in H1 2026, with volume up 5.9% and price up 0.8% year over year. Its Asian cosmetics sales increased substantially, led by China, where initiatives to strengthen the earnings base progressed. In Thailand, efforts focused on nurturing KATE and KANEBO prestige skincare and makeup. For competitors, the country distinction matters because differentiation against named brands addresses the Thai initiatives, while the stated China program places greater emphasis on the economics supporting the business.
Travel-retail execution adds another competitive route, linking a beauty supplier's results to retailer economics as well as consumer traffic. The Estée Lauder Companies reported FY2026 Asia/Pacific net sales of USD 3.75 billion, including travel retail, up 4% on both a reported and organic basis.[2] The company attributed regional growth primarily to Asia travel retail. Growth in Hainan reflected improved retail traffic and consumer sentiment. Retailer moves toward more profitable duty-free models in Korea and Hong Kong SAR helped reduce discounting, so Estée Lauder's Asia travel retail growth depended partly on its retail partners' decisions.
Asia-Pacific Beauty and Personal Care Products Industry Leaders
-
L'Oréal SA
-
Shiseido Co., Ltd.
-
Unilever PLC
-
The Estée Lauder Companies Inc.
-
Kao Corporation
- *Disclaimer: Major Players sorted in no particular order
Asia-Pacific Beauty and Personal Care Products Market Companies Covered in this Report
- L'Oréal SA
- Shiseido Co., Ltd.
- Unilever PLC
- The Estée Lauder Companies Inc.
- Kao Corporation
- Amorepacific Group
- The Procter & Gamble Company
- Beiersdorf AG
- LG Household & Health Care Ltd.
- Kenvue, Inc.
- Coty Inc.
- The Colgate-Palmolive Company
- Henkel AG & Co. KGaA
- Natura Cosméticos S.A.
- Revlon Group Holdings LLC
- Chanel SA
- LVMH Moët Hennessy Louis Vuitton
- Clarins Groupe
- Colorbar Cosmetics Pvt. Ltd.
- Honasa Consumer Ltd
Read Analysis of Asia-Pacific Beauty and Personal Care Products Companies
Key Opportunities for Market Participants
These opportunities compare product-entry and development choices for cosmetics suppliers serving China and Indonesia. Indonesia's PP 42/2024 includes cosmetics in its halal-certification requirement, and the transition period ended on October 17, 2026.[3] Products made from materials prohibited under halal rules are exempt from certification and must carry a non-halal statement. For cosmetics suppliers entering Indonesia, the materials used therefore determine whether entry preparation centers on halal certification or the required non-halal statement.
Market Opportunities Table of Asia-Pacific Beauty and Personal Care Products Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Imported cosmetics using electronic labels in Shanghai | Pudong pilot began May 11, 2026, within a 3-year national trial from February 1, 2026 | Buyers of imported cosmetics in Shanghai | Selected participants can develop compliant product ranges for the pilot route | Pudong-registered business and Pudong-port import conditions | Selected importers such as Shiseido Co., Ltd. and Chanel SA |
| China-first international cosmetics ranges | November 2025 NMPA Opinions announced a conditional exemption from manufacturing-country marketing-authorization documents | Buyers of international cosmetics first launched in China | Plan a China-first debut for products manufactured specifically for export to China | Aligning the first-launch sequence and China-specific export manufacture | International cosmetics manufacturers meeting the conditions |
| Cosmetics developed for older consumers | November 2025 NMPA Opinions encouraged age-specific R&D and registration | Older cosmetics consumers in China | Develop a range around the intended older buyer's needs | Age-specific formulation development | Cosmetics developers serving older consumers |
| Certification-ready cosmetics for Indonesia | Cosmetics entry is subject to the post-transition certification framework | Cosmetics buyers in Indonesia | Prepare certified ranges under the applicable requirements | Meeting applicable halal-certification requirements | Cosmetics manufacturers able to meet certification requirements |
| Source: Mordor Intelligence | |||||
International manufacturers have an opening to organize a product's first launch in China under the announced document exemption. Eligibility ties that choice to manufacture specifically for export to China, linking launch sequence and production planning. The announced relief best fits a China-focused range whose first launch and export manufacture can be planned together under those eligibility conditions.
Recent Industry Developments in Asia-Pacific Beauty and Personal Care Products Market
- Oct 2026: Kao Corporation launched Kanebo Cosmetics' SENSAI ULTIMATE THE FOUNDATION in Japan on October 7, using new Flash EmulDiffusion Technology to combine makeup finish with skincare benefits.
- Sep 2026: Nykaa and BOLD, L'Oréal's corporate venture fund, announced a collaboration to take financial minority stakes jointly in emerging Indian beauty and personal care brands, with founders retaining control.
Asia-Pacific Beauty and Personal Care Products Market Report Scope and Research Methodology
Market Definition and Coverage
The Asia-Pacific beauty and personal care products market measures annual spending on personal care products and cosmetics and make-up products sold to consumers across Asia-Pacific. The value reflects retail sales of finished products, classified by category, ingredient type, distribution channel, and country.
Scope exclusions: Separately sold raw ingredients and formulation inputs, personal care appliances and beauty devices sold separately, salon, spa, and other beauty or personal care services, and finished product sales to consumers outside Asia-Pacific are excluded.
Segments Covered in This Report
- By Product Type
- Personal Care Products
- Hair Care
- Shampoo
- Conditioner
- Hair Colourant
- Hair Styling Products
- Others
- Skin Care
- Facial Care Products
- Body Care Products
- Lip and Nail Care Products
- Bath and Shower
- Shower Gels
- Soaps
- Others
- Oral Care
- Toothbrush
- Toothpaste
- Mouthwashes and Rinses
- Others
- Men's Grooming Products
- Deodorants and Antiperspirants
- Perfumes and Fragrances
- Hair Care
- Cosmetics/Make-up Products
- Facial Cosmetics
- Eye Cosmetics
- Lip and Nail Make-up Products
- Personal Care Products
- By Category
- Premium Products
- Mass Products
- By Ingredient Type
- Natural and Organic
- Conventional/Synthetic
- By Distribution Channel
- Health & Beauty Stores
- Supermarkets/Hypermarkets
- Online Retail Stores
- Other Channels
- By Geography
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
Data Sources, Market Sizing, and Validation
Desk Research
Official sources such as the National Bureau of Statistics of China's 2025 retail series, India's National Statistics Office household consumption survey reported by the Press Information Bureau, Singapore's Health Sciences Authority guidance on the ASEAN Cosmetic Directive, and ASEAN product-category schedules help anchor country demand, household spending context, product boundaries, and regulatory comparability. These sources anchor country retail trends, household spending patterns, product definitions and regulatory classifications used to build and cross-check the regional estimate.
Company annual reports and investor disclosures can test regional and product mix against retail indicators, while reputable trade reporting can clarify changes in premium positioning, online retail, and country entry rules. The named sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
The primary-research design uses structured interviews and targeted surveys with Asia-Pacific brand and manufacturer executives, category and channel leaders, importers, distributors, and retail buyers. Respondents examine secondary findings on product classification, retail price realization, channel mix, country demand, and regulatory effects, while analysts record conflicting evidence by topic and seek clarification from relevant respondents. Analysts reconcile those accounts with published market signals and company disclosures, document unresolved gaps, and triangulate evidence before using it in the estimate.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The top-down model estimates Asia-Pacific consumer retail spending on finished personal care and cosmetics or make-up products, then allocates value across country, product type, category, ingredient type, and distribution channel. Country retail sales and household spending indicate demand scale, disposable income and population trends inform purchasing capacity, online and specialist-channel penetration indicate where sales occur, and company disclosures and retail price and unit evidence help test changes in product and price mix. After analysts build segment shares from retail and company sales evidence, product classifications, and channel indicators, they reconcile them to the regional total. Sampled average retail price times unit volume and selected company or channel roll-ups provide selective bottom-up checks. The 2027-2032 value forecast can use multivariate regression for relationships among retail demand, income, population, channel penetration, and price mix, with scenario analysis for material shifts in regulation, input costs, or consumer trade-down. Primary experts can test whether variable directions and country assumptions fit operating conditions. Where a country series or sampled supplier and channel check is incomplete, analysts use the strongest corroborating public indicators, record the gap, and avoid treating unsupported detail as a precise segment estimate.
Data Validation & Update Cycle
Analysts triangulate national retail and household indicators, company disclosures, customs and channel evidence, and respondent checks, then test country and segment totals for arithmetic consistency, outliers, and unexplained variance against independent signals. A second review traces material anomalies to source definitions or periods before sign-off, and relevant respondents are re-contacted when a conflict, classification change, or material regulatory or commercial event could alter an estimate. The model is refreshed annually, updated between cycles for material events, and reviewed again in a fresh pre-delivery pass.
Mordor Intelligence's Asia Pacific Beauty and Personal Care Products Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Asia-Pacific beauty and personal care products market measures annual spending on personal care products and cosmetics and make-up products sold to consumers across Asia-Pacific.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. After analysts build segment shares from retail and company sales evidence, product classifications, and channel indicators, they reconcile them to the regional total.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 169.5 B (2027) | |
| Global Consultancy A | USD 237.8 B (2026) | At its 2026 base, this estimate is 40.3% above this report's 2027 value of USD 169.5 B, 1 year later. Its stated customer types include professional salons and dermatology clinics, with professional-grade products supplied through B2B channels beyond consumer final sales. |
| Regional Consultancy B | USD 145 B (2025) | At its 2025 base, this estimate is 14.4% below this report's 2027 value of USD 169.5 B, 2 years later. Its stated retail basket is a narrower cosmetics set, and its country coverage is limited to the listed Asia-Pacific markets. |
Mordor Intelligence's analysts triangulate national retail and household indicators, company disclosures, customs and channel evidence, and respondent checks, then test country and segment totals for arithmetic consistency, outliers, and unexplained variance against independent signals.
Key Questions Answered in the Report
What is the Asia-Pacific beauty and personal care products market size and growth outlook?
From USD 159.3 billion in 2026, size is expected to reach USD 169.5 billion in 2027 and USD 228.7 billion by 2032, at 6.18% CAGR over 2027-2032.
What supports beauty and personal care demand across Asia-Pacific?
Care-focused skincare purchasing, social-media engagement, and male makeup participation support demand. Shiseido reported double-digit growth in Elixir's 2025 Japan sales value, based on customer purchasing behavior.
Which beauty and personal care product type leads in Asia-Pacific?
Personal care products held 84.96% of the market in 2026. Cosmetics/makeup products are forecast to grow fastest at 7.3% CAGR over 2027-2032.
Which companies are major Asia-Pacific beauty and personal care suppliers?
Major companies include L'Oréal SA, Shiseido Co., Ltd., Unilever PLC, The Estée Lauder Companies Inc., and Kao Corporation.
What constrains the outlook for Asia-Pacific cosmetics suppliers?
India requires pre-import cosmetics registration covering products, pack sizes, variants, and manufacturing premises. That makes assortment breadth a compliance task before market entry.
Which Asia-Pacific country has the strongest beauty and personal care growth outlook?
Indonesia is forecast to grow fastest at 8.15% CAGR over 2027-2032, while China held the largest share at 40.2% in 2026.