
United Arab Emirates Data Center Networking Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
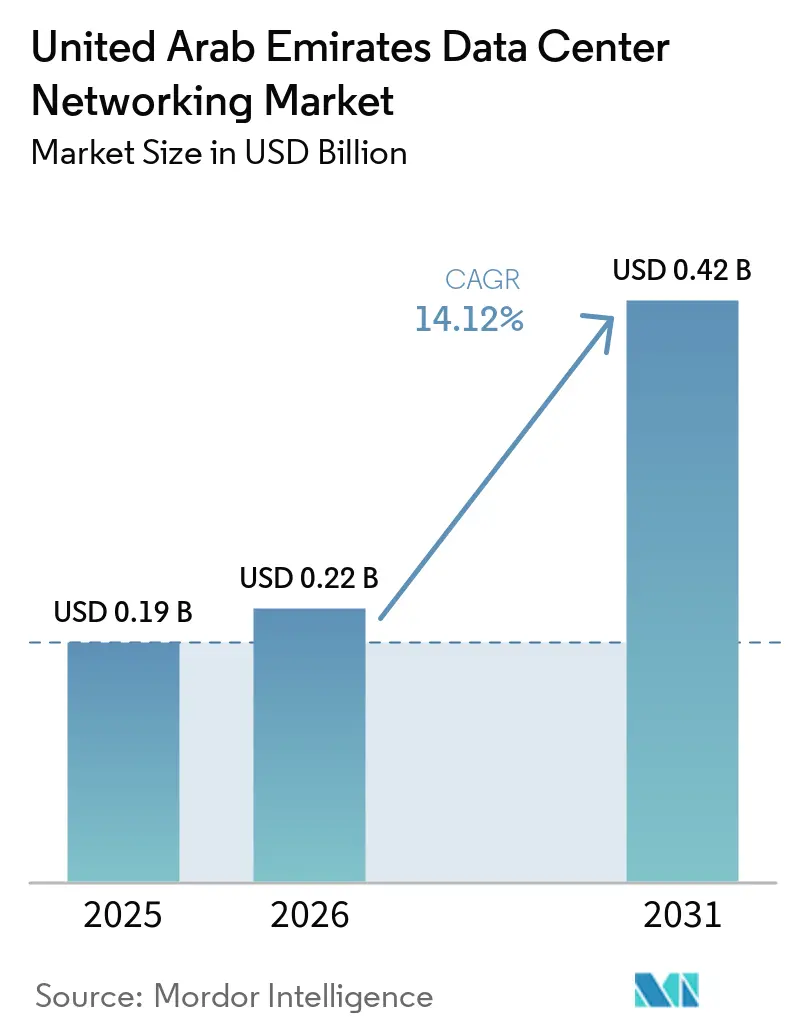
| Base Year Market Size (2025) | USD 0.19 Billion |
| Market Size (2026) | USD 0.22 Billion |
| Market Size (2031) | USD 0.42 Billion |
| Growth Rate (2026 - 2031) | 14.12 % |
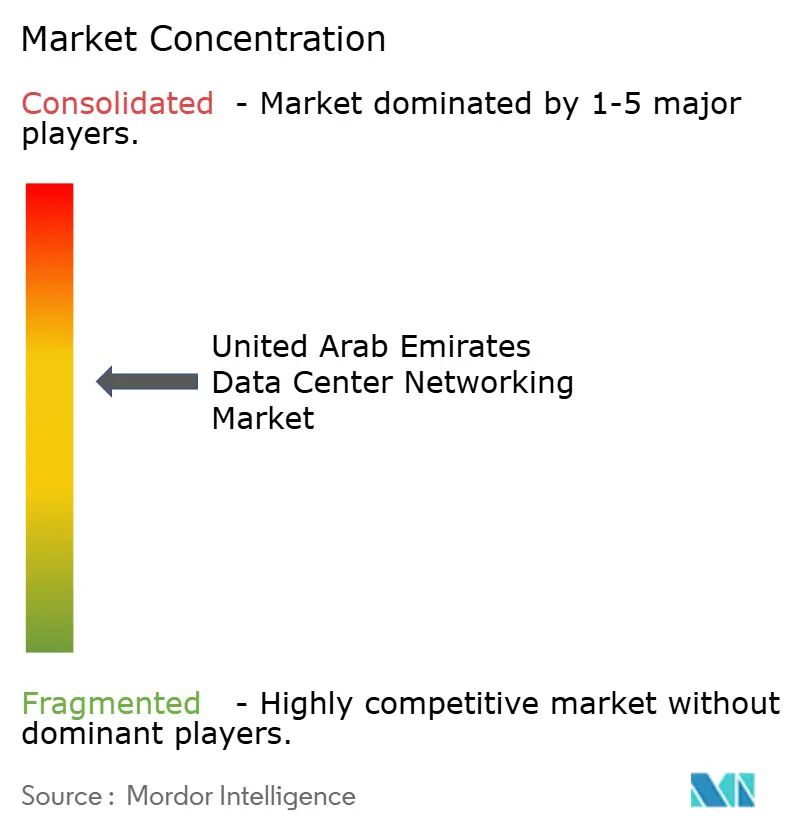
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
United Arab Emirates Data Center Networking Market Analysis by Mordor Intelligence
The UAE data center networking market size was valued at USD 0.19 billion in 2025 and estimated to grow from USD 0.22 billion in 2026 to reach USD 0.42 billion by 2031, at a CAGR of 14.12% during the forecast period (2026-2031). This rapid expansion stems from AI‐centric infrastructure projects, government digital-transformation programs, and the country’s role as a Middle East connectivity gateway. Hyperscale investors are committing multi-billion-dollar budgets to build large-footprint, AI-ready campuses, while nationwide 5G coverage accelerates edge-to-core traffic growth. Public-sector modernization mandates spur cloud migration and software-defined networking adoption, and the arrival of new submarine cables at Fujairah reinforces ultra-low-latency international routes. Strong demand for 400 G and 800 G switching fabrics, coupled with liquid-cooling innovations that address the desert climate, further amplifies capital spending across the UAE data center networking market. Strategic vendor alliances, such as G42’s Stargate UAE collaboration with Nvidia, Oracle, Cisco, and OpenAI, signal a sustained pipeline of large projects that will keep competitive pressure high through the forecast window.
Key Report Takeaways
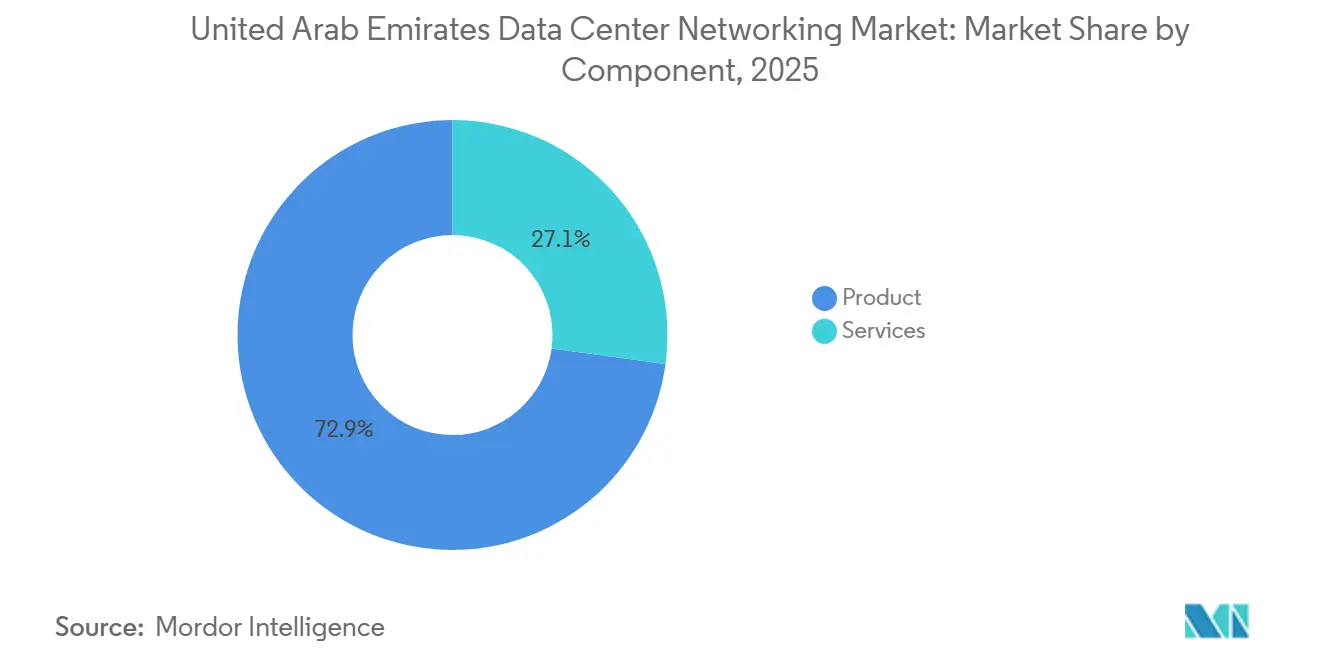
- By component, products led with 72.85% of the UAE data center networking market share in 2025, while services are projected to grow at a 14.32% CAGR through 2031.
- By end-user, IT and telecommunications accounted for 35.05% revenue share in 2025; manufacturing and industrial applications are forecast to expand at a 14.72% CAGR to 2031.
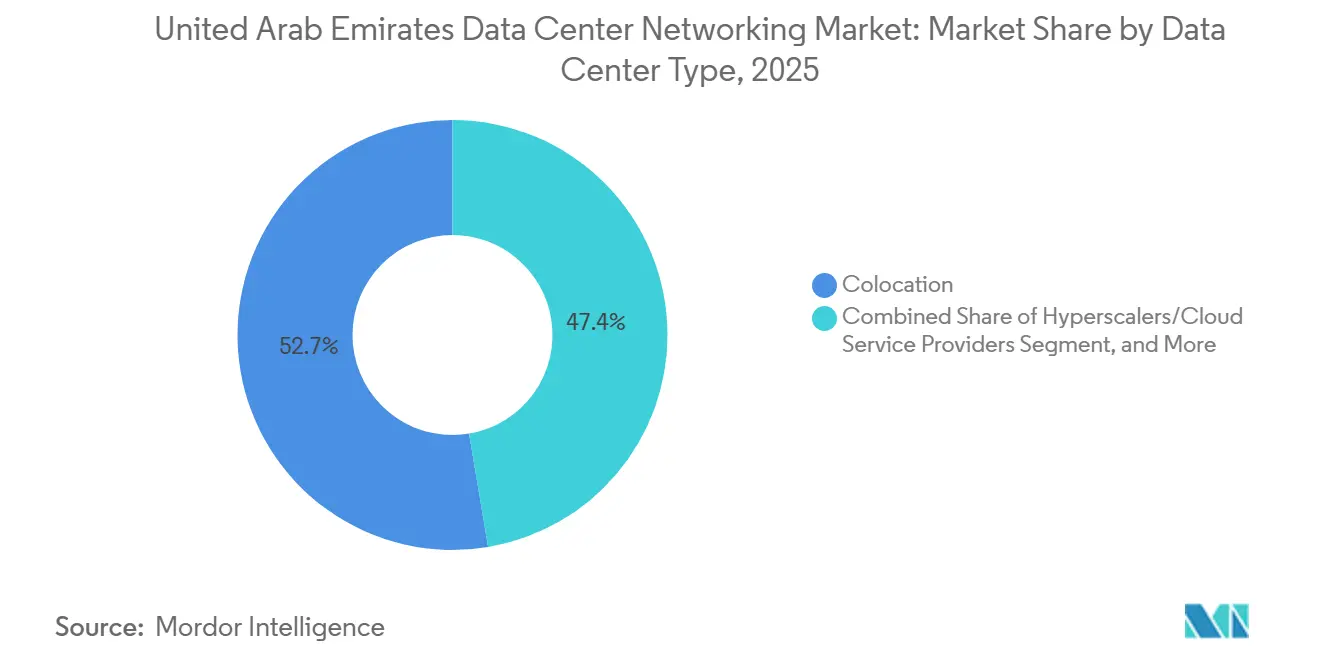
- By data-center type, colocation facilities held 52.65% of the UAE data center networking market size in 2025, whereas hyperscaler deployments are set to grow at a 15.88% CAGR during the same period.
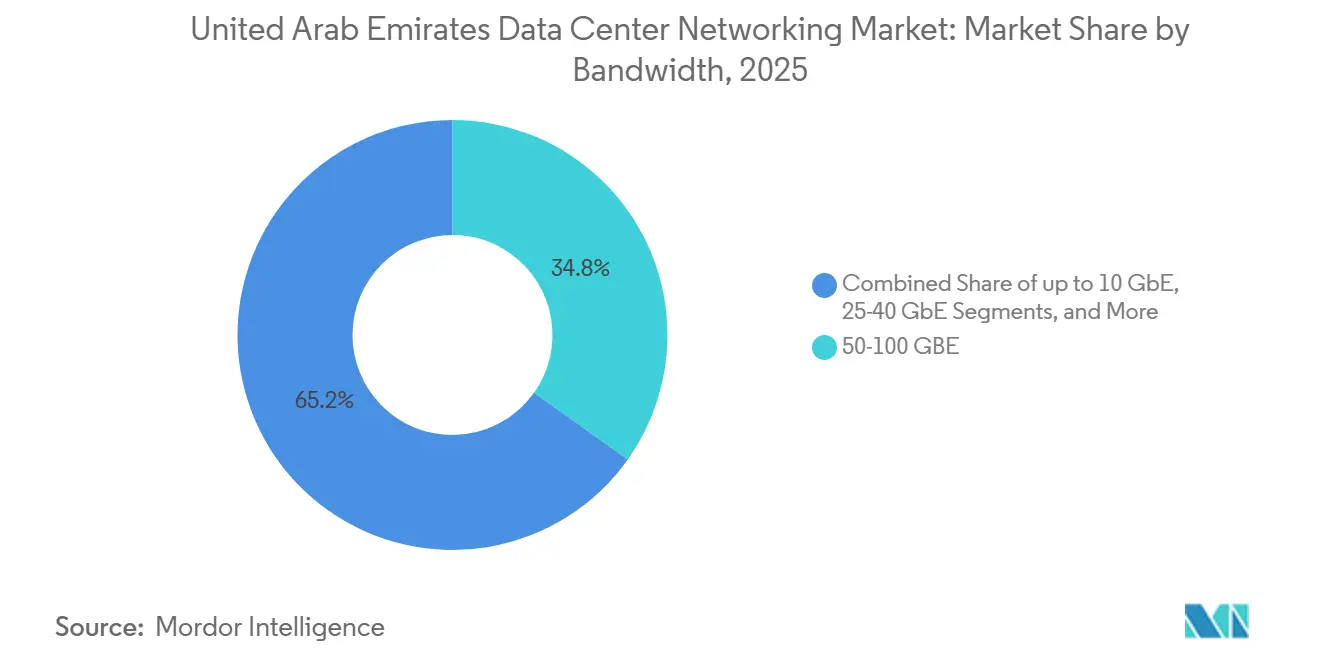
- By bandwidth, 50-100 GbE implementations captured 34.82% of the UAE data center networking market size in 2025; the Aaove 100 GbE segment is advancing at a 15.02% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
United Arab Emirates Data Center Networking Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing hyperscale data-center build-outs | +4.2% | Dubai, Abu Dhabi core with spillover to Northern Emirates | Medium term (2-4 years) |
| Rapid 5G roll-outs boosting edge-data-center interconnect demand | +3.1% | Nationwide, earliest in Dubai, Abu Dhabi, Sharjah | Short term (≤ 2 years) |
| Government-led digital-transformation programs | +2.8% | National, concentrated in major emirates | Long term (≥ 4 years) |
| Shift toward software-defined and virtualised networking | +2.3% | Global adoption with UAE early implementation | Medium term (2-4 years) |
| New submarine-cable landings at Fujairah | +1.1% | Fujairah core with nationwide benefits | Long term (≥ 4 years) |
| Adoption of liquid-cooling-ready switching hardware | +0.8% | National, notably Abu Dhabi and Dubai | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Growing hyperscale data-center build-outs in Dubai and Abu Dhabi
Intensive capital flows into hyperscale campuses are driving the most substantial uplift in network equipment demand. Khazna Data Centers, majority-owned by G42, announced a 100-megawatt AI-ready site in Ajman, while Microsoft partnered with du on a USD 544 million hyperscale facility that expands du’s five-site footprint. International investors, including Silver Lake and MGX, acquired a 40% stake in Khazna for USD 2.2 billion, validating the growth outlook. Large-scale deployments require ultra-dense switching fabrics, 400 G optics, and robust interconnection to regional Internet exchanges, reinforcing the adoption of advanced data-center networking topologies.
Rapid 5G roll-outs boosting edge-data-center interconnect demand
Nationwide 5G coverage fuels edge-computing uptake and prompts operators to deploy regional micro-data centers. e& achieved record 5G throughput of 30.5 Gbps via carrier aggregation, showcasing the network’s ability to sustain data-intensive applications e&. du activated a commercial 5G Standalone network with slicing capability for differentiated enterprise workloads. These milestones propel demand for low-latency backhaul links between far-edge locations and core facilities, accelerating the shift toward software-defined wide-area networking across the UAE data center networking market.
Government-led digital-transformation programs (Smart Dubai, UAE Vision 2031)
Public-sector strategies require near-universal digital service availability, leading ministries and municipalities to refresh underlying network fabrics. Smart Dubai’s portfolio of 130 digital initiatives, including Dubai Pulse, generates persistent demand for scalable, secure connectivity.[1]Digital Dubai, “Smart Dubai Initiatives,” digitaldubai.ae The UAE Ministry of Health deployed Fortinet SD-WAN across 160 sites to unify clinical data exchange, illustrating how agency-level roll-outs cascade into multi-million-dollar infrastructure contracts. Commitments to net-zero emissions by 2050 also incentivize energy-efficient switches and liquid-cooling solutions.
Adoption of liquid-cooling-ready switching hardware for desert-climate efficiency
Ambient temperatures surpassing 45 °C make air-only cooling impractical for high-density racks. Immersion techniques can cut energy consumption by 50% and raise rack power budgets above 250 kW, ensuring reliable operation for AI clusters.[2]IEEE Spectrum, “Immersion Cooling Cuts Datacenter Energy,” spectrum.ieee.org Vendors designing switches with integrated liquid manifolds gain a competitive edge as operators pursue aggressive power-usage-effectiveness (PUE) targets.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shortage of certified data-center network engineers | -1.8% | Nationwide, acute in Dubai and Abu Dhabi | Short term (≤ 2 years) |
| High upfront capex for next-gen 400 G+ switching fabrics | -1.4% | Global impact with UAE early adoption challenges | Medium term (2-4 years) |
| Import duties and long lead-times for specialised networking gear | -1.1% | National, all emirates | Medium term (2-4 years) |
| Data-localisation and cyber-residency rules delaying public-cloud fabrics | -0.9% | National, DIFC, and ADGM exemptions | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Import duties and long lead-times for specialised networking gear
Customs clearance adds administrative steps for AI-optimized switches, and semiconductor shortages extend delivery windows beyond six months for certain line cards. Operators consequently maintain larger inventory buffers, which ties up capital and increases total cost of ownership.
Data-localisation and cyber-residency rules delaying public-cloud fabrics
Federal Decree-Law 45 of 2021 mandates in-country storage of sensitive datasets, compelling cloud providers to re-architect global footprints.[3]Federal Decree-Law 45 (2021) Text, u.ae Certification of multi-zone regions under differing free-zone regulations lengthens deployment roadmaps and tempers near-term equipment imports, though the regulation simultaneously creates domestic build-out opportunities in the longer term.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Component: Product-centric spending remains dominant
Products accounted for 72.85% of the UAE data center networking market in 2025 as operators raced to install high-capacity switches, routers, and optical links needed for AI cluster backbones. Ethernet switches alone consumed a major portion of capex, particularly 400 G leaf-spine designs that reduce east-west latency. Optical interconnects have also advanced, driven by nationwide backbones interlinking hyperscale sites in Dubai and Abu Dhabi. Services, although smaller, are growing at a 14.32% CAGR. Integration, optimization, and managed SDN offerings gain traction as enterprises outsource complex configuration tasks to specialist partners equipped with AI-aware network analytics.
Service growth reflects a shortage of in-house network engineers and the need for continuous tuning of AI pipelines. Managed service providers bundle software updates, telemetry, and remote troubleshooting, converting one-time hardware engagements into recurring revenue streams. This evolution increases lifetime customer value in the UAE data center networking market and fosters ecosystem partnerships between global OEMs and local integrators.


By End-User: Manufacturing emerges as fastest riser
IT and telecommunications retained 35.05% of the UAE data center networking market share in 2025, mirroring telco core upgrades and cloud availability-zone roll-outs. Banking, financial services, and insurance segments follow, investing in low-latency fabrics to secure trading and payment platforms. Manufacturing and industrial enterprises, however, pace the CAGR leaderboard at 14.72% through 2031. Emirates Global Aluminium’s Industry 4.0 lighthouse designation highlights the heavy-industry shift toward real-time analytics and predictive maintenance, which require deterministic networking inside smart factories.
Healthcare also accelerates, as the Malaffi Health Information Exchange links 1.7 billion records across clinical sites. Cross-vertical dynamics underscore a broader pivot toward distributed intelligence at the plant floor and in hospitals. As each sector digitizes workflows, demand cascades down the stack for secure, high-bandwidth connections into centralized analytics clusters. These trends reinforce the multi-tenant growth story of the UAE data center networking market.
By Data-Center Type: Hyperscalers narrow the gap
Colocation providers commanded 52.65% of the UAE data center networking market size in 2025 thanks to carrier-neutral neutrality and rapid provisioning. Yet hyperscaler self-builds are growing at a 15.88% CAGR, shifting share as global cloud giants prioritize sovereign capacity. Dedicated campuses such as Microsoft’s facility offer deterministic performance for AI training while satisfying data-residency rules.
Edge and micro centers add another layer, supplying base-station proximity for 5G network slicing. Operators design hybrid interconnect fabrics that stitch edge locations to metro core nodes and on to hyperscale regions. Liquid-cooled switches inside AI pods feed high-density GPUs, while SD-WAN overlays extend policy control into micro-edge enclosures the size of a shipping container. The architecture diversification supports continued expansion of the UAE data center networking market.
By Bandwidth: 100 G+ becomes the new mainstream
Deployments in the 50-100 GbE tier held 34.82% of 2025 shipments as enterprises refreshed long-lived 10/25 G links. Nevertheless, Above 100 GbE installations are climbing at a 15.02% CAGR as operators embrace 400 G and beyond for AI cluster interconnect. Trials of 1.6 Tbps optical lanes by e& foreshadow a future where bandwidth doubles every hardware cycle. Edge nodes still leverage up to 10 GbE for sensor traffic, while 25-40 GbE uplinks bridge legacy server racks to new leaf fabrics.
Steady price declines in PAM4 optics narrow the cost delta between 100 G and 400 G ports, encouraging early adopters to leapfrog intermediate speeds. Disaggregated chassis with modular line cards allow gradual scale-out, limiting stranded capacity risks and bolstering the long-run outlook for the UAE data center networking market.
Geography Analysis
Dubai and Abu Dhabi anchor the nation’s 52 operational data centers, jointly delivering most of the 235 MW live capacity. Expansion plans add 343 MW, with Ajman emerging as a supplementary AI cluster location. Dubai’s early foundation, set by Dubai Internet City, offers dense carrier ecosystems and favorable free-zone incentives. Abu Dhabi leverages sovereign wealth backing and abundant land for mega-campuses such as Stargate UAE, slated for 5 GW over multiple phases. Fujairah’s cable-landing stations integrate international traffic, routing east-west fiber paths that lower latency for cross-continental workloads.
Northern emirates witness spill-over as power-price differentials and land-bank availability attract secondary builds. The national energy mix, featuring nuclear at Barakah and solar at Mohammed bin Rashid Al Maktoum Solar Park, helps operators meet carbon targets while containing operating costs. Federal data-sovereignty laws create a must-build environment for multinational clouds, cementing domestic capacity additions rather than remote serving. The ascending capital curve in neighboring Saudi Arabia and Qatar intensifies regional rivalry, but the UAE’s regulatory clarity and diversified power sources sustain its competitive edge.
Regulatory Landscape
The UAE data center networking environment is shaped by national privacy and cybersecurity compliance, led by Federal Decree-Law No. 45 of 2021 on personal data protection and security frameworks applied to critical ICT infrastructure. Operators and tenants commonly align controls to the National Information Assurance Framework (NIAF) and Critical Information Infrastructure Protection (CIIP) requirements under the National Electronic Security Authority (NESA), which lifts the need for network segmentation, monitoring, and secure interconnect designs across colocation and hyperscale builds.
Connectivity and resiliency expectations also flow from the Telecommunications and Digital Government Regulatory Authority (TDRA), including requirements that influence dual connectivity and infrastructure redundancy in telecom-linked facilities. In parallel, regulatory differentiation in financial and digital free zones (DIFC and ADGM) shapes governance choices for cloud and interconnection architectures, while sector-specific data residency obligations in areas such as financial services and healthcare reinforce in-country hosting and drive incremental investment in domestic switching, routing, and security appliances.
Value Chain Analysis
The UAE data center networking value chain covers global hardware and software vendors (switching, routing, optical, SDN, and security), local distributors and system integrators, and data center operators and cloud and AI platforms that specify high-density fabrics for AI workloads. At the demand and financing layers, hyperscale and AI-led build-outs draw on domestic digital infrastructure champions and large investors, while public-sector programs and sovereign-grade requirements pull through additional spend on secure network design, policy automation, and managed services.
On the delivery side, project execution depends on an interconnected set of free-zone developers and industrial partners, alongside power and facilities specialists. Recent AI-ready campus initiatives in Dubai Silicon Oasis and large Abu Dhabi AI programs highlight the role of integrated power, cooling, and controls partners alongside networking OEMs, as well as workforce development tie-ins, including the Ministry of Energy and Infrastructure engagement with 42 Abu Dhabi, to reduce deployment bottlenecks from skills shortages in advanced data center networking.
Competitive Landscape
The vendor arena blends global switch and router manufacturers, regional integrators, and emerging cloud-native software suppliers. G42 and Etisalat formed Khazna Data Centers, consolidating carrier-neutral colocation assets and elevating domestic scale. Silver Lake and MGX’s USD 2.2 billion minority stake underscores international appetite for UAE digital infrastructure. Arista Networks surpassed Cisco in global data-center switch share in Q4 2023, a signal that open-standards platforms resonate with AI-focused operators. Broadcom’s merchant silicon roadmap and Nvidia’s Mellanox interconnect technologies penetrate switching line-cards destined for AI clusters.
Strategic moves include Nokia’s acquisition of Infinera to fortify an optical super-division with SDN-ready coherent pluggables, and Qualcomm’s partnership with e& to seed edge-AI gateways. Local system integrators bolt specialized services onto hardware from these majors, filling skills gaps in deployment and supporting the UAE data center networking industry shift toward automation. Vendors that can combine energy-efficient designs, desert-rated cooling, and AI flow-aware telemetry are positioned to win upcoming tenders.
United Arab Emirates Data Center Networking Industry Leaders
Cisco Systems Inc.
VMware Inc.
Fujitsu Ltd.
Schneider Electric
Eaton Corp.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
AI-centric campus construction and sovereign compute programs create clear whitespace for high-bandwidth switching, optical interconnects, and secure multi-tenant fabrics that can scale beyond 100 GbE. Stargate UAE in Abu Dhabi is positioned as a 5 GW multi-phase AI campus, and public reporting indicates its first phase targets 200 MW completion in Q3 2026, concentrating near-term demand for leaf-spine architectures, coherent optics, and segmentation and security stacks designed for GPU clusters.
Government-backed planning and private investment also widen the opportunity set for vendors and integrators focused on shortening time-to-deploy and improving energy efficiency in harsh climate conditions. In June 2026, the Ministry of Energy and Infrastructure launched the National Data Center Observatory to identify and evaluate locations for data center development, pointing to a more structured pipeline of sites that will need metro-to-core connectivity. Microsoft has also communicated a USD 15.2 billion investment program in the UAE through 2029 to accelerate AI innovation and digital growth, reinforcing demand for modern network fabrics that meet data residency and cybersecurity expectations while supporting large-scale cloud and AI workloads.
Recent Industry Developments
- July 2026: e& UAE and Core42 announced a partnership to launch a Sovereign AI Compute platform to provide enterprises and government in-country GPU compute resources. The initiative targets a sovereign AI compute platform for UAE. The collaboration expands in-country AI workloads and data residency support, strengthening UAE sovereign AI infrastructure ecosystem.
- June 2025: G42 (Stargate UAE) unveiled Stargate UAE, a 5 GW AI campus in Abu Dhabi in partnership with Nvidia, Oracle, Cisco, and OpenAI. The project represents an AI-centric infrastructure initiative within the UAE data-center ecosystem. It signals large-scale, multi-vendor AI campus deployment driving regional demand for data-center networking capacity and AI-ready networking architectures.
- May 2025: Qualcomm and e& launched a joint engineering center in Abu Dhabi to develop 5G edge-AI gateways. This development focuses on edge-AI gateway capability for UAE telecommunications and data-center edge networks. It strengthens UAE edge compute integration with telecom and data-center networks, expanding demand for ultra-low-latency interconnects.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the market covers revenue generated in the United Arab Emirates from networking products and related services that enable connectivity inside data centers and between data center environments.
Scope exclusions: We exclude enterprise campus networking that is not deployed for data center networking use cases.
Segmentation Overview
- By Component
- Products
- Ethernet Switches
- Routers
- Storage Area Network (SAN)
- Application Delivery Controllers (ADC)
- Network Security Appliances
- Software-Defined Networking (SDN) Controllers
- Optical Interconnects
- Services
- Installation and Integration
- Training and Consulting
- Support and Maintenance
- Managed Network Services
- Products
- By End-User
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Government and Defense
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End-Users
- By Data-Center Type
- Colocation
- Hyperscalers/Cloud Service Providers
- Edge/Micro Data Centers
- By Bandwidth
- Less than or equal to 10 GbE
- 25-40 GbE
- 50-100 GbE
- Greater than 100 GbE
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts with mapping the UAE data center build-out and connectivity needs, and then linking that demand to networking hardware and service spending. We rely on public sources such as the UAE Telecommunications and Digital Government Regulatory Authority for ICT context, the International Telecommunication Union for traffic and connectivity indicators, the World Bank for macro and investment signals, and UN Comtrade for relevant trade flows tied to network equipment categories.
To make the model practical, we also use company filings and investor presentations to understand capex cycles, refresh patterns, and equipment mix, and then we cross-check those expectations against reputed press and association publications. For specific cross-checks like shipment intensity, technology migration timing, and patent activity, we use paid subscriptions for company financials and intelligence, news and financials, patent databases, and shipment-level import and export visibility. The desk sources listed above are illustrative, and other public and paid references were used during data collection, validation, and clarification.
Primary Interviews and Surveys
We speak with data center operators, network equipment distributors, system integrators, cloud and colocation specialists, and enterprise technology leaders in the United Arab Emirates. Interviews and surveys test equipment replacement cycles, bandwidth needs, realized prices, project timing, and the share of spending assigned to networking. Findings are used to check desk data, fill gaps, and adjust assumptions before final analysis.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 30% | CXOs: 15% |
| Mid tier: 45% | Functional/Unit leaders: 30% |
| Smaller Players: 25% | Managers: 55% |
Market-Sizing & Forecasting
Sizing starts from a top-down reconstruction of UAE data center networking demand, where announced and operational capacity additions, average rack density trends, and expected east-west traffic growth are converted into implied port and interconnect needs. That demand pool is then translated into value using typical device mix and service attach assumptions, followed by careful normalization for timing of deployments across the year.
Results are subsequently corroborated with selective bottom-up approximations, such as sampled ASP times shipment volume checks for key network equipment categories, channel feedback on lead times, and supplier roll-ups where public disclosures allow it. Key inputs used in the model include data center type mix (colocation, hyperscale and edge), bandwidth adoption shares (10 GbE, 25-40 GbE and higher), expansion cadence in active metros, the split between new builds and refresh, and service intensity tied to design and managed operations. Where direct volume visibility is limited, gaps are handled through proxy indicators (trade flow trends and installation timing) and then narrowed through interview-based validation.
Forecasting uses scenario analysis with a multivariate structure, where expected capacity additions, cloud demand signals, and bandwidth migration pace are the main drivers. Assumptions are tuned to what respondents consider realistic procurement and commissioning cycles, which keeps the forward view grounded in UAE project timing rather than generic upgrade curves.
Data Validation & Update Cycle
Model outputs are checked against independent signals like data center pipeline disclosures, import intensity patterns for relevant equipment categories, and observed shifts in common bandwidth standards. When large variances show up, the inputs are rechecked, outliers are explained, and follow-up calls are triggered to confirm whether the change is due to timing, pricing, or project delays.
A multi-step review is applied before sign-off, including internal analyst checks on assumptions, year-over-year movements, and segment totals that must reconcile back to the overall market. Reports are refreshed annually, and interim updates are made when material events change near-term deployments. Before delivery, a fresh analyst pass is completed so the latest public and interview-backed signals are reflected.
Mordor Intelligence's United Arab Data Center Networking Market Estimate Compared With Other Published Estimates
Published market sizes for UAE data center networking can differ because the underlying counting rules are not always the same, even when the titles look similar. Differences usually come from what is included as networking, how services are treated, which year is used as the base, and whether pricing is kept in current USD or normalized.
Enterprise WAN and carrier core network build-outs sit outside Mordor Intelligence's scope here, which tends to lower the number versus estimates that roll in broader telecom infrastructure, and then apply aggressive bandwidth upgrade assumptions without checking data center specific deployment timing.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 0.19 B (2025) | |
| Regional Consultancy A | USD 0.27 B (2025) | Often expands the definition to include broader enterprise and service-provider networking spend beyond data center environments, and then applies uniform upgrade rates that can overstate near-term demand. |
| Industry Association B | USD 0.15 B (2025) | Typically leans on conservative procurement reporting and may undercount services and higher-speed upgrades that are purchased through integrators or bundled delivery models. |
The spread mainly comes down to scope and the way services and upgrade timing are counted. By keeping the demand pool tied to data center environments and then cross-checking with practical deployment signals, the final number stays easier to explain, reproduce, and update as new capacity comes online.


Key Questions Answered in the Report
What is the current value of the UAE data center networking market?
The market stands at USD 0.22 billion in 2026 and is projected to double to USD 0.42 billion by 2031.
Which segment is expanding fastest within the UAE data center networking market?
Hyperscaler data-center deployments are growing at a 15.88% CAGR, outpacing other facility types through 2031.
How are 5G roll-outs influencing UAE data center networking investments?
Nationwide 5G coverage drives demand for edge micro-data centers and low-latency interconnects, accelerating purchases of software-defined wide-area networking solutions and higher-bandwidth backhaul links.
What are the main challenges confronting operators in the UAE data center networking industry?
Skill shortages in certified network engineers, high upfront costs for 400 G+ equipment, import lead-times, and compliance with data-localization laws are the primary hurdles.
Page last updated on:
- Data Center Server Market Servers across the global market, covering tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Data Center Construction Market Construction across the global market, covering tier, facility size and facility type.
- Mexico Data Center Cooling Market Mexico's cooling, split by cooling technology, type and end-user industry.
- United Arab Emirates Data Center Power Market The UAE's power systems, split by component, facility type and facility size.
- UAE Data Center Construction Market The UAE construction, split by tier, facility type and infrastructure.
- Malaysia Artificial Intelligence (AI) Optimised Data Center Market Malaysia AI facilities, split by facility type, component and tier.





