
UAE Construction Market Analysis by Mordor Intelligence
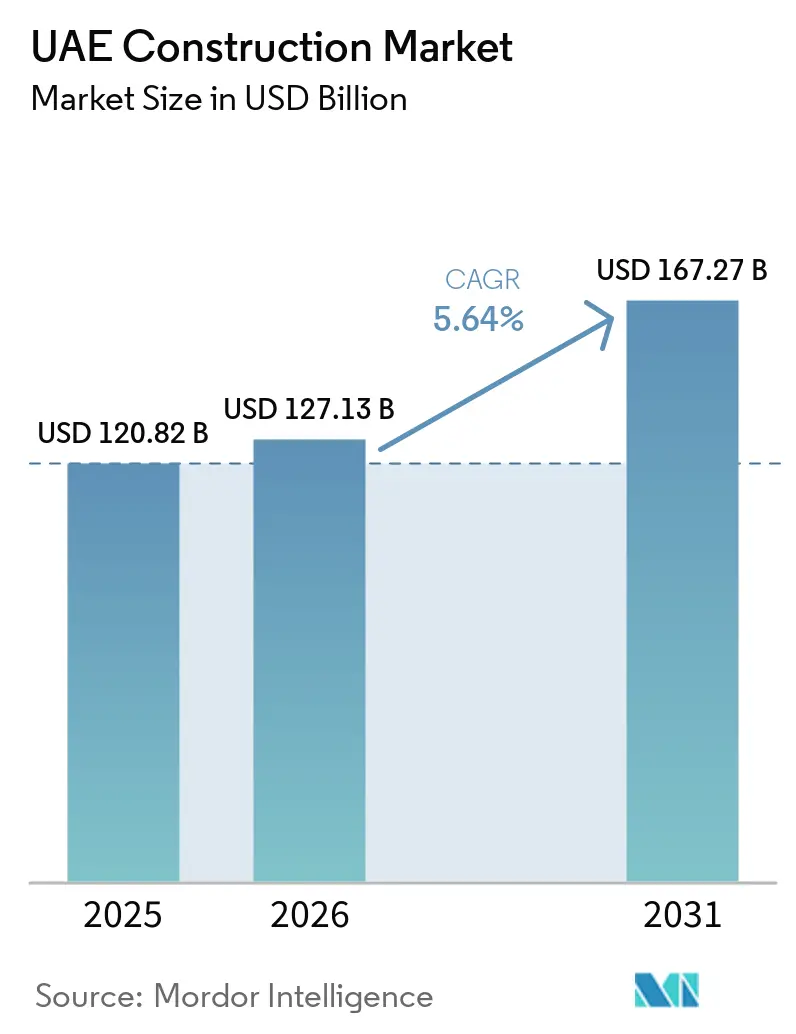
The UAE construction market size was valued at USD 127.1 billion in 2026 and estimated to grow from USD 134.3 billion in 2027 to reach USD 174.9 billion by 2032, at a CAGR of 5.42% during the forecast period (2027-2032).
Community housing, tourism and digital infrastructure sustain demand across the United Arab Emirates, with apartments and data centers requiring different delivery capabilities. Planning frameworks extend project visibility, while specialized building requirements create opportunities for technically focused contractors. Input-price pressure and execution bottlenecks can nevertheless slow the conversion of project pipelines into completed work. Combining office and residential work within a contract increases coordination needs, while modular delivery shifts selected work into factory production. The contest therefore turns on sequencing factory-built components, site works and building systems within the delivery window of an awarded project.
Key Report Takeaways
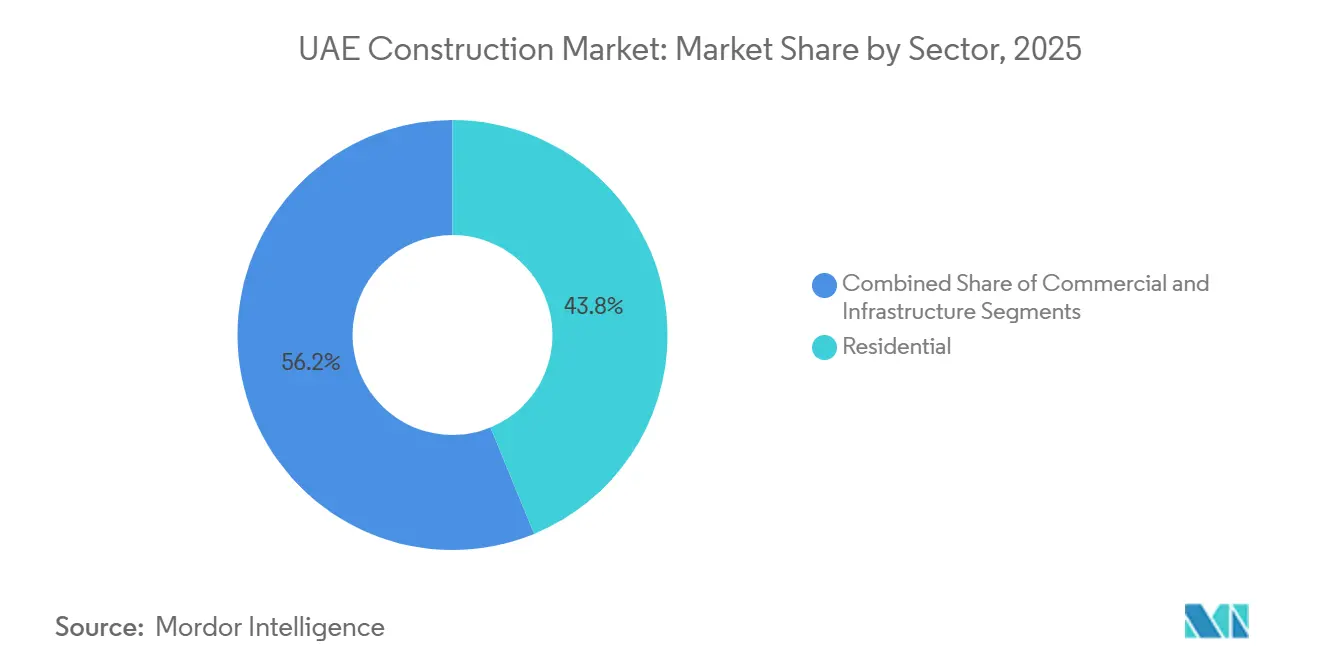
- By sector, residential led with a 43.64% UAE construction market share in 2026, while infrastructure is forecast to grow fastest at a CAGR of 6.05% during 2027-2032.
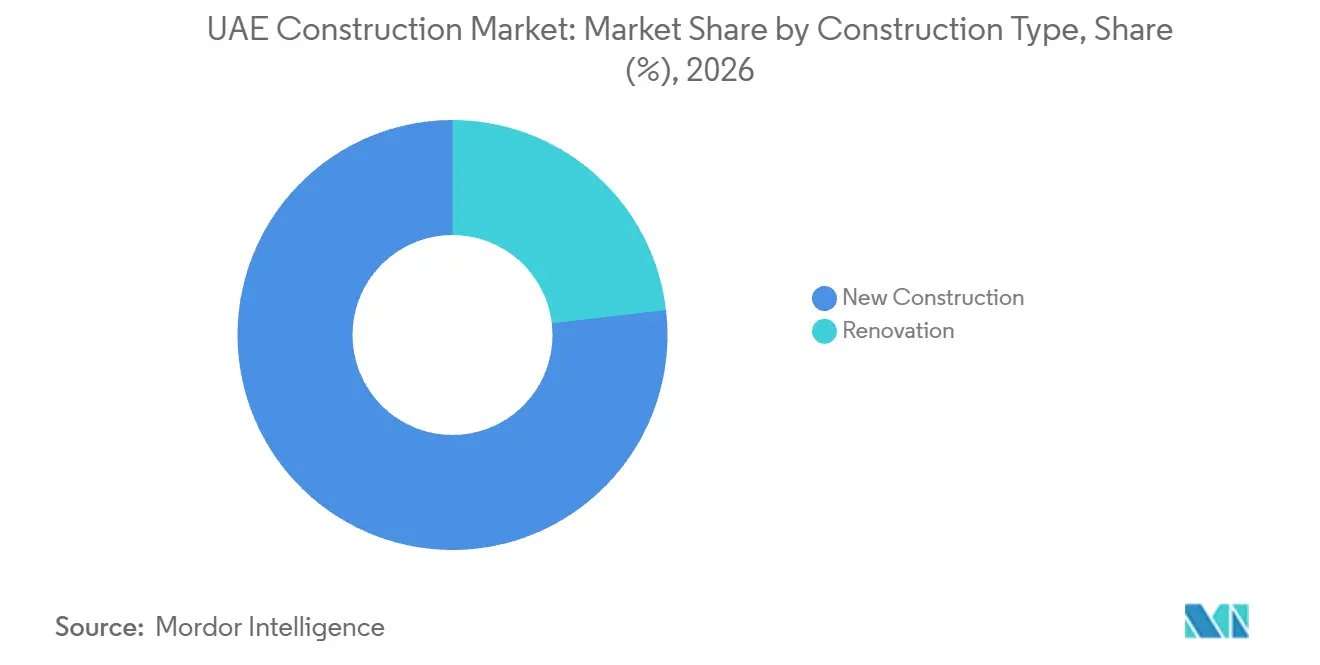
- Among construction types, new construction held a 76.86% share of the UAE construction market size in 2026, with renovation forecast to grow fastest at a CAGR of 5.62% during 2027-2032.
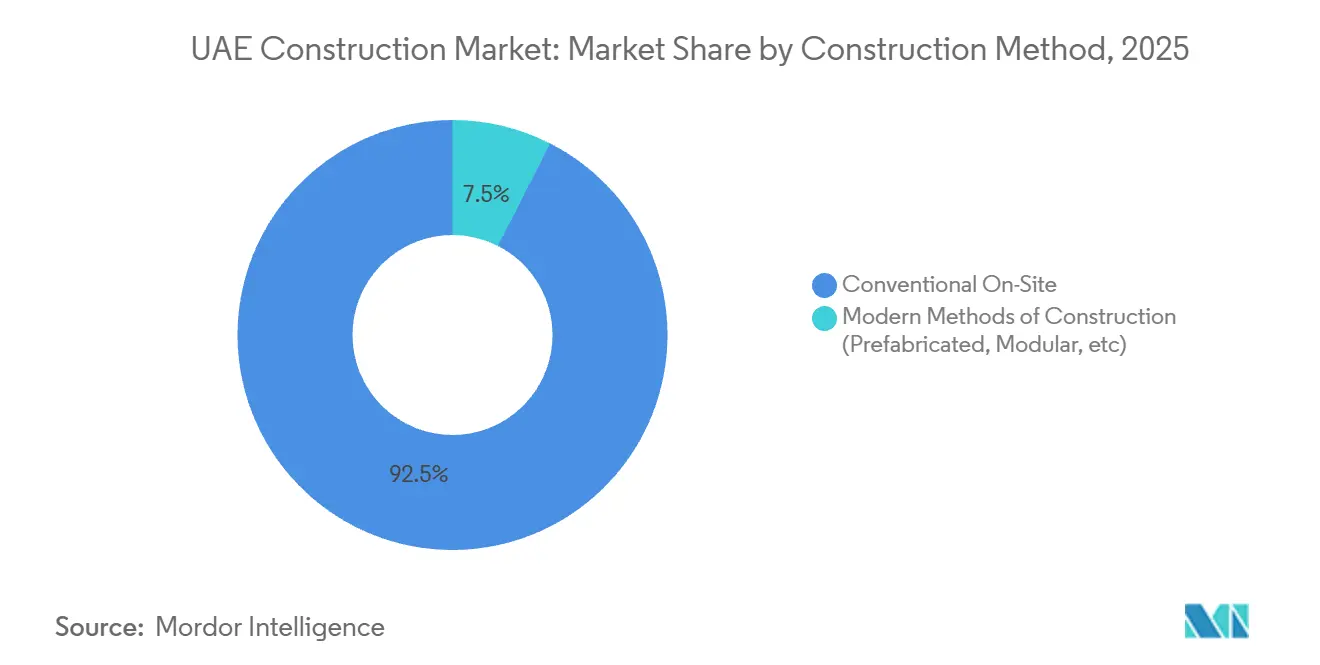
- By construction method, conventional on-site construction led with 92.43% of market value in 2026, whereas modern methods of construction, including prefabricated and modular approaches, are forecast to grow fastest at a CAGR of 6.35% during 2027-2032.
- Private funding led investment sources with 65% of market value in 2026, while public investment is forecast to grow fastest at a CAGR of 5.72% during 2027-2032.
- Across geographies, Sharjah is forecast to grow fastest at a CAGR of 5.8% during 2027-2032, while Dubai led with 47.05% of market value in 2026.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of UAE Construction Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| ‘We the UAE 2031’ vision and emirate master plans (Dubai 2040/Plan Abu Dhabi 2030) anchoring multi-year project pipelines. | +1.7% | Dubai and Abu Dhabi | Long term (≥ 4 years) |
| Tourism, hospitality, and entertainment capex (luxury resorts, theme parks, events) lifting building demand. | +1.3% | Abu Dhabi, Dubai and Ras Al Khaimah | Medium term (2-4 years) |
| Housing and community development—mid-market, BTR, and luxury—supported by strong population and expat inflows. | +1.25% | Dubai residential communities | Medium term (2-4 years) |
| Logistics/industrial and data center growth fueling warehousing, cold chain, and mission-critical builds. | +1.15% | Dubai, Abu Dhabi and Ajman | Medium term (2-4 years) |
| Energy and water programs—solar, hydrogen, grid, desalination, wastewater reuse—expanding civil/utility works. | +0.9% | Dubai utility development areas | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
‘We the UAE 2031’ vision and emirate master plans (Dubai 2040/Plan Abu Dhabi 2030) anchoring multi-year project pipelines.
Long-horizon planning supports construction demand by connecting development permissions with infrastructure needed to serve expanding communities. Launched in 2022, ‘We the UAE 2031’ established a national 10-year development framework, while Plan Abu Dhabi 2030 provides an urban structure framework for the emirate. Dubai Municipality issued 10,776 building permits in Q1 2026, up 12% from Q1 2025. In February 2026, it awarded 5 Phase Two Tasreef contracts worth AED 2.5 billion (USD 0.68 billion), serving 30 areas and an estimated 3 million residents by 2040. Together, the permits and drainage awards connect the building pipeline with planned stormwater capacity, extending construction demand into networks serving Dubai’s expanding communities.
Tourism, hospitality, and entertainment capex (luxury resorts, theme parks, events) lifting building demand.
Tourism construction is expanding through destination programs that combine accommodation with attractions, extending the work available beyond hotel shells. In September 2026, Miral announced planned investment exceeding AED 12 billion (more than USD 3.27 billion) across Yas Island over the following 5 years, including new developments, attraction expansions and additional hotel rooms.[1] This mix creates opportunities for both new-build teams and specialists working within established destinations. Wynn Al Marjan Island topped out its 70-story, 283-meter tower in Ras Al Khaimah in 2025 before entering interior fit-out and façade completion. Wynn’s move from tower structure to fit-out shows how a resort can sustain demand for façade and interior packages after topping out.
Housing and community development—mid-market, BTR, and luxury—supported by strong population and expat inflows.
Dubai Digital reported Dubai’s population at 4.58 million at end-2025, approximately 332,000 above end-2024, using administrative records and digital systems.[2] The larger resident base expands the potential need for housing and associated community facilities. Emaar Development launched 48 residential projects across its UAE communities in 2025, translating developer activity into a broad pipeline of build-to-sell offerings. In February 2025, Aldar announced The Wilds with joint-venture partner Dubai Holding, a planned Dubai community of almost 1,700 homes spanning luxury mansions, villas and apartments. The Wilds’ mixed formats can consequently support different structural and finishing packages within one developer program, widening the work available beyond a single premium building type.
Logistics/industrial and data center growth fueling warehousing, cold chain, and mission-critical builds.
Logistics and digital infrastructure create construction demand around operating requirements rather than floor space alone. In June 2026, DP World and Lintara Properties broke ground on a 20,000-square-meter Jebel Ali Free Zone logistics center, developed by Lintara for DP World to operate, with Q1 2027 completion expected.[3] Its temperature-controlled and dangerous-goods storage requires a different delivery package from an undifferentiated warehouse. RSA Cold Chain opened a multi-temperature facility offering 40,000 pallet positions in the same zone in September 2025. Separately, Microsoft and G42 announced a 200 MW UAE data-center expansion through Khazna in November 2025, with capacity expected to start coming online before end-2026. These distinct workloads broaden opportunities for specialist systems integration, making technical delivery capability a more useful differentiator than warehouse scale alone.
Restraints Impact Analysis of UAE Construction Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Execution capacity constraints and skilled labor shortages amid concurrent mega programs. | -0.42% | Dubai construction project sites | Short term (≤ 2 years) |
| Cost inflation and higher financing costs compressing developer feasibility and contractor margins. | -0.31% | Dubai residential project clusters | Short term (≤ 2 years) |
| Regulatory/permitting complexity and utility tie-in timelines affecting project schedules. | -0.15% | Dubai major development projects | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Execution capacity constraints and skilled labor shortages amid concurrent mega programs.
Execution capacity becomes a commercial constraint when the crews and materials required for a program cannot arrive together. On February 17, 2026, Dubai Municipality reported concrete shortages affecting construction project timelines in Dubai. A disrupted concrete sequence can leave other site resources waiting, making nominal contractor capacity less useful than synchronized delivery. Turner & Townsend’s 2026 report identified emerging specialist-skills shortages in Dubai amid major UAE infrastructure programs and projected them to tighten over the following 12 months. In September 2025, Khansaheb MEP reported that around 330 team members had completed Phase One training since September 2024, covering safety, general MEP knowledge and trade-specific skills. The combined constraints leave contractors exposed to resequencing costs when skilled crews and concrete cannot be scheduled together.
Cost inflation and higher financing costs compressing developer feasibility and contractor margins.
Rising input costs weaken project feasibility when selling commitments and construction obligations cannot adjust together. Supplier prices observed through August 31, 2026, showed UAE cement up 16%, concrete 10% and reinforcement steel 8% from January, according to Currie & Brown research reported by EnterpriseAM. Contractors responded with shorter quotation windows, fluctuation clauses and extension-of-time claims. These responses transfer some uncertainty to developers while making fixed delivery budgets harder to secure. A May 2026 report also described several Dubai developers facing 6-to-9-month handover delays amid input bottlenecks, cost overruns and tighter bank financing. Longer delivery periods can extend financing exposure precisely when material commitments become less predictable, leaving developers with a combined funding and completion risk.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
UAE Construction Market Segment Analysis
By Sector:
Housing Scale and Infrastructure DeliveryResidential accounted for a 43.64% share of the UAE construction market size in 2026. Abu Dhabi’s Department of Municipalities and Transport reported nearly 190,000 planned residential units associated with its 2025 development approvals, spanning new and existing neighborhoods. The plans included more than 158,000 market units and approximately 30,000 homes dedicated to UAE nationals, supported by community amenities. Market units and homes dedicated to UAE nationals form distinct planned streams, making the commissioning model relevant to a residential bid alongside building type.
Infrastructure is the fastest-growing segment, forecast at a CAGR of 6.05% during 2027-2032. Dubai’s Roads and Transport Authority (RTA) awarded the 12-kilometer Latifa bint Hamdan corridor contract in July 2026, including 7 bridges and 8 tunnels. The combination creates linked civil and structural packages whose commercial value depends on coordinating transport interfaces rather than delivering isolated buildings. Infrastructure suppliers consequently face a different competitive test, with network integration and staged delivery shaping access to the expanding workload.

By Construction Type:
New Builds Anchor Workloads as Renovation BroadensNew construction represented a 76.86% UAE construction market share in 2026. Aldar’s 2025 UAE contract awards covered residential communities, infrastructure, commercial and logistics assets, with the projects collectively expected to deliver thousands of new homes. As the contract-awarding developer, Aldar commissions contractors to execute the distinct construction scopes. Because the awards span residential, infrastructure and commercial and logistics assets, contractors reach the new-build workload through separate procurement packages rather than one housing contract.
Renovation is the fastest-growing segment, with a forecast CAGR of 5.62% during 2027-2032. DMDC secured renovation contracts for 4 Palm Jumeirah villas in November 2025, with design, construction and delivery assigned to DMDC. Its partner Residual.ae led the financial and strategic framework and resale process. That structure illustrates how an existing-property project can combine construction services with a distinct investment proposition without requiring a new development site.
By Construction Method:
Site Execution Dominates as Modular Delivery AdvancesConventional on-site construction was the largest segment, accounting for 92.43% of market value in 2026. In 2025, China State Construction Engineering Corporation completed 30 temporary diversion roads for Dubai’s King Salman Street Viaduct and Al Naseem Street Upgrade Project. It also poured the project’s first cast-in-place box girder, marking an initial structural milestone. The example shows why conventional delivery remains relevant where structural work must follow site preparation and traffic-management sequences. Contractor differentiation therefore depends on organizing access and construction stages around a functioning urban setting, rather than simply increasing the amount of labor assigned to a structure.
Modern methods of construction (prefabricated, modular, etc) are the fastest-growing segment, with a forecast CAGR of 6.35% during 2027-2032. BROAD Group completed Eagle Hills’ 16-story Earth Tower in Abu Dhabi in December 2025 using its Holon volumetric modular system. Its 259 modules were manufactured in 30 days and installed on site in 96 hours, separating factory production time from the assembly window. This division shifts more coordination into module design and production before units reach the site. The commercial case for modular specialists therefore rests on controlling the complete production-to-installation sequence, with rapid site assembly representing only one part of the delivery proposition.
By Investment Source:
Private Pipelines and Public Housing ChannelsPrivate investment was the largest segment, accounting for 65% of market value in 2026. Emaar Properties reported more than 50,800 units under construction in its UAE Development business in 2025, including joint ventures. That company pipeline illustrates the scale of work associated with developer-led programs spanning multiple delivery phases. At that scale, a contractor can gain substantial unit exposure through one developer program while retaining concentrated dependence on that client.
Public investment is the fastest-growing segment, with a forecast CAGR of 5.72% during 2027-2032. In September 2026, the Abu Dhabi Housing Authority began booking and purchase for the West Baniyas government housing project, developed by Modon Properties and planned to provide 1,500 houses. The project also includes community facilities and services, extending its construction scope beyond individual houses. The authority separately reported in May 2026 that more than 13,649 citizens had expressed interest in housing projects offered through its service. This commissioning model channels public housing demand into a developer-led community build, with Modon Properties developing the planned 1,500 houses and community facilities while the authority manages prospective beneficiaries.
Geography Analysis
Dubai UAE Construction Market
Dubai held a 47.05% UAE construction market share in 2026, making it the largest geography. Its permitted built-up area reached nearly 3.9 million square meters in Q1 2026 across residential, commercial and service-related developments, indicating a broad development pipeline. Active Dubai construction sites also received 824,381 cubic meters of concrete during the quarter, demonstrating substantial work already in execution. The combination of permitted floor area and material consumption creates entry points at different project stages, allowing contractors and suppliers to pursue both emerging packages and ongoing site requirements within the same emirate.
Sharjah UAE Construction Market
Sharjah is the fastest-growing geography, with a forecast CAGR of 5.8% during 2027-2032. On September 24, 2026, ASAS Real Estate, Sharjah Islamic Bank’s real estate arm, announced the start of infrastructure development across 11 residential, commercial and industrial land projects. The works covered internal roads, electricity, water, telecommunications and street lighting, preparing sites for subsequent construction stages. Servicing those sites links enabling infrastructure to several downstream uses, giving civil contractors an early role across a diversified development program.
Abu Dhabi’s 2025 development approvals included specialized industrial zones, data centers and advanced manufacturing facilities, creating a technical construction pipeline around industrial and digital uses. Ajman’s construction contract value increased 80% in 2025 from 2024, showing growth in its local contracting activity. Developer-led district works form another channel, illustrated by master developer Marjan’s September 2025 completion of roads, cycle tracks, landscaping and green spaces at RAK Central in Ras Al Khaimah. Municipal road delivery forms a different channel, with Fujairah’s ninth-phase internal-road works starting in July 2025 and Umm Al Quwain’s Municipality Department having completed phase one of its internal roads network. This geographic mix spreads demand across industrial facilities, developer-led districts and municipal networks, giving civil and specialist suppliers access to a broader client base than property developers alone.
Regulatory Framework and Outlook
The comparison covers selected national and Dubai requirements from the perspective of a compliant building contractor. National occupational-safety rules assign larger construction employers a dedicated staffing responsibility, while Dubai combines contractor qualification with design and building-quality duties. These obligations affect entry, project preparation and corrective work through different responsible actors. The practical distinction is whether a requirement belongs to the construction employer, the design team or the building owner.
Regulatory Table of UAE Construction Market
| Decision factor | UAE national occupational safety | Dubai building and contractor requirements |
|---|---|---|
| Primary authority | MoHRE, the federal labor authority | Dubai Municipality and competent entities for supervised areas |
| Key instruments or direction | Ministerial Resolution No. 44 of 2022 and Administrative Decision No. 19 of 2023 | Dubai Building Code under Decree No. 45 of 2021; contractor licensing standards; Law No. 3 of 2026 |
| Commercial effect | Construction employers with 100 workers or more appoint a technically qualified safety officer | Code-compliant design and qualified contractors; covered building owners appoint licensed contractors for defect correction under engineering-firm supervision |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | Hardening |
| Source: Mordor Intelligence | ||
The national Medium and No change judgments reflect a continuing qualified-officer duty at the 100-worker construction threshold, which can be incorporated into an employer’s staffing arrangements. Dubai’s Medium rating balances defined licensing and design standards with responsibilities for work on covered older buildings. The building-safety law was published on March 12, 2026, and took effect 60 days later, beginning a 1-year compliance period extendable by the Executive Council Chairman for the same period. Its owner-led certification and defect-correction process supports the Hardening judgment as contractors undertake required remediation under engineering-firm supervision during that compliance transition.
Value Chain Stages
The value chain compares how design consultants, material suppliers and construction contractors earn from successive project responsibilities. AtkinsRéalis’ June 2026 appointment for phases 3 and 4 of ORA Developers’ BAYN community in Ghantoot covered master planning, infrastructure and public-realm design. That combined scope illustrates why early design coordination can influence the constructability of several later packages. Earnings opportunities therefore depend on both performing a specialist task and managing its handoff to the next participant.
Value Chain Analysis Table of UAE Construction Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Master planning and engineering | Engineering and design consultancies such as AtkinsRéalis | Planning and design fees | Unresolved interfaces between infrastructure and public-realm designs | Coordinate linked designs before package release |
| Construction-material supply | Ready-mix concrete suppliers such as Al Ghurair Construction Readymix LLC and Emirates Beton Ready Mix LLC | Concrete sales and supply-contract revenue | Delivery slots misaligned with site pouring sequences | Align dispatch commitments with confirmed pouring schedules |
| Infrastructure and building construction | Infrastructure contractors such as Al Nasr Contracting Company L.L.C.; main building contractors such as Dutco Construction Company | Construction-contract revenue | Unclear handoffs between enabling works and subsequent building packages | Define package boundaries and acceptance milestones |
| Source: Mordor Intelligence | ||||
Value capture differs because consultants sell design responsibility, suppliers sell physical throughput and contractors undertake package execution. Aldar’s 2025 main-contract award to Dutco Construction Company for The Arthouse on Saadiyat Island illustrates the building-execution role within a developer’s wider program. Coordinating those interfaces can protect downstream progress without requiring every participant to integrate vertically. For projects with linked uses, firms able to price and control handoffs have a clearer route to additional service value than firms expanding scope without matching delivery responsibility.
Competitive Landscape
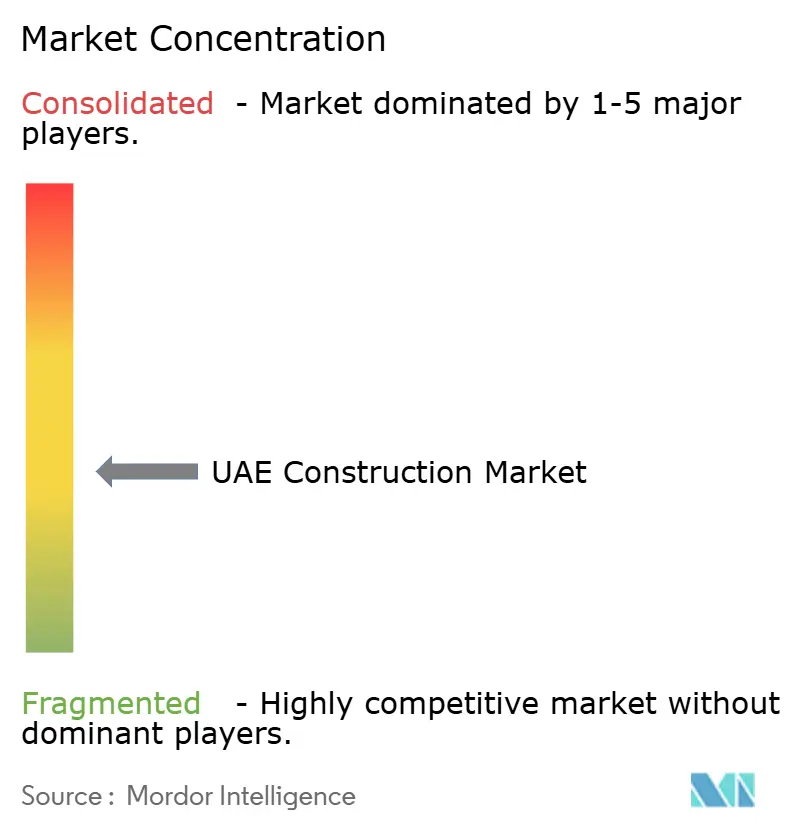
Competition is fragmented across diversified building and infrastructure contractors, with several groups overlapping across project types. ALEC Engineering & Contracting LLC’s parent construction group, ALEC Holdings, reported that 89% of its group backlog was concentrated in the UAE at year-end 2025. ASGC Construction LLC provides residential, commercial and infrastructure construction in the UAE, while China State Construction Engineering Corporation Middle East (CSCEC ME) undertakes building and infrastructure projects there. Arabian Construction Company (ACC) serves building and infrastructure projects across the Middle East, Africa and India, while Consolidated Contractors Group provides civil and infrastructure construction. For buyers, overlapping capabilities and ALEC’s domestic workload concentration make execution capacity central to assessing additional complex work.
Across its group operations focused on the UAE and Saudi Arabia, ALEC Holdings obtained 52% of its 2025 new awards through direct, bilateral negotiation. Negotiated procurement can bring technical scope and delivery commitments into the commercial discussion, creating an opportunity to differentiate through a project-specific execution proposition. The group reported 10% backlog growth in 2025, which it attributed to selective tendering and strong client relationships. Negotiated awards and competitive tenders therefore fed a single expanding order book.
CSCEC ME signed the contract for Dubai Holding’s new headquarters and Jumeirah Residences Emirates Towers in September 2026. The award covered both the headquarters and 754 branded residences across 2 towers, combining office and residential construction within one client’s package. Dubai Holding described it at signing as the largest building contract it had awarded to date. Such a combined award creates an opening for contractors able to coordinate different building uses under one delivery commitment, making breadth of building execution relevant to winning large single-client packages.
UAE Construction Industry Leaders
-
ALEC Engineering & Contracting LLC
-
ASGC Construction LLC
-
China State Construction Eng. Corp. Middle East
-
Arabian Construction Company (ACC)
-
Consolidated Contractors Group
- *Disclaimer: Major Players sorted in no particular order
UAE Construction Market Companies Covered in this Report
- ALEC Engineering & Contracting LLC
- ASGC Construction LLC
- China State Construction Eng. Corp. Middle East
- Arabian Construction Company (ACC)
- Consolidated Contractors Group
- Bechtel
- Fluor Corporation
- Jacobs
- AE Arma-Elektropanç
- Azuria Water Solutions
- Khansaheb Civil Engineering
- Al Naboodah Construction Group
- DBB Contracting LLC
- Shapoorji Pallonji Middle East
- Trojan Construction Group
- Sobha Constructions
- Engineering Contracting Co LLC
- Aldar Projects LLC
- Damac Properties – Project Construction
- Pivot Engineering & Gen. Cont.
- China Railway Construction Corp. ME
Key Opportunities for Market Participants
The opportunities compare routes into public infrastructure procurement and owner-led building upgrades, with different buyer commitments and execution barriers. In May 2026, the Abu Dhabi Investment Office and Abu Dhabi Projects and Infrastructure Centre announced 24 public-private partnership (PPP) projects planned for market release during 2026 and 2027. Their separate May announcement of procurement commencement on 3 projects used the Structured Dialogue framework across transport, education and social care. These initiatives favor a clear construction role within the wider delivery structure, rather than assuming that a public project pipeline automatically becomes a conventional building contract.
Market Opportunities Table of UAE Construction Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Abu Dhabi social-infrastructure PPP construction | Announced project-release schedule extends through 2027 | Public project sponsors and delivery consortia | Offer a defined construction package within a project delivery team | Aligning construction responsibilities with project-specific procurement terms | Education and social-infrastructure contractors such as ASGC Construction LLC, based on sector capabilities |
| Dubai rail civil works | RTA’s September 2026 schedule placed Gold Line tender issuance by end-2026 | RTA and prospective rail delivery teams | Prepare rail, tunneling and infrastructure package capabilities | Aligning the offered scope with the eventual tender | Rail and tunneling contractors such as National Projects Construction, a Trojan Construction Group subsidiary |
| Owner-led existing-building upgrades | Dubai Municipality launched voluntary greening guidance in September 2026 | Building owners and operators | Develop phased upgrades around a property’s technical needs and economic feasibility | Securing an owner-approved economic case | Building-upgrade contractors such as Khansaheb Civil Engineering |
| Source: Mordor Intelligence | |||||
The central opening is to package specialist construction capability around a specific commissioning decision. Abu Dhabi’s Structured Dialogue procurement gives construction participation a place within a broader project-delivery discussion. For education and social-infrastructure contractors such as ASGC, that creates a potential route to offer a defined works scope within a delivery team. The commercial priority is to establish responsibility for that scope before committing resources against a multi-project announcement.
Recent Industry Developments in UAE Construction Market
- Sep 2026: ASAS Real Estate, Sharjah Islamic Bank’s real estate arm, announced the start of infrastructure development works across 11 residential, commercial and industrial land projects in Sharjah.
- Sep 2026: Dubai Holding signed a construction contract with China State Construction Engineering Corporation Middle East for its new headquarters and Jumeirah Residences Emirates Towers in Dubai.
- Jul 2026: Dubai’s Roads and Transport Authority awarded the contract for the 12-kilometer Latifa bint Hamdan corridor, including 7 bridges and 8 tunnels.
UAE Construction Market Report Scope and Research Methodology
Market Definition and Coverage
The UAE construction market measures annual spending on construction work delivered in the United Arab Emirates, including geotechnical and superstructure work for residential, commercial and industrial facilities and infrastructure such as transportation, power generation, transmission and utilities. It covers new construction and renovation delivered through conventional on-site or modern methods, funded publicly or privately across Dubai, Abu Dhabi, Sharjah and the other emirates (Ajman, Ras Al Khaimah, Fujairah and Umm Al Quwain).
Scope exclusions: Land acquisition and property sales or leases, separately sold construction inputs and uninstalled prefabricated modules, standalone equipment sales rentals or maintenance, standalone design engineering consulting or project management services, and construction work outside the United Arab Emirates are excluded.
Segments Covered in This Report
- By Sector
- Residential
- Apartments/Condominiums
- Villas/Landed Houses
- Commercial
- Office
- Retail
- Industrial and Logistics
- Others
- Infrastructure
- Transportation Infrastructure (Roadways, Railways, Airways, others)
- Energy & Utilities
- Others
- Residential
- By Construction Type
- New Construction
- Renovation
- By Construction Method
- Conventional On-Site
- Modern Methods of Construction (Prefabricated, Modular, etc)
- By Investment Source
- Public
- Private
- By Geography
- Dubai
- Abu Dhabi
- Sharjah
- Other Emirates (Ajman, Ras Al Khaimah, Fujairah, UAQ)
Data Sources, Market Sizing, and Validation
Desk Research
Public baselines would be drawn from sources such as the Federal Competitiveness and Statistics Centre's construction activity and economic series, Dubai Municipality's permit and licensed-area statistics, Dubai Municipality's counts of buildings under construction, and Dubai Statistics Center's population and completed-building series. These sources help distinguish construction output, project starts, permitted area, cost conditions and underlying demand across the emirates, with each signal used only for the measure it reports.
Public company annual reports, investor materials, government budget documents and reputable UAE business reporting can add project timing, funding and contractor context, while construction approvals and completion data help check whether pipeline indicators are becoming delivered work. These sources are illustrative rather than exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured questionnaires with UAE contractors, developers and project owners, public-sector project authorities, and design or construction consultants would test the interpretation of project pipelines, work delivery and cost indicators. Analysts would use respondents to check variable-level assumptions and explain gaps in secondary evidence, then compare those accounts with public project, permit, budget and construction-output records before incorporating a finding.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 32% | CXOs: 20% | |
| Mid tier: 43% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The estimate is built top down from annual UAE construction spending and construction-output indicators, then checked selectively against supplier roll-ups and sampled contract value times delivered work volume. Permit applications and licensed floor area indicate potential starts, project awards and budget allocations track the pipeline by sector and emirate, construction cost indices capture changes in labor and material pricing, and construction value-added and employment provide checks on activity. A time-series model would forecast the main indicators where history is consistent, with scenario analysis used for major changes in project timing, financing or input costs. Segment shares would be derived from project values, approvals and output evidence across residential, commercial, infrastructure, new build, renovation, delivery method, funding source and emirate. Selective bottom-up checks would use available contractor, developer or supplier evidence to test totals and shares, while gaps would be bounded with the closest comparable output and cost indicators and kept separate from observed data. UAE construction specialists would review the assumptions behind each variable forecast and flag project delays, cancellations, cost changes or funding shifts for analyst reassessment.
Data Validation & Update Cycle
Analysts triangulate project awards, permits, budgets, contractor disclosures, output indicators and cost series, checking that each signal refers to UAE construction work and its stated period. They investigate anomalies, compare forecast and observed changes by sector and emirate, reconcile differences against source definitions, and complete sequential source, model and senior analyst reviews before sign-off. A material project delay or cancellation, a revised budget, a major cost movement or a gap between reported activity and model direction triggers source rechecking and targeted respondent re-contact. The model is refreshed annually, reviewed between cycles after material events, and given a fresh pre-delivery review.
Mordor Intelligence's UAE Construction Market Size Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The UAE construction market measures annual spending on construction work delivered in the United Arab Emirates, including geotechnical and superstructure work for residential, commercial and industrial facilities and infrastructure such as transportation, power generation, transmission and utilities.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Selective bottom-up checks would use available contractor, developer or supplier evidence to test totals and shares, while gaps would be bounded with the closest comparable output and cost indicators and kept separate from observed data.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 134.3 B (2027) | |
| Global Consultancy A | USD 107.2 B (2024) | At its 2024 base, this estimate is 20.2% below this report's 2027 value of USD 134.3 B, 3 years later. The source reports a rising annual output path through 2029, so the 2024 observation precedes later construction activity. |
| Industry Agency B | USD 111.2 B (2025) | At its 2025 base, this estimate is 17.2% below this report's 2027 value of USD 134.3 B, 2 years later. Its 2025 forecast predates two subsequent years of construction output included in the 2027 measure. |
Mordor Intelligence's analysts triangulate project awards, permits, budgets, contractor disclosures, output indicators and cost series, checking that each signal refers to UAE construction work and its stated period.
Key Questions Answered in the Report
What is the UAE construction market size and growth outlook?
The market is estimated at USD 134.3 billion in 2027 and forecast to reach USD 174.9 billion by 2032, with a CAGR of 5.42% during 2027-2032.
What drives construction demand across the UAE?
Housing, tourism and digital infrastructure support demand. Miral’s September 2026 plan included more than AED 12 billion (more than USD 3.27 billion) across Yas Island over 5 years.
Which construction sector leads UAE spending?
Residential led with 43.64% of market value in 2026. Infrastructure is forecast to grow fastest at a CAGR of 6.05% during 2027-2032.
Which companies compete for UAE construction work?
Major participants include ALEC Engineering & Contracting LLC, ASGC Construction LLC, China State Construction Engineering Corporation Middle East, Arabian Construction Company (ACC) and Consolidated Contractors Group.
What is the main delivery challenge for UAE contractors?
Dubai Municipality reported concrete shortages affecting project timelines in February 2026. Rising material prices also increased contract risk.
Which emirates lead construction activity and forecast growth?
Dubai represented 47.05% of market value in 2026. Sharjah is the fastest-growing geography, with a forecast CAGR of 5.8% during 2027-2032.