Thawing System Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 258.8 Million |
| Market Size (2031) | USD 373.28 Million |
| Growth Rate (2026 - 2031) | 7.61 % CAGR |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order. Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. |

Thawing System Market Analysis by Mordor Intelligence
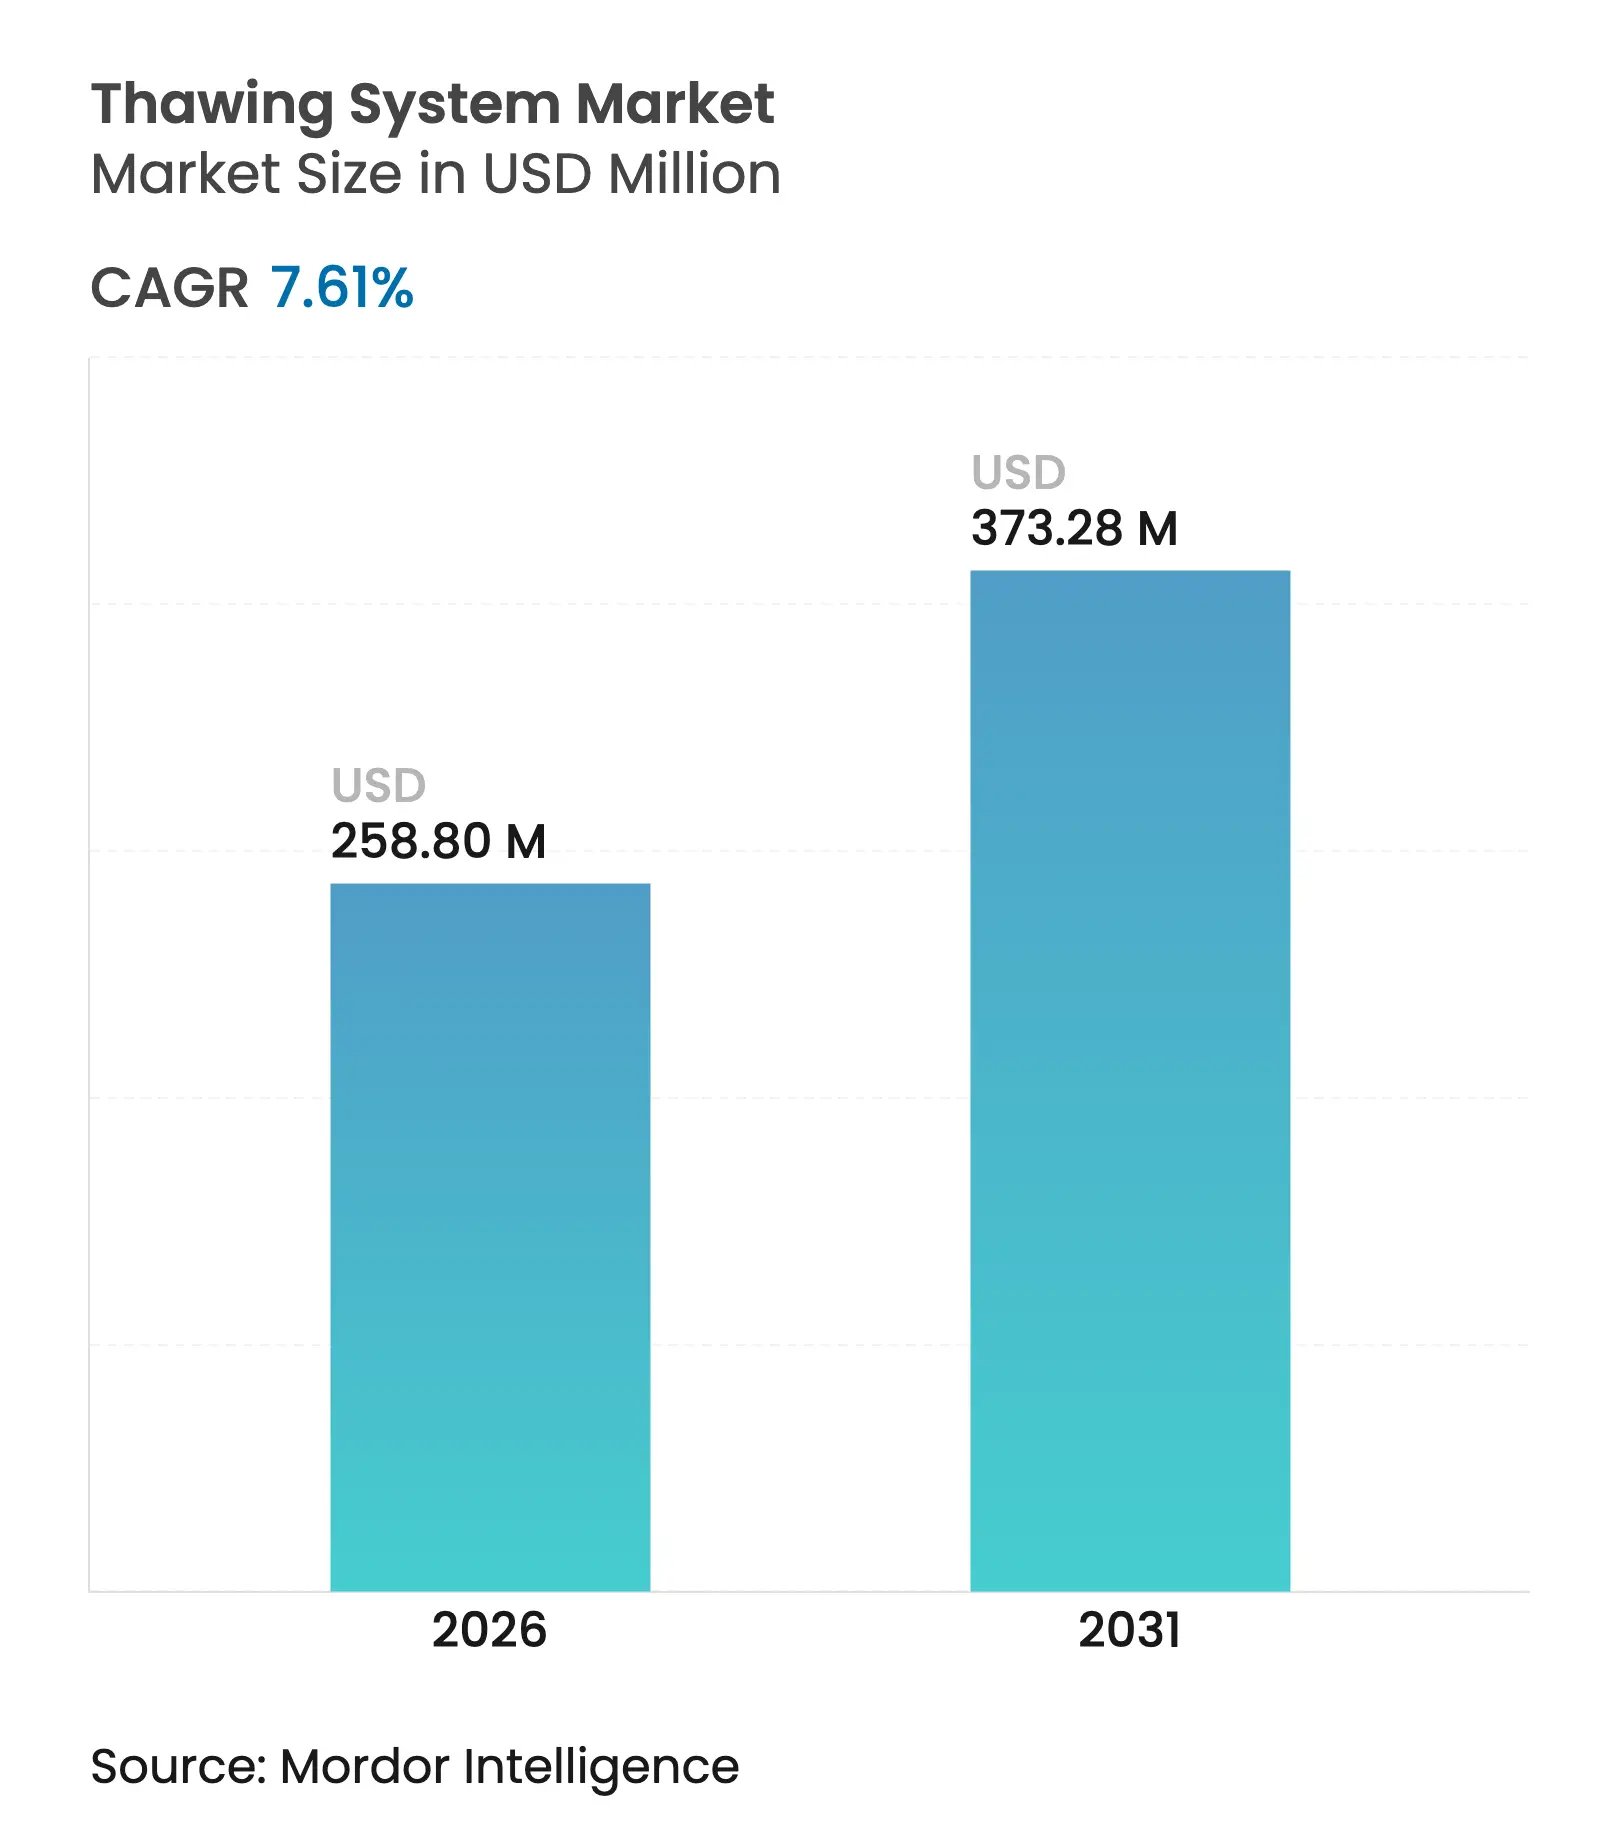
Thawing system market size in 2026 is estimated at USD 258.8 million, growing from 2025 value of USD 240.5 million with 2031 projections showing USD 373.28 million, growing at 7.61% CAGR over 2026-2031. Investment in cell and gene therapies, tighter GMP expectations, and the shift toward single-use closed consumables accelerate demand for rapid and uniform thawing platforms. Regulatory momentum, including multiple FDA cell-therapy approvals in 2024–2025 and targeted device guidance on thermal effects issued in March 2024, is catalyzing the adoption of automated solutions that eradicate operator variability. North America retains leadership owing to its mature cell-therapy pipeline, yet Asia-Pacific’s expansion of biomanufacturing capacity and regulatory harmonization drives the fastest regional growth. Technology preferences are in transition: manual plate warmers still dominate, but dielectric radio-frequency (RF) systems and dry conduction platforms gain traction, especially for organ recovery and high-value biologics. End-users increasingly demand IoT-enabled units with native data-logging that streamline GMP record-keeping and create ancillary service revenues.
Key Report Takeaways
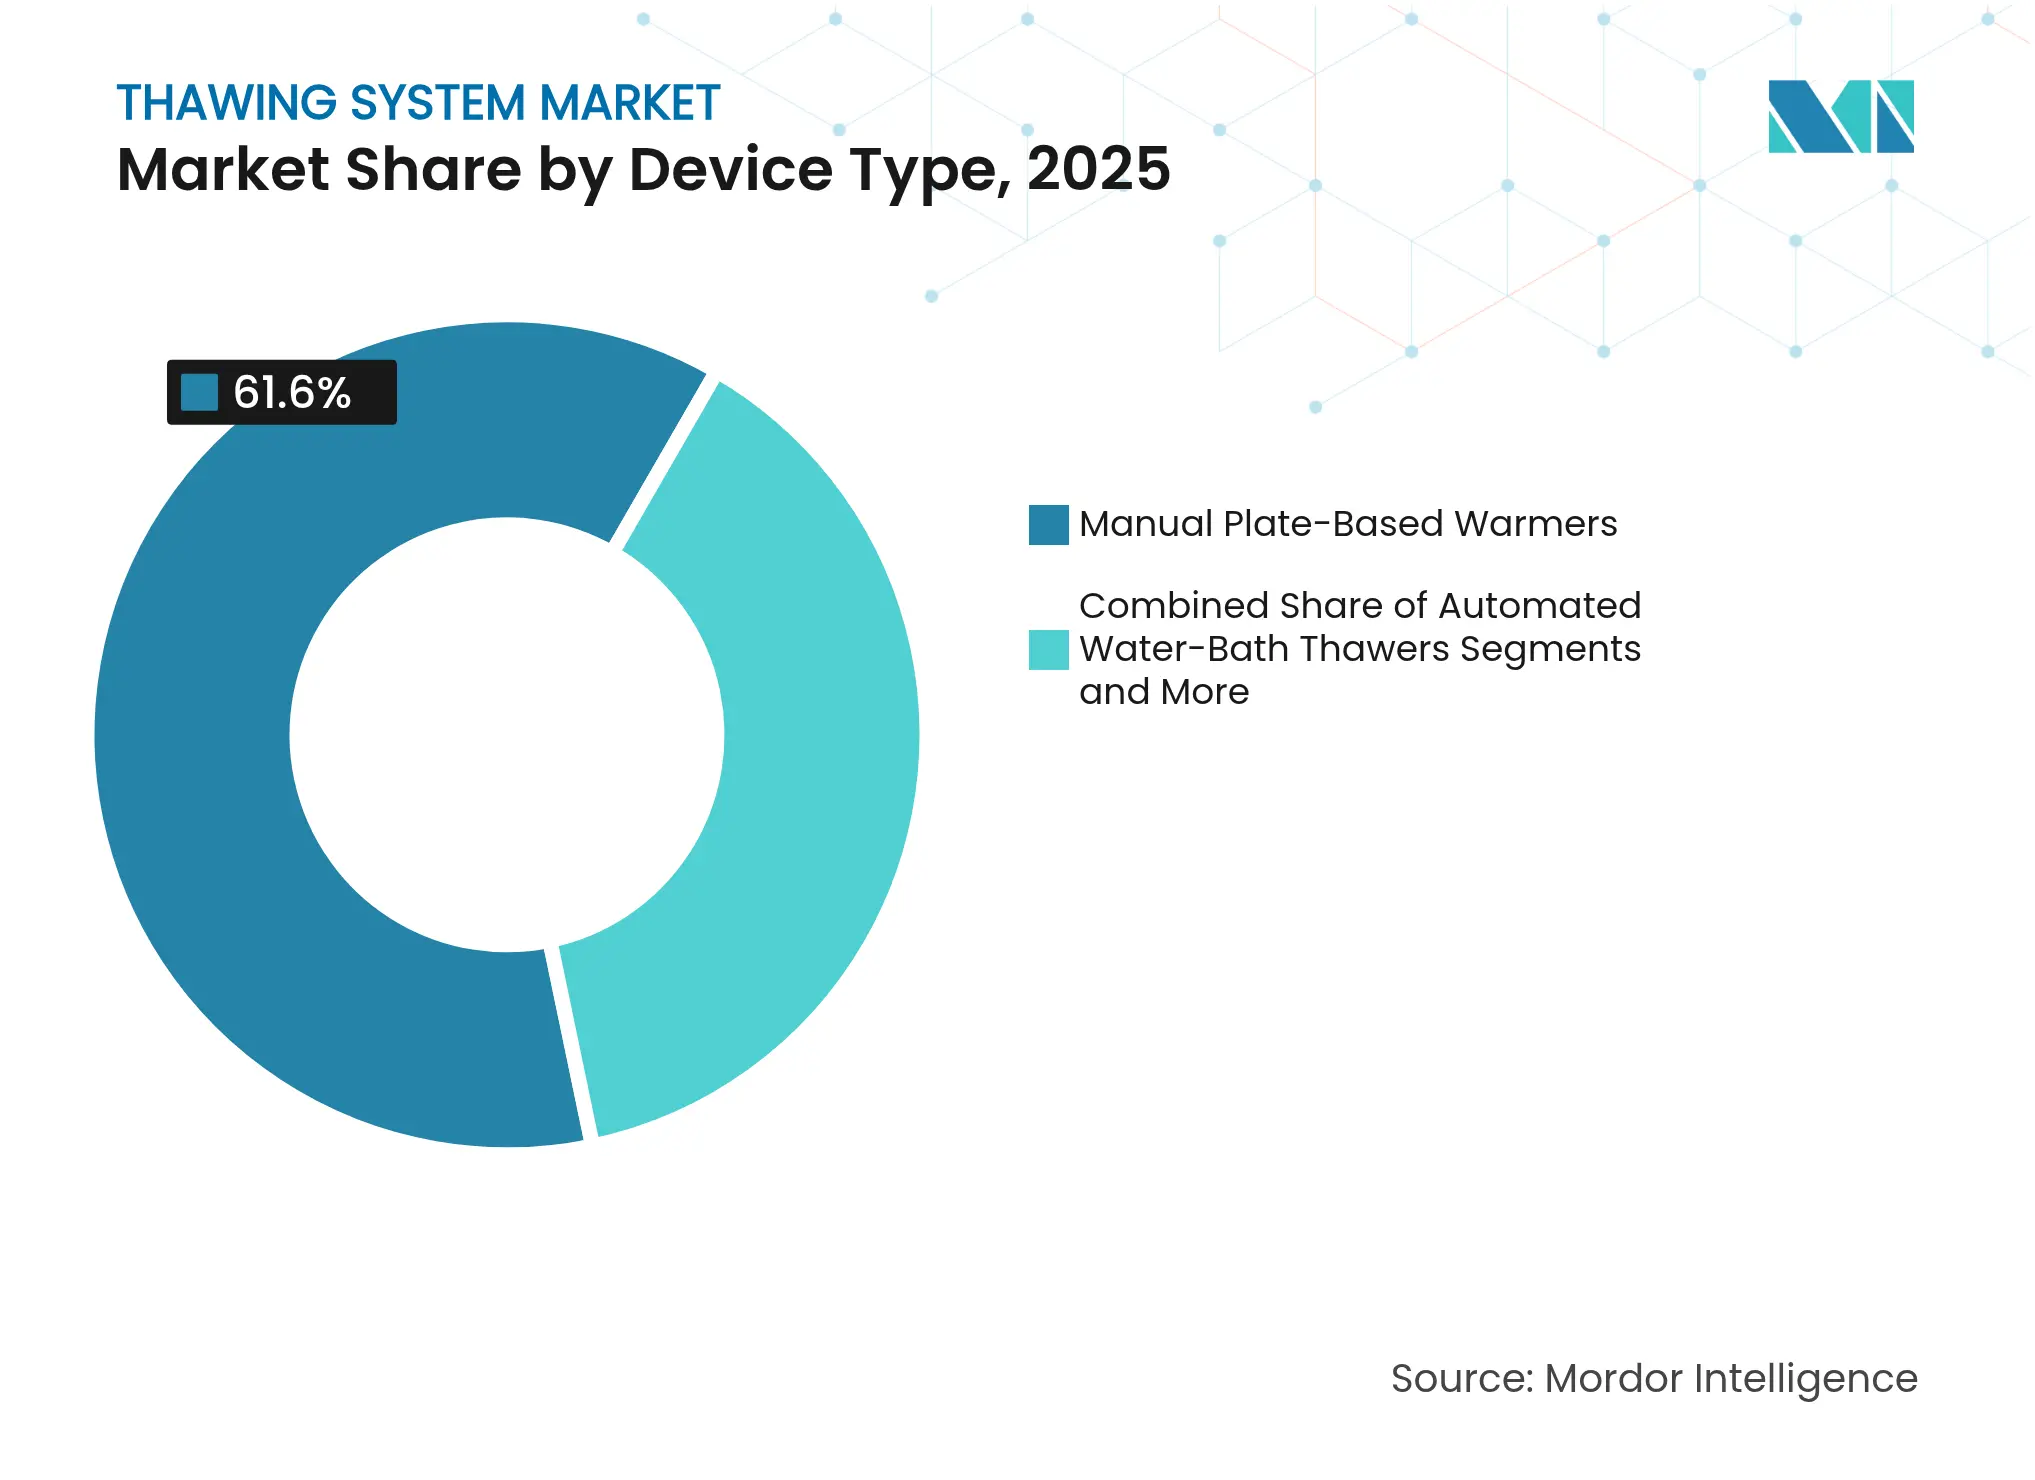
- By device type, manual plate-based warmers led with 61.60% of the thawing system market share in 2025, whereas dielectric RF thawers are projected to advance at an 7.95% CAGR through 2031.
- By sample type, blood samples accounted for 56.10% of the thawing system market size in 2025, while tissues & organs are poised for the fastest growth at a 10.02% CAGR to 2031.
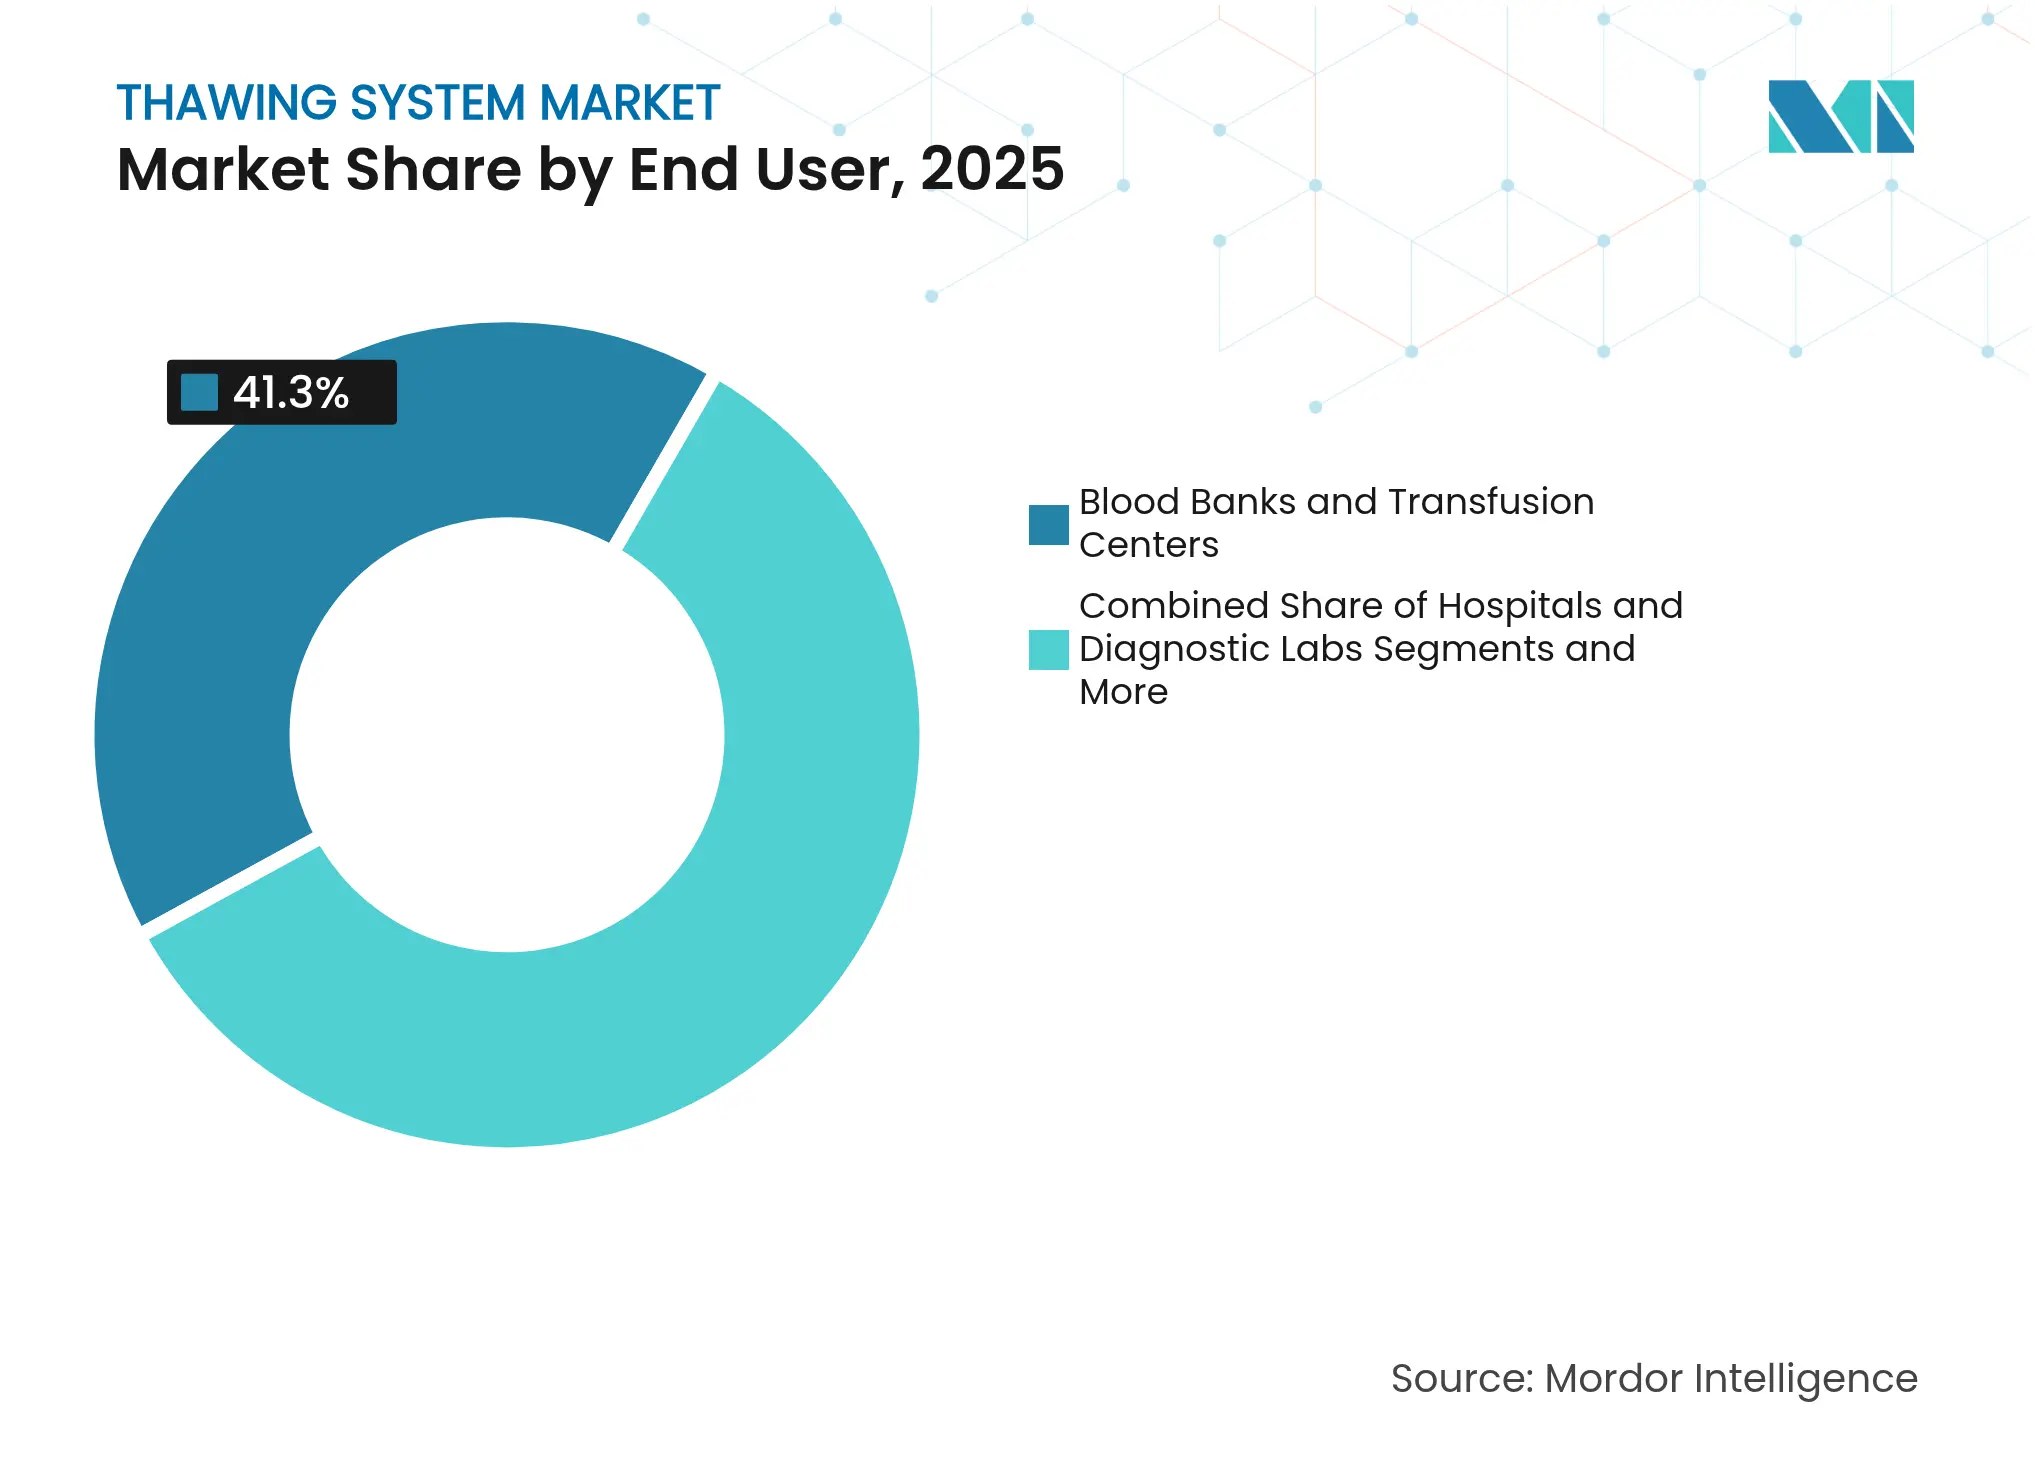
- By end-user, blood banks & transfusion centers held 41.30% revenue share in 2025; cell-therapy & biopharma manufacturers are expected to register a 9.3% CAGR over the same period.
- By thawing technology, conduction plate heating commanded 63.80% of the thawing system market share in 2025; dielectric RF warming exhibits the highest forecast CAGR at 7.95%.
- By geography, North America captured 37.80% revenue in 2025, whereas Asia-Pacific is projected to expand at an 10.68% CAGR from 2026 to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence's proprietary estimation framework, updated with the latest available data and insights as of 2026.
Global Thawing System Market Trends and Insights
Drivers Impact Analysis
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
Expanding cell & gene-therapy volumes require GMP-grade thawing solutions | +2.10% | Global, concentrated in North America & EU | Medium term (2-4 years) |
Rising blood-component transfusions mandate standardized fast thawers | +1.80% | Global, higher impact in APAC & MEA | Short term (≤ 2 years) |
Automation reduces contamination & operator variability | +1.50% | North America & EU core, spill-over to APAC | Medium term (2-4 years) |
Dielectric RF organ-warming unlocks frozen-organ banking | +1.20% | North America & EU research centers | Long term (≥ 4 years) |
Single-use closed thaw bags accelerate equipment replacement | +0.90% | Global biopharmaceutical hubs | Short term (≤ 2 years) |
IoT-enabled cryochain analytics create service-revenue streams | +0.60% | Developed markets initially, expanding globally | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Expanding Cell & Gene-Therapy Volumes Require GMP-Grade Thawing Solutions
FDA approvals for products such as Casgevy and Lyfgenia have locked in strict temperature windows—typically 37 °C for ≤ 20 minutes—forcing manufacturers to adopt functionally closed, automated devices that guarantee repeatability. Transfusion services increasingly manage thawing for autologous therapies because of their legacy competence in cold-chain handling. Partnerships like Cell and Gene Therapy Catapult with Asymptote demonstrate how benchtop equipment now comes with barcode traceability, audit logs, and disposable inserts to reduce contamination risk.[1] Investment in these systems is further justified as accelerated review pathways reward facilities that show robust GMP controls.
Rising Blood-Component Transfusions Mandate Standardized Fast Thawers
Blockchain, RFID, and AI have modernized blood-bank logistics, creating throughput bottlenecks at thaw steps. Terumo’s Reveos automated processing platform, launched in February 2025, cuts manual touchpoints from over 20 to a handful, demanding equally swift thawing modules. High-capacity blast freezers now cool plasma to −90 °C within minutes, so downstream thawers must keep pace to sustain eight-fold productivity gains. Integration with digital inventory systems enables real-time temperature event alerts that support hemovigilance programs.
Automation Reduces Contamination & Operator Variability
Water-bath units risk cross-contamination and inconsistent warming curves. GE HealthCare’s dry VIA Thaw CB1000 offers programmable profiles and built-in data capture to ease validation burdens. STEMCELL Technologies’ ThawSTAR CFT2 posted improved recovery for peripheral blood mononuclear and pluripotent stem cells relative to baths, underscoring the viability benefits of closed, dry thawing. Robotic fill-finish lines such as Finia integrate thaw, dilution, and cryo-fill into a single module, trimming human error and aligning with continuous-manufacturing philosophies.
Dielectric RF Organ-Warming Unlocks Frozen-Organ Banking
Electromagnetic warming at 27 MHz has demonstrated kidney heating rates of 150 °C per minute, limiting devitrification and preserving tissue architecture. X-Therma’s GMP-ready XT-Thrive platform attracted USD 22.4 million in Series B funding, signalling commercial confidence in RF-driven organ revival. Novel three-phase electrode layouts now deliver 91.9% field uniformity, addressing hot-spot risk and supporting regulatory submissions.
Restraints Impact Analysis
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
High capital cost of fully automated platforms | -1.40% | Global, with higher impact in emerging markets | Short term (≤ 2 years) |
Container–device incompatibility limits workflow flexibility | -0.80% | Global biopharmaceutical manufacturing | Medium term (2-4 years) |
Uneven temperature gradients risk viability in large bags | -0.70% | Global, with higher impact in cell therapy manufacturing | Medium term (2-4 years) |
Regulatory uncertainty for dielectric organ warming | -0.50% | North America & EU regulatory jurisdictions | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Capital Cost of Fully Automated Platforms
Comprehensive units that include HEPA-filtered enclosures, IoT telemetry, and GMP-tier audit trails demand sizeable upfront budgets. Although Single Use Support’s scalable RoSS.pFTU line ranges from benchtop to 500 L, capital outlays still deter smaller clinics. Economic models indicate automated thawers shave nearly four minutes per therapeutic dose and cut medication errors by 54%, offsetting costs over time. Investor activity, such as Novo Holdings buying 60% of Single Use Support in 2024, suggests hardware prices will decline as production volumes rise.
Container–Device Incompatibility Limits Workflow Flexibility
Heterogeneous bag sizes and rigid vials often require different inserts or adapters, complicating validation. Cross-platform alliances such as Sartorius with HOF Sonderanlagenbau aim to standardize freeze-thaw consumables, yet progress remains incremental. Some innovators avoid the issue by removing freezing from the workflow altogether: DefiniGEN and Atelerix have commercialized room-temperature preservation matrices that bypass the thaw step entirely. Until standards converge, end-users must stock multiple fixtures, curbing economies of scale.
Segment Analysis
By Device Type: Automation Gains Ground Despite Manual Dominance
Manual plate warmers delivered 61.60% of 2025 revenue, underscoring entrenched use within blood centers that favor low complexity and familiar upkeep. However, dielectric RF thawers lead growth with an 7.95% CAGR as transplant programs pilot organ-banking concepts. Automated plate units and water-bath replacements serve laboratories looking for consistent run-to-run performance while keeping costs below RF platforms. The thawing system market now provides dry conduction chambers that appeal to facilities prioritizing contamination avoidance.
Adoption trends mirror tighter GMP oversight. Facilities preparing for late-stage commercial cell therapies increasingly replace manual warmers with PLC-driven devices that log every temperature excursion. The thawing system industry also experiments with magnetic nanoparticle nanowarming, which uses dispersed iron oxide particles to create volumetric heating under alternating magnetic fields. In peer-reviewed trials, the two-stage protocol maintained high post-thaw viability, pointing to future disruption once scale and regulatory hurdles are resolved.
Note: Segment shares of all individual segments available upon report purchase
By Sample Type: Tissue Applications Drive Innovation
Blood components accounted for 56.10% of 2025 sales, given the sheer volume of global transfusions and established thaw procedures. Yet tissues & organs segment posts a 10.02% CAGR, reflecting research breakthroughs that extend cold-storage horizons and enable centralized organ banks. Cell- and gene-therapy vials also expand quickly as the therapy pipeline widens, demanding precise, repeatable thawing to protect potency. Embryos and oocytes remain niche but vital, and modified rehydration protocols now improve oocyte survival to 89.8% post-thaw.
Sample diversity pushes vendors to diversify formats. Supercooling extends red-blood-cell storage to 63 days at −8 °C, which means thaw workflows must ensure gentle re-warming to avoid hemolysis. Isochoric preservation, applying constant-volume pressure rather than ice formation, may eliminate classical thaw steps for organs, upending established device design. Such paradigm shifts create incremental demand as laboratories invest in hybrid systems that can thaw traditional bags today yet evolve for next-generation protocols tomorrow.
By End-User: Biopharmaceutical Manufacturing Accelerates
Blood banks and transfusion centers controlled 41.30% of 2025 turnover because of routine plasma and cellular-component workflows. Hospitals and diagnostic laboratories follow, using thawers for point-of-care applications from trauma resuscitation to stem-cell infusions. Research institutes serve as early adopters of novel technologies such as nanowarming, validating their performance in controlled environments. IVF clinics rely on small-batch units tuned for gamete and embryo handling.
Cell-therapy and biopharma manufacturers present the steepest curve, growing at 9.3% CAGR. Their multi-lot commercial processes mandate GMP recording and full electronic batch records. Thermo Fisher’s 2025 Wisconsin lab expansion focusing on biologic characterization illustrates the infrastructure wave that underpins new demand. Century Therapeutics’ iPSC-based allogeneic pipeline likewise calls for high-throughput, closed thawers that dovetail with robotic fill-finish systems. As more therapies shift from clinical to commercial scale, equipment refresh cycles shorten, reinforcing replacement revenues.
Note: Segment shares of all individual segments available upon report purchase
By Thawing Technology: Electromagnetic Methods Gain Momentum
Conduction plate heating supplied 63.80% of 2025 revenue due to its low risk profile and simple validation path. Water-bath circulation persists where legacy infrastructure remains. Convective air warming and infrared systems occupy specialized niches demanding uniform gradients. Dielectric RF warming, however, is growing at an 7.95% CAGR as organ-banking studies confirm rapid, homogeneous heating with minimal thermal stress.
Recent work improved field uniformity to over 90%, using three-phase circular electrodes that diminish edge effects. The thawing system market size for dielectric RF applications in organ preservation is forecast to expand materially once FDA pathways clarify performance testing expectations. Meanwhile microwave systems have demonstrated 300–500 °C per minute tissue warming but still require sophisticated real-time control to manage hotspots. Vendors racing to combine RF and microwave elements may eventually deliver hybrid platforms for broad specimen categories.
Geography Analysis
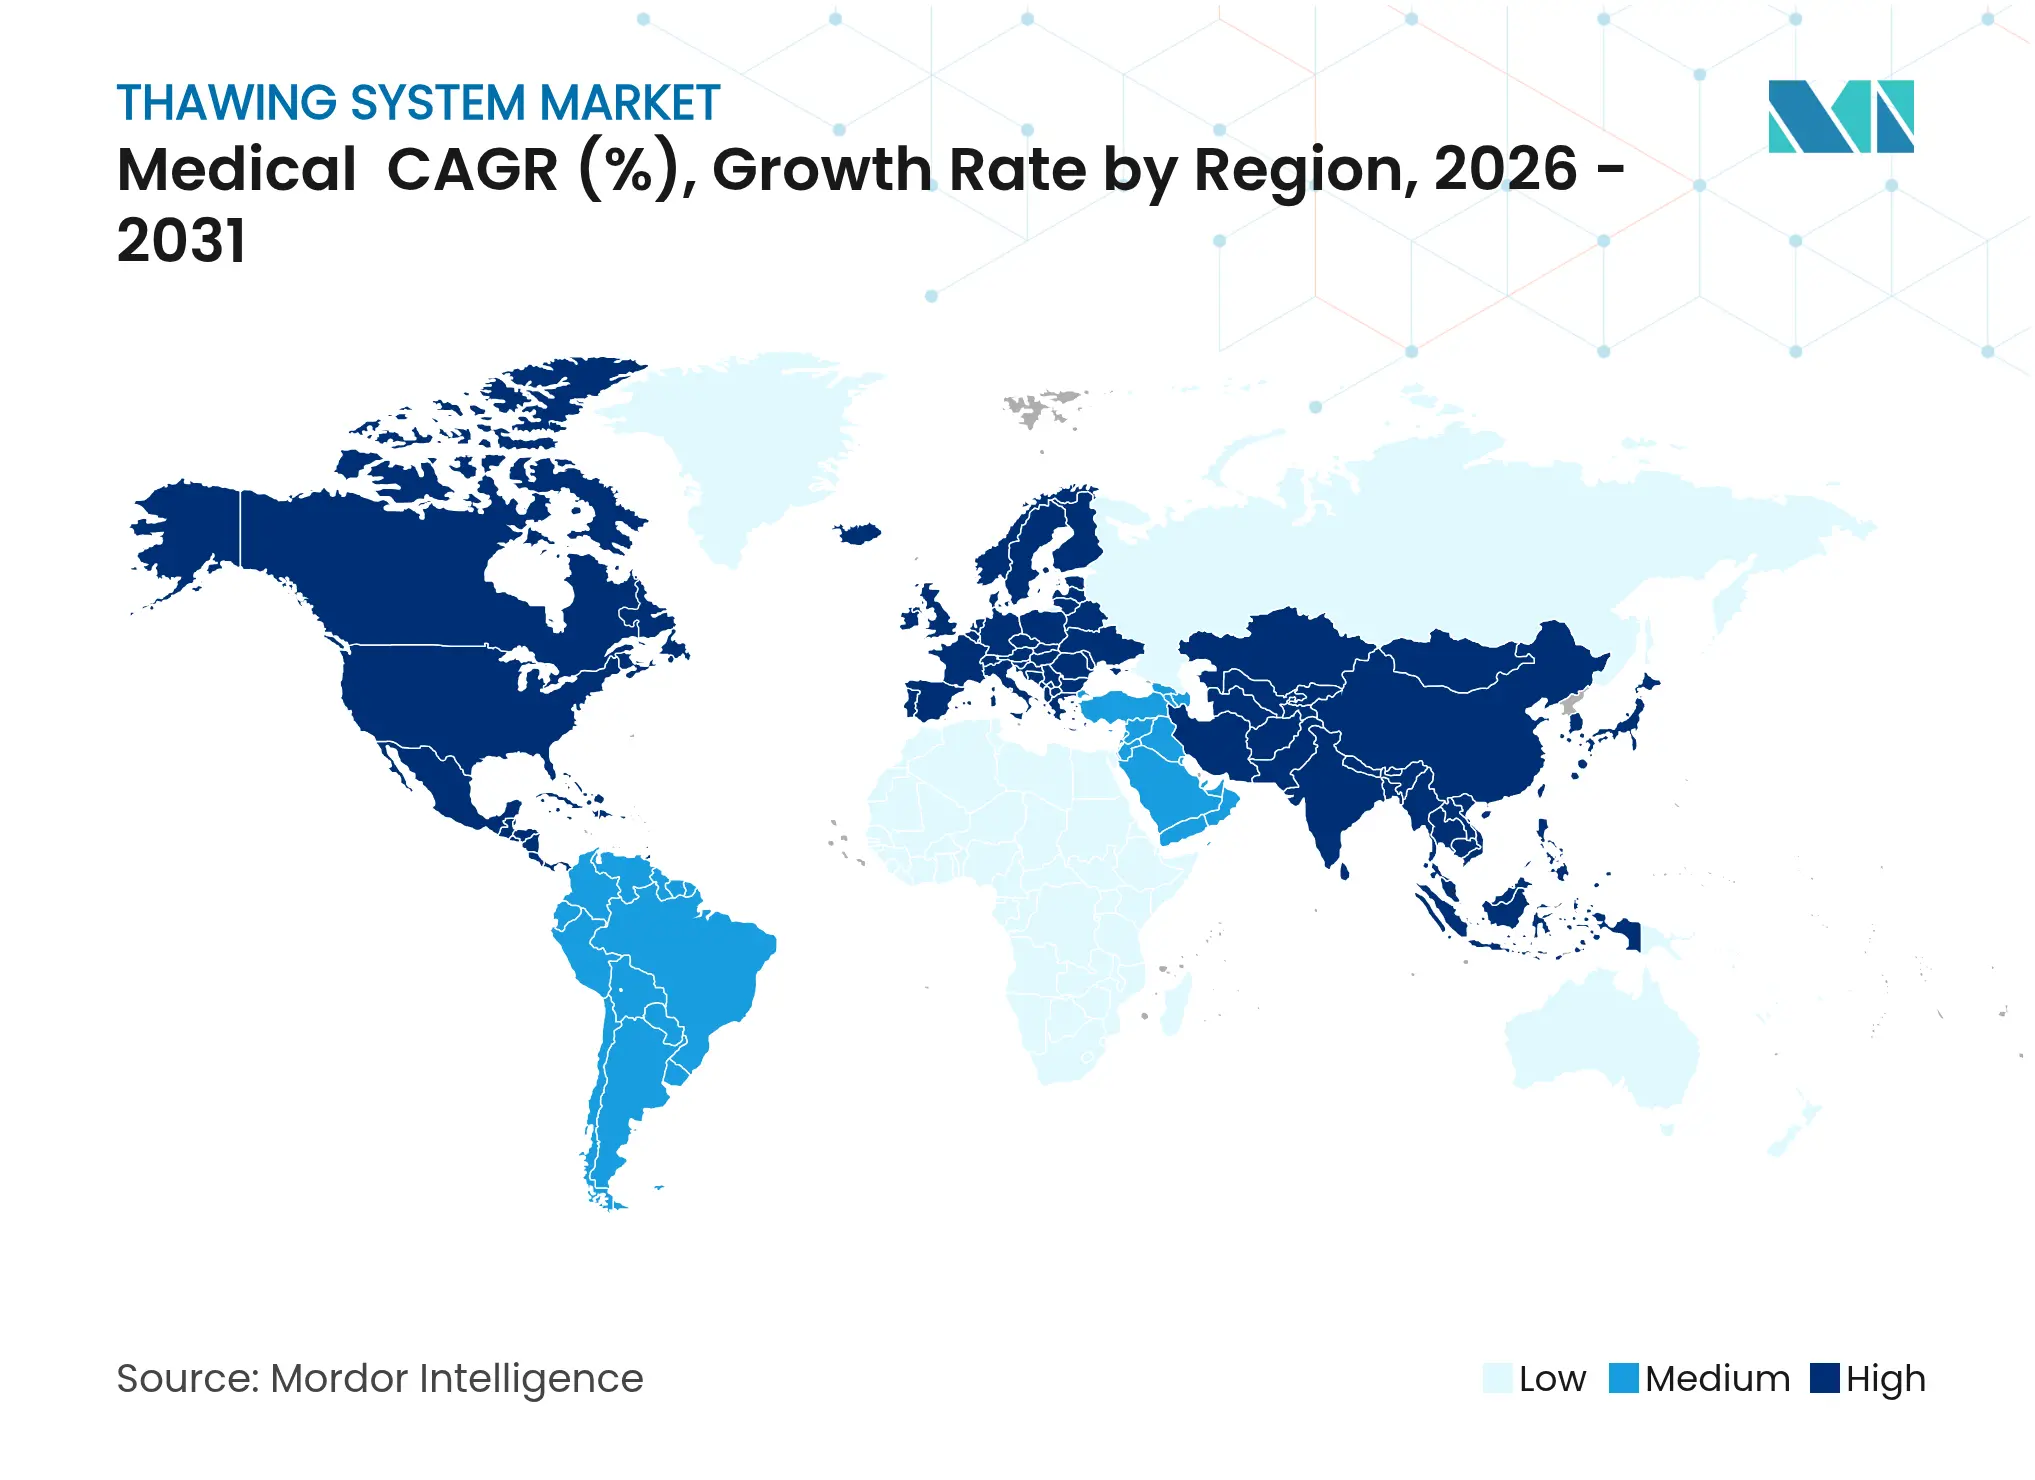
North America contributed 37.80% revenue in 2025. The region benefits from concentrated cell-therapy innovators, abundant GMP-grade contract manufacturing, and clear agency guidance on device thermal profiles. Temporary FDA staffing reductions in late 2024 raised review times, yet rigorous submissions also enhance equipment credibility once cleared. Canada’s public health¬care networks continue to pilot portable thawers for rural transfusion hubs, further reinforcing regional uptake.
Europe ranks second in value, aided by stringent Medical Device Regulation that rewards manufacturers with mature quality systems. Initiatives such as the Cell and Gene Therapy Catapult’s collaboration with Asymptote demonstrate public-private efforts to accelerate compliant automation. Getinge’s 2024 Paragonix acquisition adds an organ transport portfolio, tightening integration between storage, shipping, and thaw steps. Energy-saving policies also spur interest in isochoric refrigeration, which lowers facility operating costs by up to 70% while aligning with EU sustainability targets.
Asia-Pacific is the fastest climber, projected at 10.68% CAGR for 2026–2031. China’s device market, expected to hit EUR 30 billion, is buoyed by refreshed NMPA regulations that shorten foreign-device registration cycles. Japan is tackling its approval lag through accelerated pathways, opening earlier windows for advanced thawers. Regional cell-therapy centers in South Korea and Singapore anchor demand for fully automated, humidity-controlled equipment connected to national traceability platforms. The thawing system market thus faces its richest growth opportunity across Asia-Pacific’s upgraded biomanufacturing corridors.
Competitive Landscape
Market Concentration
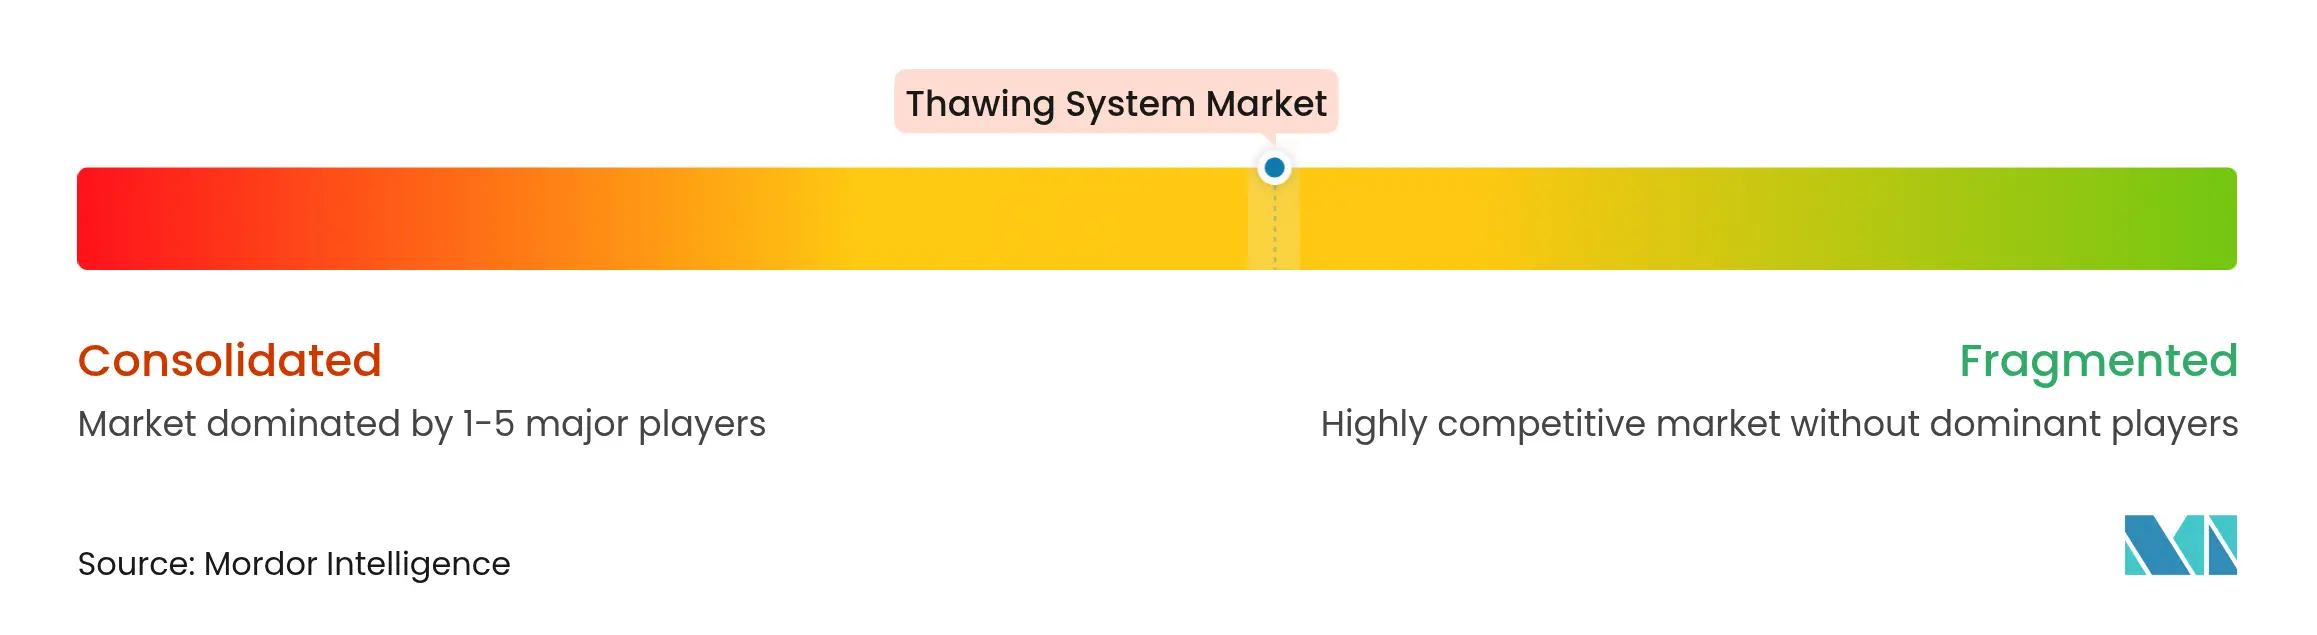
The competitive field is moderately fragmented. Established incumbent portfolios dominate blood-bank lines, while specialist entrants compete in cell-therapy and organ-banking niches. Consolidation among full-line life-science suppliers continues: Thermo Fisher’s USD 4.1 billion purchase of Solventum’s purification and filtration assets broadens its end-to-end offering and pulls thawing equipment into a wider single-use ecosystem. BioLife Solutions, already strong in cryogenic freezers, has expanded through acquisitions of Stirling Ultracold and PanTHERA CryoSolutions, targeting an integrated chain from freeze to final thaw.
Automation and digital integration drive competition. GE HealthCare, Terumo BCT, and Single Use Support embed track-and-trace software layers that feed directly into electronic batch-record systems. Start-ups like X-Therma and Pluristyx differentiate through RF warming and cryoprotective media that reduce DMSO residuals, carving high-margin niches.
White-space opportunities remain around IoT software service contracts that monetize temperature-trace datasets, and within dielectric RF organ-warming where clinical validation is early but strategic interest high.
Thawing System Industry Leaders

*Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- April 2025: Abeona Therapeutics received FDA approval for ZEVASKYN (prademagene zamikeracel), the first cell-based gene therapy for recessive dystrophic epidermolysis bullosa, requiring specialized thawing protocols for genetically modified patient skin cells.
- March 2025: DHL Group acquired CRYOPDP from Cryoport to strengthen pharma logistics, handling over 600,000 temperature-controlled shipments annually across 15 countries.
- March 2025: Teknova and Pluristyx launched the PluriFreeze cryopreservation system to accelerate cell-therapy development and support high-viability thaw outcomes.
- February 2025: Terumo Blood and Cell Technologies introduced the Reveos Automated Blood Processing System in the United States, reducing processing steps and improving blood-center efficiency.
Table of Contents for Thawing System Industry Report
1. Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2. Research Methodology
3. Executive Summary
4. Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding Cell & Gene-Therapy Volumes Require GMP-Grade Thawing Solutions
- 4.2.2 Rising Blood-Component Transfusions Mandate Standardized Fast Thawers
- 4.2.3 Automation Reduces Contamination & Operator Variability
- 4.2.4 Dielectric RF Organ-Warming Unlocks Frozen-Organ Banking
- 4.2.5 Single-Use Closed Thaw Bags Accelerate Equipment Replacement
- 4.2.6 IoT-Enabled Cryochain Analytics Create Service-Revenue Streams
- 4.3 Market Restraints
- 4.3.1 High Capital Cost Of Fully Automated Platforms
- 4.3.2 Container-Device Incompatibility Limits Workflow Flexibility
- 4.3.3 Uneven Temperature Gradients Risk Viability In Large Bags
- 4.3.4 Regulatory Uncertainty For Dielectric Organ Warming
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5. Market Size & Growth Forecasts (Value)
- 5.1 By Device Type
- 5.1.1 Manual Plate-Based Warmers
- 5.1.2 Automated Plate-Based Warmers
- 5.1.3 Automated Water-Bath Thawers
- 5.1.4 Dry-Conduction Thawers
- 5.1.5 Dielectric RF Thawers
- 5.1.6 Others
- 5.2 By Sample Type
- 5.2.1 Blood
- 5.2.2 Cell & Gene-Therapy Vials
- 5.2.3 Embryos & Oocytes
- 5.2.4 Tissues & Organs
- 5.2.5 Others
- 5.3 By End-User
- 5.3.1 Hospitals & Diagnostic Labs
- 5.3.2 Blood Banks & Transfusion Centers
- 5.3.3 Cell-Therapy & Biopharma Manufacturers
- 5.3.4 IVF & Fertility Centers
- 5.3.5 Research Institutes
- 5.3.6 Others
- 5.4 By Thawing Technology
- 5.4.1 Conduction Plate Heating
- 5.4.2 Water-Bath Circulation
- 5.4.3 Dielectric RF Warming
- 5.4.4 Convective Air Warming
- 5.4.5 Microwave / Infra-Red
- 5.4.6 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
6. Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Helmer Scientific
- 6.3.2 Sartorius AG
- 6.3.3 Boekel Scientific
- 6.3.4 Barkey GmbH & Co. KG
- 6.3.5 BioLife Solutions
- 6.3.6 Terumo Corporation
- 6.3.7 Cardinal Health
- 6.3.8 Sarstedt AG & Co. KG
- 6.3.9 CytoTherm
- 6.3.10 Single Use Support
- 6.3.11 Thermo Fisher Scientific
- 6.3.12 GE HealthCare
- 6.3.13 MedCision LLC
- 6.3.14 Plasma Solutions
- 6.3.15 REM? Group
- 6.3.16 Stericox India
- 6.3.17 3M Company
- 6.3.18 Drägerwerk AG & Co. KGaA
- 6.3.19 Eppendorf SE
- 6.3.20 Praxair Cryogenics
7. Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment
Scope and Methodology
As per the scope of the report, thawing systems are used for defrosting biological samples such as plasma, stem cells, etc. Thawing refers to the process of taking a frozen product to a temperature where there is no residual ice. This process is also called defrosting and is simply the opposite of freezing.
The thawing system market is segmented by device type (manual devices, automated devices), sample (blood, embryos, ovum, and other samples), end-user (hospitals & diagnostic laboratories, blood banks & transfusion centers, other end-users), and geography (North America, Europe, Asia-Pacific, Middle East, and Africa, South America). The report also covers the estimated market sizes and trends for 17 countries across major regions globally.
The report offers the value (in USD) for the above segments.
| By Device Type | Manual Plate-Based Warmers | |
| Automated Plate-Based Warmers | ||
| Automated Water-Bath Thawers | ||
| Dry-Conduction Thawers | ||
| Dielectric RF Thawers | ||
| Others | ||
| By Sample Type | Blood | |
| Cell & Gene-Therapy Vials | ||
| Embryos & Oocytes | ||
| Tissues & Organs | ||
| Others | ||
| By End-User | Hospitals & Diagnostic Labs | |
| Blood Banks & Transfusion Centers | ||
| Cell-Therapy & Biopharma Manufacturers | ||
| IVF & Fertility Centers | ||
| Research Institutes | ||
| Others | ||
| By Thawing Technology | Conduction Plate Heating | |
| Water-Bath Circulation | ||
| Dielectric RF Warming | ||
| Convective Air Warming | ||
| Microwave / Infra-Red | ||
| Others | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Rest of Europe | ||
| Asia Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Australia | ||
| Rest of Asia Pacific | ||
| Middle East & Africa | GCC | |
| South Africa | ||
| Rest of Middle East & Africa | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||

