
Spain Vinyl Wallpaper Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 53.5 Million |
| Market Size (2026) | USD 54.94 Million |
| Market Size (2031) | USD 62.77 Million |
| Growth Rate (2026 - 2031) | 2.70 % |
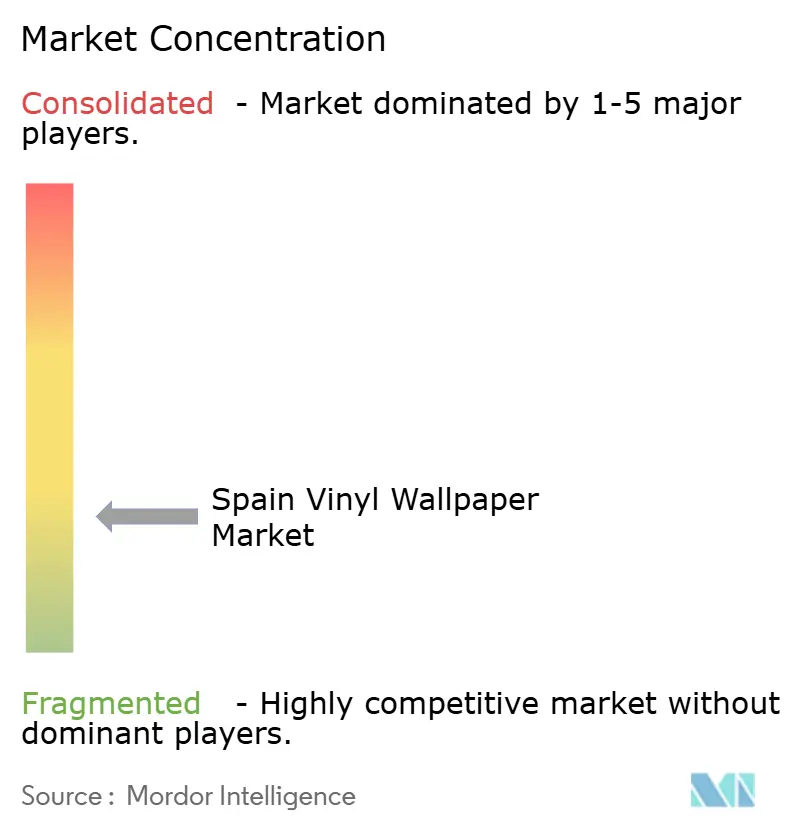
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Spain Vinyl Wallpaper Market Analysis by Mordor Intelligence
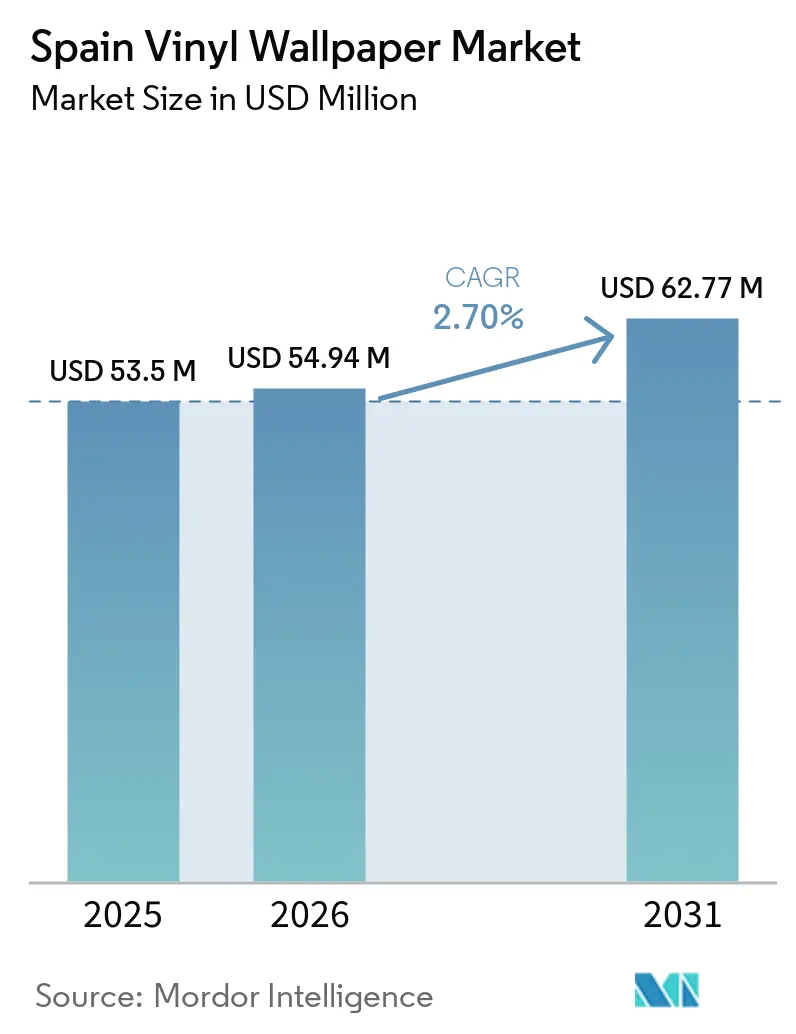
The Spain vinyl wallpaper Market size is expected to grow from USD 53.5 million in 2025 to USD 54.94 million in 2026 and is forecast to reach USD 62.77 million by 2031, growing at a 2.70% CAGR during 2026–2031. The Spanish vinyl wallpaper market is supported by a renovation cycle that has become more important than new construction for many households. Residential rehabilitation rose 11.7% year over year in the fourth quarter of 2025, while budgets for housing extensions and reforms reached EUR 677.2 million in the quarter. Vinyl products suit projects where installers and owners seek durable finishes with limited disruption. Hotel upgrades also create demand for contract products that can meet fire, cleaning, and moisture requirements. Growth is expected to trail the broader Spanish wallcovering category because nonwoven substrates continue to gain share from vinyl in residential projects, while PVC compliance costs and competition from decorative paint limit the pace of expansion.
Key Report Takeaways
- By product type, vinyl-coated paper accounted for the largest value share of the Spanish vinyl wallpaper market, at 43.00% in 2025, while fabric-backed vinyl is projected to grow at the fastest CAGR of 4.75% during 2026-2031.
- By installation type, traditional/non-self-adhesive products accounted for 72.00% of the market in 2025, while self-adhesive/peel-and-stick products are projected to grow at the fastest CAGR of 4.99% during 2026-2031.
- By application, renovation and remodeling accounted for 68.00% of the market in 2025, while new construction is projected to grow at the fastest CAGR of 3.93% during 2026-2031.
- By end user, residential accounted for 68.00% of the market in 2025, while commercial is projected to grow at the fastest CAGR of 4.17% during 2026-2031.
- By distribution channel, B2C channels accounted for 67.00% of the market in 2025, while B2B channels are projected to grow at the fastest CAGR of 4.01% during 2026-2031.
- By geography, Madrid accounted for 20.50% of the market in 2025, while the Canary Islands is projected to grow at the fastest CAGR of 4.25% during 2026-2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Spain Vinyl Wallpaper Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Renovation and remodeling demand | +1.4% | National, with concentration in Madrid, Catalonia, and Andalusia | Medium term (2-4 years) |
| Hospitality refurbishment and tourism-linked fit-out | +0.8% | Canary Islands, Balearic Islands, Costa del Sol, and Barcelona | Short term (≤ 2 years) |
| Washability and durability needs in high-traffic interiors | +0.5% | National, especially hospitality, healthcare, and education | Medium term (2-4 years) |
| Digital and made-to-measure wallcoverings | +0.4% | National, with early traction in Madrid and Barcelona | Long term (≥ 4 years) |
| Rental-friendly peel-and-stick adoption | +0.3% | Madrid, Barcelona, Valencia, and Seville | Medium term (2-4 years) |
| Faster and lower-disruption hotel renovation cycles | +0.3% | Tourism coastal areas and island clusters | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Renovation and Remodeling Demand
Spain recorded 1.9 million home renovation interventions in 2025, and 3 in 10 households made some form of home improvement[1]https://www.andimac.org/2026/03/24/3-de-cada-10-hogares-hicieron-alguna-mejora-de-su-vivienda-en-2025/. The Spanish vinyl wallpaper market benefits because wall finishes are often selected during wider room upgrades. More than 95% of Spain's 27.1 million homes were built before 2009, which leaves a large stock requiring cosmetic and structural work. Funding directed at energy efficiency can bring insulation, heating, and decorative work into the same renovation visit. Spain's 2026–2030 State Housing Plan (Royal Decree 326/2026) allocates at least 30% of its EUR 7 billion budget, about EUR 2.1 billion, to building rehabilitation.[2]https://www.mivau.gob.es/el-ministerio/sala-de-prensa/noticias/jue-29012026-1227.
Hospitality Refurbishment and Tourism-Linked Fit-Out
Tourism remains important to the Spanish vinyl wallpaper market because hotel owners must refresh guest rooms and shared areas regularly. International tourist spending reached EUR 134.7 billion in 2025, up 6.8% from 2024, after Spain received 96.8 million international visitors. Paradores has a EUR 250 million refurbishment plan covering more than half of its network before 2028. The Meliá Sol Torremolinos complex completed a EUR 52 million renovation in 2025. These projects favor suppliers that can provide certified, durable wallcoverings at the project scale. The need for reliable installation schedules also favors products that reduce closure time for hotels.
Washability and Durability Requirements in High-Traffic Interiors
Hotel stays reached 366.7 million in Spain during 2025, which increased cleaning demands in guest rooms, lobbies, and corridors. The Spain vinyl wallpaper market is therefore supported by products that can tolerate repeated wet-cloth cleaning. Contract buyers also assess fire performance under EN 13501-1 when selecting materials for public interiors. The European Construction Products Regulation provides the framework for declaring product performance in relevant construction applications[3]https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX%3A02006R1907-20241010. Type II vinyl products that combine scrub resistance with suitable fire ratings can command stronger specifications. Healthcare and education projects can also favor antimicrobial and low-VOC product ranges.
Growth of Digital and Made-to-Measure Wallcoverings
Digital printing allows shorter production runs than conventional wallpaper methods. FESPA reported that digital production can make custom wallcovering viable for small orders, including projects needing a single roll[4]https://www.fespa.com/en/news-media/the-new-wallpaper-how-digital-printing-and-ai-are-redefining-interior-design. This capability gives interior designers and boutique hotels greater freedom to specify location-specific patterns. The Spain vinyl wallpaper market can gain from this shift where design-led hospitality projects need fast sampling and shorter lead times. Digital production also reduces the commercial risk of holding large inventories for narrow designs. It may be most relevant in Madrid and Barcelona, where designers and boutique operators have early adoption potential.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| PVC and chemical-safety compliance costs | -0.4% | National, affecting all EU manufacturers and importers | Medium term (2-4 years) |
| Competition from nonwoven and paint alternatives | -0.3% | National, strongest in price-sensitive residential B2C | Long term (≥ 4 years) |
| Fire-performance documentation for contract projects | -0.2% | Hospitality, healthcare, and education locations nationwide | Short term (≤ 2 years) |
| Substrate and wall-condition constraints in older housing | -0.2% | Older areas of Madrid, Barcelona, and Andalusia | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
PVC and Chemical-Safety Compliance Costs
REACH requirements have raised compliance demands for manufacturers and importers of PVC-based products. Regulation (EU) 2023/923 sets a lead limit of 0.1% by weight in PVC material, and products above that threshold could not be placed on the EU market from November 28, 2024. The Spain vinyl wallpaper market faces added documentation and reformulation costs as suppliers move away from lead stabilizers. VinylPlus reported that the treatment of certain PVC additives remains under review through REACH and related tools. Smaller distributors that source from outside the European Union face a particular burden in confirming compliance before goods enter the region. These costs can be harder to absorb in lower-priced product categories.
Competition from Nonwoven and Paint Alternatives
Nonwoven wallpaper competes with vinyl through ease of hanging, dimensional stability, and lower PVC content. The Spain vinyl wallpaper market also faces decorative paint in small residential jobs, where paint may require less time and lower upfront spending. Small-format work represented 33% of Spain's renovation activity in 2025. Vinyl retains a functional advantage in kitchens and bathrooms because moisture resistance and washability are important. Suppliers need to demonstrate product life, cleaning performance, and installation efficiency instead of competing only on price. Older and uneven walls can also raise installation complexity, which limits adoption in some homes.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Product Type/Construction Type: Mid-Tier Vinyl Leads, Premium Formats Accelerating
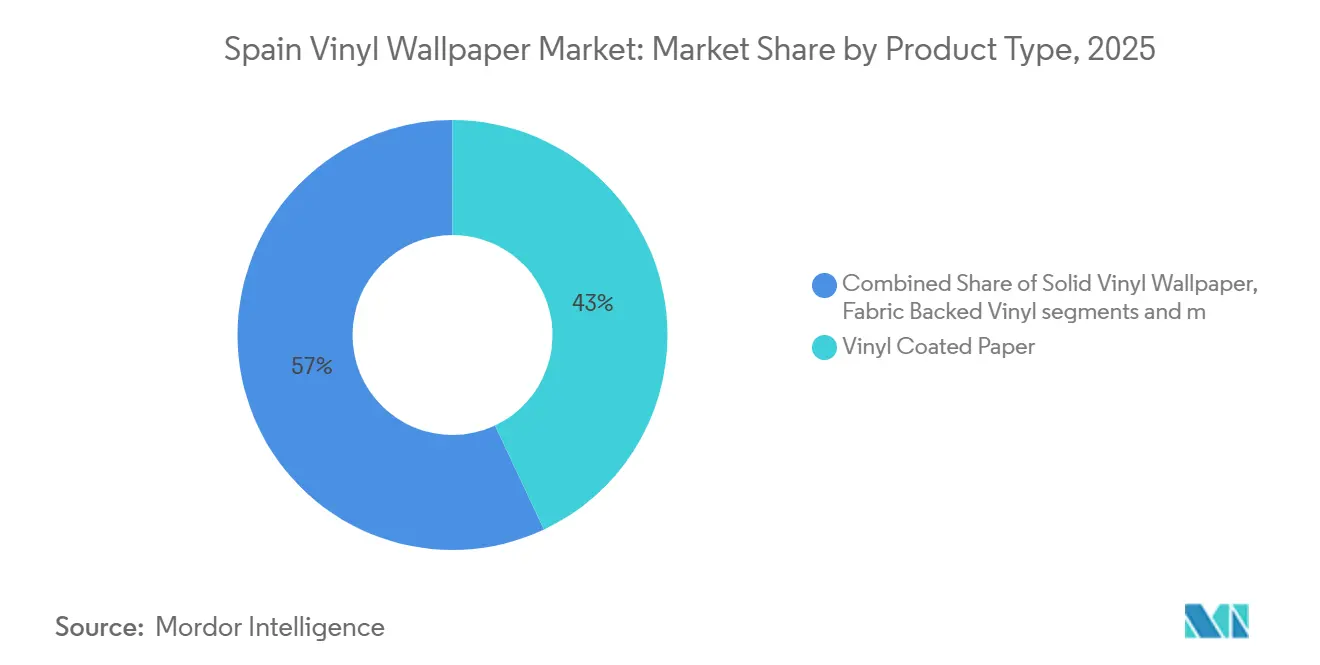
Vinyl-coated paper held 43% of the Spanish vinyl wallpaper market share in 2025. Its lower price point and compatibility with paste-to-wall methods support broad use by professional installers. The format can suit older plaster and concrete surfaces found across Spain's established housing stock. Solid vinyl remains relevant where commercial, healthcare, and institutional settings require strong scrub resistance. Nonwoven vinyl is gaining acceptance in mid- and premium residential projects because paste-to-wall installation can reduce labor time. Comprehensive renovation projects can favor this efficiency when homeowners upgrade several rooms at once. Average spending for a full renovation reached EUR 32,000 in 2025. These choices show that price, wall condition, and installation practice determine the product mix.
Nonwoven vinyl and non-PVC nonwoven substrates are gaining ground in residential DIY projects, which caps vinyl-coated paper's growth. Fabric-backed vinyl is forecast to expand at a 4.75% CAGR during 2026–2031, the highest rate among product types. This segment benefits from hotel projects that seek textured, durable finishes for public spaces. Premium formats can support boutique-style hotel positioning without relying on large standard print runs. Digitally printed specialty products remain smaller in volume but offer scope for designers and independent hotels. Product selection in contract projects must account for fire-performance declarations and cleaning requirements. Certified fabric backed products can meet these criteria while offering a more premium surface finish. The Spain vinyl wallpaper market industry is therefore likely to see lower crowding in premium formats than in vinyl coated paper. This difference gives compliant suppliers a clearer route to higher-value specifications.


By Installation Type: Traditional Holds Firm, Self-Adhesive Reshapes B2C
Traditional and non self-adhesive products held 72% of the Spain vinyl wallpaper market size in 2025. Professional contractors remain central to renovation purchasing, and 41% of renovation buyers relied on recommendations from trusted trade contacts. Paste-applied formats work well on textured and uneven surfaces in older buildings. They also provide installers with a familiar method for large room projects. Nonwoven-backed vinyl has improved the traditional route by allowing paste-to-wall application. This can reduce error rates and material waste. Traditional products will remain important where installation quality and surface tolerance matter most. Their established position limits the speed of substitution in professional projects.
Self-adhesive and peel-and-stick vinyl is forecast to grow at a 4.99% CAGR through 2031. The format suits renters and short-term rental owners who need reversible room updates. Spain's national short-term rental registry, mandatory from July 2025, was annulled by the Supreme Court in May 2026, although regional tourist licences continue to apply. Online sales benefit when visualization tools help buyers assess colors and patterns before purchase. Peel-and-stick products can reduce labor needs and avoid wall-repair costs at move-out. These qualities make self-adhesive products important to the B2C side of the Spain vinyl wallpaper market.
By Application: Renovation Dominates, New Construction Gains Momentum
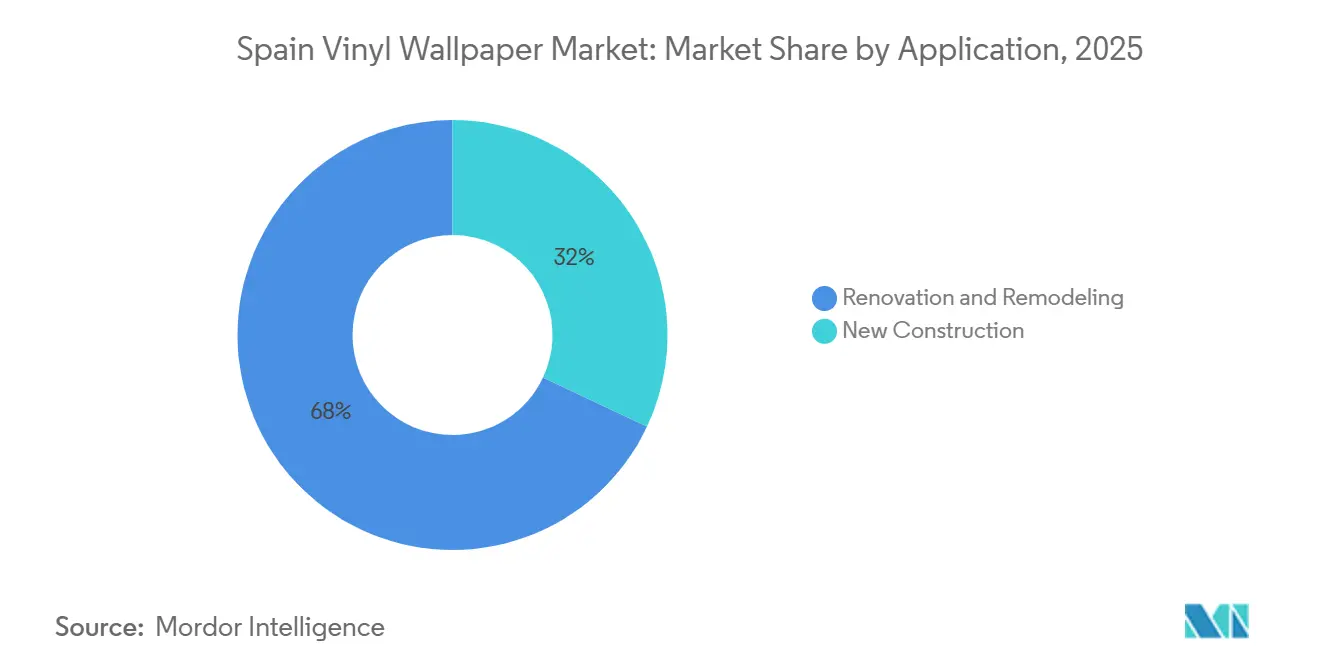
Renovation and remodeling accounted for 68% of the Spanish vinyl wallpaper market size in 2025. Mature housing stock and constrained housing supply keep refurbishment central to demand. Rehabilitation permit budgets reached EUR 667.1 million in the first quarter of 2025, the highest first-quarter level in the available historical series since 1991. Many second-hand home purchases and rental turnovers require cosmetic upgrades before occupancy. Wallcoverings can be selected alongside flooring, bathrooms, kitchens, and energy-efficiency work. Renovation demand is also spread across residential and hospitality properties. This broad base makes the application less dependent on a single property cycle. It remains the main volume base for vinyl products in Spain.
New construction is forecast to grow at a 3.93% CAGR through 2031. Free-market housing starts reached 34,200 in the fourth quarter of 2025, the highest quarterly figure in 17 years. Permits issued in 2025 and 2026 will require finishing materials during later construction phases. Common areas, kitchens, and bathrooms provide potential use cases for developer-selected vinyl wallcovering. The residual new-construction share was 32% in 2025, which leaves room for gradual gains. Growth will depend on developers' finish specifications and the pace of completions. The Spain vinyl wallpaper market should therefore see incremental volume from projects already moving through the pipeline. New construction will not displace renovation as the larger application during the forecast period.
By End User: Residential Anchors Volume, Commercial Drives Value
Residential users held 68% of the Spain vinyl wallpaper market share in 2025. Living rooms, bedrooms, kitchens, bathrooms, and children's rooms each create different demand patterns. Bathrooms and kitchens have strong replacement needs because moisture and daily wear affect wall finishes. In 2025, 10% of Spanish households renovated bathrooms at an average cost of EUR 6,700, while 6.6% renovated kitchens at EUR 9,100. Vinyl can provide a durable option in these wet and semi-wet spaces. Living rooms and bedrooms place more weight on pattern selection and visual preference. Digital printing and broader premium designs can influence the channel and product choice in these rooms.
Commercial use is forecast to grow at a 4.17% CAGR through 2031. Hotels, healthcare facilities, and co-working spaces often require Type II or higher products for durability and fire performance. The commercial segment benefits from hotel refurbishment activity in tourism-intensive areas. It also benefits from modernization work in healthcare and education facilities. Buyers in these settings need product documentation that supports procurement and regulatory review. Antimicrobial and low-VOC wallcoverings can meet part of this specification need. This places greater value on certified ranges and technical support. The Spain vinyl wallpaper industry has a stronger compliance threshold in commercial work than in most household purchases.
By Distribution Channel: B2C Channels Lead, B2B Channels Gain Structural Support
B2C channels held 67% of the Spain vinyl wallpaper market size in 2025. This route includes home centers, specialty wallpaper stores, online sellers, hypermarkets, supermarkets, and local shops. Specialty stores remain useful where buyers need samples, pattern advice, and installation guidance. Local retailers provide access for small contractors in cities where large specialist chains have limited coverage. Home centers have expanded their selections for DIY buyers, particularly for self-adhesive products. Online channels are gaining relevance as digital visualization reduces uncertainty around design choices. Professional recommendations still influence many purchasing decisions. These factors keep B2C channels the largest route to residential renovation buyers.
B2B channels are forecast to grow at a 4.01% CAGR through 2031. Contractors, installers, architects, designers, and institutional procurement teams are included in this channel. Hotel groups and investment owners increasingly consolidate purchases through professionals who can offer certified products and technical support. Architects and designers may also seek exclusive patterns and custom printing for luxury renovation projects. Design-led differentiation can favor suppliers with responsive sampling and specification services. B2B demand can be more concentrated than consumer demand because individual projects require larger volumes. The channel is positioned to gain support as hospitality and institutional upgrades move forward. Its growth reinforces the need for Spanish-language technical documents and reliable delivery.
Geography Analysis
Madrid held the largest regional share at 20.5% in 2025, supported by substantial renovation activity and a persistent housing shortage. The region recorded 216,800 renovation interventions in 2025, up 4.1% from 2024, covering more than 106,500 homes. Madrid province accounted for 27.7% of properties that used Spain’s energy-rehabilitation income-tax deductions between 2021 and 2024. More than 65% of the region’s residential buildings were over 40 years old, which keeps refurbishment central to housing improvement. Andalusia adds a strong commercial base, while Seville province represented 8.5% of properties using rehabilitation deductions.
Catalonia remains an important center for design-led residential and hospitality projects. Barcelona province represented 11.1% of national energy-rehabilitation deduction users, placing the region behind Madrid in renovation activity. The region’s housing policy and urban development activity are expected to support wall-finish demand over the medium term. The Comunitat Valenciana showed particularly strong construction activity, with permits for 19,772 new homes in 2025, up 47.3% from the prior year. Rehabilitation projects also exceeded new construction in permit volume in Valencia for the first time in 2025. These conditions support both residential replacement demand and specification-led commercial projects.
The Canary Islands is forecast to be the fastest-growing regional market, with a 4.25% CAGR during 2026–2031. Its tourism economy supports regular hotel upgrades and new hospitality development, creating recurring demand for contract-grade vinyl wallcoverings. The Balearic Islands also generate concentrated commercial demand because hospitality properties require durable finishes that can withstand frequent cleaning and guest turnover. Northern regions, including the Basque Country, Navarre, and Galicia, provide steady renovation demand from older housing stock. Regional differences are shaped mainly by tourism intensity, building age, housing activity, and the mix of residential and commercial projects.
Competitive Landscape
The Spain vinyl wallpaper market is fragmented because no supplier has a dominant position across both B2C residential and B2B contract channels. Grandeco Wallfashion Group, A.S. Création Tapeten AG, Tapetenfabrik Gebr. Rasch, Muraspec, Koroseal, and Kemen Wallcoverings/Vinelus SA are relevant participants. Mid-market residential vinyl is more crowded than premium fabric-backed and digitally printed products. This creates tighter competition in the vinyl-coated paper category. Contract suppliers differentiate through fire ratings, antimicrobial attributes, acoustic performance, washability, and documented compliance. Buyers in hospitality, healthcare, and education can place more weight on these factors than on the headline price. The absence of disclosed combined shares for leading firms prevents a more precise concentration assessment. The market remains accessible to specialized suppliers that can meet project requirements.
A.S. Création introduced the walls by Patel V digital collection at Heimtextil 2026 and released Metropolitan Stories: Vibes & Styles in February 2026. These moves support shorter-run, design-responsive product development. Muraspec launched more than 200 new designs in 2025. It also established a global wallcovering partnership with FARM RIO for bespoke printed projects. These actions show how design variety and digital capability can complement technical performance. Suppliers with established product files can have an advantage where projects need fast approval. The Spain vinyl wallpaper market is likely to reward firms that pair design service with compliant product ranges.
Muraspec and Koroseal compete in the contract segment through performance credentials rather than price alone. Koroseal's 2025 additions to its specialty range were positioned for high-end hospitality and corporate interiors. A potential opening remains in design-led vinyl products for independent Spanish hotels. Suppliers addressing this space need quick turnaround, fire-class documentation, and Spanish-language support. Sustainable additive systems and fire-retardant substrates will remain important areas of product development. These requirements can disadvantage undifferentiated importers with limited compliance documentation. They can also support established suppliers that have certified products across several performance levels. Competition is strongest where products are interchangeable and weakest where projects require tailored design and technical service.
Spain Vinyl Wallpaper Industry Leaders
Kemen Wallcoverings / Vinelus, SA
ICH Papeles Pintados
Gerflor Spain
A.S. Création Tapeten AG
Grandeco Wallfashion Group Belgium NV
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- February 2026: A.S. Création Tapeten AG launched its Metropolitan Stories: Vibes & Styles collection at Heimtextil 2026, following the walls by patel V digital print collection premiered in January 2026 at Frankfurt, signaling an accelerated cadence of design releases targeting interior designers and professional specifiers.
- May 2025: Koroseal introduced 8 new Arte specialty wallcoverings in 86 total colorways, inspired by natural textures including weathered metals, woven flax, and boucle, positioning them for high-end hospitality and corporate interiors specification.


Spain Vinyl Wallpaper Market Report Scope
| Solid Vinyl Wallpaper |
| Vinyl Coated Paper |
| Fabric Backed Vinyl |
| Non-Woven Vinyl Wallpapers |
| Other Product Type |
| Traditional/Non-Self-Adhesive |
| Self-Adhesive / Peel-and-Stick Vinyl Wallpaper |
| New Construction |
| Renovation and Remodeling |
| Residential | Living Room |
| Kitchen | |
| Bedroom | |
| Bathroom | |
| Kids Room | |
| Commercial |
| B2C Channels | Hypermarkets and Supermarkets |
| Specialty Wallpaper Stores | |
| Home Centers | |
| Online | |
| Local Shops (unorganized channels) | |
| Other Distribution Channels | |
| B2B Channels (Contractors and Installers, Interior Designers and Architects, Project Procurement and Institutional Sales) |
| Andalusia |
| Catalonia |
| Madrid |
| València |
| Canary Islands |
| Rest of Spain |
| By Product Type/Construction Type | Solid Vinyl Wallpaper | |
| Vinyl Coated Paper | ||
| Fabric Backed Vinyl | ||
| Non-Woven Vinyl Wallpapers | ||
| Other Product Type | ||
| By Installation Type | Traditional/Non-Self-Adhesive | |
| Self-Adhesive / Peel-and-Stick Vinyl Wallpaper | ||
| By Application | New Construction | |
| Renovation and Remodeling | ||
| By End User | Residential | Living Room |
| Kitchen | ||
| Bedroom | ||
| Bathroom | ||
| Kids Room | ||
| Commercial | ||
| By Distribution Channel | B2C Channels | Hypermarkets and Supermarkets |
| Specialty Wallpaper Stores | ||
| Home Centers | ||
| Online | ||
| Local Shops (unorganized channels) | ||
| Other Distribution Channels | ||
| B2B Channels (Contractors and Installers, Interior Designers and Architects, Project Procurement and Institutional Sales) | ||
| By Geography | Andalusia | |
| Catalonia | ||
| Madrid | ||
| València | ||
| Canary Islands | ||
| Rest of Spain | ||


Key Questions Answered in the Report
What is the projected value of the Spain vinyl wallpaper market by 2031?
It is estimated at USD 54.94 million in 2026 and is forecast to reach USD 62.77 million by 2031.
Which product type leads vinyl wallpaper sales in Spain?
Vinyl coated paper, with a 43.00% share in 2025.
Which installation type is growing fastest in Spain?
Self-adhesive and peel-and-stick vinyl wallpaper is projected to grow at a 4.99% CAGR through 2031.
Why is renovation important for vinyl wallcovering demand in Spain?
Renovation and remodeling held 68% share in 2025, while 1.9 million home renovation interventions were recorded during that year.
Which end users are likely to increase purchases most quickly?
Commercial users are forecast to grow at a 4.17% CAGR through 2031, led by hospitality, healthcare, and other specification-driven projects.
Page last updated on:


 Your data is secure and never sold or shared.



