
Market Overview
| Study Period | 2017 - 2029 |
|---|---|
| Forecast Data Period | 2025 - 2029 |
| Historical Data Period | 2017 - 2023 |
| Market Size (2025) | USD 10.43 Billion |
| Market Size (2029) | USD 16.81 Billion |
| Growth Rate (2025 - 2029) | 12.67 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |

Spain Light Commercial Vehicles Market Analysis by Mordor Intelligence
The Spain Light Commercial Vehicles Market size is estimated at 10.43 billion USD in 2025, and is expected to reach 16.81 billion USD by 2029, growing at a CAGR of 12.67% during the forecast period (2025-2029).
The Spanish light commercial vehicles (LCV) market continues to evolve amid changing industry dynamics and technological advancements. Traditional diesel powertrains maintain their dominance, accounting for over 75% of the market in 2022, though this share is gradually declining as alternative powertrains gain traction. The market landscape is characterized by increasing consolidation among major manufacturers, with established players focusing on expanding their product portfolios through strategic partnerships and investments. This transformation is particularly evident in the emergence of new manufacturing facilities and the adaptation of existing plants to accommodate evolving vehicle technologies.
The market demonstrates strong segmentation based on vehicle types and use cases, with panel vans emerging as the predominant choice for commercial operations. These vehicles have proven particularly valuable in urban logistics and last-mile delivery applications, where their maneuverability and cargo capacity offer significant advantages. The surge in e-commerce activities has further accelerated the demand for versatile light duty vehicles, particularly in metropolitan areas where efficient goods movement is crucial. Small trucks and pickup trucks continue to serve specific niches, particularly in the construction, agriculture, and utilities sectors.
Significant investments in manufacturing infrastructure are reshaping the Spanish LCV landscape. A notable example is Volkswagen's EUR 10 billion commitment to establish a battery facility and expand electric vehicle production capabilities in Spain, demonstrating the industry's shift toward electrification. This investment encompasses partnerships with renewable energy providers and represents a broader trend of manufacturers integrating sustainable practices into their production processes. The establishment of such facilities is creating new employment opportunities and strengthening Spain's position as a key automotive manufacturing hub in Europe.
Technological innovation and sustainability initiatives are becoming increasingly central to market development. Manufacturers are incorporating advanced driver assistance systems (ADAS) and connectivity features across their LCV ranges, responding to growing demand for safer and more efficient commercial transport vehicles. The integration of electric powertrains is gaining momentum, with electric variants expected to capture more than 15% of the market share in 2023. This transition is supported by improvements in battery technology and the gradual expansion of charging infrastructure, though adoption rates vary significantly across different commercial applications and regions.
Spain Light Commercial Vehicles Market Trends and Insights
Increasing demand for electric vehicles in Spain is driven by government subsidies and initiatives
- The Spanish automobile industry has been growing continuously over the past few years, and the demand for electric vehicles has grown significantly in recent years, especially after 2020. Various government practices in terms of rebates, such as in March 2021, the government of Spain expanded the budget for the Moves II subsidy program from EUR 100 million to EUR 120 million. Under the program, the light commercial vehicle will be subsidized by EUR 3,630, and heavy commercial vehicle buyers are eligible for a subsidy of EUR 6,000. As a result, electric commercial vehicles witnessed an annual growth of 51.06% in 2021 compared to 2020 across Spain.
- The electric car industry in Spain has also grown tremendously in recent years. In 2020, the government of Spain announced a target of having at least 5 million electric vehicles by 2030. The impact of government norms and subsidies offered has contributed to the growth in the sales of electric cars. Such factors have encouraged consumers to opt for EVs. As a result, the country witnessed a growth in the sale of electric cars by 17.90% in 2022 over 2021.
- The government and various companies are making efforts through various projects that are going to accelerate electric mobility in Spain. In March 2023, the government introduced the Moves 3 plan in Europe, including Spain. The government offered subsidies of EUR 4,500 (without scrapping) and EUR 7,000 (with scrapping) for electric vehicles; the plan was offered until December 31, 2023. Such offerings are expected to accelerate the demand for electric cars in Spain between 2024 and 2030.

OTHER KEY INDUSTRY TRENDS COVERED IN THE REPORT
- Spain's population growth trend indicates a promising future trajectory requiring proactive infrastructure and healthcare planning for sustained development
- Spain's CVP is projected to increase in 2024, indicating a gradual recovery in the automotive market and consumer confidence, possibly driven by government incentives and sustainability trends
- Spain's auto interest rates have been steadily declining, mirroring the broader monetary policies of the European Central Bank and reflecting a trend toward economic stability and growth in the country
- The demand for EVs is on the rise because of falling battery prices and rising domestic production in Spain
- Spain's strategic location and maritime strength have cemented its role in European logistics. Achieving an LPI score of 3.9 in 2023, Spain's emphasis on timeliness and ongoing infrastructure investments highlight its commitment to logistics excellence and future sustainability in the industry
- In 2022, Mercedes-Benz led Spain's light commercial vehicle market, with Fiat making a notable entry. The future may favor eco-friendly vehicles, with emerging brands challenging established leaders
- Spain's GDP per capita experienced fluctuations but is expected to rebound, reaching USD 37,651.90 by 2030
- Spain's inflation, tied to global economic shifts, is expected to stabilize for economic confidence
- Spain's EV charging network surges to 12,200 stations, fueled by government initiatives and green mobility push
- The growing electrification in Spain drives the launch of new electric vehicle models and partnerships for electric bus production
- Owing to high fuel prices, a discount of USD 0.2 per liter was applied to the retail price as a subsidy by the Spanish government in 2022
Segment Analysis: Vehicle Type
Light Commercial Pick-up Trucks Segment in Spanish LCV Market
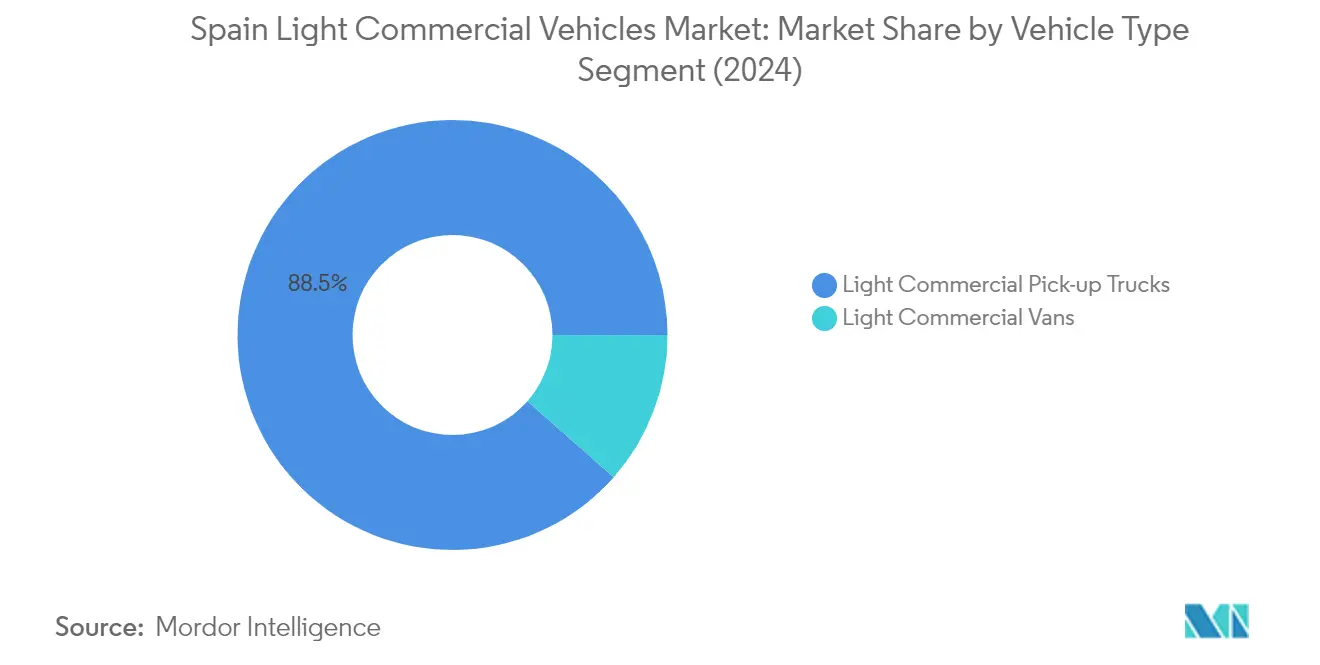
Light commercial pick-up trucks dominate the Spanish light commercial vehicles market, commanding approximately 89% market share in 2024. This segment's strong position is attributed to the versatility and utility these vehicles offer across various commercial applications. The segment's popularity is driven by their robust performance capabilities, making them ideal for construction, agriculture, and logistics sectors. These vehicles are particularly valued for their ability to handle heavy payloads while maintaining operational efficiency. The segment has also seen significant technological advancements, with manufacturers introducing advanced safety features and improved fuel efficiency. Additionally, the growing e-commerce sector and last-mile delivery requirements have further strengthened the demand for pick-up trucks in Spain's commercial vehicle landscape.

Light Commercial Vans Segment in Spanish LCV Market
The light commercial vans segment is experiencing the fastest growth in the Spanish LCV market, with a projected growth rate of approximately 12% between 2024 and 2029. This remarkable growth is primarily driven by the expanding e-commerce sector and increasing demand for urban delivery van solutions. The segment is witnessing significant innovation in terms of electrification, with manufacturers introducing new electric van models specifically designed for urban last-mile delivery. The growth is further supported by the implementation of low-emission zones in major Spanish cities, encouraging businesses to adopt more environmentally friendly delivery vehicles. Additionally, improvements in van design, focusing on enhanced cargo capacity and maneuverability in urban environments, are making these vehicles increasingly attractive to businesses operating in congested city centers.
Segment Analysis: Propulsion Type
ICE Segment in Spain Light Commercial Vehicles Market
The Internal Combustion Engine (ICE) segment continues to dominate the Spanish light commercial vehicles market, commanding approximately 91% market share in 2024. This dominance is primarily driven by the widespread acceptance of diesel vehicles, which remain the preferred choice for commercial operations due to their superior fuel efficiency and established infrastructure. The segment's strength is further reinforced by the lower acquisition costs compared to alternative powertrains, making ICE vehicles particularly attractive to small and medium enterprises. Diesel engines lead the ICE category, followed by gasoline variants, while CNG and LPG vehicles maintain a smaller but steady presence in the market. The segment's resilience is supported by the extensive service network, proven reliability, and the ability to handle diverse commercial applications across urban and rural environments.
FCEV Segment in Spain Light Commercial Vehicles Market
The Fuel Cell Electric Vehicle (FCEV) segment is emerging as the fastest-growing propulsion type in the Spanish LCV market, with a projected growth rate of approximately 61% between 2024 and 2029. This remarkable growth trajectory is driven by increasing investments in hydrogen infrastructure, government support for zero-emission commercial vehicles, and growing awareness of FCEVs' advantages in long-haul operations. The segment is benefiting from technological advancements that are improving fuel cell efficiency and reducing production costs. Major automotive manufacturers are expanding their FCEV offerings, particularly in the commercial vehicle segment, recognizing the technology's potential for heavy-duty applications. The growth is further supported by Spain's commitment to developing a hydrogen corridor and establishing refueling infrastructure across major transportation routes.
Remaining Segments in Propulsion Type
The remaining propulsion segments, including Battery Electric Vehicles (BEV), Hybrid Electric Vehicles (HEV), and Plug-in Hybrid Electric Vehicles (PHEV), are playing increasingly important roles in shaping the Spanish LCV market's transition towards sustainable mobility. BEVs are gaining traction in urban delivery applications, benefiting from zero-emission zones and lower operating costs. HEVs offer a practical bridge between conventional and fully electric powertrains, providing improved fuel efficiency without range anxiety. PHEVs combine the benefits of both electric and conventional powertrains, making them suitable for businesses requiring flexibility in their operations. These alternative propulsion technologies are supported by expanding charging infrastructure and government incentives aimed at reducing commercial vehicle emissions.
Competitive Landscape
Top Companies in Spain Light Commercial Vehicles Market
The Spanish light commercial vehicles market is characterized by intense competition and continuous innovation among major players. Companies are making substantial investments in manufacturing facilities and electric vehicle technology to capture market share and meet evolving customer demands. Strategic partnerships, particularly in battery development and charging infrastructure, have become increasingly common as manufacturers prepare for the electric transition. Product innovation focuses on developing more fuel-efficient vehicles, enhanced safety features, and improved connectivity solutions. Companies are also expanding their distribution networks and after-sales service capabilities to strengthen their market presence. The industry has witnessed a significant shift towards sustainable mobility solutions, with manufacturers introducing hybrid and electric variants across their product portfolios. Additionally, companies are investing in digitalization and smart manufacturing processes to improve operational efficiency and meet customization demands.
Consolidated Market with Strong Global Players
The Spanish light commercial vehicles market is highly consolidated, dominated by established global automotive manufacturers with extensive production and distribution networks. These major players leverage their international experience, technological capabilities, and economies of scale to maintain their competitive positions. The market structure favors large conglomerates that can invest heavily in research and development, manufacturing facilities, and marketing initiatives. Local specialists primarily operate in niche segments or serve as suppliers to the major manufacturers, contributing to the industry's value chain.
The market has witnessed several strategic mergers and acquisitions aimed at strengthening market positions and acquiring technological capabilities. These consolidation activities have primarily focused on expanding electric vehicle capabilities and enhancing digital solutions. Companies are also forming joint ventures and strategic alliances to share development costs and reduce risks associated with new technology adoption. The competitive landscape is further shaped by the presence of strong dealer networks and well-established after-sales service infrastructure, which act as significant barriers to entry for new players.
Innovation and Sustainability Drive Future Success
For incumbent players to maintain and increase their market share, focusing on technological innovation and sustainable mobility solutions is crucial. Companies need to invest in developing advanced electric powertrains, autonomous driving capabilities, and connected vehicle technologies. Building strong relationships with suppliers, particularly in the electric vehicle component sector, will be essential for ensuring supply chain resilience. Additionally, manufacturers must optimize their production processes to achieve cost efficiencies while maintaining product quality and meeting customization demands.
Contenders looking to gain ground in the market need to focus on identifying and serving underserved segments or regions. This includes developing specialized commercial transport vehicles for specific commercial applications or targeting emerging market opportunities in the electric vehicle segment. Success will depend on building strong distribution networks, offering competitive financing solutions, and providing excellent after-sales service. The regulatory environment, particularly regarding emissions standards and urban access restrictions, will continue to shape market dynamics and influence product development strategies. Companies must also consider the increasing importance of total cost of ownership in purchase decisions and adapt their value propositions accordingly.
Spain Light Commercial Vehicles Industry Leaders
-
Fiat Chrysler Automobiles N.V
-
Ford Motor Company
-
Groupe Renault
-
Peugeot S.A.
-
Volkswagen AG
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- June 2023: FORD NEXT launches New pilot program creates flexible electric solutions for drivers who use the Uber platform in select U.S. markets, allowing them to lease a vehicle for more customized time periods.
- June 2023: Mercedes-Benz extended the availability of its DRIVE PILOT system to California, marking a significant milestone. Furthermore, it is introducing a SAE Level 3 system, a first in a standard-production vehicle, for use on public freeways in the state.
- May 2023: Mercedes Benz Vans is set to introduce its new electric small van, the eCitan, designed specifically for inner-city deliveries and servicing. The eCitan comes in two size variants: a compact version measuring 4498 mm and a larger one at 5922 mm.
Spain Light Commercial Vehicles Market Report Scope
Commercial Vehicles are covered as segments by Vehicle Type. Hybrid and Electric Vehicles, ICE are covered as segments by Propulsion Type. Vehicle Type
| Commercial Vehicles | Light Commercial Pick-up Trucks |
| Light Commercial Vans |
Propulsion Type
| Hybrid and Electric Vehicles | By Fuel Category | BEV |
| FCEV | ||
| HEV | ||
| PHEV | ||
| ICE | By Fuel Category | CNG |
| Diesel | ||
| Gasoline | ||
| LPG |
| Vehicle Type | Commercial Vehicles | Light Commercial Pick-up Trucks | |
| Light Commercial Vans | |||
| Propulsion Type | Hybrid and Electric Vehicles | By Fuel Category | BEV |
| FCEV | |||
| HEV | |||
| PHEV | |||
| ICE | By Fuel Category | CNG | |
| Diesel | |||
| Gasoline | |||
| LPG | |||
Market Definition
- Vehicle Type - The category covers light commercial vehicle.
- Vehicle Body Type - This includes Light Commercial Pick-up Trucks and Light Commercial Vans.
- Fuel Category - The category includes various fuel types such as Gasoline, Diesel, LPG (Liquefied Petroleum Gas), CNG (Compressed Natural Gas), HEV (Hybrid Electric Vehicles), PHEV (Plug-in Hybrid Electric Vehicles), BEV (Battery Electric Vehicles), and FCEV (Fuel Cell Electric Vehicles)
| Keyword | Definition |
|---|---|
| Electric Vehicle (EV) | A vehicle which uses one or more electric motors for propulsion. Includes cars, buses, and trucks. This term includes all-electric vehicles or battery electric vehicles and plug-in hybrid electric vehicles. |
| BEV | A BEV relies completely on a battery and a motor for propulsion. The battery in the vehicle must be charged by plugging it into an outlet or public charging station. BEVs do not have an ICE and hence are pollution-free. They have a low cost of operation and reduced engine noise as compared to conventional fuel engines. However, they have a shorter range and higher prices than their equivalent gasoline models. |
| PEV | A plug-in electric vehicle is an electric vehicle that can be externally charged and generally includes all-electric vehicles as well as plug-in hybrids. |
| Plug-in Hybrid EV | A vehicle that can be powered either by an ICE or an electric motor. In contrast to normal hybrid EVs, they can be charged externally. |
| Internal combustion engine | An engine in which the burning of fuels occurs in a confined space called a combustion chamber. Usually run with gasoline/petrol or diesel. |
| Hybrid EV | A vehicle powered by an ICE in combination with one or more electric motors that use energy stored in batteries. These are continually recharged with power from the ICE and regenerative braking. |
| Commercial Vehicles | Commercial vehicles are motorized road vehicles designed for transporting people or goods. The category includes light commercial vehicles (LCVs) and medium and heavy-duty vehicles (M&HCV). |
| Passenger Vehicles | Passenger cars are electric motor– or engine-driven vehicles with at least four wheels. These vehicles are used for the transport of passengers and comprise no more than eight seats in addition to the driver’s seat. |
| Light Commercial Vehicles | Commercial vehicles that weigh less than 6,000 lb (Class 1) and in the range of 6,001–10,000 lb (Class 2) are covered under this category. |
| M&HDT | Commercial vehicles that weigh in the range of 10,001–14,000 lb (Class 3), 14,001–16,000 lb (Class 4), 16,001–19,500 lb (Class 5), 19,501–26,000 lb (Class 6), 26,001–33,000 lb (Class 7) and above 33,001 lb (Class 8) are covered under this category. |
| Bus | A mode of transportation that typically refers to a large vehicle designed to carry passengers over long distances. This includes transit bus, school bus, shuttle bus, and trolleybuses. |
| Diesel | It includes vehicles that use diesel as their primary fuel. A diesel engine vehicle have a compression-ignited injection system rather than the spark-ignited system used by most gasoline vehicles. In such vehicles, fuel is injected into the combustion chamber and ignited by the high temperature achieved when gas is greatly compressed. |
| Gasoline | It includes vehicles that use gas/petrol as their primary fuel. A gasoline car typically uses a spark-ignited internal combustion engine. In such vehicles, fuel is injected into either the intake manifold or the combustion chamber, where it is combined with air, and the air/fuel mixture is ignited by the spark from a spark plug. |
| LPG | It includes vehicles that use LPG as their primary fuel. Both dedicated and bi-fuel LPG vehicles are considered under the scope of the study. |
| CNG | It includes vehicles that use CNG as their primary fuel. These are vehicles that operate like gasoline-powered vehicles with spark-ignited internal combustion engines. |
| HEV | All the electric vehicles that use batteries and an internal combustion engine (ICE) as their primary source for propulsion are considered under this category. HEVs generally use a diesel-electric powertrain and are also known as hybrid diesel-electric vehicles. An HEV converts the vehicle momentum (kinetic energy) into electricity that recharges the battery when the vehicle slows down or stops. The battery of HEV cannot be charged using plug-in devices. |
| PHEV | PHEVs are powered by a battery as well as an ICE. The battery can be charged through either regenerative breaking using the ICE or by plugging into some external charging source. PHEVs have a better range than BEVs but are comparatively less eco-friendly. |
| Hatchback | These are compact-sized cars with a hatch-type door provided at the rear end. |
| Sedan | These are usually two- or four-door passenger cars, with a separate area provided at the rear end for luggage. |
| SUV | Popularly known as SUVs, these cars come with four-wheel drive, and usually have high ground clearance. These cars can also be used as off-road vehicles. |
| MPV | These are multi-purpose vehicles (also called minivans) designed to carry a larger number of passengers. They carry between five and seven people and have room for luggage too. They are usually taller than the average family saloon car, to provide greater headroom and ease of access, and they are usually front-wheel drive. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all its reports.
- Step-1: Identify Key Variables: To build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built based on these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. Market revenue is calculated by multiplying the sales volume with their respective average selling price (ASP). While estimating ASP factors like average inflation, market demand shift, manufacturing cost, technological advancement, and varying consumer preference, among others have been taken into account.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


