
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
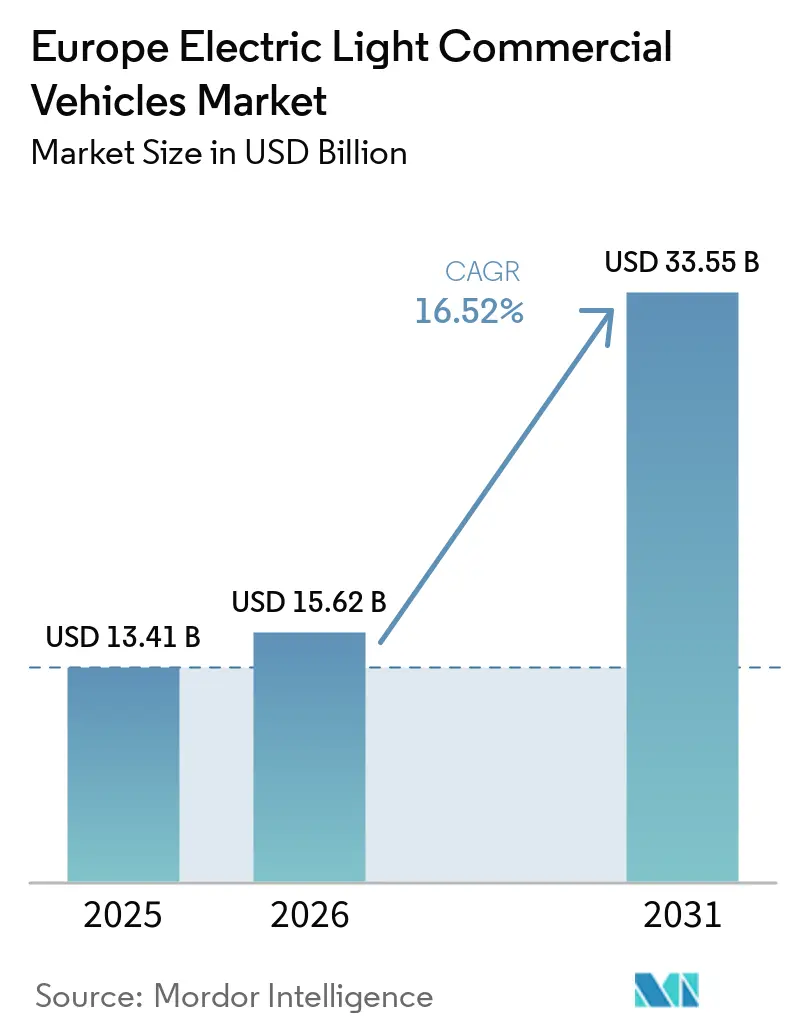
| Base Year Market Size (2025) | USD 13.41 Billion |
| Market Size (2026) | USD 15.62 Billion |
| Market Size (2031) | USD 33.55 Billion |
| Growth Rate (2026 - 2031) | 16.52 % |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Electric Light Commercial Vehicles Market Analysis by Mordor Intelligence
The European electric light commercial vehicles market was valued at USD 13.41 billion in 2025, is estimated at USD 15.62 billion in 2026, and is projected to reach USD 33.55 billion by 2031, growing at a CAGR of 16.52% from 2026 to 2031. Fleet decarbonization mandates, rapid declines in battery prices, and tighter EU fleet-average CO₂ targets are combining to push replacement cycles forward from 6 to fewer than 4 years. Urban access regulations now impose daily charges that dwarf electricity costs, so logistics operators accelerate battery-electric procurement to avoid diesel penalties. Battery platform sharing across passenger and commercial lines is compressing per-unit costs, while public–private partnerships along the trans-European transport network ensure that depot and corridor charging will scale in parallel. Grid-connection delays and fragmented homologation above 3.5 tons remain the key friction points, yet their drag is outweighed by financial incentives and the looming 2030 compliance cliff for manufacturers.
Key Report Takeaways
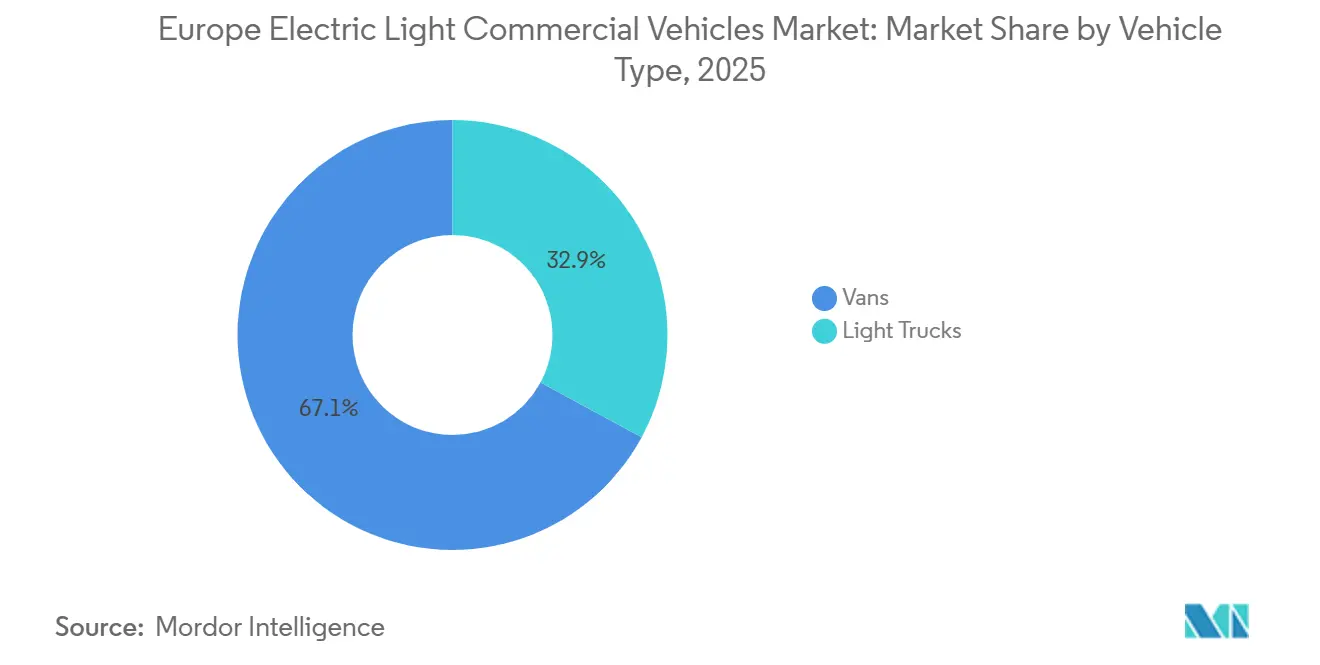
- By vehicle type, vans commanded 67.12% of the European electric LCV market share in 2025, and light trucks are forecast to expand at a 19.91% CAGR through 2031.
- By propulsion, battery-electric variants captured 80.41% of the market in 2025, while fuel-cell electric vehicles led growth at a 21.78% CAGR between 2026 and 2031.
- By tonnage, light e-LCVs below 3.5 tonnes accounted for 75.73% of the European electric LCV market in 2025, and medium-duty models are advancing at a 19.22% CAGR through 2031.
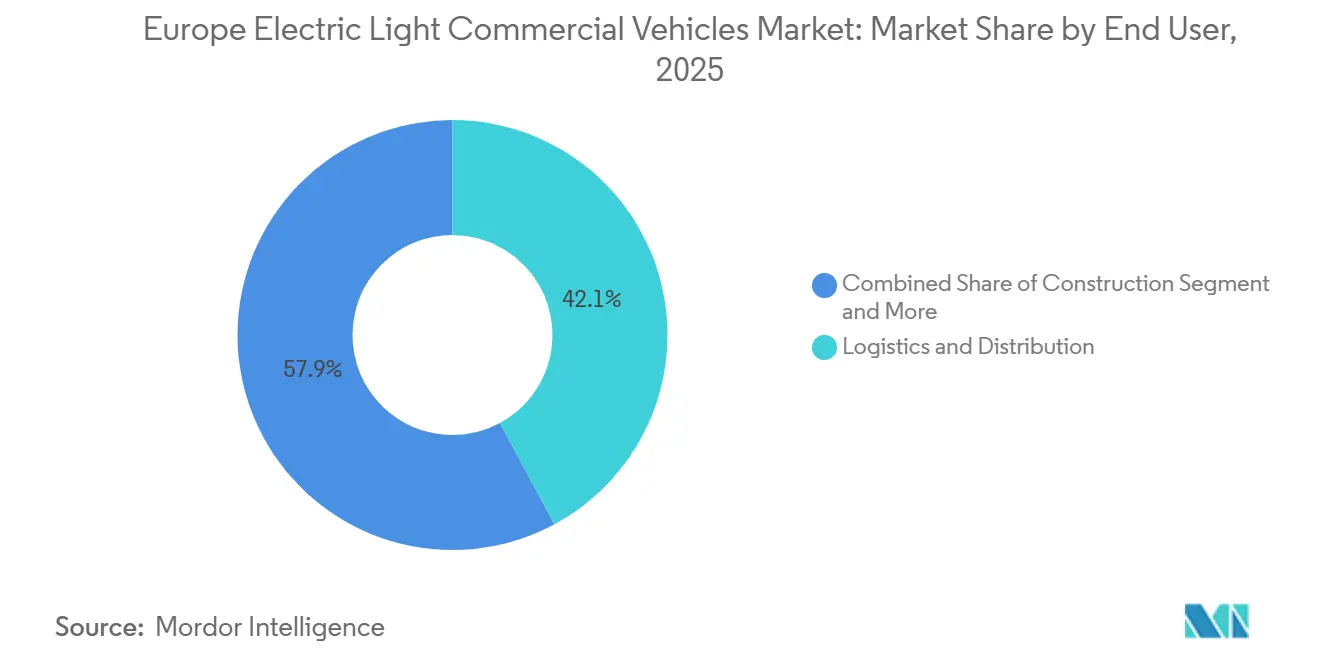
- By end-user, logistics and distribution led with 42.14% revenue share in 2025; mining and energy applications are projected to expand at an 18.43% CAGR through 2031.
- By ownership model, outright purchases accounted for 55.33% of 2025 demand, whereas leased and fleet-management solutions are growing at a 17.12% CAGR through 2031.
- By country, Germany held a 25.82% share of the European electric LCV market size in 2025 and is set to post a 17.81% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Europe Electric Light Commercial Vehicles Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Corporate Fleets Push for Decarbonization | +4.2% | Germany, France, UK, Benelux with spillover to Nordics | Medium term (2-4 years) |
| Rapid Decline in Battery-Pack USD/kWh | +3.8% | Pan-European, strongest in high-volume Germany, France, UK | Long term (≥4 years) |
| EU Fit-For-55 Targets Tighten for CO₂ Fleet-Average | +3.5% | EU27 plus UK, Norway under EEA alignment | Short term (≤2 years) |
| E-LCVs to Match Diesel Cost in Less than 4 Years | +2.3% | Western Europe core (Germany, France, UK, Benelux); lagging in Eastern Europe | Medium term (2-4 years) |
| Urban Surge in Zero-Emission Zones | +2.1% | Major metro areas: London, Paris, Amsterdam, Milan, Madrid, Berlin | Short term (≤2 years) |
| PPP Rollouts for Charging Infrastructure in TEN-T Corridors | +1.3% | Germany, France, Italy, Spain along trans-European transport network | Long term (≥4 years) |
| Source: Mordor Intelligence | |||
Accelerated Corporate Fleet Decarbonization Mandates
Multinational operators such as DHL and Amazon are committing to net-zero timelines that mandate minimum electric penetration for last-mile fleets, creating predictable off-take volumes that lower OEM investment risk [1]. The Corporate Sustainability Reporting Directive mandated Scope 3 disclosures and integrated lifecycle carbon accountability into sourcing protocols. This shift prompts procurement teams to adopt total cost of ownership models, emphasizing the value of avoided CO₂ emissions. For urban routes under 150 km per day, battery-electric vans achieve cost parity with diesel counterparts in under 3 years, factoring in maintenance savings and low-emission zone fees. In temperature-controlled logistics, electric refrigeration not only reduces costs by eliminating the need for an auxiliary diesel genset but also lowers particulate emissions in residential areas. This transition creates a self-reinforcing cycle: corporate climate commitments boost demand, substantial fleet orders bolster residual-value expectations, and OEMs introduce specialized platforms, further driving down costs.
Rapid Decline in Battery-Pack USD/kWh
Average battery prices dipped to USD 115 per kWh, down from previous levels, driven by cell-to-pack integration and rising adoption of lithium-iron-phosphate chemistry. European gigafactories, including those owned by ACC, CATL, and PowerCo, are eyeing sub-EUR 90 costs, leveraging vertical integration of cathode precursor supply. Lithium-iron-phosphate (LFP) now powers a significant percentage of European electric light commercial vehicle (e-LCV) packs, achieving material savings while delivering a performance suitable for urban duty cycles. Achieving upfront purchase parity with diesel vans hinges on further module cost reductions; at this price, a pack competes directly with a diesel powertrain. While lithium price volatility poses challenges, the EU Critical Raw Materials Act, with its emphasis on long-term supply contracts and bolstered local refining capacity, is poised to dampen short-term fluctuations.
EU Fit-for-55 CO₂ Fleet-Average Targets Tightening
Van fleet limits drop from 153.9 g/km in 2025 to 90.6 g/km by 2030, with penalties of EUR 95 per g/km per vehicle for non-compliance[2]. Manufacturers, therefore, pledge 100% battery-electric line-ups well before the 2035 zero-emission deadline. The Commission’s 2025 Automotive Package flirts with a 90 % relief option, yet OEM models suggest it costs less to go fully electric than to juggle small legacy volumes of compliant hybrids. Harmonized type-approval procedures under Regulation (EU) 2018/858 further reduce regulatory complexity and shield suppliers from fragmentation across member states. As a result, product roadmaps for 2027–2029 are locked in around a dedicated BEV chassis.
Urban Access Regulations and Zero-Emission Zones Proliferation
London’s Ultra Low Emission Zone covers all boroughs, imposing a daily charge on non-compliant vans and increasing electric vehicle registrations. Amsterdam restricts diesel freight traffic within the A10 ring road during business hours, while Paris, Milan, Madrid, and Berlin are implementing similar regulations. Compliance cameras enforce penalties effectively, making the cost savings from full electrification outweigh any remaining price premium. Pan-European delivery firms increasingly favor standardized electric fleets over managing diesel-related workarounds across municipal borders. This regulatory landscape is expected to sustain demand for zero-emission light commercial vehicles.
Restraints Impact Analysis of Europe Electric Light Commercial Vehicles Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Slow Homologation Cycles for Above 3.5 T Zero-Emission Chassis | -1.8% | EU27 plus UK, particularly fragmented in Southern and Eastern Europe | Medium term (2-4 years) |
| Grid-Connection Delays for Depot Fast-Charging Above 350 kW | -1.2% | France, Italy, Spain, Poland with acute pressure in metro areas | Short term (≤2 years) |
| Scarcity of Residual-Value Data Limiting Lease Penetration | -0.9% | Pan-European, most severe in markets with nascent e-LCV adoption (Eastern Europe) | Medium term (2-4 years) |
| Concentrated Lithium-Iron-Phosphate Supply Risk | -0.7% | Global supply chain with European gigafactory exposure | Long term (≥4 years) |
| Source: Mordor Intelligence | |||
Slow Homologation Cycles for Above 3.5 T Zero-Emission Chassis
Medium-duty platforms face fragmented national testing requirements, resulting in longer full-vehicle approval timelines than for light vans. Germany and France oppose centralization because domestic laboratories generate certification revenue, creating resistance to the European Commission’s proposal for a single EU approval process. Consequently, Iveco and MAN have delayed the launch of medium-duty models. These delays are creating a supply gap in municipal and construction applications and prolonging diesel's dominance as cities develop zero-emission waste-collection regulations.
Grid-Connection Delays for Depot Fast-Charging Above 350 kW
In France and Italy, distribution system operators are unable to assure capacity for depots requiring several megawatts. As a result, fleets are left waiting for essential transformer upgrades. Enedis highlighted pending requests, and e-distribuzione echoed similar backlogs in the vicinity of Milan and Rome. While integrating solar with storage can reduce grid dependency by half, it comes with a hefty price tag: an additional EUR 200,000–500,000 in capital for a 1 MW site. This financial burden significantly diminishes savings for smaller hauliers. Today, for many operators, it's the charger, not the van, that determines the pace of electrification.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Europe Electric Light Commercial Vehicles Market Segment Analysis
By Vehicle Type:
Van Leadership and Light-Truck UpswingVans generated 67.12% of 2025 revenue, underpinned by e-commerce fulfillment that values cubic capacity and a 1-tonne payload. Amazon’s 10,000-unit Rivian order and DHL’s 14,000-unit Streetscooter deal illustrate anchor procurement that spreads depot-charger costs. The Europe Electric LCV market size for the van category is projected to expand steadily as platform commonality with passenger MPVs lowers manufacturing overhead. Light trucks, including chassis-cab pickups, are forecast to rise at 19.91% annually because construction and municipal fleets now demand zero-emission payloads above 1.5 tonnes. Product roadmaps from Ford and Volkswagen add vehicle-to-load functionality, letting crews power equipment directly from the traction battery on site.
Van dominance persists because sub-3.5-tonne models avoid stringent homologation and qualify for AC depot charging, but momentum shifts after 2028 when stricter Scope 3 rules push utility and telecom fleets toward battery-electric pickups. Light-truck homologation remains tougher due to frame modifications for battery packs, yet regulatory clarity is improving. As residual-value data mature, leasing costs for light trucks begin to converge with vans, unlocking SME demand in rural areas previously reliant on diesel.

By Propulsion Type:
BEV Core and FCEV NicheBattery-electric models captured 80.41% share in 2025, largely because daily ranges under 200 km fit within 75 kWh packs that charge overnight on 11 kW AC. Fuel-cell vans and light trucks grow at 21.78% per year, aimed at long regional routes where a 400-km range and five-minute refueling time outweigh the higher market-entry price. Manufacturers are piloting these vehicles along key European transport corridors, with support from regional hydrogen funding initiatives.
Technically, the market is bifurcating into lower-cost battery packs for urban vans and higher-energy-density battery packs for intercity applications. Green hydrogen costs must decline for total cost of ownership (TCO) parity to become likely. However, pipeline repurposing under hydrogen backbone initiatives is reducing transport costs over time. Until hydrogen refueling station density approaches diesel coverage, battery electric vehicles (BEVs) will continue to dominate most fleet tenders. Dual-battery options also allow operators to align vehicle range with route requirements without paying for unused battery capacity.
By Tonnage:
Light Segment Prevails, Medium Duty AcceleratesVehicles below 3.5 tonnes accounted for 75.73% of deliveries in 2025, thanks to simpler approval processes, a wide range of models, and compatibility with ubiquitous 50–150 kW public chargers. This segment of the European electric LCV market continues to grow, albeit at a slower rate, as parcel delivery hubs approach saturation. Medium-duty (3.5–7.5 tonnes) expands 19.22% annually as cities replace diesel refuse trucks and utility lift platforms. Manufacturers now offer vehicles with higher payload capacities and integrated power take-off systems for hydraulic equipment, meeting operational requirements that light vans cannot fulfill.
Battery scale drives cost divergence: light vans achieve faster payback periods, whereas medium-duty vehicles require longer payback periods unless subsidies are available. Proposed emissions reductions for heavier trucks further tighten the transition timeline, encouraging early adopters who value regulatory certainty. Charging infrastructure is still catching up, with high-capacity depot chargers expected to reach commercial deployment in the future.
By End-User Sector:
Logistics Dominates, Mining Gains MomentumLogistics and distribution claimed 42.14% of 2025 revenue as postal operators and parcel giants pursue 60–100% electric last-mile fleets by 2030. Their predictable routes and centralized depots maximize charger utilization and battery life. Meanwhile, mining and energy companies exhibit an 18.43% CAGR as underground haulage and remote pipelines test battery-swap trucks to eliminate diesel ventilation costs. Construction and public services follow but hinge on grid upgrades around metropolitan job sites.
Logistics fleets enjoy the clearest return on investment because depot charging during overnight idle covers the full duty cycle. Remote mining operations pay a premium for ruggedized thermal management but recoup it by avoiding diesel transport and carbon taxes. When battery packs become modular and swappable, heavy-usage sites shorten downtime further, sharpening the appeal over diesel even in harsh climates.
By Ownership Model:
Shift Toward Leasing and Fleet ManagementOwnership accounted for 55.33% of units in 2025 as large hauliers preferred outright purchase to claim depreciation and retain secondary-market upside. Leasing grows 17.12% a year because real-time battery-health data now underpins residual-value guarantees that narrow the price gap with diesel contracts. The European electric LCV market continues to see SMEs choosing operating leases bundled with charger installation and maintenance.
Risk profiles diverge: corporates with in-house electrification teams buy assets to pilot battery-swap or repowering, while small businesses offload technology obsolescence onto lessors. Subscription offerings with one-to-twelve-month terms serve gig-economy peaks and seasonal surges where flexibility outranks long-term TCO. Over time, greater transparency into battery degradation will make leasing the default, outside of vertically integrated logistics giants.
Geography Analysis
Europe Electric Light Commercial Vehicles Market in France
France continues to dominate the European electric light commercial vehicles landscape, holding approximately 20% market share in 2024. The country's leadership position is reinforced by its comprehensive approach to electric mobility, combining robust government support with extensive charging infrastructure development. The French government's commitment to environmental sustainability is evident through its implementation of various incentives and policies designed to accelerate the adoption of electric commercial vehicles. These initiatives, coupled with the country's strategic focus on developing a comprehensive charging network, have created a favorable ecosystem for electric LCV adoption. The market's growth is further driven by increasing awareness among businesses about the long-term economic benefits of electric vehicles, including lower operational costs and maintenance requirements. Additionally, France's strong automotive manufacturing base and expertise in electric vehicle technology have ensured a steady supply of innovative electric LCV models, catering to diverse commercial needs.
Europe Electric Light Commercial Vehicles Market in Spain
Spain has emerged as the fastest-growing market in the European electric light commercial vehicles sector, with a projected CAGR of approximately 29% from 2024 to 2029. The country's remarkable growth trajectory is underpinned by its ambitious electrification goals and substantial investments in charging infrastructure. Spain's automotive industry has undergone significant transformation, with manufacturers increasingly focusing on electric vehicle production and development. The government's commitment to reducing carbon emissions has led to the implementation of comprehensive support measures, including purchase incentives and tax benefits for electric commercial vehicle operators. The country's strategic location and well-developed logistics sector have also contributed to the increasing adoption of electric LCVs, particularly in urban delivery and last-mile logistics applications. Furthermore, Spain's emphasis on renewable energy integration with electric mobility has created a sustainable ecosystem that supports the long-term growth of the electric commercial vehicle market.
Europe Electric Light Commercial Vehicles Market in United Kingdom
The United Kingdom maintains its position as a key player in the European electric light commercial vehicles market, driven by its comprehensive approach to sustainable transportation. The country's success in electric LCV adoption is supported by a well-structured regulatory framework that includes both incentives and restrictions on conventional vehicles. The UK government's clear roadmap for phasing out internal combustion engine vehicles has provided businesses with the confidence to invest in electric fleet transitions. The market has particularly benefited from the country's strong focus on developing smart charging solutions and innovative financing models for electric commercial vehicles. Urban centers across the UK have been at the forefront of implementing low-emission zones, creating additional incentives for businesses to switch to electric LCVs. The country's robust charging infrastructure network, combined with increasing model availability from both domestic and international manufacturers, has created a favorable environment for market growth.
Europe Electric Light Commercial Vehicles Market in Italy
Italy has established itself as a significant force in the European electric light commercial vehicles market, characterized by its innovative approach to sustainable mobility solutions. The country's market development is supported by a combination of national and regional initiatives aimed at promoting electric vehicle adoption. Italian cities have been particularly proactive in implementing sustainable urban mobility plans, which have created strong incentives for businesses to transition to electric commercial vehicles. The market has benefited from Italy's strong automotive manufacturing heritage, with several manufacturers developing and producing electric LCVs within the country. The integration of smart city concepts with electric mobility solutions has created unique opportunities for electric LCV deployment in urban logistics. Additionally, Italy's focus on developing innovative charging solutions, including dynamic charging corridors and smart grid integration, has helped address range anxiety concerns among commercial users.
Europe Electric Light Commercial Vehicles Market in Other Countries
The electric light commercial vehicles market across other European countries demonstrates varying levels of maturity and adoption rates, reflecting diverse economic conditions and policy frameworks. Countries such as Germany, Norway, Sweden, and Denmark have shown strong commitment to electric mobility through comprehensive support measures and infrastructure development. The Benelux region, comprising Belgium, Netherlands, and Luxembourg, has emerged as a significant market for electric LCVs, particularly in urban logistics applications. Eastern European countries, including Poland, Czech Republic, and Hungary, are gradually increasing their focus on electric commercial vehicles, supported by EU-wide initiatives and funding. The Baltic states - Estonia, Latvia, and Lithuania - are developing their electric mobility ecosystems, while Austria and Ireland continue to strengthen their positions through targeted incentives and infrastructure development. These markets collectively contribute to the broader European goal of sustainable commercial transportation, each bringing unique perspectives and solutions to the electric mobility landscape.
Competitive Landscape
Stellantis, Mercedes-Benz, Volkswagen, Ford, and Renault, the five dominant players, command a significant share of unit sales. Their success stems from diverse model lines, in-house finance divisions, and extensive service networks. Stellantis, leveraging the e-STLA Medium platform across its four brands, partners with ACC to source cells, effectively reducing logistics costs. Mercedes-Benz stands out by offering long-range variants equipped with heat-pump HVAC systems, ensuring optimal winter performance. Meanwhile, Volkswagen commits a substantial investment in Hannover, ramping up ID. Buzz Cargo production [3].
Chinese players Maxus and Cenntro are disrupting the market by significantly slashing list prices and securing municipal tenders in which total acquisition costs outweigh brand reputation. Start-ups Arrival and Quantron pioneer microfactory models, positioning final assembly close to fleet depots. This strategy not only streamlines logistics for finished vehicles but also enables body customization. However, Arrival's restructuring highlights execution challenges, especially when major orders wane. In a notable trend, technology patents at the European Patent Office surged, with a spotlight on modular skateboard frames designed for versatile wheelbases and roof heights, all centered on a unified battery tray.
There's untapped potential in medium-duty fuel-cell trucks, a segment currently lagging due to a sparse refueling network, with fewer than adequate sites spread across the continent. While Iveco-Nikola and Hyundai are piloting initiatives backed by the EU Hydrogen Strategy, the economics still lean towards diesel for many routes, given current payload-to-cost dynamics. Battery thermal management emerges as a key differentiator; Stellantis and Renault use advanced preconditioning algorithms that heat battery packs en route to depots to reduce charging times. With battery warranties now extending significantly, confidence in residual values strengthens, heightening competition between captive finance entities and independent leasing firms.
Europe Electric Light Commercial Vehicles Industry Leaders
-
Stellantis N.V.
-
Renault Group
-
Volkswagen AG
-
Ford Motor Company
-
Mercedes-Benz Group AG (Mercedes-Benz Vans)
- *Disclaimer: Major Players sorted in no particular order
Europe Electric Light Commercial Vehicles Market Companies Covered in this Report
- Mercedes-Benz Group AG (Mercedes-Benz Vans)
- Stellantis N.V (Peugeot, Citroen, Fiat Professional, Opel/Vauxhall)
- Volkswagen AG
- Ford Motor Company
- Renault Group
- Volvo Group (Volvo Trucks, Renault Trucks)
- Nissan Motor Co. Ltd.
- Toyota Motor Corporation
- Maxus
- Addax Motors NV
- Iveco Group
- MAN Truck and Bus SE
- Hyundai Motor Company
- Rivian Automotive LLC
Recent Industry Developments in Europe Electric Light Commercial Vehicles Market
- May 2026: BYD introduced the Dolphin Cargo e-Van, a compact electric commercial vehicle designed for fleet operators. The vehicle is powered by a 204 PS electric motor and a 60.4 kWh battery, offering a WLTP driving range of up to 347 miles in urban conditions and 265 miles combined.
- April 2026: Stellantis Italy has opened orders for the new Leapmotor T03 Van, a fully electric light commercial vehicle (LCV) designed for professional urban applications. The vehicle features compact exterior dimensions and a practical cargo area with a capacity of up to 657 liters. The van uses a fully electric powertrain and provides a driving range of up to 256 km on a single charge.
Europe Electric Light Commercial Vehicles Market Report Scope
The Europe electric light commercial vehicle market report is segmented by vehicle type (vans and light trucks), propulsion type (battery electric, plug-in hybrid, hybrid electric and fuel-cell electric), tonnage (light below 3.5 t and medium 3.5-7.5 t), end-user sector (logistics and distribution, construction, government and public sector, SME and services, and mining and energy), ownership model (owned and leased/fleet-management), and geography (Austria, Belgium, Czech Republic, Denmark, Estonia, France, Germany, Ireland, Italy, Latvia, Lithuania, Norway, Poland, Russia, Spain, Sweden, United Kingdom, and Rest of Europe). The market forecasts are provided in terms of value (USD) and volume (units).
Segmentation Overview
By Vehicle Type
| Vans |
| Light Trucks |
By Propulsion Type
| Battery Electric (BEV) |
| Plug-in Hybrid (PHEV) |
| Hybrid Electric (HEV) |
| Fuel-Cell Electric (FCEV) |
By Tonnage
| Light (Below 3.5 t) |
| Medium (3.5-7.5 t) |
By End-User Sector
| Logistics and Distribution |
| Construction |
| Government and Public Sector |
| SME and Services |
| Mining and Energy |
By Ownership Model
| Owned |
| Leased / Fleet-Management |
By Country
| Austria |
| Belgium |
| Czech Republic |
| Denmark |
| Estonia |
| France |
| Germany |
| Ireland |
| Italy |
| Latvia |
| Lithuania |
| Norway |
| Poland |
| Russia |
| Spain |
| Sweden |
| United Kingdom |
| Rest of Europe |
| By Vehicle Type | Vans |
| Light Trucks | |
| By Propulsion Type | Battery Electric (BEV) |
| Plug-in Hybrid (PHEV) | |
| Hybrid Electric (HEV) | |
| Fuel-Cell Electric (FCEV) | |
| By Tonnage | Light (Below 3.5 t) |
| Medium (3.5-7.5 t) | |
| By End-User Sector | Logistics and Distribution |
| Construction | |
| Government and Public Sector | |
| SME and Services | |
| Mining and Energy | |
| By Ownership Model | Owned |
| Leased / Fleet-Management | |
| By Country | Austria |
| Belgium | |
| Czech Republic | |
| Denmark | |
| Estonia | |
| France | |
| Germany | |
| Ireland | |
| Italy | |
| Latvia | |
| Lithuania | |
| Norway | |
| Poland | |
| Russia | |
| Spain | |
| Sweden | |
| United Kingdom | |
| Rest of Europe |
Market Definition
- Vehicle Type - The category covers light commercial vehicle.
- Vehicle Body Type - This includes Light Commercial Pick-up Trucks and Light Commercial Vans.
- Fuel Category - The category exclusively covers electric propulsion systems, including various types such as HEV (Hybrid Electric Vehicles), PHEV (Plug-in Hybrid Electric Vehicles), BEV (Battery Electric Vehicles), and FCEV (Fuel Cell Electric Vehicles).
| Keyword | Definition |
|---|---|
| Electric Vehicle (EV) | A vehicle which uses one or more electric motors for propulsion. Includes cars, buses, and trucks. This term includes all-electric vehicles or battery electric vehicles and plug-in hybrid electric vehicles. |
| BEV | A BEV relies completely on a battery and a motor for propulsion. The battery in the vehicle must be charged by plugging it into an outlet or public charging station. BEVs do not have an ICE and hence are pollution-free. They have a low cost of operation and reduced engine noise as compared to conventional fuel engines. However, they have a shorter range and higher prices than their equivalent gasoline models. |
| PEV | A plug-in electric vehicle is an electric vehicle that can be externally charged and generally includes all-electric vehicles as well as plug-in hybrids. |
| Plug-in Hybrid EV | A vehicle that can be powered either by an ICE or an electric motor. In contrast to normal hybrid EVs, they can be charged externally. |
| Internal combustion engine | An engine in which the burning of fuels occurs in a confined space called a combustion chamber. Usually run with gasoline/petrol or diesel. |
| Hybrid EV | A vehicle powered by an ICE in combination with one or more electric motors that use energy stored in batteries. These are continually recharged with power from the ICE and regenerative braking. |
| Commercial Vehicles | Commercial vehicles are motorized road vehicles designed for transporting people or goods. The category includes light commercial vehicles (LCVs) and medium and heavy-duty vehicles (M&HCV). |
| Passenger Vehicles | Passenger cars are electric motor– or engine-driven vehicles with at least four wheels. These vehicles are used for the transport of passengers and comprise no more than eight seats in addition to the driver’s seat. |
| Light Commercial Vehicles | Commercial vehicles that weigh less than 6,000 lb (Class 1) and in the range of 6,001–10,000 lb (Class 2) are covered under this category. |
| M&HDT | Commercial vehicles that weigh in the range of 10,001–14,000 lb (Class 3), 14,001–16,000 lb (Class 4), 16,001–19,500 lb (Class 5), 19,501–26,000 lb (Class 6), 26,001–33,000 lb (Class 7) and above 33,001 lb (Class 8) are covered under this category. |
| Bus | A mode of transportation that typically refers to a large vehicle designed to carry passengers over long distances. This includes transit bus, school bus, shuttle bus, and trolleybuses. |
| Diesel | It includes vehicles that use diesel as their primary fuel. A diesel engine vehicle have a compression-ignited injection system rather than the spark-ignited system used by most gasoline vehicles. In such vehicles, fuel is injected into the combustion chamber and ignited by the high temperature achieved when gas is greatly compressed. |
| Gasoline | It includes vehicles that use gas/petrol as their primary fuel. A gasoline car typically uses a spark-ignited internal combustion engine. In such vehicles, fuel is injected into either the intake manifold or the combustion chamber, where it is combined with air, and the air/fuel mixture is ignited by the spark from a spark plug. |
| LPG | It includes vehicles that use LPG as their primary fuel. Both dedicated and bi-fuel LPG vehicles are considered under the scope of the study. |
| CNG | It includes vehicles that use CNG as their primary fuel. These are vehicles that operate like gasoline-powered vehicles with spark-ignited internal combustion engines. |
| HEV | All the electric vehicles that use batteries and an internal combustion engine (ICE) as their primary source for propulsion are considered under this category. HEVs generally use a diesel-electric powertrain and are also known as hybrid diesel-electric vehicles. An HEV converts the vehicle momentum (kinetic energy) into electricity that recharges the battery when the vehicle slows down or stops. The battery of HEV cannot be charged using plug-in devices. |
| PHEV | PHEVs are powered by a battery as well as an ICE. The battery can be charged through either regenerative breaking using the ICE or by plugging into some external charging source. PHEVs have a better range than BEVs but are comparatively less eco-friendly. |
| Hatchback | These are compact-sized cars with a hatch-type door provided at the rear end. |
| Sedan | These are usually two- or four-door passenger cars, with a separate area provided at the rear end for luggage. |
| SUV | Popularly known as SUVs, these cars come with four-wheel drive, and usually have high ground clearance. These cars can also be used as off-road vehicles. |
| MPV | These are multi-purpose vehicles (also called minivans) designed to carry a larger number of passengers. They carry between five and seven people and have room for luggage too. They are usually taller than the average family saloon car, to provide greater headroom and ease of access, and they are usually front-wheel drive. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all its reports.
- Step-1: Identify Key Variables: To build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built based on these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. Market revenue is calculated by multiplying the sales volume with their respective average selling price (ASP). While estimating ASP factors like average inflation, market demand shift, manufacturing cost, technological advancement, and varying consumer preference, among others have been taken into account.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


