
South Africa E-commerce Market Analysis by Mordor Intelligence
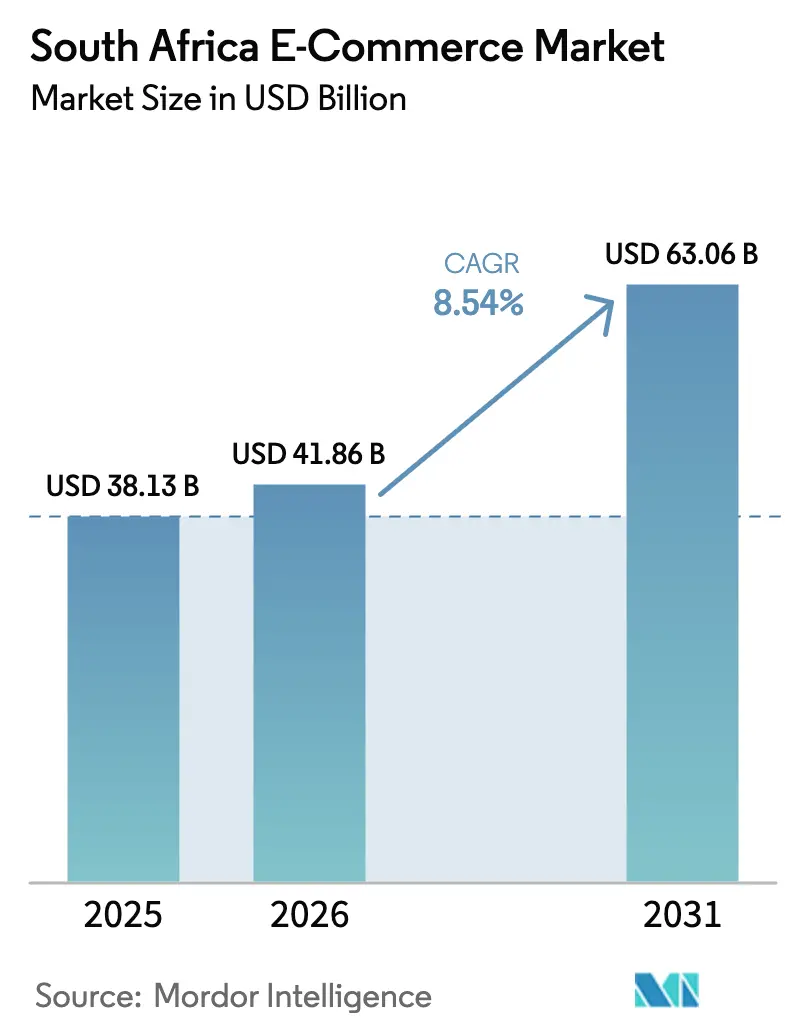
The South Africa e-commerce market size was valued at USD 41.86 billion in 2026 and estimated to grow from USD 45.43 billion in 2027 to reach USD 69.68 billion by 2032, at a CAGR of 8.93% during the forecast period (2027-2032).
Mobile ordering and wider delivery access support South Africa’s online product demand by connecting digital product selection with a practical route to receipt. Installment options can expand feasible baskets, while cross-border marketplaces give buyers additional alternatives to domestic sellers. App development and shared fulfillment services connect customer acquisition with the ability to execute the resulting orders. Seller fraud can interrupt that progression from interest to payment. Marketplace operators can therefore widen order intake yet face confidence risks from seller-level scams, while fashion retailers handling store and online returns together can incur recovery costs outside their budgets.
Key Report Takeaways
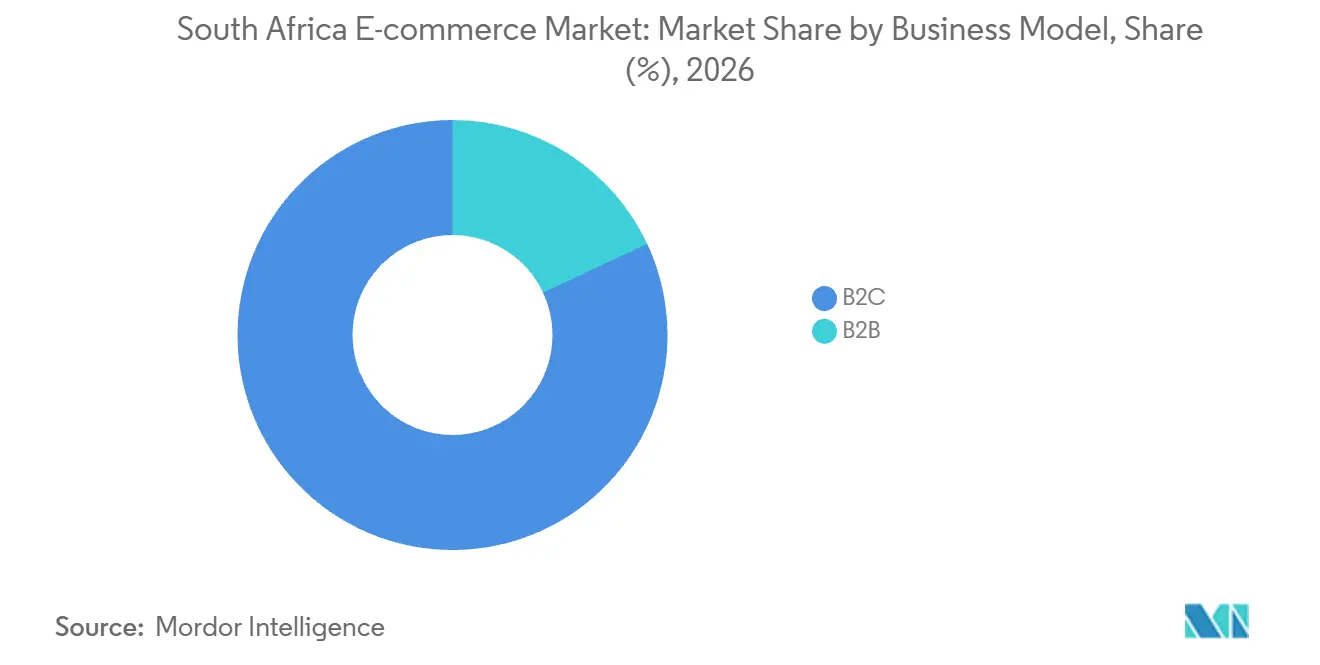
- By business model, B2C held an 81.97% South Africa e-commerce market share in 2026, while B2B is forecast to grow fastest at an 11.2% CAGR during 2027-2032.
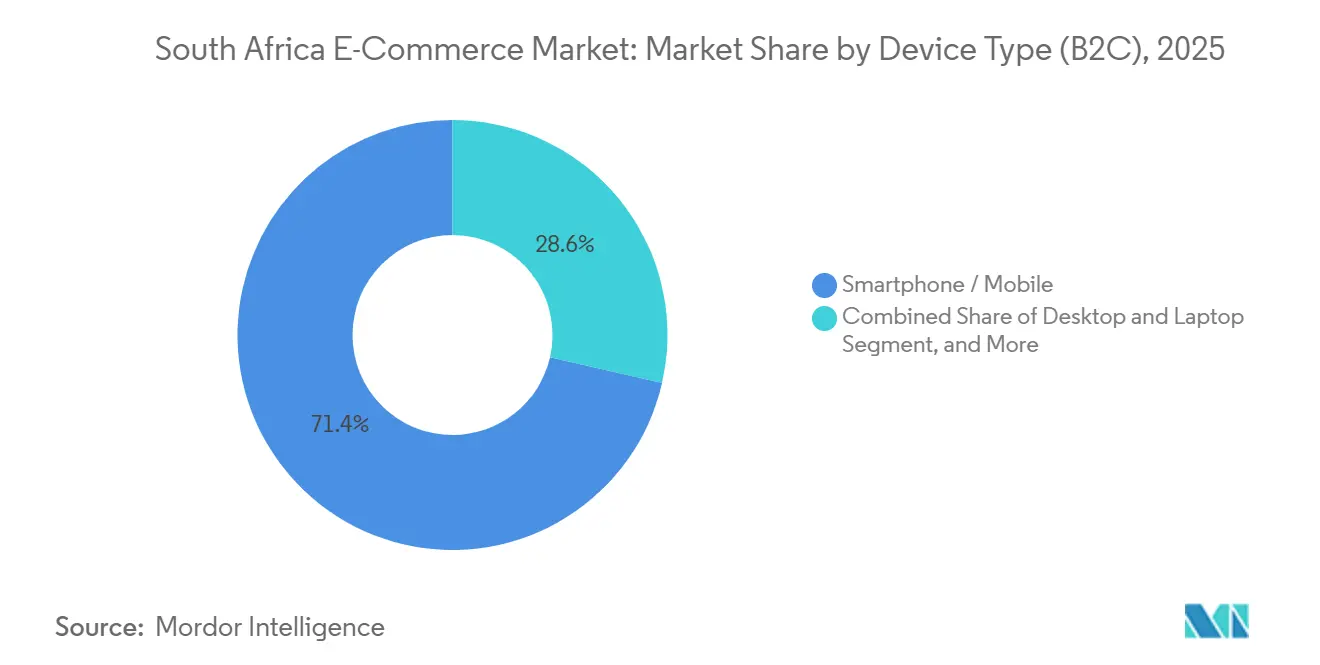
- For device type, smartphone/mobile led with a 72.06% share of B2C orders in 2026 and is also forecast to grow fastest at a 9.4% CAGR during 2027-2032.
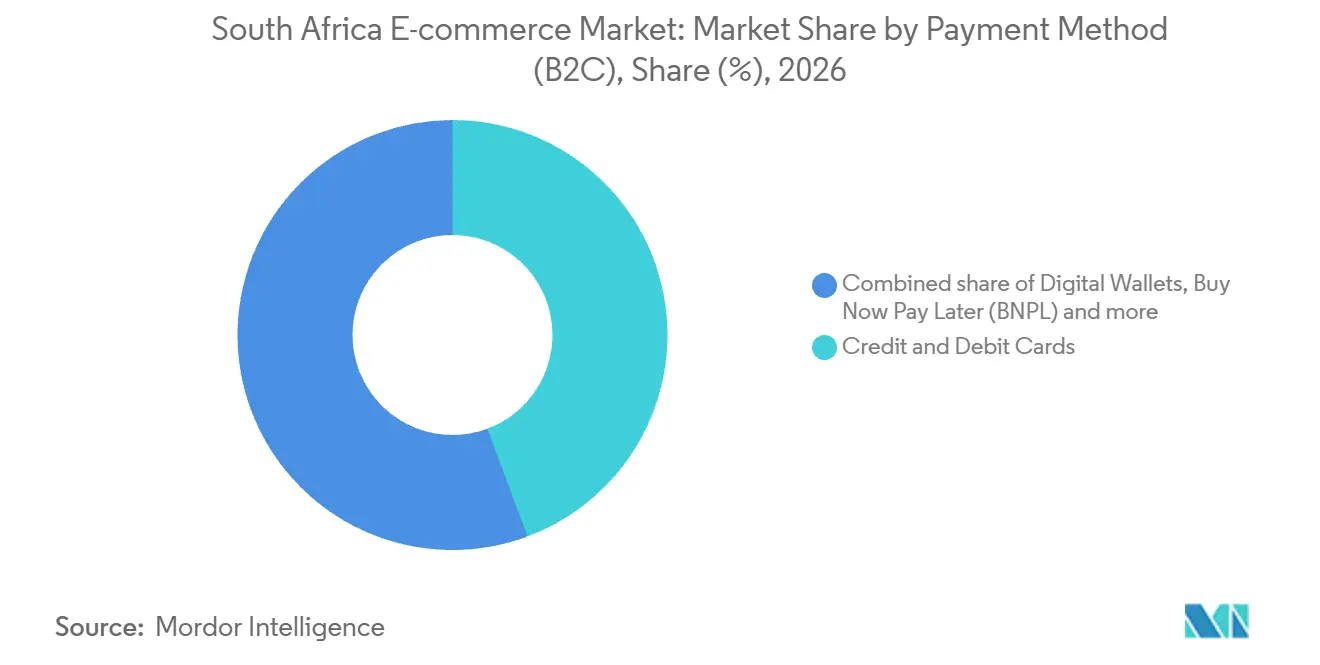
- Within B2C payment methods, credit and debit cards held a 44.33% share of B2C orders in 2026, while BNPL is forecast to grow fastest at an 11.6% CAGR during 2027-2032.
- By product category, fashion and apparel led with a 24.48% share of B2C orders in 2026, whereas food and beverages is forecast to grow fastest at a 12.1% CAGR during 2027-2032.
- Across South Africa’s regions, Gauteng led online-shopping penetration in 2025, when 46.9% of its adults shopped online.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of South Africa E-commerce Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Mobile-Only Shoppers in Township Economies Fueled by Low-Cost Android Handsets | +3.1% | Nationwide | Medium term (2-4 years) |
| Expansion of Domestic Logistics Networks into Rural and Township Last-Mile | +3% | Mamelodi, Ivory Park, and Hammanskraal | Medium term (2-4 years) |
| Rapid Adoption of BNPL by Gen-Z Consumers Boosting Average Order Value | +2.2% | Nationwide | Short term (≤ 2 years) |
| Entry of Global Fast-Fashion Marketplaces (Shein, Temu) Catalyzing Cross-Border Volumes | +2% | Nationwide | Short term (≤ 2 years) |
| Government Spectrum Auction and 5G Roll-Out Lowering Data Costs | +1.2% | Nationwide | Long term (≥ 4 years) |
| Retailers' Partnerships with Smart-Lockers in Taxi Ranks Improving Convenience | +0.6% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Mobile-Only Shoppers in Township Economies Fueled by Low-Cost Android Handsets
Township handset access and assisted ordering address different barriers to reaching an online retailer. By May 2025, MTN South Africa had distributed about 1,700 4G smartphones in Soweto. The rollout’s planned initial Itel model was specified with Android 14 Go. By September 2026, Takealot reported more than 16,000 Personal Shopper entrepreneurs helping customers access its platform through a network forming part of its Township Economy Initiative. Takealot launched a dedicated app that month to help the intermediaries manage orders and customer communication. Handset availability can widen the potential audience, while intermediary software supports a separate route to demand from customers who need shopping assistance.
Expansion of Domestic Logistics Networks into Rural and Township Last-Mile
Township delivery partnerships can turn an online grocery offer into an accessible service without requiring the retailer to build every route itself. By May 2025, SPAR had signed partnerships with KasiD and Delivery KA Speed for SPAR2U orders in Mamelodi, Ivory Park, and Hammanskraal. Residents in those areas could then order through SPAR2U, with the partners handling delivery. The division of responsibilities allows order capture and local distribution to expand together while assigning each task to a named operator. For a grocery retailer, this makes delivery coverage a concrete extension of its selling channel. Local delivery partners consequently gain a route to retail demand through integration with the retailer’s ordering service.
Rapid Adoption of BNPL by Gen-Z Consumers Boosting Average Order Value
Spreading a purchase across installments can make a larger online basket feasible without reducing its total price. In TransUnion’s Q3 2025 survey, 55% of South African Gen Z respondents reported BNPL use in the prior 12 months.[1] On July 15, 2026, PayJustNow added 3 interest-free installments to Bash, the online retail platform of The Foschini Group. That deployment connects the payment mechanism to an actual online checkout, where the immediate amount due can influence the feasible purchase. For retailers, the commercial opening is to accommodate spending across payment dates while keeping the full purchase obligation clear. Basket expansion therefore depends on affordability across the repayment schedule, rather than the first installment alone.
Entry of Global Fast-Fashion Marketplaces (Shein, Temu) Catalyzing Cross-Border Volumes
International marketplace entry gives South African buyers a direct-import route to ordering products. World Wide Worx’s 2025 report described Shein and Temu’s model as direct-to-consumer imports bypassing local wholesalers and store networks. In a 2026 survey, 21.5% of South African online shoppers used Shein and 11.6% used Temu. Across cross-border platforms in aggregate, approximately 19 million orders were placed in South Africa in 2025, representing 18.6% of e-commerce transactions. The 2026 report attributed slower cross-border growth partly to November 2024 changes in small-parcel import taxation. For domestic retailers, this substantial cross-border transaction channel means that local store coverage alone cannot secure online demand against platforms connecting shoppers directly with overseas supply.
Restraints Impact Analysis of South Africa E-commerce Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Persistent Digital Payment Fraud Driving Cart Abandonment | -1.5% | Nationwide | Short term (≤ 2 years) |
| High Reverse-Logistics Cost for Fashion Returns | -1% | Nationwide | Short term (≤ 2 years) |
| Potential Load-Shedding Disruptions to Fulfillment Centers' Uptime | -0.2% | Nationwide | Medium term (2-4 years) |
| Customs Clearance Delays for Cross-Border Parcels | -0.5% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Persistent Digital Payment Fraud Driving Cart Abandonment
Fraud can constrain an online purchase even when the platform itself is legitimate, because the individual seller can create a separate source of risk. TransUnion’s findings covered South African consumers reporting digital-fraud losses in the year before its June 2026 release. Among those consumers, 33% attributed their losses to third-party seller scams on legitimate e-commerce platforms. For a prospective buyer, that distinction means recognizing the platform may not resolve concerns about the particular offer. The exposure therefore falls on marketplace models that list third-party sellers, where confidence in the platform does not establish the reliability of each offer.
High Reverse-Logistics Cost for Fashion Returns
Fashion retailers that run store and online returns through one network carry a reverse-logistics cost that can sit outside their budgets. In a 2023 qualitative study of South African fashion retailers during supply-chain disruption recovery, participants described omnichannel reverse logistics as expensive. The commercial exposure therefore extends beyond completing the original sale to recovering goods through that combined network. The study’s participants linked hidden recovery expenses to potential reductions in profit margins when retailers had to supply additional unbudgeted capital.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
South Africa E-commerce Market Segment Analysis
By Business Model:
Consumer Scale Meets Dedicated Business ProcurementB2C accounted for an 81.97% share of the South Africa e-commerce market size in 2026. Pick n Pay reported 31.8% growth in group online turnover during the 48 weeks ended February 1, 2026.[2] The retailer attributed its online performance to asap! and identified the channel as a growth engine in its turnaround. For consumer retailers, that example illustrates how an established retail business can make online ordering a consequential selling channel. For a retailer rebuilding its business, a consumer ordering platform can consequently become part of the core recovery effort.
B2B is forecast to be the fastest-growing segment, with an 11.2% CAGR during 2027-2032. By September 2025, Takealot had relaunched Takealot for Business as a B2B procurement service aimed at buyers from SMEs to large enterprises. That range of intended users gives the service a different commercial task from attracting an individual household to an online storefront. A business-focused proposition can organize product ordering around the needs of an enterprise purchaser while drawing on the retailer’s existing online reach. The opening for B2B sellers is consequently to make that product reach useful for business procurement across organizations of different sizes.

By Device Type (B2C):
Mobile Scale Supports Further App DevelopmentSmartphone / mobile was the largest segment with a 72.06% share of B2C orders in 2026 and is forecast to be the fastest-growing segment at a 9.4% CAGR during 2027-2032. By July 25, 2025, Shoprite Holdings’ Sixty60 grocery delivery app had delivered 100 million orders since launch in South Africa. That cumulative milestone demonstrates the scale an app-based retail channel can achieve through completed deliveries. For a retailer, the relevant capability extends from presenting an online offer to executing the resulting product order. Mobile commerce therefore gives operational delivery performance a direct role in sustaining the usefulness of the shopping interface.
Further mobile adoption can also depend on how an existing service changes its digital experience. In December 2025, Pick n Pay reported 131% growth in first-time buyers since its April 2025 asap! app transformation. The company said 78% of those new customers originated from the revamped platform. That result makes new-customer participation a distinct commercial consideration when assessing investment in a retail app, alongside the scale of an established user base. The acquisition result gives app development a specific commercial purpose, reaching additional grocery customers through an existing retailer’s redesigned service.
By Payment Method (B2C):
Cards Anchor Checkout While BNPL Builds Repeat UseCredit and debit cards accounted for a 44.33% share of B2C orders in 2026, making them the largest segment. Payfast’s consumer research found that cards were the most preferred online-purchase method in both 2024 and 2025. That preference gives card acceptance a central role in how an online retailer presents its payment choices to shoppers. The segment’s leading position nevertheless leaves meaningful room for other methods, so concentrating all checkout design on a single payment route would narrow the offer. A card-led payment experience can preserve a familiar choice while leaving another route available to complete an order.
Buy now pay later (BNPL) is forecast to be the fastest-growing segment at an 11.6% CAGR during 2027-2032. In H1 2026, Weaver Fintech reported 93% retention among its BNPL customers, who transacted 5.1 times a year. Those provider-specific measures show a customer relationship extending beyond a single financed purchase. For merchants considering BNPL, repeat activity makes continuing checkout availability commercially relevant alongside the initial decision to offer installments.
By Product Category (B2C):
Apparel Reach Contrasts With Grocery Channel ExpansionFashion and apparel was the largest segment, accounting for 24.48% of B2C orders in 2026. Stitch’s 2026 consumer payments report found that 78.1% of consumers bought clothing and apparel online. For consumers already buying apparel online, sellers compete for the choice between individual garments and retailers beyond the initial decision to adopt online clothing shopping. Clear garment-level fit information and return terms therefore give apparel sellers concrete ways to compete for purchases within existing category demand.
Food and beverages is forecast to be the fastest-growing segment at a 12.1% CAGR during 2027-2032. In FY2026, Woolworths Food’s on-demand delivery revenue grew 19.6%, while online sales contributed 7.3% of its South African Food sales. The combination illustrates digital channel expansion within a retailer whose food business extends well beyond online sales. It also makes the delivery offer commercially consequential to the food business without requiring the entire customer proposition to move online at once. For established food retailers, this creates room to develop online ordering as a growing route to customers alongside a much broader food-selling operation.
Geography Analysis
Gauteng E-commerce Market
Gauteng led South African provinces in online-shopping penetration in 2025, when 46.9% of its adults shopped online. In September 2026, Inospace opened a Johannesburg fulfillment operation offering outsourced warehousing, order picking and packing, returns handling, and courier integration for customers including e-commerce businesses. Combining those functions can make the province useful to merchants that need coordinated order execution without committing immediately to a separately staffed warehouse. For smaller sellers, the combination offers a way to address an established online buyer base while contracting warehouse execution instead of staffing a facility of their own.
Western Cape investment illustrates a more localized approach to building online grocery capacity around a defined delivery area. In June 2026, Woolworths opened an online fulfillment center in Wynberg, Cape Town, to serve Woolies Dash customers across the Southern Suburbs. A facility dedicated to that catchment can align the retailer’s fulfillment resources with the area its rapid-delivery offer is intended to serve, rather than treating provincial presence as sufficient. For grocery operators, the relevant expansion decision is consequently where an additional fulfillment location improves the relationship between the service promise and the customers it is designed to reach.
KwaZulu-Natal’s Durban-area development highlights the importance of service eligibility during concentrated shopping periods. For the 2025 end-of-year peak, Amazon South Africa expanded delivery coverage in Durban and surrounding areas with same-day and next-day options on thousands of products. Same-day delivery applied to eligible products shipped by Amazon, with orders placed by 2 p.m. delivered by 8 p.m. that day. That structure makes delivery speed a product-and-location commitment, so a retailer’s regional offer depends on which items it can place inside the qualifying service. For shoppers comparing time-sensitive purchases, a precisely bounded delivery commitment can be more useful than a broad statement of regional coverage.
Regulatory Framework and Outlook
The selected jurisdictions compare national obligations with Gauteng’s provincial consumer-redress role from the perspective of online product retailers that also conduct direct marketing. South Africa’s Electronic Communications and Transactions Act requires suppliers conducting electronic transactions to provide specified information where their goods or services are offered online. The commercial comparison weighs the clarity of these obligations against the administrative work of maintaining disclosures, marketing-list procedures, and complaint responses.
Regulatory Table of South Africa E-commerce Market
| Decision factor | South Africa | Gauteng |
|---|---|---|
| Primary authority | National Consumer Commission | Gauteng Office of Consumer Affairs |
| Key instruments or direction | Consumer Protection Act and National Opt-Out Registry rollout | Consumer Affairs (Unfair Business Practices) Act and specified provincial CPA functions |
| Commercial effect | Website disclosures and phased direct-marketing registration and list-cleansing obligations | Local complaint handling and adjudication of certain referred consumer matters |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | No change |
| Source: Mordor Intelligence | ||
The national Medium rating reflects defined consumer obligations, while Hardening reflects phased marketing compliance and March 2026 recommendations for possible CPA and ECTA amendments on online cooling-off, return costs, and trade descriptions. The NCC opened marketer registration on September 15, 2026, with list cleansing scheduled from December 2026 to April 2027 and consumer registration from May 2027.[3] Gauteng’s Consumer Protection Bill was published for public comment in FY2023/24, and the province’s 2025/26 estimates described its enactment as expected. Gauteng’s Medium and No change judgments reflect the Office of Consumer Affairs’ complaint and specified referred-matter duties, since consultation, expected enactment, and national amendment recommendations do not themselves replace that provincial statutory role.
Value Chain Stages
The comparison follows an online product order from retail selling through payment processing to parcel delivery. Takealot.com sells products online and supports marketplace sellers with warehousing and logistics. Separating these activities shows where a merchant captures product-sale revenue and where specialist providers earn fees for completing the transaction and moving the parcel.
Value Chain Analysis Table of South Africa E-commerce Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Online product selling | Online retailers and marketplaces such as Takealot.com | Product-sale revenue for the selling merchant | Accepting orders beyond the seller’s fulfillment capability | Match sellable offers to a defined dispatch capability |
| Payment processing | Payment processors such as Payfast | Aggregation transaction fees and customized Gateway pricing for larger merchants | Choosing a processing arrangement that does not fit the merchant’s account setup | Align the service arrangement with merchant account requirements |
| Parcel delivery | Logistics providers such as Pargo | Service fees under a signed Rates Proposal and agreed amendments | A gap between the promised delivery and contracted service scope | Specify delivery, returns, and tracking responsibilities in the service agreement |
| Source: Mordor Intelligence | ||||
Additional processed orders can generate additional transaction-fee revenue for Payfast’s Aggregation service, while Pargo’s delivery earnings depend on the services and pricing the merchant has contracted. For merchants, the integration challenge is to make the promise to the shopper consistent with both arrangements. This creates a coordination limit for the merchant, because payment throughput can grow without extending the parcel services covered by its delivery agreement.
Competitive Landscape
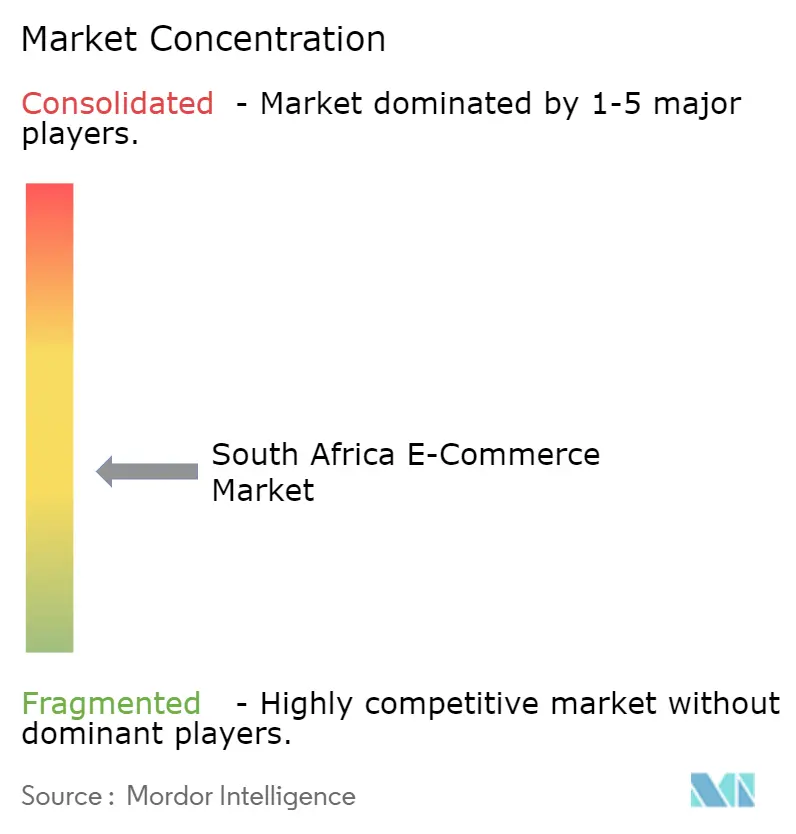
The competitive field includes Takealot Online (Pty) Ltd., Decathlon South Africa, SoFresh (Pty) Ltd., Superbalist.com (Pty) Ltd., and Checkers Sixty60 (Shoprite Holdings Ltd.). Takealot.com operates a general-merchandise platform, Decathlon sells sports products through physical and online channels, and Checkers Sixty60 provides grocery delivery. In a 2026 survey of 1,400 South African online shoppers, Takealot was used by 35.3% of respondents and Checkers Sixty60 by 15%. Takealot.com reported 15% growth in gross merchandise value in FY2026. Takealot’s 35.3% survey use, more than double the 15% for Checkers Sixty60, places the general platform ahead in surveyed reach, while Sixty60 and Decathlon each serve a narrower need in grocery delivery and sports products.
Fulfillment arrangements also connect businesses that compete for online purchases, creating a distinction between ownership of the customer proposition and operation of its logistics. In its FY2026 results, Takealot Group identified Superbalist as a customer of Takealot Fulfilment Solutions, its provider of e-commerce fulfillment to external businesses. Shoprite Holdings reported that Sixty60 platform sales, including Medirite Plus, increased 34.7% in FY2026. Superbalist accesses fulfillment through another retail group, while Shoprite operates Sixty60’s grocery-delivery platform, showing that retailers can use an external fulfillment service or combine retail and delivery within one group.
Competition is also broadening within established operators, as Shoprite Holdings reported 66.3% growth in general-merchandise online sales in FY2026. Takealot.com’s marketplace contributed 60% of its platform GMV in FY2026 and had 15,000 active sellers. The Competition Commission’s final 2025 guidance, published in February 2026, addressed leading platforms with market power, stating that it was nonbinding and cases would be assessed on their merits. Its topics included self-preferencing, competitively sensitive data, and differentiated trading terms across business users. For a marketplace operator such as Takealot, that regulatory positioning makes seller participation terms consequential to a model generating much of its merchandise value through third parties.
South Africa E-commerce Industry Leaders
-
Takealot Online (Pty) Ltd.
-
Decathlon South Africa
-
SoFresh (Pty) Ltd.
-
Superbalist.com (Pty) Ltd.
-
Checkers Sixty60 (Shoprite Holdings Ltd.)
- *Disclaimer: Major Players sorted in no particular order
South Africa E-commerce Market Companies Covered in this Report
- Takealot Online (Pty) Ltd.
- Checkers Sixty60 (Shoprite Holdings Ltd.)
- Woolworths Holdings Ltd. (Woolworths.co.za)
- Superbalist.com (Pty) Ltd.
- Shein Group Ltd.
- Zando (Jumia Technologies AG)
- Makro (Massmart Holdings Ltd.)
- Pick n Pay asap! (Pick n Pay Stores Ltd.)
- Mr Price Group Ltd.
- Yuppiechef (Pick n Pay Stores Ltd.)
- NetFlorist (Pty) Ltd.
- Bob Shop (Bob Group Pty Ltd.)
- Evetech (Pty) Ltd.
- HomeChoice (HomeChoice International plc)
- Bash (The Foschini Group Ltd.)
- Sportscene (The Foschini Group Ltd.)
- Amazon.com Inc.
- Temu (PDD Holdings Inc.)
- UCook (Silvertree Holdings)
- SoFresh (Pty) Ltd.
- Decathlon South Africa
Key Opportunities for Market Participants
The comparison identifies opportunities to bring township apparel, food, and furniture businesses into online product sales. On June 22, 2026, 22 On Sloane opened applications for a Western Cape township e-commerce program covering these sectors, with location, product-suitability, operating-history, active-business, involvement, document, and platform requirements. That targeted support provides a basis for developing distinct selling propositions, although each product category requires a different approach to making a remote order workable.
Market Opportunities Table of South Africa E-commerce Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Township apparel product orders | Targeted Western Cape market-access support | Online clothing buyers and township clothing businesses | Build tightly specified ranges with clear size choices | Conveying fit before purchase | Eligible clothing and textile businesses |
| Township food and beverage orders | Food businesses included in the same program | Online food buyers and township food producers | Define product quantities and delivery commitments together | Matching the offered product to a feasible delivery promise | Eligible food, beverage, and bakery businesses |
| Township furniture product orders | Furniture businesses included in the same program | Online home-product buyers and township furniture businesses | Specify dimensions and a delivery area before accepting orders | Resolving handling and access requirements remotely | Eligible furniture businesses |
| Source: Mordor Intelligence | |||||
The central opening is to extend the sales reach of established product businesses in the targeted Western Cape townships. The program’s operating-history and active-sales requirements make this a channel-extension opportunity for existing traders. An initial online range can consequently build on a producer’s trading record while limiting orders to products and delivery commitments it can fulfill.
Recent Industry Developments in South Africa E-commerce Market
- Sep 2026: Takealot launched an app to help its network of more than 16,000 Personal Shopper entrepreneurs manage customers, orders, and their businesses in South Africa.
- Aug 2026: Pick n Pay launched Inspire within its asap! app, allowing customers in South Africa to add products featured in its shoppable videos directly to their baskets.
- Jul 2026: PayJustNow’s service became available on The Foschini Group’s Bash online retail platform, offering 3 interest-free installments and a separate interest-bearing 12-month payment option.
South Africa E-commerce Market Report Scope and Research Methodology
Market Definition and Coverage
The South Africa e-commerce market measures the annual value of product orders placed online by consumers and businesses located in South Africa, regardless of the seller's location. It values each order at the buyer transaction price in USD.
Scope exclusions: Offline product sales, separately sold e-commerce platform, payment-processing and logistics services, devices and connectivity services used to access online stores, and online product orders by buyers outside South Africa are excluded.
Segments Covered in This Report
- By Business Model
- B2C
- B2B
- By Device Type (B2C)
- Smartphone / Mobile
- Desktop and Laptop
- Other Device Types
- By Payment Method (B2C)
- Credit and Debit Cards
- Digital Wallets
- Buy Now Pay Later (BNPL)
- Other Payment Methods
- By Product Category (B2C)
- Beauty and Personal Care
- Consumer Electronics
- Fashion and Apparel
- Food and Beverages
- Furniture and Home
- Toys, DIY and Media
- Other Product Categories
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as Statistics South Africa's monthly Retail Trade Sales series, ICASA's State of the ICT Sector report, the South African Reserve Bank's 2024/25 Annual Report and the Competition Commission's Online Intermediation Platforms inquiry provide retail activity trends, connectivity conditions, payment choices and platform conditions. These sources help select demand, access and transaction variables and frame checks on online selling activity.
Company annual reports, investor presentations and reputable South African business press can supplement public statistics with online turnover, order growth, category mix and fulfillment information, with reported dates and coverage checked against the original disclosure. The named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Primary research uses structured interviews with leaders responsible for e-commerce, digital retail, payments and fulfillment, alongside targeted merchant surveys across company sizes in South Africa. Interview guides and survey prompts test secondary estimates for buyer location, online product order value, category mix and channel growth. Unresolved gaps are triangulated against filings and public indicators, then carried as bounded assumptions until an additional source or expert check clarifies them.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 40% | CXOs: 15% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 15% | Managers: 50% |
Market-Sizing & Forecasting
An annual top-down model begins with the South African value of online product orders and checks its scale against current-price retail trade and reported e-commerce turnover. It forecasts with a multivariate relationship to retail activity, mobile and broadband access, digital payment use, retailer-reported online sales or order growth, and delivery capacity. Scenario analysis adjusts the pace where a driver series is short or disrupted. Product-category and business-model shares are built from reported online sales, transaction and purchasing mix, and category evidence, while device and payment splits classify B2C orders without counting them again. Where retailer reports use different category definitions, analysts align them before deriving product-category shares. If payment sources describe transaction method rather than order value, they inform payment mix without adding payment revenue to sales. Selective bottom-up checks multiply disclosed online volumes by average order values where both are available and roll up sampled retailer or channel values against the top-down total, with missing order, value or category data carried as bounded assumptions rather than extrapolated from a single seller. Interviews with South African e-commerce, retail, payments and fulfillment leaders check the reasonableness of each variable path and share, and divergent evidence leads analysts to revisit source definitions and scenario ranges before retaining an assumption.
Data Validation & Update Cycle
Analysts triangulate independent signals from official retail and ICT statistics, payment-system evidence, retailer filings and selected buyer or transaction indicators, checking that they refer to online product orders and the same year. Outliers or material variance from an earlier series prompt a source-definition review, arithmetic checks and a second analyst review, with follow-up questions to a respondent or source owner when an unexplained item could change a market or segment estimate. The market model is refreshed annually, updated between cycles after a material policy, payment, retailer or delivery event, and reviewed afresh immediately before delivery.
Mordor Intelligence's South Africa Ecommerce Market Size Measured Against Other Published Estimates
The South Africa e-commerce market measures the annual value of product orders placed online by consumers and businesses located in South Africa, regardless of the seller's location. Product-category and business-model shares are built from reported online sales, transaction and purchasing mix, and category evidence, while device and payment splits classify B2C orders without counting them again.
Key Gap Drivers are addressed through a consistent transaction boundary, market-specific demand inputs and cross-checks across the study. Analysts triangulate independent signals from official retail and ICT statistics, payment-system evidence, retailer filings and selected buyer or transaction indicators, checking that they refer to online product orders and the same year.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 45.43 B (2027) | |
| Market Research Firm A | USD 11.85 B (2026) | At its 2026 base, this estimate is 73.9% below this report's 2027 value of USD 45.43 B, 1 year later. The estimate is B2C-only, leaving out online product orders from South African business buyers, although its covered total also includes travel, food service, media, healthcare and technology activity. |
| Market Research Firm B | USD 101 B (2025) | At its 2025 base, this estimate is 122.3% above this report's 2027 value of USD 45.43 B, 2 years later. The estimate includes C2C, financial and digital-content services, and travel and leisure alongside e-tailing and product categories, extending beyond product orders. |
Mordor Intelligence ties the estimate to the study’s defined coverage and demand model. Analysts triangulate independent signals from official retail and ICT statistics, payment-system evidence, retailer filings and selected buyer or transaction indicators, checking that they refer to online product orders and the same year.
Key Questions Answered in the Report
What is the South Africa E-commerce market size and growth outlook?
The size is estimated at USD 45.43 billion in 2027 and forecast to reach USD 69.68 billion by 2032, at an 8.93% CAGR during 2027-2032.
Which forces support online product demand in South Africa?
Delivery access and installment options support demand. By May 2025, SPAR had signed SPAR2U delivery partnerships covering Mamelodi, Ivory Park, and Hammanskraal.
Which product category accounts for the largest share of B2C orders in South Africa?
Fashion and apparel held a 24.48% share of B2C orders in 2026. Food and beverages is forecast to grow fastest at a 12.1% CAGR during 2027-2032.
Which companies compete for South African online product orders?
Competitors include Takealot Online (Pty) Ltd., Decathlon South Africa, and Checkers Sixty60 (Shoprite Holdings Ltd.).
What cost challenge affects the outlook for online fashion sellers?
A 2023 qualitative study of South African fashion retailers during disruption recovery found that omnichannel reverse logistics could carry hidden costs requiring unbudgeted capital.
Which region leads e-commerce activity in South Africa?
Gauteng led provinces in online-shopping penetration in 2025, when 46.9% of its adults shopped online. In September 2026, Inospace opened a Johannesburg fulfillment operation for customers including e-commerce businesses.