
Philippines Foodservice Market Analysis by Mordor Intelligence
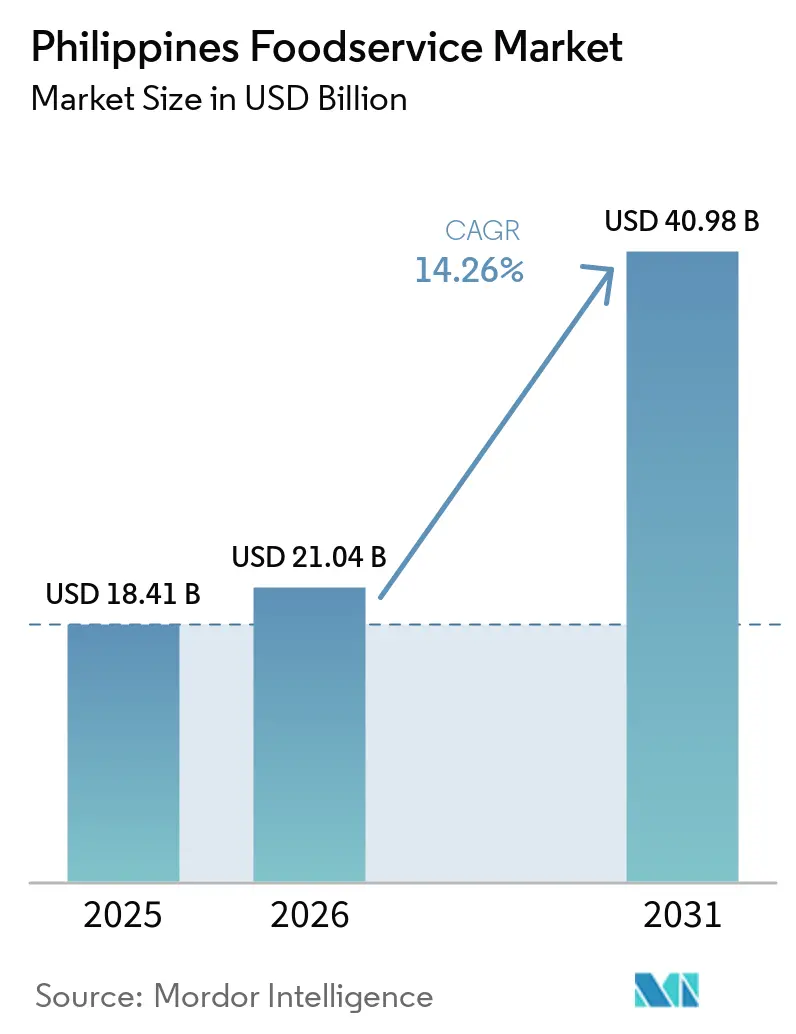
The Philippines foodservice market size is projected to expand from USD 21.04 billion in 2026 and USD 24.04 billion in 2027 to USD 46.04 billion by 2032, registering a CAGR of 13.88% between 2027 and 2032.
In the Philippines, demand can broaden when a restaurant gives customers a reason to visit and a convenient way to order between visits. Dedicated beverage occasions and activity-based dining complement digital collection, allowing operators to reach different needs through the same foodservice business. Commercial expansion nevertheless depends on dependable perishable inputs and local authorization, which can limit how quickly additional capacity becomes usable. Tea destinations can extend drink occasions through pickup, while activity venues depend on preserving the on-site attraction, so expansion should follow the occasion each format can deliver reliably.
Key Report Takeaways
- By foodservice type, quick service restaurants held a 57.04% Philippines foodservice market share in 2026, while cloud kitchens are forecast to grow fastest at a CAGR of 24.2% between 2027 and 2032.
- Independent outlets led the outlet category with a 74.24% share of the Philippines foodservice market size in 2026, whereas chained outlets are projected to record the fastest CAGR of 14.6% between 2027 and 2032.
- Across location formats, standalone outlets led with 41.3% of sales in 2026, and lodging is forecast to grow fastest at a CAGR of 14.5% between 2027 and 2032.
- By service type, dine-in accounted for 52.24% of sales in 2026, with delivery projected to grow fastest at a CAGR of 15.3% between 2027 and 2032.
- Geographically, Metro Manila leads foodservice activity, while Cebu and Bohol offer distinct visitor-based opportunities.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Philippines Foodservice Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of cloud and virtual kitchens in major cities | +3% | Nationwide | Medium term (2-4 years) |
| Experiential, social-media-friendly dine-in formats | +3.2% | Opus Mall, Manila | Medium term (2-4 years) |
| Strong cafe culture and modern tea concepts boosting dayparts | +4.2% | SM North EDSA, Quezon City | Short term (≤ 2 years) |
| Omnichannel formats and curbside/pick-up infrastructure | +5.4% | Nationwide | Short term (≤ 2 years) |
| Sustainability focus: food-waste reduction and responsible sourcing | +1.2% | Newport City, Pasay | Long term (≥ 4 years) |
| Personalization and build-your-own formats driving loyalty | +0.6% | Uptown Mall, Taguig City | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Expansion of cloud and virtual kitchens in major cities
Cloud kitchens can expand foodservice access by separating the place where a meal is prepared from the place where it is consumed. For an operator serving off-premise orders, growth need not require an equivalent addition of dining seats or table service. The relevant commercial capacity is therefore the number of orders a kitchen can prepare and hand over reliably, rather than its seating inventory. This makes the format suited to testing a delivery catchment before committing to a customer-facing dining room. A virtual brand adds a route to demand only if its kitchen can fulfill orders across the intended delivery catchment, linking format expansion to dispatch capacity.
Experiential, social-media-friendly dine-in formats
Experiential dining can generate a restaurant occasion around a shared activity, giving customers another reason to consume food and drinks on site. Dave & Buster’s opened its first Philippine location at Opus Mall in Manila in October 2025, combining dining, drinks, arcade games, and sports viewing in partnership with The Bistro Group. Bringing these activities together makes the venue itself part of the proposition, rather than relying entirely on the food order. For operators, that creates an opportunity to attract group occasions that a delivered meal cannot reproduce in full. Repeat visits hinge on the appeal of the games and sports viewing, putting the attraction’s renewal needs alongside menu development in the operator’s investment choices.
Strong cafe culture and modern tea concepts boosting dayparts
Dedicated tea destinations give operators a way to compete for an individual drink occasion rather than a complete restaurant meal. Jollibee Group opened Milksha’s first standalone milk tea concept store in the Philippines at SM North EDSA in Quezon City on January 20, 2025.[1] Chagee followed with its Philippine grand opening on August 29, 2025. These commercial entries create additional settings for beverage purchases, allowing tea specialists to address occasions that need neither a dining reservation nor a full meal. Building repeat drink visits is the tea specialist’s route into additional dayparts, shifting the concept decision toward a beverage destination rather than a smaller version of a meal-serving restaurant.
Omnichannel formats and curbside/pick-up infrastructure
Digital pickup gives restaurants a route to off-premise demand without making every order dependent on a delivery journey. In July 2025, GCash introduced Food Hub with Tablevibe, enabling app-based pickup from participating merchants. Tablevibe powered the ordering process and had a network of over 4,000 restaurants in the Philippines, with pickup availability determined by the merchant’s configuration. A shared ordering interface can make an existing restaurant easier to use for customers who collect their own meals, without requiring each operator to build a separate app. For a participating merchant, Food Hub makes collection an additional way to serve app users, with order preparation and handoff determining whether that access can support more business.
Restraints Impact Analysis of Philippines Foodservice Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Perishable supply chain gaps and cold-chain limitations | -1.5% | Bicol Region, including Camarines Sur | Long term (≥ 4 years) |
| Food safety, traceability, and sustainability compliance overhead | -1.1% | Nationwide | Medium term (2-4 years) |
| Consumer pushback on ultra-processed items | -0.4% | Nationwide | Medium term (2-4 years) |
| Labor shortages and high staff turnover | -0.7% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Perishable supply chain gaps and cold-chain limitations
Perishable supply gaps constrain restaurant expansion when a dependable menu requires ingredients that cannot be held safely between harvest and service. In March 2026, the Department of Agriculture said Bicol farmers faced high transport costs and fragmented supply chains, with inadequate cold storage forcing quick low-price sales or exposing harvests to loss. This upstream pressure makes a low farm price an unreliable indicator of economical, consistent restaurant supply. Operators dependent on those perishables face a tradeoff between menu breadth and exposure to interrupted replenishment. The department’s ceremonial switching-on of its first completed Cold Storage Expansion Program project in Pili, Camarines Sur, on March 23, 2026, addressed holding capacity. Fragmented distribution and high transport costs can make dependable deliveries costly even where ingredients can be stored safely.
Food safety, traceability, and sustainability compliance overhead
Compliance can constrain restaurant rollout because authorization and food-handler eligibility must be secured alongside the physical capacity to serve meals. San Fernando, Pampanga’s 2026 charter requires business establishments to obtain a sanitary permit when applying for a business permit. National rules also require food-handler health certificates following required examinations and prescribed immunizations, while allowing city or municipal authorities to impose permit fees by resolution. These duties mean an additional kitchen or dining room does not by itself establish readiness to trade. For an expanding operator, the commercial consequence is a need to coordinate premises authorization with eligible staffing before opening service. The resulting administrative work and locally determined fees remain part of the cost of adding capacity.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Philippines Foodservice Market Segment Analysis
By Foodservice Type:
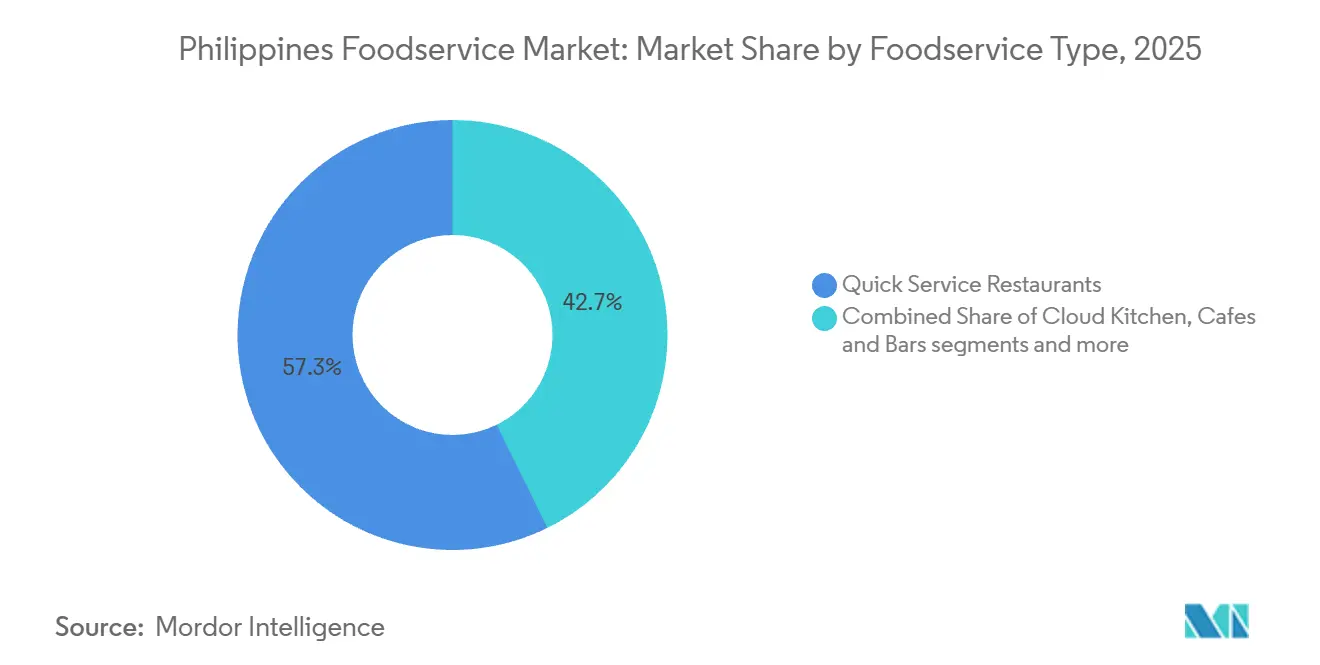
Network Scale Supports Quick-Service ReachQuick service restaurants accounted for a 57.04% share of the Philippines foodservice market size in 2026. Jollibee Foods Corporation had 1,341 Jollibee-brand stores in the Philippines at year-end 2025, including franchised and company-owned outlets. That installed base illustrates the largest segment’s ability to make a recognizable meal proposition available through an extensive network, while each outlet provides another point of access to the same brand. For an established national network, an added outlet’s value rests on reaching another catchment rather than merely increasing the number of places carrying the brand.
Cloud kitchens are forecast to be the fastest-growing segment, registering a CAGR of 24.2% between 2027 and 2032. Fruitas Holdings Inc.’s wholly owned Fly Kitchen Inc. operated a cloud kitchen serving the group’s entire product portfolio in 2025.[2] Serving a portfolio makes the kitchen a common fulfillment point for different products, so its commercial role can develop across several food propositions instead of depending on a single dining concept. Because one kitchen serves the whole portfolio, the group can add reach by loading more products onto shared capacity, and the limit is how many orders that kitchen can fulfill reliably.

By Outlet:
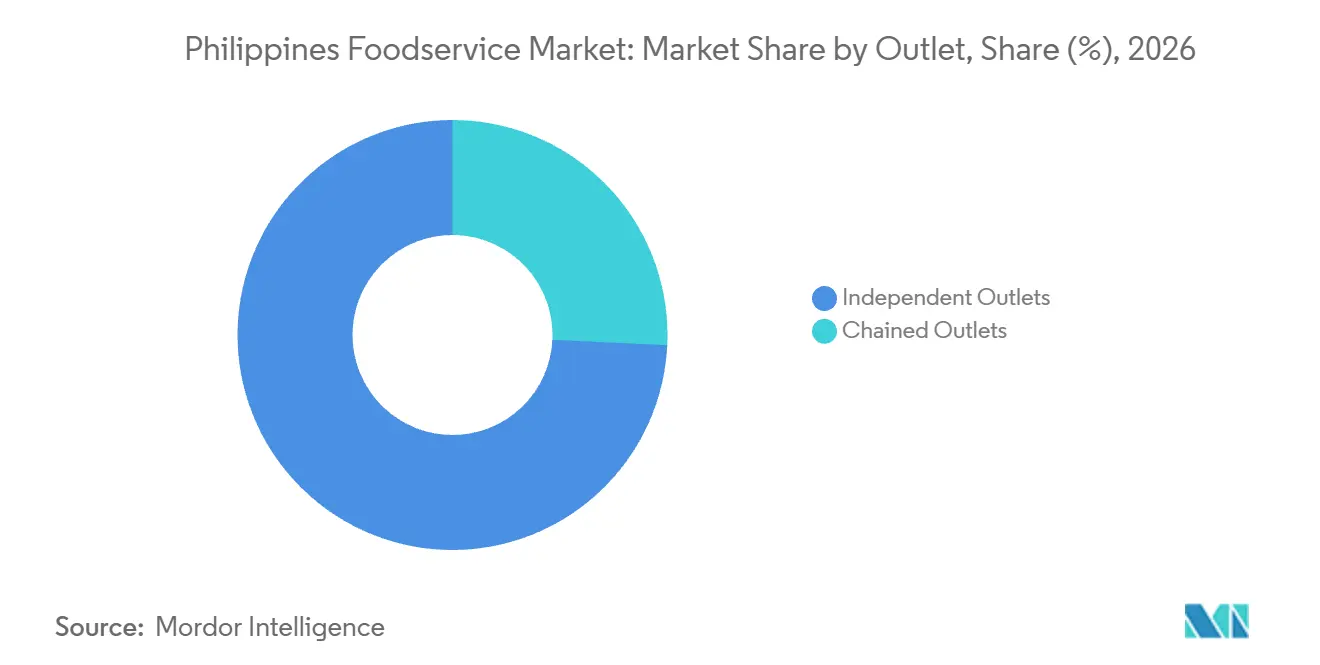
Local Distinction Meets Chain ReplicationIndependent outlets represented a 74.24% Philippines foodservice market share in 2026. On December 5, 2025, Elizabeth Mortera, owner of Quezon City’s Morning Sun Eatery, reported doubled daily sales after its late-October Michelin Bib Gourmand recognition, having earlier credited the recognition and customers. This example within the largest segment shows how an individual restaurant’s identity and outside recognition can provide a route to customer attention without a large branded network. The result belongs to a single carinderia, yet it shows that an independent outlet can draw destination demand from one guide recognition rather than from a chain’s repeated storefronts.
Chained outlets are forecast to be the fastest-growing segment, with a CAGR of 14.6% between 2027 and 2032. Figaro Culinary Group, Inc. reported 171 Angel’s Pizza stores in the Philippines in October 2026, within the network operated or franchised through Figaro Coffee Systems. A chain of that scale can organize its offer around a repeatable format, giving additional sites an established operating identity while preserving different ownership arrangements. Keeping the same restaurant identity across operated and franchised sites is the chain’s scaling task, so the ownership boundary should not become a different customer proposition.
By Location:
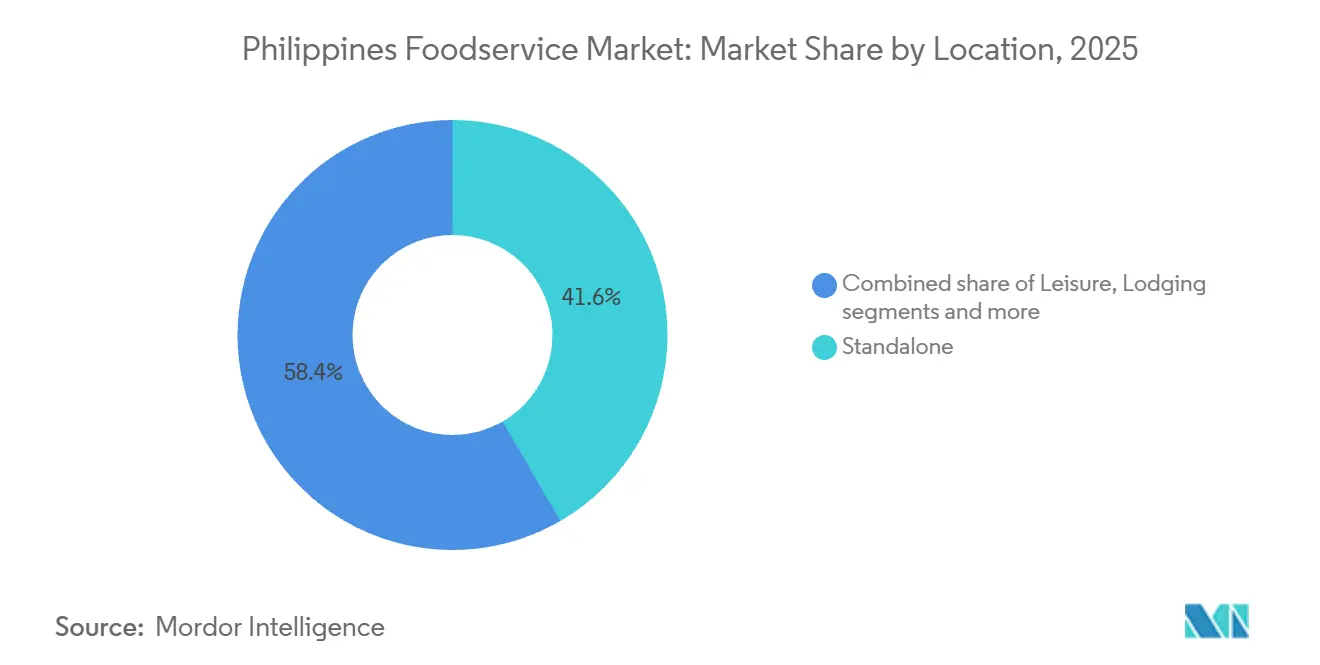
Independent Catchments and Hotel DiningStandalone outlets held 41.3% of foodservice sales in 2026, making them the largest segment by location. Shakey’s Philippines opened its first standalone Region 12 branch at the intersection of Datu Piang Street and Gensan Drive in Koronadal City on November 19, 2025. A street-based restaurant can establish its own customer catchment and service layout, making access to the individual site a central part of its commercial proposition. The resulting location decision is more specific than entering a city, because the outlet must give customers a practical route and a sufficient reason to choose that particular address.
Lodging is forecast to be the fastest-growing segment by location, registering a CAGR of 14.5% between 2027 and 2032. South Palms Resort & Spa Panglao offers 188 rooms and suites in Bohol. Its dining venues include UMA, Manja, Lola’s Kitchen, and Sirenna tiki bar. Combining accommodation with several foodservice venues creates scope to serve different meal and beverage occasions within a single property, with each venue contributing a distinct reason to stay on site. For South Palms, assigning a distinct guest occasion to each venue can broaden the resort’s dining offer without duplicating restaurants aimed at the same meal need.
By Service Type:
On-Site Occasions Meet Delivery EconomicsDine-in held 52.24% of foodservice sales in 2026, making it the largest segment by service type. In August 2025, Fogo de Chão announced its first Philippine restaurant at Glorietta 4 in Makati, with Bistro Americano Corp., a division of The Bistro Group, as its franchise partner. The announced churrasco offering included weekday lunch and dinner and weekend Brazilian brunch. For diners choosing a restaurant around a hosted occasion, that combined service can make the setting and the interaction with staff part of what they purchase. Filling several meal periods would let the announced format use the same dining room for different occasions, rather than require another site for each audience.
Delivery is forecast to be the fastest-growing segment by service type, with a CAGR of 15.3% between 2027 and 2032. Figaro Culinary Group, Inc. and its subsidiary reported food sales through third-party delivery providers and paid commissions during January through March 2026. The group acted as principal because it bore responsibility for supplying the food, carried the goods risk, and determined selling prices. This arrangement gives restaurants access to externally fulfilled orders while leaving the underlying food-sale obligations with the restaurant group. Price-setting discretion gives Figaro a lever to accommodate delivery commissions, but its food-supply responsibility prevents treating the platform fee as the channel’s only operating obligation.
Geography Analysis
Metro Manila Foodservice Market
Metro Manila is the leading foodservice geography, with room for large dining formats alongside the broader restaurant offer. Haidilao opened its second Philippine hot pot restaurant at Robinsons Galleria in Quezon City on January 31, 2025, with 284 seats. That addition illustrates how an operator can commit substantial on-site service capacity to a single metropolitan location, making the dining experience an important part of site economics. For a restaurant with that seating capacity, site selection must test the surrounding dining catchment before the operator commits to another large metropolitan room.
Cebu presents a visitor base that supports a different approach to foodservice access across travel flows. The Cebu Provincial Tourism Office recorded 3.56 million arrivals by Philippine residents and 1.97 million by non-Philippine residents in 2025. That residence-based mix gives visitor-facing operators substantial customer pools on both sides of the domestic travel boundary, so a proposition confined to one visitor channel can address only part of the opportunity. The larger resident-arrival pool makes domestic travelers the first audience to test when setting a Cebu visitor-facing restaurant’s menu, hours, and price points.
Bohol recorded 1.49 million visitor arrivals across the province in 2025, giving visitor-facing foodservice a sizable potential audience. In Davao City, the tourism office characterized local restaurants and other establishments as businesses needing greater visibility and support. These premises point to separate decisions about reaching a destination’s visitor pool and making an individual restaurant discoverable within it. For Bohol, the provincial arrival base frames a destination choice, while Davao’s restaurant-visibility problem calls for attention to how visitors choose an individual venue. Davao’s introduction of tourism circuits and tours makes route visibility a concrete option for local restaurants seeking visitors, with the commercial focus on discovery rather than additional dining capacity.
Regulatory Framework and Outlook
The comparison examines the Philippine national framework and Quezon City implementation from the perspective of a restaurant operator seeking authorization to trade. Republic Act 10611 assigns local governments responsibility for restaurant food safety and sanitation enforcement within their jurisdictions. A national brand therefore needs a local authorization process that fits the premises, making permit administration commercially relevant alongside compliance with the underlying safety duties.
Regulatory Table of Philippines Foodservice Market
| Decision factor | Philippines national framework | Quezon City |
|---|---|---|
| Primary authority | Local government units and local health offices | City Health Officer within the Quezon City Health Department |
| Key instruments or direction | Republic Act 10611 and Presidential Decree 856 | Sanitary-permit requirements and Executive Order No. 38, Series of 2025 |
| Commercial effect | Local sanitary permit required before public operation | Sanitary authorization follows inspection or evaluation against existing requirements |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | Easing |
| Source: Mordor Intelligence | ||
The national Medium rating and No change direction reflect continuity in the established local-permit duties that operators must satisfy. Quezon City’s Medium rating and Easing direction reflect Executive Order No. 38, effective December 23, 2025, which defers most business inspections except those required by law. Its annual, biennial, and triennial inspections cover high-, medium-, and low-risk businesses respectively, with the highest-risk activity governing processing and inspection requirements for businesses with multiple lines. Quezon City Health Department’s City Health Officer issues sanitary permits after a Sanitation Inspector’s or Evaluator’s compliance inspection or evaluation, so restaurant benefits depend on risk class and legally required inspections.
Value Chain Stages
The comparison follows food ingredients through restaurant preparation and then customer ordering and fulfillment, distinguishing the earnings captured at each stage. Jollibee Foods Corporation reported 5.7% year-over-year growth in systemwide sales for its Philippine business in the second quarter of 2026, covering consumer sales from company-owned and franchised stores. That operating activity gives preparation and service a direct revenue role, while distribution and platform services capture value through their own supply or service transactions.
Value Chain Analysis Table of Philippines Foodservice Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Ingredient distribution | Foodservice distributors such as DIMAX in Metro Manila | Food-product sales | Matching perishable stock with kitchen demand | Use replenishment lots aligned with expected preparation |
| Restaurant preparation and service | Restaurant operators and franchise networks such as Jollibee Foods Corporation | Consumer meal and beverage sales across company-owned and franchised outlets | Coordinating preparation across a store network | Standardize preparation and dispatch routines |
| Customer ordering and fulfillment | Ordering and delivery platforms such as GrabFood in most of Metro Manila and selected areas of Bulacan, Rizal, Cavite, Laguna, Pampanga, Cebu, Bacolod, and Davao | Merchant commission at the contracted service-fee rate | Orders outside supported delivery catchments | Align order acceptance with serviceable locations |
| Source: Mordor Intelligence | ||||
The chain places different commercial risks on the ingredient seller, meal preparer, and fulfillment intermediary. A restaurant must turn supplied ingredients into a saleable meal, while a platform’s contracted commission creates a separate claim on the economics of the order. As digital fulfillment becomes part of restaurant operations, the structural decision is how to coordinate preparation and customer access while preserving the outlet’s return from the food it sells.
Competitive Landscape
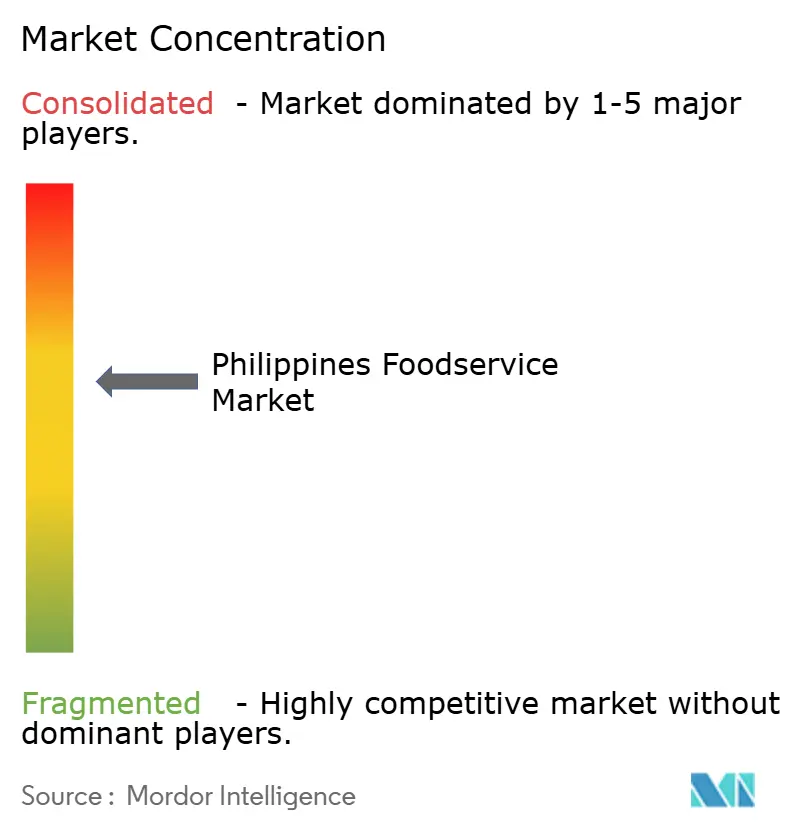
The industry is fragmented, with independent outlets competing alongside established branded restaurant networks and specialist beverage operators. Prominent participants include Jollibee Foods Corporation, Rustan Coffee Corporation (Starbucks Corporation), Max’s Group, Inc., Shakey's Pizza Asia Ventures, Inc., and Golden Arches Development Corporation (McDonald’s Philippines). Rustan Coffee Corporation trades as Starbucks Coffee locally, while Max’s Group reported 573 Philippine and overseas stores at year-end 2025, supported by a commissary and smaller production, distribution, and storage hubs. A restaurant portfolio can coordinate production across brands, while an individual outlet can concentrate its proposition on one local audience.
Company strategies combine licensed development rights and franchise-led expansion, while reported network sales provide a separate measure of commercial performance. In April 2025, McDonald’s Corporation granted Golden Arches Development Corporation a multi-unit Philippine franchise agreement through 2045, including rights to own, develop, operate, and sub-franchise restaurants under the agreement.[3] The long licensed horizon and sub-franchising rights provide a framework for additional restaurant owners to participate under the Philippine operator’s licensed structure. In August 2026, Jollibee Group said Compose Coffee’s nationwide Philippine growth would be franchise-led and pursued over 5 years, a capital-light route paralleling the McDonald’s sub-franchising arrangement. Shakey's Pizza Asia Ventures reported 17% year-over-year growth in company-wide systemwide sales in 2025, which measures the sales its network already generates, a different test from the right to open more outlets.
Competitive direction also depends on keeping food preparation dependable as restaurant concepts and fulfillment options multiply. The Code on Sanitation assigns local health authorities periodic inspection and sanitation-enforcement duties for food establishments. On January 8, 2026, Jollibee Group inaugurated its first multi-brand commissary in the Philippines in Danao City, Cebu, its largest commissary in Visayas and Mindanao. A multi-brand commissary can help Jollibee Group coordinate preparation across concepts, setting an operating benchmark for challengers whose food establishments also fall under local health authorities’ sanitation oversight. For challengers expanding several concepts in Cebu, the infrastructure decision extends beyond opening restaurants to choosing shared or separate preparation capacity.
Philippines Foodservice Industry Leaders
-
Jollibee Foods Corporation
-
Rustan Coffee Corporation (Starbucks Corporation)
-
Max’s Group, Inc.
-
Shakey's Pizza Asia Ventures, Inc.
-
Golden Arches Development Corporation (McDonald’s Philippines)
- *Disclaimer: Major Players sorted in no particular order
Philippines Foodservice Market Companies Covered in this Report
- Berjaya Corporation Bhd.
- Bounty Agro Ventures, Inc.
- Three Bears Group (Domino's Pizza)
- Golden Arches Development Corporation (McDonald’s Philippines)
- Inspire Brands, Inc.
- Jollibee Foods Corporation
- Mary Grace Foods Inc.
- Max’s Group, Inc.
- Restaurant Brands International Inc.
- Seven & I Holdings Co., Ltd.
- Shakey's Pizza Asia Ventures, Inc.
- Rustan Coffee Corporation (Starbucks Corporation)
- Figaro Culinary Group, Inc.
- Eight-8-Ate Holdings, Inc.
- Yum! Brands, Inc.
- Fruitas Holdings Inc.
- Philippine Pizza, Inc.
- One Food Group
- Red Ribbon Bakeshop Inc.
- ArmyNavy Burger Inc.
Recent Industry Developments in Philippines Foodservice Market
- Oct 2026: Conti’s Bakeshop & Restaurant opened its 113th store, its second branch at Robinsons Place Manila, offering a full restaurant experience.
- Sep 2026: Grab Philippines and NCMF Region XI agreed to pilot search filters for endorsed halal merchants and an optional Muslim-owned tag on GrabFood in Davao City, with NCMF endorsement required before either tag.
- Aug 2026: Jollibee Group opened the first Philippine Compose Coffee store in Taguig on August 7, introducing its South Korean value coffee brand to Filipino consumers.
Scope and Methodology
Segmentation Overview
By Foodservice Type
| Cafes & Bars | By Cuisine | Bars & Pubs |
| Cafes | ||
| Juice/Smoothie/Desserts Bars | ||
| Specialist Coffee & Tea Shops | ||
| Cloud Kitchen | ||
| Full Service Restaurants | By Cuisine | Asian |
| European | ||
| Latin American | ||
| Middle Eastern | ||
| North American | ||
| Other FSR Cuisines | ||
| Quick Service Restaurants | By Cuisine | Bakeries |
| Burger | ||
| Ice Cream | ||
| Meat-based Cuisines | ||
| Pizza | ||
| Other QSR Cuisines |
By Outlet
| Chained Outlets |
| Independent Outlets |
By Location
| Leisure |
| Lodging |
| Retail |
| Standalone |
| Travel |
By Service Type
| Dine-in |
| Takeaway |
| Delivery |
| By Foodservice Type | Cafes & Bars | By Cuisine | Bars & Pubs |
| Cafes | |||
| Juice/Smoothie/Desserts Bars | |||
| Specialist Coffee & Tea Shops | |||
| Cloud Kitchen | |||
| Full Service Restaurants | By Cuisine | Asian | |
| European | |||
| Latin American | |||
| Middle Eastern | |||
| North American | |||
| Other FSR Cuisines | |||
| Quick Service Restaurants | By Cuisine | Bakeries | |
| Burger | |||
| Ice Cream | |||
| Meat-based Cuisines | |||
| Pizza | |||
| Other QSR Cuisines | |||
| By Outlet | Chained Outlets | ||
| Independent Outlets | |||
| By Location | Leisure | ||
| Lodging | |||
| Retail | |||
| Standalone | |||
| Travel | |||
| By Service Type | Dine-in | ||
| Takeaway | |||
| Delivery | |||
Market Definition
- FULL-SERVICE RESTAURANTS - A foodservice establishment where customers are seated at a table, give their order to a server and are served food at a table.
- QUICK SERVICE RESTAURANTS - A foodservice establishment that provides customers convenience, speed, and food offerings at lower prices. Customers usually help themselves and carry their own food to their tables.
- CAFES & BARS - A type of foodservice business that include bars and pubs that are licensed to serve alcoholic drinks for consumption, cafes that serve refreshments and light food items, as well as specialty tea and coffee shops, dessert bars, smoothie bars, and juice bars.
- CLOUD KITCHEN - A foodservice business that utilizes a commercial kitchen for the purpose of preparing food for delivery or takeout only, with no dine-in customers.
| Keyword | Definition |
|---|---|
| Albacore Tuna | It is one of the smallest species of tuna found in the six distinct stocks known globally in the Atlantic, Pacific, and Indian oceans, as well as the Mediterranean Sea. |
| Angus beef | It is beef derived from a specific breed of cattle indigenous to Scotland. It requires certification from the American Angus Association to receive the "Certified Angus Beef" quality mark. |
| Asian cuisine | It includes full-service offerings in restaurants that serve cuisines from cultures such as Chinese, Indian, Korean, Japanese, Bengali, Southeast Asian, etc. |
| Average Order Value | It is the average value of all orders made by the customers at a foodservice establishment. |
| Bacon | It is salted or smoked meat that comes from the back or sides of a pig. |
| Bars & Pubs | It is a drinking establishment that is licensed to serve alcoholic drinks for consumption on the premises. |
| Black Angus | It is beef derived from a black-hided breed of cows that don't have horns. |
| BRC | British Retail Consortium |
| Burger | It is a sandwich consisting of one or more cooked beef patties, placed inside a sliced bread roll or bun roll. |
| Café | It is a foodservice establishment serving various refreshments (mainly coffee) and light meals. |
| Cafes & Bars | It is a type of foodservice business that include bars and pubs that are licensed to serve alcoholic drinks for consumption, cafes that serve refreshments and light food items, as well as specialty tea and coffee shops, dessert bars, smoothie bars, and juice bars. |
| Cappuccino | It is an Italian coffee drink that is traditionally prepared with equal parts double espresso, steamed milk, and steamed milk foam. |
| CFIA | Canadian Food Inspection Agency |
| Chained Outlet | It refers to a foodservice establishment that shares brands, operates in several locations, has central management, and standardized business practices. |
| Chicken Tender | It refers to chicken meat prepared from the pectoralis minor muscles of a chicken bird. |
| Cloud Kitchen | It is a foodservice business that utilizes a commercial kitchen for the purpose of preparing food for delivery or takeout only, with no dine-in customers. |
| Cocktail | It is an alcoholic mixed drink made with either a single spirit or a combination of spirits, mixed with other ingredients such as juices, flavored syrups, tonic water, shrubs, and bitters. |
| Edamame | It is a Japanese dish prepared with soybeans (harvested before they ripen or harden) and cooked in its pod. |
| EFSA | European Food Safety Authority |
| ERS | Economic Research Service of the USDA |
| Espresso | It is a concentrated form of coffee, served in shots. |
| European cuisine | It includes full-service offerings in restaurants that serve cuisines from cultures such as Italian, French, German, English, Dutch, Danish, etc. |
| FDA | Food and Drug Administration |
| Fillet Mignon | It is a cut of meat taken from the smaller end of the tenderloin. |
| Flank Steak | It is a cut of beef steak taken from the flank, which lies forward of the rear quarter of a cow. |
| Foodservice | It refers to the part of the food industry which includes businesses, institutions, and companies which prepare meals outside the home. It includes restaurants, school and hospital cafeterias, catering operations, and many other formats. |
| Franks | Also known as frankfurter or Würstchen, it is a type of highly seasoned smoked sausage popular in Austria and Germany. |
| FSANZ | Food Standards Australia New Zealand |
| FSIS | Food Safety and Inspection Service |
| FSSAI | Food Safety and Standards Authority of India |
| Full service restaurant | It refers to a foodservice establishment where customers are seated at a table, give their order to a server, and are served food at a table. |
| Ghost Kitchen | It refers to a cloud kitchen. |
| GLA | Gross Leasable Area |
| Gluten | It is a family of proteins found in grains, including wheat, rye, spelt, and barley. |
| Grain-fed beef | It is beef derived from cattle that have been fed a diet supplemented with soy and corn and other additives. Grain-fed cows can also be given antibiotics and growth hormones to fatten them up more quickly. |
| Grass-fed beef | It is beef derived from cattle that have only been fed grass as feed. |
| Ham | It refers to the pork meat taken from the leg of a pig. |
| HoReCa | Hotels, Restaurants and Cafes |
| Independent Outlet | It refers to a foodservice establishment that operates with a single outlet or is structured as a small chain with no more than three locations. |
| Juice | It is a drink made from the extraction or pressing of the natural liquid contained in fruit and vegetables. |
| Latin American | It includes full-service offerings in restaurants that serve cuisines from cultures such as Mexican, Brazilian, Argentinian, Colombian, etc. |
| Latte | It is a milk-based coffee that is made up of one or two shots of espresso, steamed milk, and a thin layer of frothed milk. |
| Leisure | It refers to foodservice offered as a part of a recreation business, such as sports arenas, zoos, movie theaters, and museums. |
| Lodging | It refers to foodservice offerings at hotels, motels, guesthouses, holiday homes, etc. |
| Macchiato | It is an espresso coffee drink with a small amount of milk, usually foamed. |
| Meat-based cuisines | This inlcudes food items like fried chicken, steak, ribs, etc. where meat is the primary ingredient for the dish. |
| Middle Eastern cuisine | It includes full-service offerings in restaurants that serve cuisines from cultures such as Arabic, Lebanese, Iranian, Israeli, etc. |
| Mocktail | It is an non-alcoholic mixed drink. |
| Mortadella | It is a large Italian sausage or luncheon meat made of finely hashed or ground heat-cured pork, which incorporates at least 15% small cubes of pork fat. |
| North American | It includes full-service offerings in restaurants that serve cuisines from cultures such as American, Canadian, Caribbean, etc. |
| Pastrami | It refers to a highly seasoned smoked beef, typically served in thin slices. |
| PDO | Protected Designation of Origin: It is the name of a geographical region or specific area that is recognized by official rules to produce certain foods with special characteristics related to location. |
| Pepperoni | It is an American variety of spicy salami made from cured meat. |
| Pizza | It is a dish made typically of flattened bread dough spread with a savory mixture usually including tomatoes and cheese and often other toppings and baked. |
| Primal cuts | It refers to the major sections of the carcass. |
| Quick service restaurant | It refers to a foodservice establishment that provides customers convenience, speed, and food offerings at lower prices. Customers usually help themselves and carry their own food to their tables. |
| Retail | It refers to a foodservice outlet inside a mall. shopping complex or a commercial real estate building, where there are other businesses operating as well. |
| Salami | It is a cured sausage consisting of fermented and air-dried meat. |
| Saturated fat | It is a type of fat in which the fatty acid chains have all single bonds. It is generally considered unhealthy. |
| Sausage | It is a meat product made of finely chopped and seasoned meat, which may be fresh, smoked, or pickled and which is then usually stuffed into a casing. |
| Scallop | It is an edible shellfish that is a mollusk with a ribbed shell in two parts. |
| Seitan | It is a plant-based meat substitute made out of wheat gluten. |
| Self-service kiosk | It refers to a self-order point-of-sale (POS) system through which customers place and pay for their own orders at kiosks, enabling totally contactless and frictionless service. |
| Smoothie | It is a beverage made by placing all the ingredients in a container and processing them together, without removing the pulp. |
| Specialty coffee & tea shops | It refers to a foodservice establishment that serves only various types of tea or coffee. |
| Standalone | It refers to a restaurants that have an independent infrastructure setup and not connected to any other business. |
| Sushi | It is a Japanese dish of prepared vinegared rice, usually with some sugar and salt, accompanied by a variety of ingredients, such as seafood—often raw—and vegetables. |
| Travel | It refers to foodservice offerings such as airplane food, dining on long-distance trains, and foodservice on cruise ships. |
| Virtual Kitchen | It refers to a cloud kitchen. |
| Wagyu Beef | It is beef derived from any of four strains of a breed of black or red Japanese cattle that are valued for their highly marbled meat. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step 1 are tested against available historical market numbers. Through an iterative process, the variables required for the market forecast are set, and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market size estimations for the forecast years are in nominal terms. Inflation is considered for average order value, and it is forecasted as per predicted inflation rates in the countries.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


