
North America Feed Lutein And Zeaxanthin Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
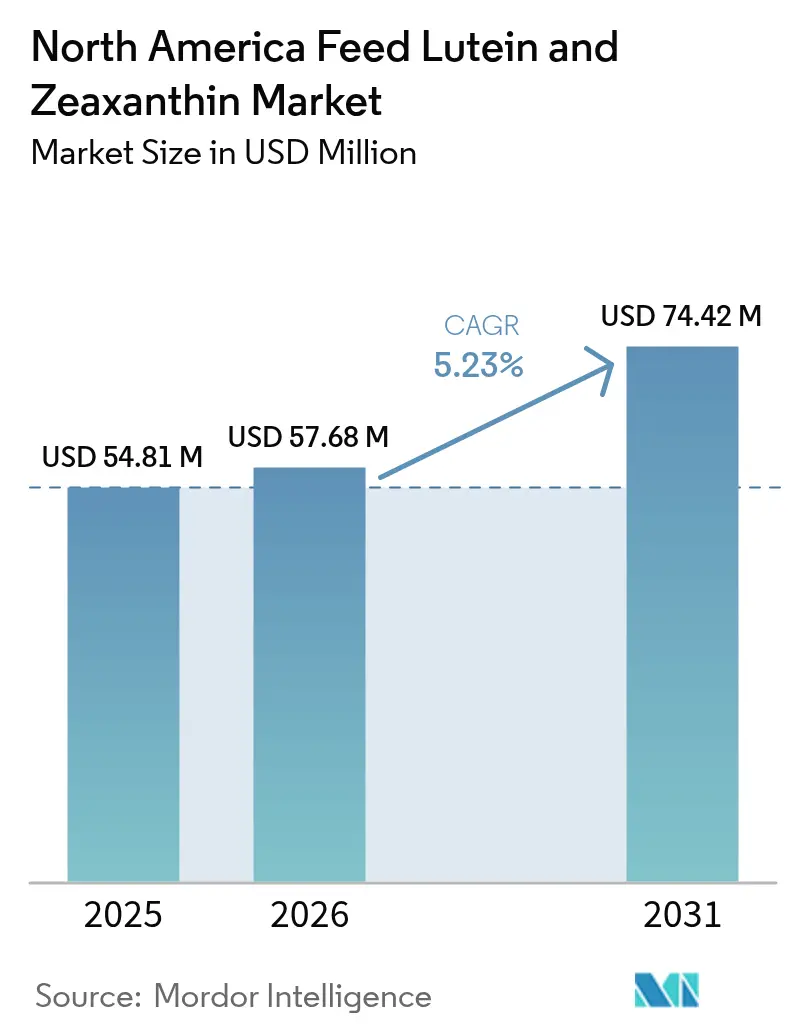
| Base Year Market Size (2025) | USD 54.81 Million |
| Market Size (2026) | USD 57.68 Million |
| Market Size (2031) | USD 74.42 Million |
| Growth Rate (2026 - 2031) | 5.23 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
North America Feed Lutein And Zeaxanthin Market Analysis by Mordor Intelligence
The North America feed lutein and zeaxanthin market size is expected to grow from USD 54.81 million in 2025 to USD 57.68 million in 2026 and is forecast to reach USD 74.42 million by 2031 at 5.23% CAGR over 2026-2031. The market is evolving due to shifting consumer preferences and demographic changes. With the United States Census Bureau forecasting a population of 417 million by 2060, the demand for animal-based protein products remains strong. The market growth is driven by the increasing demand for naturally pigmented eggs, meat, and farmed fish, supported by organic certification requirements that restrict synthetic additives. The expansion of aquaculture production, particularly in salmon and trout farming, increases the demand for astaxanthin-related xanthophylls. Poultry integrators are enhancing yolk color programs to meet quick-service restaurant requirements. Recent regulatory changes by the Food and Drug Administration and Canadian Food Inspection Agency have increased permitted carotenoid inclusion rates, providing greater formulation flexibility. Marigold cultivation contracts in Mexico and Guatemala ensure consistent lutein supply throughout the year, but raw material price fluctuations continue to pose challenges.
Key Report Takeaways
- By animal type, poultry led with 57.80% of the North America feed lutein and zeaxanthin market share in 2025, while aquaculture is forecast to record the fastest 7.69% CAGR through 2031.
- By source, natural commanded a 71.90% share of the North America feed lutein and zeaxanthin market size in 2025, and is projected to advance at a 7.36% CAGR between 2026-2031.
- By country, the United States held a 61.80% share of the market revenue in 2025, whereas Mexico is set to expand at a 6.13% CAGR to 2031.
- Market concentration is moderate, with the top five companies - DSM-Firmenich AG, BASF SE, Kemin Industries, Inc., EW Nutrition GmbH, and Nutrex NV collectively holding the majority of the market share in 2024.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
North America Feed Lutein And Zeaxanthin Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising demand for animal-based protein | +1.2% | United States and Canada | Medium term (2-4 years) |
| Surging demand for natural pigmentation | +0.9% | United States and Canada organic sectors | Long term (≥ 4 years) |
| Expansion of organic-certified egg and meat output | +0.8% | United States and Canada | Long term (≥ 4 years) |
| Technological advances in carotenoids extraction and delivery methods | +0.7% | North America research and development hubs | Medium term (2-4 years) |
| Marigold production contracts lowering supply-chain risk | +0.5% | Mexico and Guatemala supply corridors | Short term (≤ 2 years) |
| Regulatory allowances for higher inclusion caps | +0.4% | United States Food and Drug Administration and Canadian Food Inspection Agency regions | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||


Rising Demand for Animal-Based Protein
North American protein consumption patterns influence carotenoid demand as livestock producers optimize feed formulations to achieve specific egg yolk color and salmon flesh pigmentation requirements. The United States Department of Agriculture projects growth in per capita consumption of eggs and fish, particularly farmed salmon, where astaxanthin supplementation is necessary for market acceptance. The increasing per-capita egg and fish consumption across the United States and Canada has led feed formulators to adjust lutein, zeaxanthin, and astaxanthin dosing for color consistency[1]Source: “Aquaculture Opportunity Areas,” NOAA.gov. Quick-service restaurant chains require specific yolk color standards, which compel integrators to maintain consistent xanthophyll levels in feed formulations. This requirement has shifted the North America feed lutein and zeaxanthin market toward precision premixes.
Surging Demand for Natural Pigmentation
Consumer preferences for natural ingredients are reshaping carotenoid sourcing strategies as food manufacturers adapt to clean label demands. Natural carotenoids from marigold extract and paprika oleoresin command higher prices but comply with the United States Department of Agriculture (USDA) National Organic Program standards, which restrict synthetic alternatives. The demand for clean-label products increases the use of marigold and paprika-derived pigments despite their premium pricing. United States Department of Agriculture Organic regulations prohibit most synthetic carotenoids, directing poultry and premium aquaculture producers toward natural inputs, despite cost premiums reaching 200% above synthetic options[2]Source: Agricultural Marketing Service, “Organic Livestock Requirements,” USDA.gov. This shift significantly affects premium egg producers, where natural yolk pigmentation supports higher retail prices and organic certification requirements.
Technological Advancement in Carotenoids Extraction and Delivery Methods
Advancements in extraction methods have reduced natural carotenoid production costs while enhancing bioavailability through improved delivery systems. The use of supercritical CO2 extraction eliminates solvent residues and increases carotenoid purity, addressing food safety requirements and lowering processing costs compared to conventional solvent extraction. The application of enzymatic extraction using cellulases and pectinases increases yield from marigold petals and other plant sources, improving the economic viability of natural carotenoid production. Microencapsulation protects carotenoids from oxidation during feed processing and storage, extending product shelf life and minimizing supply chain waste.
Marigold Production Contracts Lowering Supply-Chain Risk
Contract farming of marigolds in Mexico and Guatemala provides stability to North American carotenoid processors' supply chains. These agreements establish minimum prices for farmers and ensure consistent raw material availability for processors, reducing the price volatility that previously limited natural pigment adoption. The long-term contracts also support investments in specialized harvesting and processing equipment, which enhances lutein extraction efficiency from marigold flowers.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Raw material price volatility | -0.8% | Global inputs into North America | Short term (≤ 2 years) |
| Stringent color uniformity specs from quick-service restaurants | -0.6% | United States and Canada foodservice | Medium term (2-4 years) |
| Stability and shelf-life issues | -0.4% | North America distribution networks | Medium term (2-4 years) |
| Limited farmer awareness outside the poultry segment | -0.3% | Rural aquaculture zones | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Raw Material Price Volatility
Raw material costs for carotenoids experience significant fluctuations due to weather-dependent crop yields and the limited number of suppliers, creating budget uncertainty for feed manufacturers who operate on narrow margins. Marigold flower prices vary by season and respond to climate conditions in major growing regions. Supply disruptions in synthetic carotenoid precursors occur due to chemical plant outages, as evidenced by the BASF Ludwigshafen facility fire in July 2024, which affected vitamin A market availability. The limited number of global carotenoid producers increases price sensitivity when individual facilities face disruptions or capacity limitations.
Stringent Color Uniformity Specs from Quick-Service Restaurants
Foodservice chains require strict color specifications for egg products and salmon portions, necessitating precise dosing of carotenoids in animal feed. These specifications often exceed natural color variation ranges, compelling producers to either combine multiple carotenoid sources or increase inclusion rates to achieve consistent results. Meeting these standards accounts for 2-3% of total feed costs in laying hen operations and up to 20% in salmon feed production. Consumers increasingly prefer natural ingredients, but economic pressures favor the use of synthetic carotenoids for achieving color consistency. The additional quality control testing requirements increase operational costs and create risks of batch rejection due to color non-compliance.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Animal Type: Poultry Maintains Dominance
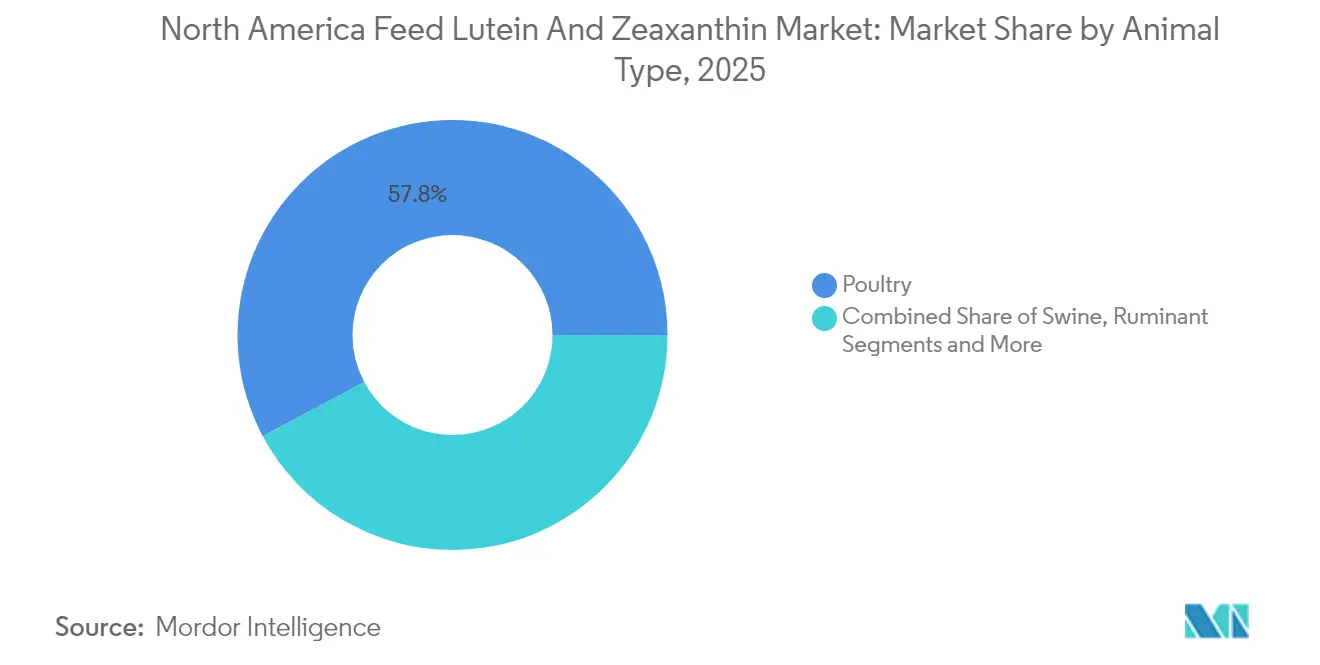
Poultry accounts for 57.80% of the North American feed lutein and zeaxanthin market share in 2025, and is projected to advance at a 7.34% CAGR between 2026-2031. Layer operations require precise lutein and zeaxanthin supplementation to meet the United States Department of Agriculture Grade AA yolk color standards required by retailers. Commercial broiler producers utilize xanthophyll supplementation to enhance skin coloration, particularly for premium branded products. The poultry segment offers the highest returns for pigment suppliers due to efficient premix distribution systems and established technical support infrastructure.
The aquaculture segment is projected to grow at a 7.69% CAGR through 2031. Salmon and trout farming operations require both astaxanthin and lutein supplementation to achieve specific flesh color characteristics for product differentiation. With pigments comprising up to 20% of total feed costs, producers increasingly adopt microencapsulated forms to minimize feed waste. The expanding shrimp production in Mexico and the Gulf Coast regions provides additional growth opportunities, as processors must maintain consistent shell pigmentation to meet export requirements.


By Source: Natural Pigments Lead but Face Cost Pressure
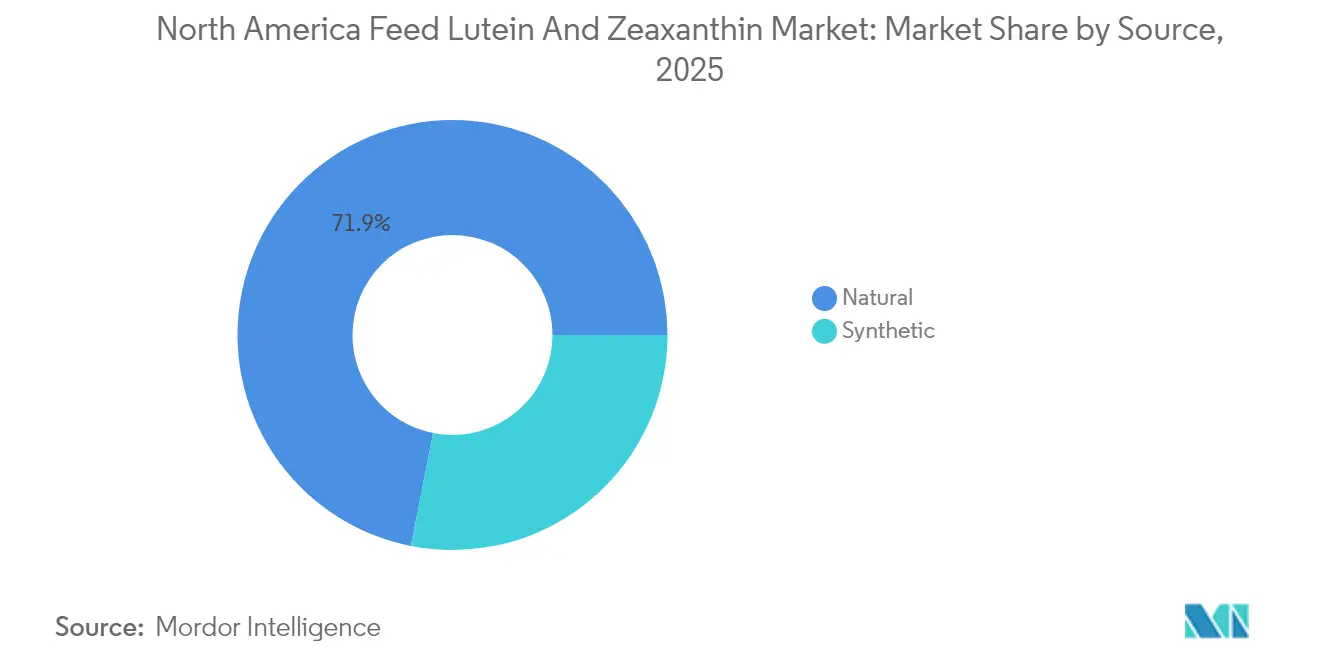
Natural ingredients account for 71.90% of the North America feed lutein and zeaxanthin market size in 2025 and are projected to grow at a 7.36% CAGR during 2026-2031, driven by regulatory requirements and consumer preference for plant-derived ingredients. Marigold, paprika, and algae serve as primary sources for lutein and zeaxanthin production, with enhanced extraction efficiencies reducing the cost difference compared to synthetic alternatives. Manufacturers leverage organic certification premiums to offset higher raw material costs, while encapsulation technology preserves the stability of natural molecules during the feed pelleting process.
Synthetic sources maintain a cost advantage in conventional feed operations, providing consistent oxidative stability and color uniformity. Their market share decreases as food service chains and retailers increase their clean-label requirements. In response, manufacturers invest in the research and development of solvent-free extraction and enzyme-based processes to increase the efficiency of natural ingredient production.
Geography Analysis
The United States holds 61.80% of the North America feed lutein and zeaxanthin market share in 2025. This dominance stems from the country's position as the second-largest poultry producer globally and its growing coastal salmon aquaculture industry. The Food and Drug Administration's established inclusion thresholds facilitate formulation approvals, though supply chain vulnerabilities emerged during events including BASF's 2024 vitamin precursor disruption.
Canada maintains a smaller but high-value position in the North America feed lutein and zeaxanthin market. The Canadian Food Inspection Agency's 2024 approval of saponified paprika oleoresin provided organic egg producers with additional pigment options. The country's salmon farms in British Columbia and Atlantic provinces use astaxanthin and lutein combinations to meet export standards, despite limited domestic pigment crop production due to climate constraints.
Mexico demonstrates the highest regional growth rate at 6.13% CAGR through 2031, benefiting from continuous marigold production and advancing poultry operations. COFEPRIS (Federal Commission for the Protection against Sanitary Risks) aligns its additive regulations with North American standards, though approval processes remain longer. The Pacific coast shrimp aquaculture industry increases its use of pigment-enhanced feeds to meet Asian market color requirements, driving demand for lutein and zeaxanthin concentrates.
Regulatory Landscape
In the United States, feed lutein and zeaxanthin fall under the broader animal food ingredient oversight of the FDA Center for Veterinary Medicine (CVM), where market access for new ingredients typically depends on an FDA food additive petition or a GRAS pathway. After the October 2024 expiration of the AAFCO-FDA Memorandum of Understanding, FDA implemented an interim Animal Food Ingredient Consultation approach for ingredients that historically moved through the AAFCO definition route. This adds an additional FDA-led pre-market review step for suppliers and premixers.
In Canada, the regulatory baseline is the Feeds Regulations, 2024 (SOR/2024-132), published July 3, 2024, which replaced the 1983 framework and governs feed manufacture, sale, and import. Under this regime, livestock feeds generally require registration unless they meet specific exemptions, and ingredient acceptability is tied to listings in the Canadian Feed Ingredients Table (CFIT). As a result, pigment suppliers document ingredient identity, permitted uses, and labeling in a way that fits Canadian poultry and aquaculture programs serving cross-border customers.
Competitive Landscape
The market shows moderate concentration, with five companies, DSM-Firmenich AG, BASF SE, Kemin Industries, Inc., EW Nutrition GmbH, and Nutrex NV - holding the majority market share in 2024, while still allowing space for niche players. DSM-Firmenich AG maintains the largest market share, with its planned spin-off of the Animal Nutrition and Health division aimed at enhancing strategic focus and shareholder value.
DSM-Firmenich AG and BASF SE maintain competitive advantages through patented microencapsulation technology, extending carotenoid shelf life by 18 months - a significant benefit for distributors operating across large geographical areas. Kemin secures its market position through proprietary marigold varieties grown under long-term contracts in Mexico, ensuring a consistent supply of natural lutein. Smaller market participants compete by developing specialized blends for regional preferences or providing comprehensive technical support services to emerging aquaculture customers.
Recent strategic decisions reflect industry transformation. DSM-Firmenich sold its Feed Enzymes Alliance stake to Novonesis for EUR 1.5 billion (approximately USD 1.6 billion) in February 2025, reallocating resources toward the expansion of carotenoids and vitamins. Kemin introduced PROSIDIUM in March 2025, expanding into biosecurity solutions that complement its existing pigment products. BASF divested its Food and Health Performance Ingredients unit in December 2024 to concentrate on nutrition and feed additives operations, including feed lutein and zeaxanthin.
North America Feed Lutein And Zeaxanthin Industry Leaders
DSM-Firmenich AG
BASF SE
Kemin Industries, Inc.
EW Nutrition GmbH
Nutrex NV
- *Disclaimer: Major Players sorted in no particular order


Market Opportunities and Future Outlook
Organic and clean-label production requirements create pull-through for natural-source pigment programs that can be supported with documentation and consistent performance. USDA National Organic Program constraints that restrict synthetic additives keep marigold- and paprika-derived carotenoids relevant for premium egg producers, while supplier progress in extraction and stabilization, including microencapsulation to reduce oxidation and pelleting loss, supports wider adoption across premixes and integrator-led yolk color programs.
Aquaculture provides a second lane for lutein and zeaxanthin demand alongside astaxanthin, especially where producers focus on tight color consistency and want to reduce pigment waste in high-cost diets. Demand is also supported by North America supply-corridor measures, including marigold cultivation contracts in Mexico and Guatemala, which help limit seasonality risk for natural lutein inputs. In addition, the regulatory changes referenced in the report context, including increased permitted carotenoid inclusion rates by the FDA and Canadian Food Inspection Agency, give formulators more room to balance natural-plus blends against stringent color requirements from quick-service restaurant and export channels.
Recent Industry Developments
- January 2026: dsm-firmenich inaugurated its Ames, Iowa, premix plant as organic certified, expanding capacity for specialized feed additive production in North America. The certification supports supply programs that need organic-compliant formulations and ties into demand for natural pigmentation inputs in premium egg and meat chains.
- October 2025: BASF launched Lutavit A/D3 1000/200 NXT, a microencapsulated vitamin formulation for animal nutrition produced at its Ludwigshafen Verbund site. The move reinforces competitive emphasis on encapsulation and stability technologies that also influence how fat-soluble nutrients and carotenoid systems are delivered through premixes.
- July 2024: BASF reported a disruption tied to its Ludwigshafen site, which the report context links to volatility in vitamin A precursor availability. The incident underscored supply-chain sensitivity for carotenoid-adjacent inputs and reinforced the value of risk-management approaches such as diversified sourcing and contracted natural raw-material corridors.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the value of lutein and zeaxanthin used as feed additives in North America. It is counted as sales into animal nutrition applications across the supply chain in the region.
Scope exclusions: This sizing excludes lutein and zeaxanthin sold mainly for human nutrition, cosmetics, and pharma uses, and it also excludes non-lutein carotenoid pigments unless they are part of the same counted product sale.
Segmentation Overview
- By Animal Type
- Poultry
- Swine
- Ruminants
- Aquaculture
- Other Animal Type (Equine, Camel, etc.)
- By Source
- Natural
- Synthetic
- By Country
- United States
- Canada
- Mexico
- Rest of North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk work started with building a simple fact base on livestock output and feed production, then narrowing it to the points where pigmentation additives are commonly used in animal diets. Public sources were used to anchor the demand pool, including USDA livestock and feed grain tables, Statistics Canada agri-food datasets, and official trade statistics from USITC DataWeb and UN Comtrade.
We also reviewed regulatory and compliance cues that affect which carotenoids can be used and how they are labeled, using documents from the FDA and the Canadian Food Inspection Agency. To connect demand with supply, we referenced company filings, investor presentations, and credible industry press. Paid subscriptions were used for company financials and intelligence, patent scans, and shipment-level trade signals when public cut data was not detailed enough. The sources listed here are illustrative and not exhaustive, since many other public and paid references were checked for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary discussions were held with feed additive suppliers, premix and compound feed participants, and technical specialists who influence pigment inclusion decisions for poultry, aquaculture, and other animal diets in North America. These inputs were used to confirm use-rate ranges, typical purchasing patterns, and observed price movement. We then used the same feedback to pressure-test the country split across the US, Canada, Mexico, and the rest of the region.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 34% | CXOs: 18% |
| Mid tier: 45% | Functional/Unit leaders: 32% |
| Smaller Players: 21% | Managers: 50% |
Market-Sizing & Forecasting
The core model used a top-down logic, converting livestock output and feed production signals into an addressable pool for pigmentation additives, then filtering it by adoption in relevant animal categories. Once that pool was formed, we applied market-consistent inclusion rates and price bands for lutein and zeaxanthin products, and then adjusted totals using country-level and channel-level checks.
To keep assumptions grounded, we tracked practical fingerprints such as poultry and aquaculture production trends, compound feed output, import and export movements for carotenoid-related inputs and finished additives, the share shift between natural and synthetic sources, and realized price direction in B2B feed additive sales. We then corroborated the result with selective bottom-up approximations, including sampled supplier revenue ranges, distributor and premix channel checks, and ASP times volume sanity tests in pockets where data was clearer. Where data gaps remained, we used conservative ranges and rechecked them in follow-up calls. For forecasting, we used scenario analysis linked to livestock production outlooks, the regulatory posture toward synthetic pigments, and customer willingness to pay for natural coloration. These scenarios were reviewed with primary experts before finalizing the curve.
Data Validation & Update Cycle
Validation relied on multiple passes that compare modeled totals against independent signals, including feed production direction, trade movements, and observed pricing for carotenoid additives in the region. When a variance appeared too large for a specific country or animal group, we reopened the assumption, rechecked notes, and triggered targeted re-contacts to confirm what had changed.
Before sign-off, the model and key inputs went through analyst reviews focused on outliers, unit consistency, and a clean year-over-year progression. The report is refreshed on an annual cycle, with interim updates when a material event occurs, such as a regulatory change or a sharp shift in raw material availability. Right before delivery, a final pass is completed so the published view reflects the latest available signals.
Mordor Intelligence's North America Feed Lutein and Zeaxanthin Market Size Versus Other Published Estimates
Published market sizes for this niche feed additive space can differ more than expected, largely because each publisher chooses a different product boundary and a different way to convert livestock activity into additive demand. Timing also contributes to the spread, because pricing for natural carotenoids can move within a year, and some estimates lock in prices too early or apply a different currency conversion point.
Key gap drivers typically come down to scope and the demand proxy used. For example, whether the model ties to compound feed output and realistic inclusion rates by animal type, or whether it extrapolates from a broader feed pigments total using a simple share. Some estimates also include adjacent carotenoids, count more upstream value, or extend beyond North America by treating Mexico-linked supply as end-market demand. Those choices can lift the total even if local consumption did not change.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 54.81 M (2025) | |
| Industry Portal A | USD 55.11 M (2025) | Uses a shorter horizon and a 2025-2030 framing, and it is less explicit about how animal-type inclusion rates and natural versus synthetic splits are validated at the country level. |
| Market Tracker B | USD 52.29 M (2022) | Anchors the market in an earlier year and appears to rely on a high-level trend extrapolation, which can miss later pricing and adoption changes that show up in feed output and trade signals. |
Import and export movements for carotenoid additives, together with compound feed and livestock output checks, are the evidence points that keep Mordor Intelligence tied to a North America consumption-led demand pool and to current-year price reality. When the scope is kept tight to feed-use lutein and zeaxanthin, and assumptions are rechecked against these external signals, the resulting number tends to sit in a narrow, explainable band even if other publications show a wider spread.


Key Questions Answered in the Report
What is the current value of the North America feed lutein and zeaxanthin market?
The market is valued at USD 57.68 million in 2026.
How fast is the market projected to grow?
It is forecast to expand at a 5.23% CAGR, reaching USD 74.42 million by 2031.
Which animal segment uses the most lutein and zeaxanthin?
Poultry leads with 57.80% market share in 2025 because of stringent yolk color standards.
Why are natural pigments gaining traction?
The United States Depertment of Agriculture Organic rules prohibit most synthetic additives and consumers favor clean-label products, giving natural pigments 71.90% share in 2025.
Which country shows the fastest growth?
Mexico is projected to grow at a 6.13% CAGR through 2031 as aquaculture and modern poultry facilities expand.
Page last updated on:





