
Network-Centric MDR Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 2.10 Billion |
| Market Size (2032) | USD 4.55 Billion |
| Growth Rate (2027 - 2032) | 16.72 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
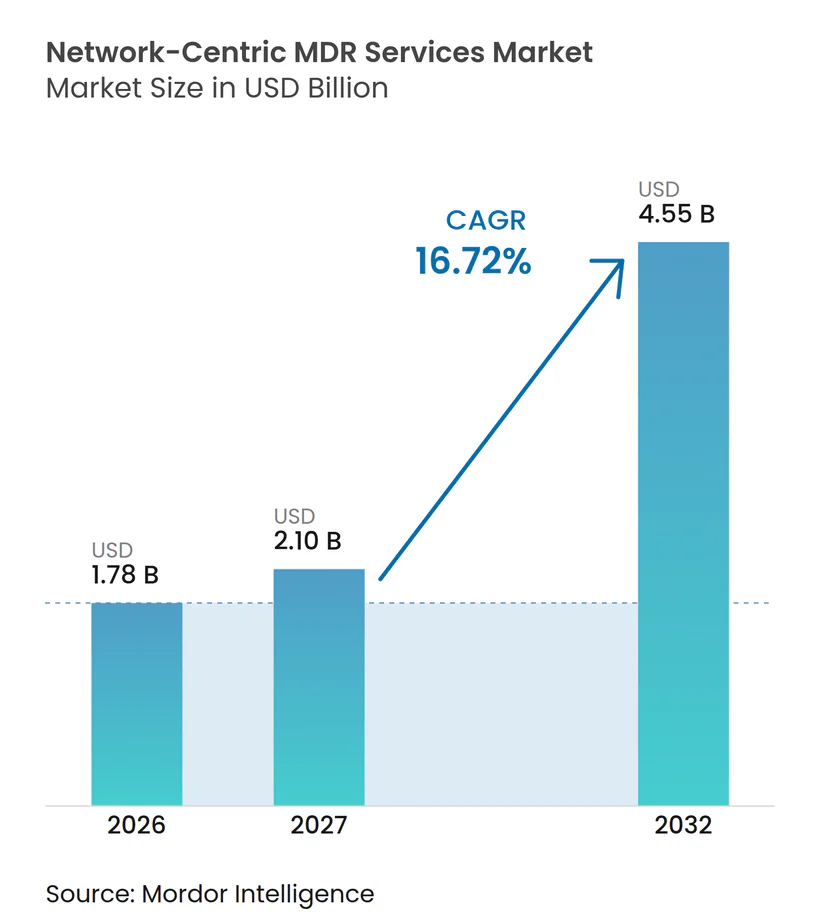
Network-Centric MDR Services Market Analysis by Mordor Intelligence
The Network-centric MDR services market size is projected to expand from USD 1.78 billion in 2026 and USD 2.10 billion in 2027 to USD 4.55 billion by 2032, registering a CAGR of 16.72% between 2027 and 2032. Demand is rising because organizations need continuous response capacity that internal security teams often cannot provide. Faster ransomware activity has increased the value of observing network traffic before attackers move across systems. Cloud adoption, hybrid work, connected devices, and operational technology have widened the environments that require monitoring. Providers are responding through broader platform capabilities, regional service coverage, and acquisitions that add response and threat-hunting expertise. Data residency rules and difficult integrations can delay deployment, but they also favor providers with established infrastructure and wider technical coverage.
Key Report Takeaways
- By service component, 24/7 Managed Security Operations and Threat Hunting Services held 63.14% of the Network-centric MDR services market share in 2026 and is projected to expand at an 17.92% CAGR through 2032
- By service model, Fully Managed Network MDR held 65.47% of revenue in 2026, while Co-Managed Network MDR is projected to expand at an 18.42% CAGR through 2032.
- By deployment mode, Cloud-Based deployment held 44.19% of revenue in 2026 and is projected to expand at an 18.87% CAGR through 2032.
- By organization size, Large Enterprises held 61.78% of the Network-centric MDR services market revenue in 2026, while Small and Medium Enterprises are projected to expand at an 18.23% CAGR through 2032.
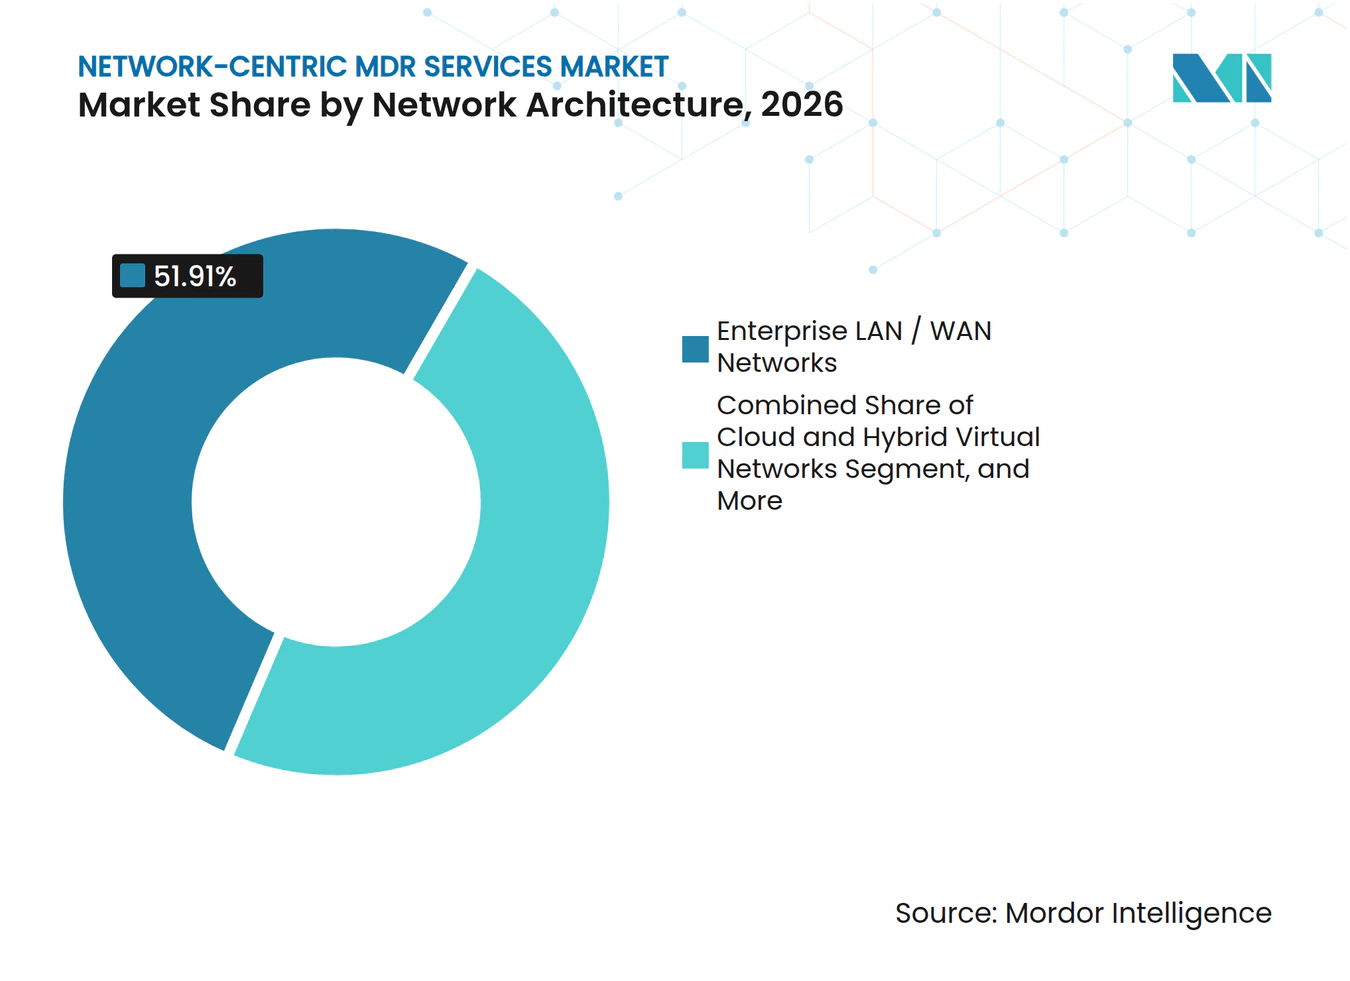
- By network architecture, Enterprise LAN/WAN Networks held 51.91% of revenue in 2026, while Cloud and Hybrid Virtual Networks are projected to expand at a 19.35% CAGR through 2032.
- By industry vertical, BFSI held 23.11% of revenue in 2026, while Manufacturing is projected to expand at an 18.41% CAGR through 2032.
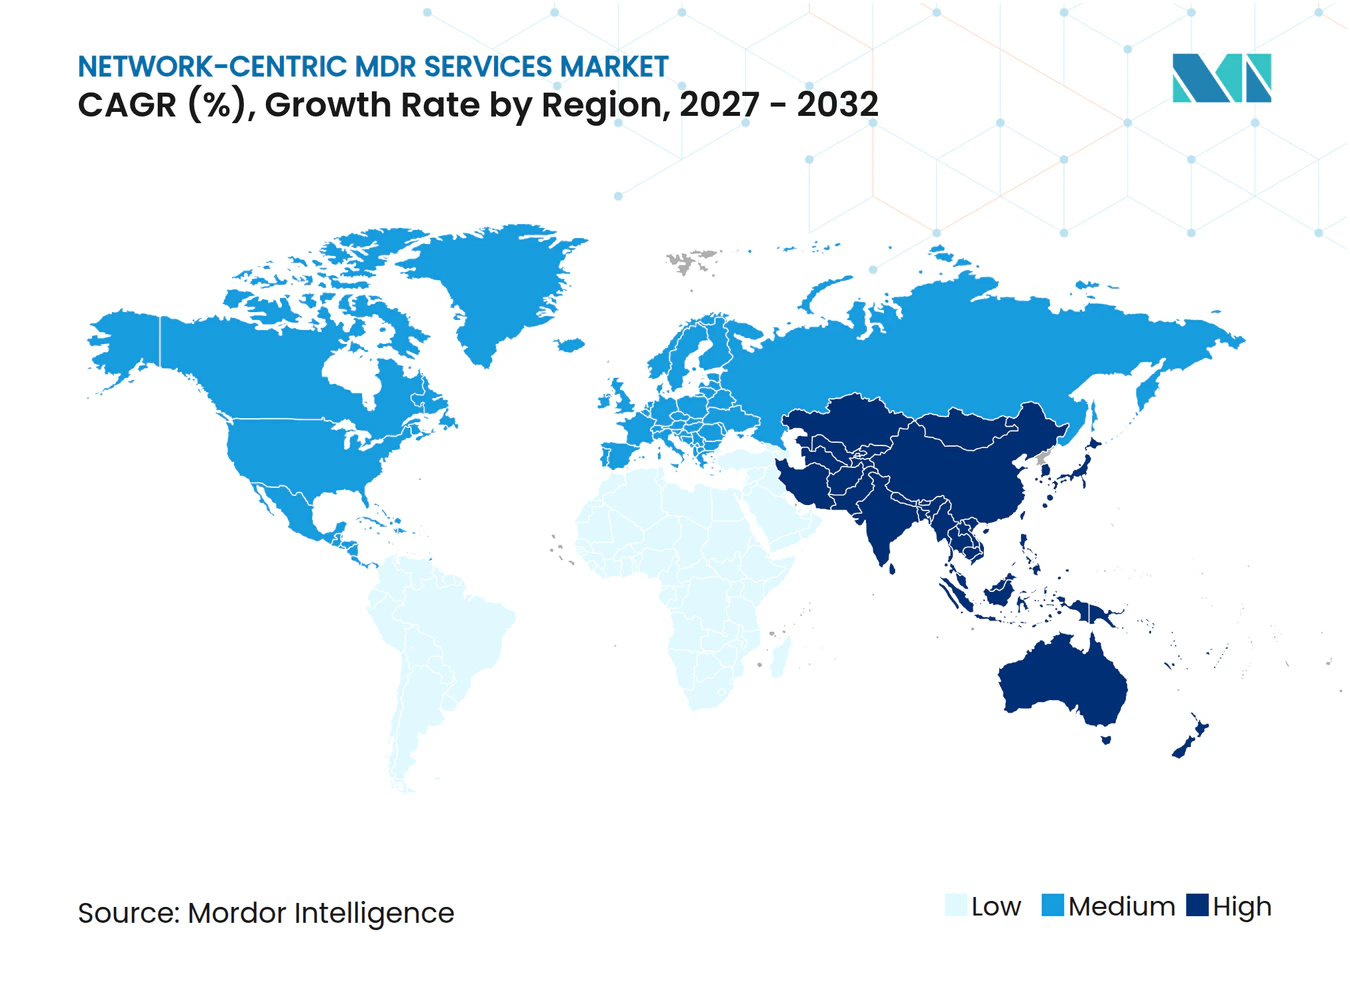
- By geography, North America held 43.93% of revenue in 2026, while The Network-centric MDR services market in Asia-Pacific is projected to expand at a 19.68% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Network-Centric MDR Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| 24/7 Detection Demand From Cybersecurity Talent Shortages | +5.2% | Global, most acute in North America, Asia-Pacific, and UK | Short term (≤ 2 years) |
| Rising Ransomware, AI-Assisted Attacks, and Lateral-Movement Risk | +4.1% | Global, with elevated intensity in North America, Europe, and Asia-Pacific | Short term (≤ 2 years) |
| Regulatory and Cyber-Insurance Requirements for Verifiable Response | +3.5% | North America and EU, with spillover to Asia-Pacific financial sectors | Medium term (2-4 years) |
| Cloud, Hybrid-Work, and IoT/OT Attack-Surface Expansion | +2.8% | Global, with core exposure in Asia-Pacific and North America manufacturing | Medium term (2-4 years) |
| Network Telemetry as the Missing Layer in Endpoint-Led XDR | +2.1% | North America and EU core, with spillover to Middle East and Africa | Medium term (2-4 years) |
| Surge-Resilient Regional SOC Coverage as a Board-Level Requirement | +1.6% | Global, with early adoption in North America and Western Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
24/7 Detection Demand From Cybersecurity Talent Shortages
The shortage of qualified security staff is changing how organizations buy detection and response services. ISACA reported that 55% of cybersecurity teams were understaffed in 2025, while 65% of organizations had unfilled security positions. The same survey found that 50% of respondents faced difficulty retaining existing staff. ISC2 found that 59% of practitioners identified critical or significant skills gaps in 2025, compared with 44% in 2024. AI security and cloud security were identified as key shortage areas, which makes traffic analysis and threat hunting difficult to sustain internally. The Network-centric MDR services market benefits when organizations use managed teams to provide continuous monitoring without building a full 24/7 security operations center.
Rising Ransomware, AI-Assisted Attacks, and Lateral-Movement Risk
Ransomware activity is increasing the need for earlier detection of movement inside enterprise networks. Zscaler reported a 275% year-over-year increase in ransomware data exfiltration to 896.2 terabytes in 2026. The report also documented USD 328 million in ransomware payments. CrowdStrike reported in March 2026 that adversaries were using AI to increase the speed and scale of operations.[1] Network telemetry can reveal east-west traffic patterns when endpoint agents are missing or disabled. This makes network visibility important for environments that include operational technology, connected devices, and systems where endpoint software cannot be deployed.
Regulatory and Cyber-Insurance Requirements for Verifiable Response
Regulatory requirements are making documented response capability more important for many buyers. The EU Digital Operational Resilience Act has applied to covered financial entities since January 17, 2025, with requirements for ICT risk management, incident reporting, and oversight of third-party providers. EU ENISA reported that 70% of surveyed organizations identified NIS2, DORA, and the Cyber Resilience Act as the main drivers of cybersecurity investment. These frameworks increase the value of records that show how incidents were detected, investigated, and contained. The Network-centric MDR services market is supported when managed providers can supply audit-ready logs and defined service-level commitments. Providers that can demonstrate a repeatable response process are better placed to serve regulated financial and other critical sectors.
Cloud, Hybrid-Work, and IoT/OT Attack-Surface Expansion
Cloud workloads, hybrid work, connected devices, and industrial systems have expanded the number of systems that security teams must observe. These environments create traffic across cloud services, sites, and devices that may not support endpoint agents. Zscaler reported that ransomware targeting of utilities increased by 622% in the year to March 2026. The exposure is important for energy, utilities, and manufacturing organizations that operate operational technology alongside enterprise IT. Monitoring industrial protocols can help providers identify unusual communications within those environments. The Network-centric MDR services market gains relevance as buyers seek coverage that extends across cloud, IT, IoT, and operational technology environments.
Restraints Impact Analysis of Network-Centric MDR Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data Privacy, Sovereign-Cloud, and Cross-Border Telemetry Constraints | -2.1% | EU, Asia-Pacific core, China, India, South Korea, and Middle East and Africa | Medium term (2-4 years) |
| Integration Complexity Across Multi-Vendor Security Stacks | -1.8% | Global, most acute in large enterprises with legacy SIEM deployments | Short term (≤ 2 years) |
| Inconsistent Analyst Quality and SLA Performance Under Stress | -1.2% | Global, concentrated in smaller regional providers | Medium term (2-4 years) |
| Unmanaged IoT, OT, and Medical-Device Blind Spots | -0.9% | North America and EU healthcare, North America and Asia-Pacific manufacturing | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Data Privacy, Sovereign-Cloud, and Cross-Border Telemetry Constraints
Data residency rules can limit the ability of providers to centralize network telemetry across borders. European regulated entities must consider DORA requirements for risk management and third-party oversight when selecting service partners.[2] Similar localization requirements can affect delivery in China, India, and South Korea. Providers may need regional infrastructure and local operational capacity before they can serve regulated organizations in these markets. The resulting separation of data can reduce the range of threat intelligence applied across customer environments. Smaller providers can be excluded from procurement processes when they cannot demonstrate the required sovereign deployment model.
Integration Complexity Across Multi-Vendor Security Stacks
Most large organizations use security tools from several vendors, which makes telemetry integration difficult. Network sensors, SIEM feeds, cloud interfaces, and operational technology parsers need to be connected before a provider can establish reliable behavioral baselines. Legacy on-premises systems can add further implementation work when customers move toward cloud-based monitoring. This work can extend onboarding from weeks to quarters and increase professional-services costs. Co-managed deployments can add coordination challenges because the customer and provider share responsibilities during serious incidents. These conditions can delay conversion to a subscription even when the underlying need for managed detection is clear.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Network-Centric MDR Services Market Segment Analysis
By Service Component:
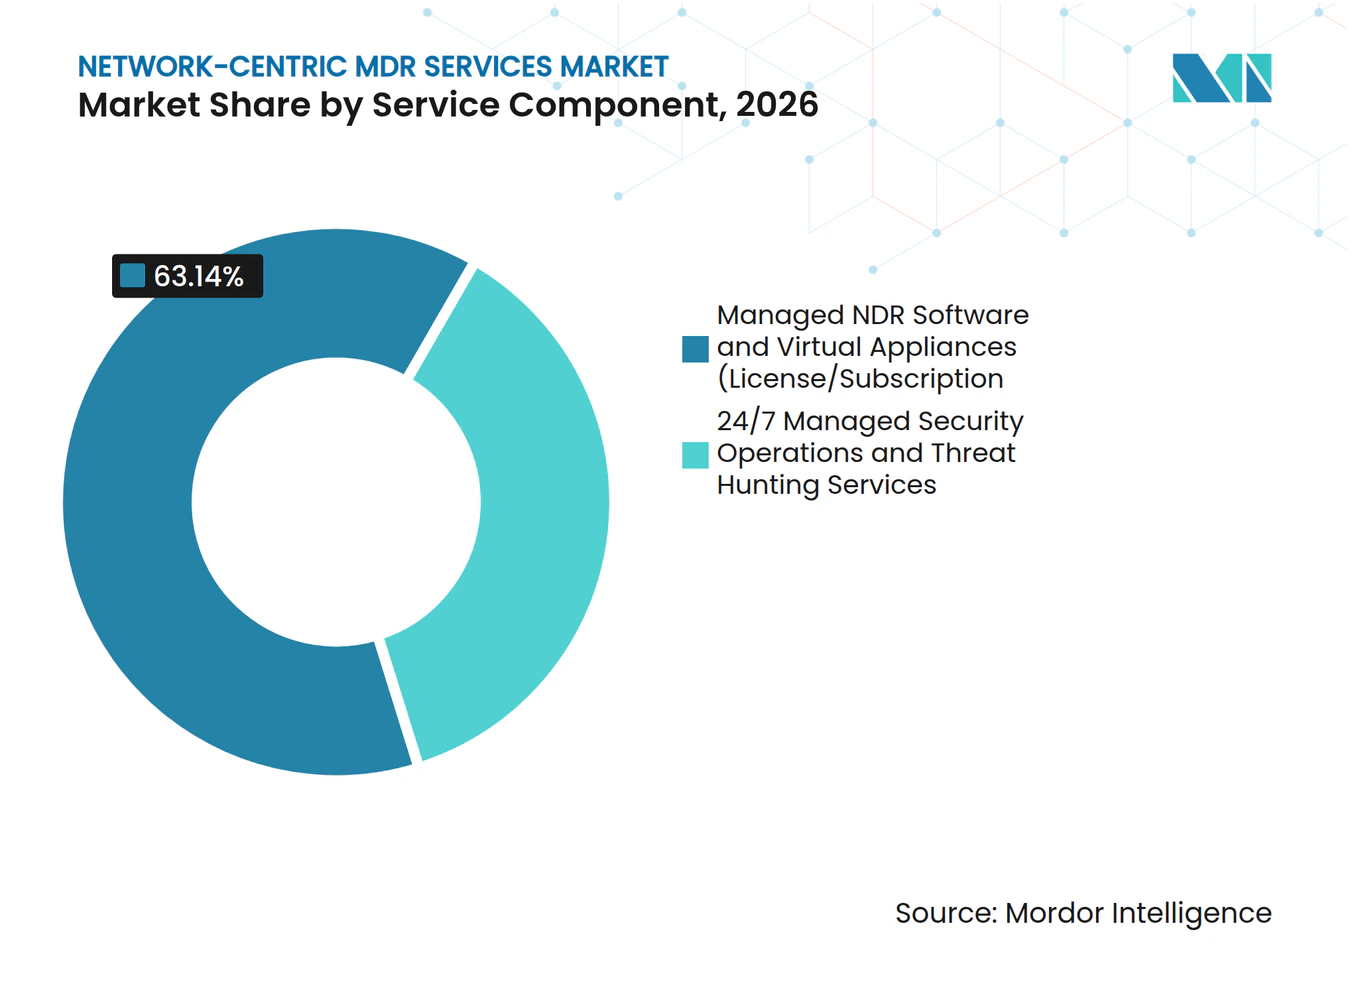
Human-Led Operations Hold the Largest Revenue Position24/7 Managed Security Operations and Threat Hunting Services held 63.14% of the Network-centric MDR services market share in 2026. The position reflects the demand for continuous operational coverage rather than a software license alone. Organizations with limited security staffing can use external teams for alert review, investigation, and incident response, which reduces the challenge of maintaining specialist coverage across every shift and incident type. ISACA found that 55% of cybersecurity teams were understaffed in 2025. This shortage supports contracts that combine monitoring with experienced analysts, while managed software and appliance buyers frequently pair the technology with a service contract to maintain continuous oversight. This arrangement allows providers to sell both the monitoring platform and the specialist operations around it, while proactive threat hunting can raise contract value because it goes beyond reviewing alerts, allowing analysts to test for suspicious activity before a confirmed incident creates a business disruption. Providers also use adversary emulation and hypothesis-led investigations to differentiate their service, especially when customers need evidence that a provider can investigate complex activity rather than only generate alerts. The Network-centric MDR services market, therefore, rewards providers that can connect technology, skilled analysts, and a clear response process. Human-led operations remain central where customers cannot justify staffing a dedicated internal team at all hours, including organizations that need reliable response coverage but have limited internal security resources.


By Service Model:
Co-Managed Delivery Expands Alongside Full OutsourcingFully Managed Network MDR held 65.47% of revenue in 2026. This model remains attractive for mid-sized organizations that lack the staff to operate network monitoring continuously. Co-Managed Network MDR is projected to expand at an 18.42% CAGR through 2032. The faster outlook reflects demand from organizations with internal teams that need added capacity and specialized expertise. Buyers can retain control of selected security decisions while using the provider for threat intelligence and operational support. The Network-centric MDR services market size for co-managed delivery benefits when mature security teams want support without a complete handoff.
The difference between the models reflects changing buyer needs rather than the replacement of one model by another, since internal capability, control preferences, and the availability of specialist staff vary considerably between organizations. Early adopters often selected fully managed services because implementation and operating responsibilities were simpler, while organizations with more developed internal programs can later shift toward co-managed operations, retaining responsibility for selected tasks while drawing on the provider for specialized investigations and continuous coverage. Providers that offer both models on a common platform can keep customers as their operating model changes. This creates an opportunity to extend existing relationships rather than lose customers to another vendor, and the model also gives providers a way to serve both understaffed buyers and organizations seeking targeted analyst augmentation, without requiring either group to adopt the same operating approach.
By Deployment Mode:
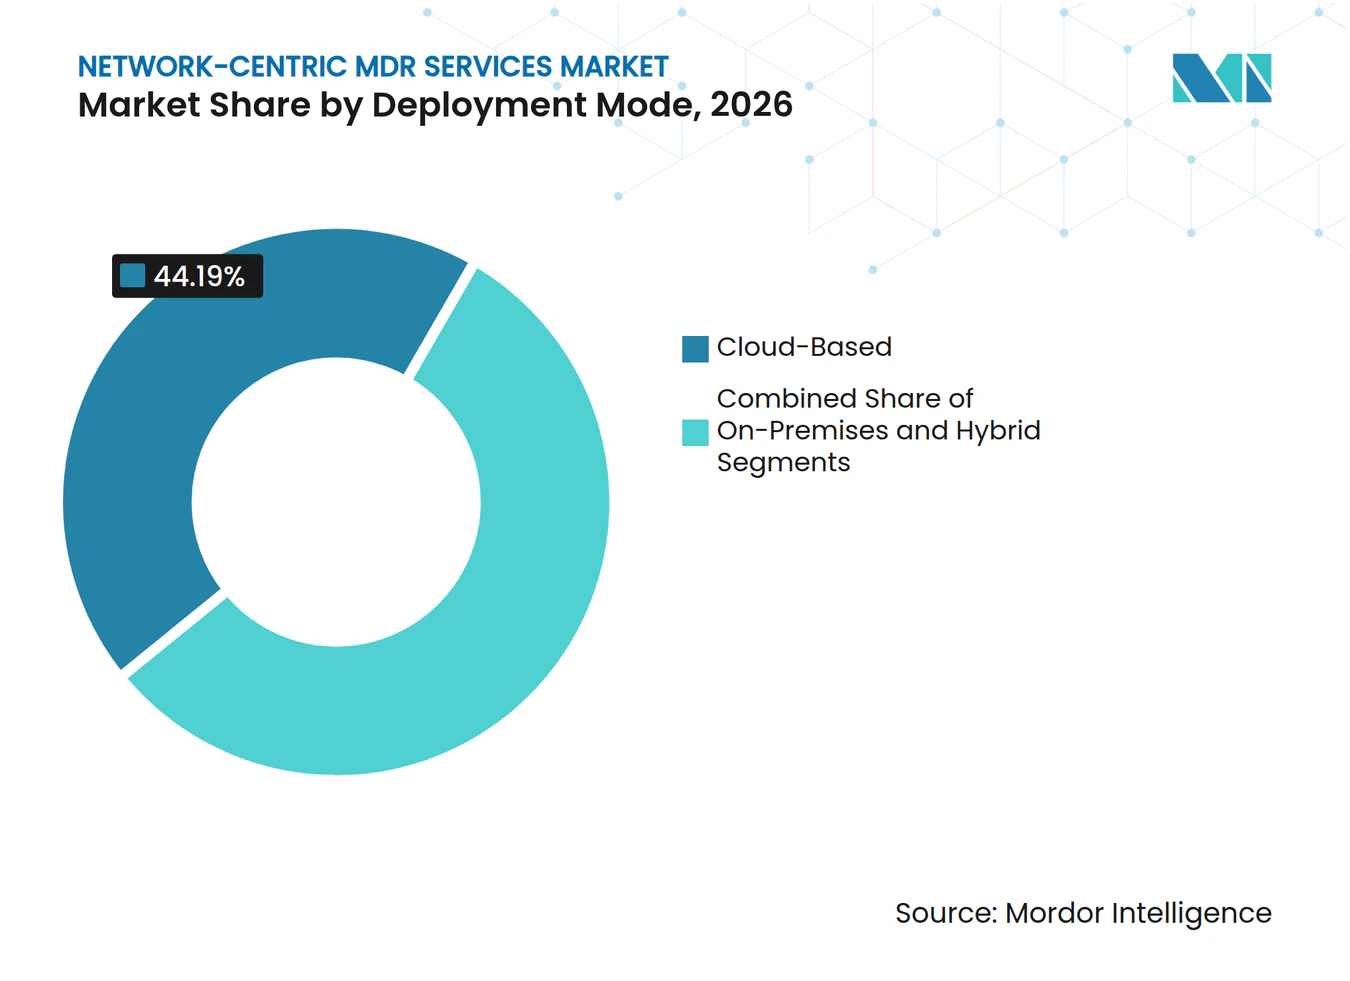
Cloud-Based Delivery Leads While Hybrid Meets Control NeedsCloud-Based deployment held 44.19% of revenue in 2026 and is projected to expand at an 18.87% CAGR through 2032. It is the common choice for new MDR programs because it can reduce initial infrastructure needs, shorten the initial implementation path, and place analytical functions in a centrally managed service environment. Cloud delivery also supports faster access to centrally managed analytics and monitoring workflows, while on-premises systems remain relevant in air-gapped defense, nuclear, and financial trading environments, where local control over sensitive systems and data remains a practical operational requirement. These environments may have latency, security, or compliance restrictions that prevent telemetry from leaving the site. Hybrid delivery uses local sensors with cloud analytics to address those requirements, giving customers a method to separate sensitive collection processes from wider analytical workflows.
Hybrid environments are important for financial services and healthcare organizations with strict data control requirements. They allow sensitive data to remain in local infrastructure while analytical processes use cloud capacity. The Network-centric MDR services market share of cloud delivery is supported by new buyers establishing formal managed detection programs. These buyers often choose cloud-native options because setup can be simpler than deploying a full on-premises platform. Providers must still offer deployment flexibility for customers whose regulated operations cannot rely on a cloud-only approach.


By Organization Size:
Small and Medium Enterprises Form a Faster-Growing Buyer GroupLarge Enterprises held 61.78% of revenue in 2026. Their scale, distributed networks, and formal security procurement processes have supported earlier adoption of managed detection services. Small and Medium Enterprises are projected to expand at an 18.23% CAGR from 2027 to 2032. Per-user pricing and managed service provider channels are making continuous monitoring more accessible to this group, particularly where security is procured alongside broader IT administration and support services. The customer base includes organizations that do not have dedicated internal security staff, and the Network-centric MDR services market is reaching these buyers through bundled IT management and security services.
The opportunity for smaller organizations is not only a matter of lower price. Delivery models can reduce the integration work and operating burden that previously made advanced network monitoring difficult to use, making the service more practical for organizations with limited technical staff and mature processes. Insurance requirements for documented security controls also encourage small and medium enterprises to formalize managed-service arrangements, because continuous monitoring can support a more consistent record of detection and response activities. Fully managed delivery can provide an entry point where the buyer has limited internal capability, while co-managed services can become relevant as the organization develops a more capable internal team, allowing the provider to supplement internal operations rather than replace them in full. Providers that make onboarding simple can strengthen their position in the Network-centric MDR services market as this buyer base expands.
By Network Architecture:
Cloud and Hybrid Networks Create the Fastest Expansion PathEnterprise LAN/WAN Networks held 51.91% of segment revenue in 2026. These networks remain the established core for internal traffic analysis across headquarters, branches, and corporate environments, where observing communications between systems can reveal activity that is not apparent from endpoint alerts alone. Cloud and Hybrid Virtual Networks are projected to expand at a 19.35% CAGR from 2027 to 2032. Multi-cloud adoption is creating traffic volumes and connections that traditional on-premises tools may not capture efficiently, particularly when workloads move between virtual environments, remote users, and separate cloud services. The Network-centric MDR services market size for cloud and hybrid networks is supported by the need to observe activity across virtual environments, while OT/ICS and IoT Networks represent a distinct strategic opportunity for the Network-centric MDR services market. Zscaler reported a 622% increase in ransomware targeting of utilities in the year to March 2026.[3] Operational environments often cannot run endpoint agents, which makes network monitoring particularly important, because the monitoring approach must avoid disrupting equipment that supports manufacturing, energy, and utility operations. Providers that can interpret Modbus, DNP3, and IEC 61850 communications can address a technical requirement that many IT-focused vendors do not cover, allowing them to monitor activity in industrial environments with specialized systems. This capability can support premium contracts in energy and manufacturing. It also helps providers distinguish their offerings in environments where visibility must operate without disrupting critical systems.
By Industry Vertical:
BFSI Anchors Revenue While Manufacturing Advances FasterBFSI held 23.11% of revenue in 2026. Financial institutions face high security requirements and must demonstrate effective risk management to regulators and business partners, which makes documented monitoring and a dependable incident process central to procurement decisions. DORA has applied to cover EU financial entities since January 2025 and has increased attention to ICT risk management and third-party oversight. Manufacturing within Other Industry Verticals is projected to expand at an 18.41% CAGR through 2032. The faster outlook is linked to the convergence of enterprise IT and factory operational technology, which adds connected systems and traffic patterns that need coordinated monitoring across production and corporate networks. Manufacturing needs visibility across connected equipment, production systems, and corporate networks. Zscaler reported a 725% increase in ransomware targeting of freight and logistics organizations in the year to March 2026. Healthcare and life sciences organizations also require continuous monitoring because ransomware outages can disrupt critical systems, including the networks and applications that support day-to-day operational continuity. Retail and e-commerce buyers focus on payment security and supply-chain risks, while energy and utility customers need visibility across distributed infrastructure and industrial environments. Energy and utilities, IT and telecommunications, and government organizations require protection for infrastructure and distributed environments.
Geography Analysis
North America Network-Centric MDR Services Market
North America held 43.93% of revenue in 2026. The Network-centric MDR services market in the region combines a large base of financial services, government, and enterprise buyers that need continuous incident response, supporting demand for providers with broad operational coverage and established response processes. The United States accounted for 50.7% of observed global ransomware activity in the referenced Zscaler dataset.[4] This threat exposure supports demand for more mature managed detection services, as organizations seek to identify and contain suspicious activity before it causes a material operational impact. Canada provides an additional financial services opportunity, while Mexico's manufacturing expansion supports demand for operational technology security, and the Network-centric MDR services market share in North America is also reinforced by the concentration of platform providers and managed security service capabilities.
Europe Network-Centric MDR Services Market
The Network-centric MDR services market in Europe has a regulatory-led demand profile, where compliance requirements have a direct influence on security budgets, supplier selection, and the need for records that demonstrate response readiness. ENISA found that 70% of surveyed organizations named NIS2, DORA, and the Cyber Resilience Act as the main driver of cybersecurity investment. By mid-2025, 14 of 27 EU member states had fully transposed NIS2 into national law. This means compliance activity will continue as implementation develops across the region, while the United Kingdom also faces security skills gaps that encourage organizations to use managed services, especially where businesses need sustained coverage but cannot recruit and retain every required specialist internally.
APAC, MEA and South America Network-Centric MDR Services Market
The Network-centric MDR services market in Asia-Pacific is projected to expand at a 19.68% CAGR from 2027 to 2032. The rate makes it the fastest-growing geography in the Network-centric MDR services market. The region is adopting cloud services quickly while many organizations face a shortage of experienced security analysts, creating a practical case for external teams that can monitor complex and distributed environments. Data-localization requirements can make provider selection more complex in China, India, and South Korea, because providers may need local data handling, infrastructure, and service arrangements for regulated buyers. Telecommunications-led service models are also relevant in markets where enterprises procure managed services through carriers, while South America, the Middle East, and Africa remain earlier-stage opportunities.
Competitive Landscape
Market Concentration
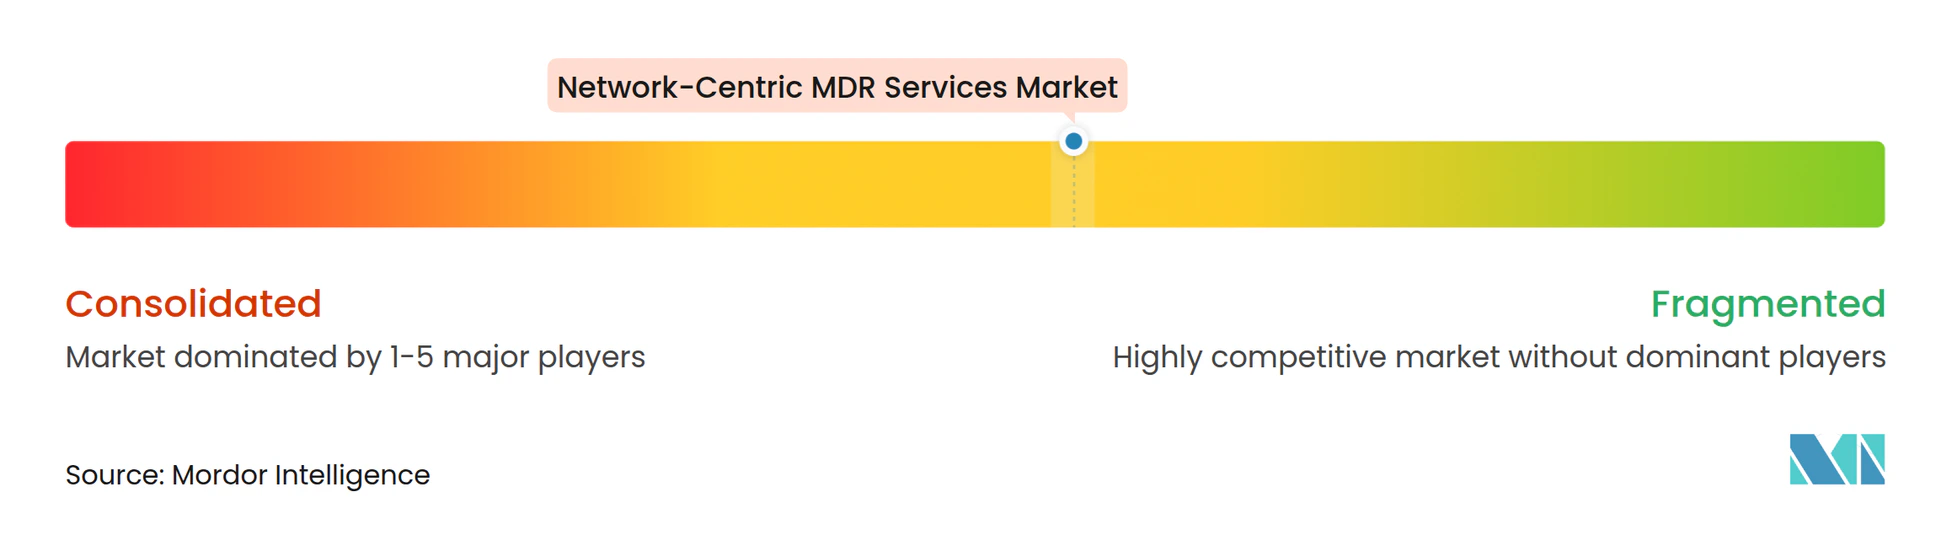
The Network-centric MDR services market remains moderately fragmented among large platform providers, while a broader group of regional and specialist vendors serves targeted needs. LevelBlue strengthened its managed detection position through the Trustwave acquisition announced in July 2025. It completed the acquisition of Cybereason in November 2025, adding XDR, digital forensics, and incident response capabilities. These moves show how large providers are adding service breadth through acquisitions, and scale matters because major buyers look for consistent coverage, response capability, and the ability to support complex environments across multiple locations, cloud services, and types of network infrastructure.
CrowdStrike launched Agentic MDR in March 2026 within Falcon Complete. The company said internal testing showed investigations up to 5x faster and more than 3x higher triage accuracy for benign classifications. SentinelOne introduced Wayfinder Threat Detection and Response with Google Cloud in November 2025. The offering combines Google Threat Intelligence with managed detection across endpoints, cloud workloads, and identities. These releases show that automation and integrated coverage are becoming central to vendor positioning, particularly as customers compare the speed of investigation, analyst efficiency, and breadth of monitored environments.
Within the Network-centric MDR services market, smaller providers can compete through regional expertise, local delivery, or knowledge of particular verticals, where an understanding of local requirements and specialized networks can remain valuable to customers. Their position becomes more difficult when larger providers extend their coverage through acquisitions and platform development. Buyers will assess the ability to monitor network traffic, cloud environments, identities, and operational technology within a coordinated service, rather than accepting disconnected tools that leave gaps between different parts of the environment. Providers also need infrastructure that supports local data handling for regulated customers. The Network-centric MDR services market rewards firms that combine technical coverage with reliable analyst-led response.
Network-Centric MDR Services Industry Leaders
-
Accenture plc
-
Arctic Wolf Networks, Inc.
-
Sophos Group plc
-
eSentire Inc.
-
SentinelOne, Inc.
- *Disclaimer: Major Players sorted in no particular order
Network-Centric MDR Services Market Companies Covered in this Report
- Accenture plc
- Arctic Wolf Networks, Inc.
- CrowdStrike Holdings, Inc.
- Sophos Group plc
- eSentire Inc.
- Rapid7, Inc.
- SentinelOne, Inc.
- Palo Alto Networks, Inc.
- Red Canary (a Zscaler Company)
- Expel, Inc.
- LevelBlue
- ReliaQuest, LLC
- Kroll, LLC
- IBM Corporation
- Google LLC (Mandiant)
- Microsoft Corporation
- Tata Consultancy Services Limited
- NTT DATA Corporation
- Orange Business
- WithSecure Corporation
Recent Industry Developments in Network-Centric MDR Services Market
- September 2026: Arctic Wolf launched Aurora MDR Connect, a new MDR tier built exclusively for MSPs, enabling partners to deliver agentic-SOC-backed managed detection and response without shipping or racking network sensors. The platform processes over 10 trillion security events and conducts over 200,000 weekly investigations, materially expanding Arctic Wolf's addressable market by lowering the deployment barrier for MSP-delivered network security.
- September 2026: KDDI America and KDDI Europe have introduced a 24/7 AI-powered Managed Detection and Response service in partnership with Exaforce to deliver enterprise-grade security and compliance across international markets. Its advanced capabilities cover endpoints, networks, SaaS, and identity access management from a single platform
- June 2026: Wipro Limited announced the expansion of its partnership with Palo Alto Networks, the global AI cybersecurity leader, to offer AI-driven Managed Detection and Response (MDR) services. The expanded relationship builds on an existing foundation with Palo Alto Networks across cloud, network, and security transformation, and reflects growing demand from clients for more integrated, AI-led security operations.
- March 2026: CrowdStrike unveiled Agentic MDR at RSA Conference 2026, integrating NVIDIA Nemotron reasoning models within Falcon Complete. Internal testing showed up to 5x faster investigations and more than 3x higher triage accuracy. Simultaneously, CrowdStrike launched SOC Transformation Services to help enterprises migrate to Falcon Next-Gen SIEM and establish agentic SOC workflows.
Global Network-Centric MDR Services Market Report Scope
Network-Centric Managed Detection and Response (MDR) Services are specialized, outsourced cybersecurity solutions where a third-party provider assumes 24/7 operational responsibility for monitoring, detecting, and mitigating advanced cyber threats explicitly within an organization's network layer.
The Network-Centric MDR Services Market Report is Segmented by Service Component (Managed NDR Software and Virtual Appliances [License/Subscription] and 24/7 Managed Security Operations and Threat Hunting Services), Service Model (Fully Managed Network MDR and Co-Managed Network MDR), Deployment Mode (Cloud-Based, On-Premises, and Hybrid), Organization Size (Large Enterprises and Small and Medium Enterprises), Network Architecture (Enterprise LAN / WAN Networks, Cloud and Hybrid Virtual Networks, and OT / ICS and IoT Networks), Industry Vertical (Banking, Financial Services and Insurance, Healthcare and Life Sciences, Government and Public Sector, IT and Telecommunications, Energy and Utilities, Manufacturing, and Other Industry Verticals), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Managed NDR Software and Virtual Appliances (License/Subscription) |
| 24/7 Managed Security Operations and Threat Hunting Services |
| Fully Managed Network MDR |
| Co-Managed Network MDR |
| Cloud-Based |
| On-Premises |
| Hybrid |
| Large Enterprises |
| Small and Medium Enterprises |
| Enterprise LAN / WAN Networks |
| Cloud and Hybrid Virtual Networks |
| OT / ICS and IoT Networks |
| Banking, Financial Services and Insurance |
| Healthcare and Life Sciences |
| Government and Public Sector |
| IT and Telecommunications |
| Energy and Utilities |
| Manufacturing |
| Other Industry Verticals |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| France | |
| Italy | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Rest of Africa |
| By Service Component | Managed NDR Software and Virtual Appliances (License/Subscription) | |
| 24/7 Managed Security Operations and Threat Hunting Services | ||
| By Service Model | Fully Managed Network MDR | |
| Co-Managed Network MDR | ||
| By Deployment Mode | Cloud-Based | |
| On-Premises | ||
| Hybrid | ||
| By Organization Size | Large Enterprises | |
| Small and Medium Enterprises | ||
| By Network Architecture | Enterprise LAN / WAN Networks | |
| Cloud and Hybrid Virtual Networks | ||
| OT / ICS and IoT Networks | ||
| By Industry Vertical | Banking, Financial Services and Insurance | |
| Healthcare and Life Sciences | ||
| Government and Public Sector | ||
| IT and Telecommunications | ||
| Energy and Utilities | ||
| Manufacturing | ||
| Other Industry Verticals | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| France | ||
| Italy | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the Network-centric MDR services market size?
The Network-centric MDR services market size is projected to be USD 2.10 billion in 2027 and USD 4.55 billion by 2032, at a 16.72% CAGR from 2027 to 2032. The forecast reflects the growing need for continuous detection, investigation, threat hunting, and response services that extend across enterprise network environments.
What is driving adoption of Network-centric MDR services?
Security staffing shortages, ransomware activity, regulatory requirements, and wider cloud, IoT, and operational technology exposure are increasing demand for continuous monitoring. Network visibility is valuable where endpoint coverage cannot observe every connected or industrial system. It can help security teams examine communications between systems and identify potentially suspicious movement that would otherwise remain outside endpoint telemetry.
Which service component has the largest revenue position?
24/7 Managed Security Operations and Threat Hunting Services held 63.14% of revenue in 2026. The segment combines alert review, investigation, threat hunting, and continuous operational coverage for complex security environments and operating conditions. This structure is relevant for organizations that need a defined response process but cannot maintain a full internal team with the required specialist capabilities.
Which Network-centric MDR deployment model is expanding fastest?
Cloud-Based deployment is projected to expand at an 18.87% CAGR through 2032. It is commonly selected for new programs because it can reduce initial infrastructure requirements. The approach also allows providers to manage analytical workflows centrally while offering customers a faster route to ongoing network monitoring, while hybrid and on-premises options remain necessary for air-gapped or tightly regulated systems that require different data-handling controls.
Which buyer group has the strongest expansion outlook?
Small and Medium Enterprises are projected to expand at an 18.23% CAGR from 2027 to 2032 as managed service models reduce operating and onboarding barriers. Provider channels can bundle network monitoring with wider IT support for these organizations. This lowers the operating burden for buyers that need security capability without separate teams to manage extensive monitoring tools, alert queues, and incident investigations.
Which region is expected to expand fastest?
The Network-centric MDR services market in Asia-Pacific is projected to expand at a 19.68% CAGR from 2027 to 2032, supported by cloud adoption and demand for managed security skills. Data localization requirements make local service capability important for regulated organizations. Providers need to demonstrate that they can meet local data handling expectations while still maintaining a dependable service model for monitoring, investigation, and response across cloud, on-premises, hybrid, and distributed customer environments.