
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 7.24 Billion |
| Market Size (2026) | USD 9.91 Billion |
| Market Size (2031) | USD 47.28 Billion |
| Growth Rate (2026 - 2031) | 36.72 % |
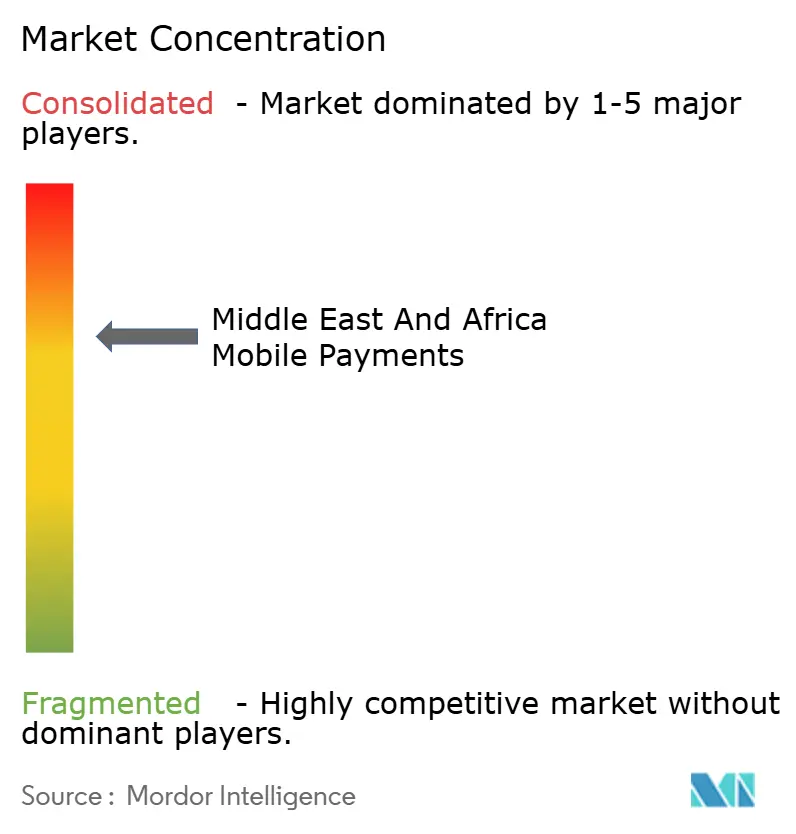
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Middle East And Africa Mobile Payments Market Analysis by Mordor Intelligence
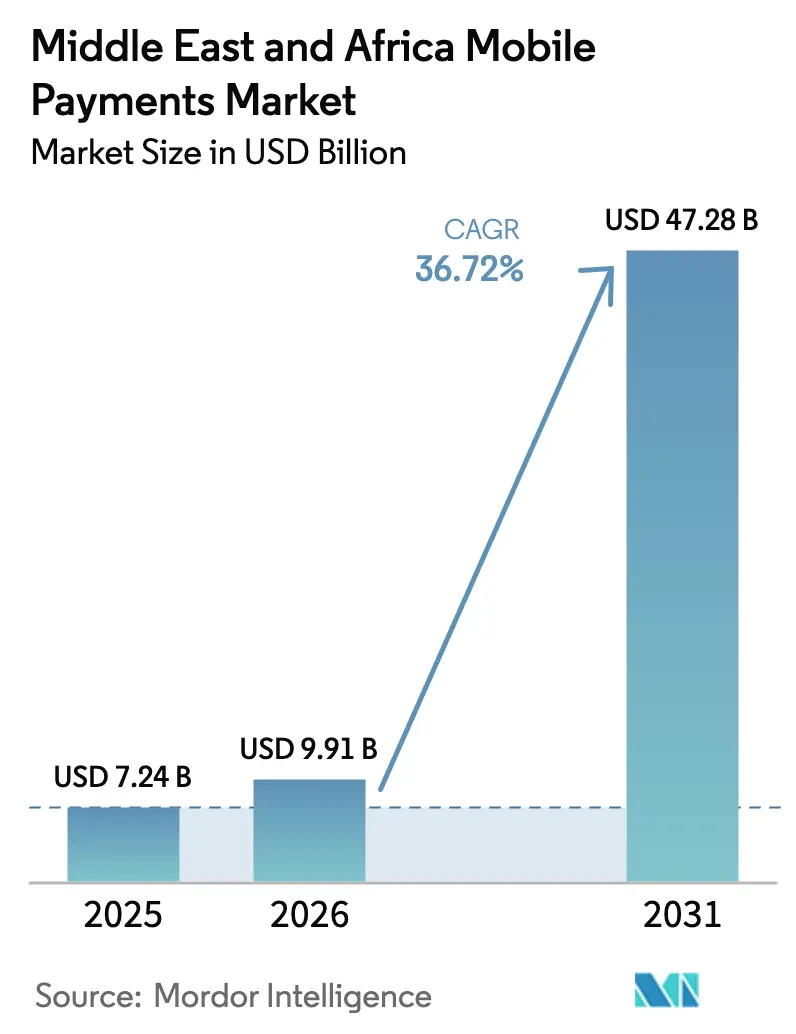
The Middle East And Africa Mobile Payments Market size was valued at USD 7.24 billion in 2025 and estimated to grow from USD 9.91 billion in 2026 to reach USD 47.28 billion by 2031, at a CAGR of 36.72% during the forecast period (2026-2031).
Explosive growth is rooted in three structural shifts: deeper smartphone penetration, widespread 4G/5G coverage and the convergence of telco wallets with bank-grade rails.[1]Rishi Raithatha, “The State of the Industry Report on Mobile Money 2025,” GSMA, gsma.com Government cash-to-digital agendas, real-time payment rails and cross-border corridors are compressing adoption cycles, while super-app ecosystems reshape customer acquisition economics. Merchant acceptance costs continue to fall as SoftPOS-enabled smartphones replace traditional terminals, enabling micro-merchants to join the formal digital economy. Intense competition among telcos, banks and fintechs is translating into product innovation around Buy Now Pay Later (BNPL), QR codes and wage-linked wallets, creating sticky user engagement and larger addressable volumes for the Middle East and Africa mobile payments market.
Key Report Takeaways
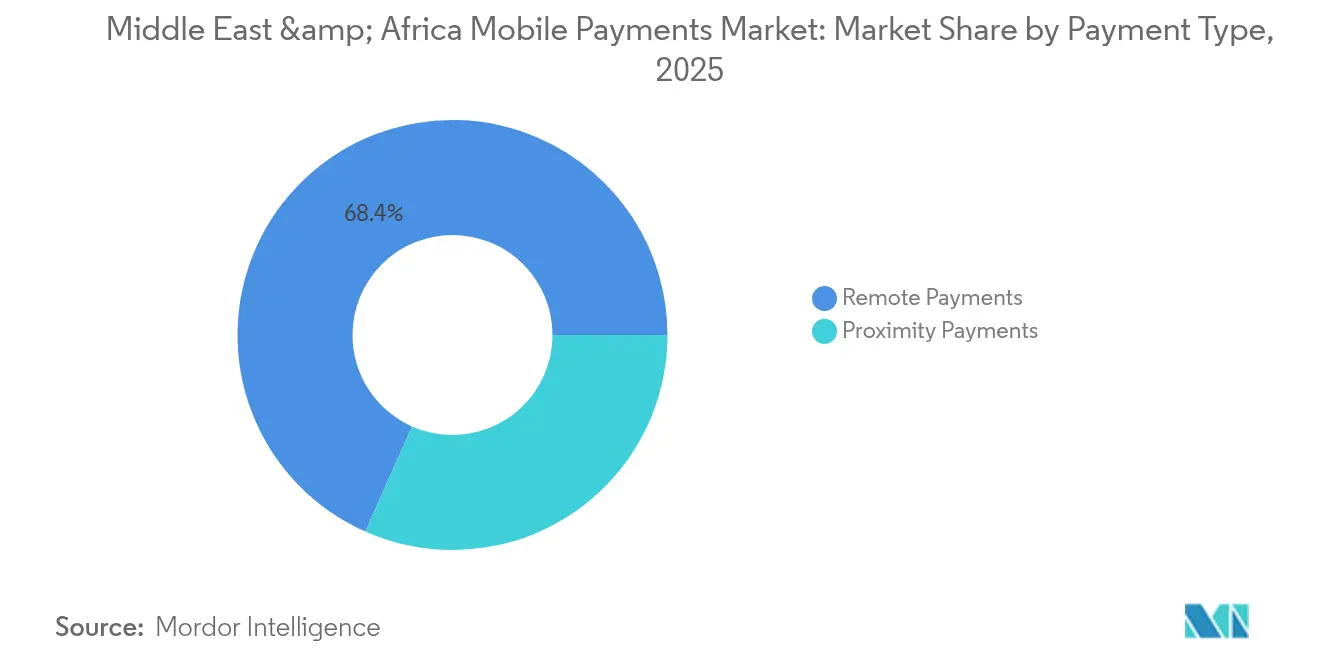
- By payment type: Remote payments held 68.35% of the Middle East and Africa mobile payments market share in 2025, while proximity payments are projected to expand at a 30.05% CAGR through 2031.
- By transaction type: In-store POS led with 40.55% revenue share in 2025; P2P transactions are growing fastest at a 32.1% CAGR to 2031.
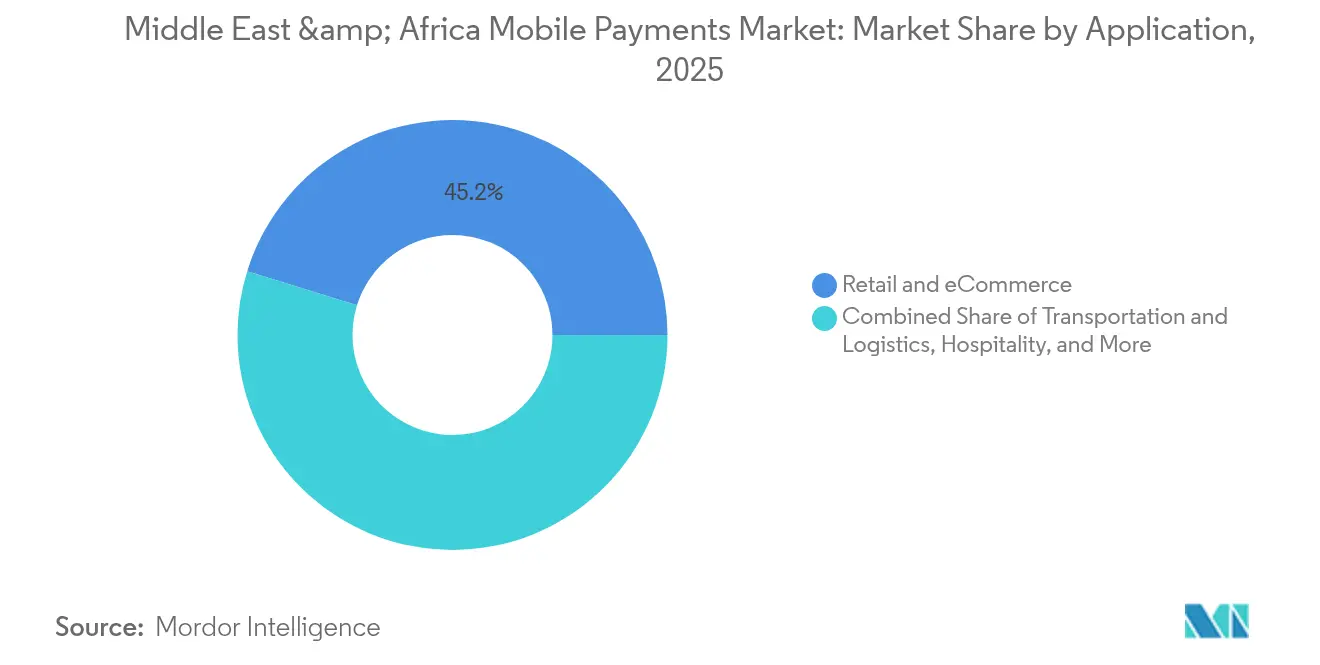
- By application: Retail & e-commerce dominated with 45.20% share in 2025; the government & public sector segment is forecast to rise at a 40.35% CAGR through 2031.
- By end-user: Personal transactions accounted for 77.30% of the Middle East and Africa mobile payments market size in 2025, while business transactions are advancing at a 28.4% CAGR to 2031.
- By geography: Africa captured 56.65% of the Middle East and Africa mobile payments market share in 2025; the Middle East region is projected to deliver the fastest growth with a 39.9% CAGR from 2026-2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Middle East And Africa Mobile Payments Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| GCC Wage-Protection-System (WPS) Mandates Accelerating Cash-to-Digital Migration | +7.8% | GCC countries (UAE, Saudi Arabia, Qatar, Kuwait, Oman, Bahrain) | Medium term (2-4 years) |
| BNPL-Enabled Wallet Loyalty Programs Boosting Transaction Frequency in UAE & KSA | +5.2% | UAE, Saudi Arabia, with spillover to other GCC states | Short term (≤ 2 years) |
| Telco-Super-App Race Unlocking Rural USSD Adoption in Sub-Saharan Africa | +9.5% | Nigeria, Kenya, South Africa, Ghana, with expansion to other Sub-Saharan countries | Medium term (2-4 years) |
| SoftPOS Roll-outs Among Micro-Merchants (Visa Tap-to-Phone Pilots) | +6.3% | South Africa, Egypt, UAE, Saudi Arabia, with expansion to other urban centers | Short term (≤ 2 years) |
| Wallet-to-Wallet GCC–Africa Remittance Corridors Cutting Transfer Fees | +4.1% | UAE-Nigeria, Saudi Arabia-Egypt, Qatar-Kenya corridors | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
GCC Wage-Protection-System (WPS) Mandates Accelerating Cash-to-Digital Migration
WPS compliance reached 99.8% in the UAE and 92% in Saudi Arabia in 2024, onboarding 5.8 million formerly cash-paid workers into digital channels.[2]White & Case LLP, “Unlocking Potential: GCC FinTech Trends, Regulations and Funding Outlook,” White & Case, whitecase.com Mandatory wage digitisation funnels recurring salary inflows into mobile wallets, boosting average non-salary transaction frequency by 3.2 times for providers such as STC Pay. The programme is expanding across Bahrain, Qatar and Oman, standardising payroll rails and lowering customer-acquisition costs. Banks benefit from float balances while telco wallets monetise fees on remittances and bill-pay. The initiative embeds financial inclusion at scale, cementing long-term volume upside for the Middle East and Africa mobile payments market.
BNPL-Enabled Wallet Loyalty Programs Boosting Transaction Frequency in UAE & KSA
Tabby’s integration with STC Pay lifted wallet transaction frequency by 42% in 2024, underscoring BNPL’s ability to extend consumer credit within existing digital wallets.[3]Visa Inc., “Visa Tap to Phone Adoption Soars: 200% Year over Year Growth Worldwide,” Visa Newsroom, visa.com BNPL adoption has reached 39% in the UAE and 42% in Saudi Arabia, driving USD 10 billion in annual wallet volumes and generating 2.7-times higher average ticket sizes versus traditional cards. Merchants gain higher conversion rates, consumers obtain deferred payments, and wallet operators capture interchange and late-fee income. Rapid scaling of BNPL-wallet hybrids is likely to deepen user stickiness and sharpen competitive differentiation in the Middle East and Africa mobile payments market.
Telco Super-App Race Unlocking Rural USSD Adoption in Sub-Saharan Africa
Orange’s Max it targets 45 million active users by 2025, leveraging USSD to reach low-end feature phones.[4]Jie Wang, “EM 2.0: A Road for the Digital Intelligent Transformation of African Carriers,” Huawei, huawei.com Telebirr in Ethiopia already services 40 million users, processing USD 3 billion in monthly transactions—roughly 30% of national GDP. Super-app positioning lets telcos bundle payments, micro-credit and insurance, extracting multi-line revenue while lowering churn. USSD resilience in low-bandwidth regions broadens addressable volumes and entrenches telcos as dominant players across the Middle East and Africa mobile payments market.
SoftPOS Roll-outs Among Micro-Merchants (Visa Tap-to-Phone Pilots)
Visa’s Tap-to-Phone recorded 200% year-over-year global growth in 2025, with strong momentum in South Africa, Egypt, UAE and Saudi Arabia. Converting Android phones into acceptance devices slashes hardware costs and formalises previously cash-only merchants—30% of new users were entirely new to digital payments. The technology supports contactless consumer preferences (61% of shoppers now prefer tap-and-go), enhances data capture for loyalty programmes and accelerates merchant onboarding. Widescale SoftPOS uptake is expected to rebalance transaction mix toward proximity payments and expand addressable GDP for the Middle East and Africa mobile payments market.
Restraints Impact Analysis of Middle East And Africa Mobile Payments Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fragmented Licensing Across 45+ African Regulators Delays Market Entry | -4.3% | Pan-African, with particular impact on cross-border payment initiatives | Long term (≥ 4 years) |
| Mobile-Money Transaction Caps in Nigeria & Egypt Reduce Ticket Size | -3.1% | Nigeria, Egypt, with spillover effects to neighboring countries | Medium term (2-4 years) |
| High USSD Fraud Rates Trigger Bank-Imposed PIN-Retry Limits | -2.7% | Sub-Saharan Africa, particularly Uganda, Zambia, and Kenya | Short term (≤ 2 years) |
| PAPSS Funding Gaps Slow Real-time Rail Deployment in Francophone Africa | -2.1% | West and Central African Economic and Monetary Union (WAEMU) countries | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Fragmented Licensing Across 45+ African Regulators Delays Market Entry
Payment providers allocate 18-24% of their operating budgets to compliance as they navigate divergent licence classes and fee structures. Approval timelines range from three months to over one year, dampening time-to-market for cross-border propositions. Activity-based licensing models in Kenya and Ghana offer promising templates, but broad harmonisation remains a long-term agenda. The resulting friction restricts capital inflows, stifles innovation and clips growth for the Middle East and Africa mobile payments market.
Mobile-Money Transaction Caps in Nigeria & Egypt Reduce Ticket Size
Tiered KYC ceilings in Nigeria cap daily wallet transfers at NGN 5 million (USD 3,275), while Egypt enforces similar ceilings to curb money-laundering risk. Consequently, average mobile-money ticket sizes remain 62% lower than bank transfers, forcing providers to prioritise frequency over value. Although regulators aim to safeguard stability, the caps limit use cases such as B2B settlements and large remittances, tempering overall wallet revenue in the Middle East and Africa mobile payments market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Middle East And Africa Mobile Payments Market Segment Analysis
By Payment Type:
Proximity Surge Reshapes Transaction LandscapeRemote payments accounted for 68.35% of the Middle East and Africa mobile payments market in 2025, driven by bill-pay and e-commerce transfers. Visa’s Tap-to-Phone and widespread NFC handsets are now nudging proximity adoption upward with a projected 30.05% CAGR, especially in GCC urban centres where contactless initiatives led to a 47% uptick in 2024. Retailers gain higher throughput at checkout, while consumers benefit from tap-and-go convenience. Transaction data mined from proximity events enables hyper-local offers, boosting merchant sales and deepening ecosystem engagement.
The rapid diffusion of SoftPOS among micro-merchants lowers acceptance costs and targets previously cash-only outlets, expanding addressable volumes for the Middle East and Africa mobile payments market. Proximity payments also facilitate offline authentication, a vital feature in intermittent-connectivity environments. As infrastructure scales, the proximity share is expected to close the gap with remote transactions, shifting provider focus toward in-store experiences and embedded commerce offerings.


By Transaction Type:
P2P Growth Drives Financial InclusionPOS transactions led with a 40.55% share in 2025, reflecting high smartphone penetration and merchant digitisation across GCC states. P2P transfers, however, are projected to outpace other flows at a 32.1% CAGR, buoyed by remittance needs and limited branch networks. First-time mobile money users in Africa initiate 78% of their journeys through P2P, making it a critical acquisition funnel for the Middle East and Africa mobile payments market size.
International mobile-money remittances reached USD 34 billion in 2024. Providers are layering value-added services such as savings pots, micro-loans and insurance to monetise rising wallet balances. As regulators progress toward real-time-gross settlement interoperability, P2P corridors will deepen liquidity and reinforce the ecosystem’s role in economic integration.
By Application:
Government Sector Emerges as Growth EngineRetail & e-commerce captured 45.20% of the Middle East and Africa mobile payments market in 2025, fuelled by mobile-first checkout journeys and QR-enabled pop-up stores. Seamless purchasing improves conversion rates and basket sizes, compelling merchants to integrate multiple wallet options.
Public-sector adoption is accelerating at a 40.35% CAGR as digital identities and e-government portals gain traction under Saudi Vision 2030 and UAE Digital Government Strategy 2025. Digital disbursement of subsidies, fines and licence fees anchors volumes, lowers cash-handling costs and enhances transparency. Large-scale use cases catalyse ecosystem effects, bringing under-banked citizens into repeated digital interactions and expanding the Middle East and Africa mobile payments market.
By End-user:
Business Segment Accelerates Digital TransformationPersonal wallets held a commanding 77.30% share in 2025, underscoring the pivotal role of mobile money in everyday financial lives. This dominance stems from salary deposits, bill payments and small-value retail transactions that together form the backbone of the Middle East and Africa mobile payments market share.
Business usage is forecast to expand at a 28.4% CAGR as enterprises digitise supplier settlements, payroll and B2B marketplaces. In Uganda, mobile-money transaction value exceeded UGX 100 trillion (USD 26 billion) in 2023. Digital workflows streamline reconciliation and improve liquidity, while higher transaction limits and API connectivity unlock embedded-finance propositions tailored for SMEs.
Geography Analysis
Africa Mobile Payments Market
Africa held 56.65% of the Middle East and Africa mobile payments market in 2025, anchored by Kenya’s mobile-money transactions that equalled 59% of national GDP. Sub-Saharan smartphone adoption is expected to reach 44% by 2025, expanding the addressable base for USSD and app-based wallets. Despite chronic infrastructure gaps, telco innovation around offline authentication mitigates session failures caused by rural latency of 250 ms, which drives an 18% USSD drop-off rate.
GCC Mobile Payments Market
The Middle East is on a faster growth curve with a projected 39.9% CAGR through 2031. Saudi Arabia’s target of 70% cashless transactions by 2025 and the UAE’s cash share already down to 17% of POS in 2023 illustrate the policy-led pivot toward digital money. Real-time payment systems processed USD 230 billion in 2023 and are forecast to surpass USD 903 billion by 2028 across the six GCC states.
MEA Mobile Payments Market
Cross-regional wallet-to-wallet remittance corridors connect GCC migrant wage earners with African recipients, trimming fees and accelerating settlement. The Pan-African Payment and Settlement System is a potential game-changer, though funding gaps are delaying its rollout in Francophone blocs. These converging factors suggest a complementary rather than competitive dynamic, with Africa’s user scale and the Middle East’s infrastructure sophistication jointly propelling the Middle East and Africa mobile payments market.
Regulatory Landscape
Regulation across the Middle East and Africa mobile payments market is tightening around licensing requirements, operational resilience, and consumer protection as wallet and mobile-money volumes grow. In Saudi Arabia, the Saudi Central Bank (SAMA) refreshed its Oversight Framework for Payment Systems and their Operators in March 2026 to align supervision with the Law of Payments and Payment Services (Royal Decree M/26), building on earlier requirements such as SAMA Rules for Electronic Wallets published in October 2024, including customer classification and transaction-limit controls. In Egypt, the Central Bank of Egypt (CBE) issued licensing regulations for Payment System Operators (PSOs) and Payment Service Providers (PSPs) under Banking Law No. 194 of 2020, with a transition period running through June 2026.
Policy direction is also pushing infrastructure modernization that affects merchant acceptance and wallet interoperability. CBE actions in February 2026 to enable contactless acceptance through smart devices (SoftPOS) reduce reliance on traditional terminals and lower barriers for micro-merchant onboarding. Across the GCC, national strategies and oversight frameworks emphasize interoperability, including domestic schemes such as MADA in Saudi Arabia, and sandbox or lab approaches linked to open banking to support embedded finance. In Africa, licensing fragmentation and transaction caps in large markets such as Nigeria and Egypt continue to slow entry.
Value Chain Analysis
The value chain for mobile payments in the Middle East and Africa spans (i) access and devices (smartphones and feature phones using apps and USSD), (ii) acceptance enablement (QR/NFC, SoftPOS, smart POS), (iii) wallet issuers and distribution (telco wallets, bank wallets, and fintech wallets supported by agent networks and cash-in/cash-out partners), (iv) processing and settlement rails (domestic switches, instant-payment systems, and cross-border connectors), and (v) risk, compliance, and value-added services (KYC/AML, fraud tooling, lending/BNPL, and merchant services). Central banks and domestic payment schemes anchor the chain through licensing and technical standards, while international networks and processors support card-linked tokenization, online acceptance, and broader merchant reach.
Two operational nodes are shaping economics more clearly: merchant acquisition and embedded finance within commerce flows. SoftPOS initiatives, including the CBE-backed contactless acceptance via smart devices (February 2026), reduce hardware and deployment costs for micro-merchants, tightening the acceptance layer. B2B commerce and logistics platforms are also becoming distribution channels for payment and credit: OmniRetail raised USD 20 million (April 2025) to expand B2B commerce and embedded finance across West Africa, MaxAB-Wasoko acquired Egypt-based Fatura (May 2025) to integrate embedded financial services into retail supply-chain networks, and Jumia opened a 27,000 sqm integrated logistics center in Cairo (July 2025), supporting fulfillment where checkout and wallet payments concentrate. Cross-border infrastructure experimentation feeds into the settlement layer as well, including a 12-month e-Franc pilot announced by the National Bank of Rwanda (February 2026) and SAMA updates to oversight of payment systems (March 2026).
Competitive Landscape
The competitive structure is bifurcated: telco-backed platforms command over 60% of active mobile-money accounts in Africa, while Middle Eastern markets showcase a mix of bank wallets and independent fintechs. East Africa is highly concentrated around M-Pesa, whereas Nigeria, Egypt and the UAE exhibit more fragmented shares. Global card networks are partnering instead of competing head-on—Mastercard’s alliance with Orange Money opens digital acceptance across seven African countries.
Strategic thrusts focus on ecosystem breadth. Super-app ambitions from Orange, MTN and STC co-locate payments with ride-hailing, micro-loans and insurance, creating multi-line monetisation. SoftPOS and biometric authentication differentiate challengers targeting micro-merchant acquisition in urban corridors. Cross-border remittance corridors, merchant aggregation in underserved segments and vertical-specific solutions such as healthcare payments represent whitespace opportunities that could reshape competitive standings within the Middle East and Africa mobile payments industry.
Incumbents are responding with accelerated M&A and minority stake investments. Recent funding rounds and partnerships—such as PayPal with TerraPay and Visa with Emirates NBD—signal a pivot toward embedded cross-border capabilities and tailored SME propositions. As regulatory sandboxes open and open-banking APIs mature, data analytics and AI-driven fraud modules will become decisive assets in earning consumer trust and scaling volumes across the Middle East and Africa mobile payments market.
Middle East And Africa Mobile Payments Industry Leaders
Orange S.A. (Orange Money)
Fawry (MyFawry)
Careem (CareemPay)
Vodafone Group
HyperPay Inc.
- *Disclaimer: Major Players sorted in no particular order
Middle East And Africa Mobile Payments Market Companies Covered in this Report
- STC Pay (Saudi Digital Payments Co.)
- MTN Group – MoMo
- Vodafone Group
- Orange S.A. (Orange Money)
- Fawry (MyFawry)
- Careem (CareemPay)
- HyperPay Inc.
- PalmPay Ltd.
- OPay Digital Services Ltd.
- Flutterwave Inc.
- Paystack Payments Ltd.
- Paymob Solutions
- BayanPay
- SADAD Payment System
- Payit Digital Wallet (ADCB)
- eand money (Etisalat)
- Zain Cash
- Beam Wallet
- Klip Digital Wallet
- Wave Mobile Money
Read Analysis of Middle East And Africa Mobile Payments Companies

Market Opportunities and Future Outlook
Cross-border rails and interoperability remain the clearest whitespace, supported by public initiatives and live pilots that connect wallets to new settlement options. The AfCFTA Secretariat launched the Africa Digital Access and Public Infrastructure for Trade (ADAPT) initiative in May 2026, selecting Kenya, Morocco, and Nigeria as pilot countries to test interoperable digital identity, payments, and trade-data systems, which aligns with the report scope around wallet-to-wallet corridors and real-time settlement. At the commercial layer, cross-border capabilities are also being activated through infrastructure networks: Emirates NBD enabled real-time blockchain-based cross-border payments on the Partior network in July 2026, and Visa, M-PESA Africa, and Onafriq launched a stablecoin-settled cross-border mobile money pilot in the Democratic Republic of the Congo in July 2026. These steps show active experimentation with alternative settlement models that can reduce friction across GCC-Africa and intra-Africa corridors.
Merchant acceptance expansion is another opportunity area, anchored in regulator-backed enablement and product moves that lower onboarding costs and widen proximity use cases. The Central Bank of Egypts February 2026 SoftPOS contactless acceptance initiative supports smartphone-based acceptance, while M-Pesa Africa and Vodacom Tanzania launched a mobile-money tap-to-pay feature in March 2026 using tokenized virtual cards via the M-Pesa SuperApp, expanding acceptance formats beyond QR and USSD. On the demand side, wage digitisation programs and government digital payment agendas already channel recurring inflows into wallets, including high WPS compliance in the UAE and Saudi Arabia by 2024 in the report context. That creates room for providers to layer value-added services such as BNPL, merchant financing, and payroll-linked products within regulated frameworks and transaction-limit constraints.
Recent Industry Developments in Middle East And Africa Mobile Payments Market
- June 2026: BNB Liberia and Orange Money launched a cross-border mobile remittance service, enabling transfers from Liberia to eight African countries. The expansion strengthens Orange Moneys corridor footprint and pushes wallet-to-wallet remittances further into regulated, app-led channels across West and East Africa.
- May 2026: Fawry partnered with valU to add flexible payment and financing options inside the myFawry app. The integration deepens consumer credit and installment use cases within an existing wallet ecosystem, supporting higher-frequency and higher-ticket digital checkout flows in Egypt.
- December 2025: Orange Money Group and Visa announced a strategic partnership to accelerate online payments, including the deployment of virtual Visa cards across Africa and the Middle East. The move links mobile wallets more directly to card-network acceptance for e-commerce, improving usability beyond closed-loop wallet ecosystems.


Middle East And Africa Mobile Payments Market Report Scope and Research Methodology
Market Definition and Coverage
This market covers the value of payments initiated on a mobile handset across the Middle East and Africa, including wallet-based and mobile money transactions used for in-store and remote purchases.
Scope exclusions: Prepaid card loads, card-present POS swipes that do not involve a handset, and desktop-only bank transfers are excluded from this market sizing.
Segments Covered in This Report
- By Payment Type
- Proximity Payments
- Remote Payments
- By Transaction Type
- Peer-to-Peer (P2P)
- In-store Point-of-Sale (POS)
- Person-to-Merchant (P2M/Checkout)
- Other Transaction Types
- By Application
- Retail and eCommerce
- Transportation and Logistics
- Hospitality and Food-Service
- Government and Public Sector
- Other Applications (Education, Healthcare)
- By End-user
- Personal
- Business
- Geography
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Kuwait
- Turkey
- Oman
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Morocco
- Rest of Africa
- Middle East
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to map the ecosystem and lock the basic math of how mobile payments move through the region. We relied on public, non-paywalled sources such as central bank payment system reports, telecom regulator releases, government statistics portals, and the World Bank Global Findex and IMF macro series to anchor population, account ownership, and spending capacity assumptions. To understand mobile money and wallet adoption patterns, we also referenced sources such as GSMA mobile money publications, along with country-level press releases from payment network operators and merchant associations.
On the supply and operating side, company annual reports, investor presentations, and audited filings helped validate business model splits and key revenue lines tied to transaction services. We also used paid database subscriptions for company financials and news screening, and for patent database checks where product roadmaps needed clarification. The sources listed above are illustrative only, and many other public documents and datasets were reviewed to collect data, validate assumptions, and resolve open questions.
Primary Interviews and Surveys
Primary interviews and short surveys focused on payment platform teams, mobile money operators, merchant aggregators, banks, and large merchants that support mobile-led checkout. Because MEA is not a single-homogeneous market, we tested adoption and pricing assumptions across the Gulf, North Africa, and Sub-Saharan Africa, then rechecked outliers where digital wallet usage or mobile money volumes were unusually high or low.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 33% | CXOs: 14% |
| Mid tier: 52% | Functional/Unit leaders: 35% |
| Smaller Players: 15% | Managers: 51% |
Market-Sizing & Forecasting
The market was estimated using a mix of top-down and bottom-up checks. On the top-down side, mobile payment value was reconstructed from the demand pool by linking active mobile wallet or mobile money users to average transaction frequency and typical ticket sizes, which are then adjusted by the share of retail and service payments that shift from cash to mobile in each sub-region. To keep the totals realistic, we corroborated them with selective bottom-up approximations using sampled provider metrics, channel checks with merchant aggregators, and ASP-like take rate ranges where monetization signals were available.
A few inputs that shape this model are smartphone and mobile internet penetration, registered and active mobile money account trends, merchant acceptance density (QR and NFC readiness), cross-border remittance corridors that spill over into wallet balances, and inflation plus FX movement that affects USD reporting. Where bottom-up inputs were missing for smaller markets, gaps were handled by scaling from comparable countries using population, urbanization, and financial inclusion indicators, followed by a reasonableness check against reported payment volumes. Forecasts were built using scenario analysis, where adoption and usage paths were stress-tested with interview feedback on regulation, pricing pressure, and wallet interoperability timelines.
Data Validation & Update Cycle
Validation was done by triangulating the model output with independent signals, such as published mobile money transaction growth, reported digital payment volumes, and macro consumption proxies that set an upper bound on addressable spend. Variance checks were run across countries and sub-regions so that unusually high per-user spend or sudden jumps in adoption were flagged and reviewed again. Before sign-off, the model and assumptions go through multi-step analyst review, and follow-up outreach is triggered when a key metric conflicts with multiple sources.
Reports are refreshed annually, and interim updates are made when major regulatory changes, large pricing resets, or step-changes in wallet adoption are observed. Right before delivery, we perform a final pass to ensure the market size and narrative reflect the latest available disclosures and public indicators.
Mordor Intelligence's Middle East and Africa Mobile Payments Market Size Measured Against Other Published Estimates
Published market values for MEA mobile payments can look far apart because the underlying counting rules are not always the same, even when the titles sound similar. Differences usually come from what is included in the payment value, the year used as the starting point, and how quickly adoption and usage are assumed to scale.
Card-present POS payments that are completed without a handset sit outside Mordor Intelligence's scope, and this single exclusion often explains why some published figures appear much larger when they treat all digital card spending as mobile-led. Gaps also show up when one estimate counts wallet top-ups as payment value, applies aggressive FX conversion timing, or projects ticket size growth without checking it against inflation and consumer spend constraints in key MEA economies.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 7.24 B (2025) | |
| Industry Association A | USD 30.00 B (2023) | Often reflects mobile money transaction value for a subset of MEA and may include cash-in and cash-out flows and wallet top-ups, which can inflate totals versus pure payment transactions. |
| Regional Consultancy B | USD 12.50 B (2024) | May mix in broader digital payments executed with cards and bank transfers, and may not separate handset-initiated checkout from other electronic payment activity, leading to a wider scope. |
The comparison shows that most of the spread is explained by scope, especially whether the figure is capturing only handset-initiated payments or a broader set of digital money movement. By anchoring the model to user activity, acceptance readiness, and realistic spend constraints, the final number stays traceable to inputs that can be checked and updated each year.


Key Questions Answered in the Report
What is the current value of the Middle East and Africa mobile payments market?
The market is valued at USD 9.91 billion in 2026 and is projected to climb to USD 47.28 billion by 2031 at a 36.72% CAGR.
Why are proximity payments growing so quickly in the region?
SoftPOS roll-outs, NFC handset penetration and government cashless agendas are simplifying acceptance for merchants and driving consumer demand for tap-and-go convenience.
How do Wage-Protection-System mandates affect mobile payments growth?
WPS rules push salaries into digital accounts, onboarding millions of low-income workers who then use wallets for everyday purchases, remittances and bill pay.
Which application segment is expanding fastest?
Government and public-sector payments are expected to grow at a 40.35% CAGR as digital IDs and e-government services embed mobile payment rails into public service delivery.
What are the main regulatory barriers facing providers?
Fragmented licensing across over 45 African regulators and transaction caps in Nigeria and Egypt increase compliance costs and limit high-ticket transactions.
How concentrated is the competitive landscape?
Roughly 70% of active users are with the top five platforms, indicating moderate concentration and ongoing room for new entrants that can differentiate on cross-border, SME or vertical-specific solutions.
Page last updated on:





