
Managed Mobile Support and Maintenance Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 15.19 Billion |
| Market Size (2032) | USD 25.15 Billion |
| Growth Rate (2027 - 2032) | 10.61 % |
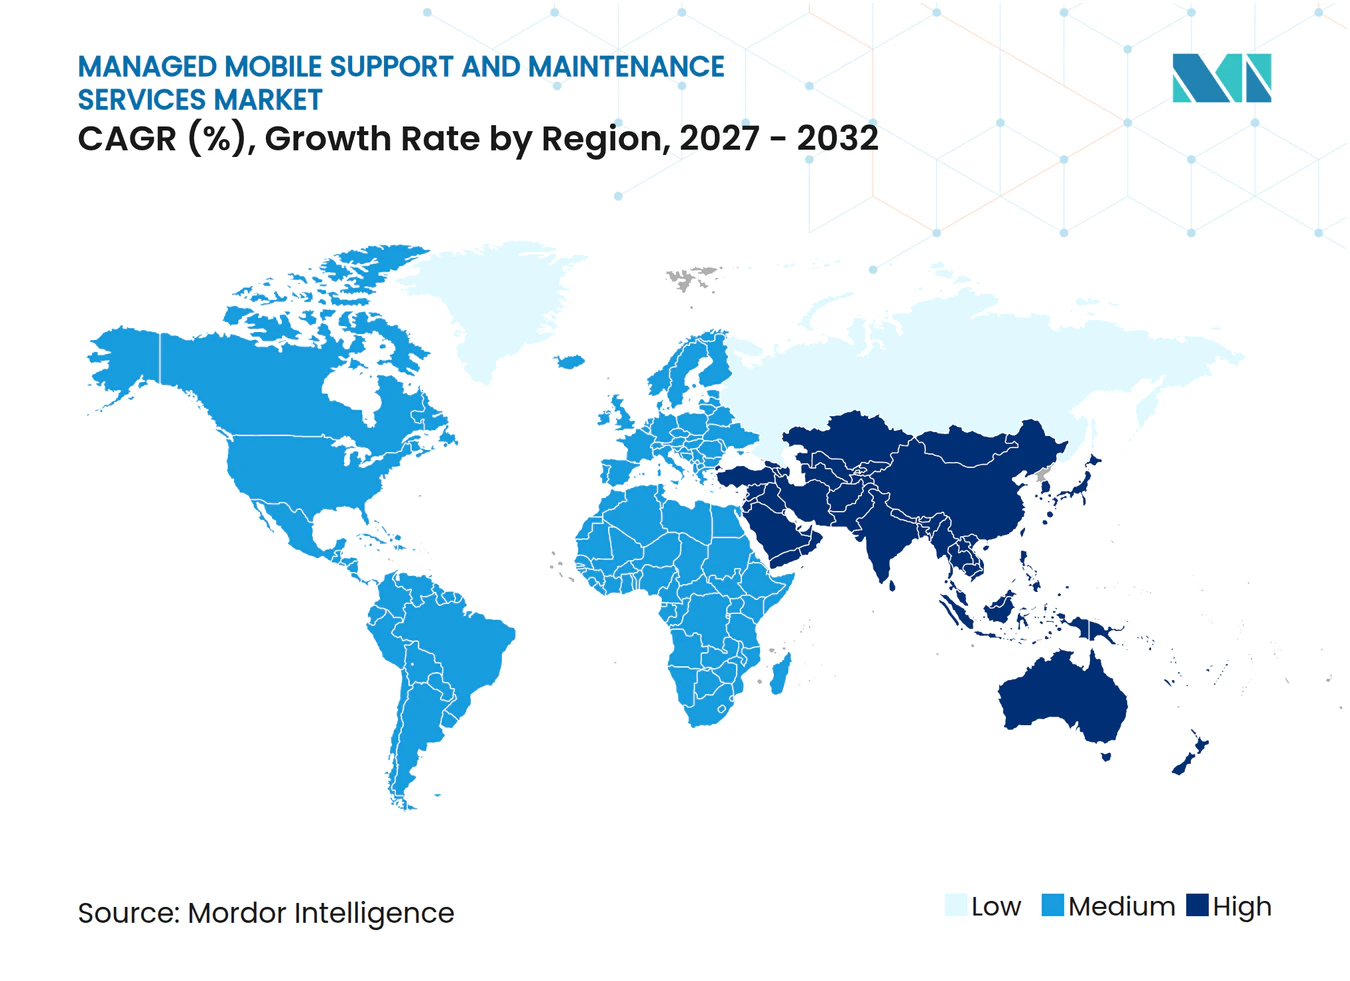
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Mobile Support and Maintenance Services Market Analysis by Mordor Intelligence
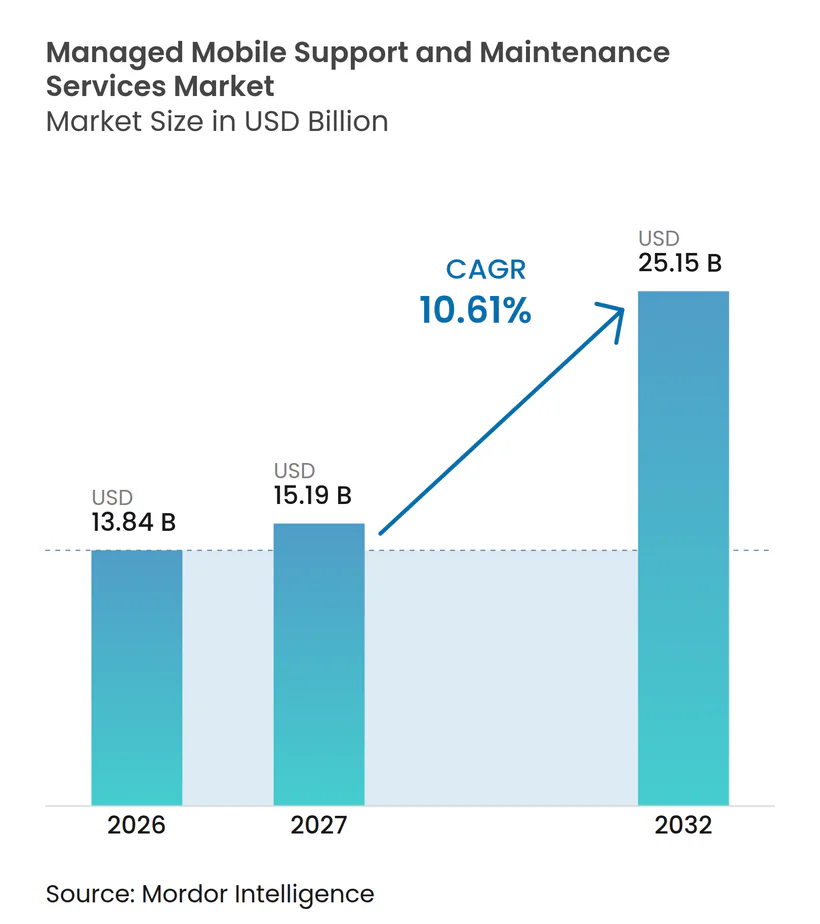
The Managed Mobility Services Market size is projected to expand from USD 13.84 billion in 2026 to USD 15.19 billion in 2027, and to USD 25.15 billion by 2032, registering a CAGR of 10.61% between 2027 and 2032. Enterprises are extending managed arrangements beyond device purchasing to include provisioning, security, expense management, support, and retirement. Hybrid work has increased the number of smartphones, rugged handhelds, laptops, and Internet of Things devices that operate across carriers and countries. This broader device base supports demand for a single provider capable of managing the full lifecycle. Providers are competing through diagnostics, experience-level agreements, and sustainability services, which can support contract renewals. Data residency rules also require local infrastructure or sovereign cloud routing in some countries, raising delivery costs and creating a higher entry barrier for smaller providers.
Key Report Takeaways
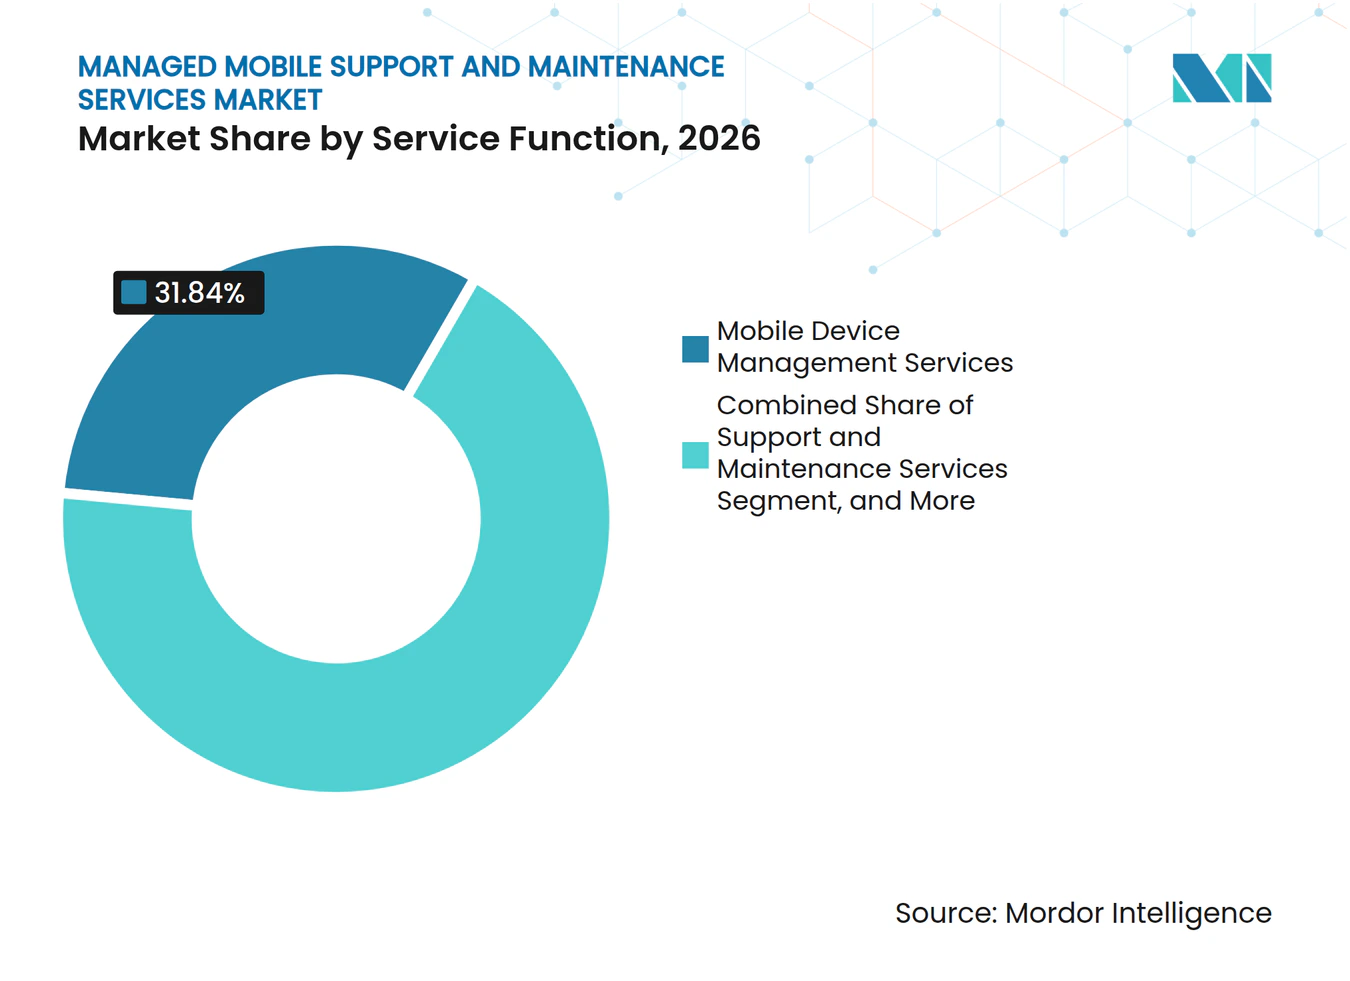
- By service function, mobile device management services held 31.84% of the Managed Mobility Services Market share in 2026, while mobile security management services are projected to expand at an 11.41% CAGR through 2032.
- By deployment model, cloud-based deployments accounted for 68.32% of the managed mobility services market share in 2026 and are projected to advance at a 10.98% CAGR through 2032.
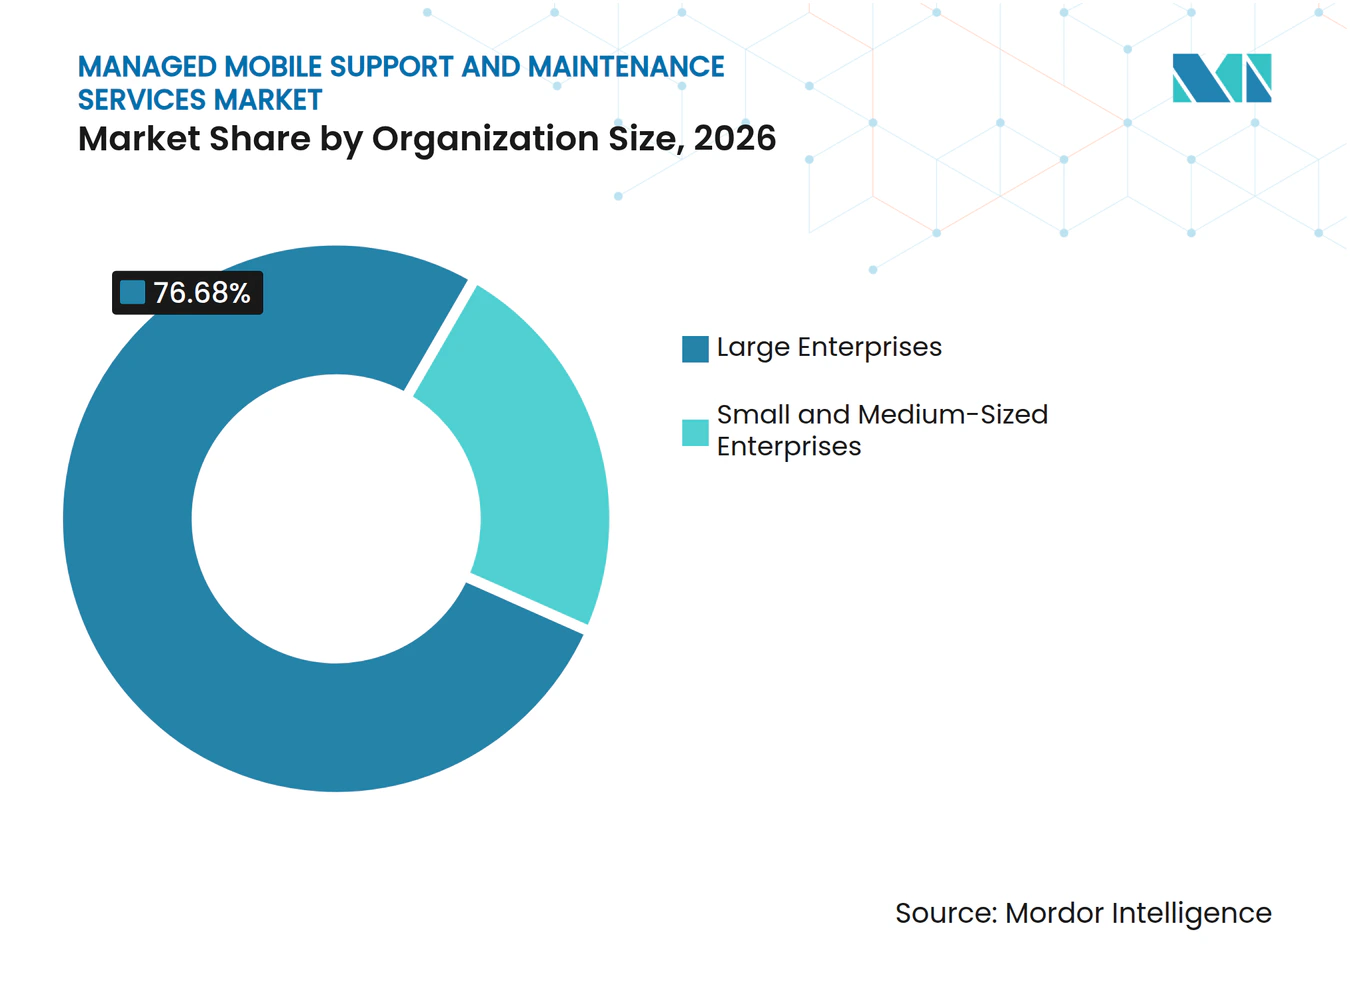
- By organization size, large enterprises held 76.68% revenue share in 2026, while SMEs are expected to expand at a 10.94% CAGR through 2032.
- By end-user industry, BFSI accounted for 18.46% revenue share in 2026, while transportation and logistics is projected to accelerate at an 11.96% CAGR through 2032.
- By geography, North America held 37.29% revenue share in 2026, while Asia-Pacific is expected to expand at an 11.58% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Mobile Support and Maintenance Services Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Enterprise Device Fleet Complexity and Distributed Workforces | +2.8% | Global, with highest intensity in North America and Europe | Short term (≤ 2 years) |
| Rising Mobile Cybersecurity and Compliance Requirements | +2.4% | Global, with strongest effect in regulated markets in North America and the EU | Short term (≤ 2 years) |
| Outsourcing of Mobility Lifecycle Costs and Specialized Skills | +2.0% | Global, with notable acceleration in North America and Asia-Pacific | Medium term (2-4 years) |
| Growth of Ruggedized and Dedicated Mobile Endpoints | +1.4% | Asia-Pacific, North America, and Europe, with spillover to the Middle East | Medium term (2-4 years) |
| Cloud-Based Unified Endpoint Management Adoption | +1.1% | Global, accelerating across Asia-Pacific and South America | Medium term (2-4 years) |
| AI-Enabled Predictive Support and Automated Remediation | +0.8% | North America and Europe, with emerging adoption in Asia-Pacific | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Enterprise Device Fleet Complexity and Distributed Workforces
Large organizations now operate device estates that combine corporate smartphones, contractor tablets, rugged handhelds, and bring-your-own devices. These fleets often use multiple operating systems and ownership models within a single administrative environment. The Managed Mobility Services Market benefits when internal teams cannot consistently manage carrier contracts, operating system refresh cycles, and device support across countries. SOTI reported that only 54% of distributed workers received integrated support in a 2025 survey of 7,300 respondents across 11 countries. The same research found that device issues cost logistics drivers 12 hours of downtime per month, while 35% worked overtime after disruptions. These operating losses make coordinated support and fleet visibility more relevant to enterprise buyers.
The spread of 5G and eSIM technology adds another layer of administration. Connectivity profiles may require updates across multiple carrier environments without manual intervention. A provider that manages devices, connectivity, and support through a shared process can reduce the number of vendors a customer uses. This model is particularly relevant for field workforces that cannot wait for local IT staff to resolve a device issue. It also makes standardized enrollment and remote policy management more important in new deployments. The resulting demand supports recurring contracts rather than one-time device projects. It also raises the value of a provider that can coordinate support across device types without sending the customer to separate teams. When users work across regions, common processes can be as important as the underlying management software. This need for coordination keeps mobility services relevant as device fleets become more distributed.
Rising Mobile Cybersecurity and Compliance Requirements
Mobile security is becoming a formal governance requirement for organizations that handle regulated data. The European Union's Digital Operational Resilience Act has applied since January 17, 2025, and it requires covered financial entities to maintain an information register and report major information and communication technology incidents within prescribed timelines.[1] These obligations increase the need to identify, govern, and respond to risks involving mobile endpoints. The Managed Mobility Services Market, therefore, has a stronger role in financial services and other sectors with strict documentation requirements. Established providers can benefit when their services are already part of a client's governance workflow. Longer contracts and higher switching costs can follow where security controls are tied to daily operating processes.
Mobile security management also moves beyond basic device configuration when organizations adopt zero-trust practices. Customers increasingly seek continuous visibility into device status, application behavior, and access controls. Jamf made its AI Assistant generally available in 2026 with fleet-level checks against CIS Level 1, CIS Level 2, and NIST 800-171 benchmarks. This example shows how security intelligence is being incorporated into endpoint management platforms. Security add-ons can broaden the scope of a managed relationship even when base device-management pricing is under pressure. Providers that combine practical support with documented controls can address both operational and compliance needs. A clear record of device state and response activity can be useful when customers need to demonstrate control to internal risk teams. This gives managed security a role in routine business operations, not only in an incident.
Outsourcing of Mobility Lifecycle Costs and Specialized Skills
Organizations are placing greater attention on the full cost of operating a device fleet. This includes procurement, activation, carrier billing, repairs, replacement, security, support, and retirement. Managed mobility providers can offer a single operating model for these tasks, which helps customers identify expenses that are difficult to track internally. The Managed Mobility Services Market also benefits where enterprises cannot recruit employees with experience across multiple endpoint platforms. Outsourcing can provide access to specialized skills without requiring each customer to build a large internal team. Device-as-a-service and subscription arrangements can also shift spending away from upfront device purchases.
Tangoe reported 20% growth in new customer logos and 20% growth in existing accounts, adding a second or third solution in its January 2026 results. The results indicate that customers can extend engagements beyond a single mobility function. A broader contract may link telecom expense management with inventory, device lifecycle, and support services. This model can make it easier for buyers to measure service performance across the full fleet. It can also reduce the need to reconcile information from separate carrier and device systems. Providers that show clear cost control and reliable service delivery can strengthen their position in renewals. They can also use lifecycle data to identify unused lines, inactive devices, and recurring support issues. This information gives procurement and IT teams a shared basis for evaluating service performance.
Growth of Ruggedized and Dedicated Mobile Endpoints
Ruggedized and dedicated endpoints are used in logistics, manufacturing, healthcare, and field services. These devices are designed for operating conditions that differ from office use, including warehouse, delivery, and production settings. Their specialized hardware requires controlled configuration, repair, replacement, and software support. This supports the Managed Mobility Services Market demand for lifecycle arrangements that extend over several years. The long operating life of rugged equipment can make service revenue more predictable than support for consumer-grade devices. It also raises the cost of downtime when a device fails during a work shift.
Getac documented a deployment of more than 10,000 ZX10 rugged Android tablets at more than 400 United States warehouses for an LTL freight carrier. Deployments of this scale require enrollment, configuration, security policies, repair planning, and ongoing field support. Transportation and logistics customers have a direct reason to limit disruption because device failures can affect delivery schedules and labor utilization. Dedicated mobile hardware also requires providers to understand hardware-specific operating constraints. This creates opportunities for specialists with experience in rugged Android environments. It can also favor partnerships between hardware manufacturers, software providers, and managed service firms. Such partnerships can combine hardware knowledge with remote management and field support. They can be particularly useful when a customer needs rapid replacement devices in several locations.
Restraints Impact Analysis of Managed Mobile Support and Maintenance Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data Sovereignty and Privacy Constraints in Remote Support | -1.8% | EU, Asia-Pacific including China, India, and South Korea, and the Middle East | Short term (≤ 2 years) |
| Integration Complexity Across Legacy IT and Telecom Environments | -1.4% | Global, with strongest effect in large enterprises in North America and Europe | Medium term (2-4 years) |
| Customer Concerns About Vendor Lock-In and Operational Control | -0.9% | Global | Medium term (2-4 years) |
| Shortage of Certified Mobility Support Professionals | -0.5% | Global, particularly acute in Asia-Pacific and the Middle East | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Data Sovereignty and Privacy Constraints in Remote Support
Remote device support can create legal and operational issues when data crosses national borders. European data protection rules may treat remote access to personal data from outside the European Economic Area as an international transfer. The European Commission explains that organizations need appropriate safeguards for transfers to third countries when it has not issued an adequacy decision.[2] Similar concerns affect centralized support designs in Asia-Pacific and the Middle East. The Managed Mobility Services Market faces additional delivery costs when providers must establish local support capacity or use sovereign cloud routing. These requirements can be especially challenging for smaller providers with limited regional infrastructure.
Data sovereignty rules do not remove the need for managed services, but they change how those services are delivered. Customers may require stronger contracts, access controls, audit records, and local processing arrangements. These conditions can lengthen sales cycles and increase the cost of entering regulated markets. Providers with in-country infrastructure may have an advantage where local presence is essential. A fragmented regulatory environment can also limit the use of a single centralized support model across countries. The result is a more complex operating model, even as demand for secure endpoint management remains strong. Customers may assess providers on their ability to explain where support is performed and how access is controlled. Clear operating boundaries can therefore become part of the service proposition in regulated settings.
Integration Complexity Across Legacy IT and Telecom Environments
Large enterprises often maintain legacy endpoint platforms, carrier portals, IT service management tools, and financial systems. These systems may not connect easily with a cloud-based unified endpoint management console. Integration work can delay deployments and make buyers cautious about changing providers. The Managed Mobility Services Market can lose momentum when a customer expects a difficult transition from its existing systems. The issue is especially relevant in large North American and European organizations that have accumulated several tools over time. Providers must show how their services will work with current enterprise resource planning, IT service management, and carrier billing processes.
Brightfin launched Brightfin Sync in May 2025 to bring mobile and endpoint asset data into the ServiceNow configuration management database. The launch reflects customer demand for stronger links between endpoint data and broader IT operations. Integration capability can be a deciding factor when buyers compare providers with similar device management features. It can also determine whether a project starts with a broad scope or a smaller pilot. Clear integration plans can reduce uncertainty for customers and help preserve contract economics. Providers that cannot demonstrate this capability may face longer sales cycles and more scope negotiations. Successful projects often depend on a phased plan that identifies the systems to be connected, the data to be exchanged, and the people responsible for support. This planning work can be essential to achieving the intended service outcome.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Mobile Support and Maintenance Services Market Segment Analysis
By Service Function, Security Services Gain Pace on MDM's Market Lead
Mobile device management services held 31.84% of the Managed Mobility Services Market share in 2026, making them the largest service function. The category includes provisioning, remote configuration, enrollment, and kiosk-mode administration. Its large installed base reflects long-standing enterprise use of formal device controls. Cloud platforms have made basic enrollment more standardized, which can increase price pressure in established MDM contracts. Customers continue to need reliable management for diverse operating systems and device types. MDM remains an important foundation for providers that offer broader lifecycle services. Mobile application management services, support, and maintenance services make up the remaining functional mix. The service portfolio is therefore not limited to a device-control console. It covers the day-to-day work needed to keep users connected, devices compliant, and applications available. Providers that can coordinate these functions can give customers a clearer view of responsibilities across the device lifecycle.
Mobile security management services are projected to grow at an 11.41% CAGR through 2032, outpacing the overall Managed Mobility Services Market. Compliance requirements and zero-trust endpoint practices are supporting this increase. Organizations are increasingly purchasing security as a defined service rather than treating it only as an MDM feature. Security services can include compliance checks, threat response, access governance, and reporting. Jamf's 2026 rollout of the AI Assistant demonstrated how fleet-level checks can be integrated into management platforms. Bundled platforms may lower standalone MDM fees while creating more revenue per managed endpoint through security functions. The competitive focus is moving toward total platform value rather than simple per-device pricing. This shift means that buyers may compare a provider's ability to manage risk and support outcomes, rather than only the cost of basic administration. It also makes service reporting and clear accountability more important during contract reviews.



By Deployment Model, Cloud Infrastructure Consolidates as On-Premises Use Cases Narrow
Cloud-based deployments accounted for 68.32% of the managed mobility services market share in 2026 and are projected to expand at a 10.98% CAGR through 2032. Cloud delivery can reduce the infrastructure burden for organizations with dispersed device fleets. It supports remote provisioning and policy enforcement without depending solely on virtual private network connections. Customers can apply consistent policies across locations from a central environment. This model is well-suited to fleets that change frequently because new devices can be enrolled remotely. It can also make it easier to connect device management with support and security workflows. These advantages make cloud delivery important to the Managed Mobility Services Market. Cloud services can also help providers apply updates and security settings more consistently across a distributed estate. For customers, this can improve visibility when devices are used outside traditional office locations. The value of cloud delivery rests as much on practical administration as on infrastructure choice.
On-premises deployments remain necessary in government, defense, and air-gapped environments with strict security classifications. Some large enterprises will also retain hybrid arrangements while they move regulated and commercial endpoints toward shared management processes. Hybrid use reflects the practical need to support both existing systems and newer cloud services. Providers must therefore support more than one deployment approach during the forecast period. The mix of deployment models can vary based on customer risk profile and existing infrastructure. This can slow down the completion of a cloud migration in sensitive environments. It also leaves room for services that help customers manage transition planning and data controls. A provider may need to support gradual migration rather than require a complete change to a customer's operating model. This makes implementation experience a relevant factor in deployment decisions.
By Organization Size, SMEs Narrow the Gap as Cloud Reduces Barriers
Large enterprises held 76.68% of the managed mobility services market share in 2026. Their lead reflects early adoption of formal MDM contracts and the high value of managing complex fleets across several countries. Financial services, healthcare, and defense supply chains often require documented governance practices. Large organizations also have more devices and a more varied set of endpoints, which increases service value per customer. Their procurement teams can seek broad contracts that combine lifecycle management, support, security, and telecom expense controls. This makes large enterprises central to current revenue for the Managed Mobility Services Market and to supplier product planning. Their requirements also influence the product capabilities offered by leading providers. They may require multilingual support, carrier coordination, and documented escalation processes simultaneously. These demands reinforce the value of providers with established operational coverage.
SMEs are expected to expand at a 10.94% CAGR through 2032, the highest rate in the organization-size segmentation. Cloud-native platforms and per-device pricing lower the entry threshold for smaller organizations. Carrier bundles can provide an early form of mobile cybersecurity support, but more formal governance requirements can create demand for wider managed services. Smaller customers may prefer simpler packaging that includes basic security, support, and device administration. They can also value standard configuration templates that reduce internal technology workloads. Providers can address this group with clearly defined service tiers rather than enterprise-scale custom programs. This creates room for targeted offerings without changing the importance of large-enterprise accounts or their established spending role. Straightforward packaging can also make it easier for smaller businesses to adopt more formal controls as their device fleets expand. This provides an additional route for suppliers that can combine usable technology with accessible support.

By End-User Industry, Transportation and Logistics Outpaces BFSI in Growth Rate
BFSI held 18.46% of the managed mobility services market share in 2026, making it the largest end-user industry. Banks, insurers, and asset managers operate large workforces that use managed smartphones and tablets. Their policies commonly cover bring-your-own-device use, identity controls, and data protection. Regulatory responsibilities make documented support and governance particularly important. Managed services can help these organizations apply consistent rules across their branch, field sales, and relationship management workforces. This sustains demand for security, compliance reporting, and lifecycle coordination. Healthcare and life sciences, manufacturing, retail and e-commerce, IT and telecom, and other sectors also contribute distinct device-management requirements.
Transportation and logistics are projected to advance at an 11.96% CAGR through 2032, the fastest end-user rate. SOTI found that logistics drivers lost 12 hours per month to device downtime, and 35% had to work overtime due to device issues. These conditions make support quality and rapid replacement practical purchasing criteria. Dedicated endpoints also create demand for specialized configuration and repair processes. Manufacturing continues to need controlled mobile devices on production floors. Retail and e-commerce support the segment through mobile point-of-sale and distributed fulfillment operations. This range of requirements maintains a diverse end-user base for the Managed Mobility Services Market. Each vertical emphasizes a different balance among availability, security, cost control, and device durability. Providers that understand those differences can structure services around specific operating environments.
Geography Analysis
North America Managed Mobile Support and Maintenance Services Market
North America accounted for 37.29% of the Managed Mobility Services Market share in 2026. Regulated enterprises in financial services and healthcare support demand for formal mobility management agreements. The region also has a mature telecom expense management environment that is embedded in corporate IT spending. The United States has the largest single-country contribution because it hosts many global providers and large enterprise customers. Canada contributes to demand from banking and logistics operations. Mexico presents a manufacturing-led opportunity as nearshoring investments create new fleet-management needs. North American buyers often seek a consolidated relationship across unified endpoint management, telecom expense management, IT service management, and diagnostics. This preference can favor suppliers with pre-integrated service architectures. The region's mature buying environment also raises expectations for measured service levels and clear accountability.
APAC Managed Mobile Support and Maintenance Services Market
Asia-Pacific is projected to expand at an 11.58% CAGR through 2032, the fastest regional rate. China supports demand through manufacturing digitization, while India adds demand from IT services and logistics. ASEAN 5G deployment supports dedicated-device use cases in logistics, manufacturing, and field services. South Korea's regulated financial sector requires strong device governance. Japan's industrial device base presents replacement needs where legacy handhelds remain in use. Brightfin announced its first Australian customer win with Mobilize IT in February 2026, which will use its ServiceNow-native platform for invoice processing, inventory management, and procurement workflows.
EMEA and South America Managed Mobile Support and Maintenance Services Market
Europe has the second-largest revenue base, led by Germany, the United Kingdom, and France. Manufacturing, financial services, and public-sector mobile workforces support regional demand. South America is at an earlier stage of adoption, with Brazil and Argentina benefiting from the digitization of logistics. The Middle East has opportunities in Saudi Arabia and the UAE through digital transformation programs and the expansion of fintech activity. Africa remains the smallest regional market, though South Africa's enterprise sector and Nigeria's banking industry are increasing investment in formal mobile fleet management. Regional data rules and local delivery needs can influence which providers can compete effectively in each geography. International providers may need local partners or in-country capacity to meet customer and regulatory expectations. This makes geographic coverage a practical competitive requirement rather than a simple sales expansion decision.
Competitive Landscape
Market Concentration
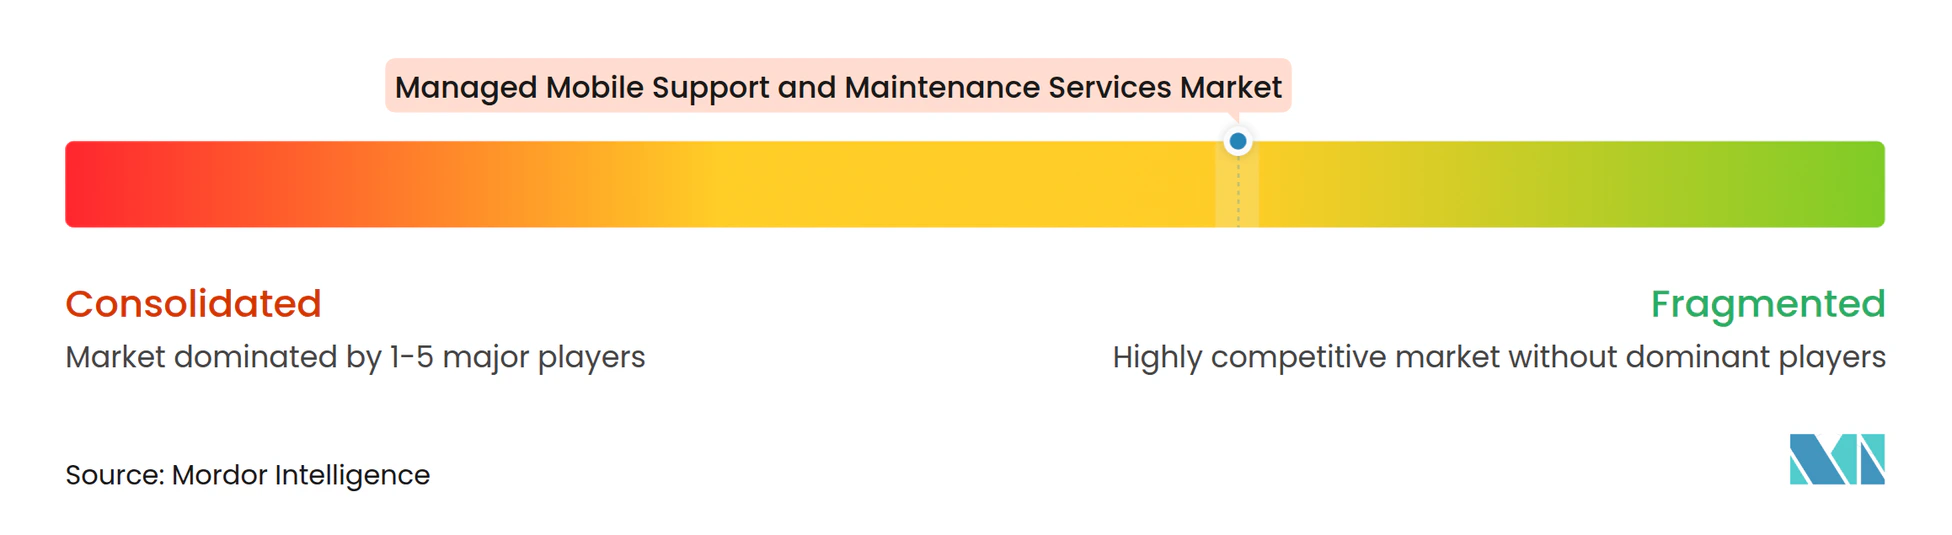
The managed mobility services market is moderately fragmented. Competition includes pure-play managed mobility operators, telecom expense management platforms, and endpoint management software providers that offer service wrappers around their platforms. Tangoe represents the telecom expense management model, with its Tangoe One platform linking expense and mobility management functions. The company reported continued customer momentum in 2026 and launched Multi-SIM management to replace manual device and line reconciliation across large cross-carrier fleets.[3] Providers are seeking to offer broader lifecycle management rather than a single standalone service. This approach can support vendor consolidation for customers with large distributed workforces. A consolidated model can help a customer connect procurement, device inventory, carrier information, support records, and security policies. It may also reduce the operational burden of managing several suppliers with separate reporting processes. The ability to deliver consistent service across countries remains important for companies with mobile workforces.
Strategic partnerships are another route to differentiation. Advantech partnered with SOTI in August 2025 to make MobiControl and XSight available across smart retail, logistics, and healthcare environments through one original equipment manufacturer channel. The partnership supports device management across Android, iOS, Windows, and Linux environments. Radix Technologies introduced RadixAI in September 2025 with predictive failure management and enterprise-wide AI orchestration capabilities. These moves show that providers are using integration, device intelligence, and hardware relationships to distinguish their offers. Competition is increasingly focused on reducing support friction and improving operational visibility. Predictive support can help a provider identify recurring issues before they disrupt users. Integration with enterprise systems can also make mobility information more useful to IT and operations teams. These capabilities can matter when customers measure service quality across a large fleet.
Smaller providers such as 42Gears Mobility Systems, ProMobi Technologies, and Esper.io focus on vertical-specific rugged device management and dedicated Android fleets. Their specialized capabilities can appeal to customers whose operating needs are not fully met by broad endpoint platforms. Opportunities remain in SME-focused managed security, healthcare remote support, and managed Internet of Things endpoints. The Stratix and T-Mobile SmartRefresh collaboration combines device lifecycle management, telecom expense visibility, and 5G connectivity for distributed workforces. Stratix received industry recognition as a representative vendor in 2026 for the second consecutive year. The competitive environment allows focused specialists and broader platforms to address different customer needs. Broad vendors can combine multiple service functions for large accounts, while focused firms can address rugged hardware, Android operations, or defined vertical requirements. This division helps explain why the market remains moderately fragmented. Customers can choose between a single broad provider and a set of specialized partners based on their fleet complexity and governance needs.
Managed Mobile Support and Maintenance Services Industry Leaders
-
SOTI Inc.
-
Jamf Software, LLC
-
Tangoe, Inc.
-
Calero-MDSL, LLC
-
42Gears Mobility Systems Private Limited
- *Disclaimer: Major Players sorted in no particular order
Managed Mobile Support and Maintenance Services Market Companies Covered in this Report
- SOTI Inc.
- Jamf Software, LLC
- 42Gears Mobility Systems Private Limited
- Esper.io, Inc.
- Miradore Oy
- Addigy, Inc.
- Kandji, Inc.
- Mosyle Corporation
- ProMobi Technologies Private Limited
- Codeproof Technologies Inc.
- Tangoe, Inc.
- Calero-MDSL, LLC
- Sakon, Inc.
- Brightfin, LLC
- Stratix Corporation
- Vox Mobile, Inc.
- Digital Management, LLC
- Mobile Mentor International Pty Limited
- VoicePlus Pty Ltd
- devicenow GmbH
Recent Industry Developments in Managed Mobile Support and Maintenance Services Market
- October 2026: Tangoe reported strong first-half 2026 momentum and launched a Multi-SIM management solution replacing manual device and line reconciliation with system-driven accuracy, targeting enterprises managing large cross-carrier mobile fleets.
- February 2026: Brightfin announced its first Australian customer win through partner Mobilise IT, selecting Brightfin's ServiceNow-native platform for invoice processing, inventory management, and procurement workflows.
- October 2025: SOTI launched enhancements to the SOTI ONE Platform at SOTI SYNC 25, including the Stella AI-powered IT assistant and SOTI XSight integration with ServiceNow for real-time diagnostics in transportation and logistics operations.
- August 2025: Advantech partnered with SOTI to offer MobiControl and XSight across smart retail, logistics, and healthcare ecosystems, enabling enterprises to deploy managed mobility through a single original equipment manufacturer channel.
Global Managed Mobile Support and Maintenance Services Market Report Scope
The Managed Mobility Services Market is defined as the market for services that enable organizations to outsource or streamline the management, monitoring, security, and maintenance of mobile devices, applications, and enterprise mobility environments. These services help organizations manage smartphones, tablets, laptops, and other mobile endpoints, secure corporate data, enforce mobility policies, support remote and hybrid workforces, and optimize mobile operations.
The Managed Mobility Services Market Report is Segmented by Service Function (Mobile Device Management Services, Mobile Application Management Services, Mobile Security Management Services, and Support and Maintenance Services), Deployment Model (Cloud-Based, On-Premises, and Hybrid), Organization Size (Large Enterprises and Small and Medium-Sized Enterprises), End-User Industry (BFSI, IT and Telecom, Healthcare and Life Sciences, Manufacturing, Retail and E-commerce, Transportation and Logistics, and Other End-User Verticals), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Mobile Device Management Services |
| Mobile Application Management Services |
| Mobile Security Management Services |
| Support and Maintenance Services |
| Cloud-Based |
| On-Premises |
| Hybrid |
| Large Enterprises |
| Small and Medium-Sized Enterprises |
| IT and Telecom |
| BFSI |
| Healthcare and Life Sciences |
| Manufacturing |
| Retail and E-Commerce |
| Transportation and Logistics |
| Other End-User Verticals |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| South Korea | |
| India | |
| ASEAN | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Turkey | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Rest of Africa |
| By Service Function | Mobile Device Management Services | |
| Mobile Application Management Services | ||
| Mobile Security Management Services | ||
| Support and Maintenance Services | ||
| By Deployment Model | Cloud-Based | |
| On-Premises | ||
| Hybrid | ||
| By Organization Size | Large Enterprises | |
| Small and Medium-Sized Enterprises | ||
| By End-User Industry | IT and Telecom | |
| BFSI | ||
| Healthcare and Life Sciences | ||
| Manufacturing | ||
| Retail and E-Commerce | ||
| Transportation and Logistics | ||
| Other End-User Verticals | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| South Korea | ||
| India | ||
| ASEAN | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Turkey | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the managed mobility services market size?
The managed mobility services market size is projected to increase from USD 13.84 billion in 2026 and USD 15.19 billion in 2027 to USD 25.15 billion by 2032, at a 10.61% CAGR.
What is driving demand for managed mobility services?
Organizations are seeking support for device provisioning, security, expense management, repairs, and retirement across increasingly complex mobile fleets. Hybrid work and the use of several device types make a coordinated lifecycle service more useful to enterprise technology teams.
Which managed mobility service function has the largest share?
Mobile device management services held 31.84% revenue share in 2026, the largest share among service functions. The category remains the operating base for enrollment, configuration, remote administration, and wider lifecycle support.
Which deployment model is most widely used for managed mobility services?
Cloud-based deployment held 68.32% revenue share in 2026 and is projected to expand at a 10.98% CAGR through 2032. It supports remote policy management and enrollment for fleets operating across sites and countries. The approach can reduce the need for local infrastructure while maintaining central oversight of policies, software status, and device inventory.
Which customer group is expanding fastest?
SMEs are projected to expand at a 10.94% CAGR through 2032 as cloud platforms and per-device pricing reduce entry barriers. Simpler service tiers can help smaller organizations adopt structured management without building large internal mobility teams.
Which region is projected to expand fastest?
Asia-Pacific is projected to advance at an 11.58% CAGR through 2032, supported by digitalization, 5G deployment, and demand for dedicated devices. China, India, Japan, South Korea, and ASEAN countries each contribute different sources of demand, including manufacturing digitization, logistics operations, regulated financial services, and replacement of older industrial handheld devices.