
Managed Mobile Device Repair Coordination Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
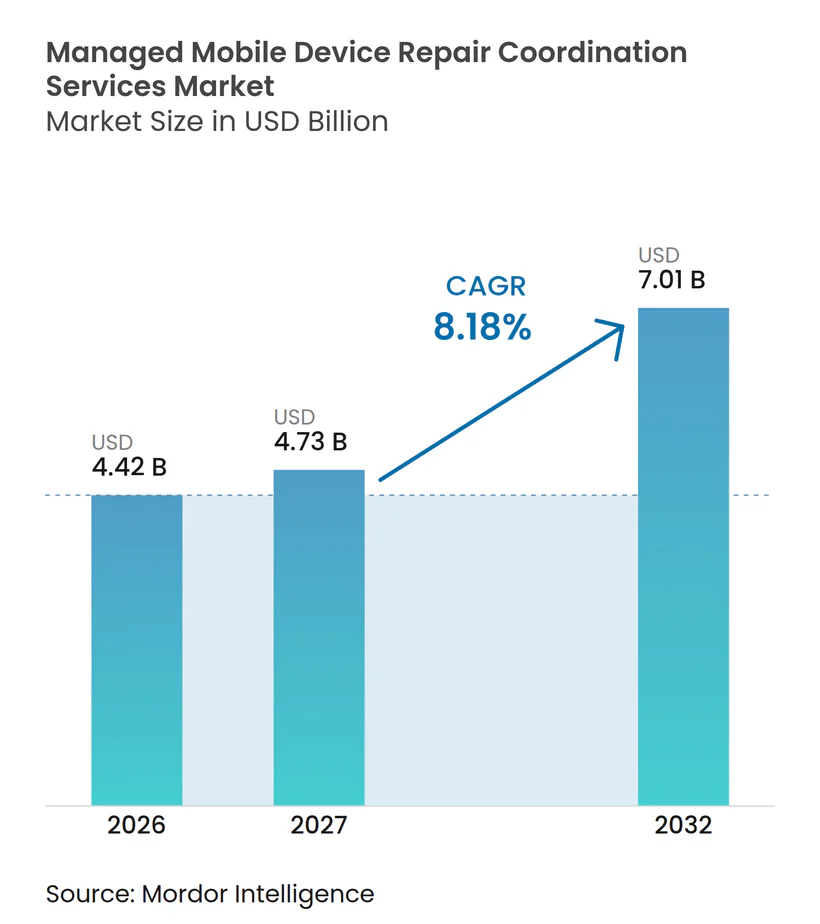
| Market Size (2027) | USD 4.73 Billion |
| Market Size (2032) | USD 7.01 Billion |
| Growth Rate (2027 - 2032) | 8.18 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Mobile Device Repair Coordination Services Market Analysis by Mordor Intelligence
The managed mobile device repair coordination services market size is projected to expand from USD 4.42 billion in 2026 to USD 4.73 billion in 2027, and to USD 7.01 billion by 2032, registering a CAGR of 8.18% between 2027 and 2032. Enterprise fleets increasingly support frontline work, so device failures now affect daily operations rather than just employee convenience. Device-as-a-Service and managed mobility contracts are shifting repair responsibility from internal IT teams to specialist providers. This change favors providers that combine intake, diagnostics, logistics, warranty routing, and secure handoff controls into a single service. Competitive differentiation increasingly depends on repair visibility, service-level performance, and documented data handling. The managed mobile device repair coordination services market also benefits as smaller organizations gain access to subscription-based coordination tools.
Key Report Takeaways
- By device type, smartphones held 59.84% of the managed mobile device repair coordination services market share in 2026, while multi-device enterprise fleets are projected to expand at a 9.18% CAGR through 2032.
- By repair type, screen and display repair accounted for 32.17% of the managed mobile device repair coordination services market size in 2026, while data recovery and secure data handling is projected to expand at a 9.56% CAGR through 2032.
- By coordination platform deployment, cloud-based platforms held 71.89% of revenue in 2026 and are projected to expand at an 8.74% CAGR through 2032.
- By organization size, large enterprises accounted for 68.36% of revenue in 2026, while SMEs are projected to grow at an 8.59% CAGR through 2032.
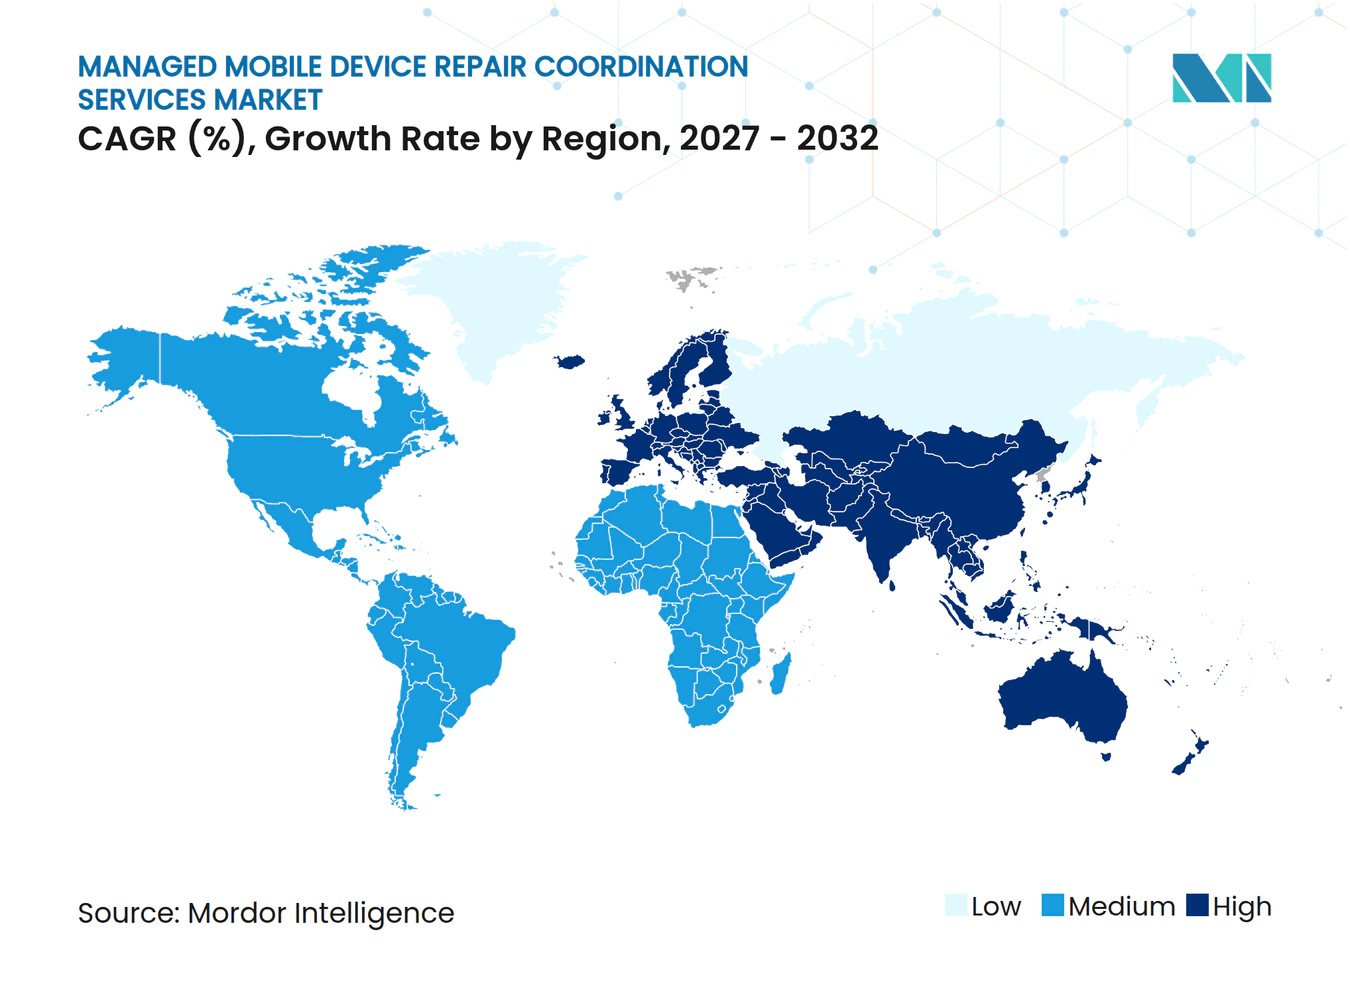
- By geography, North America held 44.12% of revenue in 2026, while Asia-Pacific is projected to expand at a 9.21% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Mobile Device Repair Coordination Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Enterprise Smartphone and Tablet Fleet Deployments | +2.8% | Global | Short term (≤ 2 years) |
| Increasing Cost of Device Replacement and Downtime | +2.0% | Global | Short term (≤ 2 years) |
| Expansion of Device-as-a-Service and Managed Mobility Models | +1.5% | North America and Europe | Medium term (2-4 years) |
| Right-to-Repair and Circular-Economy Requirements | +1.0% | Europe and North America | Medium term (2-4 years) |
| Cross-OEM Repair Visibility and SLA Standardization | +0.8% | Global | Medium term (2-4 years) |
| Repair-Orchestration Platforms Linking Diagnostics, Logistics, and Warranty Data | +0.6% | North America and Asia-Pacific | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Enterprise Smartphone and Tablet Fleet Deployments
Enterprise smartphone and tablet fleets now support logistics, retail, field service, and healthcare operations. The operating impact is greater when a frontline device fails because the device often supports task completion, communication, or access to core systems. A January 2025 survey of 461 IT decision-makers found an average of 37 minutes of lost worker productivity and 26 minutes of IT support time for each failure. The same study found that trouble tickets rose 45% by year 5 for non-rugged frontline devices. The managed mobile device repair coordination services market responds to this burden by moving organizations away from informal repair requests. Contracted programs can connect device intake, diagnostics, logistics, and closure within a defined workflow.
Increasing Cost of Device Replacement and Downtime
Replacement decisions can overlook the cost of operational interruption and IT support. This creates a stronger case for a managed repair model when a usable device can be returned under a defined service commitment. In June 2025, SOTI reported that 93% of mid-sized and large enterprises faced potential losses of USD 300,000 or more per hour of unplanned downtime. The company also reported that 56% of businesses saw a significant revenue effect from technology downtime events. The managed mobile device repair coordination services market gains when procurement teams assess repair services against these wider interruption costs. Service-level commitments, including next-business-day device availability, can therefore carry more weight in vendor selection.
Expansion of Device-as-a-Service and Managed Mobility Models
Device-as-a-Service contracts place repair coordination closer to the core device agreement. Providers retain responsibility for the hardware lifecycle and have a direct interest in protecting its value through timely repair. Managed mobility buyers increasingly seek connected management of devices, telecommunications expenses, and IT service activity. Subscription structures provide predictable per-device operating costs and reduce the capital exposure created by broad replacement cycles. This supports demand from SMEs that cannot readily absorb sudden repair costs. The managed mobile device repair coordination services market also develops a business-to-business demand channel, as repair activities are managed by service-provider operations teams.
Right-to-Repair and Circular-Economy Requirements
A right-to-repair policy expands access to parts, documentation, and qualified technicians. The European Union rules that took effect on June 20, 2025, require smartphone and tablet manufacturers to make spare parts and repair information available for 7 years after a product is discontinued. The rules also require batteries to retain 80% capacity after 800 charging cycles.[1] Texas enacted its consumer electronics right-to-repair law in 2025, and the law became effective on September 1, 2026. Broader access can help coordination providers develop larger vetted repair networks. It also gives organizations with waste-reduction goals a clearer operational reason to measure repair rates rather than replace devices.
Restraints Impact Analysis of Managed Mobile Device Repair Coordination Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fragmented OEM Warranty and Parts-Authorization Rules | -1.0% | Global | Short term (≤ 2 years) |
| Data-Security and Chain-of-Custody Risks During Repair | -0.8% | Global | Medium term (2-4 years) |
| Uneven Availability of Certified Technicians and Genuine Parts | -0.6% | Middle East, Africa, and South America | Medium term (2-4 years) |
| Low Repairability of Sealed and Highly Integrated Devices | -0.5% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Fragmented OEM Warranty and Parts-Authorization Rules
Multi-OEM fleets need repair partners that can comply with each brand's authorization rules. Work performed outside an authorized route can affect warranty coverage and leave the device owner exposed to additional hardware costs. A fleet using Samsung, Apple, and Zebra equipment may need a provider with authorization across all 3 brands. This requirement limits the available supplier pool and can delay procurement decisions. NIST SP 800-88 Rev. 2 requires device-specific sanitization choices and documentation tied to the device serial number before handoff.[2] The managed mobile device repair coordination services market is constrained because devices must be sent to separate brand-specific repair depots rather than to a single multi-brand facility.
Data-Security and Chain-of-Custody Risks During Repair
A repair handoff can expose personal, financial, health, or business data if controls are weak. Regulated organizations need evidence of custody transfers, sanitization, and agreed handling procedures before a device leaves their control. The ITU published Recommendation ITU-T L.1081 in July 2025 to set out media-sanitization practices for end-of-life and in-repair ICT devices. The recommendation aligns clear, purge, and destroy outcomes with the data's sensitivity and the storage technology involved. ISO/IEC 27001 control requirements also emphasize the importance of documenting custody transfers in regulated repair programs. Providers with recognized security controls and authorized service credentials can therefore have an advantage in sensitive enterprise accounts.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Mobile Device Repair Coordination Services Market Segment Analysis
By Device Type:
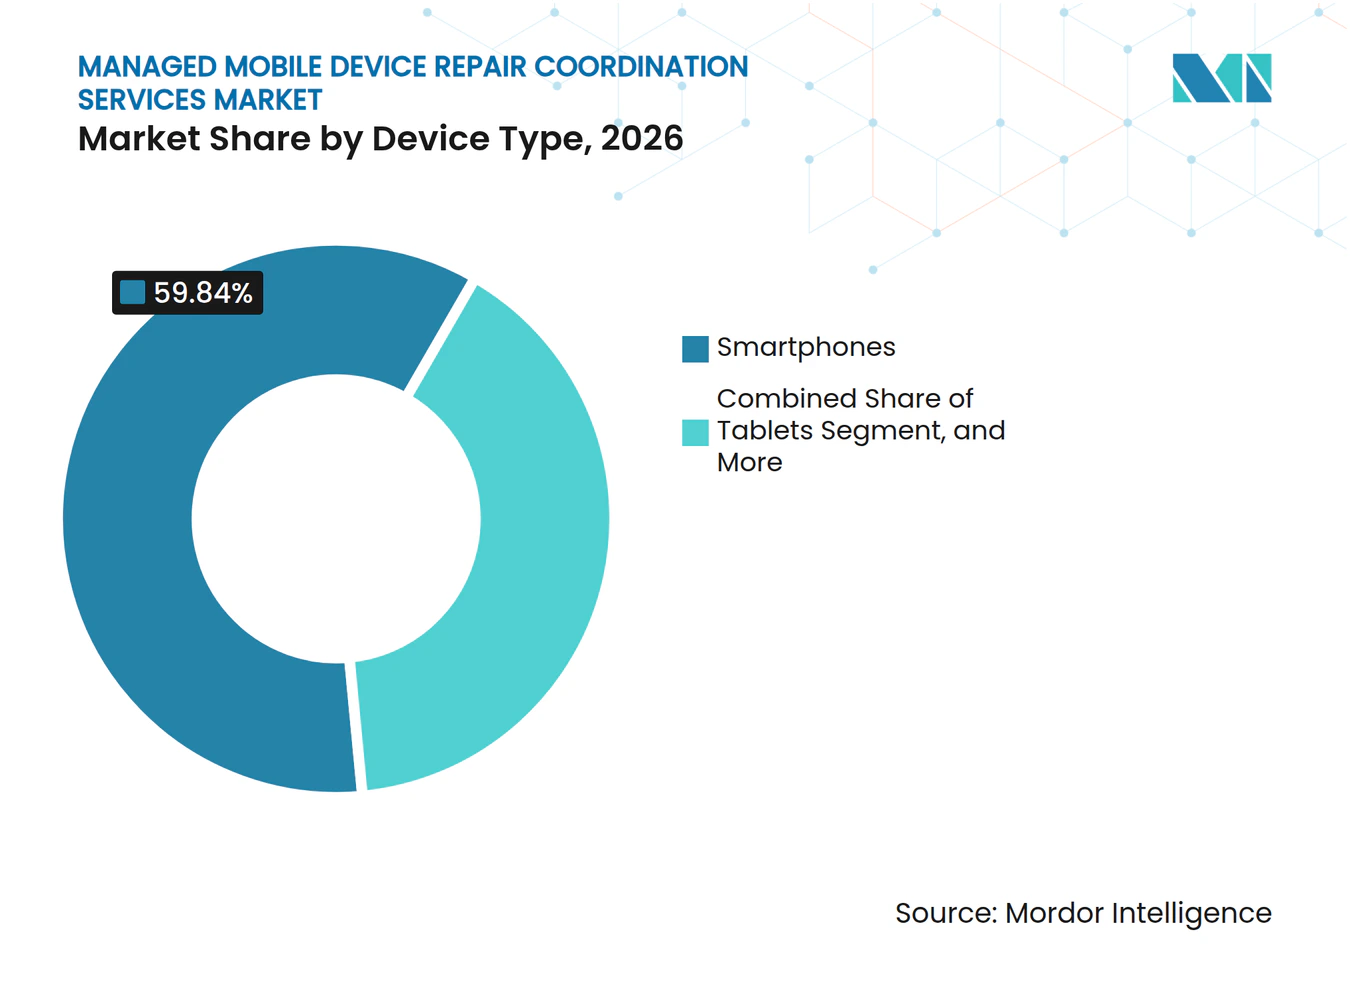
Enterprise Fleets Extend Coordination RequirementsSmartphones accounted for 59.84% of device-type value in 2026, making them the primary demand base for the managed mobile device repair coordination services market. Their use in corporate fleets exposes screens, batteries, and connectivity components to frequent frontline wear. Multi-device enterprise fleets are projected to expand at a 9.18% CAGR through 2032 as organizations place smartphones, tablets, rugged computers, and wearables under common service agreements. This broad fleet model requires coordinated repair histories, service-level tracking, and chain-of-custody records across different hardware types. It also increases the value of a single platform capable of coordinating multiple OEM repair paths.
Rugged mobile computers have a lower failure rate than consumer smartphones in some warehouse settings, but their repairs often require specialized components and technicians. This can increase revenue per repair event and make repair routing more important. Wearables add complexity because many manufacturers rely on proprietary tools and have not joined open authorized service center programs. Tablets used in healthcare and field service create different needs for screen, battery, and device availability management. Samsung SDS released Zero Touch Mobility 25.12 in 2025 with lifecycle workflows for repair requests, loaner assignments, returns, and replacements across distributed fleets. These workflows show why enterprise fleet contracts increasingly require a broader coordination layer.



By Repair Type:
Security Requirements Broaden the Repair ScopeScreen and display repair held 32.17% of spending in 2026, reflecting touchscreen exposure and the cost of OEM-grade replacement parts. Data recovery and secure data handling are projected to expand at a 9.56% CAGR through 2032, which exceeds the total managed mobile device repair coordination services market rate. Organizations increasingly treat the handling of information during repair as a compliance requirement. Battery repair and replacement remain a major category because frontline use can accelerate lithium-ion battery degradation. These repair needs require service providers to manage both physical restoration and the controls surrounding the device handoff.
The European Union Batteries Regulation 2023/1542 has begun to formalize capacity-retention disclosures for batteries. This adds a clearer reference point for organizations evaluating repair and replacement choices. The ITU-T L.1081 recommendation provides a recognized basis for documenting sanitization evidence across different repair situations. Software, firmware, and configuration remediation also become more important as fleets expand. A device that has undergone a physical repair needs secure enrollment in the organization’s management environment before it can return to service. Camera, sensor, and audio repairs are also gaining relevance where devices support inspection and transcription work.
By Coordination Platform Deployment:
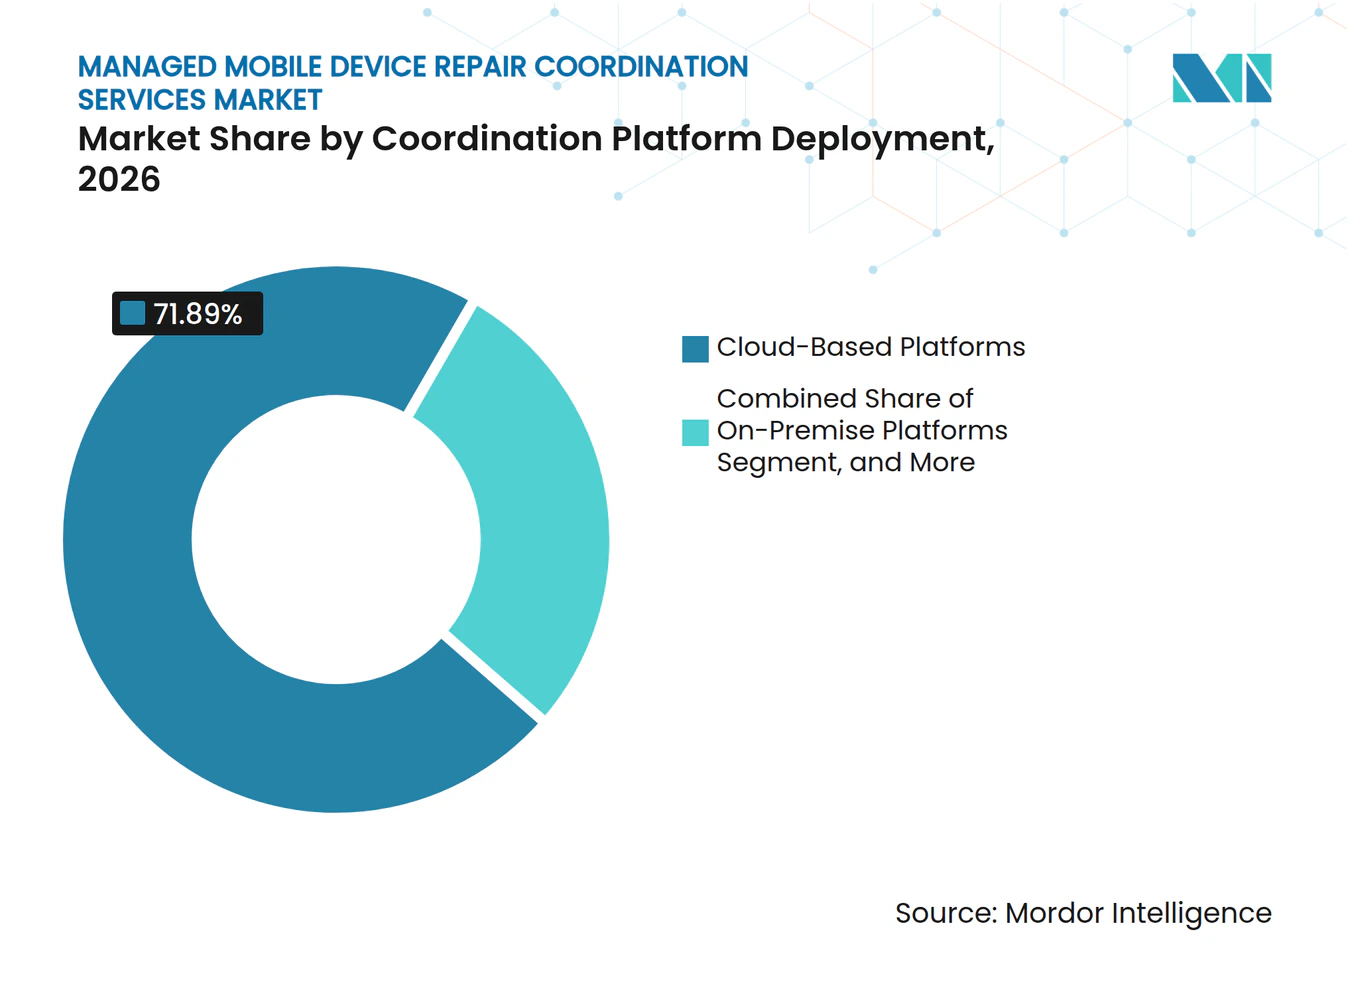
Cloud Systems Support Distributed Repair ProgramsCloud-based platforms accounted for 71.89% of deployment value in 2026 and are projected to grow at an 8.74% CAGR through 2032. This makes the cloud the leading deployment approach in both size and expected expansion. The managed mobile device repair coordination services market uses cloud systems for real-time service-level dashboards, multi-vendor connectivity, and central reporting. These capabilities matter when fleets operate across several locations and use more than 1 repair provider. Cloud deployment also supports visibility into device status for IT teams and business users.
Automated logs can help organizations provide evidence of service activity and custody events. This is useful where GDPR or sector-specific governance requirements apply to device information. On-premise platforms remain relevant in defense, intelligence, and parts of financial services where data residency needs limit external hosting. Hybrid environments can combine a cloud coordination layer with controlled local data storage. Platform suppliers that offer open application programming interfaces can connect their repair workflows with ServiceNow, Microsoft Intune, and IT service management tools. This reduces the need for repair coordination to operate as a separate workflow from broader IT operations.

By Organization Size:
SMEs Gain Access Through Subscription ModelsLarge enterprises held 68.36% of organization-size revenue in 2026, supported by their ability to negotiate multi-year managed service agreements. They can also fund the integration work needed to connect repair platforms with UEM, IT service management, and enterprise resource planning systems. SMEs are projected to expand at an 8.59% CAGR through 2032 as subscriptions and pre-integrated cloud workflows reduce the fleet threshold for managed services. The managed mobile device repair coordination services industry is increasingly serving firms that previously relied on ad hoc repair arrangements. This creates a clear opening among organizations managing 200 to 2,000 devices.
SMEs often need self-service onboarding, standard service tiers, clear service-level agreements, and links to common tools such as Microsoft Intune and Jamf. These features limit the need for a long implementation project. Large enterprises place more emphasis on cross-OEM repair capacity, data-handling credentials, and extensive application connectivity. Device-as-a-Service pricing can make budgeting more predictable for organizations that cannot absorb irregular repair costs. The managed mobile device repair coordination services market, therefore, has different selling requirements for each organization size. Providers that offer lightweight deployment for smaller fleets while preserving control features for larger accounts can address both demand profiles.
Geography Analysis
North America Managed Mobile Device Repair Coordination Services Market
North America accounted for 44.12% of revenue in 2026, giving the region the largest share in the managed mobile device repair coordination services market. The United States has a dense carrier, OEM, and enterprise ecosystem, while Canada has established managed mobility use in financial services and public sector accounts. The region also has a strong network of authorized service center repair facilities. Asurion’s uBreakiFix network reached 700 US repair locations in 2025, showing the scale of its repair footprint.[3] Such network density can support enterprise repair contracts when linked to lifecycle management systems.
APAC Managed Mobile Device Repair Coordination Services Market
Asia-Pacific is projected to expand at a 9.21% CAGR through 2032, the fastest regional rate in the managed mobile device repair coordination services market. Enterprise fleet expansion across China, India, South Korea, Australia, and Southeast Asia supports this outlook. Manufacturing and logistics firms in China are adopting Device-as-a-Service arrangements as OEM-certified programs develop around key production centers. insureMO and Nexacore announced a partnership in November 2025 for AI-enabled device protection and extended-warranty infrastructure across Asia-Pacific. The arrangement combined certified repair logistics with middleware connecting carriers, distributors, and repair providers.
EMEA and South America Managed Mobile Device Repair Coordination Services Market
Europe is the second-largest regional market, with Germany, the United Kingdom, France, Italy, and Spain as leading country markets. The European Union rules on smartphone and tablet repair make parts provenance and repair quality more relevant to enterprise device programs. South America, the Middle East, and Africa remain in the earlier stages of adoption. Brazil is expanding enterprise device use alongside 5G deployment in commercial and industrial areas. The United Arab Emirates and Saudi Arabia are investing in digital infrastructure that will need managed device services. PartServe and Motorola Mobility announced a November 2025 agreement to provide official Motorola warranty repairs in southern Africa, with online repair tracking.
Competitive Landscape
Market Concentration
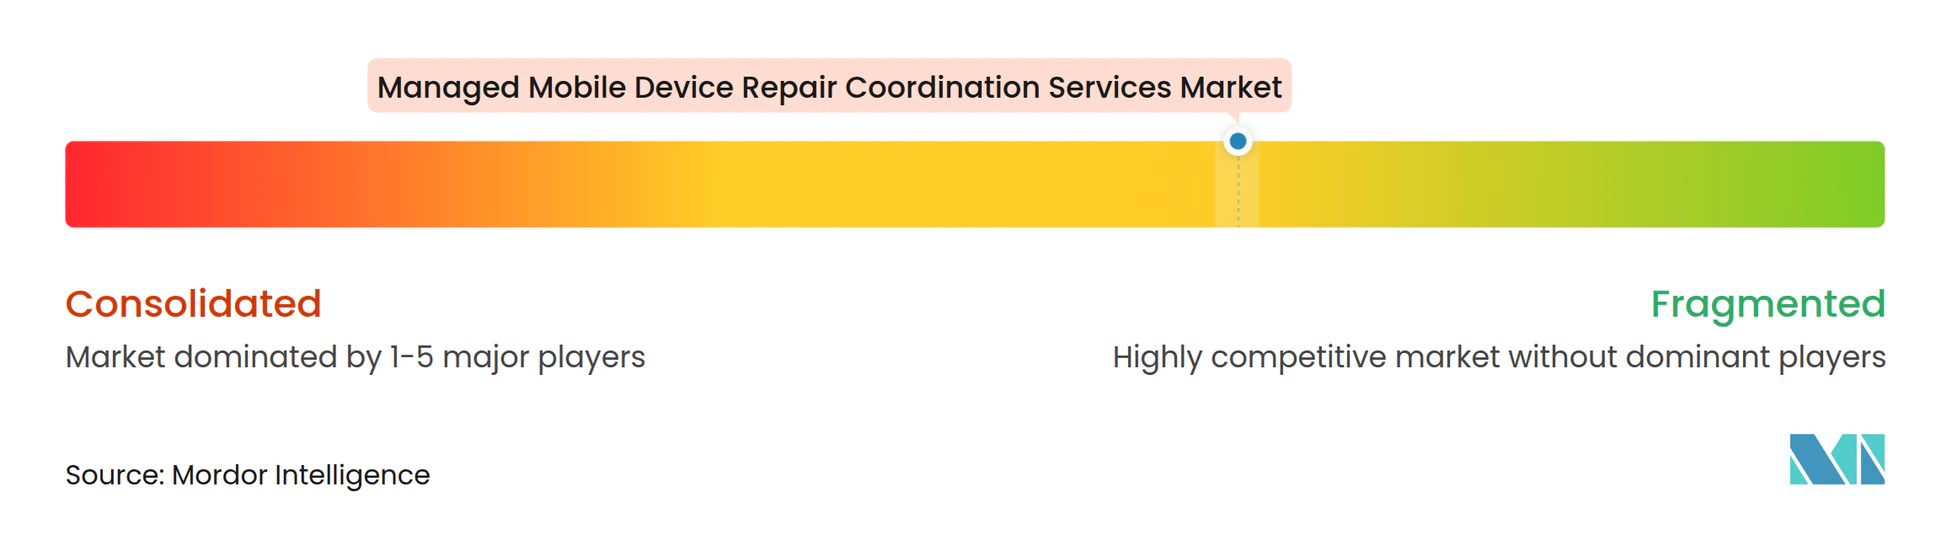
The managed mobile device repair coordination services market is moderately fragmented, with no provider holding more than a mid-teens share of global revenue. Asurion and Likewize have broad geographic and service coverage and compete for carrier and enterprise accounts. Their integrated offers can include protection, repair, trade-in, and lifecycle management. Servify, B2X Care Solutions, and Reconext compete through OEM authorization depth and software-led coordination. The competitive landscape, therefore, includes both full-lifecycle providers and specialists focused on repair operations.
Asurion announced plans to acquire Domestic and General in December 2025 for GBP 2.1 billion (USD 2.65 billion). The transaction extended Asurion’s repair coordination presence into white goods and connected home electronics across European channels. Likewize completed its acquisition of Speedperform in April 2025 to integrate Microsoft GenAI capabilities into device support workflows. These moves show how established providers are adding adjacent capabilities and software tools. They also increase the investment needed for smaller providers to match the coverage and workflow depth of large rivals.
Technology is central to contract retention in the managed mobile device repair coordination services market. Providers with real-time repair status, service-level alerts, and documented data sanitization can offer stronger operational control than depot-only operators. Asurion deployed an AI-powered technician-routing engine in 2025 to match field experts with in-home service appointments according to skill set. Security controls, authorized service credentials, and multi-OEM coverage are becoming basic requirements in regulated enterprise accounts. Expansion in Asia-Pacific, the Middle East, and Africa remains an important opportunity because managed service adoption is lower than enterprise device fleet size would suggest.
Managed Mobile Device Repair Coordination Services Industry Leaders
-
Asurion, LLC
-
Communications Test Design, Inc.
-
Reconext, Inc.
-
B2X Care Solutions GmbH
-
Tangoe, Inc.
- *Disclaimer: Major Players sorted in no particular order
Managed Mobile Device Repair Coordination Services Market Companies Covered in this Report
- Asurion, LLC
- Communications Test Design, Inc.
- Reconext, Inc.
- B2X Care Solutions GmbH
- Servify Tech, Inc.
- Tangoe, Inc.
- HOBI International, Inc.
- Mendtronix, Inc.
- Encompass Supply Chain Solutions, Inc.
- Worldwide TechServices, LLC
- Likewize Corp.
- Sims Lifecycle Services, Inc.
- TES-AMM (Singapore) Pte. Ltd.
- Brightstar Corp.
- Everphone GmbH
- Workwize B.V.
- Mobile Klinik Professional Corporation
- uBreakiFix by Asurion
- CPR Cell Phone Repair
- Batteries Plus, LLC
- Puls Technologies, Inc.
- iCracked, Inc.
- Quest International, Inc.
- Elecfix Repair Services
Recent Industry Developments in Managed Mobile Device Repair Coordination Services Market
- September 2026: Texas's House Bill 2963 (HB 2963) took effect on September 1, introducing new requirements applicable to smartphones, tablets, and laptops priced above USD 50. The legislation represents a regulatory development affecting consumer electronic devices sold in Texas, with implications for manufacturers, retailers, and distributors that must assess their product offerings and compliance obligations under the new law.
- May 2026: Asurion announced the planned acquisition of Domestic and General, one of the largest appliance-care providers across the United Kingdom and Europe, for GBP 2.1 billion (USD 2.65 billion). The deal extended Asurion's repair coordination reach into white goods and connected home electronics across the European carrier and enterprise channel.
- April 2026: Servify reported achieving profitability in FY2026 ahead of a planned IPO, following FY2025 operating revenue of INR 781 crore (USD 93.5 million), in FY2024, with the United States emerging as its largest market.
- February 2026: B2M Solutions released its 7th Annual State of Enterprise Mobility report, documenting that 81% of frontline workers across the United States, United Kingdom, France, Germany, Italy, and Spain experience monthly mobile failures, with cumulative annual productivity losses estimated at up to USD 7 billion, reinforcing the enterprise financial case for proactive managed repair coordination.
Global Managed Mobile Device Repair Coordination Services Market Report Scope
The managed mobile device repair coordination services market refers to the industry that provides centralized platforms and services to coordinate, track, and manage mobile device repair and maintenance across organizations. These services streamline the repair process by connecting enterprises with repair providers, managing service requests, facilitating device diagnostics and repair routing, tracking repair status, coordinating replacement parts, and overseeing service-level agreements (SLAs) to minimize device downtime and maintain operational continuity.
The Managed Mobile Device Repair Coordination Services Report is Segmented by Device Type (Smartphones, Tablets, Rugged Mobile Computers, Wearable Devices, and Multi-Device Enterprise Fleets), Repair Type (Screen and Display Repair, Battery Repair and Replacement, Charging Port and Connector Repair, Camera, Sensor, and Audio Component Repair, Software, Firmware, and Configuration Remediation, and Other Repair Types), Coordination Platform Deployment (Cloud-Based Platforms, On-Premise Platforms, and Hybrid Platform Environments), Organization Size (Large Enterprises and Small and Medium-Sized Enterprises), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Smartphones |
| Tablets |
| Rugged Mobile Computers |
| Wearable Devices |
| Multi-Device Enterprise Fleets |
| Screen and Display Repair |
| Battery Repair and Replacement |
| Charging Port and Connector Repair |
| Camera, Sensor, and Audio Component Repair |
| Software, Firmware, and Configuration Remediation |
| Other Repair Types |
| Cloud-Based Platforms |
| On-Premise Platforms |
| Hybrid Platform Environments |
| Large Enterprises |
| Small and Medium-Sized Enterprises |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Colombia | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Australia | |
| Southeast Asia | |
| Rest of Asia-Pacific | |
| Middle East | United Arab Emirates |
| Saudi Arabia | |
| Turkey | |
| Rest of Middle East | |
| Africa | South Africa |
| Egypt | |
| Nigeria | |
| Kenya | |
| Rest of Africa |
| By Device Type | Smartphones | |
| Tablets | ||
| Rugged Mobile Computers | ||
| Wearable Devices | ||
| Multi-Device Enterprise Fleets | ||
| By Repair Type | Screen and Display Repair | |
| Battery Repair and Replacement | ||
| Charging Port and Connector Repair | ||
| Camera, Sensor, and Audio Component Repair | ||
| Software, Firmware, and Configuration Remediation | ||
| Other Repair Types | ||
| By Coordination Platform Deployment | Cloud-Based Platforms | |
| On-Premise Platforms | ||
| Hybrid Platform Environments | ||
| By Organization Size | Large Enterprises | |
| Small and Medium-Sized Enterprises | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Colombia | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Australia | ||
| Southeast Asia | ||
| Rest of Asia-Pacific | ||
| Middle East | United Arab Emirates | |
| Saudi Arabia | ||
| Turkey | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Egypt | ||
| Nigeria | ||
| Kenya | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the size of the managed mobile device repair coordination services market?
The market is projected to expand from USD 4.42 billion in 2026 and USD 4.73 billion in 2027 to USD 7.01 billion by 2032, at an 8.18% CAGR.
What is driving demand for managed mobile device repair coordination services?
Enterprise fleet use, the cost of downtime, Device-as-a-Service adoption, and right-to-repair rules are supporting demand for structured repair programs.
Which device type leads managed repair coordination demand?
Smartphones led device-type value with a 59.84% share in 2026, while multi-device enterprise fleets are projected to expand at a 9.18% CAGR through 2032.
Which repair service is expected to expand fastest?
Data recovery and secure data handling is projected to expand at a 9.56% CAGR through 2032 as enterprises place greater emphasis on compliant device handoffs.
Why are cloud repair coordination platforms widely used?
Cloud platforms held 71.89% of deployment value in 2026 because they support centralized reporting, real-time service monitoring, and connections with distributed repair providers.
Which region is expected to expand fastest for managed repair coordination services?
Asia-Pacific is projected to expand at a 9.21% CAGR through 2032, supported by enterprise fleet expansion and developing device protection infrastructure.