
Managed Antivirus and Antimalware Services Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Market Size (2027) | USD 2.72 Billion |
| Market Size (2032) | USD 5.84 Billion |
| Growth Rate (2027 - 2032) | 16.55 % |
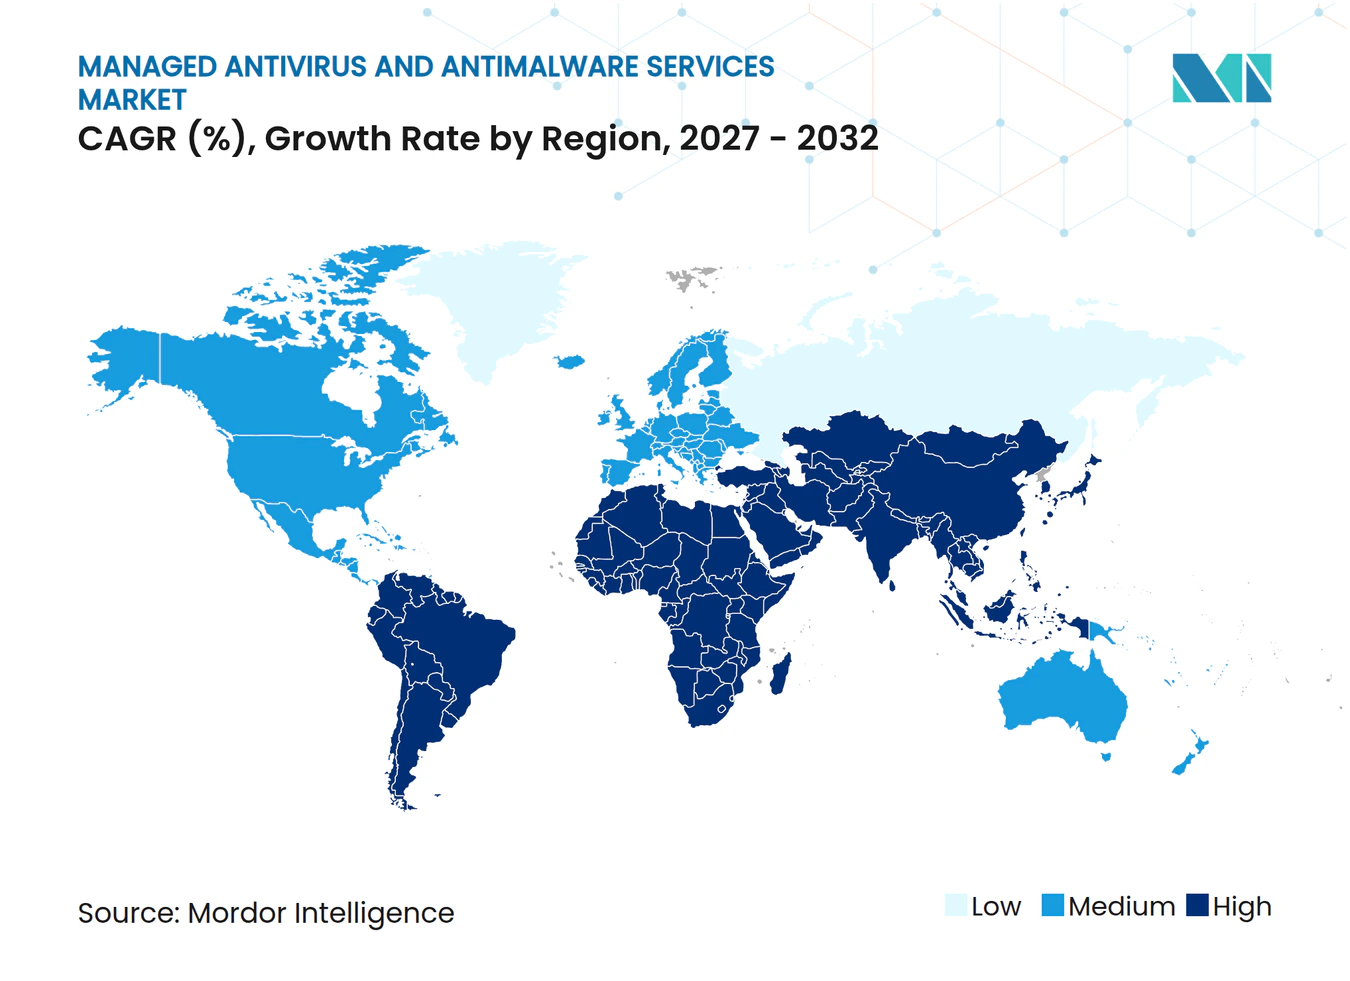
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Managed Antivirus and Antimalware Services Market Analysis by Mordor Intelligence
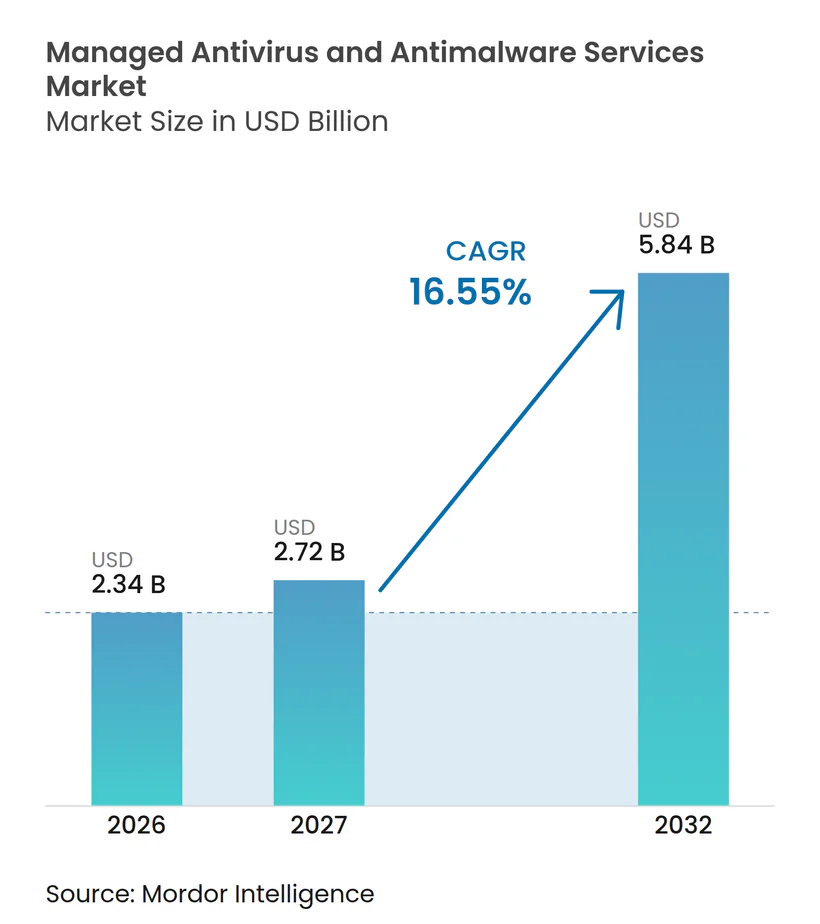
The Managed Antivirus and Antimalware Services Market size is valued at USD 2.34 billion in 2026 and is forecast to reach USD 5.84 billion by 2032, growing at a CAGR of 16.55% over 2027-2032. The Managed Antivirus and Antimalware Services Market is expanding as ransomware groups increasingly rely on data theft and techniques that avoid leaving conventional malware files on endpoints. This shift makes continuous monitoring more important than periodic signature scanning for organizations with distributed devices and cloud workloads. A persistent shortage of experienced security staff also makes externally managed 24/7 coverage more practical for many buyers. Providers are responding by combining endpoint protection, detection, and response, threat hunting, and incident response into a single subscription. Data residency rules, hybrid infrastructure, and price sensitivity among smaller organizations remain important limits on adoption and service margins.
Key Report Takeaways
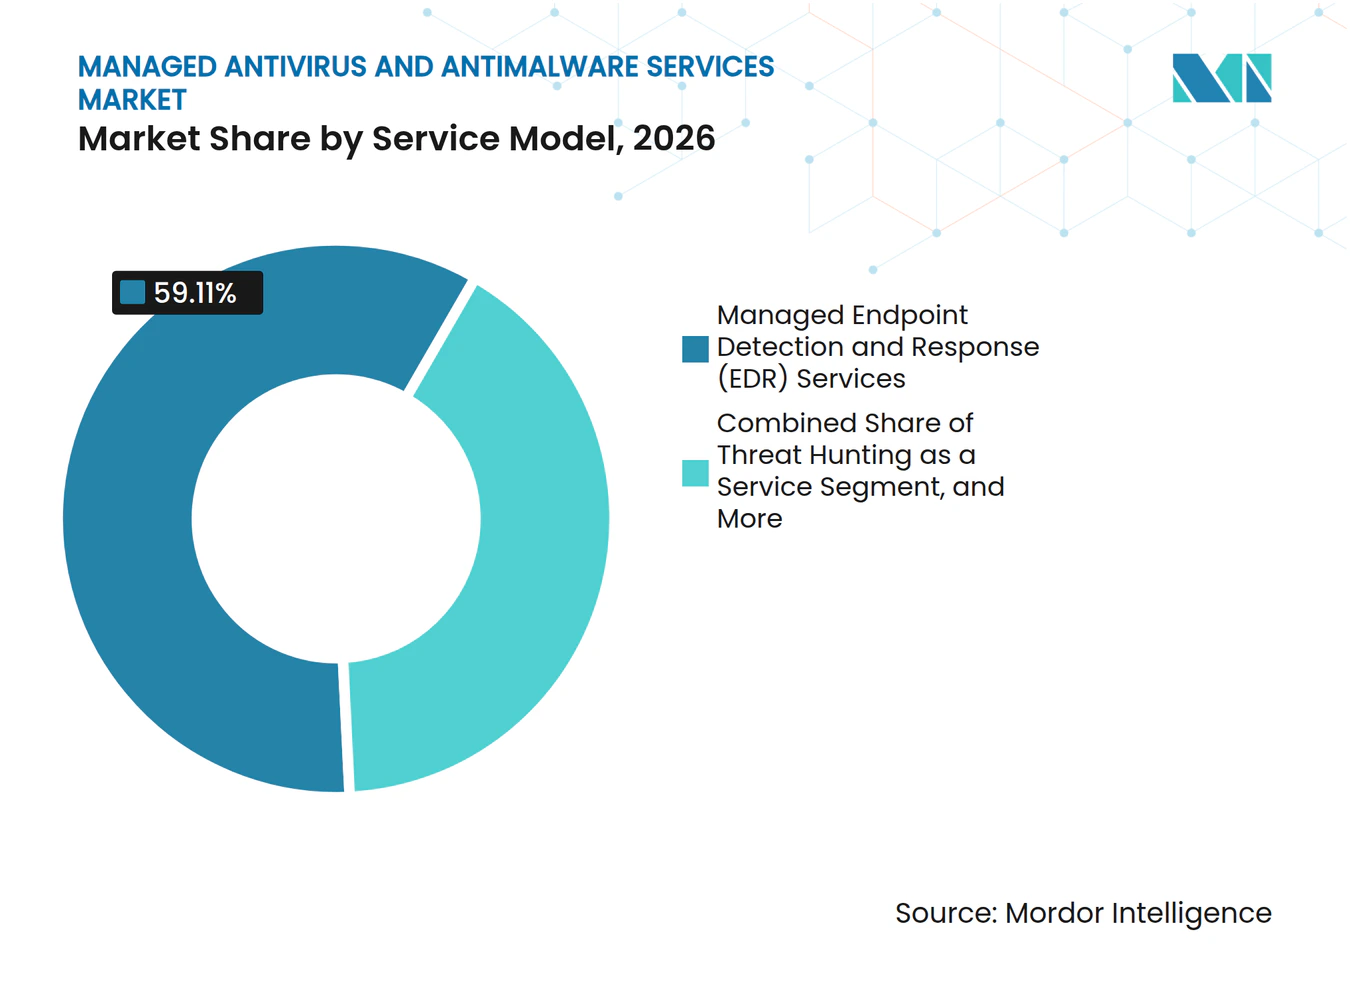
- By service model, Managed Endpoint Detection and Response Services held 59.11% of the Managed Antivirus and Antimalware Services Market share in 2026, while Threat Hunting as a Service is projected to expand at a 17.71% CAGR through 2032.
- By deployment model, public cloud held 66.14% of the Managed Antivirus and Antimalware Services Market share in 2026, while hybrid cloud is projected to expand at an 18.02% CAGR through 2032.
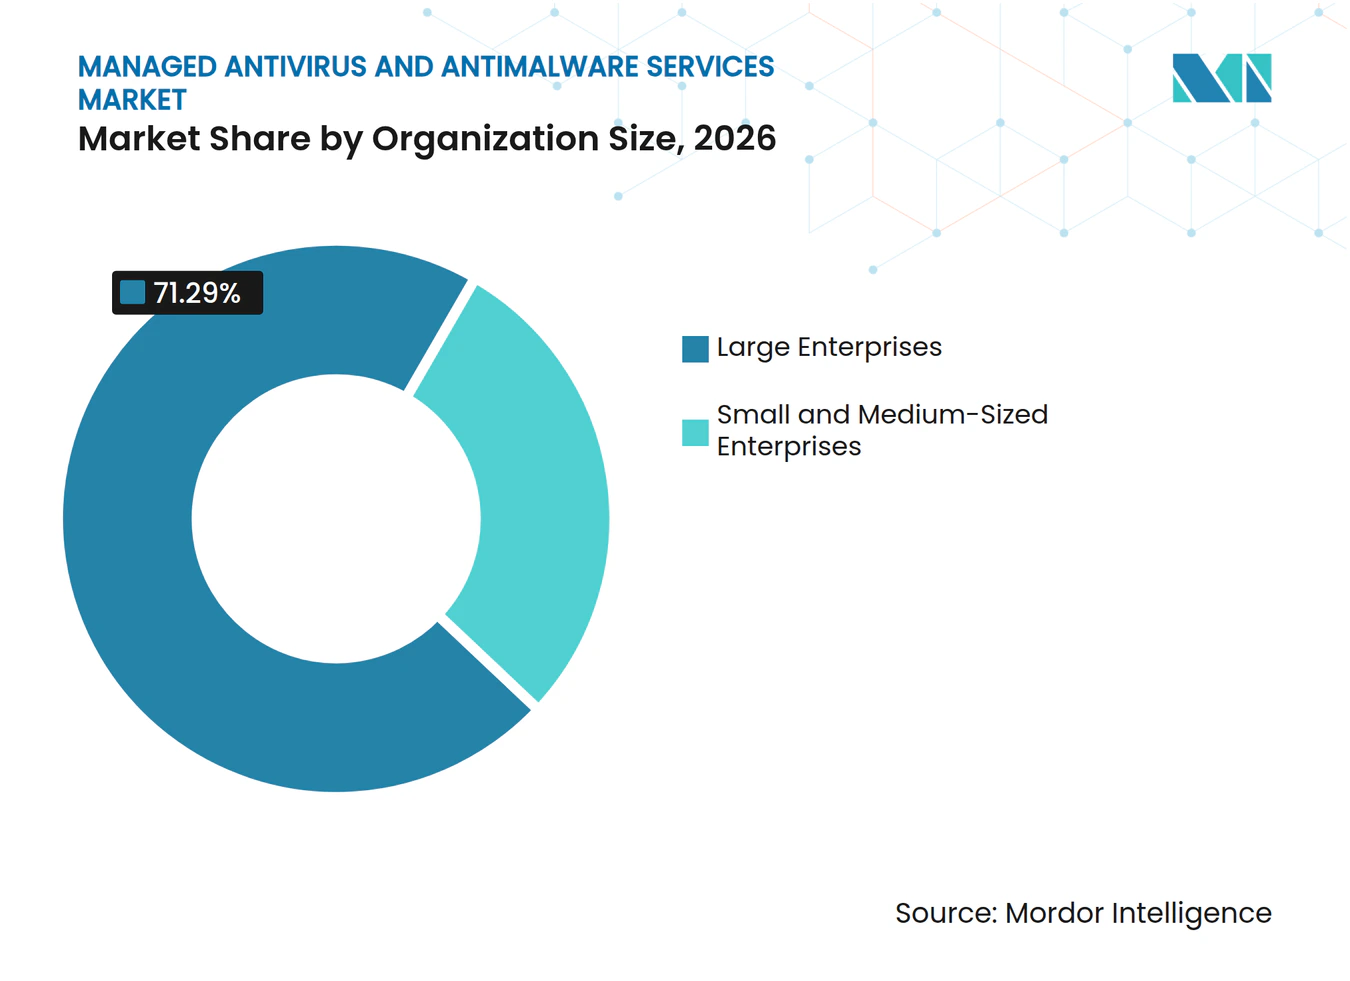
- By organization size, large enterprises held 71.29% of the Managed Antivirus and Antimalware Services Market revenue in 2026, while small and medium-sized enterprises are projected to expand at an 18.32% CAGR through 2032.
- By end-user industry, BFSI accounted for 29.33% of the Managed Antivirus and Antimalware Services Market revenue in 2026, while government and public administration is projected to expand at a 17.05% CAGR through 2032.
- By geography, North America held 37.16% of revenue in 2026, while Asia-Pacific is projected to expand at a 17.33% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Managed Antivirus and Antimalware Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating Ransomware and Fileless Malware Activity | +4.5% | Global | Short term (≤ 2 years) |
| Cybersecurity Talent Shortages and Demand for 24/7 Coverage | +3.8% | Global | Long term (≥ 4 years) |
| AI-Enabled Detection, XDR Correlation, and Automated Containment | +3.2% | North America and Europe, with spillover to Asia-Pacific | Medium term (2-4 years) |
| Regulatory Requirements for Continuous Monitoring and Incident Response | +2.5% | Europe and North America | Medium term (2-4 years) |
| Expansion of Remote Work and Bring Your Own Device Exposure | +1.8% | Global | Short term (≤ 2 years) |
| Insurance and Customer Assurance Requirements for Measurable Endpoint Controls | +1.4% | North America and Europe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Escalating Ransomware and Fileless Malware Activity
The Managed Antivirus and Antimalware Services Market is driven by attacks that prioritize persistent data theft over encryption alone. Google Cloud reported that 77% of ransomware intrusions in 2025 involved suspected or confirmed data theft, compared with 57% in 2024. Attackers increasingly use legitimate tools, including Rclone, WinRAR, and FTP clients, to make exfiltration activity resemble normal network traffic. Google Cloud also found that malware-free techniques accounted for 82% of attacker detections in 2025, up from 51% in 2020. Zscaler reported that ransomware data theft rose by more than 275% year over year to 896.2 terabytes in its 2026 report, while the average ransom payment increased 5.3% to USD 431,995. These conditions favor continuous behavioral monitoring and proactive investigation because signature updates cannot identify every attack that leaves no malicious file on disk.
Cybersecurity Talent Shortages and Demand for 24/7 Coverage
The Managed Antivirus and Antimalware Services Market also benefits from a shortage of specialist security skills. ISC2 found that 59% of organizations reported critical or significant cybersecurity skills needs in 2025, up 15 percentage points from 2024. The same study found that 95% of organizations had at least 1 active skills gap. Budget constraints prevented 33% of respondents from adequately staffing their cybersecurity teams, while 72% agreed that staff reductions significantly increase the risk of breaches. Internal 24/7 security operations require six to eight experienced analysts to maintain shift coverage, a staffing level many midmarket organizations cannot support. Outsourcing is already established, with 20% of respondents reporting outsourced cybersecurity work and 19% using third-party security service providers.
AI-Enabled Detection, XDR Correlation, and Automated Containment
AI-enabled operations are changing the service model from manual alert review toward automated investigation and containment. Palo Alto Networks introduced Unit 42 Managed XSIAM 2.0 in February 2026 and reported that more than 60% of Cortex XSIAM customers reduced median response times from days or weeks to minutes.[1] The company also cited a USD 85 million contract with a major U.S. telecommunications company as its largest contract to date. CrowdStrike released its Fall 2025 Agentic SOC offering with 7 AI agents for security workflows, including threat hunting, intelligence, and managed detection and response. XDR correlation brings endpoint, network, cloud, and identity telemetry into a shared detection process, reducing the fragmentation that increases operating costs in multi-environment deployments. Providers that show faster, controlled responses can win larger enterprise contracts because buyers need measurable evidence that security operations can act when an incident occurs.
Regulatory Requirements for Continuous Monitoring and Incident Response
The Managed Antivirus and Antimalware Services Market gains support from regulations that require organizations to document monitoring and incident response. ENISA published NIS2 Technical Implementation Guidance in June 2025 that addresses risk management, incident handling, and ongoing security monitoring. The guidance maps evidence requirements to ISO/IEC 27001:2022 and NIST Cybersecurity Framework 2.0. The Digital Operational Resilience Act became applicable in January 2025 and requires financial entities to manage third-party ICT risk and classify incidents in a structured manner. Organizations without an internal security operations center can use managed services to obtain continuous monitoring and audit-ready response records. This compliance need can maintain demand in regulated sectors even when short-term IT budgets are constrained.
Restraints Impact Analysis of Managed Antivirus and Antimalware Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Privacy, Data Residency, and Telemetry Sovereignty Concerns | -2.8% | Global, concentrated in the European Union and Asia-Pacific core | Medium term (2-4 years) |
| Multi-Cloud and Legacy Endpoint Integration Complexity | -2.3% | Global | Long term (≥ 4 years) |
| False Positives and Inconsistent Response Authorization | -1.6% | Global | Short term (≤ 2 years) |
| Price Sensitivity and Per-Endpoint Margin Pressure Among SMEs | -1.2% | Global, concentrated in South America and the Middle East and Africa | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Privacy, Data Residency, and Telemetry Sovereignty Concerns
Managed services require behavioral signals, memory artifacts, authentication events, and network logs to be sent to centralized or cloud-based security operations centers. This creates tension with national data residency laws and internal sovereignty policies. Bitdefender found that 76% of 1,200 surveyed cybersecurity managers and practitioners would likely switch vendors due to data sovereignty, jurisdictional, or foreign government access concerns. Financial services, critical infrastructure, and government organizations may be unable to route endpoint telemetry through nonresident cloud infrastructure. China, India, and several Southeast Asian markets add separate localization requirements that make standard multi-tenant delivery more difficult. These constraints can exclude otherwise capable providers from regulated contracts unless they offer local infrastructure, administration, and accountable operating entities.
Multi-Cloud and Legacy Endpoint Integration Complexity
The Managed Antivirus and Antimalware Services Market must contend with customer environments built from diverse operating systems, proprietary industrial devices, on-premises applications, and legacy security agents. These systems were often not designed to send centralized telemetry to a managed provider. The input research identifies 78% of enterprises operating hybrid or multi-cloud environments, in which each environment requires a distinct agent architecture and detection logic. Fragmentation raises onboarding costs, delays the delivery of service value, and creates gaps that attackers can exploit. Fortinet updated FortiEndpoint in March 2026 to consolidate ZTNA, SASE, EPP, EDR, and DLP in 1 agent, directly addressing agent sprawl in hybrid environments. Manufacturing, energy, and healthcare organizations also need to connect operational technology with corporate IT, and their implementation timelines can extend for quarters.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Managed Antivirus and Antimalware Services Market Segment Analysis
By Service Model:
Managed EDR Leads While Threat Hunting Gains MomentumManaged Endpoint Detection and Response Services held 59.11% of revenue in 2026. The segment leads because organizations are moving from periodic signature scans to continuous behavioral monitoring across their endpoint estates. Cyber insurance requirements are increasing the value of documented EDR coverage across managed endpoints. Managed EDR also provides buyers with 24/7 coverage without requiring a dedicated internal security team. Managed anti-malware and antivirus services remain relevant to buyers with limited regulatory exposure or tighter budgets. Ransomware recovery and incident response are also purchased as standalone retainers by BFSI and healthcare organizations that need documented response capacity. Managed vulnerability management and managed identity threat detection and response are increasingly included in full-service contracts rather than sold as isolated services.
Threat Hunting as a Service is projected to expand at a 17.71% CAGR through 2032, the highest rate within the service model segmentation. The Managed Antivirus and Antimalware Services Market benefits from this transition because data-exfiltration-led extortion cannot be addressed through passive detection alone. Arctic Wolf reported that ransomware accounted for 44% of its incident response engagements in the prior year, before its October 2026 Aurora Adaptive Threat Protection launch. The company also reported that credential-harvesting malware compromised an estimated 1.7 billion credentials across 7.4 million infected devices. SentinelOne introduced Wayfinder Threat Detection and Response with Google Cloud in November 2025, combining AI-supported threat hunting, human analyst oversight, and Google Threat Intelligence. The Managed Antivirus and Antimalware Services Market is therefore moving toward services that blend automated analysis with specialist review.



By Deployment Model:
Public Cloud Leads While Hybrid Deployments Expand FasterPublic cloud held 66.14% of revenue in 2026. Its lead reflects simpler operations, elastic scalability, and lower infrastructure requirements for multi-tenant managed security delivery. Cloud-native platforms allow providers to apply common threat intelligence, issue detection updates quickly, and maintain consistent service levels across large customer groups. These capabilities can reduce service pricing and speed up client onboarding. Private cloud retains a defined role in financial services, defense, and government, where data residency rules restrict cross-border telemetry flows. Sovereignty requirements are supporting private cloud demand, although the volume remains below that of public cloud deployments. The public cloud model remains attractive for buyers who accept centralized data processing and need service capacity that scales quickly.
Hybrid cloud is projected to grow at an 18.02% CAGR through 2032, making it the fastest-growing deployment model. The Managed Antivirus and Antimalware Services Market size for hybrid cloud is supported by enterprise estates that operate legacy infrastructure, private cloud, and public cloud in parallel. Industrial manufacturers, energy utilities, and healthcare providers face particularly complex requirements because some operational technology environments cannot send telemetry to public cloud platforms. Fortinet enhanced FortiGuard SOC-as-a-Service in March 2026 with FortiNDR network detection telemetry and FortiCNAPP cloud workload telemetry.[2] This development reflects the need for visibility across on-premises endpoints, cloud workloads, and networks. A single managed relationship across these environments can lower administrative burden for organizations that otherwise manage several security vendors.
By Organization Size:
Large Enterprises Generate Revenue While SMEs Expand FasterLarge enterprises held 71.29% of the organization-size segment in 2026. Their position reflects earlier adoption of managed EDR and MDR, larger endpoint estates, and strict compliance obligations that make documented security coverage necessary. Large buyers favor contracts that combine endpoint protection, EDR, threat hunting, and incident response with 1 provider. This contract structure supports higher recurring revenue and strengthens concentration among established platforms. Palo Alto Networks reported that its Cortex XSIAM platform had approximately 470 enterprise customers spending more than USD 1 million in average annual recurring revenue as of late 2025. The Managed Antivirus and Antimalware Services Market serves these buyers through services that provide clear accountability for detection and response outcomes. Large enterprise demand remains central to provider revenue as customer acquisition expands into smaller organizations.
Small and medium-sized enterprises are projected to grow at an 18.32% CAGR through 2032. Their growth is driven by ransomware exposure and the shift from separate security tools to per-endpoint managed subscriptions. Smaller organizations increasingly need structured protection because their threat exposure can be significant even when their security teams are limited. SentinelOne launched Managed AI Defense through the Pax8 marketplace in September 2025, combining EDR, Purple AI, managed threat hunting, and vulnerability management for managed service providers serving smaller buyers. Blue Mantis also introduced Blue Mantis Protect for midmarket organizations in September 2025, using AI-enabled detection across 9 integrated security solutions. The Managed Antivirus and Antimalware Services Market addresses an underserved group that needs structured coverage but has limited ability to maintain a large internal security team. Price sensitivity and per-endpoint margins remain constraints, particularly in lower-income regions and smaller customer accounts.

By End-User Industry:
BFSI Leads Revenue While Government Demand AcceleratesBFSI held 29.33% of end-user revenue in 2026. The BFSI sector’s high-value data, mandatory controls, and exposure to financially motivated attackers underscore its role. Financial organizations need continuous coverage and documented response processes to satisfy audit, insurance, and operational resilience needs. The Italian banking sector’s CERTFin report estimated the total cost of cybersecurity ownership at USD 550 million, representing 8% of the total IT budget. Healthcare, IT and telecommunications, manufacturing, retail and e-commerce, and energy and utilities have different requirements, including OT monitoring, carrier-grade coverage, and sector-specific controls. This range of requirements spreads end-user demand across multiple verticals while keeping BFSI at the center of current revenue.
Government and public administration is projected to grow at a 17.05% CAGR through 2032. Public agencies are treating endpoint protection as a critical service function due to nation-state activity and more specific public procurement requirements. Proximus NXT won a managed cybersecurity services framework with the Belgian Federal Government in February 2025, covering 70,000 end users across federal public services. The contract was expected to exceed USD 110 million, over 7 years. Research by the Data Security Council of India found that India’s BFSI entities experience 1.6 times as many cyberattacks per organization as their global peers. Reported cases increased from 1.4 million in 2021 to 2.9 million in 2025, reinforcing demand across government and BFSI in Asia-Pacific.
Geography Analysis
North America Managed Antivirus and Antimalware Services Market
North America held 37.16% of revenue in 2026. The Managed Antivirus and Antimalware Services Market is led regionally by the United States, which has a dense base of MDR specialists and platform vendors, as well as a developed cyber insurance market. Federal endpoint detection and response measures associated with Executive Order 14028 provide a procurement reference point for public-sector buyers. Canada and Mexico add demand linked to financial services and healthcare requirements. The Managed Antivirus and Antimalware Services Market benefits from North America’s earlier deployment of AI-supported security operations.
Europe Managed Antivirus and Antimalware Services Market
Europe is expanding its compliance obligations, creating demand for managed monitoring in covered sectors. The Managed Antivirus and Antimalware Services Market is shaped by different national implementations of NIS2, which favor providers capable of operating across multiple countries. Bitdefender expanded its European Sovereign Acceleration Program in July 2026 with EU-resident MDR services delivered from a Romanian security operations center. The offer keeps customer telemetry, investigation, and response within the European Union. Germany, the United Kingdom, France, and Italy remain the larger European national markets, while Sophos completed its USD 859 million acquisition of Secureworks in February 2025.[3] Growing concern over ransomware targeting critical infrastructure is further encouraging enterprises to adopt managed endpoint protection services.
APAC, South America and MEA Managed Antivirus and Antimalware Services Market
Asia-Pacific is projected to expand at a 17.33% CAGR through 2032, the fastest regional rate. The Managed Antivirus and Antimalware Services Market is supported in the region by cloud adoption, enterprise digitization, and cybersecurity frameworks in India, South Korea, Japan, China, and Australia. Punjab National Bank disclosed a cybersecurity allocation of USD 73.5 million to USD 84 million for its current financial year. South America, the Middle East, and Africa remain smaller revenue areas, with Brazil, Saudi Arabia, the United Arab Emirates, South Africa, and Nigeria serving as key demand centers.
Competitive Landscape
Market Concentration
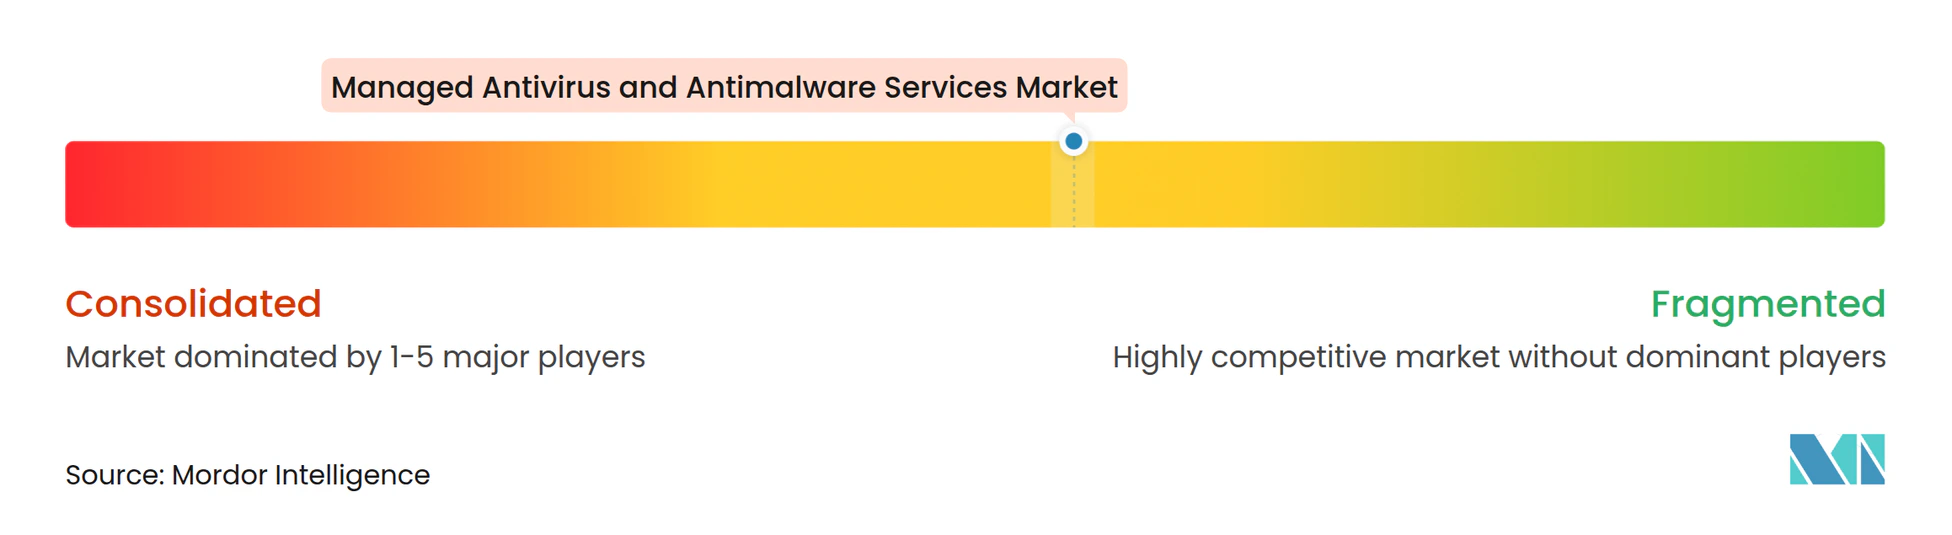
The Managed Antivirus and Antimalware Services Market is moderately concentrated, with CrowdStrike, Palo Alto Networks, Sophos, SentinelOne, and Fortinet competing alongside Arctic Wolf, Deepwatch, eSentire, Red Canary, and Expel. Leading providers combine endpoint protection, EDR, XDR, threat hunting, and incident response into integrated service platforms. This approach reduces reliance on point products and increases the value of a single provider relationship. CrowdStrike’s Fall 2025 release introduced 7 AI agents across its Agentic SOC offering. Fortinet expanded its security operations offering in March 2026 with unified SOC features, agentic AI, and broader endpoint functionality.
The Managed Antivirus and Antimalware Services Market has opportunities in sovereign infrastructure, operational technology security, and smaller organizations that still lack economical managed coverage. CrowdStrike expanded its Schwarz Digits partnership in July 2026 to make Falcon available on STACKIT for European enterprise customers. Arctic Wolf introduced Aurora Adaptive Threat Protection in October 2026 using a causal graph of endpoint processes, files, and API calls. These moves show that local deployment choices and automated response capability are significant points of competition. BYOD and remote work continue to expand the endpoint estate that providers can serve.
Acquisitions are a major route for vendors to add threat intelligence, telemetry management, browser security, and identity protection. CrowdStrike announced agreements to acquire Onum in August 2025, Pangea in September 2025, SGNL in January 2026, and Seraphic Security in January 2026.[4] Sophos acquired Secureworks in February 2025 and integrated Sophos Endpoint with Secureworks Taegis MDR and XDR across subscriptions in October 2025. Wider platforms can raise switching costs, while specialized firms seek positions through focused delivery and simpler pricing.
Managed Antivirus and Antimalware Services Industry Leaders
-
Sophos Limited
-
Trend Micro Incorporated
-
Fortinet, Inc.
-
Check Point Software Technologies Ltd.
-
Palo Alto Networks, Inc.
- *Disclaimer: Major Players sorted in no particular order
Managed Antivirus and Antimalware Services Market Companies Covered in this Report
- Arctic Wolf Networks, Inc.
- Bitdefender SRL
- Blackpoint Cyber, Inc.
- Check Point Software Technologies Ltd.
- CrowdStrike Holdings, Inc.
- Cybereason Inc.
- Cynet Security Ltd.
- Deepwatch, Inc.
- ESET, spol. s r.o.
- eSentire, Inc.
- Expel, Inc.
- Fortinet, Inc.
- Kaspersky Lab AO
- Malwarebytes Inc.
- Palo Alto Networks, Inc.
- Rapid7, Inc.
- Red Canary, LLC
- SentinelOne, Inc.
- Sophos Limited
- Trend Micro Incorporated
Recent Industry Developments in Managed Antivirus and Antimalware Services Market
- October 2026: Arctic Wolf unveiled Aurora Adaptive Threat Protection at its 2026 Security Operations Summit, introducing an AI-driven, intent-based endpoint security solution that uses a causal graph of endpoint processes, files, and API calls to predict and disrupt ransomware and credential-theft attacks before they materialize. The product is backed by the Aurora Superintelligence Platform, which processes more than 10 trillion security events weekly across more than 11,000 customers, and is designed to complement, not replace, existing EPP and EDR solutions.
- July 2026: CrowdStrike and Schwarz Digits announced an expanded strategic partnership to deliver sovereign cybersecurity across Europe, including CrowdStrike's definitive agreement to acquire XM Cyber's intellectual property for USD 600 million and the deployment of the Falcon platform on STACKIT, Schwarz Digits' sovereign cloud, enabling European enterprises to satisfy DORA and NIS2 resident-infrastructure requirements.
- July 2026: Bitdefender expanded its European Sovereign Acceleration Program to include fully EU-resident MDR services delivered by a SOC in Romania, ensuring that all customer telemetry, incident investigation, and response remain within EU boundaries. The announcement directly responds to the 76% of surveyed cybersecurity managers who indicated readiness to switch vendors due to data sovereignty concerns.
- March 2026: Fortinet announced the preview of FortiSOC, a cloud-delivered unified SOC platform, and enhanced FortiGuard SOC-as-a-Service with multi-vendor telemetry, FortiNDR, and FortiCNAPP cloud workload visibility at Fortinet Accelerate 2026. FortiEndpoint was simultaneously updated to consolidate ZTNA, SASE, EPP, EDR, and DLP into a single agent, directly addressing agent sprawl in hybrid managed environments.
Global Managed Antivirus and Antimalware Services Market Report Scope
The Managed Antivirus and Antimalware Services Market comprises outsourced cybersecurity services that provide continuous monitoring, detection, prevention, investigation, containment, and remediation of malware, ransomware, fileless threats, and endpoint-based cyberattacks across enterprise environments. The market includes managed antivirus operations, managed endpoint detection and response (EDR), threat hunting, ransomware recovery, incident response, and related monitoring and support services delivered through cloud-based or hybrid security operations models.
The Managed Antivirus and Antimalware Services Market Report is Segmented by Service Model (Managed Anti-Malware and Antivirus Services, Managed Endpoint Detection and Response [EDR] Services, Threat Hunting as a Service, Ransomware Recovery and Incident Response Services, and Other Service Models), Deployment Model (Public Cloud, Private Cloud, and Hybrid Cloud), Organization Size (Small and Medium-Sized Enterprises, and Large Enterprises), End-User Industry (Banking, Financial Services, and Insurance [BFSI], Government and Public Administration, Healthcare and Life Sciences, IT and Telecommunication, Industrial Manufacturing, Retail and E-commerce, Energy and Utilities, and Other End-User Industries), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Managed Anti-Malware and Antivirus Services |
| Managed Endpoint Detection and Response (EDR) Services |
| Threat Hunting as a Service |
| Ransomware Recovery and Incident Response Services |
| Other Service Models |
| Public Cloud |
| Private Cloud |
| Hybrid Cloud |
| Small and Medium-Sized Enterprises |
| Large Enterprises |
| Banking, Financial Services, and Insurance (BFSI) |
| Government and Public Administration |
| Healthcare and Life Sciences |
| IT and Telecommunication |
| Industrial Manufacturing |
| Retail and E-commerce |
| Energy and Utilities |
| Other End-User Industries |
| North America | United States |
| Canada | |
| Mexico | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Rest of Africa |
| By Service Model | Managed Anti-Malware and Antivirus Services | |
| Managed Endpoint Detection and Response (EDR) Services | ||
| Threat Hunting as a Service | ||
| Ransomware Recovery and Incident Response Services | ||
| Other Service Models | ||
| By Deployment Model | Public Cloud | |
| Private Cloud | ||
| Hybrid Cloud | ||
| By Organization Size | Small and Medium-Sized Enterprises | |
| Large Enterprises | ||
| By End-User Industry | Banking, Financial Services, and Insurance (BFSI) | |
| Government and Public Administration | ||
| Healthcare and Life Sciences | ||
| IT and Telecommunication | ||
| Industrial Manufacturing | ||
| Retail and E-commerce | ||
| Energy and Utilities | ||
| Other End-User Industries | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East | Saudi Arabia | |
| United Arab Emirates | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the Managed Antivirus and Antimalware Services Market size?
The Managed Antivirus and Antimalware Services Market is valued at USD 2.34 billion in 2026 and is forecast to reach USD 5.84 billion by 2032, growing at a 16.55% CAGR.
What is driving demand for managed antivirus and antimalware services?
The Managed Antivirus and Antimalware Services Market is supported by ransomware data theft, fileless attack methods, cybersecurity skills shortages, and compliance requirements.
Which service model has the largest share?
Managed Endpoint Detection and Response Services held 59.11% of revenue in 2026 because organizations require continuous behavioral monitoring.
Which deployment model is growing fastest?
Hybrid cloud is projected to grow at an 18.02% CAGR through 2032 as organizations secure legacy infrastructure, private cloud, and public cloud environments together.
Which organizations are expected to adopt these services fastest?
Small and medium-sized enterprises are projected to grow at an 18.32% CAGR through 2032 as they move toward per-endpoint managed subscriptions.
Which region is expected to grow fastest?
The Managed Antivirus and Antimalware Services Market is expected to grow fastest in Asia-Pacific, at a 17.33% CAGR through 2032.