
Market Overview
| Study Period | 2020 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 0.34 Billion |
| Market Size (2027) | USD 0.37 Billion |
| Market Size (2032) | USD 0.57 Billion |
| Growth Rate (2027 - 2032) | 9.11 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Japan Automotive Adaptive Lighting System Market Analysis by Mordor Intelligence
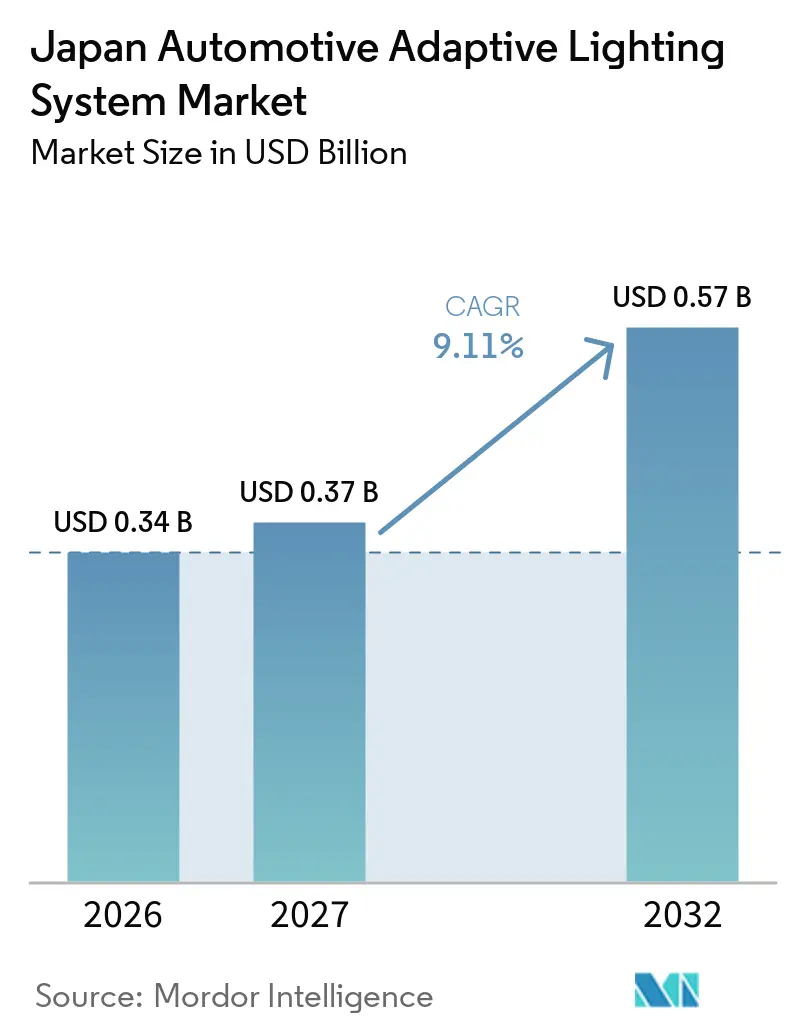
The Japan Automotive Adaptive Lighting System Market size was valued at USD 0.34 billion in 2026, is expected to reach USD 0.37 billion in 2027, and is projected to reach USD 0.57 billion by 2032, growing at a CAGR of 9.11% from 2027 to 2032. Domestic growth is shifting from baseline regulatory compliance to differentiation built on matrix LED and laser headlamp performance, where original equipment manufacturers (OEMs) tune pixel density, response latency, and V2X compatibility to secure superior JNCAP scores and insurance incentives. Passenger-car dominance is moderating as logistics operators retrofit light commercial vehicles (LCVs) to reduce liability for nighttime accidents, while an aging driver demographic makes glare-free illumination a politically salient safety issue. Competitive pressure centers on software-defined beam control that fuses steering-angle, forward-camera, and ETC 2.0 traffic data, transforming lighting modules into ADAS subsystems. Semiconductor supply tightness for high-resolution LED matrices and a shortage of trained aftermarket technicians present near-term operational risks but also spur vendors to offer over-the-air (OTA) calibration and remote diagnostics to maintain warranty integrity.
Key Report Takeaways
- By vehicle type, passenger cars held 71.26% of Japan's automotive adaptive lighting system market share in 2026, while LCVs are set to expand at a 10.13% CAGR through 2032.
- By lighting type, front adaptive lighting commanded 87.73% revenue share in 2026; rear adaptive systems are forecast to grow at a 10.16% CAGR to 2032.
- By component, lamp assemblies captured a 46.52% share of the Japanese automotive adaptive lighting system market in 2026, yet controllers will lead growth at an 11.21% CAGR through 2032.
- By sales channel, the OEM channel accounted for 83.35% of revenue in 2026, whereas aftermarket installations are projected to rise at a 11.18% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Japan Automotive Adaptive Lighting System Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stricter Japanese Vehicle-Lighting Safety Regulations | +2.1% | National | Medium term (2-4 years) |
| Increasing ADAS & Autonomous-Driving Integration | +1.8% | National | Long term (≥ 4 years) |
| Growing Consumer Demand for Premium Safety & Nighttime Visibility | +1.5% | National | Short term (≤ 2 years) |
| LED/Laser Cost Decline Accelerating OEM Adoption | +1.3% | National | Medium term (2-4 years) |
| Aging-Driver Demographics Driving Regulatory Impetus | +1.2% | National | Long term (≥ 4 years) |
| Smart-City Pilots Requiring V2I-Ready Lighting Modules | +0.9% | Tokyo, Osaka metropolitan areas | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Stricter Japanese Vehicle-Lighting Safety Regulations
Japan’s transposition of UN R149 and the National Agency for Automotive Safety & Victims’ Aid (NASVA) JNCAP scoring rubric has raised the performance bar beyond simple auto-on headlights. Higher JNCAP points reward glare-free adaptive beams that dim individual pixels, prompting OEMs to embed sensor-fusion lighting into new models to secure superior safety ratings [1]. Dual certification—device-level UN compliance and installation-level approval audited by the National Traffic Safety and Environment Laboratory (NTSEL)—extends lead times for suppliers unfamiliar with domestic procedures, fortifying incumbents with established MLIT relationships [2]. As a result, adaptive lighting is bundled with broader ADAS suites such as Mazda’s i-ACTIVSENSE, unlocking insurance discounts that sway fleet buyers.
Increasing ADAS & Autonomous-Driving Integration
Toyota’s LED Array Adaptive High Beam System, Honda’s Adaptive Driving Beam, and Nissan’s Adaptive LED Headlights exemplify a decade-long shift from reactive beam switching to predictive illumination tethered to forward-camera, speed, and navigation data [3]. The National Police Agency’s Level 4 guidelines forbid nighttime autonomous operation unless pedestrian detection is assured, making high-resolution adaptive lighting a prerequisite for wider automated-driving domains. OEMs that harmonize beam patterns with collision-warning and lane-departure systems gain regulatory flexibility to extend automated service hours, enhancing vehicle utilization metrics for ride-hailing and logistics fleets.
Growing Consumer Demand for Premium Safety & Nighttime Visibility
Cabinet Office accident statistics show the majority of pedestrian deaths occur at night, a figure that has pushed older drivers to favor models carrying the Support Car S label, which lists adaptive headlights as a recommended technology. Insurers now grant premium reductions for vehicles certified under this program, reinforcing consumer pull. Lexus’s Two-Stage Adaptive High-Beam System uses 24 individually controlled LEDs to maintain sign illumination while shielding oncoming traffic, illustrating how premium brands monetize safety differentiation. Rising take-rates lifted adaptive lighting penetration of new vehicles to a substantial rate, well ahead of pure-mandate timelines — insert the penetration figure from the model or delete the sentence.
LED/Laser Cost Decline Accelerating OEM Adoption
Rising production volumes and advancements in integrated circuits have significantly reduced the cost of LED matrix systems per vehicle, supporting their widespread adoption. ams OSRAM has secured significant design wins for its high-pixel EVIYOS array, indicating that the hardware has become more economically accessible. Concurrent investments in LiDAR laser diodes are spreading research and development costs across higher volumes, further reducing unit prices. As price barriers decline, mid-range vehicle manufacturers are increasingly standardizing matrix LED systems, narrowing the technology gap between mainstream and luxury vehicles.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Module and Integration Cost | -1.4% | National | Short term (≤ 2 years) |
| Complex Electronics/Vehicle Homologation Processes | -0.8% | National, affecting importers | Medium term (2-4 years) |
| Tight Domestic Semiconductor Supply for High-Resolution LED Matrices | -0.7% | National | Short term (≤ 2 years) |
| Limited Aftermarket Technician Proficiency Causing Warranty Risk | -0.6% | National | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Module and Integration Cost
Complete adaptive lighting packages, including sensors, wiring, and calibration labor, cost significantly more than static LED headlamp systems. Koito has made substantial investments to expand capacity, highlighting the scale required to offset fixed costs. However, smaller OEMs face difficulties in distributing software validation costs across limited-volume models. Fleet operators, which prioritize total cost of ownership, are delaying LCV upgrades as they wait for retrofit prices to decline. This trend is dampening short-term demand.
Complex Electronics/Vehicle Homologation
Japan’s dual-layer approval—UN device certification and NTSEL installation tests—adds 12–18 months to program timelines for unfamiliar entrants. Suppliers must upload digital evidence to the UNECE DETA system, then undergo separate national verification, inflating engineering budgets. Import-dependent components face added customs paperwork under the Road Vehicles Act, discouraging foreign tier-2 vendors from pursuing the market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Vehicle Type: LCVs Gain Traction
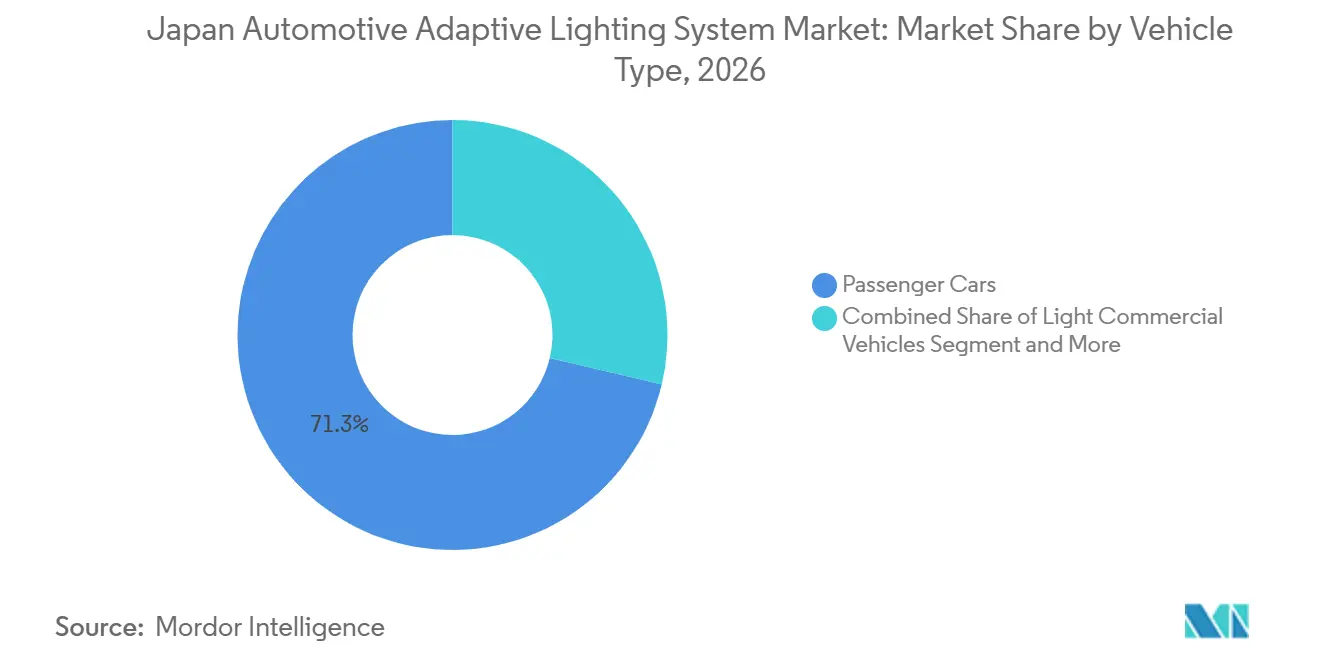
The passenger-car segment accounted for 71.26% of Japan's automotive adaptive lighting system market share in 2026, anchored by rigorous JNCAP testing that skews safety-feature rollouts toward personal vehicles. LCV demand is primed to grow at a 10.13% CAGR as e-commerce logistics fleets target nighttime accident reduction and lower insurance costs through Support Car S compliance.
Fleet retrofits benefit from ETC 2.0’s 1,600 expressway ITS spots, which feed congestion and obstacle data into adaptive controllers that pre-shape beams for upcoming traffic clusters. Toyota’s Smart Road Stud pilot in Kure City demonstrates how V2I cooperation extends visibility beyond the headlamp envelope, a synergy especially valuable to LCVs navigating urban delivery routes. OEM incentives, such as zero-interest safety loans, accelerate adoption among small-parcel operators, positioning LCVs as the fastest-growing vehicle class in the Japanese automotive adaptive lighting system market.



By Lighting Type: Rear Systems Emerge
Front adaptive lighting dominated, accounting for 87.73% of installations in 2026, a direct reflection of JNCAP’s forward-illumination test protocol. However, rear adaptive systems are projected to grow at a 10.16% CAGR through 2032, driven by smart-city pilots in Tokyo and Osaka that require V2I-capable tail-lamp modules for connected traffic management. These pilots support the development of intelligent transportation infrastructure by enabling real-time communication between vehicles and roadside systems.
Rear modules communicate lane-change intent through human-visible and machine-readable patterns, addressing the National Police Agency’s concerns regarding ambiguous turn-signal cues in mixed-autonomy traffic. The Ministry of Internal Affairs and Communications’ 5.9 GHz V2X roadmap positions tail-lamp controllers as low-latency broadcasters of vehicle status, enabling faster data exchange within connected traffic environments. This requirement increases the software content of each rear lighting unit, supports the integration of advanced communication capabilities, and diversifies revenue streams beyond front lighting assemblies.
By Component: Controllers Lead Growth
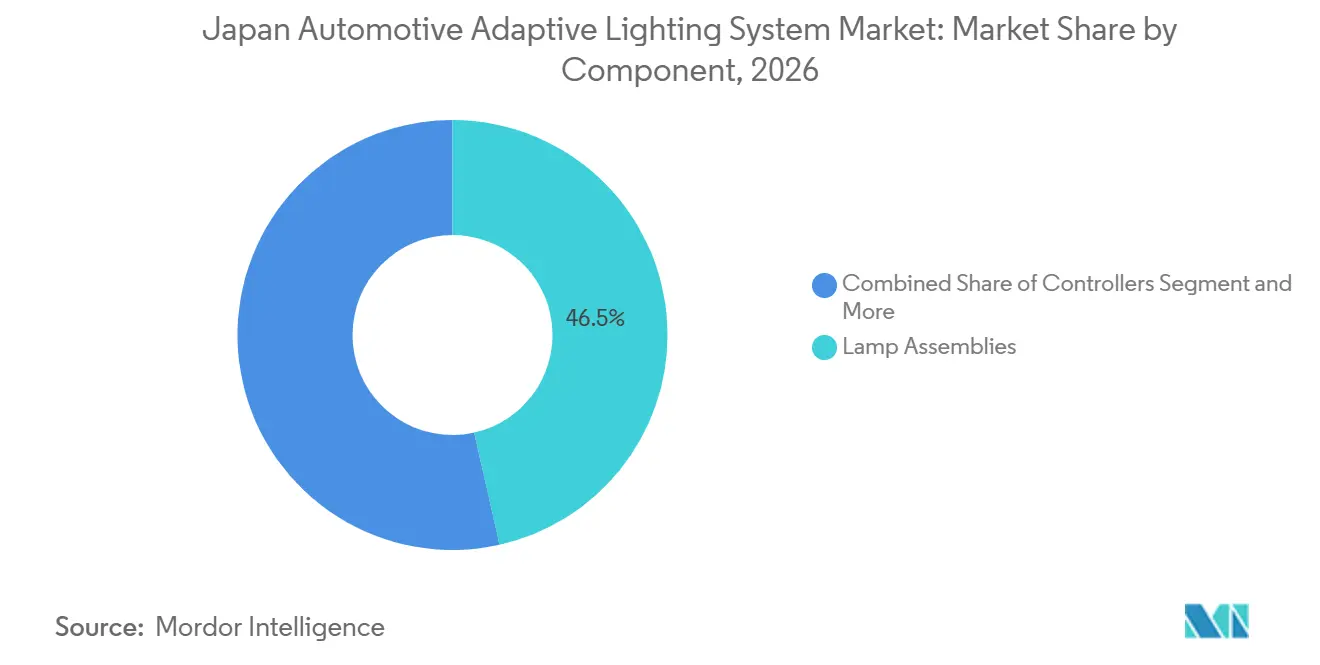
Lamp assemblies accounted for 46.52% of Japan's automotive adaptive lighting system market in 2026, but controller units are expected to register the fastest growth at a 11.21% CAGR. Modern controllers process camera, radar, and navigation data in real time to modulate pixel brightness with high precision. Their ability to rapidly interpret multiple data inputs and adjust lighting performance makes processing capability a key differentiator in advanced automotive lighting systems.
Mazda’s Adaptive LED Headlights deliver glare-free high-beam masking, wide-range low-beam distribution, and highway-mode beam elevation by adjusting duty cycles through a dedicated ECU. These controllers continuously optimize illumination patterns based on driving conditions, road geometry, and surrounding traffic. As over-the-air updates become standard, manufacturers are integrating secure boot and encryption modules into controllers to protect software functions and vehicle data. These additions increase the average selling price and gross margin compared with optical hardware while enhancing the functionality and security of lighting systems.

By Sales Channel: Aftermarket Gains Share
OEM fitment accounted for 83.35% of revenue in 2026, yet aftermarket sales are projected to grow at a 11.18% CAGR as commercial fleets retrofit older assets. Certified installers use portable photometric testers and OEM flash tools to verify the performance and alignment of adaptive lighting systems and support compliance with JNCAP safety requirements. These tools help installers maintain consistent lighting performance throughout the vehicle lifecycle, making safety compliance a recurring maintenance requirement for vehicle owners and fleet operators.
Regulatory inspections under the Road Vehicles Law detect misaligned, degraded, or malfunctioning adaptive lights, prompting fleet managers to replace failed modules with certified parts. This creates recurring aftermarket demand for suppliers such as Koito and Stanley. These suppliers increasingly combine parts distribution with service training, enabling technicians to install, calibrate, and maintain adaptive lighting systems correctly while expanding the suppliers’ aftermarket reach.
Geography Analysis
Japan's automotive adaptive lighting system market remains nationally cohesive, as MLIT mandates apply uniformly across all prefectures. However, Tokyo and Osaka act as innovation hubs, hosting SIP-adus and Digital Lifeline projects that integrate adaptive lighting systems with advanced mobile connectivity and V2X infrastructure. These initiatives accelerate early adoption among urban taxi and shuttle operators by enabling more connected and responsive vehicle lighting functions. Rural regions, characterized by aging populations and limited street lighting, are increasingly adopting Support Car S incentives that prioritize adaptive headlights to improve safety and visibility for elderly drivers in low-light conditions. Insurance discounts tailored to prefectures with larger senior populations further support market adoption.
The automatic headlamp mandate established a near-universal baseline for market penetration, shifting competition toward higher pixel resolution, faster response capabilities, and improved beam precision. Suppliers offering high-resolution pixel arrays with near-instantaneous response times secure premium OEM contracts, while mid-tier brands focus on cost-optimized solutions that balance performance with affordability. Infrastructure pilots on the Shin-Tomei Expressway demonstrate that cloud-sourced congestion data can trigger anticipatory beam adjustments well before a vehicle reaches a bottleneck. These pilots highlight the region-agnostic scalability of such systems as dedicated V2X infrastructure expands nationwide, supporting the broader deployment of connected adaptive lighting technologies.
Although domestic market fragmentation remains low, variations in local dealer training and warranty programs contribute to differences in aftermarket growth rates. Urban dealerships invest heavily in alignment benches, advanced diagnostic equipment, and OTA diagnostic portals to support increasingly sophisticated lighting systems. In contrast, rural workshops rely on OEM-dispatched mobile service vans to perform mandated calibrations and provide maintenance support in areas with limited service infrastructure. These differences influence regional revenue distribution within the Japanese automotive adaptive lighting system market.
Competitive Landscape
Market Concentration
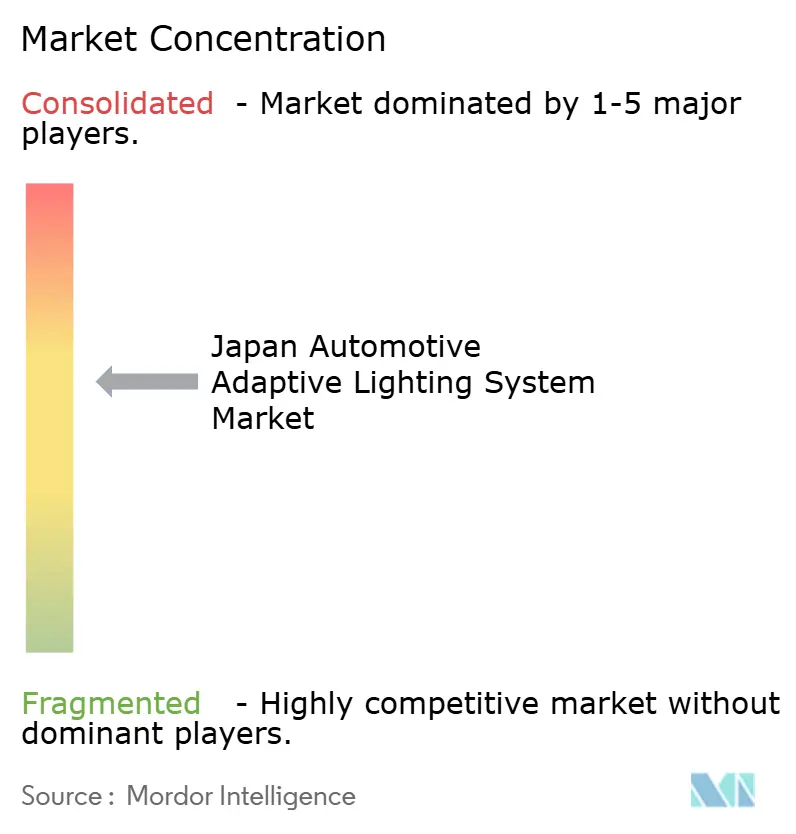
Koito Manufacturing and Stanley Electric, two key players in the domestic market, leverage vertically integrated optics and electronics capabilities to meet the stringent installation-level requirements set by MLIT. Koito’s recent expansion in Mexico and Brazil, supported by significant investment, aligns with Japanese OEM export programs. This strategy indicates a focus on balancing global production capacity while avoiding domestic price competition. In late 2023, Denso formed a joint venture with Koito to integrate lighting control into Denso’s ADAS domain controller. This collaboration enables the unified management of steering, braking, and illumination functions, creating an advanced architecture that smaller competitors may find difficult to replicate.
International players, including Valeo through Ichikoh, HELLA, and Marelli, occupy niche positions by serving specific imported and luxury vehicle models. However, NTSEL’s stringent dual-approval process, combined with OEMs’ preference for local supply chains, constrains foreign players’ market share. While ams OSRAM leads the supply of LED dies and laser sources, its ability to expand market penetration depends on partnerships with domestic Tier 1 suppliers that can navigate type-approval timelines effectively. Potential growth opportunities include rear adaptive modules designed for V2X signaling, fleet retrofit kits bundled with ETC 2.0 data services, and controller software upgrades that support future 5.9 GHz functionality without requiring hardware modifications.
To mitigate warranty risks arising from technician skill gaps, established industry players are investing in OTA infrastructure. These platforms allow dealerships to upload beam-pattern logs for remote verification. These developing service ecosystems strengthen vendor loyalty and increase switching costs, further reinforcing the market’s moderate concentration.
Japan Automotive Adaptive Lighting System Industry Leaders
-
HELLA KGaAHueck& Co.
-
Koninklijke Philips N.V.
-
Stanley Electric Co. Ltd
-
OSRAM Licht AG
-
Koito Manufacturing Co. Ltd
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- April 2026: Following an integration agreement signed in April 2025, Stanley Electric Co., Ltd. and Mitsubishi Electric Mobility officially began operations through their new joint venture. The venture combines Stanley Electric’s advanced optical design capabilities with Mitsubishi Electric’s control system technologies to develop, manufacture, and sell electronic control components for next-generation adaptive automotive lighting systems.
- January 2026: Toyota introduced the updated RAV4 in Japan with matrix LED adaptive headlights standard across all trims.
- August 2025: Tata AutoComp and Ichikoh Industries announced a joint venture to acquire Valeo’s Indian lighting assets, expanding Ichikoh’s global footprint.
Japan Automotive Adaptive Lighting System Market Report Scope
The scope of the report includes Vehicle Type (Passenger Cars, Light Commercial Vehicles, and Medium & Heavy Commercial Vehicles), Lighting Type (Front Adaptive Lighting and Rear Adaptive Lighting), Component (Lamp Assemblies, Sensors & Cameras, and More), and Sales Channel (OEM and Aftermarket). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
By Vehicle Type
| Passenger Cars |
| Light Commercial Vehicles (LCVs) |
| Medium & Heavy Commercial Vehicles (HCVs) |
By Lighting Type
| Front Adaptive Lighting (Headlamps) |
| Rear Adaptive Lighting (Tail-lamps) |
By Component
| Lamp Assemblies |
| Sensors & Cameras |
| Controllers |
| Others |
By Sales Channel
| OEM |
| Aftermarket |
| By Vehicle Type | Passenger Cars |
| Light Commercial Vehicles (LCVs) | |
| Medium & Heavy Commercial Vehicles (HCVs) | |
| By Lighting Type | Front Adaptive Lighting (Headlamps) |
| Rear Adaptive Lighting (Tail-lamps) | |
| By Component | Lamp Assemblies |
| Sensors & Cameras | |
| Controllers | |
| Others | |
| By Sales Channel | OEM |
| Aftermarket |
Key Questions Answered in the Report
How big is the Japanese automotive adaptive lighting system market in 2027?
The market is valued at USD 0.37 billion in 2027 and is forecast to reach USD 0.57 billion by 2032.
Which segment is growing fastest within Japan’s adaptive lighting landscape?
LCV installations are expanding at the highest CAGR of 10.13% as logistics fleets retrofit vehicles for nighttime safety.
What share do passenger cars hold in adaptive lighting adoption?
Passenger cars accounted for 71.26% of installations in 2026, reflecting their role in JNCAP scoring.
Who are the leading suppliers of adaptive lighting systems in Japan?
Koito Manufacturing and Stanley Electric dominate, with emerging systems integrations from Denso–Koito collaborations.
Why is rear adaptive lighting gaining attention?
Smart-city pilots in Tokyo and Osaka require V2I-enabled rear modules to broadcast vehicle intent, driving a 9.16% CAGR for this segment.
What regulatory standards influence Japan’s adaptive lighting uptake?
UN R149 compliance and JNCAP scoring criteria mandate glare-free performance and tie adaptive lighting to broader ADAS integration.