
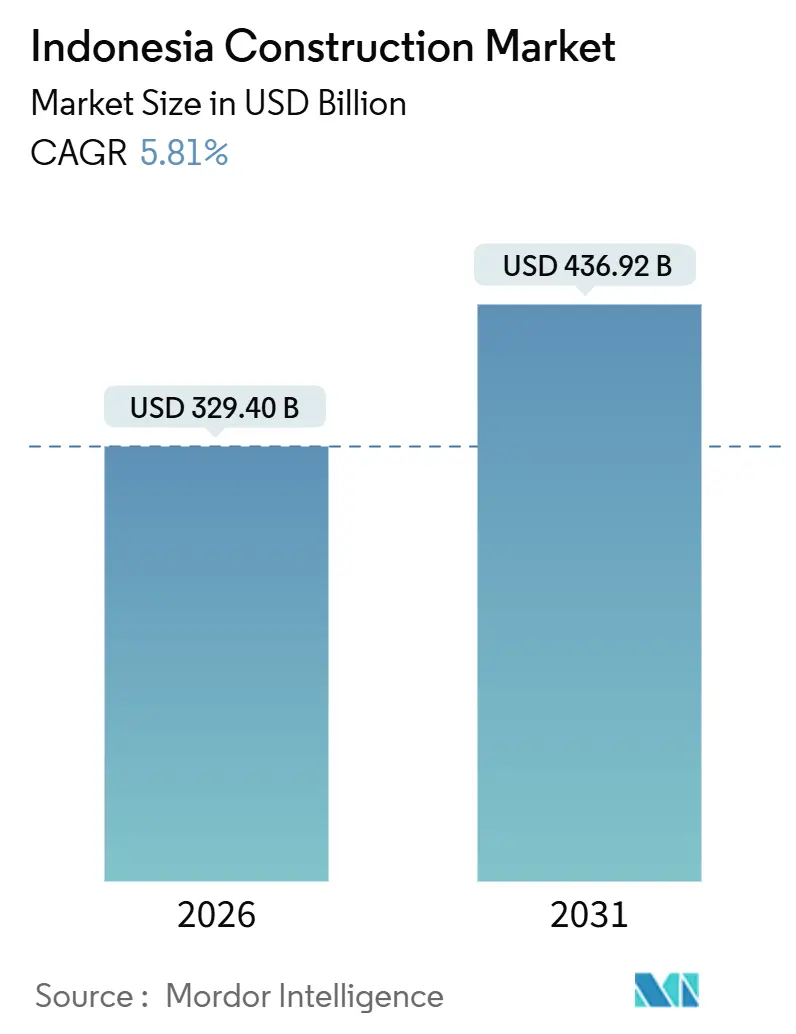
Indonesia Construction Market Analysis by Mordor Intelligence
The Indonesia construction market size is expected to increase from USD 329.4 billion in 2026 to USD 348.5 billion in 2027 and reach USD 466.9 billion by 2032, growing at a CAGR of 6.02% over 2027-2032.
Public programs and housing finance sustain construction demand in Indonesia, while industrial investment creates specialized civil and installation work. Subsidized mortgages support landed-home purchases, giving residential developers a financing channel alongside public institutional construction. Rupiah depreciation raised construction-material cost pressure in Indonesia from June 2026, although ongoing government projects were reported unaffected. Down payments and monthly settlements can limit how long contractors must finance mobilization and materials before receiving payment. That shorter cash-recovery interval can buffer material-cost exposure while builders serve housing and industrial demand.
Key Report Takeaways
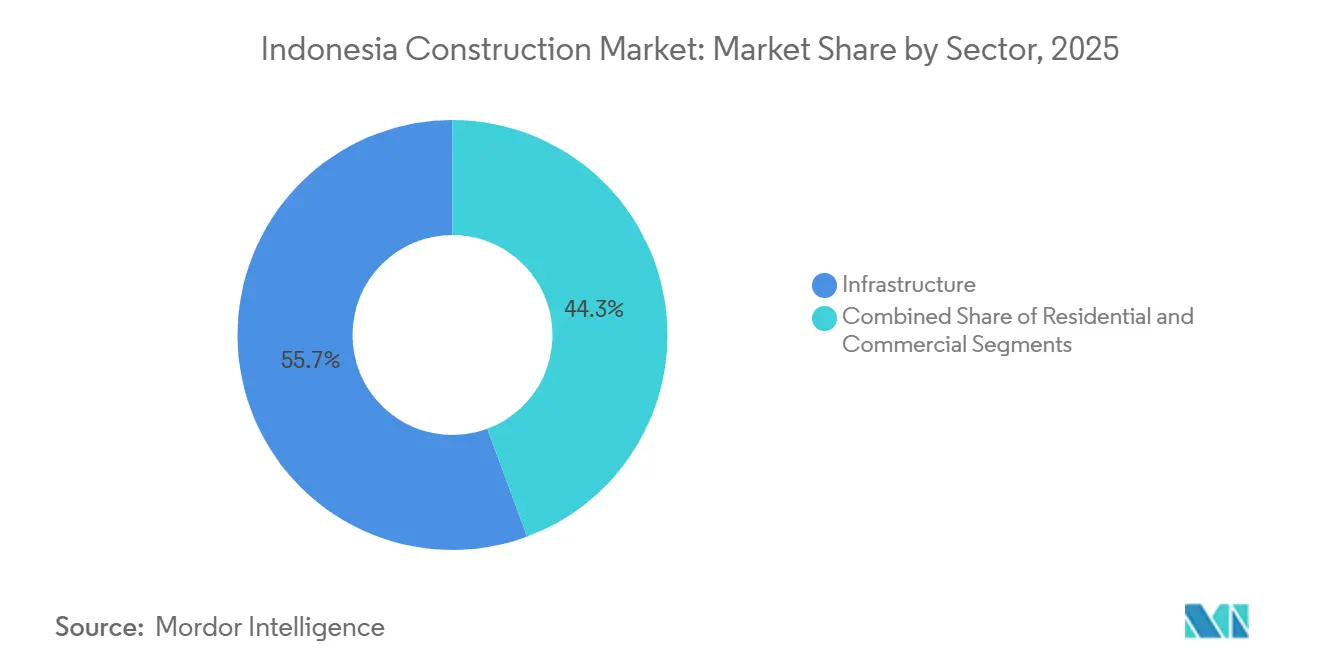
- By sector, infrastructure held a 55.54% Indonesia construction market share in 2026, while commercial construction is the fastest-growing segment at a forecast 6.68% CAGR over 2027-2032.
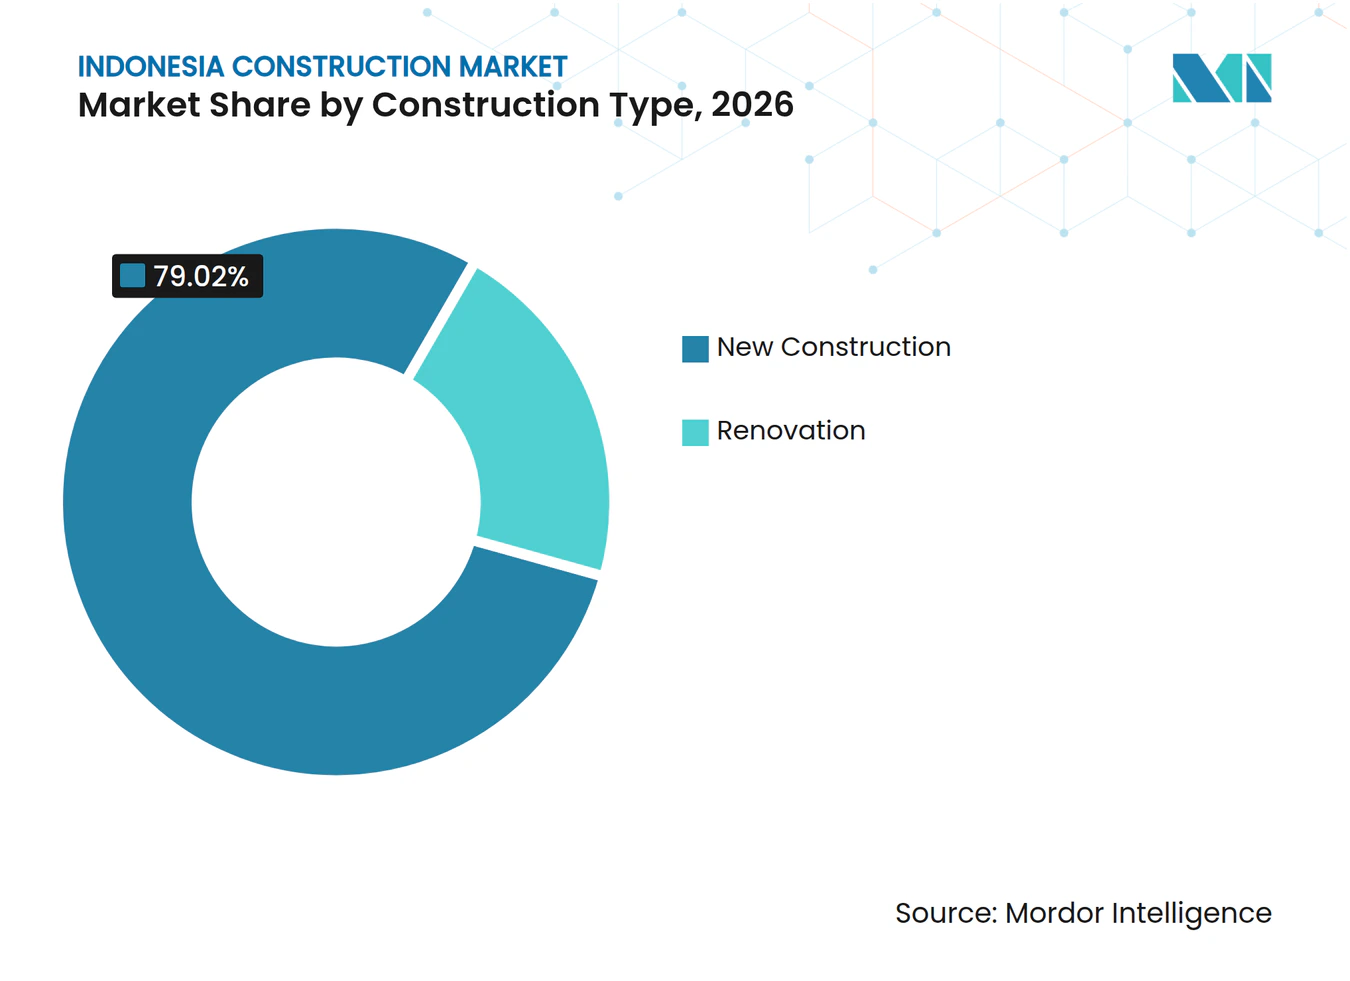
- New construction led construction types with a 79.02% share of the Indonesia construction market size in 2026, whereas renovation is forecast to grow fastest at a 6.55% CAGR over 2027-2032.
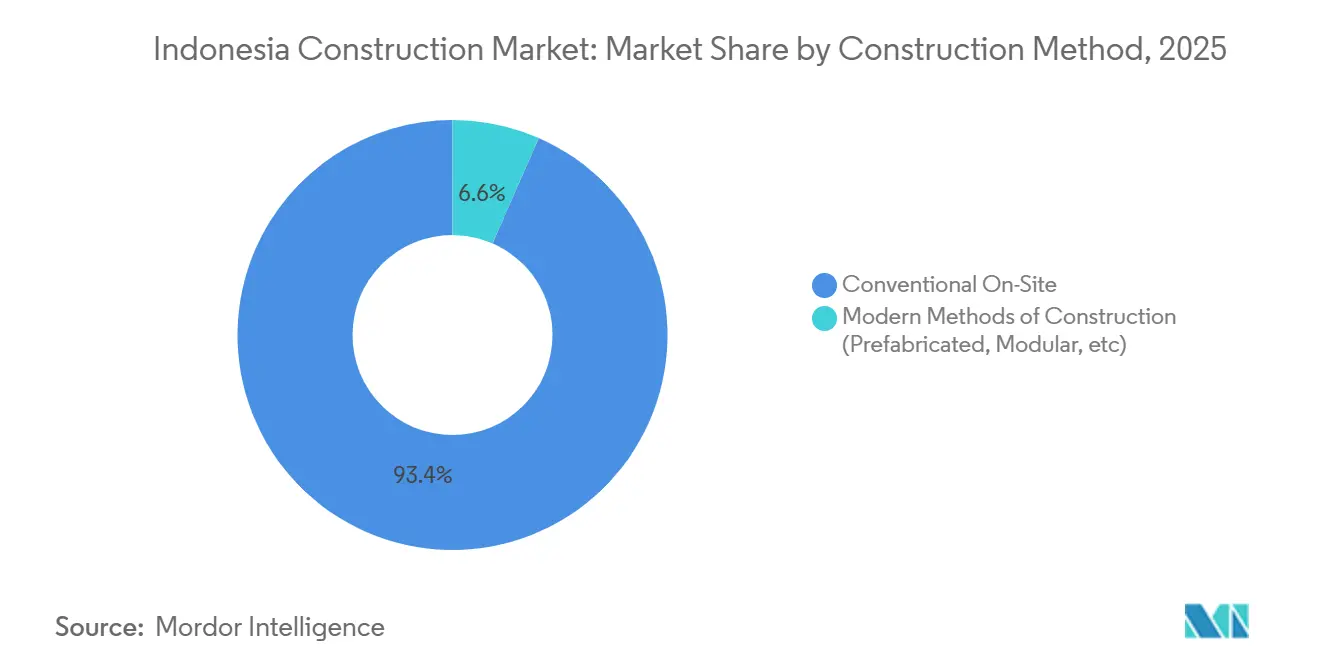
- Across construction methods, conventional on-site work held 93.36% of the market in 2026, and modern methods, including prefabricated and modular approaches, are forecast to grow fastest at a 7.3% CAGR over 2027-2032.
- By investment source, public investment accounted for 64.12% of the market in 2026, with private investment forecast to grow fastest at a 6.65% CAGR over 2027-2032.
- Java led the geographic distribution with 63.05% of the market in 2026, while Sulawesi is the fastest-growing geography at a forecast 6.7% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Indonesia Construction Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Government infrastructure megaproject pipeline (IKN, toll roads) | +2.4% | Nusantara in East Kalimantan | Long term (≥ 4 years) |
| Residential housing backlog & mortgage stimulus | +1.9% | Nationwide | Medium term (2-4 years) |
| Foreign capital & PPP inflows for industrial estates | +1.6% | Batang, Central Java | Medium term (2-4 years) |
| Mining-based downstream investments (nickel, EV metals) | +1.3% | North Maluku and Central Sulawesi | Medium term (2-4 years) |
| Data-center & hyperscale cloud build-outs | +0.7% | Bekasi Regency, West Java | Medium term (2-4 years) |
| Green-building incentives & building energy-efficiency requirements | +0.4% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Government infrastructure megaproject pipeline (IKN, toll roads)
Nusantara's institutional construction program creates demand across multiple contracted packages with a common delivery purpose. By December 6, 2025, the Nusantara Capital City Authority had signed 20 phase-two packages for 2025-2029, including physical works for the legislative and judicial complexes. That structure gives institutional builders a role in coordinating separately packaged work into facilities that can function together. In August 2026, the authority proposed using part of its 2027 budget to continue construction of those facilities. Signed phase-two packages give builders committed work, while the proposed 2027 continuation creates a separate opportunity that depends on budget approval.
Residential housing backlog & mortgage stimulus
Housing finance connects Indonesia's substantial ownership gap to buyers who can support residential development. BPS data reported by the Ministry of Housing put the 2026 home-ownership backlog at about 9.29 million households, down about 350,000 from 2025.[1] The smaller gap reduces unmet ownership need, but its remaining scale gives developers a substantial potential customer base. BP Tapera, which administers the FLPP subsidized-mortgage program, reported 177,161 mortgages disbursed by October 9, 2026, against a calendar-year target of 350,000. For residential contractors, this financing channel matters because an ownership need becomes commercially actionable when a household can fund a purchase. At 177,161 of 350,000 mortgages, about half of the 2026 FLPP target remained to be disbursed after October 9, leaving potential financed purchases beyond those already recorded.
Foreign capital & PPP inflows for industrial estates
A signed industrial-site commitment gives builders a defined tenant location around which to pursue factory construction. On July 25, 2025, Malaysia's Thong Guan Industries Berhad committed USD 7 million to use 5.04 hectares in Industropolis Batang SEZ, Central Java. Thong Guan is a plastic-packaging company, giving the site an identifiable industrial user. The July 2025 commitment covered planned industrial land use, creating a prospective production-site requirement for builders. Potential factory work was therefore tied to a particular packaging producer's site needs, with construction demand contingent on the investment proceeding.
Mining-based downstream investments (nickel, EV metals)
Nickel-processing investment generates construction demand across linked civil works, process installation, and supporting facilities. In Central Halmahera, North Maluku, PT Guang Ching Nickel Cobalt began construction of a nickel-based battery-material project on October 8, 2026.[2] In May 2025, PT Sulawesi Nickel Cobalt had installed the first high-pressure autoclave for its high-pressure acid leach plant in Morowali, Central Sulawesi. Civil works in 3 zones were substantially complete, while a dedicated sulfuric-acid plant was under development. These are linked construction scopes because the dedicated acid facility supports the leaching process. Substantially completed civil zones created a basis for mechanical installation, moving the contractor opportunity toward processing-equipment work.
Restraints Impact Analysis of Indonesia Construction Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| SOE debt overhang & funding tightness | -0.9% | Nationwide | Short term (≤ 2 years) |
| Land-acquisition bureaucracy & permitting delays | -0.7% | South Sumatra and Jambi | Medium term (2-4 years) |
| Skill-certification gap across construction labor force | -0.4% | Nationwide | Long term (≥ 4 years) |
| Volatile cement & specialty-material supply chains | -0.3% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
SOE debt overhang & funding tightness
Debt-service pressure can constrain a contractor's ability to turn awarded work into funded site activity. PT Wijaya Karya (Persero) Tbk deferred a March 25, 2026 bond-interest and sukuk profit-sharing payment after reporting limited unrestricted cash. This liquidity problem matters to construction because mobilizing a project requires financial headroom alongside the technical ability to deliver it. For an owner considering a financially stretched contractor, a signed contract therefore offers less assurance of timely execution unless the project also has dependable funding arrangements. Debt obligations competing with mobilization cash can consequently add financing costs and delay the start of otherwise deliverable construction work.
Land-acquisition bureaucracy & permitting delays
Land access can limit construction progress even when the contractor is technically ready to build. On February 21, 2025, DPR Commission V member Bakri identified land acquisition as the main obstacle on the Trans-Sumatra Toll Road's Palembang-Betung-Muaro Jambi section. He reported that PT Hutama Karya (Persero) was ready to continue construction. Where acquisition restricts site access, contractor readiness alone cannot advance the affected road work. The resulting risk is a longer interval between prepared construction capacity and productive site access, which can defer delivery despite the contractor's ability to perform the work.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Indonesia Construction Market Segment Analysis
By Sector:
Infrastructure Delivery Supports Scale as Commercial Demand BroadensInfrastructure accounted for a 55.54% share of the Indonesia construction market size in 2026. The Ministry of Public Works built 113 kilometers of new roads, upgraded capacity and preserved 720 kilometers of roads, and built 2.5 kilometers of bridges in 2025. Its water-resource program also built irrigation networks covering 13,000 hectares and rehabilitated networks covering 123,000 hectares that year. These outputs connect the largest segment to both asset expansion and work on existing networks, giving civil contractors different forms of physical delivery demand. The ministry's irrigation-rehabilitation footprint exceeded its new-network footprint, giving water-network renewal a substantial role alongside transport expansion.
Commercial construction is the fastest-growing segment, with a forecast 6.68% CAGR over 2027-2032. In Q2 2026, the commercial-property rental demand index grew 1.32% year over year, driven by hotel demand in nearly all surveyed cities and convention-hall demand in Jakarta.[3] Stronger demand for using space can improve the development case for operators considering additional or upgraded facilities. Venue builders have a city-specific lead in Jakarta, while hotel contractors face a geographically broader rental-demand signal.



By Construction Type:
New Building Programs Lead as Neighborhood Renovation ExpandsNew construction represented a 79.02% Indonesia construction market share in 2026. On October 1, 2026, the housing ministry reported that Himperra had realized more than 22,000 subsidized homes against its 47,000-home target under the FLPP subsidized-mortgage program. Himperra's FLPP target gives the largest segment a defined delivery base, with progress measured through individual homes. For residential builders, the scale of that undertaking creates demand for organizing many separate building jobs within an identifiable program. Himperra's target identifies a specific developer group for builders seeking subsidized-home work, narrowing the prospective customer base to participating developers.
Renovation is the fastest-growing segment, with a forecast 6.55% CAGR over 2027-2032. Yayasan Buddha Tzu Chi's Bebenah Kampung program had completed 441 of 500 home renovations in Johar Baru, Jakarta, by April 23, 2026. The foundation's program began in April 2025 and organized improvements within a defined neighborhood. Completing most of its target within roughly a year shows how neighborhood renewal can accumulate through separate home-level jobs.

By Construction Method:
Site Work Leads While Modular Delivery Organizes Repeated UnitsConventional on-site construction was the largest segment, accounting for 93.36% of the market in 2026. In May 2025, repairs on Sampit's South Ring Road in Central Kalimantan had reached rigid-concrete casting at several points. Coordinating those casting points is a site-delivery task, making localized road repair a concrete source of on-site work in this example.
Modern methods of construction, including prefabricated and modular approaches, form the fastest-growing segment, with a forecast 7.3% CAGR over 2027-2032. The Ministry of Public Works and PT Waskita Karya (Persero) Tbk completed temporary post-disaster housing in Bener Meriah, Aceh, using 228 prefabricated modular steel modules in March 2026. The 228 modules were prepared for 228 households, aligning repeated fabrication and assembly with a defined accommodation requirement. For housing authorities, matching the unit requirement to the delivery package connects accommodation capacity with the way construction is organized. The buyer proposition is delivery of a complete temporary-housing program, with repeatable units providing the organizing basis for the work.
By Investment Source:
Public Programs Set Scale as Private Projects Combine Property UsesPublic investment was the largest segment, accounting for 64.12% of the market in 2026. The Ministry of Public Works had a 2026 budget allocation of IDR 132.4 trillion (USD 7.41 billion) through July 31, 2026. Its program categories included water infrastructure, roads and bridges, settlements, and strategic infrastructure. This breadth gives public contracting several funded disciplines, with the relevant opportunity depending on the specific program and construction package. Water-infrastructure specialists can address their own program's works without treating the entire ministry allocation as available construction revenue.
Private investment is the fastest-growing segment, with a forecast 6.65% CAGR over 2027-2032. On October 14, 2026, PT Indonesia Belt Road High Tech Development Park was building Grand Vista Nusantara, comprising commercial space, apartments, and offices on 3.57 hectares in the KIPP 1B zone of Nusantara (IKN). The mix connects privately backed construction to several property functions within one development, giving the builder a combined site-level delivery scope. A proposal covering these uses can address one developer's combined requirements, so broader project scope and a more diverse customer base are separate commercial outcomes.
Geography Analysis
Java Construction Market
Java accounted for 63.05% of the Indonesia construction market size in 2026, making it the largest geography. On May 12, 2026, Jakarta reported about 59% construction progress on its MRT extension, with further work toward Kota Tua targeted for completion by the end of 2029. This staged metropolitan transport program creates work across successive construction phases, giving civil contractors a project base that connects individual sections with a wider network. Transport builders gain a phased delivery task in which progress on the works contributes to a larger city connection, making network execution an observable anchor of Java's construction demand.
Sulawesi Construction Market
Sulawesi is the fastest-growing geography, with a forecast 6.7% CAGR over 2027-2032. On February 25, 2026, PT Vale reported 62% overall construction progress at its IGP Pomalaa nickel project in Southeast Sulawesi. The project's feed-preparation and high-pressure acid leach areas each exceeded 36% completion, alongside supporting-facility construction at different stages. In August 2026, South Sulawesi's head of youth and sports reported foundation and access-road work underway at Stadion Sudiang. For industrial contractors, parallel process and support work offers several construction disciplines within one development, while stadium work supplies a separate public-facility customer channel.
Access projects across the remaining geographies differ in their delivery stage and the journeys they serve. Sumatra's Palembang-Pangkalan Balai toll section provided temporary holiday access from March 13 to 29, 2026, tying functional road availability to peak intercity travel. In Kalimantan, Governor Muhidin inspected Pulau Laut Bridge construction on October 7, 2026, with the Tanah Bumbu-Kotabaru connection giving bridge builders an interdistrict transport assignment. Within Others, the Ministry of Public Works reported North Maluku's Gayok and Todowongi suspension bridges complete by August 29, 2025, after 2024-2025 multiyear projects, illustrating delivered local crossing infrastructure. Bali's governor sought central road and transport support on April 8, 2026, citing residents' complaints of narrow tourist-route congestion, so that tourism-corridor need represented a request for support rather than an approved building package.
Regulatory Framework and Outlook
Selected jurisdictions are compared for an established contractor assessing building-project delivery, with Jakarta's rating reflecting the owner's approval route. Medium-high-risk construction activities require an OSS business identification number and an initially unverified standard certificate, followed by the business-capability certification route. In Jakarta, building owners or users may use a building only after it receives a functional-feasibility certificate. Contractor qualification and owner approval therefore create separate compliance tasks within the same construction program.
Regulatory Table of Indonesia Construction Market
| Decision factor | Indonesia | Jakarta |
|---|---|---|
| Primary authority | Ministry of Public Works | Dinas Cipta Karya, Tata Ruang dan Pertanahan |
| Key instruments or direction | Ministry of Public Works Regulation 6/2025 for construction-services qualification | Perda No. 1/2024 and the spatial-plan building-approval framework |
| Commercial effect | Complete required registration data and obtain the OSS identification number and initially unverified standard certificate; apply for capability certification through an LSBU body via the ministry portal | Owners obtain approvals for new buildings and specified existing-building cases; functional-feasibility certification precedes use, with defined approval and retribution exceptions |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
Indonesia's Medium rating balances medium-high-risk firms' registration and capability-certification duties with existing certificates' continued validity and assessment-free conversion within 6 months after the construction-services unit's system-start notice, supporting continuity. Jakarta's Medium rating weighs the owner's approval and feasibility-certificate sequence against maintenance-and-care alteration-approval exemptions and retribution exemptions for government-owned and religious-function buildings. On July 14, 2026, the province said its proposed revision would not raise building-approval retribution rates, supporting continuity. On August 7, 2026, legislators reported 59 of 118 proposed articles discussed, with changes possible after Ministry of Home Affairs evaluation and facilitation, leaving the rate assurance conditional.
Value Chain Stages
The value chain compares design-build coordination, material supply, specialist foundations, and physical construction as distinct sources of supplier earnings. PT Pembangunan Perumahan (Persero) Tbk signed a design-build contract on January 26, 2026, for 4 Attorney General's Office buildings, with a 360-calendar-day implementation period. Combining design and construction responsibility gives the contractor an integration role, so value capture depends on managing the handover from an agreed design to executable work.
Value Chain Analysis Table of Indonesia Construction Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Design-build coordination | Design-build coordinators such as PT Pembangunan Perumahan (Persero) Tbk | Integrated design-build contract earnings | Unresolved design-to-site interfaces | Assign interface responsibility before releasing work packages |
| Cement supply | Cement manufacturers such as PT Semen Indonesia (Persero) Tbk | Cement sales | Matching material applications to specified concrete work | Confirm application requirements before production and delivery |
| Foundation construction | Specialist foundation contractors such as PT Indonesia Pondasi Raya Tbk | Foundation construction revenue | Site-specific foundation requirements | Resolve foundation scope and structural handover criteria before mobilization |
| Physical construction | Construction contractors such as PT Pembangunan Perumahan (Persero) Tbk | Construction contract earnings | Coordinating parallel building work fronts | Sequence work packages and handovers across buildings |
| Source: Mordor Intelligence | ||||
PT Semen Indonesia (Persero) Tbk supplies multipurpose cement for residential concreting, precast products, and ready-mix concrete, linking its material role to several construction applications. A shift toward more precast delivery can change where fabrication occurs while retaining a role for upstream cement supply. PT Indonesia Pondasi Raya Tbk reported foundation construction revenue as a distinct category in 2025, demonstrating a separate specialist earning stream. The design-build contractor earns from combined design and construction, the cement supplier from material sales, and the foundation specialist from separately reported foundation work.
Competitive Landscape
Market Concentration
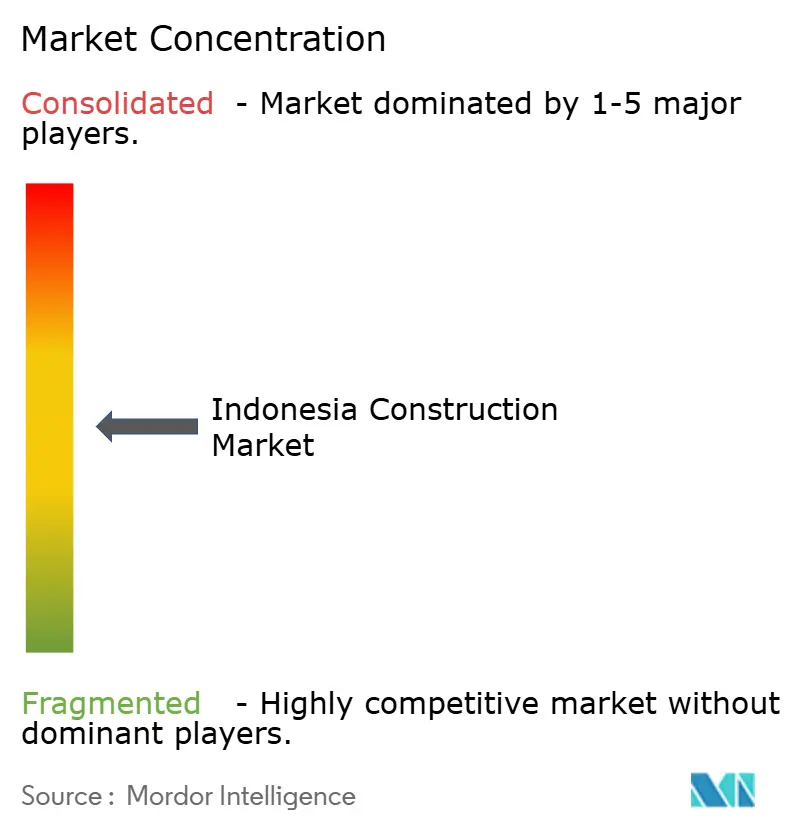
Competition is moderately fragmented, with several established contractors serving a range of infrastructure and building projects. PT Hutama Karya (Persero) was identified as contractor on the toll-road section from Palembang through Betung to Muaro Jambi in February 2025, and PT Wijaya Karya (Persero) Tbk is a state-owned construction company. Other contractors include PT Pembangunan Perumahan (Persero) Tbk, PT Adhi Karya (Persero) Tbk, and PT Waskita Karya (Persero) Tbk. Waskita reported that its 2025 new contracts were dominated by government projects, including irrigation networks, public schools, and regional hospitals across Indonesia. This contract mix favors competition based on relevant asset experience, because irrigation systems, schools, and hospitals create different physical delivery tasks within public construction.
Contract financing terms are a competitive decision because they shape how much working capital a builder must commit to executing an award. On September 28, 2026, Waskita said it was avoiding turnkey and investment projects and prioritizing monthly-payment schemes and down payments. An advance can support initial mobilization, while monthly settlements can reduce the interval over which the contractor funds work before receiving payment. For owners, a payment schedule that supports execution can widen the practical bidder pool, while heavily deferred cash receipt may exclude contractors with limited financing headroom.
PT Pembangunan Perumahan (Persero) Tbk secured a follow-on revitalization project for Terminal 1A at Soekarno-Hatta Airport in August 2026. The award had a 365-calendar-day execution period beginning August 21, 2026. Existing-asset revitalization offers a competitive route built around renewing a transport asset, complementing the delivery of new infrastructure within a contractor's business. The follow-on award makes experience with the same terminal a concrete competitive reference for challengers seeking similar refurbishment work. Challengers pursuing medium-high-risk work also need the national registration and capability-certification route, making demonstrated refurbishment experience complementary to formal business qualification.
Indonesia Construction Industry Leaders
-
PT Hutama Karya (Persero)
-
PT Wijaya Karya (Persero) Tbk
-
PT Pembangunan Perumahan (Persero) Tbk
-
PT Adhi Karya (Persero) Tbk
-
PT Waskita Karya (Persero) Tbk
- *Disclaimer: Major Players sorted in no particular order
Indonesia Construction Market Companies Covered in this Report
- PT Hutama Karya (Persero)
- PT Wijaya Karya (Persero) Tbk
- PT Pembangunan Perumahan (Persero) Tbk
- PT Adhi Karya (Persero) Tbk
- PT Waskita Karya (Persero) Tbk
- PT Nindya Karya (Persero)
- PT Brantas Abipraya (Persero)
- PT Jaya Konstruksi Manggala Pratama Tbk
- PT Total Bangun Persada Tbk
- PT Acset Indonusa Tbk
- PT PP Presisi Tbk
- PT Wijaya Karya Beton Tbk
- PT Wijaya Karya Bangunan Gedung Tbk
- PT Nusantara Infrastructure Tbk
- PT Jasa Marga (Persero) Tbk
- PT Indonesia Pondasi Raya Tbk (Indopora)
- PT Rekayasa Industri
- PT JGC Indonesia
- PT China Harbour Indonesia
- PT Ciputra Development Tbk
Key Opportunities for Market Participants
Construction opportunities under Indonesia's housing credit program (KPP) differ between business-linked renovation, new building work, and finance for housing suppliers. On September 16, 2026, the housing ministry said the program supports contractors and developers and can finance home construction or renovation. Through September 8, 2026, 85,995 debtors had used KPP demand-side financing for home renovations. The commercial opening is to connect this financing to deliverable housing work for qualifying micro, small, and medium enterprises (MSMEs).
Market Opportunities Table of Indonesia Construction Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Business-linked home renovation | Active renovation-credit channel | Qualifying business-use home renovators | Offer a bounded renovation scope aligned with the financed use | Business qualification and lender credit checks | Renovation contractors |
| Business-linked home construction | Construction is an included housing-credit use | Qualifying MSME owner-builders | Develop a complete housing construction package for the eligible borrower | Viable business history and primary collateral requirements | Small residential builders |
| Financing-supported contractor delivery | Supply-side support reaches housing businesses | Eligible housing contractors and developers | Link business financing to an executable housing contract | Concurrent-loan restrictions and possible additional collateral | Eligible housing contractors and developers |
| Source: Mordor Intelligence | |||||
Eligible borrowers need a viable business operating for at least 6 months, Indonesian citizenship or an Indonesian legal entity, tax and business registration, and satisfactory credit checks. They cannot receive KUR (people's business credit) or another KPP housing credit loan concurrently, and the financed object serves as primary collateral. Performing commercial credit can coexist under the lender's rules, which may also require additional collateral. The near-term customer is an established MSME seeking property improvements, with renovation-loan use providing a demonstrated channel for reaching that business-qualified demand.
Recent Industry Developments in Indonesia Construction Market
- Oct 2026: PT Guang Ching Nickel Cobalt began construction of a nickel-based battery-material project at Indonesia Weda Bay Industrial Park in Central Halmahera, North Maluku, on October 8.
- Aug 2026: PT Pembangunan Perumahan (Persero) Tbk secured a follow-on revitalization project for Terminal 1A at Soekarno-Hatta Airport, with a 365-day execution period beginning August 21.
- Jun 2026: Princeton Digital Group began construction of its 240 MW JC4 data center in Deltamas, Bekasi Regency, West Java, on June 30.
Indonesia Construction Market Report Scope and Research Methodology
Market Definition and Coverage
Indonesia construction market measures annual spending on construction work performed on site in Indonesia. It covers new construction and renovation across residential, commercial, and infrastructure projects, valued in USD.
Scope exclusions: Separately sold construction materials and other inputs, real estate, land and completed-property sales, standalone architecture, engineering and project consulting fees, construction machinery and equipment sold or rented separately, and standalone facility operation and routine maintenance are excluded.
Segments Covered in This Report
- By Sector
- Residential
- Apartments/Condominiums
- Villas/Landed Houses
- Commercial
- Office
- Retail
- Industrial and Logistics
- Others
- Infrastructure
- Transportation Infrastructure (Roadways, Railways, Airways, others)
- Energy & Utilities
- Others
- Residential
- By Construction Type
- New Construction
- Renovation
- By Construction Method
- Conventional On-Site
- Modern Methods of Construction (Prefabricated, Modular, etc)
- By Investment Source
- Public
- Private
- By Geography
- Java
- Sumatra
- Kalimantan
- Sulawesi
- Others
Data Sources, Market Sizing, and Validation
Desk Research
Sources such as the World Bank's Republic of Indonesia Domestic Construction Contractor Market Analysis help assess the public and private project pipeline, contractor capacity, tender conditions, and infrastructure funding. Bank Indonesia's Residential Property Price Survey and construction-material price indicators help track housing activity and input-cost movements, while the World Bank's World Development Indicators provide a macroeconomic series that includes construction within broader industry value added.
The World Bank's Indonesia Economic Prospects adds current context on domestic investment, construction activity, and national project programs. Company filings, investor materials, and reputable Indonesian business press can clarify contract awards, contractor financial conditions, and project timing. These sources are illustrative rather than exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys with Indonesian construction contractors, developers, project owners, public procurement and infrastructure specialists, and construction-material and equipment suppliers can test secondary evidence on project timing, contract values, payment terms, and execution constraints. Respondents can help clarify gaps in sector, construction-type, construction-method, investment-source, and regional evidence, with conflicting or incomplete answers checked against independent public records and other respondent perspectives.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 25% | CXOs: 20% | |
| Mid tier: 55% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
The model estimates Indonesia's annual on-site construction work value from a top-down assessment of construction output and project spending, then checks selected totals against contractor revenue and sampled contract values multiplied by completed work volumes. Sector, new construction versus renovation, conventional versus modern methods, public versus private investment, and Java, Sumatra, Kalimantan, Sulawesi, and other regions are separated using project and contractor evidence, public investment plans, completed-work indicators, and the distribution of activity across those categories.
Forecasts use scenario analysis informed by construction output and completed-work trends, planned infrastructure and housing investment, property demand and housing finance, construction cost indicators, and contractor funding conditions. These indicators shape the expected pace and mix of projects, while material and labor costs help distinguish nominal value growth from changes in the amount of work. Primary respondents can check whether the selected project, financing, and cost indicators reflect practical delivery conditions in Indonesia. Gaps in selective contractor or contract checks are handled by comparing available observations with public project and completed-work evidence and retaining only supported adjustments.
Data Validation & Update Cycle
Analysts triangulate contractor reports, public project and budget records, completed-work indicators, cost series, and independent market signals, then investigate material variances in coverage, timing, or units before sign-off. A second review checks calculations, segment shares, geographic consistency, and forecast drivers, with respondent re-contact triggered by conflicting explanations, an unexplained change in a key input, or a material new award, delay, financing shift, or cost event. The model is refreshed annually, updated between cycles when material events change project delivery or funding, and given a fresh source and calculation review before delivery.
Mordor Intelligence's Indonesia Construction Market Sizing Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Indonesia construction market measures annual spending on construction work performed on site in Indonesia.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Sector, new construction versus renovation, conventional versus modern methods, public versus private investment, and Java, Sumatra, Kalimantan, Sulawesi, and other regions are separated using project and contractor evidence, public investment plans, completed-work indicators, and the distribution of activity across those categories.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 348.5 B (2027) | |
| Global Consultancy A | USD 280 B (2025) | At its 2025 base, this estimate is 19.7% below this report's 2027 value of USD 348.5 B, 2 years later. Its earlier estimate year precedes the current measurement year, and its own published forecast indicates continued market growth. |
| Regional Consultancy B | USD 268.54 B (2023) | At its 2023 base, this estimate is 23.0% below this report's 2027 value of USD 348.5 B, 4 years later. Its earlier base year and published upward forecast path contribute to a lower comparison, while inclusion of land planning and development broadens coverage. |
Mordor Intelligence's analysts triangulate contractor reports, public project and budget records, completed-work indicators, cost series, and independent market signals, then investigate material variances in coverage, timing, or units before sign-off.
Key Questions Answered in the Report
What is the Indonesia construction market size and growth outlook?
The market is expected to reach USD 348.5 billion in 2027 and USD 466.9 billion by 2032, growing at a 6.02% CAGR over 2027-2032.
Which forces support construction demand in Indonesia?
Signed Nusantara capital construction packages, housing finance, and nickel-processing projects support demand. BP Tapera, administrator of the FLPP subsidized-mortgage program, reported 177,161 mortgages disbursed by October 9, 2026.
Which construction sector leads in Indonesia?
Infrastructure was the largest sector with 55.54% of the market in 2026. Commercial construction is forecast to grow fastest at a 6.68% CAGR over 2027-2032.
Who are Indonesia's major construction contractors?
PT Hutama Karya (Persero), PT Wijaya Karya (Persero) Tbk, PT Pembangunan Perumahan (Persero) Tbk, PT Adhi Karya (Persero) Tbk, and PT Waskita Karya (Persero) Tbk are among the major contractors.
What can constrain construction delivery in Indonesia?
Contractor liquidity and land access can limit execution. PT Wijaya Karya (Persero) Tbk deferred a March 25, 2026 bond-interest and sukuk profit-sharing payment after reporting limited unrestricted cash.
Which Indonesian regions lead construction activity and growth?
Java held 63.05% of the market in 2026. Sulawesi is forecast to grow fastest at a 6.7% CAGR over 2027-2032.