
Human Risk Management Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 4.12 Billion |
| Market Size (2031) | USD 7.69 Billion |
| Growth Rate (2026 - 2031) | 13.29 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Human Risk Management Market Analysis by Mordor Intelligence
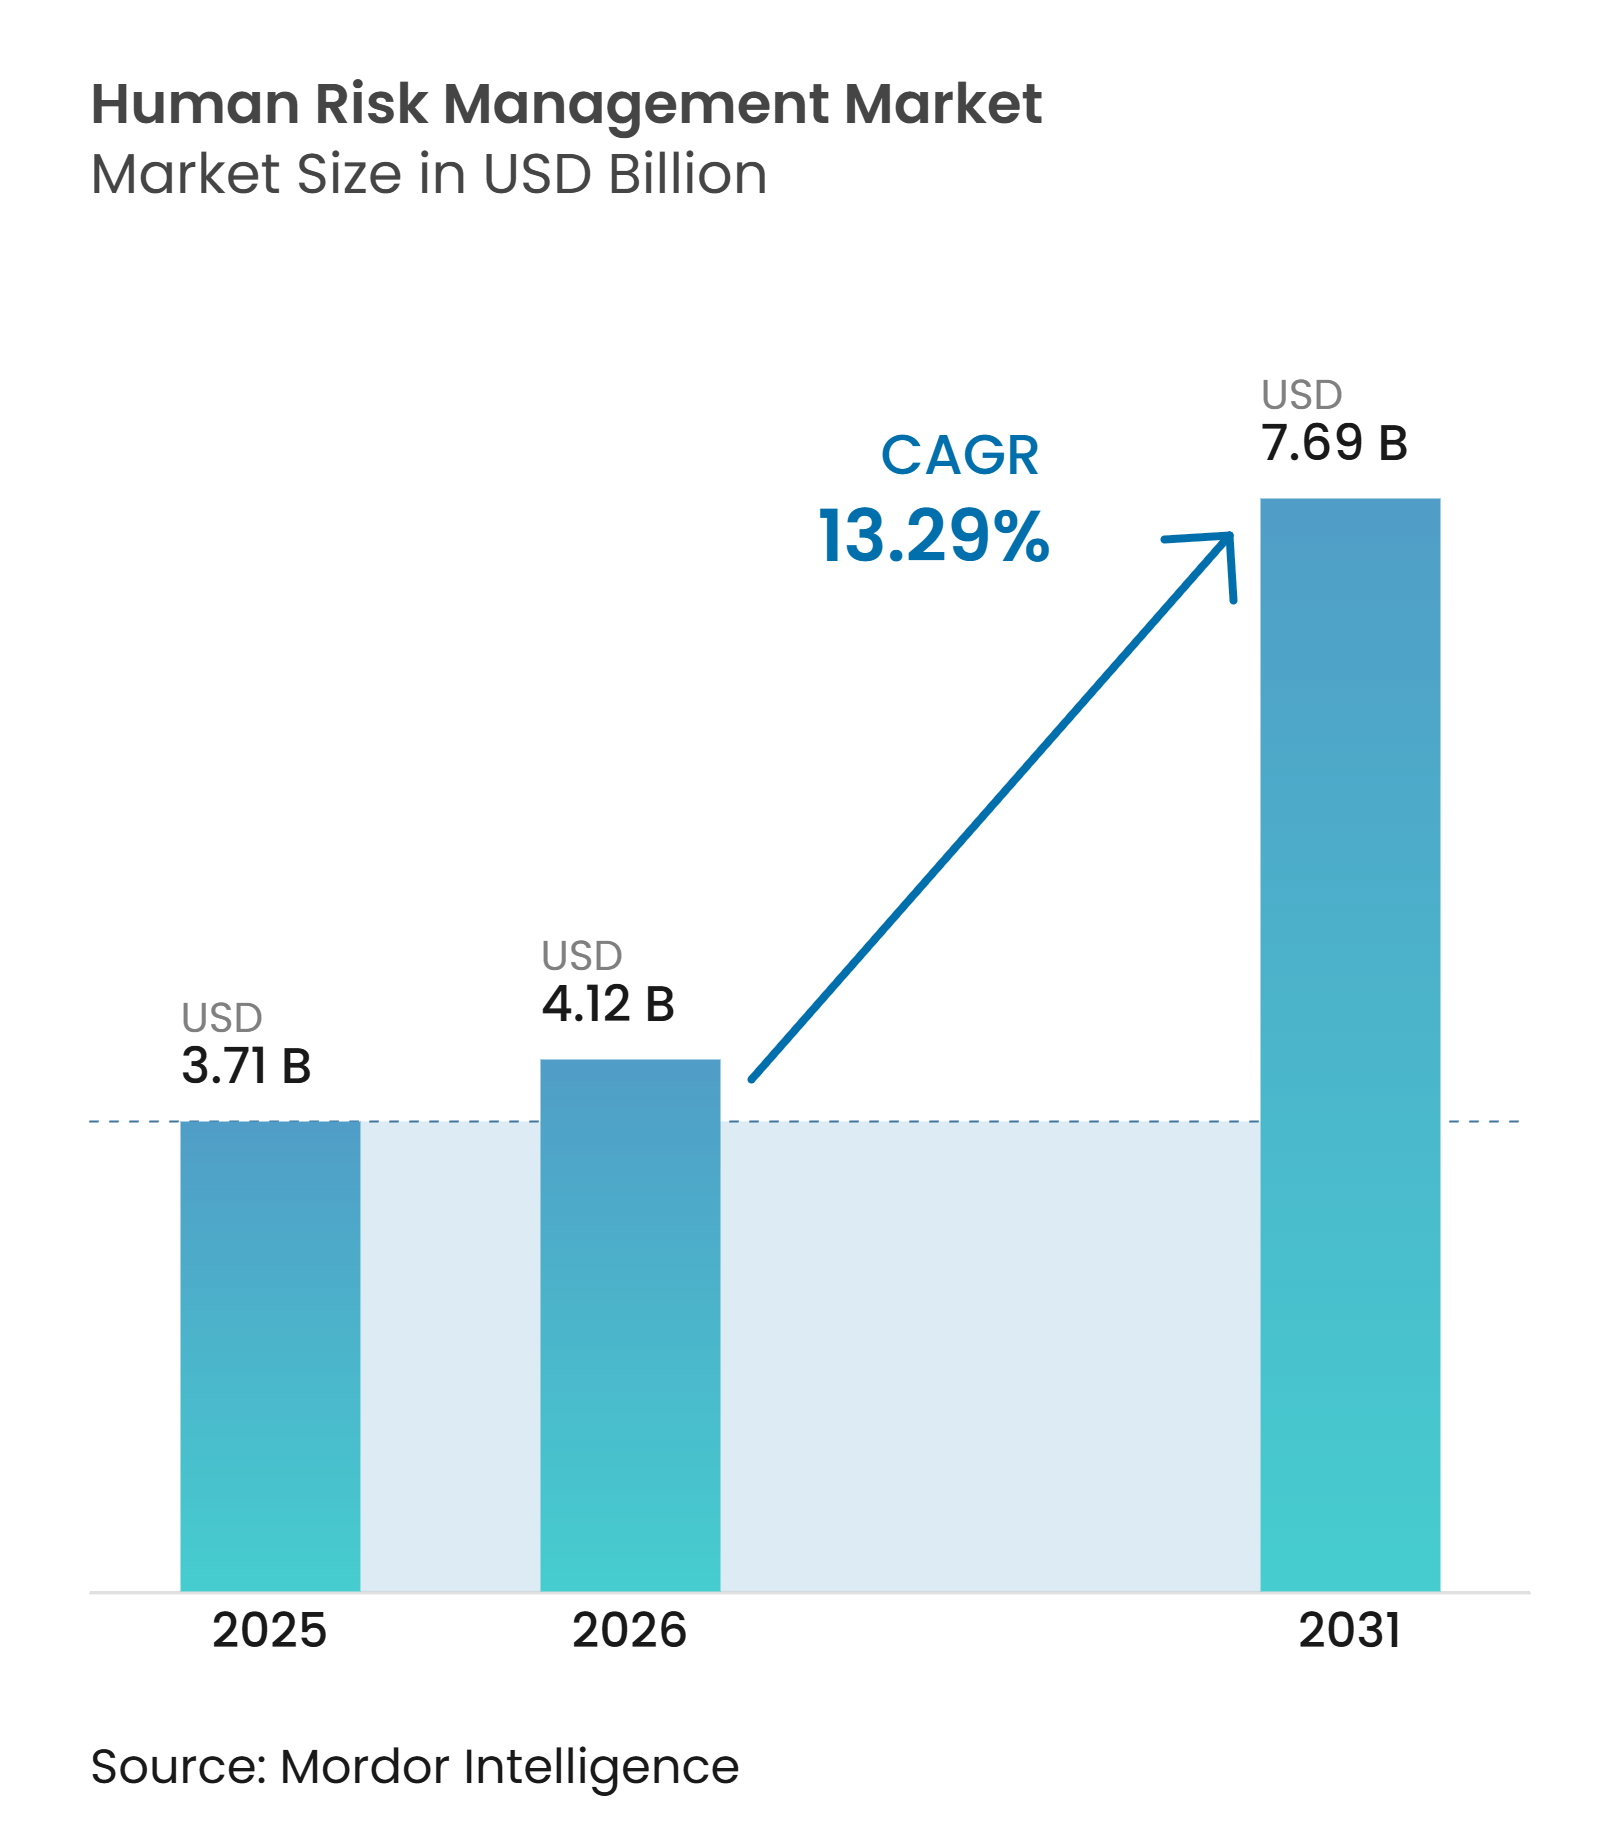
The human risk management market size was valued at USD 3.71 billion in 2025 and estimated to grow from USD 4.12 billion in 2026 to reach USD 7.69 billion by 2031, at a CAGR of 13.29% during the forecast period (2026-2031). The human risk management market is moving beyond a compliance-led purchase toward documented control within broader cyber risk programs. Business email compromise resulted in USD 3.046 billion reported losses in 2025, underscoring the need to keep employee behavior central to security planning. Buyers are increasingly seeking platforms that combine phishing simulations, training content, behavior data, and timely coaching. Large enterprises remain the principal revenue base, while cloud delivery and managed services are making these tools more accessible to smaller organizations. Vendor competition is centered on human risk management capabilities, identity-related connections, and evidence that training can reduce exposure.
Key Report Takeaways
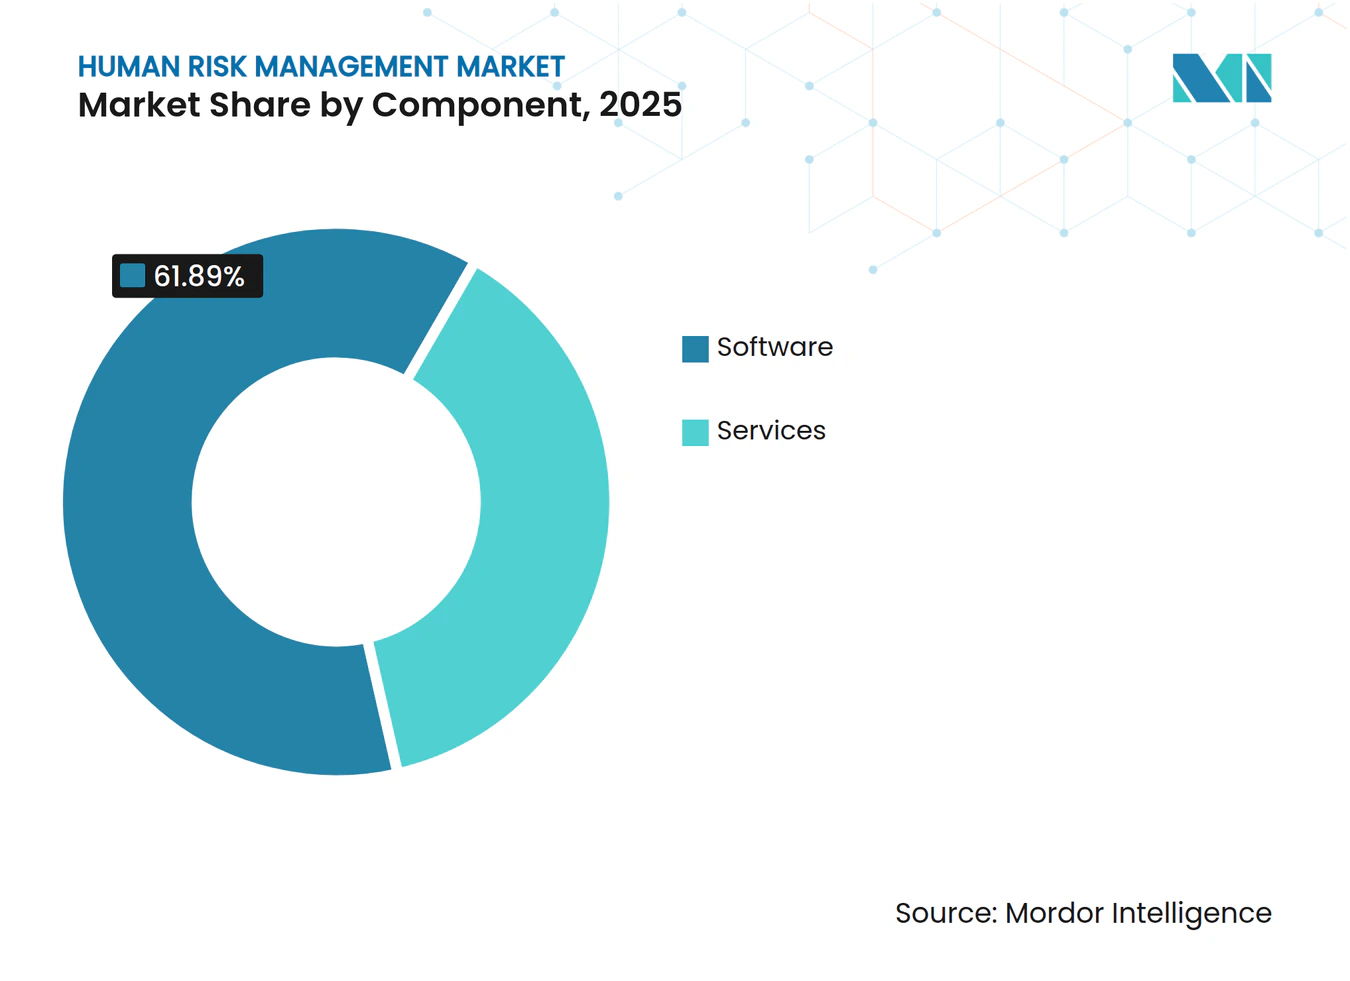
- By component, software held 61.89% of the human risk management market in 2025, while services are projected to expand at a CAGR of 16.36% through 2031.
- By deployment mode, cloud-based delivery accounted for 73.18% of the human risk management market in 2025 and is projected to grow at a 18.29% CAGR through 2031.
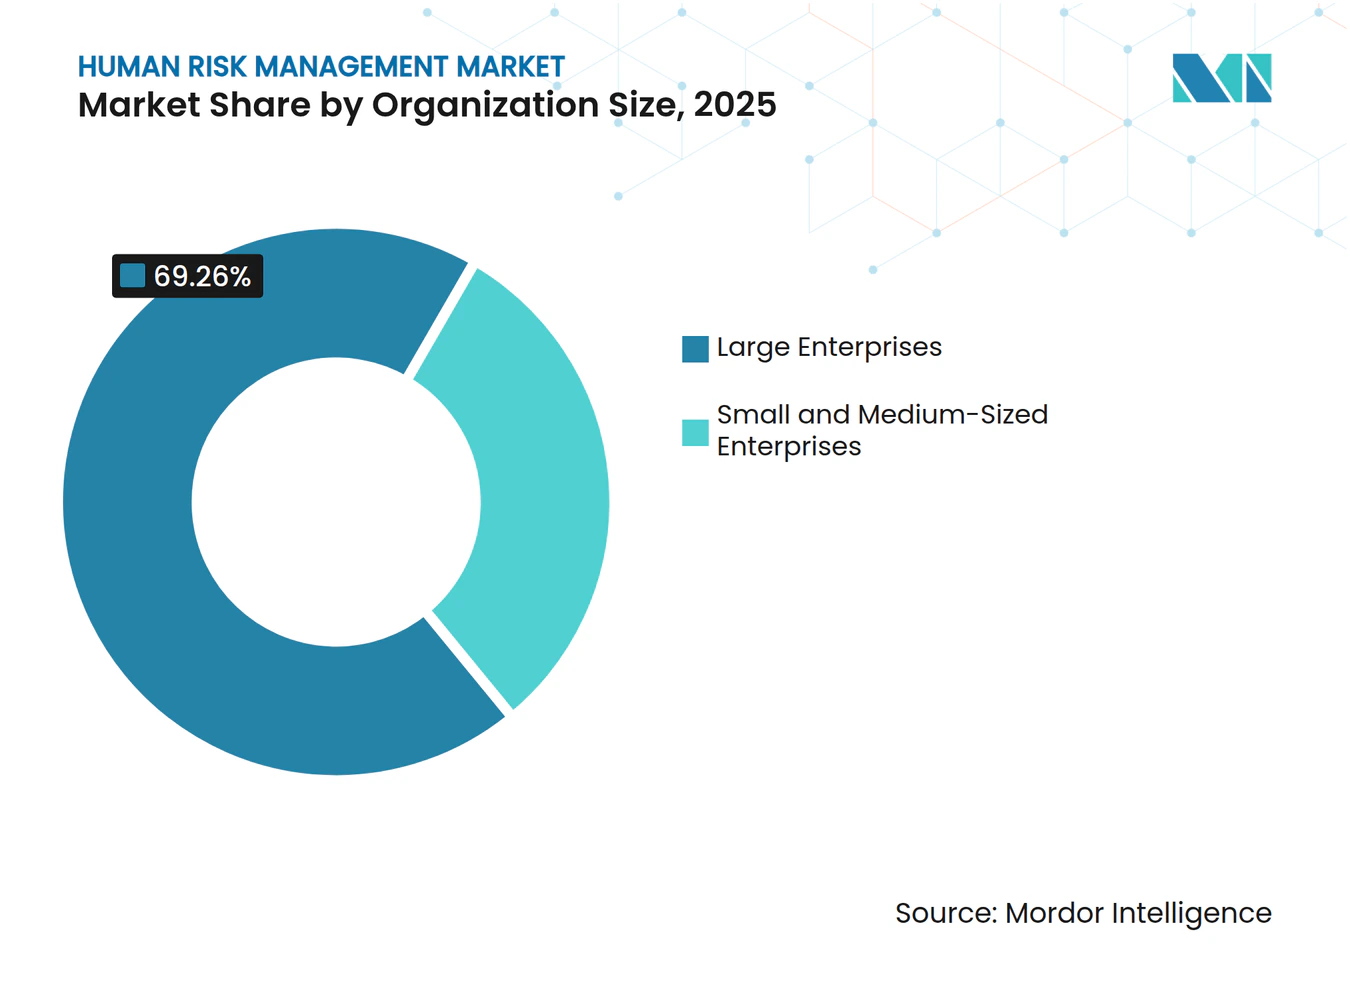
- By organization size, large enterprises accounted for 69.26% of revenue in 2025, while SMEs are projected to grow at a 15.84% CAGR through 2031.
- By end-use industry, BFSI held 27.39% of revenue in 2025, while the healthcare and life sciences industry is projected to expand at a CAGR of 16.37% through 2031.
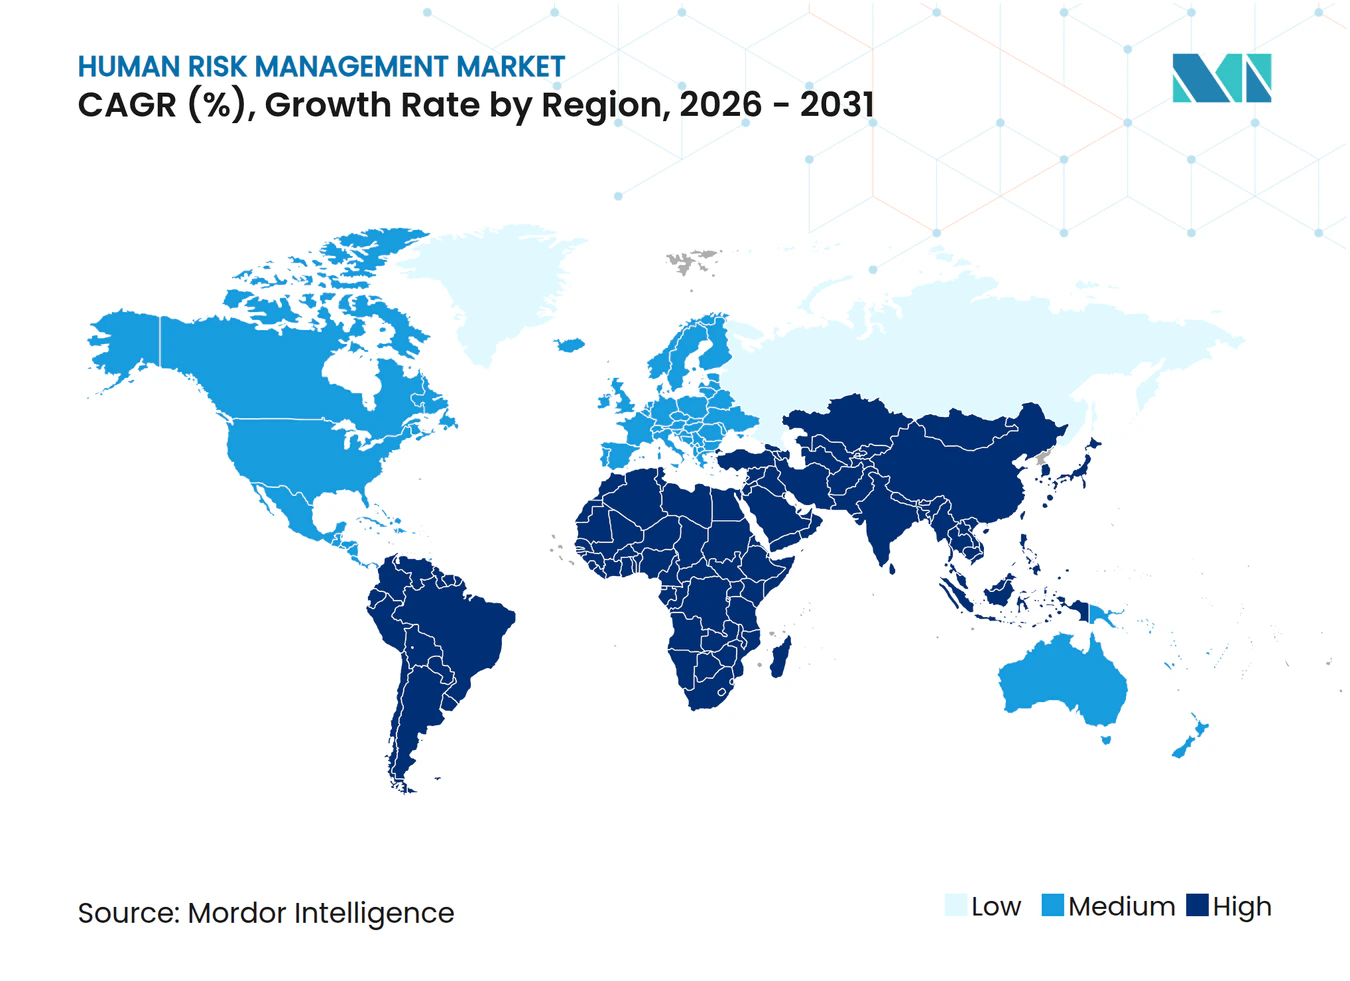
- By geography, North America held 41.37% of the human risk management market share in 2025, while the Asia-Pacific is projected to expand at an 18.96% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Human Risk Management Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Increasing AI-Enabled Phishing and Social Engineering | +3.2% | Global, with intensified exposure in North America, UK, and APAC financial hubs | Short term (≤ 2 years) |
| Rising Business Email Compromise and Credential Misuse | +2.6% | North America and Europe, with growing incidence in APAC | Short term (≤ 2 years) |
| Cyber-Insurance and Regulatory Evidence Requirements | +2.1% | North America and EU core, with spillover to Middle East and APAC through multinational supply chains | Medium term (2-4 years) |
| Expansion of Zero-Trust and Continuous Verification | +1.6% | Global, with early gains in North America, Germany, and Singapore | Medium term (2-4 years) |
| Growing Adoption of Behavioral Risk-Based Security Programs | +1.2% | North America, Western Europe, and Australia | Medium term (2-4 years) |
| Increasing Demand for Real-Time Security Coaching | +0.9% | Global, with concentration in large-enterprise North America and UK markets | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Increasing AI-Enabled Phishing and Social Engineering
Generative AI has reduced the effort, time, and specialized skills once required to create targeted social engineering campaigns. KnowBe4 reported a 17.1% rise in phishing attacks during the second half of 2025, showing that the exposure is growing as these tools become easier to use. Its global pre-training phish-prone percentage was 33.2%, and the measure reached 39.5% at enterprises with at least 10,000 employees.[1] Voice cloning and AI-generated video have broadened the channels security teams must cover beyond the familiar email-based examples. The human risk management market, therefore, favors adaptive content that changes with active threats rather than annual programs focused mainly on completion. Organizations using continuous AI-supported training reduced their phish-prone percentage to 4.2% after 12 months, an 87% reduction from the reported baseline.
Rising Business Email Compromise and Credential Misuse
Business email compromise has made employee judgment and behavioral response a more important part of email security programs. The FBI recorded USD 3.046 billion in business email compromise losses across 24,768 complaints in 2025, reflecting the financial significance of this attack category.[2] The reported average loss was USD 123,000 per complaint, and the category was 109 times more costly per complaint than phishing alone. Mimecast found that 48% of respondents saw increased business email compromise activity in the prior year, while 38% still relied only on native email security controls. The same research indicated that 8% of users can account for 80% of human-layer risk at a typical organization, making broad, uniform training less precise. This pattern supports demand for individual risk scoring and targeted intervention in the human risk management market.
Cyber-Insurance and Regulatory Evidence Requirements
Insurers and regulators increasingly expect records that demonstrate a recurring, documented, and reviewable employee training program. Total cybercrime losses exceeded USD 20 billion in the FBI’s 2025 reporting, reinforcing attention to controls that insurers may consider during underwriting. ISO/IEC 27001:2022, the NIS2 Directive, and the NIST Cybersecurity Framework 2.0 each reinforce the role of awareness and training as auditable controls. The Digital Operational Resilience Act has required role-appropriate ICT security awareness training for staff at financial entities since January 2025. This combination makes evidence of employee training relevant to governance, financial risk, audit review, and ongoing compliance discussions. It also gives providers in the human risk management market a basis for positioning documentation, reporting, and renewal support alongside course content.
Expansion of Zero-Trust and Continuous Verification
Zero-trust deployment makes employee decisions more visible within access security because identity verification depends on routine user actions. Credential handling, use of multifactor authentication, and consent choices can affect the reliability of identity-based controls across an organization. A 2025 peer-reviewed framework showed that knowledge, compliance behavior, and training completion can be combined to distinguish employees with different cybersecurity risk profiles. This supports the use of training data alongside security information and event management, extended detection and response, and identity governance processes. Living Security described human risk as a changing trajectory rather than a fixed employee label, using data from more than 100 organizations and over 200 real-time risk signals. The human risk management market is consequently becoming more connected to wider security operations and access management workflows.
Restraints Impact Analysis of Human Risk Management Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Employee Training Fatigue and Declining Engagement | -2.0% | Global, most acute in large enterprises across North America and Western Europe with established programs | Short term (≤ 2 years) |
| Privacy Restrictions on Individual Behavioral Scoring | -1.5% | EU, UK, California, and Brazil | Medium term (2-4 years) |
| Difficulty Demonstrating Direct Financial ROI | -1.2% | Global, most pronounced in cost-pressured SMEs and public-sector buyers | Medium term (2-4 years) |
| Integration Complexity Across Security and Identity Systems | -0.8% | North America and EU, where security stacks are deepest and most siloed | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Employee Training Fatigue and Declining Engagement
Training fatigue can limit the value organizations gain from awareness programs that use the same format or ask too much of employees. MetaCompliance found that 81% of 200 surveyed CISOs said programs fail when human cyber risk is treated only as a training issue rather than a risk management challenge.[3] The study also found that 25% had difficulty gaining employee attention despite allocating 15% of annual security budgets to awareness. Static and session-heavy courses can increase the time burden on employees and managers already managing operational demands. SoSafe reported 90% knowledge retention after 12 months through its platform approach, thereby supporting the use of shorter, role-specific formats. Providers in the human risk management market need to support regular learning without creating repetitive demands that weaken engagement.
Privacy Restrictions on Individual Behavioral Scoring
Individual behavioral scoring faces data protection constraints in regions where privacy laws limit the use of significant automated profiling. GDPR Article 22 can create obligations when automated profiling has legal or similarly significant effects on an individual employee. Training results, authentication logs, email interactions, and external exposure data may require a common legal basis when used within one risk profile. Living Security’s human risk dataset illustrates the breadth of signals that a platform can seek to combine for this purpose. Many mid-market buyers lack the internal capacity to establish and administer the required data governance arrangements. Privacy-preserving approaches based on aggregate signals can help the human risk management market serve buyers who need visibility into risk without individual attribution.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Human Risk Management Market Segment Analysis
By Component:
Software Leads, Services Expand Through Managed DemandSoftware held 61.89% of the human risk management market share in 2025. The result reflected mature platform deployment among large enterprises with centralized security teams. These buyers use integrated software-as-a-service consoles for phishing simulations, content management, behavioral analytics, reporting, and employee activity management. A common platform supports documented evidence across large staff populations and recurring security programs. The integrated model differs from project-based services, where costs vary with scope, support needs, and timing.
Long-term platform agreements and compliance-related renewals have historically supported recurring software spending in enterprise accounts. Services are projected to expand at a CAGR of 16.36% from 2026 to 2031 as SMEs and mid-market organizations outsource program administration. ESET found that 87% of SMBs considered cybersecurity training critical, while only 28% operated comprehensive programs that included phishing simulations.[4] This gap leaves a practical role for managed service partners supporting smaller organizations without established internal programs. Proofpoint completed its acquisition of Hornet Security in December 2025, expanding its managed awareness capability through an MSP-focused business serving more than 120 countries.


By Deployment Mode:
Cloud Delivery Changes Training EconomicsCloud-based deployment held 73.18% of the human risk management market share in 2025. It is also projected to expand at a CAGR of 18.29% from 2026 to 2031. Cloud tools can update content in response to current threat intelligence without local infrastructure updates. They remove the need to provide and maintain dedicated training systems. This model makes it easier to run common programs across distributed workforces and business locations.
Connections to Microsoft 365 identity layers have supported the move away from legacy on-premises installations. On-premises systems remain relevant for defense, critical infrastructure, and government bodies that have data sovereignty requirements. Hybrid deployment can support large enterprises that are moving sensitive workloads or systems to the cloud. KnowBe4 introduced an AI-native platform in May 2026 with AIDA Orchestration agents that manage personalized training for individual users. The cloud-native product reinforces why scalable, intelligence-linked cloud delivery remains central to the human risk management market.
By Organization Size:
Large Enterprises Lead, SMEs Narrow the GapLarge enterprises accounted for 69.26% of the human risk management market size in 2025. Multi-year contracts, enterprise-wide seat licensing, and board-level responsibility for documented training supported their leading position. These organizations commonly have the security teams and IT budgets needed to administer broad employee programs. They can support the integration work that connects training tools to email, identity, and security systems. Historically, this procurement structure made enterprise-wide platforms less accessible to smaller organizations.
SMEs are projected to expand at a CAGR of 15.84% from 2026 to 2031. Cloud-native pricing and managed security service bundles have reduced barriers linked to minimum seat requirements and limited internal capacity. ESET found that 81% of SMBs that had experienced multiple security incidents adopted frequent training. A 2025 study of Swedish SMEs associated limited training with resource constraints and misperceptions of cyber risk.[5] Pricing, packaging, and managed delivery are helping SMEs participate more actively in the security awareness training industry.

By End-Use Industry:
BFSI Anchors Spending, Healthcare Gains MomentumBFSI accounted for 27.39% of the human risk management market in 2025. Targeted financial fraud and a high concentration of sensitive information make recurring employee conditioning relevant to this sector’s controls. Financial institutions require staff to recognize phishing attempts, credential misuse, and fraudulent payment requests. The need for evidence of training also fits the governance and audit requirements common in this sector. KnowBe4 recorded a 38.1% baseline phish-prone percentage for insurance, the second-highest value in its sector comparison.
The healthcare and life sciences industry is projected to expand at a CAGR of 16.37% from 2026 to 2031. The sector had a 42.7% baseline phish-prone percentage, the highest level in KnowBe4’s industry data. Clinical workflows, varied staff groups, and a broad connected-device environment contribute to this exposure. Healthcare organizations reached a post-training phish-prone percentage of 5% after 12 months of continuous training. Government, public administration, IT, and telecommunications support additional demand through national strategies and recurring credential risks.
Geography Analysis
North America Human Risk Management Market
North America held 41.37% of global revenue in 2025. Deep enterprise procurement cycles, mature managed service ecosystems, and senior leadership accountability supported this position. The United States remained the largest source of regional revenue because financial services, healthcare, and technology organizations maintained high per-seat spending. ESET found that 93% of North American SMBs considered cybersecurity training critical, the highest result in its global survey. North America accounted for 41.37% of global revenue in 2025. Deep enterprise procurement cycles, mature managed service ecosystems, and senior leadership accountability supported this position. The United States remained the largest source of regional revenue because financial services, healthcare, and technology organizations maintained high per-seat spending. ESET found that 93% of North American SMBs considered cybersecurity training critical, the highest result in its global survey.
Europe Human Risk Management Market
Europe has a regulation-led demand profile with opportunities in DACH and Southern European markets. NIS2 readiness and the Digital Operational Resilience Act have strengthened the need for documented, role-appropriate employee training. These requirements give compliant providers a clear basis for addressing audit and governance needs. European buyers also face privacy requirements that can limit the use of individual behavioral scoring.
APAC, MEA and South America Human Risk Management Market
Asia-Pacific is projected to expand at a CAGR of 18.96% from 2026 to 2031. Japan, India, China, South Korea, and Singapore are supporting demand as digital activity and security investment increase. Cloud-native delivery is widely used from the outset, reducing migration constraints that affect more mature markets. The Middle East and Africa have a demand for capacity building through national cybersecurity programs, while South America has shown measurable training outcomes. KnowBe4 recorded a one-year residual phish-prone percentage of 7.4% in Africa and 3.3% in South America.
Competitive Landscape
Market Concentration
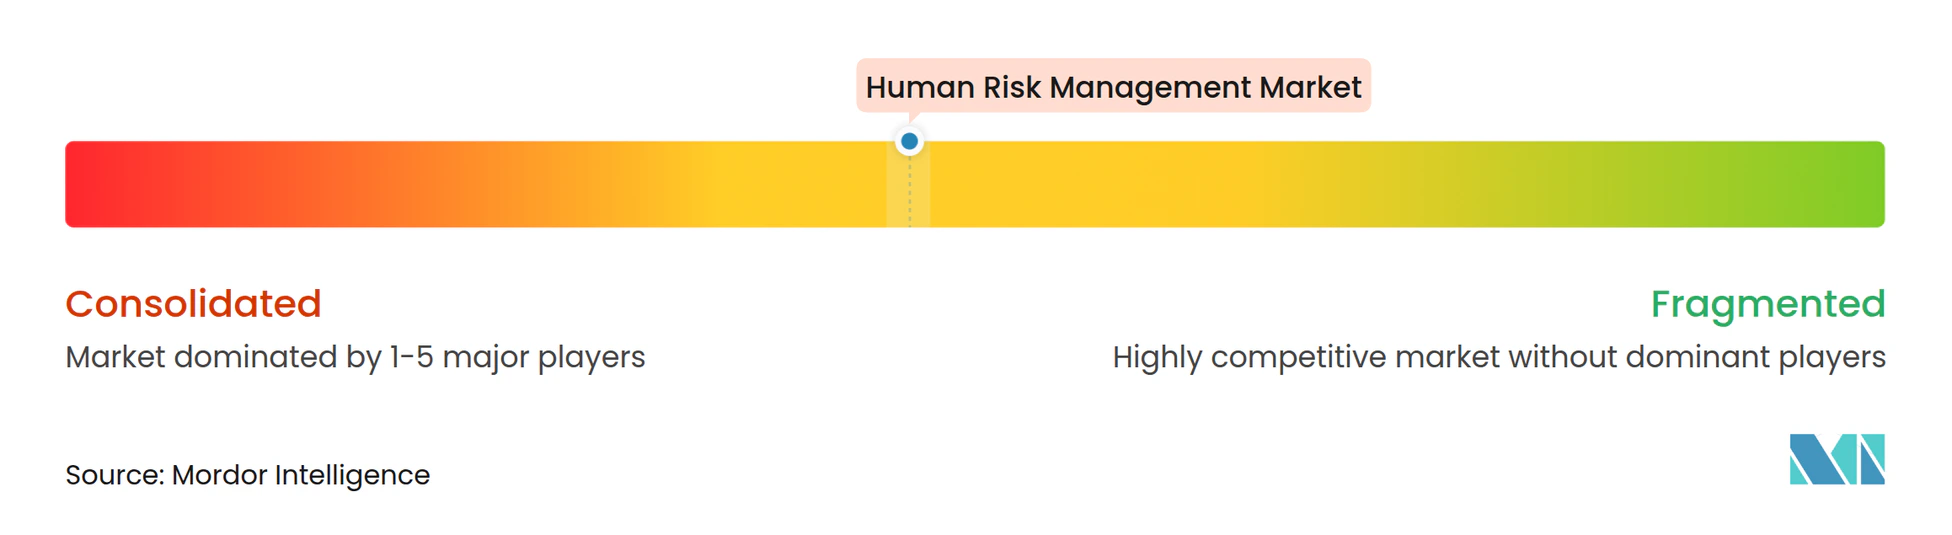
The human risk management market is moderately consolidated at the platform layer and fragmented among smaller providers. KnowBe4 and Proofpoint have the largest combined enterprise presence in the supplied material. SoSafe, Hoxhunt, IRONSCALES, CybSafe, OutThink, and Living Security compete through behavioral science, AI-native product design, or regional fit. Vendors generally follow a full-suite platform model, a human risk management model, or MSP distribution for mid-market and SME customers.
Full-suite providers combine phishing simulation, learning content, and behavioral analytics under one license. Human risk management specialists differentiate through individual scoring and links to identity-related tools. MSP-oriented vendors focus on customers without dedicated security staff. Privacy-preserving risk scoring, multi-channel deepfake simulation, and financial-loss evidence remain areas of product development.
Broader cybersecurity providers such as Arctic Wolf, Trend Micro, and Fortinet are incorporating awareness training into wider security operations offerings. This creates pricing pressure for standalone providers whose main distinction is training content. Fortinet’s FortiSAT uses AI-based attack path analysis to deliver training to users identified as high risk. Proofpoint completed the Hornetsecurity acquisition in December 2025 to expand its MSP channel reach and its addressable SME base.[6] KnowBe4 launched its AI-native Security Awareness Training platform in May 2026, adding autonomous program administration capabilities.
Human Risk Management Industry Leaders
-
KnowBe4, Inc.
-
Proofpoint, Inc.
-
Mimecast Limited
-
Hoxhunt Oy
-
Cofense, Inc.
- *Disclaimer: Major Players sorted in no particular order
Human Risk Management Market Companies Covered in this Report
- KnowBe4, Inc.
- Proofpoint, Inc.
- Mimecast Limited
- Hoxhunt Oy
- Cofense, Inc.
- OutThink Limited
- Living Security, Inc.
- CybSafe Limited
- CultureAI Limited
- IRONSCALES, Inc.
- SoSafe GmbH
- NINJIO, Inc.
- AwareGO ehf.
- Phished B.V.
- Terranova Worldwide Corporation
- Escal Institute of Advanced Technologies, Inc.
- TitanHQ Limited
- Inspired eLearning, LLC
- Hook Security, Inc.
- Cimento Technologies, Inc.
- Zepo Technologies, Inc.
- Phish Defense, Inc.
- HookPhish, Inc.
- Arctic Wolf Networks, Inc.
- Trend Micro Incorporated
- Fortinet, Inc.
Recent Industry Developments in Human Risk Management Market
- May 2026: KnowBe4 launched its AI-native Security Awareness Training platform in a 2-tier structure, SAT Advanced and SAT Foundation, bundling its AIDA suite of AI Defense Agents with a Custom AI Video Builder that generates narrated training videos across 160-plus languages, marking a strategic pivot toward autonomous program administration.
- February 2026: KnowBe4 released AIDA Orchestration, the first fully autonomous AI agent for human risk management, independently creating, scheduling, and adapting personalized phishing security tests at the individual-user level. Internal data indicated that AIDA customers reduced their risk score by 3 times compared to non-AIDA users.
- February 2026: Proofpoint announced a strategic partnership with Concentrix to deliver human- and agent-centric cybersecurity across Asia-Pacific, integrating Proofpoint's security platform into Concentrix's Security Operations Center managed services for enterprise and SMB customers.
- December 2025: Proofpoint completed its acquisition of Hornetsecurity Group, a pan-European provider of AI-powered Microsoft 365 security, compliance, and security awareness services operating across more than 120 countries, significantly extending Proofpoint's MSP channel footprint and SME addressable market.
Global Human Risk Management Market Report Scope
The human risk management market encompasses solutions that identify, assess, and mitigate security risks stemming from human behavior, including insider threats, accidental data exposure, credential compromise, and social engineering attacks. This market includes user and entity behavior analytics (UEBA) platforms that detect anomalous user activity, security awareness training and phishing simulation tools, privileged access management (PAM) solutions, and data loss prevention (DLP) systems that monitor and control users' access to sensitive data. Solutions focus on quantifying human-centric risk through behavioral baselines, implementing adaptive access controls based on risk scores, providing just-in-time security coaching, and enabling organizations to measure and reduce insider threat exposure, the impact of credential theft, and accidental security policy violations across their workforce.
The Human Risk Management Market Report is Segmented by Component (Software, and Services [Managed Serevices, and Professional Services]), Deployment (Cloud-Based, On-Premises, and Hybrid), Organization Size (Large Enterprises, and Small and Medium-Sized Enterprises), End Use Industry (Government and Public Administration, Industrial Manufacturing, Retail and E-Commerce, Transportation and Logistics, Energy and Utilities, IT and Telecommunication, Media and Entertainment, Education and Research Institutions, Healthcare and Life Sciences, Banking, Financial Services, and Insurance (BFSI), and Other End Use Industries), and Geography (North America, South America, Europe, Asia-Pacific, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Segmentation Overview
| Software | |
| Services | Managed Serevices |
| Professional Services |
| Cloud |
| On-Premises |
| Hybrid |
| Large Enterprises |
| Small and Medium-Sized Enterprises |
| Government and Public Administration |
| Industrial Manufacturing |
| Retail and E-Commerce |
| Transportation and Logistics |
| Energy and Utilities |
| IT and Telecommunication |
| Media and Entertainment |
| Education and Research Institutions |
| Healthcare and Life Sciences |
| Banking, Financial Services, and Insurance (BFSI) |
| Other End Use Industries |
| North America | United States |
| Canada | |
| South America | Brazil |
| Argentina | |
| Mexico | |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| France | |
| Italy | |
| Spain | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| South Korea | |
| Australia | |
| Singapore | |
| Malaysia | |
| Rest of Asia-Pacific | |
| Middle East | United Arab Emirates |
| Saudi Arabia | |
| Turkey | |
| Israel | |
| Rest of Middle East | |
| Africa | South Africa |
| Nigeria | |
| Egypt | |
| Kenya | |
| Rest of Africa |
| By Component | Software | |
| Services | Managed Serevices | |
| Professional Services | ||
| By Deployment | Cloud | |
| On-Premises | ||
| Hybrid | ||
| By Organization Size | Large Enterprises | |
| Small and Medium-Sized Enterprises | ||
| By End Use Industry | Government and Public Administration | |
| Industrial Manufacturing | ||
| Retail and E-Commerce | ||
| Transportation and Logistics | ||
| Energy and Utilities | ||
| IT and Telecommunication | ||
| Media and Entertainment | ||
| Education and Research Institutions | ||
| Healthcare and Life Sciences | ||
| Banking, Financial Services, and Insurance (BFSI) | ||
| Other End Use Industries | ||
| By Geography | North America | United States |
| Canada | ||
| South America | Brazil | |
| Argentina | ||
| Mexico | ||
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| France | ||
| Italy | ||
| Spain | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| South Korea | ||
| Australia | ||
| Singapore | ||
| Malaysia | ||
| Rest of Asia-Pacific | ||
| Middle East | United Arab Emirates | |
| Saudi Arabia | ||
| Turkey | ||
| Israel | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Nigeria | ||
| Egypt | ||
| Kenya | ||
| Rest of Africa | ||
Key Questions Answered in the Report
What is the current size of the human risk management market?
The human risk management market size was valued at USD 3.71 billion in 2025 and estimated to grow from USD 4.12 billion in 2026 to reach USD 7.69 billion by 2031, at a CAGR of 13.29% during the forecast period (2026-2031).
What is driving adoption of security awareness training?
AI-enabled phishing, business email compromise, documented compliance requirements, and identity-related security needs are supporting adoption. The security awareness training market favors programs that adjust to threats and show clear employee participation records.
Which deployment model leads security awareness training?
Cloud-based delivery held 73.18% of revenue in 2025 and is projected to expand at a CAGR of 18.29% through 2031. The security awareness training market benefits from cloud tools that update content and support identity system connections without local infrastructure provisioning.
Which organizations are increasing investment in employee awareness programs?
Large enterprises led revenue in 2025, while SMEs are projected to expand at a CAGR of 15.84% through 2031 as cloud and managed services reduce barriers. The security awareness training market is reaching smaller buyers through managed program delivery and flexible pricing.
Which end-use sector is growing fastest for security awareness training?
Healthcare and life sciences are projected to expand at a CAGR of 16.37% through 2031, supported by the highest baseline phish-prone percentage in the source data. This security awareness training market demand reflects varied workforces, clinical workflows, and wide device exposure.
Which region is projected to grow fastest through 2031?
Asia-Pacific is projected to expand at a CAGR of 18.96%, supported by digitalization and cloud-native adoption across major regional economies. The security awareness training market benefits where cloud delivery reduces the need for a long migration from local systems.