
Europe Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
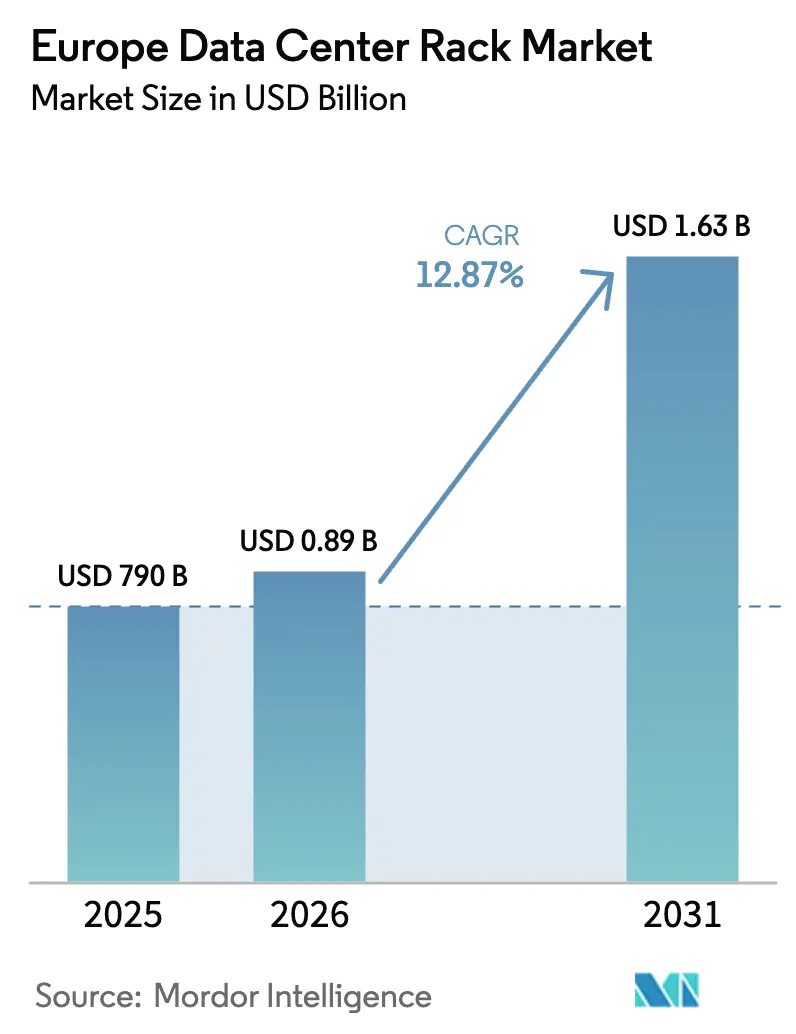
| Base Year Market Size (2025) | USD 790 Billion |
| Market Size (2026) | USD 0.89 Billion |
| Market Size (2031) | USD 1.63 Billion |
| Growth Rate (2026 - 2031) | 12.87 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Data Center Rack Market Analysis by Mordor Intelligence
The Europe data center rack market size in 2026 is estimated at USD 891.7 million, growing from 2025 value of USD 790 million with 2031 projections showing USD 1.63 billion, growing at 12.87% CAGR over 2026-2031. Strong demand reflects regulatory commitments to local data processing, a sharp rise in hyperscale construction, and an industry-wide move to liquid-cooled, 1 MW rack configurations that support artificial intelligence workloads. Operators now treat thermal management as a core design variable, prompting rapid upgrades from air-cooled to integrated liquid solutions. Procurement strategies increasingly favor standardized open-rack designs that shorten build cycles, align with new energy-efficiency mandates, and reduce total cost of ownership. Materials innovation, led by aluminum adoption, underscores the drive for lighter frames that dissipate heat more effectively and facilitate quick installation across expanding European campuses.
Key Report Takeaways
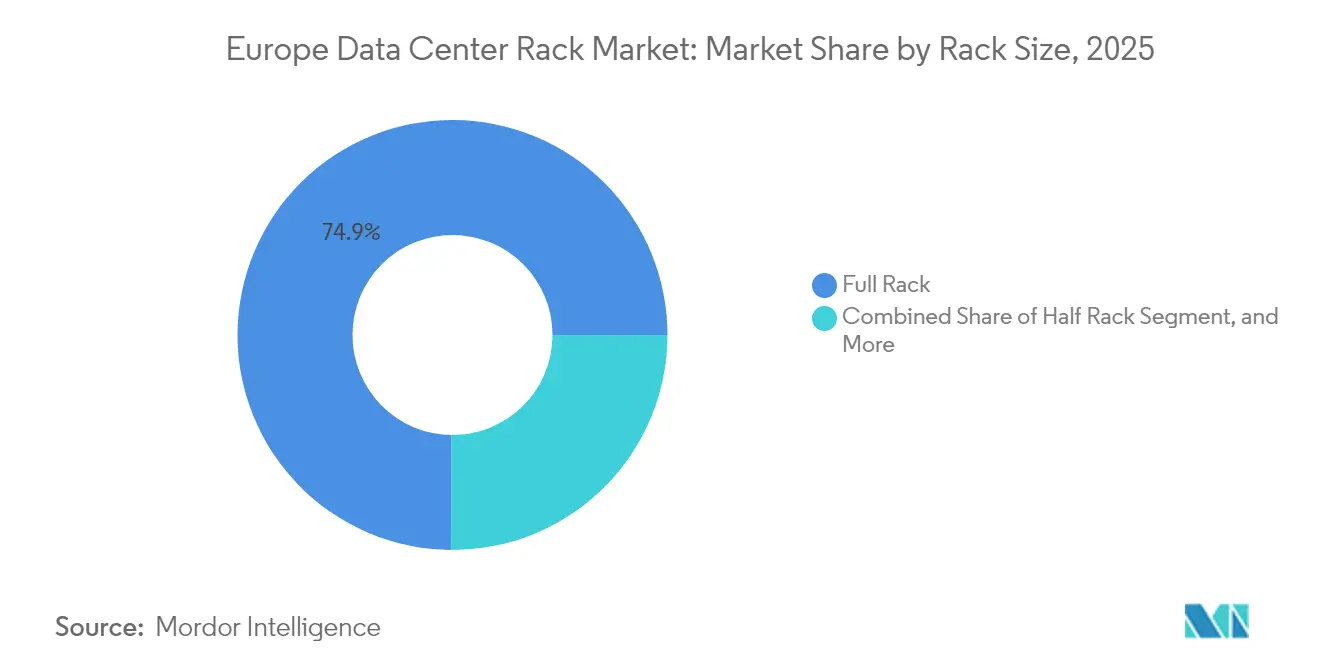
- By rack size, full racks held 74.88% revenue share in 2025; quarter racks posted the highest 15.02% CAGR through 2031.
- By rack height, the 42U format commanded 60.95% of the Europe data center rack market share in 2025, while 48U tallied the fastest 17.05% CAGR to 2031.
- By rack type, cabinet enclosures secured 81.75% share in 2025 and are advancing at a 15.95% CAGR through the forecast period.
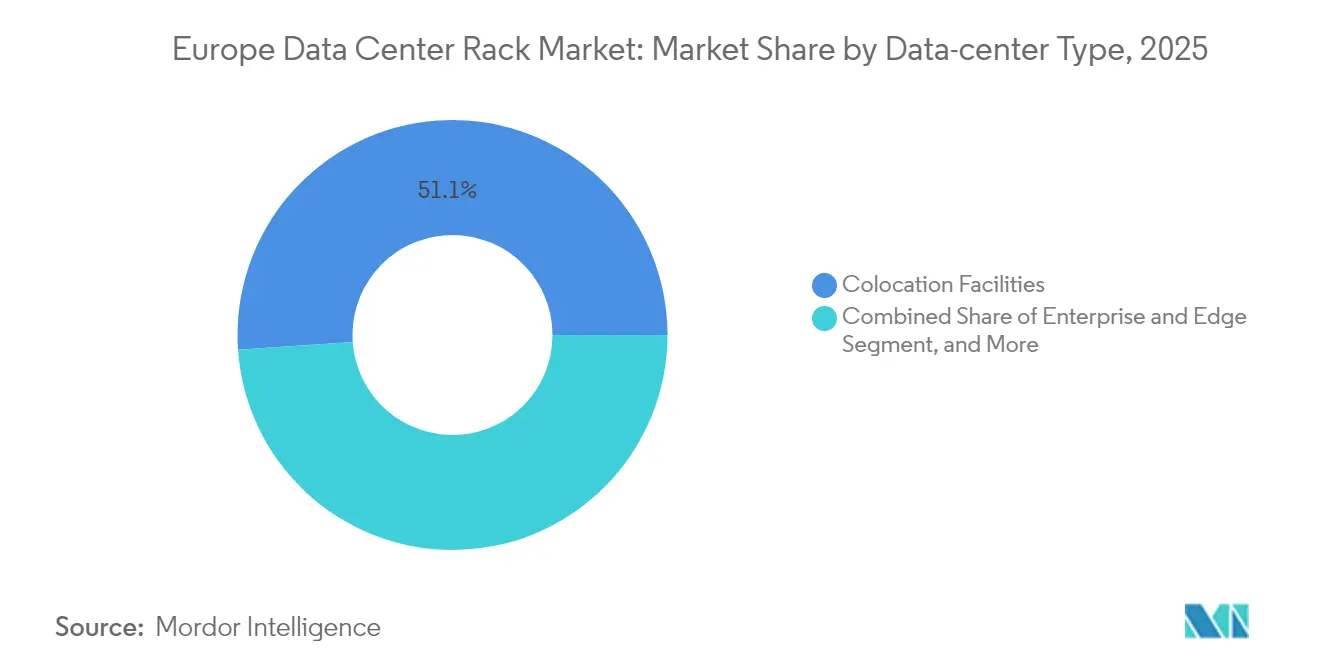
- By data center type, colocation facilities accounted for 51.10% of the Europe data center rack market size in 2025, whereas hyperscale and cloud facilities are expanding at a 14.35% CAGR to 2031.
- By material, steel retained 82.85% share in 2025, yet aluminum records the quickest 16.55% CAGR over 2026-2031.
- By country, Germany led with 18.95% share in 2025, while Ireland is set to grow at 15.85% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Europe Data Center Rack Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid hyperscale expansion | +3.2% | Germany, Netherlands, Ireland, France | Medium term (2-4 years) |
| Rising adoption of high-density computing | +2.8% | FLAP-D hubs | Short term (≤ 2 years) |
| Government digitalisation initiatives | +1.9% | EU-wide, Nordic focus | Long term (≥ 4 years) |
| Growth of colocation services | +2.1% | Western and Eastern Europe | Medium term (2-4 years) |
| Shift to OCP-compliant open-rack designs | +1.4% | Netherlands, Germany, Nordics | Medium term (2-4 years) |
| Surge of edge micro-data centers | +1.6% | Spain, Italy, Poland | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rapid Hyperscale Expansion
Hyperscale operators are rolling out capacity at an unprecedented cadence across the continent, making standard 1 MW racks commonplace instead of experimental. Project timelines now compress to months, compelling suppliers to pre-engineer modular frames that arrive ready for liquid cooling. Sovereign data rules amplify this momentum because global cloud providers must localize processing inside national borders. Bulk orders in the tens of thousands of units drive economies of scale, allowing hyperscalers to dictate design parameters that become de facto European benchmarks. The resulting volume lifts the Europe data center rack market by accelerating replacement cycles at existing campuses and doubling footprints at new greenfield sites.[1]European Commission, “Digital Decade Policy Program,” EUROPA.EU
Rising Adoption of High-Density Computing
Artificial intelligence and machine-learning clusters now consume up to 500 kW per rack, far exceeding the airflow limits of legacy frames. European facilities respond by adopting direct-to-chip or immersion cooling modules that bolt into new rack designs. Thermal performance becomes a lead specification, prompting manufacturers to embed coolant manifolds, heat exchangers, and redundant pump kits within the rack envelope. High-density rollouts no longer stay inside hyperscale walls; research labs, automotive design houses, and financial traders also procure specialized frames, expanding the addressable market. These deployments shorten refresh intervals because GPU roadmaps outpace earlier server generations, pushing the Europe data center rack market toward higher unit sales.[2]Research Institutes of Sweden Team, “Thermal Management for High-Density Racks,” RISE.SE
Government Digitalisation Initiatives
The European Union’s Digital Decade targets that 75% of enterprises adopt cloud, big data, or AI by 2030, and this policy steers public and private investment into new capacity. National programs in France, Germany, and the Nordics provide tax incentives for domestically sourced equipment, including racks built with recycled steel or low-carbon aluminum. Operators bidding on government workloads must document supply-chain provenance and energy performance, rewarding vendors that integrate monitoring sensors and power-usage-effectiveness dashboards at the factory stage. Such policy-driven demand gives European manufacturers a competitive edge and stabilizes long-term order pipelines.[3]Eurostat Staff, “Digital Economy and Society Statistics,” EUROSTAT.EC.EUROPA.EU
Growth of Colocation Services
Institutional capital flows into European colocation continue to rise, fueled by enterprises divesting on-premise IT rooms in favor of shared facilities that guarantee compliance and uptime. Colocation providers differentiate by offering pre-cabled, high-density racks certified for GPU clusters alongside standard enterprise SKUs. Multi-tenant environments require flexible load ratings, secure side panels, and adjustable airflow baffles, spurring innovation among rack vendors. Standardization across portfolios reduces maintenance costs, while scalable design options attract tenants from varied industries. This virtuous cycle enlarges the Europe data center rack market because every new colocation hall launches with thousands of cabinets installed on day one.
Restraints Impact Analysis of Europe Data Center Rack Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High initial CAPEX of advanced racks | −1.8% | Smaller European markets | Short term (≤ 2 years) |
| Supply-chain disruptions and steel volatility | −1.2% | EU manufacturing hubs | Medium term (2-4 years) |
| Stringent energy-efficiency regulations | −0.9% | Germany, Netherlands, Denmark | Long term (≥ 4 years) |
| Skilled rack-integration talent shortage | −1.1% | Western and Eastern Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Initial CAPEX of Advanced Racks
Liquid-cooled frames with integrated manifolds and redundant busbars cost three to four times more than traditional air-cooled cabinets. Smaller enterprises hesitate to absorb this premium without clear return-on-investment projections, especially when workloads remain below 50 kW per rack. Colocation operators must balance premium SKU demand with price-sensitive tenants, often delaying full-scale rollouts until anchor customers sign. National incentive programs vary widely, creating a patchwork of subsidy eligibility that complicates budgeting. These financial hurdles slow adoption velocity and shave points off the Europe data center rack market CAGR during the next two years.
Limited Availability of Skilled Rack-Integration Technicians
European operators report that one in two projects experiences staffing delays because crews trained on liquid cooling, high-voltage wiring, and leak-detection maintenance are scarce. The skill shortage lengthens commissioning timelines and forces premium pay rates that inflate total project cost. Apprenticeship programs lag behind technology evolution, leaving new graduates unfamiliar with immersion baths or dielectric fluid handling. Edge deployments in tier-2 cities face even steeper challenges because specialists gravitate to established FLAP-D hubs. Unless training capacity scales quickly, technician scarcity will cap the ramp-up speed of advanced racks and temper growth prospects.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Europe Data Center Rack Market Segment Analysis
By Rack Size:
Full Racks Propel Density GainsFull racks generated the bulk of unit demand and captured 74.88% share in 2025, a dominance that continues as enterprises consolidate scattered half-rack footprints into fewer, denser enclosures. This format now anchors large orders from colocation and hyperscale campuses, each seeking uniform rows that simplify power whips and cooling manifolds. Wider frames support side-to-side cooling loops and heavy immersion tanks, features essential for AI clusters. At the opposite end, quarter racks remain favored in retail branches and micro-edge shelters where floor space is expensive. Supply-chain efficiencies accrue because vendors mass-produce accessories, cable trays, and rear-door heat exchangers sized for full racks, further reinforcing their leadership in the Europe data center rack market.
Operators also appreciate full racks for lifecycle economics. Uniform dimensions allow reuse during data hall revamps, reducing capital outlay. Service teams carry fewer spare kits, and monitoring software can apply one template across thousands of identical cabinets. The Europe data center rack industry views these attributes as critical when forecasting workloads that may double inside five years, especially as new chip roadmaps demand ever greater wattage per square meter. Consequently, full racks will remain the primary growth engine even as niche sizes sustain specialized roles.


By Rack Height:
48U Configurations Maximize Retrofit ValueWhile the legacy 42U height retained 60.95% share in 2025, demand now swings toward 48U alternatives that yield six extra unit positions without raising ceiling height requirements. Facility owners prefer this incremental density gain because it avoids structural renovation yet creates room for power distribution units and liquid manifold trays. High-growth sectors such as automotive design, genomic research, and financial analytics load heavy GPU nodes that benefit from the added vertical clearance. The Europe data center rack market size for 48U models is projected to expand at 17.05% CAGR, outpacing every other height category.
The taller format also simplifies cable management by separating network, power, and cooling bundles into distinct vertical zones. Manufacturers respond by reinforcing frame torsion tolerance to counterbalance uneven weight distribution in partially populated cabinets. As racks approach 1 MW power loads, stability under vibration and thermal expansion becomes critical. Height evolution thus mirrors the overall trajectory toward higher density and integrated fluid cooling, reinforcing 48U’s ascent throughout new build and retrofit programs.
By Rack Type:
Cabinet Enclosures Deliver Secure, Controlled EnvironmentsCabinet designs dominated 81.75% of installations in 2025 because enclosed frames protect mission-critical hardware from unauthorized contact, dust ingress, and electromagnetic interference. Enclosures also let operators implement hot-aisle or cold-aisle containment more effectively by regulating intake and exhaust airflow. The shift toward liquid cooling intensifies cabinet adoption since door-mounted heat exchangers and side-walled distribution plates attach easily to closed frames. Consequently, cabinet shipments grow at a 15.95% CAGR, further lifting the Europe data center rack market.
Open-frame racks continue to serve non-production labs and secure staging areas where technicians need rapid component access. Wall-mount variants occupy edge closets in retail stores and cell towers, offering a compact footprint for limited-scale workloads. Even so, demand concentration remains solidly behind cabinet enclosures because European data protection rules increasingly classify the rack itself as part of the security perimeter. Manufacturers strengthen doors, hinges, and lock sets to meet evolving compliance audits, reinforcing the trend toward enclosed architectures.
By Data Center Type:
Colocation Dominates, Hyperscale AcceleratesColocation facilities absorbed 51.10% of rack shipments in 2025, reflecting enterprise migration from on-premise server rooms toward professional hosting environments. Uniform cabinet rows simplify multi-tenant layouts, and service-level agreements require racks with integrated environmental monitoring. However, hyperscale and cloud platforms represent the fastest growing deployment model at 14.35% CAGR, propelled by AI cluster expansion and sovereign cloud mandates. Hyperscalers negotiate direct agreements with rack manufacturers, often stipulating OCP-compatible frames tailored for liquid cooling and robotic deployment. These orders come in unprecedented volumes, giving suppliers firm visibility into multiyear pipelines and galvanizing the Europe data center rack market.
Enterprise and edge categories continue to serve specialized use cases such as latency-sensitive industrial automation and healthcare imaging. Edge rollouts favor shallow, climate-sealed micro cabinets that withstand warehouse dust, factory vibration, or remote outdoor placement. Vendors broaden their catalogs to include ruggedized models, yet overall volume remains modest compared with core colocation and hyperscale segments.
By Material:
Aluminum Gains Ground on Steel DominanceSteel remained the workhorse material at 82.85% share in 2025 thanks to its strength-to-price advantage and long-standing production infrastructure. Nonetheless, aluminum shipments are rising 16.55% annually because lighter frames reduce floor loading and freight costs while enhancing thermal dispersion. Alloy development now matches steel in tensile strength, enabling racks that hold 1 MW liquid baths without deformation. The European Green Deal also spotlights embodied carbon, pushing operators toward recyclable metals with lower upstream emissions. This policy tailwind extends aluminum’s appeal across Ireland, the Netherlands, and Nordic markets where renewable energy smelting further lowers lifecycle footprints. Continued innovation in extruded profiles and modular joint systems will expand aluminum’s role in the Europe data center rack market without eliminating steel’s cost-driven presence.
Hybrid designs emerge as a compromise, combining steel posts for structural rigidity with aluminum panels and doors for weight savings. Such blends optimize cost, strength, and heat conduction. Manufacturers invest in multi-metal fabrication lines capable of mixing materials on the same production run, providing customers flexibility while mitigating commodity price volatility.
Geography Analysis
Germany Data Center Rack Market
Germany maintained pole position with 18.95% share in 2025 because Frankfurt anchors the continent’s largest internet exchange and attracts capital stacks exceeding EUR 2.9 billion (USD 3.36 billion) annually for new data center infrastructure. Operators in Frankfurt, Berlin, and Munich collectively manage over 2,700 MW of IT capacity, and compliance with the national Energy Efficiency Act drives adoption of racks with embedded power-usage-effectiveness sensors. Local demand also benefits from industrial enterprises running digital twins and real-time analytics that require onsite GPU clusters. Germany’s mature ecosystem of integrators, component suppliers, and logistic corridors accelerates deployment cycles, reinforcing its leadership in the Europe data center rack market.
Ireland Data Center Rack Market
Ireland, while smaller in absolute terms, advances at a 15.85% CAGR because hyperscale investors value its wind-rich energy grid and data sovereignty alignment inside the European Union. New campuses near Dublin integrate racks rated for immersion tanks to exploit cooler ambient temperatures, supporting AI clusters with power densities above 350 kW per cabinet. Government incentives and rapid grid-connection approvals further ease expansion, turning Ireland into a strategic redundancy node for U.S. and Asian cloud providers. These dynamics enlarge the Europe data center rack market size for Irish facilities well beyond what historical population metrics might suggest.
Broader European Markets
Elsewhere, the Netherlands, Switzerland, and Nordic nations each carve specialized niches. Amsterdam remains a connectivity hot spot despite local moratoria, so operators optimize existing halls by switching to 48U aluminum racks that squeeze more compute into legacy footprints. Switzerland’s strict confidentiality standards spur demand for domestically manufactured racks with tamper-evident seals. Denmark, Sweden, and Norway exploit hydropower and free-air cooling to attract green-minded tenants, installing cabinet enclosures equipped with door heat exchangers that leverage naturally low temperatures. Eastern European countries, led by Poland, offer lower land costs and improving fiber routes, prompting edge deployments that pair compact racks with modular power pods. Collectively, these diverse geographic strategies broaden the Europe data center rack market footprint and distribute growth beyond the traditional FLAP-D corridor.
Regulatory Landscape
The European Union Energy Efficiency Directive (EU) 2023/1791 requires energy performance monitoring and reporting for data centers with installed IT power demand of at least 500 kW. That obligation pushes operators to instrument power, cooling, and utilization, which then feeds into how racks are specified and integrated. Delegated Regulation (EU) 2024/1364 sets the reporting methodology and sustainability KPIs, further reinforcing demand for telemetry-ready cabinet designs, metered PDUs, and rack-level thermal measurement that can be used in standardized reporting.
Standardization work is also shaping rack requirements. CENELEC is progressing prEN 50600-5-1, a maturity model for energy management and sustainability, with a review closing date of March 27, 2026. This gives operators and auditors another reference point when defining infrastructure specs. Alongside this, the European Commission maintains a 2030 carbon-neutral data center policy direction, increasing procurement weight for low-carbon materials, heat-reuse integration, and demonstrable efficiency performance in both new builds and major retrofits.
Value Chain Analysis
The value chain begins with upstream metals and fabricated components, with steel and, increasingly, aluminum frames, doors, panels, and fasteners. It then moves into enclosure manufacturing and the integration of rack-adjacent systems, including busbars/PDUs, cable management, sensors, and liquid-cooling interfaces. At the solution layer, suppliers such as Schneider Electric, Rittal, Vertiv, Eaton, and Legrand bundle racks with power distribution, cooling, and monitoring architectures, which system integrators and commissioning specialists then install into hyperscale, colocation, and edge facilities.
Downstream, procurement is driven by platform interoperability and compliance-ready telemetry. Operators align rack configurations to open specifications, including OCP-aligned designs, and to EU energy reporting requirements for larger sites. Delivery and servicing rely on logistics partners and field-service ecosystems that can support faster build cycles and ongoing maintenance for high-density deployments, where rack-level power and cooling integration reduces installation friction but increases reliance on qualified technicians and validated parts supply.
Competitive Landscape
Competition remains moderately fragmented because no single vendor can fulfill the diverse requirements spanning hyperscale, colocation, edge, and enterprise use cases. Schneider Electric, Rittal, and Vertiv lead on integrated solutions that bundle power distribution units, cooling manifolds, and remote-monitoring software inside pre-engineered racks. Their strong field support and extensive partner ecosystems sustain share amid continual design refreshes. Eaton and Panduit complement this group by supplying cable management and busway components that snap into multiple rack brands, fostering interoperability. The Europe data center rack industry also includes Open Compute Project contributors that champion cost-optimized frames built on shared specifications, eroding proprietary lock-in and abbreviating certification cycles.
Technological differentiation now centers on cooling integration. Vertiv released a turnkey liquid-cooling service line that couples coolant distribution units with rack-mounted cold plates, appealing to operators wary of multi-vendor coordination. Rittal invests in rear-door heat exchangers that retrofit onto installed cabinets, extending the life of earlier assets. Meanwhile, Schneider Electric pilots robotic rack handling to streamline server swaps and reduce technician fatigue. Start-ups target edge niches with rugged micro racks capable of withstanding wide temperature swings and physical shocks, features less critical in climate-controlled hyperscale halls.
Vendor strategies also respond to regulatory change. European Union mandates for reporting and reducing greenhouse emissions reward suppliers that disclose cradle-to-gate carbon metrics and embed telemetry for ongoing measurement. Manufacturers incorporating recycled aluminum or low-carbon steel can bid on public-sector projects reserved for sustainable equipment. The resulting competitive matrix favors companies that marry engineering prowess with transparent environmental credentials, factors that will reshuffle share positions over the forecast horizon.
Europe Data Center Rack Industry Leaders
Rittal GMBH & Co.KG
Schneider Electric SE
Legrand SA
Eaton Corporation plc
Vertiv Group Corp.
- *Disclaimer: Major Players sorted in no particular order
Europe Data Center Rack Market Companies Covered in this Report
- Schneider Electric SE
- Rittal GmbH and Co. KG
- Vertiv Group Corporation
- Eaton Corporation plc
- Legrand SA
- nVent Electric plc
- Dell Technologies Inc.
- Hewlett Packard Enterprise Co.
- Fujitsu Ltd.
- Cisco Systems Inc.
- Lenovo Group Ltd.
- Huawei Technologies Co. Ltd.
- International Business Machines Corp.
- Panduit Corp.
- Super Micro Computer Inc.
- Tripp Lite (Eaton)
- Chatsworth Products Inc.
- Black Box Corp.
- APC by Schneider Electric
- Vertiv (Geist)

Market Opportunities and Future Outlook
A key whitespace is compliance-driven retrofitting at the rack layer. Operators need cabinet ecosystems that simplify EU reporting and sustainability audits for facilities at or above the 500 kW IT threshold under the Energy Efficiency Directive (EU) 2023/1791 and the methodology in Delegated Regulation (EU) 2024/1364. This creates an opening for rack vendors to sell metered, sensor-rich enclosures and integration kits, covering power, cooling, and monitoring, that convert installed rows into auditable, KPI-ready assets rather than standalone mechanical frames.
Policy development adds a second, more standardized demand signal. The European Commission has been developing a Data Centre Energy Efficiency Package, including work on mandatory rating schemes and minimum performance standards for data centers (500 kW+), and a draft regulation (Ares(2026)3247482) that included a feedback call from March 26 to April 23, 2026 around an electronic label concept for transparency. Vendors that package racks with repeatable measurement, documentation, and verified configurations, including liquid-ready designs for high-density AI deployments, are positioned to compete where labeling, efficiency claims, and sustainability disclosure influence permitting, customer selection, and portfolio standardization.
Recent Industry Developments in Europe Data Center Rack Market
- March 2026: Siemens AG (with Rittal) announced a strategic partnership to develop data-center infrastructure focusing on rack-level power distribution for AI applications. The collaboration expands standardized, integrated rack power solutions supporting high-density AI deployments across European facilities.
- June 2025: Schneider Electric SE launched Prefabricated Modular EcoStruxure Pod Data Centre solutions and expands EcoStruxure Rack Solutions for high-density AI clusters. The development supports modular, rapid-build rack deployments with integrated cooling and power for AI workloads in Europe.
- April 2025: Schneider Electric SE (with Smart Campus) and Smart Campus collaborated to develop a 26 MW data center facility in Sines, Portugal powered entirely by renewable energy. The project demonstrates renewable-powered, high-density rack-ready design in a new European site.


Europe Data Center Rack Market Report Scope and Research Methodology
Market Definition and Coverage
This market covers revenues generated from data center racks supplied and installed across Europe, including cabinets and open-frame designs used to house IT equipment inside enterprise, colocation, and hyperscale facilities.
Scope exclusions: We exclude servers, storage, networking gear, building power systems, and cooling equipment, even when these are procured in the same data hall project.
Segments Covered in This Report
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Rack Height
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Material
- By Country
- Germany
- United Kingdom
- France
- Netherlands
- Ireland
- Switzerland
- Denmark
- Sweden
- Italy
- Spain
- Poland
- Norway
- Austria
- Rest of Europe
Data Sources, Market Sizing, and Validation
Desk Research
Desk research sets the starting structure for the model by clarifying how many data halls and rack positions are being added in key European markets, and what specifications are becoming common. We rely on public sources such as Eurostat for macro indicators, the European Commission for energy efficiency and digital-policy context, and national statistical offices for country-level construction and industrial activity signals.
We also review standards and technical publications (such as ISO and IEC references), plus association and operator materials that describe typical rack formats, heights, and adoption of higher-density layouts. To cross-check company and shipment narratives, we use public filings and investor presentations, supported by reputable press coverage of new facility announcements. In some places, we use paid subscriptions for company financials and intelligence, patent databases, and shipment-level import and export data to fill gaps where public datasets do not provide enough detail. The desk sources listed here are illustrative and not exhaustive, and additional references are used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work is used to confirm what is actually being purchased and installed, particularly around cabinet versus open-frame mix, preferred heights, and typical price ranges by project type. We speak with rack suppliers, data center operators, integrators, and channel partners across Europe so assumptions from desk research can be corrected. The final market build is then aligned to how buyers plan deployments over the next few years.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 29% | CXOs: 21% |
| Mid tier: 49% | Functional/Unit leaders: 28% |
| Smaller Players: 22% | Managers: 51% |
Market-Sizing & Forecasting
The core sizing starts with a top-down demand pool reconstructed from Europe data center build activity and fit-out needs, then converted into rack revenue using practical purchasing rules. Once this is in place, selective bottom-up checks are used to confirm that totals stay realistic, including sampled average selling price (ASP) by rack type multiplied by implied unit volumes, and channel feedback on project refresh cycles.
Inputs that matter in this market include new capacity additions by major hubs, the share of deployments shifting to higher rack power density (which can change cabinet requirements), the mix of cabinet racks versus open-frame racks, common rack heights (in U), and material preferences that influence price. Since not every country provides the same visibility, gaps are handled with peer-country proxies tied to comparable data center growth and construction pipelines, and then adjusted after interviews.
For forecasting, scenario analysis is used so outcomes can be flexed based on the pace of new builds, retrofit intensity, and pricing movement for steel and aluminum. The year-to-year pattern is then smoothed with simple time-series checks so spikes from one-off hyperscale projects do not distort the forward curve, unless primary inputs confirm the step-change is sustained.
Data Validation & Update Cycle
Validation is done through multiple checks so the model does not rely on a single assumption. Outputs are compared against independent signals such as announced data center expansions, rack density trends discussed by operators, and import and export movements for relevant rack and cabinet categories where applicable.
When a country result looks unusually high or low, the drivers are re-tested, and follow-up calls are triggered with interviewees to clarify pricing, lead times, and the actual cabinet versus open-frame split. Before sign-off, the work is reviewed in steps by another analyst to confirm calculations, logic, and year alignment. Reports are refreshed annually, and interim updates are made when material events occur, followed by a final pre-delivery review so clients receive the latest updated view.
Mordor Intelligence's Europe Data Center Rack Market Size Compared Against Other Published Estimates
Published market sizes for Europe data center racks can look far apart because the scope and counting logic are not always the same, even when the title sounds identical. Differences usually come from what is included with the rack, the year selected as the base, and how prices are converted and projected across countries.
Some estimates fold adjacent items into the rack number, such as bundled accessories or wider cabinet categories used outside data centers. In the Mordor Intelligence view, the value is counted only for rack products sold into data centers in Europe, and the total is kept aligned to rack-type and rack-form-factor demand signals that were cross-checked through operator and channel interviews.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 891.70 M (2026) | |
| Regional Consultancy A | USD 1292.36 M (2025) | Uses a broader rack cabinet lens and can include non-data-center cabinet use cases, and it also applies a different base-year setup that can lift the starting value. |
| Industry Report B | USD 3800.00 M (2025) | Appears to include a much wider equipment scope and aggressive price progression, which can overstate rack-only revenues when Europe project mix and specifications are not separated cleanly. |
The table shows that most of the spread is explained by what gets bundled into the rack definition, plus base-year alignment and how pricing is carried forward. By keeping the sizing tied to observable data center build signals and simple, repeatable price-by-volume logic, the resulting number stays easier to audit and reuse for planning.


Key Questions Answered in the Report
How fast is demand for racks in European hyperscale facilities growing?
In the Europe data center rack market, hyperscale and cloud campuses represent the fastest segment, expanding at 14.35% CAGR as operators deploy 1 MW liquid-cooled cabinets for AI workloads.
Which rack height is preferred for retrofit projects across Europe?
In the Europe data center rack market, the 48U format leads retrofits because it adds six rack units of capacity without altering ceiling heights, growing at 17.05% CAGR.
Why are aluminum racks gaining traction in new European data centers?
In the Europe data center rack market, aluminum frames lower floor loads, improve heat dispersion, and meet embodied-carbon goals, contributing to a 16.55% CAGR for the material segment.
What role do government policies play in rack procurement?
EU digitalisation targets and energy-efficiency rules require telemetry-enabled, locally sourced racks, steering orders toward compliant suppliers.
Which country provides the highest growth opportunity through 2031?
In the Europe data center rack market, Ireland posts the quickest 15.85% CAGR because renewable power and favorable tax regimes attract extensive hyperscale investment.
What is the main barrier slowing advanced rack adoption among smaller operators?
High upfront capital expenditure for liquid-ready racks, priced up to four times higher than air-cooled alternatives, deters budget-constrained buyers.
Page last updated on:
- Data Center Server Market Servers across the global market, covering tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Data Center Construction Market Global construction demand, split by tier, facility size and facility type.
- Switzerland Data Center Cooling Market Switzerland cooling, split by facility type, tier and cooling technology.
- France Data Center Cooling Market Cooling demand across France, covering cooling technology, type and end user vertical.
- United States Data Center Server Market The US's servers, split by data-center tier, form factor and application / workload.





