
Endoscopic Retrograde Cholangiopancreatography (ERCP) Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 2.17 Billion |
| Market Size (2031) | USD 3.19 Billion |
| Growth Rate (2026 - 2031) | 8.01 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
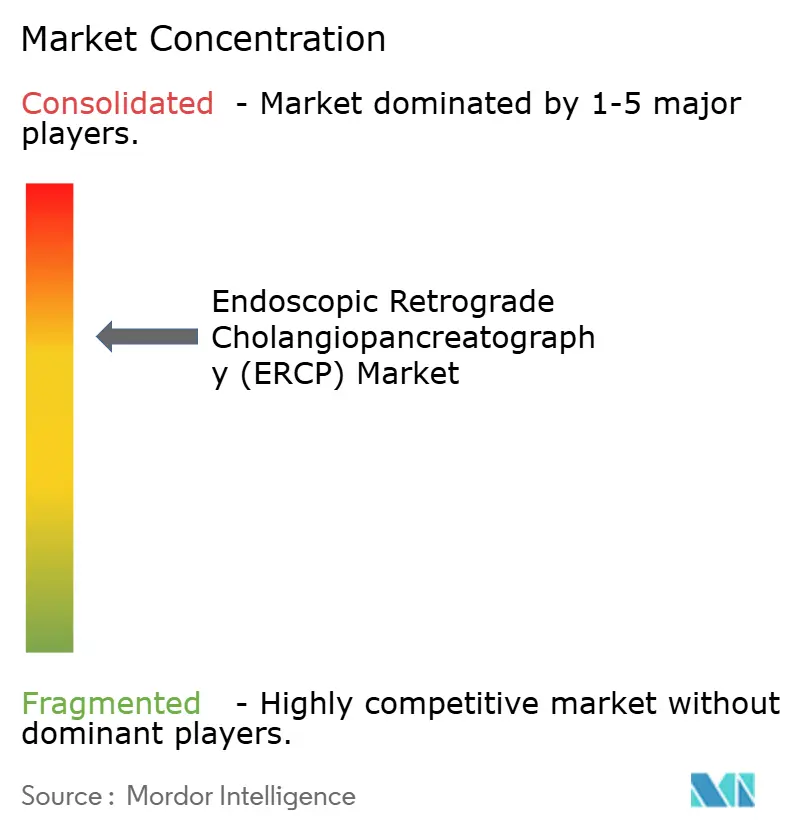
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Endoscopic Retrograde Cholangiopancreatography (ERCP) Market Analysis by Mordor Intelligence
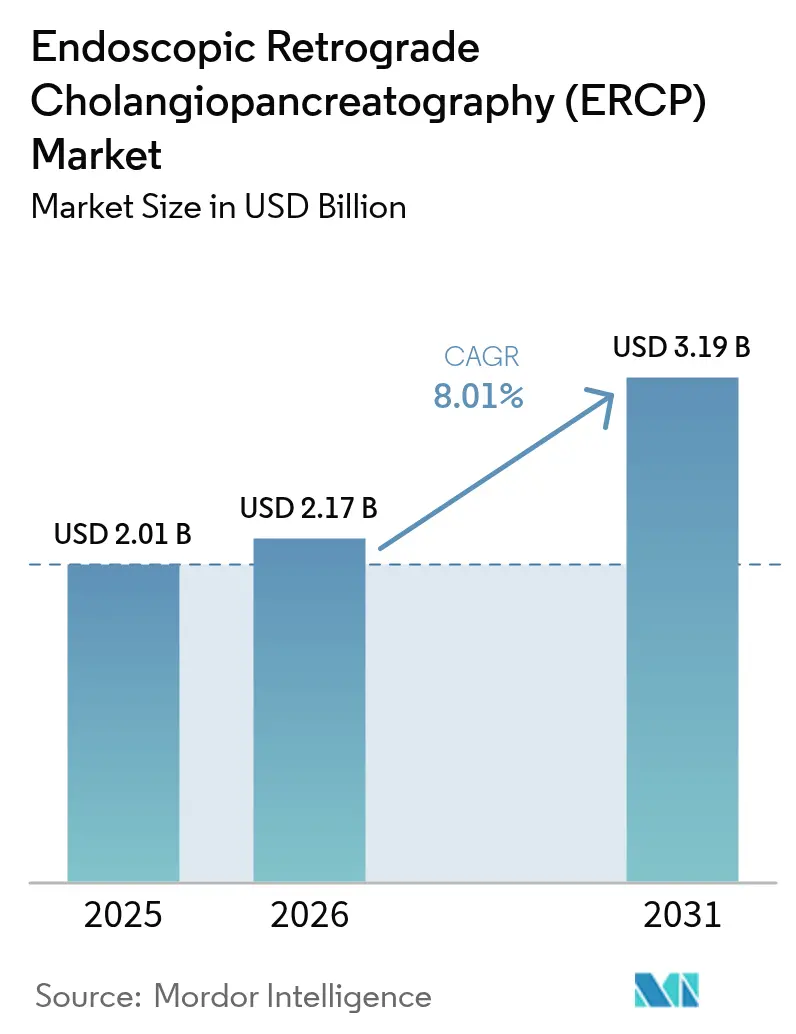
The Endoscopic Retrograde Cholangiopancreatography market size was valued at USD 2.01 billion in 2025 and estimated to grow from USD 2.17 billion in 2026 to reach USD 3.19 billion by 2031, at a CAGR of 8.01% during the forecast period (2026-2031). Rising pancreatic and biliary disease burdens, rapid uptake of single-use duodenoscopes, and broader outpatient reimbursement drive this expansion. Infection-control concerns following contamination events intensify the shift from reusable to disposable devices, while AI-enabled imaging raises cannulation success and reduces procedure times. Outpatient ERCP adoption grows as health systems seek lower costs and higher patient satisfaction, and emerging economies add new endoscopy capacity, widening global access to advanced therapeutics.
Key Report Takeaways
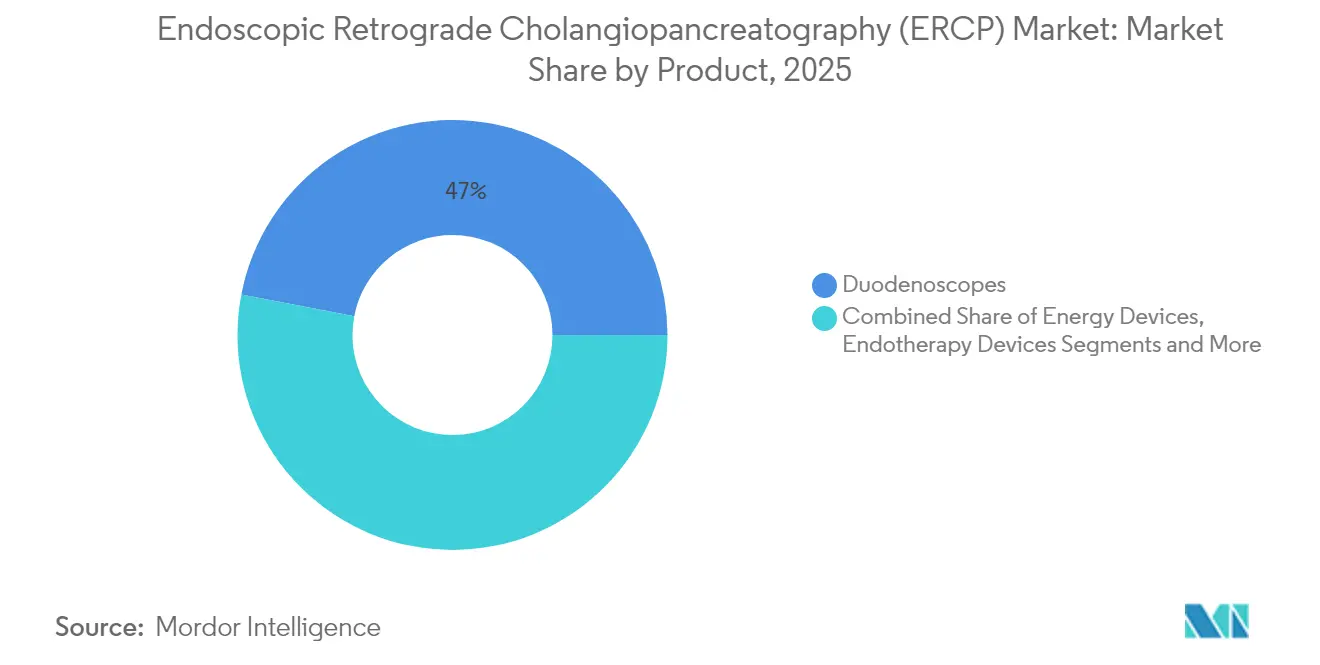
- By product category, duodenoscopes led with 46.98% of Endoscopic Retrograde Cholangiopancreatography market share in 2025, and the segment is projected to expand at an 11.62% CAGR through 2031.
- By procedure, biliary sphincterotomy held 26.35% share of the Endoscopic Retrograde Cholangiopancreatography market size in 2025, while pancreatic duct stenting is set to grow at a 12.25% CAGR to 2031.
- By end user, hospitals accounted for 58.81% revenue share in 2025, yet ambulatory surgery centers post the fastest growth at 10.54% through 2031.
- By technology, reusable systems retained 68.05% share in 2025, whereas fully single-use platforms record the highest forecast CAGR of 11.21%.
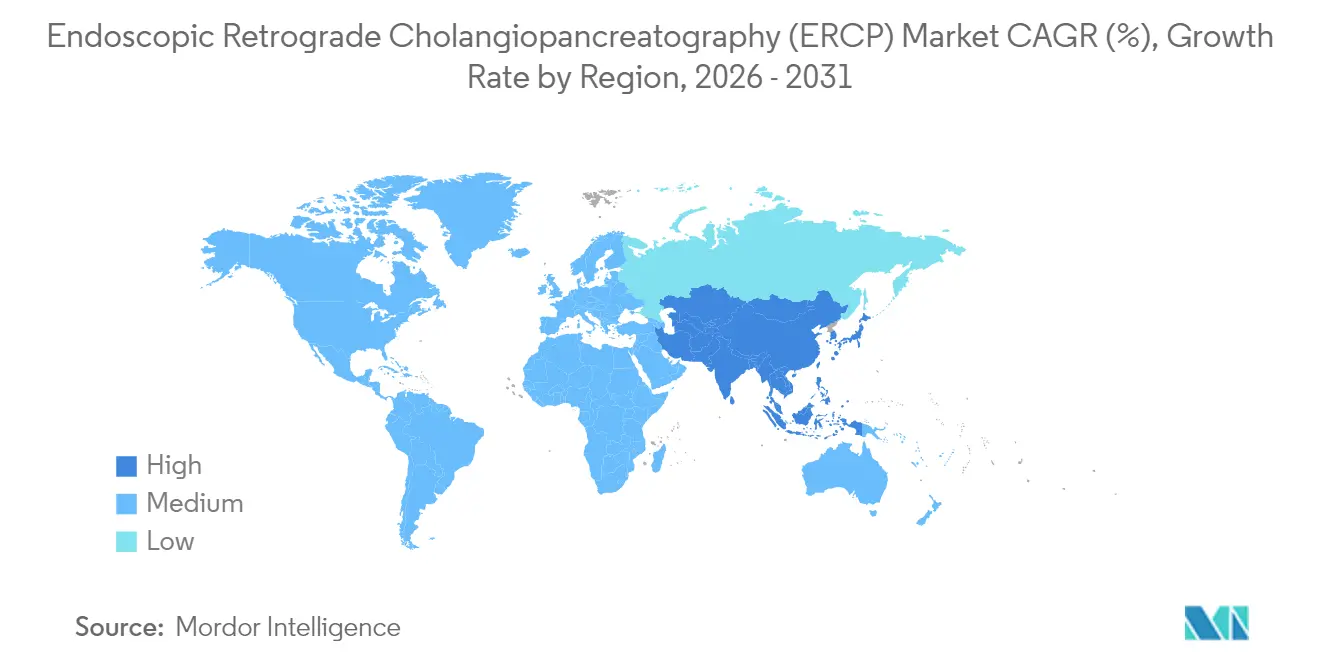
- By geography, North America captured 39.12% of Endoscopic Retrograde Cholangiopancreatography market share in 2025; Asia-Pacific displays the strongest growth momentum with a 9.92% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Endoscopic Retrograde Cholangiopancreatography (ERCP) Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising incidence of pancreatic & biliary cancers | +1.8% | Global, higher in high-income regions | Long term (≥ 4 years) |
| Growing preference for single-use duodenoscopes to curb cross-infection | +2.1% | North America & EU, expanding to APAC | Medium term (2-4 years) |
| AI-enabled imaging & navigation boosts cannulation success | +1.2% | North America, EU, select APAC markets | Medium term (2-4 years) |
| Reimbursement expansion for outpatient ERCP in OECD markets | +1.4% | OECD, mainly North America & EU | Short term (≤ 2 years) |
| Endotherapy device miniaturisation enabling pediatric ERCP | +0.6% | Global, early in developed markets | Long term (≥ 4 years) |
| ESG-driven hospital decarbonisation favouring low-water-use scopes | +0.9% | EU, North America, APAC sustainability leaders | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising incidence of pancreatic & biliary cancers
Gallbladder cancer prevalence has climbed to 20.3% among at-risk groups, notably individuals with gallstones, creating a large pool of patients who require endoscopic intervention.[1]Ali Afzal, “Epidemiology of gall bladder cancer and its prevalence worldwide: a meta-analysis,” Orphanet Journal of Rare Diseases, ojrd.biomedcentral.com Early-onset pancreatic cancer cases add clinical complexity, demanding specialised diagnostic and therapeutic protocols tailored to younger populations. These epidemiological shifts lift procedure volumes beyond normal demographic growth, especially in high-income nations with established reimbursement systems. Post-ERCP pancreatitis affects up to 15% of patients and adds more than USD 200 million in annual U.S. costs, intensifying the search for safer technologies.[2]Patrick Smith, “Preventing Pancreatitis After ERCP,” Johns Hopkins Medicine, hopkinsmedicine.orgAgeing societies and lifestyle risk factors combine to keep long-term demand for ERCP solutions strong.
Growing preference for single-use duodenoscopes to curb cross-infection
Hospitals increasingly choose single-use duodenoscopes, driven by safety, operational efficiency, and new reimbursement pathways. Boston Scientific’s EXALT Model D shows performance parity with reusable devices across seven peer-reviewed studies while removing cross-infection risks. The U.S. Centers for Medicare & Medicaid Services has granted an add-on payment for Ambu’s aScope Duodeno, alleviating cost concerns for administrators. These policy incentives, coupled with lower legal liability, accelerate broader adoption beyond high-risk cases.
AI-enabled imaging & navigation boosts cannulation success
Artificial-intelligence software raises selective cannulation success and diagnostic accuracy. Meta-analysis data reveal 93% sensitivity and 90% specificity for pancreatic cancer detection with AI-enhanced EUS, achieving an area under the curve of 0.95.[3]Hua Yin, “The Value of Artificial Intelligence Techniques in Predicting Pancreatic Ductal Adenocarcinoma with EUS Images,” Endoscopic Ultrasound, journals.lww.com Deep-learning models show 97% accuracy in spotting bile-duct dilatation on MRCP scans. Olympus plans to commercialise an AI endoscopy ecosystem in 2025, embedding cloud-based analytics to support real-time decision-making.
Reimbursement expansion for outpatient ERCP in OECD markets
Thirty new U.S. gastrointestinal endoscopy centres opened in 2023, mirroring expanded insurer coverage that equalises payment for outpatient and inpatient ERCP procedures. Ambulatory settings lower hospital infection risks, shorten recovery, and improve patient satisfaction while cutting facility costs. These benefits align with payer shifts to value-based purchasing, spurring health systems to invest in ambulatory ERCP capability.
Restraints Impact Analysis of Endoscopic Retrograde Cholangiopancreatography (ERCP) Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High capital & per-procedure cost of disposable scopes | -1.6% | Global, stronger in cost-sensitive markets | Short term (≤ 2 years) |
| Shortage of ERCP-skilled endoscopists in emerging markets | -1.1% | APAC, MEA, Latin America | Long term (≥ 4 years) |
| Risk of post-ERCP pancreatitis & related litigation | -0.8% | North America, EU | Medium term (2-4 years) |
| Slow regulatory clearance for AI-guided cannulation software | -0.5% | Worldwide, variable by region | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High capital & per-procedure cost of disposable scopes
Although infection risk falls to near zero, single-use devices still cost more per case than reusables, straining budgets in systems with tight reimbursement. Hospitals saved USD 451 million through device reprocessing programs in 2024, illustrating pressure to contain spending. As economies of scale improve and payment models evolve, the cost differential is expected to narrow.
Shortage of ERCP-skilled endoscopists in emerging markets
Advanced ERCP requires extensive training. Olympus has partnered with Rizal Medical Center in the Philippines to build a regional training hub, yet the pipeline cannot meet rising demand quickly. Until more clinicians acquire these skills, procedure volumes may lag equipment availability.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Endoscopic Retrograde Cholangiopancreatography (ERCP) Market Segment Analysis
By Product:
Duodenoscopes Drive Innovation While Endotherapy ExpandsDuodenoscopes held 46.98% of Endoscopic Retrograde Cholangiopancreatography market share in 2025 and remain on track to grow at an 11.62% CAGR through 2031. Hospital infection-control policies and supportive reimbursement drive brisk conversion to single-use models, while hybrid scopes with disposable tips help institutions with tight budgets transition gradually. Olympus, Boston Scientific, and Ambu compete closely, each offering ergonomics, imaging clarity, and sterile packaging that answer clinician demands. As institutions retire ageing reusable fleets, procurement cycles increasingly favour newer single-use or hybrid options that lower reprocessing load and litigation exposure.
Endotherapy devices form the second-largest revenue block and cover sphincterotomes, guidewires, lithotripters, and stents. Growing case complexity, particularly in pancreatic interventions, sustains multi-device demand per procedure. Radiofrequency ablation catheters such as Habib EndoHPB broaden therapeutic scope and extend stent patency. Accessories and consumables enjoy steady volume growth, reflecting the overall expansion of procedures rather than large price swings.


By Procedure:
Biliary Dominance Shifts Toward Pancreatic ComplexityBiliary sphincterotomy accounted for 26.35% of Endoscopic Retrograde Cholangiopancreatography market size in 2025, confirming its role as the traditional workhorse procedure. Pancreatic duct stenting, however, posts the quickest rise at a 12.25% CAGR as clinicians manage pancreatitis complications and malignant strictures with endoscopic techniques that once required surgery. Advances in imaging and wire technology improve cannulation precision, allowing safe navigation of complex duct anatomy. As procedural confidence grows, hospitals adopt expanded indications, driving a mix shift toward higher-value pancreatic work.
Pancreatic duct dilatation and combined EUS-ERCP techniques continue to gain ground. Technical success rates up to 92% in EUS-guided drainage highlight the expanding therapeutic envelope. Device firms market mini-sphincterotomes for difficult cannulations, reinforcing procedure adoption in less experienced hands. This broadening toolkit accelerates the transition from purely diagnostic ERCP toward comprehensive endoscopic therapy.
By End User:
Hospitals Maintain Leadership While ASCs AccelerateHospitals captured 58.81% revenue share in 2025 by handling complex cases that demand anaesthesia support, imaging infrastructure, and intensive post-procedure monitoring. Many tertiary centres also act as regional referral hubs, ensuring high patient throughput. Yet ambulatory surgery centres are forecast to record a 10.54% CAGR as payers reward lower facility fees and faster discharge. Purpose-built outpatient suites slash turnover times and free inpatient capacity for more acute care. Health systems respond by spinning up hospital-owned ASCs, blending capital efficiency with clinical oversight.
Specialty and GI clinics fill a complementary role for routine diagnostic ERCP, patient follow-up, and minor therapeutic updates. As device makers refine smaller-footprint imaging systems, these clinics gain increased capability to perform straightforward cases, easing backlog at large hospitals. Collectively, the end-user mix reflects the healthcare sector’s broader shift to decentralised, cost-effective service delivery.
By Technology:
Reusable Systems Face Single-Use DisruptionReusable duodenoscope platforms controlled 68.05% market share in 2025, supported by existing reprocessing suites and sunk capital. Fully single-use systems, however, register an 11.21% CAGR as infection-control priorities gain urgency. Administrators weigh the financial trade-off between upfront capital avoidance and higher per-case consumable expense. Hybrid approaches—reusable main bodies with disposable tips—provide a stepping-stone for budget-conscious providers who still seek lower contamination risk.
Environmental sustainability also enters procurement criteria. Low-water detergents and energy-efficient washers improve the lifecycle profile of reusable fleets, while manufacturers investigate recyclable polymers for single-use models. These parallel innovations keep all technology categories in active contention, ensuring diverse supplier strategies in the medium term.

By Application:
Biliary Disorders Lead While Pancreatic Gains MomentumBiliary disorders represented 61.02% Endoscopic Retrograde Cholangiopancreatography market share in 2025, anchored in well-defined protocols for stone removal and stricture management. Pancreatic disorders, supported by emerging radiofrequency ablation evidence and EUS-guided access, are set to climb at a 9.28% CAGR. Improved survival rates in pancreatic cancer patients augment follow-on endoscopic needs for stent exchange and drainage procedures. For high-risk surgical candidates, endoscopic therapy provides a less invasive alternative with shorter recovery windows.
This application shift is mirrored in academic training curricula, which now dedicate more rotation time to complex pancreatic interventions. Device suppliers bundle biliary and pancreatic toolkits, simplifying inventory and driving cross-application utilisation. The net effect keeps overall procedure counts rising, and pushes average selling prices upward as advanced disposables replace generic accessories.
Geography Analysis
North America Endoscopic Retrograde Cholangiopancreatography (ERCP) Market
North America maintained 39.12% of Endoscopic Retrograde Cholangiopancreatography market share in 2025 due to robust reimbursement, mature training networks, and early roll-out of single-use scopes. U.S. ambulatory centre growth signals confidence in outpatient ERCP safety profiles, while Canadian provinces adopt similar policies to relieve inpatient pressures. Market players use the region to launch premium technologies, assuming rapid payer uptake and clinician buy-in.
Europe Endoscopic Retrograde Cholangiopancreatography (ERCP) Market
Europe ranks second, driven by stringent infection-control mandates and environmental goals that elevate demand for hybrid and single-use options. The new EU Medical Device Regulation imposes uniform safety standards, smoothing cross-border distribution and encouraging pan-European procurement contracts. Hospitals in Germany and France lead adoption of AI-supported imaging, citing evidence of improved cannulation and reduced fluoroscopy exposure.
APAC Endoscopic Retrograde Cholangiopancreatography (ERCP) Market
Asia-Pacific posts the fastest expansion at 9.92% CAGR. Investments in endoscopy training centres, as seen in the Philippines, bring advanced ERCP to previously under-served populations. China and India stand out with rising pancreatic cancer incidence, translating to higher procedure volumes. Government health-insurance schemes widen access, yet specialist shortages still cap throughput in rural areas. Regional private providers respond by offering executive health packages that include ERCP screening for high-risk demographics.
MEA and South America Endoscopic Retrograde Cholangiopancreatography (ERCP) Market
The Middle East & Africa and South America show smaller absolute numbers but strong relative growth. Sustained oil revenues support capital spending in Gulf Cooperation Council countries, while Brazilian teaching hospitals establish ERCP fellowships to retain talent. These regions rely on simplified scope platforms and tele-mentoring programs to overcome limited local expertise.

Regulatory Landscape
ERCP devices primarily fall under established medical-device pathways. In the United States, the FDA 510(k) route remains central for endoscopes and associated accessories, supported by recent clearances such as Fujifilm Corporation’s Endoscope Model ED-S100TP (K251861, March 2026) and Olympus Medical Systems’ single-use distal cover MAJ-2315 (K253646, February 2026). This clearance cadence supports iterative product updates in duodenoscopes, distal-end components, and ERCP consumables while aligning with Class II expectations for performance, biocompatibility, and labeling in real-world clinical use.
In Europe, EU MDR-related requirements continue to determine market access for endoscopy portfolios, alongside ongoing updates to recognized technical benchmarks. EUDAMED registration became mandatory on 28 May 2026 for MDR/IVDR devices, increasing operational focus on UDI and device-module readiness, and on consistent device nomenclature coding. In 2026, Commission Implementing Decisions (EU) 2026/1231 and 2026/1313 (effective 17 June 2026) updated the harmonized standards list supporting presumption of conformity. ISO activity also progressed in 2026, including publication of ISO 8600-1:2025 (general requirements for medical endoscopes and endotherapy devices), which shapes verification and documentation practices in global submissions.
Value Chain Analysis
The ERCP value chain starts with specialized inputs such as optical assemblies, CMOS sensors, fiber-optics, medical-grade polymers, and precision metals. It then moves into midstream manufacturing and assembly of duodenoscopes (reusable, hybrid, and fully single-use) and endotherapy devices (guidewires, cannulation devices, sphincterotomes, stents, and lithotripters). Quality systems, sterilization validation for reusable components, and packaging and sterility assurance for single-use platforms are key value-add steps that influence both cost and time-to-market, particularly as product designs increasingly integrate imaging enhancements and workflow features geared toward ERCP efficiency.
Downstream, distribution uses direct sales and group purchasing pathways into hospitals, ambulatory surgery centers, and specialty/GI clinics. For reusable fleets, sterile reprocessing services and washer-disinfector ecosystems remain important. Supply reliability is shaped by component lead times and logistics, and a 2025 medical device supply-chain survey identified availability and lead times as a primary operational pain point for many manufacturers. That has reinforced moves toward multi-sourcing and regionalized supply strategies. The shift toward single-use duodenoscopes also changes the channel mix and inventory model by increasing reliance on consumables replenishment and sterile supply-chain performance, rather than only on capital equipment cycles.
Competitive Landscape
The Endoscopic Retrograde Cholangiopancreatography market is moderately fragmented. Olympus, Boston Scientific, and Fujifilm combine broad product portfolios, global sales footprints, and long R&D track records. Olympus emphasises AI-ready ecosystems and hybrid scope designs. Boston Scientific doubles down on single-use innovation and therapeutic accessories such as the SpyGlass DS system, which improves direct visualization in intraductal procedures. Fujifilm leverages imaging depth and processor compatibility in multi-modality suites.
Challenger firms pursue niche tactics. Ambu focuses purely on single-use technology, banking on infection risk aversion to overcome cost objections. Medtronic’s planned distribution of Dragonfly Endoscopy’s pancreaticobiliary system illustrates cross-portfolio expansion that leverages existing channels. Start-ups develop AI software to guide wire placement and lesion classification, often partnering with scope makers to speed regulatory approvals.
Regulatory classification under FDA 510(k) pathways favours incumbents that possess legacy clearances and documentation. Smaller entrants counter with faster iteration cycles, targeting unmet needs such as paediatric instruments or ultra-thin cannulation wires. Strategic alliances, licensing deals, and regional manufacturing agreements continue to reshape competitive boundaries as the market gravitates toward integrated diagnostic-therapeutic platforms.
Endoscopic Retrograde Cholangiopancreatography (ERCP) Industry Leaders
CONMED Corporation
STERIS PLC
Cook Medical
Fujifilm Holdings Corporation
Olympus Corporation
- *Disclaimer: Major Players sorted in no particular order
Endoscopic Retrograde Cholangiopancreatography (ERCP) Market Companies Covered in this Report
- Olympus
- Boston Scientific
- FUJIFILM
- Johnson & Johnson
- Medtronic
- Cook Group
- Conmed
- STERIS
- Karl Storz SE
- HOYA
- Ambu
- Micro-tech
- Taewoong Medical
- ERBE Elektromedizin
- Endo-Flex
- TeleMed Systems Inc.
- SonoScape Medical Corp.
- DCC Healthcare (Medi-Globe)
- Huger Medical Instrument Co.
Read Analysis of Endoscopic Retrograde Cholangiopancreatography (ERCP) Companies

Market Opportunities and Future Outlook
Clinical standardization and measurable quality targets create a practical whitespace for manufacturers to align ERCP device design, labeling, and training with defined performance metrics. In February 2026, the American College of Gastroenterology (ACG) and the American Society for Gastrointestinal Endoscopy (ASGE) updated ERCP-specific quality indicators, with 13 measures across preprocedure, intraprocedure, and postprocedure domains. This pushes providers toward tighter tracking of outcomes such as technical success and downstream unplanned utilization. As a result, demand increases for device ecosystems that reduce variability in cannulation and therapy steps, and for accessory portfolios that support consistent execution across mixed-acuity sites, including outpatient settings.
Product innovation and portfolio expansion are also supported by ongoing regulatory throughput and guideline updates. FDA 510(k) clearances for ERCP consumables, including Olympus Medical Systems’ Single Use Cannula V series (K250573, May 2025) and Medi-Globe GmbH’s Endoflux biliary and pancreatic stent sets (K251658, April 2026), show active development and substitution potential in high-volume disposable categories tied to both safety and workflow. In parallel, the World Endoscopy Organization’s June 2025 guideline update on biliary cannulation and sphincterotomy techniques provides a globally referenced practice baseline, which supports broader adoption of standardized techniques and device kits mapped to recommended procedural steps.
Recent Industry Developments in Endoscopic Retrograde Cholangiopancreatography (ERCP) Market
- June 2026: Cook Medical released the SureTome SW next-generation sphincterotome for ERCP procedures in the United States and Canada. The launch adds a new option in a high-turnover endotherapy category where procedural efficiency and tactile control influence standardization across sites. It also reinforces competitive intensity in accessories that are purchased repeatedly per procedure and can be bundled with broader ERCP portfolios.
- December 2025: CONMED Corporation announced its strategic exit from gastroenterology product lines, including the transition of commercial support for the GORE VIABIL biliary endoprosthesis to Olympus. The move reshapes channel access for a named biliary stent franchise and tightens portfolio concentration among large endoscopy suppliers. It also signals continued portfolio rationalization among diversified device companies where capital is being redirected to other minimally invasive priorities.
- April 2024: Ambu expanded manufacturing capacity for the aScope Duodeno 2 and aBox 2 systems to meet rising demand across North America and Europe. The capacity increase supports broader deployment of single-use ERCP platforms and reduces lead times, strengthening supply resilience in high-volume centers.


Endoscopic Retrograde Cholangiopancreatography (ERCP) Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market covers the value generated from ERCP procedures, including the main procedure-enabling equipment and the single-use or reusable accessories that are routinely used in ERCP for diagnosis and therapy across care settings.
Scope exclusions: We exclude non-ERCP GI endoscopy procedures and general imaging equipment that is not purchased or used specifically to perform ERCP.
Segments Covered in This Report
- By Product
- Duodenoscopes
- Endotherapy Devices
- Sphincterotomes
- Guidewires & Cannulation Devices
- Lithotripters
- Stents
- Other Endotherapy
- Visualization & Imaging Systems
- Energy Devices
- Accessories & Consumables
- By Procedure
- Biliary Sphincterotomy
- Biliary Stenting
- Biliary Dilatation
- Pancreatic Sphincterotomy
- Pancreatic Duct Stenting
- Pancreatic Duct Dilatation
- By End User
- Hospitals
- Ambulatory Surgery Centers
- Specialty & GI Clinics
- By Technology
- Reusable
- Hybrid (Reusable with Disposable Distal Cap)
- Fully Single-Use
- By Application
- Biliary Disorders
- Pancreatic Disorders
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research started with building a clear demand context for ERCP by tracking public disease and procedure signals, then narrowing them to what is ERCP specific. We reviewed sources such as the World Health Organization, the US CDC, the US FDA safety communications and device databases, and peer-reviewed gastroenterology journals for evidence on biliary and pancreatic disease burden, procedure practices, and infection control trends.
To convert that context into market inputs, we also used sources such as OECD health statistics, national health ministries, and public reimbursement and coding references where available. We supplemented this with company annual reports, investor presentations, and reputable press coverage of product launches and recalls. In a few places, paid subscriptions for company financials, patent databases, and news and financials were used to cross-check product focus and timing of adoption shifts. The desk sources listed are illustrative, not exhaustive, and additional references were used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on clarifying what portion of ERCP value is tied to procedure volume versus device and accessory spend, and how usage differs by setting (hospitals versus ambulatory centers) and by procedure mix. We spoke with clinicians, procurement staff, distributors, and product specialists across major regions, so secondary assumptions on utilization, replacement cycles, and pricing could be checked and corrected where needed.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 38% | CXOs: 14% | APAC: 45% |
| Mid tier: 47% | Functional/Unit leaders: 36% | EMEA: 32% |
| Smaller Players: 15% | Managers: 50% | Americas: 23% |
Market-Sizing & Forecasting
Market sizing was built using a top-down path where procedure demand was reconstructed from the addressable biliary and pancreatic case pool, the share moving to ERCP, and typical intervention patterns that drive accessory consumption. Once those totals were shaped, we used selective bottom-up checks, such as sampled ASP times volume for core accessories and channel feedback on annual unit movement, to adjust for areas where public data is thin.
Key inputs included ERCP procedure mix (diagnostic versus therapeutic), shift toward single-use or partially disposable duodenoscope setups, average accessory sets per case (for example, sphincterotomes, guidewires, balloons, and stents), replacement and service cycles for capital equipment, and regional care setting split between hospitals and ambulatory centers. Where bottom-up information was incomplete, gaps were handled using conservative ranges anchored to interview consensus, then stress testing the effect on totals.
Forecasting used scenario analysis supported by trend lines for procedure growth and technology adoption. We stepped forecasting variables up or down based on what respondents expected on infection prevention policies, reimbursement stability, and pricing progression over the forecast period.
Data Validation & Update Cycle
Outputs were validated through multiple passes where market totals were compared against independent signals, such as procedure growth direction, device replacement timing, and public safety and regulatory events that can trigger accelerated switching. When unusual swings appeared at a region or segment level, assumptions were rechecked, and targeted follow-ups were done with interviewees to confirm whether the change was real or driven by modeling.
Before sign-off, the model and narratives go through an internal analyst review that checks calculations, year alignment, and currency consistency, followed by a final variance scan against the most recent public updates. Reports are refreshed annually, and interim updates are made when material events occur. A final pre-delivery pass is completed so clients receive the latest updated view.
Mordor Intelligence's Endoscopic Retrograde Cholangiopancreatography Market Size Measured Against Other Published Estimates
Published ERCP market numbers can look far apart because the market is defined differently, even before forecasting assumptions are applied. The biggest differences usually come from what is counted as ERCP specific, meaning procedure-driven accessories and enabling equipment, versus what is grouped in from broader GI endoscopy categories. Another common driver is whether the estimate is a device-only view or a wider procedure spend view.
For ERCP specifically, the spread often comes from how reusable duodenoscope value is treated versus single-use components, how many accessory items are assumed per therapeutic case, and whether ambulatory settings are included with the same pricing logic as hospitals. Differences also show up when one estimate uses aggressive adoption curves for disposable duodenoscopes, applies currency conversion at different timing, or does not recheck assumptions after major safety communications and product changes. When ERCP accessories are counted only when they are directly tied to an ERCP case, and adjacent GI endoscopy tools are kept out, that scope choice explains why the 2026 baseline lands where it does for Mordor Intelligence.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 2.17 B (2026) | |
| Trade Journal A | USD 2.17 B (2024) | Uses an earlier base year and appears to apply a faster adoption curve for disposable setups, which can pull forward accessory value and lift near-term totals. |
| Regional Consultancy B | USD 2.23 B (2025) | Positions the figure as a current-year estimate with limited clarity on whether capital equipment, services, or only procedure kits are included, which can shift the total up or down depending on the mix. |
The table shows that the main gap is not only the year being quoted, it is also how ERCP-specific scope is kept clean versus expanded into nearby endoscopy spend. Our approach stays traceable to procedure volume, accessory intensity per case, and realistic pricing behavior by care setting, which makes the final number easier to reproduce and update when key assumptions change.


Key Questions Answered in the Report
What is the current Endoscopic Retrograde Cholangiopancreatography market size?
The Endoscopic Retrograde Cholangiopancreatography market is valued at USD 2.17 billion in 2026.
How fast is the Endoscopic Retrograde Cholangiopancreatography market expected to grow?
It is projected to expand at an 8.01% CAGR, reaching USD 3.19 billion by 2031 during 2026-2031.
Which product segment holds the largest Endoscopic Retrograde Cholangiopancreatography market share?
Duodenoscopes lead with 46.98% revenue share in 2025 and continue to grow swiftly.
Why are single-use duodenoscopes gaining traction?
They remove cross-infection risk and now benefit from supportive reimbursement, making them attractive despite higher per-case costs.
Which region shows the highest growth potential through 2031?
Asia-Pacific is forecast to grow at a 9.92% CAGR, driven by expanding healthcare infrastructure and rising disease burden.
Page last updated on:





