
Critical Limb Ischemia Treatment Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 5.47 Billion |
| Market Size (2031) | USD 7.03 Billion |
| Growth Rate (2026 - 2031) | 5.15 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
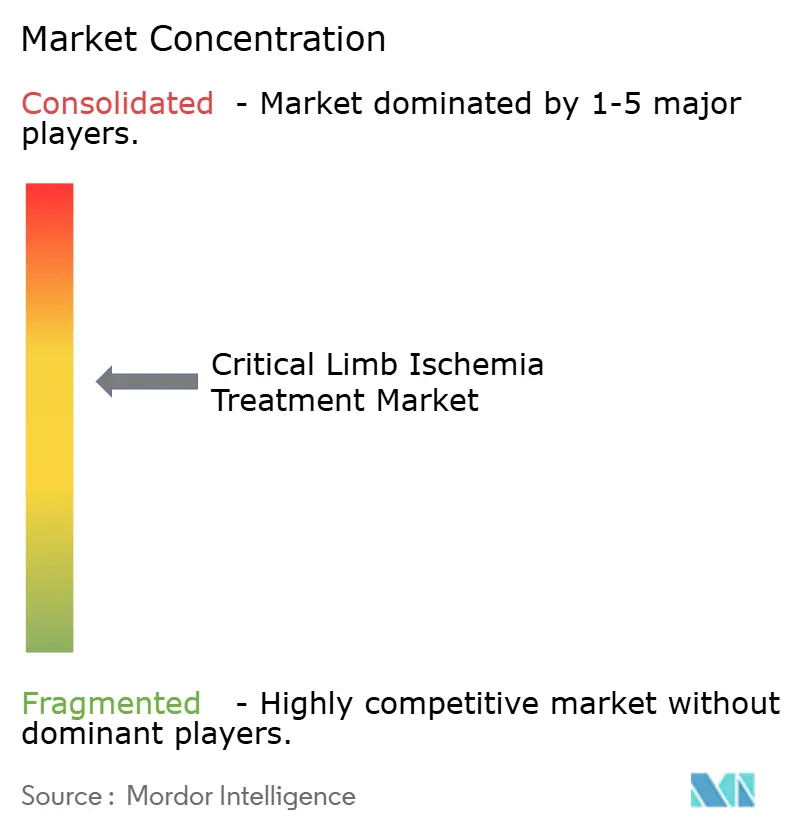
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Critical Limb Ischemia Treatment Market Analysis by Mordor Intelligence
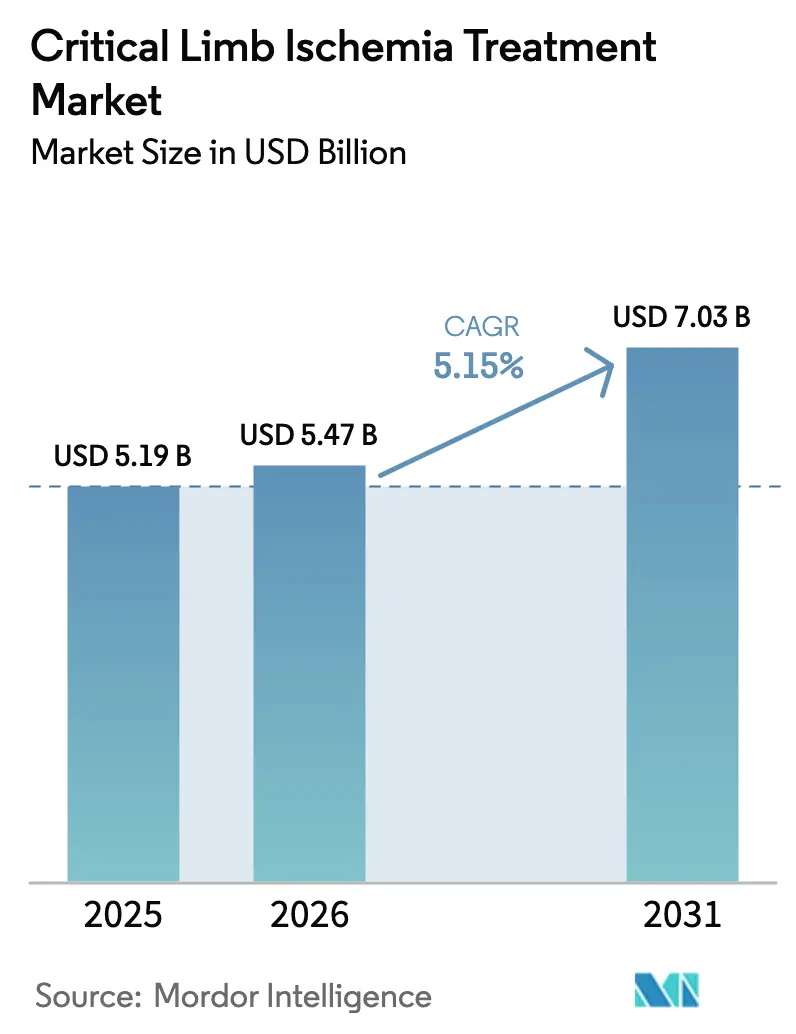
The Critical Limb Ischemia Treatment Market size was valued at USD 5.19 billion in 2025 and is estimated to grow from USD 5.47 billion in 2026 to reach USD 7.03 billion by 2031, at a CAGR of 5.15% during the forecast period (2026-2031).
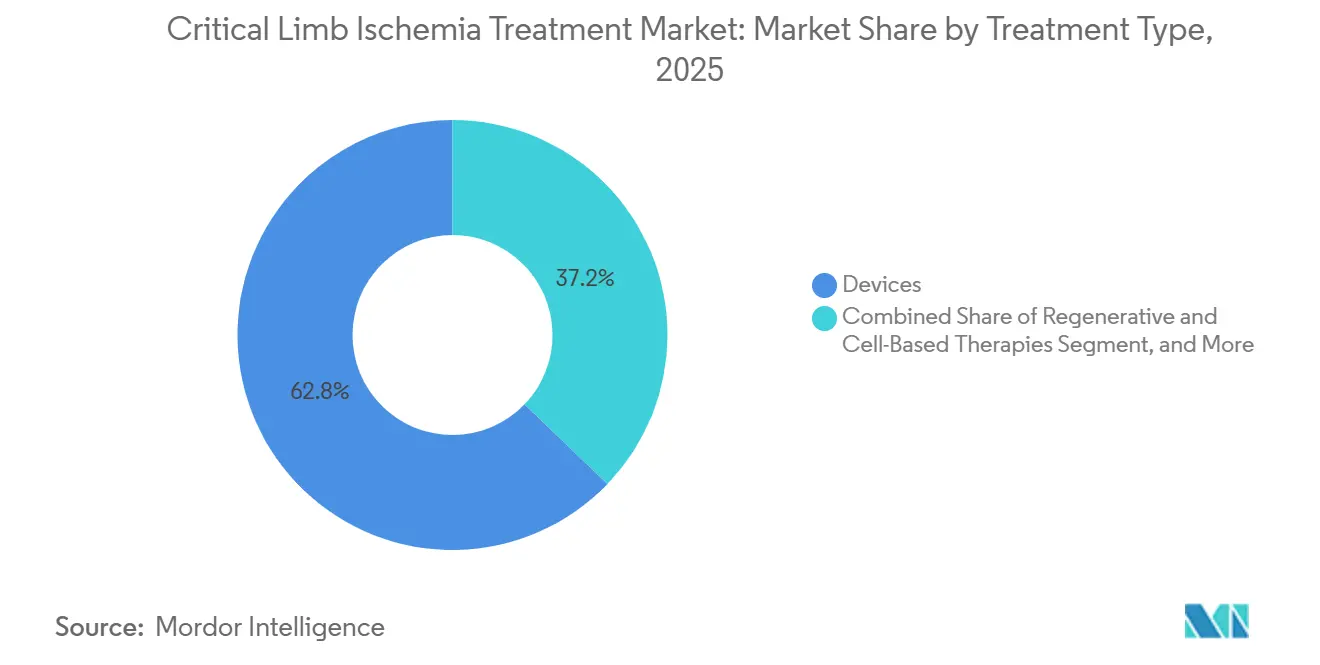
Device-based revascularization remains the cornerstone of therapy; however, its 62.81% revenue share in 2025 disguises a decisive pivot toward regenerative and cell-based options, which are expanding at more than double the overall pace. Hospitals, ambulatory surgical centers, and multispecialty vascular clinics are increasing access to these newer modalities as payers reward therapies that reduce re-intervention rates and prevent amputation. At the same time, emerging markets are unlocking latent demand through local approvals of cost-efficient drug-eluting balloons, offsetting slower growth in Europe where paclitaxel safety reviews have dampened enthusiasm for specific devices. Competitive intensity is intensifying as established device vendors defend their share against biologics start-ups, AI imaging specialists, and low-cost regional manufacturers.
Key Report Takeaways
- By treatment type, devices held 62.81% of the critical limb ischemia treatment market share in 2025, while regenerative and cell-based therapies are projected to advance at a 10.06% CAGR through 2031.
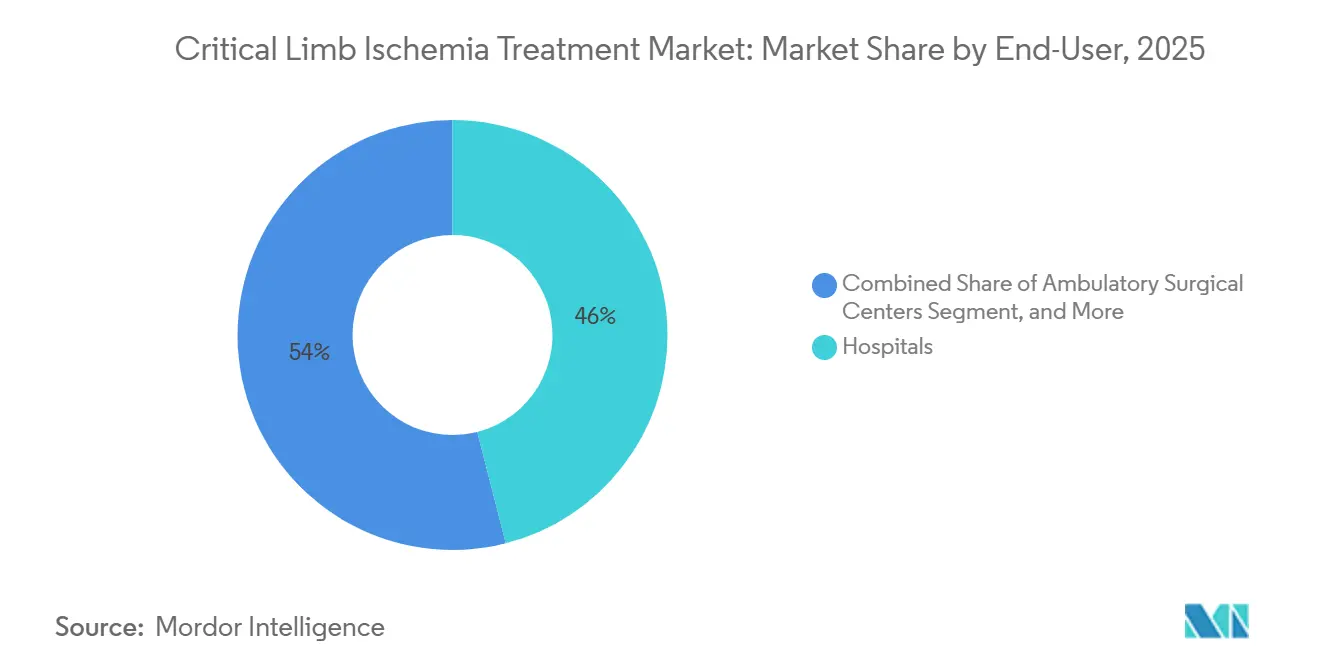
- By end-user, hospitals captured 46.03% share of the critical limb ischemia treatment market size in 2025, and ambulatory surgical centers are expanding at a 10.72% CAGR through 2031.
- By geography, North America commanded 44.32% revenue share in 2025; Asia-Pacific is forecast to post the fastest 11.53% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Critical Limb Ischemia Treatment Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Diabetes & PAD Prevalence | +1.2% | Global, with acute pressure in APAC (India, China) and Middle East | Medium term (2-4 years) |
| Growing Adoption of Minimally Invasive Revascularization Devices | +0.9% | North America & EU core, spillover to APAC urban centers | Short term (≤ 2 years) |
| Aging Population Intensifying CLI Incidence | +0.8% | Japan, Germany, Italy; emerging in South Korea, Singapore | Long term (≥ 4 years) |
| FDA Breakthrough Designations Speeding BTK Device & Cell-Therapy Launches | +1.1% | United States, with follow-on approvals in EU and Japan | Short term (≤ 2 years) |
| Expansion of Multispecialty Limb-Preservation Centers | +0.7% | United States (Medicare Advantage networks), select EU markets | Medium term (2-4 years) |
| AI-Enabled Perfusion Imaging Improving Patient Selection | +0.5% | United States, Germany, Japan; pilot programs in Australia | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Diabetes and PAD Prevalence
The International Diabetes Federation estimated 537 million adults living with diabetes in 2024 and forecasts 643 million by 2030, with four-fifths of new cases clustered in developing regions.[1]International Diabetes Federation, “IDF Diabetes Atlas 2024,” idf.org Peripheral artery disease complicates 12%–15% of older diabetics, and the Centers for Disease Control and Prevention confirmed a 15-fold higher amputation risk for diabetic patients compared with non-diabetics. In India, undiagnosed PAD prevalence exceeds 25% among urban diabetics because primary care rarely performs ankle-brachial index testing, but new public screening mandates will soon expose this hidden cohort. China faces a similar surge, reporting 140 million diabetics in 2025, yet fewer than 30% receive statins, fueling progression to critical limb ischemia. These data point to a durable demand driver for revascularization devices, adjunct pharmacotherapy, and ultimately regenerative therapeutics.
Growing Adoption of Minimally Invasive Revascularization Devices
Percutaneous transluminal angioplasty and stenting represented 78% of all U.S. critical limb ischemia interventions in 2025, up from 62% five years earlier, due to shorter recovery times and lower hospital costs.[2]American College of Cardiology, “U.S. Revascularization Trends 2025,” acc.org Boston Scientific’s paclitaxel-free Ranger balloon achieved an 82% 12-month primary patency rate in below-the-knee lesions, capturing market share from legacy paclitaxel products. Medtronic’s IN.PACT Admiral balloon remains the leader in above-the-knee disease, with 2025 sales of USD 680 million; however, the company is diversifying into sirolimus coatings to navigate safety scrutiny. Segment diversification and rapid product cycles are therefore sustaining the device franchise even as novel biologics rise.
Aging Population Intensifying CLI Incidence
Japan projects that 35% of its citizens will be at least 65 years old in 2030, a demographic shift driving CLI rates to 400 per 100,000 person-years in this age bracket, which is triple the rate in younger cohorts.[3]Ministry of Health, Labour and Welfare Japan, “Population and Disease Statistics,” mhlw.go.jp Germany recorded an 18% jump in CLI hospitalizations between 2022 and 2025 despite stable diabetes prevalence, underscoring aging as an independent risk driver. South Korea’s national insurer reported average per-patient CLI expenditures of KRW 28 million (USD 21,000) in 2024, up 22% since 2022, because elderly patients often require multiple revascularizations. These data confirm that aging countries with generous coverage will continue to be premium markets for device and cell therapies.
FDA Breakthrough Designations Speeding BTK Device and Cell-Therapy Launches
LimFlow’s deep vein arterialization system secured FDA breakthrough device status in 2024 and full approval in 2025 after demonstrating 74% amputation-free survival at one year in no-option CLI. Pluristem’s PLX-PAD allogeneic cell therapy entered Phase III after a breakthrough designation in 2024 and aims for market entry by 2027. Cesca Therapeutics’ CartiCell autologous bone marrow platform also enjoys expedited review, shortening commercial timelines by up to two years. Breakthrough pathways thus reduce regulatory risk and send strong reimbursement signals to payers.
Restraints Impact Analysis of Critical Limb Ischemia Treatment Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Cost & Limited Reimbursement in Emerging Economies | -0.6% | India, Southeast Asia, sub-Saharan Africa, Latin America | Long term (≥ 4 years) |
| Underdiagnosis and Late Presentation | -0.5% | Sub-Saharan Africa, rural India, Latin America | Medium term (2-4 years) |
| Paclitaxel Device Safety Controversy | -0.4% | EU core markets, United States (Medicare population) | Short term (≤ 2 years) |
| Shortage of Trained Vascular Specialists | -0.3% | United States, United Kingdom, Australia; acute in GCC | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Cost and Limited Reimbursement in Emerging Economies
Drug-eluting balloons and stents cost USD 1,800–3,200 in India, but government schemes reimburse just USD 600, forcing patients to pay more than a year's median income out of pocket. Brazil offers coverage in public hospitals, yet waiting times average 180 days, prompting wealthier patients to seek private centers at BRL 45,000 (approximately USD 9,000) per case. Gulf Cooperation Council nations cover CLI fully for their citizens, but expatriate coverage caps at USD 5,000 per year, which is well below real-world costs. Tiered product portfolios and local manufacturing are emerging as mitigation strategies.
Underdiagnosis and Late Presentation
The World Health Organization reports that 60% of CLI cases in sub-Saharan Africa and 45% in rural India arrive at Rutherford 6, when tissue loss is irreversible. Less than 10% of primary care visits in low-resource regions include ankle-brachial index screening due to the scarcity of Doppler equipment. Argentina documented a 14-month median lag from symptom onset to specialist referral in 2024, explaining high amputation rates. Point-of-care Dopplers priced under USD 200 could close this gap, but require national adoption schemes.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Critical Limb Ischemia Treatment Market Segment Analysis
By Treatment Type:
Regenerative Therapies Outpace Devices Despite Smaller BaseDevices accounted for 62.81% of 2025 revenue, anchored by drug-eluting stents, plain balloons, and atherectomy systems. Embolic protection devices accounted for just 3% of device revenue, as they are primarily reserved for high-risk distal work. Peripheral dilatation systems, such as Cardiovascular Systems’ Diamondback 360, grew 14% year-over-year, displacing plain angioplasty in calcified lesions. The growth of vascular and drug-eluting stents softened to a 3.2% CAGR amid headwinds from paclitaxel. Regenerative and cell-based therapies held an 8% share in 2025, but their 10.06% CAGR positions them to erode repeat device revenue, as successful biologic repair lowers re-intervention rates.


By End-User:
Ambulatory Surgical Centers Capture Complex ProceduresHospitals still accounted for 46.03% of the revenue in 2025; however, payer steering and bundled payments are shifting suitable cases to ambulatory environments that deliver similar outcomes at a lower cost. Ambulatory surgical centers executed 28% of U.S. CLI interventions in 2025 and are growing at a 10.72% CAGR, lifted by CMS coverage of below-the-knee angioplasty since 2024. Office-based labs, a subset of ASCs, accounted for 35% of Boston Scientific’s Ranger balloon sales in 2025, up from 18% in 2023, confirming a shift in channel economics. The specialty vascular and wound-care clinics segment is growing at a rapid pace, as integrated care models demonstrate a 40% reduction in major amputations.
Geography Analysis
North America Critical Limb Ischemia Treatment Market
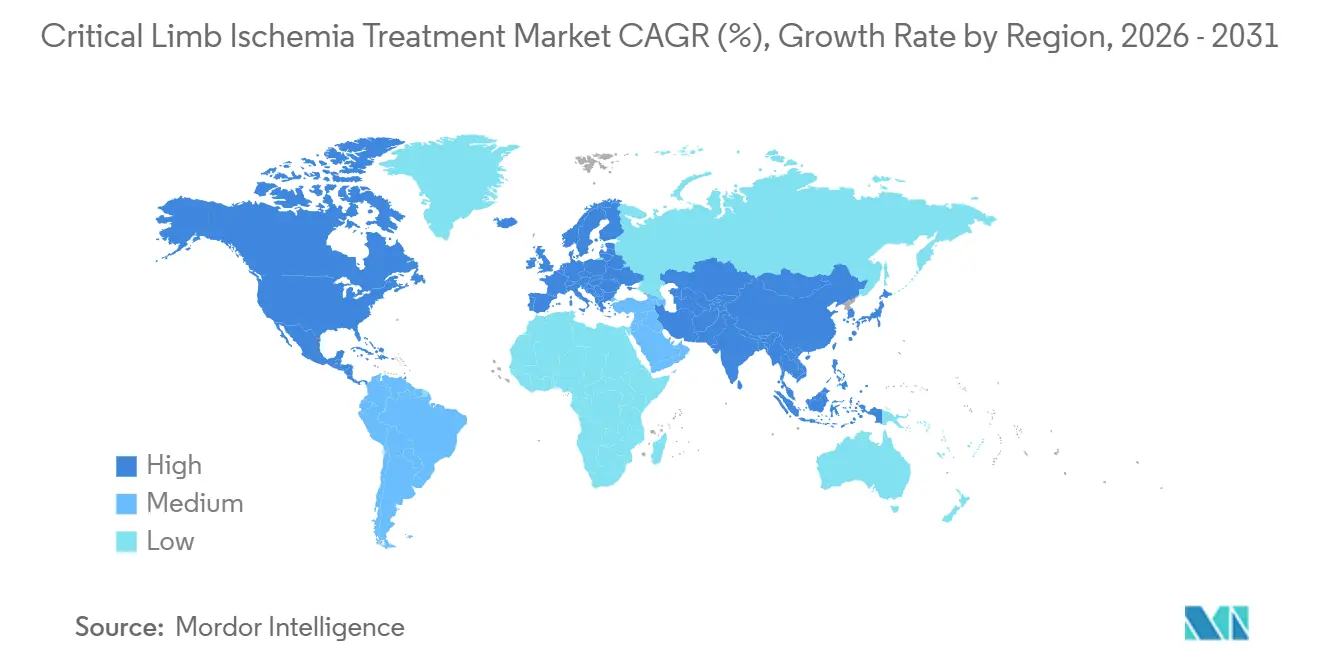
North America dominated with a 44.32% share in 2025, due to U.S. Medicare’s generous reimbursement, which underpins device usage. However, scrutiny of paclitaxel and a mature installed base temper the acceleration. Canada reimburses CLI at CAD 8,500 (USD 6,300), which is 25% below U.S. rates, thereby restraining premium adoption. Mexico expanded its vascular capacity by 18% between 2023 and 2025; however, specialist scarcity continues to keep guideline adherence below 40%. U.S. limb-preservation protocols delivered via telehealth are opening adjacent Latin markets to American devices, further consolidating supplier advantage.
Germany and United Kingdom Critical Limb Ischemia Treatment Market
Germany halted broad paclitaxel reimbursement in 2024, resulting in a one-third reduction in national sales. Conversely, the United Kingdom issued positive guidance for LimFlow’s deep vein arterialization system in 2026, creating a GBP 45 million (USD 57 million) opportunity.
APAC Critical Limb Ischemia Treatment Market
Asia-Pacific is the growth driver with an 11.53% CAGR. China’s approval of 14 home-grown drug-eluting devices between 2024 and 2025 reduced local prices by 60%, unlocking rural demand and expanding the critical limb ischemia treatment market size in the region. Japan grows 5.2% as reimbursement for cell therapies rose 18% in 2025. Australia’s TGA green-lit Cynata’s Cymerus therapy for compassionate use in 2025, reinforcing its role as a regenerative test bed.
MEA Critical Limb Ischemia Treatment Market
Saudi Arabia has earmarked SAR 12 billion (approximately USD 3.2 billion) for 50 limb-preservation clinics by 2028. The UAE’s 2024 fast-track pathway shrank device approval times from 18 to 6 months, encouraging multinational launches. Sub-Saharan Africa remains underserved, with only 22% of patients in South Africa receiving revascularization due to cost and capacity constraints.

Regulatory Landscape
Regulation for critical limb ischemia (CLI) devices and advanced therapies is increasingly shaped by expedited pathways and higher expectations for long-term safety evidence. In the United States, the FDA has used breakthrough and novel review mechanisms to accelerate limb-salvage technologies, including approval of the LimFlow System (P220025) for no-option chronic limb-threatening ischemia. This reinforces an indication-specific route that leans heavily on amputation-free survival and durable patency endpoints.
In Europe, market access continues to be influenced by MDR implementation and parallel efforts to reduce innovation bottlenecks. The European Commission has been running a targeted evaluation and reform discussion for MDR/IVDR through 2025-2026, while the Medical Device Coordination Group (MDCG) issued 2025 updates to the European Medical Device Nomenclature (EMDN) that add and refine peripheral vascular device categories, affecting conformity assessment alignment and post-market coding. For drugs and clinical development standards, EMA finalized a modernized guideline on peripheral arterial occlusive disease (replacing a 2002 framework), and professional guidance such as the European Society for Vascular Surgery (ESVS) 2026 focused update on paclitaxel-coated technologies continues to shape how coated devices are positioned in EU clinical practice.
Competitive Landscape
The five most prominent companies, Medtronic, Boston Scientific, Abbott Laboratories, Cook Medical, and Terumo, controlled significant revenue in 2025, illustrating moderate concentration. Medtronic generated USD 1.2 billion from CLI balloons and stents in fiscal 2025, but growth slipped to 2.8% amid safety questions. Boston Scientific’s USD 145 million purchase of Bolt Medical in 2024 included the Motus thrombectomy system, which addresses 18% of CLI cases complicated by clot burden. Abbott leveraged the Supera stent’s 89% two-year patency to target below-the-knee disease traditionally owned by Cook Medical’s Zilver PTX. White-space arenas include AI perfusion imaging, where Philips and Siemens are early movers, point-of-care cell processing from Cesca, and deep vein arterialization led solely by LimFlow. Disruptors such as Rexgenero and Micro Medical Solutions are exploiting local cost advantages and novel biologic platforms, eroding incumbent share from below.
Critical Limb Ischemia Treatment Industry Leaders
LimFlow SA
Cardiovascular Systems, Inc
Eli Lilly and Company
Abbott Laboratories
Medtronic
- *Disclaimer: Major Players sorted in no particular order
Critical Limb Ischemia Treatment Market Companies Covered in this Report
- Abbott Laboratories
- AngioDynamics
- B. Braun
- Biotronik SE & Co.
- Boston Scientific
- Cardiovascular Systems
- Cesca Therapeutics (ThermoGenesis)
- Cook Group
- Cynata Therapeutics
- Eli Lilly and Company
- LimFlow
- Medtronic
- Micro Medical Solutions
- Koninklijke Philips
- Pluristem Therapeutics
- Rexgenero
- Smiths Group
- Teva Pharmaceutical Industries
- Terumo Corp.
- W. L. Gore & Associates

Market Opportunities and Future Outlook
White-space growth is concentrated in below-the-knee (BTK) revascularization and limb-salvage options for no-option CLTI, where repeat interventions and amputation risk keep economic and clinical pressure high. Recent signals include FDA actions supporting novel BTK platforms, such as Abbott's Esprit BTK everolimus-eluting resorbable scaffold approval (April 2024) and Reflow Medical's De Novo clearance for the Spur Peripheral Retrievable Stent System for infrapopliteal disease (May 2025). Alongside deep vein arterialization (DVA) adoption and guideline-driven device scrutiny, these approvals widen the set of reimbursable toolkits for complex infrapopliteal anatomy and support differentiated pricing and site-of-care strategies in hospitals and ambulatory settings.
Regenerative and cell-based approaches remain a key opportunity area because they target failure modes that devices do not fully address, including microvascular dysfunction, poor collateralization, and wound-healing limitations. The pipeline is being reinforced by 2026 research advances in GMP-adaptable hiPSC-derived vascular progenitor cell platforms and engineered biomaterials designed to improve cell retention and angiogenesis, which can shorten translational timelines for companies pursuing scalable cell manufacturing and point-of-care processing models. At the same time, clinical trial activity for PAD and CLTI-adjacent populations, including registry-listed studies and late-stage programs, supports broader physician familiarity with advanced endpoints and can improve patient identification and referral flows into limb-preservation pathways.
Recent Industry Developments in Critical Limb Ischemia Treatment Market
- February 2026: Eli Lilly and Company reported that protocol modifications for its Phase 3 study (2025-523283-21-00) evaluating orforglipron in patients with peripheral artery disease were accepted by regulatory authorities. The update keeps a large cardiovascular-metabolic player active in PAD, a key upstream driver population for chronic limb-threatening ischemia, and supports continued evidence generation that can shift medical management pathways alongside devices.
- October 2025: MEDINET signed an option license to commercialize Stempeucel regenerative therapy for chronic limb-threatening ischemia in Japan. The move expands access planning for a cell-based approach in an aging, reimbursement-driven market where coverage for regenerative modalities has been increasing, and it strengthens cross-border commercialization models for advanced therapies.
- March 2024: Elixir Medical received FDA breakthrough device designation for its DynamX BTK adaptive implant designed for below-the-knee vessels. The designation signals regulatory prioritization for BTK innovation and helps accelerate clinical development and stakeholder engagement for next-generation implants targeting complex infrapopliteal disease.


Critical Limb Ischemia Treatment Market Report Scope and Research Methodology
Market Definition and Coverage
This market covers revenue generated from treatments used to manage critical limb ischemia by restoring or maintaining blood flow and supporting limb salvage, across drugs, devices, and relevant procedures in routine clinical care.
Scope exclusions: Diagnostic imaging platforms and therapies meant only for earlier intermittent claudication are not counted.
Segments Covered in This Report
- By Treatment Type
- Devices
- Embolic Protection Devices
- Peripheral Dilatation Systems
- Balloon Dilators
- Vascular & Drug-Eluting Stents
- Drugs
- Antiplatelet Agents
- Antihypertensive Agents
- Lipid-Lowering Agents
- Antithrombotic Agents
- Regenerative & Cell-Based Therapies
- Devices
- By End-User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Vascular & Wound-Care Clinics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
To build the base structure of the model, we start with public and official sources that help size the patient and procedure pool and explain care pathways. Sources used include items such as the World Health Organization health statistics, Centers for Disease Control and Prevention publications, U.S. FDA device and safety databases, and OECD health data for treatment access and utilization signals. For supporting clinical context, we also review peer-reviewed vascular and cardiology journals and guidance from vascular surgery and cardiovascular associations.
Alongside these, we use company annual reports, regulatory updates, investor presentations, and reputable healthcare press to understand portfolio mix, geographic exposure, and pricing direction. We also reference select paid subscriptions for company financials and intelligence, patent databases, and shipment-level import and export checks when device flow needs clarification. The desk sources listed here are illustrative and not exhaustive, and many other public references are used for cross-checks and clarification during the work.
Primary Interviews and Surveys
Primary work is used to pressure-test the model assumptions around therapy mix, setting shifts, and pricing behavior across the forecast window. We speak with stakeholders across device and drug supply, clinicians, and procurement and reimbursement facing roles, covering major regions so gaps from desk inputs can be closed and final totals can be reconciled to real-world care patterns.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 37% | CXOs: 16% | APAC: 48% |
| Mid tier: 44% | Functional/Unit leaders: 26% | EMEA: 32% |
| Smaller Players: 19% | Managers: 58% | Americas: 20% |
Market-Sizing & Forecasting
The core model is built using a top-down approach where prevalence and treated-pool logic is converted into spend by linking care pathways to procedure volumes and typical therapy baskets. Because the condition is not managed with one single product, the sizing is anchored on a few practical building blocks such as the CLI patient pool, revascularization procedure counts, amputation and limb-salvage trends, adoption of endovascular versus surgical routes, and setting mix across hospitals and ambulatory centers.
To make sure the totals stay realistic, results are then corroborated with selective bottom-up approximations, including sampled ASP times volume checks for key device and drug categories and limited supplier and channel conversations for mix sanity. Where direct volume signals are weak in a country, we bridge gaps using proxy indicators like diabetes prevalence, peripheral artery disease burden, specialist density, and reimbursement access, and then the assumptions are re-checked through follow-up calls.
For forecasting, we rely on scenario analysis supported by variable-level direction from interviews, and then the trajectory is smoothed against historical demand indicators so sudden jumps are avoided unless a clear trigger exists. Key forward drivers that are explicitly modeled include aging population, diabetes rates, hospital capacity and cath-lab activity, guideline-driven use of revascularization, and price movement as product mix changes over time.
Data Validation & Update Cycle
Outputs are checked using multiple layers so the model does not drift away from observable healthcare signals. We compare derived totals against independent indicators like procedure volumes, treatment rates, and regional spending patterns, and then we run variance checks by geography to spot outliers that are not supported by the underlying inputs.
Before sign-off, the work is reviewed across analysts, and any large deviation triggers a re-check of the patient pool, pricing assumptions, and currency conversion timing. Reports are refreshed annually, and interim adjustments are made when material events occur, such as major regulatory actions, reimbursement changes, or abrupt shifts in procedure activity. Right before delivery, a fresh pass is done so clients receive the most current view available.
Mordor Intelligence's Critical Limb Ischemia Treatment Market Size Compared Against Other Published Estimates
It is common to see different market sizes for critical limb ischemia treatment because each publisher chooses its own timing, scope boundaries, and pricing logic. Differences also show up when procedure intensity is assumed broadly, or when patient pools are not reconciled to how care is actually delivered by region.
In our work, the market value is kept aligned to a consistent annual USD conversion point and an explicit ASP progression by therapy category, and that refresh and validation cadence is one reason Mordor Intelligence lands at a different 2026 value than sources anchored to earlier base years. Another driver is scope handling, where some estimates blend adjacent peripheral artery disease therapies that are not specific to CLI, and others assume faster adoption of premium device mixes without matching it to reimbursement and site-of-care realities.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 5.47 B (2026) | |
| Global Consultancy A | USD 5.09 B (2024) | Uses a 2024 base and a broader treatment and device grouping, which can pull in earlier-stage PAD therapies, and it applies a faster growth path that lifts the implied 2026 run-rate. |
| Industry Publisher B | USD 5.12 B (2024) | Anchors sizing to a 2024 base with a longer forecast window, and the higher implied near-term growth can come from more aggressive uptake and pricing assumptions that are not always tied back to procedure capacity and reimbursement checks. |
The spread in published values mostly comes from base-year choice, how tightly CLI-only therapies are separated from adjacent PAD care, and how price and mix are carried forward. When the patient pool, procedure pathway, and ASP movements are kept transparent and reviewed against external signals, the resulting market size becomes easier to reproduce and explain during decision-making discussions.


Key Questions Answered in the Report
How large is the critical limb ischemia treatment market in 2026?
The market generated USD 5.47 billion in 2026 and is projected to reach USD 7.03 billion by 2031, growing at a 5.15% CAGR.
Which treatment segment is expanding fastest?
Regenerative and cell-based therapies are advancing at a 10.06% CAGR, outpacing both devices and drugs.
Why are ambulatory surgical centers gaining share in CLI procedures?
CMS reimbursement and same-day discharge protocols make ASCs cost-effective, enabling them to perform 28% of U.S. interventions in 2025.
What is driving rapid growth in Asia-Pacific?
China’s approval of locally made drug-eluting devices and India’s expansion of Ayushman Bharat coverage are propelling an 11.53% regional CAGR.
Which companies lead the competitive landscape?
Medtronic, Boston Scientific, Abbott Laboratories, Cook Medical, and Terumo together generate significant revenue, but new entrants in biologics and imaging are challenging their dominance.
Page last updated on:





