
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 5.41 Billion |
| Market Size (2026) | USD 5.69 Billion |
| Market Size (2031) | USD 7.30 Billion |
| Growth Rate (2026 - 2031) | 5.11 % |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
China Crop Protection Chemicals Market Analysis by Mordor Intelligence
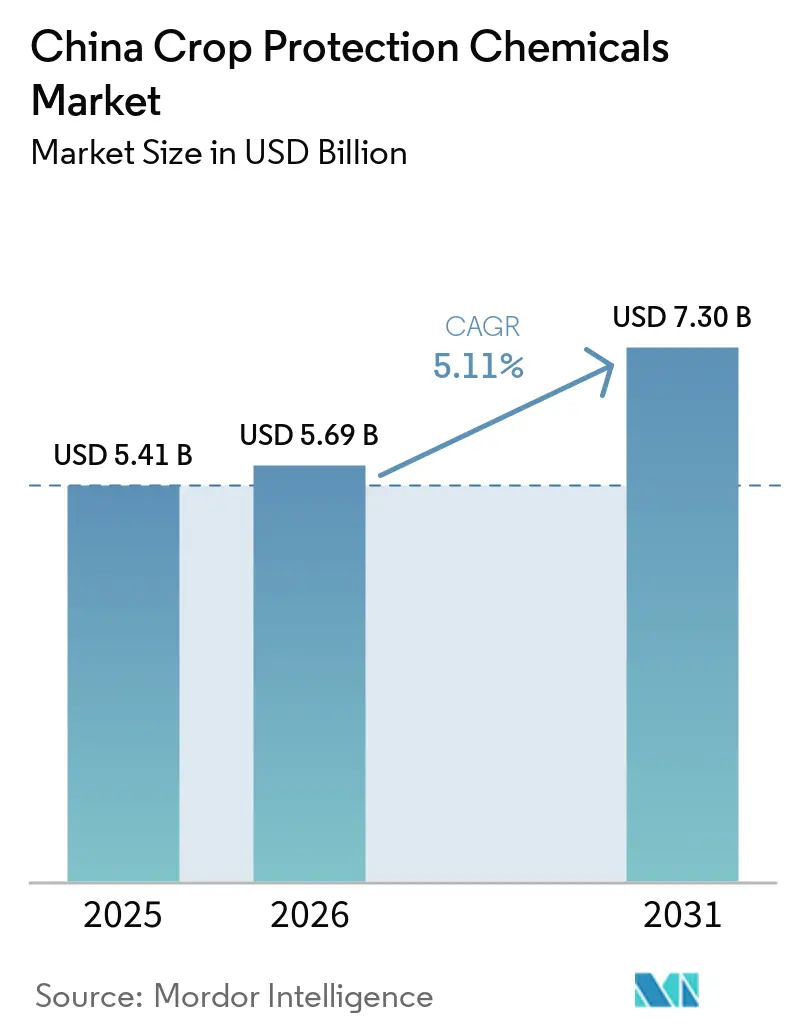
The China crop protection chemicals market size was valued at USD 5.41 billion in 2025 and is forecast to grow from USD 5.69 billion in 2026 to USD 7.30 billion by 2031, at a CAGR of 5.11% from 2026 to 2031. The market is being shaped by China's focus on food security and higher agricultural productivity, which is sustaining demand for crop protection products across major grain-producing regions. The national crop farming development plan for the 15th Five-Year Plan period targets a comprehensive grain production capacity of approximately 725 million metric tons by 2030 and calls for more precise and careful use of fertilizers and pesticides, according to the Ministry of Agriculture and Rural Affairs[1]. This policy direction supports demand for products that can provide effective pest and disease control while reducing unnecessary pesticide applications and environmental impact. The market also offers opportunities across both large-scale grain production and higher-value fruit, vegetable, and specialty-crop cultivation, where residue management and product performance are increasingly important. Suppliers with differentiated formulations, resistance-management capabilities, regulatory compliance, and established distribution networks are therefore better positioned as China's crop protection market shifts toward more efficient and targeted pesticide use.
Key Report Takeaways
- By function, herbicides accounted for 39.0% of the China crop protection chemicals market share in 2025 and are forecast to grow at a CAGR of 5.4% from 2026 to 2031.
- By application mode, foliar application accounted for 46.0% of the China crop protection chemicals market size in 2025, while soil treatment is forecast to grow at a CAGR of 5.9% from 2026 to 2031.
- By crop type, grains and cereals accounted for 52.0% of the China crop protection chemicals market share in 2025, while fruits and vegetables are forecast to grow at a CAGR of 6.0% from 2026 to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
China Crop Protection Chemicals Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Food-Security Grain Self-Sufficiency Programs | +1.5% | National, with highest relevance in Northeast, Central, and East China | Short term (≤ 2 years) |
| Labor Scarcity and Mechanized Post-Emergence Weed Control | +1.0% | National, with strongest relevance in Northeast and Central China | Medium term (2-4 years) |
| Precision Agriculture and Drone Spraying | +0.8% | National, with early gains in Heilongjiang, Jiangsu, and Xinjiang | Medium term (2-4 years) |
| Expansion of High-Value Fruits and Vegetables and Export Compliance | +0.7% | East, South, and Southwest China | Medium term (2-4 years) |
| Transgenic Corn and Soybean Commercialization Shifting Herbicide Mix | +0.5% | Northeast and Central China | Long term (≥ 4 years) |
| Distributor Consolidation and Agricultural-Input E-Commerce | +0.4% | National, with early gains in Shandong, Henan, and Jiangsu | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Food-Security Grain Self-Sufficiency Programs
China’s focus on food security and grain self-sufficiency is supporting sustained demand for crop protection chemicals across major staple-crop production areas. The national crop farming development plan for the 15th Five-Year Plan period (2026–2030) targets comprehensive grain production capacity of about 725 million metric tons by 2030 and calls for more precise and careful use of fertilizers and pesticides, according to the Ministry of Agriculture and Rural Affairs. The policy direction supports continued use of fungicides, insecticides, and herbicides to protect yields during critical crop-development stages, particularly in large-scale grain production. In addition, China’s National Food Security Law, effective from June 2024, aims to maintain absolute security in staple grains and basic self-sufficiency in other grains, reinforcing the importance of reliable domestic agricultural production and input availability, according to the United States Department of Agriculture Foreign Agricultural Service (USDA FAS). These priorities make effective crop protection an important component of maintaining stable yields and reducing production risks. Suppliers offering products with strong efficacy, appropriate application rates, and reliable availability are therefore well positioned to benefit from China’s long-term food-security agenda.
Labor Scarcity and Mechanized Post-Emergence Weed Control
Rural labor movement toward non-agricultural employment is increasing the need for labor-saving weed-control practices, particularly where manual weeding is difficult to complete within narrow crop-protection windows. Selective post-emergence herbicide programs can reduce manual field operations and the number of field passes, increasing the value of reliable chemical weed-control programs across larger managed farms. China’s expanding grain production also provides a substantial application base for herbicides. According to the USDA FAS, China is anticipated to produce a record 301.2 million metric tons of corn in marketing year 2025/26, supported by higher yields. Larger-scale corn production and greater reliance on mechanized farming support the adoption of chemical weed management as an alternative to labor-intensive practices. The China crop protection chemicals market therefore benefits as grain producers increasingly prioritize herbicide programs that provide effective post-emergence control with fewer field operations.
Precision Agriculture and Drone Spraying
The adoption of agricultural drones is changing application practices and increasing the performance requirements for crop protection formulations used across grain and horticultural crops. Drone-based spraying requires formulations that can perform consistently under lower spray volumes and varying droplet characteristics, while compatibility with adjuvants and application equipment is becoming increasingly important. Advances in agricultural spraying drones, including higher-capacity systems designed for large-scale field operations, are expanding the scope of drone-based crop protection applications. The expansion of drone-based application can improve the efficiency and timeliness of crop protection across both large and fragmented farms. This trend creates opportunities for suppliers offering formulations optimized for aerial application, while increasing the importance of compatibility with the equipment used by local agricultural service providers.
Expansion of High-Value Fruits and Vegetables and Export Compliance
The expansion of higher-value fruit and vegetable production is increasing the importance of residue management and compliance with pesticide standards, particularly for producers supplying export-oriented and quality-sensitive markets. According to the USDA FAS, China’s revised GB 2763 national food safety standard for pesticide maximum residue limits entered into force on March 1, 2026, establishing 10,749 maximum residue limits for 585 pesticides[2]. The broader residue framework increases the need for growers to select crop protection products that provide effective pest and disease control while meeting applicable domestic and export-market requirements. This is particularly relevant for fruit and vegetable producers in major horticultural regions, where buyer specifications and destination-market standards can influence pesticide selection. Suppliers offering registered products with suitable residue profiles, effective pest control, and clear application guidance are therefore better positioned to serve quality-sensitive horticultural producers and reduce the risk of residue-related shipment rejections.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Tightening Registration, Maximum Residue Limits, and Toxic-Active Restrictions | -1.0% | National, with highest compliance burden in East and South China | Short term (≤ 2 years) |
| Resistance to Glyphosate, ALS Inhibitors, Pyrethroids, Neonicotinoids, and Triazoles | -0.8% | National, with highest pressure in Northeast, East, and Central China | Medium term (2-4 years) |
| Dual-Control Energy Policies and Environmental Shutdowns Causing Technical-Grade Volatility | -0.6% | National, with primary impact in Shandong, Hebei, and Yunnan production hubs | Short term (≤ 2 years) |
| Regenerative Rice and Reduced-Input Programs Cannibalizing Conventional Pesticide Demand | -0.4% | Central and South China | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Tightening Registration, Maximum Residue Limits, and Toxic-Active Restrictions
Stricter pesticide registration requirements and restrictions on toxic active ingredients are increasing the regulatory burden for manufacturers and growers in China. Compliance with evolving safety requirements necessitates regular reviews of product portfolios, registered uses, technical documentation, and labeling. These obligations can increase the cost and administrative burden of maintaining older products, particularly for smaller formulators and suppliers with limited regulatory capabilities. Products containing restricted active ingredients or lacking sufficient residue and safety data may require additional testing, revised application instructions, or withdrawal from specific uses, potentially delaying product launches and limiting market access. The market may therefore increasingly favor companies with established registration expertise, comprehensive technical documentation, and portfolios aligned with evolving pesticide safety requirements.
Resistance to Glyphosate, ALS Inhibitors, Pyrethroids, Neonicotinoids, and Triazoles
Resistance to established herbicides is reducing the effectiveness of commonly used crop protection programs and narrowing weed-control options in major rice-producing areas. A 2025 study published in Scientific Reports found that penoxsulam resistance in Echinochloa populations from 13 rice-growing regions of Jiangsu increased ninefold over five years, while quinclorac resistance remained above 40% annually for four consecutive years[3]. The study also identified increasing resistance to other herbicides, including bispyribac-sodium and cyhalofop-butyl, as well as multiple-resistance patterns involving different modes of action. Repeated use of herbicides with similar modes of action can therefore reduce treatment effectiveness and increase the need for integrated weed management and rotation across different modes of action. This creates a restraint for the China crop protection chemicals market because growers may need to increase management complexity and adopt alternative products to maintain effective weed control, while suppliers face greater pressure to develop new active ingredients and resistance-management solutions.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Function: Herbicides Lead in Share and Growth
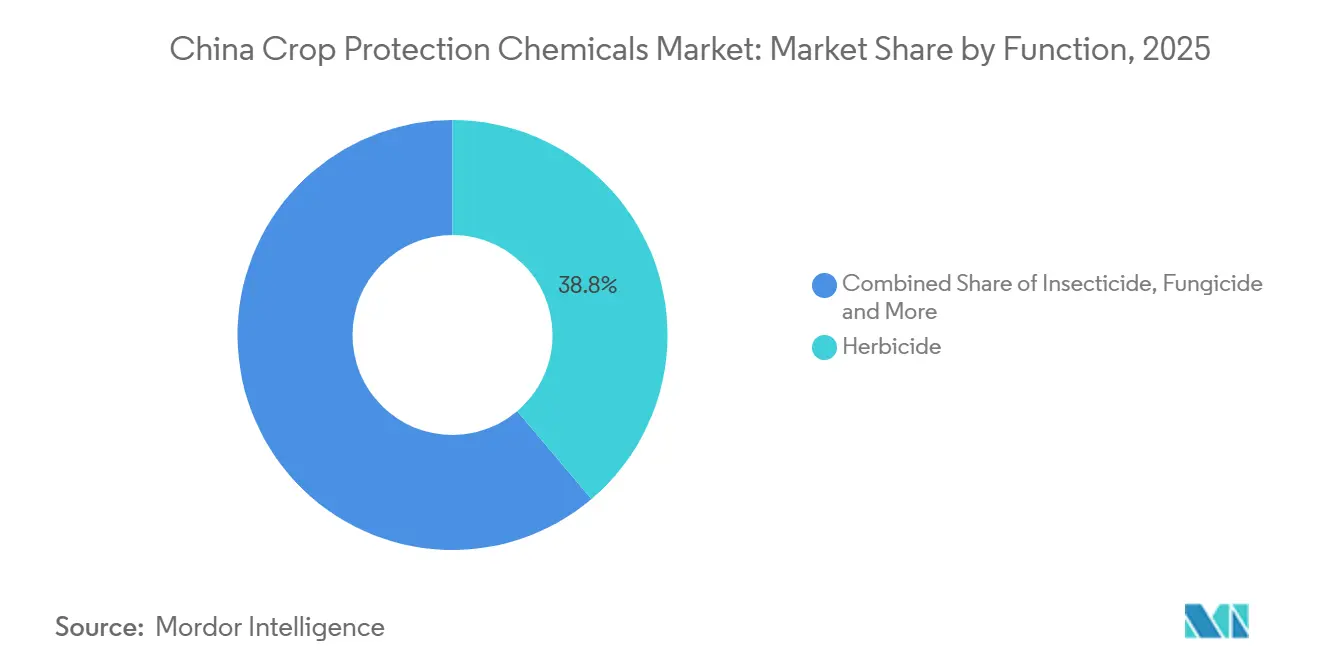
The herbicide segment accounted for 39.0% of the China crop protection chemicals market share in 2025, making it the largest function segment. Its leading position is supported by the expansion of mechanized farming, labor shortages, and the need for efficient weed control across major grain crops such as corn, wheat, and rice. Larger farms increasingly rely on chemical weed management to reduce manual field operations and maintain timely control during critical crop-growth stages. Insecticides remain important across rice, vegetables, and fruits, where recurring pest pressure supports regular applications, while fungicides continue to play an important role in disease management across grain and horticultural crops. The broad application base of herbicides across China's major cropping systems gives suppliers opportunities to serve both large-scale grain producers and smaller farms.
Herbicide is also the fastest-growing function segment, projected to expand at a 5.4% CAGR between 2026 and 2031. Its growth is supported by continued mechanization, increasing adoption of labor-saving weed-control practices, and the need to manage herbicide-resistant weed populations through more effective and diversified treatment programs. Growing demand for selective and post-emergence products is also encouraging suppliers to develop formulations with improved efficacy and crop safety. At the same time, resistance management is increasing the importance of rotating modes of action and integrating chemical and non-chemical weed-control practices. These trends are creating opportunities for players with differentiated herbicide portfolios, while regulatory requirements and resistance concerns are increasing the importance of product stewardship and application guidance.



By Application Mode: Foliar Leads While Soil Treatment Emerges as the High-Growth Channel
Foliar application accounted for 46.0% of the China crop protection chemicals market size in 2025, making it the largest application mode. Its leading position is supported by its compatibility with a broad range of herbicides, insecticides, and fungicides across major grain, fruit, and vegetable crops. Foliar spraying also provides flexibility in timing applications according to crop growth stages and pest or disease pressure. The increasing use of agricultural drones is further supporting the relevance of foliar application by enabling more targeted spraying across large and fragmented fields. However, lower-volume drone applications are increasing the importance of formulations and adjuvants that can maintain consistent coverage and efficacy under different spray conditions.
Soil treatment is the fastest-growing application mode, forecast to expand at a 5.9% CAGR between 2026 and 2031. Its growth is supported by increasing use of soil-applied solutions for nematodes, soil-borne diseases, and other pests, particularly in higher-value horticultural production where crop losses can have a greater economic impact. Fumigation and systemic soil treatments remain relevant where disease and pest pressure justifies additional treatment costs, while chemigation offers opportunities in areas with suitable irrigation infrastructure. The growing adoption of targeted soil-treatment programs is encouraging suppliers to develop products suited to specific soil conditions, crops, and application systems, creating opportunities to differentiate beyond conventional foliar formulations.
By Crop Type: Grains and Cereals Dominate While Horticulture Drives Premium Growth
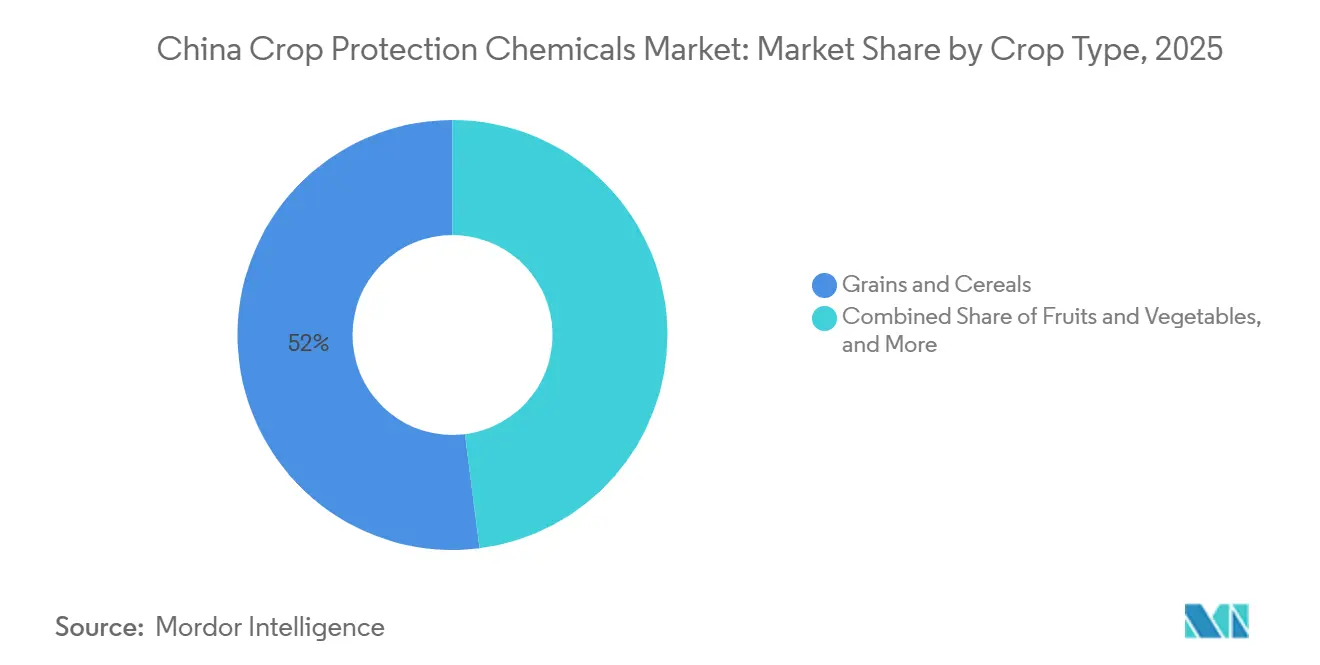
Grains and cereals accounted for 52.0% of the China crop protection chemicals market share in 2025, making them the largest crop type. Their leading position reflects the scale of China’s staple-crop production system and continued food-security priorities, which support the use of herbicides, insecticides, and fungicides across rice, wheat, corn, and other major grains. Large cultivated areas and recurring pest, weed, and disease pressure create consistent demand for crop protection products throughout the growing season. Pulses and oilseeds also contribute to herbicide demand, while turf and ornamental crops represent a smaller value segment with more specialized requirements. This broad crop base allows suppliers to serve high-volume grain production alongside more specialized crop-protection applications.
Fruits and vegetables are the fastest-growing crop type, forecast to expand at a 6.0% CAGR between 2026 and 2031. Growth is supported by intensive cultivation, higher crop values, and increasing requirements for effective pest and disease management in horticultural production. Export-oriented growers also place greater emphasis on residue compliance and the use of registered products that meet domestic and destination-market requirements. These factors are increasing demand for crop-specific formulations, lower-residue solutions, and technical guidance on application timing and product rotation. Suppliers with portfolios tailored to horticultural crops can therefore capture higher-value opportunities, although they must address stricter residue requirements and the greater complexity of crop-specific pest and disease management.

Geography Analysis
Jiangsu, Zhejiang, and Shandong represented the largest sub-regional market for crop protection chemicals in China in 2025, supported by intensive agricultural production and substantial fruit and vegetable cultivation. These provinces have strong horticultural and export-oriented production, generating demand for fungicides, insecticides, and insect-control products with suitable residue profiles. The implementation of updated pesticide residue standards is increasing the importance of registered products that meet domestic and export requirements, particularly for higher-value horticultural crops.
Heilongjiang and Jilin form the fastest-growing sub-region. Their growth is supported by large-scale grain farming, increasing mechanization, and greater adoption of drone-assisted crop protection and precision application technologies. High corn and soybean production in these provinces creates sustained demand for herbicides and other crop protection products, while the expansion of genetically engineered (GE) crop cultivation is influencing weed-management practices and herbicide demand.
Guangdong, Guangxi, and Fujian benefit from intensive horticulture and year-round pest and disease pressure, supporting regular crop protection applications across fruits and vegetables. Hebei, Henan, Xinjiang, and Inner Mongolia have larger grain-producing areas but can be more price-sensitive, potentially limiting the penetration of premium formulations. Across these provinces, differences in crop mix, farm scale, application technology, residue requirements, and purchasing capacity are creating differentiated demand for crop protection portfolios.
Competitive Landscape
Market Concentration
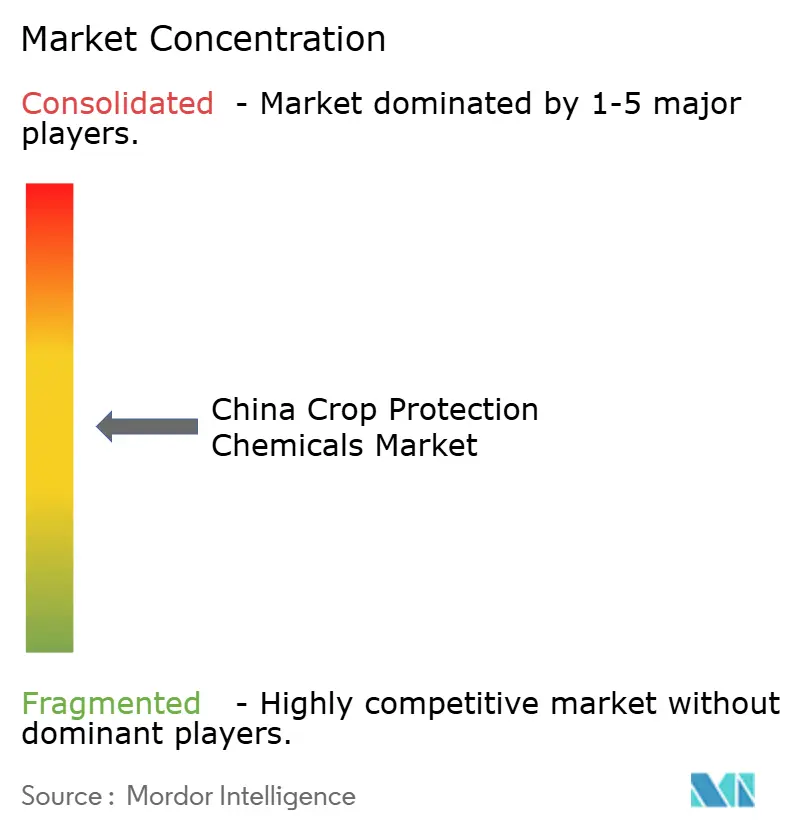
The China crop protection chemicals market was fragmented in 2025, with Syngenta Group Co., Ltd., Bayer AG, BASF SE, Corteva, Inc., and FMC Corporation among the major players. Competition involves multinational crop protection companies, domestic manufacturers of active ingredients, generic product suppliers, and regional formulators. Multinational companies compete through differentiated chemistries, broad product portfolios, and technical services, while domestic manufacturers leverage cost competitiveness and established local distribution networks. Nantong Jiangshan Agrochemical & Chemicals Co., Ltd. also contributes to domestic competition through the development and registration of crop protection products. This fragmented structure intensifies price competition in commodity products while increasing the importance of product efficacy, regulatory compliance, and distribution reach.
Competitive differentiation increasingly depends on proprietary chemistry, resistance management, and advances in product development. Multinational companies are strengthening their research and development capabilities and exploring technology-enabled approaches, while domestic manufacturers are investing in proprietary active ingredients and differentiated formulations. Nantong Jiangshan Agrochemical & Chemicals Co., Ltd.'s registration of isoxafenacil following more than a decade of development illustrates domestic investment in differentiated chemistry. Syngenta Group Co., Ltd.'s partnership with QuantumBasel in 2026 to explore quantum computing for molecular discovery and agricultural research demonstrates the use of advanced technologies in crop protection research. These developments highlight the growing importance of innovation, regulatory expertise, and application efficiency in maintaining competitive advantages.
Regional crop patterns and regulatory requirements create distinct competitive opportunities across China. Fruit and vegetable growers require crop protection products that meet residue standards and export-market requirements, while grain producers prioritize cost-effective solutions for weed, pest, and disease management across large cultivated areas. Companies with differentiated product portfolios, local registration expertise, field-level technical support, and established distribution networks are better positioned to address these varying requirements. The presence of numerous domestic manufacturers and regional formulators sustains competition, while investments in research and development and strategic partnerships offer opportunities to strengthen market positions. Consequently, competitive success depends on combining product efficacy, regulatory compliance, innovation, and distribution capabilities rather than relying solely on active-ingredient volumes or price competition.
China Crop Protection Chemicals Industry Leaders
-
BASF SE
-
Bayer AG
-
FMC Corporation
-
Syngenta Group Co., Ltd.
-
Corteva, Inc.
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: FMC launched Maipeng, a 36% bixlozone suspension concentrate herbicide in China. The product is positioned for pre-emergence soil application and addresses resistant grass weeds in wheat fields. The launch expands FMC's product positioning for wheat weed management and integrated resistance-control programs.
- July 2026: China’s pesticide registration program approved 522 pesticide products, including registrations covering newer active ingredients such as fluopyram, pyroxasulfone, and cyantraniliprole. The registrations included herbicidal, insecticidal, fungicidal, acaricidal, and plant-growth-regulating products, supporting continued portfolio development in the domestic crop protection market.
- November 2025: CAC Group launched Baishijia, a novel insecticide containing its independently developed active ingredient, cyproflanilide, to control crop-damaging insect pests.
China Crop Protection Chemicals Market Report Scope
Crop protection chemicals are substances used in agriculture to control pests, diseases, weeds, and other harmful organisms that affect crop yield and quality. They include herbicides, insecticides, fungicides, nematicides, and molluscicides applied to crops, seeds, and soil. The scope excludes biological crop protection products, microbial pesticides, botanical biopesticides, organic crop protection products, fertilizers, plant growth regulators, and other agricultural inputs that do not primarily function as conventional chemical pesticides.
The China crop protection chemicals market report is segmented by function (fungicide, herbicide, and more), by application mode (chemigation, foliar, fumigation, and more), and by crop type (commercial crops, fruits and vegetables, and more). The market sizes and forecasts are provided in terms of value (USD) and volume (metric tons).
Function
| Fungicide |
| Herbicide |
| Insecticide |
| Molluscicide |
| Nematicide |
Application Mode
| Chemigation |
| Foliar |
| Fumigation |
| Seed Treatment |
| Soil Treatment |
Crop Type
| Commercial Crops |
| Fruits and Vegetables |
| Grains and Cereals |
| Pulses and Oilseeds |
| Turf and Ornamental |
| Function | Fungicide |
| Herbicide | |
| Insecticide | |
| Molluscicide | |
| Nematicide | |
| Application Mode | Chemigation |
| Foliar | |
| Fumigation | |
| Seed Treatment | |
| Soil Treatment | |
| Crop Type | Commercial Crops |
| Fruits and Vegetables | |
| Grains and Cereals | |
| Pulses and Oilseeds | |
| Turf and Ornamental |
Market Definition
- Function - Crop Protection Chemicals are apllied to control or prevent pests, including insects, fungi, weeds, nematodes, and mollusks, from damaging the crop and to protect the crop yield.
- Application Mode - Foliar, Seed Treatment, Soil Treatment, Chemigation, and Fumigation are the different type of application modes through which crop protection chemicals are applied to the crops.
- Crop Type - This represents the consumption of crop protection chemicals by Cereals, Pulses, Oilseeds, Fruits, Vegetables, Turf, and Ornamental crops.
| Keyword | Definition |
|---|---|
| IWM | Integrated weed management (IWM) is an approach to incorporate multiple weed control techniques throughout the growing season to give producers the best opportunity to control problematic weeds. |
| Host | Hosts are the plants that form relationships with beneficial microorganisms and help them colonize. |
| Pathogen | A disease-causing organism. |
| Herbigation | Herbigation is an effective method of applying herbicides through irrigation systems. |
| Maximum residue levels (MRL) | Maximum Residue Limit (MRL) is the maximum allowed limit of pesticide residue in food or feed obtained from plants and animals. |
| IoT | The Internet of Things (IoT) is a network of interconnected devices that connect and exchange data with other IoT devices and the cloud. |
| Herbicide-tolerant varieties (HTVs) | Herbicide-tolerant varieties are plant species that have been genetically engineered to be resistant to herbicides used on crops. |
| Chemigation | Chemigation is a method of applying pesticides to crops through an irrigation system. |
| Crop Protection | Crop protection is a method of protecting crop yields from different pests, including insects, weeds, plant diseases, and others that cause damage to agricultural crops. |
| Seed Treatment | Seed treatment helps to disinfect seeds or seedlings from seed-borne or soil-borne pests. Crop protection chemicals, such as fungicides, insecticides, or nematicides, are commonly used for seed treatment. |
| Fumigation | Fumigation is the application of crop protection chemicals in gaseous form to control pests. |
| Bait | A bait is a food or other material used to lure a pest and kill it through various methods, including poisoning. |
| Contact Fungicide | Contact pesticides prevent crop contamination and combat fungal pathogens. They act on pests (fungi) only when they come in contact with the pests. |
| Systemic Fungicide | A systemic fungicide is a compound taken up by a plant and then translocated within the plant, thus protecting the plant from attack by pathogens. |
| Mass Drug Administration (MDA) | Mass drug administration is the strategy to control or eliminate many neglected tropical diseases. |
| Mollusks | Mollusks are pests that feed on crops, causing crop damage and yield loss. Mollusks include octopi, squid, snails, and slugs. |
| Pre-emergence Herbicide | Preemergence herbicides are a form of chemical weed control that prevents germinated weed seedlings from becoming established. |
| Post-emergence Herbicide | Postemergence herbicides are applied to the agricultural field to control weeds after emergence (germination) of seeds or seedlings. |
| Active Ingredients | Active ingredients are the chemicals in pesticide products that kill, control, or repel pests. |
| United States Department of Agriculture (USDA) | The Department of Agriculture provides leadership on food, agriculture, natural resources, and related issues. |
| Weed Science Society of America (WSSA) | The WSSA, a non-profit professional society, promotes research, education, and extension outreach activities related to weeds. |
| Suspension concentrate | Suspension concentrate (SC) is one of the formulations of crop protection chemicals with solid active ingredients dispersed in water. |
| Wettable powder | A wettable powder (WP) is a powder formulation that forms a suspension when mixed with water prior to spraying. |
| Emulsifiable concentrate | Emulsifiable concentrate (EC) is a concentrated liquid formulation of pesticide that needs to be diluted with water to create a spray solution. |
| Plant-parasitic nematodes | Parasitic Nematodes feed on the roots of crops, causing damage to the roots. These damages allow for easy plant infestation by soil-borne pathogens, which results in crop or yield loss. |
| Australian Weeds Strategy (AWS) | The Australian Weeds Strategy, owned by the Environment and Invasives Committee, provides national guidance on weed management. |
| Weed Science Society of Japan (WSSJ) | WSSJ aims to contribute to the prevention of weed damage and the utilization of weed value by providing the chance for research presentation and information exchange. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


