
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
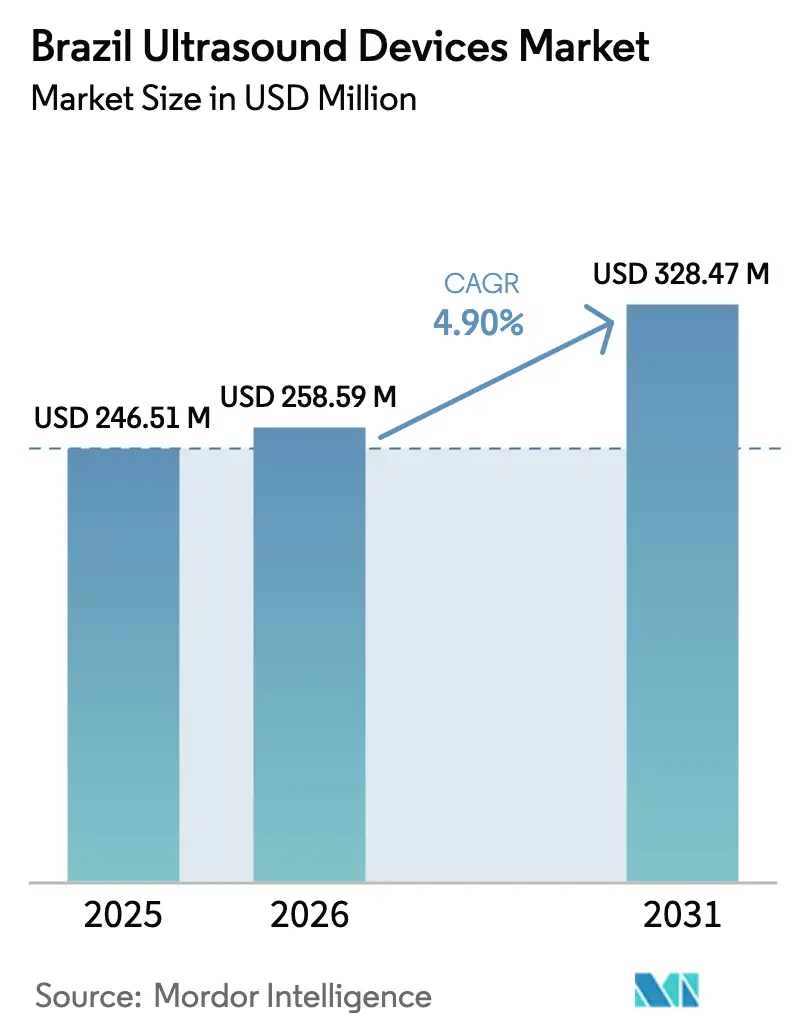
| Base Year Market Size (2025) | USD 246.51 Million |
| Market Size (2026) | USD 258.59 Million |
| Market Size (2031) | USD 328.47 Million |
| Growth Rate (2026 - 2031) | 4.90 % |
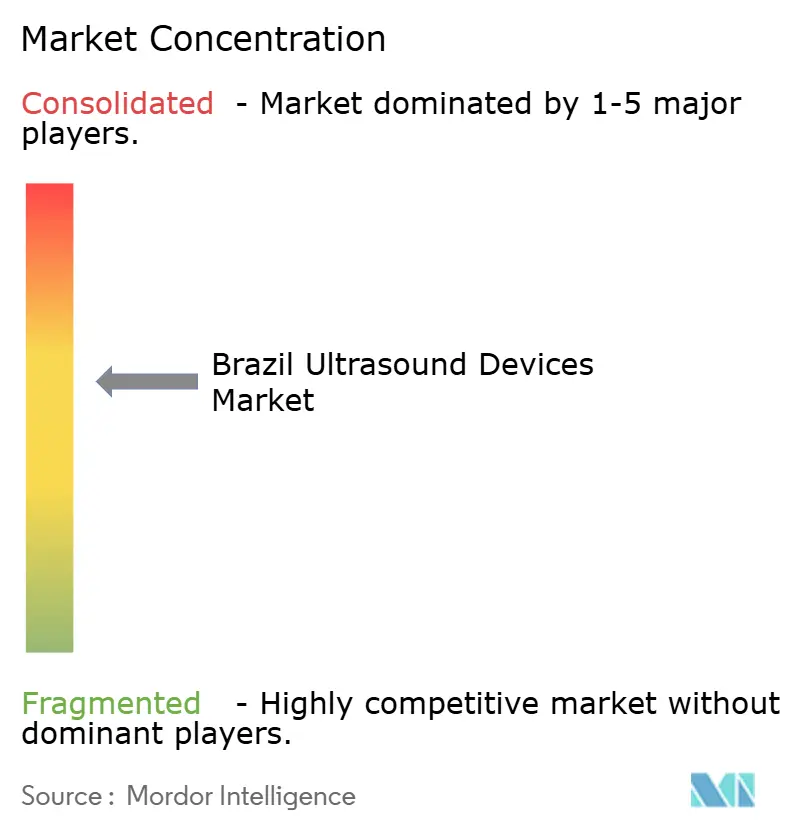
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Brazil Ultrasound Devices Market Analysis by Mordor Intelligence
The Brazil Ultrasound Devices Market size is expected to grow from USD 246.51 million in 2025 to USD 258.59 million in 2026 and is forecast to reach USD 328.47 million by 2031 at 4.90% CAGR over 2026-2031.
Growth rests on telehealth programs that move imaging services into remote municipalities, while AI integration raises productivity across crowded urban hospitals. Premium cart-based systems still dominate capital budgets, yet handheld scanners post double-digit gains as clinicians seek bedside diagnostics that do not require certified sonographers. Regional consumption is heavily skewed toward the Southeast where 54% of current installations are located, but government incentives are accelerating deployments in the North and Northeast. Price-sensitive public tenders are also widening the pathway for Chinese suppliers that pair adequate image quality with aggressive financing packages.
Key Report Takeaways
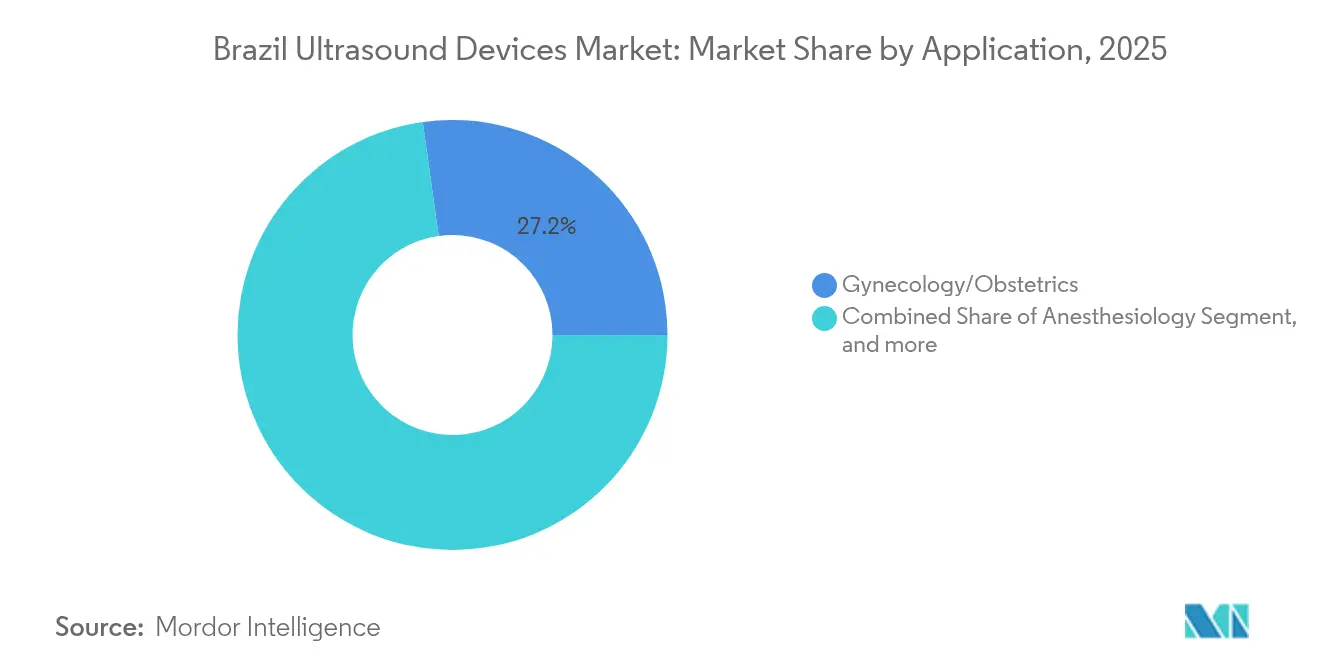
- By application, gynecology/obstetrics led with 27.21% revenue share in 2025, while anesthesiology is set to grow at an 7.78% CAGR from 2026 to 2031.
- By technology, 3D & 4D imaging captured 45.60% of the Brazil ultrasound devices market size in 2025; AI-enabled/automated ultrasound systems are poised for a 8.79% CAGR over the same horizon.
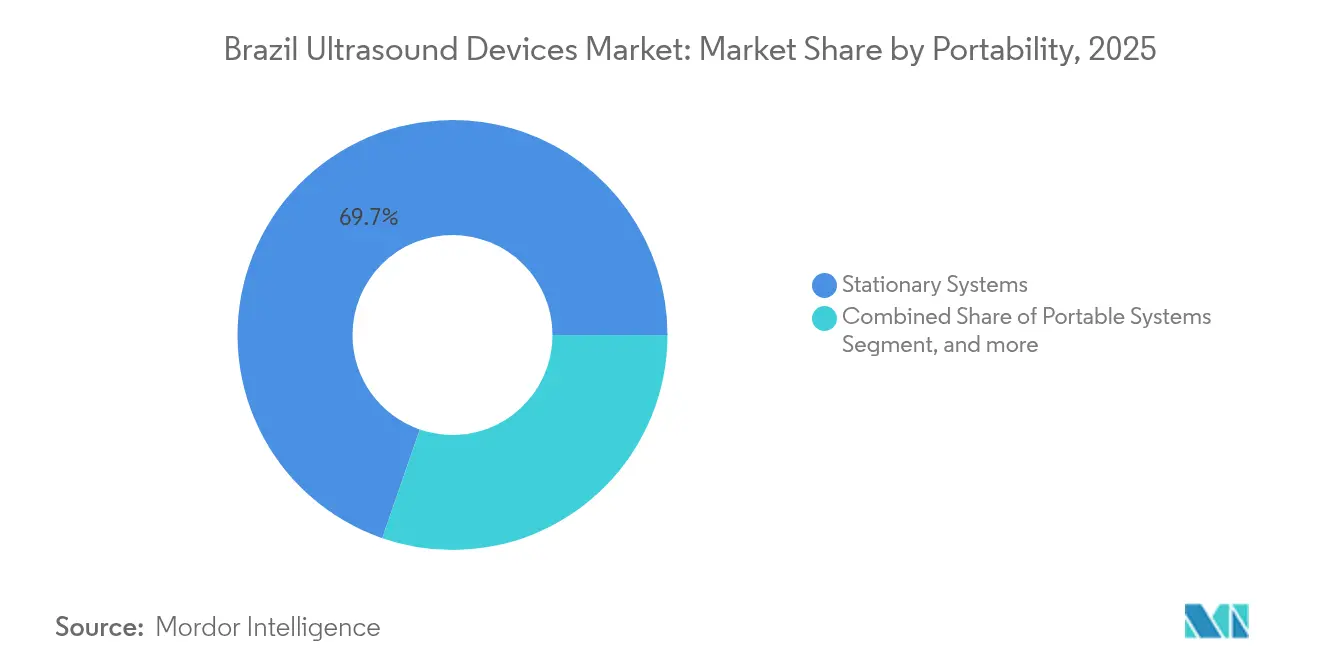
- By portability, stationary systems accounted for 69.70% of the Brazil ultrasound devices market size in 2025, whereas handheld/wireless scanners are climbing at an 10.72% CAGR toward 2031.
- By end user, hospitals represented 42.74% of the Brazil ultrasound devices market share in 2025, and diagnostic imaging centers are forecast to rise at a 7.23% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Brazil Ultrasound Devices Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of tele-ultrasound coverage through Brazil’s SUS “Telessaúde Brasil” network | +1.2% | North & Northeast | Medium term (2-4 years) |
| Rise of private diagnostic chains and imaging hubs | +0.9% | Southeast & South | Long term (≥4 years) |
| Mandatory cardiac screening for professional athletes | +0.6% | Nationwide | Short term (≤2 years) |
| High teenage pregnancy rates driving OB-GYN ultrasound demand | +0.5% | North & Northeast | Medium term (2-4 years) |
| Growing adoption of AI-enabled portable ultrasound systems | +1.0% | Nationwide | Short term (≤2 years) |
| Public–private collaborations expanding screening programs | +0.6% | Northeast & North | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||


Expansion of Tele-Ultrasound Coverage through SUS “Telessaúde Brasil” Network
Local health posts now transmit images to university hospitals where certified radiologists validate results. In 2024, 60.3% of teledermatology cases were resolved in primary care without referrals, demonstrating the same model that ultrasound sessions can emulate.[1]João Castelo-Branco, “Performance of Telehealth Centers in Pará,” teleconsulta.fiocruz.br Primary-care participation in the network already reaches 84.4%, and twelve dedicated tele-health hubs operate in the Amazon basin. By pairing low-bandwidth image compression with store-and-forward protocols, the Brazil ultrasound devices market gains access to municipalities previously unreachable by conventional service contracts. This initiative also mitigates the shortage of certified sonographers by letting nurses capture scans that specialists later interpret remotely. Medium-term impact is expected to lift utilization volumes and create recurring consumables demand for probe covers and gel in remote clinics.
Rise of Private Diagnostic Chains and Imaging Hubs
Urban conglomerates such as DASA are centralizing high-throughput equipment in regional hubs that process referrals from satellite collection points. Hub-and-spoke logistics raise utilization above 80%, enabling premium 3D & 4D consoles to recoup capital outlays faster. A 2024 study on handheld ultrasound accuracy in confirming intrauterine device placement showed 92.9% sensitivity, validating small-format imaging in busy obstetrics clinics. Chains now add handheld probes to obstetrics suites so technicians can triage routine checks, freeing premium rooms for complex fetal assessments. Over the long term, this operational model anchors a steady replacement cycle across the Brazil ultrasound devices market.
Mandatory Cardiac Screening for Professional Athletes
FIFA recommendations issued for the 2025 season place echocardiography within athlete evaluations once risk factors surface. Brazilian clubs and federations are procuring portable units that fit locker room constraints, fuelling a niche yet influential segment of the Brazil ultrasound devices market. A school-based study found handheld scanners flagged 7.9% of children with possible rheumatic abnormalities, although confirmatory machines verified only 3.2%, underscoring the value of rapid triage.[2]Victor Baggish, “FIFA Cardiac Screening Consensus,” escardio.org Demand clusters around training centres in major cities, giving manufacturers an entry point to promote AI modules that automate left-ventricular measurements.
High Teenage Pregnancy Rates Driving OB-GYN Ultrasound Demand
National fertility continues to decline, yet adolescent pregnancies persist above regional averages in the North and Northeast. Prenatal protocols require at least three scans per gestation, anchoring steady throughput for obstetric probes. Harvard T.H. Chan School researchers flagged persistent inequalities in diagnostic access, prompting federal grants that subsidize ultrasound procurement in maternal-health clinics.[3]Rifat Atun, “Cancer Care and Health System Inequities in Brazil,” hsph.harvard.edu Vendors now tailor maintenance packages that guarantee uptime in remote towns, further expanding the addressable Brazil ultrasound devices market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Class III reclassification of AI ultrasound systems | -1.1% | Nationwide | Short term (≤2 years) |
| Chronic shortage of certified sonographers | -0.9% | Nationwide | Long term (≥4 years) |
| Uneven distribution of imaging resources across regions | -0.7% | North & Northeast | Medium term (2-4 years) |
| Import dependency and currency fluctuation risks | -0.5% | Nationwide | Short term (≤2 years) |
| Source: Mordor Intelligence | |||
Class III Reclassification of AI Ultrasound Systems
ANVISA’s Resolution RDC 751/2022 raised AI-enabled devices from Class II to Class III, mandating full registration dossiers and factory inspections. Filing times lengthened, and working capital requirements climbed as importers stock units while awaiting approval. Smaller innovators risk delaying launches, narrowing competitive choices for public tenders across the Brazil ultrasound devices market. The burden is felt most in the short term until firms align quality-management files with Brazilian expectations.
Chronic Shortage of Certified Sonographers
Brazil tallies 2.77 physicians per 1,000 inhabitants, yet distribution skews toward general practice. Specialty imaging remains concentrated in capitals, leaving district hospitals without accredited sonographers. Procedure backlogs rise, lowering throughput even where equipment sits idle. Vendors respond with training modules and AI guidance, but workforce expansion needs policy intervention over the long term.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Application: Maternal Health Drives Market Leadership
Gynecology and obstetrics captured 27.21% of the Brazil ultrasound devices market size in 2025, underpinned by mandatory prenatal screening protocols and persistently high adolescent pregnancy rates in the North and Northeast. Hospitals allocate premium 3D cups and curved probes to maternity wards, ensuring fetal anomaly detection remains on par with international standards. Screening frequency supports steady consumables demand, reinforcing vendor service footprints in secondary cities.
Anesthesiology follows as the fastest-growing specialty at an 7.78% CAGR over 2026-2031. The shift toward ultrasound-guided nerve blocks lowers peri-operative opioid use, aligning with national patient-safety goals. Portable linear probes give anesthetists a real-time view of target nerves, enabling day-surgery centers to shorten turnaround times. Growth also benefits from residency-program curricula that now mandate ultrasound modules for regional blocks, widening practitioner familiarity across the Brazil ultrasound devices market.


By Technology: AI Integration Reshapes Capabilities
3D & 4D imaging commanded 45.60% of the Brazil ultrasound devices market share in 2025, driven by high-definition fetal screening and complex musculoskeletal evaluations. Private diagnostic chains market premium appointments to affluent urban consumers, leveraging volumetric renderings to differentiate services. Workstations include advanced workstation software that reconstructs heart valves for pre-surgical planning.
AI-enabled platforms are on course for a 8.79% CAGR, even after Class III reclassification raised compliance hurdles. Automating routine measurements reduces scan time for small clinics short on manpower, widening use cases in primary care. Cloud-delivered updates add cardiology and abdominal modules without hardware swaps, sustaining a longer revenue stream per installed base within the Brazil ultrasound devices market.
By Portability: Handheld Devices Transform Access Paradigms
Stationary carts retained 69.70% of the Brazil ultrasound devices market size in 2025 because tertiary hospitals still require full Doppler packages and transesophageal probes. Multi-disciplinary departments exploit integrated reporting software that links to electronic health records, justifying continued investment in high-end consoles.
Handheld scanners are rising at an 10.72% CAGR as community clinics and ambulance teams embrace their phone-like interfaces. In a 2024 field study, school nurses used handheld echocardiography to screen 3,000 children in less than four weeks, demonstrating scalability. Battery improvements now permit six hours of continuous operation, while waterproof housings suit tropical field work. This versatility strengthens the rural footprint and draws new public funding to the Brazil ultrasound devices market.
By End User: Hospitals Lead While Imaging Centers Grow Fastest
Hospitals, both public and private, accounted for 42.74% of the Brazil ultrasound devices market share in 2025. Multidisciplinary workflows rely on on-site radiologists who integrate imaging into surgical and emergency pathways. Replacement cycles are tied to accreditation audits that require image-quality benchmarks, securing recurring orders for premium probes.
Diagnostic imaging centers and radiology clinics are forecast to climb at a 7.23% CAGR as corporate networks open satellite sites near commuter rail stations. Chain operators maximize scanner uptime through extended evening hours, boosting throughput and unit economics. Public–private agreements grant these centers overflow patients from SUS, widening payer diversification and stabilizing cash flow inside the Brazil ultrasound devices market.
Geography Analysis
The Southeast holds economic and demographic primacy, translating significant share of installed systems in 2024. São Paulo and Rio de Janeiro host the headquarters of major private chains and academic hospitals that procure cutting-edge 3D & 4D consoles to maintain referral dominance. Despite volume strength, public–private disparities persist, prompting philanthropic programs to outfit peri-urban maternity wards with midrange carts.
The Northeast is the fastest-growing territory. Federal incentives subsidize equipment loans for municipalities with high maternal-mortality ratios. Regional health secretariats integrate mobile vans into prenatal outreach, connecting to obstetrics tele-consultants in Salvador. This structure raises preventive-care coverage and stimulates replacement demand for battery and probe components in the Brazil ultrasound devices market.
The North and Central-West together still represent a smaller slice, yet telemedicine corridors are shortening logistical hurdles across the Amazon basin. Twelve broadband hubs commissioned by the Federal University of Pará forward images to Belém specialists, shaving travel costs for riverine communities. Vendors tailor ruggedized kits that survive humidity and transport shocks, unlocking an untapped cohort of first-time buyers.
The South ranks second in revenue owing to higher per-capita income and insurance penetration. State legislatures pioneer unified referral portals that steer patients to the nearest available scanner, lifting utilization rates. Academic centres in Curitiba trial AI triage algorithms that flag abnormal scans for expedited review, a blueprint likely to spread nationwide and enlarge the Brazil ultrasound devices market.
Regulatory Landscape
ANVISA regulates ultrasound devices as medical devices, with market entry via Notification for Class I and II and Marketing Authorization for Class III and IV under RDC 751/2022. ANVISA IN 96/2021 sets sanitary requirements for diagnostic and therapeutic ultrasound equipment, including acceptance testing and periodic quality control expectations that hospitals and imaging centers must maintain. For Class III and IV devices, manufacturers must hold a GMP certificate issued by ANVISA.
GMP certification for Class III and IV devices affects supplier eligibility through audit readiness, which can also shift launch timing and tender participation across Brazil.
Competitive Landscape
Global multinationals dominate the premium segment, yet Chinese manufacturers are steadily gaining share by matching local technical-assistance requirements at lower price points. Global suppliers retain a technological edge, yet purchasing committees increasingly weigh life-cycle cost against headline specifications. GE Healthcare, Philips, and Siemens Healthineers collectively dominate tenders for high-end consoles, supported by local field-service networks. In 2024 they joined AdvaMed’s new Medical Imaging Division, aligning advocacy on cybersecurity patches and third-party servicing guarantees. This collaboration streamlines engagement with ANVISA during post-market surveillance inquiries.
Mindray spearheads the value segment, shipping cart models that bundle Doppler and touch-screen interfaces at a 20% discount to European peers. Local distributor networks ease after-sales logistics, helping the brand penetrate SUS procurement lists. Portable specialists Butterfly Network and Clarius Mobile Health target emergency physicians with app-based interfaces, and partnerships with telecom firms secure cloud storage packages that appeal to tele-health workflows in the Brazil ultrasound devices market.
Capital concentration remains moderate; leading brands account for nearly 55% of unit revenue, leaving space for domestic assemblers that import sub-systems and add probes locally. Currency volatility forces all vendors to hedge component costs, occasionally delaying price-list updates and lengthening negotiation cycles with public buyers.
Brazil Ultrasound Devices Industry Leaders
GE HealthCare
Siemens Healthineers AG
Koninklijke Philips N.V.
Canon Medical Systems Corporation
Fujifilm Sonosite Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Local production by global players supports supply resilience. Philips began national production of the CT 5300 scanner fully integrated with artificial intelligence in 2025. GE HealthCare prioritizes digital health and AI integration in its 2026 Brazil strategy, supported by a São Paulo engineering presence, while Canon Medical Systems operates a Campinas facility to serve the domestic market.
On the demand side, the SUS Telessaude Brasil network expansion and ongoing public-private collaborations shape uptake for AI-enabled portable ultrasound and tele-ultrasound workflows. PPPs such as the OpenCare5G project with Hospital das Clínicas in 2025 also point to practical pathways for remote imaging deployments.
Recent Industry Developments
- April 2026: Philips exhibited the Flash 5100 Point of Care ultrasound system at the 56th Jornada Paulista de Radiologia (JPR 2026) in São Paulo to support clinical decision-making. This event highlighted Philips' emphasis on connected and AI powered bedside imaging for Brazil.
- February 2026: GE HealthCare announced a USD 35 million contract expansion with BARDA to advance AI-powered ultrasound for trauma assessment and mass casualty preparedness. The deal extends public-private investment into advanced imaging capabilities and broadens GE's AI ultrasound portfolio in the region.
- January 2026: GE HealthCare announced Dasa became the first company in Brazil to implement ViewPoint 6 Ultrasound Reporting Software to integrate ultrasound data with EMR systems and improve reporting efficiency. The deployment signals movement toward streamlined ultrasound workflows in major diagnostic networks.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market covers ultrasound imaging systems sold in Brazil for diagnostic use across care settings, and it is measured as manufacturer-level revenue captured within the country during the period.
Scope exclusions: We exclude services (installation-only labor, maintenance-only contracts, and training-only fees) and used or refurbished unit re-sales when they are not booked as new-device revenue.
Segmentation Overview
- By Application
- Anesthesiology
- Cardiology
- Gynecology/Obstetrics
- Radiology/General Imaging
- Musculoskeletal
- Vascular
- Critical Care & Emergency
- Urology
- Gastroenterology
- By Technology
- 2D Ultrasound Imaging
- 3D & 4D Ultrasound Imaging
- Doppler Ultrasound (Color & Spectral)
- High-Intensity Focused Ultrasound (HIFU)
- Contrast-Enhanced Ultrasound
- AI-Enabled/Automated Ultrasound
- Point-of-Care Ultrasound (PoCUS)
- By Portability
- Stationary Systems
- Portable Systems
- Handheld/Wireless Scanners
- By End-User
- Public Hospitals (SUS)
- Private Hospitals
- Diagnostic Imaging Centers & Radiology Clinics
- Primary & Maternity Clinics
- Ambulatory Surgery Centers
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the Brazil country context, the demand backdrop, and the operating realities that influence imaging equipment purchasing. We relied on public health statistics and healthcare system references such as Brazil Ministry of Health publications, DATASUS datasets, IBGE indicators, and ANVISA regulatory information. These sources helped confirm how diagnostic services are delivered and where capacity tends to be concentrated.
We also reviewed peer-reviewed clinical journals, association websites for imaging and radiology communities, company annual reports, investor presentations, and reputable press updates on hospital capex and access to diagnostic care. Where needed, paid subscriptions for company financials and news intelligence were used, along with patent databases and shipment-level import and export data. This helped cross-check supplier presence, product cycle timing, and trade intensity for ultrasound equipment. These desk research sources are illustrative, and we also used many other public references for collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on validating the Brazil-specific buying cycle, mix of stationary versus portable systems, and how demand differs across public and private care pathways. We spoke with a spread of manufacturers and channel participants, along with imaging stakeholders such as hospital administrators and clinical users, so assumptions from desk research could be corrected and then finalized. Since this is a single-country market, we balanced responses across major Brazilian demand centers rather than splitting by global regions.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 27% | CXOs: 14% |
| Mid tier: 59% | Functional/Unit leaders: 37% |
| Smaller Players: 14% | Managers: 49% |
Market-Sizing & Forecasting
Sizing starts from a top-down reconstruction of Brazil demand, where imaging equipment need is mapped from care activity and capacity signals, then converted into unit demand and value using realistic price bands. To keep the model practical, we used inputs such as installed base replacement rhythm, purchasing share by public hospitals (SUS) versus other providers, the split between stationary and portable placements, application-led utilization intensity, and import exposure as a proxy for supply availability.
Those totals were corroborated using selective bottom-up approximations, including supplier revenue allocation to Brazil, channel checks on typical system mix, and sampled average selling price by portability and technology. When bottom-up data was incomplete for smaller participants, we handled gaps using conservative share assumptions tied to import patterns and interview feedback, followed by consistency checks against the overall demand pool.
For forecasting, we used scenario analysis supported by simple time-series smoothing of the most stable inputs, then adjusted the path based on interview consensus around procurement timing, replacement cycles, and mix shift toward portable systems. The goal was to keep each step traceable so we can explain the drivers behind year-to-year movement without overfitting the numbers.
Data Validation & Update Cycle
Outputs were validated through step-by-step variance checks before sign-off, so abnormal jumps in volumes, pricing, or mix were questioned and corrected. We compared model results against independent signals such as healthcare spending direction, imaging capacity expansion cues, and import flow changes, then rechecked any outliers against the source notes.
A second analyst review is applied to formulas, assumptions, and conversions, and respondents are re-contacted when a key variable moves outside an expected band. The report is refreshed annually, with interim updates when material events occur, and a final pre-delivery review so the view reflects the latest available information.
Mordor Intelligence's Brazil Ultrasound Devices Market Sizing Compared With Other Published Estimates
Published market sizes can differ even when they talk about the same country, because authors may choose different device boundaries, time cutoffs, and pricing logic for imported systems. Differences also come from how public sector purchases are treated, and whether the estimate is built from demand activity or from supplier-side revenues.
Key gap drivers in Brazil often include whether handheld and portable systems are grouped together, whether public tenders are counted on award date versus delivery date, and how currency conversion timing is handled when imported equipment dominates the value mix. The table shows a spread that is mainly explained by scope and timing choices, and in Mordor Intelligence's model the value counts new ultrasound system revenues sold into Brazil and excludes stand-alone service-only revenue that can inflate totals in years with heavy maintenance renewals.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 246.51 M (2025) | |
| Global Consultancy A | USD 126.20 M (2023) | Uses an earlier base year and appears to narrow the scope to a smaller subset of ultrasound systems, which can undercount value when higher-priced cart-based systems are included in other studies. |
| Trade Journal B | USD 209.20 M (2030) | Reports a more aggressive growth path and may embed a faster ASP increase and earlier adoption of portable systems, which can lift the forward-year value versus a replacement-cycle-led outlook. |
Overall, the comparison points to two practical reasons for the differences: what is counted as device revenue, and how fast pricing and mix are assumed to change. By tying the model to clear demand signals and then cross-checking with supplier and channel feedback, we keep the estimate repeatable and easier to reconcile across years.


Key Questions Answered in the Report
What is the current value of the Brazil ultrasound devices market?
The Brazil ultrasound devices market size stands at USD 258.59 million in 2026 and is projected to reach USD 328.47 million by 2031.
Which application segment generates the highest revenue?
Gynecology and obstetrics lead with 27.21% of 2025 revenue, supported by mandatory prenatal screening protocols.
Why are handheld ultrasound scanners gaining popularity?
Handheld units grow at an 10.72% CAGR because they extend imaging services to rural clinics and emergency departments lacking certified sonographers.
How does ANVISA’s Class III reclassification affect manufacturers?
The new rule demands full registration dossiers and factory inspections, lengthening approval timelines and increasing compliance costs for AI-enabled platforms.
What technologies are seeing the quickest uptake?
AI-enabled ultrasound systems record a 8.79% CAGR as automated measurements shorten exam times and alleviate workforce shortages.
Page last updated on:





